New Build Turnkey Loans NZ: How to Compare Your Options

The lowest interest rate may not be the best starting point when you’re comparing new build turnkey loans nz. The contract’s payment dates need to line up with the lender’s assessment and settlement process, and turnkey finance can work differently from buying an existing home or funding a build in stages.

With a turnkey build, the main loan is generally drawn at settlement rather than released in stages during construction. Before signing or relying on a particular loan structure, understand when your deposit is due, when settlement is expected and what the lender will assess.

This guide explains how turnkey lending differs, what lenders may consider and how to compare options beyond the headline rate. It also covers what to prepare for a conversation with a mortgage adviser. Mortgage Suite Ltd can help you weigh lender fit against your circumstances and contract, and support you through a process that can feel stressful. A decline from a mainstream bank doesn’t necessarily mean you’re out of options.

Key Takeaways

  • New build turnkey loans nz can differ from off-the-plans purchases and construction finance. Use the contract and lender’s assessment to understand which structure may fit.
  • Discuss your finances alongside the property and purchase agreement. A valuation may also form part of the lender’s assessment.
  • Gather your agreement, income details, existing commitments and deposit position before comparing proposed loan structures.
  • Look beyond the headline interest rate and consider how each option fits the contract timing and your circumstances.
  • Mortgage Suite can help you compare lender fit. Founder Krish Krishna started the business in 2000 after 18 years in banking.

What are new build turnkey loans in NZ and how do they work?

A turnkey home is a new property sold under an agreement that sets out how and when the home will be completed and handed over. The aim is for you to take possession of a finished home, but the details depend on the contract. Inclusions, completion conditions and payment dates all affect how you plan your finance.

New build turnkey loans nz aren’t simply a standard mortgage with a different label. A lender may consider the property’s status, the agreement and your financial circumstances when assessing how the loan could be arranged. Read the payment and completion terms carefully, then compare them with the proposed finance before relying on a particular structure.

What does turnkey mean when buying a new home?

“Turnkey” generally describes a home sold with an agreed completion and handover position. The contract sets out what you can expect, so don’t assume every finished home includes the same fittings, finishes or extras. Check the inclusions, any conditions that must be met before handover, and the payment dates. These details help you understand what the lender is being asked to finance and when funds may be needed.

For example, if the home is still being completed, compare the contract’s list of inclusions with the expected handover conditions. Then map the stated payment dates against your finance discussions. As completion approaches, the lender assesses the application in light of the agreement and the property’s status. Settlement follows the contract requirements once the relevant conditions are met. The contract sets the actual sequence, so don’t assume every purchase follows the same timeline.

Is turnkey finance the same as a construction loan?

Not necessarily. A turnkey purchase may be financed as a property purchase, with lending arranged for settlement under the agreement. A construction loan, by contrast, may release funds in stages as building work reaches agreed points. The turnkey contract concept centres on delivery of a completed project, while staged funding is tied to progress during the build. How a lender treats a particular arrangement depends on its details.

The signed agreement and the project stage matter. A home close to completion may raise different finance questions from a project where building has only just begun. The lender may assess the purchase terms, the property and your ability to meet repayments before deciding on a suitable structure. Neither a purchase-style loan nor staged construction finance is automatically right for every buyer.

Before signing, make sure you understand the agreement’s payment dates, completion terms and handover expectations. Resolve any uncertainties before assuming a particular finance arrangement will fit. For buyers considering new build turnkey loans nz, matching the loan discussion to the contract can help reduce the risk of a timing mismatch and make the next steps easier to plan.

How lenders assess a turnkey home loan in New Zealand

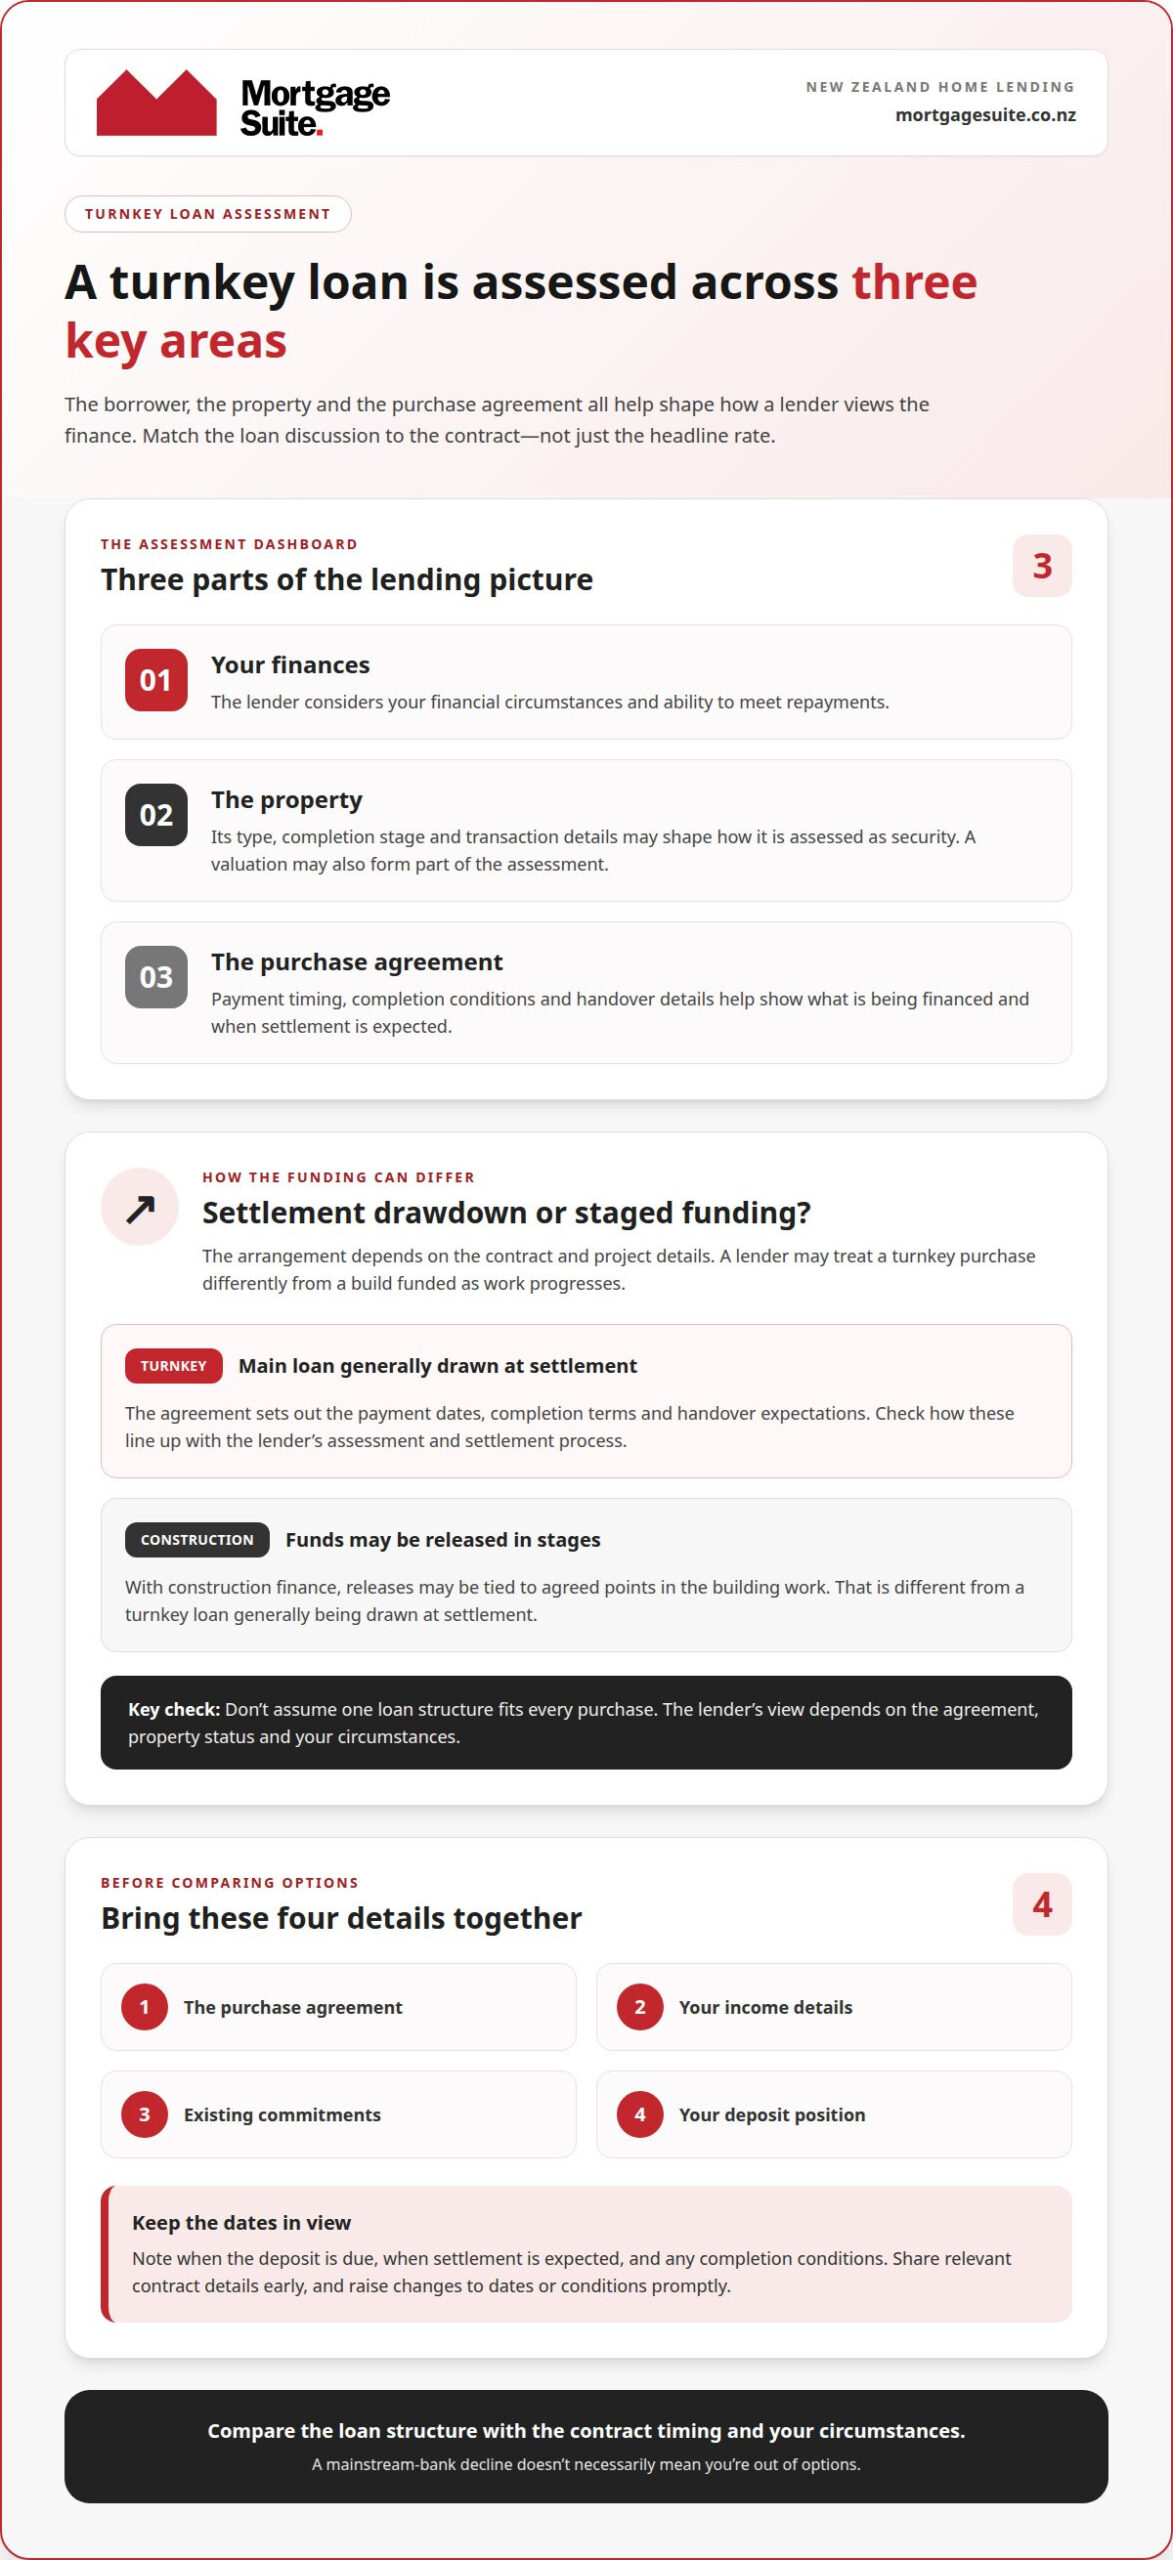
A lender considers more than the home itself. It will look at your finances, the property and the agreement that sets out how the sale will proceed. Your ability to repay matters, as do the property’s status and the timing and conditions in the contract.

A turnkey loan assessment brings together three broad areas: the borrower, the property and the purchase contract. Sharing the agreement early can help you discuss whether a proposed lending structure fits the transaction, rather than focusing only on the amount you hope to borrow.

What parts of the purchase agreement matter to finance?

Pay close attention to payment timing, completion conditions and handover details. The lender needs a clear picture of what you’re buying and when settlement is expected. If the contract dates and conditions don’t align with your finance arrangements, you may be unsure whether lending will be ready when needed. Include the contract in the finance conversation from the outset.

Read the agreement with your solicitor, who can advise you on its legal meaning. For the loan discussion, note the key dates and conditions and share the relevant details with your adviser. If a completion date changes or a condition affects settlement, raise it promptly so the finance plan can be considered against the updated position. This doesn’t replace legal advice. It helps keep the lending discussion informed.

What can affect the lender’s view of the property?

The type of home, its completion stage and the transaction details may shape how a lender assesses the property as security. A valuation may help the lender form a view of the property’s value, but whether one is needed and how it’s used depends on the application. Not every turnkey purchase follows the same process.

A completed home and one still awaiting completion provide different information for a lender to consider. The lender may assess the property alongside the purchase terms and your finances, rather than relying on the home’s description alone to decide how the loan should work. That’s one reason to look beyond the name of a proposed structure.

For new build turnkey loans nz, consider how the proposed lending fits your circumstances, the property and the contract’s settlement arrangements. Bring those details together before comparing options, and make sure any changes to the agreement are reflected in the discussion. If you’d value support weighing lender fit against your purchase details, Mortgage Suite’s home loan guidance can help you work through the questions.

Turnkey loan options compared with off-the-plans and construction finance

The useful comparison isn’t about choosing a universally “best” loan type. It’s about when the property is expected to be ready, when funds may be needed and what you’ll need to manage under the contract. For new build turnkey loans nz, the contract and lender assessment determine which finance structure applies. Use the table as a guide, not a rulebook.

Option Property and timing Payment structure and buyer focus
Turnkey purchase The home may be complete or nearing handover, depending on the agreement. Finance is arranged around the purchase and settlement terms. Check what must be completed before settlement and when payments fall due.
Off-the-plans purchase You agree to buy before the home is complete. The contract sets out the expected completion and settlement arrangements. Understand what conditions must be met before settlement and how the timing fits your finance plans.
Construction finance The project is funded while building work is under way. Funds may be released in agreed stages, depending on the finance arrangement and project. Be clear about the stage requirements and your responsibilities.

These are broad distinctions, not guarantees about how a particular lender will treat a purchase. The contract wording, project stage and lender’s assessment all matter. Compare practical details: when will the home be ready, when does the agreement require funds, and does the proposed loan structure match those points?

Turnkey purchase versus buying off the plans

A turnkey purchase may involve a home that’s ready or close to handover, while an off-the-plans purchase is agreed before completion. The contract, not the label, sets out the actual position. Before relying on a finance plan, identify what must happen before settlement, including the completion conditions and handover requirements.

Build timing can change, so don’t assume the expected completion date is certain. If timing shifts, the finance arrangements may need to be considered against the revised position. Your solicitor can explain the legal effect of the contract terms, while your mortgage adviser can help relate the dates and conditions to the lending discussion.

Turnkey purchase versus construction finance

A purchase loan is arranged around buying the property, while construction finance may release funds as agreed building stages are reached. The staged drawdown process depends on the finance arrangement and project, so don’t assume every build follows the same steps. Development funding is a separate consideration from a buyer’s home loan for a completed or near-complete turnkey property.

Use the comparison to clarify responsibilities and timing, rather than assuming one route suits everyone. If you want support comparing lender fit against your contract and circumstances, Mortgage Suite’s home loan guidance can help you work through the options.
New Build Turnkey Loans NZ: How to Compare Your Options

How to prepare for a turnkey home loan conversation

Preparation can make a complex borrowing conversation feel more manageable. Bring together the purchase agreement, a clear picture of your finances and the key dates, then compare proposed loan structures against the contract. This gives your adviser a practical starting point for discussing lender fit and timing.

Work through these steps in order:

  1. Gather the agreement. Have the signed or draft contract available, including payment dates, completion conditions and handover details.
  2. Outline your finances. Be ready to discuss income sources, regular commitments, your deposit position and any other borrowing. Don’t assume one deposit amount will suit every lender.
  3. Identify the timing. Note the expected settlement date and any dates or conditions that could affect when funds are needed.
  4. Compare the proposed structures. Consider how repayments, flexibility and lender conditions fit your plans, as well as the interest rate.

Information to have ready before discussing finance

Useful information includes your agreement, available financial records, key contract dates and a summary of your income and commitments. Think about your broader borrowing goals too, such as the repayment approach you’re comfortable with and how much flexibility matters to you. These details help shape a clearer discussion, but no single document or deposit position guarantees approval.

If parts of your income or commitments vary, explain that clearly rather than trying to reduce them to a simple estimate. The aim is to give your adviser an accurate picture of your circumstances and the purchase, so possible loan structures can be considered in context.

Questions that help compare lender options

Test whether each option fits the transaction, not just whether its headline rate looks appealing. Ask how the proposed loan aligns with the contract’s payment and settlement timing, what repayment choices are available, and which conditions or flexibility features may matter to you. You can also ask how the structure would work if the expected completion timing changed.

To explore repayment scenarios, Mortgage Suite’s mortgage calculator can give you a starting point. Treat any result as an estimate, not a lender offer, and discuss the assumptions behind it with your adviser. Mortgage School resources also offer plain-English explanations of mortgage topics to help you prepare questions.

Comparing new build turnkey loans nz is easier when each option is measured against the same information: your finances, goals and contract. If you’d like help working through those details and comparing lender fit, use the calculator as a first step in exploring repayment scenarios.

How Mortgage Suite can help you compare new build turnkey loans

Choosing finance for a new build can feel like a lot to manage, especially when the lender’s process needs to fit the purchase agreement. Mortgage Suite takes a personal approach: we learn about your goals and circumstances, then compare how different lenders may fit the property and contract. We’ll help you weigh up your options without promising that one lender or loan will suit everyone.

Krish Krishna founded Mortgage Suite in 2000 after 18 years in banking. Since then, he has arranged over a billion NZD across residential, commercial and business lending. That experience informs how we consider the full picture, including the timing and terms of your new-build agreement, rather than judging an option by its headline rate alone.

What working with a mortgage adviser can add

Bringing your finances and contract details together can make it easier to compare options across a wide range of bank and private lenders. Mortgage Suite can help you consider lender fit, discuss possible structures and negotiate on your behalf. The aim is to support an informed decision. No adviser can guarantee a particular rate, approval or outcome.

Client experiences can also give you a sense of the support people have valued. Read Mortgage Suite client reviews to learn about their experiences with guidance and lending negotiations. Every borrower’s circumstances are different, so those stories aren’t a promise that your application will follow the same path.

A calm next step for your new-build plans

You don’t need to have every lending question answered before starting a conversation. Bring the agreement, note the key contract dates, and share your borrowing goals and any concerns about how the finance might fit. Those details can help frame a useful discussion about which options may be worth considering and what questions remain.

If a mainstream bank has already said no, that isn’t automatically the end of your borrowing options. A different lender may assess your circumstances differently, though approval is never assured. The next step is to understand what the decision means for your plans and whether another lender or structure may be a better fit.

If you’re considering new build turnkey loans nz, a first discussion can help clarify how your agreement and finances relate to possible lending options. Bring your questions and contract timing, and talk with Mortgage Suite about your home-loan options.

Take the next step with confidence

Buying a new home is a big personal milestone, and it’s normal to want a clearer sense of what comes next. You don’t need to have every answer lined up. A thoughtful conversation can help you feel prepared to move forward at a pace that suits you.

If you’re exploring new build turnkey loans nz, Mortgage Suite can help you talk through your plans and consider your options. Start a conversation with Mortgage Suite when you’re ready.

Take it one step at a time. The right support can help you approach your new-build plans with greater confidence.

Frequently Asked Questions

Can I apply for a turnkey home loan before signing the purchase agreement?

Yes, you can start discussing finance before you sign. This gives you time to understand what lenders may need and whether your plans appear workable, without treating an early indication as final approval. If the agreement is still being negotiated, tell your adviser what may change. A different purchase price, ownership arrangement or contract condition could affect the application, so avoid making firm commitments based only on an initial conversation.

What happens if the turnkey property’s completion date changes?

A changed completion date may affect the timing of your finance, so get the revised date in writing and tell your adviser promptly. Ask whether any lending approval conditions or time limits need attention, and keep track of updated notices from the seller or developer. If the revised date creates a concern under your agreement, speak with your solicitor about your position and the steps available to you.

Can a turnkey home loan include the land as well as the house?

It can, if the purchase is structured to include both, but the lender needs to understand exactly what you’re buying. Check whether the agreement describes the land and home together or sets them out as separate parts of the transaction. That distinction can affect how the lender assesses the request and what information it needs. Make sure your borrowing discussion reflects the full purchase arrangement, not just the house component.

Can I use a turnkey home as an investment property?

Yes, a turnkey home may be purchased as a residential investment property, subject to the lender’s assessment. Be clear about your intended use from the outset, especially if you plan to rent the home rather than live in it. You can discuss how you expect to manage the property and any rental income as part of your overall finances. The lender will assess your circumstances and the proposed purchase before deciding what it can offer.

What if a bank declines my turnkey home loan application?

A decline doesn’t automatically rule out every option. Start by finding out the main reason for the decision, such as a concern about your application details or the property. Then you and your adviser can consider whether further information may help, or whether another lender could assess the situation differently. Mortgage Suite works across bank and private lenders, including 2nd Tier Loans for borrowers who don’t fit mainstream bank criteria. Approval is never guaranteed.

Does a turnkey home loan require a property valuation?

Not in every case. The lender decides whether it needs a valuation and what information will help it assess the property. If one is requested, ask what it needs to cover and whether it must be completed before a particular stage of the application. This can help you understand the lender’s next steps and avoid assuming that an assessment used for another property or application will be suitable.

Can I change lenders after signing a turnkey purchase agreement?

You can explore another lender after signing, but a new application may involve fresh checks and could take time to progress. Before switching, compare the new lender’s requirements with your existing approval and consider whether the change affects your ability to meet the agreement’s obligations. Your solicitor can advise on the contract, while a mortgage adviser can help you weigh up the lending options. Don’t assume a new application will be approved.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Auckland broker for comparing banks and non-bank lenders

A mainstream bank’s answer isn’t always the last word on your borrowing options. Mortgage Suite Ltd can present your application to multiple lenders, including banks and non-bank lenders, and help compare options for a first home, an investment property, a self-employed application or a business. A broker arranges lending rather than lending money directly, so the right match depends on your goals, finances and the lender’s criteria.

Comparing lenders can feel like another job on top of an already big decision. A low headline rate may catch your eye, but the loan structure, repayment flexibility and fit with your plans matter too.

Here, you’ll learn what a Mortgage Suite Ltd broker does, how lender comparisons work and what can shape an application. We’ll also cover the different needs involved in buying your first home, applying with self-employed income, purchasing an investment property or seeking business and commercial finance, so you can see what to prepare and what the next steps may look like.

Key Takeaways

  • Compare loan options by more than the headline rate: consider repayment flexibility and how the lending structure fits your plans.
  • For a first home or rental property, understand how your deposit, income and property choice can shape the options available.
  • Self-employed applicants can present their income using business records, including bank statements and profit-and-loss records.
  • Business and commercial lending needs can differ from a standard home loan, so the purpose of the funds and how they’ll be repaid matter.
  • Mortgage Suite can help explore home loans, residential investment property loans and business finance, including options beyond mainstream banks.

First-home buyer and property investor loans

A first-home loan and an investment loan serve different goals, so lenders assess each application in context. Compare the deposit, income evidence, property and repayment structure before choosing a direction.

First-home buyer mortgage advice

First-home mortgage advice can help you understand what lenders may consider before you make an offer. An adviser can review your deposit, income, regular commitments and the property you’re considering, then explain how these details affect possible loan structures. For example, a pre-approval can help you set a borrowing limit before attending open homes. Treat it as a guide, not a final loan offer.

In New Zealand, ask which Financial Advice Provider is responsible for the advice and how its disclosure and complaints process works. A reputable adviser should explain their role, the lenders they can approach and why a suggested option may suit your circumstances.

Auckland brokers may charge fees, while other payment arrangements can apply. The amount depends on the arrangement and your case, so ask for the fee, when it would be payable and any other payment details in writing before proceeding.

To find a suitable Auckland mortgage broker, compare how they explain lender choices, their advice process and relevant experience. Ask how they’ll present your application and what happens if a lender declines it. Clear answers help you understand the service before sharing documents or making decisions.

Using a broker also has limitations. Their lender panel may not include every available option, and a lender can still decline an application. Ask how the broker is paid and whether lender relationships affect the options they present. You remain responsible for deciding whether the proposed repayments fit your budget.

Loans for property investors

Residential investment property loans are assessed against both your financial position and the property’s role in your plans. Discuss the purchase purpose, deposit, expected rental income and how you’ll manage repayments if the property is vacant. These details help frame an application and show whether a proposed structure suits your wider financial commitments.

Compare repayment flexibility as well as the interest rate. A fixed interest rate keeps repayments stable during the agreed fixed term, while floating rates can vary with benchmarks such as swap rates. Floating rates may allow large repayments without a penalty, which can suit investors planning to reduce debt faster. Consider how each structure fits your cash flow and plans.

Before progressing, ask the adviser to explain the recommended loan structure, repayment options and lender criteria in plain language. A clear comparison should connect each option to your deposit, income and property goals, rather than focus on the interest rate alone.

Self-employed mortgage applications

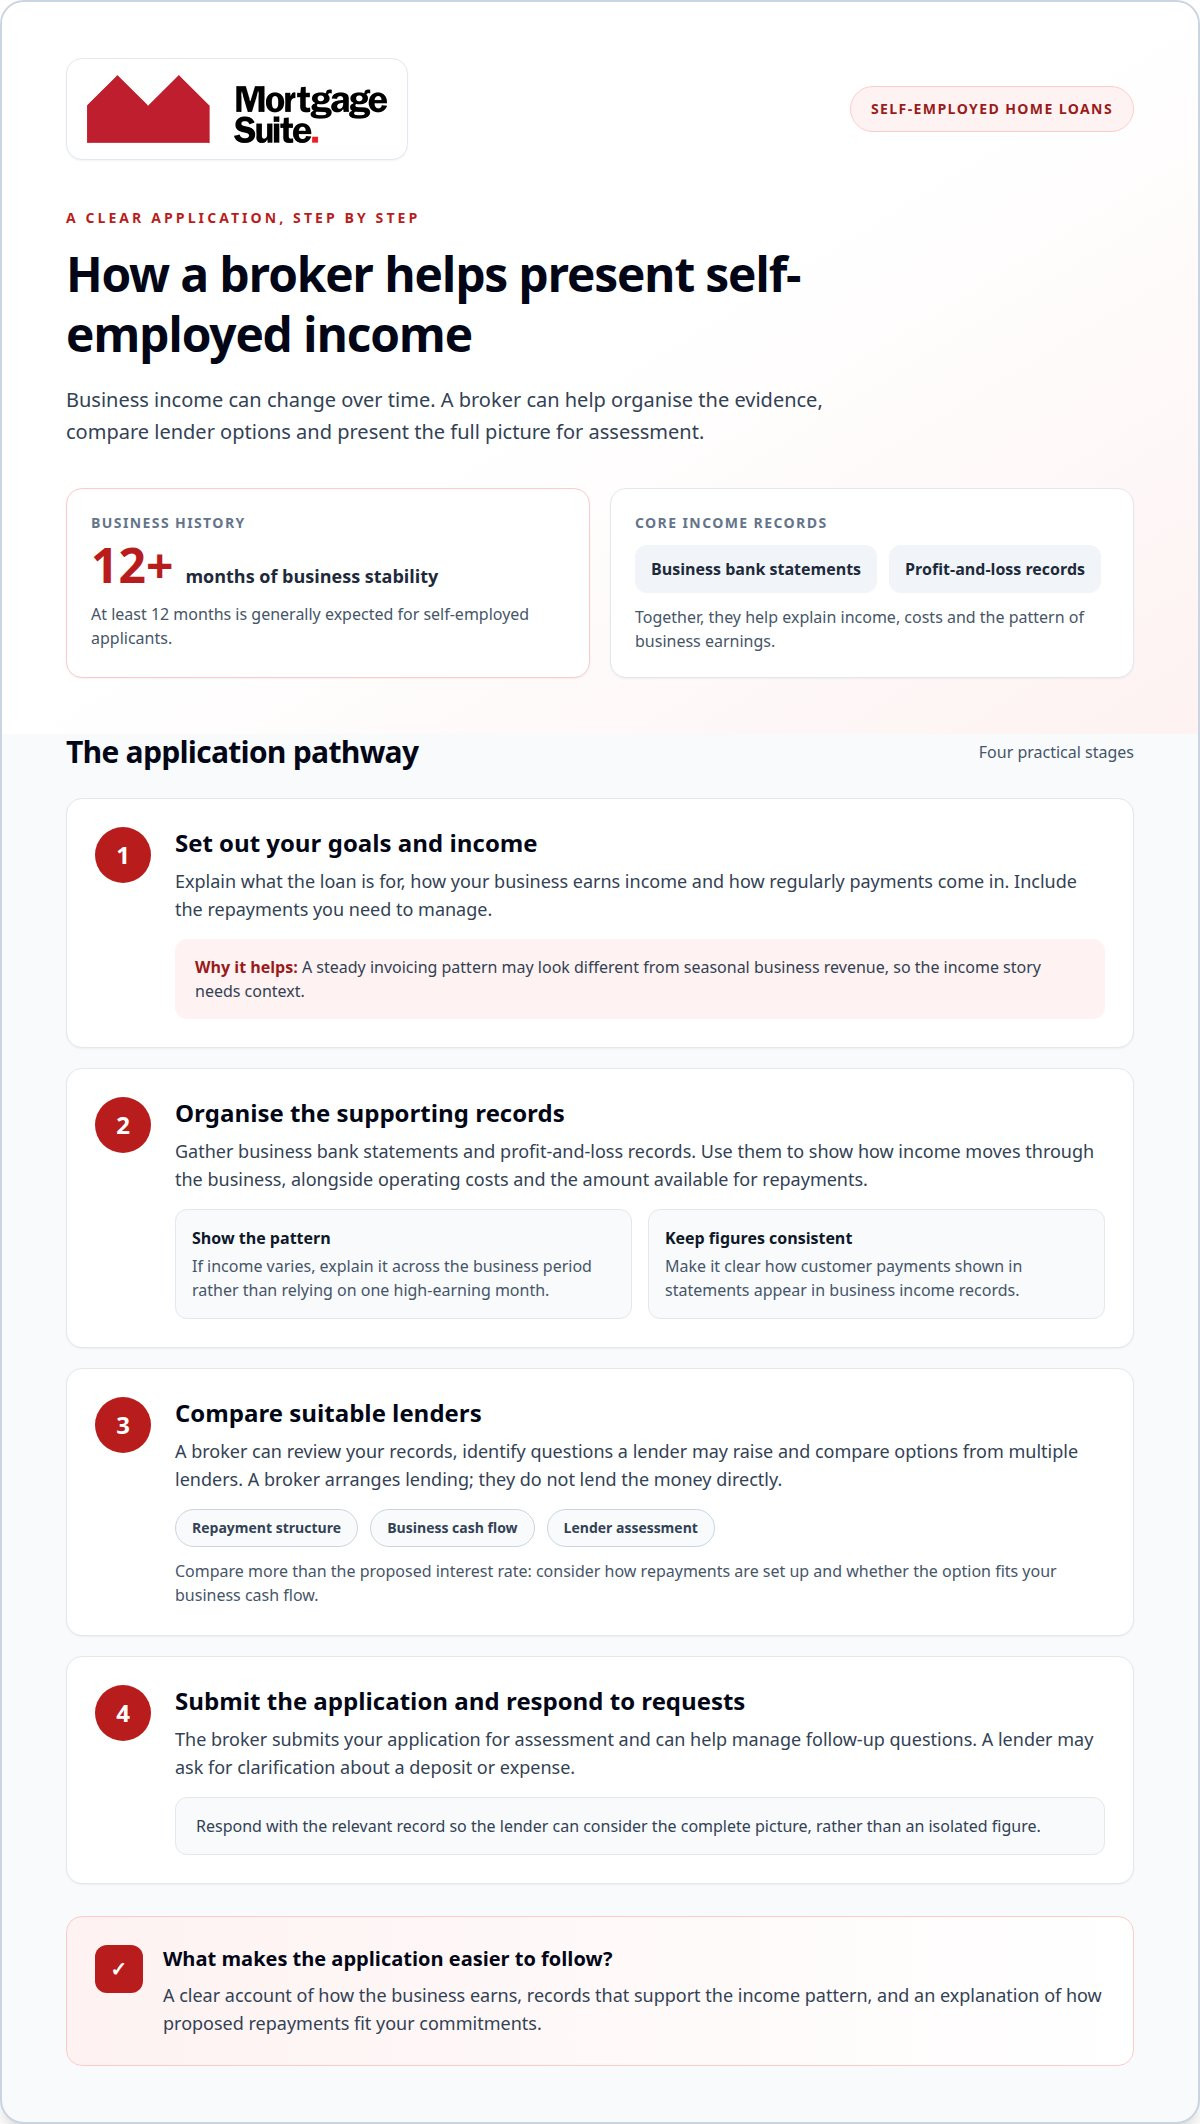
Self-employed income can be harder to present than a regular salary, especially when business earnings change between periods. In New Zealand, applicants are generally expected to show at least 12 months of business stability, and lenders can assess bank statements alongside profit-and-loss records.

Start by explaining how your business earns income and how regularly it receives payments. A contractor with steady invoices, for example, may present a different pattern from a business owner whose revenue changes seasonally. The lender considers the evidence alongside existing commitments and proposed repayments, rather than looking at one strong month alone.

Mortgage application documents

Prepare business bank statements and profit-and-loss records that show how income moves through the business. These documents help explain revenue, operating costs and the amount available to support repayments. If income varies, use the records to show the pattern across the business period, rather than relying on a single high-earning month.

Keep the figures consistent across the records you provide. For example, if a bank statement shows a customer payment, the profit-and-loss record should make its place in business income understandable. Organised documents give the lender a clearer picture of your application and reduce confusion over how you earn.

Business stability matters alongside the amount earned. A trading history of at least 12 months is generally expected for self-employed applicants, while the records help show how that business has performed. If you recently changed the way you work, explain the change and show how your current income is supported by the available evidence.

Steps to a mortgage through a broker

The steps are to discuss your goals and business income, organise supporting records, compare suitable lenders, then submit an application for assessment. A broker acts as an intermediary, presenting your application to multiple lenders rather than lending the money directly.

Start by setting out the loan purpose, the income your business generates and the repayments you need to manage. The broker can then review your bank statements and profit-and-loss records, identify questions a lender may raise, and prepare an application that explains how the figures fit together.

After comparing lender options, the broker submits the application and helps manage follow-up requests. A lender may ask for clarification if a deposit or expense needs explaining. Responding with the relevant record keeps the assessment moving and helps ensure the lender considers the complete picture, not an isolated figure.

Compare more than the proposed interest rate. Ask how repayments are structured, what the lender’s assessment focuses on and whether the option fits your business cash flow. If one mainstream bank declines the application, that decision does not automatically settle what other lenders may consider. Different lenders can assess the same income evidence under different criteria.

Before accepting an offer, make sure you understand the repayment amount, loan structure and any conditions attached to the lender’s decision. A broker can explain those details in plain language, so you can weigh the commitment against your business income and household budget.

Business and commercial loans

A business loan and a commercial property loan address different needs. A business owner seeking equipment finance has a different purpose from a company buying premises. Start by defining what the funds will pay for, how the business expects to repay them, and which assets support the request. That gives a lender a clearer basis for assessing the application.

For a business loan, explain the use of funds in practical terms. For example, a wholesaler might need working capital to pay suppliers before receiving customer payments. A lender can assess the business’s income, expenses, existing debt and repayment capacity against that purpose. A clear cash-flow picture helps show how repayments fit alongside regular operating costs.

Prepare records that make the business’s finances easy to follow. These may include business bank statements, profit-and-loss records and details of current borrowing. If income changes across the year, explain the pattern, such as higher sales during a seasonal trading period. Match the requested loan amount to a defined need, rather than presenting an unexplained figure.

Commercial property finance focuses on the property and its role in the business. A company purchasing its own premises, for instance, can explain how the site supports its operations and how repayments fit its trading income. The lender considers the property alongside the applicant’s financial position. Assess the loan against the planned use, ownership structure and repayment approach.

A term loan is provided as a lump sum with a defined repayment schedule and end date. That structure may suit a specific purchase, such as a business asset or property, where the amount and purpose are known. Compare its repayment pattern with the expected benefit of the purchase. For example, equipment should support business activity throughout the loan period.

Before an application is presented, organise the key details:

  • Purpose: describe the purchase, operating need or property transaction.
  • Repayment plan: explain which business income will meet repayments.
  • Financial records: provide statements and profit-and-loss information that support the figures.
  • Security: identify any property or business assets offered to support lending.

For a commercial property purchase, also set out the proposed use and expected contribution to the business. For example, operating from owned premises may differ from buying a property to earn rent. Those distinctions affect how the lender understands the transaction and assesses its repayment source.

If a mainstream bank declines an application, treat the decision as information about that lender’s assessment, not a verdict on the business. Another lender may consider the purpose, records or security differently. A well-organised application helps explain the business case and gives lenders the details needed to assess it.

Auckland broker for comparing banks and non-bank lenders

Comparing banks and non-bank lenders

There isn’t one best Auckland mortgage broker for every borrower. Compare how each broker explains lender choices, presents your circumstances and weighs loan structure alongside the interest rate. A useful comparison connects the lender’s criteria to your borrowing purpose, income and repayment plans.

A bank lends directly and assesses your application under its own lending criteria. A non-bank lender is also a direct lender, but its assessment approach and loan terms may differ. A broker acts as an intermediary and can present your application to multiple lenders. That can help you see alternatives if one lender’s criteria don’t fit your circumstances.

Compare the whole loan, not just its advertised rate. Check the repayment structure, any conditions, flexibility for extra repayments and how long a fixed interest rate applies. For example, a lower rate may not suit a borrower who values repayment flexibility more. Ask the broker to explain the trade-offs in plain language, using your own goals.

Non-bank lending can be relevant when an application doesn’t fit a mainstream bank’s usual criteria. Second-tier loans are options for borrowers who don’t fit mainstream banks. The lender still assesses the application, including its purpose, income, repayments and supporting information. A different lender may offer another path, but the terms and assessment can differ.

Use these points to compare a broker’s approach:

  • Lender range: ask whether the broker can present your application to banks and non-bank lenders.
  • Reasoning: expect a clear explanation of why a lender may suit your income and loan purpose.
  • Loan structure: compare repayment options and conditions, not only the headline rate.
  • Communication: find out how the broker will explain lender feedback and any next steps.

For example, a self-employed borrower may need an application that explains variable business income clearly. One lender may assess that evidence differently from another. A good comparison shows how the records support the application and why each proposed lender is worth considering. It doesn’t treat a bank’s decline as a final judgement on the borrower.

Before choosing a broker, ask how they’re paid and whether lender relationships affect the options presented. Request a written comparison that outlines the proposed lender, repayment structure, conditions and relevant trade-offs. This gives you a clearer basis for deciding, rather than relying on a broad claim that one lender is always best.

The right Auckland broker is one whose lender access and explanation fit your needs. Compare their approach using the same questions and your actual borrowing goals. A careful discussion should leave you understanding why a bank or non-bank option is being considered, and what the lender will assess.

The best fit is a broker whose lender range matches your circumstances and who clearly explains lender choices, loan structure, conditions and trade-offs. Compare how each broker handles your income and loan purpose, communicates lender feedback, and explains how they’re paid and whether lender relationships affect the options they present.

What types of brokers operate in Auckland, New Zealand?

An Auckland broker may focus on home lending, specialist applications or business finance. A mortgage broker acts as an intermediary, rather than lending money directly, and can present your application to multiple lenders. The useful distinction is the type of borrowing they handle and whether that matches your plans.

A residential mortgage broker works with home-loan applications. That can include a first-home purchase, a move to another home or borrowing for a rental property. For example, a first-home buyer may need help understanding how their deposit and income shape lender choices. An investor may need a discussion centred on the property’s purpose and planned repayments.

Some brokers focus on applications with less straightforward income or circumstances. A self-employed applicant, for instance, may need their business income explained through bank statements and profit-and-loss records. A broker familiar with those applications can help present the records clearly and approach lenders whose criteria may suit the case. The broker arranges the application; the lender makes its own assessment.

Business and commercial finance brokers work with funding for business purposes or commercial property. A business seeking funds for equipment has a different borrowing purpose from a company purchasing premises. Describe the planned use of funds and repayment source, then identify a broker whose work includes that kind of application.

Bank lending staff have a different role from brokers. They discuss lending offered by their own bank, while a broker can take an application to multiple lenders. That distinction matters if you want to compare a bank’s proposal with options from other lenders. Ask which lenders the broker can approach and how they’ll explain the differences.

To work out which type fits, match the broker’s focus to your application:

  • Buying your first home: look for experience with residential home-loan applications and pre-approval.
  • Applying with business income: ask how the broker presents self-employed earnings.
  • Buying a rental property: discuss residential investment lending and repayment plans.
  • Funding a business or premises: choose a broker whose work includes business or commercial finance.

Before sharing documents, explain your goal in one clear sentence, such as buying a first home or funding business premises. Then ask how the broker will handle that specific application, which lenders they can approach and how they’ll outline each option. Those answers help you understand whether their focus fits your borrowing needs.

Mortgage Suite

Mortgage Suite Ltd helps you compare lending options around your goals, income and borrowing needs. If you’re buying your first home, investing in residential property or seeking finance for a business or property development, the team can help present your application to suitable lenders and explain the differences in plain English.

A mainstream bank’s decline doesn’t necessarily end your options. Mortgage Suite Ltd can also consider second-tier lending for applications that don’t fit mainstream bank criteria, while explaining the terms and trade-offs involved. The focus is on helping you make an informed choice, not promising a particular outcome.

If you’d like to talk through your borrowing plans and possible next steps, contact Mortgage Suite Ltd for a free, no-obligation conversation.

Take the next step with a clear borrowing plan

Before moving ahead, decide what a useful lending outcome needs to do for you. You might want confidence about your first home purchase, room to grow a business, or a structure that supports a property purchase over time. Being clear about that priority gives an Auckland broker a practical starting point for discussing suitable options.

Mortgage Suite offers Home Loans to First Home Buyers, Residential Investment property loans and Business Loans. The next step is a conversation about your goal, your circumstances and the questions you want answered. From there, you can understand which lending options may fit and what information an application needs.

You don’t need to have every detail sorted before starting. Bring the outline of your plans, including what you’re hoping to finance and what feels uncertain. Mortgage Suite can help you talk through the lending path and possible next steps, with no obligation to decide on the spot.

Contact Mortgage Suite about your loan and take the next step with a clearer sense of direction.

Frequently Asked Questions

What documents do Auckland brokers need to assess a loan application?

Prepare documents that show your income, commitments and the purpose of the loan. For a self-employed application, this can include business bank statements and profit-and-loss records. A first-home buyer might also prepare information about their deposit, regular expenses and the property they’re considering. For example, someone buying with another person should be ready to explain how each applicant contributes to repayments and manages shared commitments.

How do Auckland mortgage rates and lending criteria compare across banks?

Rates and lending criteria can differ between banks, so compare offers using the same borrowing details. Look beyond the advertised rate: consider repayment structure, conditions, flexibility and how long any fixed rate applies. For example, ask how each bank would assess the same income and deposit, then compare its written offer and requirements. This makes differences easier to understand without assuming the lowest headline rate is automatically the best fit.

What should first-home buyers in Auckland ask a mortgage broker?

Ask which lenders they can approach, how they’ll compare suitable loan structures and what a pre-approval does and doesn’t cover. You could also ask what may change between pre-approval and a final offer, and which conditions you’ll need to meet. If you’re buying with another person, discuss how the application reflects both incomes and shared repayments. Clear answers help you understand the decision before you make an offer.

How are mortgage brokers in New Zealand regulated and checked?

Ask which Financial Advice Provider is responsible for the advice and how its disclosure and complaints process works. You can also compare the broker’s explanation of lender choices, advice process and relevant experience.

Do Auckland mortgage brokers charge fees, and how much?

Auckland brokers may charge fees, but the amount depends on the arrangement and your case. Ask for the fee, when it is payable and any other payment details in writing before proceeding.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.