Getting a mortgage in your 50s in NZ: balancing repayments and retirement

Getting a mortgage in your 50s in NZ calls for a clear plan for when the loan will be paid off and whether repayments will stay manageable if your income changes. The key isn’t simply your age; it’s whether the loan fits your expected income, retirement plans and day-to-day budget.

It’s understandable to feel cautious about taking on a long-term commitment while also thinking about retirement. New Zealand retirements may last 25 or 30 years, so balancing mortgage payments with the life you want later deserves careful thought. This guide explains how to test repayments against possible income changes, weigh mortgage payments alongside retirement savings and consider ways to keep your options flexible. You’ll also find practical steps for working out what a comfortable loan could look like for your circumstances.

Key Takeaways

  • Assess when the mortgage could be paid off and whether repayments would remain manageable if your income changes.
  • Set a budget that balances mortgage payments with your retirement plans and everyday needs.
  • Consider how options such as downsizing or part-time work could affect your repayment plan.
  • Build flexibility into your approach so you can adapt as your circumstances and priorities change.
  • Plan for a retirement that may last 25 or 30 years, rather than focusing only on the first years after work.

1. Assessing mortgage repayment affordability as income changes

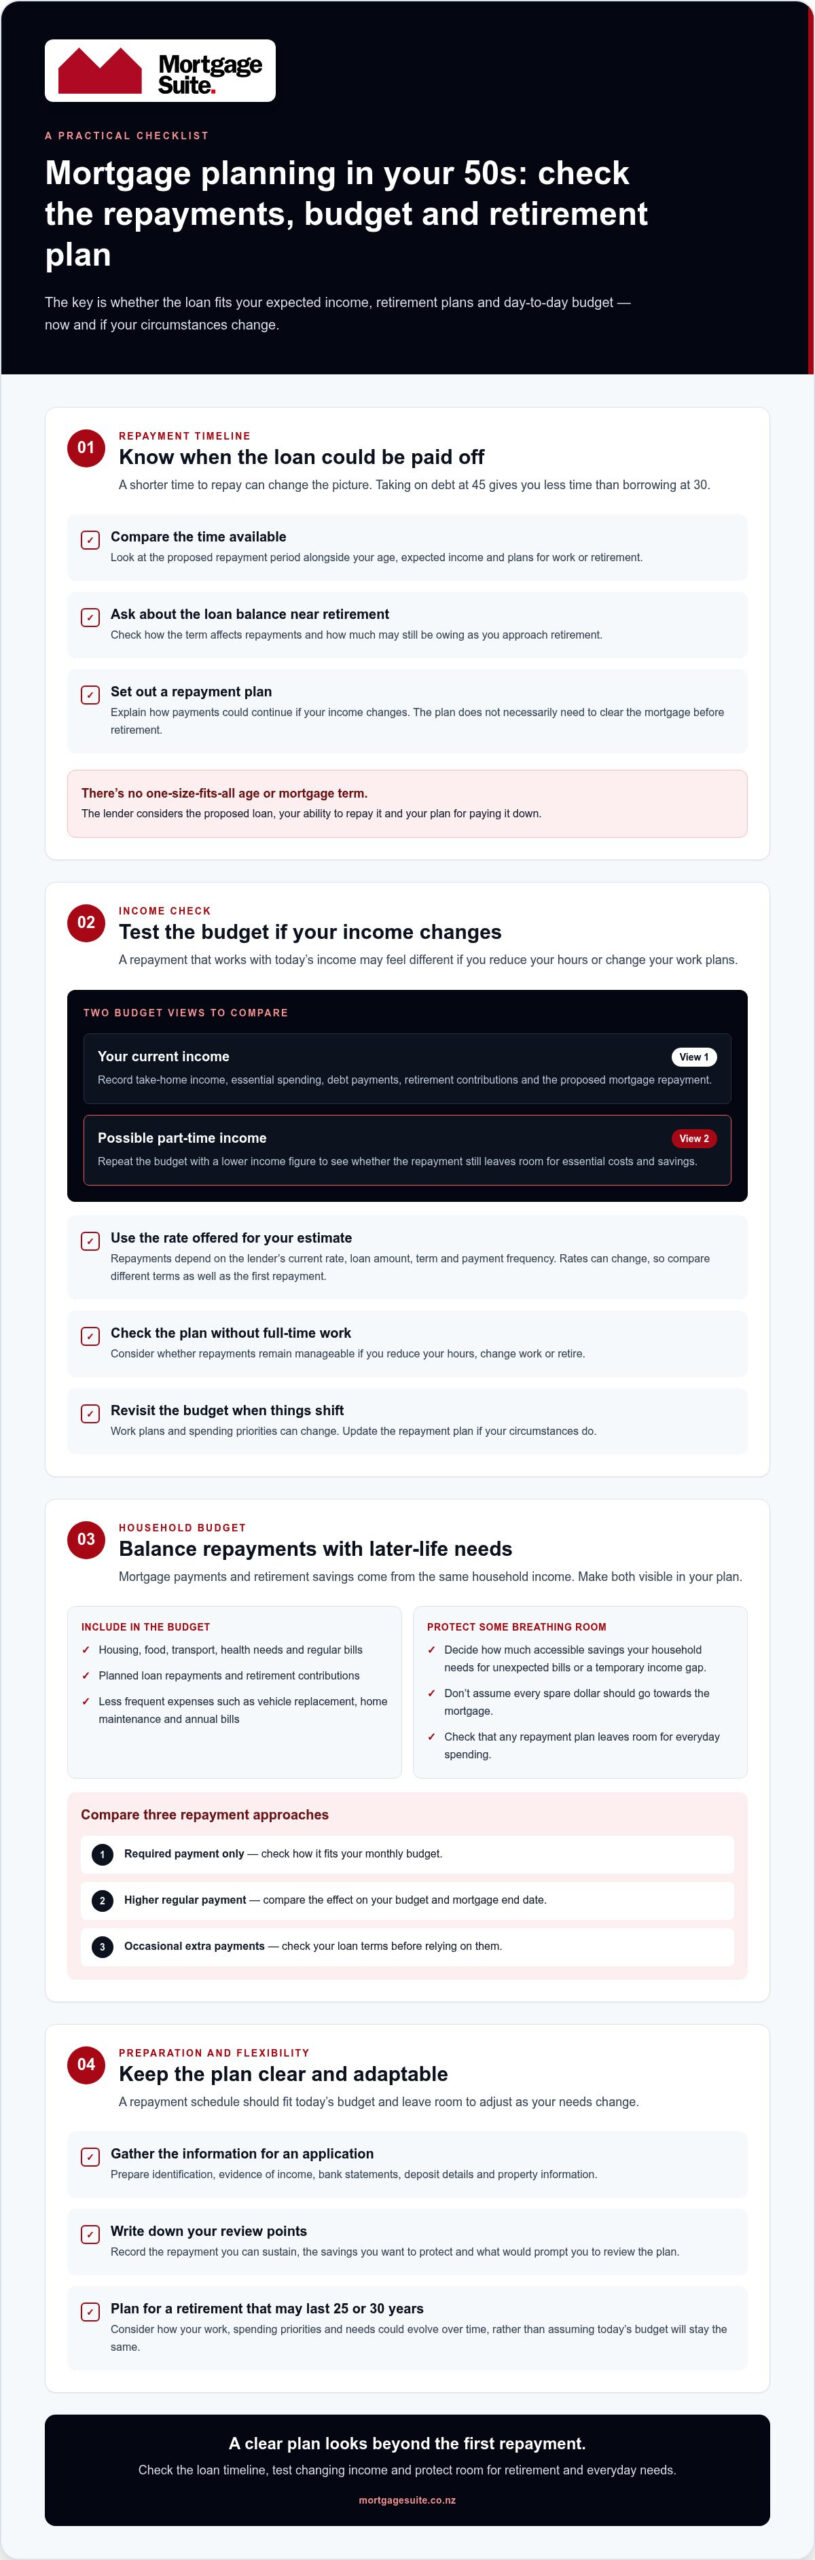
Taking on debt at 45 gives you a shorter available timeframe than borrowing at 30. For Kiwis getting a mortgage in their 50s in NZ, the key question is how repayments fit now and if income changes before the loan is cleared.

Compare borrowing in your 50s with borrowing in your 30s or 40s by looking at the time available to repay and your expected income. A borrower taking on more debt at 45 has a shorter timeframe than someone borrowing at 30. In your 50s, consider how a change in hours, work or retirement plans could affect each repayment.

New Zealand banks assess the proposed loan, repayment ability and plans for paying it down. There is no single mortgage term or maximum age figure that applies to every borrower; the lender considers the loan alongside your income and repayment plan. Ask how the term would affect repayments and the balance remaining as you approach retirement.

Banks may expect a plan for repaying the mortgage, but that plan doesn’t necessarily mean clearing it before retirement. Set out how repayments could continue if your income changes, and whether you expect to keep working, reduce hours or use another source of funds. People in their 50s and early 60s should assess when the mortgage is likely to be paid off and whether payments remain manageable if income shifts.

There is no single deposit amount for every New Zealand borrower in their 50s. The deposit needed depends on the property price, the amount borrowed, your available funds and the lender’s assessment. Work out how much you can contribute, then check the proposed loan against your budget and other commitments.

Mortgage rates and repayments depend on the lender’s current rate, loan amount, term and repayment frequency. Rates can change, so use the actual rate offered to estimate payments; Mortgage Suite’s mortgage calculator can help you explore repayment scenarios. Compare the effect of different terms, not just the first repayment amount.

Taking out a mortgage close to retirement can leave less room in your budget if income falls or costs rise. A longer repayment period may also mean carrying debt later in life. Test whether the payments would remain manageable without relying on full-time work.

To prepare an application, set a repayment budget and list your income, regular expenses and debts. Gather identification, evidence of income, bank statements, deposit details and property information. These records help show how the loan could fit your circumstances and support a clear discussion with the lender.

Many people in New Zealand do not stop working at age 65 and then spend the following 25-30 years simply living without further changes in priorities or needs. When testing affordability, consider how your work plans and spending priorities could evolve, rather than assuming today’s budget will stay unchanged. Check whether repayments would still fit if you reduced your hours or changed how you use your income, and revisit the plan if your circumstances shift. A repayment schedule that works now should also leave room to adapt as your needs change.

2. Balancing mortgage repayment with retirement savings

A mortgage and retirement savings both draw on the same household income. Start by listing essential costs, planned loan repayments and the amount you can set aside for later life. This gives you a clearer view of what remains for everyday spending. For someone in their 50s, the balance should reflect their expected retirement date and the mortgage’s likely finish date.

Build a retirement budget covering housing, food, transport, health needs and regular bills. Compare it with your expected income and any mortgage payments still due. If your budget relies on clearing the home loan, check that the repayment schedule supports that plan.

Try a simple monthly comparison. In one column, record your take-home income, essential spending, debt payments and retirement contributions. In a second version, reduce the income figure to reflect a possible move to part-time work. If the mortgage fits only the first version, consider a smaller loan, a different term or a repayment plan that leaves more room.

Don’t treat every spare dollar as mortgage money. Extra repayments can reduce the balance faster, but accessible savings can help cover an unexpected bill or temporary income gap. Decide how much readily available money your household needs before committing surplus cash to repayments. Review that decision when your work, health or family responsibilities change.

Compare three repayment approaches: the required payment only, a higher regular payment, and occasional extra payments when income allows. Record how each affects your monthly budget and the mortgage end date. Check how extra payments work under your loan terms before relying on them. Your plan should remain manageable in ordinary months, not just when income is higher.

Include less frequent expenses in your retirement budget, such as vehicle replacement, home maintenance and annual bills. Note when each is likely to fall, then set aside money regularly so it doesn’t unexpectedly compete with mortgage payments. A calendar of these expenses can reveal months when your usual repayment plan leaves too little room for other commitments.

Write down the decisions that shape your plan: the repayment amount you can sustain, the savings you want to protect and what would trigger a review. For example, a change in work hours could prompt you to update the household budget before increasing repayments. This turns a broad goal into practical steps and helps you adjust your mortgage plan as your priorities shift.

Considering downsizing, part-time work, or investment income

Alternatives to a standard mortgage for older homeowners can include borrowing less, selling and buying a smaller home, or continuing to earn work income for longer. Each changes the repayment picture differently. Downsizing may reduce the loan required, while part-time work may help cover payments without moving. Compare these options with your budget and plans.

Start with your home. Estimate what selling your current property could leave after paying off its mortgage and allowing for moving and purchase costs. Then compare the price and ongoing costs of a smaller property with those of your current home. A lower loan may mean lower repayments, but a new location could affect transport, support networks and access to services.

Part-time work can help support repayments if your retirement plans include paid work. Build a budget using the income you expect from those hours, then test it against a period when that work is unavailable. Don’t rely on the most optimistic version of your work plans to make the mortgage affordable.

Rental income may also contribute to household cash flow. If you own a property you could rent out, list the expected rent alongside ongoing expenses, including maintenance and regular bills. A vacancy or repair can reduce what remains for mortgage payments, so don’t count every dollar of rent as available to repay debt.

NZ Super, if applicable, and reliable rental income can form part of your repayment plan. Consider when each income source would begin, how regular it is and whether it is likely to continue. Lenders assess income and supporting evidence as part of the application, so keep records showing where the money comes from.

Before relying on an option, write down the steps and their timing. For downsizing, include the sale, purchase and move. For part-time work, set out the expected hours and income. For rental income, allow for periods without a tenant and property expenses. Comparing the options side by side can show whether one is enough or you need a combination.

A residential investment property loan may be relevant if you’re considering buying a property to rent out. Treat rent as one part of the plan, not a guaranteed source of repayments. Compare expected income with ownership costs and the mortgage payment, then consider whether your budget could cope if rent stopped temporarily.

Choose a fallback before committing to a repayment plan. You might reduce spending, increase work hours if possible, or reconsider the property if your income changes. Write down what would prompt a review, such as a change in employment or rental income. A clear trigger can help you respond early, before payments become difficult.
Getting a mortgage in your 50s in NZ: balancing repayments and retirement

4. Maintaining flexibility in later retirement

A flexible mortgage plan gives you room to respond as your needs change later in life. Start by identifying what could affect repayments, such as reduced work, a move or new household responsibilities. Decide which changes would prompt a review. For example, a change in regular income could be a reason to revisit your repayment amount and household budget.

Review the loan structure as well as the payment. A fixed interest rate stays unchanged for an agreed period, which can make repayments predictable during that time. Check what happens when the period ends and whether your budget could manage a different payment. Don’t build a plan around one rate staying in place indefinitely.

Keep a clear record of your mortgage balance, repayment amount and remaining term. Review these details alongside your current income and spending. If you’re paying extra, check the loan terms first. Some arrangements may limit when or how extra repayments can be made, so don’t assume surplus funds are always freely accessible.

Plan for changes to your housing needs. If stairs become difficult, for instance, you might consider moving to a more suitable property. Think through how a sale, a new purchase and any remaining mortgage would affect your monthly commitments. A home that works now may not suit your needs throughout retirement.

Keep flexibility in your wider budget, too. Separate essential bills from spending you could adjust if income changed. This makes it easier to see which costs could be reduced before missing a mortgage payment. Set aside time to review the figures after a change in work, housing or family circumstances.

At age 75, retirement drawdown strategies may need review. Use that milestone to reassess the mortgage alongside your income, housing needs and expected spending. Ask whether the existing repayment plan still fits, or whether a change in the loan or home should be considered. Treat the review as a practical checkpoint, not an assumption that your circumstances will follow a set path.

Write a simple action plan covering what you’ll monitor, what change would trigger a review and which options you could consider. For example, a fall in income might lead you to reassess spending before deciding whether to adjust repayments or housing plans. Writing down these steps makes them easier to revisit as your priorities evolve.

5. Preparing for retirement while paying a mortgage

Before retirement, make sure you understand how your mortgage works day to day. Keep the loan agreement and recent statements together, and note the repayment amount, payment dates and any conditions that affect changes. This gives you a clear reference when reviewing your plans with a partner or adviser.

Build a cash-flow plan around when income arrives and bills are due. Record regular income dates, mortgage payment dates and when larger household expenses fall. If a payment is due before income arrives, ask about adjusting the timing to make your budget easier to manage.

Check how your plan would work if an income source stopped or arrived later than expected. List essential payments first, then identify discretionary costs you could temporarily reduce. This helps you see what practical changes are available before a short-term disruption affects your ability to make mortgage payments.

Include the property itself in your retirement planning. Note upcoming maintenance, accessibility changes or repairs that could affect your household budget. For example, consider a planned bathroom upgrade alongside mortgage payments, rather than treating it as an unrelated future expense.

Keep a record of conversations and decisions about the loan. Note the date, who you spoke with, what you discussed and any agreed next steps. If your circumstances change, this record can help you explain the background clearly without relying on memory alone.

If you share the mortgage, agree how you’ll make decisions about repayments, spending and changes to the home. Write down who will manage routine payments and how you’ll discuss changes in income or household needs. A shared plan can reduce confusion during a stressful transition.

Revisit the plan after a major change, such as finishing work, moving home or taking on caring responsibilities. Update the figures and decide what action makes sense before changing repayments or making a large purchase. Keeping the plan practical and current can help you make considered choices as retirement approaches.

Consider how much your retirement plan depends on staying in the home, and whether that assumption still fits your expected income and needs. The 2025 Massey University Retirement Expenditure Guidelines note that future generations of New Zealand retirees are expected to have lower home-ownership levels. Treat this as a reason to examine your own housing arrangements rather than as a prediction of what will happen to you. Set out the likely costs of keeping the property, including mortgage payments and planned work, and compare them with the income you expect to have available. If the figures feel uncertain, identify what information you need before making a decision.

Discuss what you would do if staying in the home became difficult to afford or manage. Consider possible changes to your living arrangements, when you might make a decision and how each option could affect your budget. Don’t make a major commitment based only on an optimistic estimate of future income. Revisit your assumptions when your retirement plans or household circumstances change. If you share the home or mortgage, make sure everyone understands the options and has a chance to raise concerns. Including these questions alongside repayments and maintenance can help you weigh housing decisions against your wider retirement needs.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you assess home loan options when you are weighing a property purchase against retirement plans. The conversation can focus on your expected income, repayment comfort and the loan structure that fits your goals, rather than treating age as the only factor. If a mainstream bank has declined your application, that does not have to end the discussion; 2nd Tier Loans may suit borrowers who do not fit mainstream bank criteria.

Bring a clear picture of your income, regular commitments, deposit and plans for work or retirement. Mortgage Suite Ltd can help you consider these details and discuss suitable lending options, keeping the long-term repayment plan in view. Our advice is free of charge with no obligation. To talk through your circumstances, visit mortgagesuite.co.nz.

Make your next mortgage decision with confidence

A plan for getting a mortgage in your 50s in NZ should leave room for the life you want beyond the next repayment. Before taking your next step, write down the questions that matter most, such as how borrowing fits your priorities or what would prompt you to review your plans. A focused list can help you have a clearer conversation about your options.

Use the conversation to explore the options that fit your circumstances and the trade-offs involved. Take time to consider the information and decide what feels workable for you.

Discuss your borrowing plans and take the next step with a clearer sense of what matters to you.

Frequently Asked Questions

Can you get a mortgage in your 50s in New Zealand?

Yes, getting a mortgage in your 50s in New Zealand is possible; age alone doesn’t automatically rule you out. Lenders consider your income, debts, deposit and ability to manage repayments over the loan term. They may also look at how you plan to meet payments if your employment income changes. Presenting a clear picture of your finances helps show how the proposed borrowing fits your circumstances.

How do NZ lenders assess retirement income and mortgage affordability?

In NZ, lenders assess whether your expected income can cover repayments alongside regular household commitments. They may consider ongoing work income, NZ Super or rental income, and review evidence such as income records and bank statements. If you expect to reduce your working hours, for example, show how the resulting income fits your budget. Regular expenses and existing debts also affect how much room remains for mortgage payments.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Get a Mortgage on a Low Income in NZ in 2026

What if a lower income doesn’t automatically rule out a home loan? Working out how to get a mortgage with low income nz can feel daunting, especially if you’re worried that regular bills, existing debt or a small deposit will affect your application.

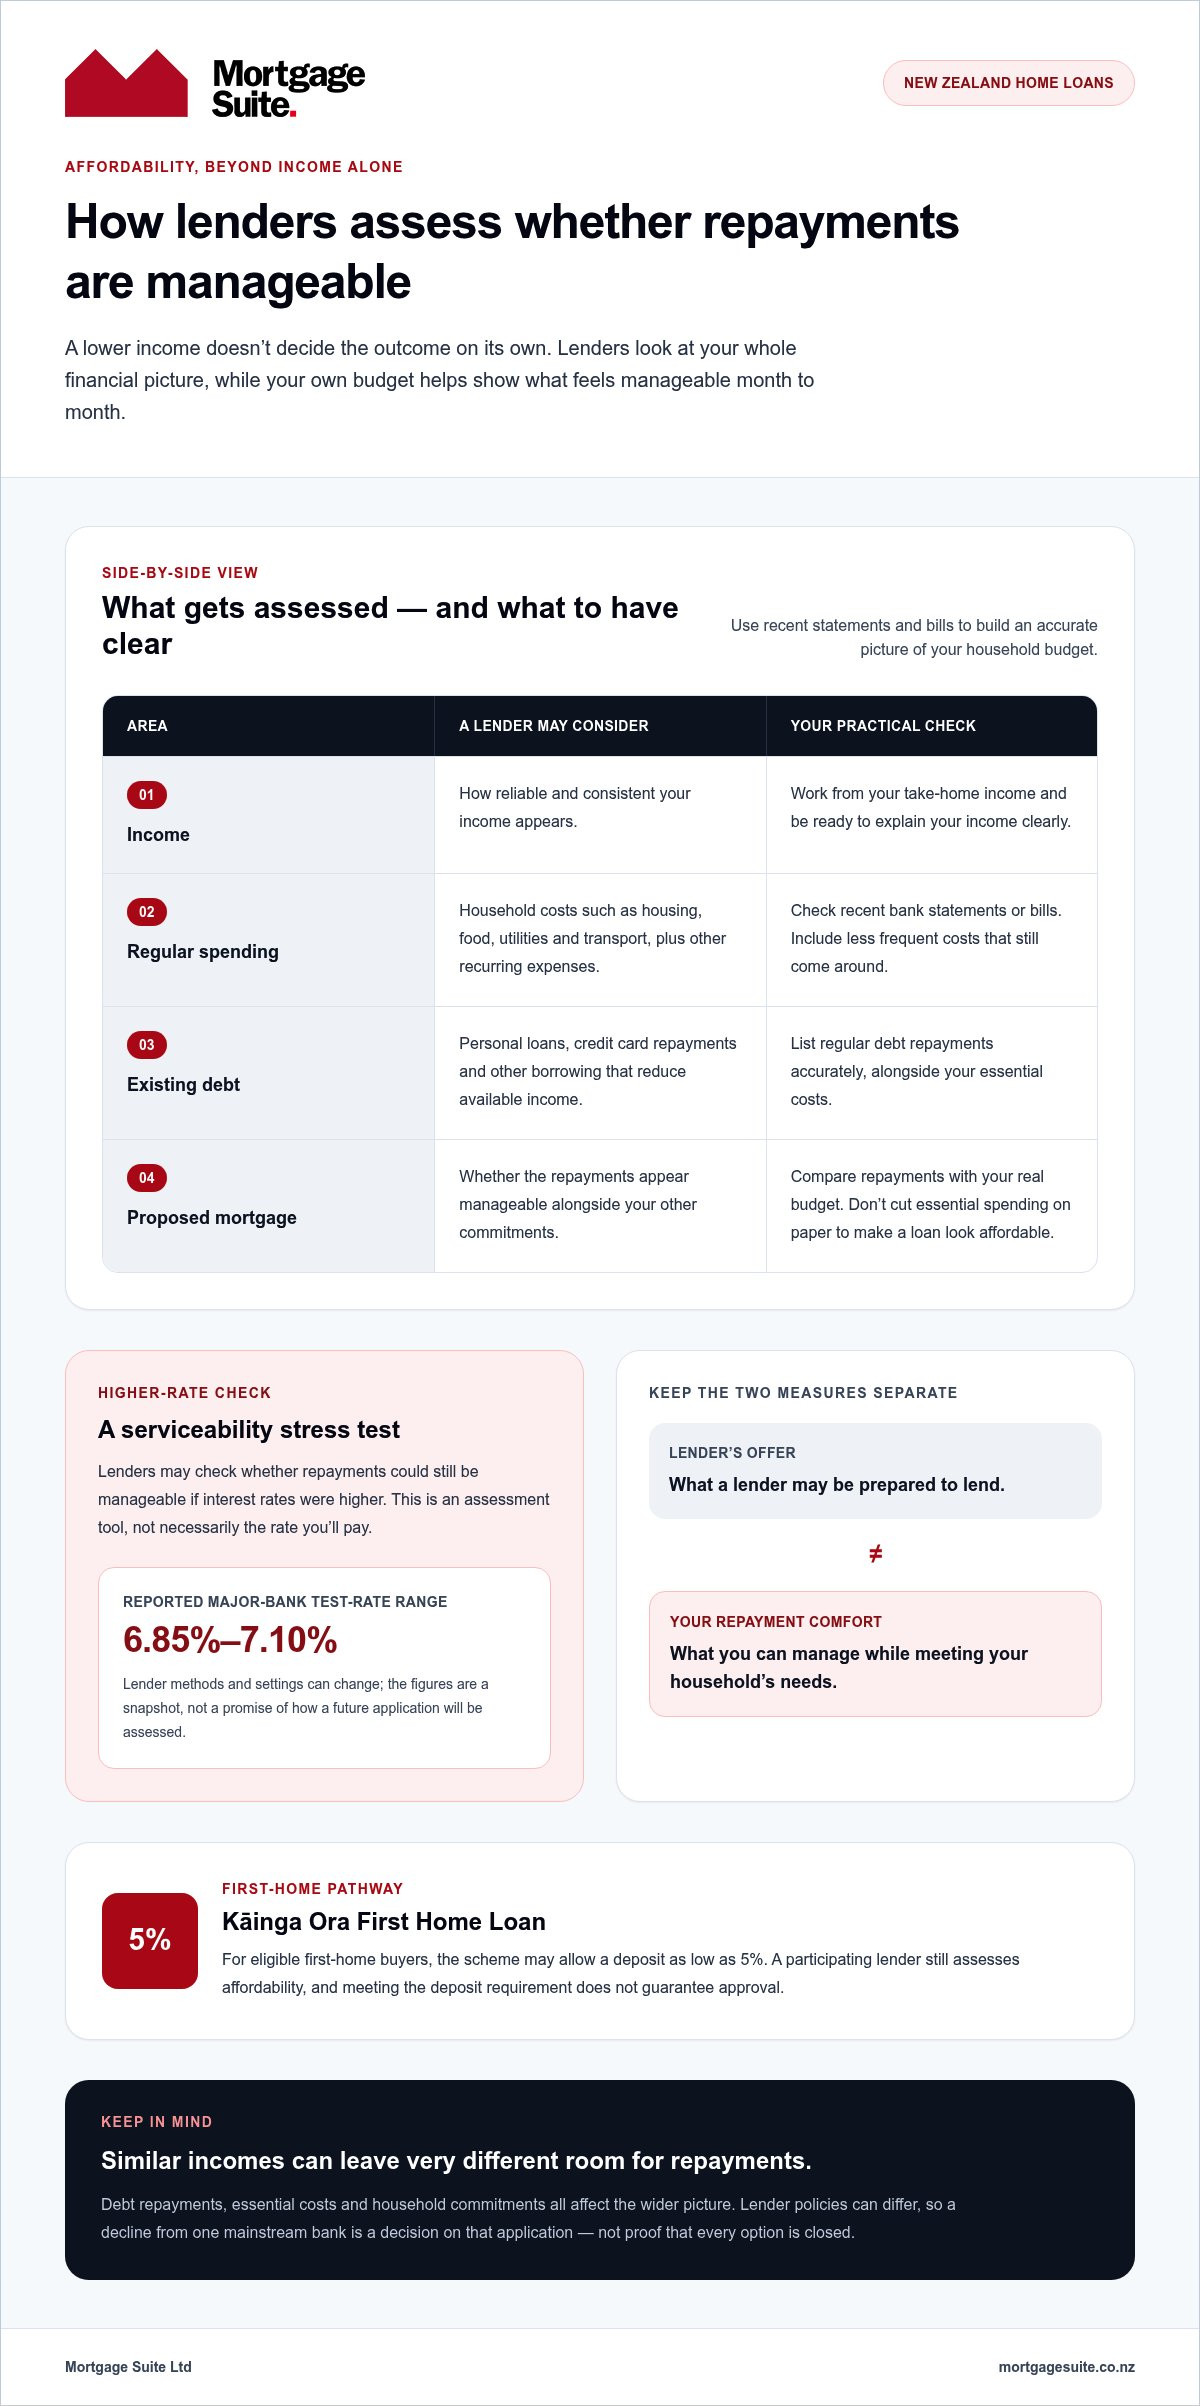
Lenders look at your full financial picture: your income, regular spending, debts and whether repayments appear affordable if interest rates rise. Their lending policies can differ, so a decline from one mainstream bank doesn’t necessarily mean you’re out of options. For eligible first-home buyers, the Kāinga Ora First Home Loan may allow a deposit as low as 5%, but meeting the deposit requirement doesn’t guarantee approval.

This guide explains how lenders assess affordability, which financial records to prepare and what pathways may be worth exploring. You’ll also learn how a mortgage adviser can organise your application and negotiate with lenders, including discussing alternative options where suitable. The aim is to help you understand your next steps and get sorted with a clearer picture, without assuming any lender will approve your application.

Key Takeaways

  • See how to get a mortgage with low income nz by looking at your full financial picture, not income alone.
  • Map your regular income, essential spending and debt to see what room your household budget may have for repayments.
  • Prepare clear, consistent financial records to help lenders assess your application.
  • Compare lending pathways by affordability, repayment structure and flexibility, and consider how each fits your longer-term plans.
  • A mortgage adviser can help organise your application and negotiate with lenders, but no pathway guarantees approval.

Can you get a mortgage on a low income in NZ? Start with affordability

Borrowing can feel stressful when income is tight. You might be wondering whether there’s room for a mortgage after rent, food, transport and other regular bills. A lower income can affect how much you may be able to borrow, but it doesn’t decide the outcome on its own.

Affordability is about whether the proposed repayments appear manageable alongside your household’s other commitments. A lender considers the overall picture, including how reliable your income is, what you spend, any existing debt and the repayments for the home loan you’re seeking. The aim is to assess your application as a whole, rather than judge you by one number.

A rough income rule can offer a starting point, but only an individual lender assessment can consider how your income, spending and commitments fit together. That’s why an online estimate or a simple percentage of income shouldn’t be treated as a borrowing limit or a sign of approval.

What does a lender look at beyond your income?

Income matters, but so does the amount left after regular household costs and debt repayments. A lender may consider whether your income is consistent, what you pay towards existing borrowing, and how a proposed mortgage repayment would sit alongside essentials such as food, utilities and transport.

Two people with similar incomes can have very different budgets. One might have few debts and modest regular commitments; the other might have personal loan repayments or be supporting dependants. Those differences can affect how much room each household appears to have for a mortgage. Be ready to explain your regular costs accurately, rather than relying on a calculator result or a general rule.

Why a lower income does not tell the whole story

Lenders assess the proposed loan against your wider repayment picture, and their policies can differ. That doesn’t mean one lender will necessarily approve an application another declines. It means lender fit may be worth exploring, with affordability and the loan’s terms kept firmly in view. If a mainstream bank says no, treat that as a decision on that application, not a judgement on you or proof that every option is closed.

If you’re exploring how to get a mortgage with low income nz, focus on presenting a clear, accurate account of your finances and understanding what may affect your application. General explanations of a mortgage loan can help clarify common terms, but they don’t describe how a New Zealand lender will assess your application. If you’re buying your first home, Home Loans for First Home Buyers in New Zealand is also a useful next read about the first-home buyer pathway. A careful look at your circumstances can help you work out what to prepare next, without assuming approval is guaranteed.

How NZ lenders assess whether your mortgage repayments are manageable

A salary can look sufficient on paper but leave little breathing room once household costs are included. Lenders look beyond gross income to estimate what could realistically remain for mortgage repayments after regular expenses and existing commitments. Your own budget matters too: a lender’s maximum offer isn’t automatically an amount that will feel comfortable month to month.

A lender’s offer shows what it may be prepared to lend; repayment comfort is about what you can manage while still meeting your household’s needs. Keep that difference in mind when weighing a possible loan amount against your real-life budget.

How income, expenses and existing debt fit together

Start with your take-home income, then list regular costs using recent bank statements or bills to keep your estimates grounded. Include essentials such as housing, food, utilities and transport, along with less frequent expenses that still recur. Don’t trim essential spending on paper just to make a mortgage look affordable. Give an accurate account of your financial commitments.

Existing personal loans, credit card repayments and other borrowing can reduce the income available for a home loan. For example, two households with similar take-home pay may have different repayment room if one has regular debt repayments or higher essential costs. The point isn’t to judge those choices. It’s to give the lender an accurate picture of what your budget can carry.

Why a lender may test repayments at a higher rate

A serviceability stress test checks whether repayments might still be manageable if interest rates were higher. It’s an assessment tool, not necessarily the interest rate you’ll pay. As reported by interest.co.nz and NZ Adviser in October 2026, major banks were using test rates ranging from 6.85% to 7.10%. Lender methods and settings can change, so those figures are a snapshot, not a promise of how a future application will be assessed.

This higher-rate check can affect how much a lender considers affordable, even if the actual rate offered is lower. If you’re looking at a low-deposit first-home option, the Kāinga Ora First Home Loan scheme still involves an affordability assessment by a participating lender. A small deposit doesn’t remove the need to show that repayments fit your circumstances.

To explore how a fixed interest rate or a different loan structure could affect repayments over time, see the Mortgage Rates NZ guide. Compare more than the headline rate: consider the repayment pattern, flexibility and how each option fits your plans. If you’re unsure how a lender may assess your budget, talk through your home-loan options with an adviser who can help organise your financial picture and discuss lender fit.

Which mortgage pathways may suit a lower-income borrower?

There isn’t one lending route that suits every household. Mainstream banks and alternative lenders may assess applications differently, while a first-home loan option has its own eligibility requirements and still depends on a participating lender’s assessment. The useful question isn’t simply which pathway may lend more. It’s which one could fit your budget and plans without leaving repayments uncomfortably tight.

For eligible first-home buyers, the Kāinga Ora First Home Loan may allow a deposit as low as 5%. That deposit level isn’t a promise of approval. You still need to meet current scheme criteria, and the participating lender assesses whether the loan is affordable for you. Check the current requirements before relying on scheme details, as criteria can change.

Pathway What to consider
Mainstream lender How its assessment fits your income, commitments, deposit and property plans.
Alternative lender Whether its different assessment approach suits your circumstances, and whether the repayments and terms remain manageable.
Kāinga Ora First Home Loan Whether you meet the current scheme criteria, and whether a participating lender considers the loan affordable.

When a mainstream lender may not be the only route

A decline from one bank is a decision on that application, not necessarily a final answer from every lender. Policies and assessment approaches differ, so another lending channel may view your circumstances differently. That doesn’t mean it will approve the application or that it will be the right fit.

An adviser can help organise your information, understand your goals and present your circumstances to suitable lending channels. If you’re weighing up a second-tier option, the 2nd Tier Lender New Zealand guide can give you more context about this type of lending. Treat alternative lending as a pathway to assess carefully, not a shortcut around affordability.

How to weigh flexibility against repayment comfort

Compare the whole loan, not just the headline interest rate. Consider how repayments are structured, what flexibility is available if your circumstances change, and whether the loan supports your longer-term plans. A feature that looks helpful may matter less than repayments that reliably fit your household budget.

To make the comparison practical, write down what matters most: predictable repayments, room in your budget for changing expenses, or flexibility to adjust the loan later. Then consider each pathway against those priorities. The right fit is personal, and an option that works for one borrower may not suit another.

If you’re weighing up how to get a mortgage with low income nz, focus on matching the lender and loan structure to your circumstances, rather than chasing the largest possible offer. A careful comparison can help you explore a fair go while keeping repayment comfort front and centre.

How to Get a Mortgage on a Low Income in NZ in 2026

How to prepare a stronger mortgage application on a lower income

A well-organised application helps show a lender how your finances work in practice. You don’t need to make your budget look perfect. Give a clear, consistent account of your income, spending and commitments, then explore lending options that fit your circumstances.

Build a clear picture of your household budget

Start with a simple household budget. List your take-home income, essential spending, regular commitments and what remains for possible mortgage repayments. Include costs that don’t happen every week or month, so your estimate reflects normal life rather than an unusually quiet period.

Next, consider whether a possible repayment would leave enough room for everyday needs and unexpected changes. If the budget only works when nothing goes wrong, that’s useful to know before applying. A realistic figure gives you a better starting point for discussing a loan size and structure that may suit you.

You can use the Mortgage Suite mortgage calculator to explore how changing the loan amount, repayment frequency or term affects estimated repayments. Treat the result as an initial guide, not an approval or a substitute for a lender’s assessment. Try a few scenarios and compare them with the budget you’ve written down.

Get your application details organised before applying

Gather clear records of your income, employment and existing financial commitments. Lenders may ask for different information, so check the current requirements for the pathway being considered before you apply. Keeping your details together can make it easier to answer questions accurately and avoid gaps in your application.

If your income has changed or varies over time, explain that plainly. Note what changed and how your current income is earned, then make sure the information you provide is consistent across your application. Don’t leave an unusual item unexplained or omit a commitment to make the figures look better. Clear context helps a lender understand the financial picture you’re presenting.

Use your preparation to discuss suitable lending pathways

Once your budget and financial details are organised, you can have a more focused discussion about which lending channels may fit. Share what matters to you, such as keeping repayments manageable or having room in your budget if circumstances change. A mortgage adviser can organise the information and present your circumstances to lenders, while explaining that an application still needs to meet the lender’s criteria.

Preparing this way can make the next steps in how to get a mortgage with low income nz feel more manageable. It also helps you compare a possible offer with your own budget, rather than relying on the largest amount a lender might consider. Talk through your home loan options with Mortgage Suite and use your figures to guide a conversation about suitable pathways.

How Mortgage Suite can help you explore a mortgage on a low income

A home loan decision involves more than working out a possible borrowing amount. An adviser can first understand what you want to achieve, how your income is earned and which commitments shape your household budget. From there, Mortgage Suite can help you consider mainstream or alternative lending channels, including second-tier lending for borrowers who don’t fit mainstream bank criteria, and identify questions to resolve before taking the next step.

Mortgage Suite helps organise your application and represent your circumstances clearly when discussing options with lenders. The focus is on finding a suitable fit for your goals and budget, not pushing you towards a particular loan. Each lender makes its own assessment, so no outcome can be promised.

What to expect from an initial conversation

You can talk through your income, regular commitments, plans for a home and what you hope a mortgage will make possible. If you’ve already spoken with a lender, share what you learned and what remains unclear. This gives the adviser a practical starting point for identifying questions, organising relevant details and considering possible pathways, without treating the conversation as a promise of approval.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to this work. That background informs the firm’s approach to understanding borrowers’ circumstances and discussing lender fit.

Take the next step without feeling pressured

You don’t need to arrive with a perfect application or a definite borrowing target. Bring the information you have and use the discussion to clarify what you can prepare next. It’s also a chance to talk about what feels manageable for your household and which questions matter most before making a decision.

If you’re considering how to get a mortgage with low income nz, a calm, informed conversation can help turn uncertainty into a practical next step. Talk with Mortgage Suite about your home-loan options when you’re ready to explore what may fit.

Take your next step with a clear plan

A home-buying plan doesn’t have to start with a final borrowing figure. Start by deciding what repayment would leave your household feeling steady, then use that as a guide when considering properties and loan options. If your income or commitments change, revisit the plan before making a major decision.

Working out how to get a mortgage with low income nz is less about finding a one-size-fits-all rule and more about understanding the options for your circumstances. A conversation can help you identify what to clarify, which questions to ask and what a sensible next step might look like. You don’t need to have everything perfectly sorted before you begin.

Mortgage Suite can help you consider your goals and discuss possible lending pathways without treating approval as a given. Talk through your home loan options with Mortgage Suite and take the next step at a pace that feels right for you. With a clearer plan, you can move forward with more confidence and give your home-buying goals a fair go.

Frequently Asked Questions

Can I get a mortgage in NZ if I earn close to the minimum wage?

Possibly, but your pay alone can’t show whether a mortgage will fit your circumstances. Before approaching a lender, work out what your household regularly spends and what remains after essentials and existing commitments. There isn’t a set income threshold that guarantees an outcome. This practical budget can help you discuss how to get a mortgage with low income nz without assuming a particular borrowing amount is within reach.

Can I apply for a mortgage if my income changes from week to week?

You can discuss an application, but be ready to explain how your income varies and how you earn it. Keep a clear record over time so the pattern is easy to understand, including quieter and busier periods if that reflects your work. Lenders may assess changing income in different ways, and no single history or rule applies to every case. Share accurate details before settling on a lending pathway.

Can a partner or family member apply for a mortgage with me?

Yes, you can explore applying together. A lender will consider each applicant’s income, commitments and circumstances, so discuss everyone’s finances openly before starting. Shared borrowing also brings shared responsibility: joint and several liability means each borrower may be responsible for the whole shared debt, not only an agreed personal share. Make sure you understand how repayments will be handled and what you’d do if one person’s circumstances changed.

Does a low income mean I will have to pay a higher interest rate?

Not automatically. Income alone doesn’t determine the interest rate a lender may offer. Its decision can reflect your overall application and the loan structure being considered. As you compare options, look at the repayment pattern and any flexibility alongside the rate, then consider whether the arrangement supports your longer-term plans. A rate that looks appealing on its own may not be the best fit if the wider loan terms don’t suit your needs.

Will a mortgage calculator tell me whether a lender will approve me?

No. A calculator can’t weigh lender-specific criteria, the property being considered or all the details of your application. Use the Mortgage Suite Mortgage Calculator to explore possible repayments, then check that the figures you enter reflect the loan scenario you’re considering. The result can help you prepare questions for a lender or adviser, but it can’t confirm that a particular loan will be approved.

Does a declined mortgage application mean I cannot borrow from another lender?

Not necessarily. Before taking another step, ask the lender to explain the main reasons for its decision and whether any information was unclear or missing. Check that you understand what would need to change before another application is considered. This can help you decide whether to update your information, wait or discuss your circumstances with an adviser. Avoid applying again until you have a clearer plan, as another lender will make its own assessment.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.