
Conquer Your Fear of Buying a House in 2026
Entering the New Zealand property market in 2026 does not require guessing the absolute bottom of the interest rate cycle. Securing a competitive fixed interest rate and passing a lender’s serviceability stress test are far more critical to long-term affordability than timing month-to-month price fluctuations. Working with Mortgage Suite gives you a supportive advocate to get sorted and find the right path forward.
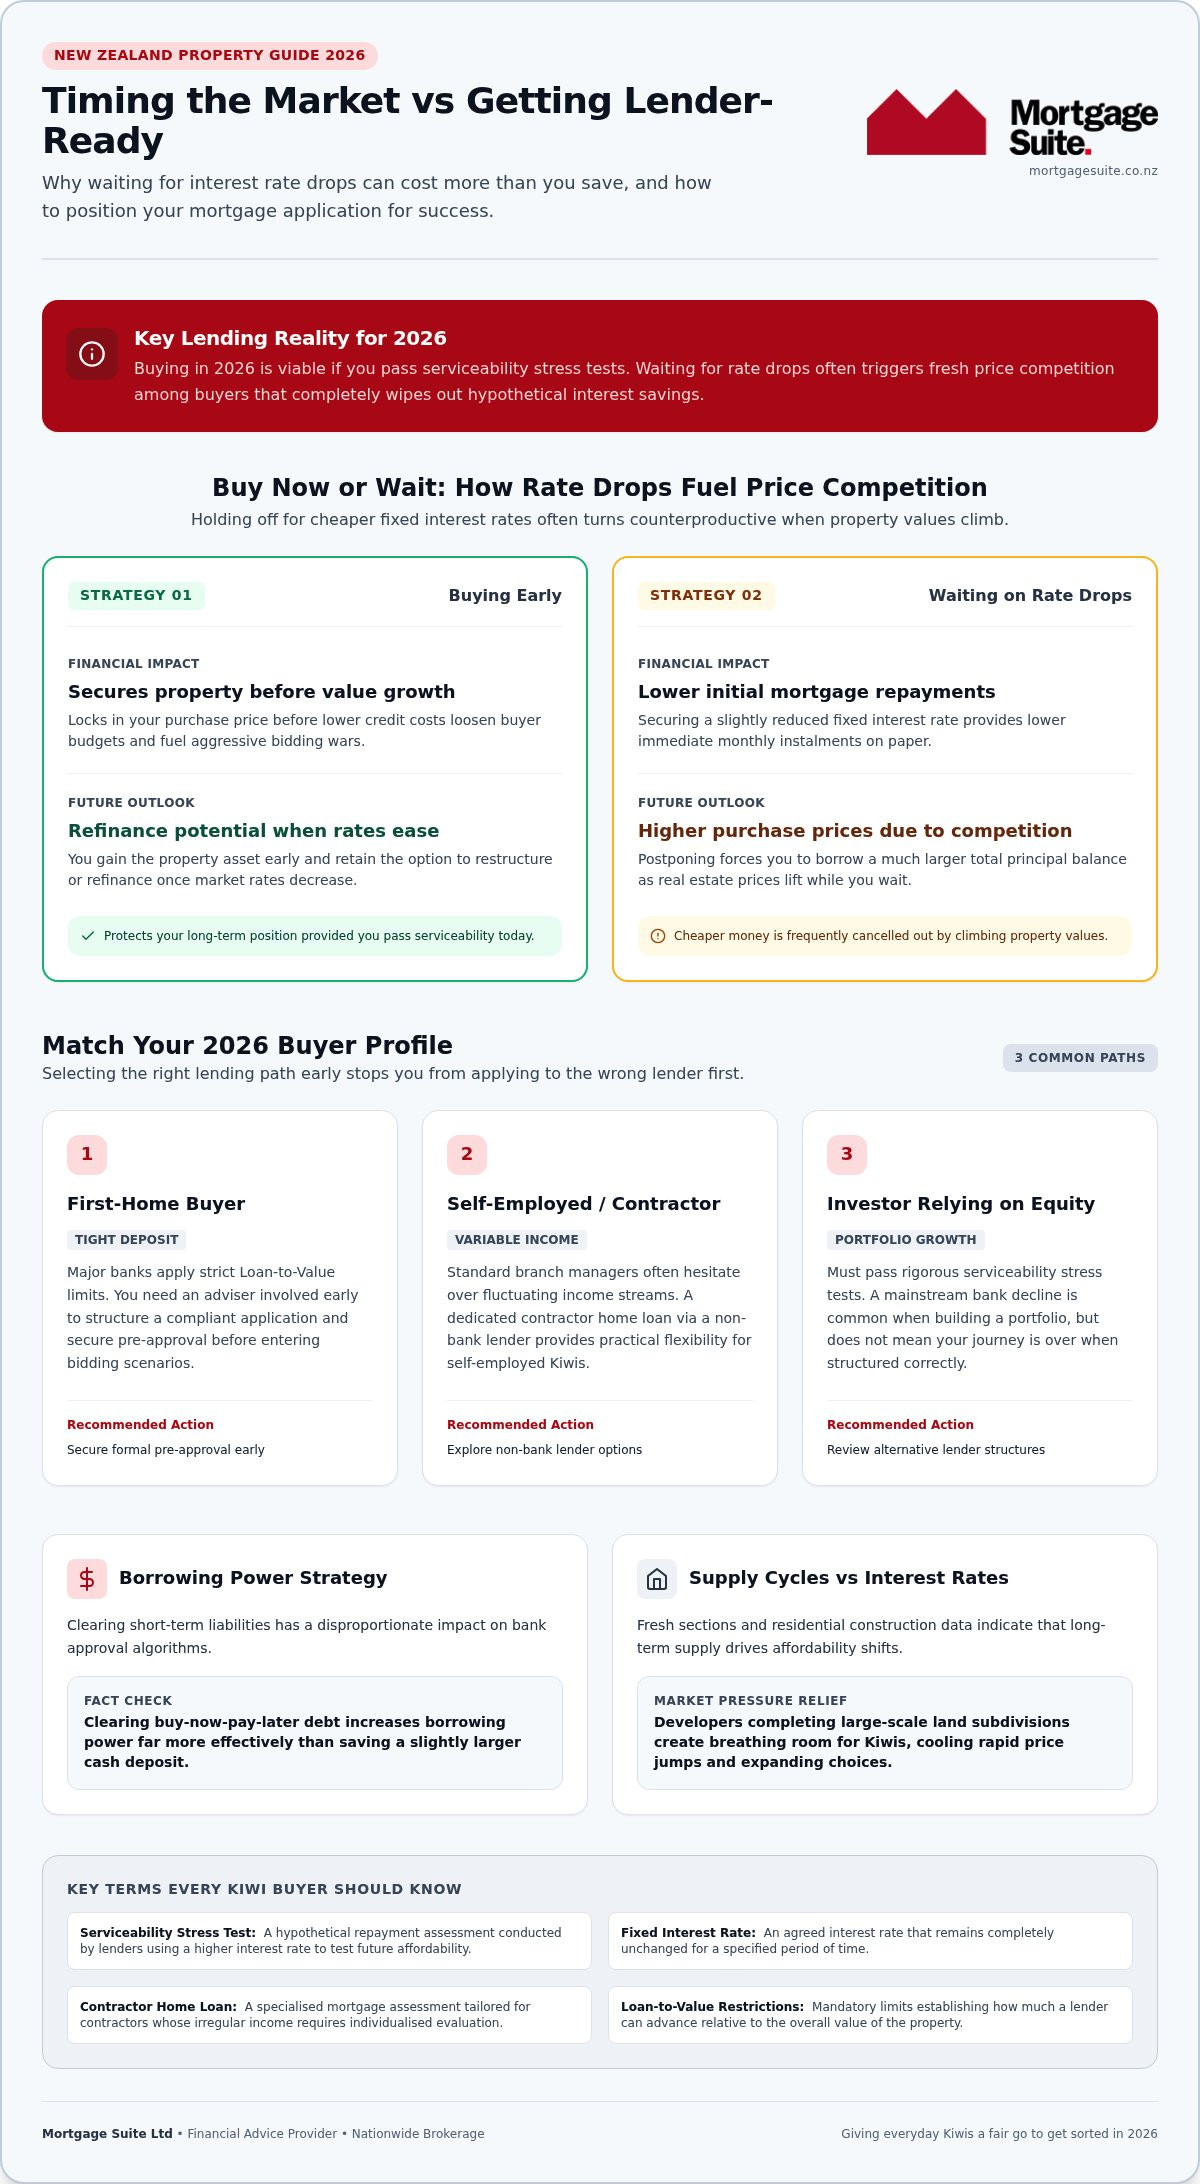
Key Takeaways: Buying in 2026 is viable if you pass serviceability stress tests, as waiting for rate drops often triggers price competition that offsets interest savings.
- U.S. Census construction data indicates supply cycles influence affordability more than short-term interest rate fluctuations.
- Delaying purchase is only recommended if your current budget cannot comfortably pass a lender’s hypothetical higher-rate serviceability test.
- The article details how clearing buy-now-pay-later debt increases borrowing power more effectively than saving a slightly larger deposit.
Match Your 2026 Buyer Profile to the Right Mortgage Path
Your financial situation dictates your property strategy in 2026, and naming your profile early stops you from applying to the wrong lender first. Buyers we work with usually sit in one of three paths; pick the one that sounds like your week-to-week reality and act on the matching step:
- First-home buyer with a tight deposit: major banks apply strict Loan-to-Value limits, so get an adviser involved early and secure pre-approval before you bid.
- Self-employed borrower or contractor: variable income often slows standard bank managers; a contractor home loan through a non-bank lender gives you practical flexibility.
- Investor relying on equity: you must pass a strict serviceability stress test before you purchase; a mainstream bank decline is common and does not end the journey.
Working with an adviser gives everyday Kiwis a fair go to get sorted without taking unnecessary risk. You can explore buying options with guidance matched to your profile.
Our team acts as your dedicated negotiator and pairs your situation with the right lender. Book a free chat when you want that match made clear.
Waiting on 2026 Rate Cuts Can Cost You More Than You Save
Holding out for a cheaper fixed interest rate sounds tidy on paper, yet timing the full interest-rate cycle remains difficult for property buyers, and the wait often costs more than the repayment saving.
Through daily advisory work we see cheaper money get offset by climbing property values. Holding off for lower fixed interest rates (an interest rate that remains unchanged for an agreed period) turns counterproductive when market appreciation outpaces what you save on repayments. Supply metrics shape those broader shifts; U.S. Census construction data shows how residential building trends track changing economic supply cycles globally, a pattern worth watching even from New Zealand.
First-time purchasers who need budget certainty may still prefer to delay until their own figures line up. Investors chasing capital growth often secure a place earlier, because delay means missing potential gain while bank decisions drag. Mainstream bank hurdles do not mean you cannot move forward.
We act as your dedicated personal advocate and structure finance that keeps your options flexible. Get sorted on buying in NZ with a plan built around today’s serviceability numbers rather than a guessed future rate. Map your next steps in a friendly chat with the team when you are ready.
Buy Now or Wait: How Rate Drops Fuel Price Competition
Timing the market to the week is nearly impossible, and waiting for interest rates to drop carries hidden financial risk you feel only after prices have already moved.
Buyers who freeze their search often watch real estate prices jump as soon as credit terms loosen. When interest rates fall, buyer competition heats up, sale figures rise, and the mortgage saving you hoped for gets erased. Purchasing now lets you secure a property before that spike, provided your budget comfortably passes a serviceability stress test (a hypothetical repayment assessment using a higher interest rate to test future affordability).
Postponing a deal for a lower rate can force you into a much larger total mortgage if home prices lift while you wait.
| Market Strategy | Financial Impact | Future Outlook |
|---|---|---|
| Buying early | Secures property before value growth | Refinance potential when rates ease |
| Waiting for rate drops | Lower initial mortgage repayments | Higher purchase prices due to buyer competition |
If you are navigating the decision on your own, solo buying guidance sets out clear borrowing options. Getting your finance sorted early means you can act when the right place appears. Reach out when you want a dedicated negotiator in your corner.
Fresh Home Building Eases Price Pressure for Kiwi Buyers
New supply is one of the few forces that genuinely eases long-term price pressure, and you feel it first as wider choice rather than as a headline rate cut.
From client work we see buyers gain breathing room when developers finish large-scale land subdivisions. Fresh sections give Kiwis a fair go by broadening choices and cooling aggressive bidding wars. Picture a busy restaurant: when extra tables open, nobody needs to tip the host just to get seated. Sustained inventory growth tends to slow rapid cost increases over time, though that supply still takes seasons to arrive.
More builds also ease rents as tenants move into new stock, which can help you save a deposit faster. If you hold commercial assets, this commercial refinancing guide sets out ways to free capital for a residential move.
When your bank manager seems hesitant, alternative lenders offer clear paths. Newly built homes suit first-home hunters who want modern insulation; existing builds suit buyers who need immediate possession. Talk to Mortgage Suite when you want those options laid out against your deposit and income.
When Delaying Property Purchase Works Against You
Sitting on the sidelines in 2026 can cost you more than time, because the market keeps moving while your deposit sits still.
In client work we see buyers waiting for lower interest rates get caught off guard as property values lift. Holding off backfires when underlying forces keep pushing even though you have not signed a thing.
Think of standing beside a moving escalator: demographic demand keeps climbing. Population growth and changing household structures mean more people compete for a finite number of homes. At the same time, the mortgage lock-in effect keeps current owners from selling. Existing owners hold older, low-rate loans, which thins listings across New Zealand. Lower supply plus steady population growth puts upward pressure on prices.
Buying sooner lets you start building equity while you secure the home you will live in. Mainstream banks may seem hesitant today, yet an initial decline is not the end of your journey. Mortgage Suite acts as your personal advocate and negotiates flexible lending that fits your goals. Ask for a chat when you want that path scoped properly.
5 Steps That Make Your 2026 Mortgage Application Lender-Ready
Getting your finances audit-ready now changes how lenders read your file in 2026. Early preparation turns a tense bank meeting into a straightforward approval conversation and helps mainstream lenders see you as lower risk.
Clearing small buy-now-pay-later balances can lift your borrowing power more than saving a modest extra deposit, because serviceability looks at monthly outgoings first.
Follow these steps to get sorted:
- Clean up short-term debt: Pay off personal loans and store cards to lower your monthly outgoings.
- Review your spending: Track daily expenses for three months to prove strong money management habits.
- Test your budget: Practice making repayments under a hypothetical serviceability stress test to check affordability.
- Gather account records: Collect certified accounts and recent bank statements to show stable earnings.
- Consult an adviser: Partner with Mortgage Suite to negotiate tailored terms across multiple bank options.
Tip: Getting your mortgage pre-approval sorted early ensures you understand your true borrowing capacity under current serviceability stress test standards.
Long-term confidence comes from having an experienced guide in your corner. One Google review of Mortgage Suite Ltd from Baycom (5★) shows the arc clearly: a household bought five properties over more than twenty years with the same broker, through purchases, and ongoing advice, and still recommends the firm.
"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"
That span of successful property work is what a steady adviser relationship can look like when you stay organised.
4 Loan Structures That Cut Your Interest Without Waiting on the Market
Smart loan structuring gives you direct control over interest charges without waiting for the wider market to move. Choosing an offset account trims daily interest by matching your cash balance against the mortgage, keeps funds accessible for unexpected costs, and lowers the interest you pay over time.
A fixed interest rate protects your household budget by locking exact repayment amounts for a set timeframe. Splitting the loan between fixed and floating portions adds flexibility, so you can clear extra debt quickly without early-repayment penalties.
Lenders also run a serviceability stress test to check your position at higher hypothetical rates. Passing that test often means cleaning up short-term debts or adjusting credit limits first.
Structuring finance is a balancing act around your real cashflow. Mortgage Suite acts as your dedicated negotiator and secures options that fit how you actually earn and spend. If you worry that restructuring will swallow your week, the team manages the process so you can get sorted without the run-around. Tell us your goals and we will walk the numbers with you.
Frequently Asked Questions
Why are home prices so high?
Strict land use rules, high building material costs, and strong population growth keep housing supply tight across New Zealand. Long-term supply shortages mean property values stay elevated even when interest rates move up or down.
Will mortgage rates drop in 2026 or 2027?
Wholesale interest rates point to possible easing, yet fixed interest rate changes depend on inflation and central bank policy. Lenders reprice as economic conditions shift, so treat any forecast as a guide rather than a promise.
Is now a good time to buy a house?
Buying works well when your household budget is stable and you secure structured financing that fits your goals. You move faster by focusing on long-term affordability rather than trying to pick the exact month rates bottom out.
Will mortgage rates drop in 2026?
Economic forecasters expect borrowing costs to stabilise, though sudden market shifts can still alter the path. A clear view of your own financial position helps you manage whatever rate movement arrives.
Is it better to buy a home now or wait for lower rates?
Waiting for lower rates can mean heavier buyer competition later, which often pushes purchase prices up. Securing a fair go now with a flexible loan structure gives you confidence whether rates ease or hold.
Overcoming the fear of buying a house in 2026
Feeling nervous about home ownership right now is normal. Strict bank tests and changing deposit rules make the path feel heavier than it needs to be, especially when headlines keep arguing about the perfect month to jump.
You do not have to handle the banks on your own. The same through-line that opened this guide still holds: a competitive fixed rate and a clean pass on the serviceability stress test matter more than calling the bottom of the cycle, and a dedicated advocate keeps those two pieces in view. The team at Mortgage Suite Ltd negotiates directly with main banks and non-bank lenders to give you a fair go. A simple decline from one mainstream lender does not mean your home-ownership plan is over.
Ready for the next step? Get sorted with your 2026 home buyer pre-approval today by booking a friendly, no-obligation chat with our mortgage advisers. More on this: Buying a House Archives.