Hidden Costs of Buying a House in NZ: Your 2026 Guide
Saving your deposit is often the straightforward part of purchasing property; the real surprise tends to arrive in the final weeks before settlement. Many Kiwis focus entirely on the purchase price, only to feel caught off guard by the hidden costs of buying a house nz that surface during due diligence and contract reviews.
It’s completely natural to worry about running out of cash reserves right when you need them most, especially when you’re trying to decipher legal jargon, council files, and strict lender conditions. You deserve a fair go and total clarity before signing an agreement. In this guide, you will discover every unexpected fee, professional inspection charge, and council cost involved across the buying journey, along with practical ways a dedicated mortgage adviser protects your hard-earned funds.
Here is your clear breakdown of upfront, settlement, and ongoing expenses so you can budget an adequate safety buffer and get sorted with confidence.
Key Takeaways
- Discover why saving your deposit is only the first hurdle, and how budgeting for upfront checks like a building report prevents costly physical surprises.
- Get clear on the hidden costs of buying a house nz, from council LIM applications to legal administration, so you can make an offer with total confidence.
- Understand how lender serviceability stress tests and Loan-to-Value restrictions can trigger specific conditions, including independent property valuations.
- Prepare for settlement day apportionments so you have the cash reserves ready to reimburse the vendor for prepaid council rates and operational fees.
- Learn how establishing an equity safety net and working alongside an accredited Financial Advice Provider keeps your finances protected from the start.
What Are the Hidden Costs of Buying a House in New Zealand?
Hidden purchase expenses are the compulsory third-party professional and administrative charges that surface throughout your property transaction. When buyers secure finance, it’s easy to assume the accumulated deposit covers every requirement. In reality, lenders expect your deposit to remain reserved purely for property equity. This means every auxiliary specialist must be funded from separate savings. Getting a clear view of the hidden costs of buying a house nz ensures your transaction proceeds smoothly from your initial offer through to key handover.
Why Your Purchase Deposit Is Only the Starting Point
Mainstream lending covers the physical asset, not the trail of specialists needed to confirm the purchase. If you commit every available cent toward your down payment, you risk a cash shortfall right when legal documents require execution. You need an unencumbered cash buffer to protect your borrowing position and satisfy standard loan conditions. Crucially, upfront inspection expenses accumulate even on properties you do not end up buying. Walking away after an unsatisfactory report costs money, but it successfully protects you from taking on costly physical defects.
Categorising Pre-Purchase, Settlement, and Post-Settlement Expenses
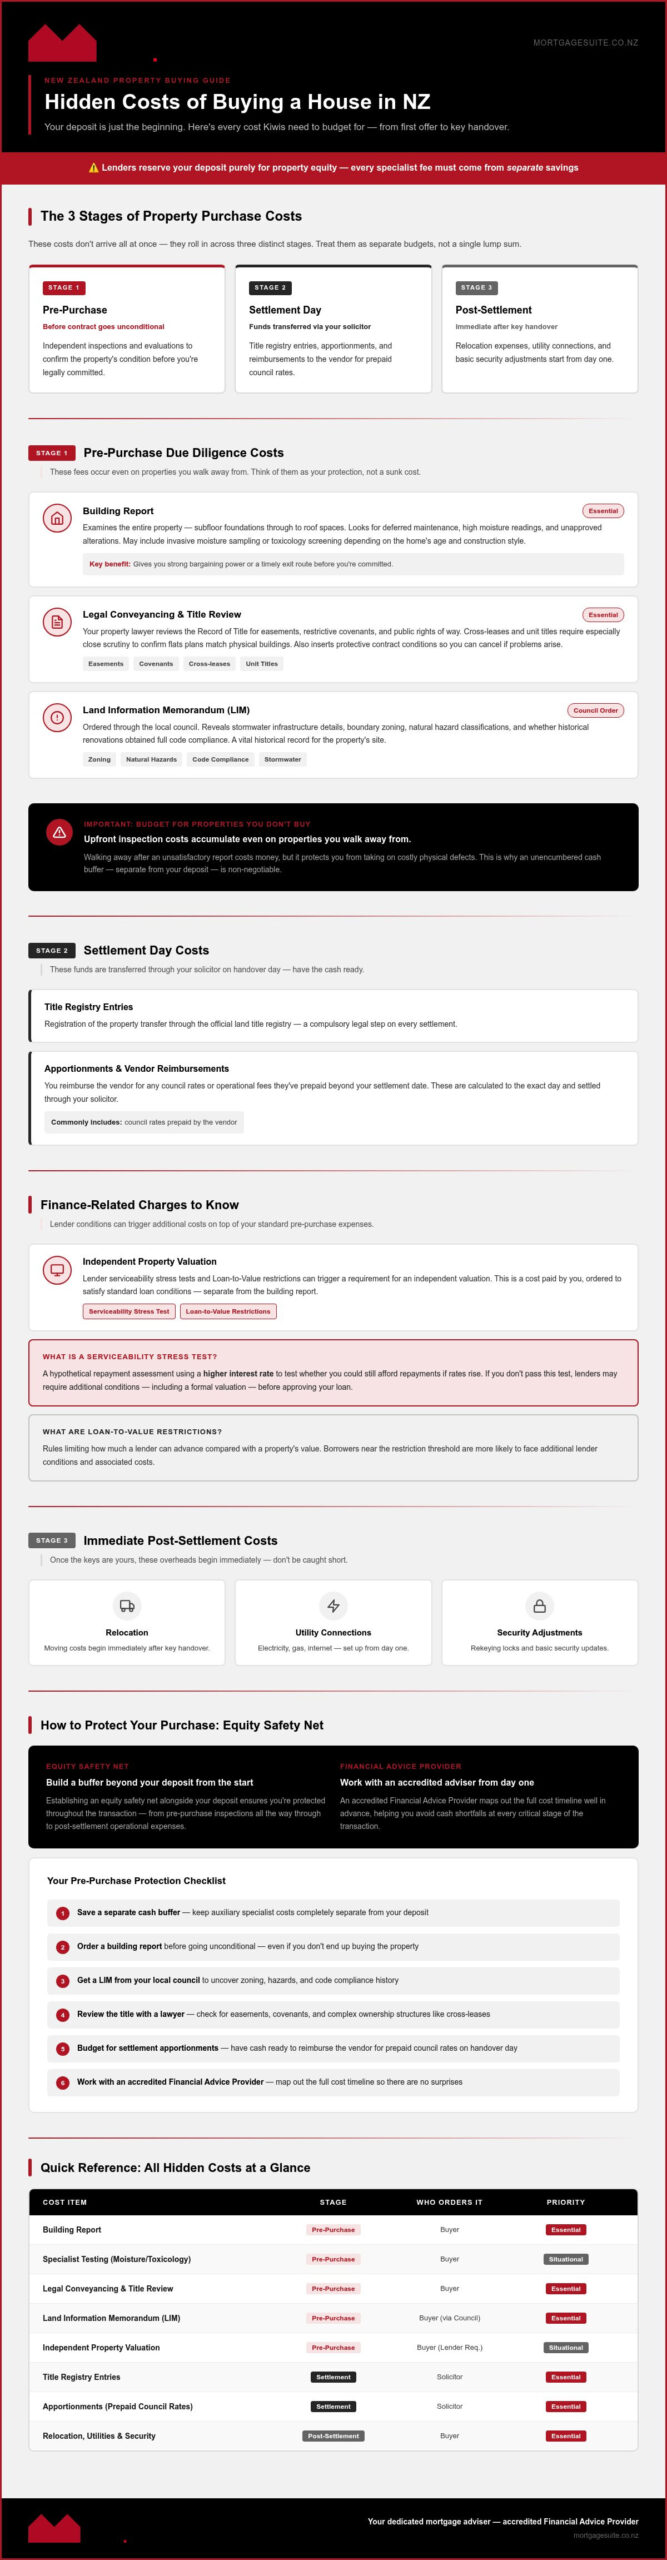
Managing your cash flow becomes much simpler when you divide these overheads into three distinct stages:
- Pre-purchase verification: These outlays happen before a contract becomes unconditional. They cover independent evaluations such as a building report, council records, and title investigations to confirm the property’s condition.
- Settlement transactions: Often grouped under the broader umbrella of closing costs, these represent the funds transferred through your solicitor on handover day. They include title registry entries and apportionments, where you reimburse the vendor for prepaid council rates.
- Immediate operational overheads: Once the keys are yours, standard relocation expenses, utility connections, and basic security adjustments take effect immediately.
A common mistake is treating these stages as a single lump sum rather than a rolling series of invoices. Our team at Mortgage Suite works alongside you to map out this timeline well in advance. Understanding these stages gives Kiwis a fair go at the market, making sure you get sorted without unexpected financial pressure.
Pre-Purchase Due Diligence: Essential Reports and Advisory Fees
Before signing an unconditional sale agreement or bidding under the hammer at an auction, thorough due diligence is non-negotiable. House hunting can become an exhausting process, particularly when you need to investigate several prospective homes before finally securing an offer. These professional evaluations represent necessary hidden costs of buying a house nz, but treating them as an investment in certainty protects you from inheriting expensive structural defects or legal headaches.
Independent Building Report and Specialist Testing
An accredited specialist examines the entire property envelope from subfloor foundations through to roof spaces when completing a building report. Beyond visual checks, inspectors look for deferred maintenance, high moisture readings, and unapproved alterations that could compromise structural integrity. Depending on the construction style and age of the home, targeted testing like invasive moisture sampling or toxicology screenings may also be sensible. Paying for inspections on properties you walk away from feels frustrating, but discovering physical damage early gives you strong bargaining power or a timely exit route.
Legal Conveyancing and Land Title Review
Your property lawyer or conveyancer plays a central role in protecting your legal interests before you commit. They examine the Record of Title to uncover easements, restrictive covenants, and public rights of way that dictate how you can use the section. Complex ownership structures like cross-leases or unit titles demand even closer scrutiny to ensure flats plans match the actual physical buildings. Your legal representative also inserts protective contract conditions around inspection satisfaction, ensuring you retain the power to cancel if unexpected problems arise.
Council Property Files and Land Information Memorandum (LIM)
Ordering a Land Information Memorandum through the local council provides vital historical records regarding storm water infrastructure, boundary zoning, and natural hazard classifications. A LIM also reveals whether historical renovations or additions obtained full code compliance certificates. Unapproved works create friction with mainstream lenders and can lead to costly council enforcement notices. If you are purchasing a subdivided section, your legal team will check that a Statement of Compliance is registered to verify that the developer satisfied every local authority requirement. Taking time to work through the educational resources at Mortgage Suite’s mortgage school helps you understand these legal steps so you can move forward with complete peace of mind.
Finance-Related Charges: Lender Conditions, Valuations, and Loan Structures
Securing conditional finance feels like a major victory, yet the lender’s final approval letter often introduces mandatory out-of-pocket requirements. These administrative checks represent another layer of the hidden costs of buying a house nz that can catch buyers off guard. When evaluating an application, banks run a serviceability stress test using elevated interest rates to confirm long-term affordability. Alongside this, strict Loan-to-Value restrictions dictate how lenders assess property risk, often triggering specific condition clauses before they release funds.
Registered Property Valuations Required by Lenders
Council rating valuations exist purely for local taxation and fail to reflect true open-market equity. If you purchase through a private treaty, buy at auction, or apply with a smaller deposit, your lender will likely require an independent registered valuation. Borrowers cannot simply select any valuer from the phone book. Mainstream banks insist on ordering reports via designated independent valuation panels to avoid bias, and the borrower pays the inspection fee directly.
Low Equity Premiums and Lender Assessment Charges
Purchasing with less than a twenty percent deposit introduces additional lending expenses. Lenders offset this higher lending risk by applying a low equity margin or an upfront premium. This charge may be applied as an ongoing interest rate loading or added directly to the total borrowing balance. Complex borrowing scenarios, such as applications with non-standard income structures, can also incur specialised administration fees. Having a dedicated mortgage adviser negotiate these terms helps keep conditional charges manageable.
Alternative Lending and 2nd Tier Finance Solutions
A decline from a traditional bank does not mean your purchasing plans are finished. Specialist non-bank lenders offer practical lending structures for self-employed workers, contractors, and borrowers recovering from past credit blips who deserve a fair go. While non-bank institutions may charge modest establishment fees to accommodate unique situations, they provide immediate access to property ownership. Once you build sufficient equity and trade reliably, your adviser can help you refinance back to a mainstream bank. Reviewing dedicated home loans for first home buyers New Zealand gives you a clear strategy to secure competitive funding without second-guessing your loan setup.
Settlement Day Realities: Apportionments, Adjustments, and Operational Expenses
Settlement day marks the official transfer of ownership, but it also brings financial reconciliations that many buyers overlook. Alongside the loan drawdown, your legal team receives a settlement statement detailing apportionments. These adjustments ensure the seller is reimbursed for any statutory liabilities paid in advance. When planning your property purchase, factoring in these final reconciliations protects you from unexpected cash demands during the final handover.
Local Council Rates and Water Apportionment Calculations
Local authorities bill property rates on set cycles throughout the year. If the current owner has prepaid rates past your handover date, your conveyancer must credit the difference back to them on settlement day. The same rule applies to regional environmental levies and metered utility accounts. A special water meter reading is taken just prior to completion, ensuring each party pays strictly for their usage up to the exact transfer minute.
Body Corporate Levies and Sinking Fund Adjustments
Purchasing a unit-title property or an apartment introduces additional shared financial commitments. Buyers must take over the vendor’s forward share of operational levies, shared building upkeep, and established sinking funds. Sinking funds represent long-term reserves set aside for major capital improvements across the development. Lenders also scrutinise these spaces closely under the Small Apartment Rule, which assesses smaller floor plans under stricter risk margins. Making sure these shared accounts are fully funded prevents surprise special levies shortly after you collect your keys.
Physical Relocation and Immediate Service Connections
Taking possession of an empty house triggers several immediate operational expenses:
- Moving logistics: Professional moving vehicles, heavy lifting hire, or short-term storage facilities.
- Security updates: Changing exterior locks and re-keying doors to ensure complete privacy.
- Utility provisioning: Telecom fibre setup fees, account connection charges, and trade visits.
- Immediate maintenance buffer: An emergency fund for plumbing washers, basic cleaning supplies, and minor repairs.
These adjustments form an unavoidable part of the hidden costs of buying a house nz. You can plan ahead and calculate your baseline monthly outlays using our free mortgage calculator to ensure your ongoing budget remains comfortable.
How to Build an Equity Safety Net and Protect Your Purchase
Establishing a resilient equity safety net is the most effective way to absorb unexpected expenses without draining your emergency savings. Rather than committing every spare cent toward a deposit, holding back liquid funds gives you room to breathe. When you account for the hidden costs of buying a house nz early, you can design a borrowing structure that protects your position right through settlement.
Structuring Your Home Loan with an Offset Account
One practical method for keeping reserves accessible is linking your lending with an offset account. Instead of locking all your surplus cash into a standard term loan, an offset facility balances your everyday savings against your mortgage debt. The lender calculates interest purely on the net difference. Keeping your contingency cash parked in an offset account reduces your ongoing interest obligations every single day, while leaving your funds completely accessible if an unexpected repair or council bill arrives. Balancing this with a fixed interest rate on the majority of your lending provides long-term certainty alongside daily flexibility.
Partnering with an Independent Mortgage Adviser
Securing property finance does not have to be a stressful, solitary process. Working alongside an accredited Financial Advice Provider gives you an experienced negotiator who advocates for your interests rather than the bank’s sales targets. A knowledgeable adviser understands where application fees can be waived, how to negotiate cash contributions toward legal bills, and how to present non-standard income profiles to secure competitive approvals. Reviewing the educational articles developed by Mortgage Suite helps clarify the lending journey, while reading client experiences in our reviews illustrates how tailored advocacy protects your finances at every step.
Practical Steps to Finalise Your Buying Strategy
Before you raise your hand at an auction or submit a tender, run a disciplined check over your total commitments:
- Calculate total upfront cash: Ensure you have separate savings to cover pre-purchase inspections, conveyancing, and council checks before making an offer.
- Protect your offer: Always instruct your solicitor to insert thorough clauses covering building reports, title checks, and finance confirmation.
- Plan for settlement day: Retain liquid funds to settle vendor apportionments for local rates and utilities without stress.
Get sorted with Mortgage Suite to structure a personalised loan solution that protects your cash flow and puts you in control of your property purchase.
Step Confidently into Your Next Property Purchase
Managing the hidden costs of buying a house nz comes down to early preparation and smart financial structuring. When you budget for pre-purchase inspections, factor in settlement day apportionments, and preserve an unencumbered cash buffer, you remove the stress of unexpected shortfalls. Purchasing a home is a major milestone, and having clear visibility over every outlay keeps you in control.
You don’t need to tackle strict lender policies alone. Backed by over 20 years of hands-on banking and negotiation experience across New Zealand, Mortgage Suite acts as your personal advocate through each stage of loan structuring. With direct access to both mainstream banks and accredited 2nd tier non-bank lenders, we ensure every buyer gets a fair go, even when borrowing circumstances are complex.
Get in touch with Mortgage Suite to discuss your home loan options and get sorted. With genuine guidance and the right lending structure behind you, taking your next step onto the property ladder becomes an exciting, confident reality.
Frequently Asked Questions
What are the most overlooked hidden costs when purchasing a house in New Zealand?
The most overlooked expenses are pre-purchase reports on properties you don’t buy, council rates apportionments, and bank panel valuations. Many buyers expect their deposit to cover everything, but third-party outlays must be paid in cash before settlement. These represent classic examples of the hidden costs of buying a house nz, along with conveyancing disbursements, moving services, and immediate utility connection fees that arise right around move-in day.
Can hidden buying costs be included directly in my home loan balance?
No, lenders generally do not allow you to roll upfront due diligence or administrative charges into your mortgage borrowing. Banks require your deposit to serve strictly as security equity against the purchase price. Expenses like building inspections, council LIM requests, and legal representation must come from unencumbered personal savings, which is why preserving an independent cash buffer is so vital throughout the purchasing process.
Why do lenders require a registered valuation when buying a property?
Lenders demand an independent registered valuation to verify the property’s true market equity before issuing unconditional finance approval. This requirement usually happens if you’re buying with a low deposit, purchasing through a private treaty, or acquiring an unconventional home. Lenders rely on their approved panel valuers rather than standard council ratings to ensure the purchase price aligns with current market risks and prudent lending margins.
What happens if a building report uncovers major unconsented work before settlement?
Uncovering unconsented work gives you legal options to negotiate repairs, request a price reduction, or exit the deal if your contract includes an inspection condition. Your solicitor reviews the findings against council files to determine liability. Lenders may also withhold final finance if unapproved structural changes pose a security risk, allowing you to walk away safely before your agreement turns unconditional.
How do local council rates get adjusted between the buyer and the seller?
Council rates are apportioned on settlement day based on the exact date legal ownership changes hands. The vendor pays rates up to the handover day, and the buyer reimburses them for any days already prepaid beyond that point. Your conveyancer calculates these daily apportionments on the settlement statement, requiring you to have clear funds ready to complete the balance handover smoothly.
What financial options exist if a mainstream bank declines my home loan application?
A mainstream bank decline is not the end of your property ownership journey, as 2nd tier non-bank lenders offer practical alternative pathways. These specialised financial institutions assess unique circumstances, such as contractor roles or non-traditional earnings, with greater flexibility. An experienced adviser can match your profile with an accredited alternative lender, providing finance now while helping you build a clear strategy to refinance later.
How does working with a mortgage adviser help manage unexpected purchase expenses?
A mortgage adviser reviews your complete financial picture to identify the hidden costs of buying a house nz well before you make an offer. By negotiating lender fee waivers, structuring flexible offset accounts, and securing bank cash contributions toward your legal expenses, your adviser helps keep out-of-pocket costs down. This personal advocacy ensures you navigate complex lender conditions without facing unexpected cash shortfalls.