Commercial Property Mortgage Rates: 2026 Aussie Guide
A higher quote isn’t always the only option. Commercial property mortgage rates are usually built around a base rate plus a lender’s margin, and the final offer can depend on the property, your business’s financial position and how you plan to repay the loan.
It’s understandable to compare a commercial loan with a home loan and wonder why the rate is higher. Commercial lending is assessed differently. A lender’s serviceability stress test can also affect how much you can borrow, particularly if your income or property doesn’t fit its usual criteria. A decline can feel like a dead end, but it doesn’t necessarily mean you’re out of options.
This guide explains what can shape a commercial loan rate, what lenders may look at and how to prepare for a clear conversation about your options. You’ll also learn how to compare loan structures against your business goals and consider lenders beyond mainstream banks. Mortgage Suite Ltd helps borrowers understand their options and negotiate with their interests in mind.
Key Takeaways
- Commercial property mortgage rates depend on the property, your business profile and the lender’s view of risk. Compare the full loan structure, not just the headline rate.
- Understand how a lender’s base rate and margin combine, and how a serviceability stress test may affect your borrowing capacity.
- A decline from a mainstream bank isn’t necessarily the end of the road. 2nd tier lending may offer another path when your property or income falls outside standard criteria.
- A building report can clarify a property’s condition for a lender. An offset account may reduce the loan balance used to calculate interest.
- Mortgage Suite Ltd can help you present your business and property plans clearly and negotiate with lenders around a deal that suits your needs.
What Determines Commercial Property Mortgage Rates in 2026?
Commercial property mortgage rates are often higher than residential rates because the lending risks differ. A home may appeal to a broad pool of buyers, while a warehouse or specialised premises can take longer to sell if a lender needs to recover its money. Lenders also assess the property alongside the business using it. A commercial mortgage is secured against commercial property, but its rate and terms depend on the details of the deal.
The Reserve Bank of New Zealand’s Official Cash Rate (OCR) can influence the wider cost of lending. It is the rate the Reserve Bank charges registered banks for overnight lending, and changes can flow through to banks’ funding and lending decisions. On 2 September 2026, the Reserve Bank increased the OCR to 2.75%. This is a market-wide influence, not a direct quote for your loan. Lenders still assess the borrower, property and loan structure before setting terms.
Your industry and trading pattern can also affect how a lender views the application. Steady trading and predictable demand may present a different picture from seasonal income or an uncertain outlook. No sector automatically receives a better rate. Lenders consider whether the business can support repayments and whether the premises could suit another use if the business moves on.
Commercial vs. Residential: Why the Gap?
Homes generally have a wider pool of potential buyers than specialised commercial buildings, which can make them easier to sell. That difference in how quickly a property might be sold can affect a lender’s view of risk. Loan-to-Value restrictions may also be tighter for commercial assets, limiting how much a lender will advance against the property’s value. Lease terms matter too: a long, reliable lease can give lenders greater confidence in rental income than a short lease or a vacant building.
The 2026 Economic Outlook for Kiwi Borrowers
New Zealand’s commercial lending market has entered a more stable, balanced phase in 2026, with confidence gradually returning after the slowdown that followed the 2022 peak. Inflation and Reserve Bank policy still shape lenders’ funding conditions and appetite for risk. A changing OCR can influence the wider lending environment without setting every borrower’s rate.
For small and medium-sized businesses, a fixed interest rate can make repayments more predictable for an agreed period. The trade-off is that the loan’s flexibility and timing still need to fit your plans. Compare the certainty a fixed rate offers with other available structures, and consider the property, lease and business income together rather than judging a deal by its headline rate alone.
How Lenders Build Your Custom Interest Rate
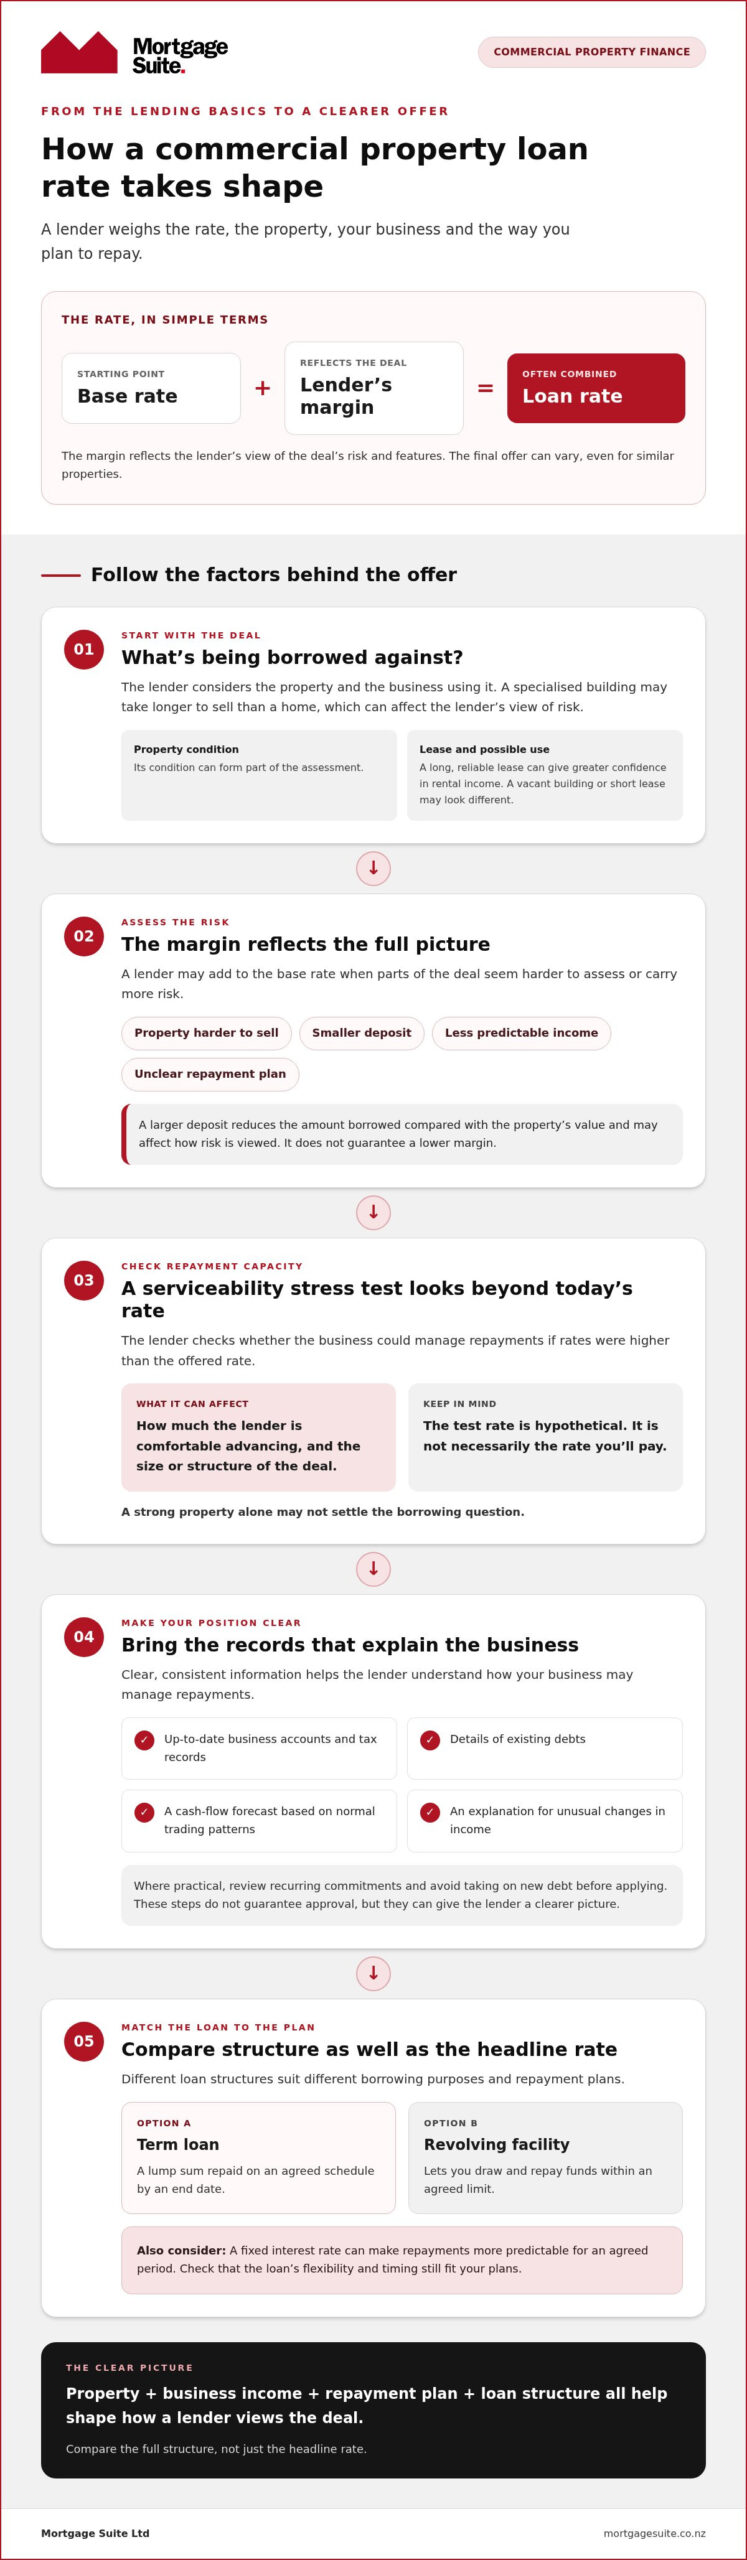
A commercial loan rate often has two parts: a base rate and a margin. The base rate is the starting point, while the margin reflects the lender’s assessment of the risk and features of your deal. That’s why commercial property mortgage rates can differ between borrowers seeking finance for similar properties.
A lender may consider the property’s condition, how much you’re borrowing compared with its value, the strength of your business income and your repayment plan. A larger deposit reduces the amount borrowed relative to the property’s value, which may affect how the lender views the risk. It doesn’t guarantee a lower margin, because the full application still matters.
Your business history helps explain how you’ll manage repayments. Consistent trading, clear accounts and a realistic repayment plan can support a lender’s understanding of your position. If income varies, explain what drives the changes and provide records that show how the business has performed over time.
Understanding the Risk Margin
A lender may add to the base rate if the security is harder to sell, the deposit is smaller, income is less predictable or the repayment plan is uncertain. With joint and several liability, each borrower can be responsible for the entire shared debt, not just a set share. Every borrower should understand that responsibility before agreeing to a shared loan.
The loan structure matters too. A term loan is a lump sum repaid on an agreed schedule by an end date. A revolving facility lets a borrower draw and repay funds within an agreed limit. These structures work differently, so consider which one fits the purpose of the borrowing and how you expect to repay it.
The Serviceability Stress Test Explained
A serviceability stress test checks whether the business could manage repayments if rates were higher than the offered rate. The test rate is hypothetical, not necessarily the rate you’ll pay. The result can limit the amount a lender is comfortable advancing and affect the size or structure of the deal. A strong property alone may not settle the borrowing question.
Make your position easier to assess. Prepare up-to-date business accounts, tax records, details of existing debts and a cash-flow forecast that reflects normal trading patterns. Present income and liabilities consistently, and explain unusual changes rather than leaving the lender to guess. Where practical, review recurring commitments and avoid taking on new debt before applying. These steps don’t guarantee approval, but they can give the lender a clearer picture of your capacity.
If the figures are difficult to present or the lender’s assessment is hard to interpret, Mortgage Suite Ltd’s commercial finance team can help you understand what’s shaping the offer and put your position forward.
Mainstream Banks vs. 2nd Tier Lenders: Finding a Fair Go
A decline from a mainstream bank can feel personal, especially after you’ve spent time preparing an application. Often, though, it reflects that lender’s criteria and appetite for particular properties, income patterns or loan structures. Another lender may assess the same deal differently. That doesn’t guarantee approval, but a bank’s answer isn’t a final judgement on your business.
2nd tier lending may be worth exploring if your property or financial situation doesn’t fit standard bank criteria. A specialised commercial building, uneven self-employed income or a time-sensitive purchase may call for a different lending approach. Mortgage Suite Ltd specialises in 2nd tier lending options for borrowers who don’t fit mainstream criteria, helping present the details of the deal clearly.
When to Look Beyond the Big Four
Lenders can assess self-employed income in different ways. One may focus closely on reported profit, while another may consider the wider trading picture and supporting records. Alternative lenders may also consider non-standard property or loan structures, though flexibility varies and the lender still assesses whether repayments are manageable. Interest-only periods may be available in some 2nd tier arrangements, but they aren’t automatic. During such a period, scheduled payments generally don’t reduce the principal, so plan how and when you’ll repay it.
The Trade-off: Rate vs. Flexibility
A flexible structure or a decision that fits your purchase timeline may matter more than the lowest headline rate. Commercial property mortgage rates are only one part of the comparison. Look at the repayment plan, loan term, conditions and what happens when the facility ends. For short-term finance, set out a realistic exit plan, such as selling an asset or refinancing, and consider what you’ll do if that takes longer than expected.
Moving back to a mainstream bank may be possible later if your financial position and deal fit its criteria at that time. You can work towards that by keeping business accounts organised, meeting repayments, reducing debt where practical and tracking changes in income or equity. Before accepting an offer, weigh the rate against the value of the structure to your business. A higher rate may be a reasonable trade-off when the terms address a genuine timing or eligibility challenge, provided the repayments and exit plan remain workable.
Compare offers on the same basis, not just by their headline figures:
- Fit: Does the lender understand the property and your income pattern?
- Structure: Do the repayment terms match your business plans?
- Next step: Is there a practical path to repay or refinance the loan?
A bank decline is stressful, but you can still take a measured next step. Understand the reason for the decision, identify what could strengthen the application and consider whether a different lending approach better fits your goals.
Strategies to Organise a Better Commercial Deal
A well-prepared application helps a lender understand the property, your business and why the finance makes sense. It won’t guarantee approval or a particular rate, but it can reduce uncertainty and make it easier to discuss a structure that fits your plans. Compare commercial property mortgage rates alongside flexibility and repayment terms, not in isolation.
Start with the property. A building report gives a professional assessment of its condition and defects. It can help you understand what you’re buying and give the lender clearer information about the security. If the report identifies issues, explain how you’ve accounted for them in your plans rather than leaving questions unanswered.
Think about cash flow too. If your lending includes an offset account, the balance in that account reduces the loan balance used to calculate interest. Keeping business funds there may help reduce the interest burden, but the benefit depends on the account and loan terms. Compare this with keeping funds available for wages, tax and day-to-day operations.
Cleaning Up Your Financial Profile
Before speaking with a broker, bring together your certified accounts, current details of business debts and a clear summary of income and expenses. Prepare a business plan explaining what the property will be used for, how it supports trading and where repayments will come from. A mortgage calculator can help you model repayment scenarios, but treat the results as a guide, not a lender decision.
Good timing can help the process run smoothly. If your accounts are being finalised, have interim figures ready and explain what has changed since the last reporting period. Lenders may review applications according to their own reporting and assessment processes, so allow time to answer questions and provide updated documents. A current, organised application is easier to assess than one assembled in a rush.
The Power of Refinancing
Refinancing may be worth considering if your business needs funds for growth, your property equity has changed or your current loan no longer suits your plans. A commercial property refinance replaces or restructures existing commercial lending. Before switching, compare the proposed terms with your current agreement, including any applicable break fees, and account for the time and conditions involved.
As your equity safety net grows, you may have more room to discuss the amount, structure or purpose of borrowing. Equity isn’t the same as available cash, and a lender will still assess affordability and the property. Set out how any released funds would support the business and how the revised repayments would fit your cash flow.
Mortgage Suite Ltd can help organise your application and negotiate with lenders around your business goals. Talk with Mortgage Suite Ltd about your commercial finance options.
How Mortgage Suite Gets Your Finance Sorted
Commercial lending can feel like a maze of forms, lender rules and unfamiliar terms. Mortgage Suite Ltd offers a personal, steady hand through the process. Founder and director Krish Krishna draws on over two decades of banking experience to help bridge the gap between lenders and borrowers, especially when a commercial deal doesn’t fit a standard mould.
That experience helps make sense of how a lender may assess your property, business income, repayment plan and loan structure together. The aim isn’t to chase a headline rate at any cost. It’s to understand your goals, explain options in plain English and negotiate a deal that makes sense for your business over the longer term. Commercial property mortgage rates matter, but so do the loan conditions and how well repayments fit your plans.
A Consultative Approach to Lending
We start by learning what you want the finance to achieve, then work through the details that could affect a lender’s decision. That may include gaps in your documents, unclear income patterns or questions about how the property supports your business. Raising these early gives you time to prepare a clearer application and address concerns before they become obstacles.
You’re not just a set of figures to process. We want you to feel comfortable asking questions, understanding the trade-offs and making informed decisions at your own pace. For clients dealing with a complex application, that supportive approach can make the process feel more manageable. You can also read Mortgage Suite Ltd client reviews to hear about other borrowers’ experiences.
Taking the Stress Out of the Process
Lender communication can take time and attention away from running your business. Mortgage Suite Ltd can act as your advocate, helping present your circumstances clearly, liaise with lenders and negotiate on your behalf. If a bank says no, we can help you understand why and consider whether another lender or second-tier option may suit the deal. There’s no promise that every application will be approved, but one lender’s decision doesn’t automatically close every door.
We take a methodical approach: looking at your objectives, the property, your financial information and a suitable structure, then helping prepare your case for lenders. As offers come in, we help you compare more than the rate, including repayment terms, flexibility and how the loan fits your next business steps.
To get started, gather a brief outline of your plans, recent business accounts and details of the property or finance you’re considering. Then arrange a conversation with Mortgage Suite Ltd about your commercial finance goals. We’ll work through the key questions with you and help map out a practical next step, without treating a complicated situation as a reason to give up.
Make Your Next Finance Move With Confidence
Your next step doesn’t have to be a full loan application. Start by getting clear on what the property needs to do for your business, what repayment structure feels manageable and which parts of your finances need explaining. That gives you a stronger foundation for a practical discussion about your options.
Commercial property mortgage rates are only one part of the decision. A suitable deal should also fit your plans, cash flow and timeframe. If your situation is complex or a lender has already said no, you can still explore whether another approach may fit. There’s no guaranteed outcome, but a clear plan and experienced support can help you make an informed choice.
Mortgage Suite is an Accredited Financial Advice Provider, offering a personal approach to commercial finance and lender discussions. The advice is free of charge with no obligation. Talk with Mortgage Suite about your commercial finance options.
You don’t have to work through the choices alone. With the right guidance, you can move forward with a clearer view of your options and a plan shaped around your business goals.
Frequently Asked Questions
Are commercial property mortgage rates fixed or floating?
They may be fixed or floating, depending on the lender and the loan structure offered. A fixed interest rate stays unchanged for an agreed period, while a floating rate can move as the lender’s pricing changes. Consider how each option fits your cash flow: a business that values predictable repayments may prefer certainty, while another may prioritise flexibility. Compare the full terms, not just the starting rate.
How much deposit do I need for a commercial property in NZ?
There’s no single deposit that applies to every commercial property purchase. The amount can vary with the property, lender and borrower’s circumstances. A specialised or harder-to-sell building may be assessed differently from standard commercial premises. Consider how the deposit affects both the proposed loan structure and the amount you may be able to borrow.
Can I get a commercial loan if I am self-employed?
Yes, being self-employed doesn’t automatically rule you out of commercial finance. Lenders will want to understand how your business earns income and whether it can support repayments. Clear accounts and records showing trading over time can help explain your position. If income varies by season or contract, include context so the lender can assess the wider picture rather than relying on one unusual period.
What happens if a mainstream bank declines my commercial loan?
A decline doesn’t automatically end your options. First, understand which part of the application concerned the bank, such as the property, income evidence or loan structure. That can help show whether a change to the application or a different lender may be worth considering. Mortgage Suite specialises in 2nd tier lending for borrowers outside mainstream criteria, though every lender makes its own assessment and approval isn’t guaranteed.
How long is a typical commercial property loan term?
Commercial loan terms vary, so there isn’t one duration that suits every borrower and property. The agreed term may depend on the loan’s purpose, repayment plan and lender’s offer. Finance for a property your business plans to hold long term may need a different structure from short-term funding with a planned sale or refinance. Check the end date and what you’ll need to do when the loan term finishes.
What is a serviceability stress test for business loans?
A serviceability stress test checks whether your business could manage repayments if interest rates were higher than the rate offered. It can affect the amount the lender is willing to advance, even if you can meet repayments at today’s rate. Before applying, review cash flow under less favourable conditions, including quieter trading periods, so you can see where repayments might put pressure on the business.
Does Mortgage Suite charge an hourly fee for advice?
No. Mortgage Suite’s advice is free of charge with no obligation. You can discuss your commercial finance needs and the lending options that may fit your circumstances without committing to proceed. A lender will still assess any loan application on its own merits, and Mortgage Suite can’t guarantee approval. The aim is to help you understand your options and next steps.