How to work out whether you need a deposit for a business loan in NZ
A deposit isn’t the only way to support a business loan application. If you’re asking, “Do I need a deposit for a business loan in NZ?”, there’s no single deposit amount for every loan. Lenders assess your contribution alongside cash flow, credit history, business records, plans and available security. These factors can also influence the interest rate, and startup loans may have higher rates than loans to established businesses.
It’s understandable to worry that limited cash upfront could rule out borrowing. Start by clarifying what the loan will fund, how repayments would fit your cash flow, and whether assets could support the application as security. This guide explains how deposits, affordability, records, business plans, credit history and security fit together, so you can assess your position and prepare a clearer application.
Key Takeaways
- Work out how much cash your business can contribute, then consider how security and the loan purpose may affect the lender’s assessment.
- Map expected income and expenses in a cash flow forecast to see whether repayments fit alongside day-to-day operating needs.
- Prepare clear financial records and a practical business plan to explain how the business will earn revenue and repay the loan.
- Review your personal credit history and address any issues you can before applying; there’s no fixed credit score cutoff for a New Zealand startup loan.
- Compare the interest and repayment terms with the loan’s purpose, so borrowing supports planned growth or a short-term cash need.
Cash flow forecasts and repayment affordability
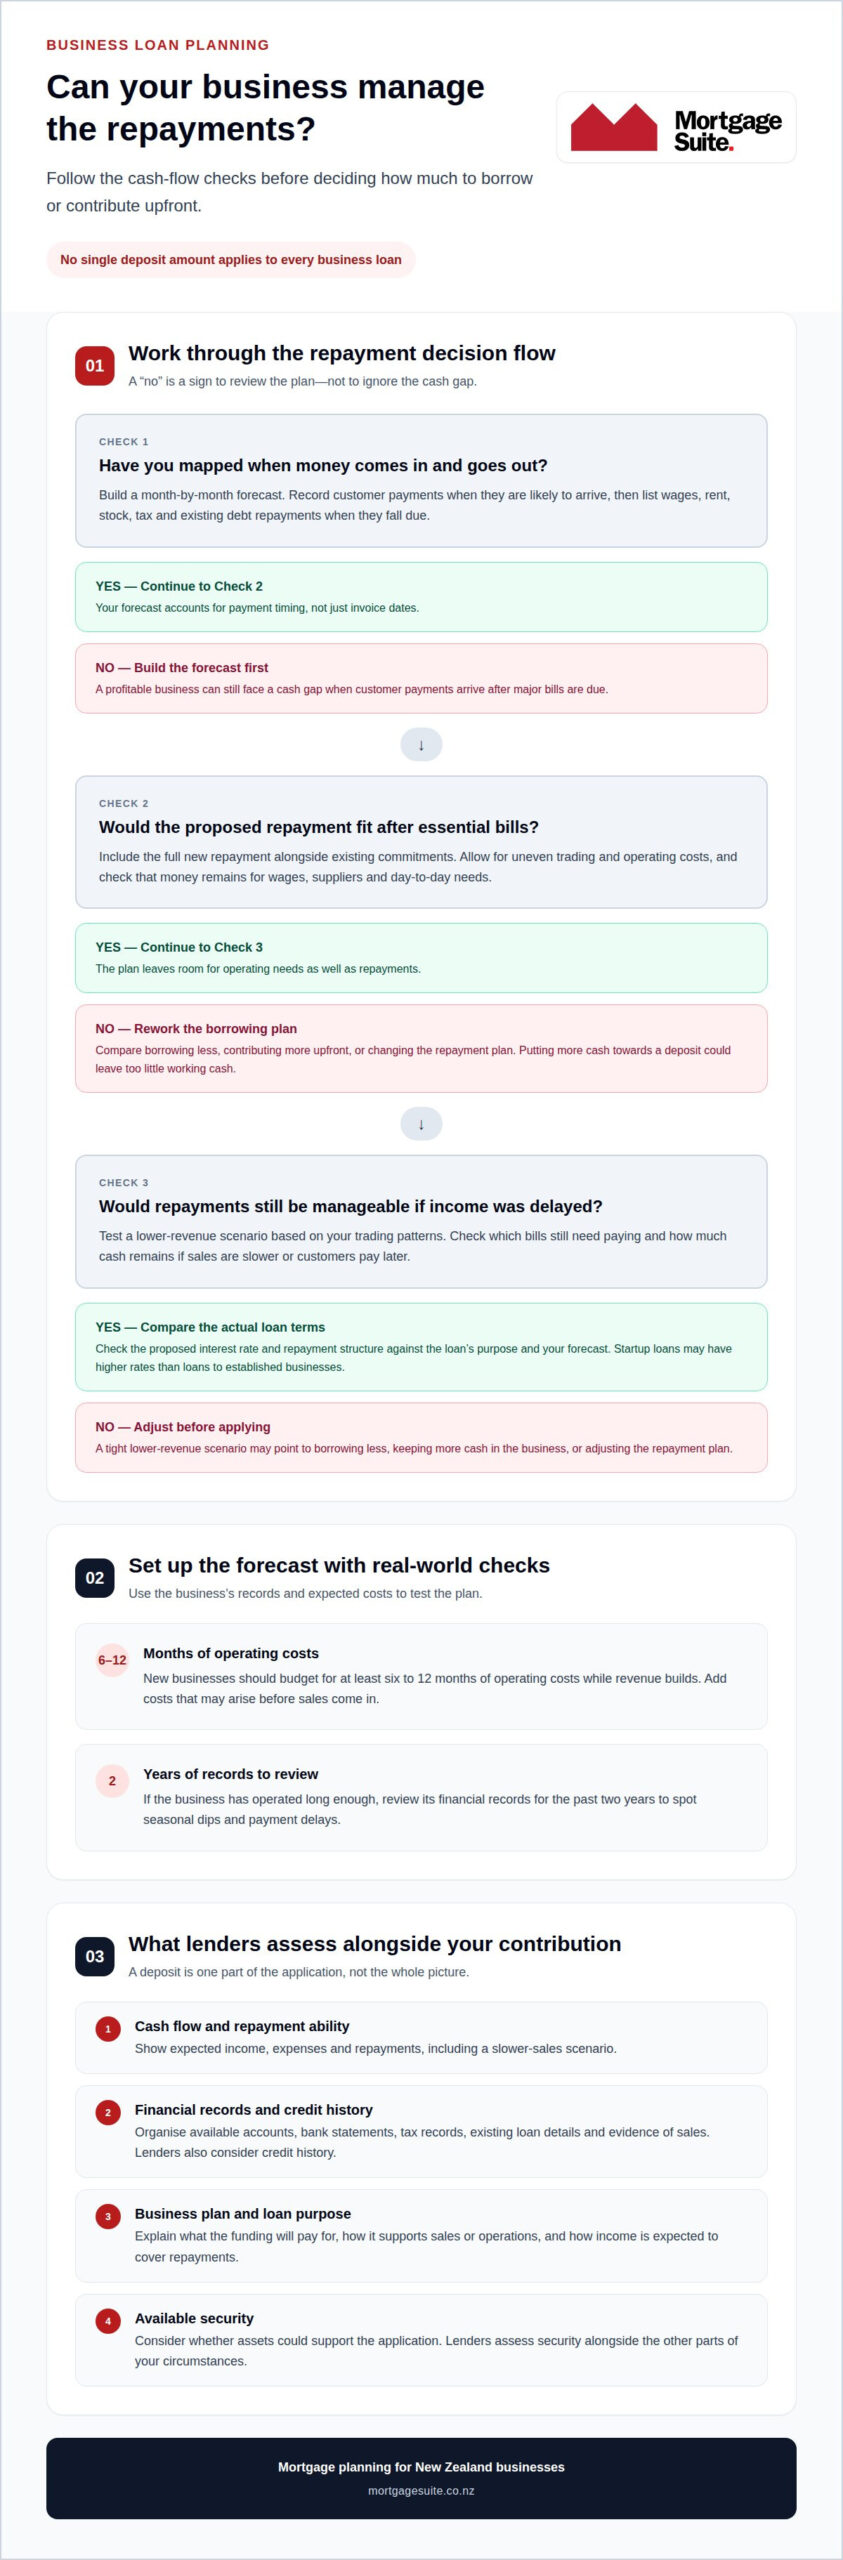
- Build a month-by-month cash flow forecast before deciding how much to borrow or contribute upfront. List expected customer payments in the months they’re likely to arrive, not simply when you issue invoices. Then record regular outgoings, such as wages, rent, stock, tax and existing debt repayments. This shows when cash is available for a new repayment and when it may be tight. A profitable business can still face a cash gap if customers pay after major bills fall due, so account for payment timing in every forecast.
- Allow for uneven trading and operating costs, particularly if the business is new or seasonal. New businesses should budget for at least six to 12 months of operating costs while revenue builds. Add expected costs that may arise before sales come in, then compare the forecast balance with the repayments you’re considering. If the business needs to retain cash for wages or suppliers, putting more money towards the loan deposit could leave too little working cash. Weigh the benefit of borrowing less against the cash buffer the business needs to keep trading.
- Test whether repayments remain manageable if income arrives later than expected. Create a lower-revenue scenario based on your trading patterns, then check which bills still need paying and how much cash remains. Include the full proposed repayment alongside existing commitments, rather than assessing the new loan in isolation. If the business has been operating long enough, review its financial records for the past two years to identify seasonal dips and payment delays. Use those patterns to plan repayments around actual cash flow, not just an optimistic sales forecast.
- Compare the interest rate and repayment structure with the loan’s purpose and cash flow. The Reserve Bank of New Zealand reported that the SME new overdraft rate was 10.06% in August 2026. That figure is an overdraft rate, not a quote for every business loan, so use the actual proposed rate and terms in your calculations. Check how repayment timing affects cash available after essential bills. A forecast that leaves little room for a slow month may point to borrowing less, contributing more upfront, or adjusting the repayment plan before applying.
Preparing financial records, a cash flow forecast and a business plan
- No single no-deposit business loan applies across New Zealand. Unsecured business loans, which don’t use an asset as security, are often available for amounts under NZ$50,000, but that doesn’t automatically mean no deposit is required. Lenders still assess repayment ability, credit history and the business plan. Prepare for the possibility that limited trading history or weak cash flow could narrow your choices.
- Gather your financial records into one clear set before approaching lenders. For an established business, organise recent accounts, bank statements, tax records, existing loan details and evidence of sales. Check that figures match across documents, and explain unusual changes, such as a large one-off expense or a major customer leaving. New businesses may have fewer trading records, so assemble available evidence of startup costs, confirmed orders, supplier quotes and money already invested.
- Prepare a cash flow forecast showing when money is expected to enter and leave the business. Separate expected sales from confirmed income, then list regular expenses and loan repayments by date. For example, if customers usually pay after supplier invoices fall due, show that timing instead of treating both amounts as happening together. Create another forecast with slower sales or delayed payments. This helps demonstrate how the business could manage repayments during a tighter period.
- Write a business plan that connects the loan amount to a clear purpose and repayment path. Explain what the funding will pay for, how that should support sales or operations, and when the business expects income to cover repayments. Startup loans in New Zealand commonly range from NZ$5,000 to NZ$500,000, depending on the plan and security offered. Use your plan to justify the amount requested, rather than choosing a figure without linking it to specific needs.
- If your new business lacks financial data, lending options may be more limited. A personal loan or borrowing more against a mortgage may be alternatives, but weigh the repayment obligation against your personal finances. Compare the loan term, interest and repayment schedule with the business forecast. For an unsecured loan, consider whether the higher rate still fits the plan. Records, a realistic forecast and a focused business plan give lenders a clearer basis for assessing the application.
Unsecured business loans may be available without an asset as security, often for amounts under NZ$50,000, but that does not guarantee that no deposit is required. Lenders assess each application based on factors such as repayment ability, credit history and the business plan.
Using borrowed money for growth or short-term cash needs
Before borrowing, match the loan to a specific business need and repayment plan. This helps you judge whether debt supports the business or adds pressure.
-
Define the borrowing need
Write down what the funds will pay for, then separate planned growth from urgent cash needs. For example, funding equipment that supports extra customer orders has a different purpose from covering a temporary delay in customer payments. New businesses should budget for at least six to 12 months of operating costs while revenue builds. Avoid borrowing without identifying which expenses the loan covers and how trading income will support repayments.
-
Review loan risks and costs
Before accepting a loan without a deposit, compare the interest, repayment schedule and any fees. Risks include committing future business income, leaving less cash for suppliers, and facing extra charges after late or missed repayments. Startup business loans may have higher interest rates than loans for established businesses. Check the total repayment obligation and whether the forecast shows the business can meet it, including during a slower trading period.
- Decide whether borrowing is suitable by linking the funds to a clear business outcome. Lenders in New Zealand assess whether a business is viable and can repay the loan and interest. A loan may suit planned growth or a short-term cash shortfall, but borrowing to bail out a business can leave the underlying problem unresolved. First identify the cause of the shortfall, such as late customer payments or rising operating expenses. Then consider whether the loan addresses that cause or only delays it.
- Set a repayment plan that protects essential business spending. Put each repayment date alongside expected income and regular bills, then consider what happens if a customer pays late. Don’t assume projected sales will arrive on schedule. If the forecast shows repayments competing with wages, rent or supplier invoices, reconsider the amount or timing before committing. This makes the effect on day-to-day trading easier to assess.
- Read the early repayment terms before planning to clear the debt ahead of schedule. Repaying early makes sense only if the interest saved exceeds any early repayment fee. Don’t make extra repayments just because of a strong sales month. First account for upcoming tax, supplier bills and operating needs. A business loan should fit the purpose, cash flow and repayment plan without leaving the business short of working cash after the funds are used.
Business plans and credit history
- Start with a business plan that clearly explains the loan request. For a startup application, the plan can carry significant weight in a lender’s assessment. State what the funds will pay for, how the business will earn income, and how that income will support repayments. For example, connect equipment funding to the work it enables, expected customer demand and resulting sales. A deposit can show your contribution, but it doesn’t replace a clear repayment plan.
- Make the plan practical enough to test, not just persuasive. Set out your product or service, likely customers, how you’ll reach them and key operating needs. Link expected sales to the cash flow forecast and explain assumptions, such as when customers pay. If income depends on a signed contract, identify it; if demand is untested, explain how the business will manage before sales grow. Keep the requested loan amount tied to specific expenses.
- Review your personal credit history before applying, especially if the business is new. A startup may have little or no trading record, so lenders may consider the founder’s credit history alongside the business plan and evidence of repayment capacity. There’s no fixed credit score cutoff for a New Zealand startup loan. A clean personal credit history with no recent defaults can strengthen an application, but credit history is only one part of the assessment.
- Check your credit information for errors and prepare a straightforward explanation for any past difficulty. For example, if a missed payment arose during a period of financial disruption, explain what happened and what has changed since. Don’t hide a past default or leave unexplained gaps in your application. Support your explanation with relevant records, such as evidence that an account is now up to date. Clear information helps a lender assess the circumstances rather than guess.
- Bring the business plan, credit information and loan request together before applying. Check that the amount requested matches the listed expenses and that forecast income supports repayments after ordinary business costs. If the business has a limited trading record, explain how the plan accounts for that gap. A deposit may strengthen the application by showing your own contribution, but the business still needs a credible purpose, realistic repayment plan and acceptable credit position.
Collateral and security for business loans
The deposit a lender requires depends on the loan purpose, your contribution, available security and evidence that repayments are affordable. Cash is only one part of the assessment; assets offered as security can also affect how the lender views risk.
- List the assets you could offer before deciding how much cash to put towards a deposit. Depending on the loan and lender, business equipment, vehicles or property may be considered as security. Security is an asset a lender may claim if repayments aren’t made. Record who owns each asset, whether another loan is secured against it, and its current condition. Note which items the business relies on daily, since losing access to them could disrupt trading.
- Separate your own contribution from the security you can provide. Your contribution is cash invested in the business or purchase; security is an asset backing the borrowing. When assessing a startup loan, lenders may consider the founder’s personal investment, security, credit history and forecast cash flow. A larger contribution or suitable security may support the application, but neither replaces evidence that repayments are affordable.
- Understand what could happen to each asset if the business can’t repay. If you offer personal property or equipment as security, that asset is exposed to the loan risk. Consider how losing access to it could affect your household or ability to trade. Review any existing lending against the asset, since another lender’s claim may affect its suitability as security. Keep the amount borrowed aligned with the asset’s role and the business’s repayment capacity.
- Compare a secured loan with an unsecured option before choosing. Unsecured business loans are often available in New Zealand for amounts under NZ$50,000, though their rates are higher because they lack security. That can avoid pledging an asset, but higher interest increases repayments. Compare the full repayment schedule with the business forecast, and weigh the cash deposit against the cost of borrowing and the risk to any asset offered.
- Prepare a security summary for the application. List each asset, its owner, any existing debt attached to it, and how the loan will be repaid. Include your own contribution and explain how each asset would support the application. A business loan guide can help you organise these details and understand how security fits into your borrowing plans.
Mortgage Suite: Home Loans to First Home Buyers
Mortgage Suite Ltd can help you assess business loans in light of your business purpose, cash flow and available security. If a mainstream bank has declined your application, that does not necessarily end your options. A different lending approach may better suit your circumstances.
Bring details of your loan purpose, financial records, forecast repayments, and any deposit or security you can offer. These provide a practical starting point for discussing your application and identifying areas that may need attention. Mortgage Suite Ltd also offers home loans to first home buyers, but for this question, the relevant next step is to discuss business finance.
For a supportive conversation about borrowing for your business, contact Mortgage Suite Ltd today.
Take the next step with a clear borrowing plan
Working out whether you need a deposit for a business loan in NZ is only the starting point. Bring your funding purpose, contribution, security and repayment plan together to get a clearer picture of your position. This makes it easier to discuss what may suit your business and where the application needs more work.
Mortgage Suite Ltd offers Business Loans, Home Loans to First Home Buyers and Residential Investment Property Loans. If you’re considering a business loan, you can discuss your circumstances and possible lending pathways without treating a bank’s decision as the final word. A conversation can help you identify practical next steps, with no obligation to proceed.
Contact Mortgage Suite Ltd about business loans and take your next step with a clearer plan.
Frequently Asked Questions
How much interest will I pay?
The interest you pay depends on the rate and repayment terms offered for your loan. To compare options, look beyond the headline rate: consider how often repayments are due, whether the rate can change, and how much interest the repayment schedule adds over the full term. Then compare the total amount repayable with your planned use of the funds, not just the first repayment.
Do business loans in New Zealand require a deposit?
Not every business loan requires a cash deposit. A lender may instead focus on how the loan is structured, what it funds and what support is available for repayment. Before applying, separate the amount you can contribute from the amount you need to borrow. This gives you a clearer basis for discussing whether the proposed loan requires an upfront contribution.
How much deposit do NZ business lenders typically require?
There’s no single deposit percentage for every NZ business loan. To estimate your contribution, start with the amount needed for the purchase or project, then subtract the funds you can put in without leaving the business short of cash. Keep your working cash separate from your deposit figure, so you can explain how the business will cover both the upfront need and day-to-day trading.
Do NZ banks require a deposit or personal guarantee for a business loan?
Neither a deposit nor a personal guarantee is required for every NZ bank business loan. A guarantee is different from a deposit: it may make you personally responsible for repayment if the business can’t meet its obligations. Read the proposed terms carefully, identify who would sign, and understand when the guarantee could apply before agreeing.
Can business assets or equipment be used as security instead of a deposit in NZ?
An asset may sometimes support a business loan, but it doesn’t automatically replace a cash deposit. If you’re buying equipment with borrowed funds, ask how the lender treats it within the proposed loan structure. Check whether it can be used as security, who owns it during repayment, and what the agreement says if the business falls behind.
What are the deposit requirements for NZ startup business loans?
Startup loans don’t have one standard deposit amount across New Zealand. A startup loan is designed for a new business without a trading history or steady revenue, so a lender may focus on the founder’s contribution and funding plan. Separate the money needed to start trading from any contribution towards a specific purchase, then show how each amount will be used.
Do government-backed or small business loans in New Zealand require a deposit?
Government backing or a small-business label doesn’t automatically remove a deposit requirement. The terms of a particular lending programme explain whether a contribution is needed and what the funds can cover. Read those conditions alongside the repayment terms, and distinguish any required upfront contribution from other eligibility requirements. A programme’s backing alone doesn’t establish that a business qualifies or that borrowing will be deposit-free.
What documents and steps are needed to apply for a business loan in NZ?
Prepare a clear application pack that connects your request to the business’s circumstances. State the amount sought and how you intend to use it, then organise the relevant records and supporting documents consistently. Include details of existing borrowing and any assets or guarantees involved. Before submitting, check that names, dates and figures agree across the paperwork, and keep copies of the final application and lender correspondence.