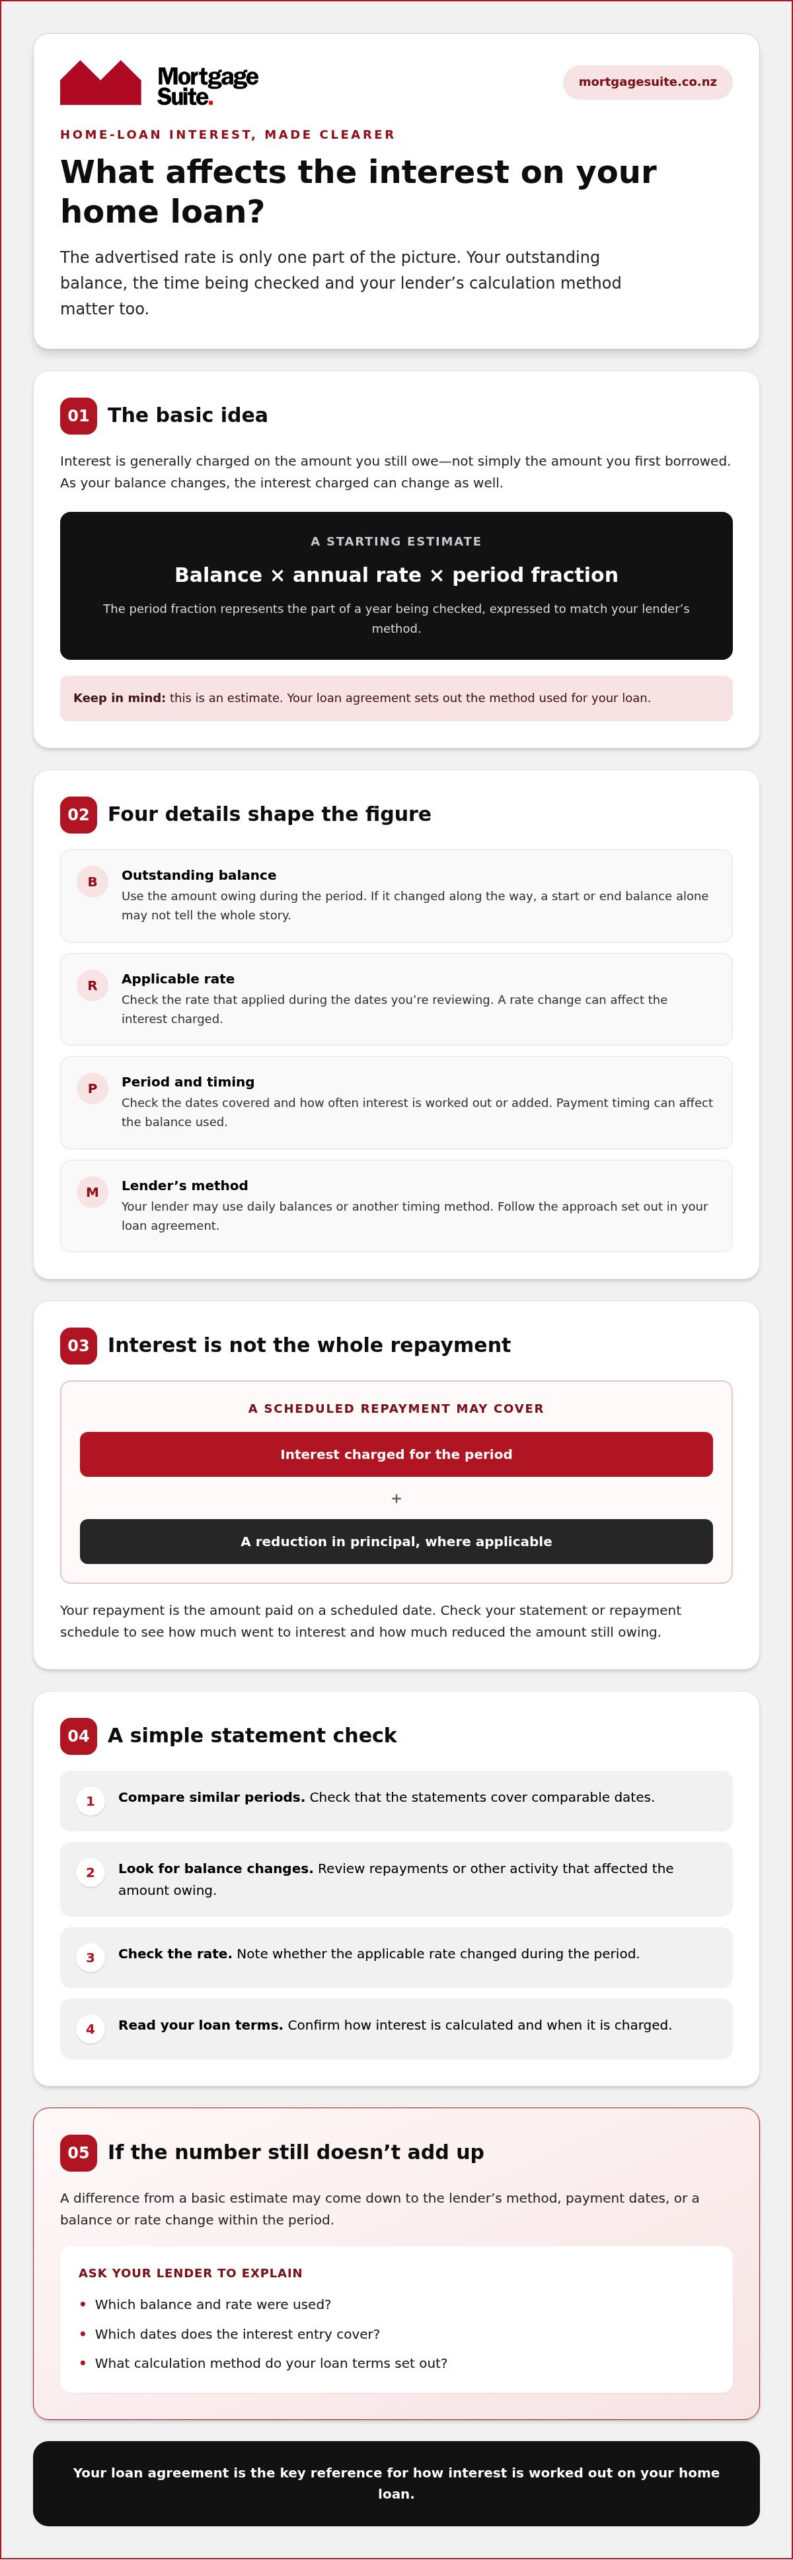
Could the flexibility of a revolving credit facility help reduce your mortgage, while also making it easier to borrow again? It’s a fair concern for Kiwis weighing up this option. Knowing how to use a revolving credit facility effectively starts with understanding that interest is generally calculated daily on the amount you owe. Money paid into the account can reduce that balance and the interest charged, while withdrawals increase it again.
The key is to pair flexibility with a clear routine, rather than treating available credit as spare spending money. This guide explains how the facility works day to day, how to direct income and manage withdrawals, and what to consider if your earnings vary. You’ll also compare revolving credit with an offset account and a loan with a fixed interest rate, so you can weigh flexibility against predictable repayments and the effort involved in managing debt.
There’s no single structure that suits every borrower. Mortgage Suite Ltd can help you compare lending options and consider a mortgage plan shaped around your cash flow and priorities.
Key Takeaways
- Learn how an approved limit differs from the amount you’ve actually borrowed, and why your lender’s terms matter.
- See how to use a revolving credit facility effectively with a planned routine for income, spending and withdrawals.
- Compare revolving credit, an offset account and a fixed interest rate by weighing flexibility against predictable repayments and the effort needed to manage debt.
- Use a separate household budget to stop available credit feeling like extra income.
- Work out whether active debt tracking suits your habits and goals, or whether another mortgage structure may feel more manageable.
What is a revolving credit facility, and what makes it different?
Mortgage flexibility can feel useful and uncertain at the same time. A revolving credit facility has an approved borrowing limit, but the amount you owe can change as money goes in and out. Think of it as a home loan with a flexible balance: you can pay money in and, subject to your lender’s terms, access some of the credit again later.
The limit is not the same as your debt. If you borrow less than the full limit, interest is generally based on the amount drawn, not the unused portion. Lenders can differ in how they apply interest, handle deposits and allow withdrawals, so read the facility terms before relying on a particular feature. For a broader explanation of revolving credit, see how it differs from borrowing repaid in fixed instalments.
Flexibility doesn’t automatically reduce your mortgage. Money paid in may lower the balance, but later withdrawals can push it up again. To understand how to use a revolving credit facility effectively, make a clear plan for paying debt down and keeping everyday spending within budget.
How the facility works in everyday banking
Depending on the lender’s arrangements, your income may be paid into the facility, reducing the amount owing. You can then use available credit for payments or transfers, within the approved limit and account rules. Some facilities calculate interest daily on the drawn balance, but the method and timing can vary by lender.
For example, your pay arrives in the account and lowers what you owe. You then transfer money to cover groceries, household bills and other planned spending. Those withdrawals increase the balance again. This pattern can keep the amount owing lower between paydays, but only if spending stays controlled and the balance trends down over time.
How it differs from an offset account or term loan
An offset account is an account whose balance reduces the loan balance used to calculate interest. It is generally kept alongside a loan, while a revolving credit facility is itself a flexible loan balance. The lender’s product rules determine how accounts are linked and which balances count.
A term loan provides a lump sum with a defined repayment schedule and end date. This can give you a clearer repayment path than a facility where you can redraw available credit. A revolving credit arrangement offers more day-to-day access, but that can mean more active monitoring. The comparison is not just about flexibility: consider whether you prefer a set schedule or are comfortable managing a changing balance.
Before choosing, compare the lender’s rules for deposits, withdrawals, interest calculations and repayments. Then consider your cash flow and habits. If easy access could make it tempting to borrow again, a less flexible structure or a mix of loan types may feel easier to manage. Mortgage Suite Ltd can help you compare lending options and consider a structure suited to your goals.
How interest and repayments work on a revolving credit facility
With a revolving credit facility, the amount you’ve borrowed may determine the interest charged, rather than the full approved limit. The exact calculation and timing depend on your lender’s terms. Cornell Law School gives a general explanation of a revolving credit facility, but its legal reference isn’t a guide to the conditions of a New Zealand home loan. Your lender’s documents explain how your account works.
That distinction matters when you’re budgeting. A lower balance can mean less debt is being counted for interest, but it doesn’t guarantee a lasting reduction or a particular saving. Interest rates and facility conditions vary, so focus on understanding your statements and setting a repayment goal that fits your cash flow.
What happens when income enters the facility
If your lender allows income to be paid into the facility, the deposit may reduce the balance used to calculate interest. The effect depends on the account’s rules, including when deposits are recognised and how interest is worked out. Check the terms rather than assuming every payment immediately changes the calculation in the same way.
For example, your pay comes in, then you transfer a planned amount to a separate everyday account for bills and household spending. The money left in the facility keeps the amount owing lower for a time. If income arrives on different dates or bills fall due soon after payday, the balance may move differently from week to week. A routine helps you see that movement clearly.
Also check what repayments your lender requires and when they’re due. A minimum required payment keeps you within the facility’s conditions, but it may not match the pace you want for reducing debt. Make a separate plan for how much you intend to leave unpaid after regular expenses, and review whether you’re sticking to it.
Why a lower balance does not automatically mean lasting progress
A deposit can bring the balance down, while later withdrawals for bills, unexpected expenses or discretionary spending can raise it again. That rise and fall is part of the facility’s flexibility, but it can make short-term cash-flow relief look like debt reduction. Compare the balance over a longer stretch and note whether it’s steadily falling, staying similar or growing.
The balance only falls over the long term when repayments consistently exceed new borrowing and interest added. If the debt isn’t moving in the direction you planned, adjust your spending routine or reconsider whether this structure suits you. The goal is to make repayments intentional, not simply to rely on money passing through the account.
Understanding the account rules is one part of choosing a suitable mortgage structure. Mortgage Suite Ltd can help you compare lending options and talk through how the terms fit your cash flow. Its mortgage learning resources can help you build your understanding before deciding on your next step.
Revolving credit vs other mortgage structures: which trade-offs matter?
Choosing a mortgage structure isn’t just about finding the lowest advertised rate. Think about how you want to repay, how predictable you need payments to feel, and whether you’re comfortable keeping a close eye on borrowing. A lower headline rate on its own can’t tell you which structure suits your goals and cash flow.
The Federal Reserve Board describes the broader distinction between revolving and nonrevolving credit. That’s a general consumer-credit explanation, not a guide to New Zealand mortgage products. Your lender’s terms determine how a home loan works, including its rate, account links and repayment rules.
| Structure | Flexibility | Payment predictability | Management effort |
|---|---|---|---|
| Revolving credit | Access to available credit can offer flexibility, subject to lender rules. | The balance and interest may change as money moves in and out. | Needs regular tracking and a clear debt-reduction plan. |
| Offset account | Linked savings can reduce the balance used to calculate interest, subject to product rules. | The loan repayments follow the lender’s terms; the offset balance can vary. | Requires attention to linked accounts and their conditions. |
| Fixed interest rate | Less day-to-day flexibility may apply, depending on the loan terms. | The interest rate stays unchanged for the agreed period, which can make planning easier. | Less active balance management may be needed, but repayments and conditions still matter. |
When flexibility may help and when it may get in the way
Flexibility may be useful if income arrives regularly and you can consistently leave some of it in the facility to reduce what you owe. A planned household budget helps you distinguish money set aside for bills from credit you could draw again.
Frequent discretionary withdrawals can work against a debt-reduction goal. That doesn’t mean you lack discipline; it simply means easy access might not suit how you prefer to manage money. Look honestly at your spending habits. Would seeing available credit make it harder to stick to your plan, or would regular reviews keep you on track? The answer can help you decide how to use a revolving credit facility effectively.
Can different mortgage structures work together?
Some borrowers consider splitting their lending across different structures, such as keeping a portion flexible and placing another portion on a fixed interest rate. Lender rules, your wider circumstances and the way you manage cash flow all shape the options available. This approach may balance access with more predictable repayments, but it isn’t a one-size-fits-all solution.
Compare the full structure, not just the rate attached to one portion. Consider repayment expectations, flexibility and how each part fits your longer-term plans. Mortgage Suite Ltd can help you weigh up lending options and consider a structure around your priorities. Understanding the trade-offs can make your decision clearer and help you work out what feels manageable.
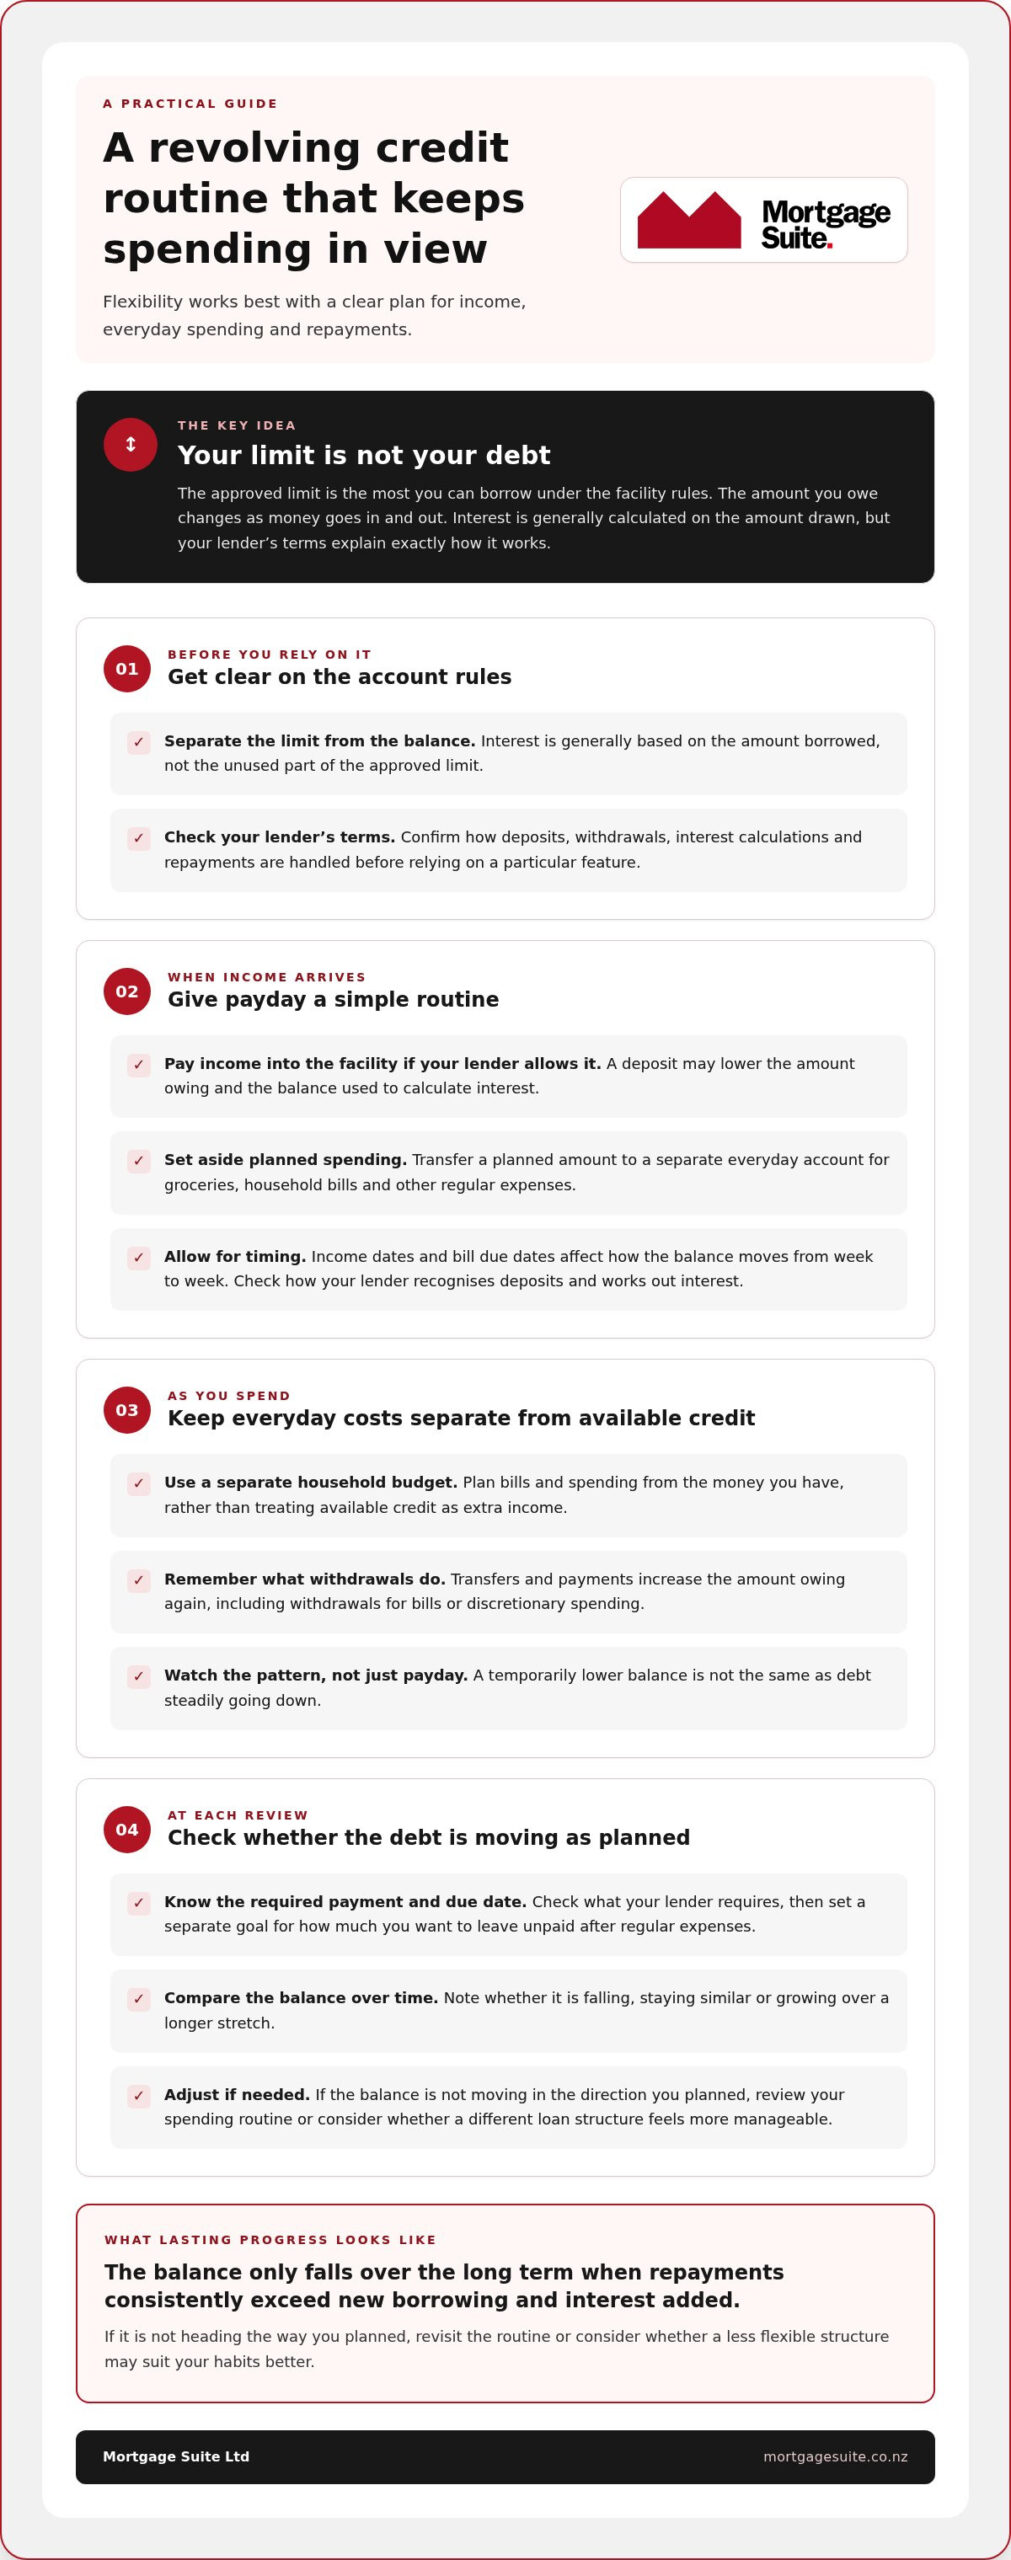
How to use a revolving credit facility effectively: a practical routine
A simple routine can help make flexibility work for you, rather than letting available credit blur the line between borrowing and spending. Start with a plan you can maintain through ordinary weeks as well as busier ones. It doesn’t need to be complicated, but it should make your goal and spending limits clear.
Set a repayment and spending plan before using the facility
Before you start, choose a realistic goal for reducing the balance. Base it on your household income, regular commitments and the lender’s repayment conditions. List essential payments and planned expenses first, so you know what needs to leave the account and what you can aim to keep towards reducing what you owe.
Then set a personal limit for withdrawals. A useful rule is: decide what each withdrawal is for before using available credit. That pause gives you a chance to check whether the expense is planned, essential or likely to push your balance away from its goal.
Build a routine you can follow
- Set a clear goal. Decide what progress would look like for your household, such as keeping the balance moving down over time.
- Direct income with a purpose. If your lender’s terms allow it, have income paid into the facility, then transfer only the amount you’ve planned for day-to-day spending.
- Budget separately. Keep a household budget or use a separate transaction account for regular spending. Treating the full available limit as spendable money can make it harder to see what you can actually afford.
- Limit withdrawals. Before drawing on the facility, check your spending plan and personal boundary. Avoid using available credit for unplanned extras if doing so would disrupt your repayment goal.
- Review your progress. Check transactions and the balance regularly, at a pace you can stick with. Look for a downward trend across normal spending cycles, not just a lower balance immediately after income arrives.
Review the balance and adjust your routine
Your plan should be practical, not rigid. If income changes or an unexpected commitment comes up, revisit what you can leave in the facility and whether planned withdrawals still make sense. Keep track of what changed, too. That helps you distinguish a one-off expense from a pattern that’s making it harder to reduce the debt.
If the balance isn’t moving as intended, use the review as a prompt to adjust the budget, spending limit or repayment goal. Avoid relying on memory alone. A simple record of the balance and recent withdrawals can show whether your routine is working, or whether easy access is making borrowing harder to manage.
To build your understanding of mortgage terms and structures, explore Mortgage Suite Ltd’s Mortgage School and use what you learn to prepare for a conversation about a structure that fits your goals.
Is a revolving credit facility right for you? Plan your next step
A revolving credit facility may suit you if you have clear goals, can plan your household spending and feel comfortable checking how your borrowing changes. It may be worth considering if your income pattern gives you room to make regular reductions to the balance. But flexibility isn’t a benefit for everyone. If you tend to rely on repeat withdrawals or find it stressful to track debt, a structure with more predictable repayments may feel easier to manage.
There’s no need to judge yourself by one feature or habit. The right mortgage structure depends on your full lending picture: your goals, income, regular commitments, comfort with managing an active balance and the lender’s terms. A revolving facility might suit one part of a plan, while a different structure could better fit another. Compare the overall arrangement, not just the access it offers.
Questions to consider before choosing
Before deciding, think through how the facility would fit your real household routine, not an ideal month. Be honest about your spending habits and what level of monitoring feels manageable. These questions can help you see whether the flexibility supports your goals or adds pressure:
- Can your household stick to a spending plan while credit remains available?
- Will you check the balance often enough to notice if the debt stops reducing?
- Would repayments linked to a fixed interest rate better match your comfort and plans?
- Do your income and regular commitments leave room for a clear repayment goal?
If you’re unsure, that’s useful to know. It may point to a need for a different structure, or for a firmer budget and withdrawal rules before you take on flexible borrowing.
Discussing your options with a mortgage adviser
Bring your goals, income pattern, regular commitments and questions to a mortgage discussion. You don’t need to have every answer sorted first. A clear picture of how money comes in and goes out can help an adviser compare lending options and talk through how different structures may fit your plans.
Mortgage Suite Ltd’s founder, Krish Krishna, brings more than two decades of banking experience to conversations about lending options and mortgage structure. The focus is on understanding your circumstances and negotiating with lenders where appropriate, not assuming one facility suits every borrower. Together, you can weigh flexibility against predictability and active debt management.
If you’re considering a revolving credit facility, discuss whether it fits your wider home-loan plans. A conversation can help you compare the structure with other options and identify questions to resolve before making a decision. The aim is a mortgage plan that fits your goals and feels manageable day to day.
Take a considered next step with your home loan
Before changing your mortgage, give yourself space to think about what you need your borrowing to do in the months and years ahead. A revolving facility should fit your real cash flow and the way you like to manage money, not just look appealing on paper. If you’re still weighing up how to use a revolving credit facility effectively, write down the questions you want answered about lender terms, repayment expectations and how the structure could fit your wider plans.
You don’t have to work through those choices alone. Mortgage Suite Ltd was founded by Krish Krishna in 2000, and focuses on understanding your circumstances and helping you compare lending options, so you can make a considered decision without pressure.
Talk through your home-loan options with Mortgage Suite Ltd and explore which structure may fit your goals and comfort with managing debt. A clear conversation can help you feel more prepared for the next step.
Frequently Asked Questions
Does a revolving credit facility automatically reduce the interest I pay?
No, interest won’t automatically fall just because you have a revolving credit facility. Deposits may lower the amount owing, but withdrawals can raise it again, so the balance over time matters. Lender terms also set how interest is calculated. Review your account statements alongside your expected deposits and withdrawals to understand how the calculation applies to your account.
Can I combine a revolving credit facility with a fixed interest rate?
Some borrowers may be able to divide their home loan between a flexible portion and one with a fixed interest rate. Lender rules and the way the loan is arranged determine whether that setup is an option. Compare the repayment requirements and access to funds for each part. A split can help match different needs, but it should have a clear purpose and remain manageable to review.
Is a revolving credit facility suitable for a first-home buyer?
It may suit some first-home buyers, but qualifying for a home loan doesn’t automatically make a revolving facility a good fit. Consider whether you can follow a household spending plan, keep track of borrowing and explain why you need the extra access. For example, if you’d rather know what repayments to expect, another structure may feel more comfortable. Discuss your income, deposit and wider borrowing plans with a mortgage adviser.
Can I withdraw money I have already paid into a revolving credit facility?
Usually, a revolving facility allows access to available credit up to its approved limit, but the lender’s rules and account setup determine how withdrawals work. Paying money in doesn’t necessarily mean you’re withdrawing your own funds later; you may be borrowing again. Before relying on access for a future expense, understand the account conditions and consider how the withdrawal could affect your repayment plan.
What should I do if my revolving credit balance stops going down?
Start by comparing recent account activity with your budget. Look for changes in income, essential bills, one-off expenses or optional withdrawals that may explain the shift. Then set a realistic new reduction goal and decide what spending you can adjust. If the balance keeps rising or the account feels hard to manage, raise the situation with Mortgage Suite Ltd early. A change in circumstances isn’t a personal failing.
Does a revolving credit facility have a fixed end date?
There isn’t one end-date rule for every facility. The lender’s offer and account conditions explain the term, any review arrangements and what may happen if the terms change. Read these details before making plans that rely on continued access to credit. If you’re working out how to use a revolving credit facility effectively, include its timeframe in your wider home-loan plan rather than assuming the arrangement will stay unchanged.
How often should I check my revolving credit balance?
Choose a review routine you can keep up with, such as checking transactions as you update your household budget and reviewing the overall balance regularly. The aim is to catch unfamiliar activity and notice whether borrowing is heading in the right direction. If frequent checks feel stressful, choose a simple, consistent review point instead. If you spot a pattern you can’t explain, review your account information to understand the activity.