How to Build a Property Portfolio in NZ: 2026 Guide

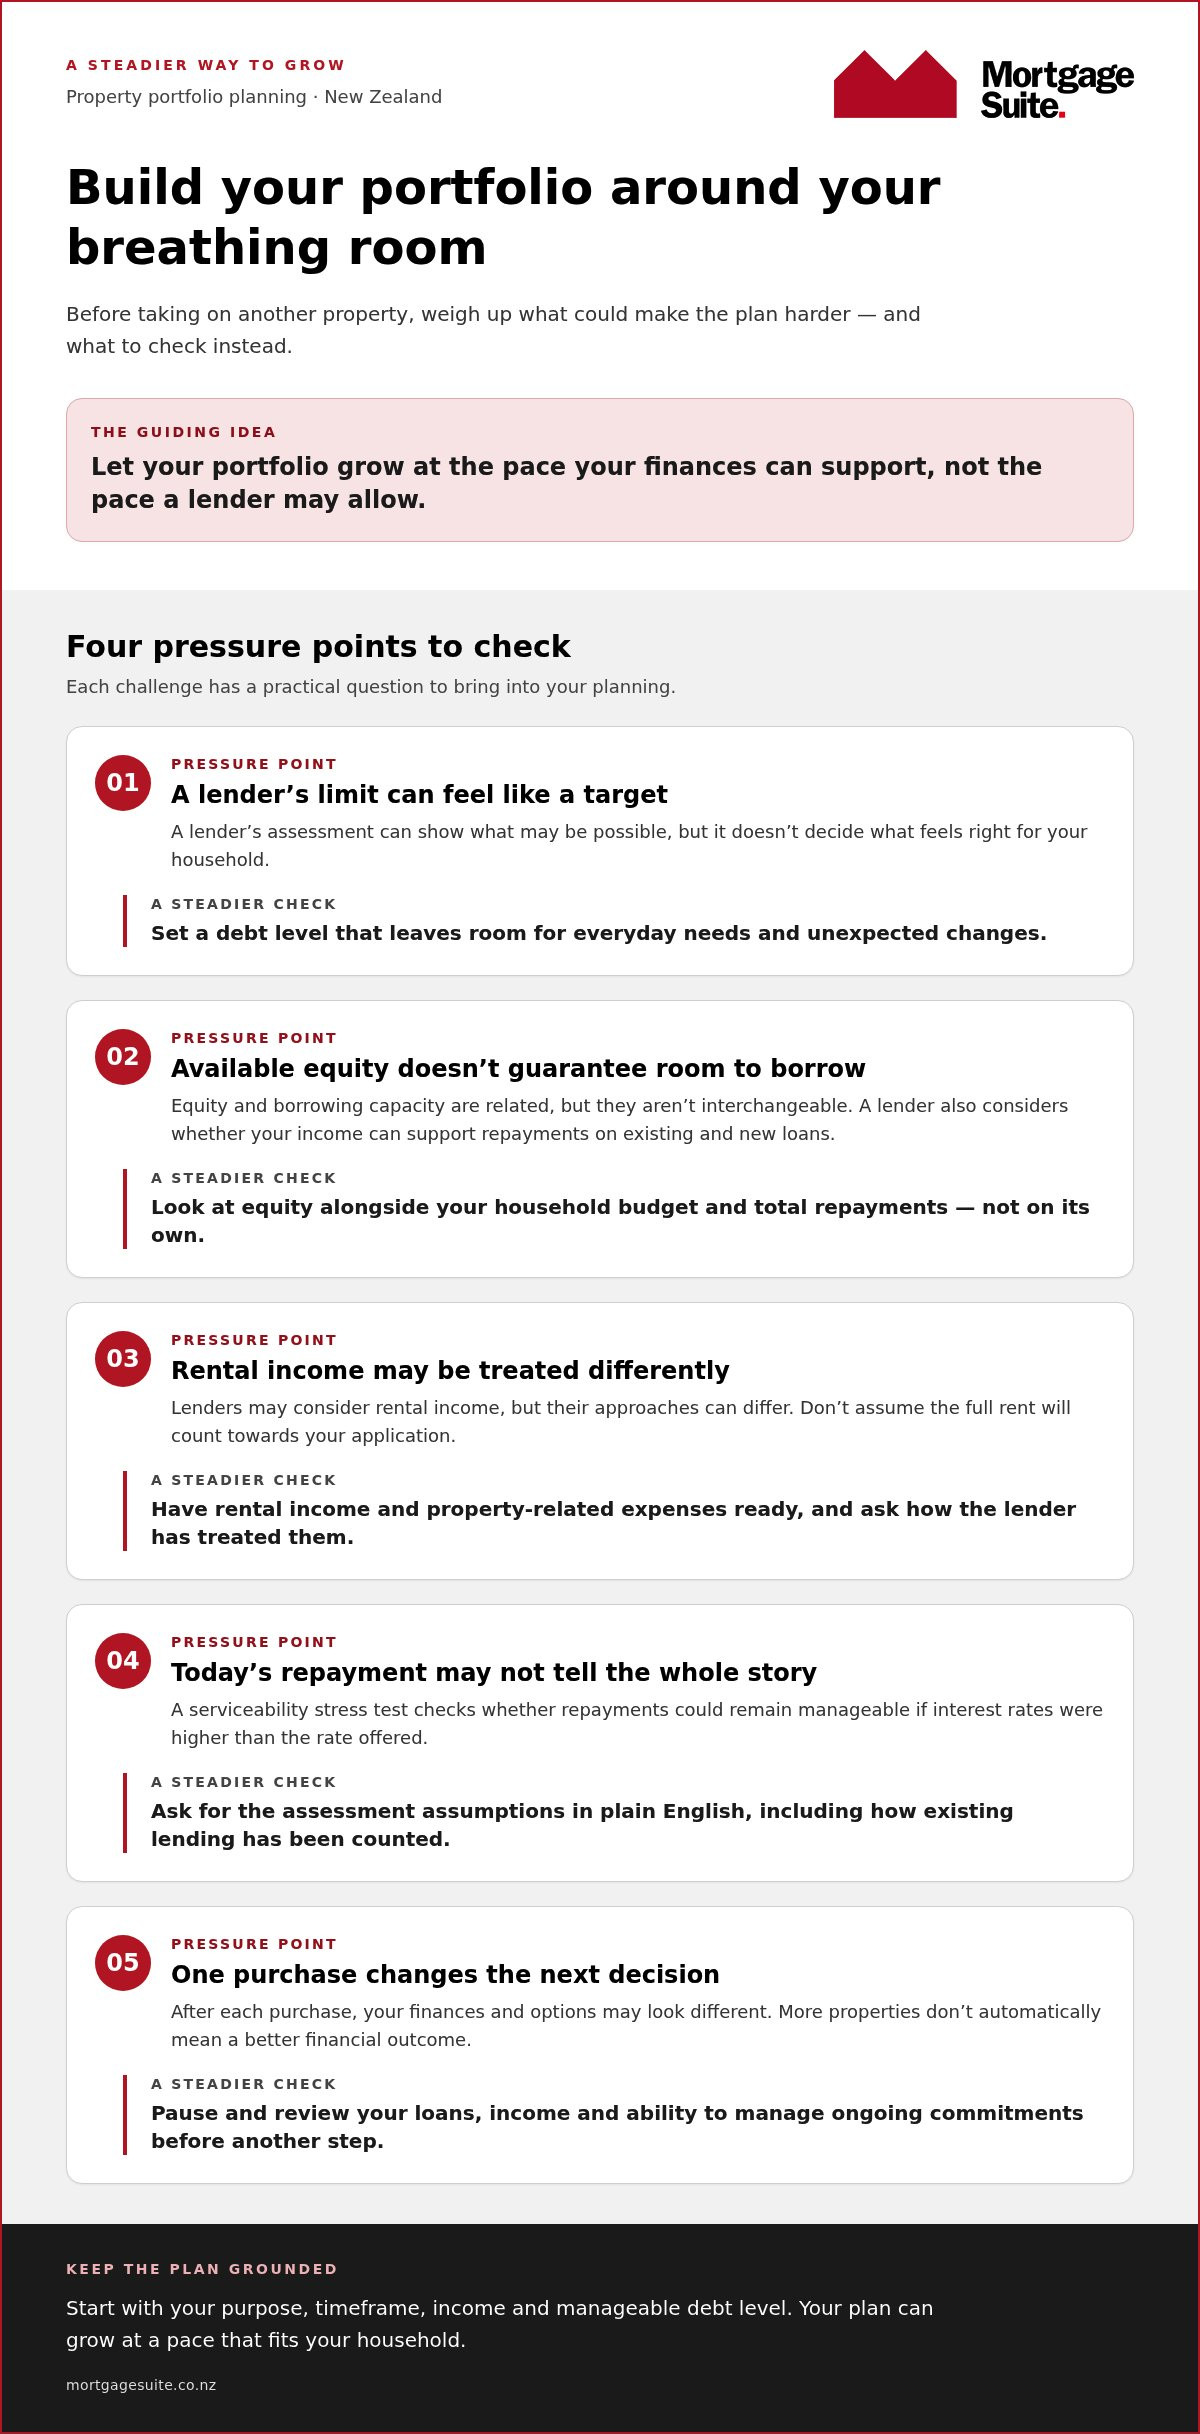
What if the next property in your portfolio should be decided by your financial breathing room, not the maximum a lender might offer? If you’re working out how to build a property portfolio nz, it’s understandable to feel unsure about how existing loans, available equity and changing repayments could affect your next move.

A sustainable plan starts with your goals and what your household can comfortably manage, not a target number of properties. This guide will help you map out practical next steps, understand how lenders may assess your income and existing debt, and review the risks before taking on another commitment.

You’ll also learn how available equity may support a purchase, why lenders test whether you could manage higher repayments, and how to plan for vacancies or changes in your circumstances. Mortgage Suite helps borrowers compare suitable lending options and structure finance as their plans develop. If a mainstream bank has declined your application, that doesn’t necessarily mean your options have run out.

Key Takeaways

  • Start with clear property and personal goals, then set a pace your household budget can support.
  • See how to build a property portfolio nz by understanding how lenders may weigh your income, expenses, existing debt and proposed repayments.
  • Compare buying one property at a time with a faster purchase plan, and weigh using available equity against building savings.
  • Check whether your budget could handle vacancies, income changes, repayments and property upkeep before taking on another loan.
  • Organise your finances and compare lending paths so your plan can adapt as your circumstances change.

How to build a property portfolio in NZ: start with a clear plan

Buying a second property can feel like a major financial step. You’re not only deciding whether a particular home suits your plans; you’re taking on another loan and the responsibilities that come with it. A useful starting point for how to build a property portfolio nz is to decide what you want property ownership to do for you, and what level of debt your household can manage comfortably.

A property portfolio is a group of properties held for investment, rather than a single purchase considered on its own. It might grow through separate purchases over time. But owning several properties isn’t a plan by itself: each purchase needs to fit your borrowing, income and ability to manage the ongoing commitments. For a broad introduction, you can explore these real estate investing principles.

What does building a property portfolio involve?

Portfolio growth is usually a sequence of decisions, not one large transaction. After each purchase, your finances and options may look different, so pause and review before taking another step. More properties don’t automatically mean a better financial outcome. Your plan needs to account for the loans and responsibilities attached to each property, not just the number you own.

Set goals before you look at another property

Start by asking what you want property ownership to support. Then consider your timeframe, how steady your income is and what commitments your household already has. Set a debt level that leaves room in your budget for everyday needs and unexpected changes. These answers can help you decide whether another purchase fits your priorities now, later or not at all.

Write down your starting point before browsing listings. It can help to consider:

  • Your purpose: What do you want property ownership to contribute to your longer-term plans?
  • Your timeframe: Are you comfortable holding a property for the period your plan requires?
  • Your income: Could you manage the commitments if your income changed or became less predictable?
  • Your debt limit: What level of repayments would still feel manageable alongside your other obligations?

Be realistic about the difference between a goal and a borrowing limit. A lender’s assessment can show what may be possible, but it doesn’t decide what feels right for your household. Leave room for property ownership and maintenance, as well as changes that could affect your income or budget. That breathing space matters more than reaching a particular portfolio size.

Growing a property portfolio won’t suit every household or financial situation, and there’s no need to rush. Let your portfolio grow at the pace your finances can support, not the pace a lender may allow. If the numbers or your circumstances don’t feel settled, taking time to strengthen your plan is a sensible next step.

How lenders assess finance as your NZ property portfolio grows

As your property plans develop, a lender will look at your overall borrowing, not just the value of the next property. Existing home and property loans, income, household expenses and proposed repayments all help shape whether a new loan may be affordable. Assessments vary between lenders, so an earlier approval or decline won’t necessarily determine the outcome of a later application.

How equity and borrowing capacity fit together

Equity is the difference between a property’s current value and the lending secured against it. If the property’s value rises or the loan balance falls, your equity may increase. But that doesn’t automatically mean you can borrow more. A lender also needs to consider whether your income can support repayments on both existing and new loans. Available equity and borrowing capacity are related, but they aren’t interchangeable.

For example, you may have equity available while your household budget has little room for another repayment. In that case, the equity alone won’t show whether another purchase is manageable. The property type and lender requirements may also affect how the property is viewed as security for lending. If you’re weighing up finance for a rental purchase, this guide to mortgage lending concepts can help you get familiar with the basics.

What lenders may consider across multiple properties

A lender may review your existing repayments alongside your regular income, household commitments and the proposed repayments for the new loan. It may also consider rental income, but lenders can treat that income differently. Don’t assume the full rent will count towards your application. The same applies to property-related expenses. Current lender criteria matter.

The assessment may also include a serviceability stress test, which checks whether repayments could remain manageable if interest rates were higher than the rate offered. This helps explain why a loan that looks affordable at today’s repayment level may be assessed differently. Ask your mortgage adviser to explain the assessment assumptions in plain English, including how existing lending and rental income have been treated.

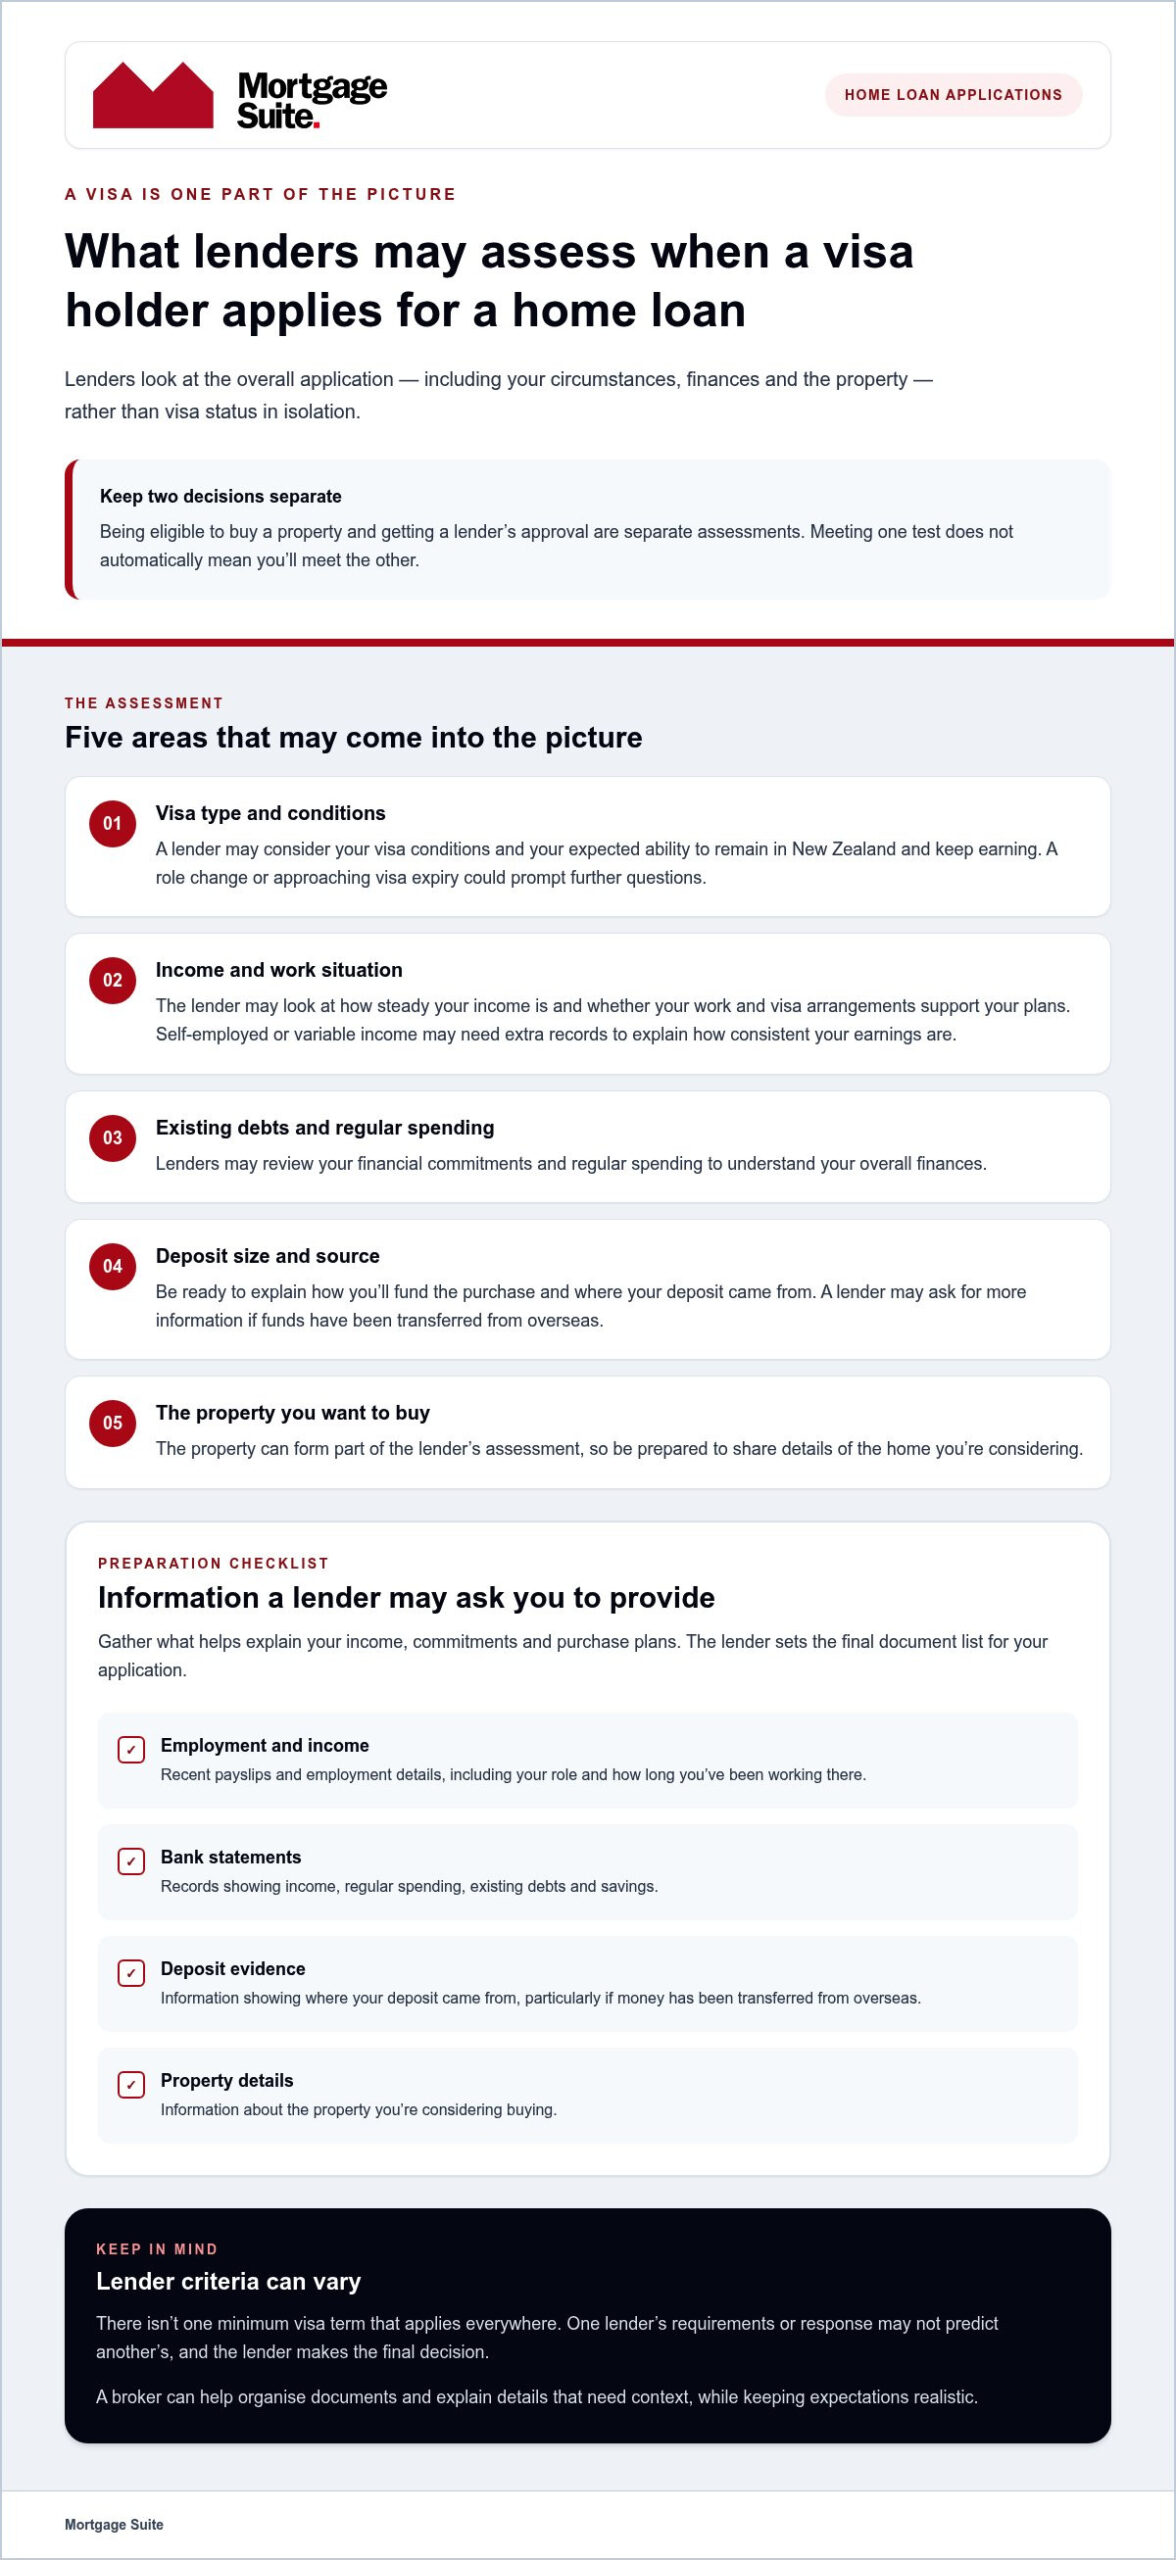
To prepare, organise an up-to-date view of your finances before discussing another purchase. Include:

  • All current lending: balances, repayments and any changes you already expect.
  • Household income and commitments: regular income alongside everyday expenses and other debt.
  • Rental details: income received and property-related expenses, while allowing for the lender’s own approach.
  • The proposed loan: expected repayments and how they fit with your existing commitments.

A clear picture makes it easier to compare possible lending paths and spot gaps before you commit to a purchase. A mortgage adviser can help present your circumstances to suitable lenders and negotiate a structure that fits your plans. If one mainstream bank says no, that isn’t automatically the end of the conversation. As you consider how to build a property portfolio nz, focus on understanding the reasons behind an assessment and which options may suit your situation.

Compare property portfolio strategies before choosing your next step

There’s no single route that suits every borrower. The right approach depends on how steady your income is, how much room your budget has for repayments and how much time you have to review each decision. A mortgage assessment can help you understand possible lending paths, but it doesn’t tell you whether a property is suitable or what return it might deliver. Consider the property choice and the finance separately.

One purchase at a time or a faster sequence?

Buying one property at a time gives you a chance to see how each new commitment affects your finances before deciding what comes next. A faster sequence may add properties sooner, but it also means taking on commitments closer together. Neither approach is automatically better. Consider how much time you want between decisions and whether your income and budget could manage the pace if circumstances change.

Approach What to weigh up
One purchase at a time More time to review repayments, income and commitments before another application, though progress may be slower.
Faster purchase sequence May add commitments sooner, so consider whether your budget and income can carry them without relying on everything going to plan.
Use available equity Could provide funds towards a purchase, but any extra borrowing adds repayments and still needs to fit lender criteria.
Build savings for a deposit Can reduce the need to borrow for the deposit, but waiting may affect your timing and requires consistent saving.

Using equity or building a deposit

Using equity means seeking further lending against value held in a property. Building savings means setting money aside towards a deposit instead. Equity may make a purchase possible sooner, but it can increase total debt and repayments. Saving first may mean waiting longer, while giving you time to build your deposit. Neither route guarantees approval or makes a property a sound choice. Compare both against your likely repayment capacity and timeframe.

Before settling on either path, consider what would happen if your income fell, expected rental income changed or a property needed attention. A plan that only works under ideal conditions may leave little room to adjust. Think about how much flexibility you want to keep and whether taking on another commitment now fits your broader financial priorities.

Use plain-English mortgage learning resources to get clearer on the lending concepts behind your options. Then compare possible finance structures against your goals, rather than choosing a purchase pace first and trying to make the borrowing fit afterwards. That’s a practical starting point for how to build a property portfolio nz while keeping the focus on a pace your finances can support.
How to Build a Property Portfolio in NZ: 2026 Guide

Check portfolio resilience before taking on another property

Before adding another loan, look beyond whether the repayments fit your budget today. A portfolio can feel manageable while income is steady and properties are occupied, but vacancies, repairs or changing household circumstances can alter the picture. A practical resilience check helps you spot pressure points before you commit.

Stress-test the household budget

A lender’s assessment and your own comfort level are two different checks. A lender decides whether an application fits its criteria; you need to decide whether repayments leave enough room for everyday needs and unexpected changes. Try the mortgage repayment calculator to explore how repayments may change under different assumptions. Treat it as a planning aid, not an approval estimate or a promise of what a lender will offer.

Work through this check before each purchase. Be honest about less favourable circumstances, not just the version where every payment arrives on time and nothing needs fixing.

  • 1. Repayments: Map the repayments for all your loans together. Would they remain manageable if rates or other household expenses rose?
  • 2. Income changes: Consider how a drop in household income, fewer work hours or a change in employment could affect your ability to meet commitments.
  • 3. Rental vacancies: Allow for a period when a property has no tenant and rental income pauses. Could you still cover its loan and other regular commitments?
  • 4. Repairs and upkeep: Think about routine maintenance as well as an unexpected repair. Does your budget have room to respond without disrupting essential household spending?
  • 5. Loan fit: Check how each loan’s repayments and structure fit with your other commitments and the plans you have for the coming years.

Plan for vacancies, repairs and changing circumstances

A suitable financial buffer can help you manage a gap in rent or property work that can’t be put off, but the right amount depends on your circumstances. Set a level that reflects your household commitments, property needs and capacity to save. Don’t rely on rent being received without interruption. Revisit the plan when your income, expenses or borrowing changes, and before taking on another property.

Keep the scope clear, too. A mortgage review can help you understand how lending fits your plans, but it doesn’t replace separate tax, legal or property-investment advice. Those matters may need input from the relevant professional. The Mortgage Suite website has information about lending options. A clear view of your commitments can help you decide whether the next step feels manageable, not simply possible.

Build your property portfolio with a finance plan that can adapt

A useful finance plan isn’t a timetable that says you must buy again by a certain date. It’s a way to keep your borrowing choices connected to your goals, income and changing commitments. If you’re considering how to build a property portfolio nz, focus on making the next decision with a clear view of what you owe, what you can manage and which finance paths may suit.

When a mortgage adviser can help

Before pursuing another purchase, an adviser can help you review your borrowing as a whole, including current loans, income and the new commitment you’re considering. They can compare lending options across suitable lenders and negotiate on your behalf, explaining how loan structure may affect your plans. The aim is to help you understand your choices, not to promise a particular rate, approval or outcome.

A mainstream-bank decline can be disappointing, but it doesn’t automatically close off every finance option. Another lender may assess your circumstances differently, depending on its current criteria and the details of your application. Mortgage Suite acts as a personal advocate through that process, helping you understand the options available and what each may mean for your wider borrowing picture.

Turn the plan into practical next steps

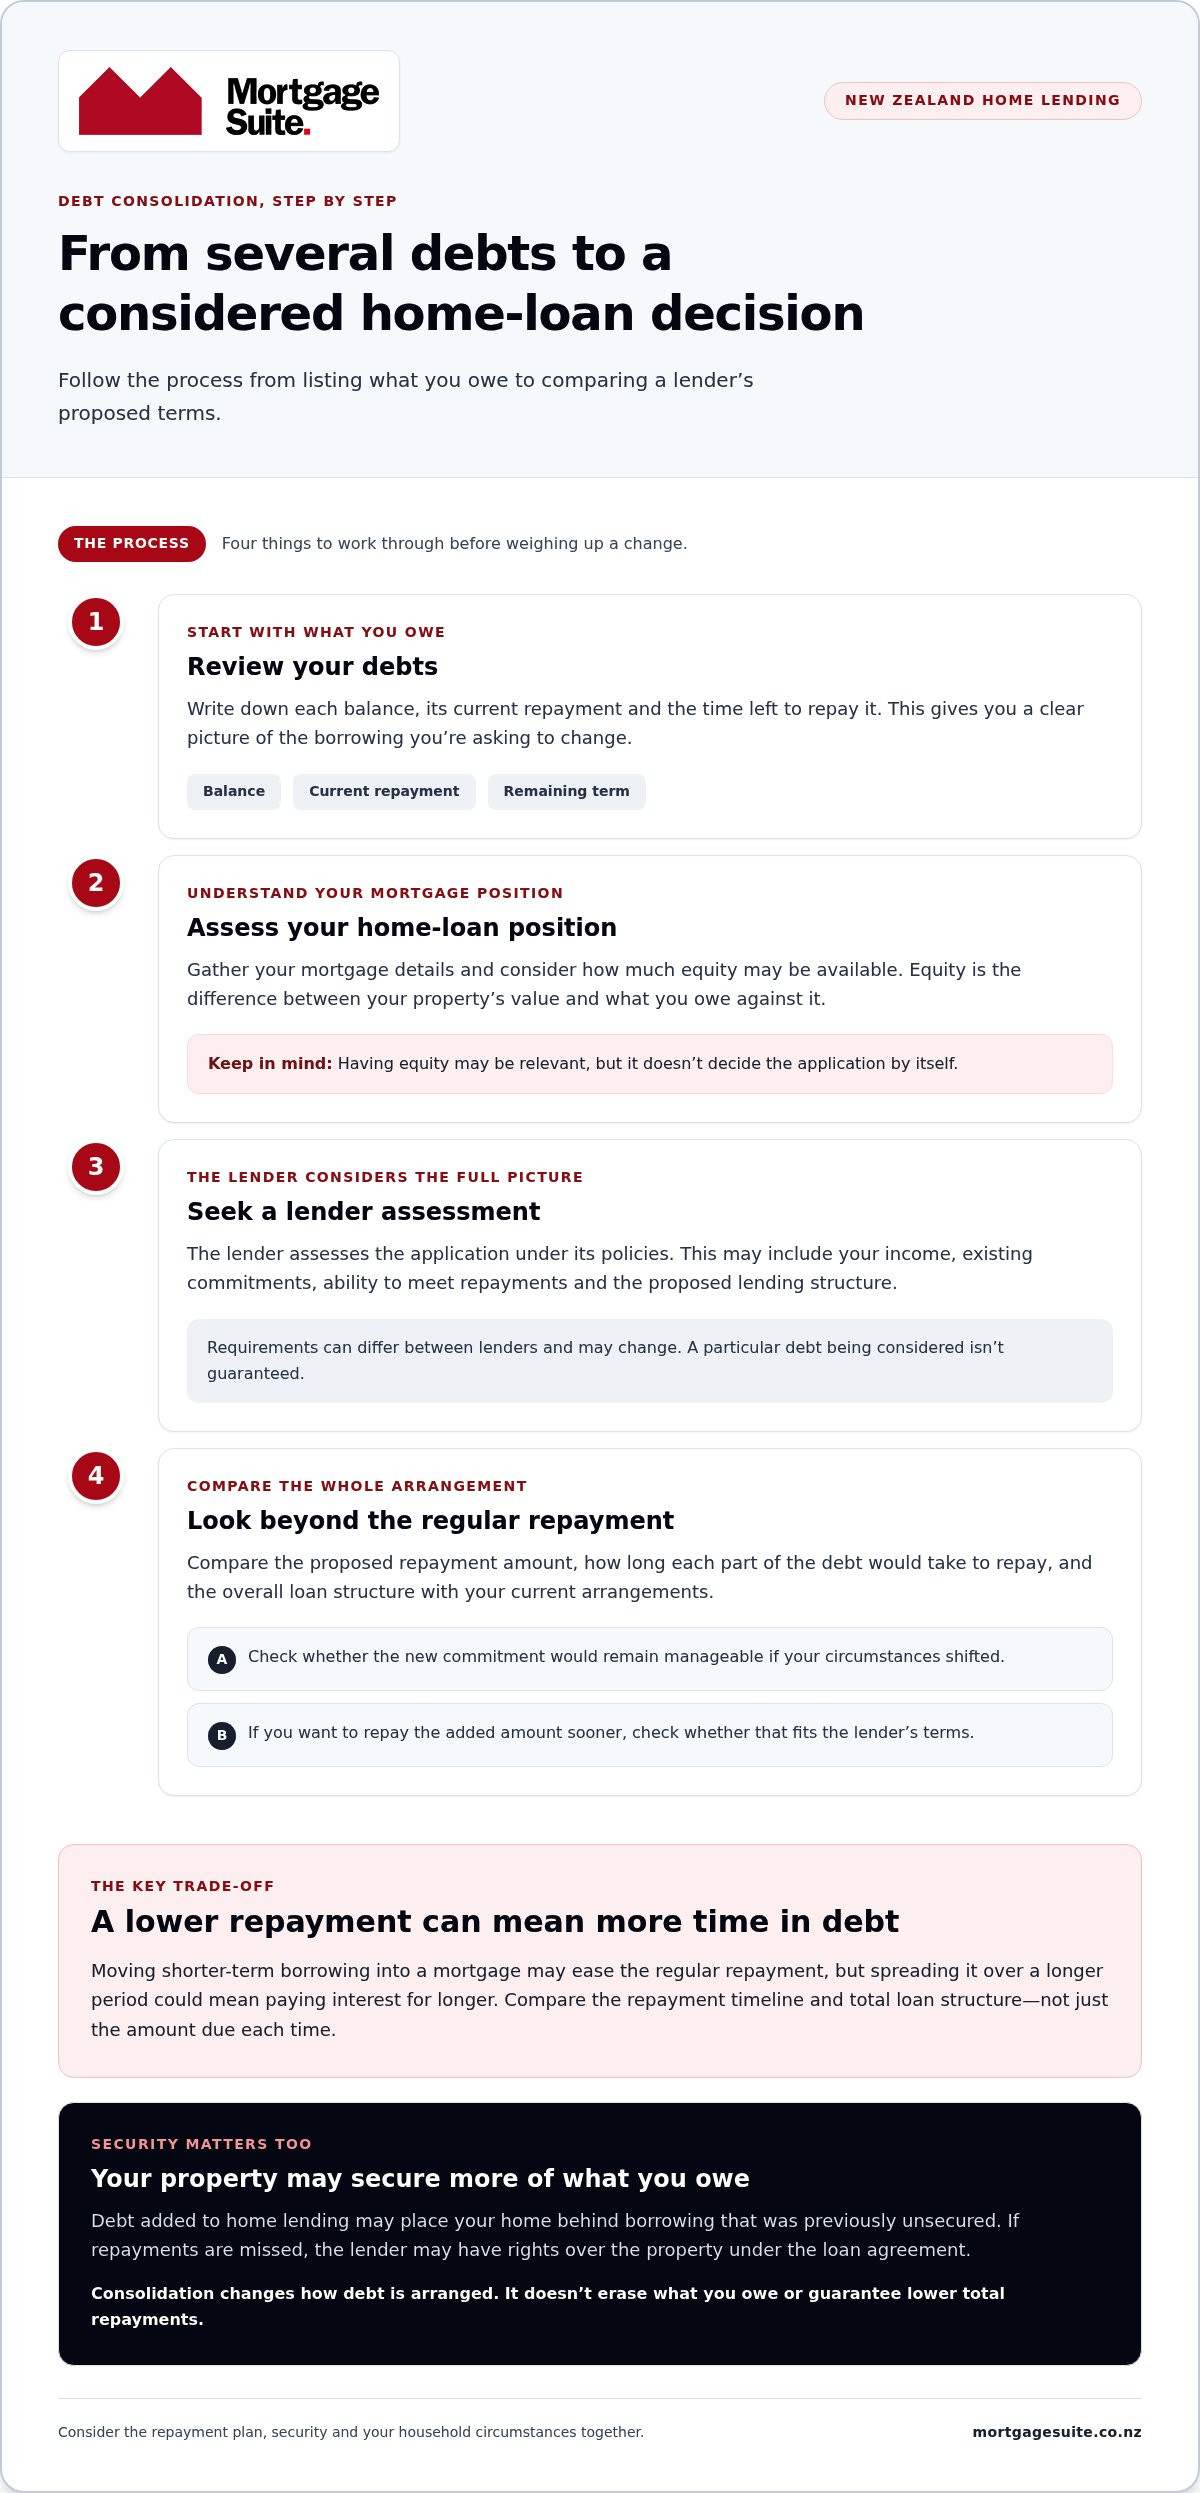
Get your information organised before a finance discussion. A clear picture makes it easier to identify questions, compare possible paths and work out what needs attention before you proceed. You can start with these steps:

  • Organise your finances: Gather details of your income, regular expenses, savings and existing lending.
  • Map your commitments: Include repayments and the ongoing responsibilities attached to each property.
  • Compare lending paths: Discuss how different lender criteria and loan structures may fit your plans.
  • Review your readiness: Consider whether the proposed commitment still feels manageable if circumstances change.

Then review the plan after a major change, such as a shift in income, new household commitments or a change to your existing lending. Revisit it before each purchase, too. A plan that fitted last year may need adjusting now, and there’s no need to follow someone else’s buying schedule.

Mortgage Suite’s team can support you as you consider your next finance decision. The Mortgage Suite website explains how to start a conversation about a property finance plan and explore a suitable way forward.

Make your next property decision with confidence

Your plan doesn’t have to map out every purchase from the start. Treat it as a working guide: revisit it as your income, commitments and goals change, and let those changes shape your next move. That gives you room to pause, adjust or proceed when the finances make sense for your household.

If you’re still considering how to build a property portfolio nz, a conversation about the lending side can help you understand the paths available. Mortgage Suite supports residential investment property borrowing and can discuss mainstream and alternative lending options. Founder Krish Krishna brings over two decades of banking experience to helping borrowers work through their finance choices. No lender can promise an outcome, but you can make your next decision with a clearer view of your options.

Talk through your property finance plans with Mortgage Suite when you’re ready to take that next step. A steady, considered pace can help you move towards your goals while keeping your household’s financial wellbeing in view.

Frequently Asked Questions

Can I build a property portfolio with only one investment property to start?

Yes, a property portfolio can begin with one investment property. Owning it doesn’t mean another purchase will suit your household, though. First, decide what you want the property to support and how long you expect to hold it. Then list your existing loan repayments and other commitments, and review your borrowing capacity before planning a next step. There’s no required property count or guaranteed route to growth.

Does having equity mean I can buy another investment property?

No, equity alone doesn’t mean you can buy another property or that a lender will approve a new loan. A lender may also consider your income, existing debt, expenses and the property offered as security. For example, having value available in one property won’t necessarily resolve a tight household budget. Look at whether repayments would be affordable as well as how much equity may be available.

How many properties should I have in a portfolio?

There’s no single number that suits everyone. If you’re considering how to build a property portfolio nz, start with what fits your goals, income, borrowing capacity and comfort with risk, rather than aiming for a particular count. For one household, keeping a single rental property may be the right fit; another may have room to grow over time. Judge progress by whether each commitment remains manageable, not by comparing portfolio sizes.

Can rental income help me qualify for another property loan?

It may help, but lenders can assess rental income in different ways. Don’t assume every dollar of rent will count in full or that rent will cover all your existing commitments in a lender’s assessment. For instance, a lender may take a cautious view of expected rent while still considering your other income and expenses. Review rental income alongside your full financial position and the lender’s current criteria.

Should I use equity or save a deposit for my next property?

Either approach may suit, depending on your circumstances. Using equity may mean taking on additional borrowing and repayments; saving towards a deposit may take longer but change how much you need to borrow. Compare the options against your timeframe, existing commitments and ability to manage repayments if circumstances shift. Before deciding, review the full lending position rather than treating available equity or savings as the only factor.

What happens if a bank declines my next property loan?

A decline isn’t a personal judgement, and it doesn’t automatically end every finance option. Start by understanding the reasons for the decision, such as how the lender viewed your income, commitments or property details. Another lender may assess your circumstances differently, but approval isn’t guaranteed. A mortgage adviser can review your position and discuss suitable mainstream or alternative lending pathways where appropriate.

Is it risky to build a property portfolio using borrowed money?

Borrowing adds repayments, so changes to income, property expenses or lending conditions can affect your household budget. The level of risk depends on your circumstances and how the lending is structured. Before taking on more debt, test your budget against less favourable conditions, consider a financial buffer that suits your situation and review your loans regularly. Property ownership isn’t risk-free, so avoid relying on everything going to plan.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Land Development Loans: Your 2026 Guide to Funding Your NZ Project

What if a bank’s “no” isn’t the end of your subdivision plans? If you’re looking for a land development loan, it can be hard to know where to turn when a mainstream lender isn’t comfortable with your project. The process can feel complicated, especially when you’re working out how to fund the land, the site preparation and the work needed to create new sections.

You deserve a clear explanation of your options, not a pile of lending jargon. This guide explains how lenders may assess a project, how funds can be released as work progresses, and what to plan for, from council requirements to site preparation and services.

Mortgage Suite’s Krish Krishna brings more than 20 years of banking experience to property development lending. He understands how lenders assess proposals and can advocate for you when your plans don’t fit a bank’s usual approach. We’ll walk through how to prepare your project, compare funding options and present a practical plan, so you can make informed decisions with greater confidence.

Key Takeaways

  • A land development loan can help fund more than the land itself, including work to prepare it for subdivision.
  • Break your funding needs into stages, from buying the land to completing the work and deciding what happens next.
  • If a mainstream bank says no, second-tier lenders may offer another path, depending on your project and circumstances.
  • Prepare a clear plan showing how the development could work, and bring together a capable team to support it.
  • An experienced lending guide can help you understand your options and present your project clearly to potential lenders.

What is a land development loan and how does it actually work?

A land development loan can fund a subdivision and the work needed to turn undeveloped land into prepared sections or a site ready for building. It’s different from a loan to buy a home, because the project centres on improving land rather than purchasing a finished place to live.

Depending on the project, funding may cover earthworks, pipes, roads and other work needed to make the land usable. Civil works means preparing the site and putting essential connections and access in place. The specific work depends on the land and the subdivision plan.

Land development usually involves several steps, from planning and preparing the site through to creating new sections. For a simple overview of the process, see What is land development? A development loan is generally intended to support a project over a shorter period than a typical home loan, with the aim of completing the work so you can sell the sections or build on them. The repayment plan needs to match that goal.

Why a standard home loan usually will not cut it

A standard home loan is designed around buying a home. A bare block has no finished house to live in, and its value may depend on work that hasn’t happened yet. That can make undeveloped land more difficult for a mainstream bank to assess.

Development funding needs to account for the plan as well as the land’s current value. A lender may consider what you intend to do, the work required and how the completed project could be sold or used. The funding and repayment plan may also be structured around the project rather than a standard home-loan setup.

The difference between “buying” and “developing”

Buying the land is the acquisition stage: ownership changes hands, but the site may still be untouched. Developing is the work that follows, such as preparing the ground, installing pipes and creating roads so the land can be divided or built on.

Because these stages have different funding needs, one arrangement may not suit the whole journey. You might need funds to secure the block first, followed by suitable finance for the work. Mapping out each stage helps show a lender what the money is for and how the project is expected to progress.

Be clear about your end goal from the start. Selling prepared sections and building homes are different plans, and your funding approach should reflect the one you’re pursuing. You don’t need every detail finalised before discussing finance, but it helps to have a clear picture of the land, the work ahead and what you hope to achieve.

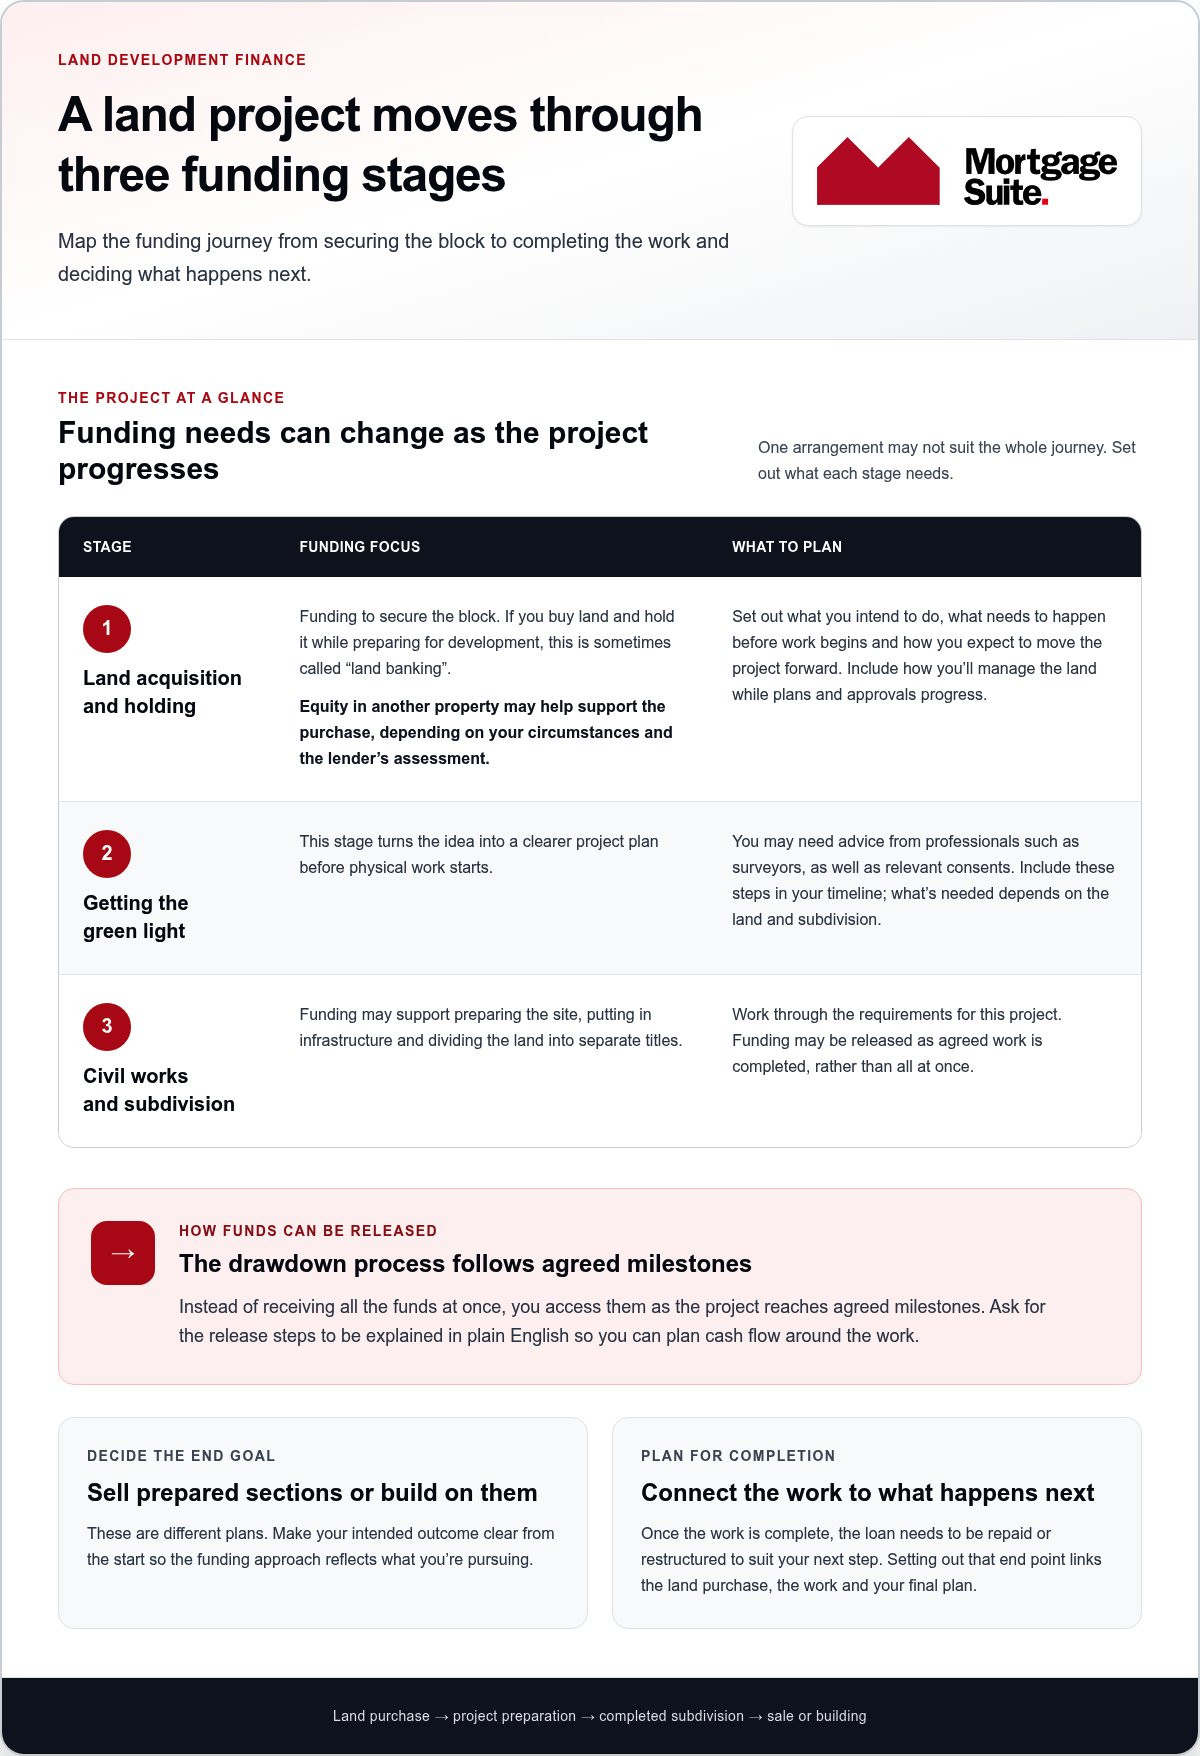
The three main stages of funding your land project

A subdivision usually moves from buying the land to preparing it, completing the work and then selling or building. Your funding needs can change at each step, so map the whole journey early rather than focusing only on the purchase.

Stage 1: Land acquisition and holding

First, you need funding to secure the block. If you buy land and hold it while preparing for development, this is sometimes called “land banking”. Even if the diggers aren’t on site yet, set out what you intend to do, what needs to happen before work can begin and how you expect to move the project forward.

Equity in another property may help support the purchase, depending on your circumstances and how a lender assesses the overall plan. It isn’t an automatic solution, but it can be part of the funding picture. Include the holding period in your plan too, so you understand how you’ll manage the land while plans and approvals progress.

Stage 2: Getting the green light

Before physical work starts, you may need advice from professionals such as surveyors, as well as relevant consents for your proposal. This stage turns an idea into a clearer project plan. The steps depend on the land and the subdivision, so include them in your timeline rather than assuming everything can happen at once. New Zealand’s planning framework is changing; the Government’s update on planning laws for land development is useful context as you consider how planning rules may affect a project.

Stage 3: Civil works and subdivision

Once the project is ready to proceed, the work may include preparing the site, putting in infrastructure and dividing the land into separate titles. This is where one block can become several sections, but progress depends on completing the work required for that particular project.

Funding may be released in stages as agreed work is completed. This is called the drawdown process: instead of receiving all the funds at once, you access them as the project reaches agreed milestones. Ask for the release steps to be explained in plain English, so you can plan cash flow around the work.

At the finish: once the work is complete, you may plan to sell the new sections or build on them. The loan then needs to be repaid or restructured to suit what happens next. Setting out that end point early connects the land purchase, the work and your final plan into one funding story.

Banks vs Non-bank lenders: Finding the right fit for your land

A mainstream bank’s “no” can be discouraging, but it doesn’t automatically mean your project has no way forward. Banks often use set lending rules designed for more straightforward proposals. A subdivision can be harder to assess because the land still needs work before it can be sold or built on, and the outcome depends on several steps being completed.

Non-bank, or second-tier, lenders are professional lending organisations, not simply a last resort. They may assess the project plan and how it could reach completion alongside your personal finances. Their approach and terms can differ from a bank’s, so the right fit depends on your proposal and circumstances. Flexibility may help a project proceed, but it’s still important to understand the repayment plan and how the loan fits your wider goals.

When a mainstream bank may fit

A bank may suit a straightforward project if you have a clear plan, a sound financial position and enough funds available to manage the work. Banks may offer lower interest rates, but their assessment can involve detailed paperwork and firm requirements. A strong credit history may help, though lenders consider the full application. The key is whether the bank’s criteria suit your project, not just whether its rate looks appealing.

For example, a simple subdivision with a well-prepared plan and resources to manage changes may fit a bank’s usual approach. If the project has unusual features or your circumstances fall outside its standard checks, the application may be more difficult to assess. That’s a reason to understand the bank’s decision, not to assume the project itself has no merit.

The second-tier option for developers

A second-tier lender may assess a land development loan by considering the project’s purpose and expected outcome, as well as your personal finances. This can help if your proposal has a clear plan but doesn’t fit a bank’s usual approach. Terms may differ, including the interest rate, so weigh any added flexibility against the full repayment arrangement.

Timing can matter if contractors are booked or work is ready to begin. Non-bank lenders may assess proposals differently, but approval timeframes vary. A clear plan and organised information can help explain what you need funding for and how the project is expected to progress.

Mortgage Suite specialises in property development and second-tier lending. Krish Krishna brings more than 20 years of banking experience and can help you understand lender expectations and present your proposal clearly. If your application has been declined, reviewing the reasons and considering a suitable alternative funding approach can help you decide what to do next.

Land Development Loans: Your 2026 Guide to Funding Your NZ Project

Getting your ducks in a row: How to qualify for a land loan

A clear, well-prepared application helps a lender understand what you want to do and how the project could work. Before applying for a land development loan, set out the plan, the people supporting it and how you expect the project to reach its end goal. A past development can strengthen your case, but a capable team, such as surveyors and other relevant specialists, can also show that you’ve thought through the work.

Be clear about your equity, meaning the money or property value you’re contributing yourself. It shows how much of your own resources are going into the project. The amount and type of contribution a lender expects will depend on your circumstances and proposal, so explain what you can bring to the table without assuming one formula applies to every project.

What to prepare for your application

Get your paperwork together early, before the right block appears and the pressure is on. A lender may want to understand whether the numbers add up, what permissions or consents apply, and how the borrowing will be repaid. A useful preparation list includes:

  • A feasibility study: Does the plan make financial sense? Set out the expected project steps and how the figures support them.
  • Planning and consent information: Include relevant council information for your proposal, such as resource consent details where applicable. Requirements can vary by project.
  • A clear exit plan: Explain how you expect to repay the lending, for example by selling completed sections or moving on to the next stage of the project.
  • Supporting documents: Gather the land details, project plans and information from the professionals helping you prepare the development.

You don’t need to present yourself as a developer who has done it all before. A realistic plan and a team with relevant experience can help explain how the project will be managed. Be upfront about any parts still in progress, too. That gives the lender a clearer picture than leaving gaps for them to fill in.

How a mortgage adviser can help you prepare

Krish Krishna brings more than 20 years of banking experience to property development lending. He can help organise your application so the purpose, figures and proposed repayment plan are clear before it reaches a lender. That means explaining the project in a way lenders can assess and helping you compare options that may suit your circumstances.

To get a starting view of your figures, use our mortgage calculator. It’s one part of preparation, not a decision on whether a lender will approve development funding. Your application still needs to show how the project fits together. Getting organised early can make it easier to act when a suitable block comes along.

Why a seasoned expert makes all the difference for your development

A development project has a lot of moving parts, and explaining them to a lender can feel like a job in itself. Krish Krishna brings more than 20 years of banking experience to Mortgage Suite, helping make sense of lender expectations and how they relate to your plans.

Think of Mortgage Suite as a bridge between the lending process and what you want to achieve with your land. We can help present your project clearly, discuss suitable funding options and negotiate with lenders on your behalf. That can be useful when your proposal doesn’t fit a bank’s usual approach. A decline can be discouraging, but it isn’t a judgement on your goals or necessarily the end of the road.

Our approach is about working alongside you, not treating your land development loan as a one-off transaction. The right funding needs to fit the project and your wider plans, not just look good on paper at the start. We’ll explain the options in plain English, so you can make decisions with a clearer picture of what each path involves.

The Mortgage Suite approach

Preparing a development application takes planning and follow-through. We help with lender conversations and explain what information may be needed, so you’re not left trying to piece together unfamiliar requirements on your own. You can read our client reviews to hear about other people’s experiences. Our About Us page also shares more about the people and approach behind Mortgage Suite.

We believe Kiwis deserve a fair go at developing their land, even if a mainstream bank has been tough to deal with. That doesn’t mean every application will be approved. It means taking the time to understand your circumstances, look at the project carefully and explore a way forward where one may be available.

Taking the next step

Start by setting out what you want to do, where you are in the process and what’s making the funding feel difficult. This gives you a useful basis for understanding what lenders may want to see and which options could suit your circumstances. No jargon, no pressure, just a clearer discussion about the next steps.

If you’re weighing up a subdivision or have already had a lender say no, Mortgage Suite can help you talk through your plans and funding options. A considered conversation can help you see what may be possible and decide how you’d like to proceed.

Take the next step with a clear plan

Funding a subdivision is easier to approach when you break it into stages, understand what lenders may look for and prepare a clear plan for the work and the end goal. The right land development loan depends on your project and circumstances, so a bank’s decision isn’t the only factor to consider.

Mortgage Suite specialises in property development and non-bank, second-tier lending across New Zealand. Krish Krishna brings more than 20 years of banking experience and can help you understand lender expectations, present your project clearly and explore suitable options. No lender can promise approval, but you can get a clearer view of possible next steps.

Ready to discuss your project? Talk with Mortgage Suite about your plans and funding options. A well-prepared project can have a way forward, and you don’t have to work through the lending questions alone.

Frequently Asked Questions

How much deposit do I need for a land development loan in NZ?

There isn’t one deposit amount that applies to every project. A lender may consider the land, the work planned, your financial position and how much of your own money or property value you can contribute. This contribution is often called equity. Prepare a clear project plan and details of your available funds so a lender can assess your circumstances and explain what may be needed.

Can I get a loan if I have never developed land before?

Yes, a lack of development experience doesn’t automatically rule you out. You can strengthen your application by showing a clear plan and bringing together a capable team, such as surveyors and other professionals who understand the work. A lender will still assess the project and your circumstances, so be upfront about your experience and how you’ll manage parts that are new to you.

What happens if the bank has already declined my application?

A bank’s decision isn’t necessarily the end of your options. Find out what made the application unsuitable, then consider whether a different lender may assess your project another way. Mortgage Suite specialises in property development and second-tier lending for borrowers who don’t fit mainstream bank criteria. Krish Krishna can help you understand the feedback and present your plans clearly, though no lender can guarantee approval.

How long does it typically take to get a land development loan approved?

There’s no set timeframe for every application. The time needed can depend on the project’s complexity, the information available and the lender’s assessment process. A straightforward proposal with organised documents may be easier to assess than one with unanswered questions about the work or repayment plan. Gather your land details, project plans and supporting information early, and allow time for the lender to review them.

Do I need to have resource consent before I apply for funding?

Not always. The right timing can depend on the project and the lender. Some funding discussions may begin while plans or consent steps are still underway, but a lender will want to understand what approvals are relevant and where you are in the process. Be clear about what’s been completed and what remains. Don’t present a proposed subdivision as approved if it isn’t.

What is the difference between a land loan and a construction loan?

A land loan generally helps fund the purchase or holding of a block, while a construction loan is used for building work. A subdivision may also need funding for site preparation and infrastructure, such as roads and pipes. The right arrangement depends on what you’re doing and when. Explain each project stage so the proposed funding matches the work, rather than assuming one loan type covers everything.

Is it more expensive to use a non-bank lender for my subdivision?

A non-bank lender may have a higher interest rate or different terms than a mainstream bank, but the right comparison goes beyond the rate alone. Look at how the funding is structured, what flexibility it offers and whether it fits your project timeline and repayment plan. Non-bank lending isn’t automatically the right choice, but it may be an option if a bank’s standard criteria don’t fit your proposal.

Can I use the equity in my family home to fund a land development?

It may be possible to use equity in your home as part of the funding plan, depending on your finances and the lender’s assessment. Equity is the portion of your home’s value that isn’t covered by lending against it. Using your home this way can put it at risk if repayments aren’t met, so consider the impact on your household and get clear advice before deciding.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How Much Can I Borrow for a Business Loan in NZ? 2026 Guide

What if the amount your business needs is more than a lender is prepared to offer? If you’re asking how much can i borrow for a business loan nz, the answer depends on more than turnover. Lenders consider whether your business can manage the repayments, its existing commitments, what the loan is for and whether you can offer security, such as property or another asset.

It’s understandable to feel unsure, especially if your income varies or your finances are more involved than a standard application. Borrowing capacity is the amount a lender may consider manageable. Your funding goal is what you need to move the business forward. Those amounts don’t always match, but understanding the difference can help you plan your next steps.

This guide explains what can shape a business loan assessment, how the loan purpose and security may affect your options, and what to organise before discussing finance. Mortgage Suite arranges business loans, commercial property finance, property development loans and 2nd tier lending. Founder Krish Krishna brings more than two decades of banking experience. A decline from a mainstream bank doesn’t necessarily close the door; your next step depends on your circumstances and which lending approach may fit.

Key Takeaways

  • There’s no single figure for how much can i borrow for a business loan nz. The amount depends on your business’s ability to manage repayments and the details of your plans.
  • Organise clear financial records and trading information so lenders can understand how your business is performing.
  • Compare finance structures by what the funds are for, how repayments work and whether security is involved.
  • Before applying, set out how much you need, when you need it and what commitments your business already has.
  • A mainstream bank’s decision is one factor, not the whole picture. Business, commercial property, development and alternative lending pathways may also be worth considering.

How much can you borrow for a business loan in NZ?

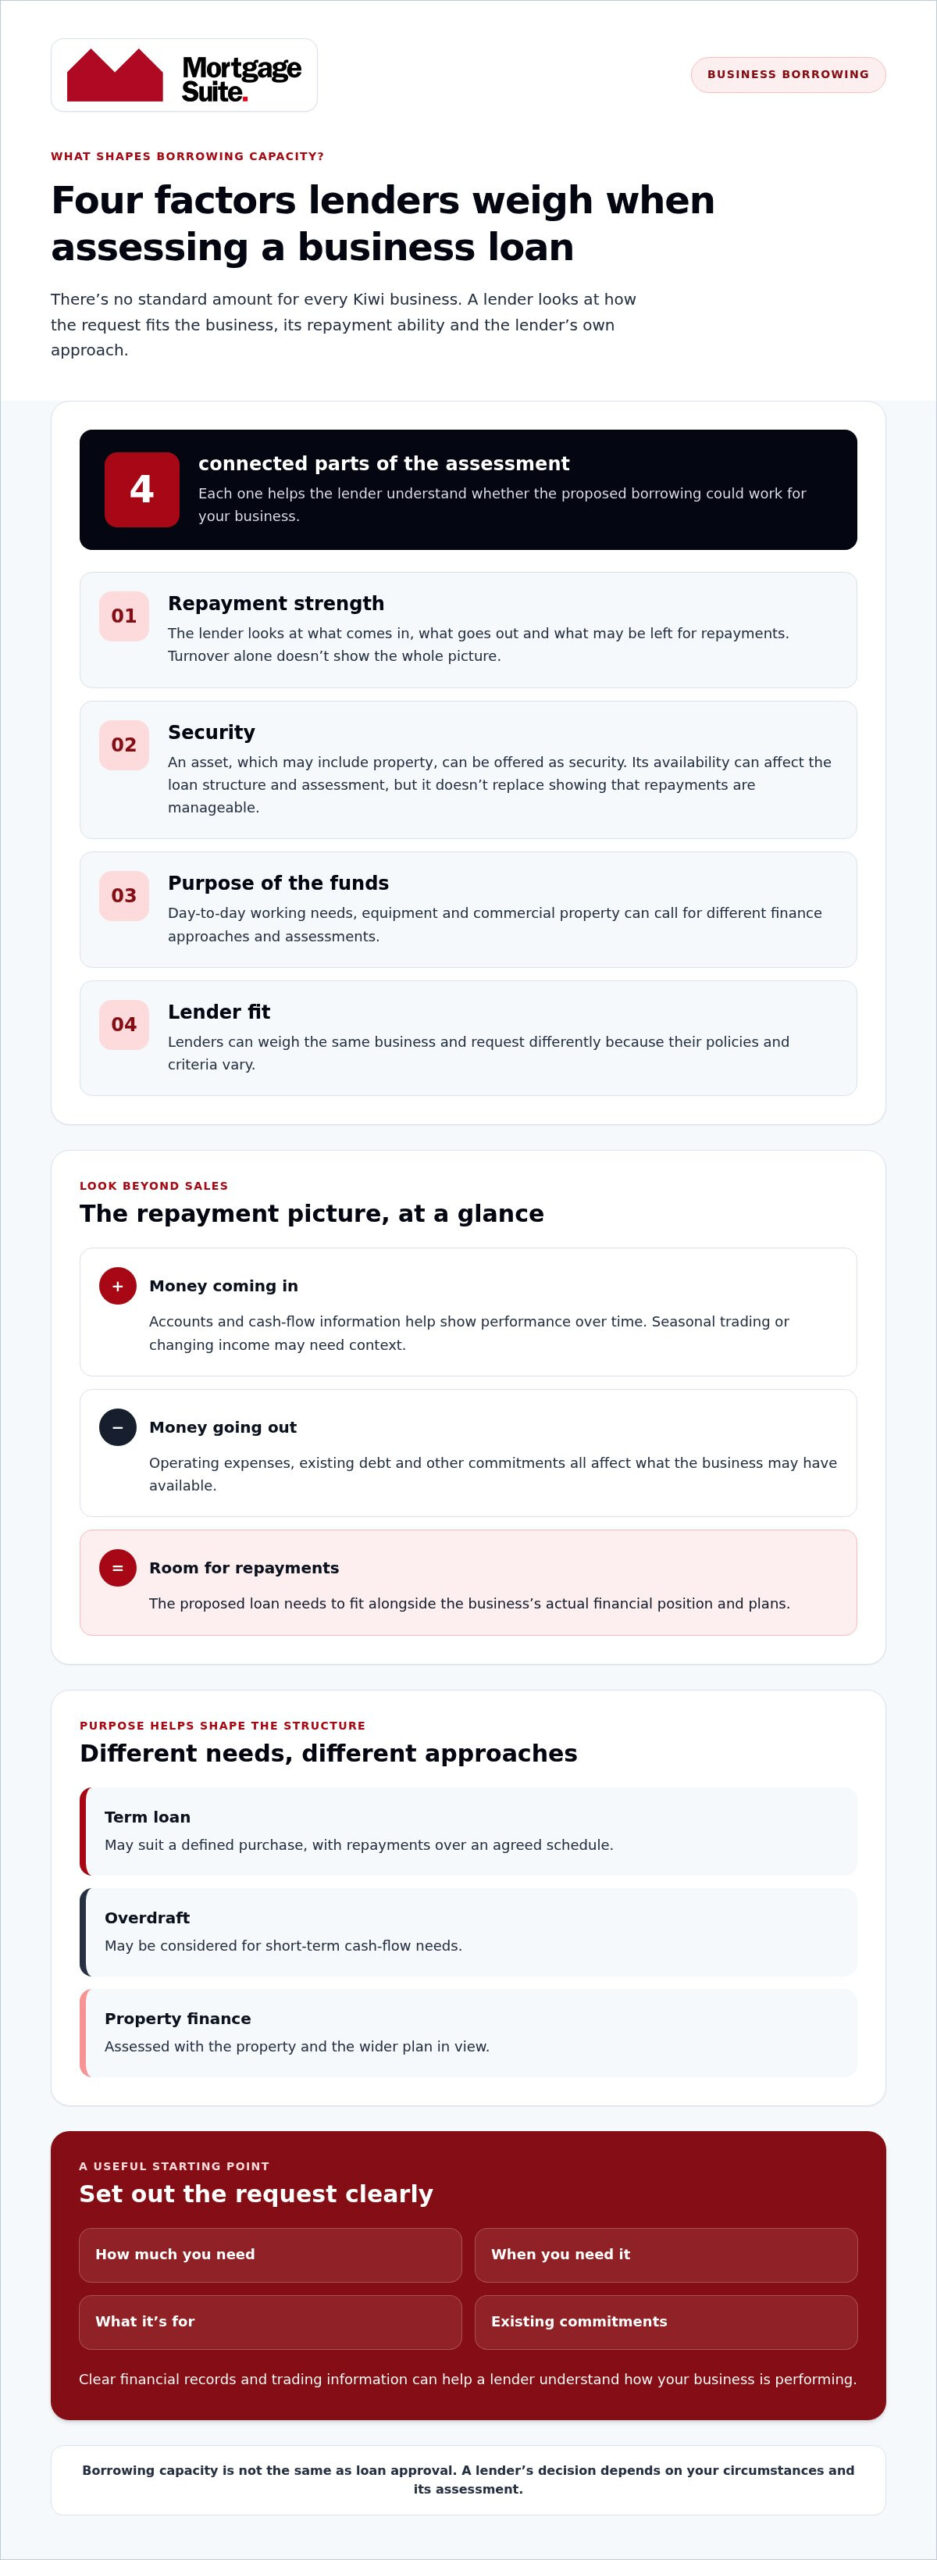
It’s difficult to estimate a borrowing limit without looking at the business, the purpose of the funds and how repayments could fit its plans. There isn’t a standard figure that applies to every Kiwi business. A useful starting point is to separate the amount you want from the amount the business could reasonably repay.

Why there is no standard business loan amount

Businesses can look very different on paper. One may have steady trading and established records, while another may be newer, seasonal or planning a major change. Existing commitments matter too, as does the reason for borrowing. Funding a specific purchase, managing a cash-flow gap or supporting growth may each call for a different assessment.

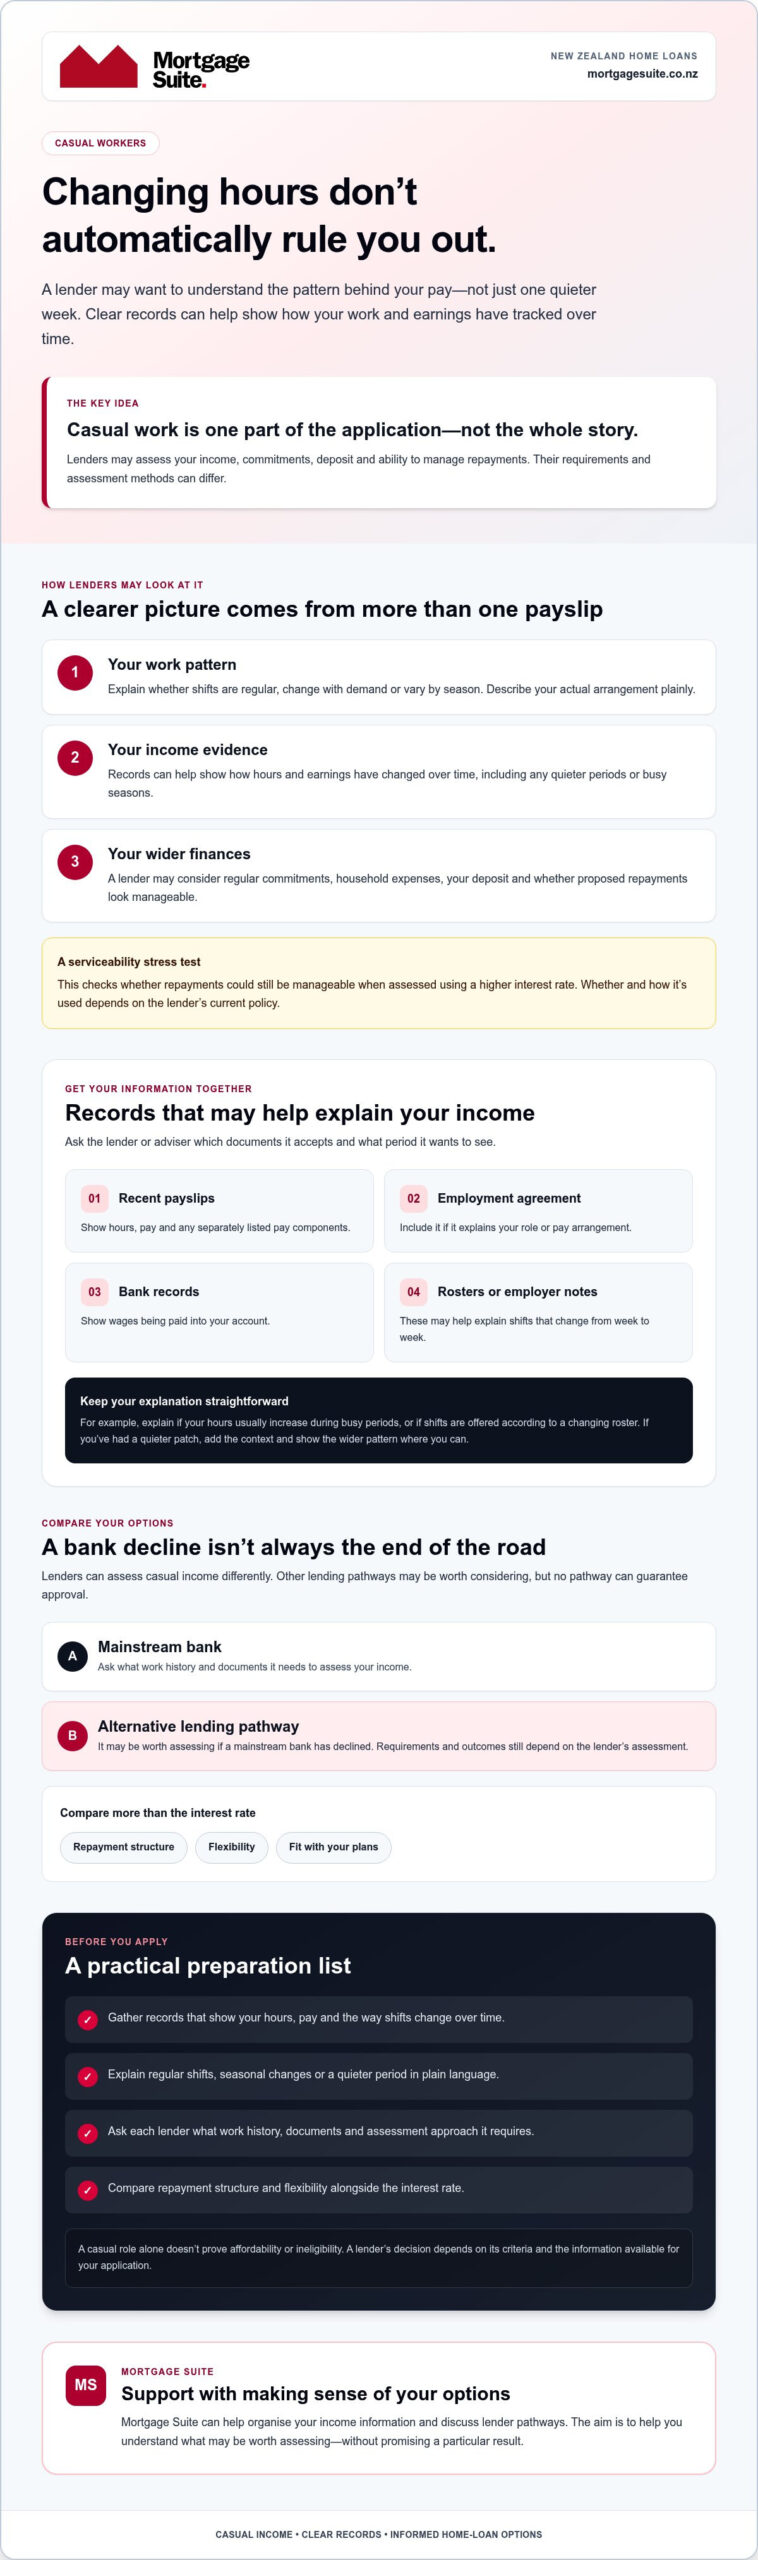
Borrowing capacity is the amount a lender may consider supportable after reviewing a business’s ability to make repayments and other relevant factors. Lenders have different policies, and they may view the same business differently. For a plain-English introduction to business loan basics, including secured and unsecured borrowing, see this overview of a Business loan.

A calculator or quick estimate can be a starting point, but it won’t account for every detail in your trading history, commitments, plans or a lender’s criteria.

Borrowing capacity is not the same as loan approval

An early estimate can help with planning, but it isn’t a full assessment or a final decision. A lender considers the information in your application and whether the proposed repayments appear manageable over time. If the repayment plan doesn’t fit the business’s financial position, you may need to reconsider the amount or structure.

For example, a business may want funds to expand, but its current cash flow may be better suited to a smaller first step or a different structure. That doesn’t mean the goal is out of reach. It means the funding plan needs to be considered alongside the business’s circumstances and the lender’s approach.

A decline from one lender can feel personal, especially after you’ve put time into an application. It isn’t a judgement on your character or your business’s potential. A decline may reflect that lender’s criteria or preferred approach, rather than every option available. Understanding why the application didn’t fit can help you decide what to adjust before exploring another path.

What determines how much a business can borrow?

A lender looks beyond sales figures to understand what money comes in, what goes out and how much may be left for repayments. The key question is whether the business could manage a proposed loan alongside existing commitments, including other debt and regular operating expenses.

Business income, performance, and existing commitments

Business accounts and cash-flow information can show how the business is performing over time. Turnover gives an indication of sales, but it doesn’t show the full picture on its own. Costs, existing repayments and changes in income all affect how much may be available for a new commitment.

Consistent earnings may give a lender a clearer repayment picture. Seasonal trading, on the other hand, can mean income rises and falls during the year. Self-employed owners may also need to explain how they draw income from the business and why it varies. That context helps a lender understand the figures rather than focus on one headline number.

Keep the picture realistic. If the business already manages several commitments, a lender will consider how a new repayment could fit alongside them, not just whether sales have been strong.

Loan purpose, security, and lender fit

The reason for borrowing helps shape the type of finance that may suit. Funding day-to-day working needs differs from buying equipment or purchasing commercial property. For example, a term loan may suit a defined purchase with repayments over an agreed schedule, while an overdraft may be considered for short-term cash-flow needs. Property finance is assessed with the property and the wider plan in view.

Security is an asset a lender may rely on if the loan isn’t repaid. A secured loan is linked to security, which may include property. With lending that doesn’t use property security, a property isn’t put forward in the same way. Available security can influence the structure and assessment, but it doesn’t replace the need to show that repayments are manageable.

Repayment strength, security, purpose and lender fit all shape how much a business may be able to borrow. Lenders can weigh these factors differently, so the same business and request may be viewed differently across applications. To work out how much can i borrow for a business loan nz, start by matching the request to a clear business purpose and a repayment plan that reflects your actual cash flow.

Mortgage Suite can help you compare business lending pathways in light of your circumstances and plans.

Which business loan approach may suit your borrowing needs?

The right structure depends on what the funds are for, how you expect to repay them and whether you can offer security. Comparing these details helps you discuss finance that fits the business purpose, rather than focusing only on the amount you’d like to borrow.

Finance approach Business-purpose fit Repayment approach Security and information to prepare
Term loan A defined business purchase or expense. A lump sum with a set repayment schedule and end date. Security depends on the lender and application. Prepare the purchase details, business accounts and cash-flow information.
Overdraft Managing short-term cash-flow needs. Provides access to funds as needed, subject to the agreed facility terms. Security requirements can vary. Explain the timing of income and expenses and how the facility would support working needs.
Commercial property finance Purchasing or refinancing commercial property. Repayments are set out under the loan agreement. The property is central to the assessment. Prepare property details, the purchase or refinance purpose and business financial information.
Property development finance Funding a property development project. The funding structure is considered in light of the project and its plans. Prepare project information, costs and timing, along with details of available security and the wider business position.

Business loan or commercial property finance?

General business lending is usually considered in relation to business activity, such as meeting working needs or funding a purchase. Commercial property finance centres on a property transaction, while property development finance relates to a development project. The asset or purpose being funded shapes the lending discussion and the information a lender may need.

If you’re buying or refinancing a commercial property, it may make sense to explore property finance rather than treat it as a general business loan. Mortgage Suite can help you consider the business purpose and property plans together.

Mainstream or 2nd tier lending?

Mainstream lenders have their own criteria, and a business, property or project may not fit the way a particular lender assesses applications. 2nd tier lending can be an alternative for some circumstances that sit outside mainstream bank criteria, but it doesn’t guarantee approval. The available structure and terms depend on the individual assessment.

How much you can borrow may partly depend on which lending approach best matches the purpose, repayment plan and available security. Mortgage Suite arranges business, commercial property, property development and 2nd tier lending, helping you compare possible paths in light of your circumstances.

How Much Can I Borrow for a Business Loan in NZ? 2026 Guide

How to prepare for a business loan assessment

Some preparation can make it easier to explain what your business needs and give a lender a clearer picture of its finances. You don’t need every answer before you start, but accurate, consistent information can make the discussion more useful.

  1. Clarify the purpose. Explain what the funds would be used for and how they would support the business. Be specific, whether you’re meeting a working need, buying equipment or funding a property project.
  2. Set out the amount and timing. Note how much you’re seeking and when you need access to the funds. Treat this as the request to assess, not proof that the full amount will be affordable.
  3. Review cash flow. Look at money coming in and regular business expenses going out. If income changes through the year, note the pattern rather than relying on the strongest trading period.
  4. List existing commitments. Record current lending and other regular repayments so you can consider how a new repayment might fit alongside them.
  5. Identify possible security. Note whether the business or its owners may be able to offer an asset, such as property, as security. The lender’s assessment will depend on the circumstances and proposed structure.

Organise the information lenders may ask about

Gather current business accounts, cash-flow information and details of existing lending. It also helps to write a short summary of what the business does, how it trades, what causes income to vary and how you plan to use the funds. Lenders may ask for different information, so focus on making the picture clear rather than assuming every application requires the same documents.

Check that the figures and explanations tell a consistent story. If income has changed or a trading period looks unusual, a brief explanation can provide useful context. This helps a lender assess the business as it operates, rather than seeing figures without background.

Build a repayment plan around the business

Compare possible repayments with everyday operating needs and existing commitments. Ask yourself whether the business could manage them during a quieter period, not only when sales are strong. This cautious view can help you consider a suitable request before applying.

If you’re still working out how much can i borrow for a business loan nz, a clear summary of purpose, timing and cash flow is a practical place to start. For plain-English finance learning, explore the Mortgage School finance guides. When you’re ready to discuss business finance, Mortgage Suite can help you consider options in light of your plans and circumstances.

How Mortgage Suite can help you explore business borrowing options

Once you’ve mapped out your business purpose, finances and likely repayments, the next step is to consider which lending path may fit. Mortgage Suite can help you compare business loans, commercial property finance, property development finance and 2nd tier lending in light of your circumstances. The focus is on understanding what you’re trying to achieve and how different lenders may view the request, not just the headline borrowing figure.

A personal discussion about your business goals

A useful conversation starts with what the funds are for, how the business is tracking and what outcome you’re working towards. You can talk through your financial position, existing commitments, available security and details that may need explaining, such as changing or seasonal income. This helps build a clearer picture of the request and which lender’s approach may be worth considering.

Mortgage Suite acts as a personal advocate, helping you assess lender fit and discuss how to present the application. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite has supported borrowers since 2000. You can read more about Mortgage Suite’s experience and approach.

A bank decline does not have to end the conversation

A decline from a mainstream bank can be disappointing, but it doesn’t define your business or mean every lending option is closed. Lenders may assess business income, security, property and project details differently. Understanding what didn’t fit can help clarify whether the request, structure or lender pathway needs another look.

For some businesses whose circumstances sit outside mainstream criteria, 2nd tier lending may be an alternative to explore. It isn’t a promise of approval, and the right option depends on the full application. Mortgage Suite can help you compare potential pathways across business and alternative lending, so you can make an informed decision about what to pursue.

If you’re asking how much can i borrow for a business loan nz, a discussion grounded in your goals and financial position is a practical next step. Talk through your business finance options with Mortgage Suite and consider a path that fits your circumstances.

Take the next step with a clearer plan

There’s no single figure that answers how much can i borrow for a business loan nz. A lender considers whether repayments fit the business’s cash flow and commitments, what the funds are for, any available security and how the application fits its lending approach. A clear picture of your finances and plans can help you explore suitable options.

If your business needs finance, commercial property funding or support for a development, the right approach starts with your circumstances, not a one-size-fits-all estimate. A decline from one lender doesn’t necessarily close off other pathways, including 2nd tier lending, though every option depends on an individual assessment.

Mortgage Suite has supported borrowers since 2000, and founder Krish Krishna brings over two decades of banking experience. That experience informs a personal approach to comparing business and alternative lending options, without promising a particular outcome.

Ready to talk through your goals and what your business may be able to manage? Talk through your business finance options. A clear conversation can help you work out a practical next step.

Frequently Asked Questions

How much can I borrow for a business loan in NZ?

There’s no standard amount that every New Zealand business can borrow. How much can i borrow for a business loan nz depends on factors such as the business’s ability to manage repayments, existing commitments, the loan purpose and available security. The amount you want may differ from what a lender considers manageable. An early estimate can help with planning, but a lender’s assessment determines what it may offer.

What do lenders look at when deciding how much a business can borrow?

Lenders consider whether the business can meet repayments alongside its usual expenses and current debt. They may review business accounts, cash-flow information, trading performance, the purpose of the loan and available security. Turnover alone doesn’t show how much money remains after costs and commitments. If income varies because the business is seasonal or self-employed, explaining the pattern can help a lender understand the figures in context.

Can I get a business loan if my business is new?

A newer business may still be able to explore finance, but its shorter trading history can make it harder for a lender to assess performance from past records. The lender may consider the business plan, expected cash flow, the owner’s relevant experience, existing commitments and available security. Requirements differ between lenders, and there’s no guaranteed outcome. Clear information about the business purpose and how repayments could be managed can support an initial discussion.

Can I borrow against property for a business loan?

Property may be offered as security for some business lending, subject to the lender’s assessment and the details of the loan. Security is an asset a lender may rely on if repayments aren’t made. Using residential property can connect personal assets with business borrowing, so consider the implications carefully. The property, the business’s ability to repay and the loan purpose all matter. Offering security doesn’t guarantee approval or a particular amount.

Can I get a business loan if a bank has declined my application?

A decline from one bank doesn’t necessarily mean every option is closed. Lenders can assess business finances, security and loan purposes differently, so it may help to understand what didn’t fit before considering another pathway. 2nd tier lending may suit some circumstances outside mainstream bank criteria, but approval isn’t guaranteed and the application still needs assessment. Mortgage Suite supports business and 2nd tier lending for varied borrower circumstances across New Zealand.

What information should I prepare before applying for a business loan?

Prepare current business accounts, cash-flow information and details of existing loans or other regular commitments. Write a short explanation of what the business does, how its income changes during the year, what the funds are for, how much you’re seeking and when you need them. If you can offer property or another asset as security, note that too. Lenders may ask for different information, so keep your records clear and consistent.

Is a business loan the same as commercial property finance?

No. A business loan is a broad term for borrowing to support a business purpose, while commercial property finance focuses on funding a commercial property purchase or another property-related transaction. The purpose and asset being financed shape the lending discussion and information required. Property development finance is another distinct pathway, aimed at funding a development project. The most suitable option depends on your plans, financial position and how repayments could fit the business.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

NZ Property Development Loan Requirements 2026

A lender’s decision on a development project depends on more than the land or your borrowing history. Lenders may also assess whether the plan can be delivered, whether the numbers make sense and how the loan will be repaid. That can make property development loan requirements nz feel unclear, especially if you’re unsure which documents to prepare or how your experience and project structure will be assessed.

It’s reasonable to want a clear picture before you apply. This guide explains the main areas lenders may assess and the project information that can support an application, including plans, budgets, building contracts and funding stages. You’ll also learn how project progress can affect the drawdown process and what options may be available if a mainstream bank’s criteria don’t fit. Mortgage Suite provides property development finance and helps organise project information and negotiate with lenders. Founder Krish Krishna brings more than two decades of banking experience to these discussions. A bank decline isn’t always the end of the conversation. Understanding what may suit your project is a practical next step.

Key Takeaways

  • Property development loan requirements nz can vary according to the lender, project type, stage and funding structure.
  • Lenders may consider your experience, finances, project feasibility, security and plan for repaying the loan.
  • Grouping supporting documents into clear categories can help you prepare a more organised application.
  • Review your project assumptions, timeline and repayment plan so you’re ready to discuss delays or changes.
  • A finance adviser can help present your project to lenders and explore suitable funding pathways if a mainstream bank isn’t the right fit.

Property development loan requirements in NZ: what lenders look at first

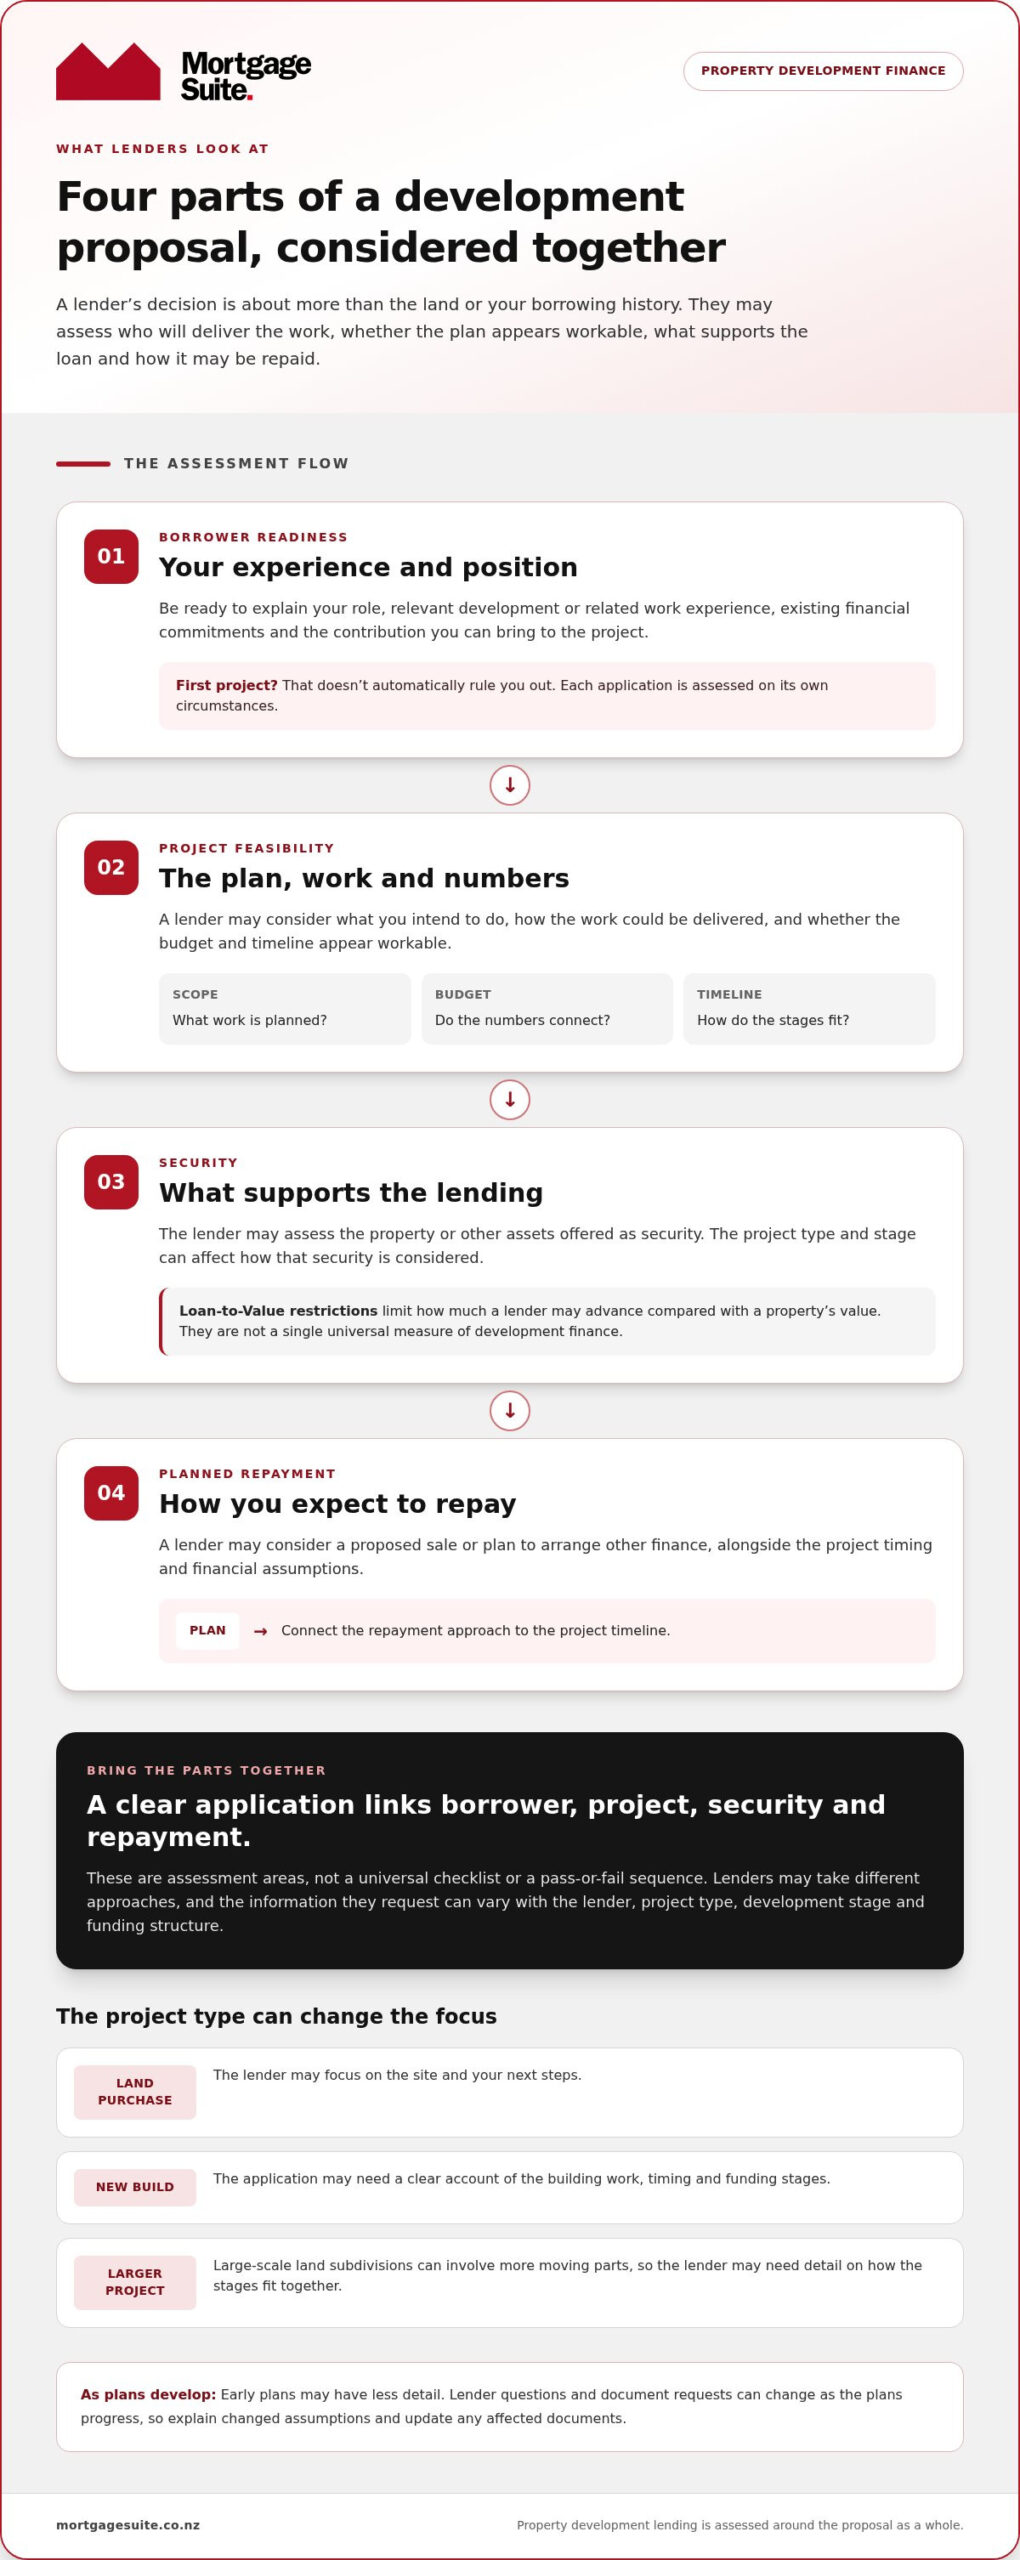
In brief: Lenders usually consider the borrower, project, available security and proposed repayment plan together. The property development loan requirements nz applicants face can vary with the lender, project type, development stage and funding structure. There isn’t one document or criterion that applies to every application.

A lender is assessing the project’s risks as a whole: who will deliver it, whether the plan appears workable, what property supports the borrowing and how you intend to repay the loan. A clear application connects these elements and explains how the project is expected to progress.

What does a property development lender assess?

Four broad areas help a lender build a picture of your proposal:

  • Your experience and position: Your background may help explain your ability to manage the work. A lender may also consider your financial position and existing commitments.
  • The project plan: The lender needs to understand what you intend to do, how the work may be delivered and whether the project appears financially workable. Development can involve connected stages, from acquiring land through to construction, as outlined in this real estate development process.
  • Security: The property or other assets offered as security help the lender assess what supports the loan. The project type and stage may affect how that security is considered.
  • Repayment plan: The lender will want to understand how you propose to repay the borrowing, such as through planned sales or by arranging other finance. The plan should fit the project timeline.

These are assessment areas, not a universal checklist. The evidence a lender requests depends on the application. Organising your information around these points can help you explain the proposal clearly.

Why development loan requirements differ between projects

A request to fund a land purchase may focus on the site and your next steps. A new build may need a clear account of the building work, timing and funding stages. A larger project, such as large-scale land subdivisions, can involve more moving parts, so a lender may need detail on how the stages fit together.

Project stage matters too. Early plans may have less detail than a project that’s further along. Lender questions and document requests can change as the plans develop, and lenders may take different approaches. The phrase property development loans in NZ covers a range of funding situations rather than one standard application. Start by organising information around your specific project and what is known at its current stage.

How lenders assess your experience, finances and project plan

A lender looks at how your background and finances fit the project, not just whether the land appears suitable. Property development loan requirements nz can differ between lenders, so use these assessment areas as guideposts rather than a pass-or-fail checklist.

Borrower readiness: What experience, financial commitments and contribution do you bring? Relevant development experience can show how you’ve handled similar work and help a lender understand your role in delivering the project. If this is your first project, that doesn’t automatically rule you out. Each application is assessed on its own circumstances.

Project feasibility: Does the plan appear workable? A clear description of the work, budget and timeline helps explain what you intend to do, how the stages connect and what could affect delivery.

Security: What property or other assets are being offered to support the lending? Owning suitable land may form part of the picture, but it doesn’t guarantee finance. The lender also considers the borrower, proposed work and repayment plan.

Planned repayment: How do you expect to repay the loan? A lender may consider your proposed sale or refinancing plan alongside the project timing and financial assumptions.

How your background and financial position may be considered

Be ready to explain your role in the project and any relevant experience, whether from previous developments or related work. Lenders may also consider your existing commitments and the contribution you can bring to the project. Together, these details give a fuller picture of your borrowing position.

How a lender may review project feasibility and security

A joined-up plan makes it easier to see how the budget, timeline and intended work relate to each other. If an assumption changes, explain why and update any documents it affects. For general property-sector context, Property Council New Zealand shares information about the industry, while lender decisions depend on the individual proposal.

Loan-to-Value restrictions are limits on how much a lender may advance compared with a property’s value. They aren’t a single universal measure of development finance. The lender, project and funding structure can all affect how security is assessed. Mortgage Suite helps organise these parts into a clear application and discuss how to present your circumstances. You can also learn about Mortgage Suite’s approach to supporting borrowers through lending decisions.

Which documents can support a property development loan application?

A well-organised application connects your circumstances with the project plan. For property development loan requirements nz, requested documents vary by lender, project type and stage. Use this preparation checklist as a starting point, then tailor it to the information available for your project. Some items may not apply, and a lender may request other evidence.

Borrower and project information to organise

  • Borrower: Identification, details of your financial position and existing commitments, and information about the project’s ownership structure.
  • Experience: A summary of relevant project history, including your role and examples of completed work, if applicable. This helps explain who will manage delivery.
  • Land or property: Information about the site, its ownership and any existing lending secured against it. A valuation or other property report may also be requested.
  • Project: A short project summary, development plans, timeline, budget and proposed funding schedule. Make clear what work is planned and when funding may be needed.
  • Repayment plan: An outline of how you expect to repay the borrowing, supported by relevant sale plans or proposed arrangements for refinancing, where applicable.

Planning, building and technical documents

Depending on the project, supporting material may include council information, consent documents, architectural or engineering plans, building reports, contractor details and building contracts. For construction, show the costs and timing for siteworks separately from base construction where that distinction helps explain the budget. A staged funding schedule can also show how these items relate to the drawdown process, the release of funds as agreed milestones are completed.

Council requirements and available evidence can differ by project and current council processes. The NZ Government Building Process guide offers information about building a home, including consents and building stages. Documents relevant to a subdivision may differ from those for a single new build.

Check that figures and dates match across your plans, contractor quotes, reports and funding schedule. If a quote changes, update the budget and timeline, or clearly explain the difference. Consistent information gives the lender a clearer view of the proposal and makes questions easier to answer. For more plain-English guidance, explore Mortgage Suite’s Mortgage School lending guides.

NZ Property Development Loan Requirements 2026

How to prepare for lender questions about risk and repayment

Lenders may ask what could change during the project and how you’d respond. Clear answers won’t guarantee approval, but they can show how your budget, timeline and repayment plan fit together.

  • 1. Review your assumptions. Check that your budget reflects the planned work, including expected changes in scope. Note what each estimate is based on and which figures are still provisional.
  • 2. Test the timeline. Set out the main project stages and consider what a delay at each point could mean for later work, funding needs or a planned sale. Record key dates and dependencies rather than relying only on a best-case schedule.
  • 3. Organise your evidence. Keep plans, quotes, reports and funding schedules together, and make sure the figures and dates agree. If an assumption changes, update related documents or explain the difference.
  • 4. Explain repayment. Describe how you expect to repay or restructure the lending and how that plan connects with project progress. Be ready to explain what could affect the timing.

How to present a clear project budget and timeline

Show how the budget lines up with project milestones and when funds may be needed. For example, if site preparation comes before building work, show those stages separately where that helps explain the funding schedule. Flag important assumptions, such as the timing of work, and explain how a change could affect the budget or completion date.

A quantity surveyor report may be useful for some projects, particularly where a lender needs more detail to understand building costs. It isn’t a universal requirement. The aim is to give a consistent, realistic picture of the work, not to suggest that every uncertainty has been removed.

How to explain the repayment or exit plan

An exit plan is how you expect to repay the development loan or restructure the lending. Depending on the project, this could involve selling completed property or arranging a Refinance. Explain the steps behind your proposal, the timing you’re working towards and the evidence that supports it. A lender may consider whether the plan fits the project’s progress, rather than treating a proposed sale or refinance as certain.

If your assumptions or timeline change, update your repayment plan too. Mortgage Suite helps organise project information and present your proposal to lenders. For general borrowing context, you can use the mortgage calculator, but remember that a calculator can’t assess a development project or predict a lender’s decision.

Getting development finance sorted with a clear application plan

Development finance can feel like a lot to pull together, especially when the project is still taking shape. A clear application plan helps you explain what you’re building, what’s already in place and how you expect to repay the borrowing. Property development loan requirements nz vary, so focus on presenting your project accurately rather than trying to fit a one-size-fits-all checklist.

What to prepare before discussing your project

Start with a short summary that gives a lender the essentials. Include:

  • Project type and stage: Explain whether you’re buying land, starting a build or progressing a subdivision, and what has happened so far.
  • Ownership structure: Set out who owns or will own the property and who is involved in the borrowing.
  • Objectives: Describe what you plan to complete and your intended repayment approach.
  • Supporting information: Bring together available financial details, property records, council or planning information, project plans, budgets, quotes and timelines.

Some details may still be developing. Mark estimates clearly and note what could change, so the application doesn’t present an assumption as a confirmed figure. You can read about Mortgage Suite and its approach to helping borrowers with lending decisions.

How Mortgage Suite can help you consider lender options

Mortgage Suite helps organise your information, identify gaps and present your project so its stages and funding needs are easy to follow. We act as your personal advocate, working with you to explain the proposal and negotiate with lenders. This can include mainstream and alternative lending channels, depending on the project and lender fit. Each lender makes its own decision, so finance can’t be guaranteed.

A mainstream-bank decline can be disappointing, but it isn’t necessarily a final judgement on your project or the end of your funding options. Another lender may assess the proposal differently, while still looking closely at its risks and repayment plan. You can read client reviews to learn about other borrowers’ experiences.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to development finance discussions. If you’re preparing an application or reconsidering your options after a decline, Mortgage Suite can help you understand your project-specific funding needs and work out a sensible next step.

Take the next step with a clearer funding plan

Understanding property development loan requirements nz starts with seeing the whole picture. Lenders may assess your experience and financial position alongside the project plan, security and intended repayment. Clear supporting documents, consistent figures and a realistic timeline can help explain how the project fits together. Requirements vary between lenders and projects.

If a mainstream bank has declined your application, that doesn’t automatically mean the project has no funding options. Mortgage Suite helps organise development finance applications and consider mainstream and alternative lending pathways. Founder Krish Krishna brings more than two decades of banking experience to those discussions, with a focus on understanding your circumstances and presenting your project clearly. Approval can’t be guaranteed, but a thoughtful funding conversation can help you identify a practical next step.

Talk through your development finance options with Mortgage Suite. A clear plan can help you approach your next steps with greater confidence.

Frequently Asked Questions

What do lenders look for in a property development loan application in NZ?

Lenders usually assess your experience and financial position alongside the project plan, security and proposed repayment. They’ll want to understand who is managing the work, whether the budget and timeline make sense, what supports the lending and how you expect to repay it. The property development loan requirements nz applicants face vary by lender and project, so prepare clear information rather than relying on a universal checklist.

How much equity do I need for a property development loan?

There’s no single equity amount that applies to every development loan. The contribution a lender expects can depend on the project, its stage, the security available and the funding structure. A lender may consider how your contribution fits with the overall budget and project risks. Before committing to a plan, get guidance on which lender criteria may suit your circumstances.

Can I get a development loan if I have not completed a project before?

Possibly. Being new to development doesn’t automatically exclude you, but a lender may want to understand how the project will be delivered. Explain your role, the experience of others involved and how the work will be managed. A clear project plan, realistic timeline and well-organised supporting information can help a lender assess the application, though they can’t guarantee approval.

What documents do I need for a property development loan?

Documents may include identification and financial details, property and ownership information, project plans, a budget, timeline, contractor quotes and relevant council or planning information. You may also need to explain how you intend to repay the loan. The exact evidence varies by lender and project stage. Keep figures and dates consistent across your plans, reports, quotes and funding schedule.

Do I need council consent before applying for development finance?

Not necessarily in every case. The information a lender requests can depend on the project, its current stage and the relevant council process. You may be asked for council information, consent documents or an update on planning progress, but don’t assume every application follows the same sequence. Set out which approvals or information you have and what remains underway, so the project status is clear.

Can I get a property development loan after a bank declines my application?

Possibly. A decline from one bank doesn’t automatically mean your project has no funding options. The decision may reflect that lender’s criteria or how the application was presented. Reviewing the reasons, project details and available evidence can help clarify next steps. Mortgage Suite assists with development finance and alternative lending options, but each lender makes its own decision and approval isn’t guaranteed.

How are development loan funds released during a project?

Some development or construction finance uses a drawdown process, meaning funds are released in stages as agreed project milestones are completed. The lender’s terms explain how releases work and what evidence may be needed at each stage. The process can vary, so align your funding schedule with the work timeline and allow for the lender’s requirements when planning cash flow.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan for visa holders in NZ: your 2026 guide

Can your visa allow you to buy a home in New Zealand but still leave a lender unsure about your application? That can happen because eligibility to purchase and mortgage approval are separate decisions. If you’re looking at a home loan for visa holders nz, understanding that difference is a useful first step.

It’s understandable to feel uncertain. Property rules can affect whether you’re allowed to buy, while lenders may assess visa type, income, deposit and supporting documents in different ways. A decline from a mainstream bank isn’t necessarily the end of the road, but no lending pathway can promise approval.

This guide explains how the two decisions fit together, what lenders may look at, how mainstream and alternative lending pathways can differ, and which documents may help explain your circumstances. Mortgage Suite helps borrowers understand their options and present their situation to lenders, so you can have a clearer conversation about possible next steps.

Key Takeaways

  • Check your right to buy a property separately from a lender’s decision to approve a mortgage. They’re different assessments.
  • For a home loan for visa holders nz, be ready to explain your visa conditions, income, debts, deposit source and the property you’re considering.
  • Compare mainstream and alternative lending pathways against your circumstances, as lender criteria and flexibility can vary.
  • Organise your key documents before discussing an application, while allowing for lenders to request different information.
  • A broker can help present your circumstances clearly and negotiate with lenders, but approval depends on the details of your application.

Home loan for visa holders in NZ: separate property eligibility from loan approval

It can be hard to tell whether your visa lets you buy a home and whether a lender will support the purchase. Treat them as two separate questions. First, establish whether you’re eligible to buy the property. Then consider how a lender may assess your finances and circumstances for a home loan for visa holders nz.

Property-purchase eligibility is your legal ability to buy a particular property in New Zealand; loan approval is a lender’s decision about whether your finances can support the borrowing. Meeting one test doesn’t automatically mean you’ll meet the other.

Can visa holders buy residential property in New Zealand?

There isn’t one answer for every visa holder. Eligibility can depend on your visa category, residence history, citizenship, who you’re buying with and the property involved. New Zealand’s overseas investment rules restrict some purchases of residential land. The Overseas Investment Amendment Act 2018 provides background on changes to those rules, but your own circumstances matter.

For example, a residence class visa holder may need consent from the Overseas Investment Office (OIO), the government body that considers certain property purchases, if they haven’t yet met the “ordinarily resident” test. This generally means holding a residence class visa, living in New Zealand for the previous 12 months and being physically present here for at least 183 days during that period. OIO consent is official permission to buy or build a home in cases where the rules require it.

Temporary visa holders are generally restricted from buying a home to live in on their own, but some situations, including buying jointly with an eligible partner, can be treated differently. Australian and Singaporean citizens also have specific exemptions. Check current OIO guidance before making decisions, as eligibility depends on your circumstances.

Why property eligibility does not guarantee a home loan

Even if you’re allowed to buy, a lender makes a separate assessment of whether the loan appears affordable and suitable. It may consider your income and how steady it is, your existing debts, the size and source of your deposit, and the property you plan to buy. Your visa conditions may also affect how a lender views your circumstances. Policies differ, so one lender’s response may not predict another’s.

Keeping the two decisions separate can make the process feel more manageable. A lender’s decision isn’t a verdict on your future, and a decline from one mainstream bank doesn’t necessarily close every pathway. Review what the lender has assessed, identify any details that need explaining, and consider whether another lender’s criteria may fit your circumstances. Property eligibility and borrowing are connected, but each needs its own clear assessment.

What lenders may assess when a visa holder applies for a home loan

Your visa is one part of the picture, not the whole application. A lender assesses the overall application, not visa status in isolation. It may consider your visa type and conditions alongside your income, work situation, debts, deposit and the property you want to buy. Each lender sets its own criteria, so a requirement applied by one lender shouldn’t be treated as a universal rule.

This is why an application for a home loan for visa holders nz may need a clear explanation of your circumstances. A lender may want to understand how steady your income is and whether your work and visa arrangements support your plans. Questions are part of assessing the application as a whole and don’t automatically mean there’s a problem.

How visa type and remaining visa term may affect an application

Lenders may look at your visa conditions and expected ability to remain in New Zealand and keep earning. Work conditions, a role change or an approaching expiry could prompt further questions, but lender policies differ. Don’t assume there’s one minimum visa term that applies everywhere. The relevant lender’s current criteria determine what it will consider in your situation.

The same applies to named loan pathways. Kāinga Ora’s First Home Loan scheme has its own eligibility criteria, so check the current details rather than assuming a visa alone determines whether you qualify.

Income, deposit and financial records lenders may review

A lender needs a clear view of the money coming in, the commitments going out and how you’ll fund the purchase. Depending on your circumstances and the lender, you may be asked for records such as:

  • Recent payslips and details of your employment, including your role and how long you’ve been working there.
  • Bank statements showing income, regular spending, existing debts and savings.
  • Evidence showing where your deposit came from, particularly if funds have been transferred from overseas.
  • Details of the property you’re considering, as the property can form part of the lender’s assessment.

If you’re self-employed or your income varies, the lender may need extra records to understand how consistent your earnings are. Gather the documents that show your income and commitments clearly, but expect the lender to set the final list for your application. You can also explore plain-English mortgage guidance as you get your information together.

Clear information can make it easier for a lender to assess your application on its merits. A broker can help organise the documents and explain details that need context, while keeping expectations realistic: the lender makes the final decision.

Mainstream and alternative home loans for visa holders: how to compare pathways

There isn’t one lender pathway that suits every visa holder. Mainstream and alternative lenders may assess applications differently, and policies can vary within each group. When comparing a home loan for visa holders nz, look at how the lender’s criteria fit your circumstances, as well as the loan’s repayment structure and flexibility. A headline interest rate alone won’t show whether the overall arrangement suits your plans.

The 2nd tier and non-bank home loans guide explains more about alternative lending. This can be a pathway to explore if your circumstances don’t fit a mainstream lender’s criteria, though suitability depends on your application and the terms available.

What to compare Mainstream lender Alternative lender
Criteria and assessment May apply defined policies to visa status, income, deposit and property details. May consider applications that sit outside some mainstream criteria, with its own assessment requirements.
Flexibility Depends on the individual lender’s rules and how your application fits them. May offer a different way to assess some circumstances, but flexibility isn’t the same across all lenders.
Loan fit Compare repayments, structure and conditions against your needs and plans. Review the full loan terms and repayment commitments, not just the initial rate.

When a mainstream lender may be worth considering

A mainstream lender may be worth exploring if your visa, income, deposit and property plans fit its current criteria. That doesn’t guarantee acceptance. Find out how the lender treats your specific visa circumstances, what evidence it needs and whether the repayment arrangement fits your budget over time. Each lender sets its own requirements, so don’t assume one bank’s policy applies to all.

When an alternative lender may be another pathway

If a mainstream lender can’t assess your application under its usual criteria, an alternative lender may be another option to consider. It won’t suit everyone or guarantee approval, so weigh its assessment approach and loan conditions carefully. Mortgage Suite helps explain possible pathways and present more complex circumstances clearly to lenders. If you’d like support comparing options, talk with Mortgage Suite about your goals and situation.

Home loan for visa holders in NZ: your 2026 guide

How to prepare a home loan application as a visa holder

A little preparation can make a home loan conversation clearer and less stressful. Before comparing lenders, bring together the details that explain your visa, finances and property plans. This gives you a practical starting point for a home loan for visa holders nz, while allowing for lenders to request documents specific to your application.

Build a clear picture of your visa and financial position

Start by checking your property-purchase eligibility for your circumstances. Then organise your information so you can explain your situation consistently. A simple summary of your income, regular commitments, deposit source and intended property can help you spot gaps before you apply.

Depending on the lender and application, useful documents may include:

  • Current visa documents and relevant visa conditions.
  • Recent payslips, employment details or other evidence of income.
  • Bank statements showing regular income, expenses, debts and savings.
  • Information or records showing where your deposit funds came from.
  • Details of the property you’re considering, if you’ve chosen one.

If you’re self-employed or your income changes from month to month, gather records that help explain how you earn and how your income varies. Keep names, dates and other personal details consistent across forms and supporting documents. The lender may ask for more or different information, so use this as a starting checklist rather than a fixed list.

Prepare questions and compare lender fit

Use these steps to get sorted before discussing an application:

  • Clarify purchase eligibility. Understand whether your visa and circumstances allow you to buy the property you have in mind.
  • Map your finances. Note your income, work history, regular expenses, existing debts and deposit source.
  • Organise your records. Bring together relevant visa, employment, income and bank documents.
  • Discuss lender options. Ask how a lender may assess your visa and income circumstances, and what information it needs to consider your application.
  • Compare the whole loan. Look at eligibility, repayment structure, flexibility and communication, as well as the interest rate.

Useful questions can help you understand whether a lender may be a fit: Which parts of my visa or income history need explaining? What documents would help clarify them? How do the repayments and conditions match my plans? For plain-English explanations as you prepare, visit Mortgage Suite’s mortgage education resources.

Mortgage Suite can help you organise your information and discuss lender options without treating one lender’s response as the final word. Talk through your home loan options with a team that can present your circumstances clearly and negotiate with lenders.

How Mortgage Suite can help visa holders explore home loan options

Working out which lender may suit your visa and financial circumstances can feel like a lot to manage alone. Mortgage Suite takes a personal approach: we learn about your goals, understand the details of your situation and consider how your application may fit different lender criteria. This gives you a clearer view of possible next steps without treating a particular loan outcome as certain.

A personal advocate when lending criteria feel hard to navigate

Lender feedback can be difficult to interpret, especially if a decision focuses on one part of your application. A broker can help explain what the feedback means, identify information that may need more context and discuss whether another lending pathway could be worth exploring. A decline from one lender isn’t necessarily a final judgement, but it also doesn’t mean another lender will approve your application.

Mortgage Suite’s founder, Krish Krishna, brings more than two decades of banking experience to conversations about borrowing. That experience supports a practical understanding of how lenders assess applications and how a borrower’s circumstances can be presented clearly. It’s guidance and advocacy, not a promise of approval. You can read more about Mortgage Suite’s team and experience.

What to expect from an initial lending conversation

An initial conversation is a chance to explain what you’re hoping to do and get a clearer picture of the information lenders may need. You can talk through your visa conditions, income, deposit, existing commitments and property plans. If some details are still uncertain, say so. A clear, honest picture helps shape a useful discussion about lender options and what may need attention before an application is presented.

Mortgage Suite can help organise the key details, match your circumstances to potential lender criteria and present your application clearly. Where appropriate, the broker can also negotiate with lenders on your behalf. For a home loan for visa holders nz, this support can help you compare possible pathways and understand what each lender is asking for, while leaving the decision with the lender.

You don’t need to have every answer before starting a conversation. If you’d like to talk through your goals and possible next steps, discuss your home loan options with Mortgage Suite. There’s no pressure to have everything sorted first.

Take your next step with a clearer plan

Buying a home with a visa involves two separate questions: whether you’re eligible to purchase, and whether a lender is prepared to approve your borrowing. Once you understand that distinction, you can focus on the details that shape a home loan for visa holders nz, including your visa conditions, income, deposit and the lender’s own criteria.

Mainstream and alternative lending pathways may suit different circumstances, but neither guarantees approval. Preparing clear information and comparing the full loan structure can help you have a more informed conversation about your options.

Mortgage Suite supports borrowers through mainstream and alternative lending applications, with personal advocacy and lender negotiation. Founder Krish Krishna brings over two decades of banking experience to that work, helping you understand lender feedback and present your circumstances clearly.

Talk through your home loan options with Mortgage Suite and explore possible next steps at your pace. Getting started doesn’t have to be daunting.

Frequently Asked Questions

Can I get a home loan in New Zealand on a work visa?

You may be able to apply, but a lender’s decision depends on your circumstances and its current criteria. A work visa doesn’t automatically mean you can buy a home independently, so check purchase eligibility separately before making plans. Lenders may consider your visa conditions, income, employment history, deposit and other commitments. For a home loan for visa holders nz, both property rules and borrowing requirements need to be considered.

Can temporary visa holders buy a house in New Zealand?

Temporary visa holders are generally restricted from buying a home to live in on their own, but individual circumstances can affect the rules. For example, a temporary visa holder may be able to buy jointly with an eligible New Zealand partner if the property is treated as shared under relationship-property rules. This means it falls within the property-sharing rules for couples. Check current Overseas Investment Office guidance before entering a purchase agreement or assuming an exception applies.

Does a residence-class visa guarantee home loan approval?

No. A residence-class visa may affect whether you’re eligible to purchase, but it doesn’t require a lender to approve a mortgage. The lender will separately assess your income, debts, deposit, ability to manage repayments and the property. Some residence visa holders may also need Overseas Investment Office consent, depending on their circumstances. Confirm purchase eligibility and borrowing requirements as separate steps before committing to a property.

What documents might a visa holder need for a home loan application?

Possible documents include current visa details, payslips, employment information, bank statements and evidence showing where your deposit came from. If you’re self-employed or your income varies, a lender may ask for additional records to understand your earnings. You may also need to provide details of the property you’re considering. The exact documents depend on the lender and your application, so treat this as a starting list, not a universal requirement.

Do all New Zealand lenders assess visa holders in the same way?

No. Lenders set their own criteria, and they may differ in how they consider visa conditions, income, employment history, deposit and property details. One lender’s decision doesn’t necessarily tell you how another will assess your application. Compare more than the interest rate: consider eligibility, repayment structure, flexibility and the information each lender needs. A broker can help explain lender feedback and present your circumstances clearly.

Can I apply for a home loan if a bank has declined my application?

Yes, a decline from one bank doesn’t automatically rule out every other lending option. First, understand the reasons for the decision and whether anything in your application needs clarification or improvement. Lenders assess applications differently, and an alternative lender may consider circumstances outside some mainstream criteria. That isn’t a promise of approval or a suitable route for everyone, but a tailored review can help you understand possible next steps.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loan for Casual Workers NZ: How to Prepare and Compare Options

Changing hours don’t automatically rule you out of a home loan for casual workers nz. The key is helping a lender understand the pattern behind your pay, rather than judging your application by one quieter week. If your earnings rise and fall between pay periods, it’s understandable to wonder whether a bank will consider the full picture.

There may be options, but lenders can assess casual income differently and their requirements vary. Clear records of your work and earnings can help explain how your income has tracked over time. A decline from a mainstream bank isn’t necessarily the end of the road, either. Other lending pathways may be worth assessing, although none can guarantee approval.

In this guide, you’ll learn what lenders may look for when reviewing casual income, which documents can help explain your circumstances, and how to compare mainstream and alternative options across New Zealand. You’ll also find practical steps for organising your application and questions to ask before you apply.

Key Takeaways

  • Casual work doesn’t automatically rule you out. Show how your hours and earnings have tracked over time.
  • For a home loan for casual workers nz, gather income records and be ready to explain regular shifts or seasonal changes.
  • Lenders can assess casual income differently. Ask what work history and documents each one needs before applying.
  • Compare mainstream and alternative options by more than the interest rate. Check the repayment structure, flexibility and how each option fits your plans.
  • Mortgage Suite can help organise your income information and discuss lender pathways, without promising a particular result.

Can casual workers get a home loan in NZ? Start with how income is viewed

Changing shifts can make planning a home purchase feel uncertain, especially if your pay varies from one week to the next. But being a casual worker doesn’t decide your home loan application on its own. A lender will assess your income evidence and wider financial situation, and each lender may approach that assessment differently.

Quick answer: Casual workers may be considered for a home loan in New Zealand, subject to the lender’s assessment of their income, commitments and overall ability to manage repayments.

What does casual employment mean when applying for a mortgage?

In everyday terms, casual employment usually means you’re offered shifts or hours as needed, rather than receiving the same set hours every week. Your pattern may still be fairly regular, or it may change with demand, rosters or the season. Describe your actual work arrangement clearly instead of assuming every casual role looks the same to a lender.

A casual employee is paid through an employer, with income recorded through payslips and employment records. A contractor may invoice for work, while a self-employed person generally earns income through their own business. These arrangements can require different ways of showing income, so don’t describe yourself as a contractor if you’re employed casually. If your income comes from contracting or running a business, guidance for self-employed borrowers may be a better fit.

Check that your records make each part of your pay clear. For example, a payslip may list holiday pay separately. The Holidays Act 2003 sets out New Zealand leave entitlements, including rules relevant to casual employees. Keep payslips and other records that explain how your earnings are made up.

Does irregular income automatically mean a home loan decline?

No. Employment type is one part of an application, not the whole story. A lender may also consider the income evidence you provide, your regular financial commitments, your deposit and whether the proposed repayments appear manageable. The information required and assessment method can vary, so ask what the lender needs before assuming how your application will be treated.

Casual employment, by itself, proves neither affordability nor ineligibility. It isn’t a personal judgement on your reliability, either. A lender’s decision reflects its criteria and the information available for your application. If one mainstream bank says no, that doesn’t automatically close off every other pathway. For a home loan for casual workers nz, a clear account of your work pattern and income can help a lender assess the full picture, though it can’t guarantee an outcome.

How lenders may assess casual income for a New Zealand home loan

For a home loan for casual workers nz, a lender may look beyond your latest payslip to understand how your earnings behave over time. It will assess whether the income you can show may support repayments, alongside your other financial commitments. Each lender sets its own criteria, so there isn’t one universal formula or required work history.

What income evidence might a casual worker be asked to provide?

Ask the lender or adviser handling your application which records it accepts and what period it wants to see. Depending on the lender, useful documents may include:

  • Recent payslips showing your hours, pay and any separately listed components.
  • Your employment agreement, if it explains your role or pay arrangement.
  • Bank records showing wages being paid into your account.
  • Rosters or written confirmation from your employer, if these help explain shifts that change from week to week.

Keep your explanation straightforward. For example, you might say that your hours usually increase during busy periods, or that shifts are offered according to a changing roster. If you’ve had a quieter patch, explain the context and provide records that show the wider pattern. Evidence won’t guarantee that a lender accepts all your income, but it can make your circumstances easier to understand.

How do affordability checks fit into the assessment?

Income is only one part of the picture. A lender may also consider regular commitments, such as other loan repayments and household expenses, then assess whether the proposed home loan repayments appear manageable. A serviceability stress test checks whether repayments could still be manageable if calculated at a higher interest rate. Whether and how a lender applies this depends on its current policy, so ask what assessment will be used for your application.

Here’s a simple illustration, not a lending rule: imagine your hours vary between quieter weeks and busier ones. A lender may review the available records to understand that pattern rather than treating one week as your usual income. The documents and method it accepts will depend on its criteria.

If you’re a first-home buyer, you can also check whether the First Home Loan scheme may fit your circumstances, and confirm its current eligibility rules with Kāinga Ora. For an early planning estimate, Mortgage Suite’s mortgage calculator can help you explore repayments. It isn’t a lender decision or a promise of how much you can borrow.

If you’d like help organising your income records and considering lender pathways, explore Mortgage Suite’s home loan support.

Mainstream bank or alternative lender: compare home loan pathways

A mainstream bank is one possible route, but it isn’t automatically the right fit for every casual worker. If your income records show a pattern and explain changes in hours or pay, ask a bank how it would assess your particular situation. Don’t rely on assumptions about a lender’s policy. Criteria and evidence requirements can differ.

Alternative, or second-tier, lending may be worth exploring if your application doesn’t fit a mainstream lender’s approach. It isn’t a guaranteed solution, and the terms need careful review. For a separate explanation, look for a 2nd Tier Lender New Zealand guide alongside the comparisons below.

What to compare Mainstream lender Alternative lender
Assessment fit Ask how it views your casual income and work pattern under its current criteria. Ask whether its approach may better suit your circumstances, and what it needs to be comfortable with the application.
Evidence requested Confirm which income records it accepts and the period it wants to review. Check what documents are needed and how changing hours or pay will be considered.
Flexibility Ask which parts of your circumstances can be considered and what conditions apply. Clarify where the lender may be flexible, and where its requirements remain firm.
Repayment structure Compare repayment choices and how they fit your budget and plans. Review the full structure, including how repayments and conditions may affect you over time.
Questions to confirm “How will you assess my casual income, and what evidence should I provide?” “What are the full terms, conditions and options if my circumstances change?”

When might a mainstream lender be worth approaching?

It may be worth asking a mainstream lender if you can document your earnings and explain why your hours vary. Give a clear account of your work pattern, then check how the lender will treat your casual income before preparing an application based on an assumption. An organised application can help explain your situation, but it can’t ensure a particular decision.

What should you ask before considering an alternative lender?

Ask how income is assessed, which records are required and what conditions come with the loan. Compare the whole arrangement, including repayment structure and flexibility, rather than focusing only on the headline interest rate. A broker can help you compare potential pathways, but can’t guarantee acceptance or remove lender conditions. When assessing a home loan for casual workers nz, make sure the pathway suits both your evidence and your longer-term plans.

Home Loan for Casual Workers NZ: How to Prepare and Compare Options

How to prepare a stronger home loan application as a casual worker

A clear application helps a lender understand your work pattern and your plans. Before you approach lenders about a home loan for casual workers nz, work through these steps to get your information in order.

  1. Clarify your goal. Note what you hope to buy, your preferred timing and what matters most in a home loan.
  2. Gather your records. Collect available payslips, employment terms, bank statements and employer details. Ask which documents the lender wants for your application.
  3. Map your income. Prepare a short timeline of changes in your hours, role or pay, using accurate records. Explain regular shifts or known seasonal changes rather than relying on estimates.
  4. Review your commitments. List regular repayments and household expenses, along with any likely changes to your household circumstances.
  5. Ask about lender criteria. Check how the lender assesses casual income, what evidence it accepts and what else it needs to consider your application.

Build a clear record of your work and income

Arrange your documents so your income is easy to follow. Check that dates, figures and details agree across your payslips, bank records and employment information. If a pay amount differs between records, be ready to explain why. Don’t change or leave out information to make your income appear steadier. A straightforward explanation, supported by accurate documents, gives the lender a clearer picture to assess.

Your timeline doesn’t need to be complicated. It could note when you started a role, when your roster changed or when seasonal work affected your hours. Keep the explanation factual, and confirm with your lender or adviser which records will help with its assessment.

Review your goals and borrowing picture before applying

Think about the property you’re aiming for, your deposit position and the commitments that shape your budget. Consider whether your household income or expenses may change. A repayment calculator can help you explore rough scenarios, but it can’t tell you what a lender will approve. The assessment depends on your circumstances and that lender’s criteria.

For plain-English mortgage learning, explore Mortgage Suite’s Mortgage School resources. You can also use its mortgage calculator to plan possible repayments. Treat both as preparation tools, not a lending decision.

If you’d like support organising your income information and discussing possible home loan pathways, talk with Mortgage Suite about your home loan options.

How Mortgage Suite can help casual workers compare home loan options

Working out which lender may suit your casual income can feel like another job on top of everything else. Mortgage Suite arranges home loans through mainstream and alternative lending pathways across New Zealand. It can help you organise your information, clarify your goals and consider which options may be worth exploring.

For a home loan for casual workers nz, the way you explain your work pattern matters. A broker can help bring together details of your shifts, income records and financial commitments so a lender can consider them in context. They can also help you ask useful questions about lender requirements and compare potential options. The lender still makes its own assessment, and no pathway can guarantee approval.

What to expect from an initial home loan conversation

You can expect to discuss how your work and pay are structured, what records you have, what you hope to achieve and which regular commitments affect your budget. It’s also a chance to identify details to check with a lender, such as which income documents it accepts or how it reviews changing hours. The next steps will depend on your circumstances and the lender’s response.

If you’d like to learn more about the people and approach behind the business, visit the Mortgage Suite About Us page.

How to choose your next step with confidence

Before moving ahead, make sure you have accurate income records and a clear explanation of changes in shifts or pay. Ask prospective lenders how they assess casual earnings, what evidence they need and what conditions may apply. As you compare options, look beyond the headline interest rate. Consider the repayment structure, flexibility and whether the loan terms fit your plans. A broker can help you weigh up those details, but can’t remove lender conditions or promise a particular result.

You may also find it helpful to read Mortgage Suite client reviews as one source of information about others’ experiences. Every borrower’s situation is different, so reviews aren’t a guide to the outcome you’ll receive.

If you’re ready to talk through your circumstances without assuming there’s only one route, talk with Mortgage Suite about your home loan options.

Take the next step with a clearer plan

A home loan for casual workers nz may be possible, but casual status alone won’t determine the outcome. Lenders can assess changing income in different ways, so clear records of your pay and work pattern can help them understand your circumstances. Before you apply, organise your documents, review your regular commitments and ask each lender what evidence it needs.

Compare the full loan option, not just the interest rate. Repayment structure, flexibility and conditions all matter when choosing a pathway that fits your plans. A mainstream bank is one possibility, and alternative lending may be worth assessing if your circumstances don’t fit its criteria. Neither route guarantees approval, but a decline from one lender doesn’t have to be the end of your options.

Mortgage Suite works with mainstream and alternative lending channels and can help you organise your income information and discuss possible next steps. If you’re ready to talk through your situation, talk with Mortgage Suite about your home loan options. Contact Mortgage Suite to discuss your circumstances and possible home loan pathways.

Frequently Asked Questions

Can casual workers get a home loan in New Zealand?

Yes, casual workers may be considered for a home loan in New Zealand, but approval depends on the lender’s assessment of the whole application. A lender may look at your income records, work pattern, deposit, regular commitments and whether repayments appear manageable. Being employed casually doesn’t automatically rule you out. If one lender declines your application, ask why and consider whether another suitable lending pathway is worth exploring.

How long do I need to have worked casually before applying for a home loan?

There isn’t one work-history period that applies to every lender. Some lender guidance refers to six to twelve months of casual employment, but requirements can differ and policies may change. Ask the lender or adviser what history it wants to see and whether your previous work in the same industry is relevant. Prepare accurate records for the period requested rather than assuming a particular length of employment will guarantee an outcome.

What income documents do casual workers need for a home loan?

Ask your chosen lender which documents it accepts and what period it wants to review. It may request recent payslips, an employment agreement and bank records showing wages received. If your hours vary, a roster or employer confirmation may help explain your work pattern. Check that dates and figures match across your documents, and be ready to explain any differences. These records support the assessment, but don’t guarantee that all your income will be counted.

Do banks count casual income when assessing a mortgage application?

Banks may include casual income in an assessment, but how they treat it depends on their criteria and the evidence available. A lender may review your income history and consider how consistent your hours and pay have been, alongside your commitments and overall ability to manage repayments. Ask directly how the bank will assess your income before relying on assumptions. The amount it accepts, if any, is a lender decision, not a fixed rule for all applications.

Can I apply for a home loan if my casual hours change each week?

Yes, you can ask about applying even if your hours change from week to week. Give the lender a clear explanation of your work pattern, including regular shifts or known seasonal changes, and provide records that show how your earnings vary. For a home loan for casual workers nz, the lender will assess your evidence and wider financial circumstances under its own criteria. Changing hours don’t automatically mean a decline, but approval isn’t guaranteed.

What can I do if a bank declines my home loan application?

Ask the bank to explain the main reasons for its decision and whether missing or unclear information affected the assessment. You can then review your records, clarify your income pattern or address other concerns before deciding what to do next. A decline from one mainstream bank isn’t a personal judgement or necessarily the end of your options. Mortgage Suite works with mainstream and alternative lending channels, but another lender will make its own assessment.

Is an alternative lender suitable for casual workers seeking a home loan?

An alternative lender may be worth considering if your circumstances don’t fit a mainstream bank’s criteria, but it won’t suit everyone and approval isn’t assured. Before proceeding, ask how your income will be assessed, what evidence is required and what conditions apply. Compare the full loan structure, repayment arrangements and flexibility, not only the interest rate. A broker can help you consider available pathways, but can’t guarantee acceptance or remove a lender’s conditions.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Cross-collateralisation and property loans in NZ: risks, options and next steps

A loan structure that looks simpler today can leave you with less control over your properties tomorrow. If you’re researching cross collateralization property loans nz, you may be weighing the convenience of linking properties against the risk that selling or refinancing one could affect another.

That uncertainty is understandable. When a lender uses more than one property as security, it may have a say in what happens to the linked properties, including how sale proceeds are used. The arrangement can sometimes help a loan proceed, but it may also limit your choices later.

This guide explains how linked property security works in New Zealand, what flexibility you could give up, and how it compares with keeping loans separate. You’ll also find practical questions to ask your lender before accepting a structure or changing an existing one, such as which properties secure each loan and what would happen if you sold or refinanced. With more than two decades of banking experience behind Mortgage Suite Ltd, the team understands how complex lending structures can feel. The aim is to help you make a considered choice that suits your wider property and borrowing plans.

Key Takeaways

  • With cross collateralization property loans nz, more than one property may secure lending, so check exactly which properties are linked to each loan.
  • Before selling or refinancing, ask your lender whether it needs to approve changes to the linked security and what conditions may apply.
  • Compare linked and separate loan arrangements against your plans, including how much flexibility you may want and how you prefer to manage your lending.
  • Use the article’s questions to prepare for a conversation with your lender or mortgage adviser, especially about releasing a property from linked security.
  • Mortgage Suite Ltd can help you assess how a proposed structure fits your wider property plans and negotiate with lenders, without promising a particular outcome.

What does cross-collateralisation mean for property loans in NZ?

Cross-collateralisation is an arrangement where one or more properties may secure more than one loan. In everyday terms, a property gives the lender backing for the money it lends. If you’re looking up cross collateralization property loans nz, the key point is that the properties and loans may be connected, rather than each loan relying on just one property.

For a neutral overview of the underlying idea, see Cross-collateralization. The exact arrangement for your lending depends on your loan documents and what the lender has agreed to. Don’t assume that a property secures only the loan you associate it with; check the paperwork or ask your lender to explain it.

How can one property secure more than one loan?

Think of a borrower with two properties and two loans. The lender might agree that each property supports its own loan. Or the lending documents may connect both properties to both loans, so the lender considers them together as security. These are simple examples, not a guide to what your own documents say.

Linked security can involve more than one property, more than one lending facility, or both. Your loan documents set out the actual arrangement, so review them and ask the lender which properties support each loan if anything is unclear.

Is cross-collateralisation the same as using equity?

No. Equity is the part of a property’s value that isn’t covered by lending secured against it. A lender may consider available equity when assessing a borrowing request, but equity alone doesn’t tell you which property secures which loan. That depends on the agreed security arrangements.

For example, you may have equity in a property, but that doesn’t confirm whether it supports one loan or is linked to other lending as well. If you’re considering a residential property purchase or already have a rental property, the article Residential Investment Property Loans NZ offers wider context on borrowing for this purpose. For your own position, check the loan documents and ask the lender to clarify any links before making plans around a property.

How cross-collateralised property loans can affect your options

A property decision can affect connected lending because the lender may have agreed to rely on more than one property as security. If you want to sell, Refinance or change one loan, the lender may need to review the arrangement and approve a change to the linked security. The result depends on your facility documents and the lender’s assessment, so don’t assume a change will happen automatically.

What could happen if you sell one linked property?

Before you commit to a sale, ask the lender what must happen for the property to be released from the security arrangement. It may assess whether the remaining property or properties still provide acceptable backing for the lending. Depending on your loan terms and circumstances, the lender may set conditions before agreeing to release a property.

Ask for the requirements early, and check your facility documents alongside the lender’s explanation. Lender decisions and conditions vary, so another borrower’s experience may not match yours. Consumer Affairs also outlines How cross-collateralization works, including why connected security can affect a borrower’s choices.

Could linked security affect a refinance?

It can. If you’re considering moving your lending to another lender, the existing security arrangement may need to be reviewed as part of the process. The new lender will assess the lending it’s being asked to take on and the properties offered as security. Your current lender may also need to agree to changes to its existing security.

That means a Refinance involves more than comparing interest rates. Consider whether the proposed structure fits your plans, what properties would secure the lending, and whether you could manage the change without affecting other loans. If commercial lending is involved, Commercial Property Refinance NZ is a relevant topic to explore alongside advice from your lender or mortgage adviser.

In short, a decision about one property can affect connected loans, so confirm the conditions before you act. If you’re unsure how your current or proposed structure fits your plans, you can talk through your property lending options with Mortgage Suite Ltd. That conversation can help you identify what to ask your lender, without assuming a particular outcome.

Cross-collateralisation vs separate property loans: what should you compare?

There’s no single structure that suits every borrower. Linked security may make it simpler to manage several loans with one lender, while separate security can make each property’s role clearer. Your choice should reflect your plans and the lender’s assessment, not just how the arrangement looks on paper.

Use this table as a starting point. The practical details, including whether a property can be released or a loan changed, depend on the lender and your loan documents. Confirm each point for your own situation.

What to compare Linked security Separate security
Flexibility A change involving one property may require the lender to review the connected lending. Each property may have a clearer link to its own loan, but changes still depend on lender approval and loan terms.
Administration Coordinating lending with one lender may feel more straightforward, though the security links can be harder to keep track of. It may be easier to see which property supports which loan, but separate arrangements can mean dealing with more than one facility or lender.
Future plans Consider whether linked security fits your plans to sell, refinance or change a loan. Consider whether a more distinct arrangement fits plans to sell, refinance or change ownership of a property.
What to confirm Ask which properties secure each loan and what conditions apply to changing that arrangement. Ask whether separate security is available and what each loan would require.

Linked security can simplify how lending is arranged, but separate security may offer more clarity and control over each property. That’s the central trade-off to weigh up when comparing cross collateralization property loans nz.

When might linked security suit a borrower?

It may suit someone who values coordinating lending across several properties with one lender and expects to keep that structure in place. But convenience doesn’t guarantee approval or better terms. Suitability depends on your plans, the loan documents and the lender’s assessment. Ask what flexibility you would retain if your circumstances change.

When might separate security be worth discussing?

If you may sell, Refinance or change ownership of a property, ask whether separate arrangements could make each property’s role easier to understand. Separation may not be available or accepted in every case, so confirm the lender’s position before deciding. For questions about how lending documents relate to property matters, you can consult a property solicitor or find information through the New Zealand Law Society Property Law Section.

Cross-collateralisation and property loans in NZ: risks, options and next steps

Questions to ask before accepting or changing linked property security

Before you agree to link properties or change an existing arrangement, get a clear picture of what the lender is asking you to accept. If you’re comparing cross collateralization property loans nz, take these questions to your lender or mortgage adviser and ask for answers in plain English:

  1. Which properties secure each loan? Ask for a clear list of the properties and loans involved, including any lending facility you may have overlooked.
  2. What needs to happen to release a property? Ask what conditions apply, whether the lender must approve the release, and how it would assess the remaining security.
  3. What if I sell or Refinance? Find out how either step could affect the other loans and what you need to arrange before proceeding.
  4. How would future borrowing fit? Ask whether taking on another loan could change the security arrangement or affect your current lending.
  5. Can the security be changed later? Check the process and conditions for separating properties or changing which property supports a loan.
  6. Are there alternatives? Ask whether separate security is possible for your circumstances, and what trade-offs the lender sees.

What to check in your loan documents

Find the documents that describe your loans and the properties connected to them. Look for the sections covering security, changes, releases and lender consent. If a clause is unclear, ask the lender to explain what it means for your situation. Don’t rely on a verbal summary alone; make sure you understand what the documents say before agreeing to a change.

Who can help you assess the structure?

A mortgage adviser can help compare possible loan structures against your borrowing goals and future property plans. A solicitor can explain the legal obligations and property-security documents. These roles are different: an adviser can discuss lending options, while a solicitor can provide independent legal advice. This guidance isn’t a substitute for having a solicitor review documents that affect your property.

For straightforward mortgage learning, visit Mortgage Suite’s Mortgage School. If you’d like support weighing a proposed structure against your plans, explore your property loan options with Mortgage Suite. Getting clear answers first can help you make a considered decision and feel more confident about your next step.

How Mortgage Suite can help you assess property loan options in NZ

Linked security can feel hard to untangle, especially if you have several properties, existing loans and plans that may change. Mortgage Suite can help you look at the full picture: how your current lending is arranged, what you want to do with your properties, and whether you may need to borrow again later.

Mortgage Suite acts as your advocate and negotiator with lenders. It isn’t the lender or a guarantor, and no particular lending outcome can be promised. Depending on your circumstances, the team can consider options through mainstream and alternative lending channels, then help you understand what questions to put to the lender about the proposed structure. If you’re researching cross collateralization property loans nz, the aim is to make the options clearer before you decide what fits your plans.

What to prepare for a lending conversation

A few notes and documents can help make the discussion more useful. Gather what you have, and don’t worry if you’re still trying to find out how a particular loan is secured.

  • Loan documents and any recent lender correspondence that describe your current lending or security.
  • Basic details of each property involved, and which loans you think may be connected to it.
  • Your upcoming plans, such as buying another property, selling, refinancing or changing how a property is owned.
  • Questions about what the lender may require to change or release security, and what conditions need to be confirmed.

Being clear about both your current position and what you hope to do next gives an adviser a better starting point. Your lender’s requirements still need to be confirmed directly, and a solicitor can explain legal documents and obligations.

Explore your options with a mortgage adviser

A conversation can help you compare possible structures against your goals, identify trade-offs and work out which details still need an answer from your lender or solicitor. If your plans include a rental property, you may also want to read Residential Investment Property Loans NZ for related borrowing context.

Mortgage Suite was founded by Krish Krishna, who brings more than two decades of banking experience. If you’d like a calm discussion about how your existing lending and future property plans fit together, talk through your property lending options. There’s no need to have every detail sorted before you start.

Make your next property lending decision with clarity

Cross-collateralisation can make lending feel more straightforward, but linked security may affect your choices if you want to sell, Refinance or change a loan. Before deciding, check which properties secure each loan, what your lender requires to release a property, and whether the structure fits your future plans. Separate security may be worth discussing too, though it won’t suit every situation.

If you’re weighing up cross collateralization property loans nz, remember that the right structure depends on your circumstances and lender approval. Review your loan documents, ask for unclear terms to be explained, and seek independent legal advice about your obligations.

Mortgage Suite can help you compare lending options and prepare questions for lenders. Founded by Krish Krishna in 2000, the business draws on his more than two decades of banking experience and works with mainstream and alternative lending channels. Mortgage Suite can act as your advocate and negotiator, but it can’t promise a particular outcome.

Talk through your property lending options and take a considered next step. You don’t need every answer before starting the conversation.

Frequently Asked Questions

What is cross-collateralisation in property loans?

Cross-collateralisation is when a lender uses one or more properties as security for more than one loan. In plain English, the property gives the lender backing for the money it lends. For example, two properties could be linked to two loans rather than each property supporting only one loan. The actual arrangement depends on what you and the lender have agreed, so check your loan documents to see which properties secure each loan.

Is cross-collateralisation risky?

It can affect your flexibility, but the impact depends on your loan structure and plans. Linked security may help you coordinate lending with one lender, while reducing the independence of each property. A sale, refinance or change to one loan could involve a review of connected security. If you’re researching cross collateralization property loans nz, ask your lender what the arrangement means for your specific loans rather than assuming it will have the same effect for everyone.

Can I sell a property that is cross-collateralised?

You may be able to sell, but first check whether the lender needs to approve a change to the security arrangement. It may assess the remaining properties and lending before agreeing to release a property. What happens next depends on your loan documents, lender requirements and circumstances. Before committing to a sale, ask what conditions apply, what information the lender needs, and whether any connected loan arrangements could be affected.

Can I refinance one loan if my properties are cross-collateralised?

You can ask about refinancing one loan, but linked security may affect how the lender reviews the change. The existing lender may need to consider whether its security arrangement will change, and a new lender will assess the lending and security proposed. Requirements differ between lenders and loan structures. Before making plans, check your facility documents and ask both your current lender and mortgage adviser what steps or conditions may apply.

How can I find out which properties secure my loans?

Start with your loan documents and look for the sections that describe the security and the properties involved. If the wording isn’t clear, ask your lender to identify which property secures each loan and explain the arrangement in plain English. A mortgage adviser can help you understand the lending structure, while a solicitor can explain legal wording and obligations. Don’t rely on assumptions based on which property you associate with a particular loan.

Can I ask a lender to separate cross-collateralised loans?

Yes, you can ask whether the lender will separate the loans or change which properties secure them. Whether it agrees depends on the lender, your loan documents and your circumstances. The lender may assess the proposed structure and the security that would remain for each loan. Ask what information it needs, what conditions apply and whether the change could affect other lending. A mortgage adviser can help you compare options, but the lender makes the decision.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Is Your Mortgage Working With Your Household Budget… Or Against It?

Is Your Mortgage Working With Your Household Budget… Or Against It?

Mortgages are often one of the biggest monthly expenses in any household budget.

But they shouldn’t leave you feeling like every dollar is already spoken for!

Your mortgage needs to work for your household budget.

While interest rates are an important part of that equation, there are other things to consider when deciding whether your mortgage is structured in a way that actually works for your day-to-day budget.

Let’s dive into the ways you can make your mortgage feel more manageable.

Signs Your Mortgage Isn’t Working For You

One of the biggest warning signs that things aren’t working well is when your mortgage makes it feel difficult to manage the rest of your finances.

That could mean your repayments leave very little room for unexpected expenses, or you are regularly relying on a credit card to get through to payday. But it could also be something less drastic than that. Perhaps:

  • Your repayments don’t line up with when you get paid
  • You have underutilised savings
  • You don’t have ready access to an emergency fund
  • Your fixed mortgage doesn’t give you any flexibility to make additional repayments
  • Your floating portion is larger than it needs to be
  • Your repayments are manageable now, but you are worried they may become unaffordable if interest rates increased.
  • Your financial circumstances have changed since you originally arranged your mortgage

None of these things necessarily mean you have the wrong mortgage. But they could be signs that it is time to take another look at your options.

What Can You Do About A Problematic Mortgage?

The good news is that there are always options. Your mortgage does not have to be a one-and-done transaction. You can review it at any time to see if there are things you can do to make it less problematic for your household budget.

These are some of the options:

1: Consider your repayment frequency

Changing from monthly to fortnightly repayments can help some families manage their cash flow more effectively. This is especially true if you line your repayments up with your pay cycle.

Selecting a payment frequency isn’t about getting the repayments as low as possible; it’s about finding a schedule that naturally works with the way your household income arrives and your expenses are paid.

2: Think about fixed and floating

Fixing your entire mortgage provides payment certainty, but it can also limit your flexibility. Having a portion of your mortgage on a floating rate can give you more freedom to make extra repayments or access funds.

It is important to remember that floating rates are generally higher than fixed rates, so this option may not be suitable for everyone. But for some families, splitting between fixed and floating portions can give you a useful balance between certainty and flexibility.

3: Could an offset account help?

If you have regular funds sitting in a savings account, an offset mortgage could potentially help reduce the amount of interest you pay.

Instead of your savings simply sitting in a separate account, an offset arrangement can link eligible accounts to your mortgage, meaning you may only pay interest on the difference between your mortgage balance and the money you have available in those accounts.

This can be particularly useful for keeping your emergency funds accessible, but still reducing the amount of interest that is calculated on your mortgage.

4: Review Your Mortgage Term

Your lender will have issued a date for when your mortgage funds need to be repaid by. But this date is not necessarily set in stone; depending on your age and circumstances, you may be able to change that end date.

Extending the term can reduce your repayments and potentially ease your monthly cash flow, while shortening it can help you pay the loan down faster when your budget allows. Either can be good options depending on your circumstances.

5: Don’t Forget Your Emergency Fund

Paying every spare dollar into your mortgage might look like a good option. But what would happen if you had an unexpected expense pop up?

A broken-down vehicle, an urgent home repair, or a change in income can quickly put pressure on the household budget. Keeping an emergency fund can give you a financial buffer and reduce the need for expensive forms of credit when something goes wrong.

The amount of money each family would need in an emergency fund varies, but a good estimate is three months’ worth of expenses.

Help Is Always Available

There is not one mortgage structure that works for every household budget.

Your ideal setup will depend on your income, expenses, financial goals, tolerance for risk, and your plans for the future. A structure that works brilliantly for one household might be completely unsuitable for another.

That’s where an experienced mortgage adviser can help you.

Rather than simply looking at the interest rate, we look at the bigger picture. We explore how your mortgage fits with your household budget, when your fixed terms expire, whether splitting your lending could help, and whether an offset account would work for your family.

We can also review your mortgage should your circumstances change. A pay rise, new family member, career change, renovation, or an updated financial goal can all be good reasons to revisit your structure.

Is Your Mortgage Helping Or Hindering Your Budget?

Your mortgage should be more than just a repayment that you suffer through each month. It should be something that fits into your wider financial life.

If you are constantly feeling squeezed by your repayments, or you are simply wondering whether your current structure is the right fit for you, it is time for a mortgage review.

At Mortgage Suite, our friendly team can look at your individual circumstances and help you understand the options that are available to you.

Get in touch with us today and let’s make sure your mortgage is working with your budget, not against it.

Second mortgage for business in NZ: how it works in 2026

Could business funding put your home at risk, even if you already have a mortgage? For some Kiwis, a second mortgage for business NZ may provide access to property equity without replacing an existing home loan. But it adds another loan secured against the property, so weigh the funding need against the security and repayment risks.

It’s understandable to feel cautious. You may be comparing a second mortgage with a business loan or refinancing, while considering whether your business income and circumstances will meet a lender’s requirements. If the property has to be sold to repay debt, the first mortgage lender generally has priority over the second mortgage lender. Understand how that could affect your options and have a realistic repayment plan before proceeding.

This guide explains how a second mortgage works in 2026, what lenders may assess and what information to prepare. It also sets out questions to ask about repayments, property security and your plan to repay the loan, so you can compare funding paths and make a considered decision.

Key Takeaways

  • A second mortgage for business NZ adds lending secured against property that already has a mortgage, so check how the existing loan’s priority may affect your options.
  • Before proceeding, consider whether the business can manage repayments and what could happen to the property if it can’t.
  • Compare a second mortgage with a term loan or refinancing by checking the security required, repayment structure and impact on existing lending.
  • Prepare accurate business financial information, details of existing lending and a clear plan for repaying the loan.
  • An adviser can help you weigh up the risks and discuss lender options suited to your circumstances, without guaranteeing approval.

What is a second mortgage for business in NZ?

A second mortgage for business is an additional loan secured against property that already has a mortgage. The property could be a home or business property, and the funds are intended for business needs. The second mortgage sits behind the existing mortgage in the order of security. You can read a neutral overview of what a second mortgage is, then check how a particular lender would structure and secure the loan.

In general, the first mortgage has priority over a later registered mortgage. If the property had to be sold to repay debts, the first lender would usually be paid before the second mortgage lender. The exact position can depend on registered interests and the loan documents, so confirm the details with the lender and an appropriate legal adviser before proceeding.

Using the funds for a business doesn’t change the fact that the property is security for the loan. If repayments aren’t maintained, the property offered as security could be at risk. Weigh the business purpose against the possible impact on your home or commercial property, and consider whether the business could still meet repayments if expected income is delayed.

How does a second mortgage differ from a first mortgage?

A first mortgage is usually the main loan secured against a property. A second mortgage is separate lending added while that first mortgage remains in place. The second lender’s position behind the first may affect how it assesses the property, existing lending and available security. Ask how the proposed loan would be recorded and what could happen if repayments fall behind.

Don’t assume the order or enforcement process based on a general explanation alone. Ask the lender to explain its terms and have the relevant documents checked if you’re unsure.

What business needs might prompt this type of lending?

A business owner might explore a second mortgage to cover a working capital gap, buy equipment or act on a business opportunity. These are examples of possible purposes, not a promise that a lender will approve the application. The lender will consider what the funds are for alongside the property security and the borrower’s wider circumstances.

Business-purpose borrowing is different from a home loan taken out to buy or refinance a home, even if the home is offered as security. Be specific about how the funds will be used and where repayments are expected to come from. If a mainstream bank has declined, that isn’t necessarily the end of the conversation. Other lender pathways may be worth discussing, though each has its own assessment.

How does a business second mortgage work, and what is at risk?

Taking out a second mortgage involves more than showing that a property has equity. The lender needs to understand what the business will use the funds for, what property will secure the loan, how existing lending affects that security, and how repayments are expected to be made. Review the proposed terms carefully, including the repayment schedule and what happens if payments are missed.

When property secures business borrowing, the borrower remains responsible for repayments and the property may be at risk if they aren’t made. That’s true even when the loan is intended to support business growth rather than a personal purchase.

  • Explain the purpose: Be ready to describe what the funds will pay for, when they are needed and how the spending supports the business.
  • Review the security: Discuss the property, existing mortgage and any other lending secured against it.
  • Test the repayment plan: Consider how the business will meet repayments if income is delayed or lower than expected.
  • Check the terms: Ask about the repayment schedule, the loan’s end date and any conditions that could affect your plans.

How does the second mortgage sit alongside existing lending?

More than one loan can be secured against the same property. As a general guide, the first registered mortgage has priority over a later one. If the property is sold to repay debts, the first lender is generally paid before the second. The exact position and any steps a lender can take depend on the registered interests, loan documents and applicable law.

Check your existing mortgage documents and ask the relevant lenders whether consent is needed and how the new loan could affect your current arrangements. A qualified legal professional can explain the implications for your particular circumstances. Don’t rely on a general article to settle those details.

What happens if the business cannot keep up with repayments?

If repayments fall behind, arrears can build and the lender may take steps under the loan terms and applicable law. The outcome depends on the circumstances, so don’t assume every lender will respond in the same way. Because the property secures the borrowing, it could ultimately be at risk.

If repayment pressure appears, contact the lender or your adviser early to discuss the situation and possible next steps. For consumer credit, the Commerce Commission explains the transfer of responsibility for regulation of consumer credit. Whether a business-purpose loan falls under consumer credit rules depends on the circumstances, so confirm what applies to your loan.

If you’re weighing up a second mortgage for business NZ, Mortgage Suite can help you discuss the funding need and possible lender pathways. Its mortgage learning resources explain lending terms to help you prepare for a conversation.

Second mortgage vs business loan or refinance: which path fits?

The right option depends on what the business needs, whether property can be offered as security, your existing lending and how repayments could fit your cash flow. A second mortgage for business NZ is one path to discuss, but it isn’t automatically the best fit. Compare the security and repayment structure, the impact on current lending and the consequences of missed payments, not just the amount you may be able to borrow.

Option Security Common use Questions to ask
Second mortgage Property that already secures an existing mortgage. Seeking further business funds while keeping existing lending in place. How does it sit alongside the current mortgage? What property is at risk, and how will repayments work?
Business term loan Depends on the lender and loan terms. Ask whether property or other security is required. A business funding need with a lump sum and a defined repayment schedule and end date. What security is required? How often are repayments due, and when must the loan be repaid?
Refinance Usually involves new lending secured against property or other agreed security; confirm the proposed arrangement. Replacing or restructuring existing lending, often with a different deal or lender. What happens to the existing loan terms? Will the new structure meet the business need and repayment plan?

When might a second mortgage be worth exploring?

You might raise this option if you want to seek extra funds while keeping your current mortgage in place. That’s a discussion point, not a recommendation or a sign that you’ll qualify. Ask the lender to explain how the existing loan affects its assessment, and compare proposed repayments with the business’s expected cash flow. If a mainstream lender’s criteria don’t fit, the Mortgage School guide to lending options may provide further context.

When should you compare a business loan or Refinance instead?

Compare a business loan if you want to understand whether its security and repayment structure could suit your business without adding another mortgage to a property. Terms vary between lenders, so check the details rather than assuming the loan is unsecured. Refinance means replacing or restructuring existing lending, often with a different deal or lender. It may be worth comparing if you’re open to changing your current arrangement. Mortgage Suite can help you discuss business and commercial finance pathways, but the lender will assess your circumstances.

Before choosing, ask each lender to set out the security, repayment schedule, loan end date and implications for existing lending. Mortgage Suite’s Mortgage School learning resources offer plain-English explanations of lending terms to help you prepare those questions.

Second mortgage for business in NZ: how it works in 2026

How to prepare before applying for a business second mortgage

A clear application starts with a clear picture of the business need and how the loan could be repaid. Before discussing a second mortgage for business NZ, work through these steps:

  • Define the purpose: Set out what the funds would pay for and how the spending supports the business.
  • Gather your records: Collect current business accounts and income information, along with details of existing loans.
  • Review the property: Note which property may be offered as security and share relevant ownership or mortgage details.
  • Plan repayments: Map likely repayments against realistic business cash flow and consider how you’d manage if income changed.

Preparation helps a lender understand your request, but it doesn’t guarantee approval. The property, business income and lender criteria all need individual assessment. Accurate records make the discussion clearer, particularly if your income or business circumstances don’t fit a straightforward pattern.

What information should a business owner gather?

Start with up-to-date business accounts, income records and a short explanation of the funding purpose. Add details of current loans, repayments and any property you may offer as security. Be ready to explain how the business expects to use the funds and where repayments will come from. Requirements vary, so ask the lender or adviser for the exact document list before you apply.

Accuracy matters. If figures have changed or trading has been uneven, explain that rather than leaving gaps for the lender to interpret. A broker may help organise the information and discuss which lender pathways could suit your circumstances, though the lender makes its own assessment.

How can you test whether repayments are manageable?

Set out expected repayments alongside the business’s regular income and commitments. Allow for ordinary business needs, existing debt repayments and household commitments where relevant. Then test a less favourable scenario: what if a customer pays late, sales fall or an unexpected business expense arrives? If the plan only works when everything goes smoothly, revisit the amount or structure before proceeding.

The Mortgage Suite calculator may help with general repayment planning. It isn’t a quote or assessment for a business loan, so confirm actual terms and repayments with the lender.

For help discussing business funding needs and possible lending pathways, contact Mortgage Suite about business finance.

Choosing your next step with a New Zealand business finance adviser

Before moving ahead, check that the proposed borrowing matches a real business need and a repayment plan you can explain. Weigh up the security being offered, the risk to the property and alternatives such as a business loan or changing existing lending. A second mortgage for business NZ may be worth discussing, but the right path depends on your circumstances and the lender’s assessment.

An adviser can help organise the facts, present your situation clearly and discuss possible lender options. That support can be useful if your income or business history doesn’t fit a mainstream bank’s usual approach. But advice can’t guarantee a lender will make an offer, set particular terms or approve an application.

What should you ask before accepting an offer?

Take time to understand the offer before you commit. Ask which property secures the borrowing, how repayments are scheduled and when the loan ends. Make sure you understand the conditions and what the lender may do if repayments are missed. If any legal wording or implications are unclear, consider getting independent legal advice before signing.

Then compare the proposed structure with your business plan and other funding paths. Would the repayment plan still make sense if income is delayed? Does the loan solve the need you identified, or could another arrangement better fit your longer-term plans? Ask the lender to explain anything you’re unsure about.

How can Mortgage Suite help you assess possible pathways?

Mortgage Suite arranges business and commercial finance, as well as second-tier lending for situations that may not fit mainstream bank criteria. Its founder, Krish Krishna, has more than two decades of banking experience. A discussion can help you set out the funding purpose, existing lending and repayment plan, then consider which lender pathways may be worth exploring. Each lender makes its own assessment, so there’s no guaranteed outcome.

You can learn more about Mortgage Suite’s background and approach and read client reviews of Mortgage Suite as part of your research.

Before speaking with an adviser, it may help to have your funding purpose, current loan details and repayment plan to hand. You can then use the discussion to consider possible next steps without committing to proceed.

Make your next business funding decision with care

A second mortgage for business NZ may be one way to seek business funds, but it also puts property security and repayment commitments in the picture. Before proceeding, be clear about what the funds are for, how repayments could fit your business cash flow, and whether a business loan or refinance might better suit your needs.

Mortgage Suite facilitates business, commercial property and second-tier lending solutions, including for borrowers whose circumstances may not fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience to lending conversations. That experience can help you discuss your circumstances and possible lender pathways, but it can’t guarantee an offer, particular terms or approval.

If you’re ready to explore your options, talk through your business lending options with Mortgage Suite. A clear conversation can help you decide what to consider next, at a pace that feels right for you.

Frequently Asked Questions

What is a second mortgage for business in New Zealand?

A second mortgage for business in New Zealand is an additional loan secured against property that already has a mortgage. The property could be a home or business property, depending on the lender’s requirements. The existing mortgage generally has priority over the later one, but the details can depend on registered interests and loan documents. A second mortgage for business NZ still puts the property at risk if repayments aren’t maintained.

Can I use a second mortgage to fund my business?

Yes, a second mortgage may be used to fund a business purpose, such as working capital or a business opportunity, if a lender is willing to offer that structure. The lender will assess the purpose of the borrowing, the property offered as security and your circumstances, including how repayments are expected to be made. Using a home as security doesn’t make the borrowing a home loan, so ask the lender to explain the proposed terms.

Can I get a second mortgage if my bank has declined my business loan?

Possibly, but a bank decline doesn’t mean another lender will approve a second mortgage. Lenders may assess applications differently, and some specialist or second-tier lenders consider situations that don’t fit mainstream bank criteria. They’ll still assess the security, business purpose, repayment plan and your wider circumstances. A finance adviser can help you understand potential lender pathways, but can’t promise an offer or approval.

What property can be used as security for a business second mortgage?

A lender may consider residential or business property, but the type of property it accepts depends on its criteria and the details of the application. Existing mortgages and other claims registered against the property can affect the assessment. Before applying, gather information about the property and current lending, then ask the lender whether it may be acceptable security and whether any existing lender’s consent is needed.

Is a second mortgage riskier than a business loan?

It depends on the security and terms of each option. A second mortgage is secured against property, so missed repayments could put that property at risk. A business loan may have a different security arrangement, but it isn’t automatically unsecured or lower-risk. Compare the repayment schedule, loan end date, security and consequences of missed payments for each offer, and consider how the structure fits your business plan.

How much can I borrow with a second mortgage for business?

There’s no set amount that applies to every borrower. A lender will assess the property and existing lending, the business’s financial position, the requested purpose and its own criteria. The amount offered, if any, will depend on that individual assessment. Prepare accurate business income records and details of current loans, then ask the lender to explain how it arrived at any proposed amount and repayment terms.

What happens if I cannot repay a business second mortgage?

If you can’t make repayments, contact the lender as early as possible and explain what’s changed. Missed payments may lead to arrears and other steps under the loan terms and applicable rules. Because the loan is secured against property, that property could ultimately be at risk. Ask the lender or an adviser about your options and seek independent legal advice if you’re unsure what the loan documents mean.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.