
Getting a mortgage in your 50s in NZ: balancing repayments and retirement

Getting a mortgage in your 50s in NZ calls for a clear plan for when the loan will be paid off and whether repayments will stay manageable if your income changes. The key isn’t simply your age; it’s whether the loan fits your expected income, retirement plans and day-to-day budget.

It’s understandable to feel cautious about taking on a long-term commitment while also thinking about retirement. New Zealand retirements may last 25 or 30 years, so balancing mortgage payments with the life you want later deserves careful thought. This guide explains how to test repayments against possible income changes, weigh mortgage payments alongside retirement savings and consider ways to keep your options flexible. You’ll also find practical steps for working out what a comfortable loan could look like for your circumstances.

Key Takeaways

  • Assess when the mortgage could be paid off and whether repayments would remain manageable if your income changes.
  • Set a budget that balances mortgage payments with your retirement plans and everyday needs.
  • Consider how options such as downsizing or part-time work could affect your repayment plan.
  • Build flexibility into your approach so you can adapt as your circumstances and priorities change.
  • Plan for a retirement that may last 25 or 30 years, rather than focusing only on the first years after work.

1. Assessing mortgage repayment affordability as income changes

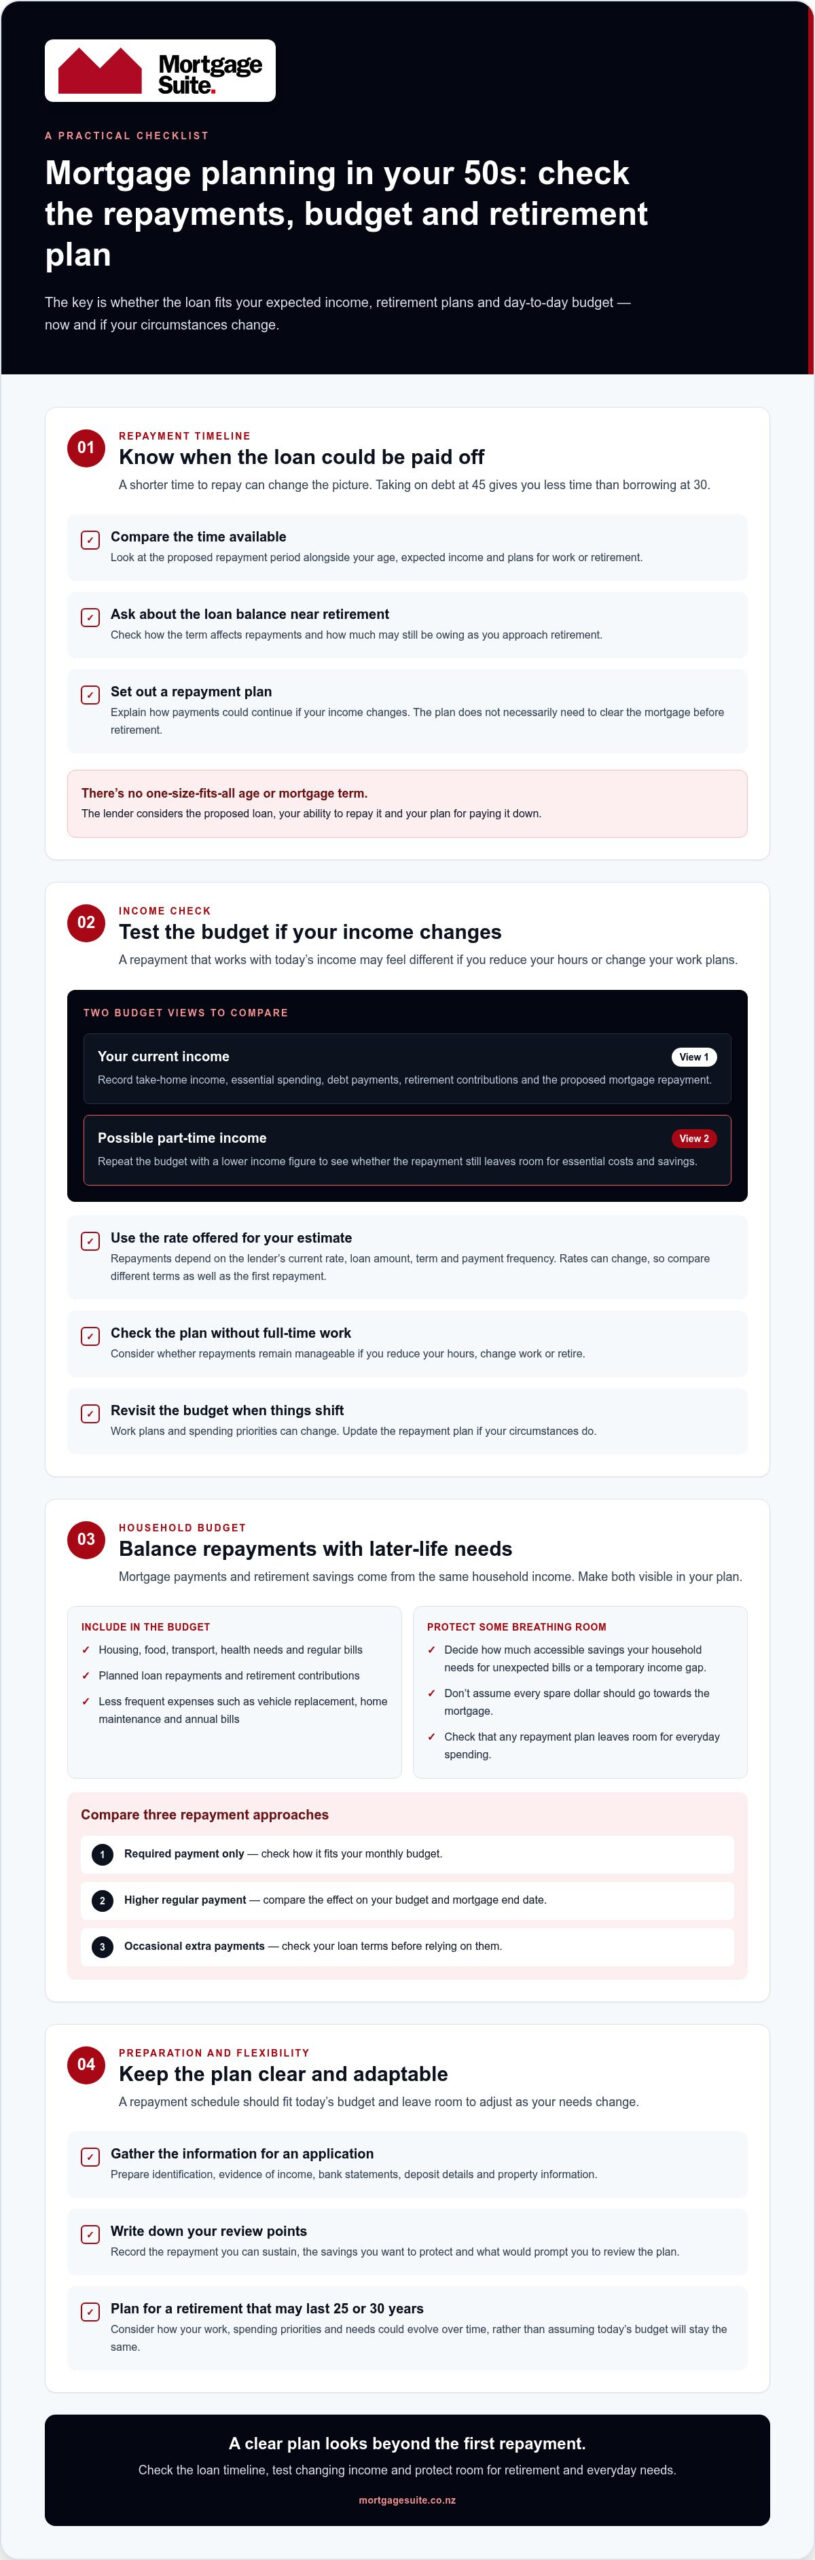
Taking on debt at 45 gives you a shorter available timeframe than borrowing at 30. For Kiwis getting a mortgage in their 50s in NZ, the key question is how repayments fit now and if income changes before the loan is cleared.

Compare borrowing in your 50s with borrowing in your 30s or 40s by looking at the time available to repay and your expected income. A borrower taking on more debt at 45 has a shorter timeframe than someone borrowing at 30. In your 50s, consider how a change in hours, work or retirement plans could affect each repayment.

New Zealand banks assess the proposed loan, repayment ability and plans for paying it down. There is no single mortgage term or maximum age figure that applies to every borrower; the lender considers the loan alongside your income and repayment plan. Ask how the term would affect repayments and the balance remaining as you approach retirement.

Banks may expect a plan for repaying the mortgage, but that plan doesn’t necessarily mean clearing it before retirement. Set out how repayments could continue if your income changes, and whether you expect to keep working, reduce hours or use another source of funds. People in their 50s and early 60s should assess when the mortgage is likely to be paid off and whether payments remain manageable if income shifts.

There is no single deposit amount for every New Zealand borrower in their 50s. The deposit needed depends on the property price, the amount borrowed, your available funds and the lender’s assessment. Work out how much you can contribute, then check the proposed loan against your budget and other commitments.

Mortgage rates and repayments depend on the lender’s current rate, loan amount, term and repayment frequency. Rates can change, so use the actual rate offered to estimate payments; Mortgage Suite’s mortgage calculator can help you explore repayment scenarios. Compare the effect of different terms, not just the first repayment amount.

Taking out a mortgage close to retirement can leave less room in your budget if income falls or costs rise. A longer repayment period may also mean carrying debt later in life. Test whether the payments would remain manageable without relying on full-time work.

To prepare an application, set a repayment budget and list your income, regular expenses and debts. Gather identification, evidence of income, bank statements, deposit details and property information. These records help show how the loan could fit your circumstances and support a clear discussion with the lender.

Many people in New Zealand do not stop working at age 65 and then spend the following 25-30 years simply living without further changes in priorities or needs. When testing affordability, consider how your work plans and spending priorities could evolve, rather than assuming today’s budget will stay unchanged. Check whether repayments would still fit if you reduced your hours or changed how you use your income, and revisit the plan if your circumstances shift. A repayment schedule that works now should also leave room to adapt as your needs change.

2. Balancing mortgage repayment with retirement savings

A mortgage and retirement savings both draw on the same household income. Start by listing essential costs, planned loan repayments and the amount you can set aside for later life. This gives you a clearer view of what remains for everyday spending. For someone in their 50s, the balance should reflect their expected retirement date and the mortgage’s likely finish date.

Build a retirement budget covering housing, food, transport, health needs and regular bills. Compare it with your expected income and any mortgage payments still due. If your budget relies on clearing the home loan, check that the repayment schedule supports that plan.

Try a simple monthly comparison. In one column, record your take-home income, essential spending, debt payments and retirement contributions. In a second version, reduce the income figure to reflect a possible move to part-time work. If the mortgage fits only the first version, consider a smaller loan, a different term or a repayment plan that leaves more room.

Don’t treat every spare dollar as mortgage money. Extra repayments can reduce the balance faster, but accessible savings can help cover an unexpected bill or temporary income gap. Decide how much readily available money your household needs before committing surplus cash to repayments. Review that decision when your work, health or family responsibilities change.

Compare three repayment approaches: the required payment only, a higher regular payment, and occasional extra payments when income allows. Record how each affects your monthly budget and the mortgage end date. Check how extra payments work under your loan terms before relying on them. Your plan should remain manageable in ordinary months, not just when income is higher.

Include less frequent expenses in your retirement budget, such as vehicle replacement, home maintenance and annual bills. Note when each is likely to fall, then set aside money regularly so it doesn’t unexpectedly compete with mortgage payments. A calendar of these expenses can reveal months when your usual repayment plan leaves too little room for other commitments.

Write down the decisions that shape your plan: the repayment amount you can sustain, the savings you want to protect and what would trigger a review. For example, a change in work hours could prompt you to update the household budget before increasing repayments. This turns a broad goal into practical steps and helps you adjust your mortgage plan as your priorities shift.

Considering downsizing, part-time work, or investment income

Alternatives to a standard mortgage for older homeowners can include borrowing less, selling and buying a smaller home, or continuing to earn work income for longer. Each changes the repayment picture differently. Downsizing may reduce the loan required, while part-time work may help cover payments without moving. Compare these options with your budget and plans.

Start with your home. Estimate what selling your current property could leave after paying off its mortgage and allowing for moving and purchase costs. Then compare the price and ongoing costs of a smaller property with those of your current home. A lower loan may mean lower repayments, but a new location could affect transport, support networks and access to services.

Part-time work can help support repayments if your retirement plans include paid work. Build a budget using the income you expect from those hours, then test it against a period when that work is unavailable. Don’t rely on the most optimistic version of your work plans to make the mortgage affordable.

Rental income may also contribute to household cash flow. If you own a property you could rent out, list the expected rent alongside ongoing expenses, including maintenance and regular bills. A vacancy or repair can reduce what remains for mortgage payments, so don’t count every dollar of rent as available to repay debt.

NZ Super, if applicable, and reliable rental income can form part of your repayment plan. Consider when each income source would begin, how regular it is and whether it is likely to continue. Lenders assess income and supporting evidence as part of the application, so keep records showing where the money comes from.

Before relying on an option, write down the steps and their timing. For downsizing, include the sale, purchase and move. For part-time work, set out the expected hours and income. For rental income, allow for periods without a tenant and property expenses. Comparing the options side by side can show whether one is enough or you need a combination.

A residential investment property loan may be relevant if you’re considering buying a property to rent out. Treat rent as one part of the plan, not a guaranteed source of repayments. Compare expected income with ownership costs and the mortgage payment, then consider whether your budget could cope if rent stopped temporarily.

Choose a fallback before committing to a repayment plan. You might reduce spending, increase work hours if possible, or reconsider the property if your income changes. Write down what would prompt a review, such as a change in employment or rental income. A clear trigger can help you respond early, before payments become difficult.
Getting a mortgage in your 50s in NZ: balancing repayments and retirement

4. Maintaining flexibility in later retirement

A flexible mortgage plan gives you room to respond as your needs change later in life. Start by identifying what could affect repayments, such as reduced work, a move or new household responsibilities. Decide which changes would prompt a review. For example, a change in regular income could be a reason to revisit your repayment amount and household budget.

Review the loan structure as well as the payment. A fixed interest rate stays unchanged for an agreed period, which can make repayments predictable during that time. Check what happens when the period ends and whether your budget could manage a different payment. Don’t build a plan around one rate staying in place indefinitely.

Keep a clear record of your mortgage balance, repayment amount and remaining term. Review these details alongside your current income and spending. If you’re paying extra, check the loan terms first. Some arrangements may limit when or how extra repayments can be made, so don’t assume surplus funds are always freely accessible.

Plan for changes to your housing needs. If stairs become difficult, for instance, you might consider moving to a more suitable property. Think through how a sale, a new purchase and any remaining mortgage would affect your monthly commitments. A home that works now may not suit your needs throughout retirement.

Keep flexibility in your wider budget, too. Separate essential bills from spending you could adjust if income changed. This makes it easier to see which costs could be reduced before missing a mortgage payment. Set aside time to review the figures after a change in work, housing or family circumstances.

At age 75, retirement drawdown strategies may need review. Use that milestone to reassess the mortgage alongside your income, housing needs and expected spending. Ask whether the existing repayment plan still fits, or whether a change in the loan or home should be considered. Treat the review as a practical checkpoint, not an assumption that your circumstances will follow a set path.

Write a simple action plan covering what you’ll monitor, what change would trigger a review and which options you could consider. For example, a fall in income might lead you to reassess spending before deciding whether to adjust repayments or housing plans. Writing down these steps makes them easier to revisit as your priorities evolve.

5. Preparing for retirement while paying a mortgage

Before retirement, make sure you understand how your mortgage works day to day. Keep the loan agreement and recent statements together, and note the repayment amount, payment dates and any conditions that affect changes. This gives you a clear reference when reviewing your plans with a partner or adviser.

Build a cash-flow plan around when income arrives and bills are due. Record regular income dates, mortgage payment dates and when larger household expenses fall. If a payment is due before income arrives, ask about adjusting the timing to make your budget easier to manage.

Check how your plan would work if an income source stopped or arrived later than expected. List essential payments first, then identify discretionary costs you could temporarily reduce. This helps you see what practical changes are available before a short-term disruption affects your ability to make mortgage payments.

Include the property itself in your retirement planning. Note upcoming maintenance, accessibility changes or repairs that could affect your household budget. For example, consider a planned bathroom upgrade alongside mortgage payments, rather than treating it as an unrelated future expense.

Keep a record of conversations and decisions about the loan. Note the date, who you spoke with, what you discussed and any agreed next steps. If your circumstances change, this record can help you explain the background clearly without relying on memory alone.

If you share the mortgage, agree how you’ll make decisions about repayments, spending and changes to the home. Write down who will manage routine payments and how you’ll discuss changes in income or household needs. A shared plan can reduce confusion during a stressful transition.

Revisit the plan after a major change, such as finishing work, moving home or taking on caring responsibilities. Update the figures and decide what action makes sense before changing repayments or making a large purchase. Keeping the plan practical and current can help you make considered choices as retirement approaches.

Consider how much your retirement plan depends on staying in the home, and whether that assumption still fits your expected income and needs. The 2025 Massey University Retirement Expenditure Guidelines note that future generations of New Zealand retirees are expected to have lower home-ownership levels. Treat this as a reason to examine your own housing arrangements rather than as a prediction of what will happen to you. Set out the likely costs of keeping the property, including mortgage payments and planned work, and compare them with the income you expect to have available. If the figures feel uncertain, identify what information you need before making a decision.

Discuss what you would do if staying in the home became difficult to afford or manage. Consider possible changes to your living arrangements, when you might make a decision and how each option could affect your budget. Don’t make a major commitment based only on an optimistic estimate of future income. Revisit your assumptions when your retirement plans or household circumstances change. If you share the home or mortgage, make sure everyone understands the options and has a chance to raise concerns. Including these questions alongside repayments and maintenance can help you weigh housing decisions against your wider retirement needs.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you assess home loan options when you are weighing a property purchase against retirement plans. The conversation can focus on your expected income, repayment comfort and the loan structure that fits your goals, rather than treating age as the only factor. If a mainstream bank has declined your application, that does not have to end the discussion; 2nd Tier Loans may suit borrowers who do not fit mainstream bank criteria.

Bring a clear picture of your income, regular commitments, deposit and plans for work or retirement. Mortgage Suite Ltd can help you consider these details and discuss suitable lending options, keeping the long-term repayment plan in view. Our advice is free of charge with no obligation. To talk through your circumstances, visit mortgagesuite.co.nz.

Make your next mortgage decision with confidence

A plan for getting a mortgage in your 50s in NZ should leave room for the life you want beyond the next repayment. Before taking your next step, write down the questions that matter most, such as how borrowing fits your priorities or what would prompt you to review your plans. A focused list can help you have a clearer conversation about your options.

Use the conversation to explore the options that fit your circumstances and the trade-offs involved. Take time to consider the information and decide what feels workable for you.

Discuss your borrowing plans and take the next step with a clearer sense of what matters to you.

Frequently Asked Questions

Can you get a mortgage in your 50s in New Zealand?

Yes, getting a mortgage in your 50s in New Zealand is possible; age alone doesn’t automatically rule you out. Lenders consider your income, debts, deposit and ability to manage repayments over the loan term. They may also look at how you plan to meet payments if your employment income changes. Presenting a clear picture of your finances helps show how the proposed borrowing fits your circumstances.

How do NZ lenders assess retirement income and mortgage affordability?

In NZ, lenders assess whether your expected income can cover repayments alongside regular household commitments. They may consider ongoing work income, NZ Super or rental income, and review evidence such as income records and bank statements. If you expect to reduce your working hours, for example, show how the resulting income fits your budget. Regular expenses and existing debts also affect how much room remains for mortgage payments.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Equity Release Home Loan NZ: A Comprehensive Guide for 2026

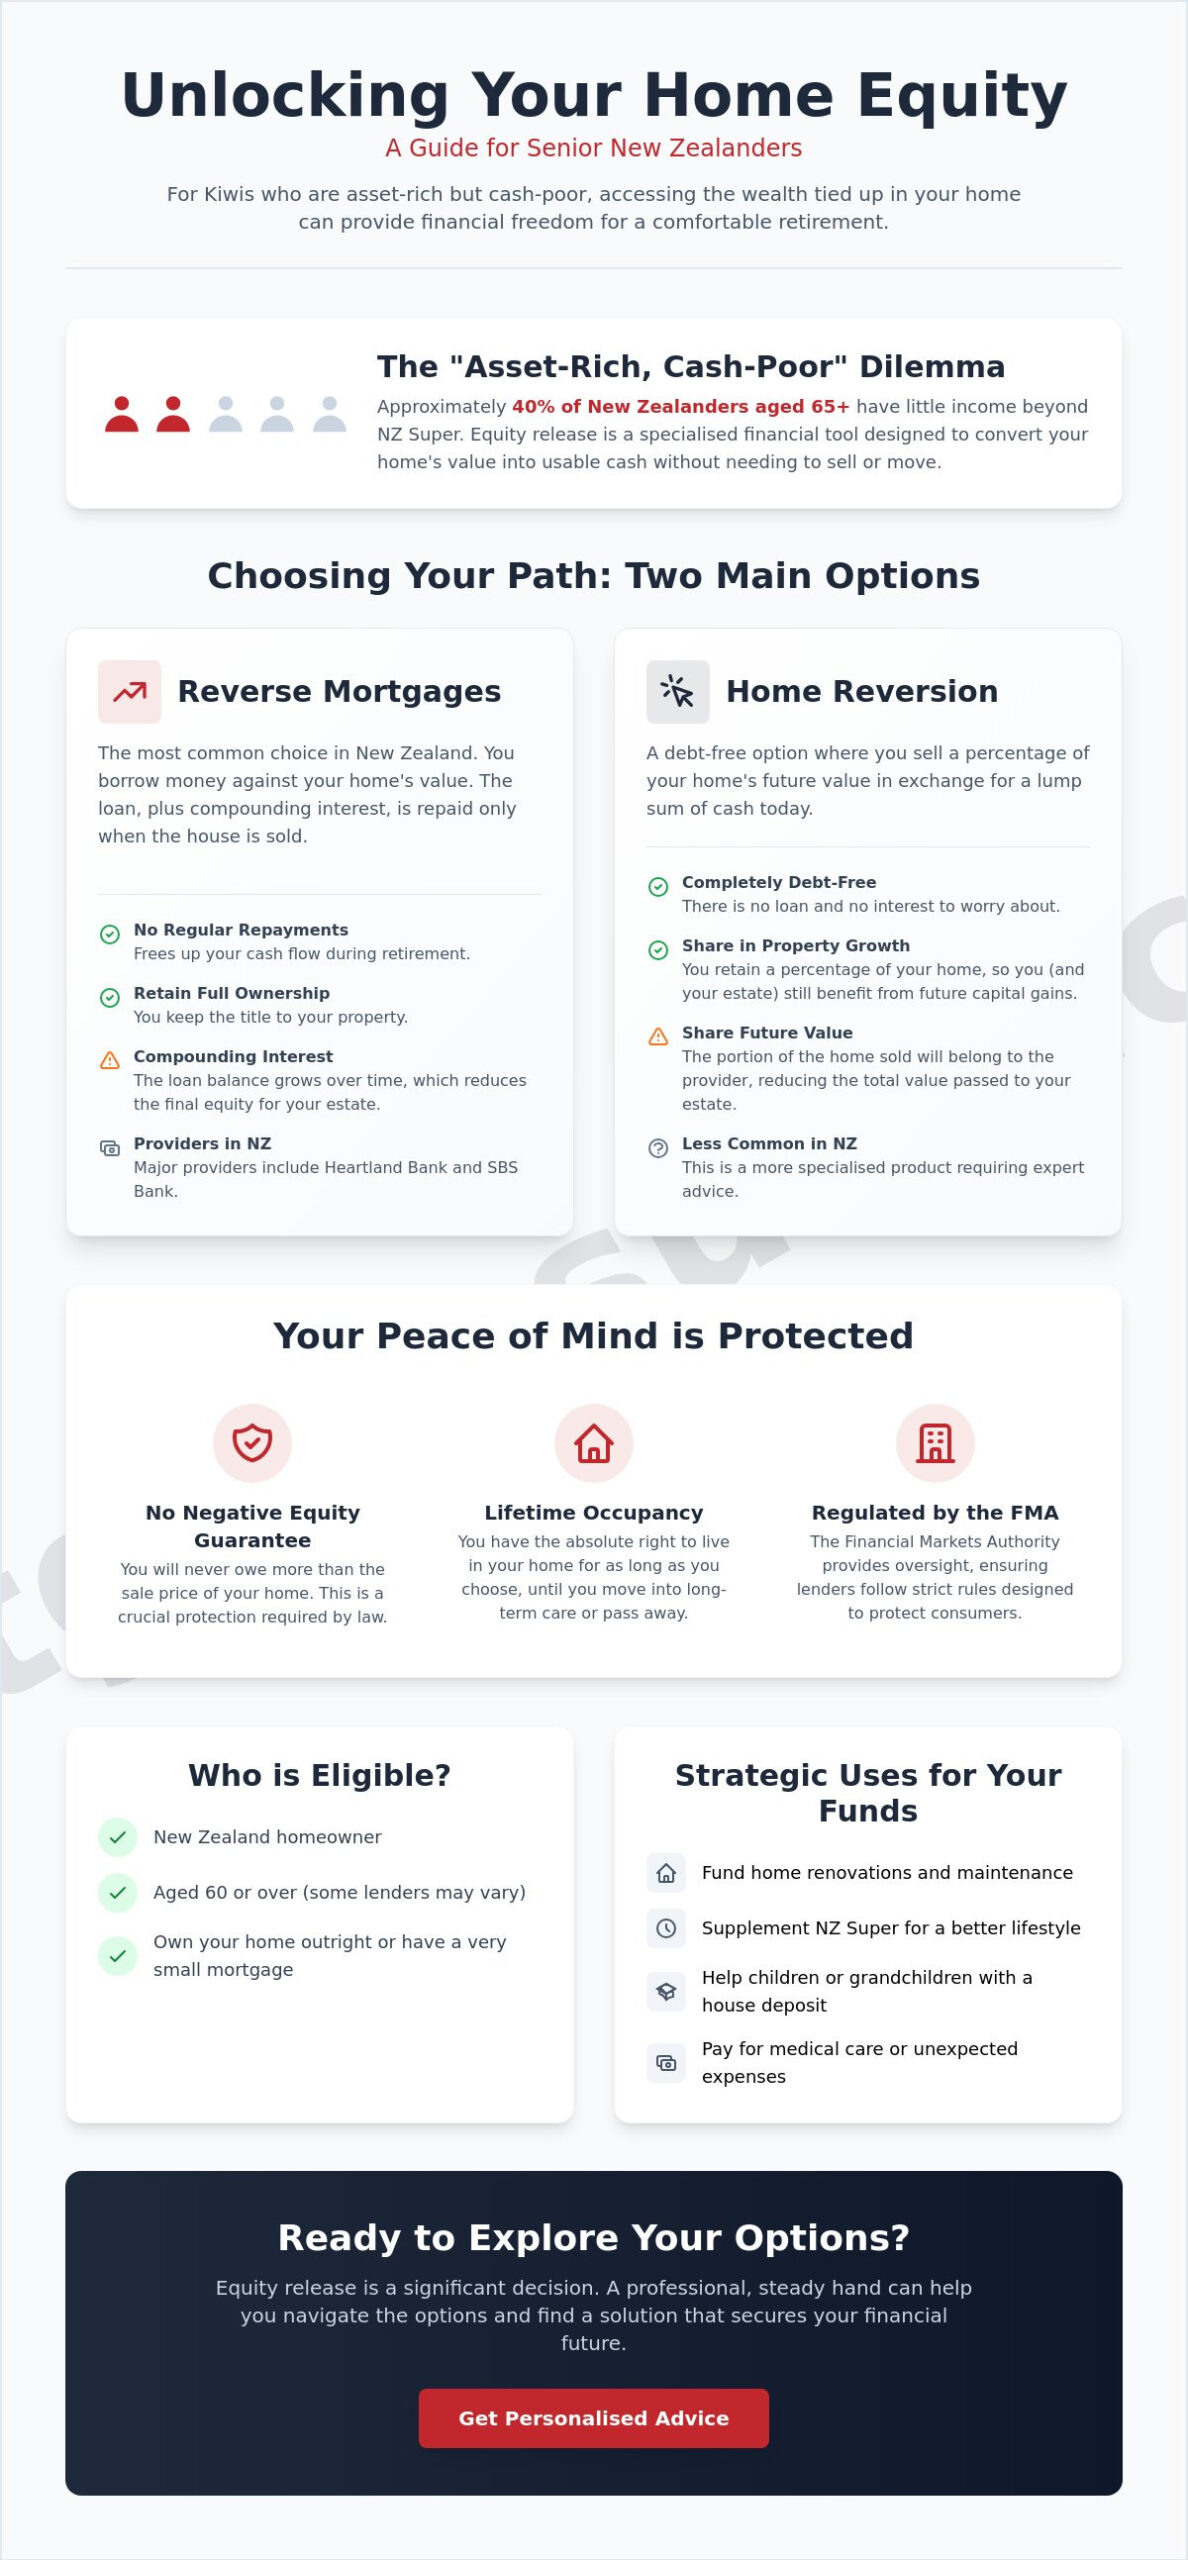
Approximately 40% of New Zealanders aged 65 and over have almost no other income besides NZ Super, which often leaves homeowners in the stressful position of being asset-rich but cash-poor. If you’ve spent decades paying off your mortgage only to feel the pinch of rising rates and insurance premiums, you’re certainly not alone. It’s a common frustration to see your wealth locked behind the front door while your daily budget feels increasingly tight. Many Kiwis are now exploring how a Home Equity Loan can bridge that gap, providing the financial breathing room needed for a truly comfortable retirement.

I understand that the thought of complex financial contracts can be daunting, but equity release is a strategic lifestyle choice that deserves a professional, steady hand. This guide will show you how to safely unlock your property’s value to fund medical care, home renovations, or even a house deposit for your grandchildren while you are still around to see them enjoy it. We’ll walk through the 2026 market landscape, including current interest rates from providers like Heartland and SBS Bank, the crucial no negative equity guarantees, and the latest FMA regulations designed to protect your legacy.

Key Takeaways

  • Understand how to access the “dead money” tied up in your property to support a comfortable lifestyle without the need to relocate or sell.
  • Compare the mechanics of reverse mortgages and home reversion to see how interest compounds versus selling a portion of your future equity.
  • Identify the specific eligibility requirements and age-based lending limits for a Home Equity Loan to ensure your financial plan is realistic and secure.
  • Learn about the “no negative equity” guarantee and other legislative safeguards that protect your home ownership and long-term peace of mind.
  • Discover how 2nd tier lending solutions can offer alternative pathways for homeowners who fall outside the rigid requirements of mainstream banks.

What is an Equity Release Home Loan in New Zealand?

For many Kiwis in 2026, the family home isn’t just a place of memories; it’s the largest financial asset they own. Equity release allows you to tap into what’s often called ‘dead money’, which is the wealth tied up in your bricks and mortar, and convert it into useable cash. This financial strategy has become a vital tool for New Zealanders who find themselves asset-rich but cash-poor, especially as the cost of living continues to climb.

The defining feature of this arrangement is how it differs from a standard Home Equity Loan. With a traditional mortgage, you’re required to make regular monthly principal and interest repayments. In contrast, an equity release product typically requires no monthly payments at all. Instead, the interest is added to the loan balance over time, and the total amount is only repaid when you eventually sell the property, move into long-term care, or pass away. You retain full ownership of your title and the absolute right to live in your home for as long as you wish.

Deciding which mechanism suits your family requires a clear understanding of the market. Most people choose between Reverse Mortgages vs. Home Reversion schemes. While a reverse mortgage is a loan that grows over time, home reversion involves selling a percentage of your property’s future value in exchange for a lump sum or income stream today. Both options are designed to provide financial freedom without the stress of meeting bank deadlines every month.

Who is Equity Release Designed For?

This path is generally tailored for homeowners aged 60 or older. While some 2nd tier lenders might offer flexibility, most mainstream providers in New Zealand, such as Heartland and SBS Bank, set their entry point at 60. It’s an ideal solution for those who are mortgage-free or have a very small remaining balance. If you’re looking to supplement your NZ Super or fund a specific life goal, a Home Equity Loan structured for equity release provides a steady hand in a fluctuating economy.

The Core Benefit: Ageing in Place

There is profound emotional and financial value in staying within your familiar neighbourhood and community. Downsizing is often touted as the only solution for retirees, yet it comes with significant baggage. Between real estate commissions, legal fees, and the physical stress of moving, you can lose a substantial portion of your wealth just by changing addresses. Equity release acts as a partnership with a lender, allowing you to stay put while managing your retirement cash flow effectively. It removes the obstacle of relocation and lets you enjoy the home you’ve worked so hard to pay off.

Reverse Mortgages vs. Home Reversion: Choosing Your Path

Selecting the right mechanism to unlock your property’s value is a pivotal decision that shapes your financial landscape for years to come. In New Zealand, the market has matured to offer two distinct paths: reverse mortgages and home reversion. While both allow you to stay in your home, they treat your property’s value in very different ways. One involves taking on a specialized Home Equity Loan where the debt grows over time, while the other involves selling a portion of your home’s future ownership today. The “best” choice isn’t universal; it depends entirely on your personal comfort with debt and how much of your home’s future capital gains you wish to protect for your estate.

If you’re feeling overwhelmed by these options, it’s helpful to view them as a strategic partnership between you and your lender. Taking the time to explore tailored home loan options can help clarify which path aligns with your long-term goals. Every homeowner’s situation is unique, and a veteran perspective is often the difference between a stressful contract and a secure retirement plan.

How Reverse Mortgages Work

A reverse mortgage is the most common form of equity release in the NZ market. Major providers like Heartland Bank and SBS Bank offer these products with variable interest rates, which sat around 7.75% to 7.99% in early 2026. The defining characteristic here is the lack of monthly repayments. Instead, the lender adds the interest to your loan balance each month. Compounding interest is interest charged on interest that causes the debt to grow over time. This means that while you enjoy the cash today, the total amount you owe increases as the years pass. The loan is eventually settled when the house is sold, typically when you move into a retirement village or pass away.

Understanding Home Reversion (The Debt-Free Option)

Home reversion, offered by providers like Lifetime Home, is often described as the debt-free alternative. Rather than borrowing money, you sell a fixed percentage of your home’s value to the provider. In exchange, you receive a lump sum or a regular income stream. The catch is that you sell this share at a discount to its current market value. For example, you might sell 25% of your home but receive less than 25% of its current worth in cash. The provider then receives their full percentage share of the final sale price whenever the home is sold. This provides total certainty because you don’t have to worry about fluctuating interest rates on a Home Equity Loan, but you do give up the potential for future capital gains on the portion you’ve sold.

Eligibility and Key Safeguards: What Kiwis Need to Know

To qualify for equity release in New Zealand, you generally need to be at least 60 years old, though some specific products like home reversion require you to be 70 or older. Your property typically needs to be a freehold title of a standard construction type. Lenders are often cautious with retirement village units or leasehold land due to the complex legal structures involved. If you’re considering a Home Equity Loan to fund your retirement, it’s vital to understand that the amount you can borrow is strictly tied to your age. This is a deliberate safety measure designed to protect your long term interests.

Lenders use a sliding scale for Loan-to-Value Ratios (LVRs) because they need to account for how long the interest might compound. At age 60, you might only be eligible to release 15% to 20% of your home’s value. By the time you reach 80, this limit often increases to 40% or 50%. This conservative approach ensures that even with the rising cost of living, you’re unlikely to exhaust your equity too early. I always recommend involving family members in these discussions. Transparency prevents future misunderstandings and ensures your heirs understand how the Home Equity Loan will eventually be settled.

Kiwis can take heart in the fact that from July 1, 2026, the Financial Markets Authority (FMA) has taken over regulatory responsibility for the Credit Contracts and Consumer Finance Act (CCCFA). This shift reinforces the high standards of responsible lending that protect your home and your legacy.

The No Negative Equity Guarantee

The most significant protection in the New Zealand market is the “No Negative Equity” guarantee. This industry standard ensures that you, or your estate, will never owe the lender more than the net sale price of your home. If the property market experiences a significant dip and the loan balance grows larger than the home’s value, the lender absorbs that loss. It’s a robust safety net that ensures no debt is ever passed on to your children or heirs.

Lifetime Occupancy and Spouse Protections

You have a legal guarantee of lifetime occupancy, meaning you cannot be evicted as long as you live in the home and meet basic obligations like paying your rates and insurance. It’s essential that both partners are named on the loan contract. This ensures the surviving spouse retains the right to live in the property if the other passes away or moves into care. To make these clauses ironclad, New Zealand law requires you to seek independent legal advice before signing any equity release agreement. This ensures you fully grasp the long term implications of the contract from a neutral professional perspective.

Equity Release Home Loan NZ: A Comprehensive Guide for 2026

Strategic Uses for Equity Release in 2026

In the current economic climate, equity release has evolved from a last resort into a sophisticated tool for lifestyle management. With approximately 25% of older New Zealand households sitting on an average of over $600,000 in home equity while struggling on a limited income, the shift toward active wealth management is clear. A Home Equity Loan allows you to convert that stagnant value into a liquid resource, ensuring your retirement years are defined by comfort rather than compromise. Whether you’re looking to fund a dream trip or simply want to ensure your daily budget isn’t dictated by the next rates increase, the strategic use of your home’s value provides a steady path forward.

For those who view their property as part of a broader wealth strategy, it’s also worth exploring non-bank investment property loans NZ. This can be particularly relevant if you’re considering using released funds to diversify your portfolio or support a family member’s investment goals. Some Kiwis also find value in using home equity for investment NZ as a way to put their property’s unlocked value to work in the broader market, rather than letting it sit idle. Taking a proactive approach to your assets ensures that your hard-earned wealth serves your current needs while still respecting your long term legacy.

Helping the Next Generation

One of the most rewarding uses of equity release is the concept of a ‘living inheritance’. Instead of leaving your wealth in a will, you can provide a tax-free gift to your children or grandchildren now. This is frequently used to help the younger generation secure a deposit for their first home, which has become increasingly difficult in the 2026 market. You can read more about the challenges they face in our home loans for first home buyers New Zealand guide. By acting now, you get to see the impact of your support while you’re still around to enjoy it, all without the tax implications that often accompany other forms of income.

Home Improvements and Health

Maintaining independence often requires practical ‘age-friendly’ modifications to your property. Funding bathroom refits, ramps, or kitchen adjustments through a Home Equity Loan ensures you can remain in your community for longer. Beyond the home, many Kiwis use these funds to cover the ‘gap’ in healthcare costs. While the public system is robust, waiting lists for elective procedures like hip replacements or specialist dental work can be long. Releasing equity lets you bypass these queues and access private care immediately.

Debt consolidation remains another powerful use of these products. Clearing high-interest credit cards or car loans by rolling them into a low-pressure equity release structure can significantly improve your monthly cash flow. If family members are looking to grow their own property portfolios, an interest only investment property loan NZ can be a smart way to maximise cash flow while building long-term wealth. If you’re ready to see how your property could work harder for your family, contact us to discuss your options today. We take pride in helping you navigate these choices with the care and expertise your situation deserves.

Beyond the Big Banks: Navigating 2nd Tier Solutions

While Heartland and SBS Bank are the most visible names in the New Zealand equity release market, they aren’t the only options available to you. For many Kiwis, the rigid criteria of mainstream institutions can become a frustrating roadblock. This is where 2nd tier solutions become essential. At Mortgage Suite Ltd, we leverage over two decades of industry experience to help you find alternative capital that fits your specific circumstances. Choosing a non-standard Home Equity Loan doesn’t mean you’re compromising on safety or security. It simply means you’re working with a veteran who knows how to navigate the complexities of the lending landscape to find a solution that works.

Working with a veteran expert negotiator like Krish Krishna provides you with a steady hand in a fluctuating market. We don’t just process applications; we advocate for your best interests throughout the entire journey. This proactive attitude is often the difference between a declined request and a successful outcome that provides the financial freedom you’ve been searching for. Our reputation is built on being a dedicated partner who values long term relationships over simple transactions.

When a Mainstream Bank Says No

Mainstream banks often struggle with “out of the box” scenarios. If your home is held in a family trust or is a unique property type, you might find the big lenders hesitant to move forward. Similarly, if your retirement income is non-traditional, a standard bank might decline your application based on their internal algorithms. A professional negotiator understands how to present your case to 2nd tier lenders who offer more flexible terms for older borrowers. We bridge the gap between the rigid world of institutional banking and the personal needs of the individual borrower, ensuring your unique situation is understood and valued. Finding the right Home Equity Loan through an alternative lender can often provide the same protections as a big bank but with the flexibility you actually need to move forward with confidence.

Why a Consultative Approach Matters

This process should never feel like a simple transaction. It’s a long-term financial partnership that requires a methodical and thorough understanding of your goals. We focus on organising a plan that balances your immediate cash needs with the inheritance goals you have for your family. By taking a consultative approach, we ensure that every step is logical and transparent, removing the anxiety often associated with complex financial decisions. This structured path creates a sense of stability, mirroring the organised nature of the financial services we provide. If you’re ready to explore a path that the big banks might have missed, Book a confidential chat with the Mortgage Suite Ltd team to explore your options and secure the retirement you deserve.

Take the Next Step Toward Financial Freedom

Unlocking the wealth in your property is a significant decision that requires a clear strategy and a steady hand. By understanding the core differences between debt-based and equity-based release, you’re already better positioned than most. It is vital to remember that your path isn’t limited to the big banks; 2nd tier lenders often provide the flexibility needed for unique property types or complex family trusts. A Home Equity Loan should be a tool that serves your lifestyle, not a source of stress.

At Mortgage Suite, we bring over 20 years of banking and lending expertise to the table. We are specialists in 2nd tier and alternative finance, with a hard-earned reputation for dedicated negotiation and client advocacy. We don’t just find loans; we build partnerships that respect your legacy and your future goals. Secure your retirement future with a tailored equity release plan from Mortgage Suite. Your home has looked after you for decades, and with the right plan, it will continue to support the comfortable retirement you’ve worked so hard to achieve.

Frequently Asked Questions

Is an equity release home loan a good idea in New Zealand in 2026?

It is a strategic lifestyle choice for many Kiwis, especially given that 40% of retirees rely almost solely on NZ Super. If your property has significant value but your daily budget is tight, this tool provides a steady hand. It allows you to stay in your community and maintain your independence while accessing the capital you’ve built up over decades.

Can I still leave my house to my children if I have a reverse mortgage?

You absolutely can leave your property to your heirs. You remain the registered owner on the title throughout the life of the loan. When the house is eventually sold, the loan balance is settled first, and every cent of the remaining equity is passed on to your estate or children as per your will.

What happens if the interest on my loan becomes more than the house is worth?

You are protected by a “No Negative Equity Guarantee” which is a standard feature of reputable New Zealand providers. This means you’ll never owe more than the net sale price of your home. Even if the market dips or interest compounds significantly, the lender absorbs the difference, ensuring no debt is ever passed to your family.

Do I have to pay tax on the money I receive from an equity release loan?

No, the funds you receive are not considered taxable income in New Zealand. Because the money is a loan against your property’s value rather than earnings, it is currently tax-free. This makes a Home Equity Loan an efficient way to supplement your cash flow without increasing your tax obligations or affecting most government benefits.

What is the minimum age for equity release home loans in NZ?

The minimum age for a standard reverse mortgage in New Zealand is 60 years old. For specific debt-free products like the Lifetime Home reversion scheme, the entry age is higher at 70. Lenders set these limits to ensure the loan structure remains sustainable over the long term, protecting both the borrower and the lender’s interests.

Can I sell my house and move if I have an existing equity release loan?

You retain the freedom to sell your home and move at any time. When you sell, the equity release loan is typically repaid from the sale proceeds. In some cases, you may be able to transfer the loan to a new property, provided the new home meets the lender’s criteria for security and value.

Are there any monthly repayments required for a reverse mortgage?

There are typically no regular monthly repayments required for a reverse mortgage. Unlike a traditional Home Equity Loan, the interest is added to your loan balance each month. This compounds over time, meaning the debt is only settled in full when you move out permanently, sell the home, or pass away.

How much equity can I typically release from my home based on my age?

The amount you can release depends on your age, with limits starting at approximately 15% to 20% of your home’s value at age 60. As you get older, this percentage increases, often reaching 40% to 50% for those aged 80 and over. These conservative limits are designed to ensure you always retain a significant portion of your home’s equity.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.