What if the amount your business needs is more than a lender is prepared to offer? If you’re asking how much can i borrow for a business loan nz, the answer depends on more than turnover. Lenders consider whether your business can manage the repayments, its existing commitments, what the loan is for and whether you can offer security, such as property or another asset.
It’s understandable to feel unsure, especially if your income varies or your finances are more involved than a standard application. Borrowing capacity is the amount a lender may consider manageable. Your funding goal is what you need to move the business forward. Those amounts don’t always match, but understanding the difference can help you plan your next steps.
This guide explains what can shape a business loan assessment, how the loan purpose and security may affect your options, and what to organise before discussing finance. Mortgage Suite arranges business loans, commercial property finance, property development loans and 2nd tier lending. Founder Krish Krishna brings more than two decades of banking experience. A decline from a mainstream bank doesn’t necessarily close the door; your next step depends on your circumstances and which lending approach may fit.
Key Takeaways
- There’s no single figure for how much can i borrow for a business loan nz. The amount depends on your business’s ability to manage repayments and the details of your plans.
- Organise clear financial records and trading information so lenders can understand how your business is performing.
- Compare finance structures by what the funds are for, how repayments work and whether security is involved.
- Before applying, set out how much you need, when you need it and what commitments your business already has.
- A mainstream bank’s decision is one factor, not the whole picture. Business, commercial property, development and alternative lending pathways may also be worth considering.
How much can you borrow for a business loan in NZ?
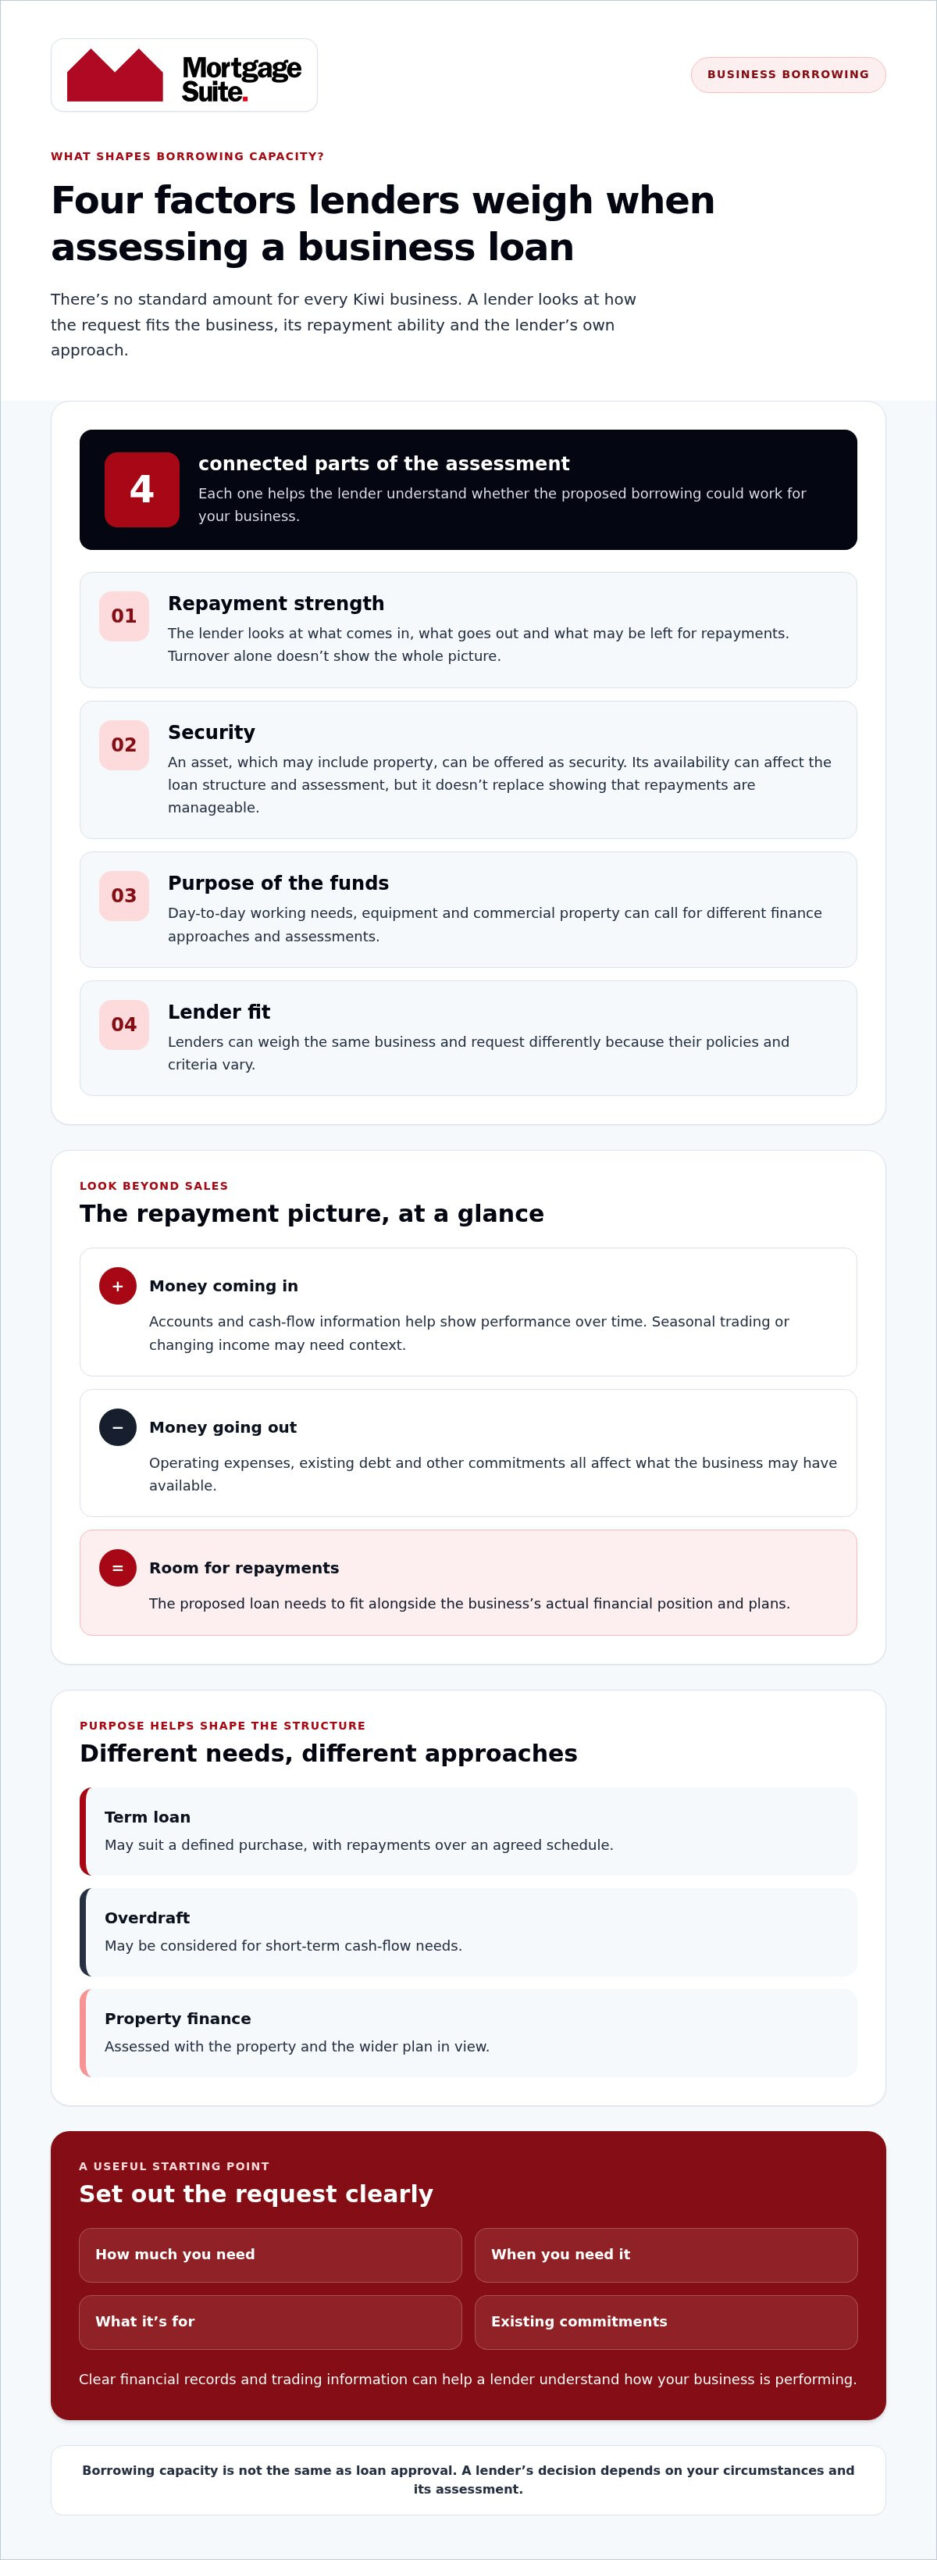
It’s difficult to estimate a borrowing limit without looking at the business, the purpose of the funds and how repayments could fit its plans. There isn’t a standard figure that applies to every Kiwi business. A useful starting point is to separate the amount you want from the amount the business could reasonably repay.
Why there is no standard business loan amount
Businesses can look very different on paper. One may have steady trading and established records, while another may be newer, seasonal or planning a major change. Existing commitments matter too, as does the reason for borrowing. Funding a specific purchase, managing a cash-flow gap or supporting growth may each call for a different assessment.
Borrowing capacity is the amount a lender may consider supportable after reviewing a business’s ability to make repayments and other relevant factors. Lenders have different policies, and they may view the same business differently. For a plain-English introduction to business loan basics, including secured and unsecured borrowing, see this overview of a Business loan.
A calculator or quick estimate can be a starting point, but it won’t account for every detail in your trading history, commitments, plans or a lender’s criteria.
Borrowing capacity is not the same as loan approval
An early estimate can help with planning, but it isn’t a full assessment or a final decision. A lender considers the information in your application and whether the proposed repayments appear manageable over time. If the repayment plan doesn’t fit the business’s financial position, you may need to reconsider the amount or structure.
For example, a business may want funds to expand, but its current cash flow may be better suited to a smaller first step or a different structure. That doesn’t mean the goal is out of reach. It means the funding plan needs to be considered alongside the business’s circumstances and the lender’s approach.
A decline from one lender can feel personal, especially after you’ve put time into an application. It isn’t a judgement on your character or your business’s potential. A decline may reflect that lender’s criteria or preferred approach, rather than every option available. Understanding why the application didn’t fit can help you decide what to adjust before exploring another path.
What determines how much a business can borrow?
A lender looks beyond sales figures to understand what money comes in, what goes out and how much may be left for repayments. The key question is whether the business could manage a proposed loan alongside existing commitments, including other debt and regular operating expenses.
Business income, performance, and existing commitments
Business accounts and cash-flow information can show how the business is performing over time. Turnover gives an indication of sales, but it doesn’t show the full picture on its own. Costs, existing repayments and changes in income all affect how much may be available for a new commitment.
Consistent earnings may give a lender a clearer repayment picture. Seasonal trading, on the other hand, can mean income rises and falls during the year. Self-employed owners may also need to explain how they draw income from the business and why it varies. That context helps a lender understand the figures rather than focus on one headline number.
Keep the picture realistic. If the business already manages several commitments, a lender will consider how a new repayment could fit alongside them, not just whether sales have been strong.
Loan purpose, security, and lender fit
The reason for borrowing helps shape the type of finance that may suit. Funding day-to-day working needs differs from buying equipment or purchasing commercial property. For example, a term loan may suit a defined purchase with repayments over an agreed schedule, while an overdraft may be considered for short-term cash-flow needs. Property finance is assessed with the property and the wider plan in view.
Security is an asset a lender may rely on if the loan isn’t repaid. A secured loan is linked to security, which may include property. With lending that doesn’t use property security, a property isn’t put forward in the same way. Available security can influence the structure and assessment, but it doesn’t replace the need to show that repayments are manageable.
Repayment strength, security, purpose and lender fit all shape how much a business may be able to borrow. Lenders can weigh these factors differently, so the same business and request may be viewed differently across applications. To work out how much can i borrow for a business loan nz, start by matching the request to a clear business purpose and a repayment plan that reflects your actual cash flow.
Mortgage Suite can help you compare business lending pathways in light of your circumstances and plans.
Which business loan approach may suit your borrowing needs?
The right structure depends on what the funds are for, how you expect to repay them and whether you can offer security. Comparing these details helps you discuss finance that fits the business purpose, rather than focusing only on the amount you’d like to borrow.
| Finance approach | Business-purpose fit | Repayment approach | Security and information to prepare |
|---|---|---|---|
| Term loan | A defined business purchase or expense. | A lump sum with a set repayment schedule and end date. | Security depends on the lender and application. Prepare the purchase details, business accounts and cash-flow information. |
| Overdraft | Managing short-term cash-flow needs. | Provides access to funds as needed, subject to the agreed facility terms. | Security requirements can vary. Explain the timing of income and expenses and how the facility would support working needs. |
| Commercial property finance | Purchasing or refinancing commercial property. | Repayments are set out under the loan agreement. | The property is central to the assessment. Prepare property details, the purchase or refinance purpose and business financial information. |
| Property development finance | Funding a property development project. | The funding structure is considered in light of the project and its plans. | Prepare project information, costs and timing, along with details of available security and the wider business position. |
Business loan or commercial property finance?
General business lending is usually considered in relation to business activity, such as meeting working needs or funding a purchase. Commercial property finance centres on a property transaction, while property development finance relates to a development project. The asset or purpose being funded shapes the lending discussion and the information a lender may need.
If you’re buying or refinancing a commercial property, it may make sense to explore property finance rather than treat it as a general business loan. Mortgage Suite can help you consider the business purpose and property plans together.
Mainstream or 2nd tier lending?
Mainstream lenders have their own criteria, and a business, property or project may not fit the way a particular lender assesses applications. 2nd tier lending can be an alternative for some circumstances that sit outside mainstream bank criteria, but it doesn’t guarantee approval. The available structure and terms depend on the individual assessment.
How much you can borrow may partly depend on which lending approach best matches the purpose, repayment plan and available security. Mortgage Suite arranges business, commercial property, property development and 2nd tier lending, helping you compare possible paths in light of your circumstances.
How to prepare for a business loan assessment
Some preparation can make it easier to explain what your business needs and give a lender a clearer picture of its finances. You don’t need every answer before you start, but accurate, consistent information can make the discussion more useful.
- Clarify the purpose. Explain what the funds would be used for and how they would support the business. Be specific, whether you’re meeting a working need, buying equipment or funding a property project.
- Set out the amount and timing. Note how much you’re seeking and when you need access to the funds. Treat this as the request to assess, not proof that the full amount will be affordable.
- Review cash flow. Look at money coming in and regular business expenses going out. If income changes through the year, note the pattern rather than relying on the strongest trading period.
- List existing commitments. Record current lending and other regular repayments so you can consider how a new repayment might fit alongside them.
- Identify possible security. Note whether the business or its owners may be able to offer an asset, such as property, as security. The lender’s assessment will depend on the circumstances and proposed structure.
Organise the information lenders may ask about
Gather current business accounts, cash-flow information and details of existing lending. It also helps to write a short summary of what the business does, how it trades, what causes income to vary and how you plan to use the funds. Lenders may ask for different information, so focus on making the picture clear rather than assuming every application requires the same documents.
Check that the figures and explanations tell a consistent story. If income has changed or a trading period looks unusual, a brief explanation can provide useful context. This helps a lender assess the business as it operates, rather than seeing figures without background.
Build a repayment plan around the business
Compare possible repayments with everyday operating needs and existing commitments. Ask yourself whether the business could manage them during a quieter period, not only when sales are strong. This cautious view can help you consider a suitable request before applying.
If you’re still working out how much can i borrow for a business loan nz, a clear summary of purpose, timing and cash flow is a practical place to start. For plain-English finance learning, explore the Mortgage School finance guides. When you’re ready to discuss business finance, Mortgage Suite can help you consider options in light of your plans and circumstances.
How Mortgage Suite can help you explore business borrowing options
Once you’ve mapped out your business purpose, finances and likely repayments, the next step is to consider which lending path may fit. Mortgage Suite can help you compare business loans, commercial property finance, property development finance and 2nd tier lending in light of your circumstances. The focus is on understanding what you’re trying to achieve and how different lenders may view the request, not just the headline borrowing figure.
A personal discussion about your business goals
A useful conversation starts with what the funds are for, how the business is tracking and what outcome you’re working towards. You can talk through your financial position, existing commitments, available security and details that may need explaining, such as changing or seasonal income. This helps build a clearer picture of the request and which lender’s approach may be worth considering.
Mortgage Suite acts as a personal advocate, helping you assess lender fit and discuss how to present the application. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite has supported borrowers since 2000. You can read more about Mortgage Suite’s experience and approach.
A bank decline does not have to end the conversation
A decline from a mainstream bank can be disappointing, but it doesn’t define your business or mean every lending option is closed. Lenders may assess business income, security, property and project details differently. Understanding what didn’t fit can help clarify whether the request, structure or lender pathway needs another look.
For some businesses whose circumstances sit outside mainstream criteria, 2nd tier lending may be an alternative to explore. It isn’t a promise of approval, and the right option depends on the full application. Mortgage Suite can help you compare potential pathways across business and alternative lending, so you can make an informed decision about what to pursue.
If you’re asking how much can i borrow for a business loan nz, a discussion grounded in your goals and financial position is a practical next step. Talk through your business finance options with Mortgage Suite and consider a path that fits your circumstances.
Take the next step with a clearer plan
There’s no single figure that answers how much can i borrow for a business loan nz. A lender considers whether repayments fit the business’s cash flow and commitments, what the funds are for, any available security and how the application fits its lending approach. A clear picture of your finances and plans can help you explore suitable options.
If your business needs finance, commercial property funding or support for a development, the right approach starts with your circumstances, not a one-size-fits-all estimate. A decline from one lender doesn’t necessarily close off other pathways, including 2nd tier lending, though every option depends on an individual assessment.
Mortgage Suite has supported borrowers since 2000, and founder Krish Krishna brings over two decades of banking experience. That experience informs a personal approach to comparing business and alternative lending options, without promising a particular outcome.
Ready to talk through your goals and what your business may be able to manage? Talk through your business finance options. A clear conversation can help you work out a practical next step.
Frequently Asked Questions
How much can I borrow for a business loan in NZ?
There’s no standard amount that every New Zealand business can borrow. How much can i borrow for a business loan nz depends on factors such as the business’s ability to manage repayments, existing commitments, the loan purpose and available security. The amount you want may differ from what a lender considers manageable. An early estimate can help with planning, but a lender’s assessment determines what it may offer.
What do lenders look at when deciding how much a business can borrow?
Lenders consider whether the business can meet repayments alongside its usual expenses and current debt. They may review business accounts, cash-flow information, trading performance, the purpose of the loan and available security. Turnover alone doesn’t show how much money remains after costs and commitments. If income varies because the business is seasonal or self-employed, explaining the pattern can help a lender understand the figures in context.
Can I get a business loan if my business is new?
A newer business may still be able to explore finance, but its shorter trading history can make it harder for a lender to assess performance from past records. The lender may consider the business plan, expected cash flow, the owner’s relevant experience, existing commitments and available security. Requirements differ between lenders, and there’s no guaranteed outcome. Clear information about the business purpose and how repayments could be managed can support an initial discussion.
Can I borrow against property for a business loan?
Property may be offered as security for some business lending, subject to the lender’s assessment and the details of the loan. Security is an asset a lender may rely on if repayments aren’t made. Using residential property can connect personal assets with business borrowing, so consider the implications carefully. The property, the business’s ability to repay and the loan purpose all matter. Offering security doesn’t guarantee approval or a particular amount.
Can I get a business loan if a bank has declined my application?
A decline from one bank doesn’t necessarily mean every option is closed. Lenders can assess business finances, security and loan purposes differently, so it may help to understand what didn’t fit before considering another pathway. 2nd tier lending may suit some circumstances outside mainstream bank criteria, but approval isn’t guaranteed and the application still needs assessment. Mortgage Suite supports business and 2nd tier lending for varied borrower circumstances across New Zealand.
What information should I prepare before applying for a business loan?
Prepare current business accounts, cash-flow information and details of existing loans or other regular commitments. Write a short explanation of what the business does, how its income changes during the year, what the funds are for, how much you’re seeking and when you need them. If you can offer property or another asset as security, note that too. Lenders may ask for different information, so keep your records clear and consistent.
Is a business loan the same as commercial property finance?
No. A business loan is a broad term for borrowing to support a business purpose, while commercial property finance focuses on funding a commercial property purchase or another property-related transaction. The purpose and asset being financed shape the lending discussion and information required. Property development finance is another distinct pathway, aimed at funding a development project. The most suitable option depends on your plans, financial position and how repayments could fit the business.