New Build Turnkey Loans NZ: How to Compare Your Options

The lowest interest rate may not be the best starting point when you’re comparing new build turnkey loans nz. The contract’s payment dates need to line up with the lender’s assessment and settlement process, and turnkey finance can work differently from buying an existing home or funding a build in stages.

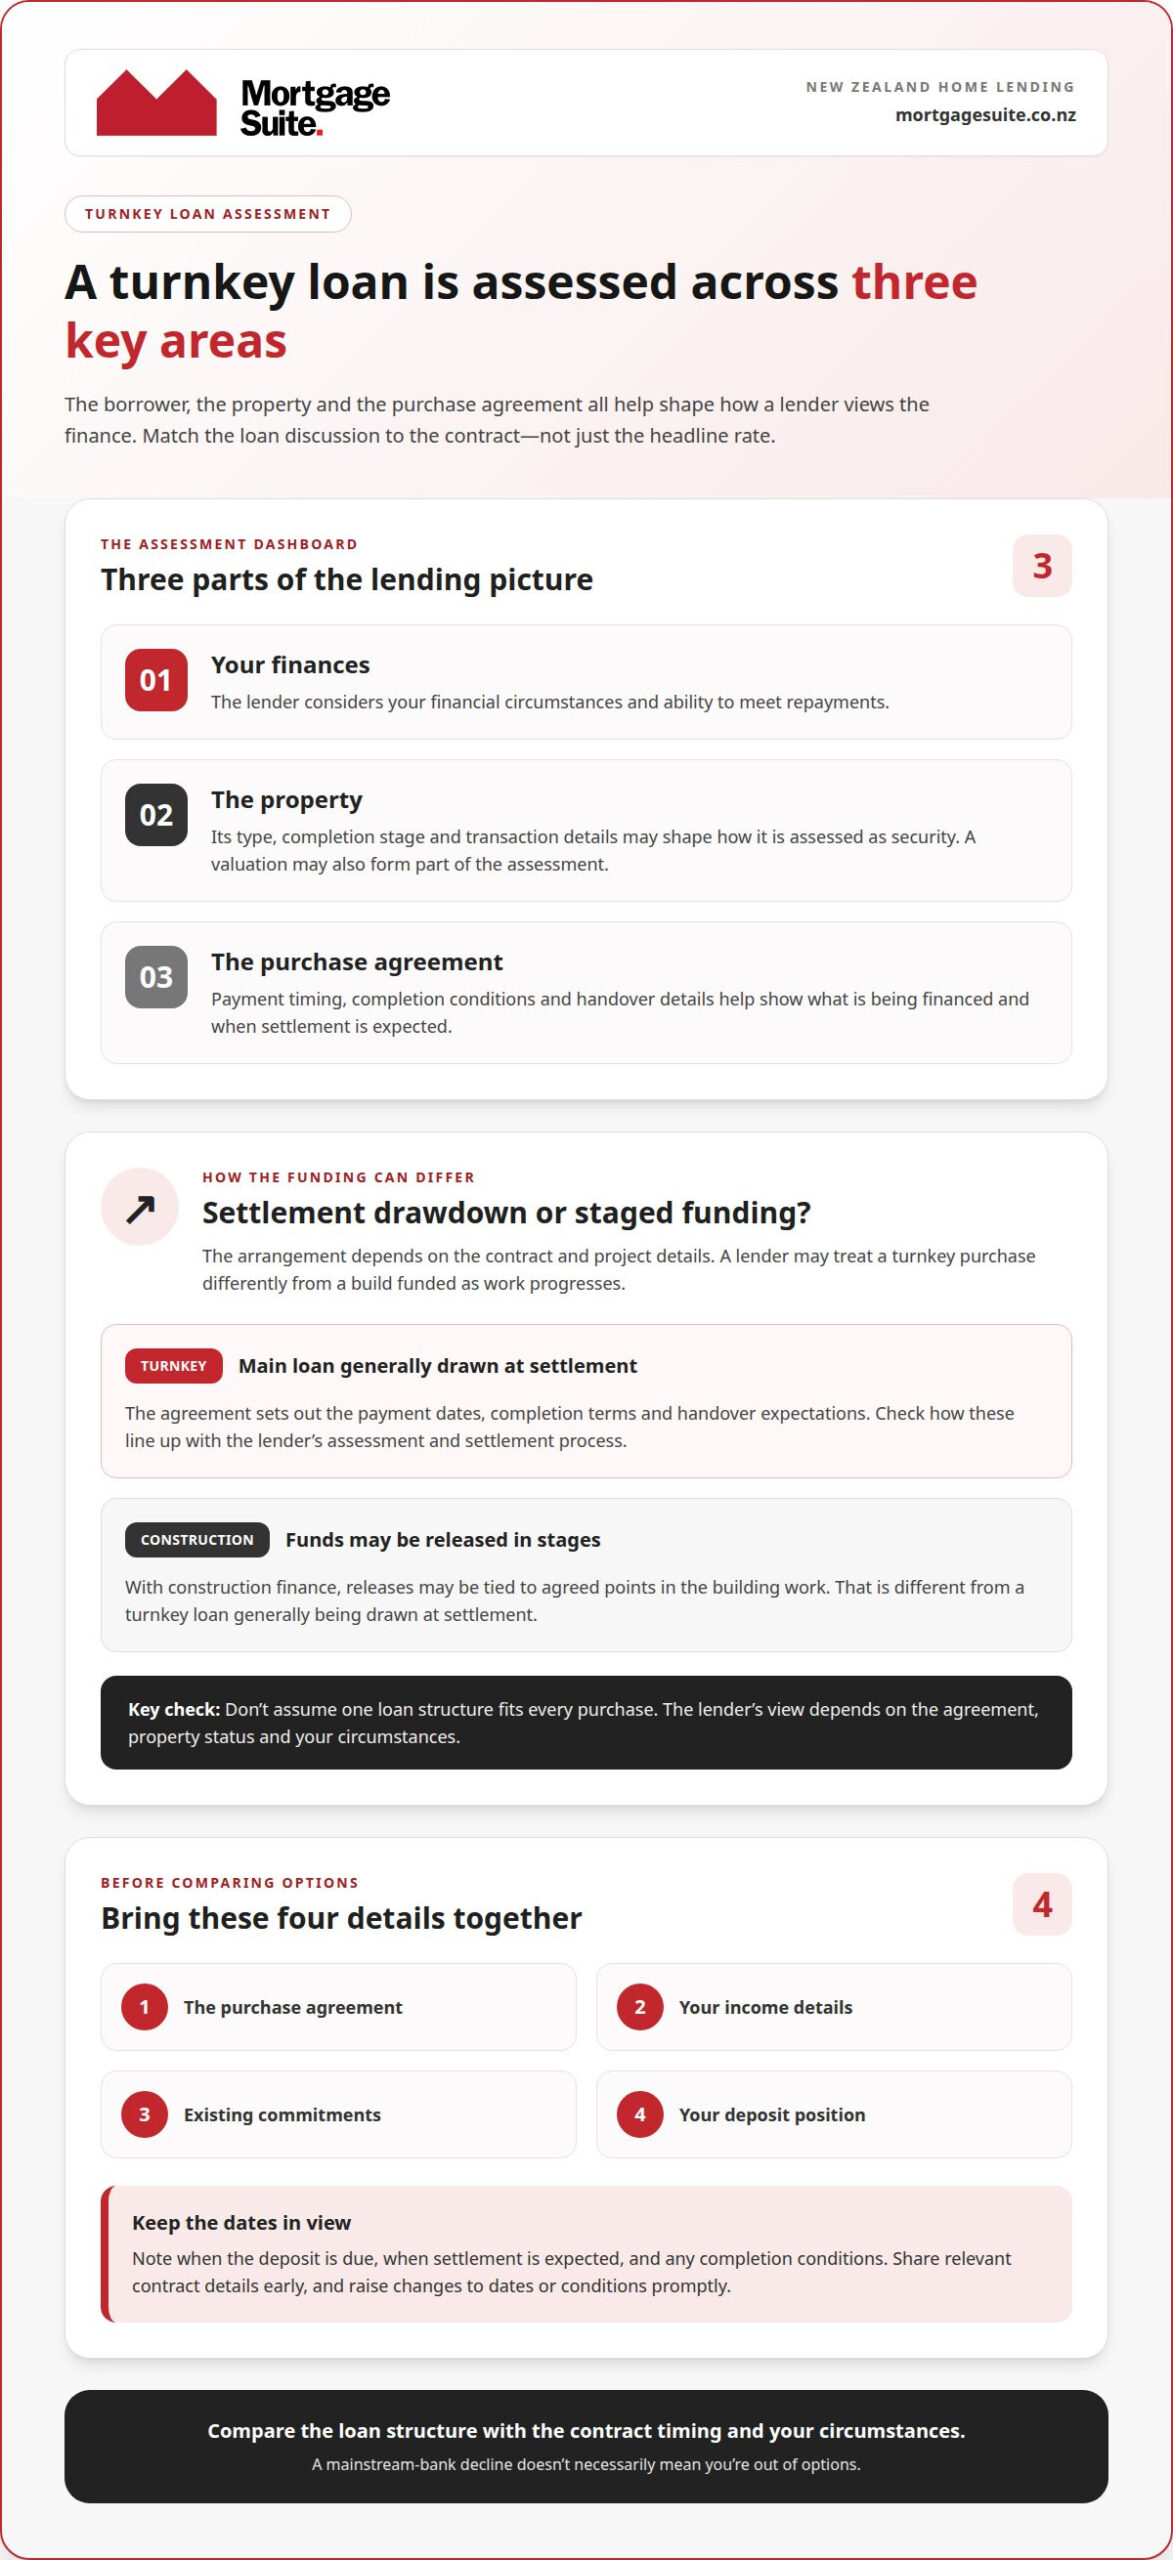
With a turnkey build, the main loan is generally drawn at settlement rather than released in stages during construction. Before signing or relying on a particular loan structure, understand when your deposit is due, when settlement is expected and what the lender will assess.

This guide explains how turnkey lending differs, what lenders may consider and how to compare options beyond the headline rate. It also covers what to prepare for a conversation with a mortgage adviser. Mortgage Suite Ltd can help you weigh lender fit against your circumstances and contract, and support you through a process that can feel stressful. A decline from a mainstream bank doesn’t necessarily mean you’re out of options.

Key Takeaways

  • New build turnkey loans nz can differ from off-the-plans purchases and construction finance. Use the contract and lender’s assessment to understand which structure may fit.
  • Discuss your finances alongside the property and purchase agreement. A valuation may also form part of the lender’s assessment.
  • Gather your agreement, income details, existing commitments and deposit position before comparing proposed loan structures.
  • Look beyond the headline interest rate and consider how each option fits the contract timing and your circumstances.
  • Mortgage Suite can help you compare lender fit. Founder Krish Krishna started the business in 2000 after 18 years in banking.

What are new build turnkey loans in NZ and how do they work?

A turnkey home is a new property sold under an agreement that sets out how and when the home will be completed and handed over. The aim is for you to take possession of a finished home, but the details depend on the contract. Inclusions, completion conditions and payment dates all affect how you plan your finance.

New build turnkey loans nz aren’t simply a standard mortgage with a different label. A lender may consider the property’s status, the agreement and your financial circumstances when assessing how the loan could be arranged. Read the payment and completion terms carefully, then compare them with the proposed finance before relying on a particular structure.

What does turnkey mean when buying a new home?

“Turnkey” generally describes a home sold with an agreed completion and handover position. The contract sets out what you can expect, so don’t assume every finished home includes the same fittings, finishes or extras. Check the inclusions, any conditions that must be met before handover, and the payment dates. These details help you understand what the lender is being asked to finance and when funds may be needed.

For example, if the home is still being completed, compare the contract’s list of inclusions with the expected handover conditions. Then map the stated payment dates against your finance discussions. As completion approaches, the lender assesses the application in light of the agreement and the property’s status. Settlement follows the contract requirements once the relevant conditions are met. The contract sets the actual sequence, so don’t assume every purchase follows the same timeline.

Is turnkey finance the same as a construction loan?

Not necessarily. A turnkey purchase may be financed as a property purchase, with lending arranged for settlement under the agreement. A construction loan, by contrast, may release funds in stages as building work reaches agreed points. The turnkey contract concept centres on delivery of a completed project, while staged funding is tied to progress during the build. How a lender treats a particular arrangement depends on its details.

The signed agreement and the project stage matter. A home close to completion may raise different finance questions from a project where building has only just begun. The lender may assess the purchase terms, the property and your ability to meet repayments before deciding on a suitable structure. Neither a purchase-style loan nor staged construction finance is automatically right for every buyer.

Before signing, make sure you understand the agreement’s payment dates, completion terms and handover expectations. Resolve any uncertainties before assuming a particular finance arrangement will fit. For buyers considering new build turnkey loans nz, matching the loan discussion to the contract can help reduce the risk of a timing mismatch and make the next steps easier to plan.

How lenders assess a turnkey home loan in New Zealand

A lender considers more than the home itself. It will look at your finances, the property and the agreement that sets out how the sale will proceed. Your ability to repay matters, as do the property’s status and the timing and conditions in the contract.

A turnkey loan assessment brings together three broad areas: the borrower, the property and the purchase contract. Sharing the agreement early can help you discuss whether a proposed lending structure fits the transaction, rather than focusing only on the amount you hope to borrow.

What parts of the purchase agreement matter to finance?

Pay close attention to payment timing, completion conditions and handover details. The lender needs a clear picture of what you’re buying and when settlement is expected. If the contract dates and conditions don’t align with your finance arrangements, you may be unsure whether lending will be ready when needed. Include the contract in the finance conversation from the outset.

Read the agreement with your solicitor, who can advise you on its legal meaning. For the loan discussion, note the key dates and conditions and share the relevant details with your adviser. If a completion date changes or a condition affects settlement, raise it promptly so the finance plan can be considered against the updated position. This doesn’t replace legal advice. It helps keep the lending discussion informed.

What can affect the lender’s view of the property?

The type of home, its completion stage and the transaction details may shape how a lender assesses the property as security. A valuation may help the lender form a view of the property’s value, but whether one is needed and how it’s used depends on the application. Not every turnkey purchase follows the same process.

A completed home and one still awaiting completion provide different information for a lender to consider. The lender may assess the property alongside the purchase terms and your finances, rather than relying on the home’s description alone to decide how the loan should work. That’s one reason to look beyond the name of a proposed structure.

For new build turnkey loans nz, consider how the proposed lending fits your circumstances, the property and the contract’s settlement arrangements. Bring those details together before comparing options, and make sure any changes to the agreement are reflected in the discussion. If you’d value support weighing lender fit against your purchase details, Mortgage Suite’s home loan guidance can help you work through the questions.

Turnkey loan options compared with off-the-plans and construction finance

The useful comparison isn’t about choosing a universally “best” loan type. It’s about when the property is expected to be ready, when funds may be needed and what you’ll need to manage under the contract. For new build turnkey loans nz, the contract and lender assessment determine which finance structure applies. Use the table as a guide, not a rulebook.

Option Property and timing Payment structure and buyer focus
Turnkey purchase The home may be complete or nearing handover, depending on the agreement. Finance is arranged around the purchase and settlement terms. Check what must be completed before settlement and when payments fall due.
Off-the-plans purchase You agree to buy before the home is complete. The contract sets out the expected completion and settlement arrangements. Understand what conditions must be met before settlement and how the timing fits your finance plans.
Construction finance The project is funded while building work is under way. Funds may be released in agreed stages, depending on the finance arrangement and project. Be clear about the stage requirements and your responsibilities.

These are broad distinctions, not guarantees about how a particular lender will treat a purchase. The contract wording, project stage and lender’s assessment all matter. Compare practical details: when will the home be ready, when does the agreement require funds, and does the proposed loan structure match those points?

Turnkey purchase versus buying off the plans

A turnkey purchase may involve a home that’s ready or close to handover, while an off-the-plans purchase is agreed before completion. The contract, not the label, sets out the actual position. Before relying on a finance plan, identify what must happen before settlement, including the completion conditions and handover requirements.

Build timing can change, so don’t assume the expected completion date is certain. If timing shifts, the finance arrangements may need to be considered against the revised position. Your solicitor can explain the legal effect of the contract terms, while your mortgage adviser can help relate the dates and conditions to the lending discussion.

Turnkey purchase versus construction finance

A purchase loan is arranged around buying the property, while construction finance may release funds as agreed building stages are reached. The staged drawdown process depends on the finance arrangement and project, so don’t assume every build follows the same steps. Development funding is a separate consideration from a buyer’s home loan for a completed or near-complete turnkey property.

Use the comparison to clarify responsibilities and timing, rather than assuming one route suits everyone. If you want support comparing lender fit against your contract and circumstances, Mortgage Suite’s home loan guidance can help you work through the options.
New Build Turnkey Loans NZ: How to Compare Your Options

How to prepare for a turnkey home loan conversation

Preparation can make a complex borrowing conversation feel more manageable. Bring together the purchase agreement, a clear picture of your finances and the key dates, then compare proposed loan structures against the contract. This gives your adviser a practical starting point for discussing lender fit and timing.

Work through these steps in order:

  1. Gather the agreement. Have the signed or draft contract available, including payment dates, completion conditions and handover details.
  2. Outline your finances. Be ready to discuss income sources, regular commitments, your deposit position and any other borrowing. Don’t assume one deposit amount will suit every lender.
  3. Identify the timing. Note the expected settlement date and any dates or conditions that could affect when funds are needed.
  4. Compare the proposed structures. Consider how repayments, flexibility and lender conditions fit your plans, as well as the interest rate.

Information to have ready before discussing finance

Useful information includes your agreement, available financial records, key contract dates and a summary of your income and commitments. Think about your broader borrowing goals too, such as the repayment approach you’re comfortable with and how much flexibility matters to you. These details help shape a clearer discussion, but no single document or deposit position guarantees approval.

If parts of your income or commitments vary, explain that clearly rather than trying to reduce them to a simple estimate. The aim is to give your adviser an accurate picture of your circumstances and the purchase, so possible loan structures can be considered in context.

Questions that help compare lender options

Test whether each option fits the transaction, not just whether its headline rate looks appealing. Ask how the proposed loan aligns with the contract’s payment and settlement timing, what repayment choices are available, and which conditions or flexibility features may matter to you. You can also ask how the structure would work if the expected completion timing changed.

To explore repayment scenarios, Mortgage Suite’s mortgage calculator can give you a starting point. Treat any result as an estimate, not a lender offer, and discuss the assumptions behind it with your adviser. Mortgage School resources also offer plain-English explanations of mortgage topics to help you prepare questions.

Comparing new build turnkey loans nz is easier when each option is measured against the same information: your finances, goals and contract. If you’d like help working through those details and comparing lender fit, use the calculator as a first step in exploring repayment scenarios.

How Mortgage Suite can help you compare new build turnkey loans

Choosing finance for a new build can feel like a lot to manage, especially when the lender’s process needs to fit the purchase agreement. Mortgage Suite takes a personal approach: we learn about your goals and circumstances, then compare how different lenders may fit the property and contract. We’ll help you weigh up your options without promising that one lender or loan will suit everyone.

Krish Krishna founded Mortgage Suite in 2000 after 18 years in banking. Since then, he has arranged over a billion NZD across residential, commercial and business lending. That experience informs how we consider the full picture, including the timing and terms of your new-build agreement, rather than judging an option by its headline rate alone.

What working with a mortgage adviser can add

Bringing your finances and contract details together can make it easier to compare options across a wide range of bank and private lenders. Mortgage Suite can help you consider lender fit, discuss possible structures and negotiate on your behalf. The aim is to support an informed decision. No adviser can guarantee a particular rate, approval or outcome.

Client experiences can also give you a sense of the support people have valued. Read Mortgage Suite client reviews to learn about their experiences with guidance and lending negotiations. Every borrower’s circumstances are different, so those stories aren’t a promise that your application will follow the same path.

A calm next step for your new-build plans

You don’t need to have every lending question answered before starting a conversation. Bring the agreement, note the key contract dates, and share your borrowing goals and any concerns about how the finance might fit. Those details can help frame a useful discussion about which options may be worth considering and what questions remain.

If a mainstream bank has already said no, that isn’t automatically the end of your borrowing options. A different lender may assess your circumstances differently, though approval is never assured. The next step is to understand what the decision means for your plans and whether another lender or structure may be a better fit.

If you’re considering new build turnkey loans nz, a first discussion can help clarify how your agreement and finances relate to possible lending options. Bring your questions and contract timing, and talk with Mortgage Suite about your home-loan options.

Take the next step with confidence

Buying a new home is a big personal milestone, and it’s normal to want a clearer sense of what comes next. You don’t need to have every answer lined up. A thoughtful conversation can help you feel prepared to move forward at a pace that suits you.

If you’re exploring new build turnkey loans nz, Mortgage Suite can help you talk through your plans and consider your options. Start a conversation with Mortgage Suite when you’re ready.

Take it one step at a time. The right support can help you approach your new-build plans with greater confidence.

Frequently Asked Questions

Can I apply for a turnkey home loan before signing the purchase agreement?

Yes, you can start discussing finance before you sign. This gives you time to understand what lenders may need and whether your plans appear workable, without treating an early indication as final approval. If the agreement is still being negotiated, tell your adviser what may change. A different purchase price, ownership arrangement or contract condition could affect the application, so avoid making firm commitments based only on an initial conversation.

What happens if the turnkey property’s completion date changes?

A changed completion date may affect the timing of your finance, so get the revised date in writing and tell your adviser promptly. Ask whether any lending approval conditions or time limits need attention, and keep track of updated notices from the seller or developer. If the revised date creates a concern under your agreement, speak with your solicitor about your position and the steps available to you.

Can a turnkey home loan include the land as well as the house?

It can, if the purchase is structured to include both, but the lender needs to understand exactly what you’re buying. Check whether the agreement describes the land and home together or sets them out as separate parts of the transaction. That distinction can affect how the lender assesses the request and what information it needs. Make sure your borrowing discussion reflects the full purchase arrangement, not just the house component.

Can I use a turnkey home as an investment property?

Yes, a turnkey home may be purchased as a residential investment property, subject to the lender’s assessment. Be clear about your intended use from the outset, especially if you plan to rent the home rather than live in it. You can discuss how you expect to manage the property and any rental income as part of your overall finances. The lender will assess your circumstances and the proposed purchase before deciding what it can offer.

What if a bank declines my turnkey home loan application?

A decline doesn’t automatically rule out every option. Start by finding out the main reason for the decision, such as a concern about your application details or the property. Then you and your adviser can consider whether further information may help, or whether another lender could assess the situation differently. Mortgage Suite works across bank and private lenders, including 2nd Tier Loans for borrowers who don’t fit mainstream bank criteria. Approval is never guaranteed.

Does a turnkey home loan require a property valuation?

Not in every case. The lender decides whether it needs a valuation and what information will help it assess the property. If one is requested, ask what it needs to cover and whether it must be completed before a particular stage of the application. This can help you understand the lender’s next steps and avoid assuming that an assessment used for another property or application will be suitable.

Can I change lenders after signing a turnkey purchase agreement?

You can explore another lender after signing, but a new application may involve fresh checks and could take time to progress. Before switching, compare the new lender’s requirements with your existing approval and consider whether the change affects your ability to meet the agreement’s obligations. Your solicitor can advise on the contract, while a mortgage adviser can help you weigh up the lending options. Don’t assume a new application will be approved.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage for a Tiny Home NZ: Costs, Rates and Land Rules

Owning land isn’t always essential to borrowing, but a movable tiny home can be harder to use as mortgage security. A mortgage for a tiny home in NZ may depend on whether you own land, have other assets to support the loan and can comfortably manage the repayments.

It’s understandable to feel unsure when a tiny home doesn’t fit the usual home-loan picture. The home’s design, where it will sit and what security you can offer all affect which finance options may suit.

This guide explains how land ownership and other assets may affect an application, how to set a repayment budget and where specialist finance may fit. You’ll get a clearer picture of what lenders assess and the practical details to prepare before deciding what to do next.

Key Takeaways

  • Land ownership isn’t the only factor in borrowing; the lender will also consider what security you can offer and how the tiny home is set up.
  • Build a repayment budget around your regular income and expenses, and test how it feels alongside your usual spending before committing.
  • Compare interest rates alongside repayment terms and loan structure, as specialist finance can work differently from a standard home loan.
  • Clarify who owns the land and how the tiny home will be placed there, as these details can affect the finance assessment.
  • If mainstream lending doesn’t suit your situation, specialist finance may be another avenue to explore.

Do I need to own land or other assets?

Owning the section beneath a tiny home can strengthen a borrowing application, but it isn’t the only possible security. A lender may also consider other property you own and how the home is attached to its site.

Using land or property as security

Security is property a lender can rely on if a borrower can’t repay a loan. For a tiny-home application, land or another property may provide stronger security than the home alone, particularly if the home can be moved.

Consider a house-and-land valuation of NZ$800,000. In this example, banks might lend 80% or even 90% of the combined valuation, depending on the application. That example concerns land and a house together, not a promise that a tiny home will be assessed the same way.

If you own a section, the lender can assess its value alongside the proposed home and your ability to make repayments. If you don’t own land, another property may be relevant security. The key question is what property supports the loan, not whether the tiny home looks like a conventional house.

Before applying, list what you own and how it relates to your tiny-home plans. For example, distinguish land you own from a site where you have permission to place the home. This helps show what security is available and clarifies the arrangement behind the application.

Assessing fixed and movable tiny homes

A tiny home fixed to land may be assessed together with the land, while a movable home may be considered separately. This matters because a home that can be moved may be harder for a lender to rely on as security.

A tiny home on wheels doesn’t automatically qualify for a standard home loan as a house secured by land. A lender may instead assess land or another property offered as security, alongside your ability to make repayments.

For a fixed home, explain how it is attached to the site and what land supports the application. For a movable home, describe where it will be kept and whether you own that land. These details help clarify what the lender could assess if you can’t repay.

Consider the whole arrangement, not just the build. A home on wheels placed on a section you own presents a different security picture from one parked on land you don’t own. If a bank mortgage isn’t suited to the movable home itself, other property may still be relevant to the lending discussion.

Land ownership can help, but it isn’t the only factor. A lender weighs the security available, whether the tiny home is fixed or movable, and whether the repayments fit your finances.

Budgeting for loan repayments

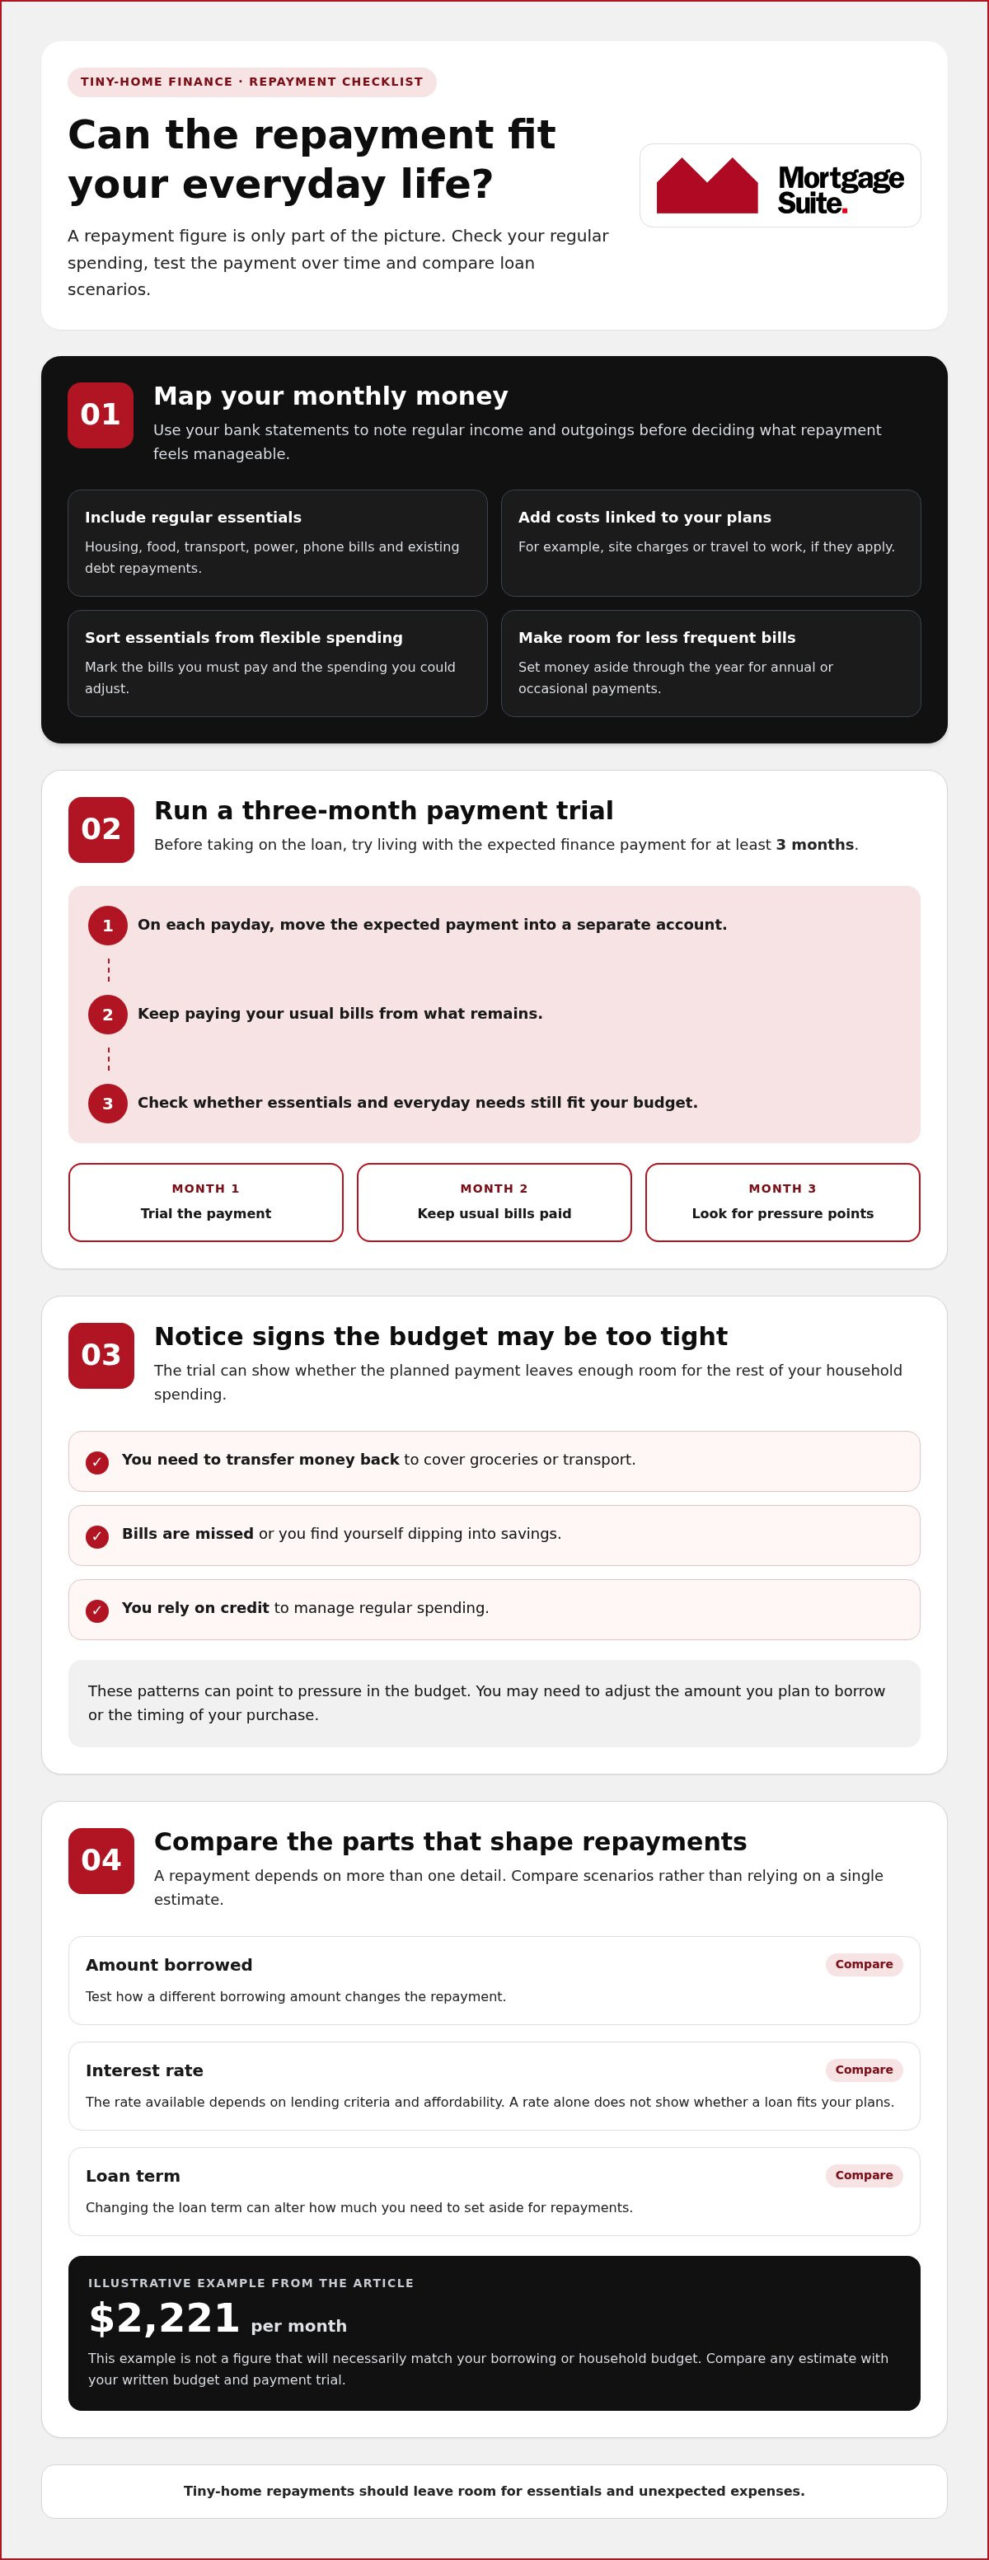
A repayment figure tells only part of the story. Your budget also needs to cover regular household spending, tiny-home upkeep and the income left after bills. Mapping out your monthly finances helps you judge whether a loan fits daily life, not just a lender’s assessment.

There’s no single repayment amount that suits every tiny-home loan. Repayments depend on the amount borrowed, the interest rate and the loan term. Changing any of these can alter what you need to set aside, so compare scenarios rather than relying on one estimate.

Start with your bank statements and record your regular income and outgoings. Include housing, food, transport, power, phone bills and existing debt repayments. Then add expenses linked to your plans, such as site charges or travel to work, if they apply.

  • Separate essentials from flexible spending: Identify bills you must pay and spending you could adjust.
  • Include irregular bills: Set money aside throughout the year for annual or occasional payments.
  • Allow for changes: Consider how your budget would cope if household income fell or another bill increased.
  • Compare scenarios: Test how a different borrowing amount or loan term changes the repayment.

Next, try living with the expected finance payment for at least 3 months before taking on the loan. Move that amount into a separate account on each payday, as though repayments have already started. Keep paying your usual bills from what remains. This practical test shows whether the planned payment leaves room for essentials and everyday needs.

If you need to transfer money back to cover groceries or transport, your repayment plan may be too tight. If you test a budget over time, look for missed bills, dipping into savings or relying on credit. These patterns can reveal pressure points. You may need to adjust the amount you plan to borrow or the timing of your purchase.

A repayment calculator can help you compare scenarios using different borrowing amounts, rates and terms. The mortgage calculator can help show how changing the amount borrowed affects repayments. Compare any result with your written budget and the three-month payment trial before deciding what feels manageable for your household.

An example tiny home finance repayment in New Zealand is $2,221 per month. Treat it as an illustration, not a figure that will necessarily match your borrowing or household budget. Your own estimate should reflect the amount you need, the available loan terms and your regular costs. Check that the repayment leaves enough room for essentials and unexpected expenses, and revisit your budget if your income or spending changes.

What are the interest rates?

Specialist tiny-home finance in New Zealand may have interest rates from 9.99% p.a. Lending criteria and affordability affect the rate available, so treat that figure as a starting point, not a universal offer. A rate alone doesn’t show whether a loan fits your plans. The repayment amount, loan term and conditions also shape the overall commitment.

Compare the loan structure as well as the headline rate. A fixed interest rate stays unchanged for an agreed period, making repayments more predictable during that time. Other structures work differently. Ask how the rate applies, when it can change and how the repayment schedule would affect your budget.

For a fair comparison, line up offers using the same borrowing amount and repayment period. Then check:

  • Interest rate: Note whether the quoted rate is fixed or can change.
  • Repayment schedule: Understand how often payments are due and how long they continue.
  • Loan conditions: Read the terms alongside the rate, including any requirements attached to the finance.
  • Affordability: Compare the proposed payment with your household budget, not just another lender’s rate.

A lower rate can look appealing, but it may not suit you if the loan structure doesn’t match your plans. For example, consider whether repayments remain manageable alongside your regular bills and tiny-home expenses. Comparing the rate, term and repayments together gives you a more useful basis for deciding.

Approval timing depends on the lender receiving the information needed to assess the application. Tiny-home finance approvals in New Zealand are often available within 24 hours after the lender has all the information. That timeframe begins once the application details are complete; preparing clear information about your income, existing commitments, the home and its intended location helps the assessment proceed.

Keep your application details consistent. If your purchase or build plans change, update the information provided, as the lender assesses the application presented. A prompt decision is useful, but speed shouldn’t replace a careful review of repayments and loan terms.

Before accepting an offer, write down the rate, how long it applies, the repayment schedule and the conditions. Compare these details with your budget and the home’s intended use. This helps you assess the whole borrowing arrangement rather than choosing on the interest rate alone.

Mortgage for a Tiny Home NZ: Costs, Rates and Land Rules

Land ownership requirements

Owning the land isn’t automatically a requirement for every tiny-home finance application. In New Zealand, the land arrangement still matters because it shows where the home will sit and what property may support the borrowing.

Separate three parts of your plan: owning a section, having an arrangement to place a home there, and offering land as loan security. These are distinct. You might own the tiny home but not the site, or own both the home and section. Each arrangement gives a lender different information to assess.

If you own the land, gather details showing who owns it and how the tiny home will be placed. If someone else owns the site, explain the arrangement and how long you expect to use it. A lender needs to understand whether the home’s location is stable and how the land relates to the borrowing. Details about site access, services and planned use can also help explain the setup.

Prepare these details before discussing finance:

  • Land ownership: Record whether the section is yours, jointly owned or owned by someone else.
  • Placement arrangement: Explain where the tiny home will sit and what agreement supports that plan.
  • Home setup: Describe whether it will be fixed in place or remain movable.
  • Security: Identify whether the land or another property is being offered to support the loan.

For example, you might own a section and plan to place a movable tiny home there. That doesn’t make the home and land the same asset. Explain each separately, including who owns them and how they’re connected. If the home will sit on a family member’s land, describe that arrangement clearly rather than presenting the site as your own property.

Land ownership can affect what a lender considers as security. A section you own may be assessed differently from land you can use but don’t own. The lender considers the available property, the tiny home’s placement and your ability to repay. Clear information helps distinguish the home’s location from property that can support the borrowing.

Before committing, compare the land arrangement with the loan structure you’re considering. If you’re buying land and a tiny home together, explain both parts of the purchase. If you already own a section, outline how the proposed home will fit the site. Clear details about ownership, placement and security help frame the application around your actual plans.

Specialist tiny home finance

Specialist finance can be another option when a tiny home doesn’t fit a standard mortgage. The loan type, security and repayment plan still need to suit your circumstances.

Lender eligibility criteria

Eligibility criteria are the lender’s requirements for deciding whether an application and its security fit a loan. Specialist lenders in New Zealand may consider tiny-home finance, but their criteria vary. There isn’t one lender list or rule that applies to every borrower.

Lenders assess factors such as income, existing commitments, repayment capacity, the home’s value and whether it can be moved. These factors shape possible loan terms, but they don’t determine an automatic approval amount or term.

A strong application explains the full arrangement: who owns the home, where it will sit, what security is available and how repayments fit your budget. If a mainstream bank declines, that doesn’t settle whether another lender’s criteria may suit your circumstances.

Mortgage eligibility for tiny homes

A mortgage may be possible, but the lender’s assessment depends on the tiny home, the land arrangement, available security and your ability to repay. A home on wheels may be treated differently from one fixed to land, so describe its setup clearly.

Planning and building requirements depend on the site and proposed home. Before committing, identify the relevant local council and ask how its planning rules, building consent process and site requirements apply to your proposal. Don’t assume a tiny home has the same requirements on every section.

There isn’t one total cost for every tiny-home project. Your overall budget depends on the home, land, site preparation and connections such as power or water. List each part separately, then compare the project budget with the borrowing you can manage.

Lenders may also consider whether the home can be valued as security and how readily it could be resold. A movable home’s location, condition and saleability can affect its usefulness as security. Include clear details about the home and site in your finance information.

Application steps and documents

An application brings together your financial position and tiny-home plans, helping a lender assess your repayment ability and available security. Prepare proof of income, a record of regular commitments, details of the home and a clear account of where it will be placed.

Include purchase or build information, the proposed site, land ownership details and any documents describing the placement arrangement. If you own other property, note whether it may support the borrowing. Keep the figures and project details consistent across your budget and application.

Before applying, organise these records and identify any missing project details. Then compare the lender’s proposed amount, term, repayments and conditions against your budget. For help exploring a finance path that fits your circumstances, discuss tiny-home finance options.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite can help you explore home-loan options, including Home Loans to First Home Buyers, when a tiny-home purchase forms part of your first-home plans. If a mainstream bank’s criteria don’t fit your circumstances, its 2nd Tier Loans may offer another lending pathway to discuss.

Bring together your income details, regular commitments, tiny-home plans and information about the land or other security. Mortgage Suite can help you consider how these factors fit together and discuss a suitable next step, without treating one lender’s decision as the final word.

If you’re a first-home buyer considering a tiny home, contact Mortgage Suite to discuss your borrowing situation and possible options.

Take the next step with a clear borrowing plan

Your tiny-home plans don’t have to follow a standard property path. Shape the finance conversation around your goals, how you’ll use the home and what you can comfortably repay. This gives you a clearer basis for deciding whether a mortgage for a tiny home in NZ suits your wider plans.

Mortgage Suite can help you talk through your circumstances and consider which lending pathway may fit. If a mainstream bank’s criteria don’t suit your situation, that doesn’t necessarily end the conversation. The next step is to look at your plans and finances together.

Before getting in touch, bring together an outline of your plans, income and regular commitments. You don’t need every detail sorted to start a useful conversation. A clear starting point can help you work out what to explore next.

Contact Mortgage Suite about your options and take a confident next step towards your tiny-home plans.

Frequently Asked Questions

How much can I get?

There’s no single borrowing amount for a mortgage for a tiny home in NZ. The amount a lender may offer depends on your income, existing commitments, repayment capacity and available security. Separate your borrowing goal from the full project budget, then work out how you’d fund any gap.

What financing options are out there?

For a mortgage for a tiny home in NZ, options may include a home loan supported by land or other property, or specialist finance for tiny homes. The suitable path depends on whether the home is fixed or movable, what security you can offer and how you plan to repay. Buying a tiny home and land together creates a different borrowing structure from purchasing a wheeled home without owning the site.

Can first-home support help fund a tiny home in NZ?

First-home support has its own eligibility rules, and whether it can contribute depends on the buyer and property arrangement. A wheeled tiny home, a home fixed to land and a land-and-home purchase may be treated differently. Keep your borrowing plan workable without relying on support until you know it applies to your purchase. Include any eligible assistance separately in your deposit plan, not as guaranteed funding.

What insurance, valuation, and resale risks affect tiny-home finance in NZ?

A movable tiny home can be harder for a lender to rely on as security and may be assessed separately from the land. The lender may assess the land or another property as security, alongside your ability to repay.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

First Home Loan eligibility for new residents in New Zealand

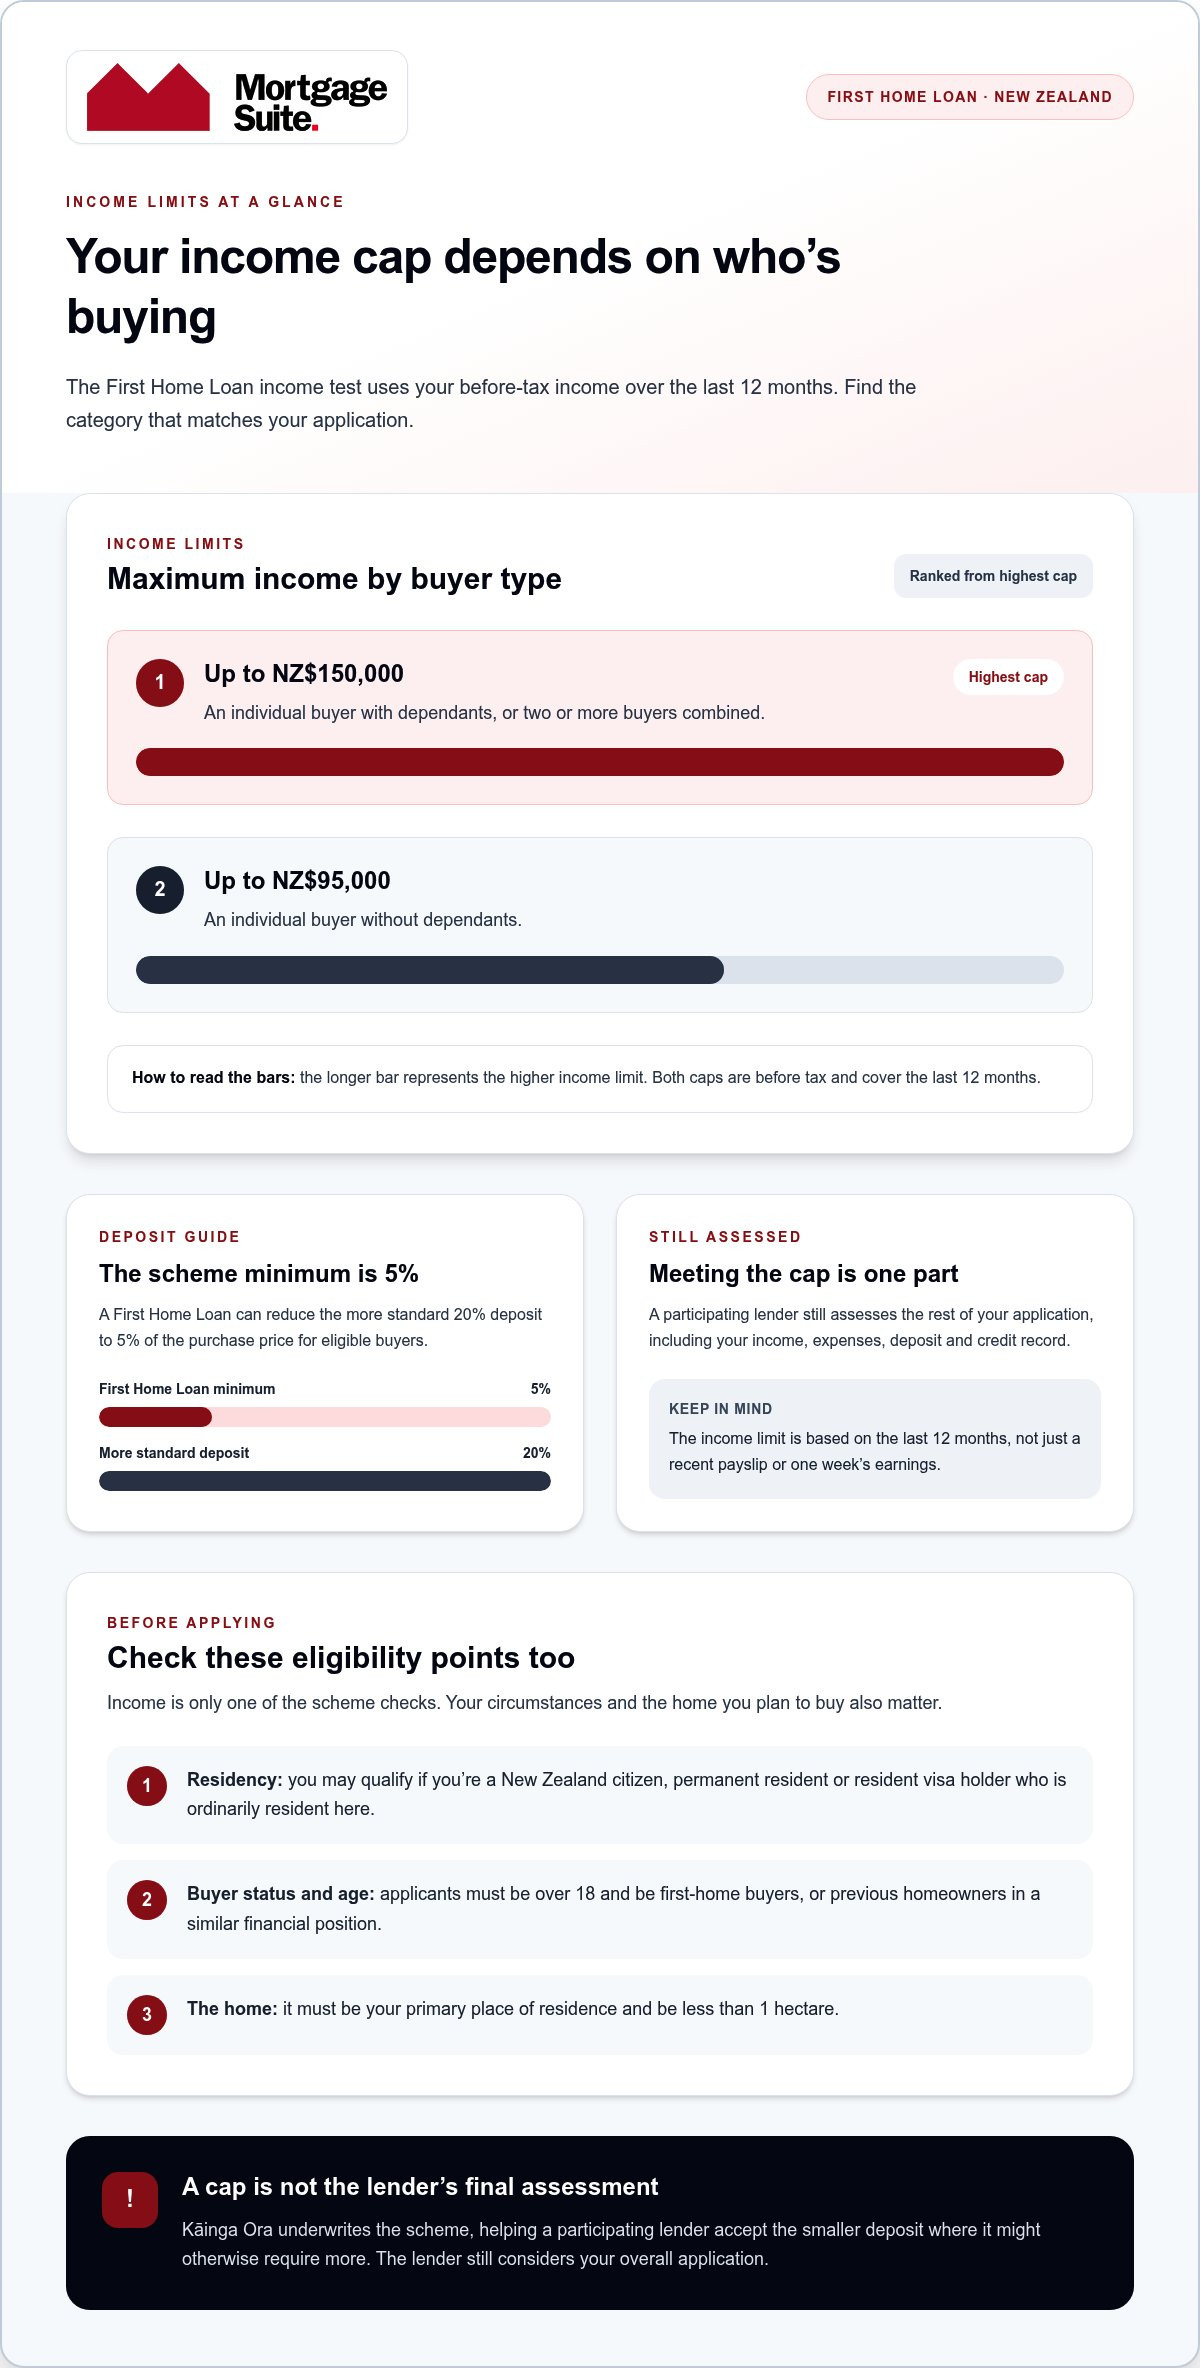
A first home loan for new residents in NZ may be possible if you’re a New Zealand citizen, permanent resident or resident visa holder who is ordinarily resident here, and you meet the scheme’s other criteria. The minimum deposit is 5% of the purchase price. Income limits also apply: up to NZ$95,000 before tax over the last 12 months for an individual buyer without dependants, or NZ$150,000 for an individual with dependants or for two or more buyers combined.

It’s understandable to feel unsure about applying for a first home loan for new residents in NZ. You may have a limited New Zealand credit history, and working out how your visa, income and overseas credit record fit together can feel like a lot to manage.

This guide explains who may qualify, what deposit and income rules apply, and how lenders assess applications. You’ll also learn what evidence to prepare, including how to present your home-country credit history, so you can understand your options and decide on a next step.

Key Takeaways

  • Check that your visa and ordinary residence status fit the scheme’s eligibility rules before you begin an application.
  • You’ll need to buy a home to live in, and you must be a first-home buyer or meet the criteria for a previous homeowner in a similar financial position.
  • If you’re new to New Zealand, evidence of your credit history from your home country can help lenders assess your application.
  • Prepare clear records of your income, deposit and financial commitments so a lender can consider your overall ability to manage repayments.
  • Mortgage Suite offers home loans to first-home buyers and can help you consider lending options that fit your circumstances.

First Home Loan deposit requirements

A First Home Loan can let eligible buyers purchase a home with a minimum deposit of 5% of its purchase price. Kāinga Ora underwrites the scheme, helping a participating lender accept that deposit where it might otherwise require more. The scheme can reduce the more standard 20% deposit to 5%, but the lender still assesses the rest of your application.

Work out the deposit by multiplying the agreed purchase price by 0.05. For example, if you’re comparing homes at different prices, calculate 5% of each price separately. This gives you a clear deposit target for each option. A larger deposit may give you more flexibility, but the scheme’s minimum is 5%.

A deposit can come from your savings or a family gift. If someone offers to help, clarify whether the money is a gift or a loan. A loan must be repaid, creating a financial commitment the lender will consider. Keep a record of who provided any gift and whether repayment is expected.

Tell the lender about gifted funds early in the application. They may ask for documents explaining where the deposit came from and whether any part must be repaid. Keep the amount and terms consistent across your application and supporting records. If several family members contribute, record each contribution separately so the source of the full deposit is clear.

The home must be less than 1 hectare and must be your primary place of residence. A First Home Loan is for a home you’ll live in, not a property you plan to rent out. Before making an offer, check that the property fits these scheme requirements and that your deposit plan covers the purchase price.

Permanent residents can generally buy residential property in New Zealand if they meet the relevant criteria. However, visa status and First Home Loan eligibility are separate checks. Depending on their circumstances and the purchase, some buyers may also need consent from Land Information New Zealand.

Foreign-buyer rules generally limit residential property purchases to citizens and residents who meet certain criteria. Some buyers need consent from Land Information New Zealand before purchasing. These rules are separate from a lender’s assessment, so consider both your eligibility to buy the property and the lender’s requirements before proceeding.

To prepare, calculate the 5% deposit, identify whether any family contribution is a gift or repayable loan, and check that the home meets the scheme’s property rules. That gives you a practical starting point for discussing the deposit with a participating lender.

Applying for a First Home Loan

Start by organising your application evidence, then work through eligibility, borrowing capacity and the property search. A First Home Loan applicant must be over 18, buy a home to live in as their primary residence, and qualify as a first-home buyer or a previous homeowner in a similar financial position.

Application documents

Prepare identity and visa records, proof of income, bank statements and evidence of savings. If your New Zealand credit history is limited, include evidence of your credit history from your home country. These documents help a lender understand your identity, income, money management and deposit funds.

Organise your records into clear groups before applying. An employee, for example, could gather recent payslips and employment details, while a self-employed applicant could prepare business income records. Include regular expenses and existing debts so the lender can assess your ability to manage repayments. Keep documents current, and check that names and dates match across your application.

  • Identity and visa documents
  • Income and employment records
  • Bank statements and savings evidence
  • Overseas credit history evidence, if you’re new to New Zealand
  • Details of debts and regular expenses

Steps to buying a first home

Use a step-by-step approach to keep your application and property search organised. First, check that you meet the First Home Loan criteria, including age, buyer status and owner-occupier requirements. Then organise your documents and set a budget that accounts for regular commitments as well as mortgage repayments.

Next, apply through a participating lender and provide the requested information. The lender assesses your income, expenses, deposit and credit record before deciding whether the application can proceed. Once you understand your borrowing position, look for a suitable home and review its condition and purchase details before making an offer.

After your offer is accepted, complete the lender’s remaining requirements and arrange the legal steps needed to transfer ownership. The purchase process can take as little as 3 to 4 weeks after finding a property, so keep documents accessible and respond promptly to requests. A property bid, once formally accepted, does not leave room for last-minute offers.

Keep your application details consistent throughout. If your employment, income or financial commitments change while you’re applying, update the lender before proceeding. If you previously owned a home, prepare information about your current financial position and how it compares with that of a first-home buyer. An organised file makes your circumstances easier to explain.

Income thresholds

First Home Loan income limits depend on how many people are buying and whether an individual buyer has dependants. The test uses before-tax income over the last 12 months, not just a recent payslip or one week’s earnings.

Use the category that matches your application:

  • An individual buyer without dependants can earn up to NZ$95,000 before tax over the last 12 months.
  • An individual buyer with one or more dependants can earn up to NZ$150,000 before tax over the last 12 months.
  • Two or more buyers can have combined before-tax income of up to NZ$150,000 over the last 12 months.

These are maximum income limits for scheme eligibility, not a guide to how much a lender will approve. The lender also considers your income alongside expenses, debts and the repayments you could manage. Meeting the income limit is one part of qualifying, not a calculation of your borrowing amount.

For two buyers, add both applicants’ income across the same 12-month period. For example, two teachers with combined income of NZ$150,000 sit at the stated limit for two or more buyers. If their combined income exceeds that threshold, they don’t meet this income criterion, even if one applicant earns considerably less than the other.

An individual with dependants has a different limit from an individual without dependants. A single parent earning NZ$120,000 before tax over the last 12 months, with one child, is below the NZ$150,000 threshold for an individual buyer with dependants. The dependant category matters, so make sure your application records your household circumstances accurately.

Before applying, list the income you received during the full 12-month period. Include each buyer’s income when applying together, and keep the figures consistent with the records you provide. If your earnings changed during that period, such as after starting a new role, use the whole period rather than treating your current pay as the only relevant amount.

Self-employed applicants should organise records that show income across the same assessment period. For example, a landscaper with annual income of NZ$95,000 appears in a scheme case study, but that figure alone doesn’t establish every applicant’s eligibility. The applicable threshold still depends on whether the applicant is buying alone, has dependants, or is applying with another buyer.

Check your income category before planning around a First Home Loan. If you’re buying with someone else, compare your combined income with the shared limit. If you’re applying alone, identify whether the dependant threshold applies, then prepare clear evidence for the full 12-month assessment period.

First Home Loan eligibility for new residents in New Zealand

Lender credit assessment

A lender assesses whether repayments fit your finances by looking at your income, expenses, debts and credit record. If you’ve recently arrived, your overseas credit history can help fill gaps in your New Zealand record.

Lenders available to recent migrants

All major banks in New Zealand offer home loans, but not every lender offers the First Home Loan scheme. The scheme is available through participating lenders, which assess applications against their own lending criteria as well as the scheme’s eligibility rules.

Compare lenders by how they assess your income, overseas records and overall application, not just by interest rates. If a mainstream bank declines your application, that decision doesn’t mean you have no other lending options.

Income, credit and employment criteria

For scheme eligibility, income limits depend on your household category and before-tax income over the last 12 months. A lender also considers whether your income and regular commitments leave room for repayments. Employment evidence helps show how you earn, while bank statements can give context to spending and existing debts.

You may have little or no New Zealand credit history as a new resident. Bring evidence of your home-country credit history alongside local bank statements and income records. This gives a lender more information than a brief local record alone. Clearly disclose relevant details, including any credit commitments that continue overseas.

Credit assessment considers the full picture, not just one document. A lender may look at whether your income is regular, how much you owe and whether your spending leaves money available for mortgage payments. Be ready to explain changes in employment or income, and make sure your application matches your supporting records.

Before applying, organise a simple file containing:

  • Evidence of income and employment, such as payslips or business records.
  • New Zealand bank statements and details of current debts.
  • Credit history documents from your home country.
  • Information about any overseas financial commitments.

For example, if you’ve recently arrived and have a brief New Zealand credit file, overseas credit records, local account statements and clear employment evidence can provide a fuller picture. These documents help a lender understand how you manage credit and income across both countries.

Answer lender questions promptly and explain any differences between overseas and New Zealand records. If a mainstream lender declines your application, another lender’s assessment approach may better fit your circumstances. A clear application helps the lender assess the evidence you provide.

Which New Zealand residency visas qualify for a home loan?

Eligible applicant categories for a First Home Loan include New Zealand citizens, permanent residents and resident visa holders. A resident visa holder may qualify if they’re ordinarily resident in New Zealand. Visa status is only one part of the picture, so have evidence of your immigration status and where you live ready for the application.

Citizenship, permanent residence and a resident visa are distinct statuses. Check which applies to you, then use the same status in your application as shown on your official documents. If you hold a resident visa, be prepared to show that you ordinarily live in New Zealand. The scheme’s other requirements still apply, even if your visa category is eligible.

Buying residential property is separate from meeting home-loan criteria. In New Zealand, residential property purchases are generally limited to citizens and residents who meet certain criteria. Some buyers may also need consent from Land Information New Zealand. This purchase assessment is distinct from the lender’s assessment of your mortgage application.

Keep both processes in view as you plan. Your visa category can help establish whether you may apply for the loan scheme, while property-purchase rules determine whether you can buy the home. If consent is required in your circumstances, that is a separate step from providing visa evidence to a lender.

Organise your information in a clear order:

  • Identify whether you’re applying as a citizen, permanent resident or resident visa holder.
  • Gather documents showing your current immigration status.
  • If you hold a resident visa, prepare evidence that you’re ordinarily resident in New Zealand.
  • Consider the separate residential property purchase rules that apply to your situation.

For example, a resident visa holder who ordinarily lives in New Zealand may fit the scheme’s resident-visa category. That status alone doesn’t mean every loan requirement is met or resolve a separate purchase-consent question. Keep these distinctions clear as you prepare your application and plan a property purchase.

Use consistent details across your visa documents and loan application, including your name and current address. If you’ve recently changed address, make sure the evidence you provide reflects your present circumstances. Mortgage School’s mortgage application guidance can help you organise the wider application paperwork alongside your residency evidence.

In September 2025, the New Zealand Government announced its intention to change the Overseas Investment Act to allow holders of an Active Investor Plus Visa, Investor 1 Resident Visa or Investor 2 Resident Visa to buy or build a house valued at NZD $5 million or more. The planned New Zealand property-purchase changes for certain investor visa holders are expected to come into effect in early 2026.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite provides Home Loans to First Home Buyers, helping you consider lending options that fit your circumstances. If your visa status, overseas credit history or income makes the application feel complicated, a clear conversation about your goals and finances can help you understand the next steps.

Gather your visa evidence, income records, deposit details and credit history from your home country. This gives your lending discussion a practical starting point and helps identify which parts of your application may need more attention. A mainstream-bank decline doesn’t necessarily close off every option, though approval depends on meeting the relevant lender’s criteria.

If you’re ready to discuss your first-home plans, contact Mortgage Suite for free, no-obligation guidance on Home Loans to First Home Buyers.

Take your next step with a clear plan

A first home loan for new residents in NZ involves more than eligibility checks. It’s a commitment that should suit the life you’re building here, including your work plans, household needs and comfort with regular repayments. Before moving ahead, write down what matters most in a home and what questions you still need answered. This gives you a practical starting point for a focused lending conversation.

Mortgage Suite offers Home Loans to First Home Buyers and can help you discuss your application and next steps. You don’t need every detail sorted before starting a conversation. Share your goals and circumstances, then work through your options with a clear view of what comes next.

Contact Mortgage Suite about your application and take the next step towards making New Zealand home.

Frequently Asked Questions

Can new residents in New Zealand buy a first home and get a mortgage?

Yes, a new resident may be able to buy a first home and apply for a mortgage in New Zealand. Treat permission to purchase and mortgage approval as separate parts of your plan. Before committing to a property, understand which checks apply to your circumstances and allow time to address each one. Progress with a lender does not, by itself, mean you have permission to complete the purchase.

What deposit do first-home buyers need for a mortgage in NZ?

An eligible First Home Loan has a minimum deposit of 5% of the purchase price. Work out the amount using the price in your offer, then keep a clear record of where the deposit funds came from. A family contribution should be clearly identified as a gift or a loan, since a repayable amount is a financial commitment. The lender assesses the deposit as part of your full application.

What are current New Zealand mortgage rates and first-home loan options?

There isn’t one mortgage rate for every New Zealand borrower. Rates and loan structures vary, so compare written offers using the same repayment frequency and fixed-rate period. Consider how each option fits your plans if your income or household needs change. A lower headline rate alone may not show whether the loan structure and flexibility suit your longer-term goals.

What extra costs and legal fees should first-home buyers budget for in NZ?

Budget for the First Home Loan’s 1.2% Lender’s Mortgage Insurance premium, which can be paid upfront or added to the loan, as well as council rates and home insurance. The material provides no basis for estimating legal fees.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loan Pre-approval in NZ: What to Expect in 2026

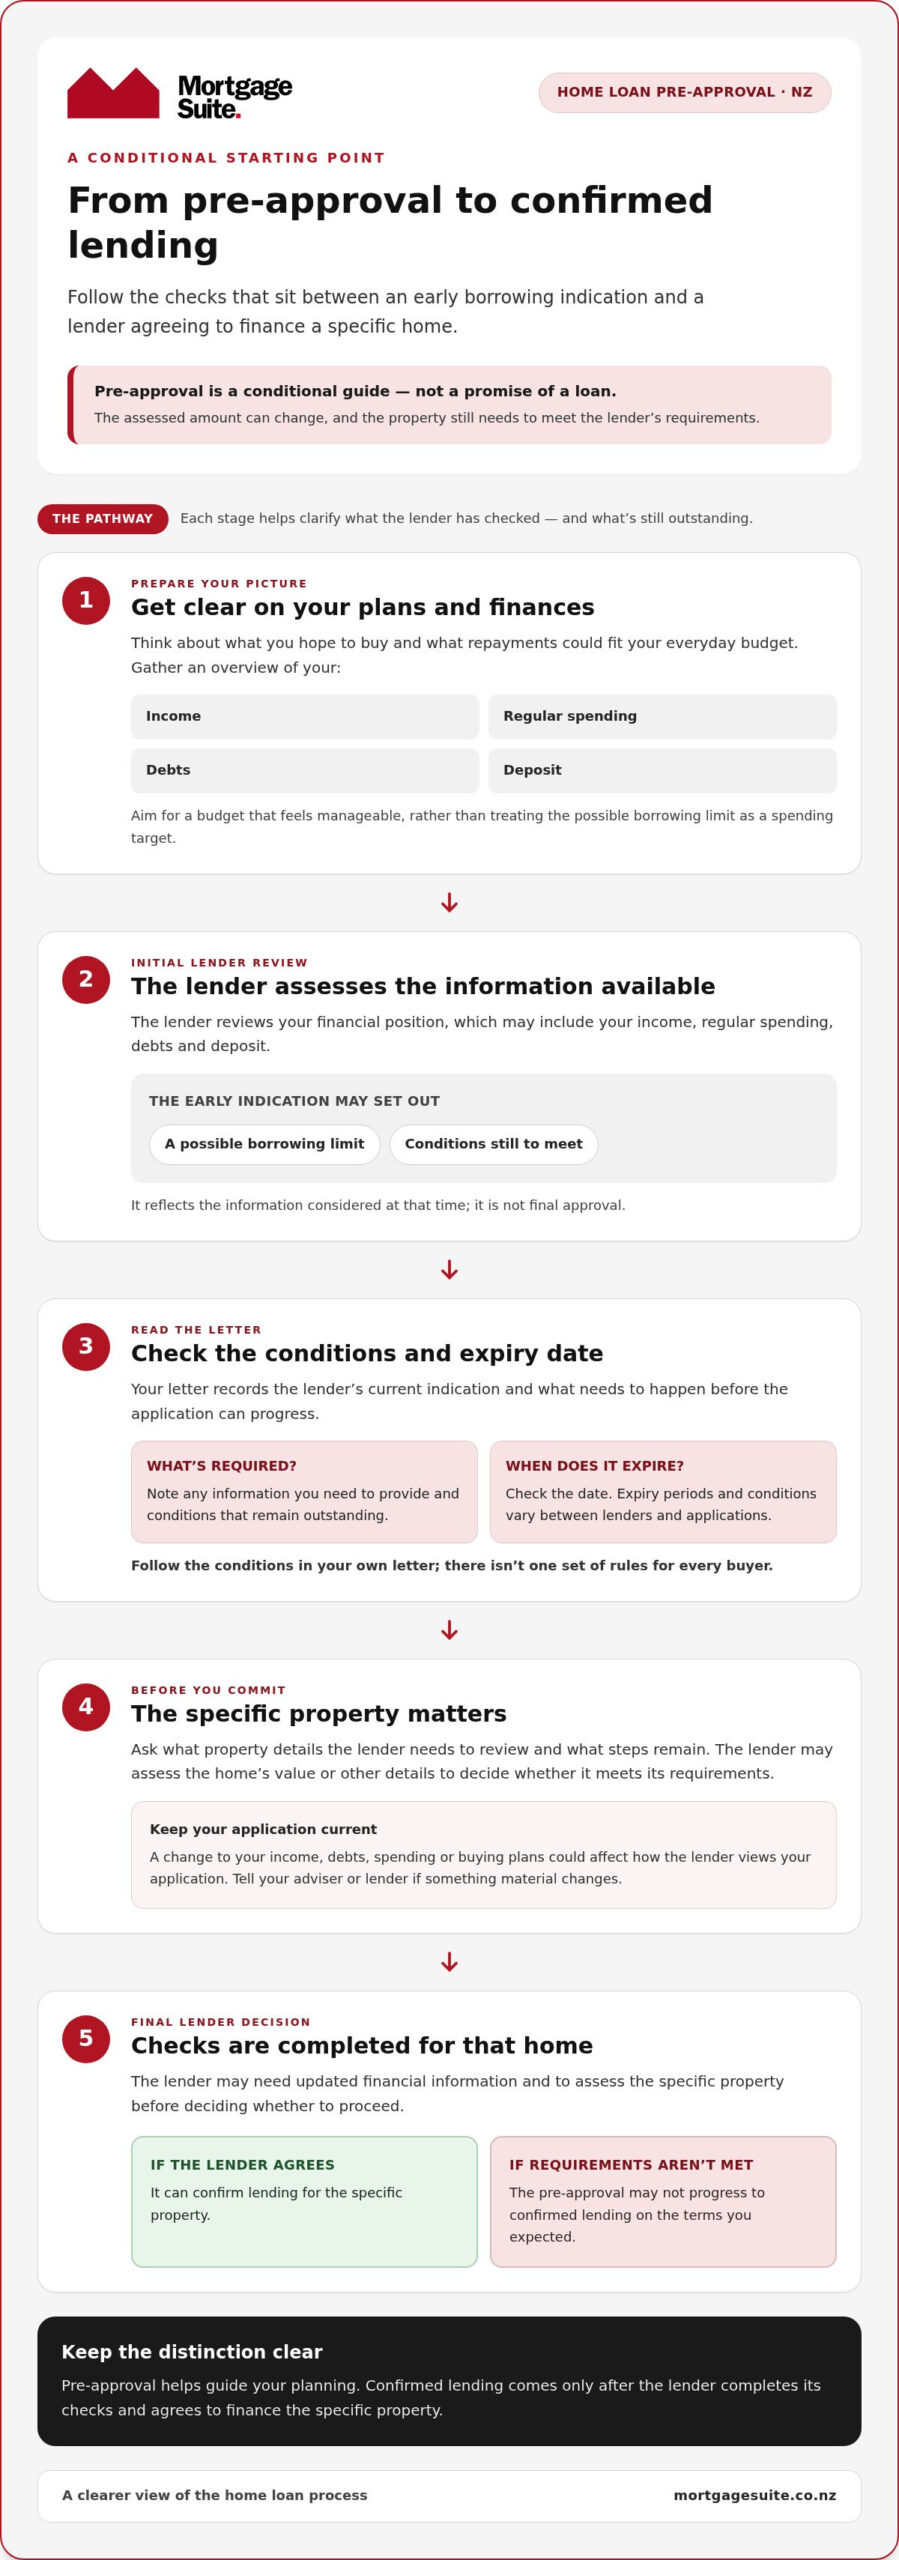
What if the amount on your pre-approval isn’t the amount a lender will ultimately offer for the home you choose? It’s understandable to want a clear borrowing figure before you start house hunting. If you’re looking into home loan pre-approval NZ, remember that pre-approval is a conditional guide, not a guarantee of a loan.

This guide explains what pre-approval can tell you, what it can’t confirm and how to prepare your application. You’ll learn what financial information to gather, how changes in your circumstances or the property could affect the outcome, and what to consider before making an offer while lending is still conditional.

We’ll also cover the steps towards confirmed lending, including the lender’s assessment of the specific property. A Mortgage Suite adviser can help you understand the process, talk through your goals and circumstances, and negotiate with suitable lenders. With clear information and a steady plan, you can take the next step with more confidence, without mistaking pre-approval for final approval.

Key Takeaways

  • Home loan pre-approval NZ can help guide your budget, but the lender’s conditions still matter when you choose a property.
  • Check the expiry date and conditions in your pre-approval so you know what needs to happen before the application can progress.
  • Prepare by setting out your plans and gathering information about your income, regular spending, debts and deposit.
  • Before making an offer, find out what property details the lender needs to review and what steps remain before a final decision.
  • Mortgage Suite can explain the process, present your circumstances to suitable lenders and negotiate on your behalf.

What does home loan pre-approval in NZ actually mean?

Planning to buy a home can feel exciting one moment and uncertain the next. You may be wondering what a lender could let you borrow, and whether that figure will hold once you find a property. Home loan pre-approval NZ is a conditional indication from a lender, based on the information available about your finances at the time. It can help you plan, but it isn’t final approval or a promise that the lender will fund any home you choose.

In its initial review, a lender considers your financial position, which may include your income, regular spending, debts and deposit. The outcome gives you an indication of a possible borrowing limit and any conditions still to be met. Those conditions depend on the lender and your application. The property may also need to meet the lender’s requirements before it agrees to the loan. That means the pre-approval amount could change, or the lending may not proceed for a particular home.

Think of pre-approval as an early checkpoint. The lender has considered your circumstances, but may not have completed every check needed to approve a loan for a specific property. A general overview of how lenders assess a mortgage loan can explain the broader process. Your own lender’s conditions are the ones to follow.

What does a pre-approval letter tell you?

The letter records the lender’s current indication, any borrowing limit it has assessed and the conditions that apply. Read it closely and note what the lender has considered and what remains outstanding. Treat the figure as a ceiling for planning, not a spending target. Work out a budget that leaves room for everyday expenses and feels manageable, rather than assuming you should borrow the maximum amount.

Why arrange pre-approval before house hunting?

An early indication can help you focus your search on homes that are more likely to fit your borrowing range. It also gives you time to understand the lender’s conditions before a suitable property comes up. That preparation can reduce last-minute uncertainty, but it can’t guarantee your offer will be accepted or the purchase completed. Keep your plans flexible and revisit the lender’s requirements when you’re considering a particular home.

Use pre-approval as a planning tool, not a green light to commit without checking the details. Your financial position can change, and the property itself matters to the lender’s decision. Knowing these limits helps you house hunt with a clearer idea of what may be possible while leaving room for the checks still to come.

Pre-approval conditions, expiry and final loan approval

A pre-approval can give you a useful starting point, but its conditions shape what happens next. The conditions vary between lenders and applications, so there’s no single expiry period or set of rules for every buyer in New Zealand. Check the letter for its expiry date and requirements. Make a note of anything you need to provide or do before the lender will consider the next stage.

Pre-approval is a conditional indication. Confirmed lending comes only after the lender completes its checks and agrees to finance the specific property. Keep that distinction in mind before making an offer or taking on other commitments.

What conditions might a lender attach?

Conditions may include providing updated financial information or having the lender assess the property you want to buy. The lender may also need to check that the home fits its criteria before confirming the loan. These are general examples, not a checklist for every lender. Your letter sets out the conditions for your application, so read it carefully and ask your adviser to explain anything that isn’t clear.

Property checks can affect the outcome. For example, a lender may need to review the property’s value or other details before deciding whether it can support the proposed lending. If the property doesn’t meet the lender’s requirements, the pre-approval may not progress to confirmed lending on the terms you expected. If you’re considering the Kāinga Ora scheme, its Kāinga Ora First Home Loan pre-approval information explains that scheme’s eligibility and application steps.

What happens when your circumstances or plans change?

Your application reflects the information considered at the time. A change to your income, debts, spending or buying plans could affect how a lender views it. The impact depends on your circumstances and the lender’s assessment. Tell your adviser or lender if something material changes, rather than assuming the existing indication still applies.

Timing matters, too. Check when your pre-approval expires and whether any conditions need attention before then. If it has expired or your situation has changed, the lender may need updated information or to review your application again. Don’t rely on an old letter as if it were a current, final decision.

Pre-approval is separate from deciding how your eventual loan will be set up. The interest rate and loan structure are considered as part of arranging lending, while pre-approval is an earlier, conditional assessment. Keeping these steps separate helps you consider the home alongside repayments and flexibility that suit your plans.

If you’re unsure how a condition affects your next move, talk with Mortgage Suite’s home loan advisers to understand the process and discuss your circumstances before you commit.

How to prepare for home loan pre-approval in NZ

A little preparation can make applying for home loan pre-approval NZ feel more manageable. Start by getting clear on what you hope to buy and what repayments could fit your everyday budget. Then gather an overview of your finances. You don’t need to guess every document a lender will request. Requirements differ, and your adviser can guide you on what’s needed for your application.

  1. Clarify your plans. Think about the type of home you’re looking for, who will be borrowing and what repayments feel comfortable. Note any plans that could affect the application, such as a change in work or a commitment you expect to take on.
  2. Organise your financial records. Gather current information about your income, regular spending, debts and deposit. Keeping it together can help you spot gaps and answer questions clearly.
  3. Talk through your income and commitments. Be ready to explain how you earn, what regular payments you make and any changes that could affect your finances. A clear picture helps the lender assess your application in context.
  4. Provide the information requested. Your adviser will explain what’s needed for your situation. Give complete, up-to-date details and ask if you’re unsure how to describe an item or which records are relevant.

What information should you organise?

Start with records that show how money comes in and goes out. Depending on your circumstances, these may include information about employment or business income, regular household spending, debts and savings for your deposit. This is a starting point, not a fixed document list. Your adviser will explain what information is needed and whether anything should be updated before the application is assessed.

Accuracy matters more than trying to make your finances look a certain way. If a payment or income source needs context, make a note of what it relates to so you can explain it. Clear, consistent information can help avoid confusion while your application is reviewed.

How can you prepare if your income is not straightforward?

If you’re self-employed, work as a contractor or have income that changes, it’s understandable to wonder how a lender will view it. Different income patterns call for a closer look at the full picture, and they’re not a reason to feel judged. Relevant records and a clear explanation of how your income works can help show the context behind your finances.

Mortgage Suite can present your circumstances to suitable lenders and discuss possible pathways, including alternative lending channels when mainstream criteria don’t fit. This doesn’t guarantee approval, but it can help you understand your options and what information may support an informed assessment.

For an early sense of how different loan amounts and repayments might affect your plans, try the Mortgage Suite mortgage calculator. Treat the result as a planning aid, not a decision about how much a lender will approve. Your borrowing capacity depends on your circumstances and the lender’s assessment.

Home Loan Pre-approval in NZ: What to Expect in 2026

Steps after pre-approval before making an offer

Finding a home that feels right is a big moment. Before moving from a shortlist to an offer, compare the property details with your pre-approval conditions. The lender still needs to assess the specific home, so the initial indication isn’t final confirmation that the purchase can be funded. A simple process can help you see what’s outstanding and keep the right people informed.

After initial pre-approval, the lender needs to review the chosen home before it can confirm the loan.

What changes when you find a property?

Share the property details with your adviser promptly so they can identify what the lender needs to review. The lender may assess whether the home meets its criteria and whether property-related conditions in your pre-approval have been met. The outcome depends on the property and the lender’s assessment, not just the borrowing figure in your letter.

It’s also sensible to do your own checks on the home. For example, a building report is a professional assessment of a property’s condition and defects. Other checks can help you understand the home and the purchase, but they don’t guarantee that the lender will approve the loan or that the property is free of issues. Keep these separate from the lender’s decision. Passing one check doesn’t automatically satisfy the others.

Before making commitments, reread the pre-approval conditions and make sure you understand what remains to be done. If a condition is unclear, raise it with your adviser before relying on the initial indication. This gives you a clearer view of what the lender still needs, without assuming that finance is confirmed.

How can you keep the purchase process organised?

Once you have a property in mind, keep the moving parts together in one place. A simple note or checklist can help you track:

  • The conditions in your pre-approval and any expiry date.
  • Property information and documents shared with your adviser or lender.
  • Requests for further information and whether you’ve responded.
  • Key purchase milestones to discuss with your adviser as they come up.

Update your record if the property changes or your circumstances shift. A pre-approval relates to the information and conditions considered at the time, so don’t treat it as final confirmation for a different home or a changed situation. If you’re buying your first home, consider your wider purchase plans alongside the finance steps so you can stay focused on what matters to you.

Home loan pre-approval NZ can help you plan, but the property review and outstanding conditions move the application towards a final decision. If you’ve found a home and want help understanding the next lending steps, talk with Mortgage Suite about your home loan.

How Mortgage Suite can support your home loan pre-approval

Applying for home loan pre-approval NZ can feel like a lot to manage, especially if you’re unsure what a lender will focus on. Mortgage Suite starts by learning about your home-buying plans, financial circumstances and what you want your loan to achieve. That conversation helps shape the next steps around you, rather than treating your application as a set of figures alone.

Your adviser can explain information requests and lender conditions in plain English, help present your application and negotiate with lenders that suit your situation. If your circumstances don’t fit a mainstream bank’s usual approach, that isn’t a judgement on you or your plans. Mortgage Suite can discuss alternative lending channels too. Each lender makes its own assessment, and no pathway guarantees approval.

This support can be useful if your income varies, you’re self-employed or your financial picture needs context. A clear explanation and relevant information can help a lender understand your circumstances, but the right approach depends on your application and the lender’s criteria. Your adviser can talk through the options and what may be needed before you decide how to proceed.

When can a mortgage adviser help with pre-approval?

An adviser can help you make sense of a lender’s requests, identify questions to resolve and keep track of conditions as your application progresses. If your work, income or commitments don’t follow a simple pattern, a tailored discussion can help present the full picture. For plain-English information as you prepare, Mortgage Suite’s Mortgage School home loan guides cover related topics.

An adviser can also help you consider whether a possible borrowing amount fits your plans, rather than focusing only on the maximum a lender may consider. Your goals matter: the home you hope to buy, the repayments you’re comfortable with and the flexibility you may want from your loan are all useful parts of the conversation.

What is a sensible next step?

Start with a conversation about what you hope to buy, how your finances work and what questions are on your mind. You don’t need every detail sorted before talking it through. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping borrowers understand the process and discuss suitable lending pathways.

From there, you can get clearer on what information may be useful and what the next step could look like for your circumstances. If you’d like to talk through your home-buying plans, get in touch with Mortgage Suite. It’s a chance to discuss your situation and options, not a promise of a particular lending outcome.

Take your next step with a clearer plan

Your next move doesn’t have to be a big commitment. Start by noting what you want your home loan to make possible, what questions are still on your mind and any changes that could affect your plans. That gives you a practical starting point for working out how home loan pre-approval NZ fits your buying journey.

A conversation can turn those questions into a clear next step, whether that’s getting your information in order or talking through a lender’s conditions. You can also discuss what matters beyond the borrowing limit, such as repayments that feel manageable and a loan structure that suits your plans. You don’t need to have every answer ready before you begin.

Talk through your home loan pre-approval options with Mortgage Suite and get a clearer sense of what to do next. With a steady plan and the right questions, you can move towards your home-buying goals with more confidence.

Frequently Asked Questions

Can I make an offer on a house with pre-approval?

You may be able to make an offer, but check how the proposed purchase fits the amount and limits in your home loan pre-approval NZ letter. Your adviser can help identify what property information the lender needs. Keep a note of outstanding items alongside your offer details so you can track what still needs attention. The seller makes a separate decision about accepting an offer, and pre-approval doesn’t reserve the property.

Does home loan pre-approval affect my credit record?

The effect can depend on the lender’s application and checking process. Before proceeding, ask what checks are part of the application and whether the lender needs to access your credit information at that stage. You can also ask what information you’ll need to provide and how it will be used for the assessment. This gives you a clearer picture of the process without assuming an enquiry will improve or harm your record.

Can I get home loan pre-approval if I am self-employed?

Yes, self-employed buyers can discuss pre-approval. To explain your circumstances, prepare a simple overview of how business income reaches you, including any changes in how you’re paid. Keep business income distinct from money available for personal use, and note regular business commitments. Your adviser can guide you on relevant records for your situation, as requirements vary between applications.

What happens if my income or debts change after pre-approval?

A change may affect your application, so record what changed and when, then update your adviser. For example, note whether a new debt has a regular repayment or whether a change in work affects your expected income. Your adviser can help identify which figures or records the lender needs to review and whether any conditions or next steps are affected. Don’t rely on the earlier figures. The lender will assess the updated information.

Can I apply for pre-approval with more than one lender?

You can discuss options with more than one lender, but first compare what each application involves. Consider the information requested, the conditions attached to any indication, and how the proposed repayments or loan structure fit your plans, not only the borrowing limit. Keep a record of applications and requests, and coordinate discussions with your adviser. That can help you avoid mixing up lender questions or providing inconsistent information.

What if a bank declines my home loan pre-approval?

Start by finding out what led to the decline and whether it relates to missing information, the lender’s assessment or another part of the application. Check that the details considered were accurate, then discuss whether further information could clarify your situation. A decline isn’t a personal judgement. Mortgage Suite can help you understand the feedback and discuss mainstream or alternative lending pathways, though no lender can be assumed to approve an application.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Get a 2nd Tier Loan in NZ: A Step-by-Step Guide for 2026

A bank’s “no” doesn’t have to end your property plans. If you’re wondering how to get a 2nd tier loan, start by finding out why your application didn’t fit a mainstream lender’s criteria and what a specialist lender may assess differently. A decline can feel personal, but it isn’t a final judgement on you or your plans.

It’s also fair to be cautious about higher interest rates. A 2nd tier loan may cost more, so it should have a clear purpose and a realistic plan for what comes next. This guide covers how to prepare your finances, choose a suitable lending pathway, present your application and work towards a future application to a main bank if your circumstances allow.

Mortgage Suite specialises in loans for borrowers who don’t fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience and helps borrowers understand their options and present their case clearly. You’ll get practical guidance without treating a bank rejection as the end of the road.

Key Takeaways

  • Learn how to get a 2nd tier loan by preparing a clear application that explains your finances and the context behind them.
  • Match your borrowing challenge, such as a small deposit or credit history, with a lender whose approach may suit your circumstances.
  • Review the loan terms and any fees before deciding whether the offer fits your plans.
  • Set a realistic goal for applying to a main bank in the future, and understand what may need to change first.
  • Use a 12-to-24-month review point to check your progress and adjust your next steps if needed.

What is a 2nd Tier Loan and Why Consider One?

A decline from a main bank can be frustrating, especially when your plans make sense to you. It may reflect how that bank assesses applications, not a final judgement on your ability to borrow. A 2nd tier loan is an alternative for people whose financial situation or property doesn’t fit a mainstream lender’s usual criteria.

These loans are offered by lenders outside the major banks, including specialist non-bank financial institutions. The Non-bank financial institution overview explains the broader category. In practice, a specialist lender may look more closely at the circumstances behind your application, rather than relying only on standard measures.

The Difference Between Main Banks and Alternative Lenders

Main banks often assess applications against set criteria. That can be difficult if your income is irregular, your deposit is smaller than expected or your credit history has a few bumps. Alternative lenders may consider the wider picture, including how you earn your income, the reason for a past issue and whether repayments look manageable now. Flexibility isn’t automatic, though. Each lender has its own rules and will still assess your ability to repay.

Some alternative lenders may be set up to assess individual cases in a different way. The timing depends on the lender and how complete your information is, so don’t assume a quick decision is guaranteed. Interest rates and loan terms can also differ from a main bank’s offer. Look beyond the approval and consider whether the repayments and conditions fit your plans.

Dispelling the Myths About Non-Bank Lending

Non-bank doesn’t mean unregulated or informal. Lenders providing consumer credit in New Zealand must meet responsible lending requirements under the Credit Contracts and Consumer Finance Act. From 1 July 2026, conduct oversight for the Act transferred to the Financial Markets Authority. A lender still needs to assess whether the loan is suitable and affordable for you.

A specialist loan isn’t automatically a last resort. Kiwis may consider one when self-employment makes income harder to show in a standard format, when they have a smaller deposit or when a past credit issue needs explaining. A different lender’s approach may offer a route to a property purchase if the application works for both borrower and lender.

Think of it as a possible step in a longer plan, not a shortcut around affordability. Before deciding how to get a 2nd tier loan, be clear about what makes your application unusual and what you can comfortably repay. Mortgage Suite specialises in lending for situations that fall outside mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience and can help present your circumstances clearly and negotiate on your behalf.

How to Prepare Your 2nd Tier Loan Application

A clear application does more than gather figures. It helps the lender understand how you earn, what has changed and why the loan may be manageable now. Be upfront about your financial history. If there are gaps or late payments, explain them rather than leaving the lender to draw its own conclusions. Clear, consistent information makes it easier to assess your circumstances.

Your explanation can add context to your bank statements. The figures show what’s happened; your account helps make sense of them. Keep it factual and focused, and make sure your documents support what you say.

The Essential Paperwork You Will Need

Before applying, organise records that show your income, spending and commitments. The documents you need will depend on how you earn and what you plan to borrow for, but a tidy file helps the lender follow your application.

  • If you’re self-employed: Gather relevant business and personal financial records, such as financial statements, tax summaries and business account records. These can show how your business earns and pays you when a standard payslip doesn’t tell the whole story.
  • If your credit history has a blip: Prepare a short explanation of what happened, when it happened and what has changed since. Include supporting information if you have it.
  • For the property: Collect key details about the home you want to buy, or the property and existing loan if you’re refinancing. This gives the lender context for the purpose of the borrowing.

Check that dates and figures agree across your records. If your income varies, explain the pattern instead of relying on one unusually strong month. Label files clearly and keep them together so it’s easy to see how the information fits.

Telling Your Story to the Lender

If a one-off event affected your finances, explain what happened without making excuses. For example, if time away from work led to missed payments, describe the circumstances and what has changed since. Keep your account brief, honest and consistent with your records.

Then show how you plan to manage your finances from here. A clear outline of your income, regular outgoings and realistic steps for keeping spending on track can help explain how repayments fit your situation. Avoid promising changes you won’t be able to maintain.

A broker can help turn a complex financial picture into a clear application and explain your circumstances to a lender. Mortgage Suite works with borrowers whose situations don’t fit mainstream bank criteria. The team focuses on understanding your goals and presenting your case with care.

The Reserve Bank of New Zealand’s oversight of non-bank deposit takers explains its role for institutions in that category. Not every specialist lender is necessarily a deposit taker, so the information doesn’t describe every lender’s status.

Choosing the Right Lender for Your Situation

There isn’t one second-tier lender that suits every borrower. Some are more familiar with assessing self-employed income, while others may consider applications involving a smaller deposit or a past credit issue. The aim is to match your main hurdle with a lender whose criteria fit your circumstances, not to send the same application everywhere.

Start by identifying what made a mainstream bank hesitate. Is your income difficult to show through payslips, is your deposit limited, or does your credit history need context? Each situation calls for a different conversation with a lender. A specialist broker can compare potential pathways, explain how lenders may view your application and negotiate on your behalf, without promising approval.

Lenders for the Self-Employed

Some lenders are more used to assessing income that doesn’t arrive as a regular salary. They may look at business records and other evidence to understand whether your earnings can support repayments. “Low-doc” generally refers to an application that uses a different or smaller set of traditional income documents, not a loan with no checks. You’ll still need to show how you earn and demonstrate that repayments are affordable.

For example, a contractor with changing monthly income may need to explain the pattern across their records rather than rely on a single payslip. The right lender depends on the details of your work, income and existing commitments.

Lenders for Credit Issues or Small Deposits

If your deposit is smaller than a bank wants, a specialist lender may assess the whole application differently. That doesn’t mean every lender will accept a lower deposit, or that the deposit is the only factor. Your income, commitments and the property matter too. If a past financial setback affected your credit history, some lenders may consider an explanation and evidence that your situation has since changed.

You may also hear the term “risk grade”. Lenders can use their own methods to assess the risk of an application. A higher perceived risk may affect the offer’s conditions or terms, so ask for a plain-English explanation of what the assessment means for your loan. There isn’t one scale shared by every lender.

Choosing between these options can be hard when each lender has different rules. Mortgage Suite helps match your situation to a suitable lending pathway and present your case clearly. You can learn about the people and experience behind that support on the Mortgage Suite About Us page.

How to Get a 2nd Tier Loan in NZ: A Step-by-Step Guide for 2026

Understanding the Costs: Rates, Fees, and Terms

A second-tier loan may help you move ahead with a property purchase when a main bank can’t offer a suitable option. But look beyond the approval and understand how the interest rate, repayments and loan conditions fit your plans. Specialist lenders may offer more flexibility for some applications, and their interest rates are often higher than those of main banks. The rate and terms will depend on the lender and your circumstances.

Don’t decide based on the rate alone. Think about how long you expect to keep the loan, what repayments you can manage and what you’ll do if your plans change. Buying sooner isn’t automatically the right choice, and property values can rise or fall. Your loan should remain manageable even if your circumstances don’t improve as quickly as you hope.

Interest Rates and Your Plans

Consider how repayments would fit your budget over time, not just at the start. A calculator can help you compare repayment scenarios at different interest rates. Use the Mortgage Suite mortgage calculator to see how a rate change may affect repayments. Then consider whether those repayments leave enough room for your other regular commitments.

There’s no standard period for staying with a second-tier lender. Some borrowers use this kind of loan as a temporary step while they work towards meeting a main bank’s criteria. You could review your position over a 12-to-24-month period, but treat that as a planning guide, not a promise that you’ll be ready to switch. Your financial position and a future lender’s assessment will determine what’s possible.

Terms to Check Before You Commit

Read the loan offer carefully and make sure you understand how it works. Check the repayment schedule, how the interest rate is set and whether the loan has conditions that could affect your plans. If you may want to change lenders or repay sooner, review the relevant terms before signing so you know what steps may apply.

  • Understand the repayments: Check when payments are due and whether the amount could change during the loan term.
  • Review the conditions: Make sure you understand any requirements attached to the loan and what you need to do to meet them.
  • Think ahead: Consider how the loan would fit if your income, property plans or timing changed.

Choosing a loan is about more than securing approval. Take time to understand the offer and whether it supports your next step. Mortgage Suite can help you compare lending options and negotiate with the lender on your behalf. Use the calculator to test different repayment scenarios before deciding what feels manageable.

The Exit Strategy: Moving Back to a Main Bank

A 2nd tier loan is often best treated as a stepping stone, not a permanent arrangement. Before taking one out, think about what would need to change for a main bank to consider your application later. A 12-to-24-month goal can give you a useful review point, but it isn’t a promise that you’ll be ready to switch by then. Your income, repayment history, credit record, equity and the bank’s criteria will all matter.

Make a plan you can act on from the start. Keep track of what held up your original application and set practical steps to address it. If the hurdle was showing self-employed income, for example, keep your financial records organised over time. If it was limited equity, review your loan balance and property value during regular check-ins.

Cleaning Up Your Financial Profile

Build a steady record of making your loan repayments on time. A consistent repayment history can help show a future lender that you’re managing your commitments. Keep other debts under control too. Paying down a car loan or credit card balance may reduce your regular outgoings, which can help when a bank reviews whether you can afford the mortgage.

Your equity may change as you repay the loan or if the property’s value rises. More equity can help with a future application, but property values can also fall, and a lender will assess the property and your finances at the time. A main bank will also consider your income, credit history and ability to manage repayments.

Working with Your Broker on the Move

Raise the possibility of switching lenders early, rather than waiting until you think you’re ready. Your broker can help you review whether the original hurdle has improved, what evidence you may need and whether it makes sense to prepare a new application. If a past credit issue contributed to the decline, be ready to show how your circumstances have changed since.

Moving lenders means applying again, and approval isn’t automatic. A main bank will assess your current position at that time, rather than relying only on the fact that another lender approved you previously. Your broker can help prepare and present the updated application, and talk through the options if you’re not yet ready to move.

Keep your longer-term goal in view, whether that’s improving your financial position, building equity or refinancing. Mortgage Suite can support you as your circumstances change and help you consider the next step when the time is right. A well-planned move back to a main bank takes preparation, but you can work towards it one practical step at a time.

Take the Next Step with a Clear Plan

A bank decline can leave you unsure where to turn, but it doesn’t have to define what happens next. Use what you’ve learned about how to get a 2nd tier loan to start a thoughtful conversation about your options, what a lender would need to see and how borrowing could fit your longer-term plans.

Every borrower’s situation is different, so the right next step depends on your goals and financial circumstances. Mortgage Suite can help you explore a suitable lending pathway and put your case forward. You can also read our client reviews to hear about other Kiwis’ experiences.

Book a chat with Mortgage Suite to find your path forward. You don’t need to have every answer before you begin. A clear conversation can help you work out what to do next, one step at a time.

Frequently Asked Questions

Is it harder to get a 2nd tier loan than a bank loan?

Not necessarily, but the assessment may work differently. A specialist lender may be more open to considering an application that falls outside a main bank’s usual criteria, while still checking whether the loan is affordable and suitable. For example, a lender may look closely at how a recent change in work affects your income. Approval isn’t guaranteed, and each lender sets its own requirements.

How much deposit do I need for a 2nd tier lender in NZ?

There isn’t one deposit amount that applies to every 2nd tier loan. The amount a lender may require can depend on the property, your finances and how the lender assesses the overall application. A smaller deposit doesn’t automatically rule you out, but it may affect the options available. Before making an offer, check that your expected deposit and other funds fit the proposed lending terms.

Can I get a 2nd tier loan if I have bad credit?

Possibly. A credit issue doesn’t automatically mean every lender will decline your application, but the details matter. A lender may consider what caused the issue, whether it’s resolved and how you’ve managed your commitments since. For example, a paid account in dispute may be viewed differently from ongoing missed payments. Be open about your credit history and provide a clear explanation rather than leaving the lender to guess.

What are the interest rates like for non-bank lenders?

Non-bank loan rates are generally higher than main bank rates, but the difference depends on the lender and your application. The rate is only one part of the offer: repayment terms, fees and conditions can also affect whether it suits your plans. Compare written offers on the same basis, and check what happens to repayments if the rate changes. Avoid relying on claims about a typical rate without a specific offer to review.

How long does the 2nd tier loan process take?

There’s no guaranteed turnaround time. The process can depend on how quickly you provide the requested information, how complex your income is and whether the lender needs a property valuation or further checks. You can help avoid preventable delays by sending complete, consistent documents and responding promptly to questions. If you’re working towards a purchase date, allow time for assessment and legal steps rather than assuming approval will arrive immediately.

Do I need a mortgage broker to get a 2nd tier loan?

You don’t necessarily need a broker, but a specialist can help you understand which lenders may suit your circumstances and present your application clearly. If you’re weighing up how to get a 2nd tier loan after a bank decline, a broker can also help explain the lender’s questions and talk through the offer with you. Mortgage Suite supports borrowers whose applications don’t fit mainstream bank criteria, but no broker can promise approval.

Can I use a 2nd tier loan to buy an investment property?

A 2nd tier loan may be an option for a residential investment property if the lender’s criteria fit your circumstances and the property. The lender will assess your finances, existing commitments and the property as part of the application. Mortgage Suite helps borrowers explore residential investment property lending as well as other specialist loan options.

What happens if I want to pay off my 2nd tier loan early?

Check your loan agreement before making an early repayment, as the terms may set out notice requirements or charges. The details can differ between loans and may depend on whether you’re paying off the full balance or making an extra repayment. If you’re planning to refinance, ask for a current payout figure and factor in any applicable charges and legal steps before setting a completion date.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Build a Property Portfolio in NZ: 2026 Guide

What if the next property in your portfolio should be decided by your financial breathing room, not the maximum a lender might offer? If you’re working out how to build a property portfolio nz, it’s understandable to feel unsure about how existing loans, available equity and changing repayments could affect your next move.

A sustainable plan starts with your goals and what your household can comfortably manage, not a target number of properties. This guide will help you map out practical next steps, understand how lenders may assess your income and existing debt, and review the risks before taking on another commitment.

You’ll also learn how available equity may support a purchase, why lenders test whether you could manage higher repayments, and how to plan for vacancies or changes in your circumstances. Mortgage Suite helps borrowers compare suitable lending options and structure finance as their plans develop. If a mainstream bank has declined your application, that doesn’t necessarily mean your options have run out.

Key Takeaways

  • Start with clear property and personal goals, then set a pace your household budget can support.
  • See how to build a property portfolio nz by understanding how lenders may weigh your income, expenses, existing debt and proposed repayments.
  • Compare buying one property at a time with a faster purchase plan, and weigh using available equity against building savings.
  • Check whether your budget could handle vacancies, income changes, repayments and property upkeep before taking on another loan.
  • Organise your finances and compare lending paths so your plan can adapt as your circumstances change.

How to build a property portfolio in NZ: start with a clear plan

Buying a second property can feel like a major financial step. You’re not only deciding whether a particular home suits your plans; you’re taking on another loan and the responsibilities that come with it. A useful starting point for how to build a property portfolio nz is to decide what you want property ownership to do for you, and what level of debt your household can manage comfortably.

A property portfolio is a group of properties held for investment, rather than a single purchase considered on its own. It might grow through separate purchases over time. But owning several properties isn’t a plan by itself: each purchase needs to fit your borrowing, income and ability to manage the ongoing commitments. For a broad introduction, you can explore these real estate investing principles.

What does building a property portfolio involve?

Portfolio growth is usually a sequence of decisions, not one large transaction. After each purchase, your finances and options may look different, so pause and review before taking another step. More properties don’t automatically mean a better financial outcome. Your plan needs to account for the loans and responsibilities attached to each property, not just the number you own.

Set goals before you look at another property

Start by asking what you want property ownership to support. Then consider your timeframe, how steady your income is and what commitments your household already has. Set a debt level that leaves room in your budget for everyday needs and unexpected changes. These answers can help you decide whether another purchase fits your priorities now, later or not at all.

Write down your starting point before browsing listings. It can help to consider:

  • Your purpose: What do you want property ownership to contribute to your longer-term plans?
  • Your timeframe: Are you comfortable holding a property for the period your plan requires?
  • Your income: Could you manage the commitments if your income changed or became less predictable?
  • Your debt limit: What level of repayments would still feel manageable alongside your other obligations?

Be realistic about the difference between a goal and a borrowing limit. A lender’s assessment can show what may be possible, but it doesn’t decide what feels right for your household. Leave room for property ownership and maintenance, as well as changes that could affect your income or budget. That breathing space matters more than reaching a particular portfolio size.

Growing a property portfolio won’t suit every household or financial situation, and there’s no need to rush. Let your portfolio grow at the pace your finances can support, not the pace a lender may allow. If the numbers or your circumstances don’t feel settled, taking time to strengthen your plan is a sensible next step.

How lenders assess finance as your NZ property portfolio grows

As your property plans develop, a lender will look at your overall borrowing, not just the value of the next property. Existing home and property loans, income, household expenses and proposed repayments all help shape whether a new loan may be affordable. Assessments vary between lenders, so an earlier approval or decline won’t necessarily determine the outcome of a later application.

How equity and borrowing capacity fit together

Equity is the difference between a property’s current value and the lending secured against it. If the property’s value rises or the loan balance falls, your equity may increase. But that doesn’t automatically mean you can borrow more. A lender also needs to consider whether your income can support repayments on both existing and new loans. Available equity and borrowing capacity are related, but they aren’t interchangeable.

For example, you may have equity available while your household budget has little room for another repayment. In that case, the equity alone won’t show whether another purchase is manageable. The property type and lender requirements may also affect how the property is viewed as security for lending. If you’re weighing up finance for a rental purchase, this guide to mortgage lending concepts can help you get familiar with the basics.

What lenders may consider across multiple properties

A lender may review your existing repayments alongside your regular income, household commitments and the proposed repayments for the new loan. It may also consider rental income, but lenders can treat that income differently. Don’t assume the full rent will count towards your application. The same applies to property-related expenses. Current lender criteria matter.

The assessment may also include a serviceability stress test, which checks whether repayments could remain manageable if interest rates were higher than the rate offered. This helps explain why a loan that looks affordable at today’s repayment level may be assessed differently. Ask your mortgage adviser to explain the assessment assumptions in plain English, including how existing lending and rental income have been treated.

To prepare, organise an up-to-date view of your finances before discussing another purchase. Include:

  • All current lending: balances, repayments and any changes you already expect.
  • Household income and commitments: regular income alongside everyday expenses and other debt.
  • Rental details: income received and property-related expenses, while allowing for the lender’s own approach.
  • The proposed loan: expected repayments and how they fit with your existing commitments.

A clear picture makes it easier to compare possible lending paths and spot gaps before you commit to a purchase. A mortgage adviser can help present your circumstances to suitable lenders and negotiate a structure that fits your plans. If one mainstream bank says no, that isn’t automatically the end of the conversation. As you consider how to build a property portfolio nz, focus on understanding the reasons behind an assessment and which options may suit your situation.

Compare property portfolio strategies before choosing your next step

There’s no single route that suits every borrower. The right approach depends on how steady your income is, how much room your budget has for repayments and how much time you have to review each decision. A mortgage assessment can help you understand possible lending paths, but it doesn’t tell you whether a property is suitable or what return it might deliver. Consider the property choice and the finance separately.

One purchase at a time or a faster sequence?

Buying one property at a time gives you a chance to see how each new commitment affects your finances before deciding what comes next. A faster sequence may add properties sooner, but it also means taking on commitments closer together. Neither approach is automatically better. Consider how much time you want between decisions and whether your income and budget could manage the pace if circumstances change.

Approach What to weigh up
One purchase at a time More time to review repayments, income and commitments before another application, though progress may be slower.
Faster purchase sequence May add commitments sooner, so consider whether your budget and income can carry them without relying on everything going to plan.
Use available equity Could provide funds towards a purchase, but any extra borrowing adds repayments and still needs to fit lender criteria.
Build savings for a deposit Can reduce the need to borrow for the deposit, but waiting may affect your timing and requires consistent saving.

Using equity or building a deposit

Using equity means seeking further lending against value held in a property. Building savings means setting money aside towards a deposit instead. Equity may make a purchase possible sooner, but it can increase total debt and repayments. Saving first may mean waiting longer, while giving you time to build your deposit. Neither route guarantees approval or makes a property a sound choice. Compare both against your likely repayment capacity and timeframe.

Before settling on either path, consider what would happen if your income fell, expected rental income changed or a property needed attention. A plan that only works under ideal conditions may leave little room to adjust. Think about how much flexibility you want to keep and whether taking on another commitment now fits your broader financial priorities.

Use plain-English mortgage learning resources to get clearer on the lending concepts behind your options. Then compare possible finance structures against your goals, rather than choosing a purchase pace first and trying to make the borrowing fit afterwards. That’s a practical starting point for how to build a property portfolio nz while keeping the focus on a pace your finances can support.

How to Build a Property Portfolio in NZ: 2026 Guide

Check portfolio resilience before taking on another property

Before adding another loan, look beyond whether the repayments fit your budget today. A portfolio can feel manageable while income is steady and properties are occupied, but vacancies, repairs or changing household circumstances can alter the picture. A practical resilience check helps you spot pressure points before you commit.

Stress-test the household budget

A lender’s assessment and your own comfort level are two different checks. A lender decides whether an application fits its criteria; you need to decide whether repayments leave enough room for everyday needs and unexpected changes. Try the mortgage repayment calculator to explore how repayments may change under different assumptions. Treat it as a planning aid, not an approval estimate or a promise of what a lender will offer.

Work through this check before each purchase. Be honest about less favourable circumstances, not just the version where every payment arrives on time and nothing needs fixing.

  • 1. Repayments: Map the repayments for all your loans together. Would they remain manageable if rates or other household expenses rose?
  • 2. Income changes: Consider how a drop in household income, fewer work hours or a change in employment could affect your ability to meet commitments.
  • 3. Rental vacancies: Allow for a period when a property has no tenant and rental income pauses. Could you still cover its loan and other regular commitments?
  • 4. Repairs and upkeep: Think about routine maintenance as well as an unexpected repair. Does your budget have room to respond without disrupting essential household spending?
  • 5. Loan fit: Check how each loan’s repayments and structure fit with your other commitments and the plans you have for the coming years.

Plan for vacancies, repairs and changing circumstances

A suitable financial buffer can help you manage a gap in rent or property work that can’t be put off, but the right amount depends on your circumstances. Set a level that reflects your household commitments, property needs and capacity to save. Don’t rely on rent being received without interruption. Revisit the plan when your income, expenses or borrowing changes, and before taking on another property.

Keep the scope clear, too. A mortgage review can help you understand how lending fits your plans, but it doesn’t replace separate tax, legal or property-investment advice. Those matters may need input from the relevant professional. The Mortgage Suite website has information about lending options. A clear view of your commitments can help you decide whether the next step feels manageable, not simply possible.

Build your property portfolio with a finance plan that can adapt

A useful finance plan isn’t a timetable that says you must buy again by a certain date. It’s a way to keep your borrowing choices connected to your goals, income and changing commitments. If you’re considering how to build a property portfolio nz, focus on making the next decision with a clear view of what you owe, what you can manage and which finance paths may suit.

When a mortgage adviser can help

Before pursuing another purchase, an adviser can help you review your borrowing as a whole, including current loans, income and the new commitment you’re considering. They can compare lending options across suitable lenders and negotiate on your behalf, explaining how loan structure may affect your plans. The aim is to help you understand your choices, not to promise a particular rate, approval or outcome.

A mainstream-bank decline can be disappointing, but it doesn’t automatically close off every finance option. Another lender may assess your circumstances differently, depending on its current criteria and the details of your application. Mortgage Suite acts as a personal advocate through that process, helping you understand the options available and what each may mean for your wider borrowing picture.

Turn the plan into practical next steps

Get your information organised before a finance discussion. A clear picture makes it easier to identify questions, compare possible paths and work out what needs attention before you proceed. You can start with these steps:

  • Organise your finances: Gather details of your income, regular expenses, savings and existing lending.
  • Map your commitments: Include repayments and the ongoing responsibilities attached to each property.
  • Compare lending paths: Discuss how different lender criteria and loan structures may fit your plans.
  • Review your readiness: Consider whether the proposed commitment still feels manageable if circumstances change.

Then review the plan after a major change, such as a shift in income, new household commitments or a change to your existing lending. Revisit it before each purchase, too. A plan that fitted last year may need adjusting now, and there’s no need to follow someone else’s buying schedule.

Mortgage Suite’s team can support you as you consider your next finance decision. The Mortgage Suite website explains how to start a conversation about a property finance plan and explore a suitable way forward.

Make your next property decision with confidence

Your plan doesn’t have to map out every purchase from the start. Treat it as a working guide: revisit it as your income, commitments and goals change, and let those changes shape your next move. That gives you room to pause, adjust or proceed when the finances make sense for your household.

If you’re still considering how to build a property portfolio nz, a conversation about the lending side can help you understand the paths available. Mortgage Suite supports residential investment property borrowing and can discuss mainstream and alternative lending options. Founder Krish Krishna brings over two decades of banking experience to helping borrowers work through their finance choices. No lender can promise an outcome, but you can make your next decision with a clearer view of your options.

Talk through your property finance plans with Mortgage Suite when you’re ready to take that next step. A steady, considered pace can help you move towards your goals while keeping your household’s financial wellbeing in view.

Frequently Asked Questions

Can I build a property portfolio with only one investment property to start?

Yes, a property portfolio can begin with one investment property. Owning it doesn’t mean another purchase will suit your household, though. First, decide what you want the property to support and how long you expect to hold it. Then list your existing loan repayments and other commitments, and review your borrowing capacity before planning a next step. There’s no required property count or guaranteed route to growth.

Does having equity mean I can buy another investment property?

No, equity alone doesn’t mean you can buy another property or that a lender will approve a new loan. A lender may also consider your income, existing debt, expenses and the property offered as security. For example, having value available in one property won’t necessarily resolve a tight household budget. Look at whether repayments would be affordable as well as how much equity may be available.

How many properties should I have in a portfolio?

There’s no single number that suits everyone. If you’re considering how to build a property portfolio nz, start with what fits your goals, income, borrowing capacity and comfort with risk, rather than aiming for a particular count. For one household, keeping a single rental property may be the right fit; another may have room to grow over time. Judge progress by whether each commitment remains manageable, not by comparing portfolio sizes.

Can rental income help me qualify for another property loan?

It may help, but lenders can assess rental income in different ways. Don’t assume every dollar of rent will count in full or that rent will cover all your existing commitments in a lender’s assessment. For instance, a lender may take a cautious view of expected rent while still considering your other income and expenses. Review rental income alongside your full financial position and the lender’s current criteria.

Should I use equity or save a deposit for my next property?

Either approach may suit, depending on your circumstances. Using equity may mean taking on additional borrowing and repayments; saving towards a deposit may take longer but change how much you need to borrow. Compare the options against your timeframe, existing commitments and ability to manage repayments if circumstances shift. Before deciding, review the full lending position rather than treating available equity or savings as the only factor.

What happens if a bank declines my next property loan?

A decline isn’t a personal judgement, and it doesn’t automatically end every finance option. Start by understanding the reasons for the decision, such as how the lender viewed your income, commitments or property details. Another lender may assess your circumstances differently, but approval isn’t guaranteed. A mortgage adviser can review your position and discuss suitable mainstream or alternative lending pathways where appropriate.

Is it risky to build a property portfolio using borrowed money?

Borrowing adds repayments, so changes to income, property expenses or lending conditions can affect your household budget. The level of risk depends on your circumstances and how the lending is structured. Before taking on more debt, test your budget against less favourable conditions, consider a financial buffer that suits your situation and review your loans regularly. Property ownership isn’t risk-free, so avoid relying on everything going to plan.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Guarantor Home Loan NZ: How It Works and What to Consider in 2026

Could family support help you buy a home while putting someone else’s property at risk? A guarantor home loan nz arrangement may help address a deposit shortfall, but it isn’t simply a way to get across the line. The guarantee’s limits, risks and conditions for release matter just as much as the support it may provide.

If you’re considering asking someone to guarantee your loan, it’s understandable to feel unsure about what they’d be agreeing to. A guarantor may become responsible for the guaranteed debt if you can’t repay, and the lender will still assess whether you can afford the loan.

This guide explains how guarantor home loans work in New Zealand in 2026, what lenders may consider and what to check in the guarantee documents. You’ll also find practical questions to ask the lender and an independent legal adviser, including what the guarantee covers and how the guarantor might be released. Take time to understand the arrangement before anyone agrees, and don’t feel pressured to proceed.

Key Takeaways

  • Ask whether a guarantor could help with your deposit shortfall, but remember the lender will still assess your ability to repay.
  • Before discussing a guarantor home loan nz, clarify what the guarantee covers and whether any property will be used as security.
  • Weigh the potential support for the borrower against the responsibilities the guarantor may take on under the signed terms.
  • Prepare for a lender conversation by setting out income, debts, savings and a realistic repayment plan.
  • Ask the lender and an independent legal adviser about the guarantee documents, lender criteria and possible ways to end the arrangement.

What is a guarantor home loan in New Zealand?

Saving a deposit can feel like the biggest barrier to buying your first home. If you have income to support repayments but need to discuss extra support for your application, a guarantor arrangement may be one option to explore. In a guarantor home loan nz arrangement, another person supports your home-loan application under terms agreed with the lender. That support may involve providing security, but the structure depends on the proposed arrangement.

A loan guarantee is a promise to support a loan if the borrower doesn’t meet their obligations. The guarantee documents set out what that promise means. The borrower’s loan is the debt used to buy the home; the guarantor’s promise is a separate commitment. A guarantee may strengthen an application, but it doesn’t ensure approval. The lender still considers the borrower’s circumstances and its own criteria.

For broader first-home buying and borrowing guidance, explore Mortgage Suite’s mortgage school.

How is a guarantor different from a co-borrower?

A guarantor supports a loan through a guarantee rather than simply joining in the home purchase. A co-borrower, by contrast, applies for the loan with another borrower. The responsibilities are not automatically the same, and the role names alone don’t explain the full arrangement. Check the lender’s proposal and documents to establish who is responsible for what.

Pay particular attention to what the guarantee covers, whether any security is involved and what could happen if repayments aren’t made. Don’t assume every lender uses the same structure or wording. Both parties should understand the specific terms before deciding whether to proceed.

Who might consider a guarantor home loan?

A first-home buyer might explore this option if they believe they can manage repayments but need to discuss deposit support with a lender. A guarantee doesn’t make a loan affordable by itself or mean the application will meet the lender’s criteria. The lender still needs to assess the full application.

A family member may be willing to help, but should first consider their own finances, commitments and plans. There’s no one-size-fits-all answer: the borrower’s finances, the guarantor’s position and the lender’s requirements all affect which options may be available.

How does a guarantor home loan work in New Zealand?

A guarantor arrangement is considered as part of a home-loan application, not as an automatic shortcut to approval. The borrower applies for a loan and explains the support being proposed. The lender then assesses the application and guarantee, including what the guarantor is offering and whether the arrangement meets its criteria. Criteria vary between lenders, so ask what applies to your situation.

The process generally involves these steps:

  • The borrower applies: They provide information about their finances and the home they want to buy.
  • The lender reviews the proposal: It considers the borrower’s application and the proposed guarantee, and may assess the guarantor’s circumstances too.
  • Both parties check the documents: Before signing, the borrower and guarantor should understand the terms, any security involved and what could happen if repayments aren’t made.

If the guarantee involves property, the lender may look at its equity. Equity is the difference between a property’s value and the lending secured against it. Ask whether property is part of the proposed arrangement and what that could mean for the guarantor.

The lender’s documents set out the scope of the guarantee. Read them carefully rather than relying on a general description of how these arrangements work.

What might the guarantor be agreeing to?

Don’t assume the guarantor’s responsibility is limited to a particular amount or situation. The exact commitment depends on the guarantee wording and the lender’s arrangement. Ask the lender: what event could require the guarantor to pay or provide support? What debt does the guarantee cover? What property, if any, is involved?

A general explanation of how guarantor mortgages work can introduce the concept, but it doesn’t set the terms for a New Zealand loan. The proposed lender documents do that. The guarantor should get independent legal advice before signing and ask the lender to explain its requirements.

What does the lender assess?

The lender may consider the borrower’s income, existing commitments and ability to manage repayments. It may also assess the guarantor’s financial circumstances and any property offered as security. The checks and documents required depend on the lender and the application, so confirm what is needed rather than relying on another borrower’s experience.

To build your understanding of lending terms and prepare questions for a lender, explore Mortgage Suite’s mortgage learning resources.

Guarantor home loan benefits and risks: what should both sides weigh?

A guarantor arrangement gives the borrower another option to discuss with a lender, but it also asks someone else to accept a formal commitment. For a guarantor home loan nz application, weigh the potential support against the exact responsibilities in the documents. A guarantee isn’t a risk-free shortcut or a promise that the lender will approve the loan.

Before signing, both parties should be able to explain what the guarantee covers, what security is involved and how the arrangement could end.

Possible support for the borrower Responsibilities and limits for the guarantor
A lender may consider a guarantee as part of an application where the borrower needs to discuss deposit support. The guarantor may have to provide support or meet a financial responsibility if an event described in the agreement occurs.
The arrangement may help address a deposit gap, depending on the lender’s policy and the borrower’s full financial position. Any property used as security may be affected under the agreed terms. The guarantor should confirm exactly what is involved.
It gives the borrower another option to ask about, rather than assuming the same approach suits every lender. The commitment may affect future borrowing plans, depending on how another lender views the guarantee and the guarantor’s circumstances.

What could a guarantor arrangement help with?

Some lenders may consider a guarantee when assessing an application, but their policies and criteria differ. It may be relevant if a borrower has income to manage repayments but needs to discuss a deposit shortfall. The lender will still consider the borrower’s broader financial position, including income, debts and ability to meet repayments. A guarantee doesn’t replace that assessment, and it may not be available or suitable in every case.

What risks should the guarantor understand?

The guarantor’s risk depends on the signed terms and any security involved. If the borrower can’t meet their obligations, the guarantor may face financial responsibility as set out in the agreement. Don’t rely on a verbal summary or assume the guarantee covers only one specific part of the loan. Read the documents and ask the lender to explain any wording that isn’t clear.

Consider future plans, too. If the guarantor later applies for borrowing, another lender may take the guarantee into account. The effect depends on that lender’s assessment and the details of the arrangement. Ask how and when the guarantee could end, who must agree to release it and what conditions need to be met. Don’t treat release as automatic unless the lender confirms the terms in writing.

Guarantor Home Loan NZ: How It Works and What to Consider in 2026

How to prepare for a guarantor home loan discussion

A useful conversation starts before anyone approaches a lender or signs paperwork. For a guarantor home loan nz discussion, both people need time to ask questions and decide whether the arrangement fits their circumstances. Work through the details without treating family support as a foregone conclusion.

  1. Agree to talk openly. Discuss what support is being considered, what each person feels comfortable with and whether either has concerns.
  2. Get the borrower’s finances in order. Write down income, debts, savings and planned repayments. This gives both people a clearer starting point for discussing affordability with a lender.
  3. Review the guarantor’s position. Consider existing commitments, any property that might be involved and future borrowing needs. Ask the lender what information it needs and how it will assess the proposed support.
  4. Ask about the guarantee’s terms. Clarify what the guarantee covers, whether property is used as security, how long it may apply and what conditions could allow it to be changed or released.
  5. Read, question and get advice. Review the lender’s documents, ask for plain-English explanations and make sure the guarantor gets independent legal advice before signing.

Questions the borrower and guarantor should ask

Keep a written list and check the answers against the lender’s documents. Ask:

  • What exactly would the guarantor be responsible for under these documents?
  • What conditions must be met before the guarantee can be changed or released?
  • What happens if the borrower can’t keep up with repayments?
  • Could the guarantee affect the guarantor’s future borrowing plans, and how might a lender assess that?

Ask the lender to explain anything that remains unclear. Don’t rely on assumptions about the guarantee’s scope, duration or release conditions. Those details depend on the proposed arrangement and documents.

What should each person review before signing?

Read the full set of lender documents carefully. If a term is unfamiliar, ask the lender what it means in this specific agreement. The guarantor should also seek independent legal advice to understand their position. That advice works alongside, not instead of, clear information from the lender.

Before proceeding, check that the arrangement still suits both people’s circumstances and future plans. Mortgage Suite’s Mortgage School home-loan guides offer background to help you prepare. For support understanding lender options and preparing questions, talk with Mortgage Suite about your home-loan situation.

Choosing your next step for a guarantor home loan in NZ

Before moving ahead with a guarantor home loan nz arrangement, get clear on three things: the lender’s current criteria, what the guarantee documents commit each person to, and whether the borrower’s repayment plan is realistic. If anything is uncertain, pause and ask for an explanation. A careful decision helps both the borrower and guarantor understand what they’re agreeing to.

A decline from a mainstream bank doesn’t necessarily close off every option. Different lenders may assess applications differently, but there’s no promise another lender will approve the loan. Mortgage Suite works with mainstream and alternative lending channels and can help you explore options and prepare for lender conversations based on your circumstances.

When is it worth getting professional guidance?

Consider speaking with a mortgage adviser if lender requirements are difficult to compare or you’re unsure how to present the application and proposed guarantee. An adviser may help organise the borrower’s information, clarify which lender options to discuss and communicate with potential lenders. The guarantor can also ask the lender directly about the proposed commitment.

Borrowers and guarantors may need separate legal advice about their own responsibilities. A mortgage adviser can help explain lending options, but that doesn’t replace independent legal advice for a guarantor reviewing the documents.

What happens after the first conversation?

A first discussion can cover the borrower’s goals, finances and intended purchase, as well as who may act as guarantor and what support is being considered. From there, an adviser can help identify questions to raise with lenders. Any suggested route depends on lender criteria and both people’s circumstances. The next step might be to gather more information, compare options or decide that a guarantee isn’t the right fit.

For more background on home-loan decisions and the wider buying process, visit Mortgage Suite’s Mortgage School. If you’d like to talk through your home-loan options, Mortgage Suite can help you consider a practical next step, without pressure or any promise of approval.

Take your next step with confidence

A guarantor home loan nz arrangement may help you explore a path to your first home, but the decision should rest on more than the deposit gap. Check the lender’s criteria, make sure repayments look manageable and understand exactly what the guarantee asks of the guarantor.

Both people should read the documents carefully and get clear answers about the guarantee’s scope, any security involved and how it could end. The guarantor should also seek independent legal advice. If a mainstream bank has declined your application, that doesn’t necessarily mean every option is closed. What may be possible depends on your circumstances and the lender’s assessment.

Mortgage Suite works with home-loan clients across New Zealand. Founder Krish Krishna brings more than two decades of banking experience, helping borrowers understand lender options without promising an outcome.

If you’re ready to discuss your circumstances and possible next steps, talk through your home-loan options with Mortgage Suite. Start with your questions and decide what feels right.

Frequently Asked Questions

Can a guarantor help me get a home loan in New Zealand?

A guarantor may support your application, but can’t guarantee approval. Some lenders may consider a guarantee as part of their assessment, including when you need to discuss a deposit shortfall. They’ll still assess your income, debts and ability to manage repayments, along with the proposed guarantee. If you’re considering a guarantor home loan nz option, ask the lender what criteria apply to your circumstances.

Does a guarantor have to own a home?

Not necessarily. Whether a guarantor needs to own a home depends on the lender’s requirements and the type of support being considered. Some arrangements may involve property as security, while others may be structured differently. Ask the lender what the guarantor would need to provide and whether any property is involved. Don’t assume a particular arrangement applies until you’ve checked the proposed terms.

Can a guarantor lose their home?

A guarantor could put a home at risk if it is used as security and the borrower doesn’t meet the loan obligations, depending on the signed terms and any action the lender may take. This doesn’t mean a guarantor will automatically lose their home, but the possibility should be understood before signing. Ask the lender to explain the security involved and get independent legal advice on the documents.

How much deposit do I need with a guarantor home loan?

There’s no single deposit amount that applies to every guarantor arrangement. The lender will assess the borrower’s finances, the proposed guarantee and its own lending criteria. A guarantee may help address a deposit shortfall, but it doesn’t replace checks on whether the borrower can manage repayments. Ask the lender what deposit it requires for your application and whether the guarantee changes that requirement.

Can a guarantor be removed from a home loan later?

A guarantor may be released, but this isn’t automatic. The lender’s documents set out the arrangement, and the lender will confirm whether its release conditions have been met. Before signing, ask what would need to happen for the guarantee to end, who must approve the change and how to request it. Don’t rely on an informal understanding or assume the guarantee ends after a set time.

Does being a guarantor affect your ability to borrow?

It may affect future borrowing, depending on the guarantee’s terms and how a future lender assesses the guarantor’s finances and commitments. If you’re considering borrowing for another purpose, ask the lender how this guarantee could be taken into account. The effect can vary, so don’t assume it will have no impact or prevent you from borrowing. Review your plans and seek advice before agreeing to guarantee a loan.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Technical Guide to Finance for Minor Dwelling NZ Projects

Securing finance for minor dwelling nz work typically requires an equity top-up or a staged construction loan, with bank Loan-to-Value restrictions limiting borrowing up to 80% for owner-occupiers and65-70% for property investors. Total project funding must cover costs that vary significantly based on whether you choose a simple prefab or a custom build. Working with a dedicated financial adviser helps you get sorted with the right lender, so you can weigh equity use, staged drawdowns and deposit size before you commit.

Key Takeaways: Finance for a minor dwelling in NZ requires 20% equity for owner-occupiers or30-35% for investors, typically funded via equity top-ups or staged construction loans.

  • Lenders generally limit borrowing to 80% LVR for homeowners and65-70% for property investors.
  • It is not worth it if poor positioning ruins backyard access and reduces land appeal.
  • Choose a staged construction loan if you want to pay interest only as work advances.
  • The article recommends adding a 15% contingency margin to quotes to cover unexpected siteworks.

Equity, construction loans or savings: which path fits your build

Before you pick a product, match the funding path to the situation you are actually in:

  • You already hold strong equity in the main home: an equity top-up against that property is often the simplest route, keeping repayments on one facility.
  • You want to limit interest while the build runs: a dedicated construction loan with staged drawdowns means you pay interest only on funds released as work advances.
  • A mainstream bank has declined you, or your income is complex: non-bank and 2nd tier lending pathways can still move the project forward when standard criteria feel too rigid.

You can fund a granny flat (minor dwelling) build using equity, a construction loan, or personal savings.

Using existing equity in your home keeps payments streamlined because you borrow against your current property to fund the new project rather than opening a separate build facility from day one.

A dedicated construction loan suits you when you prefer progressive release of funds. With staged drawdowns, interest applies only to the money already used as base construction moves ahead.

If you want to keep family close and pool resources, shared funding options sit inside our family finance Archives, Mortgage Suite mortgage brokers hub and can make the project achievable without stretching one household alone.

A mainstream bank decline does not leave you without a path. Non-bank lenders offer alternative criteria when traditional rules do not fit your file.

Book a friendly chat with Mortgage Suite when you want a clear read on which of these three routes fits your equity, timing and risk comfort.

How much a minor dwelling really costs you in NZ in 2026

Quoted shell prices rarely match what you will actually pay once site and consent work land on the invoice. Building a granny flat involves direct costs alongside project fees that shift with design choice, site slope and local council requirements. Budgeting for building the shell (base construction) is only your first step toward getting sorted.

Total commitments also depend on deposit requirements, interest rates and initial bank fees. Many Kiwis meet unexpected expenses during ground and site preparation work (siteworks). You might need bridging finance support from Mortgage Suite to cover Cashflow while building. Mortgage Suite helps you line those costs up against serviceability before you sign.

Alternative lenders remain available if a bank steps back on a complex build. Tailored non-bank funding suits property owners who need short-term flexibility; mainstream banks still fit standard projects where you hold a larger cash deposit. As your dedicated advocate, our specialists push for a balanced deal on the file you actually have.

Tip: Always add a 15% contingency margin to your base construction quote before submitting loan applications to cover unexpected siteworks.

Request a personalised quote when you want those figures tested against your equity and income.

LVR limits: how much equity banks expect before they lend

Bank criteria for a granny flat turn on how you borrow and how much equity you can show.

Mainstream lenders enforce strict Loan-to-Value restrictions (LVR restrictions) across New Zealand. Owner-occupiers typically need a twenty percent deposit or equity safety net. Property investors face tougher boundaries, usually requiring thirty to thirty-five percent equity.

What few people think of: you can top up equity by securing borrowing against your main home rather than running a separate construction loan. Building the shell this way can act as a financial bridge, treating the project as a simple property cash-out and avoiding a full progress-payment structure.

If you run a firm, Cashflow during additions gets tight fast. You might explore business finance guidance from our brokers so commercial capital stays separate from the residential project.

A decline from your local manager is not the end of the road. Lenders apply serviceability stress tests differently, so another bank may still say yes on the same numbers.

Our team acts as your dedicated negotiator to secure a fair go on equity structuring. Tell us if you want a friendly, zero-pressure chat about your options.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

That file shows the arc clearly: repeated purchases over two decades, steady broker support on each deal, and five properties settled with the same adviser relationship intact.

What lenders treat as a minor dwelling on your title

A granny flat is a self-contained secondary home built on the same property as a main house. Building one helps you create extra living space for extended family or generate steady rental income.

Proposed settings have pointed toward allowing small standalone units up to 60 square metres without a building consent. You must still meet local council district plans and environmental standards. Council rules vary nationwide, so checking local rules is vital before any site work starts.

Local rules and lender settings can feel heavy when you plan the project. If a bank declines the first request, alternative lenders often still have a route to get you sorted. Structured property funding notes in our franchise finance resource hub show how clear packaging helps you reach the same property goals.

Need finance for minor dwelling nz? Compare 3 funding structures

The structure you choose decides whether you pay interest on the full build sum from day one or only as stages complete. Funding structures vary with your goals and existing equity; the right pick can save you thousands over the project.

Funding Structure Best Fit For Primary Benefit
Equity Cash-Out Homeowners with high equity Access funds upfront instantly
Construction Progress Draw Large custom builds Pay interest only on drawn funds
Personal or Non-Bank Loan Complex income or bank declines Flexible approval terms

An equity cash-out lets you draw funds against your main house and cover costs directly, without waiting on stage certificates.

Progress payments suit stage-by-stage projects: you only pay interest on funds released during the staged building the shell phase.

Non-bank options give you a fair go when traditional banks hesitate. Refinancing (moving your mortgage) onto a flexible structure keeps the project moving when a standard panel says no.

Talk with Mortgage Suite Ltd when you want these three structures modelled against your equity and build quote.

Technical Guide to Finance for Minor Dwelling NZ Projects

5 Drawdown steps that protect you from early interest drag

Construction payments need careful organisation as the build advances. This sequence helps you get sorted through each release without paying interest ahead of completed work:

  1. Submit plans: Pass your consented design and fixed-price contract to your financial adviser for initial lending assessment.
  2. Complete groundworks: Your lender releases early funding after your builder finishes siteworks.
  3. Finish the shell: Stage payments become available as workers complete building the shell.
  4. Final inspections: Council inspects the property to issue a Code Compliance Certificate (CCC) before final funds release.
  5. Move in: Transfer remaining funds so you can complete the project and collect the keys.

Staging payment requests too early can trigger interest charges before work finishes. Mortgage Suite helps you time each funding release so Cashflow stays protected. A dedicated negotiator beside you keeps every payout step plain and on schedule.

Hidden costs your advertised granny flat price leaves out

Advertised prices usually cover base construction (the core building work excluding items such as land, fencing and landscaping) rather than the full turnkey cost. Ground preparation before building gets underway can push the total up quickly. Council consent fees, utility connections, driveways and siteworks rarely sit inside the headline figure. Think of advertised pricing like buying a new car without tyres or a steering wheel: you hold the structure, yet you cannot use it yet.

Planning for those extras prevents budget stress later. A fair go on finance starts with the complete cost picture before you sign contracts.

The team at Mortgage Suite Ltd can help you map these extras into the right construction facility so the loan matches the real project, not only the brochure number. Ask for a personalised cost review when you are ready to lock the full budget.

When a secondary unit can cut the value you expect

Adding a granny flat does not automatically lift your property’s overall market valuation.

Poor positioning that ruins backyard access can reduce overall land appeal. Overcapitalising is another real threat: spending on unapproved siteworks or high-end finishes may not translate into a higher figure from bank valuation panels.

You should talk with your local council and an independent valuer first. That early check protects your equity before you apply for finance and stops you funding work the panel will not recognise.

Structure your borrowing so weekly Cashflow stays steady

How you split and price the debt decides whether the build weeks feel manageable or tight. Structuring debt properly keeps weekly costs in check while you build a granny flat.

During base construction, interest-only payments protect your cash balance until tenants move in. You then switch to principal and interest once rental income starts flowing.

Splitting the loan helps: fix one portion for stability and leave another on a floating rate if your household wants room for early repayments. A floating portion links easily to an offset account and cuts interest as surplus cash sits against the balance.

Mortgage Suite helps you negotiate tailored terms so you stay in control from first drawdown through to rental settlement. Reach out when you want that split sketched against your expected rent and outgoings.

Frequently asked questions

How much does a minor dwelling cost in NZ in 2026?

Building costs depend heavily on size, land slope and site preparation work. Market figures show a broad range across the country, spanning from low-cost transportable units up to fully custom secondary homes based on listings sampled in current market data. You can control these expenses by choosing basic layouts and working with advisers who structure your loan around the real siteworks bill.

Do I need consent for a 70m² granny flat in 2026?

You almost certainly need council approval for a self-contained unit of this size. Building code requirements and local planning rules apply to safeguard structural integrity, wastewater connections and boundary clearances. Talk with our team early so we can help you fulfil the financing requirements alongside council approval steps.

What’s the cheapest way to build a minor dwelling in NZ?

Selecting a prefabricated design or a standardised granny flat usually minimises initial construction expenses. Streamlined site access and simple plumbing layouts keep overall build costs down. We can explore flexible lending options so the facility fits the lower build sum without stretching your household budget.

Can you rent out a minor dwelling in NZ?

You can rent out a secondary property provided it complies with local council bylaws and the Healthy Homes standards. Secondary rental income is a practical way to lift total household Cashflow. We frequently assist Kiwis with securing property development funding to bring these self-contained projects to life.

What’s the difference between a minor dwelling and a granny flat?

A granny flat is simply a common everyday name for an official secondary home on the same land title. Councils and banks treat them as independent residential spaces with dedicated kitchens and bathrooms. Clear definitions help us present a clean case to lenders when negotiating your property finance.

Ready to Get Your Secondary Build Moving?

Financing a granny flat still comes down to the same decisions you met at the start: whether equity, a staged construction loan or savings (and non-bank backup) fits your file, how LVR caps shape your deposit, and which drawdown rhythm protects Cashflow until rent or family use begins. You do not have to work that through alone. Mortgage Suite Ltd advisers advocate on your behalf to secure the borrowing structure your project needs. A mainstream bank decline is not the end of your options in 2026.

Our advisers help you read bank requirements in plain language and get sorted with clear next steps. Calculate your repayments with our finance calculator to test your numbers today, then come back with the result for a friendly, no-obligation chat about the build.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

Your final home loan cap in New Zealand rests on bank serviceability tests and debt-to-income caps, not on a headline rate alone. Before you chase a listing, you need clear answers to three linked questions: how much a lender will fund against your income, how large a deposit you must show, and whether stretching to the edge of that limit still leaves you room to live. Work through those decision points in order and you avoid months of mismatched applications.

Key Takeaways: Your maximum mortgage borrowing in NZ is generally capped at six times your gross income under 2024 debt-to-income (DTI) limits and bank serviceability tests.

  • Lenders apply a serviceability stress rate of 8.5% or higher to test your repayment capacity.
  • Except when buying new builds, most mainstream banks require a 20% deposit for existing properties.
  • Therefore, first-home buyers should target the Kāinga Ora 5% deposit scheme if savings are modest.
  • Boarder income can boost eligibility but banks typically apply a 20% to 50% safety haircut.

Match your NZ borrower category before you apply

Banks do not treat every earner the same way, so the first useful step is naming the file type you will present.

  • Self-employed contractor: put certified accounts or tax returns in order early; lenders want proof of stable income before they discuss a figure.
  • Investor balancing several properties: map equity and Loan-to-Value limits across the portfolio so one highly geared title does not drag the whole application down.

Your home loan capacity depends mostly on that borrowing group. A contractor home loan is assessed very differently from a standard wage earner’s file, and criteria shift with how you earn. Naming your real category early helps you avoid mainstream declines that simply mean the file sat in the wrong queue. If you want local guidance, the team at Mortgage Suite negotiates directly with lenders as your supportive advocate. Book a short chat when you are ready to place your file in the right path.

How lenders set the figure you can actually borrow

Lenders build your borrowing power by subtracting living costs and debt commitments from total gross household income, then testing the remainder at a higher serviceability rate. They are not only looking at today’s fixed rate; they want proof you can still meet repayments if rates rise. Existing personal loans tighten debt-to-income scaling and shrink the final limit, and each bank treats board income, overtime, and living costs differently.

Tailored packaging is what secures approval. A decline from your main bank usually means your setup did not match that bank’s formula, not that you are locked out of the market. We act as your personal negotiator so the right lender sees your true financial strength. You can browse notes on borrowing power for more on how assessments differ, then book a friendly review of your own numbers when you want a concrete figure.

Deposit size that unlocks mainstream and low-deposit paths

Most New Zealand banks prefer a 20% equity safety net on existing property. Saving that sum is hard work, and standard Loan-to-Value settings limit how much high-ratio lending mainstream lenders will book. Low-deposit routes still exist. You may need only a 10% cash cushion if you meet targeted criteria, and eligible first-home buyers can secure funding with a 5% deposit through the Kāinga Ora 2026 First Home Loan programme.

Building a new home often sits outside the usual equity caps, which is why some buyers find construction finance more reachable than a second-hand purchase at the same price point. A decline from one bank manager is not the end of a homeownership plan; clear alternative pathways still reach lenders when the file is presented well. The Mortgage Suite team can walk through your deposit options in a no-obligation chat.

Tip: Check whether your prospective flat triggers the small-unit rule, as lenders may demand a higher deposit percentage.

2024 DTI limits cap your max borrowing capacity

New Reserve Bank settings restrict a home loan to six times your gross income. High earners who already carry personal debts feel the pinch first, because every store card or car loan consumes servicing space before the mortgage is even typed in. Picture your borrowing limit as a bucket: existing debt fills it before mortgage funding gets a turn.

These caps are designed to keep household debt manageable, even when they frustrate a purchase timeline. A bank decline on DTI grounds is still not the end of the path. As dedicated negotiators, we review alternative funding structures when the first formula falls short. Client stories on our testimonials page show how tightly packaged applications move through complex criteria.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Situation: a household already holding several properties needed fresh funding of $200,000 under tighter income caps. Solution: long-running advice and responsive packaging across purchases. Result: five properties settled over two decades with the same adviser relationship intact. An experienced adviser helps you read strict lending caps without giving up a sound long-term plan.

How flatmate rent can lift your borrowing capacity

Boarder income can raise overall borrowing capacity, yet mainstream banks usually count only a portion of it. Lenders apply a safety haircut so vacancy does not break the file; current market practice is a 20% to 50% discount when that cashflow enters the debt-to-income maths. Banks also run boarder payments through the higher serviceability stress rate, so the boost is real but smaller than the raw rent total.

Taking in flatmates remains a practical move for a single buyer who needs extra servicing room on a first purchase. If assessors will not accept your full boarder figure, negotiation with other lenders is the next step rather than abandoning the income line altogether. We put that case directly to the credit desk when the first pass looks too thin.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

Serviceability stress tests cut what you can bid

Banks set your maximum borrowing limit with a serviceability stress test: a hypothetical repayment check at a higher interest rate to probe future affordability. Real fixed rates matter less inside the calculator than those test rates. When actual fixed rates sit well below the test rate, the bank still judges your income against the steeper threshold, and that gap trims the price you can bid.

Assessment Type Typical Interest Rate Impact on Affordability
Actual Fixed Rate Current market level Sets actual monthly repayments
Bank Stress Rate 8.5%+ Reduces calculated borrowing cap

Test rates can penalise higher incomes harder than you expect, because the same loading is applied across the board. If the stress figure leaves your shortlist out of reach, flexible non-bank or second-tier structures are worth comparing before you rewrite your property brief. Mortgage Suite acts as your personal advocate when you need that comparison done without sales pressure.

Paperwork that speeds your pre-approval

Organised files move lender assessments faster, and gathering paperwork early removes a common source of delay. Treat the pack like a road-trip checklist: one missing item stalls the whole trip.

  1. Verify income: recent payslips, or certified accounts if you are self-employed.
  2. Show savings: bank statements that prove deposit funds and a genuine savings history.
  3. List debts: a clear debt-to-income summary, including credit cards.
  4. Detail living costs: an accurate monthly household expense breakdown for the lender.

A contractor home loan usually needs two years of trading history or current contracts on the desk. Mainstream hurdles do not have to stop the process when the file is complete and directed to a lender that accepts your income type. Reach out for a confidential chat when you want a second pair of eyes on the pack before you submit.

When stretching your borrowing limit is a bad move

Maxing out mortgage potential leaves little shield against rate rises or sudden lifestyle bills. Squeezing every last dollar from an assessment often backfires once the unexpected lands. A buffer is what keeps the household steady when life shifts.

Treat the limit like a rubber band: pull it to the edge and any extra tension snaps the budget. Passing a serviceability stress test shows you can pay on today’s assumptions; it does not price future cost spikes. Borrowing below your theoretical maximum is often the steadier choice if you want sleep at night as well as keys in the door. If the numbers feel tight, ask us to model a safer cap before you sign a sale and purchase.

Secure your pre-approval with non-bank options

A bank decline is rarely the end of a property plan. Alternative lenders supply a useful safety margin when mainstream credit policy says no. Non-bank institutions often apply more flexible criteria for complex income or smaller deposits, and they look past a single computer scoreboard.

Use that path as a springboard when you need short-term flexibility, then refinance later if your profile fits a bank book. At Mortgage Suite we act as your dedicated advocate through pre-approval and drawdown, so the credit story stays consistent from first call to settlement. Contact the team for a confidential chat when you want those options laid out side by side.

Frequently asked questions

How much can you afford to repay?

Your affordable repayment depends on total household income, living expenses, and current personal debts. Lenders review day-to-day spending to confirm enough remains for ordinary life after the mortgage leaves the account. We help you line those figures up so the repayment you offer is one you can sustain.

How much will a bank lend on a property?

Banks set a maximum by running a serviceability stress test across income and expenses, using a higher test interest rate to guard against future increases. They also apply debt-to-income caps to the overall funding total. If one bank declines, our team compares alternative lenders that read the same numbers under different policy settings.

How much of my income can go to mortgage repayments?

Most lenders prefer home loan repayments at no more than 30–35% of gross income. Staying inside that band leaves room for bills you cannot defer. Each bank weights household size slightly differently, so a short adviser conversation clarifies where your file sits.

What percentage of a property’s value can banks lend?

Banks usually lend up to 80% of value on owner-occupied homes under standard Loan-to-Value settings. First-home buyers with smaller deposits can sometimes borrow a higher share when they meet low-deposit criteria. A smaller flat may attract a higher deposit demand under small-unit policy. We can test your case across more than one lender credit desk.

What is a minimum surplus or UMI and how much is needed?

Uncommitted Monthly Income is the cash left after bills, living costs, and loan repayments. Lenders want a positive surplus buffer, often $1,000 each month, as evidence you can absorb a surprise expense. Mortgage Suite works with lenders to present that surplus clearly so the buffer you actually run is the one on the page.

Getting sorted with your home loan

Working out how much you can borrow for a mortgage across NZ starts with the same three decision points you met at the top: servicing capacity, deposit path, and whether the limit you are offered still leaves a liveable buffer under debt-to-income and stress-test rules.

Mainstream criteria can feel opaque, and a decline is rarely the end of your options in 2026. Mortgage Suite Ltd advisers act as your personal advocate, comparing non-bank alternatives and negotiating structure when the first formula does not fit. If you want clarity on your borrowing capacity, contact the team for expert mortgage advice.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

What if the biggest hurdle to your next purchase isn’t the bank’s ‘no’, but the way your current loans are tied together? For many Kiwi investors, the challenge of financing multiple investment properties nz has become a bit of a puzzle lately. You’ve probably noticed that mainstream banks are getting sticky about further lending; meanwhile, with the Official Cash Rate at 2.75% as of September 2026, those interest rates are likely putting a squeeze on your rental yields. It’s frustrating when you know the equity is there, but the red tape feels like it’s tightening around your long-term goals.

I know it’s confusing to deal with the new 7x debt-to-income (DTI) limits while trying to keep your cash flow healthy. This guide is here to help you restructure your existing debt to unlock that trapped equity and regain control. We’ll look at how to organise a loan structure that stays flexible for the next five years, focusing on lower monthly repayments and a clear path to your next deposit. You’ll discover how to move forward with your New Zealand portfolio with the confidence of someone who knows exactly how the banking system works.

Key Takeaways

  • Learn why a full portfolio audit is the first step to ensuring your current loan setup aligns with your 2026 financial goals.
  • Discover how to calculate your “useable” equity to release cash for your next deposit without needing to sell any of your existing properties.
  • Understand why the big banks might be saying no and how 2nd tier lenders can provide the flexibility you need to keep growing.
  • Follow a clear, step-by-step process for financing multiple investment properties nz that prioritises healthy cash flow and long-term stability.
  • Gain an insider’s perspective on how to structure your debt so it remains adaptable to market changes over the next five years.

What Does Refining Multiple Investment Properties Actually Mean?

Most people think refinancing is just a fancy way to say you’re looking for a lower interest rate. While a better rate is always a win, refining your portfolio goes a lot deeper. If you’re financing multiple investment properties nz, a simple rate-switch doesn’t look at how your loans interact with each other. A true refinement is a full audit of your debt setup. It’s about making sure your current structure actually matches what you want to achieve in 2026 rather than just sticking with what worked three years ago.

The way the market looks in 2026 has changed significantly. With the Official Cash Rate at 2.75% and debt-to-income (DTI) limits capped at seven times what you earn, the old ‘top-up’ method often hits a wall. A top-up just piles more debt on the existing heap. A structural refinement, however, might involve moving loans between different lenders or changing how your equity is split to give you more freedom. Understanding New Zealand property market dynamics is vital here; as rules shift, your structure has to evolve to keep your portfolio healthy.

The Three Pillars of a Refined Loan

A well-organised portfolio usually rests on three specific choices that impact your daily life and your ability to buy again:

  • Interest-only vs Principal and Interest: We check which one fits your current rental income. In a higher interest environment, interest-only terms can protect your daily cash flow, while principal and interest might be better if you’re focusing on paying down debt.
  • Extending loan terms: Resetting your loan back to a 30-year term gives your monthly budget some vital breathing room, even if you’ve already been paying it down for a few years.
  • Splitting your risk: Putting all your properties with one bank is risky. If they change their internal rules, your whole portfolio gets squeezed. Spreading your loans across different lenders keeps you in the driver’s seat.

Signs It Is Time to Refine Your Portfolio

You don’t have to wait for a problem to check your numbers. If your fixed-rate term is ending soon, you’re probably facing a bit of a shock compared to what you paid a few years ago. This is the perfect time to look at the whole picture. Another sign is a jump in property values. If you reckon your properties are worth significantly more now, you might have “lazy equity” that could be working harder for you. Finally, if you’re planning to buy another investment property within the next 12 months, you’ll need a structure that makes getting that next deposit easy to access without a bank audit slowing you down.

Unlocking Equity: The Engine Room of Your Property Growth

Growth doesn’t always require a huge pile of cash sitting in a savings account. For most Kiwi investors, the fuel for their next purchase is already sitting right under their feet. When you’re looking at financing multiple investment properties nz, your existing portfolio is usually your best source of funding. However, there’s a big difference between the total equity you see on paper and the “useable” equity a bank will actually let you touch. Understanding this distinction is the secret to growing your portfolio without having to sell a single asset.

As of late 2026, the Reserve Bank settings require a 30% deposit for existing investment properties, meaning you can generally borrow up to 70% of the property’s value. For new builds, that requirement often drops to a 20% deposit. By refining your current loans, you can often release this equity as a cash deposit for your next move. You can use our mortgage calculator to get a rough idea of what your current numbers look like before you start the formal process.

Calculating Your Useable Equity

Equity is simply the gap between what your property is worth and what you owe the bank. While you might be able to borrow up to 80% against the value of your own home, the rules for rental properties are stricter. Banks generally cap lending at 70% for existing rentals to stay within current rules. This is why getting a fresh, professional appraisal is the first step in any refinement. If your properties have gone up in value, that “lazy equity” can be unlocked to form the deposit for your next purchase. It’s about making your current assets work harder so you don’t have to.

Refining Your Loan to Buy Again

Once you’ve identified your useable equity, you can use it as a virtual deposit. This means the bank uses the value in your current properties to secure the loan for the new one. A common trap many investors fall into is having the bank tie all your properties together as one big security. This gives the bank a lot of power but leaves you with very little flexibility. A smart refinement strategy keeps your home and your rentals separate. This ensures that if you decide to sell one property later, the bank can’t automatically grab all the money to pay down your other loans. If you want to see how we’ve helped others navigate these structures, feel free to read our client reviews to see the results of a tailored approach.

Mainstream Banks vs 2nd Tier Lenders: Choosing Your Path

It’s a common story in the current market: you’ve built a solid portfolio, your equity is high, but the ‘Big Four’ banks simply won’t budge. This usually happens because mainstream banks operate with very rigid templates. If your situation is slightly outside the box, perhaps you’re self-employed or have complex income streams, you might find yourself stuck. When you’re financing multiple investment properties nz, hitting a wall with your primary bank doesn’t have to be the end of the road. It’s often just a sign that you need to look beyond the high-street branches to find a lender that prioritises your potential over their paperwork.

The rise of non-bank and 2nd tier lenders has changed the game for New Zealand investors. These lenders often have a more common-sense approach to lending. They’re willing to look at the bigger picture of your portfolio’s performance rather than just ticking boxes. Krish Krishna spent over two decades inside the banking system, and he uses that insider knowledge to negotiate directly with these lenders on your behalf. You can learn more about our approach on our about us page, where we explain how we bridge the gap between rigid bank rules and your personal goals.

When a 2nd Tier Lender Makes Sense

A 2nd tier lender isn’t just a fallback option; it’s a strategic tool. You might find this path useful if your debt-to-income (DTI) ratio is slightly over the current 7x limit set for mainstream banks. It’s also a fantastic solution if you need a short-term ‘bridge’ to get a renovation or a small development project finished before you move to long-term finance. If you’re curious about how these alternatives work, check out our 2nd tier lender New Zealand guide for a deeper look at your options.

The Exit Strategy: Moving Back to the Bank

We rarely suggest using a non-bank lender as a forever home for your loan. Instead, we view it as a stepping stone. The goal is to use the flexibility of a 2nd tier lender to secure your property, then refine your financial profile over 12 to 24 months to become ‘bank-ready’ again. This involves maintaining a clean credit history and organising your income records so that a mainstream bank will eventually welcome you back with open arms. By treating this as a journey, you can keep financing multiple investment properties nz without getting permanently sidelined by a single ‘no’ from a mainstream manager.

Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

A Step-by-Step Guide to Refining Your Portfolio in 2026

Refining your portfolio isn’t a weekend DIY project, but it also shouldn’t feel like a mountain of paperwork. Since the 2026 market involves stricter debt limits and a shifting interest rate cycle, the process for financing multiple investment properties nz requires a methodical approach. It’s about moving from a reactive state to a proactive one. Here is the path we take to get your portfolio back in peak condition.

  • Step 1: The Portfolio Audit. We start by gathering your latest mortgage statements and estimated property values. This shows us exactly where your equity is hiding.
  • Step 2: Goal Setting. Are you prioritising monthly cash flow to offset the 2.75% OCR, or are you chasing aggressive growth? Your goals dictate the structure.
  • Step 3: The Broker Chat. This is where we shop the market for you. We compare mainstream banks against 2nd tier lenders to find the best fit for financing multiple investment properties nz.
  • Step 4: The Application. We help you prep a “financial CV” that highlights your strengths to 2026 lenders.
  • Step 5: The Settlement. We handle the transition to your new, refined structure so you can start seeing the benefits.

Preparing Your Financial Paperwork

Lenders in 2026 are obsessed with the spare cash you have left over each month. This is the money you have left after all your living expenses and debts are paid. Banks now use open banking systems to see your real spending habits directly from your accounts. Because of this, tidying up small personal debts like car loans or credit cards before you apply makes the whole process a piece of cake. It clears the path for your investment loans to take centre stage and shows the bank you’re a disciplined borrower.

Navigating the 2026 Interest Rate Cycle

With the OCR at 2.75% as of September 2026, choosing between fixed and floating rates is a balancing act. Refining your portfolio might mean fixing for shorter periods, such as six or twelve months, to stay agile while the market settles. You can dive deeper into these strategies in our Mortgage Rates NZ 2026 Guide to see how different terms affect your bottom line. If you’re ready to see how these steps apply to your specific properties, we invite you to reach out for a consultative chat with our team.

The Mortgage Suite Difference: Mentorship Over Transactions

Finding a lender for financing multiple investment properties nz is one thing, but building a sustainable financial future is quite another. Most people go to a bank and receive a one-off transaction. They get a loan, a rate, and a thank you. At Mortgage Suite Ltd, we believe that serious investors deserve more than just a signature on a page. We approach our work as mentors, guiding you through the complexities of debt structure to ensure your portfolio doesn’t just grow, but thrives over the long term.

This approach is built on a foundation of deep institutional knowledge. Krish Krishna spent over two decades working inside the banking system, which means he knows exactly how the credit teams on the other side of the desk think. He understands the hidden triggers that cause a mainstream bank to say no and, more importantly, how to present your case so they say yes. We often take on the “hard cases” that other brokers might avoid, using our experience to find solutions for self-employed Kiwis or those with complex income streams that don’t fit a standard bank template.

Real Stories, Real Results

Our success isn’t just measured by the loans we settle, but by the wealth our clients build. We act as your dedicated negotiator, standing between you and the lenders to fight for the best possible terms. If you want to see the impact this personal touch has made, you can read through our client reviews. You’ll see stories of investors who were stuck at a dead end until we helped them refine their path. We don’t just focus on the next purchase; we focus on how that purchase fits into your life five or ten years from now. Our commitment is to provide a conversational, jargon-free experience that leaves you feeling empowered rather than overwhelmed.

Your Next Step to a Better Portfolio

Refining your property loans shouldn’t feel like a chore. With the right guide, it’s actually a piece of cake. Whether you’re feeling the “rate shock” of 2026 or you’re ready to unlock equity for your next big move, we’re here to help you organise your next steps with confidence. We invite you to learn more about us and how we operate nationally across New Zealand. When you’re ready, reach out for a no-obligation chat about your current property setup. Let’s take a look at your numbers together and find a way to make financing multiple investment properties nz work for your unique situation.

Take Charge of Your Property Future

Building a successful portfolio in 2026 requires more than just luck; it requires a debt structure that is built to last. You now understand how a strategic audit can turn stagnant equity into a fresh deposit and why non-bank lenders are a practical way to bypass rigid bank templates. By refining your current setup, you ensure your monthly budget has breathing room while keeping your growth plans on track.

Navigating the path of financing multiple investment properties nz is a piece of cake when you have a seasoned mentor by your side. With over two decades of banking experience and a specialty in complex loan scenarios, we offer national service to help Kiwi investors succeed. We invite you to book a conversational chat with Krish to refine your portfolio today. Let’s work together to unlock your equity and build a structure that gives you total confidence for the next five years. Your next big move is closer than you think.

Frequently Asked Questions

Is it worth refining my investment property loan if interest rates are high?

Yes, it is often more important when rates are high. Refining is about managing your monthly cash flow and yields, not just chasing a low rate. By adjusting your loan terms or switching to interest-only, you can create breathing room in your budget. This strategic approach to financing multiple investment properties nz ensures your portfolio remains sustainable even when market conditions are challenging. It’s about long-term stability rather than short-term fixes.

How much equity do I need to release to buy another investment property in NZ?

To buy an existing investment property, you generally need a 30% deposit, while new builds typically require 20%. You can release this deposit from your current properties by calculating your useable equity. This is the difference between your property’s market value and what you owe, usually capped at a 70% loan-to-value ratio for rentals. Getting a fresh appraisal is the best way to see how much “lazy equity” you can actually put to work.

What is the difference between refinancing and refining a mortgage?

Refinancing is usually a simple transaction, like moving to a new bank for a slightly better interest rate. Refining is a much more thorough process. It involves a full audit of your entire portfolio to ensure your loan terms, lender types, and repayment structures align with your 2026 goals. Refining looks at the big picture of your wealth, whereas refinancing is often just a one-off attempt to save a few dollars each month.

Can I refine my loan if I am self-employed or have a complex income?

Absolutely. We specialise in helping self-employed investors and those with non-standard income streams who don’t fit the rigid templates of mainstream banks. Because Krish has over two decades of banking experience, he knows how to package your application to highlight your strengths. We often use 2nd tier lenders who take a more common-sense approach to complex income, ensuring you can keep growing your portfolio without being held back by paperwork.

How long does the process of refining a property loan typically take?

The timeframe can vary, but you should generally allow between four and six weeks from start to finish. This period includes your initial portfolio audit, getting property appraisals, and comparing different lender options. Once we’ve chosen the best path, the formal application and settlement usually move quite quickly. We manage the entire process for you to ensure it’s a piece of cake and stays on track for your next purchase when financing multiple investment properties nz.

Will I have to pay break fees if I switch lenders mid-term?

You might face break fees if you’re currently in a fixed-rate term and decide to switch lenders. However, we don’t just look at the fee in isolation. We run the numbers to see if the long-term savings or the equity you unlock will outweigh that initial cost. Often, a more flexible structure or a better cash flow position makes paying a small fee now a very smart investment for your future.

What happens if a mainstream bank has already declined my application?

A decline from a mainstream bank is often just a sign that you don’t fit their specific internal rules. It doesn’t mean you can’t get a loan. We specialise in 2nd tier lending and alternative finance for exactly these scenarios. By looking at your portfolio through a different lens, we can often find a lender that is happy to support your goals, even if the “Big Four” have already said no.

How does the Official Cash Rate (OCR) affect my decision to refine now?

The OCR, which sits at 2.75% as of September 2026, directly impacts the interest rates banks offer. When the OCR moves, it’s the perfect time to review your structure. Refining now allows you to hedge your bets by choosing the right mix of fixed and floating terms. This keeps you agile, allowing you to take advantage of future market shifts while protecting your current rental yields from unexpected rate shocks.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.