How to Build a Property Portfolio in NZ: 2026 Guide

What if the next property in your portfolio should be decided by your financial breathing room, not the maximum a lender might offer? If you’re working out how to build a property portfolio nz, it’s understandable to feel unsure about how existing loans, available equity and changing repayments could affect your next move.

A sustainable plan starts with your goals and what your household can comfortably manage, not a target number of properties. This guide will help you map out practical next steps, understand how lenders may assess your income and existing debt, and review the risks before taking on another commitment.

You’ll also learn how available equity may support a purchase, why lenders test whether you could manage higher repayments, and how to plan for vacancies or changes in your circumstances. Mortgage Suite helps borrowers compare suitable lending options and structure finance as their plans develop. If a mainstream bank has declined your application, that doesn’t necessarily mean your options have run out.

Key Takeaways

  • Start with clear property and personal goals, then set a pace your household budget can support.
  • See how to build a property portfolio nz by understanding how lenders may weigh your income, expenses, existing debt and proposed repayments.
  • Compare buying one property at a time with a faster purchase plan, and weigh using available equity against building savings.
  • Check whether your budget could handle vacancies, income changes, repayments and property upkeep before taking on another loan.
  • Organise your finances and compare lending paths so your plan can adapt as your circumstances change.

How to build a property portfolio in NZ: start with a clear plan

Buying a second property can feel like a major financial step. You’re not only deciding whether a particular home suits your plans; you’re taking on another loan and the responsibilities that come with it. A useful starting point for how to build a property portfolio nz is to decide what you want property ownership to do for you, and what level of debt your household can manage comfortably.

A property portfolio is a group of properties held for investment, rather than a single purchase considered on its own. It might grow through separate purchases over time. But owning several properties isn’t a plan by itself: each purchase needs to fit your borrowing, income and ability to manage the ongoing commitments. For a broad introduction, you can explore these real estate investing principles.

What does building a property portfolio involve?

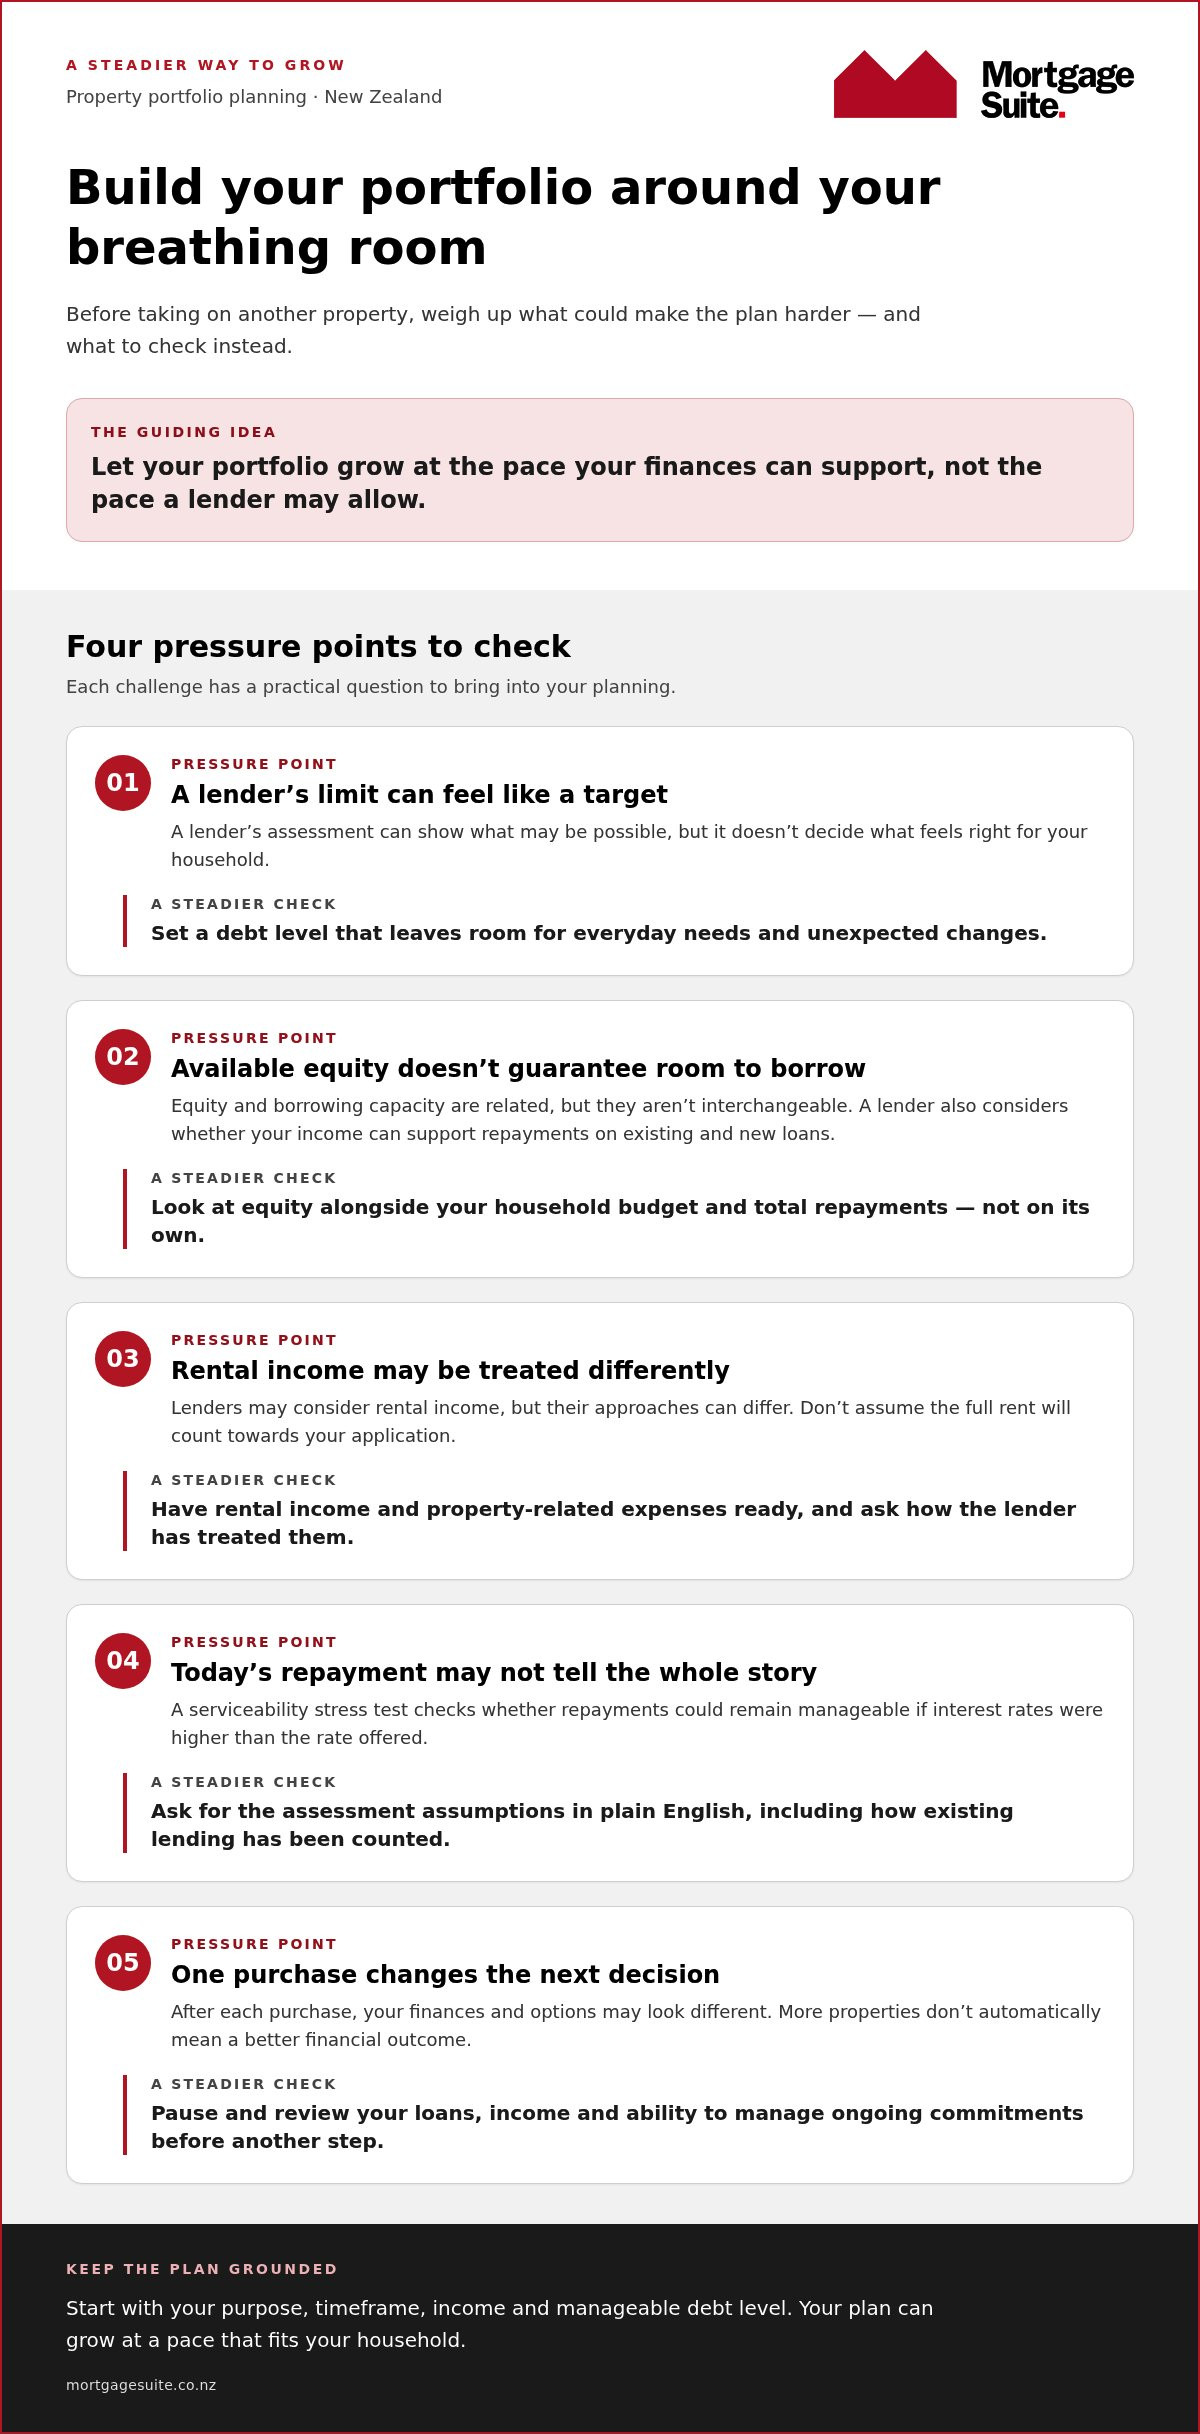
Portfolio growth is usually a sequence of decisions, not one large transaction. After each purchase, your finances and options may look different, so pause and review before taking another step. More properties don’t automatically mean a better financial outcome. Your plan needs to account for the loans and responsibilities attached to each property, not just the number you own.

Set goals before you look at another property

Start by asking what you want property ownership to support. Then consider your timeframe, how steady your income is and what commitments your household already has. Set a debt level that leaves room in your budget for everyday needs and unexpected changes. These answers can help you decide whether another purchase fits your priorities now, later or not at all.

Write down your starting point before browsing listings. It can help to consider:

  • Your purpose: What do you want property ownership to contribute to your longer-term plans?
  • Your timeframe: Are you comfortable holding a property for the period your plan requires?
  • Your income: Could you manage the commitments if your income changed or became less predictable?
  • Your debt limit: What level of repayments would still feel manageable alongside your other obligations?

Be realistic about the difference between a goal and a borrowing limit. A lender’s assessment can show what may be possible, but it doesn’t decide what feels right for your household. Leave room for property ownership and maintenance, as well as changes that could affect your income or budget. That breathing space matters more than reaching a particular portfolio size.

Growing a property portfolio won’t suit every household or financial situation, and there’s no need to rush. Let your portfolio grow at the pace your finances can support, not the pace a lender may allow. If the numbers or your circumstances don’t feel settled, taking time to strengthen your plan is a sensible next step.

How lenders assess finance as your NZ property portfolio grows

As your property plans develop, a lender will look at your overall borrowing, not just the value of the next property. Existing home and property loans, income, household expenses and proposed repayments all help shape whether a new loan may be affordable. Assessments vary between lenders, so an earlier approval or decline won’t necessarily determine the outcome of a later application.

How equity and borrowing capacity fit together

Equity is the difference between a property’s current value and the lending secured against it. If the property’s value rises or the loan balance falls, your equity may increase. But that doesn’t automatically mean you can borrow more. A lender also needs to consider whether your income can support repayments on both existing and new loans. Available equity and borrowing capacity are related, but they aren’t interchangeable.

For example, you may have equity available while your household budget has little room for another repayment. In that case, the equity alone won’t show whether another purchase is manageable. The property type and lender requirements may also affect how the property is viewed as security for lending. If you’re weighing up finance for a rental purchase, this guide to mortgage lending concepts can help you get familiar with the basics.

What lenders may consider across multiple properties

A lender may review your existing repayments alongside your regular income, household commitments and the proposed repayments for the new loan. It may also consider rental income, but lenders can treat that income differently. Don’t assume the full rent will count towards your application. The same applies to property-related expenses. Current lender criteria matter.

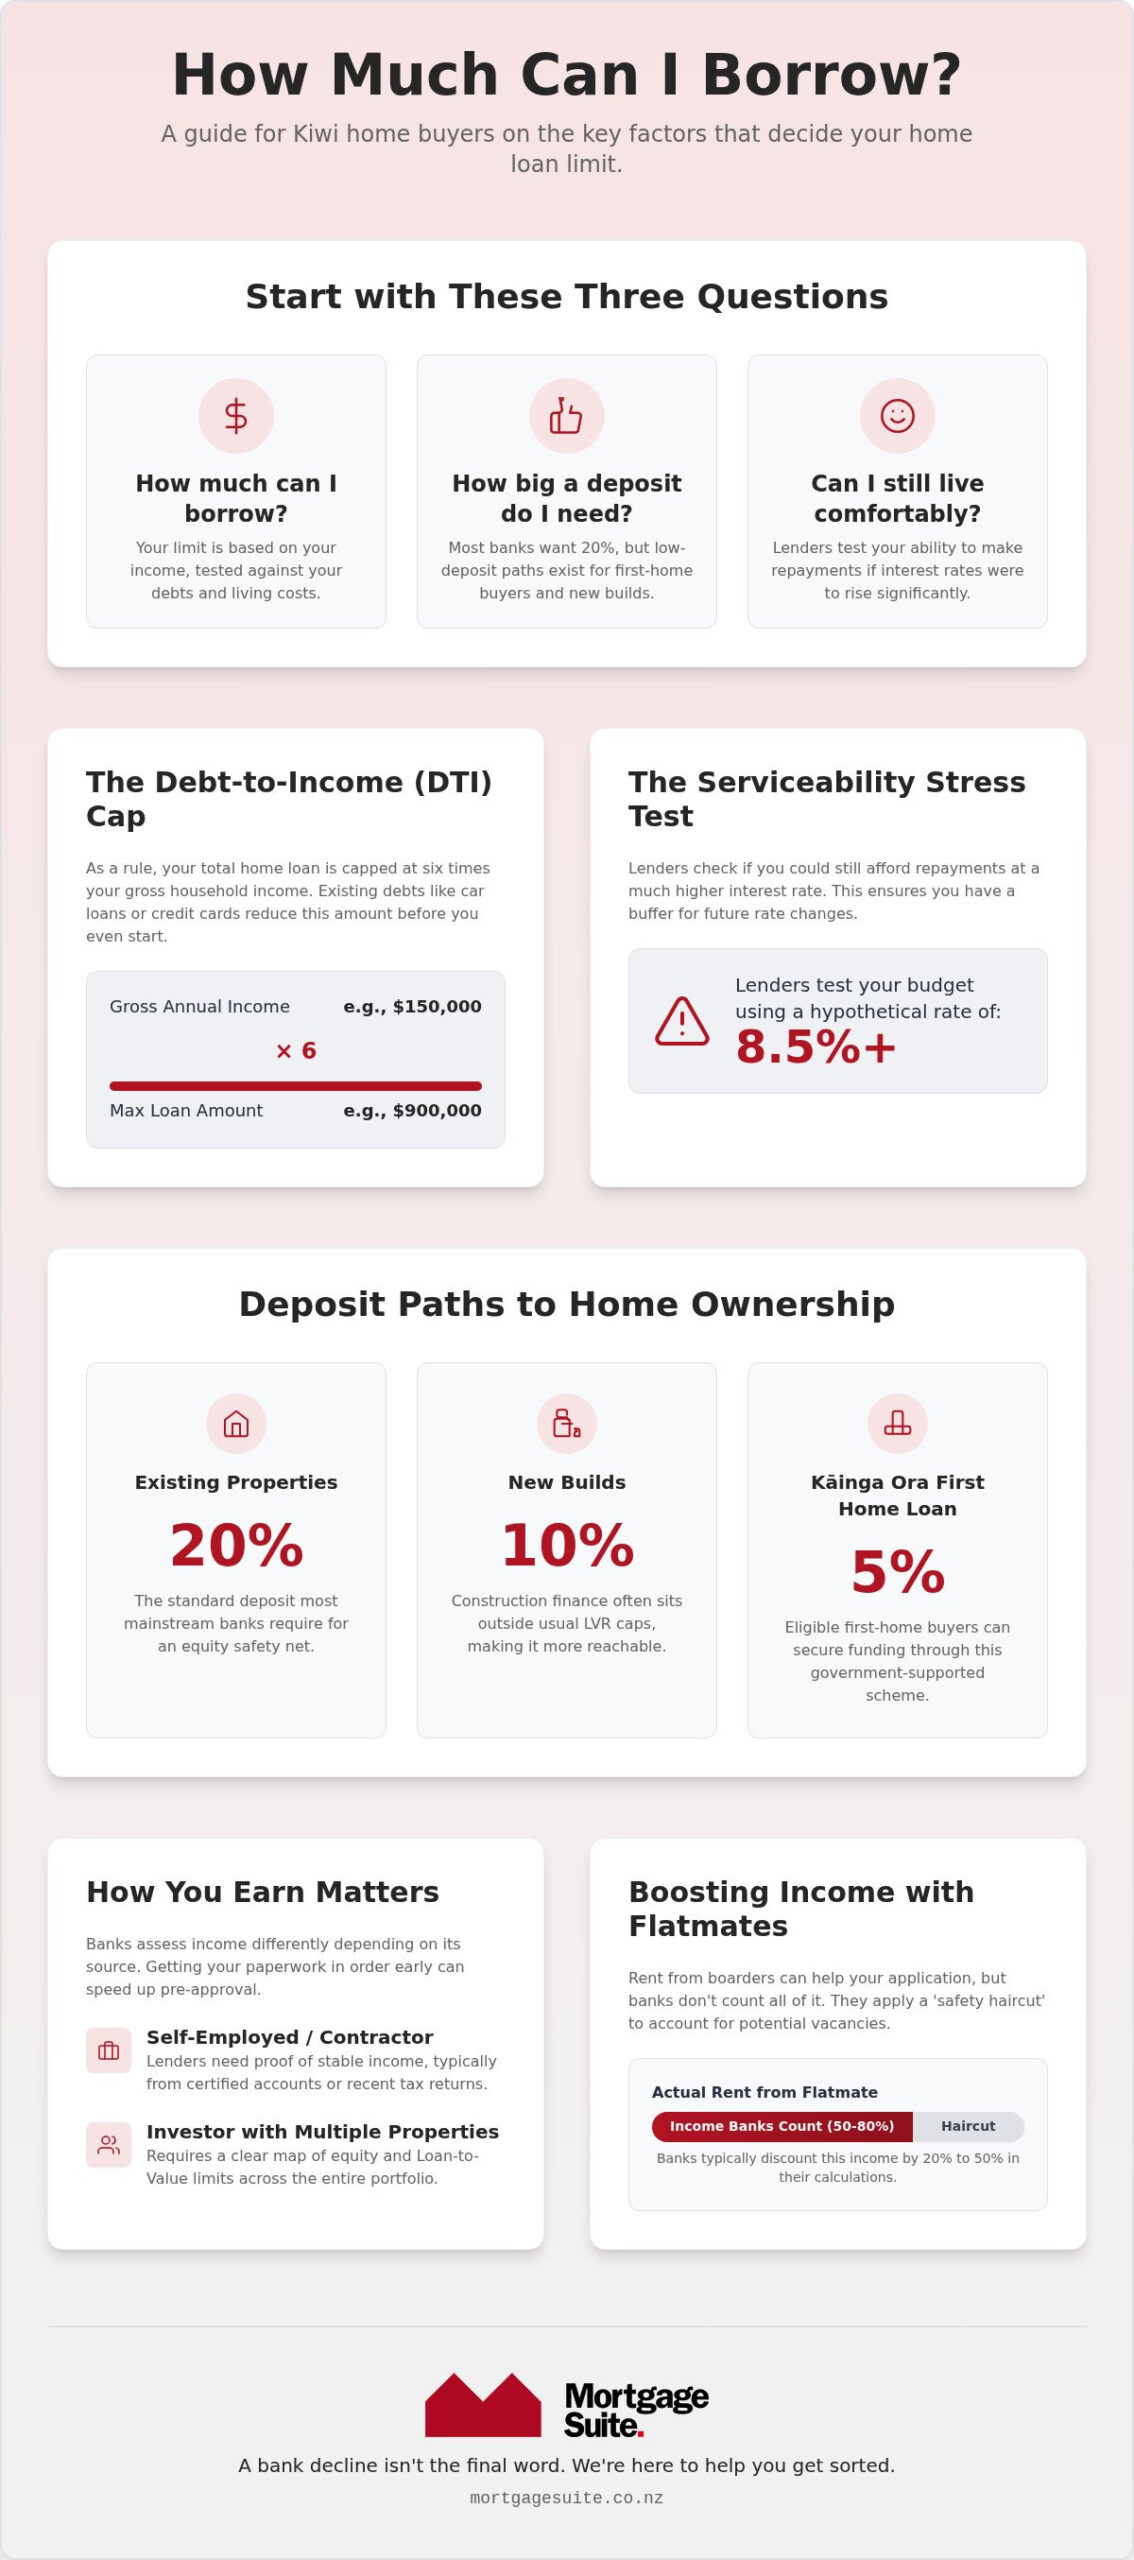
The assessment may also include a serviceability stress test, which checks whether repayments could remain manageable if interest rates were higher than the rate offered. This helps explain why a loan that looks affordable at today’s repayment level may be assessed differently. Ask your mortgage adviser to explain the assessment assumptions in plain English, including how existing lending and rental income have been treated.

To prepare, organise an up-to-date view of your finances before discussing another purchase. Include:

  • All current lending: balances, repayments and any changes you already expect.
  • Household income and commitments: regular income alongside everyday expenses and other debt.
  • Rental details: income received and property-related expenses, while allowing for the lender’s own approach.
  • The proposed loan: expected repayments and how they fit with your existing commitments.

A clear picture makes it easier to compare possible lending paths and spot gaps before you commit to a purchase. A mortgage adviser can help present your circumstances to suitable lenders and negotiate a structure that fits your plans. If one mainstream bank says no, that isn’t automatically the end of the conversation. As you consider how to build a property portfolio nz, focus on understanding the reasons behind an assessment and which options may suit your situation.

Compare property portfolio strategies before choosing your next step

There’s no single route that suits every borrower. The right approach depends on how steady your income is, how much room your budget has for repayments and how much time you have to review each decision. A mortgage assessment can help you understand possible lending paths, but it doesn’t tell you whether a property is suitable or what return it might deliver. Consider the property choice and the finance separately.

One purchase at a time or a faster sequence?

Buying one property at a time gives you a chance to see how each new commitment affects your finances before deciding what comes next. A faster sequence may add properties sooner, but it also means taking on commitments closer together. Neither approach is automatically better. Consider how much time you want between decisions and whether your income and budget could manage the pace if circumstances change.

Approach What to weigh up
One purchase at a time More time to review repayments, income and commitments before another application, though progress may be slower.
Faster purchase sequence May add commitments sooner, so consider whether your budget and income can carry them without relying on everything going to plan.
Use available equity Could provide funds towards a purchase, but any extra borrowing adds repayments and still needs to fit lender criteria.
Build savings for a deposit Can reduce the need to borrow for the deposit, but waiting may affect your timing and requires consistent saving.

Using equity or building a deposit

Using equity means seeking further lending against value held in a property. Building savings means setting money aside towards a deposit instead. Equity may make a purchase possible sooner, but it can increase total debt and repayments. Saving first may mean waiting longer, while giving you time to build your deposit. Neither route guarantees approval or makes a property a sound choice. Compare both against your likely repayment capacity and timeframe.

Before settling on either path, consider what would happen if your income fell, expected rental income changed or a property needed attention. A plan that only works under ideal conditions may leave little room to adjust. Think about how much flexibility you want to keep and whether taking on another commitment now fits your broader financial priorities.

Use plain-English mortgage learning resources to get clearer on the lending concepts behind your options. Then compare possible finance structures against your goals, rather than choosing a purchase pace first and trying to make the borrowing fit afterwards. That’s a practical starting point for how to build a property portfolio nz while keeping the focus on a pace your finances can support.
How to Build a Property Portfolio in NZ: 2026 Guide

Check portfolio resilience before taking on another property

Before adding another loan, look beyond whether the repayments fit your budget today. A portfolio can feel manageable while income is steady and properties are occupied, but vacancies, repairs or changing household circumstances can alter the picture. A practical resilience check helps you spot pressure points before you commit.

Stress-test the household budget

A lender’s assessment and your own comfort level are two different checks. A lender decides whether an application fits its criteria; you need to decide whether repayments leave enough room for everyday needs and unexpected changes. Try the mortgage repayment calculator to explore how repayments may change under different assumptions. Treat it as a planning aid, not an approval estimate or a promise of what a lender will offer.

Work through this check before each purchase. Be honest about less favourable circumstances, not just the version where every payment arrives on time and nothing needs fixing.

  • 1. Repayments: Map the repayments for all your loans together. Would they remain manageable if rates or other household expenses rose?
  • 2. Income changes: Consider how a drop in household income, fewer work hours or a change in employment could affect your ability to meet commitments.
  • 3. Rental vacancies: Allow for a period when a property has no tenant and rental income pauses. Could you still cover its loan and other regular commitments?
  • 4. Repairs and upkeep: Think about routine maintenance as well as an unexpected repair. Does your budget have room to respond without disrupting essential household spending?
  • 5. Loan fit: Check how each loan’s repayments and structure fit with your other commitments and the plans you have for the coming years.

Plan for vacancies, repairs and changing circumstances

A suitable financial buffer can help you manage a gap in rent or property work that can’t be put off, but the right amount depends on your circumstances. Set a level that reflects your household commitments, property needs and capacity to save. Don’t rely on rent being received without interruption. Revisit the plan when your income, expenses or borrowing changes, and before taking on another property.

Keep the scope clear, too. A mortgage review can help you understand how lending fits your plans, but it doesn’t replace separate tax, legal or property-investment advice. Those matters may need input from the relevant professional. The Mortgage Suite website has information about lending options. A clear view of your commitments can help you decide whether the next step feels manageable, not simply possible.

Build your property portfolio with a finance plan that can adapt

A useful finance plan isn’t a timetable that says you must buy again by a certain date. It’s a way to keep your borrowing choices connected to your goals, income and changing commitments. If you’re considering how to build a property portfolio nz, focus on making the next decision with a clear view of what you owe, what you can manage and which finance paths may suit.

When a mortgage adviser can help

Before pursuing another purchase, an adviser can help you review your borrowing as a whole, including current loans, income and the new commitment you’re considering. They can compare lending options across suitable lenders and negotiate on your behalf, explaining how loan structure may affect your plans. The aim is to help you understand your choices, not to promise a particular rate, approval or outcome.

A mainstream-bank decline can be disappointing, but it doesn’t automatically close off every finance option. Another lender may assess your circumstances differently, depending on its current criteria and the details of your application. Mortgage Suite acts as a personal advocate through that process, helping you understand the options available and what each may mean for your wider borrowing picture.

Turn the plan into practical next steps

Get your information organised before a finance discussion. A clear picture makes it easier to identify questions, compare possible paths and work out what needs attention before you proceed. You can start with these steps:

  • Organise your finances: Gather details of your income, regular expenses, savings and existing lending.
  • Map your commitments: Include repayments and the ongoing responsibilities attached to each property.
  • Compare lending paths: Discuss how different lender criteria and loan structures may fit your plans.
  • Review your readiness: Consider whether the proposed commitment still feels manageable if circumstances change.

Then review the plan after a major change, such as a shift in income, new household commitments or a change to your existing lending. Revisit it before each purchase, too. A plan that fitted last year may need adjusting now, and there’s no need to follow someone else’s buying schedule.

Mortgage Suite’s team can support you as you consider your next finance decision. The Mortgage Suite website explains how to start a conversation about a property finance plan and explore a suitable way forward.

Make your next property decision with confidence

Your plan doesn’t have to map out every purchase from the start. Treat it as a working guide: revisit it as your income, commitments and goals change, and let those changes shape your next move. That gives you room to pause, adjust or proceed when the finances make sense for your household.

If you’re still considering how to build a property portfolio nz, a conversation about the lending side can help you understand the paths available. Mortgage Suite supports residential investment property borrowing and can discuss mainstream and alternative lending options. Founder Krish Krishna brings over two decades of banking experience to helping borrowers work through their finance choices. No lender can promise an outcome, but you can make your next decision with a clearer view of your options.

Talk through your property finance plans with Mortgage Suite when you’re ready to take that next step. A steady, considered pace can help you move towards your goals while keeping your household’s financial wellbeing in view.

Frequently Asked Questions

Can I build a property portfolio with only one investment property to start?

Yes, a property portfolio can begin with one investment property. Owning it doesn’t mean another purchase will suit your household, though. First, decide what you want the property to support and how long you expect to hold it. Then list your existing loan repayments and other commitments, and review your borrowing capacity before planning a next step. There’s no required property count or guaranteed route to growth.

Does having equity mean I can buy another investment property?

No, equity alone doesn’t mean you can buy another property or that a lender will approve a new loan. A lender may also consider your income, existing debt, expenses and the property offered as security. For example, having value available in one property won’t necessarily resolve a tight household budget. Look at whether repayments would be affordable as well as how much equity may be available.

How many properties should I have in a portfolio?

There’s no single number that suits everyone. If you’re considering how to build a property portfolio nz, start with what fits your goals, income, borrowing capacity and comfort with risk, rather than aiming for a particular count. For one household, keeping a single rental property may be the right fit; another may have room to grow over time. Judge progress by whether each commitment remains manageable, not by comparing portfolio sizes.

Can rental income help me qualify for another property loan?

It may help, but lenders can assess rental income in different ways. Don’t assume every dollar of rent will count in full or that rent will cover all your existing commitments in a lender’s assessment. For instance, a lender may take a cautious view of expected rent while still considering your other income and expenses. Review rental income alongside your full financial position and the lender’s current criteria.

Should I use equity or save a deposit for my next property?

Either approach may suit, depending on your circumstances. Using equity may mean taking on additional borrowing and repayments; saving towards a deposit may take longer but change how much you need to borrow. Compare the options against your timeframe, existing commitments and ability to manage repayments if circumstances shift. Before deciding, review the full lending position rather than treating available equity or savings as the only factor.

What happens if a bank declines my next property loan?

A decline isn’t a personal judgement, and it doesn’t automatically end every finance option. Start by understanding the reasons for the decision, such as how the lender viewed your income, commitments or property details. Another lender may assess your circumstances differently, but approval isn’t guaranteed. A mortgage adviser can review your position and discuss suitable mainstream or alternative lending pathways where appropriate.

Is it risky to build a property portfolio using borrowed money?

Borrowing adds repayments, so changes to income, property expenses or lending conditions can affect your household budget. The level of risk depends on your circumstances and how the lending is structured. Before taking on more debt, test your budget against less favourable conditions, consider a financial buffer that suits your situation and review your loans regularly. Property ownership isn’t risk-free, so avoid relying on everything going to plan.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

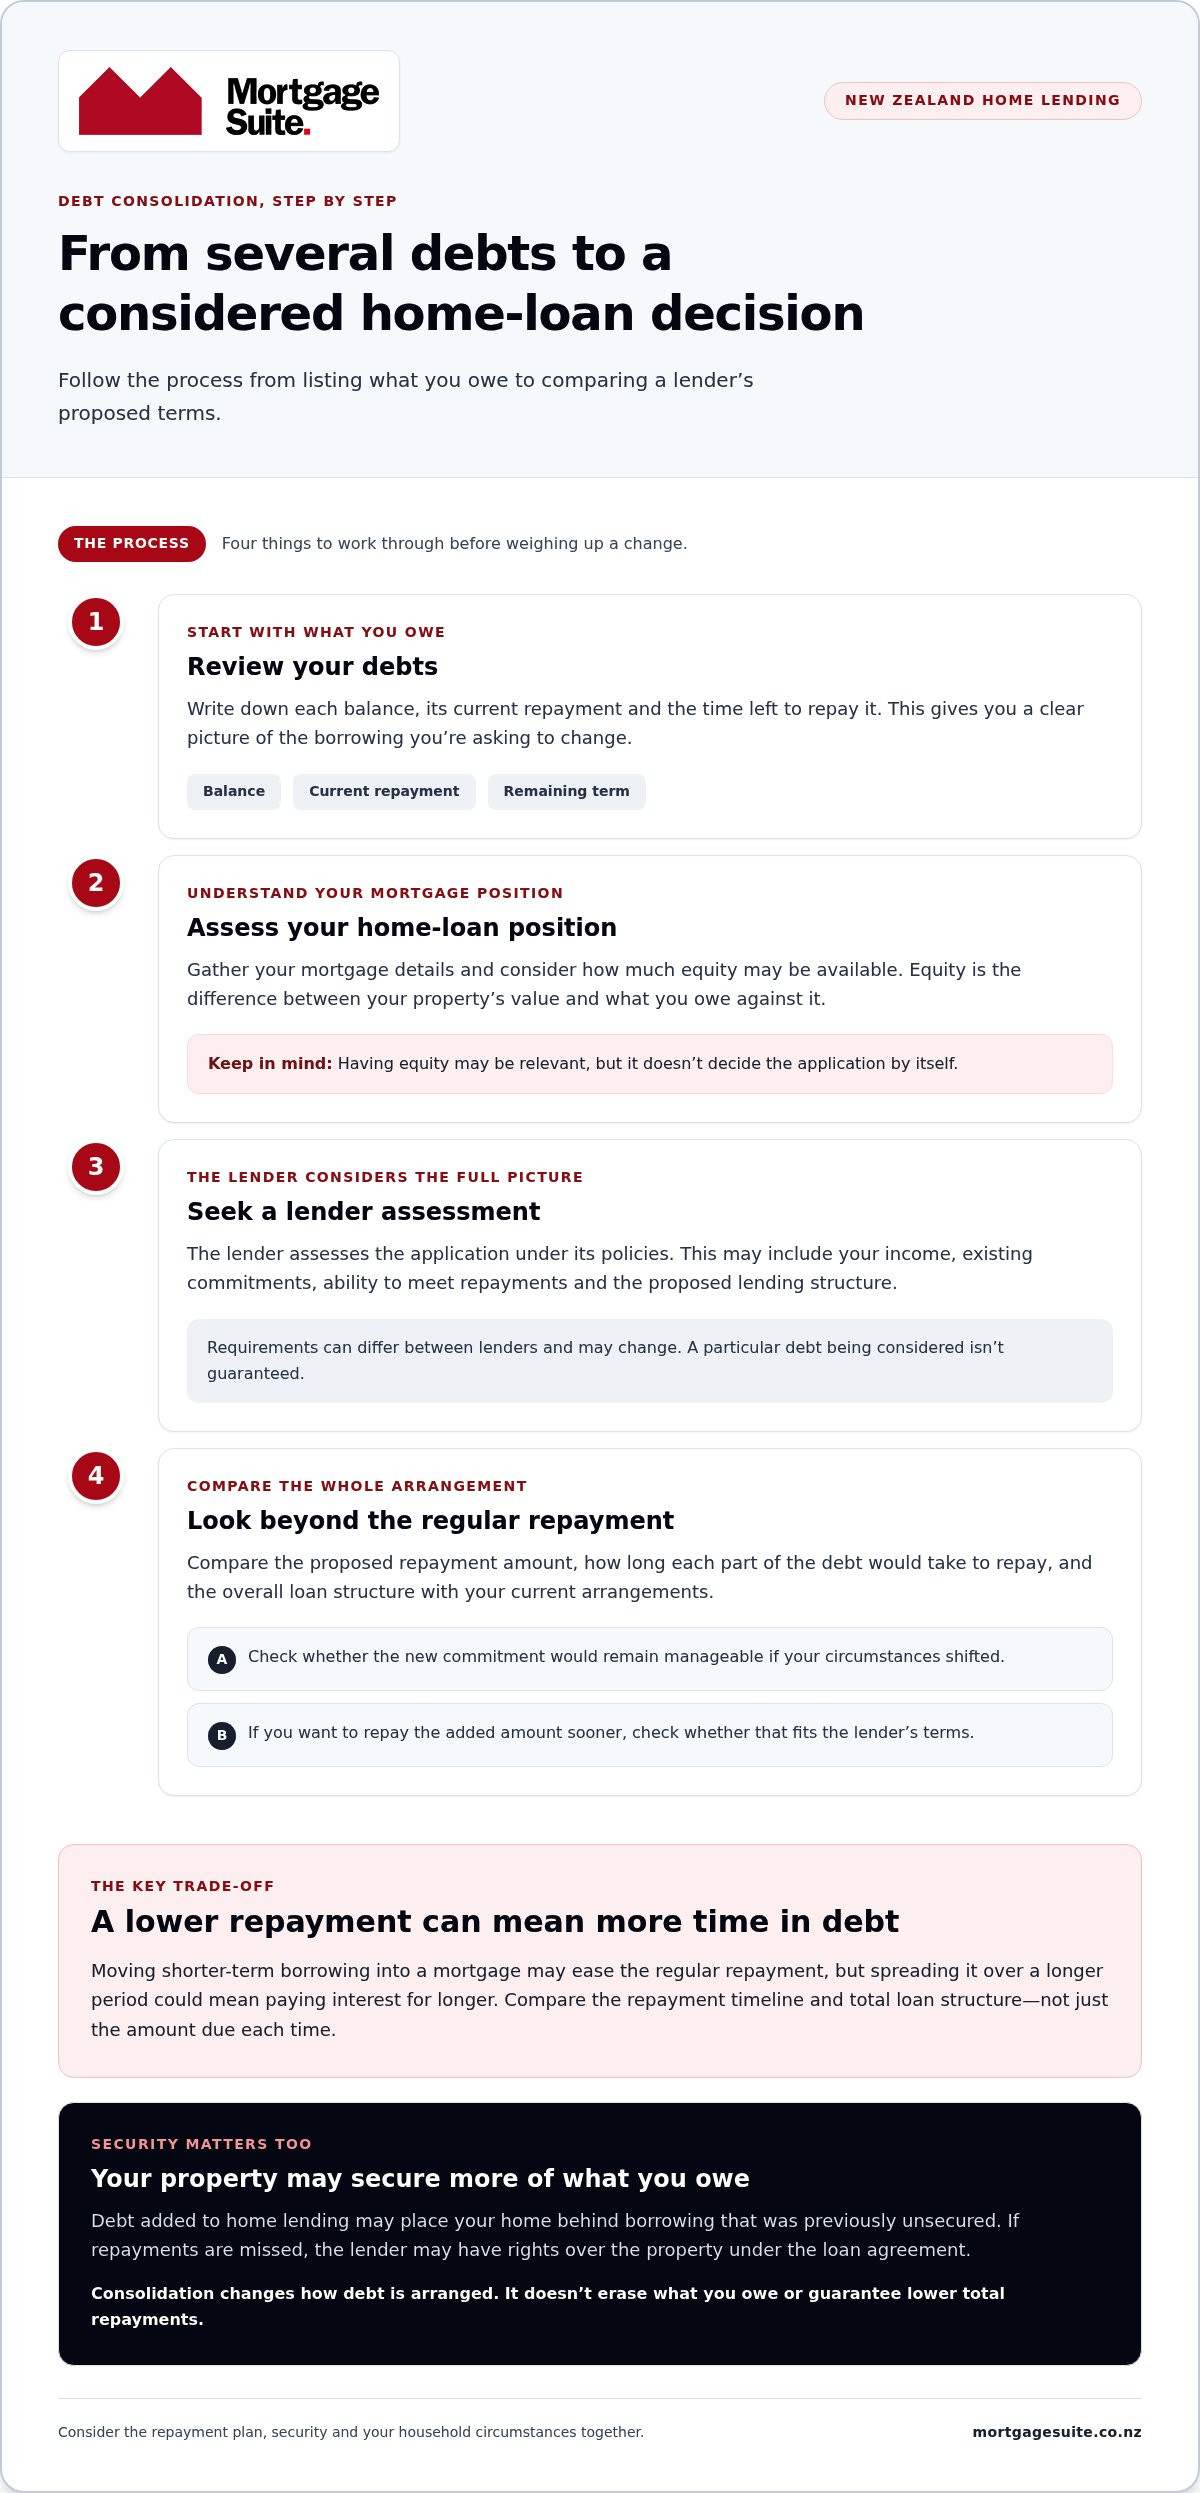
Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan for visa holders in NZ: your 2026 guide

Can your visa allow you to buy a home in New Zealand but still leave a lender unsure about your application? That can happen because eligibility to purchase and mortgage approval are separate decisions. If you’re looking at a home loan for visa holders nz, understanding that difference is a useful first step.

It’s understandable to feel uncertain. Property rules can affect whether you’re allowed to buy, while lenders may assess visa type, income, deposit and supporting documents in different ways. A decline from a mainstream bank isn’t necessarily the end of the road, but no lending pathway can promise approval.

This guide explains how the two decisions fit together, what lenders may look at, how mainstream and alternative lending pathways can differ, and which documents may help explain your circumstances. Mortgage Suite helps borrowers understand their options and present their situation to lenders, so you can have a clearer conversation about possible next steps.

Key Takeaways

  • Check your right to buy a property separately from a lender’s decision to approve a mortgage. They’re different assessments.
  • For a home loan for visa holders nz, be ready to explain your visa conditions, income, debts, deposit source and the property you’re considering.
  • Compare mainstream and alternative lending pathways against your circumstances, as lender criteria and flexibility can vary.
  • Organise your key documents before discussing an application, while allowing for lenders to request different information.
  • A broker can help present your circumstances clearly and negotiate with lenders, but approval depends on the details of your application.

Home loan for visa holders in NZ: separate property eligibility from loan approval

It can be hard to tell whether your visa lets you buy a home and whether a lender will support the purchase. Treat them as two separate questions. First, establish whether you’re eligible to buy the property. Then consider how a lender may assess your finances and circumstances for a home loan for visa holders nz.

Property-purchase eligibility is your legal ability to buy a particular property in New Zealand; loan approval is a lender’s decision about whether your finances can support the borrowing. Meeting one test doesn’t automatically mean you’ll meet the other.

Can visa holders buy residential property in New Zealand?

There isn’t one answer for every visa holder. Eligibility can depend on your visa category, residence history, citizenship, who you’re buying with and the property involved. New Zealand’s overseas investment rules restrict some purchases of residential land. The Overseas Investment Amendment Act 2018 provides background on changes to those rules, but your own circumstances matter.

For example, a residence class visa holder may need consent from the Overseas Investment Office (OIO), the government body that considers certain property purchases, if they haven’t yet met the “ordinarily resident” test. This generally means holding a residence class visa, living in New Zealand for the previous 12 months and being physically present here for at least 183 days during that period. OIO consent is official permission to buy or build a home in cases where the rules require it.

Temporary visa holders are generally restricted from buying a home to live in on their own, but some situations, including buying jointly with an eligible partner, can be treated differently. Australian and Singaporean citizens also have specific exemptions. Check current OIO guidance before making decisions, as eligibility depends on your circumstances.

Why property eligibility does not guarantee a home loan

Even if you’re allowed to buy, a lender makes a separate assessment of whether the loan appears affordable and suitable. It may consider your income and how steady it is, your existing debts, the size and source of your deposit, and the property you plan to buy. Your visa conditions may also affect how a lender views your circumstances. Policies differ, so one lender’s response may not predict another’s.

Keeping the two decisions separate can make the process feel more manageable. A lender’s decision isn’t a verdict on your future, and a decline from one mainstream bank doesn’t necessarily close every pathway. Review what the lender has assessed, identify any details that need explaining, and consider whether another lender’s criteria may fit your circumstances. Property eligibility and borrowing are connected, but each needs its own clear assessment.

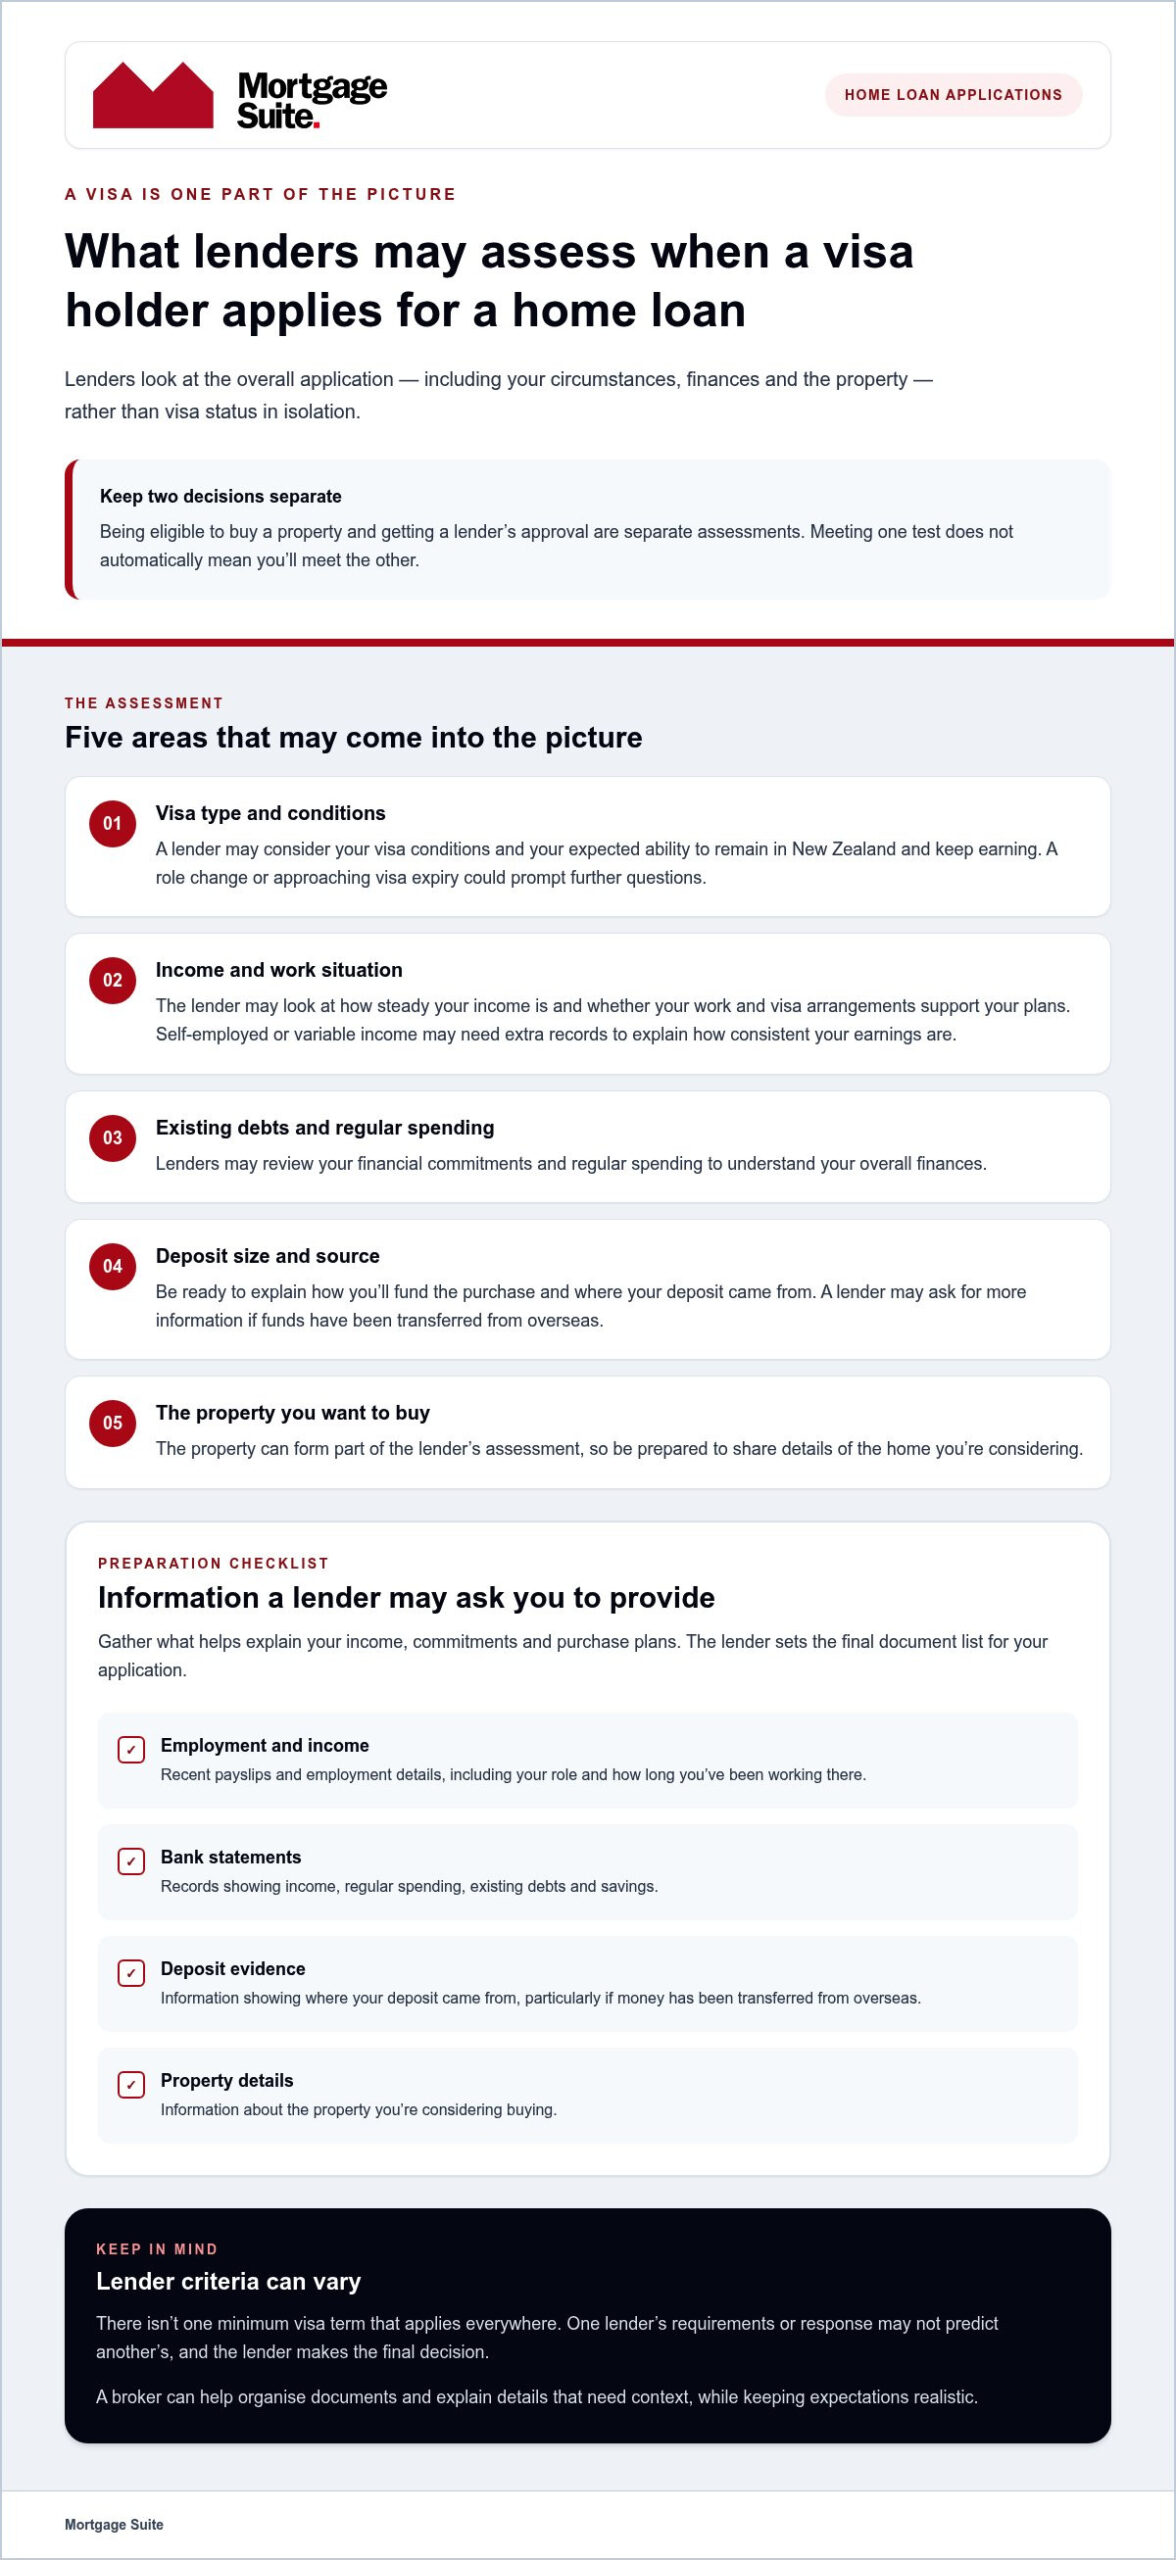
What lenders may assess when a visa holder applies for a home loan

Your visa is one part of the picture, not the whole application. A lender assesses the overall application, not visa status in isolation. It may consider your visa type and conditions alongside your income, work situation, debts, deposit and the property you want to buy. Each lender sets its own criteria, so a requirement applied by one lender shouldn’t be treated as a universal rule.

This is why an application for a home loan for visa holders nz may need a clear explanation of your circumstances. A lender may want to understand how steady your income is and whether your work and visa arrangements support your plans. Questions are part of assessing the application as a whole and don’t automatically mean there’s a problem.

How visa type and remaining visa term may affect an application

Lenders may look at your visa conditions and expected ability to remain in New Zealand and keep earning. Work conditions, a role change or an approaching expiry could prompt further questions, but lender policies differ. Don’t assume there’s one minimum visa term that applies everywhere. The relevant lender’s current criteria determine what it will consider in your situation.

The same applies to named loan pathways. Kāinga Ora’s First Home Loan scheme has its own eligibility criteria, so check the current details rather than assuming a visa alone determines whether you qualify.

Income, deposit and financial records lenders may review

A lender needs a clear view of the money coming in, the commitments going out and how you’ll fund the purchase. Depending on your circumstances and the lender, you may be asked for records such as:

  • Recent payslips and details of your employment, including your role and how long you’ve been working there.
  • Bank statements showing income, regular spending, existing debts and savings.
  • Evidence showing where your deposit came from, particularly if funds have been transferred from overseas.
  • Details of the property you’re considering, as the property can form part of the lender’s assessment.

If you’re self-employed or your income varies, the lender may need extra records to understand how consistent your earnings are. Gather the documents that show your income and commitments clearly, but expect the lender to set the final list for your application. You can also explore plain-English mortgage guidance as you get your information together.

Clear information can make it easier for a lender to assess your application on its merits. A broker can help organise the documents and explain details that need context, while keeping expectations realistic: the lender makes the final decision.

Mainstream and alternative home loans for visa holders: how to compare pathways

There isn’t one lender pathway that suits every visa holder. Mainstream and alternative lenders may assess applications differently, and policies can vary within each group. When comparing a home loan for visa holders nz, look at how the lender’s criteria fit your circumstances, as well as the loan’s repayment structure and flexibility. A headline interest rate alone won’t show whether the overall arrangement suits your plans.

The 2nd tier and non-bank home loans guide explains more about alternative lending. This can be a pathway to explore if your circumstances don’t fit a mainstream lender’s criteria, though suitability depends on your application and the terms available.

What to compare Mainstream lender Alternative lender
Criteria and assessment May apply defined policies to visa status, income, deposit and property details. May consider applications that sit outside some mainstream criteria, with its own assessment requirements.
Flexibility Depends on the individual lender’s rules and how your application fits them. May offer a different way to assess some circumstances, but flexibility isn’t the same across all lenders.
Loan fit Compare repayments, structure and conditions against your needs and plans. Review the full loan terms and repayment commitments, not just the initial rate.

When a mainstream lender may be worth considering

A mainstream lender may be worth exploring if your visa, income, deposit and property plans fit its current criteria. That doesn’t guarantee acceptance. Find out how the lender treats your specific visa circumstances, what evidence it needs and whether the repayment arrangement fits your budget over time. Each lender sets its own requirements, so don’t assume one bank’s policy applies to all.

When an alternative lender may be another pathway

If a mainstream lender can’t assess your application under its usual criteria, an alternative lender may be another option to consider. It won’t suit everyone or guarantee approval, so weigh its assessment approach and loan conditions carefully. Mortgage Suite helps explain possible pathways and present more complex circumstances clearly to lenders. If you’d like support comparing options, talk with Mortgage Suite about your goals and situation.

Home loan for visa holders in NZ: your 2026 guide

How to prepare a home loan application as a visa holder

A little preparation can make a home loan conversation clearer and less stressful. Before comparing lenders, bring together the details that explain your visa, finances and property plans. This gives you a practical starting point for a home loan for visa holders nz, while allowing for lenders to request documents specific to your application.

Build a clear picture of your visa and financial position

Start by checking your property-purchase eligibility for your circumstances. Then organise your information so you can explain your situation consistently. A simple summary of your income, regular commitments, deposit source and intended property can help you spot gaps before you apply.

Depending on the lender and application, useful documents may include:

  • Current visa documents and relevant visa conditions.
  • Recent payslips, employment details or other evidence of income.
  • Bank statements showing regular income, expenses, debts and savings.
  • Information or records showing where your deposit funds came from.
  • Details of the property you’re considering, if you’ve chosen one.

If you’re self-employed or your income changes from month to month, gather records that help explain how you earn and how your income varies. Keep names, dates and other personal details consistent across forms and supporting documents. The lender may ask for more or different information, so use this as a starting checklist rather than a fixed list.

Prepare questions and compare lender fit

Use these steps to get sorted before discussing an application:

  • Clarify purchase eligibility. Understand whether your visa and circumstances allow you to buy the property you have in mind.
  • Map your finances. Note your income, work history, regular expenses, existing debts and deposit source.
  • Organise your records. Bring together relevant visa, employment, income and bank documents.
  • Discuss lender options. Ask how a lender may assess your visa and income circumstances, and what information it needs to consider your application.
  • Compare the whole loan. Look at eligibility, repayment structure, flexibility and communication, as well as the interest rate.

Useful questions can help you understand whether a lender may be a fit: Which parts of my visa or income history need explaining? What documents would help clarify them? How do the repayments and conditions match my plans? For plain-English explanations as you prepare, visit Mortgage Suite’s mortgage education resources.

Mortgage Suite can help you organise your information and discuss lender options without treating one lender’s response as the final word. Talk through your home loan options with a team that can present your circumstances clearly and negotiate with lenders.

How Mortgage Suite can help visa holders explore home loan options

Working out which lender may suit your visa and financial circumstances can feel like a lot to manage alone. Mortgage Suite takes a personal approach: we learn about your goals, understand the details of your situation and consider how your application may fit different lender criteria. This gives you a clearer view of possible next steps without treating a particular loan outcome as certain.

A personal advocate when lending criteria feel hard to navigate

Lender feedback can be difficult to interpret, especially if a decision focuses on one part of your application. A broker can help explain what the feedback means, identify information that may need more context and discuss whether another lending pathway could be worth exploring. A decline from one lender isn’t necessarily a final judgement, but it also doesn’t mean another lender will approve your application.

Mortgage Suite’s founder, Krish Krishna, brings more than two decades of banking experience to conversations about borrowing. That experience supports a practical understanding of how lenders assess applications and how a borrower’s circumstances can be presented clearly. It’s guidance and advocacy, not a promise of approval. You can read more about Mortgage Suite’s team and experience.

What to expect from an initial lending conversation

An initial conversation is a chance to explain what you’re hoping to do and get a clearer picture of the information lenders may need. You can talk through your visa conditions, income, deposit, existing commitments and property plans. If some details are still uncertain, say so. A clear, honest picture helps shape a useful discussion about lender options and what may need attention before an application is presented.

Mortgage Suite can help organise the key details, match your circumstances to potential lender criteria and present your application clearly. Where appropriate, the broker can also negotiate with lenders on your behalf. For a home loan for visa holders nz, this support can help you compare possible pathways and understand what each lender is asking for, while leaving the decision with the lender.

You don’t need to have every answer before starting a conversation. If you’d like to talk through your goals and possible next steps, discuss your home loan options with Mortgage Suite. There’s no pressure to have everything sorted first.

Take your next step with a clearer plan

Buying a home with a visa involves two separate questions: whether you’re eligible to purchase, and whether a lender is prepared to approve your borrowing. Once you understand that distinction, you can focus on the details that shape a home loan for visa holders nz, including your visa conditions, income, deposit and the lender’s own criteria.

Mainstream and alternative lending pathways may suit different circumstances, but neither guarantees approval. Preparing clear information and comparing the full loan structure can help you have a more informed conversation about your options.

Mortgage Suite supports borrowers through mainstream and alternative lending applications, with personal advocacy and lender negotiation. Founder Krish Krishna brings over two decades of banking experience to that work, helping you understand lender feedback and present your circumstances clearly.

Talk through your home loan options with Mortgage Suite and explore possible next steps at your pace. Getting started doesn’t have to be daunting.

Frequently Asked Questions

Can I get a home loan in New Zealand on a work visa?

You may be able to apply, but a lender’s decision depends on your circumstances and its current criteria. A work visa doesn’t automatically mean you can buy a home independently, so check purchase eligibility separately before making plans. Lenders may consider your visa conditions, income, employment history, deposit and other commitments. For a home loan for visa holders nz, both property rules and borrowing requirements need to be considered.

Can temporary visa holders buy a house in New Zealand?

Temporary visa holders are generally restricted from buying a home to live in on their own, but individual circumstances can affect the rules. For example, a temporary visa holder may be able to buy jointly with an eligible New Zealand partner if the property is treated as shared under relationship-property rules. This means it falls within the property-sharing rules for couples. Check current Overseas Investment Office guidance before entering a purchase agreement or assuming an exception applies.

Does a residence-class visa guarantee home loan approval?

No. A residence-class visa may affect whether you’re eligible to purchase, but it doesn’t require a lender to approve a mortgage. The lender will separately assess your income, debts, deposit, ability to manage repayments and the property. Some residence visa holders may also need Overseas Investment Office consent, depending on their circumstances. Confirm purchase eligibility and borrowing requirements as separate steps before committing to a property.

What documents might a visa holder need for a home loan application?

Possible documents include current visa details, payslips, employment information, bank statements and evidence showing where your deposit came from. If you’re self-employed or your income varies, a lender may ask for additional records to understand your earnings. You may also need to provide details of the property you’re considering. The exact documents depend on the lender and your application, so treat this as a starting list, not a universal requirement.

Do all New Zealand lenders assess visa holders in the same way?

No. Lenders set their own criteria, and they may differ in how they consider visa conditions, income, employment history, deposit and property details. One lender’s decision doesn’t necessarily tell you how another will assess your application. Compare more than the interest rate: consider eligibility, repayment structure, flexibility and the information each lender needs. A broker can help explain lender feedback and present your circumstances clearly.

Can I apply for a home loan if a bank has declined my application?

Yes, a decline from one bank doesn’t automatically rule out every other lending option. First, understand the reasons for the decision and whether anything in your application needs clarification or improvement. Lenders assess applications differently, and an alternative lender may consider circumstances outside some mainstream criteria. That isn’t a promise of approval or a suitable route for everyone, but a tailored review can help you understand possible next steps.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Second mortgage for business in NZ: how it works in 2026

Could business funding put your home at risk, even if you already have a mortgage? For some Kiwis, a second mortgage for business NZ may provide access to property equity without replacing an existing home loan. But it adds another loan secured against the property, so weigh the funding need against the security and repayment risks.

It’s understandable to feel cautious. You may be comparing a second mortgage with a business loan or refinancing, while considering whether your business income and circumstances will meet a lender’s requirements. If the property has to be sold to repay debt, the first mortgage lender generally has priority over the second mortgage lender. Understand how that could affect your options and have a realistic repayment plan before proceeding.

This guide explains how a second mortgage works in 2026, what lenders may assess and what information to prepare. It also sets out questions to ask about repayments, property security and your plan to repay the loan, so you can compare funding paths and make a considered decision.

Key Takeaways

  • A second mortgage for business NZ adds lending secured against property that already has a mortgage, so check how the existing loan’s priority may affect your options.
  • Before proceeding, consider whether the business can manage repayments and what could happen to the property if it can’t.
  • Compare a second mortgage with a term loan or refinancing by checking the security required, repayment structure and impact on existing lending.
  • Prepare accurate business financial information, details of existing lending and a clear plan for repaying the loan.
  • An adviser can help you weigh up the risks and discuss lender options suited to your circumstances, without guaranteeing approval.

What is a second mortgage for business in NZ?

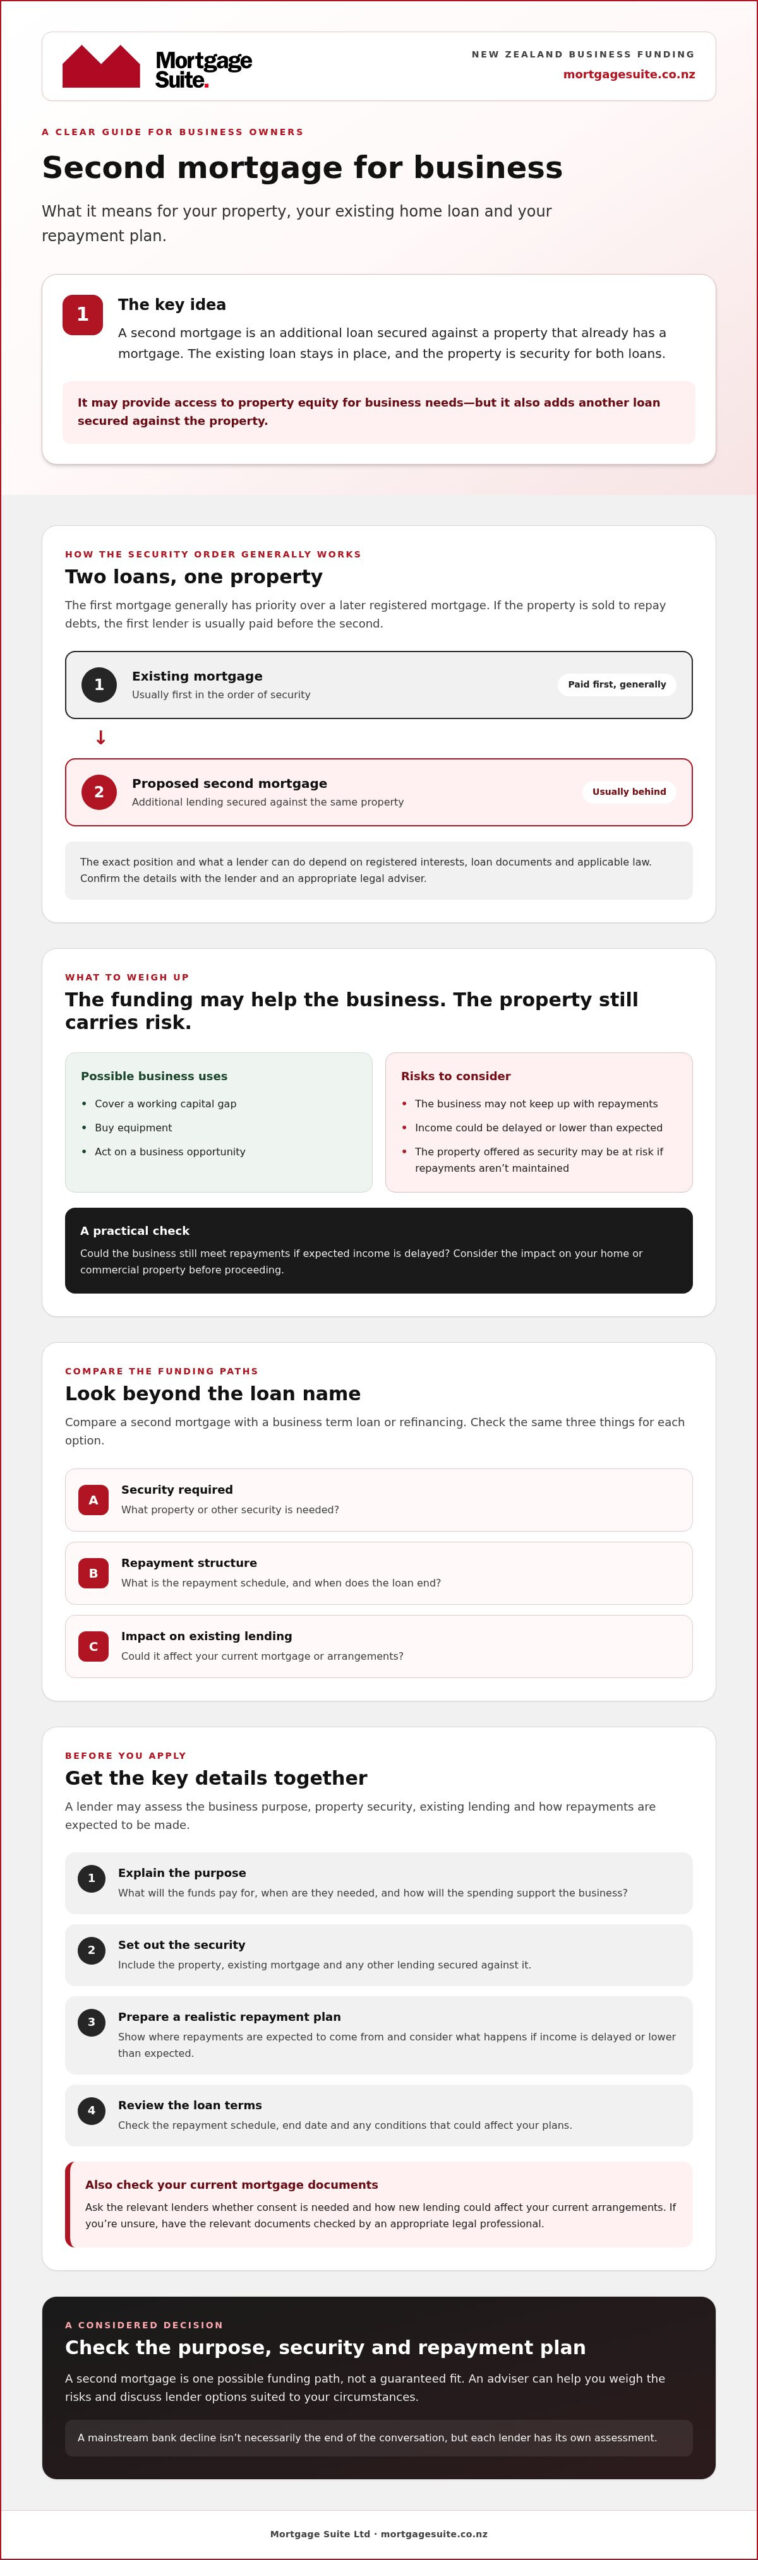
A second mortgage for business is an additional loan secured against property that already has a mortgage. The property could be a home or business property, and the funds are intended for business needs. The second mortgage sits behind the existing mortgage in the order of security. You can read a neutral overview of what a second mortgage is, then check how a particular lender would structure and secure the loan.

In general, the first mortgage has priority over a later registered mortgage. If the property had to be sold to repay debts, the first lender would usually be paid before the second mortgage lender. The exact position can depend on registered interests and the loan documents, so confirm the details with the lender and an appropriate legal adviser before proceeding.

Using the funds for a business doesn’t change the fact that the property is security for the loan. If repayments aren’t maintained, the property offered as security could be at risk. Weigh the business purpose against the possible impact on your home or commercial property, and consider whether the business could still meet repayments if expected income is delayed.

How does a second mortgage differ from a first mortgage?

A first mortgage is usually the main loan secured against a property. A second mortgage is separate lending added while that first mortgage remains in place. The second lender’s position behind the first may affect how it assesses the property, existing lending and available security. Ask how the proposed loan would be recorded and what could happen if repayments fall behind.

Don’t assume the order or enforcement process based on a general explanation alone. Ask the lender to explain its terms and have the relevant documents checked if you’re unsure.

What business needs might prompt this type of lending?

A business owner might explore a second mortgage to cover a working capital gap, buy equipment or act on a business opportunity. These are examples of possible purposes, not a promise that a lender will approve the application. The lender will consider what the funds are for alongside the property security and the borrower’s wider circumstances.

Business-purpose borrowing is different from a home loan taken out to buy or refinance a home, even if the home is offered as security. Be specific about how the funds will be used and where repayments are expected to come from. If a mainstream bank has declined, that isn’t necessarily the end of the conversation. Other lender pathways may be worth discussing, though each has its own assessment.

How does a business second mortgage work, and what is at risk?

Taking out a second mortgage involves more than showing that a property has equity. The lender needs to understand what the business will use the funds for, what property will secure the loan, how existing lending affects that security, and how repayments are expected to be made. Review the proposed terms carefully, including the repayment schedule and what happens if payments are missed.

When property secures business borrowing, the borrower remains responsible for repayments and the property may be at risk if they aren’t made. That’s true even when the loan is intended to support business growth rather than a personal purchase.

  • Explain the purpose: Be ready to describe what the funds will pay for, when they are needed and how the spending supports the business.
  • Review the security: Discuss the property, existing mortgage and any other lending secured against it.
  • Test the repayment plan: Consider how the business will meet repayments if income is delayed or lower than expected.
  • Check the terms: Ask about the repayment schedule, the loan’s end date and any conditions that could affect your plans.

How does the second mortgage sit alongside existing lending?

More than one loan can be secured against the same property. As a general guide, the first registered mortgage has priority over a later one. If the property is sold to repay debts, the first lender is generally paid before the second. The exact position and any steps a lender can take depend on the registered interests, loan documents and applicable law.

Check your existing mortgage documents and ask the relevant lenders whether consent is needed and how the new loan could affect your current arrangements. A qualified legal professional can explain the implications for your particular circumstances. Don’t rely on a general article to settle those details.

What happens if the business cannot keep up with repayments?

If repayments fall behind, arrears can build and the lender may take steps under the loan terms and applicable law. The outcome depends on the circumstances, so don’t assume every lender will respond in the same way. Because the property secures the borrowing, it could ultimately be at risk.

If repayment pressure appears, contact the lender or your adviser early to discuss the situation and possible next steps. For consumer credit, the Commerce Commission explains the transfer of responsibility for regulation of consumer credit. Whether a business-purpose loan falls under consumer credit rules depends on the circumstances, so confirm what applies to your loan.

If you’re weighing up a second mortgage for business NZ, Mortgage Suite can help you discuss the funding need and possible lender pathways. Its mortgage learning resources explain lending terms to help you prepare for a conversation.

Second mortgage vs business loan or refinance: which path fits?

The right option depends on what the business needs, whether property can be offered as security, your existing lending and how repayments could fit your cash flow. A second mortgage for business NZ is one path to discuss, but it isn’t automatically the best fit. Compare the security and repayment structure, the impact on current lending and the consequences of missed payments, not just the amount you may be able to borrow.

Option Security Common use Questions to ask
Second mortgage Property that already secures an existing mortgage. Seeking further business funds while keeping existing lending in place. How does it sit alongside the current mortgage? What property is at risk, and how will repayments work?
Business term loan Depends on the lender and loan terms. Ask whether property or other security is required. A business funding need with a lump sum and a defined repayment schedule and end date. What security is required? How often are repayments due, and when must the loan be repaid?
Refinance Usually involves new lending secured against property or other agreed security; confirm the proposed arrangement. Replacing or restructuring existing lending, often with a different deal or lender. What happens to the existing loan terms? Will the new structure meet the business need and repayment plan?

When might a second mortgage be worth exploring?

You might raise this option if you want to seek extra funds while keeping your current mortgage in place. That’s a discussion point, not a recommendation or a sign that you’ll qualify. Ask the lender to explain how the existing loan affects its assessment, and compare proposed repayments with the business’s expected cash flow. If a mainstream lender’s criteria don’t fit, the Mortgage School guide to lending options may provide further context.

When should you compare a business loan or Refinance instead?

Compare a business loan if you want to understand whether its security and repayment structure could suit your business without adding another mortgage to a property. Terms vary between lenders, so check the details rather than assuming the loan is unsecured. Refinance means replacing or restructuring existing lending, often with a different deal or lender. It may be worth comparing if you’re open to changing your current arrangement. Mortgage Suite can help you discuss business and commercial finance pathways, but the lender will assess your circumstances.

Before choosing, ask each lender to set out the security, repayment schedule, loan end date and implications for existing lending. Mortgage Suite’s Mortgage School learning resources offer plain-English explanations of lending terms to help you prepare those questions.

Second mortgage for business in NZ: how it works in 2026

How to prepare before applying for a business second mortgage

A clear application starts with a clear picture of the business need and how the loan could be repaid. Before discussing a second mortgage for business NZ, work through these steps:

  • Define the purpose: Set out what the funds would pay for and how the spending supports the business.
  • Gather your records: Collect current business accounts and income information, along with details of existing loans.
  • Review the property: Note which property may be offered as security and share relevant ownership or mortgage details.
  • Plan repayments: Map likely repayments against realistic business cash flow and consider how you’d manage if income changed.

Preparation helps a lender understand your request, but it doesn’t guarantee approval. The property, business income and lender criteria all need individual assessment. Accurate records make the discussion clearer, particularly if your income or business circumstances don’t fit a straightforward pattern.

What information should a business owner gather?

Start with up-to-date business accounts, income records and a short explanation of the funding purpose. Add details of current loans, repayments and any property you may offer as security. Be ready to explain how the business expects to use the funds and where repayments will come from. Requirements vary, so ask the lender or adviser for the exact document list before you apply.

Accuracy matters. If figures have changed or trading has been uneven, explain that rather than leaving gaps for the lender to interpret. A broker may help organise the information and discuss which lender pathways could suit your circumstances, though the lender makes its own assessment.

How can you test whether repayments are manageable?

Set out expected repayments alongside the business’s regular income and commitments. Allow for ordinary business needs, existing debt repayments and household commitments where relevant. Then test a less favourable scenario: what if a customer pays late, sales fall or an unexpected business expense arrives? If the plan only works when everything goes smoothly, revisit the amount or structure before proceeding.

The Mortgage Suite calculator may help with general repayment planning. It isn’t a quote or assessment for a business loan, so confirm actual terms and repayments with the lender.

For help discussing business funding needs and possible lending pathways, contact Mortgage Suite about business finance.

Choosing your next step with a New Zealand business finance adviser

Before moving ahead, check that the proposed borrowing matches a real business need and a repayment plan you can explain. Weigh up the security being offered, the risk to the property and alternatives such as a business loan or changing existing lending. A second mortgage for business NZ may be worth discussing, but the right path depends on your circumstances and the lender’s assessment.

An adviser can help organise the facts, present your situation clearly and discuss possible lender options. That support can be useful if your income or business history doesn’t fit a mainstream bank’s usual approach. But advice can’t guarantee a lender will make an offer, set particular terms or approve an application.

What should you ask before accepting an offer?

Take time to understand the offer before you commit. Ask which property secures the borrowing, how repayments are scheduled and when the loan ends. Make sure you understand the conditions and what the lender may do if repayments are missed. If any legal wording or implications are unclear, consider getting independent legal advice before signing.

Then compare the proposed structure with your business plan and other funding paths. Would the repayment plan still make sense if income is delayed? Does the loan solve the need you identified, or could another arrangement better fit your longer-term plans? Ask the lender to explain anything you’re unsure about.

How can Mortgage Suite help you assess possible pathways?

Mortgage Suite arranges business and commercial finance, as well as second-tier lending for situations that may not fit mainstream bank criteria. Its founder, Krish Krishna, has more than two decades of banking experience. A discussion can help you set out the funding purpose, existing lending and repayment plan, then consider which lender pathways may be worth exploring. Each lender makes its own assessment, so there’s no guaranteed outcome.

You can learn more about Mortgage Suite’s background and approach and read client reviews of Mortgage Suite as part of your research.

Before speaking with an adviser, it may help to have your funding purpose, current loan details and repayment plan to hand. You can then use the discussion to consider possible next steps without committing to proceed.

Make your next business funding decision with care

A second mortgage for business NZ may be one way to seek business funds, but it also puts property security and repayment commitments in the picture. Before proceeding, be clear about what the funds are for, how repayments could fit your business cash flow, and whether a business loan or refinance might better suit your needs.

Mortgage Suite facilitates business, commercial property and second-tier lending solutions, including for borrowers whose circumstances may not fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience to lending conversations. That experience can help you discuss your circumstances and possible lender pathways, but it can’t guarantee an offer, particular terms or approval.

If you’re ready to explore your options, talk through your business lending options with Mortgage Suite. A clear conversation can help you decide what to consider next, at a pace that feels right for you.

Frequently Asked Questions

What is a second mortgage for business in New Zealand?

A second mortgage for business in New Zealand is an additional loan secured against property that already has a mortgage. The property could be a home or business property, depending on the lender’s requirements. The existing mortgage generally has priority over the later one, but the details can depend on registered interests and loan documents. A second mortgage for business NZ still puts the property at risk if repayments aren’t maintained.

Can I use a second mortgage to fund my business?

Yes, a second mortgage may be used to fund a business purpose, such as working capital or a business opportunity, if a lender is willing to offer that structure. The lender will assess the purpose of the borrowing, the property offered as security and your circumstances, including how repayments are expected to be made. Using a home as security doesn’t make the borrowing a home loan, so ask the lender to explain the proposed terms.

Can I get a second mortgage if my bank has declined my business loan?

Possibly, but a bank decline doesn’t mean another lender will approve a second mortgage. Lenders may assess applications differently, and some specialist or second-tier lenders consider situations that don’t fit mainstream bank criteria. They’ll still assess the security, business purpose, repayment plan and your wider circumstances. A finance adviser can help you understand potential lender pathways, but can’t promise an offer or approval.

What property can be used as security for a business second mortgage?

A lender may consider residential or business property, but the type of property it accepts depends on its criteria and the details of the application. Existing mortgages and other claims registered against the property can affect the assessment. Before applying, gather information about the property and current lending, then ask the lender whether it may be acceptable security and whether any existing lender’s consent is needed.

Is a second mortgage riskier than a business loan?

It depends on the security and terms of each option. A second mortgage is secured against property, so missed repayments could put that property at risk. A business loan may have a different security arrangement, but it isn’t automatically unsecured or lower-risk. Compare the repayment schedule, loan end date, security and consequences of missed payments for each offer, and consider how the structure fits your business plan.

How much can I borrow with a second mortgage for business?

There’s no set amount that applies to every borrower. A lender will assess the property and existing lending, the business’s financial position, the requested purpose and its own criteria. The amount offered, if any, will depend on that individual assessment. Prepare accurate business income records and details of current loans, then ask the lender to explain how it arrived at any proposed amount and repayment terms.

What happens if I cannot repay a business second mortgage?

If you can’t make repayments, contact the lender as early as possible and explain what’s changed. Missed payments may lead to arrears and other steps under the loan terms and applicable rules. Because the loan is secured against property, that property could ultimately be at risk. Ask the lender or an adviser about your options and seek independent legal advice if you’re unsure what the loan documents mean.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Conquer Your Fear of Buying a House in 2026

Entering the New Zealand property market in 2026 does not require guessing the absolute bottom of the interest rate cycle. Securing a competitive fixed interest rate and passing a lender’s serviceability stress test are far more critical to long-term affordability than timing month-to-month price fluctuations. Working with Mortgage Suite gives you a supportive advocate to get sorted and find the right path forward.

Key Takeaways: Buying in 2026 is viable if you pass serviceability stress tests, as waiting for rate drops often triggers price competition that offsets interest savings.

  • U.S. Census construction data indicates supply cycles influence affordability more than short-term interest rate fluctuations.
  • Delaying purchase is only recommended if your current budget cannot comfortably pass a lender’s hypothetical higher-rate serviceability test.
  • The article details how clearing buy-now-pay-later debt increases borrowing power more effectively than saving a slightly larger deposit.

Match Your 2026 Buyer Profile to the Right Mortgage Path

Your financial situation dictates your property strategy in 2026, and naming your profile early stops you from applying to the wrong lender first. Buyers we work with usually sit in one of three paths; pick the one that sounds like your week-to-week reality and act on the matching step:

  • First-home buyer with a tight deposit: major banks apply strict Loan-to-Value limits, so get an adviser involved early and secure pre-approval before you bid.
  • Self-employed borrower or contractor: variable income often slows standard bank managers; a contractor home loan through a non-bank lender gives you practical flexibility.
  • Investor relying on equity: you must pass a strict serviceability stress test before you purchase; a mainstream bank decline is common and does not end the journey.

Working with an adviser gives everyday Kiwis a fair go to get sorted without taking unnecessary risk. You can explore buying options with guidance matched to your profile.

Our team acts as your dedicated negotiator and pairs your situation with the right lender. Book a free chat when you want that match made clear.

Waiting on 2026 Rate Cuts Can Cost You More Than You Save

Holding out for a cheaper fixed interest rate sounds tidy on paper, yet timing the full interest-rate cycle remains difficult for property buyers, and the wait often costs more than the repayment saving.

Through daily advisory work we see cheaper money get offset by climbing property values. Holding off for lower fixed interest rates (an interest rate that remains unchanged for an agreed period) turns counterproductive when market appreciation outpaces what you save on repayments. Supply metrics shape those broader shifts; U.S. Census construction data shows how residential building trends track changing economic supply cycles globally, a pattern worth watching even from New Zealand.

First-time purchasers who need budget certainty may still prefer to delay until their own figures line up. Investors chasing capital growth often secure a place earlier, because delay means missing potential gain while bank decisions drag. Mainstream bank hurdles do not mean you cannot move forward.

We act as your dedicated personal advocate and structure finance that keeps your options flexible. Get sorted on buying in NZ with a plan built around today’s serviceability numbers rather than a guessed future rate. Map your next steps in a friendly chat with the team when you are ready.

Buy Now or Wait: How Rate Drops Fuel Price Competition

Timing the market to the week is nearly impossible, and waiting for interest rates to drop carries hidden financial risk you feel only after prices have already moved.

Buyers who freeze their search often watch real estate prices jump as soon as credit terms loosen. When interest rates fall, buyer competition heats up, sale figures rise, and the mortgage saving you hoped for gets erased. Purchasing now lets you secure a property before that spike, provided your budget comfortably passes a serviceability stress test (a hypothetical repayment assessment using a higher interest rate to test future affordability).

Postponing a deal for a lower rate can force you into a much larger total mortgage if home prices lift while you wait.

Market Strategy Financial Impact Future Outlook
Buying early Secures property before value growth Refinance potential when rates ease
Waiting for rate drops Lower initial mortgage repayments Higher purchase prices due to buyer competition

If you are navigating the decision on your own, solo buying guidance sets out clear borrowing options. Getting your finance sorted early means you can act when the right place appears. Reach out when you want a dedicated negotiator in your corner.

Fresh Home Building Eases Price Pressure for Kiwi Buyers

New supply is one of the few forces that genuinely eases long-term price pressure, and you feel it first as wider choice rather than as a headline rate cut.

From client work we see buyers gain breathing room when developers finish large-scale land subdivisions. Fresh sections give Kiwis a fair go by broadening choices and cooling aggressive bidding wars. Picture a busy restaurant: when extra tables open, nobody needs to tip the host just to get seated. Sustained inventory growth tends to slow rapid cost increases over time, though that supply still takes seasons to arrive.

More builds also ease rents as tenants move into new stock, which can help you save a deposit faster. If you hold commercial assets, this commercial refinancing guide sets out ways to free capital for a residential move.

When your bank manager seems hesitant, alternative lenders offer clear paths. Newly built homes suit first-home hunters who want modern insulation; existing builds suit buyers who need immediate possession. Talk to Mortgage Suite when you want those options laid out against your deposit and income.

Conquer Your Fear of Buying a House in 2026

When Delaying Property Purchase Works Against You

Sitting on the sidelines in 2026 can cost you more than time, because the market keeps moving while your deposit sits still.

In client work we see buyers waiting for lower interest rates get caught off guard as property values lift. Holding off backfires when underlying forces keep pushing even though you have not signed a thing.

Think of standing beside a moving escalator: demographic demand keeps climbing. Population growth and changing household structures mean more people compete for a finite number of homes. At the same time, the mortgage lock-in effect keeps current owners from selling. Existing owners hold older, low-rate loans, which thins listings across New Zealand. Lower supply plus steady population growth puts upward pressure on prices.

Buying sooner lets you start building equity while you secure the home you will live in. Mainstream banks may seem hesitant today, yet an initial decline is not the end of your journey. Mortgage Suite acts as your personal advocate and negotiates flexible lending that fits your goals. Ask for a chat when you want that path scoped properly.

5 Steps That Make Your 2026 Mortgage Application Lender-Ready

Getting your finances audit-ready now changes how lenders read your file in 2026. Early preparation turns a tense bank meeting into a straightforward approval conversation and helps mainstream lenders see you as lower risk.

Clearing small buy-now-pay-later balances can lift your borrowing power more than saving a modest extra deposit, because serviceability looks at monthly outgoings first.

Follow these steps to get sorted:

  1. Clean up short-term debt: Pay off personal loans and store cards to lower your monthly outgoings.
  2. Review your spending: Track daily expenses for three months to prove strong money management habits.
  3. Test your budget: Practice making repayments under a hypothetical serviceability stress test to check affordability.
  4. Gather account records: Collect certified accounts and recent bank statements to show stable earnings.
  5. Consult an adviser: Partner with Mortgage Suite to negotiate tailored terms across multiple bank options.

Tip: Getting your mortgage pre-approval sorted early ensures you understand your true borrowing capacity under current serviceability stress test standards.

Long-term confidence comes from having an experienced guide in your corner. One Google review of Mortgage Suite Ltd from Baycom (5★) shows the arc clearly: a household bought five properties over more than twenty years with the same broker, through purchases, and ongoing advice, and still recommends the firm.

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

That span of successful property work is what a steady adviser relationship can look like when you stay organised.

4 Loan Structures That Cut Your Interest Without Waiting on the Market

Smart loan structuring gives you direct control over interest charges without waiting for the wider market to move. Choosing an offset account trims daily interest by matching your cash balance against the mortgage, keeps funds accessible for unexpected costs, and lowers the interest you pay over time.

A fixed interest rate protects your household budget by locking exact repayment amounts for a set timeframe. Splitting the loan between fixed and floating portions adds flexibility, so you can clear extra debt quickly without early-repayment penalties.

Lenders also run a serviceability stress test to check your position at higher hypothetical rates. Passing that test often means cleaning up short-term debts or adjusting credit limits first.

Structuring finance is a balancing act around your real cashflow. Mortgage Suite acts as your dedicated negotiator and secures options that fit how you actually earn and spend. If you worry that restructuring will swallow your week, the team manages the process so you can get sorted without the run-around. Tell us your goals and we will walk the numbers with you.

Frequently Asked Questions

Why are home prices so high?

Strict land use rules, high building material costs, and strong population growth keep housing supply tight across New Zealand. Long-term supply shortages mean property values stay elevated even when interest rates move up or down.

Will mortgage rates drop in 2026 or 2027?

Wholesale interest rates point to possible easing, yet fixed interest rate changes depend on inflation and central bank policy. Lenders reprice as economic conditions shift, so treat any forecast as a guide rather than a promise.

Is now a good time to buy a house?

Buying works well when your household budget is stable and you secure structured financing that fits your goals. You move faster by focusing on long-term affordability rather than trying to pick the exact month rates bottom out.

Will mortgage rates drop in 2026?

Economic forecasters expect borrowing costs to stabilise, though sudden market shifts can still alter the path. A clear view of your own financial position helps you manage whatever rate movement arrives.

Is it better to buy a home now or wait for lower rates?

Waiting for lower rates can mean heavier buyer competition later, which often pushes purchase prices up. Securing a fair go now with a flexible loan structure gives you confidence whether rates ease or hold.

Overcoming the fear of buying a house in 2026

Feeling nervous about home ownership right now is normal. Strict bank tests and changing deposit rules make the path feel heavier than it needs to be, especially when headlines keep arguing about the perfect month to jump.

You do not have to handle the banks on your own. The same through-line that opened this guide still holds: a competitive fixed rate and a clean pass on the serviceability stress test matter more than calling the bottom of the cycle, and a dedicated advocate keeps those two pieces in view. The team at Mortgage Suite Ltd negotiates directly with main banks and non-bank lenders to give you a fair go. A simple decline from one mainstream lender does not mean your home-ownership plan is over.

Ready for the next step? Get sorted with your 2026 home buyer pre-approval today by booking a friendly, no-obligation chat with our mortgage advisers. More on this: Buying a House Archives.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

Your final home loan cap in New Zealand rests on bank serviceability tests and debt-to-income caps, not on a headline rate alone. Before you chase a listing, you need clear answers to three linked questions: how much a lender will fund against your income, how large a deposit you must show, and whether stretching to the edge of that limit still leaves you room to live. Work through those decision points in order and you avoid months of mismatched applications.

Key Takeaways: Your maximum mortgage borrowing in NZ is generally capped at six times your gross income under 2024 debt-to-income (DTI) limits and bank serviceability tests.

  • Lenders apply a serviceability stress rate of 8.5% or higher to test your repayment capacity.
  • Except when buying new builds, most mainstream banks require a 20% deposit for existing properties.
  • Therefore, first-home buyers should target the Kāinga Ora 5% deposit scheme if savings are modest.
  • Boarder income can boost eligibility but banks typically apply a 20% to 50% safety haircut.

Match your NZ borrower category before you apply

Banks do not treat every earner the same way, so the first useful step is naming the file type you will present.

  • Self-employed contractor: put certified accounts or tax returns in order early; lenders want proof of stable income before they discuss a figure.
  • Investor balancing several properties: map equity and Loan-to-Value limits across the portfolio so one highly geared title does not drag the whole application down.

Your home loan capacity depends mostly on that borrowing group. A contractor home loan is assessed very differently from a standard wage earner’s file, and criteria shift with how you earn. Naming your real category early helps you avoid mainstream declines that simply mean the file sat in the wrong queue. If you want local guidance, the team at Mortgage Suite negotiates directly with lenders as your supportive advocate. Book a short chat when you are ready to place your file in the right path.

How lenders set the figure you can actually borrow

Lenders build your borrowing power by subtracting living costs and debt commitments from total gross household income, then testing the remainder at a higher serviceability rate. They are not only looking at today’s fixed rate; they want proof you can still meet repayments if rates rise. Existing personal loans tighten debt-to-income scaling and shrink the final limit, and each bank treats board income, overtime, and living costs differently.

Tailored packaging is what secures approval. A decline from your main bank usually means your setup did not match that bank’s formula, not that you are locked out of the market. We act as your personal negotiator so the right lender sees your true financial strength. You can browse notes on borrowing power for more on how assessments differ, then book a friendly review of your own numbers when you want a concrete figure.

Deposit size that unlocks mainstream and low-deposit paths

Most New Zealand banks prefer a 20% equity safety net on existing property. Saving that sum is hard work, and standard Loan-to-Value settings limit how much high-ratio lending mainstream lenders will book. Low-deposit routes still exist. You may need only a 10% cash cushion if you meet targeted criteria, and eligible first-home buyers can secure funding with a 5% deposit through the Kāinga Ora 2026 First Home Loan programme.

Building a new home often sits outside the usual equity caps, which is why some buyers find construction finance more reachable than a second-hand purchase at the same price point. A decline from one bank manager is not the end of a homeownership plan; clear alternative pathways still reach lenders when the file is presented well. The Mortgage Suite team can walk through your deposit options in a no-obligation chat.

Tip: Check whether your prospective flat triggers the small-unit rule, as lenders may demand a higher deposit percentage.

2024 DTI limits cap your max borrowing capacity

New Reserve Bank settings restrict a home loan to six times your gross income. High earners who already carry personal debts feel the pinch first, because every store card or car loan consumes servicing space before the mortgage is even typed in. Picture your borrowing limit as a bucket: existing debt fills it before mortgage funding gets a turn.

These caps are designed to keep household debt manageable, even when they frustrate a purchase timeline. A bank decline on DTI grounds is still not the end of the path. As dedicated negotiators, we review alternative funding structures when the first formula falls short. Client stories on our testimonials page show how tightly packaged applications move through complex criteria.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Situation: a household already holding several properties needed fresh funding of $200,000 under tighter income caps. Solution: long-running advice and responsive packaging across purchases. Result: five properties settled over two decades with the same adviser relationship intact. An experienced adviser helps you read strict lending caps without giving up a sound long-term plan.

How flatmate rent can lift your borrowing capacity

Boarder income can raise overall borrowing capacity, yet mainstream banks usually count only a portion of it. Lenders apply a safety haircut so vacancy does not break the file; current market practice is a 20% to 50% discount when that cashflow enters the debt-to-income maths. Banks also run boarder payments through the higher serviceability stress rate, so the boost is real but smaller than the raw rent total.

Taking in flatmates remains a practical move for a single buyer who needs extra servicing room on a first purchase. If assessors will not accept your full boarder figure, negotiation with other lenders is the next step rather than abandoning the income line altogether. We put that case directly to the credit desk when the first pass looks too thin.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

Serviceability stress tests cut what you can bid

Banks set your maximum borrowing limit with a serviceability stress test: a hypothetical repayment check at a higher interest rate to probe future affordability. Real fixed rates matter less inside the calculator than those test rates. When actual fixed rates sit well below the test rate, the bank still judges your income against the steeper threshold, and that gap trims the price you can bid.

Assessment Type Typical Interest Rate Impact on Affordability
Actual Fixed Rate Current market level Sets actual monthly repayments
Bank Stress Rate 8.5%+ Reduces calculated borrowing cap

Test rates can penalise higher incomes harder than you expect, because the same loading is applied across the board. If the stress figure leaves your shortlist out of reach, flexible non-bank or second-tier structures are worth comparing before you rewrite your property brief. Mortgage Suite acts as your personal advocate when you need that comparison done without sales pressure.

Paperwork that speeds your pre-approval

Organised files move lender assessments faster, and gathering paperwork early removes a common source of delay. Treat the pack like a road-trip checklist: one missing item stalls the whole trip.

  1. Verify income: recent payslips, or certified accounts if you are self-employed.
  2. Show savings: bank statements that prove deposit funds and a genuine savings history.
  3. List debts: a clear debt-to-income summary, including credit cards.
  4. Detail living costs: an accurate monthly household expense breakdown for the lender.

A contractor home loan usually needs two years of trading history or current contracts on the desk. Mainstream hurdles do not have to stop the process when the file is complete and directed to a lender that accepts your income type. Reach out for a confidential chat when you want a second pair of eyes on the pack before you submit.

When stretching your borrowing limit is a bad move

Maxing out mortgage potential leaves little shield against rate rises or sudden lifestyle bills. Squeezing every last dollar from an assessment often backfires once the unexpected lands. A buffer is what keeps the household steady when life shifts.

Treat the limit like a rubber band: pull it to the edge and any extra tension snaps the budget. Passing a serviceability stress test shows you can pay on today’s assumptions; it does not price future cost spikes. Borrowing below your theoretical maximum is often the steadier choice if you want sleep at night as well as keys in the door. If the numbers feel tight, ask us to model a safer cap before you sign a sale and purchase.

Secure your pre-approval with non-bank options

A bank decline is rarely the end of a property plan. Alternative lenders supply a useful safety margin when mainstream credit policy says no. Non-bank institutions often apply more flexible criteria for complex income or smaller deposits, and they look past a single computer scoreboard.

Use that path as a springboard when you need short-term flexibility, then refinance later if your profile fits a bank book. At Mortgage Suite we act as your dedicated advocate through pre-approval and drawdown, so the credit story stays consistent from first call to settlement. Contact the team for a confidential chat when you want those options laid out side by side.

Frequently asked questions

How much can you afford to repay?

Your affordable repayment depends on total household income, living expenses, and current personal debts. Lenders review day-to-day spending to confirm enough remains for ordinary life after the mortgage leaves the account. We help you line those figures up so the repayment you offer is one you can sustain.

How much will a bank lend on a property?

Banks set a maximum by running a serviceability stress test across income and expenses, using a higher test interest rate to guard against future increases. They also apply debt-to-income caps to the overall funding total. If one bank declines, our team compares alternative lenders that read the same numbers under different policy settings.

How much of my income can go to mortgage repayments?

Most lenders prefer home loan repayments at no more than 30–35% of gross income. Staying inside that band leaves room for bills you cannot defer. Each bank weights household size slightly differently, so a short adviser conversation clarifies where your file sits.

What percentage of a property’s value can banks lend?

Banks usually lend up to 80% of value on owner-occupied homes under standard Loan-to-Value settings. First-home buyers with smaller deposits can sometimes borrow a higher share when they meet low-deposit criteria. A smaller flat may attract a higher deposit demand under small-unit policy. We can test your case across more than one lender credit desk.

What is a minimum surplus or UMI and how much is needed?

Uncommitted Monthly Income is the cash left after bills, living costs, and loan repayments. Lenders want a positive surplus buffer, often $1,000 each month, as evidence you can absorb a surprise expense. Mortgage Suite works with lenders to present that surplus clearly so the buffer you actually run is the one on the page.

Getting sorted with your home loan

Working out how much you can borrow for a mortgage across NZ starts with the same three decision points you met at the top: servicing capacity, deposit path, and whether the limit you are offered still leaves a liveable buffer under debt-to-income and stress-test rules.

Mainstream criteria can feel opaque, and a decline is rarely the end of your options in 2026. Mortgage Suite Ltd advisers act as your personal advocate, comparing non-bank alternatives and negotiating structure when the first formula does not fit. If you want clarity on your borrowing capacity, contact the team for expert mortgage advice.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

You’ve spent months searching for the right property, only to have your long-term bank turn you down at the final hurdle. It’s a frustrating, anxious experience that makes you feel like the system is working against you, especially with the strict debt-to-income rules currently in play. If you’re wondering what to do when bank declines mortgage nz, the first thing to remember is that a “no” from a mainstream lender isn’t the end of your journey. It’s often just a sign that you need a more flexible, expert approach to get the deal across the line.

We understand the sting of being rejected by a bank you’ve been loyal to for years. This guide shows you how to turn that setback into a successful purchase by using 2nd tier lenders as a strategic bridge. You’ll learn how these specialist providers work outside the rigid boxes of traditional banks and why a smart exit strategy is your ticket back to mainstream rates in a year or two. We’ll walk through the 2026 market conditions and give you a clear, professional plan to secure your loan and move into your new home with confidence.

Key Takeaways

  • A rejection from a main bank doesn’t mean your home-buying dreams are over; it’s simply a signal to switch to a more flexible 2nd tier lender.
  • Discover exactly what to do when bank declines mortgage nz by shifting the focus to your unique “borrower story” and long-term potential.
  • Learn why matching your specific financial situation to a specialist lender’s unique criteria is the secret to turning a decline into an approval.
  • Get a clear view of the temporary costs involved and how these non-bank options serve as a vital bridge to your property goals.
  • Master the exit strategy that allows you to “graduate” back to a mainstream bank within 12 to 24 months once your situation has stabilised.

What is a 2nd Tier Loan and Why is it Your Best Plan B?

Getting a “no” from a main bank feels like a dead end, but in the New Zealand property market, it’s often just the start of a different conversation. Most people are taught that if the big four banks won’t help, nobody will. That isn’t true. A 2nd tier loan is a flexible, regulated alternative for unique financial situations. These lenders operate differently from the high-street names you see in every shopping centre. They provide a vital path forward when you’re figuring out what to do when bank declines mortgage nz.

Second-tier lenders are often called “non-bank” lenders. They don’t take deposits from the public like a traditional bank does. Instead, they raise their own capital to lend out. Because they aren’t bound by the same rigid internal rules as the main banks, they can look at your application with much more nuance. They are specialists in finding ways to say “yes” when a computer algorithm at a main bank has already said “no”.

The Difference Between Main Banks and Alternative Lenders

Main banks are designed for efficiency. They love “perfect” applications where every piece of data fits into a pre-defined box. If you’re self-employed with a fluctuating income, or if you have a slightly smaller deposit than the current 2026 regulations prefer, you might not fit that box. This is where a non-bank financial institution shines. They take the time to look at your whole story rather than just your credit score.

Speed is another major factor. While a main bank might take weeks to process a complex application, alternative lenders are often much faster. They understand that property deals move quickly and that you can’t afford to wait. The trade-off is usually a slightly higher interest rate or different fee structure, but for many Kiwis, this is a small price to pay to secure a home in a competitive market. To understand how these different options affect your long-term plans, you can explore the resources in our mortgage school.

Dispelling the Myths About Non-Bank Lending

There’s a common misconception that anything outside a main bank is risky or untrustworthy. It’s time to clear that up. These lenders are reputable, highly regulated businesses that must follow the same consumer protection laws as any other financial provider. They aren’t “loan sharks”; they are professional advocates for borrowers who need a bit more flexibility.

Think of a 2nd tier loan as a strategic stepping stone. It isn’t necessarily a thirty-year commitment. Instead, it’s a way to get into the market now, build equity, and prove your reliability. By the time you’ve held the loan for a year or two, you’ll often be in a much stronger position to “graduate” back to a main bank. Knowing what to do when bank declines mortgage nz often starts with embracing this tactical “Plan B” to keep your home-ownership goals on track.

How to Prepare Your 2nd Tier Loan Application

Preparing for a non-bank application is quite different from a standard bank meeting. It’s about building a comprehensive case for yourself. When you’re stuck on what to do when bank declines mortgage nz, your first move should be gathering every detail of your financial life, even the bits you’re worried about. Being upfront is your greatest asset in this process. If there’s a skeleton in the closet, it’s better to bring it out now rather than let a lender find it later. 2nd tier lenders invest in people and their potential, not just a credit score, so they value transparency and a clear plan over a perfect history.

The Essential Paperwork You Will Need to Organise

You’ll need to look beyond the standard documents a main bank asks for. If you’re self-employed, gather your full financial accounts and tax returns for the last two years. Lenders want to see the real-world consistency of your earnings, even if they don’t fit a standard salary pattern. If you’ve had a credit hiccup in the past, get a copy of your credit report and prepare a brief, honest note explaining the circumstances. These lenders are professional, regulated, and often belong to independent dispute resolution bodies, which ensures you’re treated with fairness throughout the application. You should also have the specific details of the property you’re eyeing ready, as the type of dwelling often impacts the lender’s risk assessment.

Telling Your Story to the Lender

This is where you move beyond the columns of a spreadsheet. A main bank might see a dip in your income from eighteen months ago and decline you without a second thought. A 2nd tier lender will listen if you explain that the dip was a one-off event, such as a temporary illness or a strategic business pivot. You need to show them that your plan for future financial stability is robust and well-thought-out. This is exactly why having a veteran negotiator on your side is a game-changer. We know how to “translate” your unique life situation into the specific language that non-bank lenders understand. If you’re ready to start building your case and want to work with a partner who knows the system, you can learn more about us and how we advocate for our clients. Knowing what to do when bank declines mortgage nz is all about presenting your future potential as clearly as your financial past.

Choosing the Right Lender for Your Specific Situation

Every non-bank lender in New Zealand has its own “personality” and set of rules. Unlike the main banks, which all tend to follow very similar guidelines, 2nd tier lenders often specialise in specific types of borrowers. One might have a high appetite for helping people buy existing family homes with smaller deposits, while another might focus almost entirely on business owners with complex tax structures. Finding what to do when bank declines mortgage nz often comes down to knowing which of these hundreds of options is the right fit for your specific hurdle.

The challenge for most Kiwis is that these lenders don’t usually advertise on television or have branches on the high street. They work primarily through specialist brokers who understand their unique criteria. Matching your situation to the right lender is a bit like solving a puzzle. It requires a deep understanding of how each provider views risk and what kind of “borrower story” they find most compelling. This is where Mortgage Suite Ltd and our 20-plus years of expertise become your biggest advantage, as we know exactly which door to knock on to get your deal across the line.

Lenders Who Favour the Self-Employed

If you run your own business, you’ve likely discovered that main banks struggle with income that isn’t a steady, fortnightly salary. Many 2nd tier lenders were built specifically to solve this problem. They offer what we call “low-doc” options. In plain English, this simply means they use alternative ways to verify your income, such as looking at your business bank statements or a simple letter from your accountant, rather than demanding years of perfect tax returns. They focus on your current ability to manage repayments and the overall health of your business, giving you the credit you deserve for your hard work.

Options for Credit Hiccups or Smaller Deposits

A past financial setback or a deposit that doesn’t quite hit the 20 per cent mark for an existing home can lead to an instant decline from a main bank. However, some lenders specialise in “recovery” loans. They look at your “risk grade”-a professional assessment of your current reliability-and offer a path forward even if your history isn’t spotless. Unlike some competitors who suggest that new builds are the only way to buy with a small deposit, we find lenders who are happy to support you in buying an existing property. These loans act as a vital bridge, allowing you to secure your home now while you work on improving your financial position for the future.

Knowing what to do when bank declines mortgage nz is about looking beyond the surface and finding a partner who sees the value in your specific situation. With the right lender, that initial rejection becomes nothing more than a temporary detour on your way to home ownership.

What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

Understanding the Costs: Rates, Fees, and the “Opportunity Cost”

When you’re trying to figure out what to do when bank declines mortgage nz, the numbers on the page can feel a bit heavy. It’s true that 2nd tier lenders charge higher interest rates than the main banks. This is because they’re taking on more risk by looking at applications that don’t fit the standard criteria. However, it’s vital to view these costs as a tactical investment rather than a permanent burden. You can use our Mortgage Calculator to see how these different rates look in reality and how they might fit into your monthly budget.

Interest Rates vs. The Cost of Missing Out

The real question isn’t just “how much is the interest?” but “how much will it cost me to wait?”. With inflation currently sitting at 3 per cent and the property market constantly shifting, staying on the sidelines can be expensive. If house prices rise while you’re spending another year or two saving for a larger deposit, you might find yourself priced out of the very suburb you want to live in. Most of our clients don’t stay on a 2nd tier rate forever. We view these loans as a 12-to-24-month bridge. When you calculate the “real” cost over this short period, the extra interest is often far less than the potential growth in your home’s value during that same time.

Think of it as a temporary premium for speed and flexibility. By getting into the market now, you start building equity immediately. You’re no longer paying rent to someone else, and you’re finally on the property ladder. This strategic move allows you to “graduate” back to a main bank once your financial situation has stabilised or you’ve proven your repayment history to the wider market.

Upfront Fees and Budgeting

Beyond the interest rate, you’ll need to budget for specific upfront costs. These typically include establishment or application fees, which cover the intensive manual assessment required for alternative lending. You’ll also need to factor in valuation reports from approved professionals and legal costs that might be slightly higher due to the complexity of the contracts. It’s also worth checking the early exit terms. Since the goal is to move back to a main bank as soon as possible, you want to ensure your loan structure allows for that transition without heavy penalties. If you want a clear, honest breakdown of how these costs apply to your situation, get in touch with us today for a professional assessment. We’re here to ensure there are no surprises on your journey to home ownership.

The Exit Strategy: How to Move Back to a Main Bank

Securing a 2nd tier loan is a massive win, but it’s rarely the final stop on your home ownership journey. We always encourage our clients to view this as a temporary bridge rather than a thirty-year commitment. The goal is simple: use this period to stabilise your finances and build a solid track record. When you’re considering what to do when bank declines mortgage nz, the long-term plan is just as important as the immediate approval. We work with you to set a clear 12-to-24-month target to “graduate” back to a main bank, where you can access lower interest rates and standard terms.

Cleaning Up Your Financial Profile

Your time with a 2nd tier lender is your chance to prove to the main banks that you’re a reliable borrower. The most critical factor here is maintaining a perfect repayment history. Every single payment on your new loan must be on time, without exception. This shows future lenders that your previous credit hiccup is firmly in the past. At the same time, focus on reducing other liabilities. Paying down credit cards or clearing car finance can significantly improve your debt-to-income ratio, which is a key metric for banks in 2026. If you’re a first-time owner, our Home Loans for First Home Buyers Guide offers deeper insights into how these factors influence bank decisions.

Don’t forget that as property values potentially grow, your equity increases. A higher equity position naturally lowers the bank’s risk, making it much easier to qualify for those competitive rates you missed out on initially. We’ll keep an eye on the market with you to identify the best moment to make your move.

Working with Your Broker on the Move

You shouldn’t wait until your fixed term is nearly over to start thinking about the switch. We usually begin the conversation about six months before your target graduation date. This gives us enough time to review your polished profile and identify any final adjustments needed. Re-applying with a year of perfect mortgage history and a cleaner debt profile allows you to walk into a main bank with genuine confidence. We don’t just secure your first loan and disappear; we stay with you for the whole journey. Our reputation is built on these long-term partnerships, helping Kiwis navigate what to do when bank declines mortgage nz and eventually seeing them successfully refinance into the mainstream banking system.

Take the Next Step Toward Your New Home

A bank decline is often just a nudge toward a more flexible path. By choosing a 2nd tier loan as a strategic bridge, you can secure your property now and build a solid foundation for a future return to a main bank. Knowing what to do when bank declines mortgage nz means looking past the initial rejection and focusing on your long-term potential. We’ve seen how a clear exit strategy and professional advocacy can transform an anxious situation into a successful purchase.

With over 20 years of expert banking and brokerage experience, we specialise in finding “outside the box” lending solutions that the big banks often ignore. You can read our client reviews to see how we’ve helped other Kiwis succeed where they once felt stuck. If you’re ready to move forward, book a friendly chat with Mortgage Suite to find your path forward. Your home ownership goals are still within reach, and we’re here to help you navigate the system with confidence.

Frequently Asked Questions

Is it harder to get a 2nd tier loan than a main bank loan?

Getting a 2nd tier loan is often more straightforward than a main bank loan because these lenders have more flexible criteria. While main banks rely on rigid “yes” or “no” computer models, alternative lenders take a manual approach to understand your whole financial story. They are specialists in finding ways to approve applications that don’t fit the standard box, making them a reliable path when you’re stuck on what to do when bank declines mortgage nz.

Can I still get a home loan if I have a bad credit history?

You can absolutely secure a home loan with a less-than-perfect credit history by working with a specialist non-bank lender. These providers are designed to help borrowers who have had past financial setbacks. Instead of a flat rejection, they look at your current stability and your plan for the future. They assess the “risk grade” of your application and offer a loan structure that reflects your specific recovery journey, helping you move forward with confidence.

What are the typical interest rates for non-bank lenders in 2026?

In the 2026 market, interest rates for non-bank lenders vary based on your specific situation. For “near-prime” borrowers with good credit, rates are typically 1 to 2 per cent higher than mainstream bank rates. If your application is more complex or involves significant credit issues, specialist rates can range between 10 per cent and 14.5 per cent. These higher rates reflect the extra risk the lender takes on to help you get into the property market.

How long does the 2nd tier loan application process take?

The application process with a 2nd tier lender is often significantly faster than a main bank, sometimes taking just a few days for an initial approval. Because these lenders aren’t bogged down by the same massive institutional layers, they can make decisions quickly once they have your full paperwork. This speed is a huge advantage when you’re competing for a property and need a clear answer on what to do when bank declines mortgage nz.

Do I really need a mortgage broker to access these lenders?

While you can technically approach some lenders yourself, most 2nd tier providers in New Zealand deal exclusively through professional mortgage brokers. A broker acts as your advocate, translating your “borrower story” into the specific format these lenders require. We have access to hundreds of different criteria sets and know exactly which specialist provider is most likely to say yes to your unique situation, saving you time and protecting your credit score.

What happens if I want to pay off my 2nd tier loan earlier than planned?

You can pay off your 2nd tier loan early, but you should always check the specific terms for early exit fees. Since these loans are often intended as a temporary bridge, many are structured with flexibility in mind. However, some lenders include a minimum term or a set fee to cover their setup costs. We ensure you understand these details upfront so your plan to move back to a bank remains cost-effective and clear.

Will a 2nd tier loan affect my ability to get a bank loan later?

Holding a 2nd tier loan actually strengthens your future bank application, provided you maintain a perfect repayment history. Successfully managing a non-bank loan proves to mainstream lenders that you are a reliable, low-risk borrower. This track record is exactly what banks look for when they consider taking you back. It serves as a professional “graduation” certificate that demonstrates your financial stability has been fully restored after your initial hurdle.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

You’ve spent months scouring listings and finally found a place to call your own, only for your bank to decline your application because your income isn’t “traditional” or your deposit is a bit light. It feels like a total dead end, but a “no” from a mainstream bank is often just the start of a different conversation. Many people assume that non bank lenders nz home loans are a last resort for those in financial trouble, but in 2026, they’ve become a tactical tool for savvy Kiwis who simply don’t fit a rigid, standard box.

It’s completely normal to feel a bit nervous about looking beyond the big household names, especially if you’re worried about higher interest rates or confusing terms. We understand that you want a clear path to home ownership without the stress of being treated like a number. This guide is designed to strip away the mystery and show you exactly how these alternatives work, providing a steady hand to help you reach your goals.

We’ll explore how these lenders look at your whole story, explain the real difference in costs following the recent OCR shifts, and help you decide if this is the right stepping stone for your future. You’ll gain the confidence to move forward with a plan that actually fits your life.

Key Takeaways

  • Learn how to move past a bank rejection by finding lenders that look at your whole financial picture rather than just a computer-generated score.
  • Understand the actual costs of non bank lenders nz home loans and why paying a bit more now can be a smart move to secure your future home.
  • Discover how these flexible options specifically help self-employed Kiwis and first-home buyers who don’t fit the standard bank boxes.
  • Find out how working with a dedicated negotiator ensures you get a fair deal and a clear plan to eventually move back to a mainstream bank.

What exactly are non-bank lenders in the NZ home loan market?

If you’ve ever felt like just another number at a big bank, non-bank lenders might be the breath of fresh air you need. Simply put, these are companies that provide home loans but don’t hold a traditional banking licence. They are a specific type of non-bank financial institution that focuses on getting people into homes when the traditional path is blocked. By March 2024, lending from these institutions in New Zealand reached about $5.7 billion, showing just how many Kiwis are choosing this path.

Unlike the big banks that use the money in your savings account to lend to others, these lenders get their funds from private investors or larger wholesale markets. This is a major reason why non bank lenders nz home loans offer more flexibility. They aren’t tied to the same rigid rules that govern how banks must handle your neighbour’s term deposit. You might hear people call them second tier lenders. Don’t let that label fool you into thinking they are second best. It’s just a way to categorise them outside the Big Four. They’re often more agile and more willing to listen to your specific story.

The difference between a bank and a non-bank

Most Kiwis are used to the Big Four banks. They have branches on every corner and huge advertising budgets. But they also have very narrow boxes for who they will lend to. Alternative lenders don’t have those massive overheads or the same one size fits all mentality. While they aren’t registered banks, they are still strictly regulated. They must follow the Credit Contracts and Consumer Finance Act, which ensures they are responsible and safe. The real difference is their flexibility. They look at the person behind the application, not just the checkboxes on a form.

Why non-banks are a fair dinkum option for Kiwis

The biggest hurdle for many home buyers is the “computer says no” moment. If you’re self-employed or have a small credit blip from years ago, a bank might reject you instantly. Non-banks are a fair dinkum choice because they use actual humans to assess your application. They’ve helped thousands of families get sorted when the big guys turned them away. With dozens of different lenders in the NZ market today, there’s a huge variety of options. If you want to learn more about how these rules work behind the scenes, our Mortgage School is a great place to start. It’s all about finding the right partner for your journey.

Why the big banks might say no (and why non-banks say yes)

Mainstream banks love what we call “vanilla” applications. If you have a steady salary, a spotless credit history, and a 20% deposit, you are their dream client. But for many Kiwis, life isn’t always that tidy. Banks rely on rigid algorithms to make decisions. If your situation doesn’t tick every single box, the computer simply spits out a decline. This is where Canstar explains non-bank mortgage lending as a vital alternative, because these lenders use human common sense rather than just a software programme.

Common reasons for a bank decline include small credit blips from years ago, having a deposit under 20%, or trying to buy a property that doesn’t meet their strict criteria. Non-bank lenders nz home loans work differently because they look at the whole story. They want to understand why a hurdle exists and what your plan is to move past it. As your broker, my job is to act as a dedicated negotiator. I know which lenders are comfortable with certain “problems” and how to present your case so it gets a “yes” instead of a flat rejection.

Self-employed and “outside the box” income

Business owners and contractors often struggle with traditional banks because their income can fluctuate. A bank usually demands two full years of perfect tax returns, which isn’t always helpful if you’ve just had a growth year or recently started out. Non-banks offer “alt-doc” options, which means they can verify your income using GST returns or bank statements instead of just tax summaries. If you’re navigating this path, our Self Employed Home Loan Guide offers deeper insights into how to prepare your application for success.

Property types that banks often shy away from

Sometimes it isn’t you; it’s the house. Banks often refuse to lend on small apartments under 40 or 50 square metres, lifestyle blocks with unusual zoning, or “fixer-uppers” that need significant work. They see these as high-risk assets. Non-bank lenders nz home loans take a more practical view of property value and risk. They specialise in the unique corners of the New Zealand market, seeing the potential in a property where a bank only sees a liability. If you’ve found a unique spot that the big banks won’t touch, it’s worth having a chat to get to know our team and see how we can help you secure it.

The real cost: Interest rates, fees, and your budget

Let’s be direct about the numbers. You’ll likely pay more for a non-bank loan than you would at a big bank. It’s a trade-off. By choosing a lender that looks at your whole story, you might pay a slightly higher interest rate, but you’re actually getting into the property market instead of watching prices climb from the sidelines. Most people use non bank lenders nz home loans as a tactical stepping stone. You stay for one or two years, tidy up your credit or build your business history, and then move back to a mainstream bank once you fit their box.

Fees are another area where things differ. While a bank might waive an application fee, non-banks usually charge an establishment fee to cover the manual work of assessing a complex file. In the current 2026 market, these typically range between $2,000 and $5,000. You might also see small monthly admin fees around $10 to $13. It’s about looking at the total cost of the “bridge” to get you to your goal rather than just the sticker price.

Comparing interest rates: Bank vs. Non-bank

The gap between a bank rate and a non-bank rate is often called the margin. Usually, near-prime rates sit about 1% to 2% higher than what the big banks offer. With the Official Cash Rate sitting at 2.75% as of September 2026, near-prime rates often start around 6.35%. It’s vital to see how this looks in real dollars. You can use our mortgage calculator to compare different scenarios. Remember, the “cheapest” rate isn’t always the best deal if the lender won’t actually give you the money.

Managing the extra cost in your weekly budget

A higher rate doesn’t have to break your budget if you plan correctly. We often suggest structuring your loan with a focus on flexibility, allowing you to make extra payments when possible. This helps you build equity faster so you can refinance sooner. Getting into a home now, even at a higher rate, can often save you more in the long run than waiting years to save a massive deposit while house prices potentially increase. It’s about looking at the big picture of your financial success and long-term security.

Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

Common situations where non-bank home loans shine

While mainstream banks often wait for a perfect set of circumstances, non bank lenders nz home loans are built for the reality of life in New Zealand. They shine brightest when you need a solution that looks at your future potential rather than just your past paperwork. For many, these lenders provide a strategic way to move forward when the traditional path is blocked by rigid rules or timing issues.

There are several specific scenarios where these alternative options become the best tool for the job:

  • Low deposit hurdles: If you have a deposit under 20% and don’t qualify for specific government grants, non-banks can often bridge that gap.
  • New business owners: If you’ve been self-employed for less than two years, a bank will likely turn you away. Non-banks are often happy to help once you have a few months of solid trading under your belt.
  • Past credit hiccups: A single missed payment or an old default can stay on your record for years. Non-bank lenders focus on your current ability to pay rather than a mistake from the past.
  • Growing property portfolios: Investors often hit a wall with banks due to strict rules on how much they can borrow compared to their income. Non-banks don’t have to follow the same Reserve Bank limits, allowing for more growth.

Bridging the gap for first-home buyers

Getting on the property ladder is often a race against time. If you wait another two years to save a larger deposit, house prices might have climbed even further, leaving you in the same position. By using a non-bank, you can secure a property now with a smaller deposit. This allows you to start building equity in your own home rather than paying off someone else’s mortgage. Our guide on Home Loans for First Home Buyers NZ explains how to navigate these rules to your advantage.

Credit repair and moving forward

A non-bank loan is often the best way to prove to the wider market that you are a reliable borrower. By making every payment on time for 12 to 24 months, you actively repair your credit profile. This creates a clear track record that eventually makes you very attractive to mainstream banks. Think of it as a transition period where you get the house you want while tidying up your financial history. Once your situation is sorted, we can help you move back to a bank with a lower rate. See how we’ve helped other Kiwis make this exact transition and find their way to financial success.

How to find the right non-bank lender for your goals

Applying for a mortgage shouldn’t feel like a guessing game. It is tempting to jump online and send applications to every lender you find, but this can actually backfire. Every time a lender checks your credit, it leaves a footprint. Too many footprints in a short time can make you look desperate to other lenders. The trick isn’t to apply more; it is to apply smarter. Working with a specialist who understands the landscape of non bank lenders nz home loans means you only apply to the ones most likely to say yes.

A specialist broker acts as your dedicated negotiator. Because I have spent over 20 years on the inside of the banking world, I know exactly what these lenders are looking for. We do the heavy lifting by comparing different non bank lenders nz home loans to find the one that fits your specific story. This saves you time and protects your credit score from unnecessary dings. We handle the paperwork and the talking, so you can focus on finding the right house.

One thing many people forget to check is the fine print. You need to look at more than just the interest rate. Are there penalties for paying the loan off early? How much are the ongoing admin fees? Most importantly, you need a clear exit strategy from day one. We don’t view a non-bank loan as a forever home for your debt. It is a bridge. We help you map out exactly what needs to happen so you can refinance back to a mainstream bank in 12 to 24 months. This might involve tidying up spending habits or building a longer history of business income.

The Mortgage Suite advantage

When you work with us, you are getting more than just a middleman. You are getting a partner with deep institutional knowledge. Krish Krishna’s 20 years of banking experience means he knows the rules, the shortcuts, and the people who make the decisions. We have established relationships with a wide range of 2nd tier lenders across New Zealand, giving you options that you simply won’t find on your own. You can read more about our philosophy and how we prioritise your success over just closing a deal.

Your next steps to getting sorted

Getting started is simpler than you might think. Your first job is to gather your paperwork. Having your bank statements and proof of income ready to go makes a massive difference in how a lender views your application. It shows you are organised and serious. Once you have your bits and pieces together, the next step is to book a chat. We will sit down, listen to your story, and figure out a path forward together. If you are still feeling a bit unsure, read our client reviews to see how we have helped other Kiwis move from a bank rejection to home ownership.

Take the next step toward your new home

A “no” from a big bank doesn’t have to be the end of your property dreams. Non bank lenders nz home loans offer a flexible and fair dinkum alternative for Kiwis who don’t fit into a standard box. Whether you have a unique income or a past credit hurdle, these options provide a reliable bridge to financial success. By focusing on a clear exit strategy from day one, you can secure your home now and move back to a mainstream bank when the time is right.

With over 20 years of banking and brokerage experience, we specialise in navigating the inside rules to get you sorted. We’re proud to help families nationwide find a steady hand in a shifting market. You don’t have to guess your way through the process alone. Our team is here to act as your dedicated negotiator, ensuring you get a fair deal that actually works for your budget.

Book a free, no-obligation chat with Krish to see your options. It’s time to stop worrying about the paperwork and start planning your move. We’re ready to help you turn that “no” into a “yes”.

Frequently Asked Questions

Are non-bank lenders safe in New Zealand?

Yes, non-bank lenders are safe and must follow the same responsible lending laws as major banks. They are strictly regulated under the Credit Contracts and Consumer Finance Act, which ensures they treat you fairly and don’t lend more than you can afford to repay. While they aren’t registered banks, they are professional financial companies that help thousands of Kiwis. Choosing non bank lenders nz home loans is a secure way to enter the market.

Will I pay much higher interest rates with a non-bank lender?

You’ll generally pay a slightly higher rate, often around 1% to 2% above what a mainstream bank offers. This is because these lenders take on more risk by helping people who don’t fit the standard criteria. However, many borrowers find this extra cost is worth it to secure a home today rather than waiting years to save a larger deposit while house prices potentially climb even further. It’s about the long-term gain.

Can I move back to a main bank later on?

Absolutely, and that is usually the main goal for our clients. Most people use a non-bank loan as a temporary stepping stone for 12 to 24 months. During this time, you can tidy up your credit history or build a longer record of business income. Once your situation meets the big banks’ criteria, we can help you refinance to a lower rate. We build this exit strategy into your plan from the start.

Do non-bank lenders require a bigger deposit?

Not always. While big banks often demand a 20% deposit, non-bank lenders can be much more flexible. They aren’t always tied to the same strict speed limits set by the Reserve Bank regarding low-deposit lending. This means they might accept a smaller deposit if the rest of your application is strong and your income is stable. Every lender has different rules, so we look at your specific situation to find the best match.

How long does it take to get a non-bank home loan approved?

Approval times can often be faster than at a major bank because non-bank lenders are typically smaller and more agile. While a big bank might take weeks to process a complex file, an alternative lender can often give an answer within a few working days. Having your paperwork, like bank statements and proof of income, ready to go from the start will help speed up the process even more and keep things moving quickly.

Can I get a non-bank loan if I am self-employed with only one year of accounts?

Yes, this is a situation where non bank lenders nz home loans really shine. Most mainstream banks demand at least two full years of tax returns, but alternative lenders offer “alt-doc” options. They can use other evidence, such as GST returns or recent bank statements, to verify your income. This is a huge help for new business owners who are making good money but haven’t been trading long enough for a traditional bank.

Are there extra fees involved with non-bank home loans?

There are typically some extra costs, such as an establishment fee, which covers the manual work of assessing a non-standard application. These often range between $2,000 and $5,000 depending on the lender. You might also see small monthly admin fees of around $10 to $13. While these are higher than at a bank, they are often a small price to pay for the flexibility that gets you into your own home years sooner than waiting.

What happens if my credit history isn’t perfect?

Non-bank lenders focus on your whole story rather than just a computer-generated credit score. If you had a credit blip a few years ago due to a missed bill or a specific life event, they are often willing to listen to the explanation. They want to see that you are back on track and can comfortably afford the repayments today. This human approach is why many Kiwis with imperfect histories still find success.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Contractor Home Loan NZ: Getting Your Mortgage Sorted in 2026

What if your bank saw your contracting career as a sign of professional success rather than a massive risk factor? For many Kiwis, the dream of home ownership feels like it’s on hold because their income doesn’t arrive in a tidy, fortnightly payslip. If you’ve been told you need years of perfect books or a “standard” job to qualify for a contractor home loan nz, you’re likely feeling the frustration of trying to fit a square peg into a round hole.

It’s exhausting to deal with lenders who don’t seem to understand that your fluctuating monthly income is just part of a thriving, modern career. We know the paperwork mountain feels high, but securing a mortgage shouldn’t mean sacrificing your independence. This guide will show you exactly how to navigate the 2026 market, from organising the right documents to finding a lender who looks at the big picture of your finances. You’ll discover a clear path to getting your mortgage sorted without the typical big-bank stress and discover how to make your career choice work for your home ownership goals.

Key Takeaways

  • Understand why big banks often struggle with non-standard income and how to bypass their rigid “computer says no” systems.
  • Learn how to present your true earning power to lenders using simple methods that show your actual take-home pay, not just what’s on your tax return.
  • Compare the benefits of the “Big Four” banks against flexible 2nd tier lenders to find the best contractor home loan nz for your unique situation.
  • Follow our five-step checklist to organise your paperwork and clean up your spending before a lender even sees your application.
  • Discover how a steady hand with decades of experience can turn a complex application into a successful home purchase.

Why Big Banks Often Give Contractors the Cold Shoulder

Banks are creatures of habit. They’ve spent decades building systems that love one thing above all else: a predictable, fortnightly payslip. If you don’t have one, you’re suddenly an outlier. A contractor home loan nz isn’t actually a different financial product; it’s just a mortgage application that requires a human being to look at your bank statements instead of a computer algorithm. While the core concept of what is a mortgage remains the same, the path to getting one is much steeper when you’re your own boss.

When you apply at a big bank, you’re often met with a “computer says no” response. This happens because their software is designed to flag anything “different” as a “risk”. In reality, being a contractor often means you’re more resilient and higher-earning than a salaried employee, but the bank’s rigid rules don’t see it that way. They see your business expenses, which your accountant uses to lower your tax bill, as a lack of income. It’s a frustrating paradox; the more efficient you are with your taxes, the less the bank thinks you can afford to borrow.

The Salary-Only Mindset vs. Your Reality

Traditional lenders struggle with invoices because they represent a “maybe”. They worry that if your current contract ends, your income disappears entirely. This “fluctuating income” myth is one of the biggest hurdles we help clients clear. At Mortgage Suite, we don’t just look at the bottom line on your tax return. We look at your industry experience, your contract history, and the true value of your business. We treat you like a partner, not a set of data points. If you’re feeling overwhelmed by these concepts, our Mortgage School is a great place to start getting educated before you apply.

Common Contractor Scenarios We See

Every contractor’s story is unique, but we see a few common patterns that big banks usually reject. We regularly work with people in these situations to find a way forward:

  • IT Professionals: You might be on a high daily rate but only have a six-month contract. Banks see the end date; we see your high demand and niche skills.
  • Tradies and Sole Traders: Your income might peak in summer and dip in winter. We help show the bank your annual average rather than a single quiet month.
  • Creative Freelancers: Managing five different income streams can confuse a standard bank manager. We help pull those threads together into a coherent financial picture.

Cracking the Code: How Lenders Look at Your Income

Understanding how a bank calculates your earnings is the absolute secret to a successful application. When you’re chasing a contractor home loan nz, the number your accountant gives you at the end of the financial year isn’t always the number the bank uses to decide if you’re a “yes”. Your accountant’s main goal is to keep your tax bill as low as possible, which is great for your wallet but can look like low income to a bank manager. This is where we show your true financial strength by looking at your “add-backs”. We take expenses that don’t actually cost you cash every month, like the drop in value of your equipment or a one-off office fit-out, and add them back to your profit. It’s a simple way of showing the lender that this money is actually available to cover your mortgage.

A seasoned expert knows that your history in your industry is your biggest asset. Lenders often care more about how long you’ve worked in your specific field than the length of your current contract. If you’ve spent fifteen years as a project manager but only started your own business last year, we can often present you as a very safe bet. We focus on building a file that highlights your professional reputation and your consistent ability to secure high-value work. Organising your application this way makes it much harder for a bank to say no just because your business is relatively new.

Taxable Income vs. Actual Cash Flow

Banks have a specific way of asking how much you can afford to pay back each week. They want to see your cash flow, which is the real money moving through your accounts. We help you identify one-off costs that shouldn’t hurt your chances, like a new work ute or a major marketing campaign. By separating these unique expenses from your regular living costs, we give you a fair go at proving what you can really afford to borrow. If you’re curious about how your income might translate into a loan, check out our mortgage calculator to see what’s possible today.

The Two-Year Rule: Is it Still Relevant?

You don’t always need two full years of accounts to buy a home in New Zealand. While the big banks are quite rigid about this, we frequently help people who only have one year of financial history. In many cases, we use alternative lenders as a helpful bridge. These companies are often much more flexible with newer businesses. This allows you to get the keys to your home today and then move your loan to a major bank once you’ve got a longer track record under your belt. Learn more about 2nd tier lending and how it can help you get around the strict two-year requirement.

Mainstream vs. 2nd Tier: Finding the Right Fit

Most Kiwis grow up thinking the major banks are the only places to get a mortgage. While these big institutions offer competitive rates for standard borrowers, they aren’t always the best choice for your first contractor home loan nz. These massive organisations operate like financial factories; they need every application to look exactly the same. If your income comes from multiple sources or your business expenses are high, you might find their systems aren’t built to handle your complexity. This is where alternative, or 2nd tier, lenders become a vital part of your strategy.

Specialist lenders don’t just look at a score on a screen. They employ real people who take the time to understand your industry and your earning potential. They often offer loans that require less paperwork, which means they might accept GST returns or bank statements instead of two years of full financial accounts. You’ll likely pay a slightly higher interest rate with these lenders, but it’s often a price worth paying to get into your home now rather than waiting years to satisfy a traditional bank’s strict criteria.

When to Choose a 2nd Tier Lender

Choosing an alternative lender is often a smart “stepping stone” strategy. If you’re a first home buyer who has recently started contracting, you might not fit the standard bank boxes yet. We often help clients secure a 2nd tier loan to get them into the property market today. Once you’ve built up a year or two of solid accounts, we can then help you move that loan back to a mainstream bank at a lower rate. It’s about getting the keys in your hand now so you can start building equity. Check out our Mortgage School for more tips on how to prepare for this transition.

The Pros and Cons of Non-Bank Loans

The biggest advantage of a non-bank lender is speed and a personalised approach. You aren’t just another number in a call centre queue. These lenders are often much faster at giving you an answer, which is crucial when you’re trying to buy in a competitive market. While the interest rate might be higher, the flexibility they offer can be the difference between buying a home and missing out entirely. We weigh these options with you to ensure the choice makes sense for your long-term goals.

Feature Mainstream Banks 2nd Tier Lenders
Approval Speed Often slow (7 to 10 days) Fast (2 to 3 days)
Flexibility Rigid, computer-led rules Human-led, common sense
Income Proof Full financials required Accepts GST or bank statements

Contractor Home Loan NZ: Getting Your Mortgage Sorted in 2026

Your Contractor Home Loan Checklist: Getting Sorted

Preparing for a contractor home loan nz is about more than just having a deposit. It’s about telling a financial story where you’re a reliable professional, not a risky outlier. To get bank-ready, you need to look at your finances through a lender’s eyes. This starts with your accountant. They aren’t just there to file your GST; they’re your primary witness. An accountant can provide a letter confirming your projected income or explaining that a large expense was a one-off business investment that won’t happen again next year.

One secret weapon many people overlook is an updated CV. While it sounds odd to bring a resume to a mortgage meeting, a professional profile showing a long history of successful projects proves to the bank that you’re in high demand. If your current contract ends, your CV shows you have the skills to land the next one immediately. This simple document turns you from a “temporary worker” into a “highly sought-after specialist” in the eyes of the credit team.

Before a broker even sees your file, take a few months to clean up your personal spending. Banks look closely at your uncommitted monthly income. Frequent small debts like buy-now-pay-later schemes or high-interest credit cards can significantly lower your borrowing power. We recommend following these five essential steps to get sorted:

  • Collaborate with your accountant to frame your income correctly.
  • Audit your bank statements and pause non-essential subscriptions.
  • Refresh your professional CV to show career longevity.
  • Clear small debts and close unused credit cards or personal loans.
  • Organise your tax documents so everything is ready to go.

The Paperwork You Actually Need

Lenders want to see proof that your business is healthy. This means gathering your IRD income summaries and GST returns for the last year. While big banks might ask for more, having six months of clean business bank statements is often the most important factor. These statements prove the cash flow we discussed earlier. You’ll also need to show exactly where your deposit is coming from, whether it’s genuine savings, equity in another property, or a gifted sum from family.

Improving Your Chances of a “Yes”

Reducing your personal debt is the fastest way to boost your application. Even a credit card you don’t use with a $10,000 limit is seen as a potential debt by the bank. It’s also helpful to keep a buffer of cash in your business account to show you can handle a quiet month without stress. To get a better idea of your position, try using our mortgage calculator to see how your current debts might affect your borrowing. If you want a hand getting your documents in order, contact our team at Mortgage Suite for a personalised review.

How Mortgage Suite Navigates the Maze for You

Applying for a mortgage when you work for yourself can feel like walking through a maze where the walls keep moving. At Mortgage Suite, we see our role as the steady hand that guides you through every turn. Krish Krishna leads our team with over two decades of experience inside the banking industry. This isn’t just a number on a page; it means we know exactly how the people on the other side of the desk think. We don’t just fill out forms. We act as your dedicated negotiator, presenting your financial story in a way that makes sense to a lender’s credit department.

The big banks often have a rigid view of what a “safe” borrower looks like. We challenge that view by highlighting your professional potential and your industry reputation. Whether you’re looking for a standard bank mortgage or a 2nd tier loan that fits your current lifestyle, we handle the complex heavy lifting. This allows you to stay focused on your business while we manage the endless follow-ups and paperwork required for a successful contractor home loan nz application. We’ve seen every possible scenario and know exactly how to bridge the gap between your personal needs and the rigid world of institutional banking.

A Personalised Path to Home Ownership

We believe in straight talk. You won’t get any corporate lectures or confusing financial jargon from us. Instead, we offer a non-corporate experience that puts your goals first. Our process is designed to be as stress-free as possible, moving at your pace while ensuring every detail is perfect before it reaches a lender. We take pride in the relationships we build, and our client reviews show that we care about the person behind the loan, not just the numbers on the screen. We’re here to be your advocate, ensuring you get a fair go from the very start.

Ready to Get Started?

If you’re ready to see what’s possible, the first step is a simple, no-obligation chat. You don’t need to have all your paperwork perfectly organised yet. In a quick 15-minute consultation, we can look at your current situation and give you a clear idea of your options. We’ll explain how we can help you navigate the 2026 market and what the next steps look like for your specific career path. You can learn more about Mortgage Suite and our mission to help Kiwis who don’t fit the standard bank box. Let’s get your mortgage sorted together.

Take the Next Step Toward Your New Home

Contracting gives you freedom and flexibility, and your mortgage should reflect that success. By understanding how lenders view your income and preparing your file with a professional eye, you can bypass the “computer says no” culture of the big banks. Whether you need a mainstream bank or a flexible 2nd tier solution, the right strategy turns a complex application into a successful result. We’ve shown you that the paperwork mountain is manageable when you have the right guide by your side.

With over 20 years of banking and brokerage expertise, we know how to present your case to get a fair go. We specialise in alternative and 2nd tier lending solutions for those who don’t fit the standard box, acting as a dedicated advocate who knows exactly how to talk to the banks on your behalf. Securing a contractor home loan nz doesn’t have to be a mountain of stress. You’ve worked hard to build your career; now it’s time to make that career work for your home ownership goals.

Get your contractor home loan sorted with Mortgage Suite and take the first step toward the keys to your new home. We’re here to make the process simple, clear, and successful.

Frequently Asked Questions

Can I get a home loan with only 6 months of contracting history?

Yes, you can certainly secure a loan with six months of history, though you’ll likely need to look beyond the big banks. Most mainstream lenders prefer two years of accounts, but 2nd tier specialists often accept six months if you have a solid background in the same industry. We focus on showing the lender that your career is stable despite the recent change in how you’re paid.

Do contractors pay higher interest rates in New Zealand?

Contractors don’t automatically pay higher rates, but it depends on which lender approves your application. If your file is strong enough for a mainstream bank, you’ll get the same market rates as anyone else. If you require the flexibility of a 2nd tier lender to get your contractor home loan nz approved, you might pay a slightly higher rate. This is often a temporary step until you have more history.

Can I use my business income to buy a house if I am a sole trader?

You can absolutely use your sole trader income to buy a house. Lenders treat your business profit as your personal income. We work with you to identify “add-backs” like depreciation or one-off equipment costs that shouldn’t count against your borrowing power. This ensures the bank sees your actual cash flow rather than just the lower figure your accountant uses to reduce your tax bill.

How much deposit does a contractor need for a home loan in NZ?

Deposit requirements for contractors usually follow the same standard rules as salaried employees. For most first home buyers, a 20% deposit is the gold standard, though some schemes allow for as little as 5% or 10% depending on the property. If you’re looking at an investment property, you’ll generally need closer to 30% or 35% to satisfy current New Zealand lending restrictions and bank policies.

What happens if my contract is about to end?

Having a contract near its end date isn’t an automatic “no” if we can prove your future earning potential. We use your professional CV and industry history to show the bank that you’re in high demand and likely to secure a new contract quickly. Providing a letter of intent from your current client or showing a history of back-to-back contracts helps alleviate the bank’s concerns about potential income gaps.

Can I get a “low-doc” loan as a contractor in 2026?

Low-doc loans are a very real option in 2026, especially through alternative lenders. These loans allow you to prove your income using GST returns or business bank statements instead of full, accountant-prepared financial statements. This is a popular choice for contractors who haven’t completed their first full year of trading but have a clear and consistent stream of income hitting their business accounts every month.

Does being a contractor affect my ability to get a first home grant?

Your employment status doesn’t stop you from getting a first home grant, but your total income must stay under the government caps. The key challenge for contractors is proving their taxable income for the previous 12 months. As long as you can provide the correct IRD summaries and meet the standard criteria, you’re just as eligible as a salaried worker to access these government support schemes.

Is it better to apply as an individual or through my company?

Most lenders will look at your total household or global income regardless of whether you’re a sole trader or a company director. Even if you trade through a company, the bank will usually require you to be a personal guarantor for the loan. We help you structure the application to show your income in the most favourable light, ensuring the bank understands the full picture of your finances.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Structuring Investment Property Loans NZ: The 2026 Strategy Guide

Most Kiwi investors believe the interest rate is the most important part of their mortgage, but in 2026, a “cheap” rate won’t save you if your loan structure is actually blocking your next purchase. If you’ve ever felt stuck after buying just one or two properties, it’s usually not a lack of equity or income holding you back. It’s often the way your debt is organised. Getting the right advice on structuring investment property loans nz is now the difference between a stagnant portfolio and a growing one, especially with the current debt-to-income (DTI) limits of seven times your income.

We understand that the fear of the bank taking your family home if an investment fails is a heavy burden to carry. It’s a common worry that keeps many people from taking the next step. You want to build a legacy for your family, not put their roof at risk. This guide will show you exactly how to set up your property loans to protect your personal assets, maximise your borrowing power, and move your portfolio forward at a faster pace. We’ll explore how to navigate the 2026 lending environment, from managing DTI rules to using lenders that look beyond the standard bank boxes.

Key Takeaways

  • Discover why the way you organise your debt matters far more than snagging the lowest interest rate when it comes to your long-term wealth.
  • Find out how to separate your personal home from your rentals so you never have to worry about the bank having too much control over your family’s future.
  • Learn why thinking beyond the big banks and properly structuring investment property loans nz can help you bypass rigid debt-to-income limits.
  • Get clear on whether paying only the interest or chipping away at the loan itself is the best move for your 2026 cash flow goals.
  • Understand why a strategic property plan is a marathon rather than a sprint and how the right expert help can unlock your future borrowing power.

Why the way you set up your loan matters more than the interest rate

It’s easy to get fixated on the numbers at the bottom of a bank’s flyer. Most investors spend hours comparing interest rates, hoping to shave a tiny fraction off their monthly repayments. While that’s understandable, it’s often a distraction from a much bigger risk. A low rate on a poorly organised loan can actually end up costing you hundreds of thousands of dollars in lost capital growth. If you can’t borrow for that third or fourth property because your bank says “no”, you miss out on the compounding gains of those assets over the next decade. That’s a massive price to pay for a slightly lower rate today.

When we talk about structuring investment property loans nz, we’re really talking about protecting your future borrowing power. If you set things up the wrong way, you might find yourself “stuck” after your first or second property because you’ve accidentally handed all the control to the bank. This happens when the bank uses your family home to secure everything, leaving you with very little room to move when you want to expand your portfolio.

What exactly is loan structuring?

In simple terms, loan structuring is the way your debt is organised across different banks and properties. It’s about deciding which assets secure which loans and whether those loans are linked together. Think of it as building a house. You wouldn’t spend all your money on expensive taps if the foundation was built on shifting sand. Good structure provides a solid foundation. It involves Avoiding cross-collateralisation, which keeps your family home safe from your investment risks. When your loans are structured correctly, you maintain “options” that allow you to pivot when the market or your life changes. You can learn more about these mechanics in our Mortgage School, where we break down how lending actually works behind the scenes.

The 2026 context: Why things have changed

The rules of the game have shifted significantly. In 2026, banks are being more careful than ever. With the Debt-to-Income (DTI) limits introduced a couple of years ago, your ability to borrow isn’t just about how much your house is worth; it’s about how your income is viewed by the lender. Since the Reserve Bank raised the OCR to 2.75% in September 2026, the cost of borrowing has increased, making every decision more impactful. We see many clients who have plenty of equity but can’t buy their next property because their current bank has “boxed them in” with rigid rules. By looking at the big picture, we help you protect your borrowing power so you can keep growing even when the big banks are tightening their belts.

The ‘all your eggs in one basket’ trap: Avoiding cross-collateralisation

Banks love it when you keep all your loans in one place. They often frame it as a way to “simplify” your life, but the reality is much more one-sided. This setup, often called cross-collateralisation, means the bank uses every property you own to secure every loan you have. It gives them maximum security and leaves you with very little control. When you’re structuring investment property loans nz, this is the number one trap to avoid if you want to keep your family home safe and your investment options open.

One of the biggest risks is the “Sale of Property” clause hidden in the fine print. If your loans are linked and you decide to sell one investment property, the bank can step in and take all the profit to pay down your other debts. You might have been counting on that cash for a new deposit or a renovation, but the bank gets to decide where that money goes first. By keeping your properties separate, you ensure that you, not the bank, decide how to spend your hard-earned capital.

How the ‘linking’ trap works in real life

If your home and your rentals are tied together, your entire financial life is at the mercy of a single bank’s valuation. If the market dips and one property loses value, the bank might suddenly view your whole portfolio as “risky.” They could freeze your credit limits or demand you pay back more of the principal. This is why we always recommend keeping your personal home as a standalone asset, completely separate from your investment debt. Cross-collateralisation is essentially the bank using all your properties to back every loan, which is a position you never want to be in.

Steps to un-link your properties

Breaking free from this trap is a process, but it’s worth the effort for the peace of mind it brings. Here is how you can start to untangle your finances:

  • Use different lenders: The most effective way to protect your home is to have your home loan at one bank and your investment loans at another.
  • Demand standalone security: When setting up a new loan, ensure the documentation only lists the specific property being purchased as security.
  • Refinance away from all-in-one facilities: Many older loan structures use a single “limit” backed by multiple houses. Moving to separate, fixed-term loans is often a smarter move.

You can use our mortgage calculator to see how much equity you currently have. This is a great first step in working out if you have enough leverage to move your investment loans to a different lender. Deciding between Interest-only or paying off the principal is also much easier when your loans aren’t all tangled together. If you’re not sure how your current loans are set up, having a quick chat with someone who knows the system can clarify things quickly.

Interest-only or paying off the principal: Which path is right for you?

Deciding how to pay back your bank is a massive part of structuring investment property loans nz. You have two main choices: paying just the interest or paying both the interest and the loan amount together. In 2026, “Cash Flow is King” has become the mantra for successful investors. With the Official Cash Rate at 2.75% and Debt-to-Income (DTI) limits generally capped at seven times your income, every dollar that leaves your account needs to be justified. Choosing the wrong repayment path can quickly dry up your cash reserves and stop your growth in its tracks.

A smart strategy many seasoned investors use is to focus on paying off their own home first while keeping their investments on interest-only terms. Since the interest on your family home isn’t tax-deductible, it makes sense to clear that debt as fast as possible. By keeping your investment debt separate and paying only the interest, you maximise your tax efficiency. It’s a winning move that helps you get rid of “bad” debt while your “good” investment debt works for you. Just make sure you chat with your accountant to ensure this setup fits your specific tax situation.

When interest-only makes sense

Interest-only payments keep your monthly “out-of-pocket” costs as low as possible. This is vital when you’re trying to grow a portfolio because it leaves more cash in your pocket at the end of each week. That extra money can be funnelled into a separate account to build a deposit for your next property faster. It’s important to remember that in 2026, most big banks will only let you stay on interest-only for a set period, often five years, before they want you to start paying back the principal. You need a plan for when that term ends so you don’t get a nasty surprise.

The argument for paying it all down

There is a lot to be said for the peace of mind that comes with seeing your debt balance actually drop. Paying off the principal means you are building equity in your properties every single month, regardless of what the market is doing. This extra equity can then be used as security for more loans later on. The trick is to find a “sweet spot” between growth and security. You want enough cash to live comfortably and keep buying, but you also want to know that you’re slowly becoming debt-free. If you’re unsure where you stand, you can check your current equity levels with our mortgage calculator.

Structuring Investment Property Loans NZ: The 2026 Strategy Guide

Thinking outside the big banks: When a second-tier lender makes sense

Many people assume that 2nd tier lenders are only for those who’ve made financial mistakes. That’s a huge misconception. In the current market, these lenders are often the secret weapon for smart investors who are structuring investment property loans nz to keep growing. When the big four banks start tightening their belts, a non-bank lender can offer the oxygen your portfolio needs to survive and thrive. It’s not about being a “bad” borrower; it’s about being a strategic one.

Mainstream banks are often bound by very strict, “one-size-fits-all” rules. If you don’t fit perfectly into their box, they simply say no. Non-bank lenders, on the other hand, often have more practical ways of looking at your situation. They might be more willing to accept a higher percentage of your rental income or look at your business earnings with a bit more common sense. This is often the “key” that unlocks property number three or four when a big bank has slammed the door shut. At Mortgage Suite, we pride ourselves on knowing exactly which non-bank door to knock on for your specific needs.

The flexibility of non-bank lenders

These lenders often look at your “real-world” income differently. While a big bank might use a very conservative “stress test” on your interest rates, a non-bank might use a more realistic figure. This can significantly increase your borrowing capacity under the current DTI rules. They are also fantastic for short-term needs, like bridging finance if you’ve bought before selling, or funding a quick renovation to add value. Simply put, 2nd tier lending is a professional alternative to mainstream banking that prioritises results over rigid paperwork. You can find out more in our 2nd tier lender new zealand your 2026 guide to alternative home loans.

Is a non-bank loan more expensive?

Let’s be honest about the numbers. Yes, the interest rates at a second-tier lender might be slightly higher than what you’d see on a billboard for a major bank. However, you have to weigh that against the “cost of doing nothing.” If a slightly higher rate allows you to secure a property that grows in value by fifty thousand dollars in a year, that small extra interest cost is a drop in the ocean. You aren’t just paying for money; you’re paying for the opportunity to grow.

We often use a “stepping stone” strategy with our clients. This involves using a non-bank lender to get the deal done now, then moving the loan back to a big bank once your equity has grown or your income has increased. It’s about being proactive and finding a path forward when others see a dead end. You can read through our Mortgage Suite reviews to see how other Kiwi investors have used this exact path to build their wealth. If you’re feeling stuck with your current bank, reach out for a consultation so we can explore the alternatives together.

Creating your long-term property plan with a bit of expert help

Successfully structuring investment property loans nz is a marathon, not a sprint. It’s about looking five or ten years down the track, not just at next month’s repayment. If you only talk to a bank teller, you’re getting a product that fits their sales target today. A teller isn’t there to help you buy your fourth house in three years. You need a partner who understands the long game and how each choice today impacts your options tomorrow. We’re here to make sure you don’t just get a loan, but a strategy that supports your life goals.

The rules in New Zealand change fast. We’ve seen the Bright-line test shift to two years and the OCR climb to 2.75% in September 2026. Because the environment is always moving, your strategy for structuring investment property loans nz needs to move with it. We recommend a full review every 12 to 24 months. This ensures you’re still protected and still have the best possible path to your next purchase. If you’re curious about how we work and why we’re so passionate about this, you can learn more about us and our client-first philosophy.

The value of a veteran negotiator

Krish Krishna brings over 20 years of banking experience to your side of the table. He’s seen every market cycle and knows exactly how banks think. At Mortgage Suite, we act as a steady hand for our clients through every hurdle. We don’t just take the easiest offer the bank gives us; we fight for the structure that actually works for you. Our job is to clear the path and remove the obstacles, so you can focus on finding the right property to add to your collection. We handle the complex negotiations so you don’t have to deal with the stress.

Your next steps to a better structure

Getting started is easier than you think. First, gather your current loan documents for a quick health check. You might be surprised at how a few small tweaks can unlock a lot of potential. We also encourage you to keep learning through our Mortgage School resources. It’s packed with information to help you stay ahead of the curve. Let’s get your property investment journey sorted for 2026 and beyond. We’re here to help you build a portfolio that truly lasts. Give us a call for a no-worries chat whenever you’re ready to take that next step.

Take the next step toward your property goals

Building a successful portfolio in 2026 isn’t just about finding the right house; it’s about having the solid foundation that only a smart strategy can provide. By avoiding the trap of linking your family home to your investments and choosing a repayment path that protects your cash flow, you keep the power in your hands. Mastering the art of structuring investment property loans nz ensures that you’re never “stuck” when the next great opportunity comes along.

With over 20 years of banking and mortgage expertise, Mortgage Suite acts as your steady hand in a fluctuating market. We offer access to both mainstream banks and 2nd tier lenders, specialising in the complex investment and development finance that often stumps the big banks. Our mission is to remove the obstacles standing in your way so you can focus on growing your wealth. Book a friendly chat with the Mortgage Suite team today to get your structure sorted. We’re here to help you move forward with confidence.

Frequently Asked Questions

What is the best way to structure an investment property loan in NZ?

The most effective approach is to keep your loans standalone and separate from your family home. This protects your personal assets and keeps your options open for future growth. Many successful investors use a mix of interest-only terms for their rentals while aggressively paying off their own home. This keeps cash flow high and debt manageable. Every situation is unique, so it’s vital to have a plan that matches your long-term goals.

How much deposit do I need for an investment property in 2026?

In 2026, you generally need a 30% deposit for an existing investment property, which means a 70% loan-to-value ratio. However, if you’re looking at a new build, the requirement is often lower at 20%. Some non-bank lenders might offer more flexibility depending on your overall financial position. It’s also possible for banks to lend to a small number of investors with less than a 30% deposit, though these spots are limited and highly competitive.

Can I use the equity in my own home to buy a rental property?

Yes, using the equity in your own home is a very common way to fund a rental property deposit. You can often top up your current home loan to release cash, which then acts as the deposit for your new investment. The key is to ensure the new investment loan is kept at a separate bank where possible. This prevents the properties from being linked together, which keeps your family home much safer if the market changes.

What are DTI ratios and how do they affect my property investment?

Debt-to-income (DTI) ratios limit how much you can borrow based on your yearly earnings. In 2026, investors are generally capped at borrowing seven times their total income. This rule makes structuring investment property loans nz even more critical because you need to ensure every dollar of income is counted correctly by the lender. If your big bank says your DTI is too high, we can often find second-tier lenders who look at your income with more flexibility.

Is it better to have all my loans with one bank or spread them out?

Spreading your loans across different banks is usually the smarter move for investors. While having everything in one place might seem easier, it gives that single bank too much control over your life. If they decide to change their rules or lower your credit limits, your whole portfolio is affected. By using multiple lenders, you maintain your borrowing power and ensure that a problem at one bank doesn’t stop your entire property journey.

Can I get an investment loan if the big banks have already said no?

If the big banks have turned you down, it doesn’t mean your journey is over. We specialise in 2nd tier loans that don’t fit the standard bank boxes. These lenders often have different rules for things like income, age, or property types. Using a non-bank lender can be a great stepping stone to get a deal done now, with the plan to move back to a mainstream bank once your equity or income has grown.

What is cross-collateralisation and why should I avoid it?

Cross-collateralisation is when a bank uses all your properties to secure every one of your loans. You should avoid it because it gives the bank the right to take the profit from any property sale to pay down your other debts. It also means your family home is at risk if an investment fails. Keeping your loans standalone ensures that you stay in the driver’s seat and can make your own decisions about your money.

How often should I review my loan structure?

You should review your loan structure every 12 to 24 months. Lending rules, interest rates, and your own life goals can change quickly, so what worked two years ago might be holding you back today. A regular health check ensures you’re still on the best rates and that your structure is still protecting your home and maximising your growth. It’s also a good time to check your equity levels as the market moves.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.