
Cost to Build a House in NZ 2026: Your Full Financial Breakdown

What if the most dangerous number in your building project isn’t the total price, but the one you haven’t accounted for yet? It’s a question many Kiwis are asking as they look at the cost to build a house nz 2026, only to find themselves buried under conflicting advice and shifting estimates. You’ve probably noticed that one person quotes you a bargain rate while another warns of a budget blowout, leaving you worried about being left short by the bank halfway through the build.

We understand that the dream of a new home shouldn’t feel like a financial gamble. That’s why we’ve put together this clear, jargon-free guide to help you plan with confidence. You’ll get a realistic look at today’s true construction costs and learn the crucial difference between an initial quote and your final bill. We’ll also show you exactly how to secure the right finance for your project, even if mainstream banks have already said no. From square metre averages to the essential safety net funds you’ll need, we’ve got you covered.

Key Takeaways

  • Understand why the initial builder’s quote is only one part of the story and how to plan for your total project budget from day one.
  • Learn the real cost to build a house nz 2026 by looking past standard square metre rates to include often-overlooked site and design expenses.
  • Discover how to spot “hidden” costs like council consents and groundworks before they surprise your bank account or stall your progress.
  • Explore how to keep your build moving with 2nd tier loans if mainstream banks aren’t a good fit for your unique financial profile.
  • Get a clear roadmap for assembling a professional team that aligns your dream home design with your actual borrowing limits.

The Real Deal on Building Costs in NZ for 2026

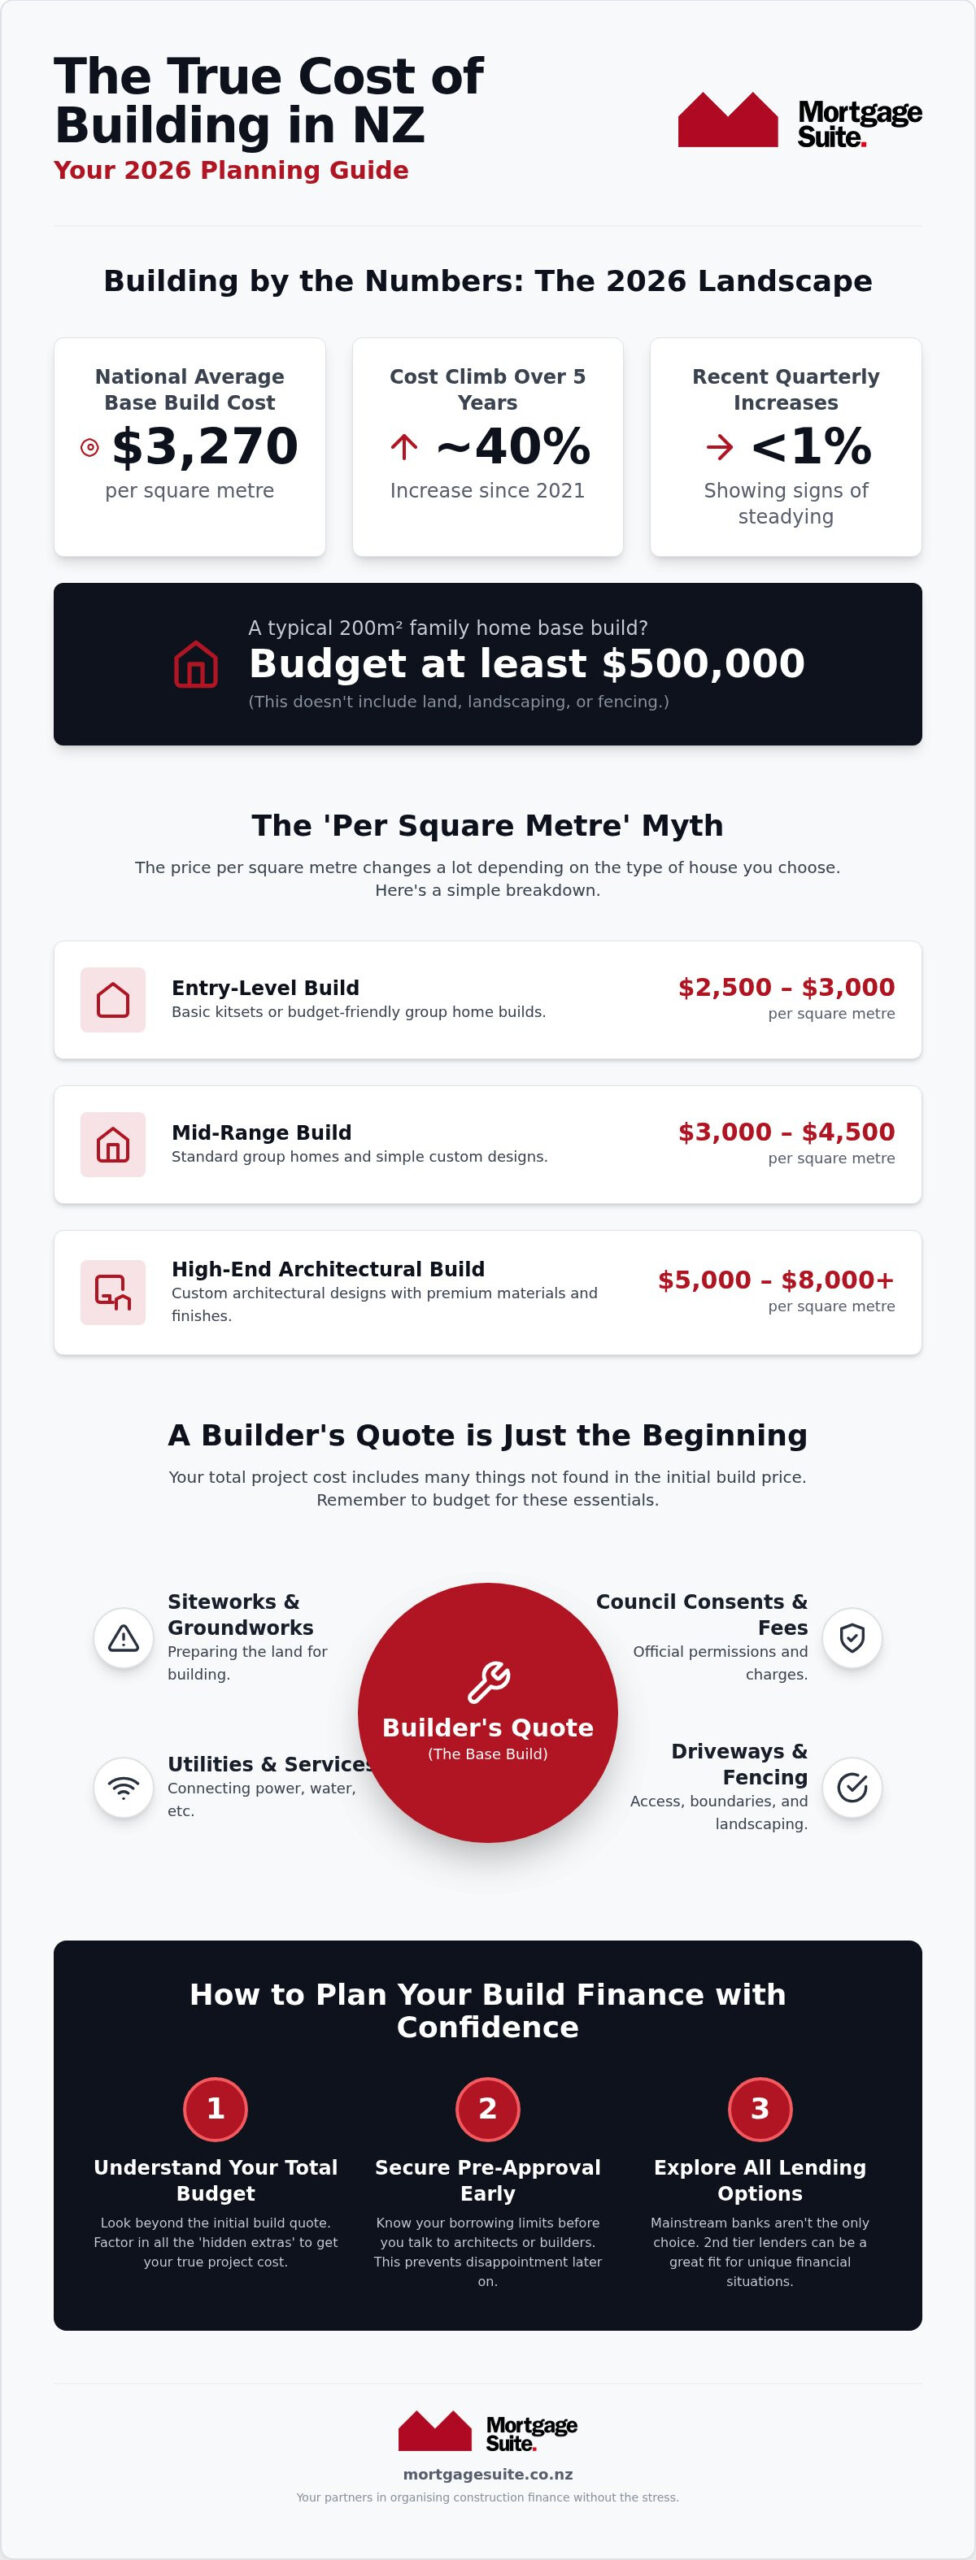
Building a house is a massive financial undertaking, and in 2026, the gap between a builder’s initial quote and the final “move-in” cost is wider than ever. Most people start by looking at the headline figures for the cost to build a house nz 2026, but these numbers often skip over the essentials like driveways, fencing, and council fees. Understanding Housing in New Zealand means recognising that your budget needs to cover the entire project, not just the timber and nails. While the national average sits around $3,270 per square metre, this is strictly for base construction. The industry has seen costs climb nearly 40% over the last five years, though the pace of these increases has finally started to steady to under 1% per quarter.

For a standard 200sqm four-bedroom family home in 2026, you should budget at least $500,000 for the base construction, keeping in mind this excludes land, fencing, and landscaping.

Why the “Square Metre Rate” is Just a Starting Point

Think of a square metre rate like the price of a car’s base model. It covers the engine and the wheels, but it doesn’t include the tow bar, the tinted windows, or the upgraded stereo. In the same way, a standard rate often assumes a simple, rectangular floor plan on a flat section. If your design includes complex corners, high ceilings, or expensive cladding, that rate will climb quickly. Every extra corner in a foundation requires more labour and materials. Additionally, 2026 compliance requirements and healthy homes standards mean that even a “basic” build now includes higher-quality insulation and ventilation than houses built just a few years ago, which adds to that baseline cost.

The 2026 Economic Landscape for Kiwis

The current market shows a mix of slowing inflation and lingering instability in material prices. While we aren’t seeing the double-digit spikes of previous years, builders are still cautious about offering fixed-price contracts because the price of timber or steel can still fluctuate. Waiting for prices to “drop” is rarely a winning strategy; historically, building costs in New Zealand tend to plateau rather than fall. Instead of waiting, the smartest move is to get your finance sorted early. Using a mortgage calculator can give you a rough idea of your limits, but getting a professional pre-approval is what allows you to talk to builders with real confidence. Having your funding strategy ready before you fall in love with a set of architectural plans prevents the heartbreak of a project that’s simply too expensive to finish.

Breaking Down the ‘Per Square Metre’ Myth

Many people get caught up in the “headline” rate, but the cost to build a house nz 2026 varies wildly based on your chosen construction style. A kitset home might start at the lower end around $2,500 per square metre, while a standard group home usually sits between $3,000 and $4,500. If you’re looking at a premium architectural project, you could easily see figures between $5,000 and $8,000 per square metre. According to official building activity data, the actual value of work being put in place reflects this complexity. It’s not just about the size of the floor plan; it’s about the level of finish and the structural requirements of the design.

Your choice of materials acts like a volume knob for your budget. Switching from basic brick to high-end cedar cladding or opting for a complex steel roof instead of standard tiles will push your costs up quickly. Then there’s the “two-storey tax”. While building up saves on land, it adds significant costs for scaffolding, floor joists, and structural engineering. Often, a larger single-storey home is actually cheaper to build than a smaller two-storey one because the construction process is much simpler.

  • Entry-Level: $2,500 – $3,000 per sqm (Basic kitsets or budget group builds)
  • Mid-Range: $3,000 – $4,500 per sqm (Standard group builders and simple custom designs)
  • High-End: $5,000 – $8,000+ per sqm (Architectural designs with premium finishes)

Group Builders: The Entry-Level Pathway

Group builders are a popular choice because they buy materials in bulk, passing those “economies of scale” savings on to you. They use standardised plans, which makes the process more predictable and faster. In 2026, the key is looking for a fixed-price contract that clearly defines what’s included. These contracts offer peace of mind for your bank, but remember that any customisation or change to the plan will likely trigger an extra cost that can quickly eat into your contingency fund.

Architectural and Custom Builds

Architectural builds are for those who want something truly unique, but they come with a higher price tag. You’re paying for specialised design work and often more complex site requirements. These projects usually require a much larger mortgage, so it’s vital to align your “dream” with your actual borrowing power before the first sketch is drawn. If you’re unsure where your limit sits, it’s a good idea to talk with a specialist who can help you understand your financial boundaries before you fall in love with a plan that’s out of reach.

The ‘Hidden’ Extras: Siteworks, Consents, and Consumables

When you’re calculating the cost to build a house nz 2026, the builder’s quote is often just the visible part of the iceberg. Beneath the surface lie the “hidden” extras that can derail a budget if they aren’t factored in from the start. These aren’t just minor details; they are fundamental requirements like getting power to your front door or ensuring the ground can actually support your home. According to the latest building cost statistics from Stats NZ, these non-construction expenses are becoming a larger portion of the total project investment.

Utility connections are a prime example. Bringing power, water, and fibre from the street to your house can cost thousands, especially on rural or large sections where the house is set back from the road. Then there’s the finish. Many people leave landscaping and driveways out of their initial loan, only to find they’ve run out of cash when it’s time to move in. Including these in your total project budget ensures you aren’t living in a sea of mud for the first year or struggling to get your final code compliance certificate because the driveway isn’t finished.

The Ground Under Your Feet

Earthworks and retaining walls are the real budget killers of 2026. A “cheap” section on a steep slope might look like a bargain, but the price of cutting, filling, and securing that land can easily wipe out any savings. Soil tests are non-negotiable now. If the ground is soft or unstable, you’ll need deeper foundations or specialised engineered slabs. Banks are notoriously cautious about tricky sections because the risk of a budget blowout is much higher. It’s always a smart move to get a geotechnical report before you commit to buying the land, as this gives your lender the confidence they need to approve your finance.

Council and Professional Fees

You’ll need to budget for architects, engineers, and building consents before the first nail is driven. Development contributions are another factor; they’re a fee charged by councils to fund local infrastructure like pipes and roads. These costs can be substantial and are often due early in the process. If you haven’t planned your cash flow, these upfront bills can be a major hurdle. You can use our mortgage calculator to see how including these professional fees and council charges in your loan might change your monthly repayments and overall borrowing strategy.
Cost to Build a House in NZ 2026: Your Full Financial Breakdown

Funding Your Build: From Mainstream Banks to 2nd Tier Options

Securing the money for your project is often more complex than choosing the floor plan. When you look at the total cost to build a house nz 2026, you need a lender who understands that construction isn’t a one-off payment. Most construction loans work through a “drawdown” process. Instead of giving you all the money at once, the bank releases funds in stages as your builder reaches specific milestones, like finishing the foundation or getting the roof on. This keeps your interest costs lower at the start and ensures the builder is only paid for work they’ve actually done.

While the big household-name banks are the first stop for many, they aren’t always the best fit. A 2nd tier loan is a tactical tool that can bridge the gap when mainstream criteria are too rigid, allowing you to start your build now rather than waiting years for a perfect bank profile. This is where a broker becomes your biggest asset. We have access to rates and terms you won’t find on a standard website, and we know exactly how to pitch your story to the right lender to get a “yes”.

What if the Bank Says No?

Mainstream banks love a simple salary, but many Kiwis today are self-employed or have income from several different places. If a big bank declines your application, it’s usually because your financial profile doesn’t fit their narrow box. 2nd tier lenders look at the bigger picture, focusing on your ability to handle the repayments rather than just a tick-box exercise. You can learn more about how these different lending paths work at our Mortgage School.

The Contingency Buffer

In 2026, a 10-15% contingency buffer is a non-negotiable part of your budget. This “just in case” fund protects you if material prices shift or if those hidden siteworks mentioned earlier cost more than expected. The beauty of a well-structured construction loan is that you only pay interest on the money you’ve actually drawn down. If you don’t need the full buffer, you don’t pay for it. If you already own a home, you might even be able to use the equity in that property to fund your new project, which can be a much smoother path than trying to save a massive cash deposit from scratch.

If you’re ready to see which funding option fits your build, get in touch with our team to discuss your project today.

How to Organise Your Construction Finance Without the Stress

Planning your dream home is exciting, but the financial side can quickly feel overwhelming if you don’t have a clear roadmap. The first and most vital step is to get an honest appraisal of your borrowing power before you even look at a floor plan. Knowing exactly how much you can afford for the cost to build a house nz 2026 prevents the heartbreak of designing a home that the bank simply won’t fund. Once you have your budget, it’s time to assemble your “A-Team”. This should include an experienced mortgage broker, a solicitor who understands construction contracts, and a designer who respects your financial boundaries.

When you finally have a contract in front of you, read it with a fine-tooth comb. Pay close attention to the “variations” clause. In 2026, these clauses often allow builders to pass on unexpected material price hikes to you. You need to know exactly what happens to your loan if the price shifts mid-build. Throughout the construction process, keep the communication lines open with your broker. We handle the paperwork for each stage of the drawdown, so letting us know when a milestone is approaching ensures your builder gets paid on time and your project stays on track.

Getting Your Paperwork Sorted

Lenders need more than just a handshake to approve a construction loan. They’ll want to see detailed plans, full specifications, and a signed build contract. It’s important to realise that “fixed-price” doesn’t always mean the final bill is set in stone. Many 2026 contracts include allowances for things like siteworks that might change once the digging starts. If you’re looking at a larger-scale project rather than a single family home, you might find our Property Development Loans NZ guide helpful for navigating those more complex funding requirements.

Partnering with an Expert

Krish Krishna and the team at Mortgage Suite are the steady hands you need during this process. We’ve spent over 20 years helping Kiwis navigate the banking world, and we’re passionate about finding solutions when the big banks make things difficult. We take the stress out of the paperwork and the negotiation so you can focus on the fun parts, like choosing your kitchen colours and floor plans. Our reputation is built on being dedicated advocates for our clients, ensuring you get the best possible terms for your situation. You can read our client reviews to see how we’ve helped others turn their building dreams into reality. If you’re ready for a straight-talk chat about your project, get in touch with Mortgage Suite today and let’s get your build moving.

Ready to Turn Your Building Plans into Reality?

Building a home is about more than just the floor plan; it’s about having a rock-solid financial strategy from day one. By now, you know that the true cost to build a house nz 2026 includes those often-forgotten siteworks and council fees that can catch people out. You also understand that the right team can help you bridge the gap between a builder’s initial quote and your final move-in budget. Having a clear picture of your total project costs allows you to make decisions with certainty rather than guesswork.

With over 20 years of banking experience, our team has helped countless Kiwis secure the funding they need, even when mainstream banks say no. We specialise in finding flexible solutions through 2nd tier loans that work for your unique financial profile. We take the stress out of the paperwork so you can focus on the excitement of your build. Book a free, no-obligation chat with our experts to get your project moving with confidence. Your new home is closer than you think when you have a steady, expert hand guiding you through the process.

Frequently Asked Questions

Is it actually cheaper to build or buy an existing house in NZ in 2026?

Building a new home often has a higher upfront price tag in 2026 compared to buying an existing property, but it offers better long-term value. New builds are more energy-efficient and come with modern warranties, which saves you thousands on maintenance and heating. While an older house might look cheaper initially, you’ll often face hidden costs for renovations or repairs that a new construction project simply won’t have.

How much of a deposit do I really need for a construction loan?

Mainstream banks usually look for a 20% deposit for a construction loan, but there are pathways for first-home buyers to start with as little as 10%. If you already own the section, the equity in that land can often serve as your deposit. We’ll help you look at your total assets to see if we can secure a loan without you needing to find a massive pile of cash upfront.

What is a 2nd tier lender and why would I use one instead of a big bank?

2nd tier lenders are non-bank institutions that offer more flexibility than mainstream banks. They’re a fantastic choice for self-employed Kiwis or those with non-standard income who don’t fit the big banks’ rigid criteria. At Mortgage Suite, we specialise in these solutions to ensure you can still build your home even if the household-name banks have turned you away. It’s about finding a lender that sees your potential.

Can I use my KiwiSaver to help pay for the cost to build a house?

Yes, you can usually withdraw your KiwiSaver savings to help cover the cost to build a house nz 2026 if it’s your first home. These funds are typically used for the land deposit or the initial construction stages. You’ll need to check with your provider for specific eligibility rules, as the money usually needs to be in your account for at least three years before you can access it for a build.

What happens if the building costs go over the original quote?

If your project goes over the original quote, you’ll rely on your contingency fund, which should be 10-15% of the total budget. This is why we stress the importance of a realistic budget from the start. If the increase is significant, you’ll need to talk to your broker immediately to see if your loan facility can be extended before the builder continues with the extra work.

How long does it usually take to get a construction loan approved?

Getting a construction loan approved usually takes between 10 and 15 working days. This timeframe is longer than a standard mortgage because the lender needs to review your build contract, detailed plans, and a valuation as if complete. Being organised with your paperwork from the start is the best way to speed up the process and get your project moving without unnecessary delays.

Are there any grants available for first-home builders in 2026?

First-home builders in 2026 should look into the First Home Grant and other government support schemes. These grants can provide a helpful boost to your deposit, provided you meet the income and house price caps. We recommend checking the latest criteria early in your planning phase, as these rules can change and may impact how much you’re able to borrow for your new home project.

What is the “builder’s margin” and is it negotiable?

The builder’s margin is a percentage, usually between 10% and 20%, added to the cost of materials and labour to cover the builder’s overheads and profit. While it might seem like a lot, it’s what keeps the building company running and ensures they can manage your project professionally. It’s generally not negotiable, as trying to cut this margin often leads to lower-quality work or a builder who can’t finish the job.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Buying Land and Building a House in NZ: Your Step-by-Step 2026 Guide

You’ve likely spent months scrolling through floor plans and dream kitchen designs, but the most important blueprint for your new home isn’t the one drawn by an architect; it’s the one drafted by your lender. Buying land and building a house nz can feel like a mountain of paperwork and hidden “gotchas,” especially when you start hearing about development contributions or complex loan drawdowns. It’s completely normal to feel a bit overwhelmed by the fear of costs spiralling out of control or the worry that a mainstream bank might turn you down just because your situation doesn’t fit their standard box.

We believe you deserve more than just a loan; you need the peace of mind that comes from having a seasoned expert in your corner. At Mortgage Suite Ltd, we specialise in helping you navigate the 2026 landscape, from managing the latest building levy changes to mastering the stage-by-stage payment process. This guide is designed to strip away the confusion and show you exactly how to secure your section and unlock the specialised construction finance required to finally get the keys to a place you call home.

Key Takeaways

  • Get your finance pre-approved before you start looking at sections so you can bid with the confidence of knowing your true spending limit.
  • Understand the unique stages of buying land and building a house nz, including how “progressive drawdowns” keep your build moving from the slab to the final sign-off.
  • Identify potential hidden expenses like council development contributions early on to ensure your budget remains realistic and stress-free.
  • Explore how second-tier lenders can provide a vital lifeline for your project if the mainstream banks aren’t willing to help.
  • Learn how an expert broker acts as your personal negotiator to streamline the complex communication between you, your builder, and the bank.

Is Buying Land and Building a House in NZ Right for You?

Deciding between an existing property and a fresh start is the first major hurdle you’ll face. While an older home offers the convenience of moving in next month, buying land and building a house nz provides a blank canvas to create a space that actually works for your family. It’s a choice between the “what you see is what you get” reality of the current market and the long-term satisfaction of a home designed specifically for your lifestyle. In 2026, this decision carries even more weight as building standards continue to evolve, making new homes significantly more efficient than those built even a decade ago.

Buying a section means engaging with New Zealand’s land registration system, a process that ensures your ownership is legally secure and clearly documented. However, the physical reality of that dirt is what really matters for your wallet. The slope of the land, the soil type, and how easily you can connect to water and power will dictate your entire build budget. We often see people fall in love with a view, only to realise later that the cost of the foundations will eat up half their kitchen budget. It’s about balancing your vision with the practicalities of the site.

The Pros of Starting from Scratch

The most obvious benefit is customisation. You aren’t trying to fit your life into someone else’s old floor plan; you’re building for the way you live now. Beyond the layout, a new build in 2026 means your home will be warmer, drier, and healthier. Modern building codes require high-performance insulation and double glazing that older Kiwi homes simply can’t match. You’ll also enjoy much lower maintenance costs in those first ten years. Most builders provide a Master Build guarantee, giving you a steady hand to rely on if any structural issues arise, which offers a level of peace of mind you won’t get with a 1970s bungalow.

The Challenges to Keep in Mind

Building isn’t without its hurdles, and timeline uncertainty is the biggest one. Weather delays, council consent hold-ups, and material supply shifts can push your move-in date out by months. Financially, it’s also more complex than a standard mortgage. You’ll likely be managing interest on your land loan while also preparing for progressive payments as the house goes up. This is why we always insist on a healthy contingency fund. We recommend setting aside at least 10% to 15% of your total build cost to cover those unexpected “site works” or price adjustments that often pop up once the diggers start moving dirt. Being prepared for these shifts makes the process a lot less stressful.

The 5 Essential Steps to Buying Land and Starting Your Build

While many people start their journey by driving through new subdivisions on a Sunday afternoon, the real work begins much earlier. To succeed when buying land and building a house nz, you need a logical plan that protects your bank account and your sanity. Following a structured path ensures you don’t fall in love with a section you can’t afford or a design that a lender simply won’t back. It starts with your budget and ends with the first shovel in the ground.

  • Step 1: Get your finance sorted. Before looking at dirt, you must know your borrowing limit. Banks typically require a 20% deposit for urban land, but this can jump to 50% for rural blocks. Knowing these numbers early prevents heartbreak later.
  • Step 2: Find the right section. Look beyond the view. Consider the sun’s path, the slope of the land, and how much “site work” will be needed before the slab can even be poured.
  • Step 3: Perform due diligence. This is the investigation phase. You’ll need to check the title, the council files, and the physical state of the ground.
  • Step 4: Select your partners. You need to find a qualified builder who understands your vision and, more importantly, your budget. A solid reputation is worth more than the lowest quote.
  • Step 5: Finalise the loan. Once you have a fixed-price contract, your broker can secure the construction finance, allowing for the first drawdown to pay for the initial stages of work.

If the numbers feel a bit daunting, remember that you don’t have to crunch them alone. A quick chat to the team at Mortgage Suite Ltd to organise your pre-approval can clarify exactly where you stand before you sign any contracts.

Due Diligence: What to Check Before You Sign

In New Zealand, a Geotech report is a non-negotiable. Our varied landscape means one section might be solid rock while the neighbour’s is soft clay; this report tells your builder exactly how deep the foundations need to go. You should also examine the Land Title for easements, which are legal rights for others to use part of your land, or covenants that might restrict what colour you can paint your roof. Finally, check that services like water, power, and high-speed fibre are already at the boundary, as bringing these in from the street can cost a small fortune.

Choosing Your Build Method

You generally have two paths: a house and land package or a standalone build. Packages are often simpler because the developer has already handled the consents and basic design. However, if you’re building on your own bare land, you’ll likely need a fixed-price contract. Lenders in 2026 are very cautious about cost-plus arrangements where the price can float. They want to see exactly what the final bill will be before they agree to the loan, which protects you from nasty surprises halfway through the project.

Buying a finished home is a lot like buying a car; you pay the price and drive it away. However, buying land and building a house nz is more like a subscription service where you pay as you go. A construction loan is fundamentally different from a standard mortgage because the bank doesn’t give you all the money at once. Instead, they release funds in chunks, known as “drawdowns,” only after specific milestones are reached on-site. This keeps the project on track and ensures the bank isn’t lending more than what the property is currently worth at any given moment.

The “progressive drawdown” process usually follows the natural rhythm of your build. You’ll start with an initial payment for the land, followed by stages like the floor slab, the wall framing, the roof, and the final interior fit-out. Before the bank pays out each stage, they’ll want to see an invoice from your builder. Sometimes, they’ll even send a valuer to the site to check that the house actually has a roof before they pay for one. This methodical approach might feel like extra paperwork, but it’s a safety net that ensures your builder is being paid for work actually completed. For more details on homeowner rights during this phase, the official government guide to building is a great resource to have on hand.

One of the best features of these loans is that they are typically interest-only during the construction phase. This is a lifesaver for your weekly budget. Since you’re likely still paying rent or a mortgage elsewhere while you wait for the keys, you only pay interest on the amount you’ve actually drawn down. If you’ve only used $100,000 for the land and the slab, you only pay interest on that $100,000, not the full $800,000 loan. This keeps your costs manageable until the day you finally move in and convert to a standard principal and interest mortgage.

Mainstream Banks vs 2nd Tier Lenders

If your local bank branch says “no” because your deposit is a bit light or your income is slightly unconventional, don’t pack up your tools just yet. Second-tier lenders often provide the flexibility that big banks lack. They are often more willing to look at the overall value of your project rather than just ticking boxes. These non-bank lenders can be the perfect bridge to get your project off the ground, especially for land purchases that don’t fit the standard criteria. You can find out more about these alternative options in our 2nd tier lender New Zealand guide.

Using Equity and KiwiSaver

You don’t always need a pile of cash sitting in a savings account to start. If you already own a property, you might be able to use the equity in that home to cover your new deposit. For those starting from scratch, KiwiSaver remains a powerful tool. In 2026, you can still withdraw your savings for a first home build, provided you’ve been a member for at least three years. We cover all the latest rules and tips in our home loans for first home buyers New Zealand guide to ensure you’re making the most of every dollar available to you.

Budgeting for Your Build: Hidden Costs and How to Avoid Them

When you’re buying land and building a house nz, the number at the bottom of your build contract is rarely the number you’ll see on your final bank statement. It’s easy to get swept up in the excitement of choosing tiles and tapware, but the real budget killers are the costs that never even make it onto the builder’s quote. Understanding these “invisible” expenses early is the difference between a smooth project and a stressful financial scramble halfway through the frame stage.

One of the most significant surprises for new builders is the development contribution. Councils charge these fees to fund the extra pressure your new home puts on local infrastructure like water pipes, sewerage, and roading. Depending on your region, this can add thousands to your total. You also need to account for professional fees before a single nail is driven. Architects, surveyors, and structural engineers all play a vital role in getting your plans approved, and their expertise is essential for navigating the complex soil conditions often found across New Zealand.

Don’t forget the “finishing” costs that many standard contracts leave out. It’s common for a build price to exclude the driveway, fencing, basic landscaping, and even your letterbox or clothesline. If you don’t budget for these from day one, you might find yourself living in a beautiful new home surrounded by a sea of mud. To get a realistic view of your borrowing capacity and account for these hidden fees, book a strategy session with our team today.

The Council and Consent Maze

You’ll need to navigate two main types of permission: resource consent and building consent. Resource consent deals with how your home affects the land and neighbours, while building consent ensures the structure itself is safe and up to code. In 2026, it’s vital to plan for council fee increases and the new combined building levies which aim to streamline the process. Your goal is the Code Compliance Certificate (CCC); this is the most important document you’ll ever own, as it proves the house is finished correctly and allows the bank to finalise your loan.

Managing Your Contingency Fund

Lenders almost always insist on a 10% to 15% contingency buffer before they approve a construction loan. This isn’t just “extra money” for the bank; it’s a safety net for “variations” that occur once work begins. Perhaps the diggers found unexpected rock underground, or you decided to upgrade the kitchen cabinetry at the last minute. A fixed-price contract is your best friend because it provides a legal shield against fluctuating material costs and ensures the bank has a clear figure to lend against. Having that buffer ready means these small changes won’t bring your entire build to a grinding halt.

Making It Happen: How an Expert Broker Simplifies the Build Process

Navigating the financial side of buying land and building a house nz is often the most stressful part of the entire project. While your builder focuses on the physical structure, you need someone who understands the inner workings of the banking world to ensure the money keeps flowing. This is where a specialist broker becomes your most valuable asset. We don’t just find you a loan; the team at Mortgage Suite Ltd acts as your dedicated negotiator, ensuring the bank’s requirements align with your builder’s timeline and your personal budget.

We bridge the gap between your vision and the bank’s rigid boxes. We manage the constant back and forth communication between you, your lender, and your construction team. This means when a drawdown is due or a variation occurs, you aren’t stuck in the middle trying to translate banking speak into builder speak. We organise the paperwork and the approvals so you can stay focused on the exciting parts of your new home without the administrative headache.

The Mortgage Suite Ltd Advantage

Our approach is built on Krish Krishna’s 20 plus years of deep banking experience. Having seen the process from inside the big banks, Krish knows exactly how to present your application to get a “yes” faster. We also offer a significant advantage by looking beyond the high street lenders. If your project doesn’t fit standard criteria, we can tap into our network of 2nd tier loans that offer more flexibility for unique builds or smaller deposits. We take pride in making these complex financial structures feel simple, conversational, and easy to follow.

Ready to Start Your Build Journey?

The first step is always the most important. We offer a personalised assessment to help you understand your true borrowing power before you sign any contracts. We’ll help you organise your documents and create a clear finance plan that covers everything from the initial land purchase to the final council sign-off. If you’re looking at larger scale builds or multi unit sites, you might also find our property development loans NZ guide particularly useful for understanding how to fund your next big project. Let’s get your build moving with confidence and a professional in your corner.

Ready to Turn Your Vision Into a Reality?

Building your own home is a massive undertaking, but it’s also one of the most rewarding ways to secure your future in New Zealand. We’ve explored how the right section dictates your budget and how to manage the unique “pay as you go” nature of construction loans. By staying ahead of hidden council fees and keeping a solid contingency buffer, you can avoid the common pitfalls that often trip up first-time builders.

Success when buying land and building a house nz comes down to having a steady hand to guide you through the banking maze. We bring over 20 years of industry experience to the table, specialising in 2nd tier lending for those who don’t fit the standard bank boxes. Our team is dedicated to providing personalised, jargon-free advice that makes your finance feel like the easiest part of the build.

You have the dream; now it’s time to build the foundation. Chat with Krish and the team at Mortgage Suite today to plan your build finance and take that first confident step toward your new front door. Your dream home is closer than you think.

Frequently Asked Questions

Can I use my KiwiSaver to buy land if I am not building immediately?

No, you generally cannot use your KiwiSaver funds just to hold onto a piece of land. To make a withdrawal, you must intend to build your first home on that section as your primary residence. Lenders and the government usually require a clear plan or a build contract to prove that construction will start within a reasonable timeframe after the land purchase is finalised.

How much deposit do I need to buy land and build in NZ in 2026?

Most New Zealand banks require a minimum 20% deposit for vacant residential land within urban boundaries. If you are looking at lifestyle blocks or rural land, this requirement often increases to between 30% and 50%. However, when buying land and building a house nz as part of a total package, some specific schemes may allow eligible buyers to start with as little as a 5% deposit.

What is a Master Build guarantee and why do lenders want to see it?

A Master Build guarantee is a 10-year protection plan that covers structural defects, workmanship issues, and builder insolvency. Lenders insist on seeing this because it significantly reduces their financial risk. It provides a safety net that ensures the project will be completed even if the builder runs into trouble, protecting both your investment and the bank’s security.

How do progress payments (drawdowns) work during a build?

Progress payments are released in stages as your builder hits specific milestones on the construction site. Instead of getting the full loan at the start, the bank pays out for completed work such as the floor slab, framing, and the roof. This methodical process ensures that the builder is paid fairly for work already done while keeping the project on a strict financial schedule.

Can I get a loan for a tiny house or a transportable home on bare land?

Yes, it is possible, but it is often more complex than a standard residential loan. Most mainstream banks require the home to be fixed to permanent foundations and connected to all essential services before they will consider it a mortgageable property. If the big banks aren’t comfortable with your project, we can often find more flexible options through our network of second-tier lenders.

What happens if my build goes over budget during construction?

If your build costs exceed the original estimate, you will typically use your 10% to 15% contingency fund first. If the costs climb even higher, you may need to apply for a loan top-up or contribute more of your own savings. This is why we always advocate for a fixed-price contract, as it provides a legal shield against unexpected price hikes for materials or labour.

Is interest-only the best way to pay for a construction loan?

Interest-only repayments are a popular choice during the build phase because they keep your weekly costs low while you might still be paying rent or another mortgage. You only pay interest on the amount of the loan you have actually used. Once the house is finished and you have your final council sign-off, the loan usually converts to a standard principal and interest mortgage.

How long does it take to get a construction loan approved in NZ?

You should generally allow between 5 and 10 working days for a construction loan approval, provided your paperwork is complete. The process can take a bit longer if the bank needs to review detailed build contracts, Geotech reports, or specific council consents. Having a broker organise your application upfront ensures the bank has everything they need to give you a faster answer.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.