
Guarantor Home Loans NZ: The 2026 Guide to Buying Sooner

You’ve spent years skipping holidays and tightening your belt, yet every time you get close to a deposit, New Zealand house prices seem to take another leap out of reach. It’s exhausting to feel like you’re doing everything right while the market moves faster than you can save. This is why many first home buyers are now looking at guarantor home loans NZ as a way to bridge the gap. We know it feels daunting to ask for help, and the fear of being locked out of the market forever is a heavy weight to carry.

The good news is that a family guarantee can help you secure your home much sooner than you thought possible. You don’t need to wait another decade to save a massive deposit when there’s a professional way to use existing family home value safely. In this 2026 guide, we’ll show you exactly how these loans work; we’ll explain how to protect your loved ones’ assets while you get ahead and provide a clear roadmap to your own front door. You’ll gain the confidence to move forward and understand the process without getting lost in confusing bank talk.

Key Takeaways

  • Learn how a family guarantee acts as a bridge to help you meet bank deposit requirements without years of extra saving.
  • Discover how guarantor home loans NZ can be organised with limited guarantees to protect your family’s assets and cap their financial risk.
  • Understand the essential safety nets, including the requirement for independent legal advice, to ensure everyone involved is fully protected.
  • Get a clear, step-by-step roadmap for the application process, from the first conversation to getting the keys to your new home.
  • Find out why working with a specialist negotiator is the best way to navigate different bank rules and keep family relationships stress-free.

What is a guarantor home loan and how does it work in NZ?

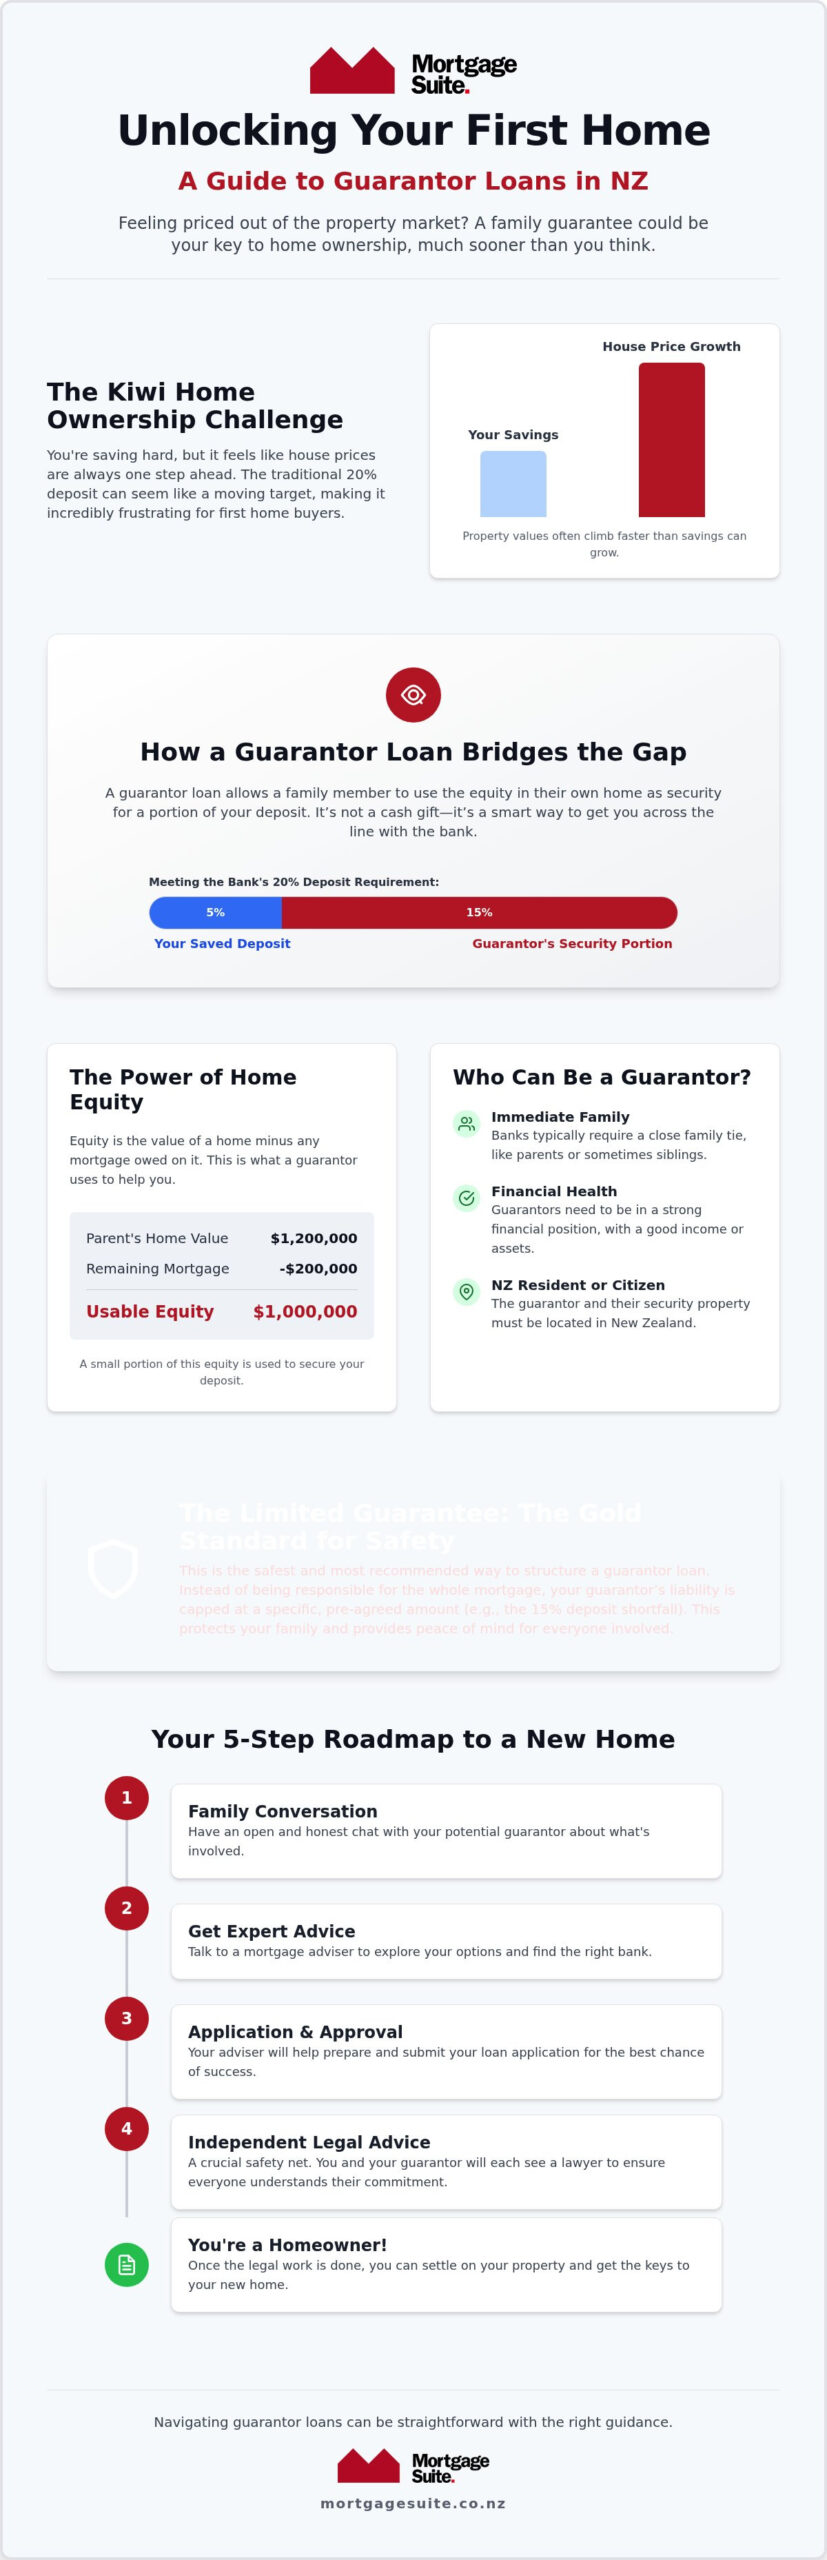
Buying your first home in New Zealand often feels like trying to hit a moving target. Just as you save up a decent amount, house prices shift again, and that 20% deposit the banks demand feels further away than ever. This is where guarantor home loans NZ come into play as a strategic tool. A guarantor home loan is a formal promise by a family member to cover a specific portion of the mortgage if needed. It isn’t a gift of cash; rather, it’s a legal arrangement that uses the value in a family member’s property to help you get across the line.

Think of this setup as a financial bridge. Most mainstream banks want you to have a 20% deposit to avoid extra fees or higher interest costs. If you’ve only saved 5%, a guarantor can provide a “security guarantee” for the remaining 15%. This allows you to buy your home now instead of waiting another five years to save. It’s a way to get into the market sooner, which is vital when property values are climbing faster than most people can put money aside in a savings account. If you want to dive deeper into how these basics work, our Mortgage School has plenty of resources to help you get started.

The role of equity in a guarantee

To understand how this works, you need to understand equity. Equity is simply the difference between what a house is worth and what is still owed on the mortgage. If your parents’ home is worth $1.2 million and they only owe $200,000, they have $1 million in equity. Banks “lock” a small slice of that equity to act as your deposit. This is often a much better option for Kiwi families than a cash gift. It keeps the parents’ savings intact and sitting in the bank, while their “house value” does the heavy lifting for the next generation. It’s a smart way to use existing family wealth without anyone needing to physically hand over a cheque.

Who can be a guarantor in New Zealand?

Not everyone can step into this role. In the world of guarantor home loans NZ, banks are quite specific about who they’ll accept. Usually, this role is reserved for immediate family members, such as parents or sometimes siblings. The bank needs to know that there is a strong, permanent bond between you and the person helping you.

Lenders also look at the guarantor’s own financial health. They prefer people who are still working or have significant assets because they want to ensure the guarantor can actually handle the responsibility if things go wrong. Most importantly, the person providing the guarantee must be a New Zealand resident or citizen. We’ve seen many cases where a family member wants to help from overseas, but local banks almost always require the security to be located right here in New Zealand.

Common ways to organise a guarantor loan

When you start looking at guarantor home loans NZ, you’ll quickly realise there isn’t just one way to set things up. Banks offer different structures depending on what you need and what your family is comfortable with. The most common split is between a limited guarantee and a full guarantee. A full guarantee means the person helping you is responsible for the whole loan, which is quite a big ask and rarely recommended. Most families prefer a limited version where the risk is managed and clear from day one.

You might also hear about servicing guarantees. This is a bit different because it helps you meet the bank’s income rules rather than just the deposit requirement. If your salary is just a bit short of what the bank wants to see, a family member can sometimes step in to support the repayments in the bank’s eyes. It’s also vital to know the difference between being a co-borrower and a guarantor. A co-borrower owns part of the house and is equally responsible for every cent of the debt. A guarantor doesn’t own the property; they simply provide extra security to help you get the keys.

The Limited Guarantee: Keeping things safe

This is the gold standard for protecting your family. With a limited guarantee, we specify an exact dollar amount that your guarantor is responsible for. If you need $100,000 to reach your 20% deposit, that’s the only amount they secure. This caps their risk and gives everyone peace of mind. As your home value goes up over time, or as you pay down the mortgage, you can eventually ask the bank to release the guarantee. This means your parents can get their names off your loan once you have enough equity of your own. If you’re unsure about how to structure this, chatting with an expert can help clarify the best path for your family.

Gifting vs. Guaranteeing

Many people wonder if it’s better for parents to just give them a cash gift. Gifting cash is simple, but it means the parents lose access to those funds forever. Using a guarantee allows them to keep their savings in their own accounts while using the paper value of their home to help you. The main pro of a gift is that it’s clean with no ongoing legal ties, but the downside is the immediate hit to the parents’ bank balance. A guarantee is often more sustainable for families who want to help without affecting their daily retirement funds. You can find more detail on different ways to build your deposit at our Mortgage School.

Managing risks and protecting your family

It’s natural to feel a bit of a knot in your stomach when you think about mixing family with finances. The question we hear most often is: “What happens if I can’t make my mortgage payments?” When setting up guarantor home loans NZ, we build in layers of protection to ensure your parents’ home is never at unnecessary risk. It’s about being proactive rather than reactive, making sure everyone feels secure before any papers are signed.

One of the most important safety nets in New Zealand is the requirement for independent legal advice. Your parents or family members must speak with their own lawyer before agreeing to anything. This ensures they aren’t just taking your word for it; they get a professional, unbiased view of the commitment. It’s a crucial step that keeps everyone’s eyes open and protects the family bond. We’ve seen hundreds of these arrangements, and the ones that work best are built on total transparency.

Most importantly, you need to remember that a guarantee is not forever; it is a temporary leg-up until you have enough equity of your own. It’s a tool to get you started, not a lifelong burden for your family. The goal is always to get them off the loan as quickly as the bank allows.

The exit strategy

We start planning your parents’ exit from the loan before you even get the keys. The aim is to reach 20% equity in your new home, at which point the bank no longer needs that extra security. This happens through a combination of your regular repayments and any growth in the property’s value. Once you’ve reached that threshold, you can formally apply to the bank to discharge the guarantee. You can use our mortgage calculator to see how even small extra repayments can help you reach that goal years sooner.

Insurance and safety nets

To keep things truly stress-free, we always suggest looking at income protection. This acts as a shield; if you’re unable to work due to illness or injury, the insurance covers your mortgage costs so your guarantor isn’t affected. Beyond the paperwork, the best protection is a good old-fashioned “kitchen table” chat. Being honest about your budget and your long-term plans ensures there are no surprises down the track. When everyone is on the same page, the process moves from being a source of anxiety to a shared family success story.
Guarantor Home Loans NZ: The 2026 Guide to Buying Sooner

The application process: From chat to keys

The path to owning your first home doesn’t have to be a mystery. When you’re looking into guarantor home loans NZ, the process is quite structured, moving from a simple conversation to holding the keys in your hand. We break it down into five clear steps so you always know what’s coming next. It starts with an initial chat where we look at your situation to see if a guarantee is the right fit for you and your family. We want to make sure everyone is comfortable before moving a single centimetre forward.

Once we agree it’s the right path, we do the heavy lifting on the numbers. We check how much equity your guarantor has and, crucially, look at your own ability to handle the repayments. Following this, we get you a pre-approval. This is your golden ticket; it gives you the green light to start visiting open homes and making offers with total confidence. After you find the perfect place, the legal teams step in. Your guarantor gets their independent advice, and the bank documents are prepared. Finally, we reach settlement day. This is when the money moves, the deal closes, and you finally get to move into your new home.

If you’re ready to take that first step and see if you qualify, you can book a chat with our team to get started.

What the bank looks for

Even with a family member’s help, the bank still needs to be sure about your personal financial habits. They focus heavily on your ability to pay, looking at whether you can afford the mortgage repayments comfortably on your own salary. They also look at the quality of the house you’re buying; for example, some banks are stricter on apartments than they are on standalone houses. A clean credit history remains essential. Even with a guarantor, banks want to see that you’ve been responsible with your bills and any existing debts over the last few years.

Using a mortgage calculator

Before you fall in love with a specific property, it’s a great idea to run the numbers yourself. Our mortgage calculator is a practical tool that helps you estimate your weekly or fortnightly costs. You can play around with different scenarios to see how your deposit size directly changes your repayments. Using a guarantee to reach a 20% deposit often helps you avoid low equity fees, which keeps more money in your pocket every week. Understanding these costs early on helps you house hunt within a budget that actually fits your lifestyle.

Why work with a broker for your guarantor loan?

Trying to figure out the bank system on your own is often a recipe for stress. Every lender in the country has a different set of rules for guarantor home loans NZ. Some banks are quite relaxed about how much equity a parent needs, while others have very strict limits on the age of the guarantor or their employment status. We know these policies inside out, which means we can point you toward the lender most likely to say yes. Having a broker on your side means you don’t have to spend your weekends guessing or filling out endless forms for banks that won’t fit your specific needs.

Krish Krishna brings over two decades of deep banking experience to every client meeting. He understands the “banker’s mindset” and knows exactly how to package your application to highlight your strengths. This veteran expertise is vital if your situation is a bit outside the box. If a mainstream bank turns you down, we don’t just give up. We can explore 2nd tier and non-bank options that mainstream brokers might not even consider. This gives you a much higher chance of success in a competitive market.

We also act as a vital buffer between you and your family. Mixing money with parents can be awkward, and it’s easy for misunderstandings to crop up. We step in as the professional middleman to handle the sensitive conversations. We explain the risks and the rewards to your parents clearly, so you don’t have to feel like you’re “selling” them on the idea. It keeps the family dynamic positive while ensuring the bank gets exactly what they need.

The benefit of a dedicated negotiator

We don’t just submit your application; we negotiate the terms. This might mean pushing the bank to release the guarantee earlier or fighting for a structure that offers your family more protection. A broker is often far more approachable than a busy bank manager who might see you as just another number. We take the time to listen and build a long-term plan for your homeownership journey. You can read more about our personal, mentor-style approach on our About Us page.

Real stories from Kiwi buyers

The best part of our job is seeing the relief on a buyer’s face when they finally get their own set of keys. We’ve worked with many young Kiwis who felt completely locked out of the property market. By setting up guarantor home loans NZ correctly, they’ve been able to bypass the deposit hurdle and start building their own equity years ahead of schedule. The sense of security that comes with owning your own home in a volatile market is life-changing. Take a look at our Reviews to see how we’ve helped other families achieve their property dreams.

Step into your own home sooner

Owning your first home in New Zealand doesn’t have to be a distant dream. By using a family guarantee, you can bypass the traditional deposit hurdle and start building your own future right now. We’ve explored how these loans act as a temporary bridge, the different ways to organise them safely, and the importance of having a solid exit strategy to protect your loved ones. Understanding guarantor home loans NZ is the first step toward moving out of the rental cycle and into a property you actually own.

With over 20 years of banking experience, we specialise in finding first-home buyer solutions and act as alternative lending experts when the big banks say no. We’re here to guide you through every step of the journey with a professional, mentor-style approach that puts your family first. Chat with Krish about your guarantor options today and let’s turn that homeownership goal into a reality. Your new front door is much closer than it feels.

Frequently Asked Questions

Can I buy a house with no deposit if I have a guarantor?

Yes, it is entirely possible to buy with no cash deposit if your guarantor has enough equity to cover the full amount. If they can secure the 20% deposit the bank requires, you can borrow the rest. However, most lenders still prefer to see that you have some savings of your own to prove you can manage a budget. Having even a small amount of “genuine savings” makes your application much more attractive to the bank.

Do my parents have to pay my mortgage every month?

No, your parents don’t have to make any of your monthly mortgage payments. You are the sole person responsible for the loan, and the payments come directly from your own bank account each month. Your parents only ever become involved if you completely stop paying and the bank has no other way to recover the debt. As long as you manage your budget well, their role is simply to provide the security needed for your deposit.

What happens to the guarantee if my parents want to sell their house?

If your parents decide to sell their property, the guarantee usually needs to be settled or moved to a new house. Since the guarantee is secured against their specific home, the bank will want that portion of the debt paid back from the sale money. However, if they are buying a new place, we can often negotiate with the bank to move the security across. It’s vital to talk to us before they sign any sale papers.

How much equity do my parents need to have to be guarantors?

Generally, your parents need enough equity to cover their own mortgage plus the portion they are guaranteeing for you, with a healthy buffer left over. Most banks want to see that the total debt against their home doesn’t go over 80% of its value. For guarantor home loans NZ, we calculate this by looking at their current house value and subtracting any money they still owe. It’s a straightforward calculation we can do together.

Is a guarantor loan more expensive than a regular home loan?

No, these loans don’t usually cost more than a standard mortgage. In fact, they can actually be cheaper because they help you reach that 20% deposit threshold. This often means you qualify for the bank’s best “special” rates and avoid the extra low-equity fees that people with small deposits are usually charged. It’s a very effective way to keep your weekly costs down while getting into the property market years ahead of schedule.

How long does a guarantor usually stay on the mortgage?

A guarantor typically stays on the mortgage until you have reached 20% equity in your property. This happens over time as you pay down the loan and as the value of your home increases. For most New Zealanders, this process takes anywhere from two to five years. Once you hit that 20% mark, we can formally apply to the bank to release your parents from the agreement, leaving the home and the debt entirely in your name.

What if I am self-employed and want a guarantor loan?

You can certainly get a guarantor loan if you work for yourself, but the bank will want to see a clear history of your business income. Usually, this involves providing at least two years of financial statements and tax returns. If the mainstream banks find your situation a bit too complex, we can look at alternative lending options that are more flexible with self-employed people while still using a family guarantee to help you buy sooner.

Can I use KiwiSaver and a guarantor at the same time?

Yes, combining your KiwiSaver withdrawal with a guarantee is a very effective strategy for many first home buyers. You can use your KiwiSaver funds as your initial cash contribution and then use a family guarantee to top up the rest of the 20% deposit. This approach is often the fastest way to get into a home because it uses every financial tool you have. Using guarantor home loans NZ alongside your savings can significantly lower your overall borrowing costs.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loan Deposit Requirements NZ: Your 2026 Guide to Getting on the Property Ladder

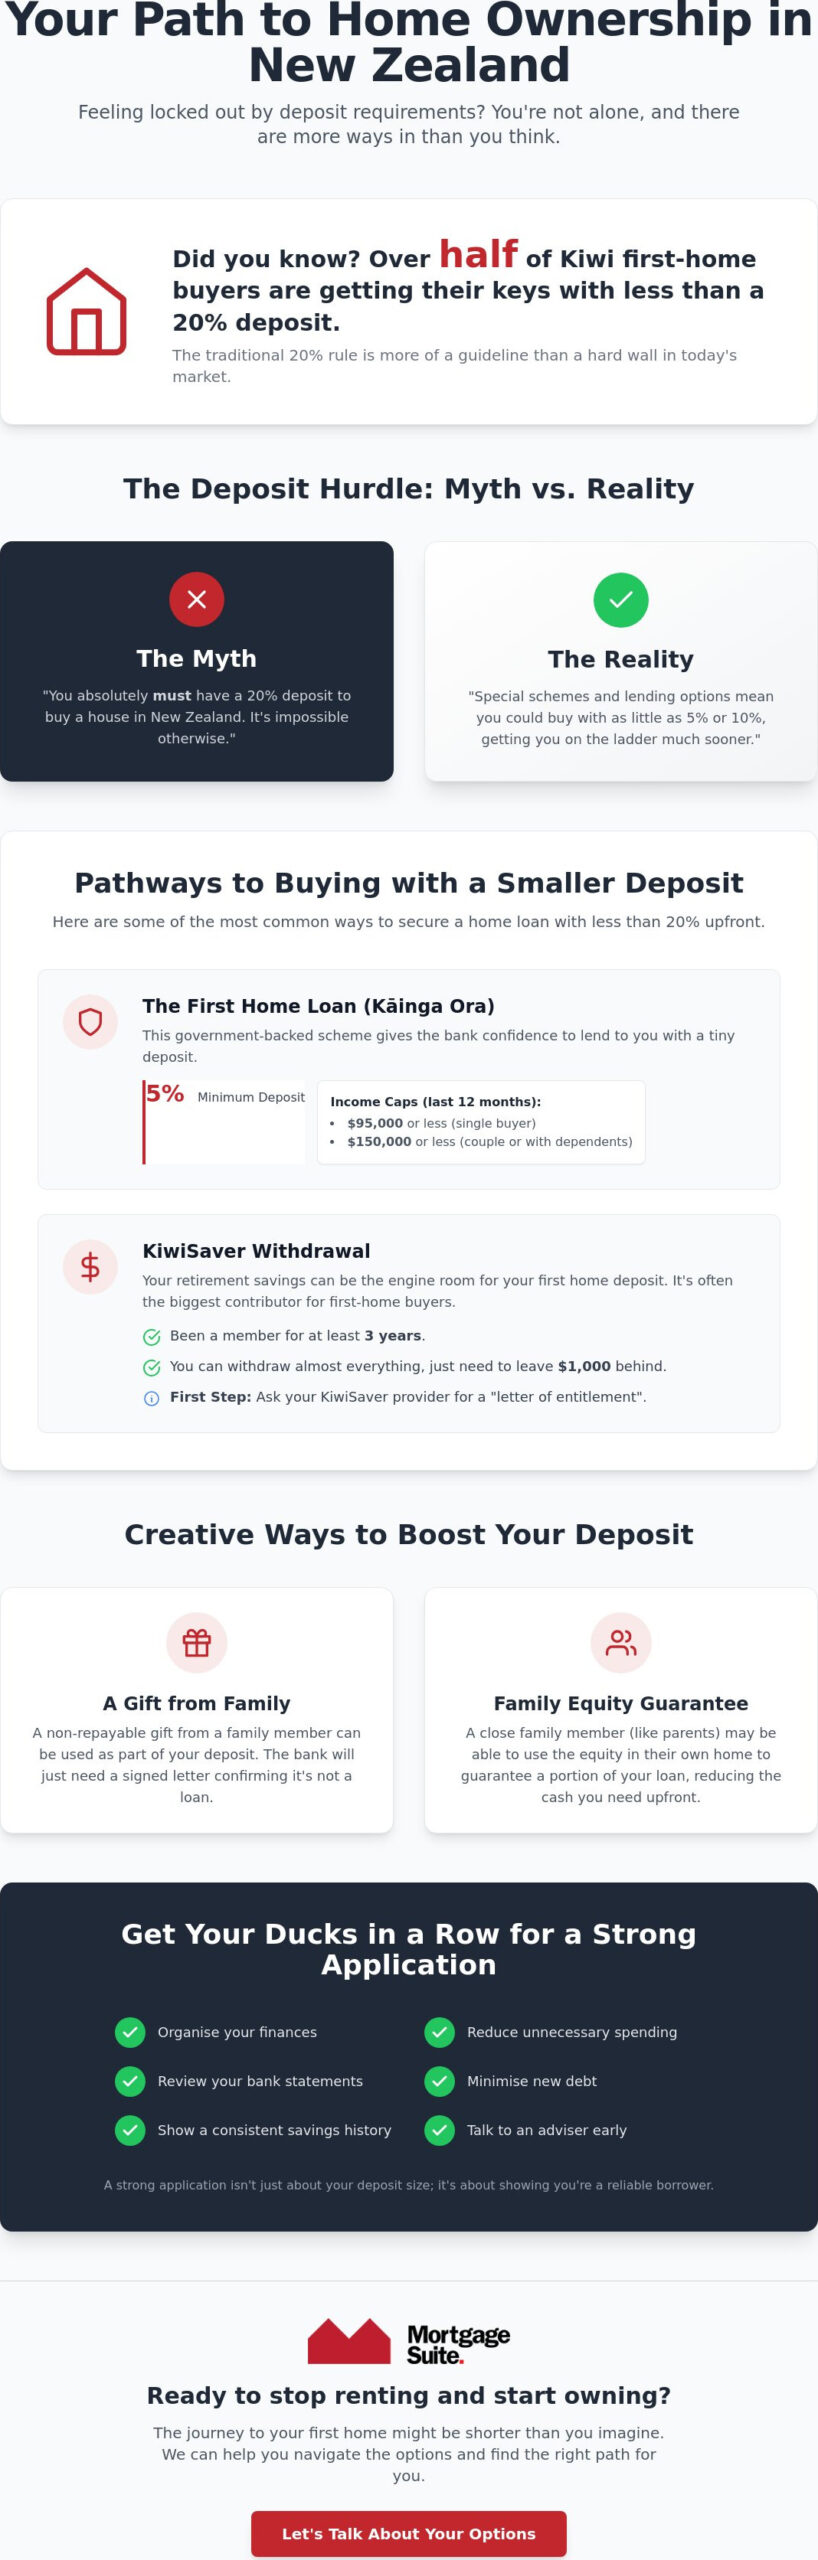
Did you know that over half of Kiwi first-home buyers are currently getting their keys with less than a 20% deposit? It’s a statistic that might surprise you, especially if you’ve spent months feeling like the goalposts for home loan deposit requirements NZ are constantly moving. While the traditional 20% benchmark is often presented as a brick wall, the reality of the 2026 property market is far more flexible for those who have a steady hand to guide them through the various options available.

We know it’s exhausting to hear conflicting advice about 5%, 10%, and 20% deposits while worrying that a mainstream bank might simply say no. It’s a stressful spot to be in, but you don’t have to navigate this journey alone. This guide will show you exactly how much you need to save and reveal the clever ways to buy your first home even with a smaller savings pot. We’ll break down the current Kāinga Ora 5% rules, explain why new builds are a game-changer for low deposits, and give you the practical knowledge and confidence to finally stop renting and start owning.

Key Takeaways

  • Understand why the traditional 20% deposit isn’t always a requirement and how you can join the thousands of Kiwis buying with a much smaller upfront payment.
  • Learn how to navigate the current home loan deposit requirements NZ, including government-backed schemes that allow for a deposit as low as 5%.
  • Discover creative ways to boost your deposit, from utilising family equity guarantees to receiving gifts that help you reach your goal faster.
  • Find out how to look beyond mainstream banks and explore alternative lending options if your financial situation doesn’t fit their rigid criteria.
  • Pick up expert tips on organising your finances and bank statements to ensure your 2026 application is as strong as possible before you approach a lender.

The lowdown on home loan deposit requirements NZ in 2026

When you start looking at houses, the first big hurdle is always the deposit. Simply put, a home loan deposit is the chunk of cash you pay upfront when you buy a property. Your house deposit is simply the difference between the total purchase price of your new home and the amount you need to borrow through a mortgage. It represents your “skin in the game,” and it’s the primary way banks measure how much risk they’re taking on when they lend you money.

In New Zealand, you’ll often hear about the “20% rule.” This isn’t just a random number the banks made up to be difficult; it’s largely driven by the Reserve Bank of New Zealand. They set these rules to keep the entire housing market stable and ensure that both lenders and borrowers don’t end up in over their heads. While the home loan deposit requirements NZ can feel like a massive barrier, understanding why these rules exist is the first step toward navigating them successfully. The government has tried various ways to help people enter the market, such as the KiwiBuild programme, which aimed to increase the supply of affordable homes for those struggling to save a massive deposit.

Why do banks prefer a 20% deposit?

Banks love a 20% deposit because it acts as a safety net. If property values take a temporary dip, that 20% buffer ensures the bank can still recover the loan amount if the house needs to be sold. From your perspective, having that 20% often unlocks the “special” lower interest rates that you see advertised on billboards. If you have a smaller deposit, banks often charge extra costs, sometimes called low equity margins, which can make your monthly repayments more expensive. Aiming for that 20% mark is the most straightforward way to keep your long term costs down.

The difference between a deposit and equity

It’s easy to get these two terms mixed up, but they’re actually quite different. A deposit is the actual cash you have sitting in your bank account right now, ready to be handed over. Equity, on the other hand, is the value of the property you actually own after you subtract what you owe the bank. For example, if your house is worth $800,000 and your mortgage is $600,000, you have $200,000 in equity.

First-home buyers almost always start with a cash deposit, often built up through years of disciplined saving or KiwiSaver contributions. Investors, however, often use the equity in their existing homes to buy more property. Understanding this distinction is vital because it changes how you approach home loan deposit requirements NZ depending on where you are in your property journey. Whether you’re starting with a pile of cash or looking to leverage what you already own, the goal is the same: showing the bank you have a solid foundation.

How to buy a house with a 5% or 10% deposit

If you’ve been staring at house prices and feeling like you’ll be renting forever, I have some good news. The 20% rule we discussed earlier isn’t a legal requirement for everyone. In fact, there are several pathways that allow you to bypass the standard home loan deposit requirements NZ and get into your own place much sooner than you might have expected. While the big banks prefer a larger buffer, they are permitted to lend a certain percentage of their money to people with smaller deposits, provided those borrowers are in a strong financial position.

Using KiwiSaver to boost your deposit

For most Kiwis, KiwiSaver is the engine room of their house deposit. If you have been a member for at least three years, you can generally withdraw almost all of your savings to put toward your first home. You just need to leave a minimum of $1,000 in your account. The very first thing you should do is contact your provider and ask for a “letter of entitlement.” This document is vital because it proves to the bank exactly how much cash you can contribute. It’s often the single biggest contributor for first-home buyers, turning a modest savings account into a serious deposit overnight.

Government help: The First Home Loan

This is a significant leg-up for those struggling to reach the 10% or 20% mark. The First Home Loan scheme is underwritten by Kāinga Ora, which essentially means the government gives the bank the confidence to accept a tiny 5% deposit. To qualify in 2026, you must meet certain income criteria. Specifically, you need to have earned $95,000 or less in the last 12 months as a single buyer, or $150,000 or less if you are buying as a couple or have dependents. While the government has removed the previous house price caps, you still need to prove to the lender that your income is high enough to comfortably service the mortgage repayments every fortnight.

Beyond government schemes, new builds or “turnkey” properties are another excellent option. These homes are often exempt from the usual lending restrictions, meaning banks are frequently more willing to offer 10% deposit options on brand-new houses. This can be a much easier path than trying to buy an existing home where the 20% rule is more strictly applied. If you want to explore these pathways in more detail, our low deposit home loan NZ guide provides a deeper look at the mechanics of these applications. If you’re feeling overwhelmed by the choices, chatting with a specialist mortgage adviser can help you identify which low-deposit route is the most realistic for your current income and savings.

Creative ways to top up your house deposit

Saving for a house in 2026 doesn’t have to be a solo mission. Many Kiwis find that the quickest way to meet home loan deposit requirements NZ is by combining their resources with others. Whether that’s a partner, a sibling, or a close friend, sharing the deposit burden can cut your saving time in half and get you into the market much sooner. If you are considering this path, our ultimate first home buyer guide New Zealand offers practical strategy tips on how to structure these types of joint purchases safely.

The “Bank of Mum and Dad”: Gifting and Guarantees

The “Bank of Mum and Dad” remains a powerhouse in the local property market. If your family is in a position to help, a gifted deposit can bridge the gap to that 20% mark. However, there is a specific process to follow. Banks require a “gifted deposit letter” signed by your family members, which confirms the money is a true gift and not a loan that needs to be repaid. This ensures your debt-to-income ratio stays healthy and the bank feels confident in your ability to manage the mortgage.

If your parents don’t have spare cash but do have equity in their own home, a family guarantee might be the answer. This allows them to use a portion of their property’s value as security for your loan. It’s a clever way to meet the home loan deposit requirements NZ without anyone actually handing over a cent upfront. While the First Home Loan scheme is a government-backed option for low deposits, a family guarantee is a private arrangement that can often achieve a similar result for those who don’t meet the government’s income caps.

Using equity if you already own property

If you already own a home and want to grow your portfolio, you might not need any cash at all. By re-mortgaging your current property, you can “unlock” the value you’ve built up over the years and use it as a deposit for your next purchase. This is a common strategy for those looking at residential investment property loans NZ, where the deposit requirements are usually higher, often around 30% or 35%.

Using equity is a sophisticated way to expand your holdings without draining your savings account. It allows you to leverage the growth in the market to fund your next move. Just remember that you’ll need to prove to the bank that your income can support the increased debt across both properties. This approach turns your existing home into a financial tool that helps you climb the property ladder faster than saving cash ever could.

Home Loan Deposit Requirements NZ: Your 2026 Guide to Getting on the Property Ladder

What to do if the big banks say “no”

Getting a “no” from a big bank can feel like a punch in the gut, but it’s rarely the end of the road. These major lenders have very specific, rigid “boxes” that you have to fit into. If your life doesn’t look exactly like their standard template, they might decline you even if you’re actually quite good with money. It’s helpful to remember that a rejection is often just a “not right now” from that particular bank, rather than a final verdict on your home ownership dreams.

While the big four banks have strict rules, there is a whole world of alternative lending that offers much more flexibility. These lenders take a different approach to home loan deposit requirements NZ, looking at your overall financial situation rather than just ticking off automated boxes. If your deposit isn’t quite the standard shape or your income is a bit unique, a 2nd tier lender New Zealand might be the solution you’ve been looking for.

Why non-bank lenders are a smart alternative

These lenders are often a lifesaver for people who are self-employed or those who have had a few credit hiccups in the past. They usually have more wiggle room with deposit sizes than the big banks do. You can think of these loans as a temporary bridge. They get you into your home today so you can start building equity. Once you’ve shown you can handle the mortgage for a year or two, you can often move your loan back to a mainstream bank to get different interest rates.

Navigating the 2nd tier landscape

There’s an old myth that non-bank lenders are a “last resort” or a bit dodgy, but that’s simply not true. They are reputable, regulated businesses that just have a different appetite for risk and a more human way they review your application. Because this part of the market is so varied, having an expert in your corner is a must. We can help you find a lender that fits your specific needs and help you plan your eventual move back to a big bank. If the mainstream lenders have turned you away, reach out to our team at Mortgage Suite Ltd to see what other doors we can open for you.

Getting your ducks in a row for a 2026 application

You’ve explored the rules and the creative workarounds. Now comes the most important part: making yourself look like the perfect borrower on paper. Even if you meet the basic home loan deposit requirements NZ, a messy bank statement or a forgotten credit card debt can stall your progress. It’s about presenting a clear, stable financial picture that gives lenders the confidence to say yes. It’s not just about the money you have; it’s about the habits you show.

Before you even think about visiting an open home, you need to get a pre-approval. This is essentially a “green light” from a lender that tells you exactly how much you can borrow. It saves you from the heartbreak of falling in love with a house that’s out of your price range. For a step-by-step guide on this process, check out our how to qualify for a home loan NZ checklist. Having this sorted early means you can act quickly when you find the right place.

The 3-month “financial diet”

Banks in 2026 are incredibly thorough. They don’t just look at your salary; they look at what we call your financial character. This means they’ll scan your bank statements for the last three to six months to see exactly where your money goes. Frequent takeaway orders, multiple streaming subscriptions, or regular high-end retail spending might seem small, but they suggest a lack of discipline to a lender. We recommend a three-month “financial diet” before you apply. This involves cutting back on unnecessary spending and ensuring you stay well within your credit limits.

Most importantly, you need to show “genuine savings.” This is money you’ve actually saved over time through your own hard work, rather than a lump sum gift or a windfall. Lenders value this because it proves you have the discipline required to manage a mortgage long-term. By tidying up your accounts now, you make it much easier for a bank to approve your application later.

Why a mortgage broker is your best advocate

Working through the maze of home loan deposit requirements NZ is much easier when you have a veteran in your corner. A mortgage adviser isn’t just someone who fills out forms. We are your advocates and negotiators. We know which lenders are currently looking for new customers and which ones have tightened their belts. At Mortgage Suite Ltd, we have over 20 years of experience in the mortgage world, making the “impossible” happen for our clients. We handle the heavy lifting, from the initial paperwork to the final negotiation with the bank. Our goal is to take the stress off your shoulders and find a path forward, even if your situation doesn’t fit the standard mould.

Your path to home ownership starts here

Getting on the property ladder might feel like a mountain to climb, but the path is often clearer than it first appears. We’ve explored how the traditional 20% rule isn’t your only option. Between government-backed schemes for 5% deposits and the flexibility offered by new builds, your current savings might already be enough to get you started. Success in the current market comes down to two things: cleaning up your financial habits to meet home loan deposit requirements NZ and having the right advocate to navigate the lending system for you.

Our team at Mortgage Suite Ltd brings over 20 years of deep banking and brokerage experience to your side. As a trusted NZ family business, we are specialists in 2nd tier and complex loans, helping Kiwis who don’t fit the rigid boxes of mainstream banks. We pride ourselves on providing a personalised service that focuses on your long term success rather than just a transaction. Ready to see if you qualify? Chat with Krish and the team at Mortgage Suite Ltd today.

You don’t have to figure out these complex financial decisions alone. With a bit of disciplined planning and a steady hand to guide you, that first set of house keys is well within your reach.

Frequently Asked Questions

Can I buy a house in NZ with a 5% deposit in 2026?

Yes, you can buy with a 5% deposit through the First Home Loan scheme if you meet the income caps we discussed earlier. This is currently one of the most effective ways to manage the home loan deposit requirements NZ when you’re starting with a smaller savings pot. You just need to show the bank that you have a steady income and can comfortably handle the mortgage repayments.

Does my KiwiSaver count as a house deposit?

It certainly does, and for many people, it’s the biggest part of their upfront payment. If you’ve been a member for at least three years, you can withdraw your savings and employer contributions, though you must leave at least $1,000 in your account. Just remember to get a letter from your provider early on so you know exactly how much you have to work with.

What is the First Home Grant and is it still available?

The First Home Grant was a government payment that ended on May 22, 2024, so it’s no longer available for new applicants. While that specific cash help has gone, the First Home Loan scheme still exists to help people get into a home with just a 5% deposit. For a full breakdown of what changed and what government support remains available today, our guide on First Home Grant NZ eligibility explains the current landscape clearly. It’s one of the remaining ways to work around the standard home loan deposit requirements NZ.

Do I need a 20% deposit for a brand-new house?

No, you generally only need a 10% deposit for a brand-new house or a property that’s being built. New builds are usually exempt from the standard deposit rules that the Reserve Bank sets for older houses. This makes them a fantastic option if you’re finding it difficult to save the full 20% buffer that big banks usually ask for.

Can my parents give me money for a house deposit?

Yes, your parents can provide a gifted deposit as long as they sign a letter confirming it doesn’t need to be paid back. This ensures the bank doesn’t view the gift as another debt you have to manage. They could also use a family guarantee, which uses the value in their own home as security so you don’t need as much cash upfront.

What happens if I have a 10% deposit but the bank says no?

If a big bank turns you down, it doesn’t mean you’re stuck. Alternative lenders often have more flexible rules for people who have a 10% deposit but don’t fit the standard bank criteria. At Mortgage Suite Ltd, we can help you find a lender that looks at your whole financial picture and values your income and stability over a rigid set of rules.

How long does it take to get a home loan pre-approval?

Most pre-approvals take between two and five working days, depending on how busy the banks are and how complex your finances look. Having your bank statements and proof of income organised before you apply will help speed things up. Once you have that “green light,” you can go house hunting with the confidence of knowing exactly what your budget is.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.