Mortgage approval with bad credit in NZ: what lenders assess

Bad credit doesn’t automatically prevent a mortgage application in New Zealand. For mortgage approval with bad credit in NZ, lenders assess your full application, including whether the borrowing fits your financial position. A past credit issue matters, but it is not the whole story.

If you’ve been declined or feel uneasy about applying, it’s natural to wonder whether trying again is worthwhile. The uncertainty can feel heavy, especially when buying a home matters to you. Understanding how lenders assess applications can help you decide what to prepare and which questions to ask.

This guide explains the factors lenders consider and practical ways to present your circumstances clearly. You’ll learn how to prepare for a lender’s review, weigh your options and choose a sensible next step. The aim is to help you approach the process with confidence, without treating a credit setback as a personal judgement or assuming the outcome in advance.

Key Takeaways

  • Lenders assess whether your income can cover regular expenses, existing debt and likely mortgage repayments, not just your credit history.
  • A paid, older default may be viewed differently from a recent unpaid one, so explain the circumstances and show how your finances have changed.
  • Your property’s assessed value and the equity available can affect how a lender views the application and the security for the loan.
  • Review your credit report for errors, avoid unnecessary credit applications and organise clear records of your income and spending.
  • A decline from a mainstream bank doesn’t automatically close off other options; different lenders have different criteria for home loans.

Income, expenses and existing debt

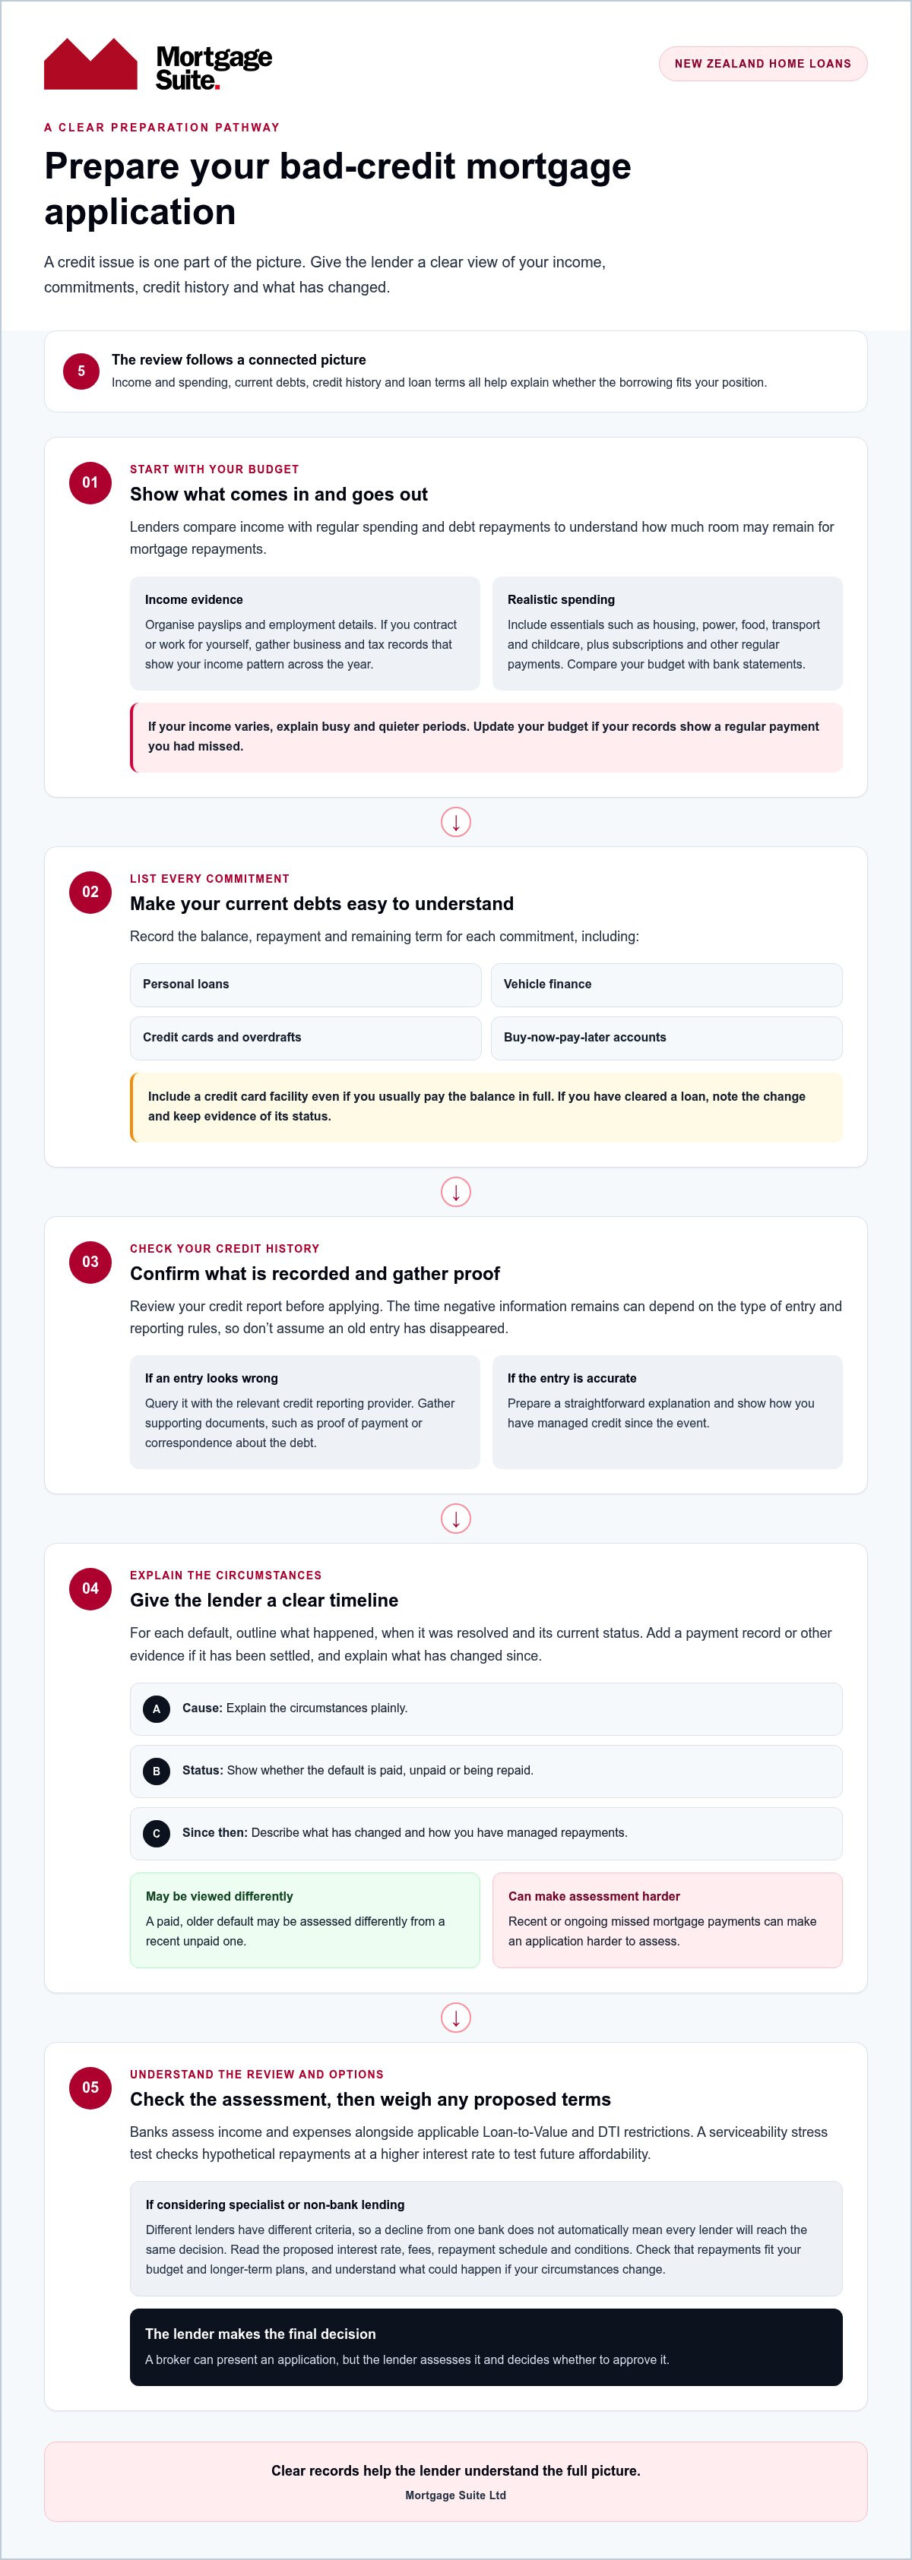
A lender compares your income with regular spending and debt repayments to assess how much room remains for a mortgage. The aim is to understand your household budget, not just your salary. For example, two applicants with similar incomes may have different borrowing capacity if one supports dependants or has higher regular commitments.

Show where your income comes from and how reliably it arrives. Employed applicants can organise payslips and employment details. If you earn through contracting or self-employment, gather business and tax records that show your income pattern across the year. A seasonal earner, for example, can distinguish a busy period from quieter months, helping the lender understand typical income rather than an unusually strong week.

Build a realistic record of household spending before applying. Include regular essentials such as housing, power, food, transport and childcare, as well as subscriptions and other recurring payments. Compare your bank statements with your budget. If your records show a sports fee or childcare payment you left out, update the budget rather than relying on an estimate that understates your commitments.

List every current credit commitment, including personal loans, vehicle finance, credit cards, overdrafts and buy-now-pay-later accounts. Record each balance, repayment and remaining term. A credit card limit can matter even if you usually pay the balance in full, so include the facility, not just the amount currently owed. If you’ve recently cleared a loan, note the change and keep evidence of its status.

The Reserve Bank’s current Loan-to-Value and DTI restrictions apply to banks’ residential lending in New Zealand. These restrictions sit alongside a bank’s assessment of your income and expenses. A serviceability stress test assesses hypothetical repayments at a higher interest rate to test future affordability. It considers how the proposed repayments fit your budget under that assessment.

Before applying, prepare a simple monthly budget and compare it with your account activity. Highlight variable income, one-off expenses and debts nearing repayment. If you’re already struggling to meet mortgage payments, contact your lender as early as possible. A clear summary of what you can afford and where you’re under pressure gives the lender useful context for discussing your position.

Lender assessment of credit history and defaults

For a bad-credit application, prepare identification, income evidence, bank statements, debt details and records showing the status of any default. How long negative information remains on a New Zealand credit report depends on the type of entry and reporting rules.

Lender options for bad-credit borrowers

Mainstream banks and non-bank lenders assess home loan applications against their own criteria. A decline from one bank doesn’t automatically mean every lender will reach the same decision. A lender may look closely at the cause of a default, whether it has been paid, your recent repayment history and the strength of the rest of your application.

A paid, older default may be assessed differently from a recent unpaid default. Recent or ongoing missed mortgage payments can make an application harder to assess. Explain clearly what happened, when you resolved it and what has changed since. Where applicable, include a payment record or other evidence that the default is settled.

Non-bank or specialist lending may provide another route when a mainstream bank’s criteria don’t fit your circumstances. Read the proposed loan terms carefully, including the interest rate, fees, repayment schedule and any conditions. Consider whether repayments remain manageable and how the loan fits your longer-term plans. A mortgage broker can present an application, but the lender makes the final decision after assessing it.

How long negative credit information remains

There isn’t one timeframe for every type of negative entry on a New Zealand credit report. The entry type and reporting rules affect how long information remains visible, while lenders may weigh an older paid default differently from a recent unpaid one. Don’t assume an old entry has disappeared; review your report before applying.

If you believe an entry on your credit report is wrong, contact the relevant credit reporting provider to query it. Gather supporting documents, such as proof of payment or correspondence about the debt. If the information is accurate, prepare a straightforward explanation and show how you’ve managed credit since the event. This gives the lender context instead of leaving a negative entry unexplained.

Organise your application documents into clear groups: identity, income, regular spending, current debts and credit history. Include a short timeline for each default, covering the original issue, any repayment arrangement and its current status. If circumstances contributed to missed payments, explain them plainly and show what has changed. Consistent records help the lender compare your explanation with the information in your application.

With specialist lending, consider the whole arrangement, not only whether an application can proceed. Check how repayments are structured, whether the terms suit your income pattern and what could happen if your circumstances change. Make sure you understand all fees and conditions before committing. Comparing proposed repayments with your household budget can help you judge whether the loan is sustainable.

Property value and home equity

There isn’t one deposit amount that suits every bad-credit home loan application. The deposit depends on the property value, the amount borrowed and the lender’s assessment of your application. A larger contribution can reduce the amount you need to borrow, but lenders also consider whether repayments fit your finances and how your credit history affects the application.

The property matters because it secures the mortgage. The lender considers its value alongside the loan amount, rather than relying only on the price you hope to pay. If the lender’s valuation is below the purchase price, you may need to reconsider your contribution or the property you’re considering.

Home equity is the property’s value minus the debt secured against it. For example, a New Zealand property worth NZ$800,000 with a NZ$500,000 mortgage has approximately NZ$300,000 in equity before other costs or secured debts. This is an estimate, not necessarily money you can freely use for another purpose.

Other lending secured against the property can reduce the equity available. If you’re relying on an existing home, list each secured debt and use current balances, not the original loan amounts. For example, a separate loan secured against the same property must be considered alongside the mortgage when assessing the overall position.

A lender’s valuation can differ from your estimate. The property’s condition, features and sale evidence may affect its assessed value. If the valuation is lower than expected, you may need to adjust the loan request. That can affect the deposit you need to contribute, so leave room to revisit your figures before committing to a purchase.

The Reserve Bank’s current Loan-to-Value restrictions apply to banks’ residential lending in New Zealand. These restrictions limit how much a bank can lend compared with a property’s value. They form one part of the assessment, alongside the bank’s own criteria and your financial position. Non-bank lenders assess applications under their own criteria.

Before applying, write down the property’s estimated value, proposed mortgage, deposit or available equity, and any debts secured against the property. Keep the figures separate and identify which funds are available for the purchase. If your credit history includes a default, explain it accurately. Equity can support the security assessment, but it doesn’t replace the lender’s review of your finances.
Mortgage approval with bad credit in NZ: what lenders assess

Steps to improve a mortgage application

A clear application helps lenders understand your finances and credit history. Focus on accurate records, manageable debt and a straightforward explanation of past issues.

Strengthening a mortgage application

Strengthening an application means making your financial position easier to assess before you apply. Complete, consistent information helps a lender understand your current repayment habits alongside earlier credit problems.

  • Avoid unnecessary credit applications, which can add new enquiries to your credit history.
  • Pay existing bills and debt repayments on time, and keep records showing your payment history.
  • List every debt and credit facility accurately, including balances and repayment commitments.
  • Explain any default clearly, including whether it has been paid and what changed afterwards.

Check that your application, bank statements and supporting documents tell the same story. If you’ve cleared a debt, for example, include evidence of its current status rather than relying on memory. If your income or spending has changed, explain when and why. A short, factual explanation is more useful than leaving a lender to interpret a gap or mismatch.

Review your recent account activity before applying. Regular unarranged overdraft use or missed payments may prompt questions about how you manage repayments. Avoid taking on new debt while preparing your application, and keep your spending records up to date. These steps won’t erase past credit events, but they can show how you manage your finances now.

Checking and correcting a credit report

Reviewing your credit report means checking the information held about your borrowing and repayment history. Before applying, look for errors, unfamiliar accounts and debts recorded with the wrong status. If you believe an entry is incorrect, contact the relevant credit reporting provider to query it.

Compare each entry with your records, such as account statements, payment confirmations and correspondence about a debt. Note the creditor, account details and what you believe is wrong. Send the provider evidence supporting your query, and keep copies of your request and any response.

If the entry is accurate, prepare a brief explanation for the lender rather than disputing it. Include the circumstances, whether the debt has been paid and any steps taken to prevent a repeat. For example, explain how a repayment arrangement brought an overdue account up to date, if applicable. Keep your explanation consistent with the dates and documents in your application.

After reviewing your report, update your application documents to reflect any corrected information. Keep the provider’s response with your records so you can explain a change if the lender asks about it. Avoid applying for several new credit facilities while you prepare. A tidy, consistent file gives a clearer picture of your current position.

Which New Zealand banks and non-bank lenders offer home loans to borrowers with bad credit?

There isn’t one fixed list of New Zealand lenders that accepts every bad-credit application. Banks and non-bank lenders assess applications using their own criteria, so the decision depends on your full financial picture, not just the type of lender.

A mainstream bank may assess your income, debts, credit history, deposit and property security together. If one bank declines, that doesn’t automatically determine how another lender will view your circumstances. For example, an older paid default and a recent unpaid default may be assessed differently.

Non-bank lenders may be another option when a bank’s criteria don’t suit your application. They still assess whether repayments are manageable and whether the property supports the lending. Their criteria and loan terms can differ, so compare the whole arrangement rather than focusing only on whether an application can proceed.

Before approaching a lender, organise a clear summary of:

  • Your income sources and regular household spending.
  • Every current debt, repayment and credit facility.
  • Any default, including its status and what has changed since.
  • The property value, deposit or available equity.

This helps show how your current position addresses the concerns behind an earlier decline. If the issue was a default, include evidence of payment where relevant. If existing debt affected affordability, show the current balances and repayments. The lender can then assess your application against its criteria using up-to-date information.

Compare the proposed interest rate, fees, repayment structure and loan conditions. A lower advertised rate doesn’t necessarily mean refinancing will reduce the overall cost. Refinancing expenses can include interest, loan fees, legal costs, valuation costs and break costs on an existing fixed-rate loan. Include these in your comparison before deciding whether a new loan suits your plans.

A non-bank or specialist loan may have different terms from a mainstream bank’s offer. Read the repayment schedule and conditions, and consider whether payments remain manageable if your income or expenses change. A repayment that fits today’s budget, for example, may feel different after a change in work hours or household costs.

To narrow your options, prepare one complete, accurate application rather than making unnecessary credit applications to several lenders. Explain the reason for the credit issue, what has improved and how the proposed repayments fit your budget. Different criteria may offer another route, but each lender makes its own assessment.

Mainstream banks and non-bank lenders may both consider home loan applications from borrowers with bad credit. Which lender may suit you depends on its criteria and your full financial picture.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you explore Home Loans to First Home Buyers if your credit history has made the next step feel uncertain. A mainstream bank’s decision isn’t the whole picture: your income, debts, deposit and property plans all help shape an application.

Bring together your credit report, details of any defaults, income records and a clear summary of your current debts. Mortgage Suite Ltd can help you understand how these pieces fit together and discuss home loan options suited to your circumstances. The aim is to clarify your position and help you consider the lending structure, repayments and longer-term plans, rather than focusing on one headline rate.

If you’re ready to discuss your first-home application, contact Mortgage Suite Ltd to talk through your next steps.

Take your next step with a clear plan

A credit setback can make planning a home purchase feel daunting, but it doesn’t define every future lending conversation. Use your next step to understand what a lender may need to see and whether your plans fit your current financial position.

For mortgage approval with bad credit in NZ, focus on presenting your circumstances clearly and choosing a loan structure that remains workable over time. Mortgage Suite Ltd can discuss Home Loans to First Home Buyers, Residential Investment property loans and Business Loans, depending on the purpose of your borrowing.

A lender makes the final decision after assessing your application, so approval isn’t guaranteed. A thoughtful conversation can still help you identify what to prepare and which questions matter for your next move.

Contact Mortgage Suite Ltd to discuss your borrowing plans and take the next step with a clearer picture of your options.

Frequently Asked Questions

Can you get mortgage approval in New Zealand with bad credit?

Yes, it may be possible, because lenders assess applications using their own criteria and consider more than a credit entry. They may weigh the type and status of the issue alongside your current finances and the property securing the loan. A recent unpaid default differs from an older paid one. The lender makes the final decision after reviewing your application, so approval isn’t assured.

What credit score do NZ mortgage lenders require?

There isn’t one credit-score number that guarantees mortgage approval in New Zealand. Lenders use their own criteria, and a score is only one part of the information they may consider. They also assess the details behind negative entries, your current financial position and the property. If you’re unsure what appears on your file, review your credit report before applying and query any information you believe is incorrect.

How do missed payments, defaults, debt collection, and bankruptcy affect a NZ mortgage application?

Missed mortgage payments, defaults, collection activity and bankruptcy can all prompt closer scrutiny of your credit history. Recent or ongoing missed mortgage payments can make refinancing more difficult. A lender may assess an older paid default differently from a recent unpaid one. For debt collection or bankruptcy, be ready to explain the circumstances and provide accurate records of the current status. Don’t leave unresolved entries unexplained.

How can you improve your chances of mortgage approval with bad credit in New Zealand?

Prepare before applying: review your credit report, query any incorrect entry with the relevant reporting provider and avoid unnecessary credit applications. Make sure your explanation of past problems matches the dates and status in your documents. If your situation has changed, describe how, such as a debt being paid or income becoming more consistent. A complete, accurate application helps lenders assess your current position.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

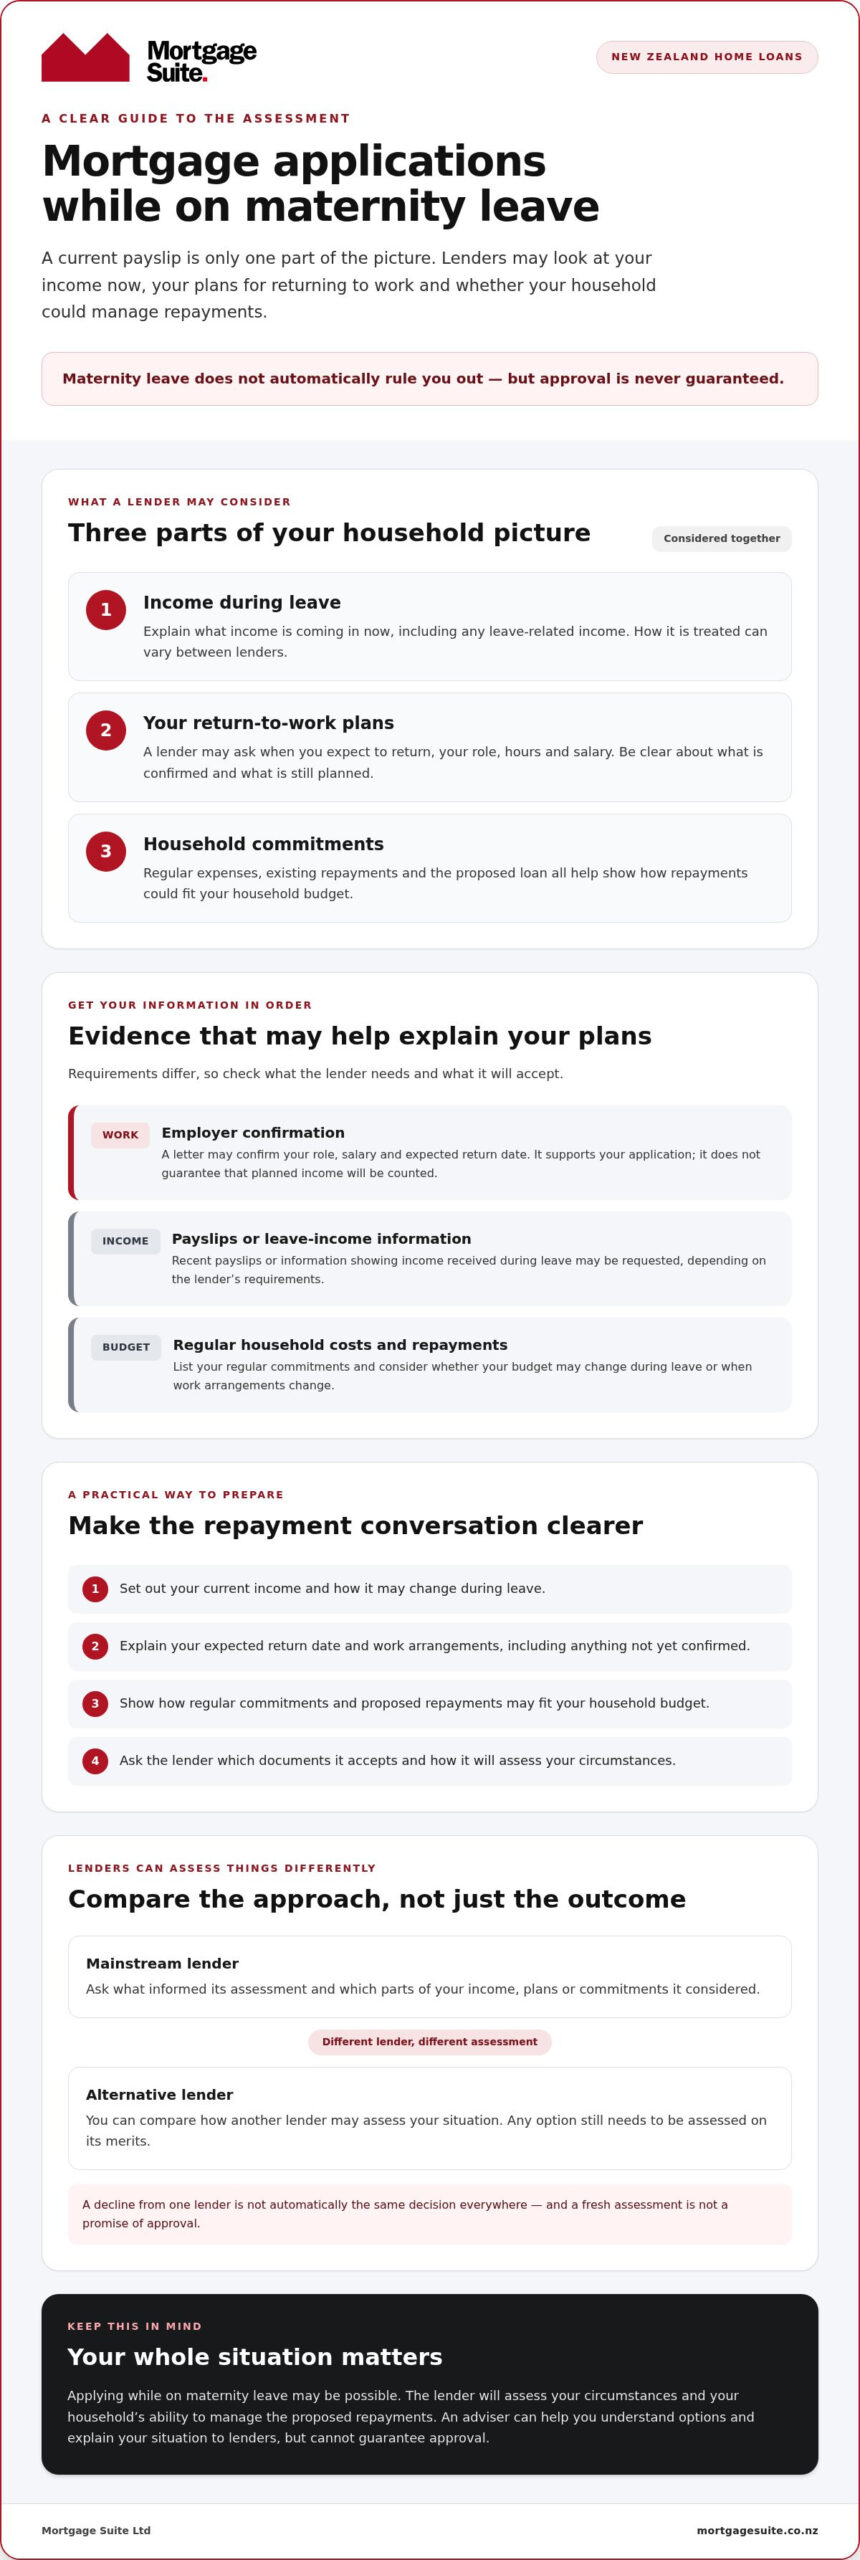
A maternity-leave mortgage application isn’t decided by your current payslip alone. If you’re wondering whether getting a mortgage while on maternity leave nz is possible, the answer depends on how a lender assesses your income now, your return-to-work plans and your household’s ability to manage repayments.

Time away from work doesn’t automatically rule you out, but approval isn’t guaranteed. Lenders can assess applications differently, so it helps to give them a clear picture of your finances and plans. This guide explains what may affect an assessment and how to prepare useful information.

You’ll learn how lenders may view parental leave payments, your expected return date and a temporary drop in household income. We’ll also cover documents that may help, such as an employer letter confirming your role, salary and expected return date, and ways to explain how repayments will fit your budget. Mortgage Suite can help you understand and compare mainstream and alternative lending options, so you can consider a sensible next step without assuming every lender will reach the same decision.

Key Takeaways

  • Getting a mortgage while on maternity leave nz may be possible, but a lender will assess your circumstances and ability to manage repayments.
  • Ask how the lender will consider your current income, planned return to work and household commitments.
  • Prepare employment and income evidence, such as confirmation of your role, salary and expected return date. Check which documents the lender needs.
  • Compare how mainstream and alternative lenders assess your situation rather than assuming every lender will take the same view.
  • A mortgage adviser can help you understand your options and explain your circumstances to lenders, but can’t guarantee approval.

Can you get a mortgage while on maternity leave in NZ?

Yes, applying for a home loan while you’re on maternity leave may be possible. Being on leave doesn’t automatically mean you’ll be approved, and it doesn’t automatically rule you out. A lender needs to assess whether your household could manage the proposed repayments while your income is reduced and under your expected work arrangements after leave.

Getting a mortgage while on maternity leave nz depends on your full situation, not just the fact that you’re away from work. Lenders may consider your income, employment plans, regular household commitments and the amount you want to borrow. Requirements differ, so check what a lender currently accepts rather than relying on a friend’s experience or an old online example.

Does maternity leave automatically stop a mortgage application?

No single outcome applies to every borrower. Maternity leave is a temporary change in your work and income, but the lender will still assess the whole financial picture. Your return-to-work plans, another applicant’s income and your household commitments may all be relevant. These details help explain how your household expects to manage repayments, but none guarantees approval.

Parental leave sits within New Zealand’s employment framework. You can read more about the Parental Leave and Employment Protection Act 1987, but a lender’s mortgage assessment is separate from your employment rights.

What will a lender want to understand about your situation?

Expect to discuss your current income and how it may change during leave. A lender may ask whether your employer has confirmed your expected return date, role and salary. If your arrangements aren’t final, be upfront about that and ask what information could clarify your position.

The lender will also consider your household’s regular commitments and the proposed loan. Be ready to explain how repayments would fit your budget during leave and after you return to work. Ask which documents the lender accepts to confirm income and employment plans. Don’t assume every lender requires the same evidence or will reach the same view.

If a mainstream bank declines your application, ask what informed its decision and whether another lender may assess your circumstances differently. An alternative option would still need to be assessed on its merits, so treat the next step as a fresh conversation, not a promise of approval.

How lenders may assess income and affordability during maternity leave

A lender’s central question is whether your household appears able to manage the proposed repayments. It may discuss the income coming in now, how that could change during leave, your expected work arrangements afterwards and other regular household income. How leave-related income is treated can vary. Ask the lender how it would assess your circumstances rather than assuming your usual salary will be counted in full.

New Zealand’s Parental leave entitlements information explains the leave framework and points to payment details. It can help you understand your own situation, but it doesn’t determine how a lender will assess your mortgage application. If you’re getting a mortgage while on maternity leave nz, make clear which income is confirmed and which arrangements are planned.

How a return-to-work plan can help explain your application

If your return arrangements are confirmed, note your expected return date and whether you’ll be returning to the same role or working different hours. An employer letter may help explain your role, hours and pay. It’s supporting information, not a guarantee that the lender will count your planned income when assessing affordability. Ask what form of confirmation it accepts and whether it needs anything else.

How household commitments can affect the assessment

Income is only part of the picture. List your regular household expenses and existing repayments, then consider how the budget may change if childcare or work arrangements affect your spending or income. This gives you and the lender a practical basis for discussing whether repayments look manageable while your income is different.

You can use the Mortgage Suite mortgage calculator to explore possible repayments as part of your planning. Treat the result as an estimate, not a lender decision or a promise of approval.

Examples of evidence a lender may ask for, depending on its requirements:

  • Recent payslips or information showing income received during leave.
  • An employer letter confirming your expected return date, role, hours or pay, if available.
  • Details of other regular household income, existing repayments and ongoing expenses.

This is a starting point, not a universal checklist. Before gathering documents, ask your chosen lender or adviser which evidence it accepts and how it will consider your income and commitments. A clear explanation can help you compare options and decide what to do next.

Mainstream or alternative lender: what should you compare?

A lender’s approach can affect how your maternity-leave income and work plans are considered. Instead of looking only for an immediate yes, compare what each lender needs to understand, how it assesses your household budget and whether the proposed loan could suit your plans beyond the leave period. Criteria can change, so ask for current requirements rather than treating another borrower’s experience as a guide to your own application.

Use these questions to compare options. They don’t describe a guaranteed policy for any lender:

What to compare What to ask
Confirmed income Which income documents do you need, and how will you assess income during leave?
Return-to-work plans What evidence of my expected return date, role, hours or pay can you consider?
Household commitments How will you assess regular expenses, existing repayments and expected changes to our budget?
Loan fit What repayment choices or loan structure should we consider for our longer-term household plans?

Questions to ask before choosing a lender

Ask each lender for a clear list of the income and employment details it needs. Check how it treats a planned return to work and changing household expenses. Discuss whether the proposed repayments and loan structure fit your plans after you return. This helps you compare the overall suitability of an option, not just whether an application might proceed now.

When an alternative lending conversation may be useful

If a mainstream lender declines your application, that doesn’t mean every option is closed. Mortgage Suite can help you explore mainstream and alternative lending channels, including 2nd-tier lending, where suitable. Each option still depends on an assessment of your circumstances, and terms and suitability can differ. If you’re getting a mortgage while on maternity leave nz, ask what a lender’s decision was based on before choosing your next step.

Alternative lending isn’t automatically a better fit. Compare how the lender will assess your confirmed income, return-to-work evidence and household commitments. Make sure you understand the proposed repayments and structure. A lending adviser can help you organise your questions and explain your circumstances, without promising approval. The aim is to make a considered choice that fits your situation.

Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

How to prepare a mortgage application while on maternity leave

Preparation can make an initial lending conversation clearer and help you identify missing information early. Start by mapping your household finances, confirming what you know about your employment and return-to-work plans, and gathering available evidence. Then ask which lending options may suit your circumstances. If you’re getting a mortgage while on maternity leave nz, explain changes to your income or work arrangements openly and consistently.

A practical document checklist to start with

Pull together what you already have. This is a starting point, not a list every lender will require. Check the exact document list with your chosen lender or adviser before relying on any particular item.

  • Recent payslips or other available records showing your income during leave.
  • Employment details, such as your role and any confirmed changes to your hours or working arrangements.
  • Written confirmation of your expected return date and pay, if your employer has provided it.
  • Details of regular household expenses, existing repayments and other income.
  • Information about your current leave arrangements and any expected changes to your household budget.

If something hasn’t been confirmed, say so. Clear, consistent information helps the person reviewing your application understand what’s known and what’s still being planned.

How to make the first conversation more useful

Before speaking with a lender or adviser, note your property goal, preferred timing and questions about how your income during leave and return-to-work plans may be assessed. Include relevant changes to your household finances, such as a shift in work hours or expected childcare arrangements. You don’t need every answer ready. Being clear about what’s confirmed and what’s uncertain gives the conversation a useful starting point.

Review possible repayments against your household budget. Consider whether they look manageable with your current income and how your budget might change when work arrangements shift. An estimate can support your planning, but it isn’t a lending decision. Ask how a proposed loan might fit your longer-term plans if you’re unsure.

For plain-English help with lending basics, explore Mortgage Suite’s Mortgage School. When you’re ready to discuss your circumstances, talk with Mortgage Suite about your home loan. A lending professional can help you organise information and discuss possible options, but approval depends on the lender’s assessment.

Getting support with a maternity-leave mortgage application

You don’t have to work through every lending question on your own. Gather the evidence you have, note what’s confirmed about your return to work and ask lenders how they would assess your circumstances. If getting a mortgage while on maternity leave nz feels like a lot to manage, a mortgage adviser can help organise your questions and compare possible options.

An adviser can help explain your situation to lenders and clarify what further information may be useful. Mortgage Suite can present your circumstances and discuss possible options with lenders, including whether mainstream or alternative lending channels may be worth exploring. Any recommendation depends on a careful review of your circumstances, and no particular lending decision is assured.

What a mortgage adviser can help you work through

Start by discussing the parts of your application that may need context. Your current income may differ from your expected income after returning to work, or your return date may still be unconfirmed. An adviser can help identify what needs explaining, ask what supporting evidence a lender may accept and communicate the details clearly. They can also help compare potential lender fit, while making clear that each lender makes its own assessment.

Mortgage Suite supports borrowers through mainstream and alternative lending channels. Founder Krish Krishna established the business in 2000 and brings more than two decades of banking experience. That background can inform a practical conversation about your circumstances, but it can’t assure a particular lending decision.

Choose your next step with confidence

Before getting in touch, you may want to read about Mortgage Suite’s background and browse client reviews to learn about other borrowers’ experiences. Reviews are individual accounts, not a promise that your application will have the same outcome.

Bring the information you have and ask direct questions: what needs more evidence, how could your return-to-work plans be considered, and which lender options may suit your household? Take time to understand the answers and decide what feels sensible. A mainstream lender’s decline isn’t necessarily the end of your options, but any next route still needs to suit your circumstances and pass the lender’s assessment.

If you’d like to discuss your situation and explore possible next steps, talk through your home-loan options. You don’t need every detail sorted before starting the conversation.

Take a clear next step with your home-loan plans

Getting a mortgage while on maternity leave nz may be possible, but each lender will assess your circumstances. A clear picture of your current income, confirmed work plans and household commitments can help you explain your application and ask useful questions. Requirements differ between lenders, and approval is never guaranteed.

Gather the evidence you have, check what a lender needs and compare options that could suit your household now and longer term. A decline from one lender doesn’t necessarily mean every option is closed. Mortgage Suite Ltd has supported borrowers since 2000, and founder Krish Krishna brings more than two decades of banking experience. The team can discuss mainstream and alternative lending channels, subject to an assessment of your situation.

If you’d like to discuss your next step, talk through your home-loan options. Bring your questions and the information you have, and Mortgage Suite can help you explore possible lending options.

Frequently Asked Questions

Can I get a mortgage while on maternity leave in NZ?

It may be possible, but there’s no answer that applies to every borrower. For getting a mortgage while on maternity leave nz, lenders assess your income, employment, household commitments and proposed loan using their own criteria. Explain your leave arrangements and any confirmed return-to-work plans, then ask what evidence the lender needs. A mortgage adviser can help you understand which mainstream or alternative options may be worth exploring, subject to assessment.

Will a lender count my income while I am on maternity leave?

How a lender treats income during leave can vary, so don’t assume it will count your income in a particular way. Ask how it assesses your current income and any expected change when you return to work. You may need to provide employment details or confirmation of your work arrangements. Check the lender’s current requirements before applying, as policies and accepted evidence can differ.

What documents might I need for a mortgage application during maternity leave?

The documents requested depend on the lender and your circumstances. You may be asked for information about your income, employment, leave arrangements, regular household commitments and any confirmed return-to-work plan. Treat a checklist as a starting point, not a guaranteed list of requirements. Contact the lender or adviser early to confirm exactly what they need, including whether documents must be recent or supplied in a particular format.

Can I apply for a mortgage before I return to work?

You can ask a lender or adviser about applying before your planned return, but the timing and evidence needed depend on your circumstances and the lender’s criteria. Explain your current leave, employment status and any confirmed work arrangements. The lender may also want to understand how your household commitments fit alongside the proposed repayments. Ask what information could support an assessment now rather than assuming how planned income will be treated.

Does maternity leave affect mortgage pre-approval in New Zealand?

It can affect the information a lender asks for, but it doesn’t automatically decide the outcome. Pre-approval is based on the lender’s assessment at that time and may include conditions. Be upfront about your leave arrangements, income and expected work changes, and check what evidence is needed. If your circumstances change after pre-approval, contact the lender to ask whether it needs to review your application before you rely on it.

What if my bank declines my mortgage application while I am on maternity leave?

A decline from one lender isn’t necessarily a final judgement on your borrowing prospects. Ask for a clear explanation and whether further information could help. Lenders assess applications differently, but another option isn’t guaranteed. A mortgage adviser can help you understand the issues, compare possible mainstream and alternative lending channels, and decide whether to provide more evidence or make changes before approaching another lender. Any option remains subject to assessment.

Should I wait until I return to work before applying for a mortgage?

There’s no single best time for every borrower. Applying before you return may suit some circumstances, while waiting could give you clearer income evidence. Consider your property plans, household budget and the documents available now. Ask a lender or adviser how each timing option may be assessed before deciding. Don’t treat planned income as guaranteed, and check whether changes to your circumstances or work arrangements could affect the information the lender needs.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Freelancer Mortgage NZ: How to Get Your Home Loan Sorted in 2026

What if a mainstream bank’s “no” is only the start of your home loan conversation? If you’re wondering whether you can get a mortgage without a permanent 9-to-5 job, the answer may be yes. A freelancer mortgage nz application can take more explaining, but variable income doesn’t automatically rule you out.

It’s understandable to worry that lenders will judge your work status or that the paperwork will be difficult to pull together. If a bank has already declined your application, that can feel like a verdict. It isn’t necessarily one: lenders can assess freelance income differently, so first find out what the decline was based on.

This guide to the freelancer mortgage nz process explains how to prepare your income records, what lenders may look for and where specialist lending could fit. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping clients explore lending options. Approval can’t be promised, but you can get a clearer picture of what may suit your circumstances.

Key Takeaways

  • A freelancer mortgage nz application can be assessed using more than a standard pay slip. Learn which records may help show a clear picture of your income.
  • A lender’s view of risk doesn’t necessarily reflect your overall financial health. Find out how to explain your circumstances clearly.
  • A mainstream bank’s decline is one decision, not a final judgement. 2nd tier lending may be another option to explore.
  • Organising your paperwork before applying can make the process more manageable and help you identify what to do next.
  • Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping clients explore lending options.

Why Being Your Own Boss Can Make Banks Nervous

If you’ve ever felt like an outsider when asking a bank about a home loan, you’re not alone. A standard application makes salaried income easy to check: a regular pay slip shows what comes in and when. Freelance income can arrive from several clients, vary from month to month and appear across business accounts and financial statements. That takes more explanation, but it doesn’t mean your finances are unhealthy.

A lender is assessing whether you can manage repayments, not deciding whether freelancing is a good career choice. A mortgage loan is borrowing secured against a property, and the lender needs to understand your ability to repay it. A pay slip may be simpler to assess than an income pattern that changes over time. The difference between what a lender can quickly verify and your actual financial position is a question to clarify, not a verdict on your earning ability.

The Myth of the ‘Risky’ Freelancer

Freelance work isn’t automatically less secure than salaried work. You might earn as much as, or more than, someone on a salary, but lenders need evidence to support the income they use in their assessment. Mainstream banks commonly ask for two full years of financial statements and look at how your earnings hold up over time. The focus is your demonstrated earning power, not simply your employment type.

Fluctuating Income and the Bank Safety Margin

A safety margin is room in the lender’s assessment for repayments to remain manageable if income dips or expenses rise. It isn’t a single set amount that applies to every lender. Banks may review one or two years of financial information and use an average or a more cautious income figure, depending on their approach. A quiet month on its own doesn’t tell the whole story.

For example, you may have a slower period between projects followed by steady work from returning clients. Clear records can help show that pattern and distinguish a temporary lull from a longer-term drop in income. Lenders still need to be satisfied that repayments are affordable, but their assessment methods differ. Ask how a lender will treat your income history rather than assuming every lender will assess it the same way.

That’s why a freelancer mortgage nz application is best built around clear evidence of your income and commitments. Your work status is one part of your circumstances, not a flaw. A clear explanation can help a lender assess your actual financial position.

Proving Your Income Without a Standard Pay Slip

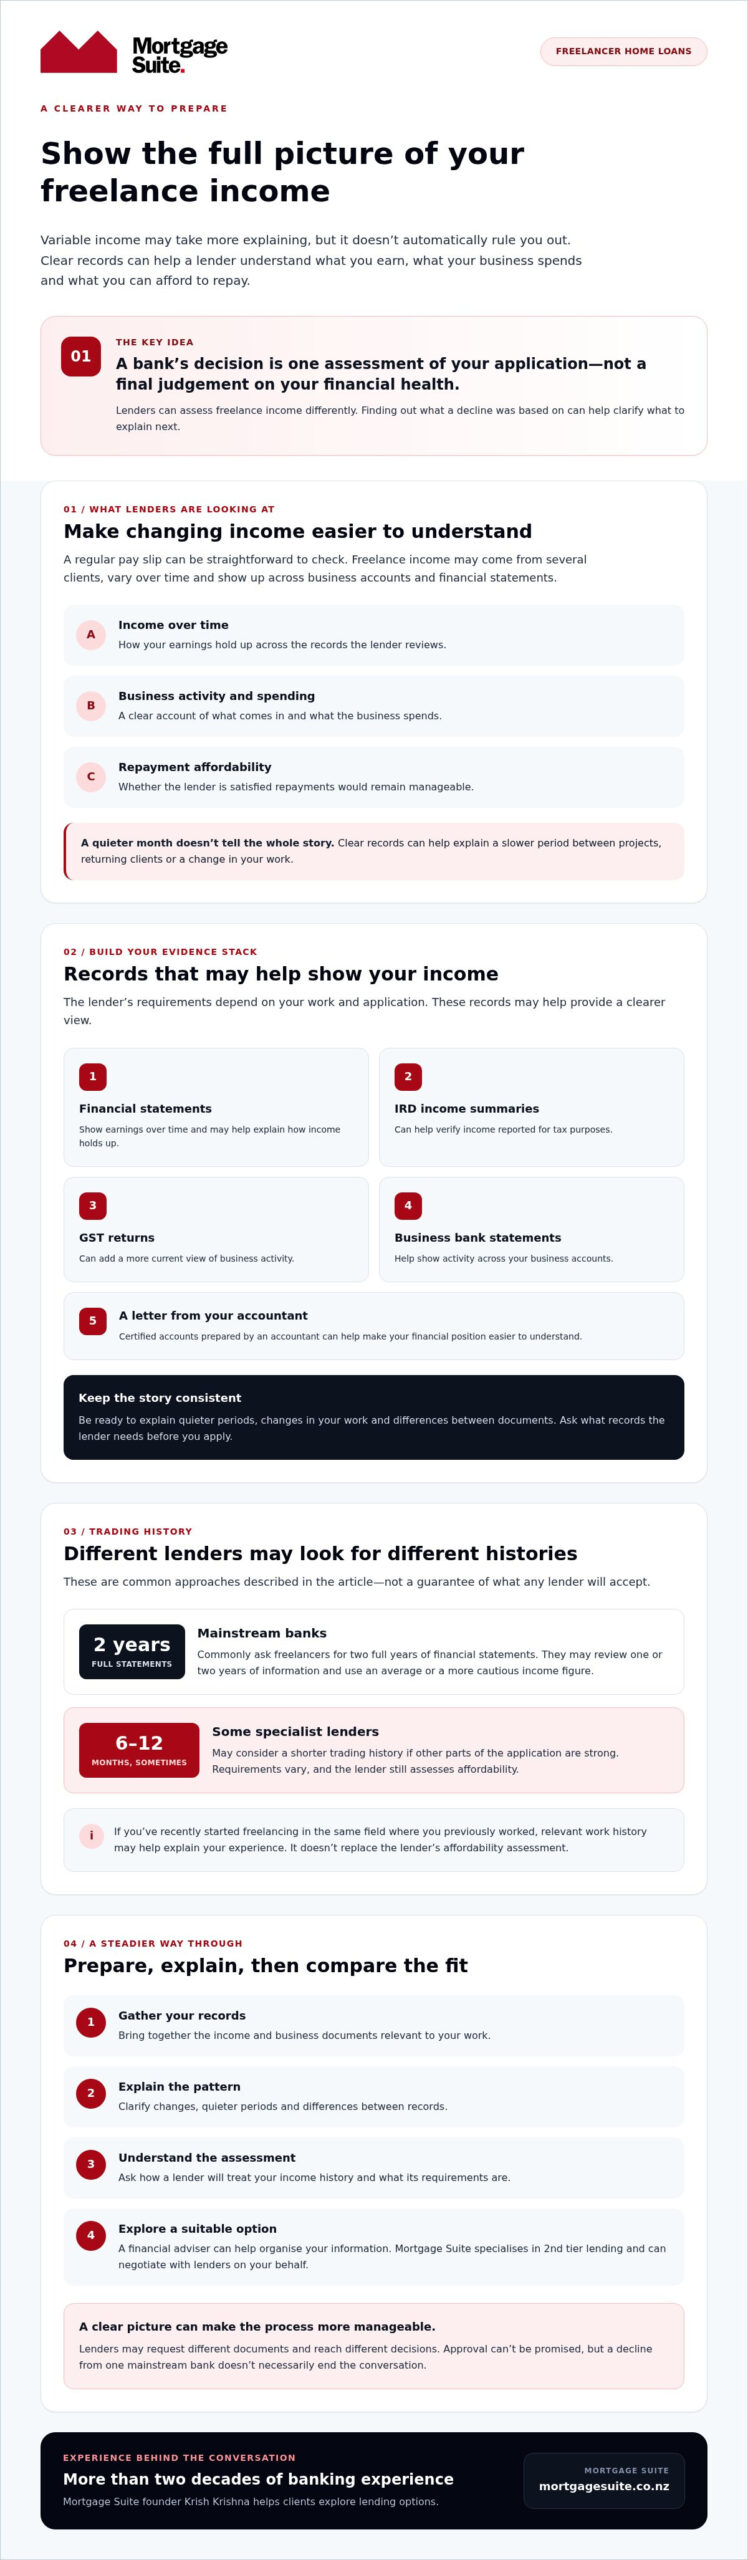
A contractor home loan is a mortgage application where the lender assesses income earned through contracting or freelance work rather than relying on a regular employee pay slip. The aim is to show a clear picture of what you earn, what your business spends and what you can afford to repay.

Start by gathering records that support a consistent account of your income and business activity. Depending on your work and the lender’s requirements, these could include financial statements, IRD income summaries, GST returns, business bank statements and a letter from your accountant. Be ready to explain quieter periods, changes in your work and differences between documents. Clear explanations can help prevent confusion later.

In the freelancer mortgage nz process, a financial adviser can help organise your information and present it in a way a lender can assess. Lenders may request different documents and reach different decisions. Being prepared means you can explain your income and circumstances more clearly.

The Role of IRD Records and GST Returns

IRD income summaries can help verify income reported for tax purposes. They aren’t pay slips, but they may form part of the official record a lender considers alongside your other documents. GST returns can add a more current view of business activity, while certified accounts prepared by an accountant can help make your financial position easier to understand. Ask what records the lender needs before you apply.

What if You Have Only Been Trading for One Year?

Mainstream banks commonly ask freelancers for two full years of financial statements. Some specialist lenders may consider a shorter trading history, sometimes around six to 12 months, if other parts of the application are strong. Requirements vary, so one year in business doesn’t automatically rule you out.

If you’ve recently started freelancing in the same field where you previously worked, include evidence of that experience and any relevant work history. It may help explain how your skills and client base support the business, but it won’t replace a lender’s assessment of affordability. Mortgage Suite specialises in 2nd tier lending for people who don’t fit mainstream criteria and can negotiate with lenders on your behalf. A suitable option depends on your full application, and approval isn’t guaranteed.

To understand how Mortgage Suite supports borrowers, see its team and approach.

Mainstream Banks vs 2nd Tier Lenders: Finding Your Best Fit

A “no” from a mainstream bank can feel personal, especially after you’ve gathered paperwork and explained how you earn. But it’s one lender’s decision using its own criteria, not a final judgement on you or your finances. Another lender may assess your income, work history and property equity differently. First, ask what drove the decline. Then consider whether clearer evidence or a different lending approach could suit your situation.

2nd tier lenders are an alternative for borrowers who don’t fit mainstream criteria. They’re not a shortcut around affordability checks, and approval is never guaranteed. They may, however, take a different view of a freelancer’s overall application. Mortgage Suite specialises in 2nd tier lending and can negotiate with lenders on your behalf. For more detail, read this guide to 2nd tier lender New Zealand options.

When the Local Branch Says No

A lender’s assessment process may not capture every detail of your work, income pattern or experience, particularly if your situation doesn’t fit standard categories. A decline can sting, but it doesn’t mean you’ve run out of options. Ask which parts of the application raised concern. That information can help you decide whether to provide clearer evidence, approach a different lender or review the loan structure.

The Flexibility of Non-Bank Home Loans

Some non-bank lenders may consider an equity safety net: the value you hold in a property after accounting for the borrowing secured against it. They may also assess applications differently, but lending criteria and available terms vary. Ask how repayments would fit your freelance cash flow, what conditions apply and whether the arrangement supports your longer-term plans.

It’s tempting to compare loans by the headline interest rate alone. For a freelancer, the fit also depends on how income is assessed, how repayments are structured and whether the arrangement leaves room for quieter periods. A loan that looks appealing at first glance may not suit your cash flow or future goals. Compare the full structure and ask questions before deciding.

For some borrowers, a 2nd tier loan may be a step towards buying sooner, with a possible plan to refinance to a mainstream lender later. That depends on your circumstances at the time, your repayment record and the criteria of the lender you approach. Treat refinancing as a goal to review, not a promise. In a freelancer mortgage nz application, the best-fit lender is one whose assessment and loan structure make sense for your situation and plans.

Freelancer Mortgage NZ: How to Get Your Home Loan Sorted in 2026

Your Step-by-Step Guide to a Successful Freelancer Application

A home loan application is easier to manage when you know what to do first. Get your records in order, check how repayments could fit your budget, then present your income and plans clearly to a lender. Preparation can reduce last-minute stress, and a well-organised application helps a lender understand the story behind the figures.

Here’s a practical place to start:

  • Separate business and personal spending. Make it easy to see which costs relate to your work and which are household expenses. If accounts have been mixed, add clear notes rather than leaving transactions unexplained.
  • Gather your financial statements. Have your latest statements ready, and aim to include the last two years if available. Lenders’ requirements vary, so ask what they need for your circumstances.
  • Review smaller debts. List balances and regular repayments. Paying down a debt may help your overall picture, but consider your cash reserves and speak with an adviser before making changes to your finances.

For a freelancer mortgage nz application, don’t just send documents without context. Explain changes in income, gaps between projects and unusual business expenses. That context can help a lender make sense of the figures.

Run a Serviceability Stress Test

A serviceability stress test is a lender’s way of checking whether you could still manage repayments if they assessed your borrowing using a higher interest rate than the one offered. It tests future affordability, not what rates will do.

You can try a similar check on your own budget. Use the mortgage calculator to explore repayment scenarios, then consider what would happen if your income dipped or household costs rose. Leave room for quieter trading periods, regular bills and business expenses. The calculator can help you explore possibilities, but it won’t confirm what a lender will approve.

Once you’ve prepared your records and tested your budget, you’ll be in a better position to discuss your options and identify any gaps before applying. Mortgage Suite can help present your circumstances to lenders and negotiate on your behalf. Talk with Mortgage Suite about your home loan options.

How Mortgage Suite Advocates for NZ Freelancers

Applying for a home loan as a freelancer can feel like you’re expected to fit your finances into a box designed for salaried workers. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to understanding clients’ circumstances and negotiating with lenders on their behalf.

That experience can help make sense of what a lender needs to see, where your application may need more explanation and which lending options could be worth exploring. It isn’t a promise of approval. Mortgage Suite can help you present your case clearly and explore possible options. Lenders make their own decisions, but a clear application gives them a better account of your circumstances.

You can learn more about Krish and the team on the About Us page.

Why a Negotiator Beats a Computer Algorithm

Your figures matter, but so does the context behind them. A negotiator can explain how your work history, client income and business records fit together, rather than leaving a lender to interpret unfamiliar details on their own. They can also discuss the loan structure, repayment fit and safety margin, not just the headline rate. Lenders still make their own decisions, but clear communication can help them understand your circumstances.

Getting Your Application Across the Line

Freelance work keeps you busy. Support with organising documents and responding to lender questions can make the application feel more manageable while you stay focused on your work. The steps and time involved depend on your circumstances and the lender, so ask what support you can expect throughout the process.

If you’re ready to explore a freelancer mortgage nz application, start by talking through your income, goals and any previous lender feedback. Mortgage Suite specialises in 2nd tier lending for people who don’t fit mainstream criteria and can negotiate with lenders to explore possible options. Approval isn’t guaranteed, but a bank decline doesn’t have to be the end of the conversation.

Talk with Mortgage Suite about getting your home loan sorted.

Take the Next Step Towards Your Home

Your freelance income doesn’t have to follow a standard pay-slip pattern for you to explore a home loan. Clear financial records can help lenders understand your earning history, and a decline from one bank doesn’t automatically close the door to other options. The right lender and loan structure depend on your circumstances, so focus on getting an assessment that accounts for your plans.

For a freelancer mortgage nz application, help explaining the story behind your figures can make the process more manageable. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience, and the company specialises in 2nd tier lending for people who don’t fit mainstream criteria. No one can promise approval, but you can get a clearer view of your options with help negotiating with lenders.

Ready to take the next step? Talk with Mortgage Suite about your freelancer home loan options.

Frequently Asked Questions

Can I get a mortgage if I have only been freelancing for a year?

Possibly. Some specialist lenders may consider a shorter trading history when other parts of your application are strong. Mainstream banks commonly ask for two full years of financial statements, while some non-bank lenders may consider around six to 12 months of records. Previous experience in the same industry, a clear income trail and your overall ability to manage repayments may help explain your position. Each lender assesses applications differently, and approval isn’t guaranteed.

Do I need a bigger deposit as a freelancer in New Zealand?

Not automatically. The deposit a lender requires depends on its criteria, the property and your overall application, including how it assesses your freelance income. Reserve Bank Loan-to-Value restrictions also affect how much some banks can lend against a property, but they don’t guarantee that a particular borrower will be approved with a smaller deposit. Ask lenders what deposit they require and whether your income evidence and property choice affect their decision.

What is a serviceability stress test and how does it affect me?

A serviceability stress test checks whether you could manage repayments if a lender assessed your application using a higher interest rate than the one offered. It helps the lender consider whether repayments could remain affordable if conditions change. As a freelancer, you can also test your budget by allowing for quieter work periods and household expenses. A mortgage calculator can help you explore repayment scenarios, but it doesn’t confirm how much a lender will approve.

Why did my mainstream bank decline my home loan application?

A decline can happen for several reasons, and it isn’t necessarily a final judgement on your financial health. The bank may have wanted a longer record of freelance income, assessed your earnings cautiously, or found that your expenses, debts, deposit or chosen property didn’t fit its criteria. Ask for the reason behind the decision. That can help you identify what to clarify or whether another lender may assess your circumstances differently.

What documents do I need to prove my income to a lender?

Lenders may ask for financial statements, IRD income summaries, GST returns, business bank statements and information from your accountant. The exact list depends on the lender and your work setup. These records help show your reported income and how your business is trading. Keep business and personal transactions clear, and explain gaps or unusual changes so the lender can understand the figures rather than guess what they mean.

Is a 2nd tier lender safe for a freelancer mortgage?

A 2nd tier lender can be an alternative for borrowers who don’t fit mainstream bank criteria, but check the full loan terms before deciding. Ask about repayments, fees, conditions, the loan structure and whether it suits your plans. Mortgage Suite specialises in 2nd tier lending. A lender’s suitability depends on your circumstances, and no lender can promise approval.

Can I still get a mortgage if my income fluctuates significantly?

Possibly. Lenders may review income over time and use an average or a more cautious figure to allow for changes in earnings. Clear records can help show whether quieter months are a normal gap between projects or part of a longer-term change. Include your business expenses and existing repayments in your budget, too. The freelancer mortgage nz options available to you depend on the lender’s assessment of your income and ability to repay.

What is the “Small Apartment Rule” and does it apply to me?

The Small Apartment Rule describes lender criteria that may treat apartments below a specified floor area as higher-risk security. There isn’t one standard size requirement across all lenders, so criteria may differ depending on the lender and the property. If you’re considering an apartment, ask how its size and features affect the deposit and lending criteria before making an offer. A lender’s assessment of the property is separate from its assessment of your income.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.