Contractor Home Loan NZ: Getting Your Mortgage Sorted in 2026

What if your bank saw your contracting career as a sign of professional success rather than a massive risk factor? For many Kiwis, the dream of home ownership feels like it’s on hold because their income doesn’t arrive in a tidy, fortnightly payslip. If you’ve been told you need years of perfect books or a “standard” job to qualify for a contractor home loan nz, you’re likely feeling the frustration of trying to fit a square peg into a round hole.

It’s exhausting to deal with lenders who don’t seem to understand that your fluctuating monthly income is just part of a thriving, modern career. We know the paperwork mountain feels high, but securing a mortgage shouldn’t mean sacrificing your independence. This guide will show you exactly how to navigate the 2026 market, from organising the right documents to finding a lender who looks at the big picture of your finances. You’ll discover a clear path to getting your mortgage sorted without the typical big-bank stress and discover how to make your career choice work for your home ownership goals.

Key Takeaways

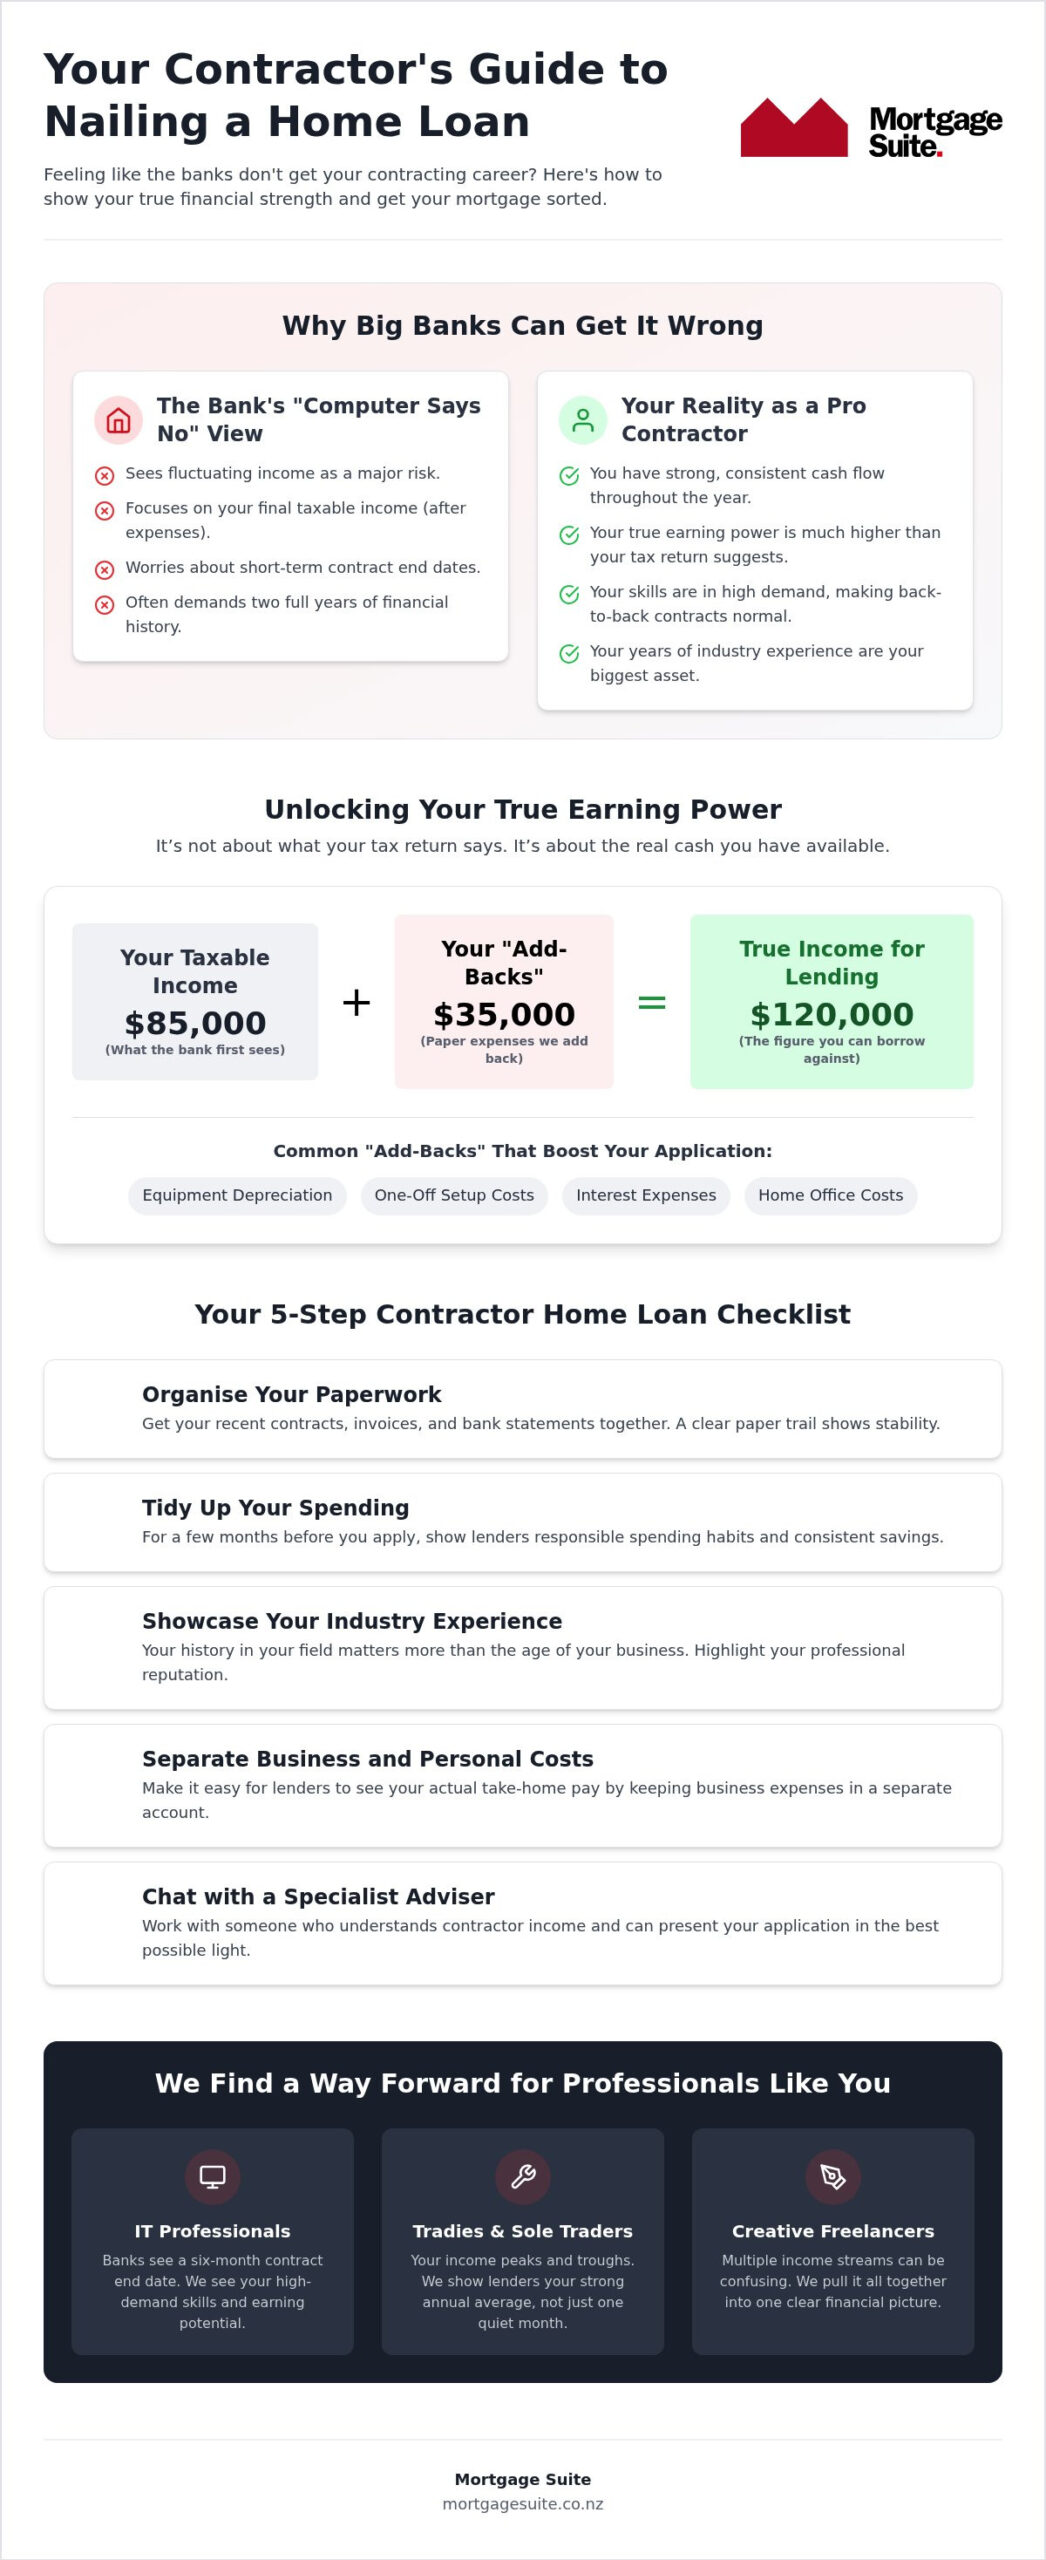
  • Understand why big banks often struggle with non-standard income and how to bypass their rigid “computer says no” systems.
  • Learn how to present your true earning power to lenders using simple methods that show your actual take-home pay, not just what’s on your tax return.
  • Compare the benefits of the “Big Four” banks against flexible 2nd tier lenders to find the best contractor home loan nz for your unique situation.
  • Follow our five-step checklist to organise your paperwork and clean up your spending before a lender even sees your application.
  • Discover how a steady hand with decades of experience can turn a complex application into a successful home purchase.

Why Big Banks Often Give Contractors the Cold Shoulder

Banks are creatures of habit. They’ve spent decades building systems that love one thing above all else: a predictable, fortnightly payslip. If you don’t have one, you’re suddenly an outlier. A contractor home loan nz isn’t actually a different financial product; it’s just a mortgage application that requires a human being to look at your bank statements instead of a computer algorithm. While the core concept of what is a mortgage remains the same, the path to getting one is much steeper when you’re your own boss.

When you apply at a big bank, you’re often met with a “computer says no” response. This happens because their software is designed to flag anything “different” as a “risk”. In reality, being a contractor often means you’re more resilient and higher-earning than a salaried employee, but the bank’s rigid rules don’t see it that way. They see your business expenses, which your accountant uses to lower your tax bill, as a lack of income. It’s a frustrating paradox; the more efficient you are with your taxes, the less the bank thinks you can afford to borrow.

The Salary-Only Mindset vs. Your Reality

Traditional lenders struggle with invoices because they represent a “maybe”. They worry that if your current contract ends, your income disappears entirely. This “fluctuating income” myth is one of the biggest hurdles we help clients clear. At Mortgage Suite, we don’t just look at the bottom line on your tax return. We look at your industry experience, your contract history, and the true value of your business. We treat you like a partner, not a set of data points. If you’re feeling overwhelmed by these concepts, our Mortgage School is a great place to start getting educated before you apply.

Common Contractor Scenarios We See

Every contractor’s story is unique, but we see a few common patterns that big banks usually reject. We regularly work with people in these situations to find a way forward:

  • IT Professionals: You might be on a high daily rate but only have a six-month contract. Banks see the end date; we see your high demand and niche skills.
  • Tradies and Sole Traders: Your income might peak in summer and dip in winter. We help show the bank your annual average rather than a single quiet month.
  • Creative Freelancers: Managing five different income streams can confuse a standard bank manager. We help pull those threads together into a coherent financial picture.

Cracking the Code: How Lenders Look at Your Income

Understanding how a bank calculates your earnings is the absolute secret to a successful application. When you’re chasing a contractor home loan nz, the number your accountant gives you at the end of the financial year isn’t always the number the bank uses to decide if you’re a “yes”. Your accountant’s main goal is to keep your tax bill as low as possible, which is great for your wallet but can look like low income to a bank manager. This is where we show your true financial strength by looking at your “add-backs”. We take expenses that don’t actually cost you cash every month, like the drop in value of your equipment or a one-off office fit-out, and add them back to your profit. It’s a simple way of showing the lender that this money is actually available to cover your mortgage.

A seasoned expert knows that your history in your industry is your biggest asset. Lenders often care more about how long you’ve worked in your specific field than the length of your current contract. If you’ve spent fifteen years as a project manager but only started your own business last year, we can often present you as a very safe bet. We focus on building a file that highlights your professional reputation and your consistent ability to secure high-value work. Organising your application this way makes it much harder for a bank to say no just because your business is relatively new.

Taxable Income vs. Actual Cash Flow

Banks have a specific way of asking how much you can afford to pay back each week. They want to see your cash flow, which is the real money moving through your accounts. We help you identify one-off costs that shouldn’t hurt your chances, like a new work ute or a major marketing campaign. By separating these unique expenses from your regular living costs, we give you a fair go at proving what you can really afford to borrow. If you’re curious about how your income might translate into a loan, check out our mortgage calculator to see what’s possible today.

The Two-Year Rule: Is it Still Relevant?

You don’t always need two full years of accounts to buy a home in New Zealand. While the big banks are quite rigid about this, we frequently help people who only have one year of financial history. In many cases, we use alternative lenders as a helpful bridge. These companies are often much more flexible with newer businesses. This allows you to get the keys to your home today and then move your loan to a major bank once you’ve got a longer track record under your belt. Learn more about 2nd tier lending and how it can help you get around the strict two-year requirement.

Mainstream vs. 2nd Tier: Finding the Right Fit

Most Kiwis grow up thinking the major banks are the only places to get a mortgage. While these big institutions offer competitive rates for standard borrowers, they aren’t always the best choice for your first contractor home loan nz. These massive organisations operate like financial factories; they need every application to look exactly the same. If your income comes from multiple sources or your business expenses are high, you might find their systems aren’t built to handle your complexity. This is where alternative, or 2nd tier, lenders become a vital part of your strategy.

Specialist lenders don’t just look at a score on a screen. They employ real people who take the time to understand your industry and your earning potential. They often offer loans that require less paperwork, which means they might accept GST returns or bank statements instead of two years of full financial accounts. You’ll likely pay a slightly higher interest rate with these lenders, but it’s often a price worth paying to get into your home now rather than waiting years to satisfy a traditional bank’s strict criteria.

When to Choose a 2nd Tier Lender

Choosing an alternative lender is often a smart “stepping stone” strategy. If you’re a first home buyer who has recently started contracting, you might not fit the standard bank boxes yet. We often help clients secure a 2nd tier loan to get them into the property market today. Once you’ve built up a year or two of solid accounts, we can then help you move that loan back to a mainstream bank at a lower rate. It’s about getting the keys in your hand now so you can start building equity. Check out our Mortgage School for more tips on how to prepare for this transition.

The Pros and Cons of Non-Bank Loans

The biggest advantage of a non-bank lender is speed and a personalised approach. You aren’t just another number in a call centre queue. These lenders are often much faster at giving you an answer, which is crucial when you’re trying to buy in a competitive market. While the interest rate might be higher, the flexibility they offer can be the difference between buying a home and missing out entirely. We weigh these options with you to ensure the choice makes sense for your long-term goals.

Feature Mainstream Banks 2nd Tier Lenders
Approval Speed Often slow (7 to 10 days) Fast (2 to 3 days)
Flexibility Rigid, computer-led rules Human-led, common sense
Income Proof Full financials required Accepts GST or bank statements

Contractor Home Loan NZ: Getting Your Mortgage Sorted in 2026

Your Contractor Home Loan Checklist: Getting Sorted

Preparing for a contractor home loan nz is about more than just having a deposit. It’s about telling a financial story where you’re a reliable professional, not a risky outlier. To get bank-ready, you need to look at your finances through a lender’s eyes. This starts with your accountant. They aren’t just there to file your GST; they’re your primary witness. An accountant can provide a letter confirming your projected income or explaining that a large expense was a one-off business investment that won’t happen again next year.

One secret weapon many people overlook is an updated CV. While it sounds odd to bring a resume to a mortgage meeting, a professional profile showing a long history of successful projects proves to the bank that you’re in high demand. If your current contract ends, your CV shows you have the skills to land the next one immediately. This simple document turns you from a “temporary worker” into a “highly sought-after specialist” in the eyes of the credit team.

Before a broker even sees your file, take a few months to clean up your personal spending. Banks look closely at your uncommitted monthly income. Frequent small debts like buy-now-pay-later schemes or high-interest credit cards can significantly lower your borrowing power. We recommend following these five essential steps to get sorted:

  • Collaborate with your accountant to frame your income correctly.
  • Audit your bank statements and pause non-essential subscriptions.
  • Refresh your professional CV to show career longevity.
  • Clear small debts and close unused credit cards or personal loans.
  • Organise your tax documents so everything is ready to go.

The Paperwork You Actually Need

Lenders want to see proof that your business is healthy. This means gathering your IRD income summaries and GST returns for the last year. While big banks might ask for more, having six months of clean business bank statements is often the most important factor. These statements prove the cash flow we discussed earlier. You’ll also need to show exactly where your deposit is coming from, whether it’s genuine savings, equity in another property, or a gifted sum from family.

Improving Your Chances of a “Yes”

Reducing your personal debt is the fastest way to boost your application. Even a credit card you don’t use with a $10,000 limit is seen as a potential debt by the bank. It’s also helpful to keep a buffer of cash in your business account to show you can handle a quiet month without stress. To get a better idea of your position, try using our mortgage calculator to see how your current debts might affect your borrowing. If you want a hand getting your documents in order, contact our team at Mortgage Suite for a personalised review.

How Mortgage Suite Navigates the Maze for You

Applying for a mortgage when you work for yourself can feel like walking through a maze where the walls keep moving. At Mortgage Suite, we see our role as the steady hand that guides you through every turn. Krish Krishna leads our team with over two decades of experience inside the banking industry. This isn’t just a number on a page; it means we know exactly how the people on the other side of the desk think. We don’t just fill out forms. We act as your dedicated negotiator, presenting your financial story in a way that makes sense to a lender’s credit department.

The big banks often have a rigid view of what a “safe” borrower looks like. We challenge that view by highlighting your professional potential and your industry reputation. Whether you’re looking for a standard bank mortgage or a 2nd tier loan that fits your current lifestyle, we handle the complex heavy lifting. This allows you to stay focused on your business while we manage the endless follow-ups and paperwork required for a successful contractor home loan nz application. We’ve seen every possible scenario and know exactly how to bridge the gap between your personal needs and the rigid world of institutional banking.

A Personalised Path to Home Ownership

We believe in straight talk. You won’t get any corporate lectures or confusing financial jargon from us. Instead, we offer a non-corporate experience that puts your goals first. Our process is designed to be as stress-free as possible, moving at your pace while ensuring every detail is perfect before it reaches a lender. We take pride in the relationships we build, and our client reviews show that we care about the person behind the loan, not just the numbers on the screen. We’re here to be your advocate, ensuring you get a fair go from the very start.

Ready to Get Started?

If you’re ready to see what’s possible, the first step is a simple, no-obligation chat. You don’t need to have all your paperwork perfectly organised yet. In a quick 15-minute consultation, we can look at your current situation and give you a clear idea of your options. We’ll explain how we can help you navigate the 2026 market and what the next steps look like for your specific career path. You can learn more about Mortgage Suite and our mission to help Kiwis who don’t fit the standard bank box. Let’s get your mortgage sorted together.

Take the Next Step Toward Your New Home

Contracting gives you freedom and flexibility, and your mortgage should reflect that success. By understanding how lenders view your income and preparing your file with a professional eye, you can bypass the “computer says no” culture of the big banks. Whether you need a mainstream bank or a flexible 2nd tier solution, the right strategy turns a complex application into a successful result. We’ve shown you that the paperwork mountain is manageable when you have the right guide by your side.

With over 20 years of banking and brokerage expertise, we know how to present your case to get a fair go. We specialise in alternative and 2nd tier lending solutions for those who don’t fit the standard box, acting as a dedicated advocate who knows exactly how to talk to the banks on your behalf. Securing a contractor home loan nz doesn’t have to be a mountain of stress. You’ve worked hard to build your career; now it’s time to make that career work for your home ownership goals.

Get your contractor home loan sorted with Mortgage Suite and take the first step toward the keys to your new home. We’re here to make the process simple, clear, and successful.

Frequently Asked Questions

Can I get a home loan with only 6 months of contracting history?

Yes, you can certainly secure a loan with six months of history, though you’ll likely need to look beyond the big banks. Most mainstream lenders prefer two years of accounts, but 2nd tier specialists often accept six months if you have a solid background in the same industry. We focus on showing the lender that your career is stable despite the recent change in how you’re paid.

Do contractors pay higher interest rates in New Zealand?

Contractors don’t automatically pay higher rates, but it depends on which lender approves your application. If your file is strong enough for a mainstream bank, you’ll get the same market rates as anyone else. If you require the flexibility of a 2nd tier lender to get your contractor home loan nz approved, you might pay a slightly higher rate. This is often a temporary step until you have more history.

Can I use my business income to buy a house if I am a sole trader?

You can absolutely use your sole trader income to buy a house. Lenders treat your business profit as your personal income. We work with you to identify “add-backs” like depreciation or one-off equipment costs that shouldn’t count against your borrowing power. This ensures the bank sees your actual cash flow rather than just the lower figure your accountant uses to reduce your tax bill.

How much deposit does a contractor need for a home loan in NZ?

Deposit requirements for contractors usually follow the same standard rules as salaried employees. For most first home buyers, a 20% deposit is the gold standard, though some schemes allow for as little as 5% or 10% depending on the property. If you’re looking at an investment property, you’ll generally need closer to 30% or 35% to satisfy current New Zealand lending restrictions and bank policies.

What happens if my contract is about to end?

Having a contract near its end date isn’t an automatic “no” if we can prove your future earning potential. We use your professional CV and industry history to show the bank that you’re in high demand and likely to secure a new contract quickly. Providing a letter of intent from your current client or showing a history of back-to-back contracts helps alleviate the bank’s concerns about potential income gaps.

Can I get a “low-doc” loan as a contractor in 2026?

Low-doc loans are a very real option in 2026, especially through alternative lenders. These loans allow you to prove your income using GST returns or business bank statements instead of full, accountant-prepared financial statements. This is a popular choice for contractors who haven’t completed their first full year of trading but have a clear and consistent stream of income hitting their business accounts every month.

Does being a contractor affect my ability to get a first home grant?

Your employment status doesn’t stop you from getting a first home grant, but your total income must stay under the government caps. The key challenge for contractors is proving their taxable income for the previous 12 months. As long as you can provide the correct IRD summaries and meet the standard criteria, you’re just as eligible as a salaried worker to access these government support schemes.

Is it better to apply as an individual or through my company?

Most lenders will look at your total household or global income regardless of whether you’re a sole trader or a company director. Even if you trade through a company, the bank will usually require you to be a personal guarantor for the loan. We help you structure the application to show your income in the most favourable light, ensuring the bank understands the full picture of your finances.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Buying Property as a Contractor in NZ: Your 2026 Guide to Getting Sorted

Why should choosing a career with freedom and flexibility feel like a penalty when you walk into a bank? You’ve worked hard to build a high-earning career, yet many bank managers still treat your income like a guessing game. It’s incredibly frustrating to have a healthy bank balance but still face a wall of “no” because your paperwork doesn’t fit a standard 9-to-5 template. If you’ve been worried that buying property as a contractor nz is out of reach because you don’t have years of tidy tax returns, you’re certainly not alone.

We believe your contract structure is a sign of your expertise, not a financial weakness. You deserve a clear path to home ownership that recognises your actual earning power. This guide will show you how to secure a home loan as a contractor in New Zealand, even if the big banks have already turned you away. We’ll explore which lenders offer the most flexibility and how you can get into your new home without waiting years for a “perfect” set of books. It is time to stop waiting and start planning your move.

Key Takeaways

  • Learn why being a contractor is actually a career strength in the 2026 property market, provided you know which lenders to approach.
  • Discover the exact steps for buying property as a contractor nz by focusing on your total industry experience rather than just your most recent contract.
  • Understand why alternative lenders are often the perfect choice for contractors who need a flexible approach to income proof.
  • Find out how starting your preparation six months early can help you organise your finances to meet strict lending criteria.
  • See how professional negotiation can turn a bank’s “no” into a “yes” by presenting your financial history in a way that highlights your stability.

Can You Actually Buy a House as a Contractor in NZ?

The short answer is a resounding yes. Buying property as a contractor nz is entirely achievable in 2026, even if your local bank manager seemed a bit hesitant when you first mentioned your work status. While the landscape has changed, the core mortgage loan fundamentals remain the same; lenders simply want to know that you can afford the repayments over the long term. They aren’t necessarily looking for a reason to say no, but they are looking for proof of stability.

The old idea that you must have two years of perfect tax returns is a common myth that stops many people before they even start. In reality, your financial fitness is about your overall stability and industry experience. If you’ve done the same type of work for five years but only contracted for six months, many lenders will take that previous experience into account. It’s about the story your numbers tell, not just the length of time you’ve been your own boss.

Understanding the Different Types of Contracting

How a lender looks at you often depends on how you get paid. If you’re a PAYE contractor, you’re often in the strongest position. Since tax is taken out before the money hits your account, some banks may even treat you like a permanent employee if your contract has a decent amount of time left on it. This makes the application process feel much more like a standard home loan.

Sole traders have a slightly different path. Lenders will look closely at your tax records to understand your actual profit after all your expenses are paid. They want to see that there’s enough left over to live comfortably and pay a mortgage. For company directors, the situation is more layered. Banks will look at the salary you pay yourself plus any profit the business keeps. It’s a more complex calculation, but it provides a much fuller picture of your actual wealth and ability to handle a loan.

Why NZ Banks Are Often Cautious

Most big banks are designed for people with predictable, steady paycheques. When they see a contractor, they immediately worry about income gaps, those times between projects where you might not be earning. This perceived risk makes them cautious. They calculate how much the bank thinks you can afford to pay back by looking for the lowest common denominator, often averaging your income over a long period or applying factors to your earnings to account for potential downtime.

This traditional box-ticking exercise is where many highly skilled contractors get stuck. A bank’s computer system might see a three-week holiday between contracts as a red flag, whereas a human negotiator sees it as a well-deserved break for a successful professional. When you’re buying property as a contractor nz, you need a strategy that bypasses these rigid internal bank rules and focuses on your actual ability to manage the debt.

What NZ Lenders Really Want to See from Contractors

When you’re looking into buying property as a contractor nz, it’s easy to get fixated on your daily or hourly rate. While earning good money is great for your bank balance, lenders are actually hunting for something different: sustainable income. They want to see that your earnings aren’t just a temporary spike. A bank looks for a track record that suggests you’ll be able to keep meeting those mortgage repayments years down the track. They aren’t just buying into your current project; they’re buying into your long-term career stability.

This is where your industry experience before you started contracting becomes your secret weapon. If you’ve spent a decade in your field and only recently moved to contracting, that experience proves you’re highly employable. Another major factor is your actual profit after expenses versus the total money coming in before costs. Many contractors work hard to keep their taxable income low by claiming business expenses. While this is smart for tax, it can accidentally lower how much you can afford to repay in the eyes of a bank, as they generally only look at the “bottom line” profit on your tax returns.

The Magic Number: Is Two Years Still the Standard?

Most mainstream banks still treat 24 months of financial records as their default requirement. They like the neatness of two full years of tax summaries. However, this isn’t a brick wall. If you work in high-demand sectors like IT, healthcare, or engineering, many lenders are willing to look at a shorter history. If you have one year of strong accounts and a signed contract that extends into the future, we can often build a compelling case. Having a larger deposit, typically 20% or more, also goes a long way in giving the lender peace of mind.

Documenting Your Income Correctly

Your paperwork needs to tell a clear, honest story. You’ll need your tax summaries and GST returns ready to go, as these are the primary documents a lender will use to check your earnings. They will also look closely at your current contract end date. If your contract is due to finish shortly, having a renewal letter or a history of rolling contracts with the same client is incredibly helpful. It’s often a good idea to chat with a specialist to review your accounts before you approach a bank, ensuring your business expenses aren’t unfairly masking your true ability to repay a loan.

Your Step-by-Step Guide to Getting Mortgage-Ready

Success in buying property as a contractor nz often comes down to what you do months before you ever visit an open home. Think of your mortgage application as a story you’re telling the bank; you want that story to be one of stability and discipline. Starting your preparation at least six months ahead of time gives you the space to polish your financial profile and address any small issues that might otherwise cause a delay. It’s much easier to fix a paperwork gap now than it is when you’ve already found your dream house.

One of the most powerful things you can do is maintain a healthy cash buffer in your business account. Lenders love seeing that you don’t live hand-to-mouth. If you have enough cash set aside to cover a few months of expenses, it proves that a short gap between contracts won’t put your mortgage at risk. At the same time, you should strictly avoid taking on any major new debt. That shiny new work ute on finance might look great, but the monthly repayments will directly reduce how much a bank is willing to lend you for a home.

Step 1: Get Your Financial House in Order

The first step is to draw a clear line between your personal life and your business. You should have separate bank accounts for everything. When a lender sees personal grocery shops mixed in with business software subscriptions, it makes your income harder to verify and your spending habits look messy. You also need to ensure your relationship with the IRD is spotless. Being up to date with your GST and income tax payments is non-negotiable for a smooth approval.

A smart trick is to write a brief, one-sentence summary of your work history. Instead of just showing a few months of contracting, highlight your total years in the industry. This simple document helps the lender see your long-term expertise and reliability rather than just your current tax status. It shifts the conversation from “how long have you been a contractor” to “how long have you been an expert in your field.”

Step 2: Maximise Your Deposit and KiwiSaver

Your deposit is the ultimate lever for getting a “yes.” While some lenders accept less, hitting that 20% mark often unlocks lower interest rates and simpler approval processes at mainstream banks. If you’re a first-time buyer, you should definitely check your eligibility for a KiwiSaver first home withdrawal NZ. It’s often the biggest boost to a contractor’s deposit, especially if you’ve been contributing consistently over several years.

For those with high cash flow but lower savings, we often look at alternative ways to show your equity. This might include using existing property as security or receiving a gift from family. When buying property as a contractor nz, the goal is to show the lender that you have skin in the game, regardless of where those funds originated. The more equity you bring to the table, the more flexible a lender becomes with your income structure.

Banks vs. 2nd Tier Lenders: Choosing the Right Path

Choosing which lender to approach is a major decision when buying property as a contractor nz. Mainstream banks are like the big department stores of the financial world; they offer the lowest interest rates, but their rules are often set in stone. If your situation doesn’t fit their standard mould, you’ll likely get a quick rejection. This is where a 2nd tier lender New Zealand comes into play. These specialists are more like boutiques; they have the time to look at your actual bank statements and work out how much you can really afford to pay back, rather than just relying on an automated system.

Many people worry that choosing a non-bank lender means paying much higher interest. While the rates can be slightly higher, you need to weigh that against the cost of waiting. If you spend another two years trying to meet a big bank’s strict requirements, house prices could jump significantly during that time. In many cases, it makes more sense to get into your home now and plan on moving your loan to another bank later once you have a longer track record as a contractor. It’s a stepping stone strategy that gets you on the property ladder much sooner than the traditional route allows.

When to Stick with the Big Banks

If you have more than two years of solid, increasing income on your tax returns, a big bank is usually your best bet. You’re also in a strong position if you are applying with a partner who has a standard job. Having one person with a predictable paycheque acts as a safety net for the lender, making them much more comfortable with your contracting income. Lenders also tend to be more relaxed if you work in a high-demand industry where new contracts are easy to find and tend to last for long periods without gaps.

When 2nd Tier Lending Makes More Sense

If you’ve been working for yourself for less than a year, or if your latest tax return shows a lot of one-off business costs that make your actual profit look lower than it really is, a 2nd tier lender is often the only realistic path. These lenders are much more interested in your current cash flow and your future potential than your past tax history. At Mortgage Suite Ltd, we specialise in finding loans that don’t fit bank criteria NZ. If the big banks aren’t listening, reach out to our team to see how we can help you find a lender that actually understands how your business works.

How We Organise Your Contractor Home Loan Application

Getting a mortgage shouldn’t feel like a stressful audit or a high-stakes interrogation. When you’re buying property as a contractor nz, the biggest mistake is simply handing over a stack of bank statements and hoping the person on the other side understands them. We take a completely different approach. We don’t just submit papers; we translate your financial life into a story that makes sense to a lender. We focus on your expertise, your industry longevity, and your future earning potential, rather than just the latest figure on a tax bill.

Krish Krishna leads our team at Mortgage Suite Ltd with over two decades of banking and negotiation experience. He knows exactly how bank credit teams think because he has spent years on that side of the desk. This insider knowledge is vital because lending rules in New Zealand aren’t static. Some banks might be closed to contractors one month, while others are actively “hungry” to grow their business in that sector. We identify the lenders who are currently looking for clients exactly like you, so you don’t have to face unnecessary rejections.

The Mortgage Suite Ltd Advantage for Contractors

We provide a bridge to lenders that many people don’t even know exist. Our team has direct access to alternative capital and private lenders who operate with much more flexibility than the big four banks. This is a massive advantage if you’re looking into residential investment property loans NZ to build your long-term wealth. Whether you’re buying your first home or an investment, we’re personally committed to finding a “yes” even when other institutions have already said “no.”

Ready to Get Sorted?

Your first step shouldn’t be a cold appointment at a local bank branch where the manager might not grasp the nuances of contract structures. Instead, your journey should start with a relaxed conversation. In our initial consultation, we’ll look at your current contracts, your industry history, and your deposit goals. It’s a helpful dialogue designed to give you a clear roadmap without the corporate pressure. We want to remove the obstacles so you can focus on finding the right house.

When you’re ready to meet, try to have your latest tax summaries and current contract details ready. Don’t worry if your books aren’t “perfect” just yet; our job is to help you organise them so they look attractive to the right lender. If you’re serious about buying property as a contractor nz, it’s time to work with a team that actually understands your career path. Book a chat with the Mortgage Suite Ltd team today and let’s get your home loan sorted.

Take the Next Step Toward Your New Home

Buying property as a contractor nz doesn’t have to be a source of stress or a series of rejections. We’ve seen that the traditional two year rule is often more of a guideline than a brick wall, especially when you have a solid industry background and the right strategy in place. Whether you’re approaching a big bank with a hybrid application or using a 2nd tier lender as a strategic stepping stone, your career choice should be your greatest asset, not a hurdle.

You deserve a partner who understands the nuances of your income and knows how to present your story to the people who make the decisions. Krish Krishna brings over 20 years of banking and negotiation experience to your side, offering a personalised service that focuses on finding a solution when others only see problems. We specialise in 2nd tier and alternative lending, ensuring you can move into your new home without unnecessary delays. It’s time to stop letting rigid bank rules hold you back from your property goals.

Let us negotiate your contractor home loan for you and get your future sorted today. You’ve worked hard to build your career; now let’s make sure it works for your home ownership dreams.

Frequently Asked Questions

Can I buy a house if I have only been contracting for six months?

Yes, you can certainly buy a house with six months of contracting history, though you’ll likely need to look beyond the big mainstream banks. If you have a long history of working in the same industry before you started contracting, specialist lenders are often happy to consider your application. They focus on your overall career stability rather than just the length of your current contract.

Do contractors need a bigger deposit than permanent employees in NZ?

You don’t strictly need a bigger deposit, but having 20% saved makes the process much easier. While some lenders may accept a smaller deposit, hitting that 20% mark helps offset the bank’s concerns about fluctuating income. It often unlocks better interest rates and more flexible lending terms, making buying property as a contractor nz a much smoother experience.

What documents do I need to prove my income as a sole trader?

Lenders will primarily want to see your IR3 tax summaries, GST returns, and recent business bank statements. These documents provide a clear picture of your earnings and your ability to manage your tax obligations. It is also helpful to have your current contract handy to show your agreed rate and the expected length of your current project.

Will a bank look at my gross turnover or my net profit?

Banks almost always focus on your net profit, which is the amount you have left after all business expenses are paid. This is because your net profit represents the actual income available to meet your mortgage repayments. If you’ve worked hard to minimise your taxable income, it’s a good idea to chat with us about how that impacts your borrowing power.

Can I use my KiwiSaver if I am a self-employed contractor?

Yes, being a contractor doesn’t stop you from using your KiwiSaver for a first home deposit. As long as you’ve been a member for at least three years and meet the standard criteria, you can withdraw your funds. This remains one of the most effective ways to boost your deposit when buying property as a contractor nz.

What happens if my current contract is due to end soon?

A contract ending soon isn’t an automatic “no” if you can show a history of steady work. Lenders look for a track record of contract renewals or a high demand for your skills in the current market. Providing a letter of intent from your current client or showing a new signed contract can often solve this concern for the lender.

Are interest rates higher for contractor home loans?

Interest rates are generally the same as standard loans if you meet a mainstream bank’s criteria. If your application needs to go through a 2nd tier lender because of a shorter work history, the rate might be slightly higher. Many contractors use these lenders as a temporary solution for a year or two before moving back to a bank.

Is it better to apply for a home loan as a sole trader or a company director?

Neither structure is strictly better, as lenders are mostly interested in the total income you can prove. Whether you draw a salary as a director or take drawings as a sole trader, the lender will look at the underlying profit of the business. The most important factor is having clear, organised financial records that show your true earning potential.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.