NZ Property Development Loan Requirements 2026

A lender’s decision on a development project depends on more than the land or your borrowing history. Lenders may also assess whether the plan can be delivered, whether the numbers make sense and how the loan will be repaid. That can make property development loan requirements nz feel unclear, especially if you’re unsure which documents to prepare or how your experience and project structure will be assessed.

It’s reasonable to want a clear picture before you apply. This guide explains the main areas lenders may assess and the project information that can support an application, including plans, budgets, building contracts and funding stages. You’ll also learn how project progress can affect the drawdown process and what options may be available if a mainstream bank’s criteria don’t fit. Mortgage Suite provides property development finance and helps organise project information and negotiate with lenders. Founder Krish Krishna brings more than two decades of banking experience to these discussions. A bank decline isn’t always the end of the conversation. Understanding what may suit your project is a practical next step.

Key Takeaways

  • Property development loan requirements nz can vary according to the lender, project type, stage and funding structure.
  • Lenders may consider your experience, finances, project feasibility, security and plan for repaying the loan.
  • Grouping supporting documents into clear categories can help you prepare a more organised application.
  • Review your project assumptions, timeline and repayment plan so you’re ready to discuss delays or changes.
  • A finance adviser can help present your project to lenders and explore suitable funding pathways if a mainstream bank isn’t the right fit.

Property development loan requirements in NZ: what lenders look at first

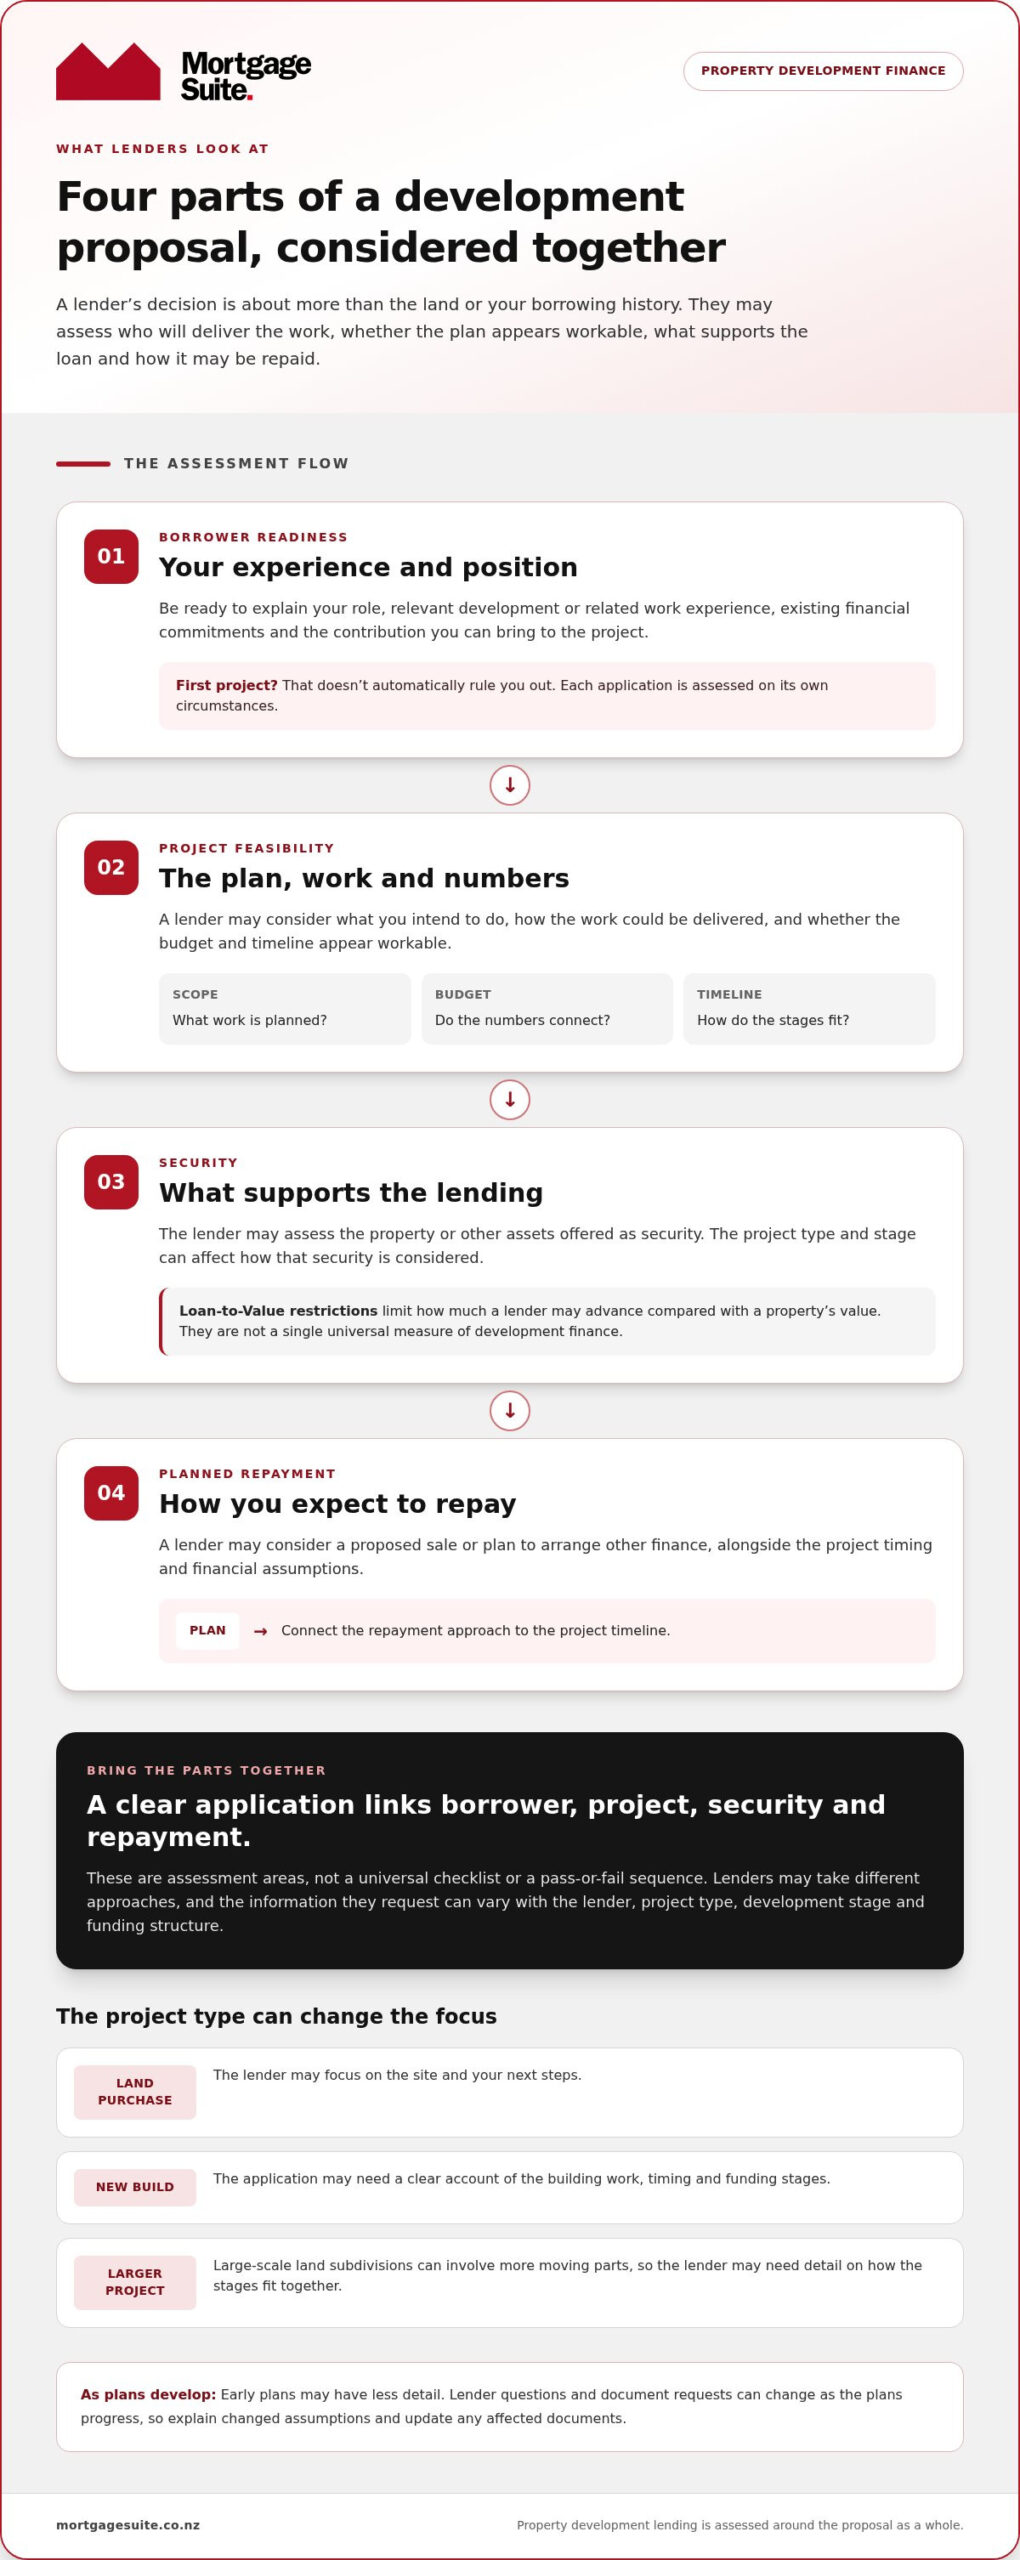
In brief: Lenders usually consider the borrower, project, available security and proposed repayment plan together. The property development loan requirements nz applicants face can vary with the lender, project type, development stage and funding structure. There isn’t one document or criterion that applies to every application.

A lender is assessing the project’s risks as a whole: who will deliver it, whether the plan appears workable, what property supports the borrowing and how you intend to repay the loan. A clear application connects these elements and explains how the project is expected to progress.

What does a property development lender assess?

Four broad areas help a lender build a picture of your proposal:

  • Your experience and position: Your background may help explain your ability to manage the work. A lender may also consider your financial position and existing commitments.
  • The project plan: The lender needs to understand what you intend to do, how the work may be delivered and whether the project appears financially workable. Development can involve connected stages, from acquiring land through to construction, as outlined in this real estate development process.
  • Security: The property or other assets offered as security help the lender assess what supports the loan. The project type and stage may affect how that security is considered.
  • Repayment plan: The lender will want to understand how you propose to repay the borrowing, such as through planned sales or by arranging other finance. The plan should fit the project timeline.

These are assessment areas, not a universal checklist. The evidence a lender requests depends on the application. Organising your information around these points can help you explain the proposal clearly.

Why development loan requirements differ between projects

A request to fund a land purchase may focus on the site and your next steps. A new build may need a clear account of the building work, timing and funding stages. A larger project, such as large-scale land subdivisions, can involve more moving parts, so a lender may need detail on how the stages fit together.

Project stage matters too. Early plans may have less detail than a project that’s further along. Lender questions and document requests can change as the plans develop, and lenders may take different approaches. The phrase property development loans in NZ covers a range of funding situations rather than one standard application. Start by organising information around your specific project and what is known at its current stage.

How lenders assess your experience, finances and project plan

A lender looks at how your background and finances fit the project, not just whether the land appears suitable. Property development loan requirements nz can differ between lenders, so use these assessment areas as guideposts rather than a pass-or-fail checklist.

Borrower readiness: What experience, financial commitments and contribution do you bring? Relevant development experience can show how you’ve handled similar work and help a lender understand your role in delivering the project. If this is your first project, that doesn’t automatically rule you out. Each application is assessed on its own circumstances.

Project feasibility: Does the plan appear workable? A clear description of the work, budget and timeline helps explain what you intend to do, how the stages connect and what could affect delivery.

Security: What property or other assets are being offered to support the lending? Owning suitable land may form part of the picture, but it doesn’t guarantee finance. The lender also considers the borrower, proposed work and repayment plan.

Planned repayment: How do you expect to repay the loan? A lender may consider your proposed sale or refinancing plan alongside the project timing and financial assumptions.

How your background and financial position may be considered

Be ready to explain your role in the project and any relevant experience, whether from previous developments or related work. Lenders may also consider your existing commitments and the contribution you can bring to the project. Together, these details give a fuller picture of your borrowing position.

How a lender may review project feasibility and security

A joined-up plan makes it easier to see how the budget, timeline and intended work relate to each other. If an assumption changes, explain why and update any documents it affects. For general property-sector context, Property Council New Zealand shares information about the industry, while lender decisions depend on the individual proposal.

Loan-to-Value restrictions are limits on how much a lender may advance compared with a property’s value. They aren’t a single universal measure of development finance. The lender, project and funding structure can all affect how security is assessed. Mortgage Suite helps organise these parts into a clear application and discuss how to present your circumstances. You can also learn about Mortgage Suite’s approach to supporting borrowers through lending decisions.

Which documents can support a property development loan application?

A well-organised application connects your circumstances with the project plan. For property development loan requirements nz, requested documents vary by lender, project type and stage. Use this preparation checklist as a starting point, then tailor it to the information available for your project. Some items may not apply, and a lender may request other evidence.

Borrower and project information to organise

  • Borrower: Identification, details of your financial position and existing commitments, and information about the project’s ownership structure.
  • Experience: A summary of relevant project history, including your role and examples of completed work, if applicable. This helps explain who will manage delivery.
  • Land or property: Information about the site, its ownership and any existing lending secured against it. A valuation or other property report may also be requested.
  • Project: A short project summary, development plans, timeline, budget and proposed funding schedule. Make clear what work is planned and when funding may be needed.
  • Repayment plan: An outline of how you expect to repay the borrowing, supported by relevant sale plans or proposed arrangements for refinancing, where applicable.

Planning, building and technical documents

Depending on the project, supporting material may include council information, consent documents, architectural or engineering plans, building reports, contractor details and building contracts. For construction, show the costs and timing for siteworks separately from base construction where that distinction helps explain the budget. A staged funding schedule can also show how these items relate to the drawdown process, the release of funds as agreed milestones are completed.

Council requirements and available evidence can differ by project and current council processes. The NZ Government Building Process guide offers information about building a home, including consents and building stages. Documents relevant to a subdivision may differ from those for a single new build.

Check that figures and dates match across your plans, contractor quotes, reports and funding schedule. If a quote changes, update the budget and timeline, or clearly explain the difference. Consistent information gives the lender a clearer view of the proposal and makes questions easier to answer. For more plain-English guidance, explore Mortgage Suite’s Mortgage School lending guides.
NZ Property Development Loan Requirements 2026

How to prepare for lender questions about risk and repayment

Lenders may ask what could change during the project and how you’d respond. Clear answers won’t guarantee approval, but they can show how your budget, timeline and repayment plan fit together.

  • 1. Review your assumptions. Check that your budget reflects the planned work, including expected changes in scope. Note what each estimate is based on and which figures are still provisional.
  • 2. Test the timeline. Set out the main project stages and consider what a delay at each point could mean for later work, funding needs or a planned sale. Record key dates and dependencies rather than relying only on a best-case schedule.
  • 3. Organise your evidence. Keep plans, quotes, reports and funding schedules together, and make sure the figures and dates agree. If an assumption changes, update related documents or explain the difference.
  • 4. Explain repayment. Describe how you expect to repay or restructure the lending and how that plan connects with project progress. Be ready to explain what could affect the timing.

How to present a clear project budget and timeline

Show how the budget lines up with project milestones and when funds may be needed. For example, if site preparation comes before building work, show those stages separately where that helps explain the funding schedule. Flag important assumptions, such as the timing of work, and explain how a change could affect the budget or completion date.

A quantity surveyor report may be useful for some projects, particularly where a lender needs more detail to understand building costs. It isn’t a universal requirement. The aim is to give a consistent, realistic picture of the work, not to suggest that every uncertainty has been removed.

How to explain the repayment or exit plan

An exit plan is how you expect to repay the development loan or restructure the lending. Depending on the project, this could involve selling completed property or arranging a Refinance. Explain the steps behind your proposal, the timing you’re working towards and the evidence that supports it. A lender may consider whether the plan fits the project’s progress, rather than treating a proposed sale or refinance as certain.

If your assumptions or timeline change, update your repayment plan too. Mortgage Suite helps organise project information and present your proposal to lenders. For general borrowing context, you can use the mortgage calculator, but remember that a calculator can’t assess a development project or predict a lender’s decision.

Getting development finance sorted with a clear application plan

Development finance can feel like a lot to pull together, especially when the project is still taking shape. A clear application plan helps you explain what you’re building, what’s already in place and how you expect to repay the borrowing. Property development loan requirements nz vary, so focus on presenting your project accurately rather than trying to fit a one-size-fits-all checklist.

What to prepare before discussing your project

Start with a short summary that gives a lender the essentials. Include:

  • Project type and stage: Explain whether you’re buying land, starting a build or progressing a subdivision, and what has happened so far.
  • Ownership structure: Set out who owns or will own the property and who is involved in the borrowing.
  • Objectives: Describe what you plan to complete and your intended repayment approach.
  • Supporting information: Bring together available financial details, property records, council or planning information, project plans, budgets, quotes and timelines.

Some details may still be developing. Mark estimates clearly and note what could change, so the application doesn’t present an assumption as a confirmed figure. You can read about Mortgage Suite and its approach to helping borrowers with lending decisions.

How Mortgage Suite can help you consider lender options

Mortgage Suite helps organise your information, identify gaps and present your project so its stages and funding needs are easy to follow. We act as your personal advocate, working with you to explain the proposal and negotiate with lenders. This can include mainstream and alternative lending channels, depending on the project and lender fit. Each lender makes its own decision, so finance can’t be guaranteed.

A mainstream-bank decline can be disappointing, but it isn’t necessarily a final judgement on your project or the end of your funding options. Another lender may assess the proposal differently, while still looking closely at its risks and repayment plan. You can read client reviews to learn about other borrowers’ experiences.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to development finance discussions. If you’re preparing an application or reconsidering your options after a decline, Mortgage Suite can help you understand your project-specific funding needs and work out a sensible next step.

Take the next step with a clearer funding plan

Understanding property development loan requirements nz starts with seeing the whole picture. Lenders may assess your experience and financial position alongside the project plan, security and intended repayment. Clear supporting documents, consistent figures and a realistic timeline can help explain how the project fits together. Requirements vary between lenders and projects.

If a mainstream bank has declined your application, that doesn’t automatically mean the project has no funding options. Mortgage Suite helps organise development finance applications and consider mainstream and alternative lending pathways. Founder Krish Krishna brings more than two decades of banking experience to those discussions, with a focus on understanding your circumstances and presenting your project clearly. Approval can’t be guaranteed, but a thoughtful funding conversation can help you identify a practical next step.

Talk through your development finance options with Mortgage Suite. A clear plan can help you approach your next steps with greater confidence.

Frequently Asked Questions

What do lenders look for in a property development loan application in NZ?

Lenders usually assess your experience and financial position alongside the project plan, security and proposed repayment. They’ll want to understand who is managing the work, whether the budget and timeline make sense, what supports the lending and how you expect to repay it. The property development loan requirements nz applicants face vary by lender and project, so prepare clear information rather than relying on a universal checklist.

How much equity do I need for a property development loan?

There’s no single equity amount that applies to every development loan. The contribution a lender expects can depend on the project, its stage, the security available and the funding structure. A lender may consider how your contribution fits with the overall budget and project risks. Before committing to a plan, get guidance on which lender criteria may suit your circumstances.

Can I get a development loan if I have not completed a project before?

Possibly. Being new to development doesn’t automatically exclude you, but a lender may want to understand how the project will be delivered. Explain your role, the experience of others involved and how the work will be managed. A clear project plan, realistic timeline and well-organised supporting information can help a lender assess the application, though they can’t guarantee approval.

What documents do I need for a property development loan?

Documents may include identification and financial details, property and ownership information, project plans, a budget, timeline, contractor quotes and relevant council or planning information. You may also need to explain how you intend to repay the loan. The exact evidence varies by lender and project stage. Keep figures and dates consistent across your plans, reports, quotes and funding schedule.

Do I need council consent before applying for development finance?

Not necessarily in every case. The information a lender requests can depend on the project, its current stage and the relevant council process. You may be asked for council information, consent documents or an update on planning progress, but don’t assume every application follows the same sequence. Set out which approvals or information you have and what remains underway, so the project status is clear.

Can I get a property development loan after a bank declines my application?

Possibly. A decline from one bank doesn’t automatically mean your project has no funding options. The decision may reflect that lender’s criteria or how the application was presented. Reviewing the reasons, project details and available evidence can help clarify next steps. Mortgage Suite assists with development finance and alternative lending options, but each lender makes its own decision and approval isn’t guaranteed.

How are development loan funds released during a project?

Some development or construction finance uses a drawdown process, meaning funds are released in stages as agreed project milestones are completed. The lender’s terms explain how releases work and what evidence may be needed at each stage. The process can vary, so align your funding schedule with the work timeline and allow for the lender’s requirements when planning cash flow.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Freelancer Mortgage NZ: How to Get Your Home Loan Sorted in 2026

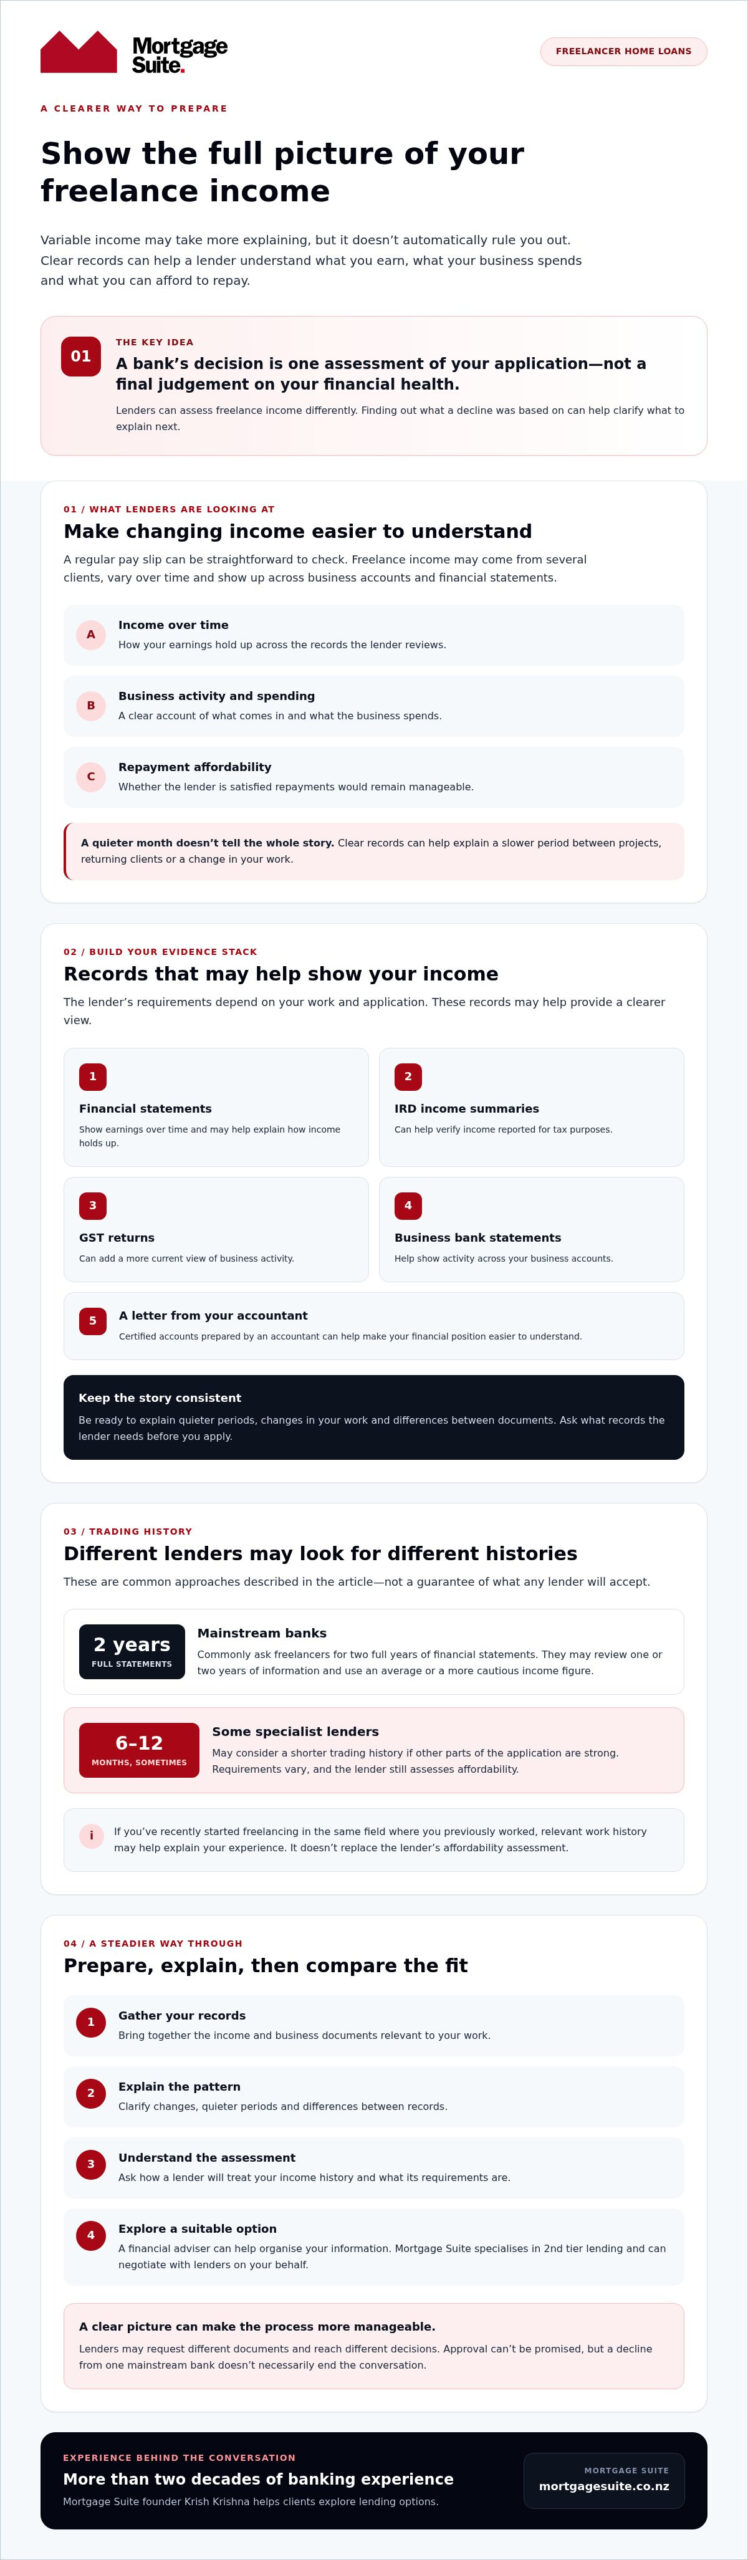
What if a mainstream bank’s “no” is only the start of your home loan conversation? If you’re wondering whether you can get a mortgage without a permanent 9-to-5 job, the answer may be yes. A freelancer mortgage nz application can take more explaining, but variable income doesn’t automatically rule you out.

It’s understandable to worry that lenders will judge your work status or that the paperwork will be difficult to pull together. If a bank has already declined your application, that can feel like a verdict. It isn’t necessarily one: lenders can assess freelance income differently, so first find out what the decline was based on.

This guide to the freelancer mortgage nz process explains how to prepare your income records, what lenders may look for and where specialist lending could fit. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping clients explore lending options. Approval can’t be promised, but you can get a clearer picture of what may suit your circumstances.

Key Takeaways

  • A freelancer mortgage nz application can be assessed using more than a standard pay slip. Learn which records may help show a clear picture of your income.
  • A lender’s view of risk doesn’t necessarily reflect your overall financial health. Find out how to explain your circumstances clearly.
  • A mainstream bank’s decline is one decision, not a final judgement. 2nd tier lending may be another option to explore.
  • Organising your paperwork before applying can make the process more manageable and help you identify what to do next.
  • Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping clients explore lending options.

Why Being Your Own Boss Can Make Banks Nervous

If you’ve ever felt like an outsider when asking a bank about a home loan, you’re not alone. A standard application makes salaried income easy to check: a regular pay slip shows what comes in and when. Freelance income can arrive from several clients, vary from month to month and appear across business accounts and financial statements. That takes more explanation, but it doesn’t mean your finances are unhealthy.

A lender is assessing whether you can manage repayments, not deciding whether freelancing is a good career choice. A mortgage loan is borrowing secured against a property, and the lender needs to understand your ability to repay it. A pay slip may be simpler to assess than an income pattern that changes over time. The difference between what a lender can quickly verify and your actual financial position is a question to clarify, not a verdict on your earning ability.

The Myth of the ‘Risky’ Freelancer

Freelance work isn’t automatically less secure than salaried work. You might earn as much as, or more than, someone on a salary, but lenders need evidence to support the income they use in their assessment. Mainstream banks commonly ask for two full years of financial statements and look at how your earnings hold up over time. The focus is your demonstrated earning power, not simply your employment type.

Fluctuating Income and the Bank Safety Margin

A safety margin is room in the lender’s assessment for repayments to remain manageable if income dips or expenses rise. It isn’t a single set amount that applies to every lender. Banks may review one or two years of financial information and use an average or a more cautious income figure, depending on their approach. A quiet month on its own doesn’t tell the whole story.

For example, you may have a slower period between projects followed by steady work from returning clients. Clear records can help show that pattern and distinguish a temporary lull from a longer-term drop in income. Lenders still need to be satisfied that repayments are affordable, but their assessment methods differ. Ask how a lender will treat your income history rather than assuming every lender will assess it the same way.

That’s why a freelancer mortgage nz application is best built around clear evidence of your income and commitments. Your work status is one part of your circumstances, not a flaw. A clear explanation can help a lender assess your actual financial position.

Proving Your Income Without a Standard Pay Slip

A contractor home loan is a mortgage application where the lender assesses income earned through contracting or freelance work rather than relying on a regular employee pay slip. The aim is to show a clear picture of what you earn, what your business spends and what you can afford to repay.

Start by gathering records that support a consistent account of your income and business activity. Depending on your work and the lender’s requirements, these could include financial statements, IRD income summaries, GST returns, business bank statements and a letter from your accountant. Be ready to explain quieter periods, changes in your work and differences between documents. Clear explanations can help prevent confusion later.

In the freelancer mortgage nz process, a financial adviser can help organise your information and present it in a way a lender can assess. Lenders may request different documents and reach different decisions. Being prepared means you can explain your income and circumstances more clearly.

The Role of IRD Records and GST Returns

IRD income summaries can help verify income reported for tax purposes. They aren’t pay slips, but they may form part of the official record a lender considers alongside your other documents. GST returns can add a more current view of business activity, while certified accounts prepared by an accountant can help make your financial position easier to understand. Ask what records the lender needs before you apply.

What if You Have Only Been Trading for One Year?

Mainstream banks commonly ask freelancers for two full years of financial statements. Some specialist lenders may consider a shorter trading history, sometimes around six to 12 months, if other parts of the application are strong. Requirements vary, so one year in business doesn’t automatically rule you out.

If you’ve recently started freelancing in the same field where you previously worked, include evidence of that experience and any relevant work history. It may help explain how your skills and client base support the business, but it won’t replace a lender’s assessment of affordability. Mortgage Suite specialises in 2nd tier lending for people who don’t fit mainstream criteria and can negotiate with lenders on your behalf. A suitable option depends on your full application, and approval isn’t guaranteed.

To understand how Mortgage Suite supports borrowers, see its team and approach.

Mainstream Banks vs 2nd Tier Lenders: Finding Your Best Fit

A “no” from a mainstream bank can feel personal, especially after you’ve gathered paperwork and explained how you earn. But it’s one lender’s decision using its own criteria, not a final judgement on you or your finances. Another lender may assess your income, work history and property equity differently. First, ask what drove the decline. Then consider whether clearer evidence or a different lending approach could suit your situation.

2nd tier lenders are an alternative for borrowers who don’t fit mainstream criteria. They’re not a shortcut around affordability checks, and approval is never guaranteed. They may, however, take a different view of a freelancer’s overall application. Mortgage Suite specialises in 2nd tier lending and can negotiate with lenders on your behalf. For more detail, read this guide to 2nd tier lender New Zealand options.

When the Local Branch Says No

A lender’s assessment process may not capture every detail of your work, income pattern or experience, particularly if your situation doesn’t fit standard categories. A decline can sting, but it doesn’t mean you’ve run out of options. Ask which parts of the application raised concern. That information can help you decide whether to provide clearer evidence, approach a different lender or review the loan structure.

The Flexibility of Non-Bank Home Loans

Some non-bank lenders may consider an equity safety net: the value you hold in a property after accounting for the borrowing secured against it. They may also assess applications differently, but lending criteria and available terms vary. Ask how repayments would fit your freelance cash flow, what conditions apply and whether the arrangement supports your longer-term plans.

It’s tempting to compare loans by the headline interest rate alone. For a freelancer, the fit also depends on how income is assessed, how repayments are structured and whether the arrangement leaves room for quieter periods. A loan that looks appealing at first glance may not suit your cash flow or future goals. Compare the full structure and ask questions before deciding.

For some borrowers, a 2nd tier loan may be a step towards buying sooner, with a possible plan to refinance to a mainstream lender later. That depends on your circumstances at the time, your repayment record and the criteria of the lender you approach. Treat refinancing as a goal to review, not a promise. In a freelancer mortgage nz application, the best-fit lender is one whose assessment and loan structure make sense for your situation and plans.

Freelancer Mortgage NZ: How to Get Your Home Loan Sorted in 2026

Your Step-by-Step Guide to a Successful Freelancer Application

A home loan application is easier to manage when you know what to do first. Get your records in order, check how repayments could fit your budget, then present your income and plans clearly to a lender. Preparation can reduce last-minute stress, and a well-organised application helps a lender understand the story behind the figures.

Here’s a practical place to start:

  • Separate business and personal spending. Make it easy to see which costs relate to your work and which are household expenses. If accounts have been mixed, add clear notes rather than leaving transactions unexplained.
  • Gather your financial statements. Have your latest statements ready, and aim to include the last two years if available. Lenders’ requirements vary, so ask what they need for your circumstances.
  • Review smaller debts. List balances and regular repayments. Paying down a debt may help your overall picture, but consider your cash reserves and speak with an adviser before making changes to your finances.

For a freelancer mortgage nz application, don’t just send documents without context. Explain changes in income, gaps between projects and unusual business expenses. That context can help a lender make sense of the figures.

Run a Serviceability Stress Test

A serviceability stress test is a lender’s way of checking whether you could still manage repayments if they assessed your borrowing using a higher interest rate than the one offered. It tests future affordability, not what rates will do.

You can try a similar check on your own budget. Use the mortgage calculator to explore repayment scenarios, then consider what would happen if your income dipped or household costs rose. Leave room for quieter trading periods, regular bills and business expenses. The calculator can help you explore possibilities, but it won’t confirm what a lender will approve.

Once you’ve prepared your records and tested your budget, you’ll be in a better position to discuss your options and identify any gaps before applying. Mortgage Suite can help present your circumstances to lenders and negotiate on your behalf. Talk with Mortgage Suite about your home loan options.

How Mortgage Suite Advocates for NZ Freelancers

Applying for a home loan as a freelancer can feel like you’re expected to fit your finances into a box designed for salaried workers. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to understanding clients’ circumstances and negotiating with lenders on their behalf.

That experience can help make sense of what a lender needs to see, where your application may need more explanation and which lending options could be worth exploring. It isn’t a promise of approval. Mortgage Suite can help you present your case clearly and explore possible options. Lenders make their own decisions, but a clear application gives them a better account of your circumstances.

You can learn more about Krish and the team on the About Us page.

Why a Negotiator Beats a Computer Algorithm

Your figures matter, but so does the context behind them. A negotiator can explain how your work history, client income and business records fit together, rather than leaving a lender to interpret unfamiliar details on their own. They can also discuss the loan structure, repayment fit and safety margin, not just the headline rate. Lenders still make their own decisions, but clear communication can help them understand your circumstances.

Getting Your Application Across the Line

Freelance work keeps you busy. Support with organising documents and responding to lender questions can make the application feel more manageable while you stay focused on your work. The steps and time involved depend on your circumstances and the lender, so ask what support you can expect throughout the process.

If you’re ready to explore a freelancer mortgage nz application, start by talking through your income, goals and any previous lender feedback. Mortgage Suite specialises in 2nd tier lending for people who don’t fit mainstream criteria and can negotiate with lenders to explore possible options. Approval isn’t guaranteed, but a bank decline doesn’t have to be the end of the conversation.

Talk with Mortgage Suite about getting your home loan sorted.

Take the Next Step Towards Your Home

Your freelance income doesn’t have to follow a standard pay-slip pattern for you to explore a home loan. Clear financial records can help lenders understand your earning history, and a decline from one bank doesn’t automatically close the door to other options. The right lender and loan structure depend on your circumstances, so focus on getting an assessment that accounts for your plans.

For a freelancer mortgage nz application, help explaining the story behind your figures can make the process more manageable. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience, and the company specialises in 2nd tier lending for people who don’t fit mainstream criteria. No one can promise approval, but you can get a clearer view of your options with help negotiating with lenders.

Ready to take the next step? Talk with Mortgage Suite about your freelancer home loan options.

Frequently Asked Questions

Can I get a mortgage if I have only been freelancing for a year?

Possibly. Some specialist lenders may consider a shorter trading history when other parts of your application are strong. Mainstream banks commonly ask for two full years of financial statements, while some non-bank lenders may consider around six to 12 months of records. Previous experience in the same industry, a clear income trail and your overall ability to manage repayments may help explain your position. Each lender assesses applications differently, and approval isn’t guaranteed.

Do I need a bigger deposit as a freelancer in New Zealand?

Not automatically. The deposit a lender requires depends on its criteria, the property and your overall application, including how it assesses your freelance income. Reserve Bank Loan-to-Value restrictions also affect how much some banks can lend against a property, but they don’t guarantee that a particular borrower will be approved with a smaller deposit. Ask lenders what deposit they require and whether your income evidence and property choice affect their decision.

What is a serviceability stress test and how does it affect me?

A serviceability stress test checks whether you could manage repayments if a lender assessed your application using a higher interest rate than the one offered. It helps the lender consider whether repayments could remain affordable if conditions change. As a freelancer, you can also test your budget by allowing for quieter work periods and household expenses. A mortgage calculator can help you explore repayment scenarios, but it doesn’t confirm how much a lender will approve.

Why did my mainstream bank decline my home loan application?

A decline can happen for several reasons, and it isn’t necessarily a final judgement on your financial health. The bank may have wanted a longer record of freelance income, assessed your earnings cautiously, or found that your expenses, debts, deposit or chosen property didn’t fit its criteria. Ask for the reason behind the decision. That can help you identify what to clarify or whether another lender may assess your circumstances differently.

What documents do I need to prove my income to a lender?

Lenders may ask for financial statements, IRD income summaries, GST returns, business bank statements and information from your accountant. The exact list depends on the lender and your work setup. These records help show your reported income and how your business is trading. Keep business and personal transactions clear, and explain gaps or unusual changes so the lender can understand the figures rather than guess what they mean.

Is a 2nd tier lender safe for a freelancer mortgage?

A 2nd tier lender can be an alternative for borrowers who don’t fit mainstream bank criteria, but check the full loan terms before deciding. Ask about repayments, fees, conditions, the loan structure and whether it suits your plans. Mortgage Suite specialises in 2nd tier lending. A lender’s suitability depends on your circumstances, and no lender can promise approval.

Can I still get a mortgage if my income fluctuates significantly?

Possibly. Lenders may review income over time and use an average or a more cautious figure to allow for changes in earnings. Clear records can help show whether quieter months are a normal gap between projects or part of a longer-term change. Include your business expenses and existing repayments in your budget, too. The freelancer mortgage nz options available to you depend on the lender’s assessment of your income and ability to repay.

What is the “Small Apartment Rule” and does it apply to me?

The Small Apartment Rule describes lender criteria that may treat apartments below a specified floor area as higher-risk security. There isn’t one standard size requirement across all lenders, so criteria may differ depending on the lender and the property. If you’re considering an apartment, ask how its size and features affect the deposit and lending criteria before making an offer. A lender’s assessment of the property is separate from its assessment of your income.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.