
Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

A maternity-leave mortgage application isn’t decided by your current payslip alone. If you’re wondering whether getting a mortgage while on maternity leave nz is possible, the answer depends on how a lender assesses your income now, your return-to-work plans and your household’s ability to manage repayments.

Time away from work doesn’t automatically rule you out, but approval isn’t guaranteed. Lenders can assess applications differently, so it helps to give them a clear picture of your finances and plans. This guide explains what may affect an assessment and how to prepare useful information.

You’ll learn how lenders may view parental leave payments, your expected return date and a temporary drop in household income. We’ll also cover documents that may help, such as an employer letter confirming your role, salary and expected return date, and ways to explain how repayments will fit your budget. Mortgage Suite can help you understand and compare mainstream and alternative lending options, so you can consider a sensible next step without assuming every lender will reach the same decision.

Key Takeaways

  • Getting a mortgage while on maternity leave nz may be possible, but a lender will assess your circumstances and ability to manage repayments.
  • Ask how the lender will consider your current income, planned return to work and household commitments.
  • Prepare employment and income evidence, such as confirmation of your role, salary and expected return date. Check which documents the lender needs.
  • Compare how mainstream and alternative lenders assess your situation rather than assuming every lender will take the same view.
  • A mortgage adviser can help you understand your options and explain your circumstances to lenders, but can’t guarantee approval.

Can you get a mortgage while on maternity leave in NZ?

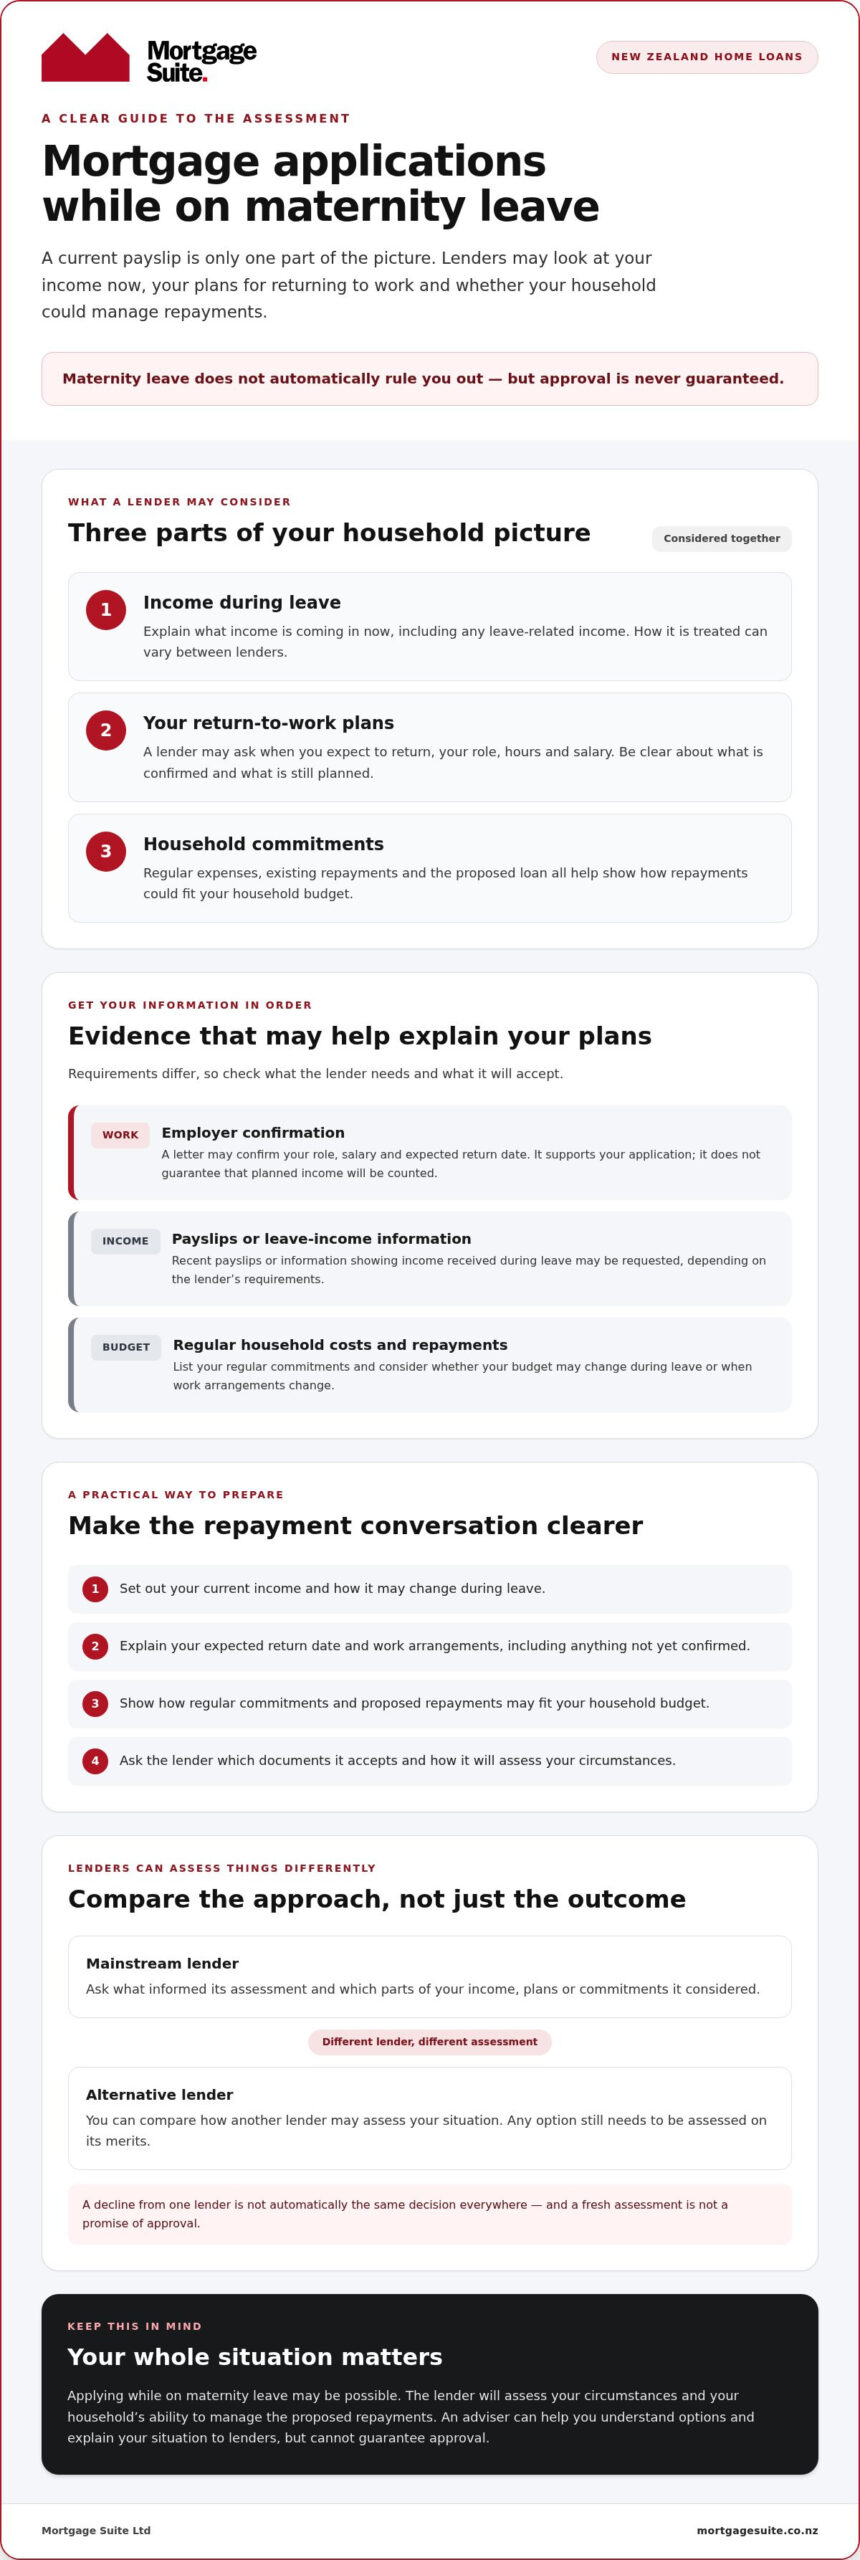
Yes, applying for a home loan while you’re on maternity leave may be possible. Being on leave doesn’t automatically mean you’ll be approved, and it doesn’t automatically rule you out. A lender needs to assess whether your household could manage the proposed repayments while your income is reduced and under your expected work arrangements after leave.

Getting a mortgage while on maternity leave nz depends on your full situation, not just the fact that you’re away from work. Lenders may consider your income, employment plans, regular household commitments and the amount you want to borrow. Requirements differ, so check what a lender currently accepts rather than relying on a friend’s experience or an old online example.

Does maternity leave automatically stop a mortgage application?

No single outcome applies to every borrower. Maternity leave is a temporary change in your work and income, but the lender will still assess the whole financial picture. Your return-to-work plans, another applicant’s income and your household commitments may all be relevant. These details help explain how your household expects to manage repayments, but none guarantees approval.

Parental leave sits within New Zealand’s employment framework. You can read more about the Parental Leave and Employment Protection Act 1987, but a lender’s mortgage assessment is separate from your employment rights.

What will a lender want to understand about your situation?

Expect to discuss your current income and how it may change during leave. A lender may ask whether your employer has confirmed your expected return date, role and salary. If your arrangements aren’t final, be upfront about that and ask what information could clarify your position.

The lender will also consider your household’s regular commitments and the proposed loan. Be ready to explain how repayments would fit your budget during leave and after you return to work. Ask which documents the lender accepts to confirm income and employment plans. Don’t assume every lender requires the same evidence or will reach the same view.

If a mainstream bank declines your application, ask what informed its decision and whether another lender may assess your circumstances differently. An alternative option would still need to be assessed on its merits, so treat the next step as a fresh conversation, not a promise of approval.

How lenders may assess income and affordability during maternity leave

A lender’s central question is whether your household appears able to manage the proposed repayments. It may discuss the income coming in now, how that could change during leave, your expected work arrangements afterwards and other regular household income. How leave-related income is treated can vary. Ask the lender how it would assess your circumstances rather than assuming your usual salary will be counted in full.

New Zealand’s Parental leave entitlements information explains the leave framework and points to payment details. It can help you understand your own situation, but it doesn’t determine how a lender will assess your mortgage application. If you’re getting a mortgage while on maternity leave nz, make clear which income is confirmed and which arrangements are planned.

How a return-to-work plan can help explain your application

If your return arrangements are confirmed, note your expected return date and whether you’ll be returning to the same role or working different hours. An employer letter may help explain your role, hours and pay. It’s supporting information, not a guarantee that the lender will count your planned income when assessing affordability. Ask what form of confirmation it accepts and whether it needs anything else.

How household commitments can affect the assessment

Income is only part of the picture. List your regular household expenses and existing repayments, then consider how the budget may change if childcare or work arrangements affect your spending or income. This gives you and the lender a practical basis for discussing whether repayments look manageable while your income is different.

You can use the Mortgage Suite mortgage calculator to explore possible repayments as part of your planning. Treat the result as an estimate, not a lender decision or a promise of approval.

Examples of evidence a lender may ask for, depending on its requirements:

  • Recent payslips or information showing income received during leave.
  • An employer letter confirming your expected return date, role, hours or pay, if available.
  • Details of other regular household income, existing repayments and ongoing expenses.

This is a starting point, not a universal checklist. Before gathering documents, ask your chosen lender or adviser which evidence it accepts and how it will consider your income and commitments. A clear explanation can help you compare options and decide what to do next.

Mainstream or alternative lender: what should you compare?

A lender’s approach can affect how your maternity-leave income and work plans are considered. Instead of looking only for an immediate yes, compare what each lender needs to understand, how it assesses your household budget and whether the proposed loan could suit your plans beyond the leave period. Criteria can change, so ask for current requirements rather than treating another borrower’s experience as a guide to your own application.

Use these questions to compare options. They don’t describe a guaranteed policy for any lender:

What to compare What to ask
Confirmed income Which income documents do you need, and how will you assess income during leave?
Return-to-work plans What evidence of my expected return date, role, hours or pay can you consider?
Household commitments How will you assess regular expenses, existing repayments and expected changes to our budget?
Loan fit What repayment choices or loan structure should we consider for our longer-term household plans?

Questions to ask before choosing a lender

Ask each lender for a clear list of the income and employment details it needs. Check how it treats a planned return to work and changing household expenses. Discuss whether the proposed repayments and loan structure fit your plans after you return. This helps you compare the overall suitability of an option, not just whether an application might proceed now.

When an alternative lending conversation may be useful

If a mainstream lender declines your application, that doesn’t mean every option is closed. Mortgage Suite can help you explore mainstream and alternative lending channels, including 2nd-tier lending, where suitable. Each option still depends on an assessment of your circumstances, and terms and suitability can differ. If you’re getting a mortgage while on maternity leave nz, ask what a lender’s decision was based on before choosing your next step.

Alternative lending isn’t automatically a better fit. Compare how the lender will assess your confirmed income, return-to-work evidence and household commitments. Make sure you understand the proposed repayments and structure. A lending adviser can help you organise your questions and explain your circumstances, without promising approval. The aim is to make a considered choice that fits your situation.
Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

How to prepare a mortgage application while on maternity leave

Preparation can make an initial lending conversation clearer and help you identify missing information early. Start by mapping your household finances, confirming what you know about your employment and return-to-work plans, and gathering available evidence. Then ask which lending options may suit your circumstances. If you’re getting a mortgage while on maternity leave nz, explain changes to your income or work arrangements openly and consistently.

A practical document checklist to start with

Pull together what you already have. This is a starting point, not a list every lender will require. Check the exact document list with your chosen lender or adviser before relying on any particular item.

  • Recent payslips or other available records showing your income during leave.
  • Employment details, such as your role and any confirmed changes to your hours or working arrangements.
  • Written confirmation of your expected return date and pay, if your employer has provided it.
  • Details of regular household expenses, existing repayments and other income.
  • Information about your current leave arrangements and any expected changes to your household budget.

If something hasn’t been confirmed, say so. Clear, consistent information helps the person reviewing your application understand what’s known and what’s still being planned.

How to make the first conversation more useful

Before speaking with a lender or adviser, note your property goal, preferred timing and questions about how your income during leave and return-to-work plans may be assessed. Include relevant changes to your household finances, such as a shift in work hours or expected childcare arrangements. You don’t need every answer ready. Being clear about what’s confirmed and what’s uncertain gives the conversation a useful starting point.

Review possible repayments against your household budget. Consider whether they look manageable with your current income and how your budget might change when work arrangements shift. An estimate can support your planning, but it isn’t a lending decision. Ask how a proposed loan might fit your longer-term plans if you’re unsure.

For plain-English help with lending basics, explore Mortgage Suite’s Mortgage School. When you’re ready to discuss your circumstances, talk with Mortgage Suite about your home loan. A lending professional can help you organise information and discuss possible options, but approval depends on the lender’s assessment.

Getting support with a maternity-leave mortgage application

You don’t have to work through every lending question on your own. Gather the evidence you have, note what’s confirmed about your return to work and ask lenders how they would assess your circumstances. If getting a mortgage while on maternity leave nz feels like a lot to manage, a mortgage adviser can help organise your questions and compare possible options.

An adviser can help explain your situation to lenders and clarify what further information may be useful. Mortgage Suite can present your circumstances and discuss possible options with lenders, including whether mainstream or alternative lending channels may be worth exploring. Any recommendation depends on a careful review of your circumstances, and no particular lending decision is assured.

What a mortgage adviser can help you work through

Start by discussing the parts of your application that may need context. Your current income may differ from your expected income after returning to work, or your return date may still be unconfirmed. An adviser can help identify what needs explaining, ask what supporting evidence a lender may accept and communicate the details clearly. They can also help compare potential lender fit, while making clear that each lender makes its own assessment.

Mortgage Suite supports borrowers through mainstream and alternative lending channels. Founder Krish Krishna established the business in 2000 and brings more than two decades of banking experience. That background can inform a practical conversation about your circumstances, but it can’t assure a particular lending decision.

Choose your next step with confidence

Before getting in touch, you may want to read about Mortgage Suite’s background and browse client reviews to learn about other borrowers’ experiences. Reviews are individual accounts, not a promise that your application will have the same outcome.

Bring the information you have and ask direct questions: what needs more evidence, how could your return-to-work plans be considered, and which lender options may suit your household? Take time to understand the answers and decide what feels sensible. A mainstream lender’s decline isn’t necessarily the end of your options, but any next route still needs to suit your circumstances and pass the lender’s assessment.

If you’d like to discuss your situation and explore possible next steps, talk through your home-loan options. You don’t need every detail sorted before starting the conversation.

Take a clear next step with your home-loan plans

Getting a mortgage while on maternity leave nz may be possible, but each lender will assess your circumstances. A clear picture of your current income, confirmed work plans and household commitments can help you explain your application and ask useful questions. Requirements differ between lenders, and approval is never guaranteed.

Gather the evidence you have, check what a lender needs and compare options that could suit your household now and longer term. A decline from one lender doesn’t necessarily mean every option is closed. Mortgage Suite Ltd has supported borrowers since 2000, and founder Krish Krishna brings more than two decades of banking experience. The team can discuss mainstream and alternative lending channels, subject to an assessment of your situation.

If you’d like to discuss your next step, talk through your home-loan options. Bring your questions and the information you have, and Mortgage Suite can help you explore possible lending options.

Frequently Asked Questions

Can I get a mortgage while on maternity leave in NZ?

It may be possible, but there’s no answer that applies to every borrower. For getting a mortgage while on maternity leave nz, lenders assess your income, employment, household commitments and proposed loan using their own criteria. Explain your leave arrangements and any confirmed return-to-work plans, then ask what evidence the lender needs. A mortgage adviser can help you understand which mainstream or alternative options may be worth exploring, subject to assessment.

Will a lender count my income while I am on maternity leave?

How a lender treats income during leave can vary, so don’t assume it will count your income in a particular way. Ask how it assesses your current income and any expected change when you return to work. You may need to provide employment details or confirmation of your work arrangements. Check the lender’s current requirements before applying, as policies and accepted evidence can differ.

What documents might I need for a mortgage application during maternity leave?

The documents requested depend on the lender and your circumstances. You may be asked for information about your income, employment, leave arrangements, regular household commitments and any confirmed return-to-work plan. Treat a checklist as a starting point, not a guaranteed list of requirements. Contact the lender or adviser early to confirm exactly what they need, including whether documents must be recent or supplied in a particular format.

Can I apply for a mortgage before I return to work?

You can ask a lender or adviser about applying before your planned return, but the timing and evidence needed depend on your circumstances and the lender’s criteria. Explain your current leave, employment status and any confirmed work arrangements. The lender may also want to understand how your household commitments fit alongside the proposed repayments. Ask what information could support an assessment now rather than assuming how planned income will be treated.

Does maternity leave affect mortgage pre-approval in New Zealand?

It can affect the information a lender asks for, but it doesn’t automatically decide the outcome. Pre-approval is based on the lender’s assessment at that time and may include conditions. Be upfront about your leave arrangements, income and expected work changes, and check what evidence is needed. If your circumstances change after pre-approval, contact the lender to ask whether it needs to review your application before you rely on it.

What if my bank declines my mortgage application while I am on maternity leave?

A decline from one lender isn’t necessarily a final judgement on your borrowing prospects. Ask for a clear explanation and whether further information could help. Lenders assess applications differently, but another option isn’t guaranteed. A mortgage adviser can help you understand the issues, compare possible mainstream and alternative lending channels, and decide whether to provide more evidence or make changes before approaching another lender. Any option remains subject to assessment.

Should I wait until I return to work before applying for a mortgage?

There’s no single best time for every borrower. Applying before you return may suit some circumstances, while waiting could give you clearer income evidence. Consider your property plans, household budget and the documents available now. Ask a lender or adviser how each timing option may be assessed before deciding. Don’t treat planned income as guaranteed, and check whether changes to your circumstances or work arrangements could affect the information the lender needs.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Can I Get a Home Loan with a Default in NZ? Your 2026 Guide to Saying Yes

What if your credit default was just a minor speed bump instead of a brick wall? If you’ve been asking yourself, “can i get a home loan with a default nz,” the answer is a resounding yes. It’s completely natural to feel judged by mainstream banks or stressed about interest rates, especially with the OCR now at 2.50% and house prices sitting about 18% lower than their previous peak. You might feel like a past financial mistake is holding you back, but a default is just one chapter of your story, not the whole book.

We agree that life happens, and a missed utility bill from years ago shouldn’t stop you from owning a home today. In this 2026 guide, you’ll discover how to find lenders who look at the reason behind your credit score and value your current financial stability. We’ll provide a clear roadmap to approval and explain how professional advocacy can help you secure a loan, even when the big banks say no.

Key Takeaways

  • Understand why a credit default stays on your New Zealand record for five years and why mainstream banks often use automated systems to decline these applications.
  • Discover how to answer the question “can i get a home loan with a default nz” by looking beyond big banks to 2nd tier lenders who specialise in unique situations.
  • Learn the essential steps to prepare your file, including how to organise your bank accounts to show perfect conduct for at least three months before you apply.
  • Find out how working with a seasoned professional can help you navigate the non-bank market and find a lender who values your current stability over past mistakes.

What Does Having a Default Actually Mean for Your Home Loan?

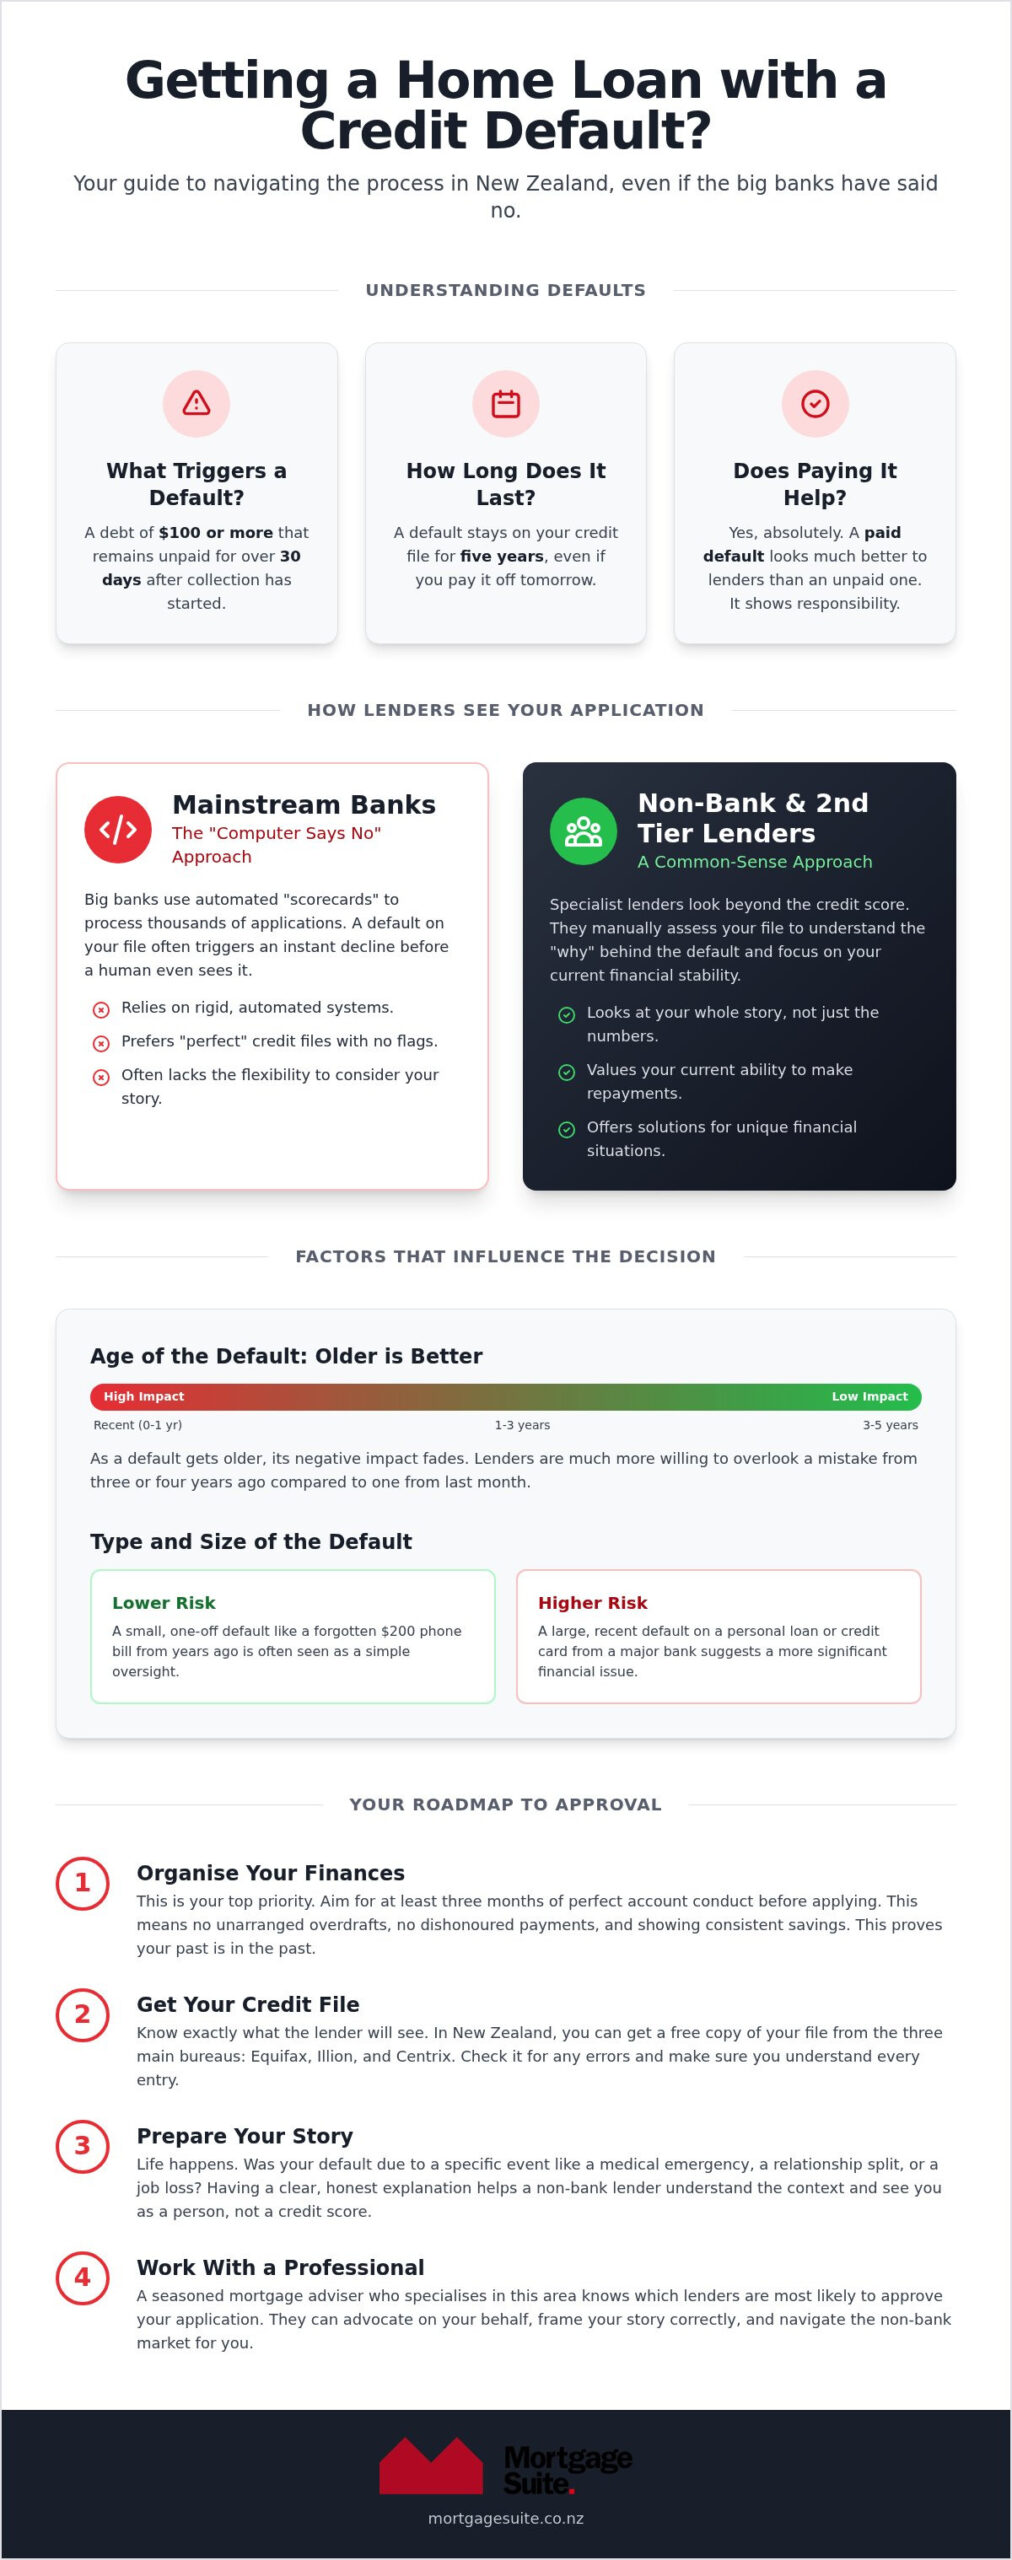
A default isn’t just a missed payment; it’s a formal flag on your credit file. In New Zealand, this happens when a debt of at least $100 remains unpaid for more than 30 days and the provider has started a collection process. Once that mark is on your record, it stays there for five years. This remains true even if you settle the debt the very next day, though a paid default looks much better to a lender than an unpaid one.

When you’re wondering, “can i get a home loan with a default nz,” it helps to see things from the lender’s perspective. To a mainstream bank, a default is often viewed as a red flag regarding your reliability. They use it as a shortcut to judge whether you’ll keep up with mortgage repayments. An unpaid default suggests a debt is still outstanding and creates an immediate barrier, while a paid default proves you’ve taken responsibility for your past obligations, making you a much more viable candidate for a loan.

How NZ Credit Bureaus Score Your History

New Zealand’s financial landscape relies on three main bureaus: Equifax, Illion, and Centrix. These agencies collect data from various sources to help lenders understand what a credit score is and how it reflects your individual financial habits. Most lenders now use comprehensive credit reporting. This is actually good news for you, as it means your file shows your positive habits, like on-time utility payments, alongside any past defaults.

While your numerical score is a quick reference point, it’s rarely the final word in the non-bank sector. We find that the story behind the entries is far more important than the score itself. If your default was caused by a specific life event, such as a medical emergency or a relationship breakdown, rather than a long-term pattern of overspending, we can use that context to advocate for your application.

The Impact of Default Age and Type

Lenders don’t treat every default the same way. There is a significant difference between a small, forgotten internet bill and a large default on a previous credit card or personal loan. A $200 telco default from four years ago is often viewed as a simple oversight. However, a $5,000 default from a major bank just twelve months ago suggests a more serious level of financial risk that requires a specialist approach.

The age of the default is a massive factor in your favour. As a default gets older, its negative impact on your ability to secure a home loan starts to fade. A lender is much more likely to say yes to someone with a three or four-year-old paid default than someone with a fresh mark from last month. We specialise in identifying which 2nd tier lenders are most comfortable with your specific history, ensuring we present your case to the right people at the right time.

Why Mainstream NZ Banks Say No (And Why It’s Not the End)

Mainstream institutions like ANZ, ASB, and Westpac process thousands of applications every month. To keep up with this volume, they rely on automated “scorecards” to filter out anyone who doesn’t meet their perfect profile. If you’ve been searching for an answer to “can i get a home loan with a default nz,” you’ve likely discovered that these systems aren’t built for nuance. When a default shows up on your record, the bank’s software often triggers an automatic decline. This “low-touch” approach is efficient for the bank, but it means a human lender may never hear the context behind your past financial situation.

These major banks are currently facing tighter internal risk appetites. With the FMA recently taking over CCCFA oversight in July 2026, many institutions have become even more cautious. They prefer “clean” credit files that don’t require manual investigation or extra paperwork. It’s a common worry to think “can i get a home loan with a default nz” after a big bank turns you down, but it’s helpful to remember that their “no” is often just a “no for now.” It simply means your application doesn’t fit their current, narrow set of rules.

The Automated Decline vs. Manual Assessment

The biggest hurdle at a main bank is that their computers often filter out your application before a person ever looks at it. In years past, you could sit down with a local manager who understood your history. Today, the New Zealand banking culture has moved toward a much more rigid, policy-driven style of lending. If the computer sees a “red flag” like a default, the process usually stops. This “computer says no” situation is incredibly frustrating, especially if you now have a stable job and a solid deposit.

Meeting the Standard Bank Criteria

Learning how to qualify for a home loan NZ involves looking at more than just your yearly income. Mainstream banks want to see perfect account conduct, particularly in the six months before you apply. Even if you’re earning a great salary, a recent default can be a total deal-breaker for them. They want to see that you’re managing every cent with care. Before you start the process, you should Check your own credit record for free to make sure there aren’t any surprises waiting for you.

When the big banks won’t look past the automated scorecards, it’s time to find a dedicated advocate who can present your case to lenders who actually value a manual assessment.

Exploring 2nd Tier and Non-Bank Lending Options

If the big banks have turned you away because of an automated scorecard, don’t lose heart. There is a whole layer of the New Zealand mortgage market specifically designed for your situation. These institutions are known as 2nd tier lenders. While they don’t hold a full banking licence like the big four, they have significant capital and specialise in what we call “non-conforming” loans. These are simply mortgages that don’t fit into the standard, rigid boxes that mainstream banks prefer. If you’ve been asking yourself, “can i get a home loan with a default nz,” these lenders are often the most likely path to a yes.

The biggest difference you’ll notice is the human element. Instead of a computer algorithm making the final call, 2nd tier lenders use manual underwriting. This means a real person actually reviews your application, looks at your current income, and listens to the story behind your past credit issues. Because these lenders take on files that mainstream banks consider higher risk, their interest rates are typically higher than standard bank rates to reflect that increased risk level. However, for many Kiwis, this is a fair trade-off to get onto the property ladder.

The Benefits of Non-Bank Lenders

Non-bank lenders offer a level of flexibility you simply won’t find at a traditional branch. In some cases, they can be more lenient with deposit requirements or offer “Alt-Doc” options for self-employed people who might not have two years of perfect tax returns ready to go. We often view these lenders as a helpful bridge. The goal isn’t necessarily to stay with them for thirty years. Instead, we focus on an “exit strategy” where you build a solid repayment history for two or three years before we help you move back to a mainstream bank at a lower rate.

What to Expect with a 2nd Tier Loan

It’s important to go into this process with your eyes open. You can find more detail in our 2nd tier lender New Zealand guide, but the main thing to understand is risk-based pricing. This means your specific interest rate is determined by the “weight” of your credit file. For example, in mid-2026, specialist rates from providers like Avanti Finance or Pepper Money might range anywhere from 6.35% to over 11% depending on the age and size of your default. You should also be prepared for establishment fees, which are often higher than the standard fees charged by the big banks. We’ll always talk you through these costs upfront so there are no surprises on settlement day.

When you’re wondering “can i get a home loan with a default nz,” the answer usually lies in finding the right 2nd tier partner who sees your potential rather than just your past.

Can I Get a Home Loan with a Default in NZ? Your 2026 Guide to Saying Yes

How to Organise Your Finances for a Successful Application

When you’re asking “can i get a home loan with a default nz,” the answer depends heavily on the preparation you do before we even approach a lender. Think of this as your “pre-flight” checklist. While a default is a hurdle, your recent behaviour is what proves you are a safe bet for a mortgage. Non-bank lenders are looking for a clear shift in how you manage your money, and there are four specific steps you should take to get your file in top shape.

  • Clear the debt: If you haven’t already, pay off the default. Once it’s settled, ask the provider for a “Letter of Release.” This is a formal document proving the debt is gone, which is much more powerful than simply having a “paid” status on your credit report.
  • Show perfect conduct: Lenders will look at your bank statements for the last three to six months. They want to see zero unarranged overdrives, zero missed payments, and no “dishonoured” fees. Every cent needs to be accounted for.
  • Aim for a 20% deposit: While some lenders might look at smaller deposits, 20% is often the “magic number” for people with defaults. It lowers the lender’s risk and can help you secure a much better interest rate.
  • Write your story: Prepare a Letter of Explanation. This is your chance to show the person behind the paperwork and explain exactly what happened when that default occurred.

If you want to get your application ready for a lender, we can guide you through every step of this checklist to ensure you’re presenting the best possible version of your financial self.

Writing the Letter of Explanation

Lenders in the 2nd tier space aren’t robots; they want to understand the “why.” If your default was caused by a specific life event like a redundancy, a serious illness, or a relationship split, be honest about it. Keep your explanation concise and professional. Avoid “sob stories” and stick to the facts. The most important part of this letter is showing what has changed in your life to ensure that those past mistakes won’t happen again. You want to demonstrate that you’re now in a position of stability and control.

Cleaning Up Your Credit File

Before you apply, you should request a copy of your credit report from Centrix, Equifax, and Illion. Check for any errors or small debts you might have forgotten about. It’s vital to pay all your current bills on time, including your power, phone, and even your Netflix subscription. These small “on-time” markers build a positive history. Also, avoid applying for any new credit in the lead-up to your mortgage. Applying for things like car loans or “buy now, pay later” services like Afterpay can make you look desperate for credit, which is the last thing you want when trying to answer “can i get a home loan with a default nz.”

Partnering with Mortgage Suite Ltd to Navigate the Process

Being turned down by a bank is a setback, but it certainly isn’t a dead end. When you are still trying to figure out “can i get a home loan with a default nz,” the most effective strategy is to have an expert who understands the 2nd tier landscape inside out. This is where the value of a seasoned mentor becomes clear. Krish Krishna brings over 20 years of banking and brokerage experience to your side. He doesn’t just pass on your paperwork; he “translates” your financial history into a language that lenders understand, highlighting your current strengths while providing the necessary context for past defaults.

Working with Mortgage Suite Ltd means moving away from a transactional mindset. We don’t just look for any loan; we look for a partnership that supports your long-term financial health. As dedicated negotiators, we know exactly which 2nd tier lenders are currently active and which ones have an appetite for your specific type of credit file. This insider knowledge is vital for avoiding another “no” and building a direct path to “yes.” We take the stress of the unknown off your shoulders and replace it with a steady, professional hand.

The Advantage of a Seasoned Professional

One of the biggest benefits of partnering with a specialist is access. Many 2nd tier and non-bank lenders in New Zealand do not deal directly with the public; they only accept applications through trusted brokers. We know how to structure your application to mitigate the impact of a default, focusing on your stable income and account conduct instead. This expertise ensures your file isn’t just another number in a pile. It’s a professional presentation that demands a manual review by a real person who can see your potential.

Your Next Steps Toward Home Ownership

Our goal is to answer “can i get a home loan with a default nz” with a clear, actionable plan that puts you back in control of your future. We start with a no-obligation chat to assess where you stand right now. From there, we create what we call a “road to bank” plan. This is a strategy designed to get you into a home now using a 2nd tier lender, with the ultimate aim of moving you back to a mainstream bank once your credit file has cleared. It’s about more than just a house; it’s about a long-term relationship built on trust and results.

Ready to stop guessing and start planning? Book a consultation with Mortgage Suite Ltd today to see what’s possible for your situation.

Your Path to Home Ownership Starts Now

A credit default might feel like a permanent “no,” but it’s actually just a prompt to look in the right direction. By focusing on non-bank lenders who value manual assessments over automated scorecards, you can find a way forward that mainstream banks simply can’t offer. This guide has shown that your recent account conduct and a clear explanation of your past are your strongest tools. If you’ve been wondering, “can i get a home loan with a default nz,” the reality is that with the right preparation and professional advocacy, you certainly can.

At Mortgage Suite Ltd, we use over 20 years of banking expertise to act as your dedicated negotiators for non-bank lending. We are specialists in hard-to-place home loans and are committed to helping you build a bridge back to long-term financial health. You don’t have to face the paperwork or the stress alone. Talk to Krish and the team about your home loan options today and let’s start working on your plan. Your goal of owning a home in New Zealand is still within reach, and we’re here to help you grab it.

Frequently Asked Questions

Can I get a home loan with an unpaid default in NZ?

Yes, it is possible, but your options will be much more limited than if the debt was settled. Mainstream banks almost always require defaults to be paid before they consider an application. Some 2nd tier lenders may approve a loan with an unpaid default if the amount is small, like a minor phone bill, but they usually expect you to pay it off using your loan proceeds at settlement.

How much deposit do I need for a home loan if I have a default?

You will generally need a deposit of at least 20% when applying with a credit default. While mainstream banks sometimes offer lower deposit options for first home buyers with perfect credit, non-bank lenders require more equity to offset the risk. Having a larger deposit shows the lender that you’re committed and provides a safety buffer for their investment.

Will my interest rate be higher because of a credit default?

Yes, you should expect to pay a higher interest rate than the standard bank “special” rates. Because 2nd tier lenders are taking on more risk, they use risk-based pricing. While major banks have floating rates around 6.04% in July 2026, specialist non-bank rates can range from 6.35% to over 11% depending on how recent or serious your default was.

How long after a default can I apply for a mortgage?

You can apply for a mortgage at any time, but your chances of approval increase significantly once the default is at least 6 to 12 months old. Lenders want to see a clear period of “clean” financial behaviour after the event occurred. If you’ve been asking “can i get a home loan with a default nz” shortly after a missed payment, focusing on six months of perfect bank statements is the best way to start.

Does paying a default improve my chances of getting a loan?

Paying your default is the most effective way to improve your chances of a successful application. It transforms you from someone with an active debt into someone who has taken responsibility and cleared their obligations. Most non-bank lenders will ask for a “Letter of Release” from the original provider to prove the matter is fully settled before they issue an approval.

Can a mortgage broker help me if I’ve been declined by my own bank?

A specialist broker is often the best resource after a bank decline because we have access to lenders that don’t deal with the public. We can help you answer “can i get a home loan with a default nz” by manually presenting your case to a human underwriter. This bypasses the automated computer systems that mainstream banks use to auto-decline anyone with a less-than-perfect credit score.

What is the difference between a default and a judgement on a credit file?

A default is a record from a service provider or lender about an unpaid debt, whereas a judgement is a formal court order. Judgements are more serious because they indicate the debt reached a legal level of enforcement. Both stay on your New Zealand credit report for five years, but a judgement will require a more detailed explanation and proof of settlement for a lender to consider your file.

Can I use my KiwiSaver for a deposit if I have a default?

Yes, a credit default does not stop you from withdrawing your KiwiSaver funds for a first home deposit. As long as you meet the standard criteria set by your provider, those funds are yours to use. This can be a huge help in reaching the 20% deposit mark that many non-bank lenders require when they see a default on a credit file.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.