
First home buyer loans NZ: 2026 deposit rules and cash-back offers

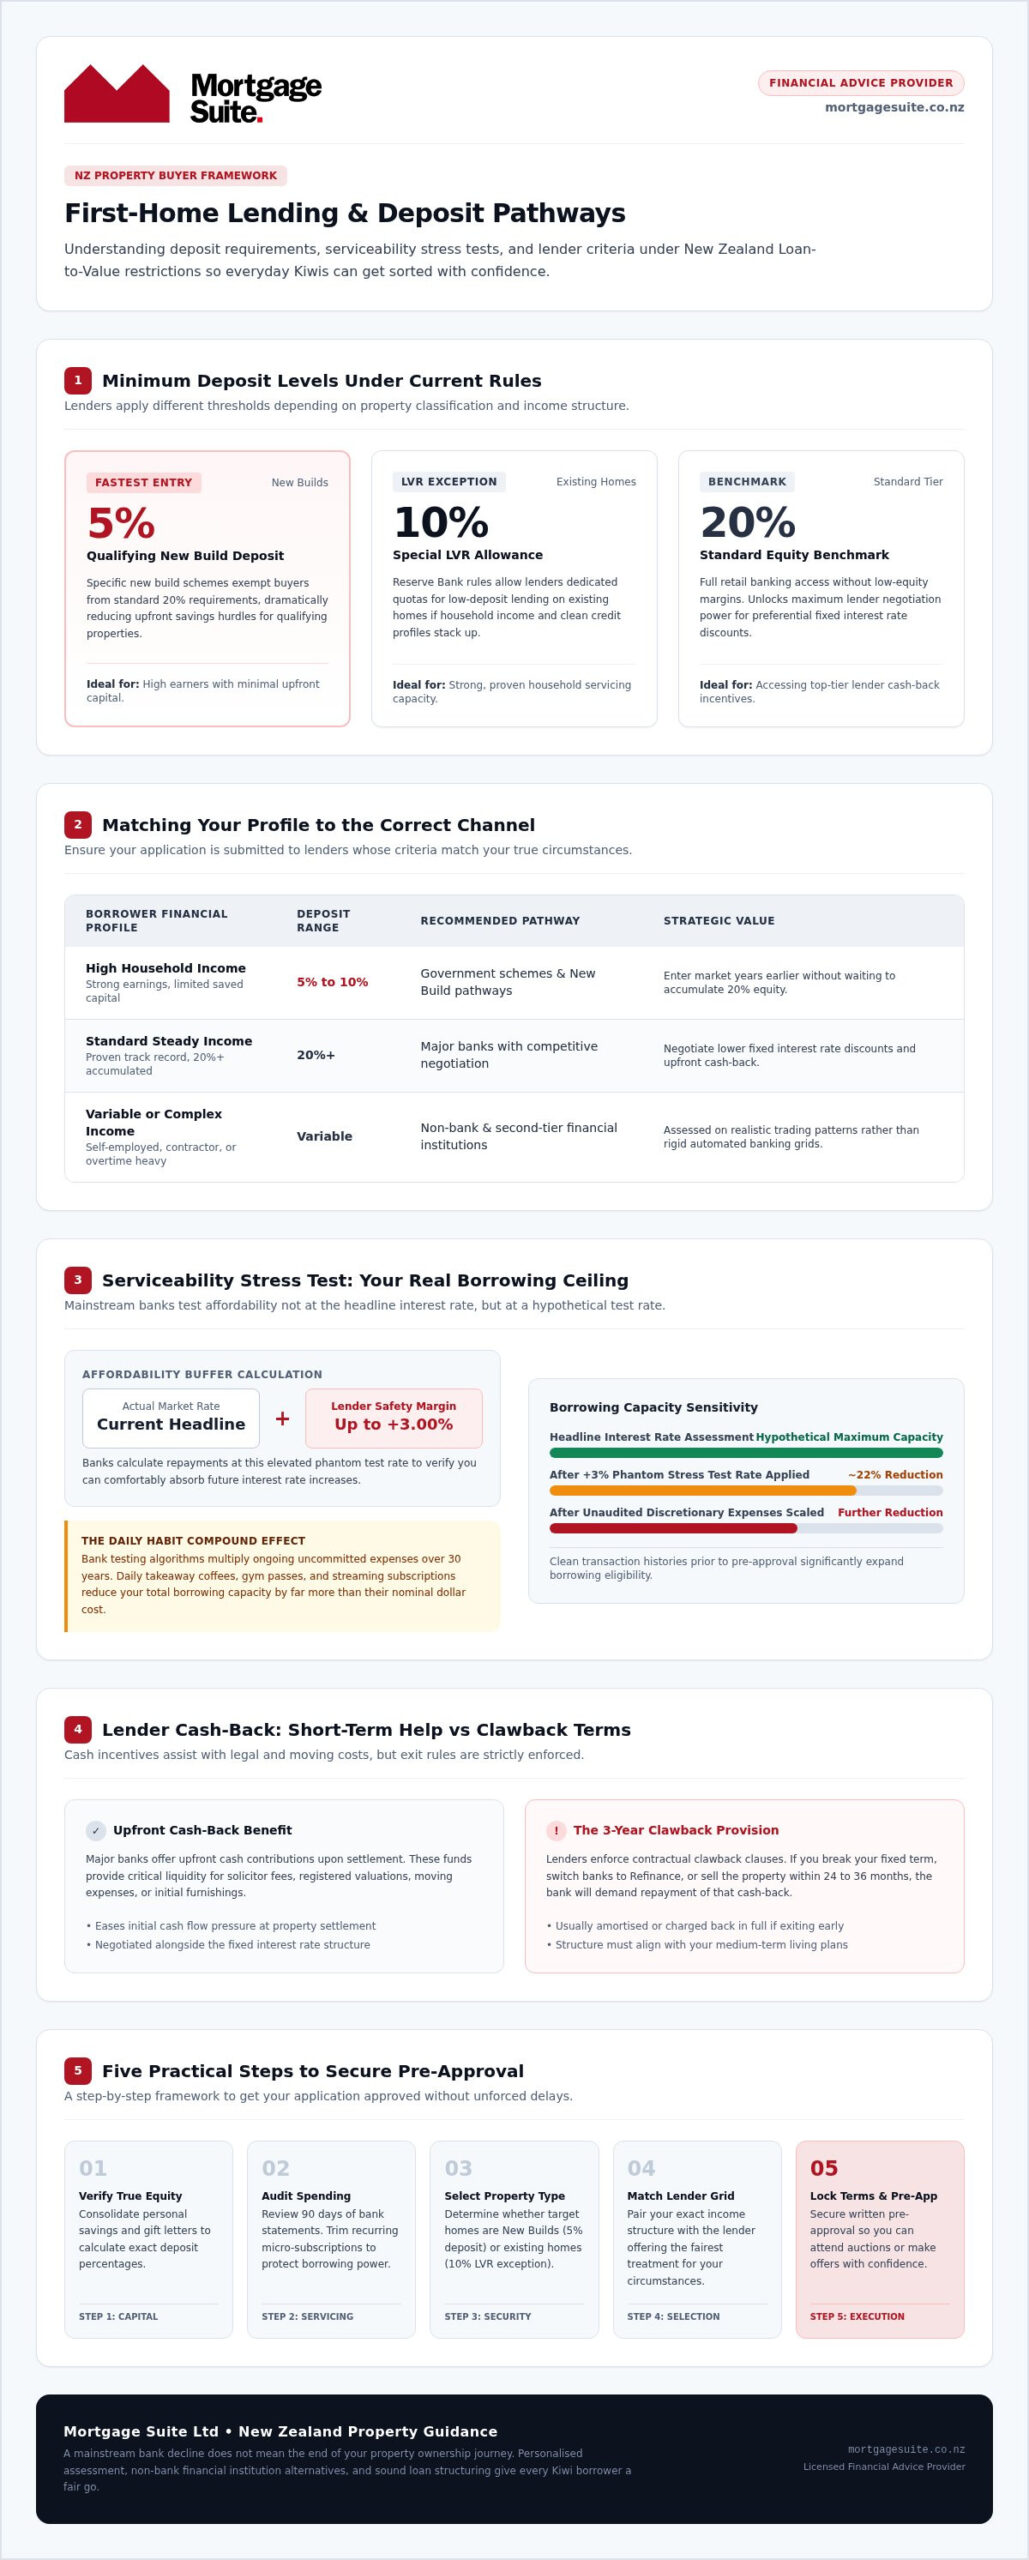
You can buy your first home in New Zealand under 2026 deposit rules with as little as 10% equity in many cases, or 5% on qualifying New Builds, and still chase lender cash-back where the offer fits your term. Working around current lending rules helps you secure government support and lender cash incentives without wasting months on the wrong pathway. We can help you get sorted with a lender that fits your goals.

Key Takeaways: You can secure first home buyer loans in NZ with a 5% deposit for new builds or 10% for existing properties under LVR exceptions.

  • Lenders apply stress tests using phantom interest rates up to 3% above current market rates.
  • Unless you maintain your fixed term, banks strictly enforce clawback provisions on cash-back incentives.
  • Best-for high earners to target 5% to 10% deposit schemes rather than waiting for 20%.
  • Bank calculators treat daily coffee or streaming subscriptions as significant reductions to total borrowing capacity.

Match your deposit and income to the right first-home path

Your path to property depends on deposit size and household income, so match both to the right lender before you lodge a full file. With clients we see that pairing deposit level to lender early saves weeks of frustration: banks strictly review income, while alternative lenders offer more flexibility on complex files.

Three situations come up often:

  • High income with a smaller deposit: apply for low-deposit government or New Build pathways (5%-10%) rather than waiting for 20%.
  • Steady standard income with 20%+ saved: negotiate a locked-in interest rate (fixed interest rate) and compare cash-back against the rate.
  • Complex or variable income: explore non-bank and 2nd tier lending so serviceability is judged on real patterns, not a single rigid grid.

Kiwis with strong earnings can secure a First Home Loan with a 10% deposit under Loan-to-Value restrictions. If your bank says no, switching banks later (Refinance) remains an option once equity grows. You get sorted faster when the strategy fits the file you actually have.

Financial Profile Deposit Level Immediate Next Step
High Income 5% to 10% Apply for low deposit government schemes
Standard Income 20%+ Negotiate a locked-in interest rate
Complex Income Variable Explore non-bank lending options

You deserve a fair go on whichever row matches your life right now.

Yes, you can buy with a 10% deposit under LVR rules

Yes, you can secure a property with a 10% deposit under Loan-to-Value restrictions, provided you meet standard bank affordability criteria. Local rules allow Reserve Bank Loan-to-Value restrictions to include special low-deposit exceptions for buyers, so mainstream bank grids can feel rigid while usable options still sit beside them.

Think of these central bank rules like a nightclub door policy: most guests need a standard entry pass, yet venue security keeps dedicated spots open for specific buyers. For first-home buyers, some specific “New Build” schemes let you get started with as little as a 5% deposit. That is a separate pathway from a standard 20% existing-home purchase, and from the 10% LVR exceptions used when income and credit stack up cleanly.

Saving large reserves is tough when rent and living costs already claim most of the month. Working alongside our team through the first-home buyers guide gives you a fair go when negotiating with lenders. We act as your dedicated advocate so you get sorted without unnecessary stress.

Tip: Check if your prospective property qualifies as a New Build to immediately slash your deposit requirement to 5%.

Stress tests set your real borrowing limit, not the sticker rate

Banks set your home loan limit with a serviceability stress test that checks whether repayments stay affordable if interest rates rise. From client work we see that bank calculators often apply phantom interest rates up to three percent above actual market rates. That testing margin protects both you and the lender from future shocks.

A detail many buyers miss: those test rates also scale up routine daily expenses, which cuts borrowing capacity harder than the cash spent suggests. A daily coffee run or streaming subscription reduces total borrowing power by more than the nominal amount leaving your account. Kiwis often get declined by mainstream lenders simply because the formulas treat tight budgets harshly.

Presenting income and expenses clearly changes the outcome. Working with first-home buyer advisers helps you show actual income so you get sorted with a fair go rather than a blunt decline letter.

Cash-back helps upfront costs if you can hold the fixed term

Our direct professional experience shows that financial institutions rely on clawback provisions to retrieve money if you exit early, and lenders enforce those rules strictly.

You must keep your locked-in interest rate for the set term to avoid paying the funds back. If you switch banks later within three years, the bank can take that cash right back. Our team acts as your personal advocate to negotiate fair terms, and you can read more on options for Kiwis in the first-home buyer articles.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Working with an experienced adviser across multiple purchases keeps your long-term finance structure steadier against strict clawback terms. Ask us to line up the cash-back against the rate and the clawback window before you sign.

2026 Government first-home criteria hinge on income and caps

Government criteria for first-home support depend on household income, regional house caps, and total personal assets. Mainstream banks enforce those limits tightly, yet missing one grant does not end your property goals. In professional practice, applying with a 10% deposit under Loan-to-Value restrictions through a non-bank financial institution often gives more practical flexibility than waiting years to fit rigid government boxes.

From client work, buyers often get turned down by big lenders simply because earnings sit slightly over a threshold, and that outcome usually causes unnecessary panic. As detailed on the Inland Revenue Department 2026 KiwiSaver guide, special withdrawal rules apply when buying your initial home. Think of government grants as a narrow gateway, while tailored lending acts as a wide, accessible driveway.

Mortgage Suite Ltd works as your dedicated negotiator to secure a fair go when the first door closes. If mainstream banks say no, we look for answers on 2nd tier and non-bank paths. Reach out for a friendly, confidential chat to review where you sit against 2026 criteria.
First home buyer loans NZ: 2026 deposit rules and cash-back offers

When a low-deposit home loan costs you more than it saves

A 10% deposit under Loan-to-Value restrictions can backfire when your monthly budget has no room for unexpected expenses. From client work we see that buying with minimal equity creates real pressure: extra fees push regular payments higher than the spreadsheet suggested at offer time.

High loan-to-value margin fees often sit on top of your standard interest rate. Mainstream banks usually charge those extra margins when you borrow over eighty percent of a property’s value, and the premiums eat into income while you also lose interest-rate discounts. Banks still run strict serviceability stress tests on these files, which makes approval harder on a tight budget.

This route works poorly when costs already feel close to the edge, because it slows long-term equity growth as well. If rising costs worry you right now, talk with Mortgage Suite to explore safer deposit and structure pathways before you stretch to the maximum.

Secure home loan pre-approval in five practical steps

Pre-approval gives you clear spending boundaries before you make an offer on a home. From client work we see bank assessments run faster when paperwork is ready from day one, which cuts avoidable delays. Many first-home buyers are surprised to learn that our services are usually at no cost to them.

  1. Gather documents: Collect your recent payslips, bank statements, and proof of ID.
  2. Calculate your deposit: Combine your savings, family gifts, or cash assistance toward a 10% deposit under Loan-to-Value restrictions (or 5% on a qualifying New Build).
  3. Run a serviceability stress test: Check your monthly budget against higher hypothetical interest rates.
  4. Submit your application: Pass your file to a broker who matches your goals with suitable lenders.
  5. Get sorted: Receive written confirmation of your approved limit.

Getting pre-approved works like a pre-paid ticket to an auction: you know your ceiling before you bid. If you expected a large broker fee, remember our help comes free for most buyers. Contact us when you want that written limit in hand.

Split fixed and flexible balances so rate rises hurt less

Splitting your loan balance gives you flexibility when household income drops unexpectedly. Fixing a portion locks in repayments, while placing the rest in an offset account helps you pay the home down faster without losing access to emergency funds.

From client work we see rigid single-structure loans cause heavy stress during sudden life changes. Keeping extra money in a linked account reduces calculated interest daily, yet leaves cash available if money gets tight. Think of your mortgage structure like a Swiss Army knife: two tools beat one heavy blade when conditions change.

That mix suits Kiwis who want steady repayments beside quick cash access. Mortgage Suite helps you get sorted with a customised setup so Your Home Loan stays Our Priority when rates or income shift. Book a time and we will map fixed and flexible portions around your budget.

Frequently asked questions

Can you buy your first home with a 10% deposit?

You can buy a home with a 10% deposit under Loan-to-Value restrictions through low-deposit options at mainstream banks or non-bank lenders, and some New Build schemes go as low as 5%. Low-deposit applications bring extra lender checks, so strong bank statements help you get sorted quickly. Our team acts as your dedicated negotiator when deposit funds feel tight.

How much cash back can I get?

Lenders periodically offer cash incentives of $2,500–$150,000 to first-home buyers, but exact amounts depend on current bank offers and your overall loan size. We review changing bank promotions so you can weigh each incentive against the rate, the fixed term, and clawback rules before you commit.

How do I check how much I can borrow?

You calculate borrowing capacity from household income, everyday expenses, and existing personal debts, then a lender runs its own serviceability test. A mainstream-bank decline does not mean you have run out of choices for buying a house. Talking with a mortgage broker helps uncover flexible non-bank avenues and clear next steps.

How much could you afford to borrow?

Your affordable limit depends on passing a lender serviceability assessment that tests your ability to pay higher rates. Sorting your budget early keeps property searches realistic and avoids unnecessary strain. Reach out for a friendly chat to calculate your true borrowing power before you make offers.

How much deposit do I need to buy a house?

Most standard existing-property purchases require a twenty percent deposit, but select options allow lower equity. Specific New Build schemes let you buy with as little as a 5% deposit, and 10% pathways exist where LVR exceptions and income allow. First-home buyers often learn that our broking services usually come at no cost while you work toward those deposit levels.

Getting sorted with your first home purchase

Buying your first property in New Zealand in 2026 still turns on the same questions you started with: which deposit path fits you (5%, 10%, or 20%+), whether cash-back is worth the clawback term, and how stress tests shape your true limit. A mainstream bank decline is rarely the end of the road for Kiwis looking for a fair go. As advisers at Mortgage Suite Ltd, we advocate on your behalf for tailored lending and sensible cash-back choices. First home buyer loans NZ become simpler when you have a dedicated negotiator in your corner, matching long-term goals to the right lender so you step into the market with confidence. Get in touch with Mortgage Suite today to get sorted.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How Long Does Pre-approval Last in NZ? Your 2026 Home Loan Guide

Imagine you’ve finally spotted a home that ticks every box, but a nagging thought keeps you awake: is my bank offer about to expire? It’s a common worry for many Kiwis, and the most pressing question is usually how long does pre approval last nz-wide. In the current 2026 market, most major banks give you a 90-day window to make your move. That three-month countdown can feel like a high-stakes sprint, especially when you’re trying to balance weekend open homes with the anxiety of shifting interest rates.

We know that the fear of losing a house because your finance expires is incredibly draining. You’ve worked hard to get your deposit ready, and you deserve to shop with total confidence. This guide will show you exactly how to manage your timeline and keep your momentum going without the stress. We’ll explore how to handle those standard expiry dates, the simple steps to organise an extension, and how to stay protected if your financial situation shifts before you sign on the dotted line.

Key Takeaways

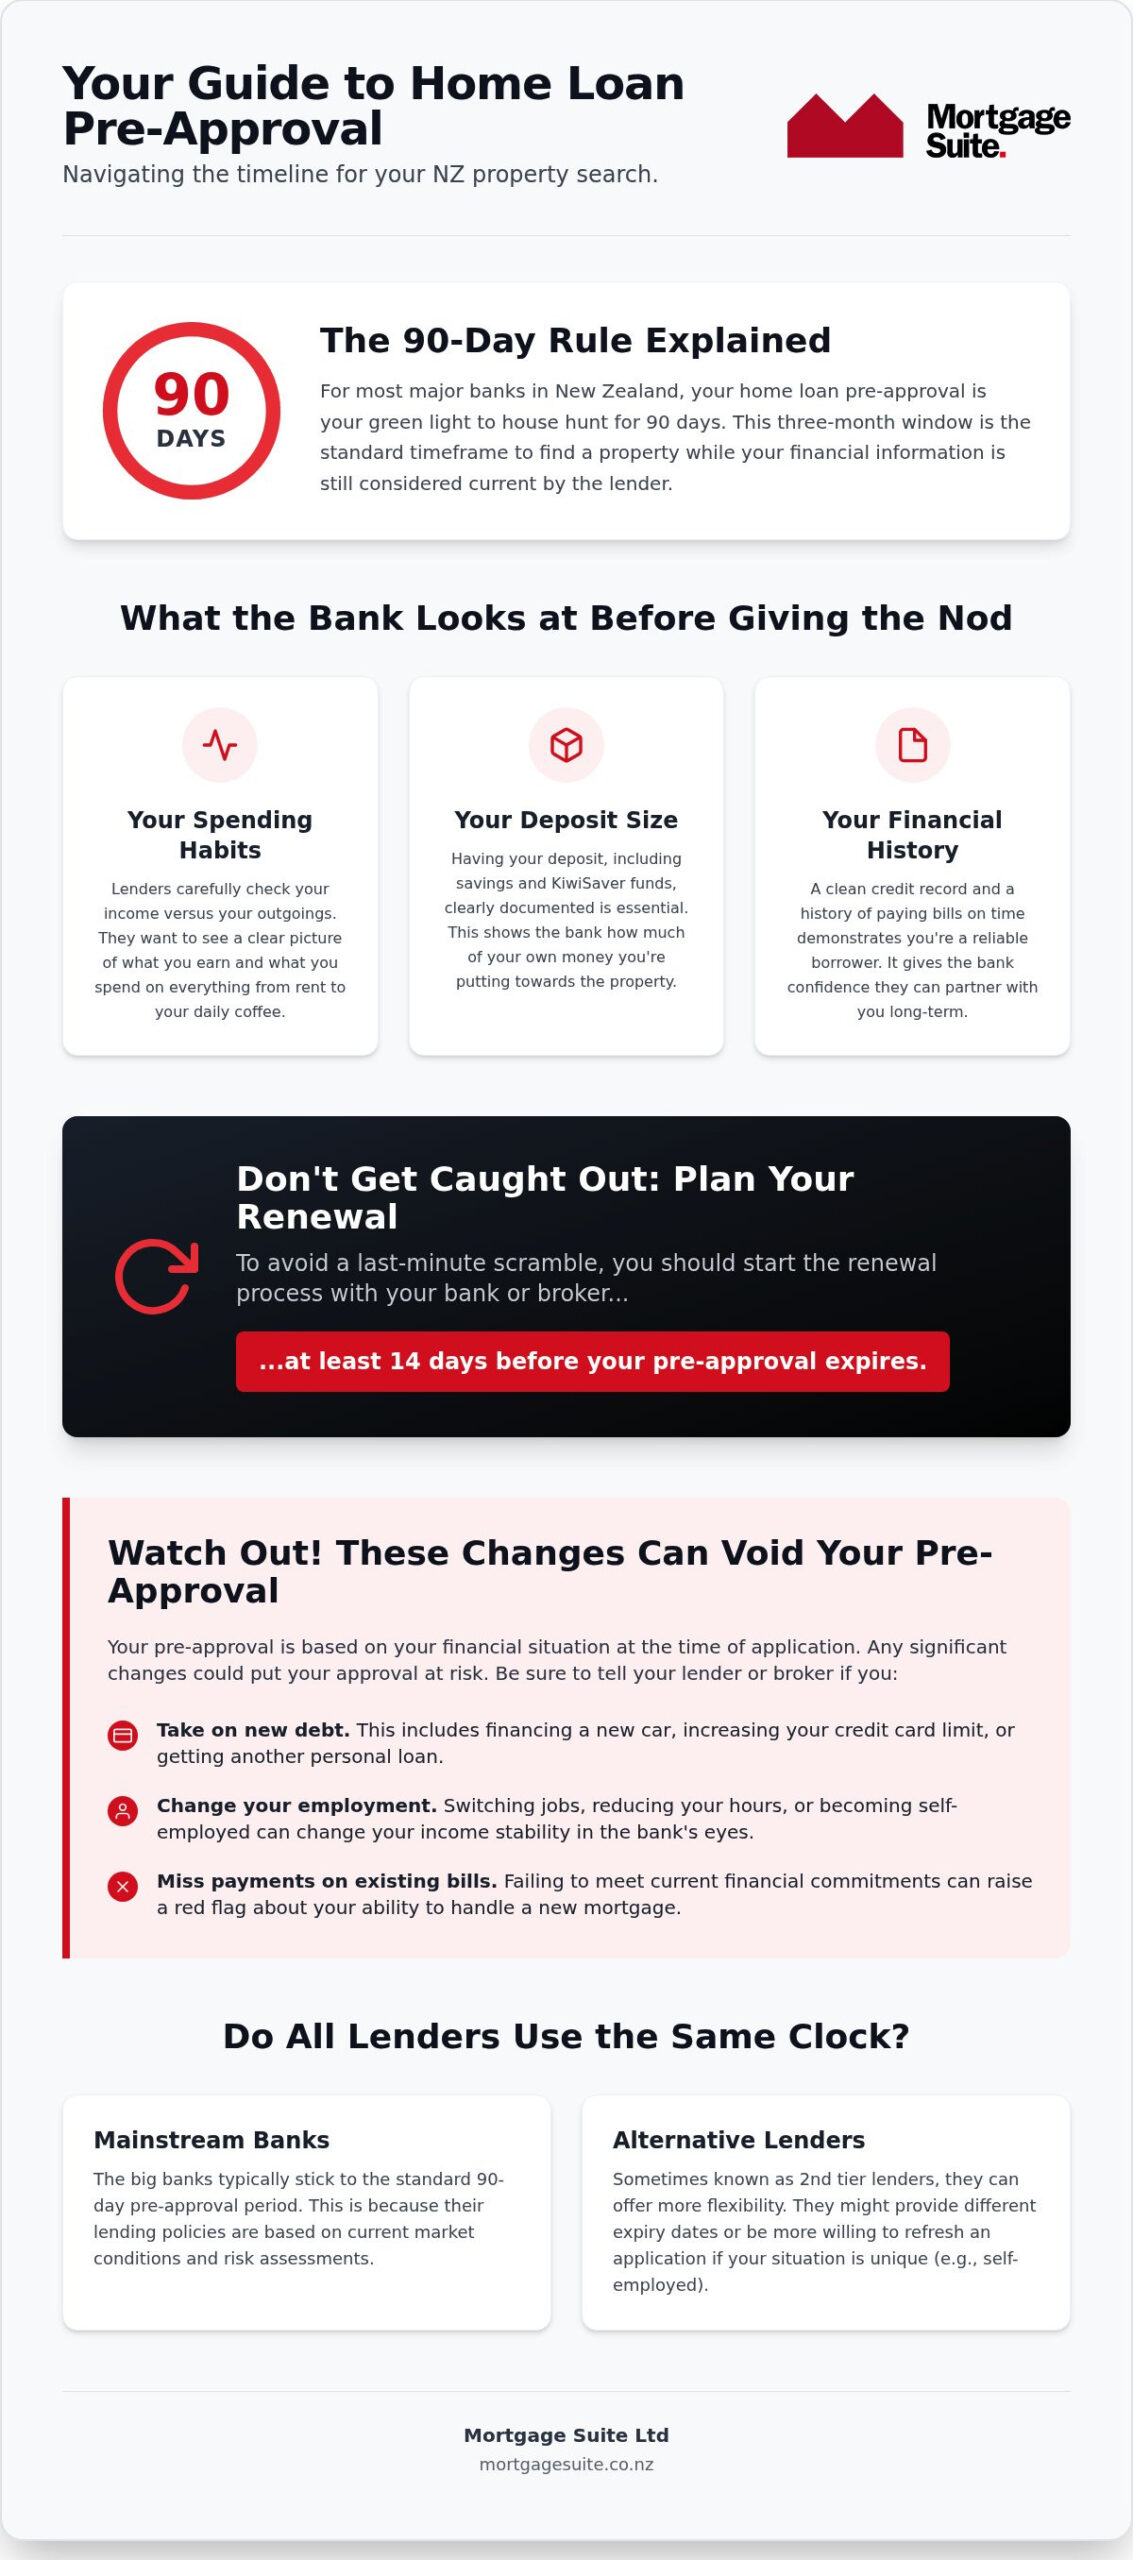
  • Learn why the standard 90-day window is the typical timeframe for most New Zealand banks and how to make the most of those three months.
  • Discover exactly how long does pre approval last nz-wide and why you should start the renewal process at least 14 days before your current offer expires.
  • Understand the major lifestyle changes, such as taking on new debt or switching jobs, that could accidentally void your home loan agreement.
  • Find out how to keep your house-hunting momentum high by using a broker’s expertise to access alternative lenders if the big banks change their minds.

Understanding home loan pre-approval in the NZ market

Think of a pre-approval as your “golden ticket” to the New Zealand property market. It’s essentially a bank giving you a high-five and saying they’re likely to lend you a specific amount, provided the house you eventually find meets their criteria. Before you start worrying about how long does pre approval last nz-wide, you should understand what pre-approval means in a practical sense. It’s the bridge between “just looking” and actually being able to sign a contract with confidence.

In plain English, there are two stages to this “yes.” A conditional pre-approval is what most people start with. This means the bank likes your finances, but they still need to check the property reports and valuations for the specific house you want to buy. An unconditional approval is the final green light for a specific property where all the boxes are ticked. Getting this sorted before you step foot in an open home is a total game-changer for your stress levels.

Why you need a “yes” before you start hunting

Walking into an open home without a pre-approval is like going grocery shopping without your wallet. You might see plenty of things you want, but you can’t actually take any of them home. Having that bank letter in your pocket prevents the heartbreak of falling for a property that’s outside your actual borrowing capacity. It also sets a firm boundary for your budget, which is vital if you end up in a heated auction room. Real estate agents will take your offers much more seriously because they know you’re a serious buyer who’s already done the hard yards. If you want to brush up on the basics, our mortgage school is a great place to start. Knowing exactly how long does pre approval last nz-wide helps you plan your weekends so you’re not rushing into a bad deal just because a deadline is looming.

What the bank looks at before giving you the nod

Banks aren’t just looking at your salary; they want to see the whole picture of your financial life. They’ll look closely at your “income vs outgoings.” This is basically a look at what’s coming in versus what you’re spending on things like rent, utilities, and even your daily lattes. They also check the size of your deposit. With the national median house value sitting around $804,303 in mid-2026, having your KiwiSaver funds and savings clearly documented is essential. Finally, they’ll look at your history with money. Staying on top of your bills and keeping a clean credit record shows the bank that you’re a reliable partner. This transparency helps them decide how much they can safely lend you without putting your lifestyle at risk.

The standard timeline: How long your pre-approval stays valid

Once you get that initial “yes” from a lender, the clock starts ticking. In the current New Zealand market, the standard answer to how long does pre approval last nz-wide is usually 90 days. This three-month window is designed to give you enough time to visit open homes, do your due diligence, and put in an offer without the bank’s information becoming stale. It’s a period of stability in what can often feel like a fast-moving process.

Banks prefer this timeframe because your financial life can change quickly. A lot can happen in 90 days; you might get a pay rise, or perhaps you’ve decided to finally pay off that old credit card. By keeping the window to three months, the bank ensures they are lending based on your most current situation. If you’re feeling a bit lost with the timing, you can read more about us and how we guide you through every step of the journey.

The 90-day rule explained

Banks reckon three months is the sweet spot for checking your finances because market conditions shift. For example, with the annual inflation rate at 4.1% in the June 2026 quarter, the cost of living is always on the move. If interest rates rise while you’re house hunting, your “buying power” might actually shrink. This happens because banks use a “stress test” to see if you could still afford your mortgage if rates went even higher. If the market rates go up, their test gets tougher, which might reduce the total amount they are willing to let you borrow. This is why a “full” pre-approval, where the bank has actually seen your documents, is much more reliable than a “soft” indication or a quick chat over the phone.

Do all lenders use the same clock?

While the big mainstream banks usually stick to that 90-day limit, alternative or 2nd tier lenders can sometimes be more flexible. These lenders often look at your situation with a more personal lens, which is helpful if your income is a bit unique or you’re self-employed. They might offer different expiry dates or be more willing to refresh your application without making you start from scratch. Your broker is the best person to keep an eye on the calendar for you. We track these dates across different lenders so you don’t have to. Think of pre-approval as a “rolling” green light; if time does run out, it’s rarely a dead end. Usually, it just means providing a few fresh payslips to show the bank that your situation is still as solid as it was on day one.

Factors that can cut your pre-approval short or change the deal

Even though we’ve established that 90 days is the standard answer to how long does pre approval last nz-wide, that timeline isn’t actually written in stone. It’s more like a weather forecast; it’s accurate as long as the conditions stay the same. If your personal situation or the wider market shifts, the bank has every right to look at your application again. Having seen every market cycle over the last two decades, I can tell you that staying “bank-ready” is just as important as finding the right house.

A pre-approval is a snapshot of your life at a specific moment. If that snapshot changes, the bank’s level of risk changes too. This doesn’t mean you’ll lose your chance at a home, but it does mean you might need to provide fresh information or look at alternative lenders who are more comfortable with your new circumstances.

Big life changes that affect your loan

Switching jobs during your house hunt is one of the most common ways to accidentally reset your clock. Even if you’re moving for a higher salary, banks often prefer to see you’ve passed a probation period before they’ll commit to a long-term loan. Moving from a steady salary to being self-employed is an even bigger shift, as banks usually want to see a solid track record of business income before they say yes again.

New debt is another major hurdle. It’s tempting to grab that interest-free deal on a new couch or upgrade your car while you’re waiting for the right house, but these choices reduce your “buying power.” Every dollar you commit to a car loan or a credit card is a dollar that can’t go toward your mortgage repayments. We also see “spending creep” catch people out; if your bank statements show your monthly bills have shot up since you first applied, a lender might second-guess their initial offer.

The “subject to property” condition

The bank isn’t just lending to you; they’re essentially investing in the house you choose. This is why every pre-approval is “subject to property.” Before they give the final nod, they need to see the Sale and Purchase Agreement and, quite often, a registered valuation. If the valuation comes in lower than the price you’ve agreed to pay, the bank may only lend based on that lower value, leaving you to find the difference.

Specific property issues can also cause a bank to pull back. Things like certain types of cladding or houses with known maintenance problems can make a property too risky for a mainstream lender. If this happens, don’t panic. This is where our experience with 2nd tier lenders becomes a massive advantage, as they often have different rules for properties that don’t fit the standard bank box. You can check out our reviews to see how we’ve helped others navigate these exact hurdles.

How Long Does Pre-approval Last in NZ? Your 2026 Home Loan Guide

Steps to take as your pre-approval nears expiry

If you’ve been spending your weekends at open homes and the calendar is starting to look a bit crowded, don’t panic. It is incredibly common for the house-hunting journey to take longer than the initial three months. While we’ve discussed that how long does pre approval last nz-wide is typically 90 days, reaching the end of that window doesn’t mean you’re back at square one. It’s simply a prompt to check in and ensure your financial “snapshot” is still accurate for the bank.

The secret to a stress-free extension is what we call the 14-day rule. You should start the conversation with your broker at least two weeks before your current letter expires. This gives the bank enough time to process the update without your buying power actually lapsing. If you wait until the very last day, you might find yourself unable to put in a clean offer on a house you love because your finance is technically in limbo.

The renewal process: what to expect

In most cases, renewing your pre-approval isn’t a brand-new application from scratch. If your job, income, and debt levels haven’t changed since your first “yes,” it’s usually just a quick check-up. The bank will want to see that your situation is still ship-shape. This typically means providing your two or three most recent payslips and perhaps a fresh look at your main bank account statements to ensure your spending hasn’t spiked.

A quick chat with us can save you hours of paperwork. We already have your history on file, so we know exactly what the bank needs to see to hit the “refresh” button. Mortgage Suite Ltd handles the heavy lifting and the back-and-forth with the lenders, leaving you free to focus on finding the right property. If you’re curious about the finer details of the lending process, you can learn more at our Mortgage School.

Keeping your credit score healthy

A common worry is whether renewing your pre-approval will hurt your credit rating. Every time a bank does a formal check on your file, it leaves a small footprint. While one or two inquiries for a mortgage are perfectly normal and won’t cause your score to plummet, you want to avoid “too many inquiries” in a short space of time. This is another area where having a broker works in your favour.

Our goal is to keep your buying power strong while protecting your financial reputation. We can often use the information we already have to get an extension or look at alternative lenders without triggering unnecessary new credit checks. If the market shifts or your bank’s rules change during your search, we can pivot quickly to other options, including 2nd tier lenders who might offer more flexibility. If your current offer is about to run out, it’s a great time to get in touch with our team so we can keep your search on track.

Partnering with Mortgage Suite Ltd to secure your dream home

Finding a home is a journey, and having the right guide makes all the difference. When you’re constantly checking the calendar and wondering how long does pre approval last nz-wide, you need more than just a computer-generated bank letter; you need an advocate. Krish Krishna brings over two decades of banking experience to your side of the table. This isn’t just about filling in forms. It’s about having a seasoned mentor who knows exactly how to present your financial story to a lender to get the best possible outcome.

We understand that not every borrower fits into a neat little box. If a mainstream bank decides your situation is too complex, or if your pre-approval expires and they’ve changed their lending rules, we don’t just give up. We specialise in 2nd tier loans and non-bank options that offer a different path forward. This “negotiator advantage” means we can often find solutions that you simply wouldn’t find by walking into a local branch alone. Our goal is to remove the obstacles and make the entire process feel like a walk in the park.

A steady hand in a fluctuating market

The property market has its share of twists and turns, but you don’t have to navigate them by yourself. We keep track of your expiry dates and renewal deadlines so you can keep your eyes on the property listings. Our client-first approach means we stay with you from that very first “yes” all the way through to the day you get your keys. We pride ourselves on being a steady hand when things feel uncertain. If you want to see how we’ve helped other buyers stay confident during their search, you can read what other Kiwis say about us.

Ready to get your pre-approval sorted?

Taking the first step shouldn’t be intimidating. We believe in simple, jargon-free conversations that help you understand your true buying power in today’s market. Whether you’re a first home buyer or looking at a residential investment, now is a great time to get your ducks in a row. We’ll help you figure out exactly how long does pre approval last nz-wide for your specific lender and ensure you’re ready to pounce when the right house appears. If you’re ready to start your journey with a team that puts you first, get in touch with the team at Mortgage Suite Ltd today.

Take the next step toward your new home with confidence

Securing a “yes” from a lender is a massive milestone, but it’s only the beginning of your journey. Knowing exactly how long does pre approval last nz-wide helps you plan your weekends and set a realistic pace for your search. While that 90-day window is the standard starting point, remember that it’s a rolling green light rather than a hard stop. By staying “bank-ready” and keeping an eye on your 14-day renewal deadline, you can keep your momentum high without the stress of finance expiring at the wrong moment.

With over two decades of banking experience, we’ve seen every market cycle and know how to navigate the hurdles that trip up other buyers. We’re experts in both mainstream bank lending and 2nd tier options, which is why we’re so highly rated by New Zealand home buyers. We act as your mentor and negotiator, ensuring you have the best possible chance of success regardless of how the market shifts. Book a chat with Krish and the team at Mortgage Suite Ltd today to get your buying power sorted for 2026. You’ve got a dedicated team behind you, and we can’t wait to help you open the door to your new home.

Frequently Asked Questions

Can I extend my pre-approval if I haven’t found a house yet?

Yes, you can almost always extend your offer if you haven’t found the right property within the initial timeframe. Most lenders allow a renewal for another 90 days, provided your financial situation hasn’t changed. You’ll simply need to provide your latest payslips or bank statements to show the bank that your income and spending are still stable. Understanding how long does pre approval last nz-wide helps you stay ahead of these deadlines.

Does it cost anything to get or renew a pre-approval in NZ?

No, getting or renewing a pre-approval is generally a free service provided by banks and lenders in New Zealand. There are no application fees or hidden costs to find out what you can borrow. This is why it’s such a valuable tool for house hunting; it gives you the confidence to bid at auctions without any upfront financial commitment. If you choose to work with a broker, their service is also typically free for you.

What happens if interest rates go up while I have pre-approval?

If interest rates rise, the bank might reassess how much they are willing to lend you. This happens because they use a “stress test” rate to ensure you can still afford repayments if rates climb even higher. A significant jump in market rates could mean your maximum budget shrinks, even if your income stays the same. This is a key reason why knowing how long does pre approval last nz-wide is vital for your planning.

Can I change banks after my pre-approval expires?

Yes, you are never locked into one bank and can definitely look at other options once your current offer expires. In fact, if your original bank’s rules have tightened, it’s often a smart move to see what other lenders can offer. We often help clients pivot to different banks or even 2nd tier lenders if they find a property that doesn’t fit the standard bank box. It’s all about finding the best fit for your needs.

Is pre-approval a guarantee that I will get the loan?

No, a pre-approval is a conditional commitment rather than a final guarantee. The bank still needs to approve the specific property you want to buy and ensure it meets their standards. They will check the Sale and Purchase Agreement and often require a registered valuation. Final approval also depends on your financial situation remaining exactly the same as it was when you first applied, so avoid taking on any new debt during your search.

Do I need a new pre-approval if I change my budget?

Yes, you’ll need an updated letter if you decide to increase your borrowing amount or if your deposit size changes. While you don’t need a new letter to buy a more affordable house, having an accurate budget ensures you’re looking at the right properties. If your income has gone up or you’ve saved more, a quick chat with your broker can help refresh your “buying power” so you can bid with total confidence at your new level.

How long does it take to get a pre-approval in New Zealand?

You can typically expect an outcome within two to five working days once you’ve submitted all your documents. This timeframe can vary depending on how busy the banks are and whether your application is straightforward or requires a bit more explanation. Having your payslips, bank statements, and identification ready to go before you apply will help speed up the process. We work closely with lenders to ensure your application moves through the system quickly.

What is the difference between pre-approval and approval in principle?

These two terms are essentially the same thing in the New Zealand mortgage market. Both mean the bank has looked at your finances and agreed to lend you a certain amount, provided the property you choose meets their criteria. Whether a bank calls it a pre-approval or an “approval in principle,” it serves the same purpose: it provides the professional assurance you need to show real estate agents and sellers that you are a genuine and prepared buyer.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.