
Working Capital Loans NZ: Your 2026 Guide to Boosting Business Cash Flow

Imagine it’s Friday afternoon and you’re staring at a stack of unpaid invoices while the clock ticks down toward your staff’s payday. You’ve been waiting over 60 days for a major client to settle their account, and your local bank branch just gave you a cold “no” because you don’t fit their rigid rules. It’s a frustrating spot to be in, but you aren’t alone. Most Kiwi business owners know that feeling of having a healthy order book but a temporary gap in the bank account. This is where working capital loans become the essential fuel for your business engine, providing the cash you need to keep things moving while you wait for those payments to land.

We understand that you need a partner who looks at your industry expertise rather than just a spreadsheet. In this 2026 guide, you’ll learn how to bridge the gap between your mounting bills and your future growth with the right financial solution. We’ll explore how to access fast cash that respects your specific trading cycle and why 2nd tier lenders might be the breakthrough your business deserves. From managing seasonal dips to seizing sudden opportunities, we’re going to show you how to take the stress out of your cash flow for good.

Key Takeaways

  • Learn how working capital loans act as a bridge between your outgoing bills and the time it takes for customers to settle their invoices.
  • Discover whether a flexible safety net you can dip into or a one-off lump sum of cash is the better fit for your specific business cycle.
  • Understand why a “no” from a mainstream bank doesn’t mean your plans are over, especially when exploring 2nd tier lending options for Kiwi businesses.
  • Learn how to organise your financial numbers to create a solid plan that gives lenders the confidence to back your vision.
  • Find out how having a seasoned negotiator in your corner helps you connect with lenders who’re actively looking to support businesses like yours.

What exactly is a working capital loan and how does it help your business?

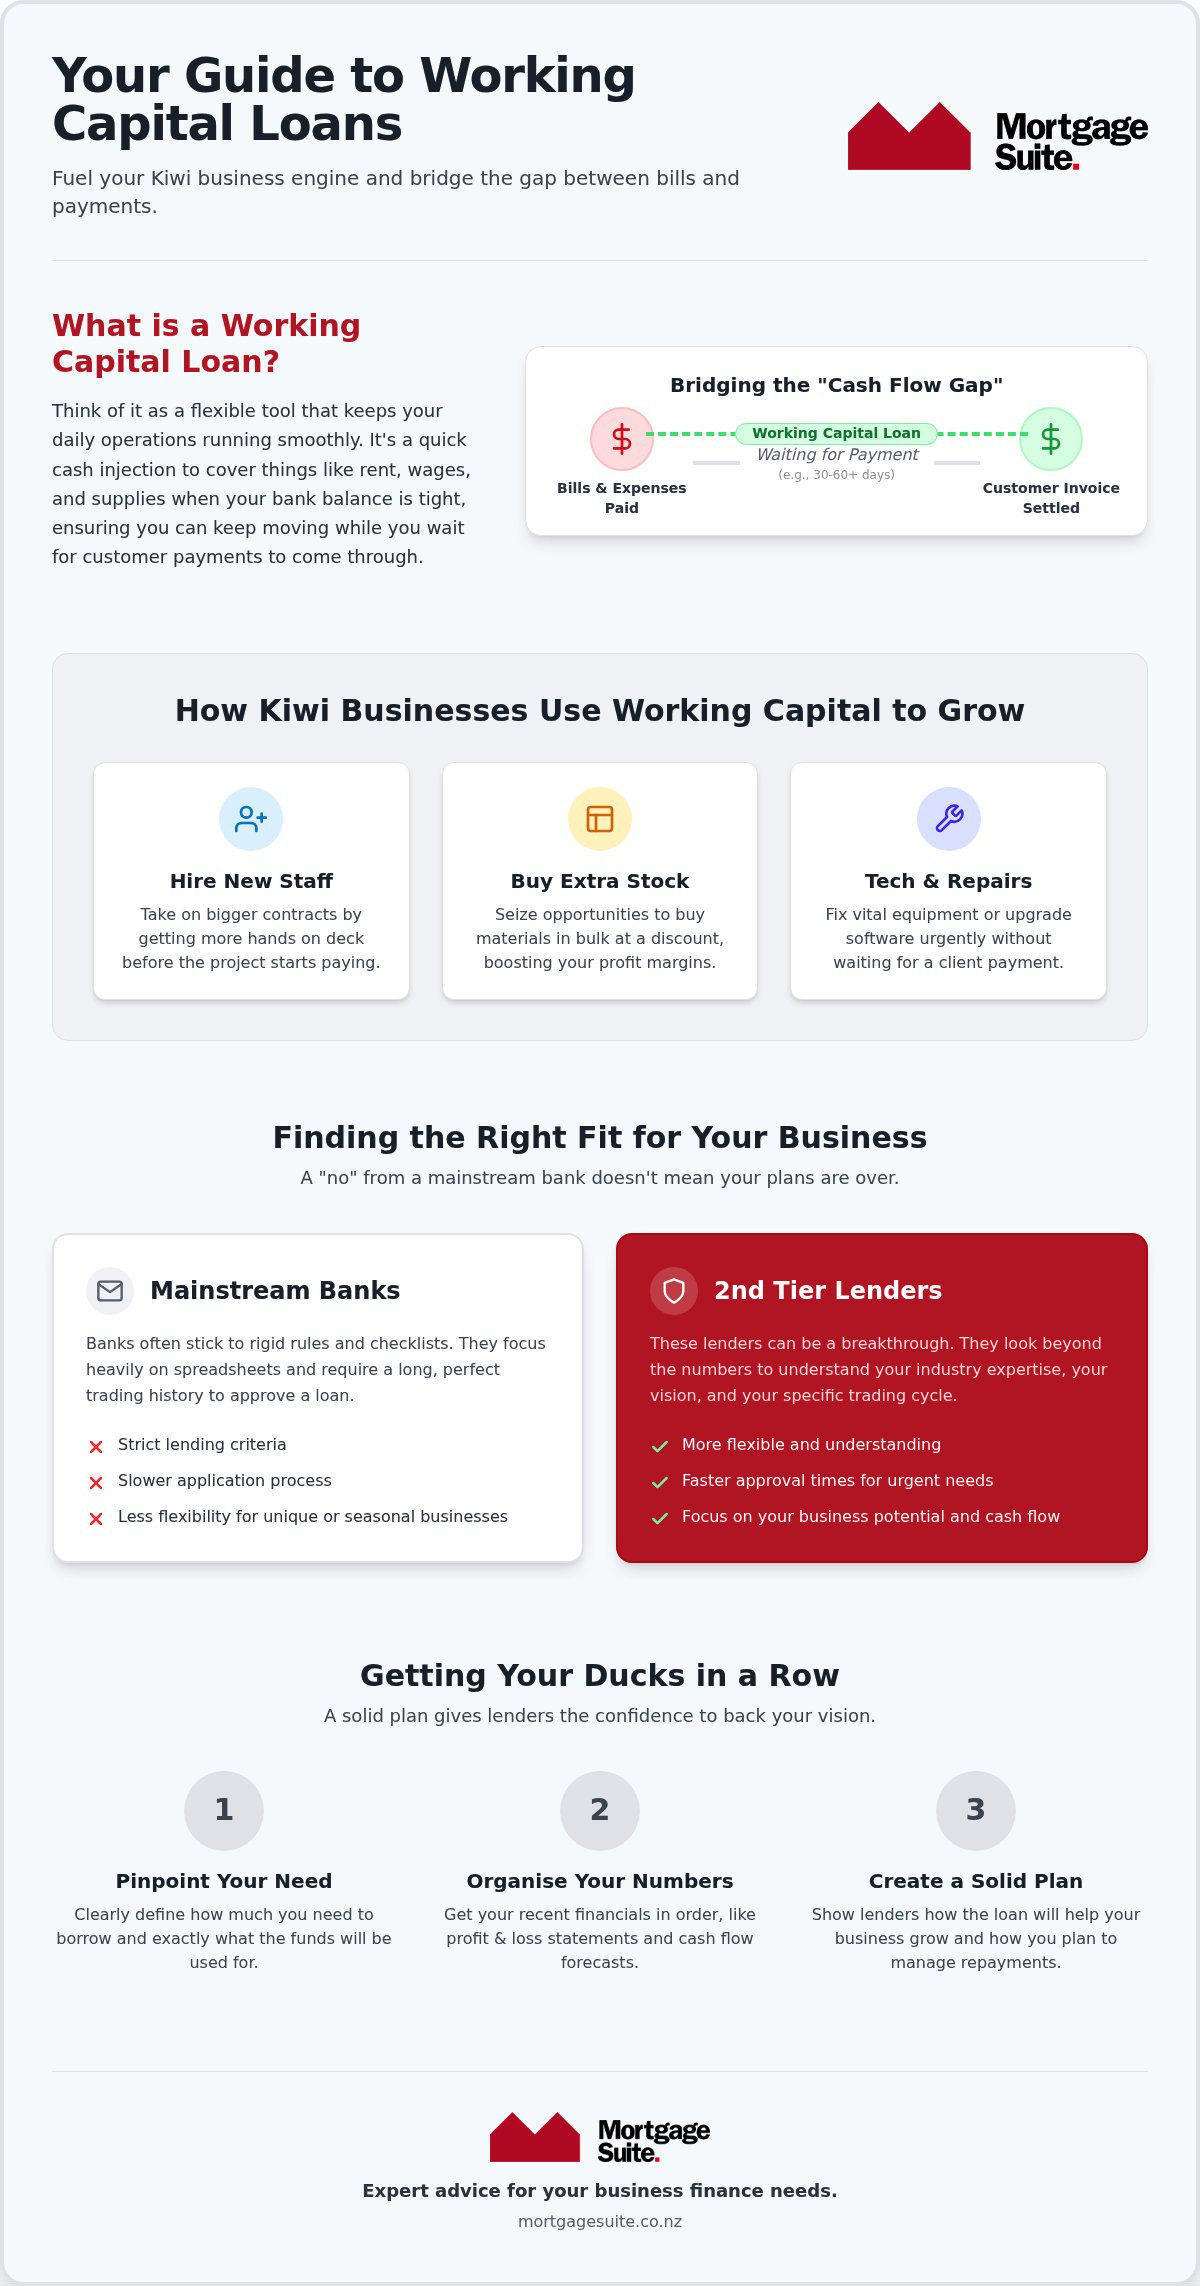
Think of a working capital loan as a flexible tool that keeps your daily operations running smoothly. Unlike a mortgage paid over decades, these are designed for the here and now. They provide a quick injection of ready cash to cover things like rent, utilities, and payroll when your bank balance isn’t quite matching your current workload. It’s a professional way to keep the engine running without having to dip into your own back pocket or use the family’s personal savings.

The primary purpose of working capital loans is to bridge the timing difference between your outgoings and your income. In a perfect world, every customer would pay the moment you finish a job. In the real world, you’re often paying for materials and labour weeks before the final invoice is settled. This finance acts as a safety net, ensuring you can meet your obligations today while waiting for the rewards of your hard work tomorrow.

The “Cash Flow Gap”: Why even healthy businesses need extra funds

It’s a common myth that only struggling businesses need extra help. In reality, some of the fastest-growing companies in New Zealand face the tightest cash flow. This happens because high growth requires upfront investment. You might have a massive pipeline of work lined up, but if you don’t have the cash to buy the supplies or pay the team, that growth stalls. Having a lot of work on doesn’t always mean you have a lot of cash in the bank.

New Zealand’s unique market also plays a role. Many Kiwi industries are seasonal, such as a retail shop in a tourist town or a landscaping crew during a wet winter. During these quiet patches, your fixed costs don’t go away. Working capital loans allow you to maintain your momentum during slow months so you’re ready to hit the ground running when the busy season returns. It prevents your next big project from stalling just because you’re waiting on a large client to pay.

Common ways Kiwis use working capital to grow

Having access to available funds isn’t just about survival; it’s about being proactive and seizing opportunities. Here are a few ways local businesses use this funding to get ahead:

  • Hiring new staff: Taking on a new contract often means you need more hands on deck before that contract starts paying.
  • Buying extra stock at a discount: If a supplier offers a significant discount for a large order, having the cash to buy upfront can boost your profit margins.
  • Technology and repairs: If a vital piece of equipment breaks or your software needs an urgent upgrade, you can’t always wait for a client payment to fix it.

Exploring the different ways to fund your day-to-day operations

Choosing the right way to fund your business is a bit like picking the right vehicle for a trip. You wouldn’t take a heavy truck for a quick run to the shops, and you wouldn’t use a small car to move a house. In the world of business finance, the structure you choose matters just as much as the amount you borrow. Working capital loans come in various shapes, and the best fit depends entirely on whether you need a permanent safety net or a one-off boost.

One of the first decisions you’ll face is whether to go with a secured or unsecured option. A secured loan uses an asset, such as a property, as a guarantee for the lender. This often results in more competitive terms because the risk is lower for the bank. Unsecured loans don’t require that same security, which can make the application process faster, though lenders will look much more closely at your trading history and cash flow to ensure you’re a safe bet.

Repayment terms also play a huge role in your daily stress levels. A shorter loan term might mean higher weekly repayments, but you’ll pay far less in interest over the life of the loan. Spreading the cost over a longer period keeps your weekly outgoings lower, which is often easier on the budget during the early stages of a growth push. It’s all about finding that sweet spot where the debt feels manageable within your normal trading cycle.

Business Overdrafts and Lines of Credit

A business overdraft is the ultimate “just in case” fund. It sits quietly in the background of your business bank account, ready for those moments when a bill arrives before a customer payment does. The best part is that you only pay interest on the money you actually use. If you have a limit of NZ$20,000 but only spend NZ$2,000 to cover a quiet week, you aren’t paying for the other NZ$18,000. It’s a perfect way to manage the natural ups and downs of a standard trading month without any fuss.

Term Loans for specific business goals

When you have a specific goal in mind, a term loan is usually the better path. This provides a lump sum of cash upfront, which you then pay back over a fixed period. It’s the ideal choice for one-off costs like launching a new website, funding a major marketing push, or upgrading essential equipment. Because the repayments are fixed, you can plan your budget with total certainty. We often help clients structure these repayments to match their specific business income, ensuring the debt supports your growth rather than hindering it. If you want to see how we’ve helped others navigate these choices, you can read more about our approach to business lending.

Working capital loans shouldn’t be a burden. By choosing the right structure, you ensure that the extra funds act as a springboard for your Kiwi business rather than just another bill to worry about.

Mainstream banks vs. 2nd tier lenders: Finding the right fit

Many Kiwi business owners walk into their local branch expecting a partnership and walk out feeling like just another number on a spreadsheet. The big banks have rigid, “cookie-cutter” rules that don’t always cater to the unique reality of running a business in 2026. If your situation doesn’t fit their exact mould, they’re often quick to shut the door. This can be incredibly disheartening, but it’s important to remember that a bank’s “no” is usually about their own internal policy, not the quality of your business.

The main difference lies in how a lender views risk. Mainstream banks are built for stability and high-volume, low-risk lending. They prefer businesses that look exactly like the one they funded yesterday. When you’re looking for working capital loans, you need someone who sees the potential in your future contracts and your industry expertise, rather than just staring at your past tax returns. Alternative lenders fill this gap by looking at the big picture of your business health.

When the big banks say “no”

Banks usually want to see at least two years of perfect trading history and often require physical assets, like a commercial building or residential property, as security. If you’re a service-based business or you’ve recently pivoted your strategy, you might find them incredibly nervous about lending. Being declined by a major bank isn’t the end of your plans; it’s simply a sign that you need a different type of partner. This is where a 2nd Tier Lender New Zealand can provide a lifeline. These lenders specialise in non-standard scenarios and are often more comfortable with complex credit or shorter trading histories.

The flexibility of alternative business financing

While banks focus on what happened in the past, alternative lenders often prioritise where your business is going. They’re willing to customise working capital loans to fit your specific industry needs, whether you’re in construction, retail, or professional services. The trade-off is often a slightly higher interest rate, but you gain much higher flexibility and, most importantly, speed. When a sudden opportunity arrives, like a chance to buy a competitor’s stock at a discount or hire a key team member to land a big contract, you can’t afford to wait six weeks for a bank committee to meet. Speed is the biggest advantage of non-bank lending, often getting cash into your account in a fraction of the time a traditional bank would take.

Navigating these alternative options alone can be overwhelming. This is why having a dedicated negotiator who knows the “inside track” of the banking world makes all the difference. We help you compare different deals to ensure you’re getting a fair price and terms that won’t cause stress during a slow month. We focus on finding a lender who understands your industry, ensuring your finance supports your growth rather than holding it back.
Working Capital Loans NZ: Your 2026 Guide to Boosting Business Cash Flow

Getting your ducks in a row: How to apply for a business loan in NZ

Applying for a loan shouldn’t feel like you’re being interrogated. It’s really just a consultative conversation about where your business is now and where you want it to go. When you’re looking for working capital loans, the goal is to show a lender that you’re a safe pair of hands. They want to see that you have a plan and that you’re in total control of your numbers. Being prepared makes the difference between a quick approval and a long, drawn-out process.

Being honest about your history is vital. If you’ve had some “bumps in the road” like a slow trading year or a credit hiccup, tell us early. It’s much easier to explain a situation upfront than to have a lender discover it later. A veteran broker acts as your advocate; we do the heavy lifting of presenting your case to the right people in a way that highlights your strengths. We know which lenders are more comfortable with your specific industry and who will see the value in your reputation.

The paperwork you will actually need

You don’t need a mountain of files to get started. Most lenders just want to see your recent financial statements. These show your profit and any current debts you’re managing. They’ll also look at your bank statements to understand the daily health of your business cash flow. This gives them a clear picture of how money moves through your accounts. If you want to brush up on how to get your finances ready, visit our Mortgage School for more practical tips.

Telling the story of your business

Numbers tell part of the story, but your vision fills in the gaps. A simple one-page business plan is often more powerful than a complex spreadsheet. When you use working capital loans to grow, show the lender exactly how the cash will help you make more money. Maybe it’s hiring a new lead generator or buying stock to fulfil a big contract. Don’t forget to highlight the experience of your team and your solid reputation in the local market. Lenders love to see that you’ve been in the game for a while and have a loyal customer base.

We know how to navigate this process because we’ve seen every scenario over the last two decades. If you’re ready to get started, you can talk to us about your business goals today.

Why having an expert in your corner makes all the difference

Finance isn’t just a series of calculations performed by an algorithm. It’s a deeply human industry built on relationships, trust, and the art of negotiation. While working capital loans offer the immediate liquidity your business needs, the real value lies in how those funds are sourced and structured. A veteran broker acts as your steady hand, ensuring you don’t just get any loan, but the right one for your specific goals.

Lender appetite changes constantly. One month a bank might be eager to support retail businesses, and the next, they’ve reached their limit for that sector and tightened their criteria. We stay on top of these shifts so you don’t have to. We know which lenders are “hungry” for your type of business right now, which saves you from the frustration of multiple declines that can hurt your credit score.

Personalised service over “computer says no”

Krish Krishna brings over two decades of banking experience to your side of the table. This deep institutional knowledge means he understands the “inside track” of how credit committees think. When a computer algorithm says “no” because of a minor technicality, a dedicated negotiator knows how to reframe the conversation and speak the bank’s language to unlock doors that seemed shut. This personalised approach removes the stress from your shoulders, allowing you to focus on running your business while we handle the complex paperwork and follow-ups. You can see how this has made a difference for others by visiting our reviews page.

Planning for the long term

We view our clients as partners, not transactions. Your first working capital loans are often just the beginning of a long-term relationship. As your business matures and your needs change, we’re here to help you evolve your financial strategy. This might eventually lead to exploring a Commercial Property Refinance NZ to unlock equity for even larger projects.

Having a mentor who has seen every possible scenario gives you the confidence to make bold moves. We’re committed to your success over the long haul, acting as a bridge between the rigid world of traditional banking and your personal business needs. If you’re ready to see what’s possible for your Kiwi business, get in touch with the team at Mortgage Suite Ltd today.

Take the next step toward a stronger cash flow

Managing your daily finances doesn’t have to be a source of constant pressure. By now, you’ve seen how the right funding can bridge the gap between your hard work and your bank balance. Whether you’re navigating a seasonal dip or gearing up for a major expansion, working capital loans provide the liquidity needed to keep your business engine running smoothly without risking your personal savings. It’s about having the freedom to say “yes” to new opportunities when they arrive.

Success in business finance often comes down to who you have in your corner. With over 20 years of banking experience, we specialise in 2nd tier lending solutions that look at the big picture of your success rather than just a credit score. We provide national coverage for all New Zealand businesses, ensuring that even if the big banks have said no, you still have a clear path forward. Our role is to act as your dedicated negotiator, finding a repayment plan that fits your specific trading cycle.

Ready to secure the future of your Kiwi business? Talk to Krish and the team at Mortgage Suite Ltd about your business goals today. Let’s turn your growth plans into a reality with a professional partner you can trust.

Frequently Asked Questions

How much can I borrow for my business in New Zealand?

The amount you can borrow depends largely on your business turnover and the health of your monthly cash flow. Most lenders want to see that your repayments won’t put undue stress on your daily operations. While some unsecured options start small for minor repairs or stock, larger amounts usually require some form of security. We look at your specific trading history to find a limit that supports your growth without becoming a heavy burden.

Do I always need to use my house as security for a business loan?

You don’t always have to put your family home on the line to get funding. While mainstream banks often demand residential property as security, many alternative lenders offer unsecured working capital loans based on your business’s performance. You might also use business assets like vehicles or heavy machinery as collateral instead. This flexibility is a key reason why many Kiwi business owners are moving away from traditional bank branches toward more specialised 2nd tier lenders.

How fast can I get the money once I apply?

Speed is one of the biggest advantages of working with non-bank lenders. In many cases, you can have an answer within 24 to 48 hours of submitting your paperwork. If your documentation is organised and your plan is clear, the funds can often be in your account just a few days later. This is significantly faster than the weeks or months it can take to move through a traditional bank’s rigid committee process.

Can I get a working capital loan if I have bad credit?

Yes, a less-than-perfect credit score doesn’t have to be a deal-breaker for your business plans. While a big bank might give an automatic “no” for past credit hiccups, 2nd tier lenders are often more interested in your current cash flow and future potential. They look at the “big picture” of why those issues happened and how your business is performing today. We specialise in presenting these scenarios to lenders who value your industry experience over a computer score.

What is the difference between a business loan and a commercial mortgage?

The main difference is the length of the commitment and what the money is used for. A commercial mortgage is a long-term loan, often over 15 to 25 years, specifically for buying property. In contrast, working capital loans are shorter-term solutions designed to cover day-to-day costs like payroll or stock. They’re built for speed and flexibility rather than long-term property investment, helping you manage the natural peaks and troughs of your trading cycle.

How do repayments work for a seasonal business?

We can help you find a lender who understands that your income isn’t the same every month. Some specialised lenders offer flexible repayment structures where you pay more during your peak season and less during the quiet months. This prevents the stress of high repayments when cash flow is naturally lower. It’s all about matching the debt to your specific business cycle so the loan remains a helpful tool rather than a source of worry.

What happens if I want to pay the loan back early?

Many modern business loans are designed to be flexible, but it’s important to check the fine print for early repayment fees. Some lenders encourage you to pay back the debt as soon as your customers settle their invoices, while others might charge a small fee to cover their lost interest. We always look for options that give you the freedom to clear your balance early without being penalised, ensuring you only pay for the money while you actually need it.

Do I need a full business plan to get a small loan?

You don’t necessarily need a 50-page document to secure a small amount of funding. For most working capital loans, a simple one-page summary explaining how the money will be used and how it will help you grow is often enough. Lenders mainly want to see that you understand your numbers and have a clear strategy for repayment. We can help you pull this information together so it’s presented professionally to the right people.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Small Business Loan NZ: A Roundup of Funding Options for 2026

What if the reason your bank said “no” had nothing to do with your company’s potential and everything to do with their rigid, outdated tick-boxes? Many Kiwi business owners spend weeks wrestling with complex application forms only to be met with a cold, automated rejection because their financials look a bit “non-standard”. It is incredibly frustrating to feel like just another file in a giant system when you are trying to build a legacy. We understand that your business is more than just a balance sheet; it is the result of your hard work and passion.

Finding a small business loan NZ doesn’t have to be a source of constant stress. You deserve a flexible lender who acts as a partner rather than a gatekeeper, helping you secure growth funds without the sleepless nights. This article will help you understand the different types of funding available in the current market and how to choose the right fit for your company’s growth. We will break down the funding landscape for 2026, explore the practical differences between secured and unsecured options, and look at how personalised service can help you overcome the obstacles often found at larger institutions.

Key Takeaways

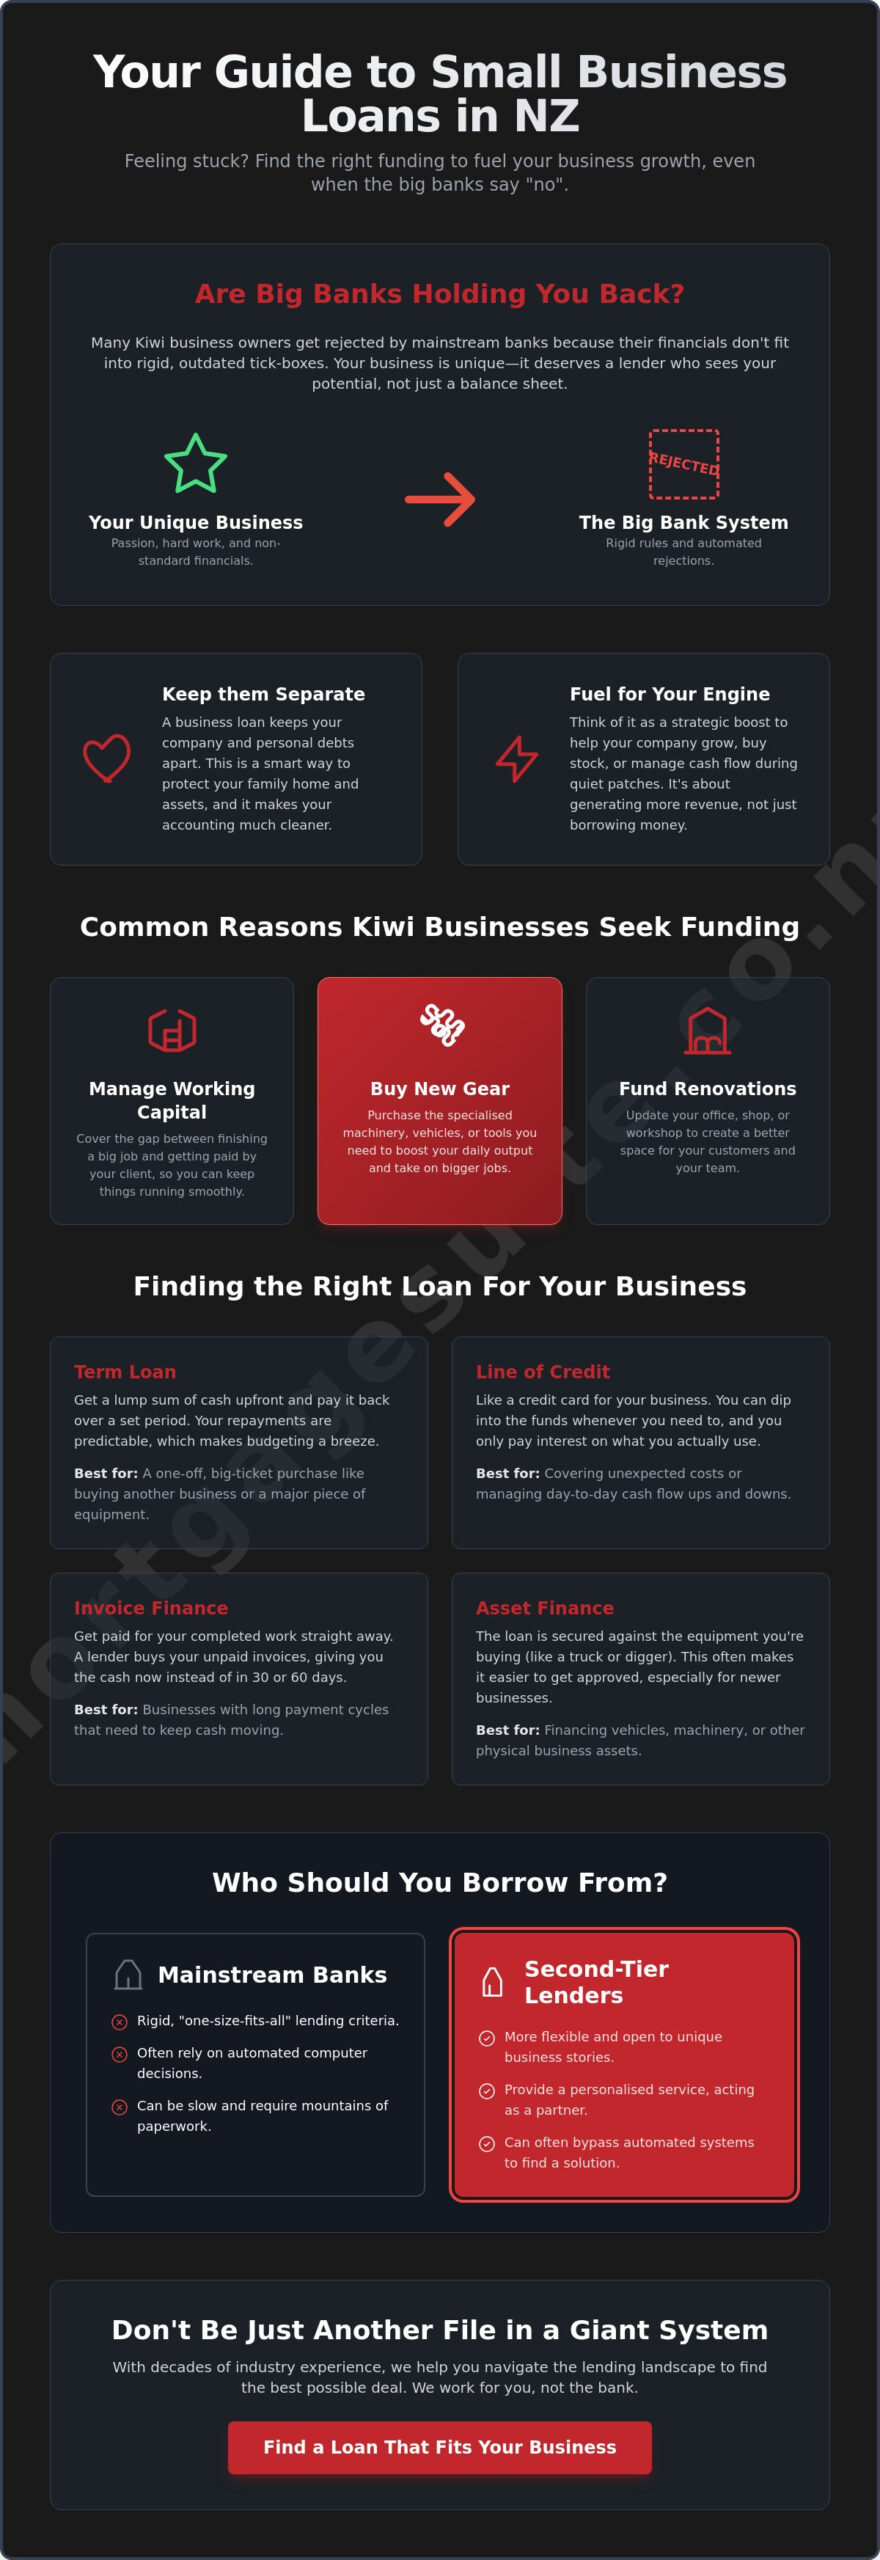
  • Understand how to use business finance as a strategic tool to fuel growth while keeping your personal and company debts separate.
  • Compare classic term loans with flexible lines of credit to find the right cash flow solution for your specific projects.
  • See why a small business loan NZ from a second-tier lender often provides the flexibility that mainstream banks lack for unique businesses.
  • Master the essential steps to get your financials organised and clearly explain how new funding will drive your future profits.
  • Learn how a personalised approach and decades of industry experience can help you bypass automated systems to secure the best possible deal.

What exactly is a small business loan in the NZ market?

In its simplest form, a small business loan NZ is a financial tool designed to help your company grow or stay steady during quiet patches. Think of it as a boost for your company’s engine. Unlike a personal loan used for a holiday or a new car, business-purpose borrowing is specifically about generating more revenue or improving your operations. It is the fuel that allows you to take on a bigger contract, buy bulk stock at a discount, or move into a larger warehouse before you have the full amount of cash sitting in your account.

Separating your personal debt from your business debt is a smart move for any owner. It helps protect your family assets and makes your yearly accounting much cleaner. We have noticed more Kiwi owners moving away from traditional bank overdrafts recently. This shift is happening because many big banks are tightening their lending rules or trimming overdraft limits without much warning. A structured loan often provides more certainty than an overdraft that could be reviewed or reduced at the bank’s whim. Whether you are dealing with a “feast or famine” cash flow cycle or just need to bridge a gap, the right loan provides a safety net that lets you focus on the work itself rather than worrying about the bank balance every morning.

Common reasons Kiwis seek business funding

  • Purchasing new vehicles or specialised machinery: Getting the right tools to increase your daily output or take on more technical jobs.
  • Funding renovations: Updating your office, retail shop, or workshop to create a better environment for your team and customers.
  • Managing working capital: Covering the gap between finishing a large project and actually getting paid by the client.

Asset finance vs. general business loans

There are several different types of business funding to consider depending on your specific needs. Asset finance is quite straightforward because the equipment you are buying, like a truck or a digger, usually acts as the security for the loan. If you are a newer business, asset finance is often easier to secure because the lender has a physical item to hold as a guarantee. This reduces their risk and can sometimes lead to better terms for you.

General-purpose business loans offer more flexibility. You can use these funds for things that don’t have a physical “serial number”, such as a new marketing campaign, hiring a key staff member, or launching a new service line. Because there is not always a physical asset involved, lenders will look more closely at your overall cash flow and business history. Choosing between these options depends on your long-term goals, but having a seasoned expert to help you weigh up the pros and cons ensures you don’t end up with a structure that hinders your future growth.

A roundup of business funding types available to you

Choosing the right small business loan NZ depends entirely on what you plan to do with the money. A classic term loan is often the best fit for a one-off, long-term project. You receive a lump sum upfront and pay it back over a set period, which makes your monthly budgeting very predictable. If you are looking to buy the building your business operates from, a commercial mortgage works in a similar way but over a much longer timeframe. Owning your premises can be a fantastic way to build equity rather than just paying off someone else’s mortgage. If you are considering this path, our step-by-step guide on how to buy commercial property loan NZ requirements and processes will walk you through exactly what to expect.

For day-to-day operations, you might consider a business line of credit or invoice finance. A line of credit lets you dip into funds only when you need them, meaning you only pay interest on what you actually use. Invoice finance is a bit different; it allows you to get paid early for work you have already finished by “selling” your unpaid invoices to a lender. This is a brilliant way to keep cash moving if your clients usually take 30 or 60 days to pay. Even government initiatives like the Small Business Cashflow Scheme have shown how specific, targeted funding can help Kiwis manage through unpredictable times. If you are unsure which path fits your current goals, talking to an expert about business loans can help clarify your options.

Choosing between secured and unsecured loans

The main trade-off here is between cost and speed. A secured loan usually requires you to pledge an asset, such as a property or a piece of heavy machinery, as a guarantee. Because this lowers the risk for the lender, you can often secure a much lower interest rate. For instance, while some specialist lenders might charge 14.99% or more for unsecured debt, a property-backed loan could be significantly cheaper. Unsecured loans are faster to get because there is no asset to value, but you will pay a premium for that convenience through higher rates and smaller borrowing limits.

The rise of flexible business facilities

Modern lending has moved beyond the clunky, old-fashioned bank overdraft. Many SMEs are now opting for flexible business facilities that allow you to pay down your balance and then “re-borrow” up to your limit whenever you need to. A business flexible facility acts as a safety net for cash flow, giving you peace of mind that funds are there if you need them. These facilities are replacing overdrafts because they often offer better terms and more transparency, helping you stay in control of your debt rather than feeling like the bank is in the driver’s seat.

Mainstream banks vs. 2nd tier lenders: Which is right for you?

When you start looking for a small business loan NZ, the local branch is usually the first stop. However, the experience can be a bit of a letdown for many owners. Big banks rely heavily on “tick-box” systems and automated platforms. If your business doesn’t fit their exact template, or if your financials have a few quirks because you’re self-employed, the computer often says no before a human even looks at your file. It is a rigid approach that doesn’t always account for the reality of running a company in 2026, especially when you need a lender who can see your potential rather than just your past tax returns.

This is where 2nd tier lenders come into play. These are specialised companies that take a more holistic, big-picture view of your situation. They don’t just look at a credit score; they look at your current contracts, your daily cash flow, and your future plans. Speed is another massive factor that sets them apart. While a mainstream bank might take weeks to process a single application, a non-bank lender can often give you an answer in a matter of days. If you have found a piece of equipment you need to buy immediately to finish a lucrative job, that speed is worth its weight in gold. Knowing when to use a bank for low-cost, slow-moving debt and when to look for alternative capital is a key skill for any growing business.

The benefits of 2nd tier lending solutions

They offer much more flexible criteria, which is a lifesaver for self-employed Kiwis who might not have two years of perfect tax returns ready to go. If your business has a shorter trading history, a 2nd tier lender is far more likely to listen to your story and look at your bank statements to understand your true earning power. You get a personalised assessment from a person who understands the local market, rather than just being a number in an automated bank queue.

Comparing the long-term costs

We often talk to clients who are worried about the cost of non-bank finance. It is true that 2nd tier lenders often charge a slightly higher interest rate than a mainstream bank. However, you have to weigh that cost against the opportunity of growth. A slightly higher rate is often worth the ease of access if it means you can secure a new contract or expand your team today. Many of our clients use this type of finance as a stepping stone; you use the funds to grow your turnover and prove your stability, which eventually makes you more attractive to a mainstream bank later on. For a deeper dive into these differences, you can read our guide on Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026.

Small Business Loan NZ: A Roundup of Funding Options for 2026

How to get your business “loan-ready” in 5 steps

Preparing for a small business loan NZ is a lot like getting a house ready for an auction. You want to make sure everything looks its best before the inspectors start poking around. It isn’t just about filling out a form; it’s about presenting a professional, reliable image of your company. The first and most vital step is to organise your financials. Ensure your Profit and Loss statement and balance sheet are completely up to date. Lenders need to see that you have a firm grip on your numbers. If your records are a bit of a muddle, it signals to the lender that your management might be too.

Next, you must know your “why”. You need to be able to explain, in plain English, exactly how the funds will generate a profit. If you’re borrowing to buy a new piece of specialised machinery, show them the extra revenue that machine will bring in each month. Lenders love a clear plan. While you’re at it, check your credit score. Many owners forget that lenders will often look at both your business and personal credit history. If there’s an old, unpaid utility bill from five years ago causing a blemish, it’s better to fix it now rather than being surprised during the application process. You should also identify what security you can offer, whether it’s the asset you’re buying or equity in a property, to help lower your interest rate.

Finally, don’t try to navigate this alone. Talking to an expert who understands the 2026 lending market can save you dozens of hours of legwork and help you avoid the common traps that lead to a “no”. If you want to put your best foot forward, you can get in touch about a business loan with a team that knows exactly what lenders are looking for.

The documents you’ll likely need

Most lenders now use secure digital links to view your last six months of bank statements, which saves you from printing out reams of paper. You’ll also need a clear, one-page summary of what the funds are for and proof of your business registration and GST status. Having these ready to go shows you’re serious and well-organised.

Common pitfalls to avoid

One of the biggest mistakes is “credit shopping” by applying to multiple lenders at once. Each application can leave a mark on your credit file, and too many at once makes you look like a high-risk borrower. Also, be careful not to underestimate how much you actually need. It’s often better to borrow a slightly larger amount once than to have to go back and ask for more a few months later. Lastly, always have a plan for how you’ll manage repayments during those inevitable quiet months.

Many business owners feel like they are shouting into a void when dealing with big bank call centres. An automated application might be efficient for the bank, but it rarely captures the nuance of your specific situation. Securing a small business loan NZ should be a collaborative process, not a cold transaction. Having a steady hand to guide you means having someone who knows how to frame your story so lenders see the opportunity rather than the risk. It is about moving away from the “computer says no” culture and towards a solution that actually supports your goals.

With 20 years of banking experience, our team has seen how the internal gears of lending institutions turn. We know the questions they will ask before they even ask them. This deep institutional knowledge allows us to act as your dedicated advocate, negotiating terms that a standard application would never uncover. We don’t just look for any loan; we look for the one that fits your business lifecycle. Whether you are a tradie needing a new vehicle or a company looking for complex funding, we bridge the gap between the rigid world of banking and your personal needs as a borrower.

The Mortgage Suite difference for business owners

It starts with personal mentorship from Krish Krishna and the team. We don’t just process files; we provide a consultative experience that helps you understand your options clearly. We specialise in both residential and commercial property-backed business loans, which often provide the most cost-effective way to fund growth. By using equity in your home or premises, we can often unlock better rates than standalone business debt. Our focus is always on the long-term relationship. We want to see your business thrive year after year, which is why we prioritise your success over just closing a one-off transaction.

Taking the next step for your business

The path to growth doesn’t have to be paved with endless paperwork and stress. A quick conversation is often all it takes to clarify which funding option is best for your current stage. We handle the heavy lifting, from the initial negotiations to the final signatures, so you can stay focused on running your company. Having a professional handle the legwork ensures you don’t miss out on better terms simply because you didn’t have time to shop around. If you are ready to explore what is possible, reach out for a no-obligation chat about your goals. We are here to help you find a way forward that feels right for you and your future.

Empowering your business for the years ahead

We have explored how the right funding acts as a powerful catalyst for growth, whether you are choosing between secured debt or understanding why 2nd tier lenders offer the flexibility mainstream banks lack. Getting your company “loan-ready” by organising your financials and knowing your “why” is the most effective way to secure the capital you need to scale. By understanding the full range of options available in 2026, you can make a decision that supports your cash flow rather than hindering it.

Navigating the search for a small business loan NZ doesn’t have to be a solo mission or a source of stress. With over 20 years of banking and brokerage experience, our team at Mortgage Suite Ltd specialises in finding creative solutions for businesses that big institutions often decline. We provide a highly personalised, jargon-free service that treats you like a partner rather than just another application number. Let’s find the right business loan for your next big move and ensure your company has the steady financial support it deserves. You have already done the hard work of building your business; now let us help you secure its future growth with confidence.

Frequently Asked Questions

What is the maximum amount I can borrow for a small business loan in NZ?

The maximum you can borrow for a small business loan NZ typically reaches up to $500,000 with many specialist lenders. Some providers offer smaller amounts starting from $2,000 to cover minor expenses. Your specific limit depends on your company’s turnover, how long you have been trading, and whether you are providing any assets as security for the debt.

Do I need to provide security like my home for a business loan?

You don’t always need to use your family home as security for a business loan. Many lenders offer unsecured options that rely on your business’s cash flow instead of physical assets. However, if you do choose to use property as a guarantee, you will often be rewarded with a lower interest rate and a higher borrowing limit because the lender’s risk is lower.

How long does the application process usually take for a non-bank loan?

Non-bank lenders usually move much faster than traditional institutions, often providing an initial decision within 24 to 48 hours. If your paperwork is organised and you use digital bank statement links, the funds can sometimes be in your account within a single business day. This speed is a massive help when you need to jump on a time-sensitive opportunity or fix a cash flow gap.

Can I get a business loan if I have only been trading for six months?

Yes, you can certainly find funding even if you have only been trading for six months. While mainstream banks often want to see two years of perfect tax returns, 2nd tier lenders are more interested in your recent bank statements and growth potential. You might find that an unsecured small business loan NZ is a more accessible option at this early stage of your journey.

What is the difference between a secured and an unsecured business loan?

The main difference is what happens if you can’t make your repayments. A secured loan is backed by a physical asset, like a truck or a property, which the lender can take if things go wrong. Because this is lower risk for them, the interest rates are usually cheaper. Unsecured loans don’t require assets but come with higher rates to cover the lender’s extra risk.

How do interest rates for business loans compare to home loan rates?

Interest rates for business loans are almost always higher than home loan rates because the risk to the lender is greater. For example, while a home-backed business rate might sit around 6% to 10%, an unsecured loan from a specialist lender could start at 14.99% and go higher. It’s a trade-off for the speed and flexibility you receive when you don’t fit the standard bank criteria.

Can I use a business loan to pay off tax debt or existing creditors?

Yes, using a business loan to clear tax debt or pay off urgent creditors is a common strategy to get a company back on track. Many 2nd tier lenders are happy to help with debt consolidation if it means your daily cash flow will improve. It’s often better to have one manageable loan repayment than several stressful debts hanging over your head while you’re trying to grow.

Will a business loan application affect my personal credit score?

Applying for a business loan will usually show up on your personal credit report. Most lenders perform a thorough check of your credit history as part of their assessment process. It’s a good idea to avoid applying to several different lenders at once. Too many enquiries in a short space of time can lower your score and make you look like a higher risk to potential lenders.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.