Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

You’ve spent months scouring listings and finally found a place to call your own, only for your bank to decline your application because your income isn’t “traditional” or your deposit is a bit light. It feels like a total dead end, but a “no” from a mainstream bank is often just the start of a different conversation. Many people assume that non bank lenders nz home loans are a last resort for those in financial trouble, but in 2026, they’ve become a tactical tool for savvy Kiwis who simply don’t fit a rigid, standard box.

It’s completely normal to feel a bit nervous about looking beyond the big household names, especially if you’re worried about higher interest rates or confusing terms. We understand that you want a clear path to home ownership without the stress of being treated like a number. This guide is designed to strip away the mystery and show you exactly how these alternatives work, providing a steady hand to help you reach your goals.

We’ll explore how these lenders look at your whole story, explain the real difference in costs following the recent OCR shifts, and help you decide if this is the right stepping stone for your future. You’ll gain the confidence to move forward with a plan that actually fits your life.

Key Takeaways

  • Learn how to move past a bank rejection by finding lenders that look at your whole financial picture rather than just a computer-generated score.
  • Understand the actual costs of non bank lenders nz home loans and why paying a bit more now can be a smart move to secure your future home.
  • Discover how these flexible options specifically help self-employed Kiwis and first-home buyers who don’t fit the standard bank boxes.
  • Find out how working with a dedicated negotiator ensures you get a fair deal and a clear plan to eventually move back to a mainstream bank.

What exactly are non-bank lenders in the NZ home loan market?

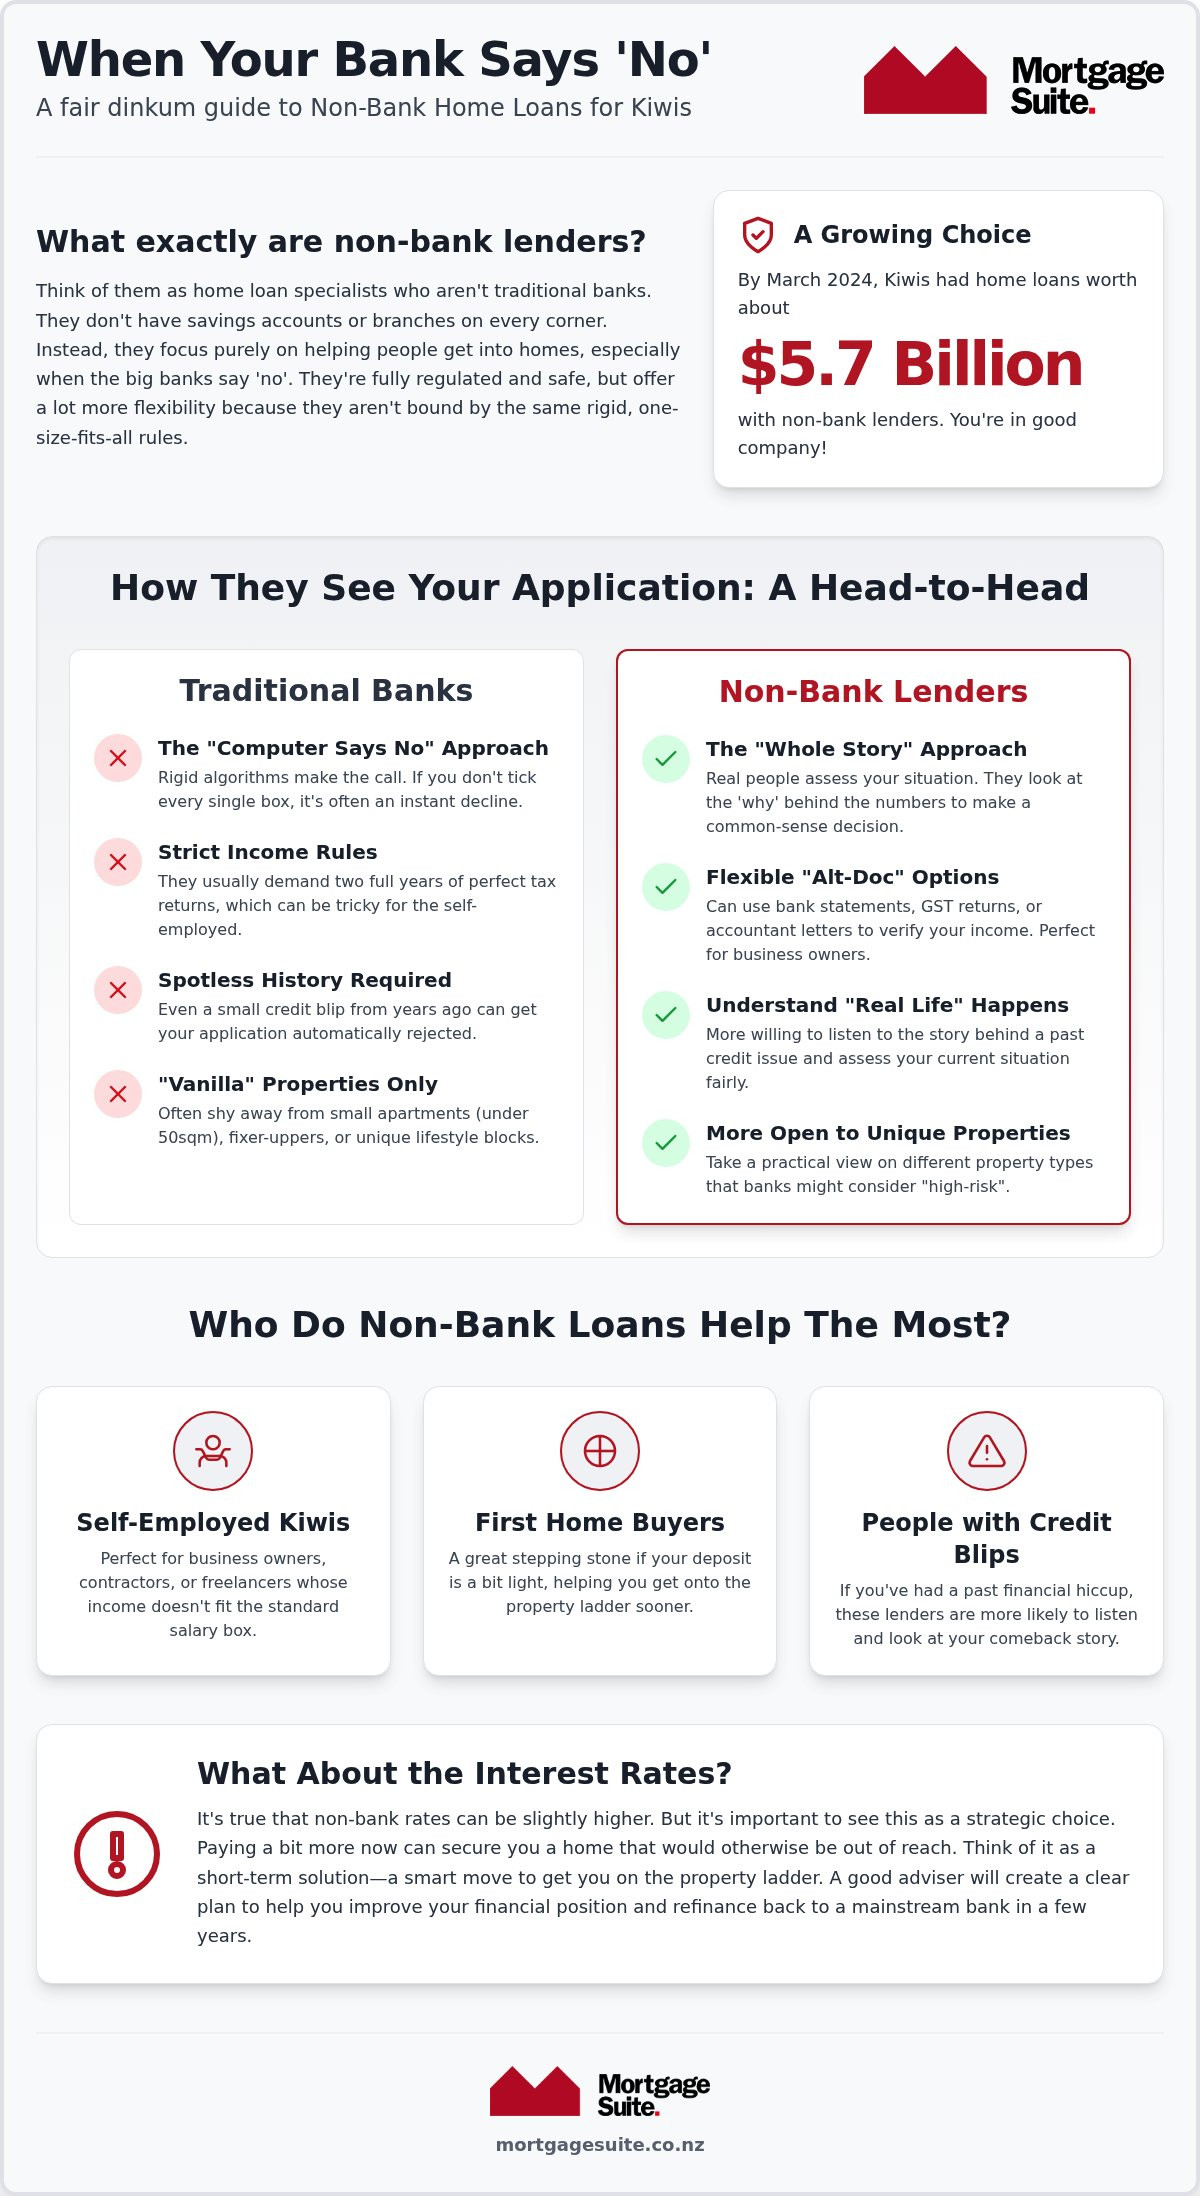
If you’ve ever felt like just another number at a big bank, non-bank lenders might be the breath of fresh air you need. Simply put, these are companies that provide home loans but don’t hold a traditional banking licence. They are a specific type of non-bank financial institution that focuses on getting people into homes when the traditional path is blocked. By March 2024, lending from these institutions in New Zealand reached about $5.7 billion, showing just how many Kiwis are choosing this path.

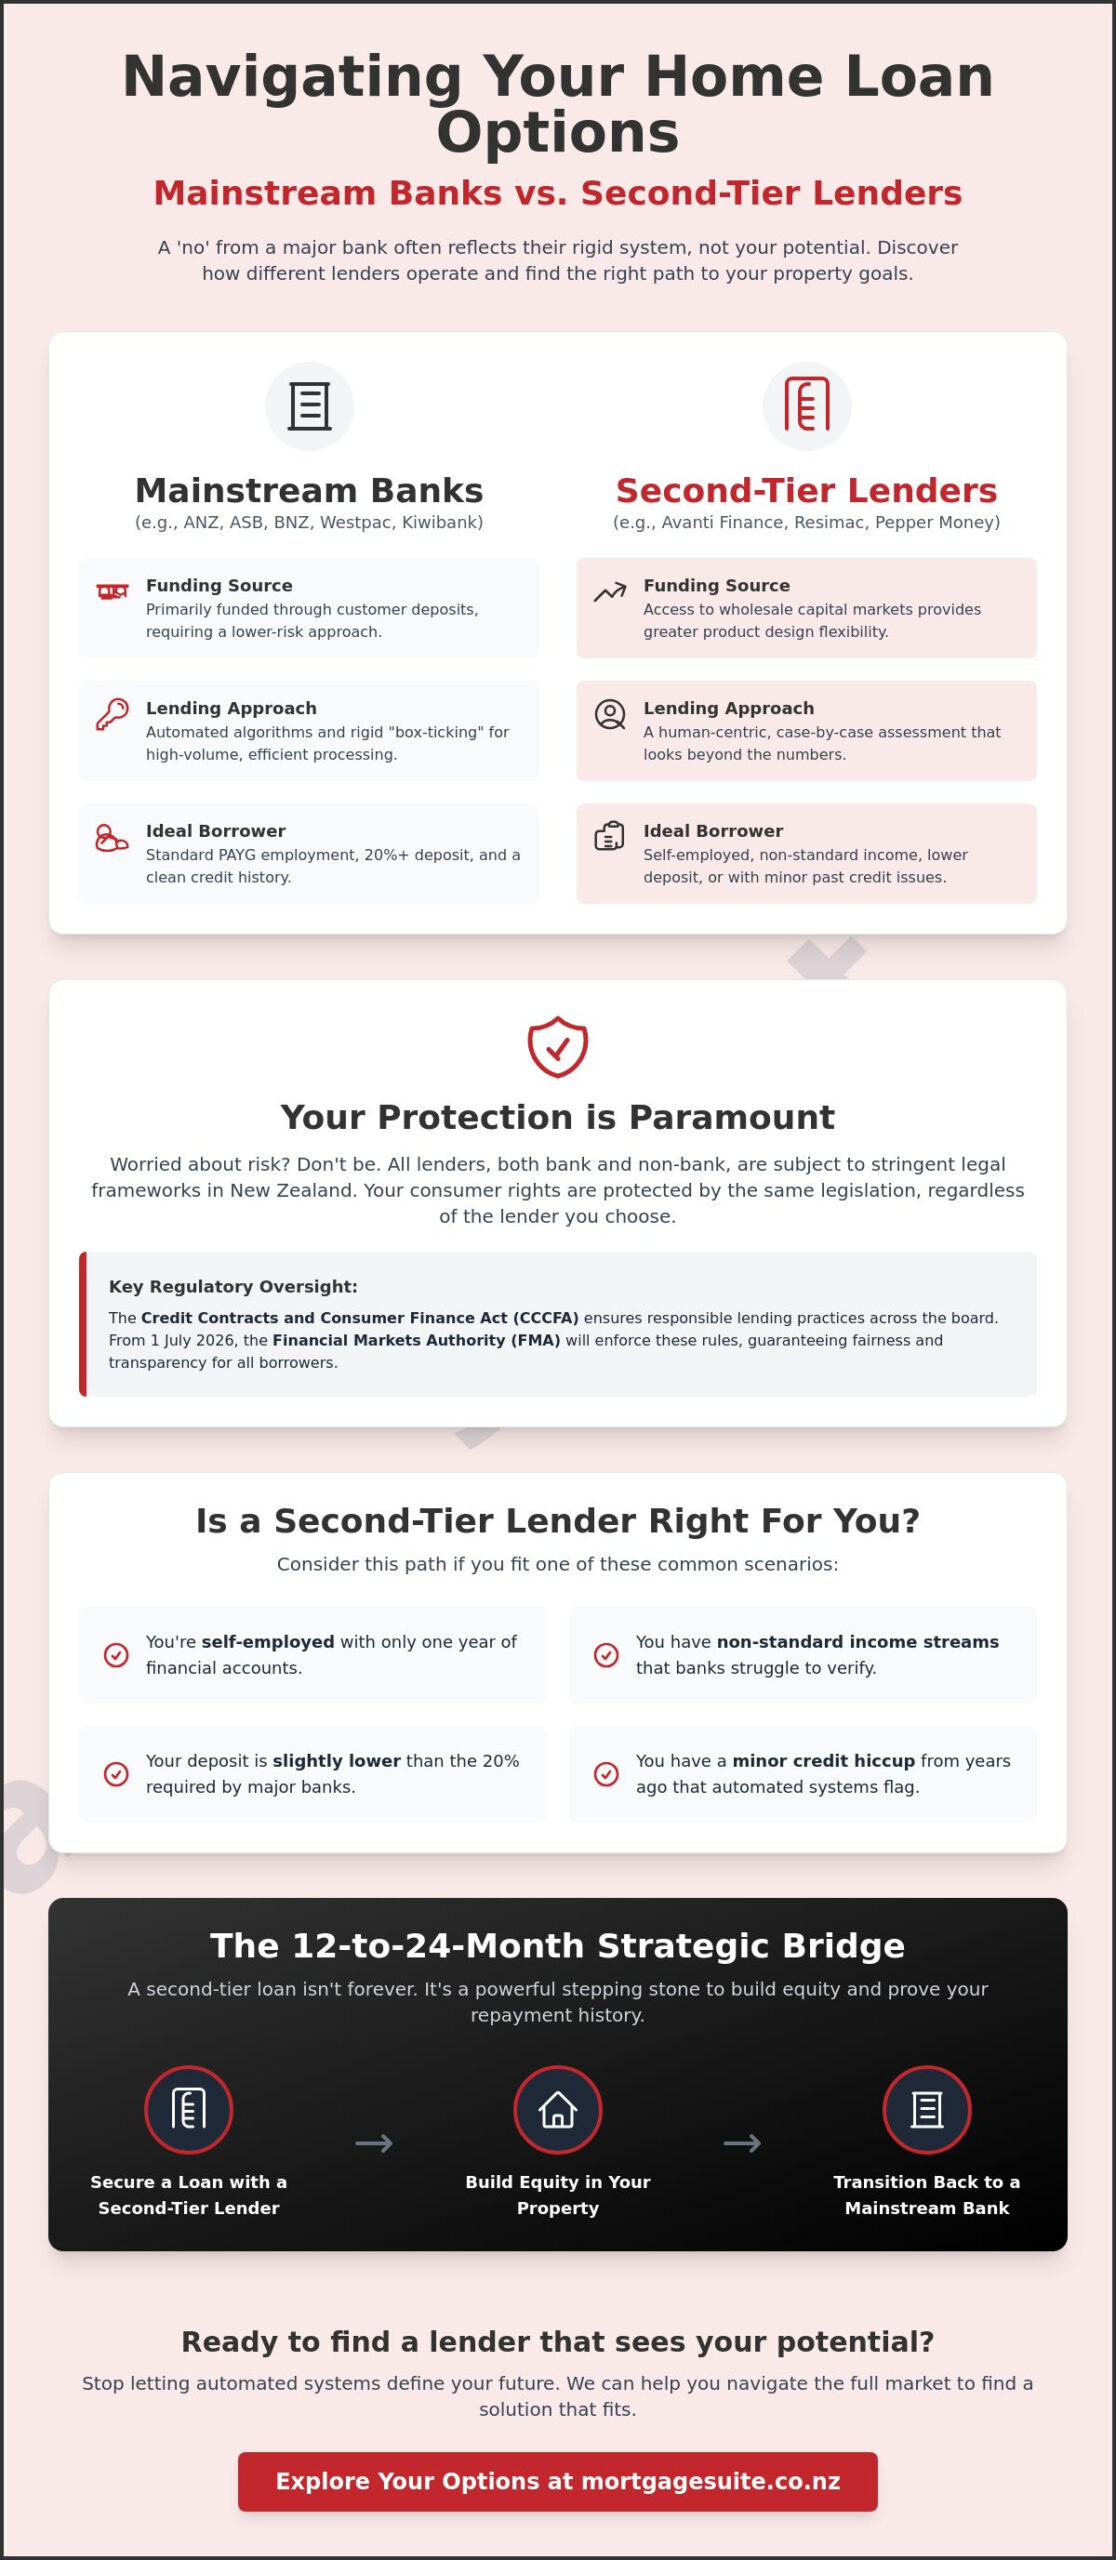
Unlike the big banks that use the money in your savings account to lend to others, these lenders get their funds from private investors or larger wholesale markets. This is a major reason why non bank lenders nz home loans offer more flexibility. They aren’t tied to the same rigid rules that govern how banks must handle your neighbour’s term deposit. You might hear people call them second tier lenders. Don’t let that label fool you into thinking they are second best. It’s just a way to categorise them outside the Big Four. They’re often more agile and more willing to listen to your specific story.

The difference between a bank and a non-bank

Most Kiwis are used to the Big Four banks. They have branches on every corner and huge advertising budgets. But they also have very narrow boxes for who they will lend to. Alternative lenders don’t have those massive overheads or the same one size fits all mentality. While they aren’t registered banks, they are still strictly regulated. They must follow the Credit Contracts and Consumer Finance Act, which ensures they are responsible and safe. The real difference is their flexibility. They look at the person behind the application, not just the checkboxes on a form.

Why non-banks are a fair dinkum option for Kiwis

The biggest hurdle for many home buyers is the “computer says no” moment. If you’re self-employed or have a small credit blip from years ago, a bank might reject you instantly. Non-banks are a fair dinkum choice because they use actual humans to assess your application. They’ve helped thousands of families get sorted when the big guys turned them away. With dozens of different lenders in the NZ market today, there’s a huge variety of options. If you want to learn more about how these rules work behind the scenes, our Mortgage School is a great place to start. It’s all about finding the right partner for your journey.

Why the big banks might say no (and why non-banks say yes)

Mainstream banks love what we call “vanilla” applications. If you have a steady salary, a spotless credit history, and a 20% deposit, you are their dream client. But for many Kiwis, life isn’t always that tidy. Banks rely on rigid algorithms to make decisions. If your situation doesn’t tick every single box, the computer simply spits out a decline. This is where Canstar explains non-bank mortgage lending as a vital alternative, because these lenders use human common sense rather than just a software programme.

Common reasons for a bank decline include small credit blips from years ago, having a deposit under 20%, or trying to buy a property that doesn’t meet their strict criteria. Non-bank lenders nz home loans work differently because they look at the whole story. They want to understand why a hurdle exists and what your plan is to move past it. As your broker, my job is to act as a dedicated negotiator. I know which lenders are comfortable with certain “problems” and how to present your case so it gets a “yes” instead of a flat rejection.

Self-employed and “outside the box” income

Business owners and contractors often struggle with traditional banks because their income can fluctuate. A bank usually demands two full years of perfect tax returns, which isn’t always helpful if you’ve just had a growth year or recently started out. Non-banks offer “alt-doc” options, which means they can verify your income using GST returns or bank statements instead of just tax summaries. If you’re navigating this path, our Self Employed Home Loan Guide offers deeper insights into how to prepare your application for success.

Property types that banks often shy away from

Sometimes it isn’t you; it’s the house. Banks often refuse to lend on small apartments under 40 or 50 square metres, lifestyle blocks with unusual zoning, or “fixer-uppers” that need significant work. They see these as high-risk assets. Non-bank lenders nz home loans take a more practical view of property value and risk. They specialise in the unique corners of the New Zealand market, seeing the potential in a property where a bank only sees a liability. If you’ve found a unique spot that the big banks won’t touch, it’s worth having a chat to get to know our team and see how we can help you secure it.

The real cost: Interest rates, fees, and your budget

Let’s be direct about the numbers. You’ll likely pay more for a non-bank loan than you would at a big bank. It’s a trade-off. By choosing a lender that looks at your whole story, you might pay a slightly higher interest rate, but you’re actually getting into the property market instead of watching prices climb from the sidelines. Most people use non bank lenders nz home loans as a tactical stepping stone. You stay for one or two years, tidy up your credit or build your business history, and then move back to a mainstream bank once you fit their box.

Fees are another area where things differ. While a bank might waive an application fee, non-banks usually charge an establishment fee to cover the manual work of assessing a complex file. In the current 2026 market, these typically range between $2,000 and $5,000. You might also see small monthly admin fees around $10 to $13. It’s about looking at the total cost of the “bridge” to get you to your goal rather than just the sticker price.

Comparing interest rates: Bank vs. Non-bank

The gap between a bank rate and a non-bank rate is often called the margin. Usually, near-prime rates sit about 1% to 2% higher than what the big banks offer. With the Official Cash Rate sitting at 2.75% as of September 2026, near-prime rates often start around 6.35%. It’s vital to see how this looks in real dollars. You can use our mortgage calculator to compare different scenarios. Remember, the “cheapest” rate isn’t always the best deal if the lender won’t actually give you the money.

Managing the extra cost in your weekly budget

A higher rate doesn’t have to break your budget if you plan correctly. We often suggest structuring your loan with a focus on flexibility, allowing you to make extra payments when possible. This helps you build equity faster so you can refinance sooner. Getting into a home now, even at a higher rate, can often save you more in the long run than waiting years to save a massive deposit while house prices potentially increase. It’s about looking at the big picture of your financial success and long-term security.
Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

Common situations where non-bank home loans shine

While mainstream banks often wait for a perfect set of circumstances, non bank lenders nz home loans are built for the reality of life in New Zealand. They shine brightest when you need a solution that looks at your future potential rather than just your past paperwork. For many, these lenders provide a strategic way to move forward when the traditional path is blocked by rigid rules or timing issues.

There are several specific scenarios where these alternative options become the best tool for the job:

  • Low deposit hurdles: If you have a deposit under 20% and don’t qualify for specific government grants, non-banks can often bridge that gap.
  • New business owners: If you’ve been self-employed for less than two years, a bank will likely turn you away. Non-banks are often happy to help once you have a few months of solid trading under your belt.
  • Past credit hiccups: A single missed payment or an old default can stay on your record for years. Non-bank lenders focus on your current ability to pay rather than a mistake from the past.
  • Growing property portfolios: Investors often hit a wall with banks due to strict rules on how much they can borrow compared to their income. Non-banks don’t have to follow the same Reserve Bank limits, allowing for more growth.

Bridging the gap for first-home buyers

Getting on the property ladder is often a race against time. If you wait another two years to save a larger deposit, house prices might have climbed even further, leaving you in the same position. By using a non-bank, you can secure a property now with a smaller deposit. This allows you to start building equity in your own home rather than paying off someone else’s mortgage. Our guide on Home Loans for First Home Buyers NZ explains how to navigate these rules to your advantage.

Credit repair and moving forward

A non-bank loan is often the best way to prove to the wider market that you are a reliable borrower. By making every payment on time for 12 to 24 months, you actively repair your credit profile. This creates a clear track record that eventually makes you very attractive to mainstream banks. Think of it as a transition period where you get the house you want while tidying up your financial history. Once your situation is sorted, we can help you move back to a bank with a lower rate. See how we’ve helped other Kiwis make this exact transition and find their way to financial success.

How to find the right non-bank lender for your goals

Applying for a mortgage shouldn’t feel like a guessing game. It is tempting to jump online and send applications to every lender you find, but this can actually backfire. Every time a lender checks your credit, it leaves a footprint. Too many footprints in a short time can make you look desperate to other lenders. The trick isn’t to apply more; it is to apply smarter. Working with a specialist who understands the landscape of non bank lenders nz home loans means you only apply to the ones most likely to say yes.

A specialist broker acts as your dedicated negotiator. Because I have spent over 20 years on the inside of the banking world, I know exactly what these lenders are looking for. We do the heavy lifting by comparing different non bank lenders nz home loans to find the one that fits your specific story. This saves you time and protects your credit score from unnecessary dings. We handle the paperwork and the talking, so you can focus on finding the right house.

One thing many people forget to check is the fine print. You need to look at more than just the interest rate. Are there penalties for paying the loan off early? How much are the ongoing admin fees? Most importantly, you need a clear exit strategy from day one. We don’t view a non-bank loan as a forever home for your debt. It is a bridge. We help you map out exactly what needs to happen so you can refinance back to a mainstream bank in 12 to 24 months. This might involve tidying up spending habits or building a longer history of business income.

The Mortgage Suite advantage

When you work with us, you are getting more than just a middleman. You are getting a partner with deep institutional knowledge. Krish Krishna’s 20 years of banking experience means he knows the rules, the shortcuts, and the people who make the decisions. We have established relationships with a wide range of 2nd tier lenders across New Zealand, giving you options that you simply won’t find on your own. You can read more about our philosophy and how we prioritise your success over just closing a deal.

Your next steps to getting sorted

Getting started is simpler than you might think. Your first job is to gather your paperwork. Having your bank statements and proof of income ready to go makes a massive difference in how a lender views your application. It shows you are organised and serious. Once you have your bits and pieces together, the next step is to book a chat. We will sit down, listen to your story, and figure out a path forward together. If you are still feeling a bit unsure, read our client reviews to see how we have helped other Kiwis move from a bank rejection to home ownership.

Take the next step toward your new home

A “no” from a big bank doesn’t have to be the end of your property dreams. Non bank lenders nz home loans offer a flexible and fair dinkum alternative for Kiwis who don’t fit into a standard box. Whether you have a unique income or a past credit hurdle, these options provide a reliable bridge to financial success. By focusing on a clear exit strategy from day one, you can secure your home now and move back to a mainstream bank when the time is right.

With over 20 years of banking and brokerage experience, we specialise in navigating the inside rules to get you sorted. We’re proud to help families nationwide find a steady hand in a shifting market. You don’t have to guess your way through the process alone. Our team is here to act as your dedicated negotiator, ensuring you get a fair deal that actually works for your budget.

Book a free, no-obligation chat with Krish to see your options. It’s time to stop worrying about the paperwork and start planning your move. We’re ready to help you turn that “no” into a “yes”.

Frequently Asked Questions

Are non-bank lenders safe in New Zealand?

Yes, non-bank lenders are safe and must follow the same responsible lending laws as major banks. They are strictly regulated under the Credit Contracts and Consumer Finance Act, which ensures they treat you fairly and don’t lend more than you can afford to repay. While they aren’t registered banks, they are professional financial companies that help thousands of Kiwis. Choosing non bank lenders nz home loans is a secure way to enter the market.

Will I pay much higher interest rates with a non-bank lender?

You’ll generally pay a slightly higher rate, often around 1% to 2% above what a mainstream bank offers. This is because these lenders take on more risk by helping people who don’t fit the standard criteria. However, many borrowers find this extra cost is worth it to secure a home today rather than waiting years to save a larger deposit while house prices potentially climb even further. It’s about the long-term gain.

Can I move back to a main bank later on?

Absolutely, and that is usually the main goal for our clients. Most people use a non-bank loan as a temporary stepping stone for 12 to 24 months. During this time, you can tidy up your credit history or build a longer record of business income. Once your situation meets the big banks’ criteria, we can help you refinance to a lower rate. We build this exit strategy into your plan from the start.

Do non-bank lenders require a bigger deposit?

Not always. While big banks often demand a 20% deposit, non-bank lenders can be much more flexible. They aren’t always tied to the same strict speed limits set by the Reserve Bank regarding low-deposit lending. This means they might accept a smaller deposit if the rest of your application is strong and your income is stable. Every lender has different rules, so we look at your specific situation to find the best match.

How long does it take to get a non-bank home loan approved?

Approval times can often be faster than at a major bank because non-bank lenders are typically smaller and more agile. While a big bank might take weeks to process a complex file, an alternative lender can often give an answer within a few working days. Having your paperwork, like bank statements and proof of income, ready to go from the start will help speed up the process even more and keep things moving quickly.

Can I get a non-bank loan if I am self-employed with only one year of accounts?

Yes, this is a situation where non bank lenders nz home loans really shine. Most mainstream banks demand at least two full years of tax returns, but alternative lenders offer “alt-doc” options. They can use other evidence, such as GST returns or recent bank statements, to verify your income. This is a huge help for new business owners who are making good money but haven’t been trading long enough for a traditional bank.

Are there extra fees involved with non-bank home loans?

There are typically some extra costs, such as an establishment fee, which covers the manual work of assessing a non-standard application. These often range between $2,000 and $5,000 depending on the lender. You might also see small monthly admin fees of around $10 to $13. While these are higher than at a bank, they are often a small price to pay for the flexibility that gets you into your own home years sooner than waiting.

What happens if my credit history isn’t perfect?

Non-bank lenders focus on your whole story rather than just a computer-generated credit score. If you had a credit blip a few years ago due to a missed bill or a specific life event, they are often willing to listen to the explanation. They want to see that you are back on track and can comfortably afford the repayments today. This human approach is why many Kiwis with imperfect histories still find success.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Working Capital Loans NZ: Your 2026 Guide to Boosting Business Cash Flow

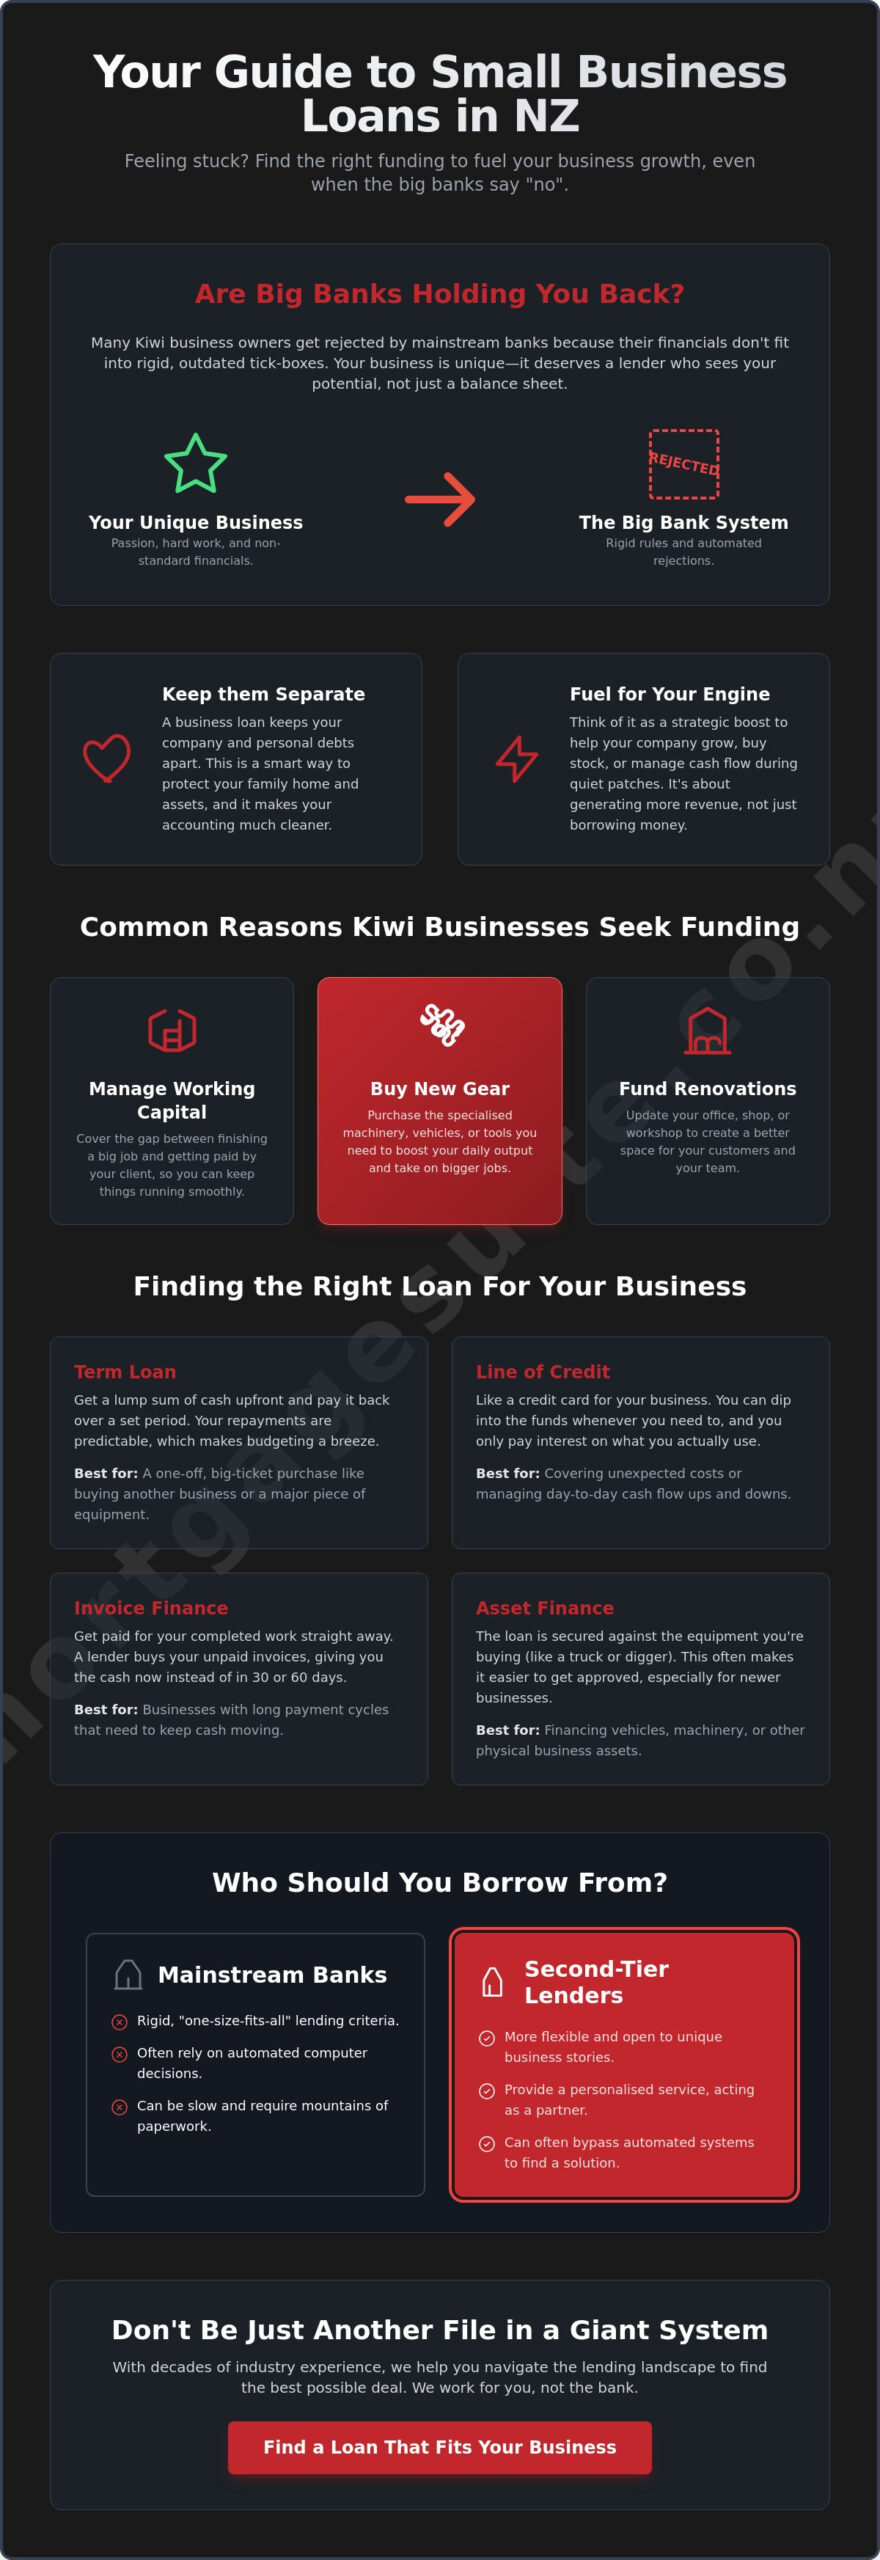
Imagine it’s Friday afternoon and you’re staring at a stack of unpaid invoices while the clock ticks down toward your staff’s payday. You’ve been waiting over 60 days for a major client to settle their account, and your local bank branch just gave you a cold “no” because you don’t fit their rigid rules. It’s a frustrating spot to be in, but you aren’t alone. Most Kiwi business owners know that feeling of having a healthy order book but a temporary gap in the bank account. This is where working capital loans become the essential fuel for your business engine, providing the cash you need to keep things moving while you wait for those payments to land.

We understand that you need a partner who looks at your industry expertise rather than just a spreadsheet. In this 2026 guide, you’ll learn how to bridge the gap between your mounting bills and your future growth with the right financial solution. We’ll explore how to access fast cash that respects your specific trading cycle and why 2nd tier lenders might be the breakthrough your business deserves. From managing seasonal dips to seizing sudden opportunities, we’re going to show you how to take the stress out of your cash flow for good.

Key Takeaways

  • Learn how working capital loans act as a bridge between your outgoing bills and the time it takes for customers to settle their invoices.
  • Discover whether a flexible safety net you can dip into or a one-off lump sum of cash is the better fit for your specific business cycle.
  • Understand why a “no” from a mainstream bank doesn’t mean your plans are over, especially when exploring 2nd tier lending options for Kiwi businesses.
  • Learn how to organise your financial numbers to create a solid plan that gives lenders the confidence to back your vision.
  • Find out how having a seasoned negotiator in your corner helps you connect with lenders who’re actively looking to support businesses like yours.

What exactly is a working capital loan and how does it help your business?

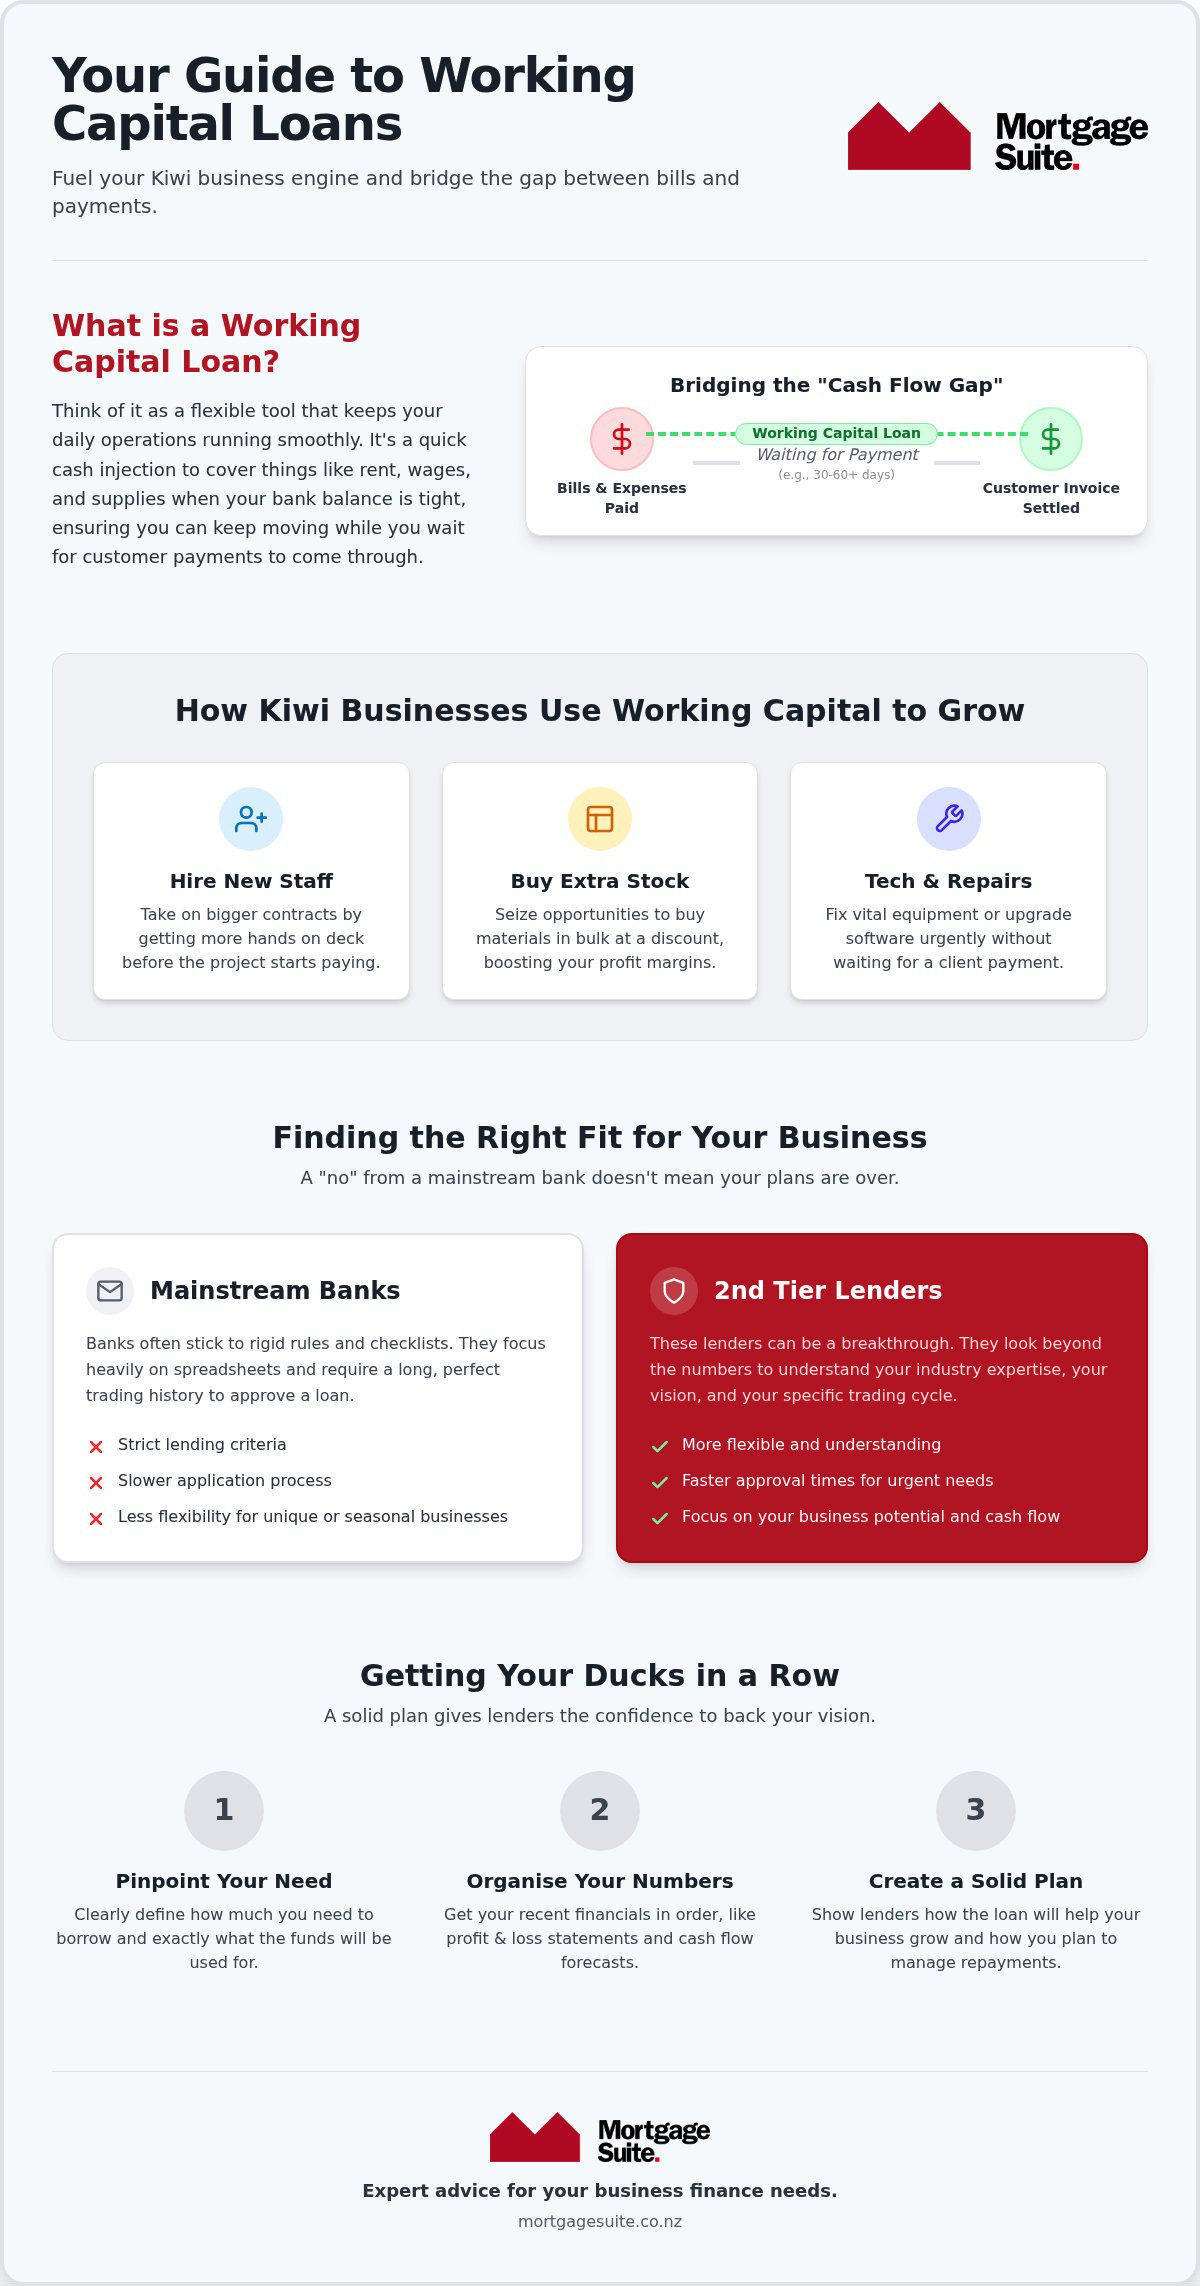
Think of a working capital loan as a flexible tool that keeps your daily operations running smoothly. Unlike a mortgage paid over decades, these are designed for the here and now. They provide a quick injection of ready cash to cover things like rent, utilities, and payroll when your bank balance isn’t quite matching your current workload. It’s a professional way to keep the engine running without having to dip into your own back pocket or use the family’s personal savings.

The primary purpose of working capital loans is to bridge the timing difference between your outgoings and your income. In a perfect world, every customer would pay the moment you finish a job. In the real world, you’re often paying for materials and labour weeks before the final invoice is settled. This finance acts as a safety net, ensuring you can meet your obligations today while waiting for the rewards of your hard work tomorrow.

The “Cash Flow Gap”: Why even healthy businesses need extra funds

It’s a common myth that only struggling businesses need extra help. In reality, some of the fastest-growing companies in New Zealand face the tightest cash flow. This happens because high growth requires upfront investment. You might have a massive pipeline of work lined up, but if you don’t have the cash to buy the supplies or pay the team, that growth stalls. Having a lot of work on doesn’t always mean you have a lot of cash in the bank.

New Zealand’s unique market also plays a role. Many Kiwi industries are seasonal, such as a retail shop in a tourist town or a landscaping crew during a wet winter. During these quiet patches, your fixed costs don’t go away. Working capital loans allow you to maintain your momentum during slow months so you’re ready to hit the ground running when the busy season returns. It prevents your next big project from stalling just because you’re waiting on a large client to pay.

Common ways Kiwis use working capital to grow

Having access to available funds isn’t just about survival; it’s about being proactive and seizing opportunities. Here are a few ways local businesses use this funding to get ahead:

  • Hiring new staff: Taking on a new contract often means you need more hands on deck before that contract starts paying.
  • Buying extra stock at a discount: If a supplier offers a significant discount for a large order, having the cash to buy upfront can boost your profit margins.
  • Technology and repairs: If a vital piece of equipment breaks or your software needs an urgent upgrade, you can’t always wait for a client payment to fix it.

Exploring the different ways to fund your day-to-day operations

Choosing the right way to fund your business is a bit like picking the right vehicle for a trip. You wouldn’t take a heavy truck for a quick run to the shops, and you wouldn’t use a small car to move a house. In the world of business finance, the structure you choose matters just as much as the amount you borrow. Working capital loans come in various shapes, and the best fit depends entirely on whether you need a permanent safety net or a one-off boost.

One of the first decisions you’ll face is whether to go with a secured or unsecured option. A secured loan uses an asset, such as a property, as a guarantee for the lender. This often results in more competitive terms because the risk is lower for the bank. Unsecured loans don’t require that same security, which can make the application process faster, though lenders will look much more closely at your trading history and cash flow to ensure you’re a safe bet.

Repayment terms also play a huge role in your daily stress levels. A shorter loan term might mean higher weekly repayments, but you’ll pay far less in interest over the life of the loan. Spreading the cost over a longer period keeps your weekly outgoings lower, which is often easier on the budget during the early stages of a growth push. It’s all about finding that sweet spot where the debt feels manageable within your normal trading cycle.

Business Overdrafts and Lines of Credit

A business overdraft is the ultimate “just in case” fund. It sits quietly in the background of your business bank account, ready for those moments when a bill arrives before a customer payment does. The best part is that you only pay interest on the money you actually use. If you have a limit of NZ$20,000 but only spend NZ$2,000 to cover a quiet week, you aren’t paying for the other NZ$18,000. It’s a perfect way to manage the natural ups and downs of a standard trading month without any fuss.

Term Loans for specific business goals

When you have a specific goal in mind, a term loan is usually the better path. This provides a lump sum of cash upfront, which you then pay back over a fixed period. It’s the ideal choice for one-off costs like launching a new website, funding a major marketing push, or upgrading essential equipment. Because the repayments are fixed, you can plan your budget with total certainty. We often help clients structure these repayments to match their specific business income, ensuring the debt supports your growth rather than hindering it. If you want to see how we’ve helped others navigate these choices, you can read more about our approach to business lending.

Working capital loans shouldn’t be a burden. By choosing the right structure, you ensure that the extra funds act as a springboard for your Kiwi business rather than just another bill to worry about.

Mainstream banks vs. 2nd tier lenders: Finding the right fit

Many Kiwi business owners walk into their local branch expecting a partnership and walk out feeling like just another number on a spreadsheet. The big banks have rigid, “cookie-cutter” rules that don’t always cater to the unique reality of running a business in 2026. If your situation doesn’t fit their exact mould, they’re often quick to shut the door. This can be incredibly disheartening, but it’s important to remember that a bank’s “no” is usually about their own internal policy, not the quality of your business.

The main difference lies in how a lender views risk. Mainstream banks are built for stability and high-volume, low-risk lending. They prefer businesses that look exactly like the one they funded yesterday. When you’re looking for working capital loans, you need someone who sees the potential in your future contracts and your industry expertise, rather than just staring at your past tax returns. Alternative lenders fill this gap by looking at the big picture of your business health.

When the big banks say “no”

Banks usually want to see at least two years of perfect trading history and often require physical assets, like a commercial building or residential property, as security. If you’re a service-based business or you’ve recently pivoted your strategy, you might find them incredibly nervous about lending. Being declined by a major bank isn’t the end of your plans; it’s simply a sign that you need a different type of partner. This is where a 2nd Tier Lender New Zealand can provide a lifeline. These lenders specialise in non-standard scenarios and are often more comfortable with complex credit or shorter trading histories.

The flexibility of alternative business financing

While banks focus on what happened in the past, alternative lenders often prioritise where your business is going. They’re willing to customise working capital loans to fit your specific industry needs, whether you’re in construction, retail, or professional services. The trade-off is often a slightly higher interest rate, but you gain much higher flexibility and, most importantly, speed. When a sudden opportunity arrives, like a chance to buy a competitor’s stock at a discount or hire a key team member to land a big contract, you can’t afford to wait six weeks for a bank committee to meet. Speed is the biggest advantage of non-bank lending, often getting cash into your account in a fraction of the time a traditional bank would take.

Navigating these alternative options alone can be overwhelming. This is why having a dedicated negotiator who knows the “inside track” of the banking world makes all the difference. We help you compare different deals to ensure you’re getting a fair price and terms that won’t cause stress during a slow month. We focus on finding a lender who understands your industry, ensuring your finance supports your growth rather than holding it back.

Working Capital Loans NZ: Your 2026 Guide to Boosting Business Cash Flow

Getting your ducks in a row: How to apply for a business loan in NZ

Applying for a loan shouldn’t feel like you’re being interrogated. It’s really just a consultative conversation about where your business is now and where you want it to go. When you’re looking for working capital loans, the goal is to show a lender that you’re a safe pair of hands. They want to see that you have a plan and that you’re in total control of your numbers. Being prepared makes the difference between a quick approval and a long, drawn-out process.

Being honest about your history is vital. If you’ve had some “bumps in the road” like a slow trading year or a credit hiccup, tell us early. It’s much easier to explain a situation upfront than to have a lender discover it later. A veteran broker acts as your advocate; we do the heavy lifting of presenting your case to the right people in a way that highlights your strengths. We know which lenders are more comfortable with your specific industry and who will see the value in your reputation.

The paperwork you will actually need

You don’t need a mountain of files to get started. Most lenders just want to see your recent financial statements. These show your profit and any current debts you’re managing. They’ll also look at your bank statements to understand the daily health of your business cash flow. This gives them a clear picture of how money moves through your accounts. If you want to brush up on how to get your finances ready, visit our Mortgage School for more practical tips.

Telling the story of your business

Numbers tell part of the story, but your vision fills in the gaps. A simple one-page business plan is often more powerful than a complex spreadsheet. When you use working capital loans to grow, show the lender exactly how the cash will help you make more money. Maybe it’s hiring a new lead generator or buying stock to fulfil a big contract. Don’t forget to highlight the experience of your team and your solid reputation in the local market. Lenders love to see that you’ve been in the game for a while and have a loyal customer base.

We know how to navigate this process because we’ve seen every scenario over the last two decades. If you’re ready to get started, you can talk to us about your business goals today.

Why having an expert in your corner makes all the difference

Finance isn’t just a series of calculations performed by an algorithm. It’s a deeply human industry built on relationships, trust, and the art of negotiation. While working capital loans offer the immediate liquidity your business needs, the real value lies in how those funds are sourced and structured. A veteran broker acts as your steady hand, ensuring you don’t just get any loan, but the right one for your specific goals.

Lender appetite changes constantly. One month a bank might be eager to support retail businesses, and the next, they’ve reached their limit for that sector and tightened their criteria. We stay on top of these shifts so you don’t have to. We know which lenders are “hungry” for your type of business right now, which saves you from the frustration of multiple declines that can hurt your credit score.

Personalised service over “computer says no”

Krish Krishna brings over two decades of banking experience to your side of the table. This deep institutional knowledge means he understands the “inside track” of how credit committees think. When a computer algorithm says “no” because of a minor technicality, a dedicated negotiator knows how to reframe the conversation and speak the bank’s language to unlock doors that seemed shut. This personalised approach removes the stress from your shoulders, allowing you to focus on running your business while we handle the complex paperwork and follow-ups. You can see how this has made a difference for others by visiting our reviews page.

Planning for the long term

We view our clients as partners, not transactions. Your first working capital loans are often just the beginning of a long-term relationship. As your business matures and your needs change, we’re here to help you evolve your financial strategy. This might eventually lead to exploring a Commercial Property Refinance NZ to unlock equity for even larger projects.

Having a mentor who has seen every possible scenario gives you the confidence to make bold moves. We’re committed to your success over the long haul, acting as a bridge between the rigid world of traditional banking and your personal business needs. If you’re ready to see what’s possible for your Kiwi business, get in touch with the team at Mortgage Suite Ltd today.

Take the next step toward a stronger cash flow

Managing your daily finances doesn’t have to be a source of constant pressure. By now, you’ve seen how the right funding can bridge the gap between your hard work and your bank balance. Whether you’re navigating a seasonal dip or gearing up for a major expansion, working capital loans provide the liquidity needed to keep your business engine running smoothly without risking your personal savings. It’s about having the freedom to say “yes” to new opportunities when they arrive.

Success in business finance often comes down to who you have in your corner. With over 20 years of banking experience, we specialise in 2nd tier lending solutions that look at the big picture of your success rather than just a credit score. We provide national coverage for all New Zealand businesses, ensuring that even if the big banks have said no, you still have a clear path forward. Our role is to act as your dedicated negotiator, finding a repayment plan that fits your specific trading cycle.

Ready to secure the future of your Kiwi business? Talk to Krish and the team at Mortgage Suite Ltd about your business goals today. Let’s turn your growth plans into a reality with a professional partner you can trust.

Frequently Asked Questions

How much can I borrow for my business in New Zealand?

The amount you can borrow depends largely on your business turnover and the health of your monthly cash flow. Most lenders want to see that your repayments won’t put undue stress on your daily operations. While some unsecured options start small for minor repairs or stock, larger amounts usually require some form of security. We look at your specific trading history to find a limit that supports your growth without becoming a heavy burden.

Do I always need to use my house as security for a business loan?

You don’t always have to put your family home on the line to get funding. While mainstream banks often demand residential property as security, many alternative lenders offer unsecured working capital loans based on your business’s performance. You might also use business assets like vehicles or heavy machinery as collateral instead. This flexibility is a key reason why many Kiwi business owners are moving away from traditional bank branches toward more specialised 2nd tier lenders.

How fast can I get the money once I apply?

Speed is one of the biggest advantages of working with non-bank lenders. In many cases, you can have an answer within 24 to 48 hours of submitting your paperwork. If your documentation is organised and your plan is clear, the funds can often be in your account just a few days later. This is significantly faster than the weeks or months it can take to move through a traditional bank’s rigid committee process.

Can I get a working capital loan if I have bad credit?

Yes, a less-than-perfect credit score doesn’t have to be a deal-breaker for your business plans. While a big bank might give an automatic “no” for past credit hiccups, 2nd tier lenders are often more interested in your current cash flow and future potential. They look at the “big picture” of why those issues happened and how your business is performing today. We specialise in presenting these scenarios to lenders who value your industry experience over a computer score.

What is the difference between a business loan and a commercial mortgage?

The main difference is the length of the commitment and what the money is used for. A commercial mortgage is a long-term loan, often over 15 to 25 years, specifically for buying property. In contrast, working capital loans are shorter-term solutions designed to cover day-to-day costs like payroll or stock. They’re built for speed and flexibility rather than long-term property investment, helping you manage the natural peaks and troughs of your trading cycle.

How do repayments work for a seasonal business?

We can help you find a lender who understands that your income isn’t the same every month. Some specialised lenders offer flexible repayment structures where you pay more during your peak season and less during the quiet months. This prevents the stress of high repayments when cash flow is naturally lower. It’s all about matching the debt to your specific business cycle so the loan remains a helpful tool rather than a source of worry.

What happens if I want to pay the loan back early?

Many modern business loans are designed to be flexible, but it’s important to check the fine print for early repayment fees. Some lenders encourage you to pay back the debt as soon as your customers settle their invoices, while others might charge a small fee to cover their lost interest. We always look for options that give you the freedom to clear your balance early without being penalised, ensuring you only pay for the money while you actually need it.

Do I need a full business plan to get a small loan?

You don’t necessarily need a 50-page document to secure a small amount of funding. For most working capital loans, a simple one-page summary explaining how the money will be used and how it will help you grow is often enough. Lenders mainly want to see that you understand your numbers and have a clear strategy for repayment. We can help you pull this information together so it’s presented professionally to the right people.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Cash Flow Loans for Small Business NZ: 2026 Funding Guide

What if the bank’s “no” isn’t actually the end of your growth plans, but just a sign that you’re looking in the wrong place for capital? Most Kiwi business owners know the frustration of waiting weeks for a loan approval while GST deadlines loom or seasonal dips make it hard to pay the team. You might feel like your only option is a traditional business loan against property nz, yet the 2026 lending market offers far more flexibility than the rigid systems of the past. It’s stressful when complex forms and jargon stand between you and the working capital you need to keep things moving.

We understand that your business doesn’t operate on a tidy, predictable schedule. This guide will show you how to bridge financial gaps and fuel your growth with the right cash flow loan tailored for the New Zealand market. You’ll learn how to secure fast access to funds without the fear of losing personal assets as security. We’ll also walk through the latest 2026 regulations, flexible repayment terms that match your specific revenue cycle, and how to get a crystal clear understanding of the total cost of borrowing before you sign anything.

Key Takeaways

  • Understand why cash flow loans are the essential tool for managing seasonal dips and keeping your daily operations running smoothly.
  • Compare your options between secured and unsecured funding, including how a business loan against property nz can unlock lower interest rates.
  • Navigate the shift from government-backed schemes to the 2026 private lending market with confidence and clarity.
  • Learn the simple list of documents you need to prepare to ensure your application is processed without the usual bank delays.
  • Discover how a seasoned negotiator can help you find flexible lending solutions that mainstream banks typically don’t offer.

What exactly are cash flow loans for small business in NZ?

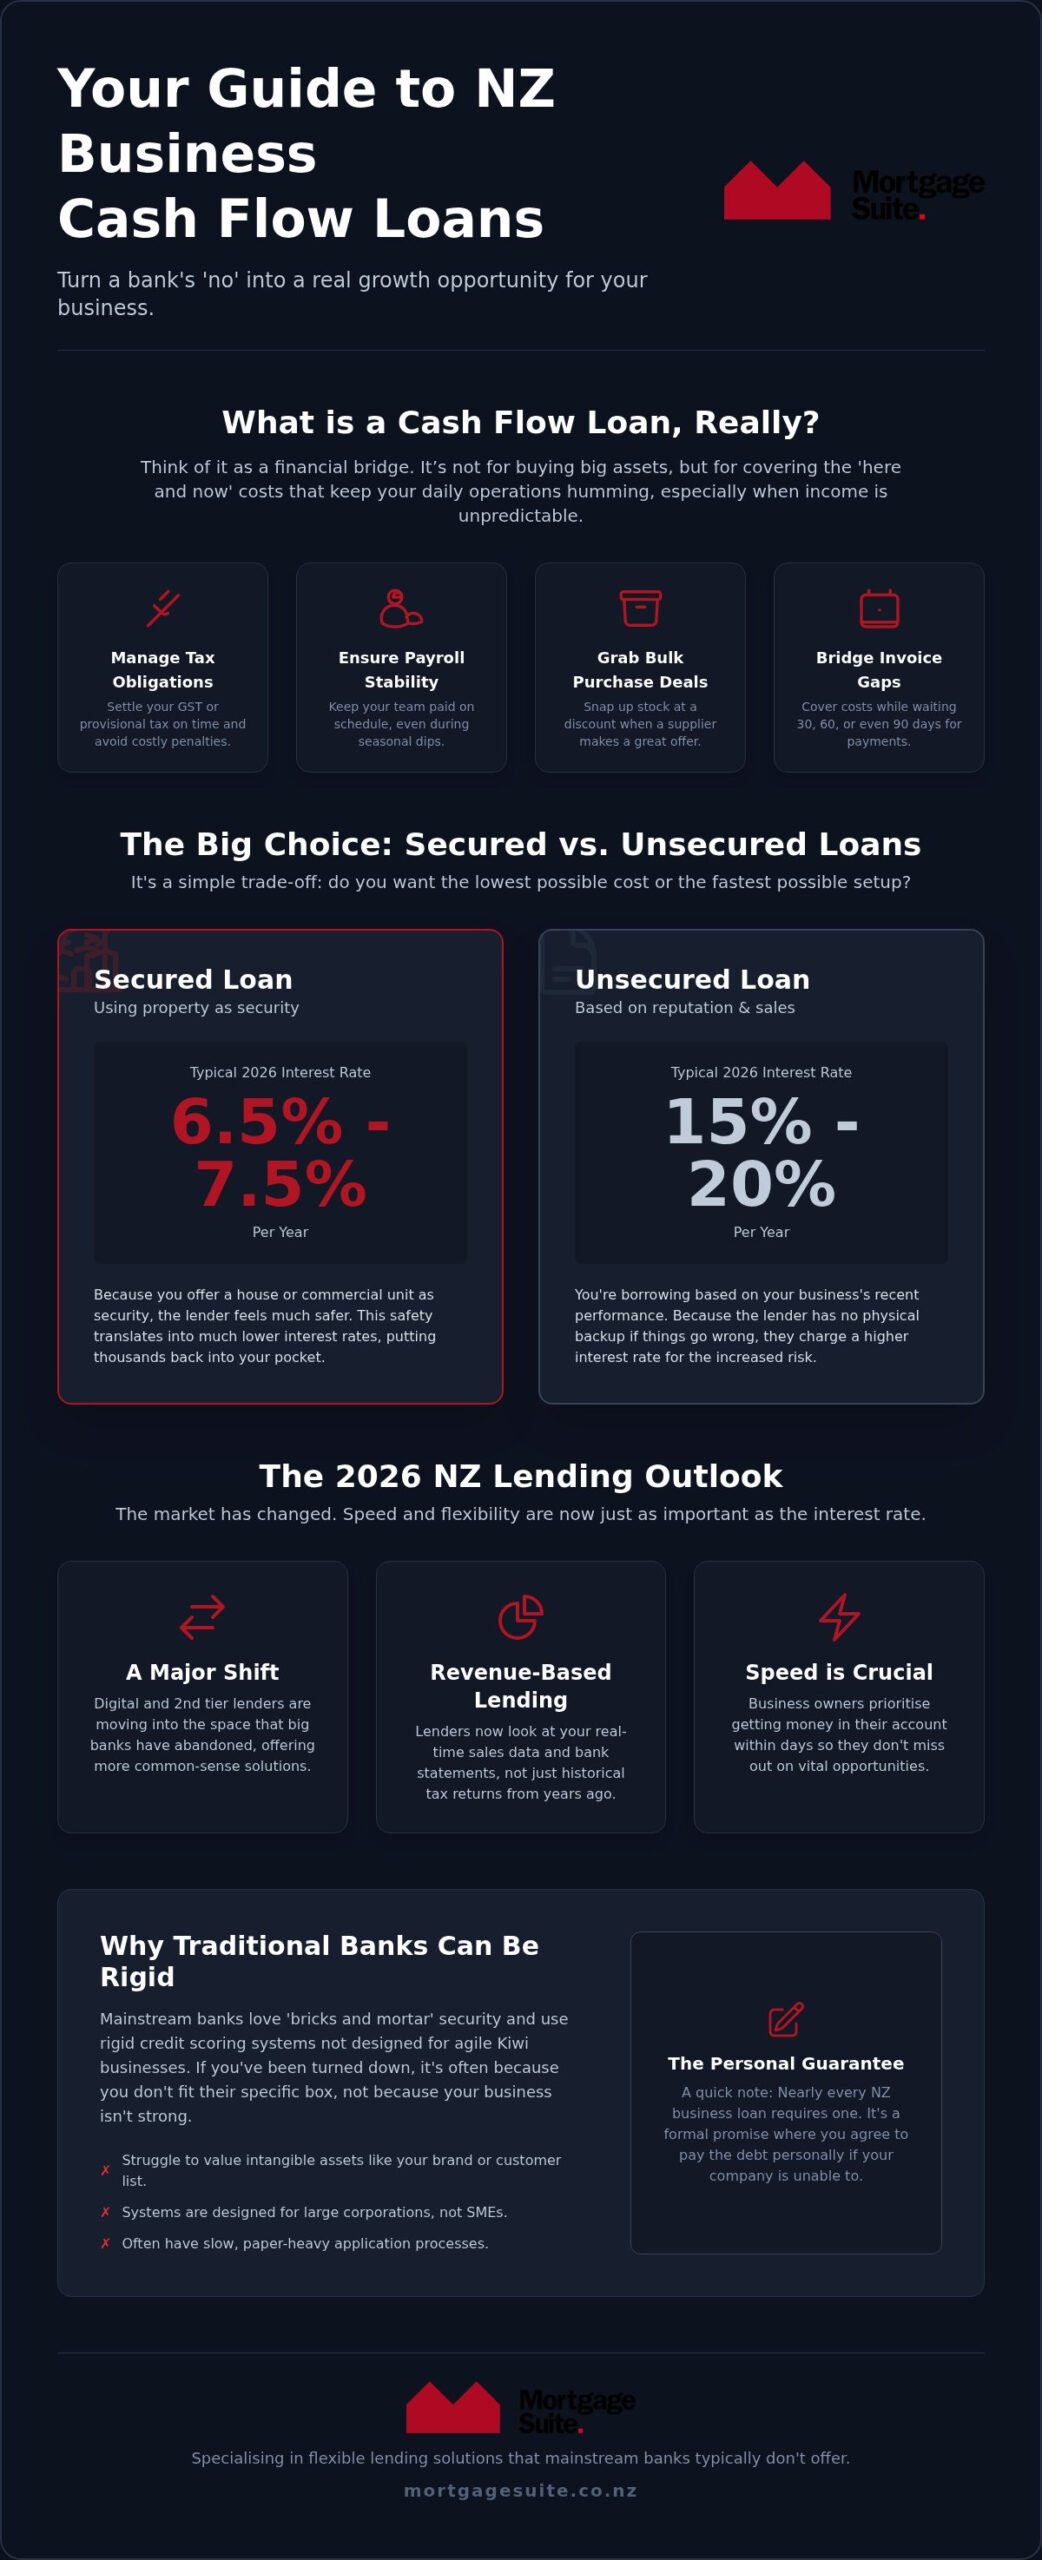
Think of a cash flow loan as a financial bridge that helps you get from one side of a busy month to the other. While a typical business loan is often used to buy big, long-term things like a new warehouse or a fleet of delivery vans, a cash flow loan is designed to keep your daily operations humming. It is money specifically meant to cover the “here and now” costs that keep a business alive. For many Kiwi business owners, money doesn’t always arrive in a perfectly straight line. You might experience busy periods followed by quieter months, or have large invoices that take time to clear. This is where flexible funding steps in to ensure you aren’t caught short when bills arrive.

These loans act as the lifeblood for small and medium businesses during growth spurts. When you’re expanding, you often have to spend money on staff and stock long before the new sales actually hit your bank account. Common ways our clients use these funds include:

  • Managing Tax Obligations: Settling your GST or provisional tax on time to avoid Inland Revenue penalties.
  • Payroll Stability: Ensuring your team is paid on time during seasonal dips or while waiting for large invoices to be cleared.
  • Bulk Purchasing: Snapping up stock at a discount when a supplier offers a limited-time deal.
  • Bridging Gaps: Covering the 30, 60, or 90-day wait periods common in commercial contracts.

It is different from a standard bank overdraft, which can often be reduced or cancelled by the bank at short notice. It also differs from a long-term commercial mortgage because the focus is on having enough cash on hand rather than decades of debt. If you have equity in your home or a commercial unit, a business loan against property nz can often provide a much more cost-effective solution than a high-interest loan that doesn’t use any security.

Why traditional banks often say no to cash flow

Mainstream banks love “bricks and mortar” security. They often struggle to see the value in things they can’t touch, like the value of your brand or reputation, your customer list, or your future contract pipeline. Their rigid credit scoring systems are designed for big corporations, not for agile Kiwi businesses that might have a fluctuating balance sheet. If you’ve been turned down because you don’t fit a specific bank box, it isn’t the end of the road. Using a business loan against property nz through a 2nd tier lender allows for a more common-sense approach where your property equity supports your business’s potential.

The 2026 outlook for NZ business lending

The lending environment in 2026 has changed significantly. Digital lenders and 2nd tier options have moved into the space that banks have abandoned. We are seeing a major shift toward revenue-based lending, where lenders look at your real-time sales data and bank statements rather than just historical tax returns. In this fast-paced market, speed and flexibility are becoming just as important as the interest rate. Business owners now prioritise getting the money in their account within days so they don’t miss out on vital opportunities.

Secured vs unsecured: Is a business loan against property right for you?

Deciding between a secured and unsecured loan usually comes down to a simple trade-off: do you want the lowest possible cost or the fastest possible setup? Borrowing money for your business means looking at how much you’re willing to pay for convenience. If you go for an unsecured loan, you are borrowing based on your reputation and your recent sales. Because the lender has no physical backup if things go wrong, they charge more. In 2026, these interest rates often sit between 15% and 20% per year.

If you choose a business loan against property nz, the picture changes. Because you are offering a house or commercial unit as security, the lender feels much safer. This safety translates into much lower interest rates, often around 6.5% to 7.5%. It’s a significant saving that can put thousands of dollars back into your pocket every month. It’s a big step to put an asset on the line, but for many Kiwi owners, the lower monthly repayments are what allow the business to grow sustainably.

You should also be aware of the Personal Guarantee. In the New Zealand lending world, almost every business loan requires one. It’s a document where you promise to pay the debt personally if your company can’t. It effectively means your personal assets are still connected to the loan, even if you don’t formally register a mortgage against them. It is a standard part of the process that ensures you are just as committed to the loan as the lender is.

Secured loans: Using your assets to grow

Security isn’t limited to your family home. Lenders in 2026 are often happy to look at commercial units, vehicles, or even heavy machinery. Sometimes, property development loans NZ can be used alongside cash flow funding to keep a project moving. The real benefit here is the borrowing limit. If you need more than NZ$250,000, having an asset to back the loan is usually the only way to get the green light from a lender.

Unsecured loans: Fast capital without the assets

If you’re in a service industry like consulting or trade work, you might not have big assets to pledge. Unsecured loans are perfect for these situations. Lenders check your bank statements and GST filings to see your sales volume. It’s a quick process with less paperwork, though you’ll pay those higher interest rates for the speed. If you’re weighing up which path is right for your current situation, exploring your options with an expert can help you find the best balance for your goals.

Moving beyond the Government SBC scheme: Private lending options

For many Kiwi businesses, the Small Business Cashflow Scheme (SBCS) provided a much-needed safety net during a time of total uncertainty. However, as we move through 2026, the landscape has shifted from government support to a focus on debt collection. Those five-year terms are reaching their final deadlines. If you still have an outstanding balance with the Inland Revenue, you’re likely facing the reality of fixed repayment schedules that don’t care about your seasonal dips. The IRD isn’t a bank; they don’t have the tools to offer the flexible, revenue-matched terms that a modern business needs to thrive.

This year is the perfect time to look at moving that debt into a private commercial facility. While the government scheme was a “one size fits all” fix, private lenders offer a much more tailored approach. For example, moving your existing debt into a business loan against property nz can drastically simplify your monthly outgoings. By using the equity in your home or commercial unit, you can secure a loan that fits your current business reality rather than sticking with a rigid government plan. It’s about taking control of your debt and ensuring your repayments work for you, not against you.

What to do if your SBC loan is expiring

The worst thing you can do is wait for the final deadline or a default notice. if your term is ending, start looking at your options now. Bundling your government debt along with any other high-interest business loans into one manageable payment makes your accounting much cleaner. It also gives you a chance to reset your cash flow. A broker can help you navigate this transition, acting as your advocate to find a lender that values your business’s future potential. We can help you move from government reliance to a more sustainable commercial independence.

The rise of 2nd tier lenders for Kiwi SMEs

Many business owners are surprised to find that a 2nd tier lender New Zealand can often be more helpful than a mainstream bank. These lenders are special because of the way they look at your business. Instead of a computer algorithm deciding your fate, a real person listens to your story and looks at your current bank statements. There’s a common myth that 2nd tier lending is only for businesses with bad credit, but that isn’t the case in 2026. Many of our most successful clients choose these lenders because they offer speed, flexibility, and a business loan against property nz that fits their specific sales cycle. It’s about finding a partner who understands the reality of running a business in the local market.

Cash Flow Loans for Small Business NZ: 2026 Funding Guide

How to get your business ready for a cash flow loan application

Preparing for a loan isn’t just about filling in a form and hoping for the best. It’s about showing a lender that you’re a safe pair of hands with a clear plan for the future. In 2026, lenders are faster than ever, but they’re also smarter. They use sophisticated software to scan your data in seconds, so your financials need to be sharp from the moment you hit submit. If you’re looking to secure a business loan against property nz, the first thing a lender will want to see is that your business has the “heartbeat” of consistent revenue to support the repayments.

Lenders generally focus on what we call the “Big Three” documents. These provide a transparent window into your business health without the need for hundreds of pages of jargon-filled reports. You will need:

  • Bank Statements: Usually the last six months of trading to show your daily cash ins and outs.
  • GST Returns: This proves to the lender that you’re meeting your obligations with the Inland Revenue.
  • A Simple Profit and Loss: A basic summary of your income and expenses over the last year.

Beyond the numbers, you need to be able to tell your story. Don’t just say you need “working capital.” Be specific. If you need NZ$80,000 to buy bulk inventory for the summer rush or to hire two new tradies for a large contract, say so. Lenders love a clear purpose because it shows you’re thinking like a strategist, not just someone trying to keep the lights on.

Cleaning up your financial house

Messy bank statements are a common reason for a fast “no.” If your business account is full of personal spending or small, unexplained transfers, it makes you look unorganised. Before you apply, take a month to keep things strictly business. It’s also vital to ensure you aren’t behind on any IRD payment plans. If you have a temporary dip in revenue or a one-off big expense, like a major equipment repair, be upfront about it. Explaining the “why” behind a dip is always better than letting a lender guess the reason. You can get a head start on your application by chatting with us about your current financial position.

The broker’s role in the application process

Many business owners make the mistake of applying to five different lenders at once. In the NZ market, every time a lender does a hard credit check, it leaves a mark on your file. Too many marks in a short time make you look desperate for cash, which can hurt your chances of approval. A broker acts as your advocate and negotiator. We take your “Big Three” documents and package them in a way that highlights your strengths. Because we know which 2nd tier lenders are currently looking for businesses in your specific industry, we can find the right business loan against property nz without damaging your credit score. We do the hard work so you can stay focused on running your business.

How Mortgage Suite helps you secure the best business finance

Navigating the finance market alone can feel like a full-time job. With over 20 years of banking experience, we’ve seen how the big banks operate from the inside. This insider knowledge is what we use to act as your dedicated negotiator. We don’t just look at a spreadsheet; we look at the person behind the business. Our approach is built on finding the lenders that the general public often misses. While a single bank will only ever show you their own products, we provide a market-wide view that includes 2nd tier options and private funds specifically designed for Kiwi SMEs.

When you’re looking for a business loan against property nz, you need more than just an interest rate. You need a structure that won’t cripple your growth. We take the stress out of the process by providing jargon-free, honest advice. There are no hidden fees or complex financial shorthand here. We speak your language and focus on the result: getting the capital you need to move forward without the usual bank headaches.

More than just a loan: a financial partnership

We believe in looking at your entire financial world. This means considering how your personal debt and mortgage rates NZ might impact your business borrowing capacity. Often, there’s a gap between where your business is today and where you want it to be in twelve months. We help you bridge that gap by acting as your advocate. When we deal with 2nd tier lenders on your behalf, we aren’t just submitting a form. We are presenting a case for why your business is a sound investment, ensuring you get terms that reflect your true potential and current market conditions.

Your next steps to better cash flow

Getting started is as simple as a phone call. We don’t believe in high-pressure sales tactics or making you wait for weeks just to get an initial answer. When you call us, you’ll get a conversational, helpful partner who listens first. We’ll discuss your goals, look at your options for a business loan against property nz, and map out a clear path forward. From that first chat to having funds in your account, the process is designed to be as seamless as possible. You’ve done the hard work of building your business; let us do the hard work of funding it. Contact Mortgage Suite Ltd today for a no-obligation chat about your business goals.

Take control of your business cash flow today

Managing the ups and downs of business revenue doesn’t have to be a solo struggle. Whether you’re transitioning away from the expiring government scheme or looking to fund a major new contract, the right capital structure makes all the difference. Remember that speed and flexibility often outweigh a slightly lower bank rate, especially when a growth opportunity is waiting. Using a business loan against property nz remains one of the most effective ways to secure lower interest rates and higher limits for your enterprise.

At Mortgage Suite, we bring over 20 years of banking expertise to the table as a 100% Kiwi owned and operated team. We specialise in 2nd tier and alternative lending, finding the solutions that mainstream banks simply can’t offer. You don’t have to navigate the jargon or the complex applications alone. We are here to act as your dedicated advocate and negotiator. If you’re ready to stop worrying about the next GST bill and start focusing on your long-term goals, book a free, no-obligation chat with our business lending experts. Your next stage of growth is closer than you think.

Frequently Asked Questions

What is the typical interest rate for a small business cash flow loan in NZ?

Interest rates depend largely on whether the loan is secured or unsecured. For a business loan against property nz, you can currently expect rates between 6.5% and 7.5% p.a. in the 2026 market. If you choose an unsecured option, rates are higher to reflect the increased risk to the lender, typically ranging from 15% to 20% p.a. based on your trading history.

Can I get a business loan if I’ve been declined by my main bank?

Yes, you certainly can. Mainstream banks often have very rigid criteria that don’t account for the unique way Kiwi SMEs operate. We specialise in 2nd tier lending, where providers use human-led underwriting to look at your current bank statements and future potential. A “no” from a big bank is often just a sign that you need a more flexible lender who understands your industry.

Do I need to provide my house as security for a cash flow loan?

Not necessarily. While a business loan against property nz offers the lowest interest rates, you can also use commercial units, vehicles, or heavy machinery as collateral. If you don’t want to use any physical assets, you can opt for an unsecured loan. These are faster to set up but usually come with higher interest rates and lower borrowing limits.

How long does it take to get the money once the loan is approved?

Speed is a major benefit of modern business lending. Once your loan is approved, funds are often transferred to your bank account within 24 to 48 hours. If your loan is secured against property, the process can take a few extra days for valuations and legal paperwork, but it is still significantly faster than the weeks of waiting often required by traditional banks.

What is the difference between a cash flow loan and a business line of credit?

A cash flow loan provides a lump sum of money upfront which you repay over a set term with fixed payments. A business line of credit works more like a credit card; you have a pre-approved limit and you only draw down funds when you need them. You only pay interest on the amount you actually use, making it a flexible tool for managing ongoing daily expenses.

Can I use a cash flow loan to pay my GST or tax bill?

Yes, this is one of the most common reasons New Zealand business owners seek short-term funding. Using a loan to settle GST or provisional tax helps you avoid the high interest and late payment penalties charged by the Inland Revenue. It allows you to spread the cost of your tax obligations over several months, keeping your daily working capital intact for growth.

Is there a penalty for paying back my business loan early?

Most 2nd tier and non-bank lenders in the current market do not charge penalties for early repayment. In many cases, paying the loan back early can actually save you a significant amount in interest. However, it is important to check the specific terms of your agreement, as some older or more traditional contracts may still include early exit fees.

What documents do I need to provide for an unsecured business loan?

Lenders typically require what we call the “Big Three” documents to assess an unsecured application. You will need to provide your last six months of bank statements, your most recent GST returns, and a basic profit and loss statement. These documents give the lender a clear picture of your recent revenue and help them confirm that the repayments are affordable for your business.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

2nd Tier Lender New Zealand: Your 2026 Guide to Alternative Home Loans

What if the bank’s “no” isn’t actually the end of your home-buying journey, but just a sign you’re looking in the wrong place? It is incredibly disheartening to feel like a mere tick-box on a spreadsheet, especially when a slightly messy credit history or self-employed income makes you “too hard” for traditional lenders. Finding a 2nd tier lender New Zealand wide can be the breakthrough you need, offering a common-sense approach that looks at your whole financial picture rather than just a computer-generated score.

We understand the anxiety that comes with being turned away, but these alternative options are designed for people who need a partner, not just a processor. This guide explores how to secure a flexible home loan that respects your unique situation, providing a fair go when the big banks won’t budge. You will discover exactly how these lenders operate in 2026, the specific benefits they offer for non-standard financial profiles, and how to create a clear strategy for eventually refinancing back to a mainstream bank once your circumstances settle.

Key Takeaways

  • Understand that 2nd tier lenders are professional, legitimate institutions that offer a genuine alternative when big banks won’t help.
  • Discover how a 2nd tier lender New Zealand wide uses a common-sense approach to look at your whole financial picture rather than just ticking boxes.
  • Learn why flexibility often comes with a slightly higher interest rate and how the speed of these lenders can save your property deal.
  • Find out how to organise a professional paper trail and why being upfront about your history helps secure a faster approval.
  • Explore how seasoned expertise can bridge the gap between rigid banking rules and your personal goal of home ownership.

What is a 2nd Tier Lender in New Zealand?

Think of a 2nd tier lender as a specialised financial institution that focuses purely on helping people secure property. Unlike the big banks you see on every street corner, these organisations don’t offer everyday savings accounts, credit cards, or travel insurance. They aren’t “retail banks” in the traditional sense; instead, they are professional lenders who use their own capital or institutional funds to provide mortgages. This narrow focus is actually their greatest strength because it allows them to be far more flexible than a bank that’s trying to be everything to everyone.

The main difference you’ll notice is the way they look at your application. While big banks often rely on rigid computer algorithms that spit out a “yes” or “no” based on strict “tick-box” criteria, a 2nd tier lender New Zealand homeowners use often applies a common-sense approach. They’re interested in the “why” behind your financial situation. If you’re self-employed and your income fluctuates, or if you had a minor credit hiccup a few years ago, these lenders are more likely to look at the big picture rather than just the numbers on a screen. They provide a vital alternative for Kiwis who have the ability to pay a mortgage but don’t quite fit the narrow mould of mainstream banking.

Non-Bank vs. 2nd Tier: Is there a difference?

No worries if you’re a bit confused by the different names; they basically mean the same thing in our local market. “Non-bank” describes their legal structure, meaning they are a non-bank financial institution that doesn’t hold a full banking licence from the Reserve Bank. “2nd tier” describes their position as a secondary option to the “Big Four” banks. Whether you call them non-banks or 2nd tier, the result is the same: a professional lender that offers a different path to home ownership.

Why they are a safe bet for Kiwis

Some people worry that stepping away from a big bank means less protection, but that isn’t the case. Every 2nd tier lender New Zealand has must follow the Credit Contracts and Consumer Finance Act (CCCFA). This means they are legally required to be responsible lenders, just like the household names. These institutions have been a solid part of our property market for decades. Many are backed by massive global investment firms or well-known local institutions, ensuring they have the stability and reputation to support your long-term goals. They aren’t “last resorts” but rather strategic partners for those who need a more personalised touch.

Why the Mainstream Banks Might Say ‘No’

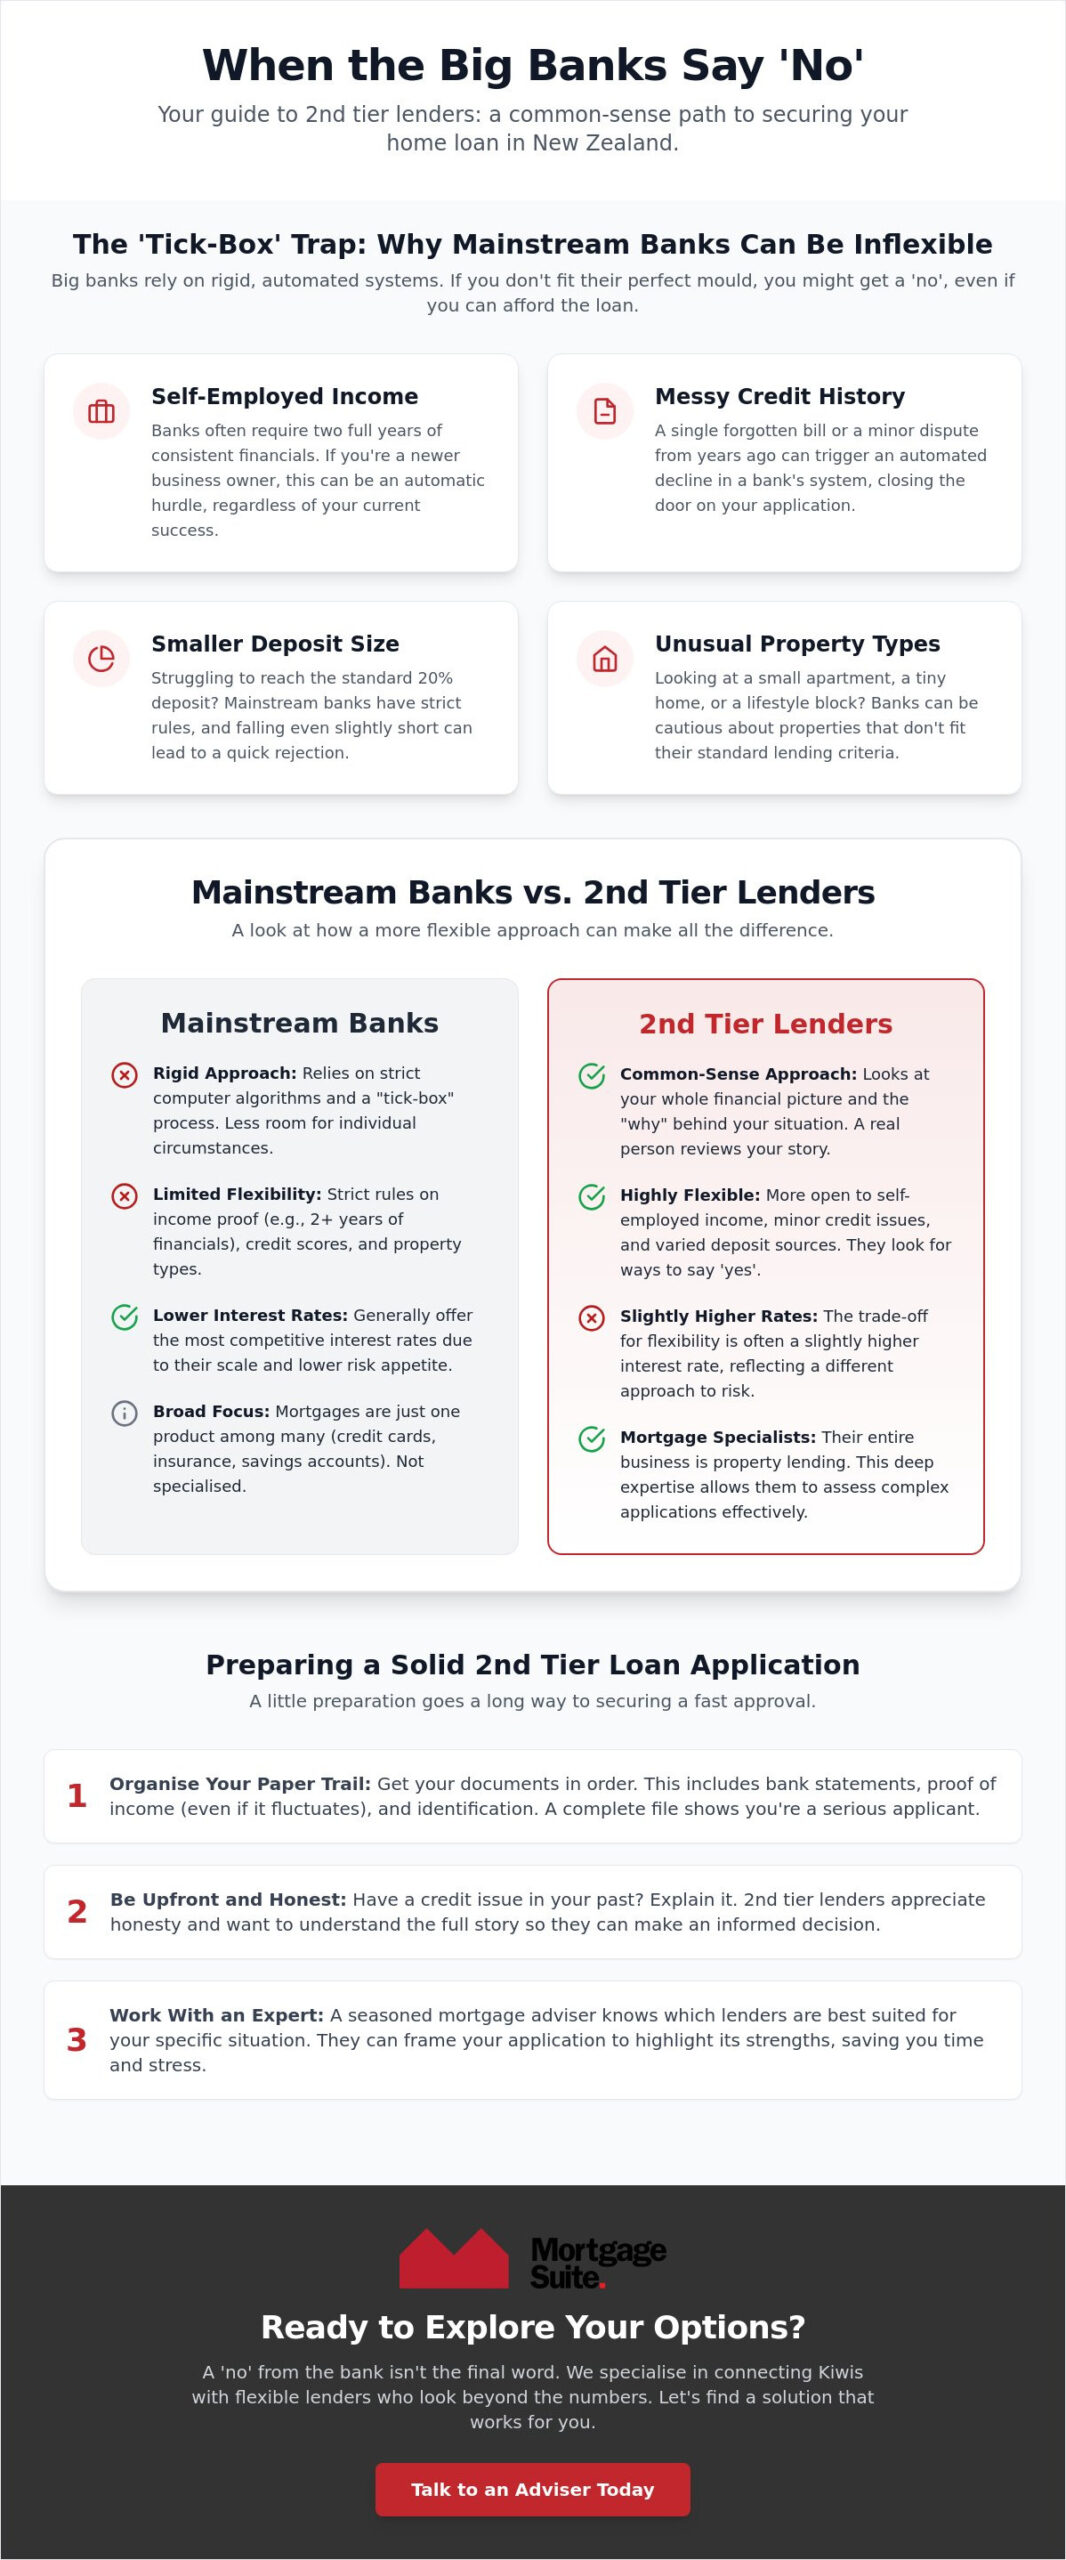
It’s a sinking feeling when you’ve done everything right, saved your deposit, and found the perfect home, only to have a bank manager shake their head. The reality is that the Big Four banks are massive machines built for speed and volume. To keep things moving, they rely on rigid, one-size-fits-all rules. If your financial situation has even a tiny bit of “colour” or complexity, you often fall outside their very narrow appetite for risk. A “no” from a mainstream lender usually isn’t a reflection of your ability to pay; it’s simply a sign that you don’t fit their specific, pre-programmed mould.

This is where a 2nd tier lender New Zealand wide provides a much-needed alternative. While banks look for reasons to say no to protect their high-volume systems, 2nd tier lenders look for reasons to say yes. They take the time to understand the story behind the numbers. They recognise that modern lives are rarely tidy, and they’re willing to look at the big picture of your financial health rather than just a computer-generated score.

Common hurdles for the ‘Big Four’

There are several reasons why a perfectly capable borrower might get a “thanks, but no thanks” from a traditional bank. These hurdles are often non-negotiable for mainstream lenders:

  • Self-employed income: Banks usually demand two full years of perfect financial records. If you’ve been in business for 12 months and are doing well, a bank might still decline you simply because you haven’t reached that two-year mark.
  • Deposit size: With government rules often requiring a 20% deposit for owner-occupiers, many Kiwis find themselves just a few thousand dollars short.
  • Credit history: A forgotten power bill from three years ago or a minor credit card dispute can stay on your file and trigger an automatic decline in a bank’s system.
  • Property types: Banks are often wary of apartments under a certain size, tiny homes, or lifestyle blocks with unusual titles.

The ‘Tick-Box’ trap

Modern banking relies heavily on automated software. When you submit an application, an algorithm scans for specific data points. If one “box” isn’t ticked, the system can auto-decline the application before a person even looks at it. In contrast, the 2nd tier space relies on a human-led decision-making process. These are experienced professionals who can see that a past credit hiccup was a one-off event or that your self-employment income is stable and growing. This approach is the foundation for non-conforming loans, which are specialised products designed specifically for “out-of-the-box” situations that don’t meet standard bank criteria. If you’re feeling stuck in this tick-box trap, it might be time to talk to an expert who knows how to present your case to the right people. If you’ve already received a formal rejection, our comprehensive guide for those declined by bank home loan NZ applicants explains exactly what steps to take next to recover and find a path to approval.

Comparing 2nd Tier Lenders vs. Mainstream Banks

Choosing between a big bank and a 2nd tier option isn’t about finding a “better” lender, but rather the right lender for your current situation. Mainstream banks are great for people who fit a very specific profile and want the lowest possible interest rate. However, that low rate often comes with a lack of flexibility and a slow, complicated process. If you need a lender who can look past a messy bank statement or move quickly to secure a property, a 2nd tier lender New Zealand wide offers a level of service the big banks simply aren’t built to provide.

One of the biggest advantages is the personalised approach. You won’t find yourself stuck in a massive call centre queue or waiting weeks for a computer to process your paperwork. Instead, you’re working with people who understand that every borrower has a unique story. They can be far more creative with loan structures, such as offering longer periods where you only pay the interest. This can help with your cash flow while you’re getting established or finishing a renovation. It’s about finding a solution that fits your life, not forcing your life to fit their rules. For property investors in particular, this flexibility extends to residential investment property loans NZ borrowers use to grow their portfolios when mainstream banks won’t budge on LVR restrictions.

Interest rates and fees: The real story

Let’s be upfront about the trade-offs. Because these lenders take on more complex cases, their interest rates are generally higher than the “special” rates advertised by the Big Four. For many Kiwis, the slightly higher cost is a small price to pay for the value of actually getting into a home. It’s often a short-term strategy to get into the market now rather than waiting years to save a larger deposit. To help with the initial costs, many of these lenders allow you to add the setup fees to your total loan balance, meaning you don’t need even more cash upfront to get the deal across the line.

Flexibility and Speed

Speed is where these lenders truly shine. While a big bank might take weeks to give you a definitive answer, a 2nd tier lender can often organise a conditional approval in as little as 48 hours. This is a game-changer if you’re trying to secure a property at auction or need a short-term loan to cover the gap between selling one home and buying another. They are experts in providing non-conforming home loans New Zealand families use to navigate tricky transitions. Whether it’s a short-term fix or a long-term plan, their ability to move fast ensures you don’t miss out on the right opportunity just because a bank’s internal rules changed overnight. This same speed and flexibility makes them a natural fit for those seeking property development loans NZ wide, where tight project timelines and complex income structures often rule out the big banks entirely.

2nd Tier Lender New Zealand: Your 2026 Guide to Alternative Home Loans

How to Prepare a Solid 2nd Tier Loan Application

Getting your ducks in a row before you talk to a lender makes a world of difference. When you apply with a 2nd tier lender New Zealand wide, you aren’t just submitting a pile of numbers; you’re telling a story. These lenders are looking for a reason to say yes, but they need to see that you’re professional and organised. Gathering a clear paper trail is the first step to proving you’re a reliable partner who takes their finances seriously. It shows you’ve moved past the “too hard” basket and are ready to take control of your property journey.

Honesty is your best policy here. We always tell our clients that lenders hate surprises but they love honesty. If you have a bit of a colourful credit history or a period of low income, it’s much better to be upfront about it. When you explain the “why” behind a past mistake, it allows the lender to focus on your current ability to afford the repayments. They want to see that you have a stable income now and a clear plan for the future. This is where a mortgage broker becomes your best mate. We know exactly which lenders are comfortable with your specific situation and how to present your case so it stands out for the right reasons. If you’re unsure what went wrong with a previous application, our step-by-step recovery guide for Kiwis declined by bank home loan NZ wide can help you understand the reasons behind the rejection and how to address them before reapplying.

The ‘Exit Strategy’: Planning your return to the bank

Think of this loan as a bridge, not a destination. You don’t necessarily need a 2nd tier loan for a full 30-year term. Instead, many Kiwis use these products for 12 to 24 months to “clean up” their financial profile. During this time, you can prove a stable income or wait for old credit marks to fall off your record. Once your situation has settled, Mortgage Suite Ltd can help you refinance back to a mainstream bank with a lower rate. You can learn more about how this transition works in our guide to non-bank lenders nz.

The documentation you’ll need

To give yourself the best chance of a fast approval, you’ll need to have your paperwork ready to go. Lenders will look closely at your recent bank statements to check how you manage your bank accounts. They want to see that you’re handling your money well, without unarranged overdrafts or missed payments. You’ll also need to prepare:

  • Proof of deposit: This could be your savings, a gift from family, or equity you’ve built up in another property.
  • Income verification: For those who work for themselves, this might include recent sets of accounts or GST returns to show your business is healthy. Self-employed borrowers who struggle to meet traditional documentation requirements may also want to explore low doc home loans NZ lenders offer as an alternative path to approval.
  • A written explanation: A short, honest note explaining any past credit issues helps you get ahead of the lender’s questions and shows you’re proactive.

If you’re ready to stop guessing and start moving forward with a plan tailored to you, the best next step is to get in touch for a personalised chat about your options.

How Mortgage Suite Ltd Connects You to Alternative Funding

At Mortgage Suite Ltd, we believe everyone deserves a fair go at owning a home. Our founder, Krish Krishna, brings more than 20 years of deep banking experience to your side of the table. This isn’t just a number on a CV; it’s your secret weapon. Because Krish has spent two decades understanding the inner workings of the financial world, he knows exactly how to navigate the systems that often feel like a maze to everyday Kiwis. He has seen the process from both sides and knows what it takes to get a deal across the line.

Our role is to act as a bridge between you and the right 2nd tier lender New Zealand has available. We take your complex situation, whether you’re self-employed, have a non-standard income, or a few credit marks, and ‘translate’ it into a language that lenders understand and respect. We don’t just pass on your paperwork. Mortgage Suite Ltd builds a professional case for you, highlighting your strengths and providing clear context for any past hurdles. This hands-on approach often makes the difference between a quick decline and a solid approval. Our process is built on several key advantages:

  • Direct access to a wide range of lenders you won’t find on the high street.
  • Deep knowledge of “hidden” lending criteria that changes from month to month.
  • A proactive attitude toward overcoming obstacles that stop big banks in their tracks.
  • A long-term commitment to your financial success, not just a one-off transaction.

Expert negotiation on your behalf

We don’t just stop at the first “yes” we receive. Our goal is to fight for the best possible terms for your specific needs. Because Mortgage Suite Ltd has established relationships with a huge range of lenders across the country, we have access to options that the general public cannot reach directly. Every lender has its own unique appetite for risk at any given time. We know which ones are looking for your type of deal right now. From the top of the North Island to the bottom of the South, we provide national reach for all types of property loans, including residential investment property loans NZ investors need to unlock equity and grow their portfolios in 2026, ensuring you get a solution that works for your long-term goals.

Ready for a fair go?

If you’ve been turned away by your bank, please remember that it’s just a detour, not the end of the road. We invite you to reach out for a confidential, judgment-free chat about your situation. Mortgage Suite Ltd has seen every possible scenario and we know how to find a path forward. Our commitment is to partner with you for your long-term financial success, helping you get into your home now while planning for your eventual return to a mainstream bank. When you’re ready to explore what’s possible, you can book a consultation with our team. Let’s get to work on making your home ownership goals a reality.

Your Path to Home Ownership Starts Here

Securing a mortgage doesn’t have to be a stressful battle against a bank’s rigid computer system. Alternative options provide the flexibility and common-sense approach that modern Kiwis need to move forward. Whether you’re navigating self-employment income or a non-standard credit history, finding the right 2nd tier lender New Zealand wide can be the bridge that gets you into your home sooner rather than later. By focusing on a clear exit strategy and preparing a professional application, you can turn a bank’s decline into a successful new beginning.

With over 20 years of banking and mortgage expertise, Mortgage Suite Ltd specialises in these complex, non-conforming loans. Our founder-led service ensures you receive personalised attention from someone who truly knows how to negotiate with alternative lenders to get the best possible result for your situation. You don’t have to figure this out on your own. Chat with Mortgage Suite Ltd about your 2nd tier loan options today and let us help you find a fair go in the property market. Your dream home is still within reach, and we’re here to help you secure it.

Frequently Asked Questions

Is a 2nd tier lender safe to use in New Zealand?

Yes, they are completely safe and professional organisations. Every 2nd tier lender New Zealand has must comply with the Credit Contracts and Consumer Finance Act (CCCFA). This ensures they follow strict responsible lending rules just like the big banks. Many are backed by large investment firms; providing a secure and regulated environment for your home loan. You can feel confident that your rights are protected under New Zealand law.

Will my interest rate be much higher with a 2nd tier lender?

Generally, yes, the interest rates are slightly higher than those offered by mainstream banks. This reflects the extra flexibility they provide and the higher risk they take on. However, for many people, the small increase in cost is a fair trade for actually getting into a home. It is often a short-term solution while you work toward qualifying for a standard bank rate in the future.

Can I move back to a mainstream bank later on?

Absolutely, and for most clients, this is the ultimate goal. We often set up these loans with a 12 to 24 month plan in mind. Once you have built up more equity or cleaned up your credit history, we can help you refinance back to a mainstream bank. This “exit strategy” ensures you aren’t paying a higher rate for any longer than you actually need to.

Do 2nd tier lenders require a bigger deposit?

Not necessarily. In some cases, a 2nd tier lender New Zealand wide might actually be more flexible with deposit sizes than a big bank. While banks are often restricted by tight government rules on low-deposit lending, alternative lenders have more freedom to look at your individual situation. They focus more on your ability to make the repayments rather than just the cash you have upfront.

How long does it take to get a 2nd tier loan approved?

These lenders are typically much faster than traditional banks. You can often get a conditional approval within 48 hours, whereas a big bank might take two weeks or more. Because they are smaller and more focused, they don’t have the same layers of bureaucracy. This speed is a huge advantage if you are trying to buy a property at auction or have a tight deadline.

Can I get a 2nd tier loan if I’m self-employed?

Yes, they are often the best option for business owners and contractors. Banks often demand two years of perfect financial records, which many self-employed Kiwis don’t have. Alternative lenders are happy to look at other proof of income, such as GST returns or recent bank statements. They understand how business income works and won’t penalise you for having a complex financial structure. If you want to understand all the options available to you as a business owner, our detailed guide to low doc home loans NZ self-employed borrowers use in 2026 covers exactly how alternative documentation can work in your favour.

What happens if I have bad credit history?

They take a common-sense approach to your past. Instead of an automatic “no” from a computer, a human will look at why the credit issue happened and what has changed since then. If you can show that you are back on track and can afford the loan now, they are often willing to help. It’s about your current character and ability to pay, not just a past mistake.

Are 2nd tier lenders the same as ‘payday’ lenders?

No, they are completely different. Payday lenders offer very small, high-interest loans for a few weeks. In contrast, 2nd tier lenders provide long-term property finance and mortgages. They are professional financial institutions that offer competitive alternatives to the big banks. They are a legitimate part of the New Zealand property market and help thousands of families secure their own homes every year.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Small Business Loan NZ: A Roundup of Funding Options for 2026

What if the reason your bank said “no” had nothing to do with your company’s potential and everything to do with their rigid, outdated tick-boxes? Many Kiwi business owners spend weeks wrestling with complex application forms only to be met with a cold, automated rejection because their financials look a bit “non-standard”. It is incredibly frustrating to feel like just another file in a giant system when you are trying to build a legacy. We understand that your business is more than just a balance sheet; it is the result of your hard work and passion.

Finding a small business loan NZ doesn’t have to be a source of constant stress. You deserve a flexible lender who acts as a partner rather than a gatekeeper, helping you secure growth funds without the sleepless nights. This article will help you understand the different types of funding available in the current market and how to choose the right fit for your company’s growth. We will break down the funding landscape for 2026, explore the practical differences between secured and unsecured options, and look at how personalised service can help you overcome the obstacles often found at larger institutions.

Key Takeaways

  • Understand how to use business finance as a strategic tool to fuel growth while keeping your personal and company debts separate.
  • Compare classic term loans with flexible lines of credit to find the right cash flow solution for your specific projects.
  • See why a small business loan NZ from a second-tier lender often provides the flexibility that mainstream banks lack for unique businesses.
  • Master the essential steps to get your financials organised and clearly explain how new funding will drive your future profits.
  • Learn how a personalised approach and decades of industry experience can help you bypass automated systems to secure the best possible deal.

What exactly is a small business loan in the NZ market?

In its simplest form, a small business loan NZ is a financial tool designed to help your company grow or stay steady during quiet patches. Think of it as a boost for your company’s engine. Unlike a personal loan used for a holiday or a new car, business-purpose borrowing is specifically about generating more revenue or improving your operations. It is the fuel that allows you to take on a bigger contract, buy bulk stock at a discount, or move into a larger warehouse before you have the full amount of cash sitting in your account.

Separating your personal debt from your business debt is a smart move for any owner. It helps protect your family assets and makes your yearly accounting much cleaner. We have noticed more Kiwi owners moving away from traditional bank overdrafts recently. This shift is happening because many big banks are tightening their lending rules or trimming overdraft limits without much warning. A structured loan often provides more certainty than an overdraft that could be reviewed or reduced at the bank’s whim. Whether you are dealing with a “feast or famine” cash flow cycle or just need to bridge a gap, the right loan provides a safety net that lets you focus on the work itself rather than worrying about the bank balance every morning.

Common reasons Kiwis seek business funding

  • Purchasing new vehicles or specialised machinery: Getting the right tools to increase your daily output or take on more technical jobs.
  • Funding renovations: Updating your office, retail shop, or workshop to create a better environment for your team and customers.
  • Managing working capital: Covering the gap between finishing a large project and actually getting paid by the client.

Asset finance vs. general business loans

There are several different types of business funding to consider depending on your specific needs. Asset finance is quite straightforward because the equipment you are buying, like a truck or a digger, usually acts as the security for the loan. If you are a newer business, asset finance is often easier to secure because the lender has a physical item to hold as a guarantee. This reduces their risk and can sometimes lead to better terms for you.

General-purpose business loans offer more flexibility. You can use these funds for things that don’t have a physical “serial number”, such as a new marketing campaign, hiring a key staff member, or launching a new service line. Because there is not always a physical asset involved, lenders will look more closely at your overall cash flow and business history. Choosing between these options depends on your long-term goals, but having a seasoned expert to help you weigh up the pros and cons ensures you don’t end up with a structure that hinders your future growth.

A roundup of business funding types available to you

Choosing the right small business loan NZ depends entirely on what you plan to do with the money. A classic term loan is often the best fit for a one-off, long-term project. You receive a lump sum upfront and pay it back over a set period, which makes your monthly budgeting very predictable. If you are looking to buy the building your business operates from, a commercial mortgage works in a similar way but over a much longer timeframe. Owning your premises can be a fantastic way to build equity rather than just paying off someone else’s mortgage. If you are considering this path, our step-by-step guide on how to buy commercial property loan NZ requirements and processes will walk you through exactly what to expect.

For day-to-day operations, you might consider a business line of credit or invoice finance. A line of credit lets you dip into funds only when you need them, meaning you only pay interest on what you actually use. Invoice finance is a bit different; it allows you to get paid early for work you have already finished by “selling” your unpaid invoices to a lender. This is a brilliant way to keep cash moving if your clients usually take 30 or 60 days to pay. Even government initiatives like the Small Business Cashflow Scheme have shown how specific, targeted funding can help Kiwis manage through unpredictable times. If you are unsure which path fits your current goals, talking to an expert about business loans can help clarify your options.

Choosing between secured and unsecured loans

The main trade-off here is between cost and speed. A secured loan usually requires you to pledge an asset, such as a property or a piece of heavy machinery, as a guarantee. Because this lowers the risk for the lender, you can often secure a much lower interest rate. For instance, while some specialist lenders might charge 14.99% or more for unsecured debt, a property-backed loan could be significantly cheaper. Unsecured loans are faster to get because there is no asset to value, but you will pay a premium for that convenience through higher rates and smaller borrowing limits.

The rise of flexible business facilities

Modern lending has moved beyond the clunky, old-fashioned bank overdraft. Many SMEs are now opting for flexible business facilities that allow you to pay down your balance and then “re-borrow” up to your limit whenever you need to. A business flexible facility acts as a safety net for cash flow, giving you peace of mind that funds are there if you need them. These facilities are replacing overdrafts because they often offer better terms and more transparency, helping you stay in control of your debt rather than feeling like the bank is in the driver’s seat.

Mainstream banks vs. 2nd tier lenders: Which is right for you?

When you start looking for a small business loan NZ, the local branch is usually the first stop. However, the experience can be a bit of a letdown for many owners. Big banks rely heavily on “tick-box” systems and automated platforms. If your business doesn’t fit their exact template, or if your financials have a few quirks because you’re self-employed, the computer often says no before a human even looks at your file. It is a rigid approach that doesn’t always account for the reality of running a company in 2026, especially when you need a lender who can see your potential rather than just your past tax returns.

This is where 2nd tier lenders come into play. These are specialised companies that take a more holistic, big-picture view of your situation. They don’t just look at a credit score; they look at your current contracts, your daily cash flow, and your future plans. Speed is another massive factor that sets them apart. While a mainstream bank might take weeks to process a single application, a non-bank lender can often give you an answer in a matter of days. If you have found a piece of equipment you need to buy immediately to finish a lucrative job, that speed is worth its weight in gold. Knowing when to use a bank for low-cost, slow-moving debt and when to look for alternative capital is a key skill for any growing business.

The benefits of 2nd tier lending solutions

They offer much more flexible criteria, which is a lifesaver for self-employed Kiwis who might not have two years of perfect tax returns ready to go. If your business has a shorter trading history, a 2nd tier lender is far more likely to listen to your story and look at your bank statements to understand your true earning power. You get a personalised assessment from a person who understands the local market, rather than just being a number in an automated bank queue.

Comparing the long-term costs

We often talk to clients who are worried about the cost of non-bank finance. It is true that 2nd tier lenders often charge a slightly higher interest rate than a mainstream bank. However, you have to weigh that cost against the opportunity of growth. A slightly higher rate is often worth the ease of access if it means you can secure a new contract or expand your team today. Many of our clients use this type of finance as a stepping stone; you use the funds to grow your turnover and prove your stability, which eventually makes you more attractive to a mainstream bank later on. For a deeper dive into these differences, you can read our guide on Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026.

Small Business Loan NZ: A Roundup of Funding Options for 2026

How to get your business “loan-ready” in 5 steps

Preparing for a small business loan NZ is a lot like getting a house ready for an auction. You want to make sure everything looks its best before the inspectors start poking around. It isn’t just about filling out a form; it’s about presenting a professional, reliable image of your company. The first and most vital step is to organise your financials. Ensure your Profit and Loss statement and balance sheet are completely up to date. Lenders need to see that you have a firm grip on your numbers. If your records are a bit of a muddle, it signals to the lender that your management might be too.

Next, you must know your “why”. You need to be able to explain, in plain English, exactly how the funds will generate a profit. If you’re borrowing to buy a new piece of specialised machinery, show them the extra revenue that machine will bring in each month. Lenders love a clear plan. While you’re at it, check your credit score. Many owners forget that lenders will often look at both your business and personal credit history. If there’s an old, unpaid utility bill from five years ago causing a blemish, it’s better to fix it now rather than being surprised during the application process. You should also identify what security you can offer, whether it’s the asset you’re buying or equity in a property, to help lower your interest rate.

Finally, don’t try to navigate this alone. Talking to an expert who understands the 2026 lending market can save you dozens of hours of legwork and help you avoid the common traps that lead to a “no”. If you want to put your best foot forward, you can get in touch about a business loan with a team that knows exactly what lenders are looking for.

The documents you’ll likely need

Most lenders now use secure digital links to view your last six months of bank statements, which saves you from printing out reams of paper. You’ll also need a clear, one-page summary of what the funds are for and proof of your business registration and GST status. Having these ready to go shows you’re serious and well-organised.

Common pitfalls to avoid

One of the biggest mistakes is “credit shopping” by applying to multiple lenders at once. Each application can leave a mark on your credit file, and too many at once makes you look like a high-risk borrower. Also, be careful not to underestimate how much you actually need. It’s often better to borrow a slightly larger amount once than to have to go back and ask for more a few months later. Lastly, always have a plan for how you’ll manage repayments during those inevitable quiet months.

Many business owners feel like they are shouting into a void when dealing with big bank call centres. An automated application might be efficient for the bank, but it rarely captures the nuance of your specific situation. Securing a small business loan NZ should be a collaborative process, not a cold transaction. Having a steady hand to guide you means having someone who knows how to frame your story so lenders see the opportunity rather than the risk. It is about moving away from the “computer says no” culture and towards a solution that actually supports your goals.

With 20 years of banking experience, our team has seen how the internal gears of lending institutions turn. We know the questions they will ask before they even ask them. This deep institutional knowledge allows us to act as your dedicated advocate, negotiating terms that a standard application would never uncover. We don’t just look for any loan; we look for the one that fits your business lifecycle. Whether you are a tradie needing a new vehicle or a company looking for complex funding, we bridge the gap between the rigid world of banking and your personal needs as a borrower.

The Mortgage Suite difference for business owners

It starts with personal mentorship from Krish Krishna and the team. We don’t just process files; we provide a consultative experience that helps you understand your options clearly. We specialise in both residential and commercial property-backed business loans, which often provide the most cost-effective way to fund growth. By using equity in your home or premises, we can often unlock better rates than standalone business debt. Our focus is always on the long-term relationship. We want to see your business thrive year after year, which is why we prioritise your success over just closing a one-off transaction.

Taking the next step for your business

The path to growth doesn’t have to be paved with endless paperwork and stress. A quick conversation is often all it takes to clarify which funding option is best for your current stage. We handle the heavy lifting, from the initial negotiations to the final signatures, so you can stay focused on running your company. Having a professional handle the legwork ensures you don’t miss out on better terms simply because you didn’t have time to shop around. If you are ready to explore what is possible, reach out for a no-obligation chat about your goals. We are here to help you find a way forward that feels right for you and your future.

Empowering your business for the years ahead

We have explored how the right funding acts as a powerful catalyst for growth, whether you are choosing between secured debt or understanding why 2nd tier lenders offer the flexibility mainstream banks lack. Getting your company “loan-ready” by organising your financials and knowing your “why” is the most effective way to secure the capital you need to scale. By understanding the full range of options available in 2026, you can make a decision that supports your cash flow rather than hindering it.

Navigating the search for a small business loan NZ doesn’t have to be a solo mission or a source of stress. With over 20 years of banking and brokerage experience, our team at Mortgage Suite Ltd specialises in finding creative solutions for businesses that big institutions often decline. We provide a highly personalised, jargon-free service that treats you like a partner rather than just another application number. Let’s find the right business loan for your next big move and ensure your company has the steady financial support it deserves. You have already done the hard work of building your business; now let us help you secure its future growth with confidence.

Frequently Asked Questions

What is the maximum amount I can borrow for a small business loan in NZ?

The maximum you can borrow for a small business loan NZ typically reaches up to $500,000 with many specialist lenders. Some providers offer smaller amounts starting from $2,000 to cover minor expenses. Your specific limit depends on your company’s turnover, how long you have been trading, and whether you are providing any assets as security for the debt.

Do I need to provide security like my home for a business loan?

You don’t always need to use your family home as security for a business loan. Many lenders offer unsecured options that rely on your business’s cash flow instead of physical assets. However, if you do choose to use property as a guarantee, you will often be rewarded with a lower interest rate and a higher borrowing limit because the lender’s risk is lower.

How long does the application process usually take for a non-bank loan?

Non-bank lenders usually move much faster than traditional institutions, often providing an initial decision within 24 to 48 hours. If your paperwork is organised and you use digital bank statement links, the funds can sometimes be in your account within a single business day. This speed is a massive help when you need to jump on a time-sensitive opportunity or fix a cash flow gap.

Can I get a business loan if I have only been trading for six months?

Yes, you can certainly find funding even if you have only been trading for six months. While mainstream banks often want to see two years of perfect tax returns, 2nd tier lenders are more interested in your recent bank statements and growth potential. You might find that an unsecured small business loan NZ is a more accessible option at this early stage of your journey.

What is the difference between a secured and an unsecured business loan?

The main difference is what happens if you can’t make your repayments. A secured loan is backed by a physical asset, like a truck or a property, which the lender can take if things go wrong. Because this is lower risk for them, the interest rates are usually cheaper. Unsecured loans don’t require assets but come with higher rates to cover the lender’s extra risk.

How do interest rates for business loans compare to home loan rates?

Interest rates for business loans are almost always higher than home loan rates because the risk to the lender is greater. For example, while a home-backed business rate might sit around 6% to 10%, an unsecured loan from a specialist lender could start at 14.99% and go higher. It’s a trade-off for the speed and flexibility you receive when you don’t fit the standard bank criteria.

Can I use a business loan to pay off tax debt or existing creditors?

Yes, using a business loan to clear tax debt or pay off urgent creditors is a common strategy to get a company back on track. Many 2nd tier lenders are happy to help with debt consolidation if it means your daily cash flow will improve. It’s often better to have one manageable loan repayment than several stressful debts hanging over your head while you’re trying to grow.

Will a business loan application affect my personal credit score?

Applying for a business loan will usually show up on your personal credit report. Most lenders perform a thorough check of your credit history as part of their assessment process. It’s a good idea to avoid applying to several different lenders at once. Too many enquiries in a short space of time can lower your score and make you look like a higher risk to potential lenders.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mainstream vs Second Tier Lenders in NZ: The 2026 Professional Guide

Getting a “no” from a major bank often has more to do with their rigid, automated algorithms than your actual ability to manage a mortgage. It is a common frustration in 2026, especially as debt-to-income restrictions and strict “box-ticking” criteria make it harder for self-employed Kiwis or those with unique financial stories to secure a home loan. You might feel like you’re being penalised for not fitting a narrow mould, but the reality is that the traditional banking system simply isn’t designed to read between the lines of a non-standard application.

We understand the hesitation that comes with looking beyond the big four banks. You want to ensure you aren’t being exploited by high interest rates or caught in a loan that doesn’t serve your long-term goals. This guide clarifies the landscape of mainstream vs second tier lenders nz, helping you decide which path actually supports your property ambitions. We’ll show you why a second-tier lender can be a powerful, regulated stepping stone that builds the equity you need to eventually return to a mainstream bank. From understanding the new 2026 FMA regulations to comparing current near-prime rates, you’ll gain the confidence to choose a lender that treats you as a partner, not just a transaction.

Key Takeaways

  • Learn to distinguish between the “Big Four” banks and reputable institutional non-bank lenders to find a partner that suits your unique financial situation.
  • Understand the regulatory protections under the CCCFA that ensure alternative lending is a safe, professional choice rather than a risky last resort.
  • Evaluate the practical trade-offs of mainstream vs second tier lenders nz, including how a small interest rate premium provides the flexibility needed for non-standard applications.
  • Discover why self-employed status or minor credit issues needn’t stall your property journey when working with lenders who look beyond automated tick-boxes.
  • Develop a clear 12-to-24-month roadmap to use second-tier lending as a strategic bridge, allowing you to build the equity required to transition back to a mainstream bank.

Defining the Landscape: Mainstream Banks vs Second Tier Lenders

To understand the choice between mainstream vs second tier lenders nz, we must first look at how the market is structured. In the top tier, we have the registered banks. These are the household names like ANZ, ASB, BNZ, and Westpac, often referred to as the “Big Four,” alongside the locally owned Kiwibank. These institutions are the backbone of Banking in New Zealand, operating under strict prudential supervision from the Reserve Bank. They are designed for high-volume, low-risk lending, which makes them efficient for “standard” borrowers but often inaccessible for everyone else.

Second-tier lenders, such as Avanti Finance, Resimac, and Pepper Money, aren’t registered banks but are sophisticated financial institutions. The primary difference lies in their engine room. While mainstream banks fund their lending largely through customer deposits, second-tier lenders access wholesale capital markets. This distinction is crucial because it gives non-bank lenders the flexibility to design products that don’t have to fit the rigid regulatory moulds imposed on traditional banks. Calling them “Tier 2” is often a misnomer; these are institutional-grade organisations with robust balance sheets and professional management that offer a viable alternative within the landscape of mainstream vs second tier lenders nz.

The “Mainstream” Philosophy: Why Banks Say No

Banks are built for efficiency and volume. They rely on automated algorithms to process thousands of applications, which means if your situation doesn’t fit a pre-defined “box,” the computer often says no. This isn’t a reflection of your financial character. It’s frequently a result of the Reserve Bank’s LVR (Loan-to-Value Ratio) restrictions. For instance, banks can only allocate 25% of their new owner-occupier lending to those with less than a 20% deposit. If a bank has already reached this quota for the quarter, they’ll decline even the strongest applications simply because they don’t have the regulatory room to say yes.

The Second Tier Spectrum: Near-Prime to Specialist

The non-bank sector is not a monolith. It’s a broad spectrum designed to catch what the banks miss. It includes:

  • Near-Prime: These loans are for borrowers who are almost “bank-ready” but might have a slightly lower deposit or a very minor credit hiccup from years ago.
  • Specialist: This category serves complex scenarios, such as self-employed individuals with only one year of financial accounts or those with non-standard income streams.
  • Private Lending: These are typically short-term, asset-based solutions for property development or urgent business needs where speed is more important than the long-term interest rate.

This variety ensures that even if the mainstream path is blocked, there’s usually a professional alternative available that views your application with a human eye rather than an automated script.

The Safety Factor: Are Non-Bank Lenders Regulated in New Zealand?

A common concern when comparing mainstream vs second tier lenders nz is the perceived risk of leaving the big banks. Some borrowers worry that stepping away from a household name means entering an unregulated “wild west” of finance. This is a misconception. The New Zealand non-bank sector has undergone a period of intense professionalisation, moving far beyond the “loan shark” tropes of the past. Today, these institutions are sophisticated, highly capitalised, and subject to stringent legal frameworks.

Your consumer rights do not change based on who provides your mortgage. Whether you’re with a multi-national bank or a specialist provider, you’re protected by the same legislation. From 1 July 2026, the Financial Markets Authority (FMA) takes over the administration and enforcement of the Credit Contracts and Consumer Finance Act (CCCFA). This shift brings consumer credit under a unified conduct regime, ensuring that fairness and transparency are non-negotiable standards across the entire industry.

The CCCFA and Responsible Lending Obligations

The law is very clear about the duties of a lender. Every provider must follow strict responsible lending principles, which include a legal requirement to verify that you can afford the loan without suffering substantial hardship. If you’re exploring 2nd tier loans, you can be certain that the lender is legally bound to assess your income and expenses just as rigorously as a mainstream bank. In 2026, the CCCFA serves as the primary legislative shield that mandates transparency, prohibits oppressive conduct, and ensures all borrowers are treated with a high standard of care throughout the life of their mortgage.

Hardship protections are also universal. If your circumstances change, every lender in New Zealand is required to have clear processes for managing financial difficulty. This provides a safety net that ensures you aren’t left vulnerable if life takes an unexpected turn.

Institutional Backing and Stability

Stability is often a point of confusion. While mainstream banks are “Registered Banks” subject to Reserve Bank prudential supervision, many second-tier lenders are either NZX-listed entities or backed by massive global investment firms. Their business models are built on long-term reputation and reliability. It’s helpful to remember that while a bank is a “Deposit Taker” (they hold your money), a non-bank lender is a “Lender Only.” In this relationship, the lender’s stability matters far less to you than your stability matters to them. They’ve already provided the capital; your only job is to manage the repayments. This structure makes mainstream vs second tier lenders nz a comparison of two equally professional, yet differently funded, paths to home ownership.

Side-by-Side: Comparing Interest Rates, Fees, and Lending Criteria

When weighing up mainstream vs second tier lenders nz, the conversation usually starts with the interest rate. It’s a natural focus for any borrower. In the current 2026 market, you’ll notice a gap between bank “specials” and the rates offered by institutional non-bank lenders. This gap is known as the risk premium. It isn’t a penalty for having a non-standard profile; it’s a reflection of the specialised manual underwriting required to approve your loan and the higher cost of wholesale funding. While mainstream 1-year fixed rates might sit between 4.49% and 4.79%, near-prime alternatives often start slightly higher, reflecting the added flexibility they provide.

Fee structures also differ between the two tiers. Mainstream banks might waive application fees for standard residential loans to attract volume. In contrast, second-tier lenders typically charge an establishment fee. These fees often range from $2,000 to $5,000 depending on the complexity of the application. While this is an upfront cost, it’s often the price of admission for a bespoke solution that a bank simply cannot offer. You are essentially paying for a human to look at your story rather than a computer rejecting your data.

The Cost of Flexibility: Is it Worth It?

Don’t let a small interest rate premium deter you from your property goals. Consider a comparison between a 6.5% bank rate and a 7.5% second-tier rate over a 24-month horizon. On a $500,000 mortgage, the difference is roughly $5,000 a year. If national house prices have risen 5.1% year-to-date in 2026, the “opportunity cost” of waiting two years for a bank to say “yes” far outweighs the extra interest. You’re buying time and entry into the market. Additionally, non-bank lenders usually have fewer “strings attached” regarding your broader finances. They won’t demand you move your credit cards or insurance to them, giving you greater control over your financial life.

Servicing and Uncommitted Income

Banks are notorious for “shading” income. They might only count 80% of your bonuses or commissions, which can significantly reduce your borrowing power. Second-tier lenders take a more realistic approach. They often look at the full picture of your earnings, which is a key advantage when comparing mainstream vs second tier lenders nz for self-employed borrowers. By using a more generous Uncommitted Monthly Income (UMI) threshold, a non-bank lender might qualify you for a loan amount that is $100,000 higher than a mainstream bank would allow. While mainstream banks often apply a servicing sensitivity rate of 2% to 3% above their floating rate, second-tier lenders frequently use a lower buffer or a more nuanced assessment of your actual living expenses.

Mainstream vs Second Tier Lenders in NZ: The 2026 Professional Guide

Identifying the Right Fit: When to Move Beyond the Big Four

Banks are designed for the “vanilla” borrower. If you have a steady PAYE job, a 20% deposit, and a flawless credit history, the major banks will welcome you with open arms. However, life rarely follows such a straight line. Choosing between mainstream vs second tier lenders nz becomes a critical decision when your financial profile has a few more “flavours” than the banks are comfortable with. Whether it’s the way you earn your living or a minor stumble in your past, there are specific scenarios where moving beyond the Big Four isn’t just an option; it’s a strategic necessity.

Property type also plays a massive role in a bank’s appetite for risk. If you are looking at a tiny apartment under 40 square metres, a leasehold property, or a remote rural block, you might find bank criteria suddenly tighten or disappear entirely. Mainstream lenders often have rigid “red zones” for certain postcodes or construction types. Second-tier lenders tend to be more pragmatic, assessing the specific asset and its value rather than applying a blanket rejection to anything non-standard.

Self-Employed and Business Owner Solutions

Banks love predictability. For a business owner, predictability is often a luxury that doesn’t show up on a standard tax return. Most mainstream banks demand at least two years of perfect financial statements before they’ll even consider an application. This creates a massive hurdle for entrepreneurs who are growing rapidly or have legitimate tax-effective accounting structures. Second-tier underwriters provide a “manual touch” that banks lack. They are often happy to verify income using GST returns or a letter from your accountant. This flexibility is essential when you need residential investment property loans NZ to help expand your portfolio while your business capital is tied up in operations.

Credit Impairment and the Path to Recovery

A missed power bill from five years ago shouldn’t be a life sentence for your mortgage aspirations. Unfortunately, bank algorithms often see any credit “blip” as an automatic decline. Specialist lenders distinguish between active defaults and historical mishaps. They want to hear the story behind the score. Was the default due to a genuine dispute or a period of illness that has since been resolved? By understanding the context, they can offer home loans for first home buyers New Zealand even when the applicant’s history isn’t perfect. This approach allows you to secure your home now, build a clean repayment history, and prepare for a future move back to a mainstream bank.

If you have been told “no” by your bank because you don’t fit their narrow criteria, talk to us about a tailored solution that recognises your true financial potential.

The Strategic Exit: Transitioning from Second Tier Back to Mainstream

One of the most significant misunderstandings about mainstream vs second tier lenders nz is the idea that once you step outside the big banks, you are “stuck” there forever. In reality, a second-tier loan should often be viewed as a strategic bridge rather than a final destination. For many Kiwis, these lenders provide the essential entry point into the property market, allowing them to build equity and establish a track record while they prepare for a future transition back to Tier 1 banking.

A successful exit strategy usually operates on a 12-to-24 month roadmap. During this period, your primary focus is “conduct.” While a second-tier lender might have been more flexible with your initial application, a mainstream bank will eventually scrutinise your recent history with an uncompromising eye. To be bank-ready, you must demonstrate 100% on-time repayments across all facilities, including your mortgage, credit cards, and utility bills. Banks typically look at the most recent six to twelve months of account behaviour; even a single unarranged overdraft can reset your progress.

Equity growth is the second pillar of your transition. With national house prices having risen 5.1% year-to-date in 2026, many borrowers find that the combination of market growth and their own principal repayments helps them reach the 20% LVR “sweet spot” faster than anticipated. When your equity improves and your financial conduct is spotless, you gain the leverage needed to refinance. We keep a close watch on the Official Cash Rate (OCR), which sits at 3.25% as of Q2 2026, to help you time your move when bank appetite and interest rate cycles align in your favour.

Building the “Bank-Ready” Profile

Organising your finances for a mainstream bank requires a disciplined approach. This involves more than just paying bills on time. It means cleaning up discretionary spending and ensuring your income is documented exactly how a bank underwriter expects to see it. Working with a specialist advisor is vital here; we help you identify the specific triggers that will make a mainstream bank say “yes.” Remember that while second-tier lenders provide an invaluable service, “loyalty” in the lending world can be expensive. Staying with a higher-interest provider longer than necessary can cost you thousands in potential savings.

Consulting a Seasoned Expert

Navigating the nuances of mainstream vs second tier lenders nz requires a guide who understands both worlds intimately. Krish Krishna brings 20 years of deep banking experience to your side, acting as a dedicated negotiator who speaks the language of both institutional banks and non-bank providers. This high-level consultancy ensures your transition is seamless, proactive, and focused on your long-term wealth. We don’t just help you get a loan; we help you manage a lifecycle of lending that evolves with your success.

Ready to find your best path? Book a consultation with Mortgage Suite Ltd today and let’s map out your journey back to mainstream banking.

Take Control of Your Property Journey

A bank rejection isn’t the end of your home ownership dreams; it’s simply a sign that you need a more sophisticated approach. Understanding the nuances of mainstream vs second tier lenders nz allows you to stop trying to fit into a bank’s rigid box and start using the specialised tools available in the 2026 market. By viewing a non-bank loan as a regulated, strategic bridge, you can secure your property now and build the clean repayment record needed to return to a major bank on your own terms.

With over 20 years of banking and lending expertise, we specialise in 2nd tier loans that banks often decline. We provide personalised advocacy and expert negotiation for every client, ensuring you aren’t just getting a loan, but a clear, long-term financial roadmap. You don’t have to navigate these complex decisions alone when you have a seasoned partner ready to champion your success.

Secure your financial future with a tailored lending strategy from Mortgage Suite. Your property goals are within reach, and we are here to help you bridge the gap with absolute confidence.

Frequently Asked Questions

Are second-tier lenders safe to use in New Zealand?

Yes, they are entirely safe and professional. In New Zealand, all non-bank lenders must adhere to the same responsible lending principles as major banks. They are regulated under the CCCFA and overseen by the Financial Markets Authority. Because they don’t take deposits from the public, your primary relationship is as a borrower; this means your focus is simply on meeting your repayment obligations under a legally binding contract.

How much higher are the interest rates with a non-bank lender?

You can generally expect to pay a premium of between 1% and 2% above standard bank rates. This difference reflects the specialised nature of the lending and the higher cost of wholesale funding. When comparing mainstream vs second tier lenders nz, it’s vital to view this extra cost as an investment in market entry rather than a permanent expense, especially if it allows you to secure a property in a rising market.

Can I move back to a mainstream bank if my credit improves?

Absolutely, and for many of our clients, this is the ultimate goal. Once you have established a clean repayment history and your credit score or equity has improved, you can look to refinance. This transition usually takes between one and two years of flawless financial conduct. We work with you to ensure your profile meets the stricter “box-ticking” requirements of the major banks when the time is right to move.

Do second-tier lenders require a larger deposit?

Second-tier lenders often provide more flexibility regarding your deposit size. While mainstream banks are heavily restricted by Reserve Bank LVR rules, non-bank providers can sometimes consider applications with lower equity if the overall security and income are strong. This makes them an excellent option for those who are close to a 20% deposit but aren’t quite there yet, helping them avoid the rigid “no” from traditional institutions.

What happens if a second-tier lender goes out of business?

Your mortgage contract and its terms remain legally protected. If a lender ceases operations, their “loan book” is typically sold to another reputable financial institution. You will simply continue making your repayments to the new provider under your original agreement. Because the lender has already advanced you the capital, their internal business changes don’t negatively impact your right to remain in your home as long as you meet your obligations.

Why would my mortgage broker suggest a second-tier lender over a bank?

A specialist advisor suggests these lenders when they provide the only viable path to a “yes.” If you are self-employed or have a non-standard income, a bank’s automated system might reject you instantly. Second-tier lenders use manual underwriting to understand your specific story. They are often the best tool for bridging the gap between a bank decline and successful home ownership, providing a bespoke solution that traditional banks aren’t built to handle.

Are there hidden fees associated with non-bank mortgages?

There are no “hidden” fees; all costs must be clearly disclosed upfront under New Zealand law. You will likely encounter an establishment or application fee, which covers the cost of the manual assessment. While these fees are higher than what a bank might charge for a standard loan, they are transparently listed in your loan offer. We ensure you understand every dollar involved before you sign any documentation.

Can I get a first home grant if I use a second-tier lender?

Yes, using a non-bank lender does not prevent you from accessing government assistance. As long as you and the property meet the standard Kainga Ora requirements, you can still utilise the First Home Grant or other support schemes. The choice of mainstream vs second tier lenders nz is separate from your eligibility for these grants, meaning you can still benefit from government help while using a more flexible lending provider.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.