
New Build Turnkey Loans NZ: How to Compare Your Options

The lowest interest rate may not be the best starting point when you’re comparing new build turnkey loans nz. The contract’s payment dates need to line up with the lender’s assessment and settlement process, and turnkey finance can work differently from buying an existing home or funding a build in stages.

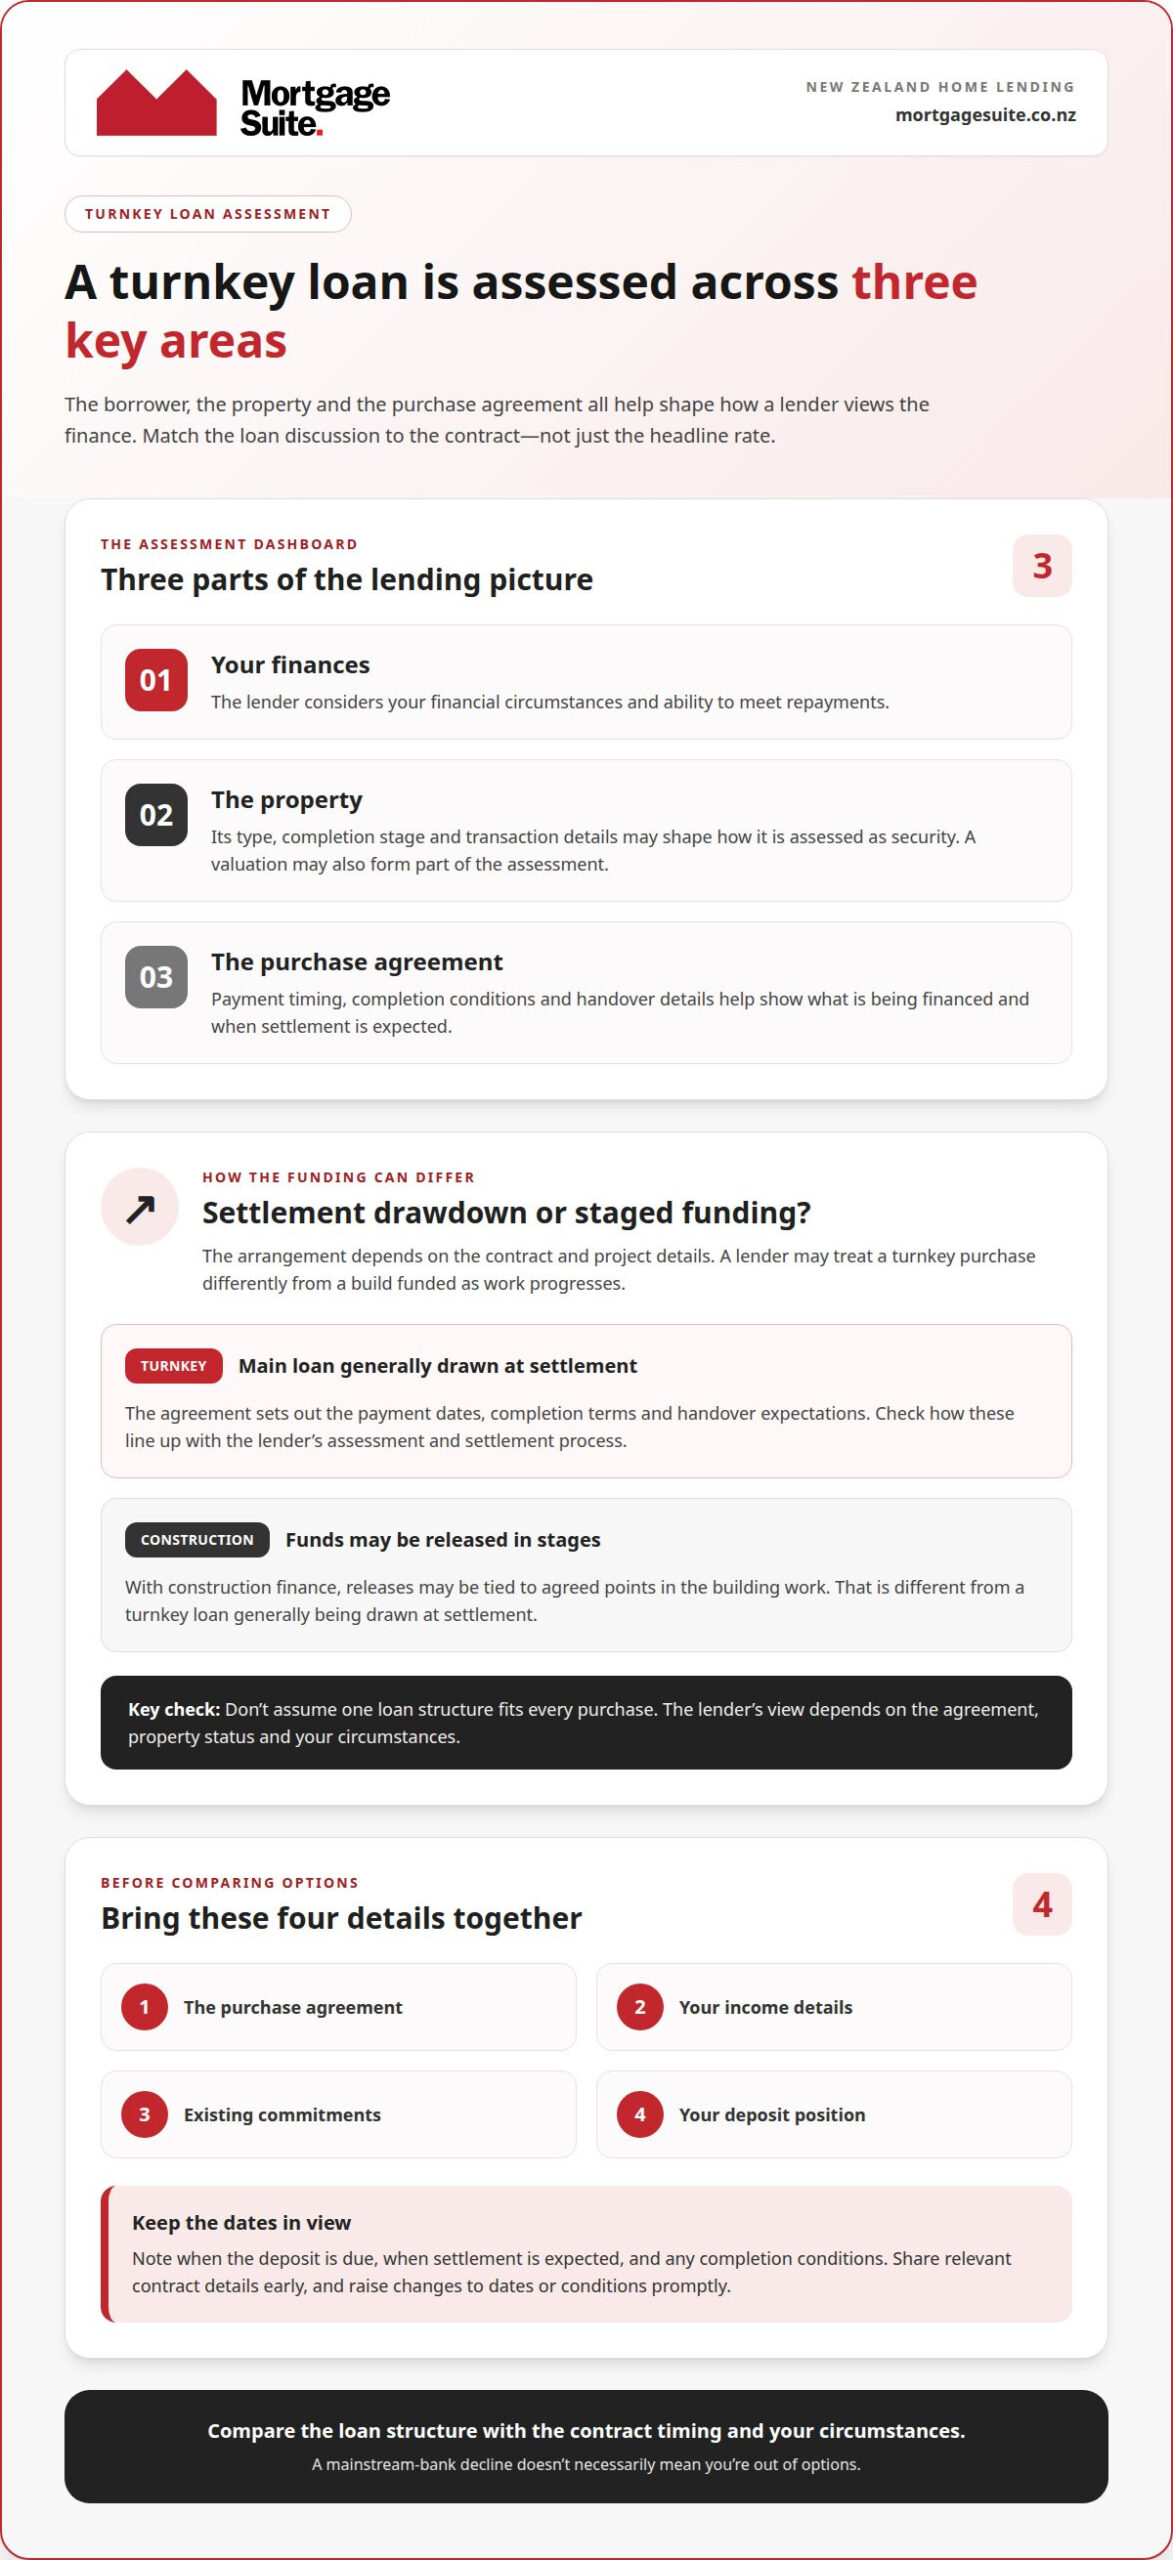
With a turnkey build, the main loan is generally drawn at settlement rather than released in stages during construction. Before signing or relying on a particular loan structure, understand when your deposit is due, when settlement is expected and what the lender will assess.

This guide explains how turnkey lending differs, what lenders may consider and how to compare options beyond the headline rate. It also covers what to prepare for a conversation with a mortgage adviser. Mortgage Suite Ltd can help you weigh lender fit against your circumstances and contract, and support you through a process that can feel stressful. A decline from a mainstream bank doesn’t necessarily mean you’re out of options.

Key Takeaways

  • New build turnkey loans nz can differ from off-the-plans purchases and construction finance. Use the contract and lender’s assessment to understand which structure may fit.
  • Discuss your finances alongside the property and purchase agreement. A valuation may also form part of the lender’s assessment.
  • Gather your agreement, income details, existing commitments and deposit position before comparing proposed loan structures.
  • Look beyond the headline interest rate and consider how each option fits the contract timing and your circumstances.
  • Mortgage Suite can help you compare lender fit. Founder Krish Krishna started the business in 2000 after 18 years in banking.

What are new build turnkey loans in NZ and how do they work?

A turnkey home is a new property sold under an agreement that sets out how and when the home will be completed and handed over. The aim is for you to take possession of a finished home, but the details depend on the contract. Inclusions, completion conditions and payment dates all affect how you plan your finance.

New build turnkey loans nz aren’t simply a standard mortgage with a different label. A lender may consider the property’s status, the agreement and your financial circumstances when assessing how the loan could be arranged. Read the payment and completion terms carefully, then compare them with the proposed finance before relying on a particular structure.

What does turnkey mean when buying a new home?

“Turnkey” generally describes a home sold with an agreed completion and handover position. The contract sets out what you can expect, so don’t assume every finished home includes the same fittings, finishes or extras. Check the inclusions, any conditions that must be met before handover, and the payment dates. These details help you understand what the lender is being asked to finance and when funds may be needed.

For example, if the home is still being completed, compare the contract’s list of inclusions with the expected handover conditions. Then map the stated payment dates against your finance discussions. As completion approaches, the lender assesses the application in light of the agreement and the property’s status. Settlement follows the contract requirements once the relevant conditions are met. The contract sets the actual sequence, so don’t assume every purchase follows the same timeline.

Is turnkey finance the same as a construction loan?

Not necessarily. A turnkey purchase may be financed as a property purchase, with lending arranged for settlement under the agreement. A construction loan, by contrast, may release funds in stages as building work reaches agreed points. The turnkey contract concept centres on delivery of a completed project, while staged funding is tied to progress during the build. How a lender treats a particular arrangement depends on its details.

The signed agreement and the project stage matter. A home close to completion may raise different finance questions from a project where building has only just begun. The lender may assess the purchase terms, the property and your ability to meet repayments before deciding on a suitable structure. Neither a purchase-style loan nor staged construction finance is automatically right for every buyer.

Before signing, make sure you understand the agreement’s payment dates, completion terms and handover expectations. Resolve any uncertainties before assuming a particular finance arrangement will fit. For buyers considering new build turnkey loans nz, matching the loan discussion to the contract can help reduce the risk of a timing mismatch and make the next steps easier to plan.

How lenders assess a turnkey home loan in New Zealand

A lender considers more than the home itself. It will look at your finances, the property and the agreement that sets out how the sale will proceed. Your ability to repay matters, as do the property’s status and the timing and conditions in the contract.

A turnkey loan assessment brings together three broad areas: the borrower, the property and the purchase contract. Sharing the agreement early can help you discuss whether a proposed lending structure fits the transaction, rather than focusing only on the amount you hope to borrow.

What parts of the purchase agreement matter to finance?

Pay close attention to payment timing, completion conditions and handover details. The lender needs a clear picture of what you’re buying and when settlement is expected. If the contract dates and conditions don’t align with your finance arrangements, you may be unsure whether lending will be ready when needed. Include the contract in the finance conversation from the outset.

Read the agreement with your solicitor, who can advise you on its legal meaning. For the loan discussion, note the key dates and conditions and share the relevant details with your adviser. If a completion date changes or a condition affects settlement, raise it promptly so the finance plan can be considered against the updated position. This doesn’t replace legal advice. It helps keep the lending discussion informed.

What can affect the lender’s view of the property?

The type of home, its completion stage and the transaction details may shape how a lender assesses the property as security. A valuation may help the lender form a view of the property’s value, but whether one is needed and how it’s used depends on the application. Not every turnkey purchase follows the same process.

A completed home and one still awaiting completion provide different information for a lender to consider. The lender may assess the property alongside the purchase terms and your finances, rather than relying on the home’s description alone to decide how the loan should work. That’s one reason to look beyond the name of a proposed structure.

For new build turnkey loans nz, consider how the proposed lending fits your circumstances, the property and the contract’s settlement arrangements. Bring those details together before comparing options, and make sure any changes to the agreement are reflected in the discussion. If you’d value support weighing lender fit against your purchase details, Mortgage Suite’s home loan guidance can help you work through the questions.

Turnkey loan options compared with off-the-plans and construction finance

The useful comparison isn’t about choosing a universally “best” loan type. It’s about when the property is expected to be ready, when funds may be needed and what you’ll need to manage under the contract. For new build turnkey loans nz, the contract and lender assessment determine which finance structure applies. Use the table as a guide, not a rulebook.

Option Property and timing Payment structure and buyer focus
Turnkey purchase The home may be complete or nearing handover, depending on the agreement. Finance is arranged around the purchase and settlement terms. Check what must be completed before settlement and when payments fall due.
Off-the-plans purchase You agree to buy before the home is complete. The contract sets out the expected completion and settlement arrangements. Understand what conditions must be met before settlement and how the timing fits your finance plans.
Construction finance The project is funded while building work is under way. Funds may be released in agreed stages, depending on the finance arrangement and project. Be clear about the stage requirements and your responsibilities.

These are broad distinctions, not guarantees about how a particular lender will treat a purchase. The contract wording, project stage and lender’s assessment all matter. Compare practical details: when will the home be ready, when does the agreement require funds, and does the proposed loan structure match those points?

Turnkey purchase versus buying off the plans

A turnkey purchase may involve a home that’s ready or close to handover, while an off-the-plans purchase is agreed before completion. The contract, not the label, sets out the actual position. Before relying on a finance plan, identify what must happen before settlement, including the completion conditions and handover requirements.

Build timing can change, so don’t assume the expected completion date is certain. If timing shifts, the finance arrangements may need to be considered against the revised position. Your solicitor can explain the legal effect of the contract terms, while your mortgage adviser can help relate the dates and conditions to the lending discussion.

Turnkey purchase versus construction finance

A purchase loan is arranged around buying the property, while construction finance may release funds as agreed building stages are reached. The staged drawdown process depends on the finance arrangement and project, so don’t assume every build follows the same steps. Development funding is a separate consideration from a buyer’s home loan for a completed or near-complete turnkey property.

Use the comparison to clarify responsibilities and timing, rather than assuming one route suits everyone. If you want support comparing lender fit against your contract and circumstances, Mortgage Suite’s home loan guidance can help you work through the options.
New Build Turnkey Loans NZ: How to Compare Your Options

How to prepare for a turnkey home loan conversation

Preparation can make a complex borrowing conversation feel more manageable. Bring together the purchase agreement, a clear picture of your finances and the key dates, then compare proposed loan structures against the contract. This gives your adviser a practical starting point for discussing lender fit and timing.

Work through these steps in order:

  1. Gather the agreement. Have the signed or draft contract available, including payment dates, completion conditions and handover details.
  2. Outline your finances. Be ready to discuss income sources, regular commitments, your deposit position and any other borrowing. Don’t assume one deposit amount will suit every lender.
  3. Identify the timing. Note the expected settlement date and any dates or conditions that could affect when funds are needed.
  4. Compare the proposed structures. Consider how repayments, flexibility and lender conditions fit your plans, as well as the interest rate.

Information to have ready before discussing finance

Useful information includes your agreement, available financial records, key contract dates and a summary of your income and commitments. Think about your broader borrowing goals too, such as the repayment approach you’re comfortable with and how much flexibility matters to you. These details help shape a clearer discussion, but no single document or deposit position guarantees approval.

If parts of your income or commitments vary, explain that clearly rather than trying to reduce them to a simple estimate. The aim is to give your adviser an accurate picture of your circumstances and the purchase, so possible loan structures can be considered in context.

Questions that help compare lender options

Test whether each option fits the transaction, not just whether its headline rate looks appealing. Ask how the proposed loan aligns with the contract’s payment and settlement timing, what repayment choices are available, and which conditions or flexibility features may matter to you. You can also ask how the structure would work if the expected completion timing changed.

To explore repayment scenarios, Mortgage Suite’s mortgage calculator can give you a starting point. Treat any result as an estimate, not a lender offer, and discuss the assumptions behind it with your adviser. Mortgage School resources also offer plain-English explanations of mortgage topics to help you prepare questions.

Comparing new build turnkey loans nz is easier when each option is measured against the same information: your finances, goals and contract. If you’d like help working through those details and comparing lender fit, use the calculator as a first step in exploring repayment scenarios.

How Mortgage Suite can help you compare new build turnkey loans

Choosing finance for a new build can feel like a lot to manage, especially when the lender’s process needs to fit the purchase agreement. Mortgage Suite takes a personal approach: we learn about your goals and circumstances, then compare how different lenders may fit the property and contract. We’ll help you weigh up your options without promising that one lender or loan will suit everyone.

Krish Krishna founded Mortgage Suite in 2000 after 18 years in banking. Since then, he has arranged over a billion NZD across residential, commercial and business lending. That experience informs how we consider the full picture, including the timing and terms of your new-build agreement, rather than judging an option by its headline rate alone.

What working with a mortgage adviser can add

Bringing your finances and contract details together can make it easier to compare options across a wide range of bank and private lenders. Mortgage Suite can help you consider lender fit, discuss possible structures and negotiate on your behalf. The aim is to support an informed decision. No adviser can guarantee a particular rate, approval or outcome.

Client experiences can also give you a sense of the support people have valued. Read Mortgage Suite client reviews to learn about their experiences with guidance and lending negotiations. Every borrower’s circumstances are different, so those stories aren’t a promise that your application will follow the same path.

A calm next step for your new-build plans

You don’t need to have every lending question answered before starting a conversation. Bring the agreement, note the key contract dates, and share your borrowing goals and any concerns about how the finance might fit. Those details can help frame a useful discussion about which options may be worth considering and what questions remain.

If a mainstream bank has already said no, that isn’t automatically the end of your borrowing options. A different lender may assess your circumstances differently, though approval is never assured. The next step is to understand what the decision means for your plans and whether another lender or structure may be a better fit.

If you’re considering new build turnkey loans nz, a first discussion can help clarify how your agreement and finances relate to possible lending options. Bring your questions and contract timing, and talk with Mortgage Suite about your home-loan options.

Take the next step with confidence

Buying a new home is a big personal milestone, and it’s normal to want a clearer sense of what comes next. You don’t need to have every answer lined up. A thoughtful conversation can help you feel prepared to move forward at a pace that suits you.

If you’re exploring new build turnkey loans nz, Mortgage Suite can help you talk through your plans and consider your options. Start a conversation with Mortgage Suite when you’re ready.

Take it one step at a time. The right support can help you approach your new-build plans with greater confidence.

Frequently Asked Questions

Can I apply for a turnkey home loan before signing the purchase agreement?

Yes, you can start discussing finance before you sign. This gives you time to understand what lenders may need and whether your plans appear workable, without treating an early indication as final approval. If the agreement is still being negotiated, tell your adviser what may change. A different purchase price, ownership arrangement or contract condition could affect the application, so avoid making firm commitments based only on an initial conversation.

What happens if the turnkey property’s completion date changes?

A changed completion date may affect the timing of your finance, so get the revised date in writing and tell your adviser promptly. Ask whether any lending approval conditions or time limits need attention, and keep track of updated notices from the seller or developer. If the revised date creates a concern under your agreement, speak with your solicitor about your position and the steps available to you.

Can a turnkey home loan include the land as well as the house?

It can, if the purchase is structured to include both, but the lender needs to understand exactly what you’re buying. Check whether the agreement describes the land and home together or sets them out as separate parts of the transaction. That distinction can affect how the lender assesses the request and what information it needs. Make sure your borrowing discussion reflects the full purchase arrangement, not just the house component.

Can I use a turnkey home as an investment property?

Yes, a turnkey home may be purchased as a residential investment property, subject to the lender’s assessment. Be clear about your intended use from the outset, especially if you plan to rent the home rather than live in it. You can discuss how you expect to manage the property and any rental income as part of your overall finances. The lender will assess your circumstances and the proposed purchase before deciding what it can offer.

What if a bank declines my turnkey home loan application?

A decline doesn’t automatically rule out every option. Start by finding out the main reason for the decision, such as a concern about your application details or the property. Then you and your adviser can consider whether further information may help, or whether another lender could assess the situation differently. Mortgage Suite works across bank and private lenders, including 2nd Tier Loans for borrowers who don’t fit mainstream bank criteria. Approval is never guaranteed.

Does a turnkey home loan require a property valuation?

Not in every case. The lender decides whether it needs a valuation and what information will help it assess the property. If one is requested, ask what it needs to cover and whether it must be completed before a particular stage of the application. This can help you understand the lender’s next steps and avoid assuming that an assessment used for another property or application will be suitable.

Can I change lenders after signing a turnkey purchase agreement?

You can explore another lender after signing, but a new application may involve fresh checks and could take time to progress. Before switching, compare the new lender’s requirements with your existing approval and consider whether the change affects your ability to meet the agreement’s obligations. Your solicitor can advise on the contract, while a mortgage adviser can help you weigh up the lending options. Don’t assume a new application will be approved.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Obtaining Low Equity Loans

What if you could stop paying your landlord’s mortgage and move into your own place next month, even without a massive six-figure deposit tucked away? Many Kiwis feel stuck in the rent trap, fearing that a “no” from the big banks or confusing income caps will keep them from securing a 5 percent deposit home loan nz for years to come. It’s a common worry, but the path to your first home is often closer than it looks when you have a seasoned professional in your corner.

We know how frustrating it is to feel like you’re falling behind while trying to navigate complex banking criteria on your own. You’re about to discover exactly how to secure a home loan with just a 5% deposit and move into your first home sooner than you thought possible. We’ll break down the latest eligibility rules, explore how new builds can bypass traditional restrictions, and show you how professional advocacy can help you organise the paperwork to turn a complex process into a successful move.

Key Takeaways

  • Learn why you don’t need a massive 20% deposit to get started and how a smaller entry point can get you into your home years earlier.
  • Understand the specific income and eligibility criteria needed to qualify for a 5 percent deposit home loan nz through the First Home Loan scheme.
  • Discover why choosing a new build property could be your fastest route to home ownership thanks to special exemptions on deposit requirements.
  • Get practical tips on how to organise your bank statements and KiwiSaver details so the banks see you as a reliable, low-risk borrower.
  • Find out how an expert negotiator with over 20 years of experience can help you find alternative paths when the big banks say no.

Breaking the 20% Rule: How a 5% Deposit Works in NZ

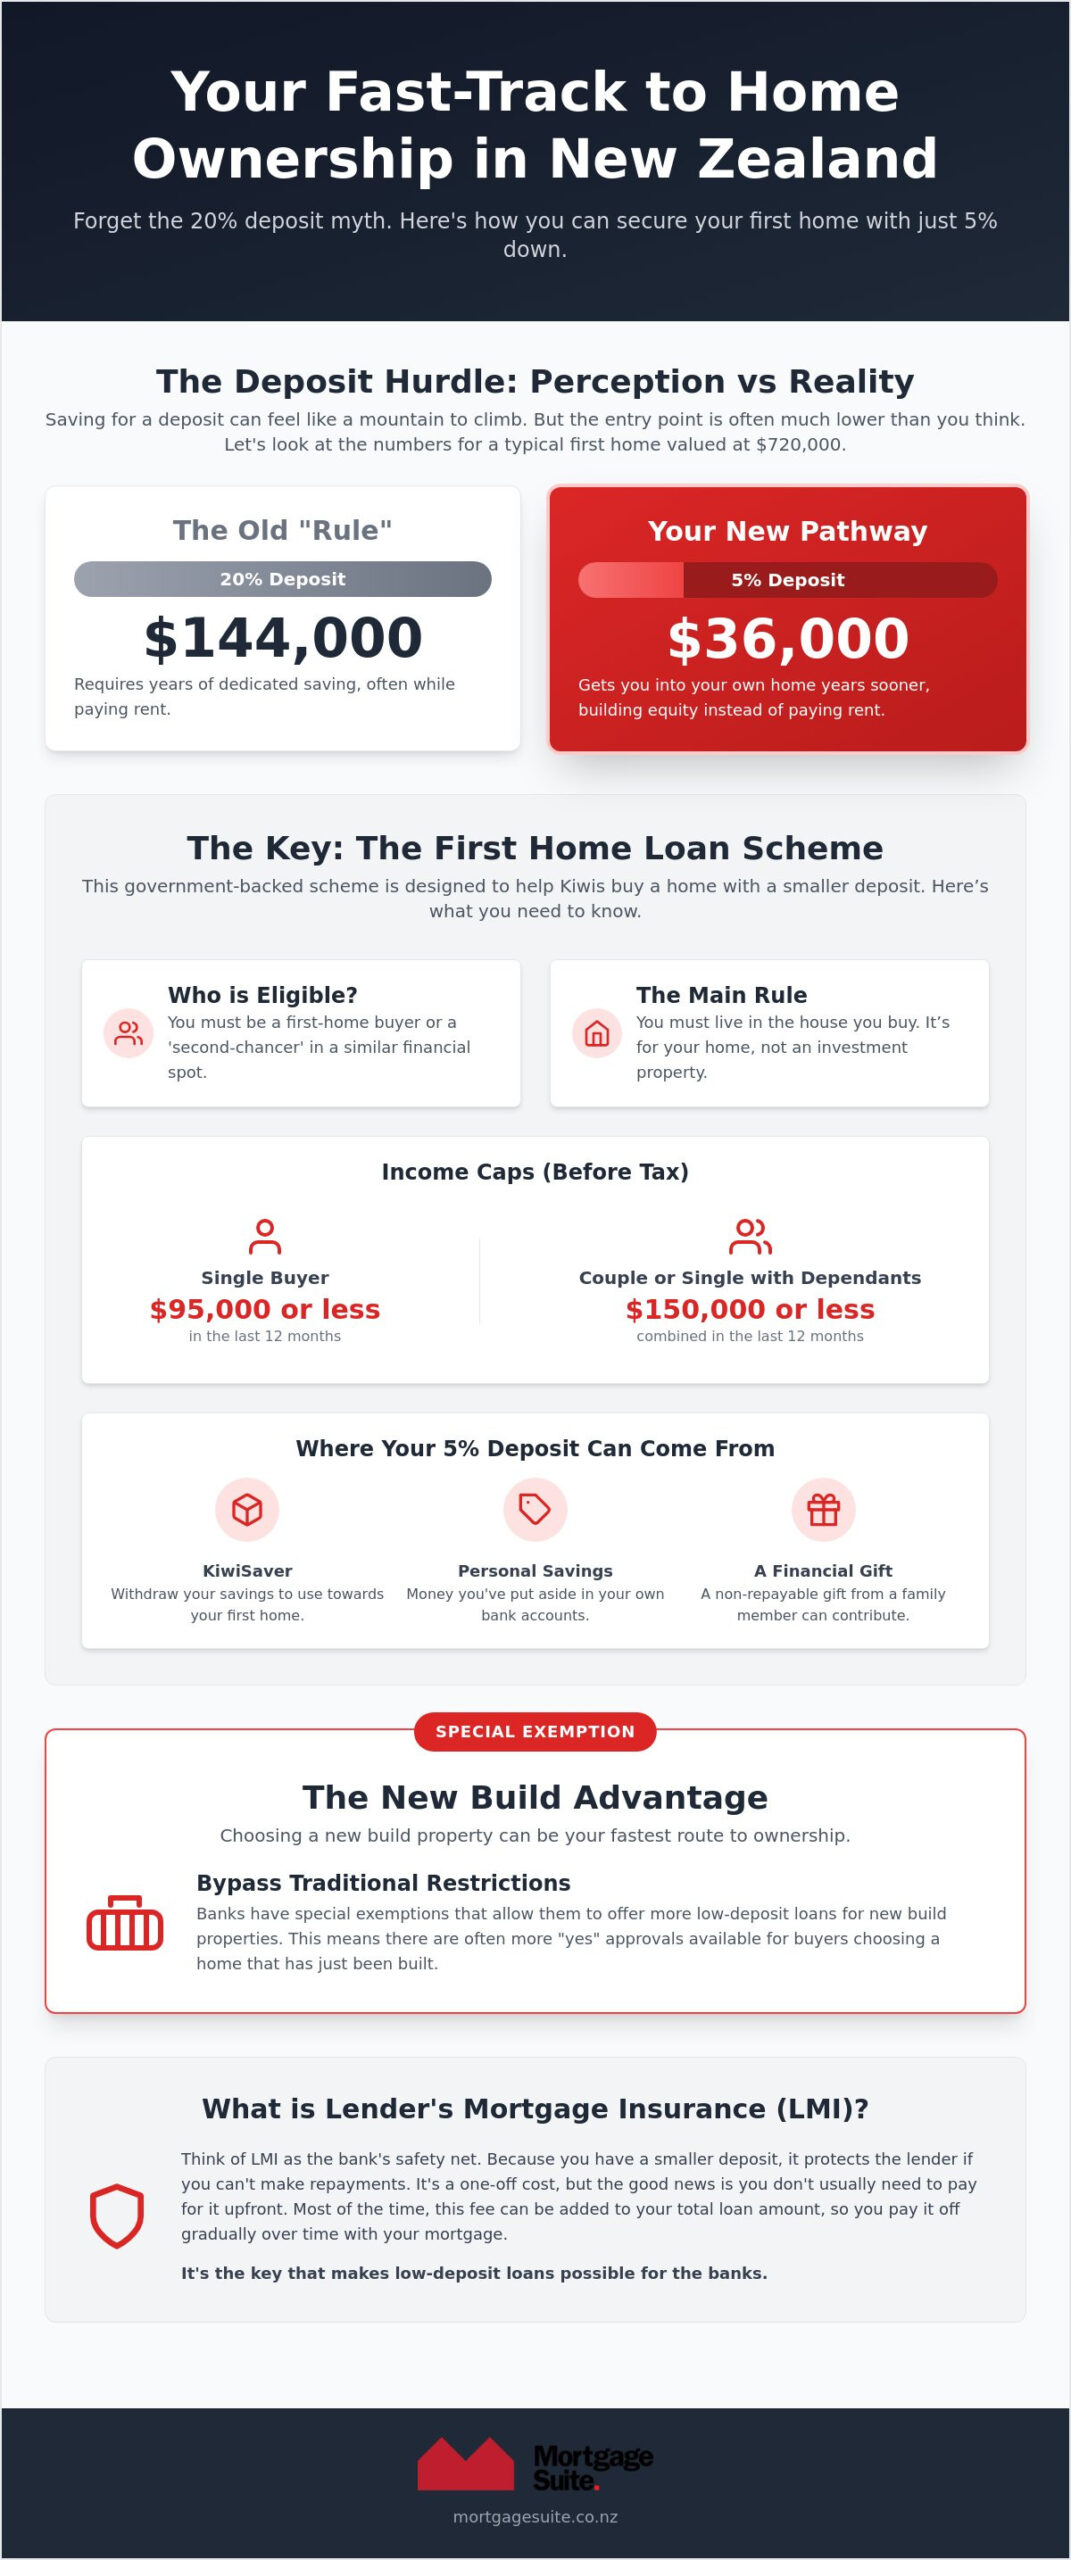
You’ve likely heard that 20% is the magic number for a house deposit. It’s often talked about as if it’s a law, but in reality, it’s just a standard guideline that banks prefer. For many first-time buyers, saving that much cash feels like trying to catch a moving train while you’re still standing on the platform. A 5 percent deposit home loan nz acts as a vital bridge, allowing you to cross over from renting to owning much sooner than you ever thought possible. By only requiring a small portion of the purchase price upfront, these loans help you bypass the years of extra saving that usually keep people stuck in the rent trap.

To understand why banks usually ask for more, we need to look at Loan-to-Value (LVR) restrictions. These are essentially rules that govern how much a bank can lend compared to the value of the property you’re buying. Usually, lenders want a 20% buffer to protect themselves if the market shifts. However, the government often steps in to help by underwriting these low-deposit loans. This means they provide a guarantee that reduces the risk for the bank. When the risk is lower, the bank feels much more comfortable saying “yes” to your application, even with a smaller deposit in your bank account.

What is Lender’s Mortgage Insurance (LMI)?

LMI is essentially a bank safety fee. It’s a one-off cost that protects the lender in case you can’t keep up with your repayments; it doesn’t actually provide any cover for you as the borrower. While it might sound like an extra hurdle, it’s the price of admission for entering the market early. The best part is that you don’t usually need to find this cash on top of your deposit. Most lenders are happy to add this fee to your total loan amount, so it’s paid off gradually over the life of your mortgage rather than all at once.

Why the 2026 Market Favourably Views Low Deposits

In early 2026, the median price for properties bought by first-home buyers reached approximately $720,000. If you were strictly following the 20% rule, you’d need $144,000, which is a massive mountain to climb while living costs are high. Recent data shows that first-home buyers now make up about 27.5% of the market, and over half of them are using deposits of less than 20%. Banks have become more flexible, particularly for buyers who are ordinarily resident in New Zealand and have a stable work history. Getting into a home now with a 5% deposit allows you to start building your own equity through capital gains rather than spending another five years chasing a savings goal that keeps moving further away.

The First Home Loan Scheme: Are You Eligible?

The First Home Loan scheme is the heavy lifter for most low-deposit entries in New Zealand. It’s a partnership between Kāinga Ora and specific lenders designed to help people who can manage mortgage repayments but struggle to save a massive upfront sum. To qualify, you must be a first-home buyer or a “second-chance” buyer who is in a similar financial position to a first-time purchaser. A strict requirement is that you must intend to live in the property as your primary home. This scheme isn’t for people looking to flip houses for a quick profit or build a rental portfolio. If you happen to own Māori land, you might still be eligible, as this usually doesn’t count against you in the same way as owning a standard residential property would.

Income and Savings Requirements

The 2026 criteria for a 5 percent deposit home loan nz are quite specific about what you can earn. If you’re buying on your own with no dependants, your income for the last 12 months must be $95,000 or less before tax. For couples or solo parents with dependants, that combined limit is $150,000. When banks assess your application, they’ll look at your total income package. This includes your base salary, regular bonuses, and even consistent earnings from side hustles. Your 5% deposit can be pulled together from several sources, such as your KiwiSaver withdrawal, personal savings, or even a financial gift from family members. Having these different streams makes the entry point much more accessible for many Kiwi families.

Property Criteria and Regional Differences

There are also rules about the type of property you can buy. The land size is generally limited to one hectare, which fits most standard suburban sections. One significant advantage in the current market is that house price caps were removed back in 2022, meaning you have more freedom to choose a home that fits your needs without being restricted by a specific regional price ceiling. However, you still need to meet the bank’s own lending criteria for the specific property type. For a deeper look at how these rules apply to different regions, you can read The Ultimate First Home Buyer Guide for New Zealanders.

Navigating these various rules and requirements can feel like a lot to handle on your own. If you’re unsure how your specific income or deposit source fits into the scheme, speaking with a professional mortgage broker can help you organise your application with confidence. We can help you determine exactly where you stand before you start visiting open homes.

Comparing Your Options: 5% vs 10% vs New Build Deposits

While a 5 percent deposit home loan nz is a fantastic way to jump into the market, it’s not the only path available. Choosing between a 5% and a 10% deposit often comes down to a trade-off between time and cost. If you wait until you have a 10% deposit, you might secure a slightly better interest rate or reduce your bank safety fees. However, if house prices rise while you’re saving that extra 5%, you could end up needing a much larger loan anyway. It’s a bit of a balancing act. You’ll also find that mortgage rates NZ lenders offer can vary depending on exactly how much skin you have in the game. Generally, the more you can put down, the more “special” rates become available to you.

For those who can’t quite reach that 5% mark on their own, there’s the “Family Springboard” or guarantor model. This is where a family member uses the equity in their own home to help secure yours. It can sometimes allow you to buy with a very small cash deposit, or even none at all, though it requires a high level of trust and clear legal advice for everyone involved. If you don’t have that family support, the First Home Loan scheme remains your strongest bet for a low-deposit entry into an existing home.

The New Build Advantage

New builds are currently the “golden ticket” in the Kiwi property market. Because new homes are exempt from standard lending restrictions, banks are much more relaxed about deposit sizes. You can often secure a “turnkey” property with just a 10% deposit, where you pay a small amount upfront and the rest when the house is finished. The best part is that these 10% new build loans usually don’t have the same strict income caps as government-backed schemes. This makes them a great option for professional couples who earn too much for the 5% scheme but haven’t saved a full 20% yet.

10% Deposits with Mainstream Banks

Mainstream banks do offer 10% deposit loans on existing houses, but they have “speed limits” on how many of these they can approve each month. These are internal quotas set to keep their overall risk in check. This is why you might get a “no” from your own bank even if you have a perfect credit score. They might simply have run out of space for low-deposit borrowers that month. An expert broker knows exactly which bank has “room” in their quota, helping you find a path forward when your local branch can’t help.

Obtaining Low Equity Loans

Step-by-Step: How to Organise Your 5% Deposit Application

Moving from the research phase to an actual application is where the real work begins. Organising a 5 percent deposit home loan nz is about more than just having the cash; it’s about proving to a lender that you are a reliable partner for the next thirty years. Because you’re asking for a higher level of lending, the bank will look at your life through a magnifying glass. Following a clear, logical plan will help you avoid the common pitfalls that lead to a “no” from mainstream lenders.

  • Step 1: Sort your KiwiSaver. Contact your provider early to get a letter confirming your withdrawal eligibility. This is often the biggest chunk of your deposit, so you need the exact figure before you start visiting open homes.
  • Step 2: Clean up your bank statements. Banks really dislike seeing “buy now pay later” payments or frequent gambling on your recent records; these suggest a lack of financial discipline.
  • Step 3: Gather your evidence. You’ll need your last six months of pay slips and a letter from your employer confirming your status. If family members are helping you, you’ll also need a formal gift letter stating the money does not need to be repaid.
  • Step 4: Partner with a broker. Instead of guessing which bank might say yes, a broker can shop your application to the specific lenders most likely to approve a low-deposit loan based on your unique income.
  • Step 5: Confirm your deposit makeup. Since the First Home Grant was discontinued in May 2024, you’ll need to ensure your full 5% is sourced entirely from your savings, KiwiSaver, or family gifts.

Polishing Your Financial Profile

The “three-month rule” is a standard you should live by before you even think about applying. Banks want to see that you can manage your money without relying on credit cards or overdrafts for at least ninety days. If you have car loans or other personal debts, try to pay them down as much as possible because these directly reduce your borrowing power. Uncommitted monthly income is simply the cash you have left over after all your bills and living costs are paid each month. This is the bank’s favourite metric because it shows them exactly how much “breathing room” you have to make mortgage repayments comfortably.

The Role of Pre-Approval

You should never walk into an auction or sign a sale and purchase agreement without a pre-approval in your pocket. For a 5% loan, this process is much more rigorous than a standard application because there is less room for error. Lenders will often put specific conditions on a pre-approval, such as requiring a registered valuation of the property you want to buy. Most approvals last for about sixty to ninety days. If you haven’t found a home by then, you’ll need to refresh the application with your latest pay slips and bank statements. To get your application ready for the bank’s scrutiny, contact Mortgage Suite Ltd today to start the process.

Why a Mortgage Broker is Your Secret Weapon for Low-Deposit Loans

Walking into your local bank branch only gives you one set of options. If that particular bank has already hit its monthly quota for low-deposit lending, they’ll likely tell you “no,” even if your finances are in great shape. A broker works differently by looking at the whole market rather than just one set of products. When you’re aiming for a 5 percent deposit home loan nz, you need an advocate who knows which lenders are currently hungry for new business and which ones have the most flexible criteria for first-time buyers.

At Mortgage Suite, we bring a level of expertise that goes beyond just filling out forms. Krish Krishna offers over 20 years of “insider” banking experience, which means he knows exactly how bank managers think and what they need to see to approve a loan. We do the heavy lifting for you, from organising the initial paperwork to negotiating the best possible terms. This professional advocacy is often the difference between staying in the rent trap and finally getting the keys to your own front door.

When the Mainstream Banks Say ‘No’

There are many reasons why a big bank might turn down an application. Perhaps you’re self-employed and don’t have two years of perfect tax returns yet, or maybe your income comes from several different “side hustles” that don’t fit a standard box. If the big four banks aren’t an option, a 2nd tier lender New Zealand can be a fantastic stepping stone. These lenders often look at the bigger picture and are more willing to help “outside the box” cases. We specialise in these alternative paths, helping you get into a home now so you can start building equity immediately rather than waiting years to fit a traditional bank’s rigid profile.

The Cost of a Broker (Hint: It’s Usually Free for You)

Many first-home buyers are surprised to learn that our services are usually at no cost to them. Brokers are typically paid by the banks, which means you get a professional negotiator and mentor in your corner for free. This is incredibly valuable when you’re dealing with the stress of auctions or making a fast offer on a property. We make sure your finance is robust and ready to go, giving you the confidence to bid when you find a place you love. To see how we can help you navigate the process and find a way forward, get your 5% deposit journey started with a quick chat today.

Move Into Your First Home Sooner Than You Planned

Owning your own home in New Zealand doesn’t have to be a distant dream that’s five or ten years away. By understanding how a 5 percent deposit home loan nz works, you can stop paying rent and start building your own future right now. Whether you’re looking at an existing property through the government’s scheme or exploring the flexibility of a new build, the path to home ownership is much wider than the big banks often lead you to believe.

The key is preparation and professional advocacy. From cleaning up your bank statements to finding the right lender for your specific income, every step you take today brings you closer to your first set of keys. At Mortgage Suite, our founder Krish Krishna uses over 20 years of banking experience to help you navigate the paperwork and negotiate with lenders. We specialise in finding alternative paths for those who have been declined by mainstream banks, providing a steady hand to ensure your application stands out.

Ready to secure your first home with a 5% deposit? Let’s get the ball rolling with Mortgage Suite today.

You’ve got the drive to own your own place; now you just need the right team to cross the finish line. We’re here to help you move in sooner than you thought possible.

Frequently Asked Questions

Is a 5% deposit enough to buy a house in NZ in 2026?

Yes, a 5% deposit is absolutely enough to buy a home in 2026, especially through the government-backed First Home Loan scheme. With the median purchase price for first-home buyers sitting around $720,000, you would only need to have $36,000 saved to get started. This makes entering the market much more realistic than trying to save a massive 20% chunk while property prices continue to shift.

Can I use my KiwiSaver as part of my 5% deposit?

You can definitely use your KiwiSaver funds to make up part or even all of your 5% deposit. Most first-home buyers find that their KiwiSaver is their biggest asset when it comes to buying. Just make sure you get your withdrawal pre-approval sorted early so you know exactly how much cash you have to play with when you start house hunting. This ensures there are no surprises when it comes time to pay the deposit.

What are the income limits for the First Home Loan scheme?

The income limits for a 5 percent deposit home loan nz are currently set at $95,000 for a single buyer without dependants. If you’re buying as a couple or a solo parent with children, that combined limit is $150,000. These figures are based on your total before-tax income over the last 12 months; this includes any regular bonuses or extra earnings you’ve made from side jobs.

Do I have to pay a higher interest rate with a 5% deposit?

While you might not always get the “special” rates reserved for people with 20% equity, many lenders offer competitive rates for first-home buyers. You will usually need to pay a 1.2% bank safety fee, which is often called Lender’s Mortgage Insurance. This fee can often be added to your total loan amount so you don’t have to find extra cash upfront when you’re already stretching your savings.

Can my parents gift me the 5% deposit?

Yes, your parents or family members can gift you the money for your deposit. This is a very common way for Kiwis to get onto the property ladder sooner. The bank will just need a signed letter from them stating that the money is a genuine gift and doesn’t need to be paid back. This keeps your financial records clear and shows the bank that you don’t have extra debt to worry about.

What happens if I earn more than the Kāinga Ora income cap?

If your income is above the government caps, you still have several great options for buying with a low deposit. New build properties are often exempt from standard rules, which means you might only need a 10% deposit regardless of what you earn. We can also look at 2nd tier lenders who have more flexible criteria for people with higher incomes but smaller savings; they often provide the perfect stepping stone.

How long does it take to get a 5% deposit home loan approved?

You should generally allow about five to ten working days for a low-deposit loan to be approved. Because these applications are more detailed, the bank needs extra time to check your spending habits and income evidence. Working with a broker can speed this up because we make sure your application is perfect before it even hits the bank manager’s desk, which reduces the chance of delays.

Are there any hidden fees with low-deposit home loans?

There aren’t really any “hidden” fees, but there are standard costs you should plan for. These include the 1.2% bank safety fee, a professional valuation of the house, and a building inspection report. It’s also a good idea to have some cash set aside for your lawyer’s fees and moving costs. Having these costs organised early means you won’t be caught short when you’re ready to settle on your new home.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.