
Assessing business loan repayments with bad credit in New Zealand

A bad credit history doesn’t automatically rule out a business loan in New Zealand. If you’re asking how to get a business loan with bad credit in NZ, lenders will look at whether your business is viable and can repay the loan and interest. Your credit history matters, but it is only part of the picture.

It’s understandable to feel uncertain, especially after a lender has declined your application. A decline isn’t a judgement on you or your business, and it doesn’t necessarily close off every option. The next step is to understand what a lender needs to see and whether repayments fit your business’s cash flow.

This guide explains what can affect eligibility, how to assess repayments and which financial documents can support an application. It also covers what to do after a decline, so you can address gaps and decide on a clearer next step.

Key Takeaways

  • Prepare tax returns for the past two to three years, alongside clear financial records, bank statements and a business plan.
  • Build a cash flow forecast using cautious income estimates and realistic costs to see whether repayments fit your business finances.
  • Lenders assess whether your business is viable and can repay the loan and interest; accelerated lending generally calls for at least 12 months of consistent profitability.
  • If an application is declined, use the lender’s reasons to strengthen your business plan and address gaps in the financial evidence.
  • A low credit score doesn’t tell the whole story. Your trading record, repayment capacity and the purpose of the borrowing can all help show your business’s position.

Preparing financial statements, tax returns and bank statements

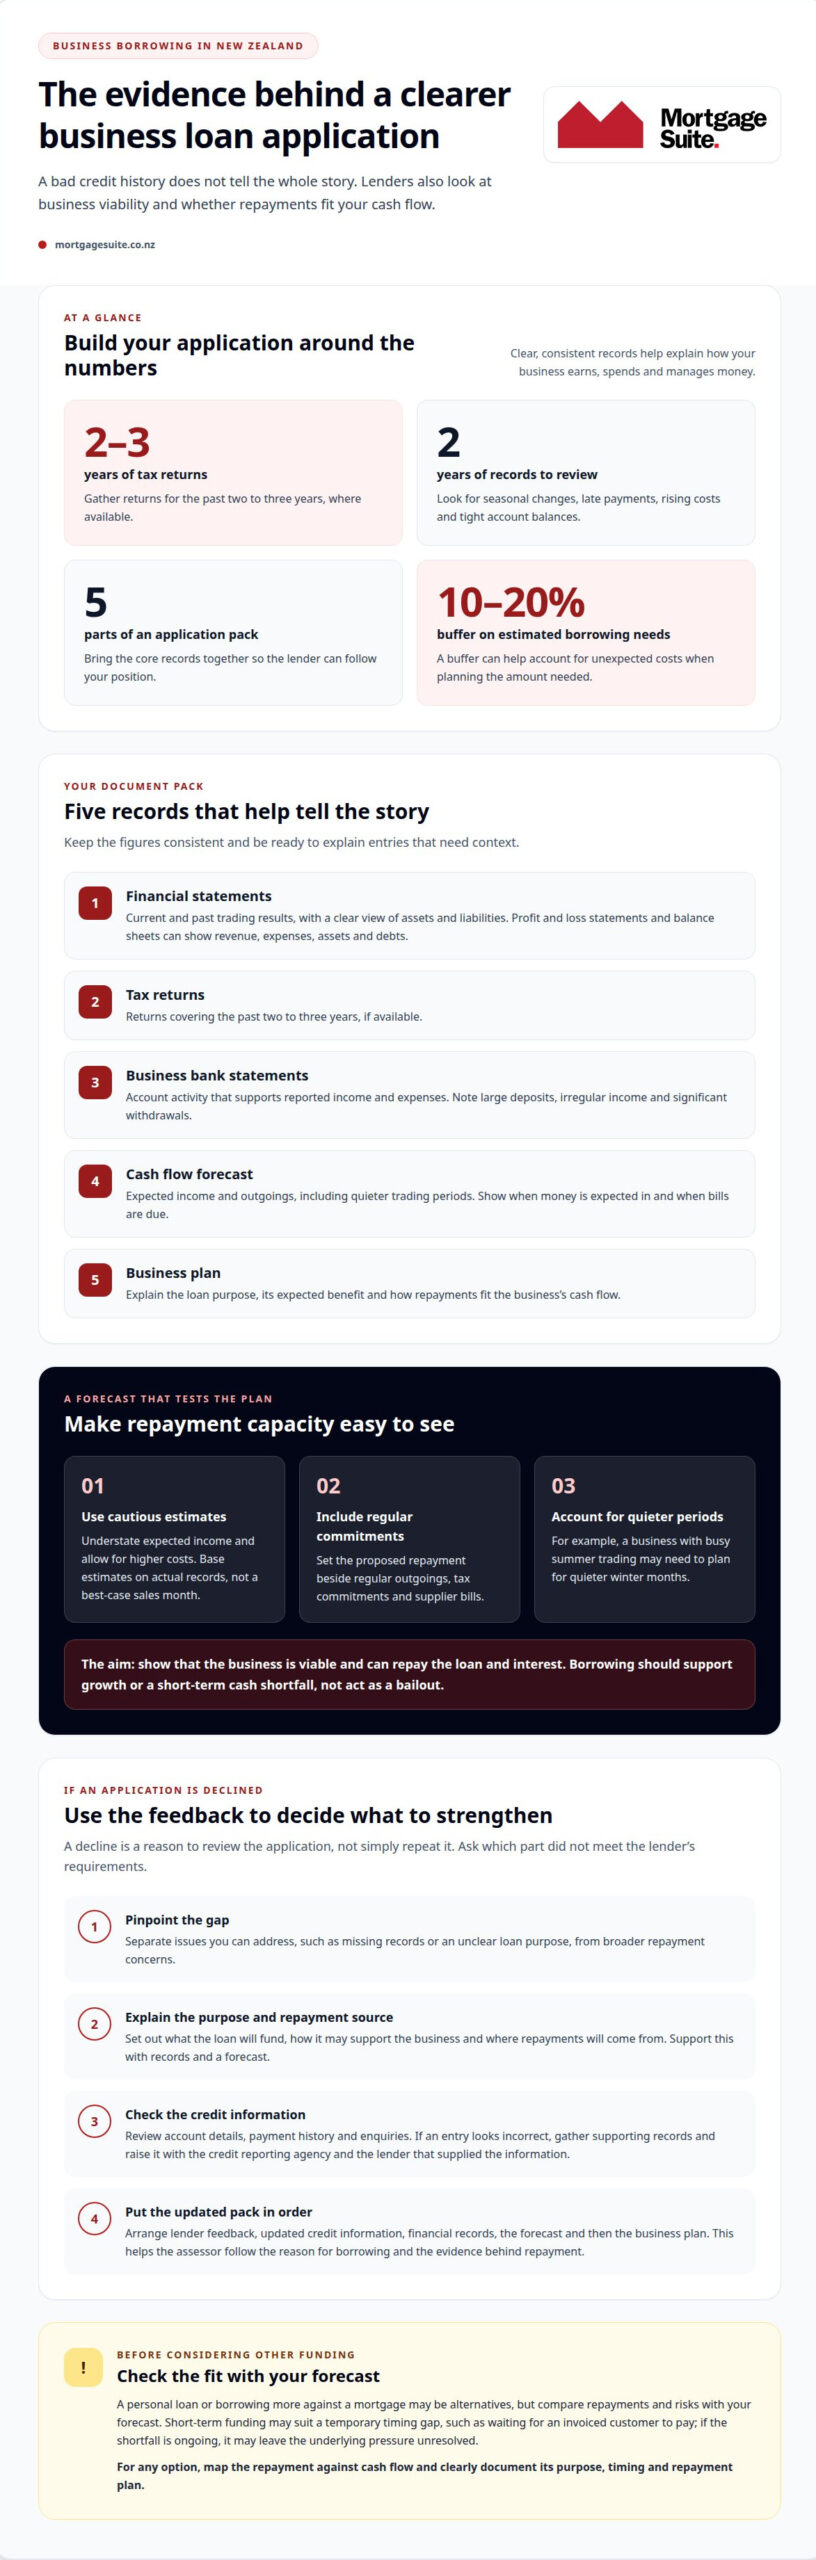
Organised records help show how your New Zealand business earns, spends and manages money. Before applying, gather financial statements, tax returns and business bank statements. Lenders assess whether a business is viable and can repay the loan and interest. Clear, consistent records make it easier to explain your trading position, especially when your credit history may raise questions.

Start with tax returns for the past two to three years, where available, and financial statements for the same period, such as profit and loss statements and balance sheets. These show revenue, expenses, assets and debts. Compare the figures with your bank statements, noting large deposits, irregular income and significant withdrawals. Prepare a short explanation and supporting records for any entries that need context.

Review the past two years of financial records to understand repayment capacity. Look for seasonal changes, late customer payments, rising expenses and periods when the account balance was tight. For example, a business with busy summer trading may need to plan for quieter winter months. Use the records to prepare a cash flow forecast showing when money is expected in and when bills are due.

Prepare these documents as a practical application pack:

  • Financial statements: current and past trading results, plus a clear view of assets and liabilities.
  • Tax returns: returns covering the past two to three years, if available.
  • Bank statements: business account activity that supports the reported income and expenses.
  • Cash flow forecast: expected income and outgoings, including quieter trading periods.
  • Business plan: the loan purpose, expected benefit and how repayments fit the business’s cash flow.

Build the forecast cautiously: understate expected income and allow for higher costs. Base estimates on actual records rather than a best-case sales month. Set the proposed repayment beside regular outgoings, tax commitments and supplier bills. A 10-20% buffer on estimated borrowing needs can help account for unexpected costs. Borrowing should support growth or a short-term cash shortfall, not act as a bailout.

What alternatives to business loans are available for New Zealand businesses with bad credit? If your business has limited financial data to support an application, options may be narrower. A personal loan or borrowing more against a mortgage may be alternatives, but compare the repayments and risks with your forecast before deciding.

Bridging finance or other short-term funding may suit a temporary timing gap, such as waiting for an invoiced customer to pay. Identify the incoming funds expected to cover the gap, then map the repayment against your cash flow forecast. If the shortfall is ongoing, short-term funding may leave the underlying pressure unresolved. Clearly document the purpose, timing and repayment plan.

What if my business loan application is declined?

A decline is a reason to review the application, not simply repeat it. Use the lender’s feedback to address gaps in your business plan, repayment evidence or credit information before applying again.

Strengthening an application

Make your business plan answer three practical questions: what will the loan fund, how will it support the business, and where will repayments come from? For example, explain how new equipment could increase production or meet confirmed customer demand. Support the explanation with financial records and a cash flow forecast showing how repayments fit alongside wages, supplier bills and tax obligations.

Applying with poor credit

A low credit score does not tell a lender everything about your business. Explain the circumstances behind missed payments and provide evidence of current trading and repayment capacity. For example, distinguish a one-off late payment during a temporary cash-flow squeeze from ongoing difficulty meeting business commitments. The application still needs to show that the business is viable and can repay the loan and interest.

High-cost loans and director guarantees

High-cost borrowing can add pressure to cash flow, especially if frequent repayments fall due before customers pay. Before accepting an offer, compare its repayment schedule with your forecast and consider what could happen during a quieter trading period. A director guarantee is a personal commitment connected to the company’s debt. Read the agreement carefully and understand the personal responsibility it creates before signing.

Checking and correcting a credit report

Request your credit report from a credit reporting agency, then review the account details, payment history and enquiries. If an entry appears incorrect, gather supporting records, such as payment receipts or lender correspondence, and raise the error with the agency. Contact the lender that supplied the information too. Keep copies of your request and evidence so you can track the correction process.

For your next application, organise documents in a simple sequence: lender feedback, updated credit information, financial records, forecast, then business plan. This helps the assessor follow your reason for borrowing and the evidence behind repayment. A complete application also makes it easier to identify unanswered questions before assessment begins.

During assessment, the lender considers business viability and whether repayments are affordable. If your application is declined, ask which part did not meet the lender’s requirements. Separate issues you can address, such as missing records or an unclear loan purpose, from broader repayment concerns. Revise the relevant documents rather than resubmitting the same case unchanged.

If the feedback points to weak repayment capacity, review the borrowing amount and timing against your business’s actual cash flow. If it points to credit information, resolve any disputed entry first and include the outcome in your updated application. These steps give the next assessment a clearer, more complete picture of your business.

Assessing repayment capacity with cash flow forecasts

A profit on paper doesn’t show exactly when cash will be available for repayments. Use a cash flow forecast to map expected receipts against payment dates, then test whether the business can meet each instalment without missing essential bills.

Build the forecast around actual cash movements. Record when customers are expected to pay, not simply when you issue invoices. Include regular outgoings such as wages, rent, supplier invoices, tax and existing debt repayments. A late customer payment, for example, may leave the business short when a loan instalment is due, even if the sale was profitable.

Compare the forecast balance before and after each proposed repayment. Ask whether enough cash will remain for ordinary operating needs. If an instalment coincides with payroll or a large supplier payment, test a different repayment date or loan structure. Your forecast should make timing pressure clear, rather than relying on a monthly total that hides low-balance days.

Test more than the expected trading pattern. Model a quieter sales period, delayed customer receipts or an unexpected business expense. Reduce expected income and increase costs in a cautious scenario, then check whether repayments remain manageable. If the forecast only works when every customer pays on time, the borrowing plan may leave too little room for normal disruption.

Include existing commitments in the same calculation. Add current loan repayments, credit facilities and regular business expenses before assessing room for another instalment. Separate one-off costs from recurring bills, but don’t omit costs just because they vary. A realistic forecast helps show whether the proposed borrowing adds a manageable commitment or strains available cash.

The loan term and repayment size also affect affordability. A shorter term or higher repayments may reduce interest charges, provided the business can afford the schedule. Compare the cash left under each option, especially during slower trading periods. Choose a structure your forecast can support, rather than one that only looks attractive because of its headline rate.

Plan for repayment dates and make payments on time. New Zealand banks and other lenders usually charge extra for late or missed loan payments, so add due dates to your business calendar and monitor account balances before each instalment. If cash flow changes, update the forecast promptly and identify pressure before a payment is missed.

Calculate the impact of early repayment too. Compare the interest saved with any early repayment fee before using spare cash to reduce the debt. That cash may be needed for wages, stock or supplier bills before the next customer payment arrives. A forecast helps you weigh potential savings against upcoming business commitments.

Use the final forecast as a decision tool, not just an application attachment. Check available cash across the full repayment schedule, note the periods with the least room, and decide whether the borrowing amount or timing needs to change. The forecast should show how repayments fit your business’s actual trading cycle.
Assessing business loan repayments with bad credit in New Zealand

Applying with a low credit score

A low credit score can make an application harder, but it doesn’t explain the whole business position. Lenders also assess viability and whether the business can repay the loan and interest. Your application should connect your credit history with current trading evidence, the borrowing purpose and a workable repayment plan.

Start by identifying what the credit issue represents. A missed payment during a temporary disruption differs from ongoing difficulty meeting commitments. Explain the circumstances plainly, then show what has changed, such as overdue accounts being settled or payments becoming regular again. Keep the explanation factual and support it with relevant records.

Next, make the loan purpose specific. “Working capital” alone may not explain how the borrowing will help. Describe the need, such as paying a supplier while waiting for an agreed customer payment, and show how the funds fit your business plan. Link the purpose to expected income or a defined short-term gap, not an assumed turnaround.

Present the application as a clear case, not a pile of documents. Put the business plan, financial records and cash flow forecast in a logical order. Highlight recent changes that affect the figures, such as a new contract or the loss of a major customer. This helps the assessor understand your current position instead of drawing conclusions from one credit entry.

  • Explain: Give the date, cause and outcome of the credit problem.
  • Support: Include records showing current account conduct and business activity.
  • Connect: Link the loan purpose to a realistic business need.
  • Test: Show how the repayment fits around existing commitments.

Choose an application route that suits the evidence you can provide. Some New Zealand online lenders can make business lending decisions within 24 to 72 hours using cloud accounting data. Traditional bank business loan applications can take two to six weeks from application to approval. Speed alone doesn’t show whether the repayment structure suits your business.

Ask what information the lender needs and provide a complete response. If the application relies on cloud accounting data, make sure the records reflect current trading and explain unusual entries. When applying through a bank, allow time for questions about credit history, loan purpose or cash flow. A complete file can clarify the assessment, but it cannot replace evidence of repayment capacity.

Keep new borrowing enquiries focused. Before submitting another application, address the reason a previous lender declined and update the relevant information. If the concern was unclear income, for example, explain trading receipts more clearly. If it was the loan purpose, revise the plan so the use of funds and repayment source are easy to follow.

Eligibility requirements for New Zealand businesses

Eligibility depends on more than a credit score. New Zealand lenders assess whether a business is viable and can repay the loan and interest.

Lender credit score requirements

What credit score do New Zealand business lenders require? No single score determines eligibility on its own. Lenders weigh credit history alongside business viability, repayment capacity and the evidence in the application. A low score may prompt questions about missed payments, so explain their cause and show what has changed.

A consistent record of profitability may help support an application for accelerated business lending in New Zealand. That track record can help show how the business performs, but it does not replace an assessment of its ability to meet repayments. Use current trading information to explain changes since the period covered by older accounts.

Security for a business loan

Can a business loan in New Zealand be secured with property, equipment or a personal guarantee? A lender may consider property or equipment as security, or request a director’s personal guarantee. The loan agreement sets out the security and what the borrower or guarantor agrees to. Read those terms closely before signing.

For property or equipment, identify the asset and any existing finance attached to it. For a guarantee, understand who becomes responsible if the business cannot meet its obligations. Ask how the terms relate to the loan amount, repayment schedule and default conditions. Security can affect the lender’s assessment, but it does not replace evidence that repayments are affordable.

What New Zealand rules apply to business lending, responsible lending and loan agreements? Review the written agreement for the amount borrowed, interest, fees, repayment dates, security and consequences of missed payments. Make sure the application and agreement reflect the business’s actual repayment capacity, not an optimistic sales forecast.

Beyond credit and security, lenders look at the business’s financial position and borrowing purpose. Your business plan should explain what the funds will support, while financial records show trading performance and existing commitments. A forecast then connects expected cash flow with the proposed repayments.

Check that the amount requested matches the business need. If borrowing will fund equipment, for example, explain how it supports operations and how repayments fit alongside supplier bills and wages. A clear purpose helps an assessor understand your case. A vague request can make the benefit and repayment source harder to assess.

Before applying, organise evidence around three points: consistent trading, a clear use for the funds and repayment capacity. If profitability has been uneven, explain the pattern using actual business records. Eligibility rests on the whole application, not a credit score alone.

Mortgage Suite: Business Loans

Mortgage Suite offers Business Loans, including 2nd tier lending for borrowers who don’t fit mainstream bank criteria. If a bank has declined your application or your credit history complicates the process, Mortgage Suite can help you consider how your business purpose, financial records and repayment capacity fit together.

Bring your loan purpose, current financial information and any lender feedback to a conversation with Mortgage Suite. This helps clarify your circumstances and the questions an application may need to address. A suitable path depends on your business and its ability to manage repayments, so approval cannot be promised.

If you’d like to discuss your business borrowing needs, contact Mortgage Suite.

Take your next step with a clear plan

Your next move can be a focused conversation about what your business needs and what repayments it can realistically manage. If you’re considering how to get a business loan with bad credit in NZ, bring your borrowing purpose and current financial position to that discussion. A mainstream bank’s decision doesn’t have to be the final word on your plans.

Mortgage Suite offers Business Loans, as well as Home Loans for First Home Buyers and Residential Investment Property Loans. If your business and personal borrowing needs overlap, a conversation can help clarify which lending direction fits your goals.

Contact Mortgage Suite to discuss your options and work through a practical next step. You can move forward with a clearer plan and the support to get sorted.

Frequently Asked Questions

Want a Bad Credit Business Loan Today?

Start by confirming when the money is needed and what payment it must cover. If a supplier invoice is due, ask whether its payment date can be adjusted while you consider funding. Don’t promise a payment date based on a loan that hasn’t been approved. A clear deadline helps you decide whether borrowing is suitable or whether changing the timing could ease immediate pressure.

How much interest will I pay?

The interest rate depends on the lender and loan structure. Ask whether the rate is fixed or can change, and what conditions affect it. A fixed rate stays unchanged for an agreed period, while a variable rate can move. Compare how each structure fits your plans, including whether you value predictable repayments or more flexibility if circumstances change.

What loans am I eligible for?

Business lending can cover needs such as start-up funding, working capital and equipment finance. A business buying a delivery vehicle, for example, may need a different loan structure from one managing a gap between invoices and customer payments. Describe what the funds will support, then consider whether the borrowing period matches how long the business expects to benefit.

Can you get a business loan in New Zealand with bad credit?

Yes, a New Zealand business can apply for a loan with bad credit. Be clear about the business structure and who would borrow, such as a sole trader or a company with directors. This helps frame the application correctly. If personal and business finances have been managed separately, explain the arrangement so the lender can identify which records relate to the business.

Which New Zealand lenders offer business loans to borrowers with bad credit?

Business loan options may come from mainstream banks, non-bank lenders or private lenders. The right category depends on the type of borrowing and the lender’s criteria, rather than a single nationwide list for bad-credit applicants. Mortgage Suite Ltd can consider lending options beyond mainstream banks, including 2nd tier lending. Focus on whether the product suits the business purpose and its plans for the funds.

What interest rates and fees do bad-credit business loans in NZ charge?

There isn’t one interest rate for every borrower or loan. Ask how the rate is set, whether it can change and what might trigger a review. Request the proposed terms in writing so you can understand how the rate applies throughout the loan. Compare the structure and flexibility of each option, not just its opening rate.

What documents and financial information are needed to apply for an NZ business loan?

Alongside financial records, an application may benefit from documents showing who owns or runs the business. Depending on the purpose, relevant records could include an equipment supplier quote, a customer contract or details of the business structure. These connect the application to a real business activity. Keep names, ownership details and the proposed use of funds consistent across the paperwork.

How can you improve your chances of getting approved for a business loan in New Zealand?

Make sure everyone involved in the application agrees on its key details before it goes to a lender. Directors or business owners should align on the borrowing purpose, who will sign and how the funds will be used. If one director expects equipment finance while another describes working capital, resolve that difference first. A consistent account makes the application easier to follow.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

First Home Loan with Bad Credit NZ: Your 2026 Guide to Getting a ‘Yes’

Does a single missed payment from three years ago mean you’re locked out of the property market forever? Many Kiwis believe a less-than-perfect credit score is a permanent “no” when applying for a first home loan with bad credit nz. It’s heart-breaking to feel like the big banks are judging your entire future based on a past mistake you’ve already moved on from. You’ve likely felt the sting of a quick rejection or struggled to make sense of credit report jargon that feels designed to keep you on the sidelines.

We believe that life happens, and a number on a screen shouldn’t define your ability to provide a home for your family. Securing your own place is still achievable in 2026 by looking beyond mainstream options toward lenders who value your whole story. This guide will show you how to find these flexible providers and explain the actual costs involved in the current market. We’ll provide a clear, supportive roadmap to help you move past the stress and finally get the “yes” you’ve been waiting for.

Key Takeaways

  • Learn what your credit record actually shows lenders and why a few missed bills don’t have to be a permanent roadblock.
  • Discover why mainstream banks might decline you and how 2nd tier lenders offer a more flexible path to a first home loan with bad credit nz.
  • Understand the role of human underwriters who look at the story behind your numbers rather than just relying on an automated computer score.
  • Get a simple five-step plan to tidy up your current financial habits and prove to lenders that you’re a reliable borrower today.
  • Find out how expert negotiation and over 20 years of banking experience can help bridge the gap between you and your first home.

What Does ‘Bad Credit’ Really Mean for a First Home Buyer in NZ?

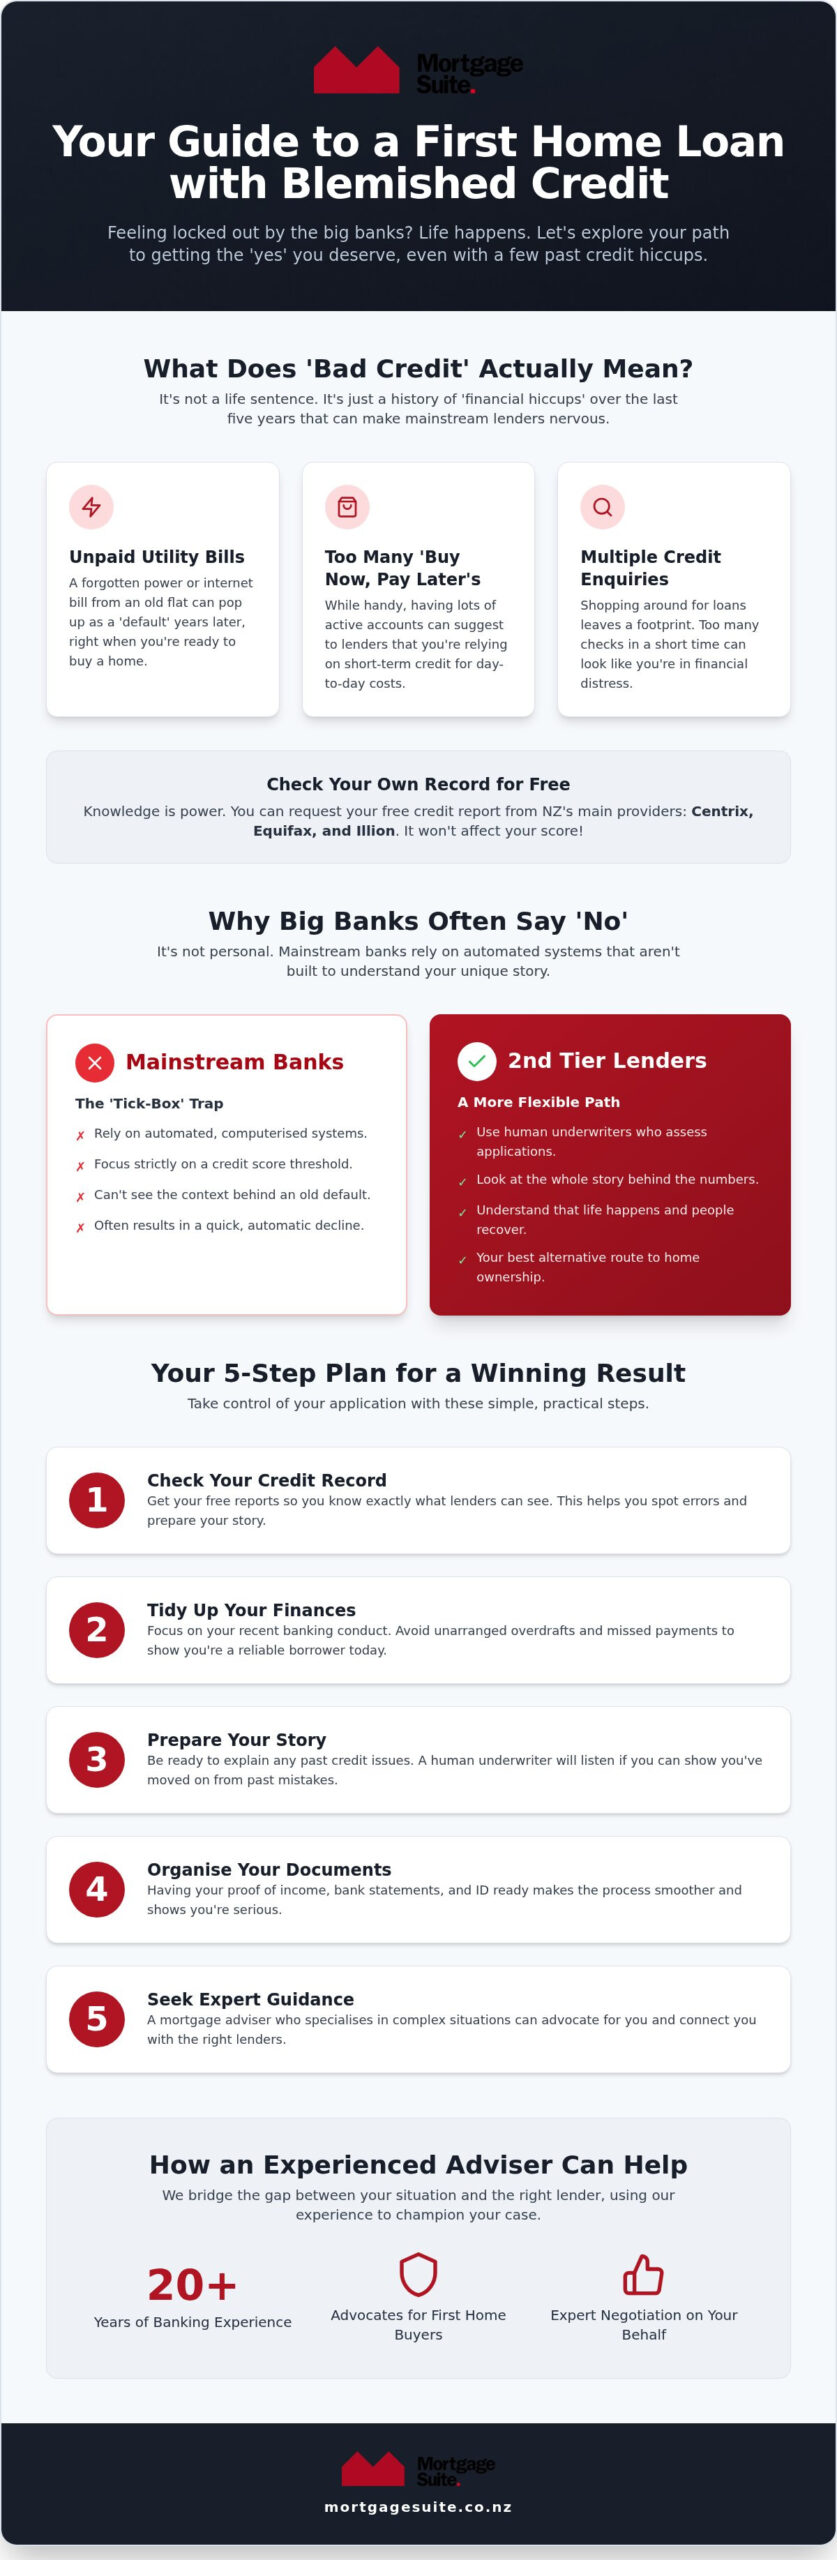
In New Zealand, your credit history acts like a financial diary. It records how you’ve handled bills and loans over the last five years. When you apply for a first home loan with bad credit nz, the lender isn’t just looking at a single number; they’re looking at your patterns. Essentially, bad credit is a history of “financial hiccups” that makes mainstream banks nervous. They use this data to guess how likely you are to pay them back on time. If they see a pattern of late payments, they might decide the risk is too high for their standard “tick-box” systems.

Understanding What ‘Bad Credit’ Really Means helps take the mystery out of the process. It isn’t just about big debts or bankruptcy. Even small things like a missed phone bill or a late credit card payment can stay on your record for years. These small marks tell a story about your financial discipline, even if you’ve since become much better at managing your money. Lenders want to know they can trust you with a mortgage, so they look at these past actions as a guide for the future.

Common Credit Hiccups That Trip Up Kiwis

You might be surprised by what shows up on a report. Often, it’s the small things that cause the most trouble during an application. These aren’t always signs of being “bad with money,” but they can flag you as a higher risk in a bank’s computerised system.

  • Unpaid utility bills: Power or internet bills from an old flat often go unnoticed. You might move house and forget a final payment, only to find it’s become a “default” years later when you’re finally ready to buy.
  • Too many ‘buy now, pay later’ accounts: Services like Afterpay or Laybuy are convenient, but having multiple active accounts can signal to a lender that you’re struggling to cover day-to-day costs.
  • Multiple credit enquiries: If you’ve been shopping around for a car loan or a personal loan, every time a company checks your credit, it leaves a footprint. Too many of these in a short space of time can make you look like you’re in financial distress.

How to Check Your Own Credit Record for Free

Before you start your journey toward a first home loan with bad credit nz, you need to see what the lenders see. You don’t have to pay a cent to get this information. In New Zealand, you can request your report from the three main providers: Centrix, Equifax, and Illion. It’s a good idea to check all three because they don’t always show the same information. A default might show up on one but not the others, and you want the full picture.

One of the best things about checking your own record is that it doesn’t hurt your credit rating. These are called “soft” enquiries. By getting these reports early, you can spot any errors or old debts you’ve forgotten about. This gives you the chance to start tidying things up and preparing your story before you sit down with a lender. Knowledge is power, and knowing exactly what’s on your record is the first step toward getting that “yes.”

Why Mainstream NZ Banks Say No (And Why It’s Not the End of the Road)

Walking into your local bank branch only to be told “no” is a crushing experience. It feels personal, as if the bank is judging your character based on a few numbers on a screen. However, it’s helpful to remember that the “Big Four” banks operate like massive machines. They process thousands of applications every week and rely on automated systems to do the heavy lifting. If you are seeking a first home loan with bad credit nz, these automated systems often act as a wall rather than a gate.

The ‘Tick-Box’ Trap

Banks use computerised “tick-box” systems that lack human common sense. These programmes are designed to find the “perfect” borrower. If your credit score doesn’t hit a specific threshold, the system triggers an automatic decline. It doesn’t matter if you now have a high income or a massive deposit. The computer doesn’t stop to ask why you had a default three years ago; it just sees the mark and moves on to the next file.

There is also a big difference between “conduct issues” and “historic defaults.” Conduct issues involve recent messiness, like unarranged overdrafts or missed payments in the last few months. Historic defaults are old mistakes from years ago. While a human might see that you’ve turned a corner, a bank’s software often treats them with the same level of suspicion. This rigid approach is partly due to the strict environment created by the Credit Contracts and Consumer Finance Act. Even with the official government lending law changes designed to bring more balance to the market, banks remain very conservative.

The Real Reason for the Decline

When a bank declines you, they often give a vague reason like “you don’t meet our criteria.” This is usually about how much risk the bank is willing to take at that specific time. Banks want the safest possible bets to keep their shareholders happy. Even the Kāinga Ora First Home Loan scheme, which is designed to help people into homes, still maintains relatively strict credit requirements. It’s a great tool, but it isn’t a silver bullet for everyone. If you’ve been declined, it’s rarely a reflection of your worth. It’s just a sign that your situation doesn’t fit that specific bank’s narrow rules.

A specialist broker can often find out the actual reason for a decline, which allows us to address the issue head-on. To learn more about how these factors influence your application, you can explore our Mortgage School for expert guidance. If you’ve been told “no” recently, it might be time to talk to a specialist who looks at your whole story instead of just a tick-box. Finding a different type of lender can change your entire outlook on home ownership.

2Nd Tier Lenders: Your Alternative Route to Home Ownership

When the big banks turn you away, it is easy to feel like your property dreams are over. However, there is a whole world of lenders beyond the household names you see on every street corner. These are often called 2nd tier or non-bank lenders. They are professional financial companies that specialise in providing mortgages to people who don’t fit the standard bank requirements. If you are looking for a first home loan with bad credit nz, these lenders are often the key to getting a “yes” because they operate very differently from mainstream institutions.

The biggest difference is the human element. While a bank relies on a computer to say yes or no, 2nd tier lenders employ a specialist team who actually review your application and listen to your story. They still follow the Credit Contracts and Consumer Finance Act 2003 to ensure they are lending responsibly, but they are much more willing to look at the context of your situation. This means they are often more comfortable with past defaults, being self-employed, or other life events that would cause a bank to immediately decline your file.

Mainstream Bank vs. 2nd Tier Lender

It is helpful to view a non-bank loan as a “bridge” rather than a forever home for your mortgage. Mainstream banks offer the lowest interest rates, but their rules are incredibly strict and they usually prefer a 20% deposit if your credit isn’t perfect. In contrast, 2nd tier lenders are much more flexible. They might accept a smaller deposit or a more complex credit history, though they charge a slightly higher rate to cover the extra risk they are taking on.

We often recommend a “Stepping Stone Plan” for our clients. This involves staying with a 2nd tier lender for one or two years to get your foot in the door. During this time, you prove you are a reliable borrower by making every payment on time. Once your credit record clears and you have built up some equity in your home, we then help with moving your loan to a different bank later to secure those lower mainstream rates. It is a proactive way to start your home ownership journey sooner.

What to Expect with a Non-Bank Loan

We believe in being completely honest about the trade-offs involved. Because these lenders take on more risk, they do charge more for their services. You can typically expect an interest rate that is 1% to 3% higher than the headline bank rates. You can use our Mortgage Calculator to see exactly how these different rates would affect your weekly repayments and make sure the numbers work for your budget.

While paying a bit more in interest feels tough, it is often much cheaper than waiting years for your credit record to be perfectly clean. If house prices continue to rise while you are waiting, the cost of the house could increase by far more than the extra interest you would pay over a couple of years. Getting into a first home loan with bad credit nz now allows you to start building your own equity instead of paying off someone else’s mortgage while you wait for your score to improve.

First Home Loan with Bad Credit NZ: Your 2026 Guide to Getting a 'Yes'

5 Steps to Organise Your Application for a Winning Result

You cannot change the mistakes of the past, but you can certainly control how you handle your money today. Lenders aren’t just looking at the hiccups you had years ago; they want to see that you are now a safe pair of hands. Preparation is 90% of the battle when your credit isn’t perfect. We recommend gathering every piece of evidence that explains your past credit issues so you can present the full picture to the bank. Getting a first home loan with bad credit nz is much easier when you focus on showing that you have truly turned a corner.

The ‘Clean-Up’ Phase

Before you start looking at open homes, you need to tidy up your financial life. This phase is about proving that your old habits are gone and you are ready for the responsibility of a mortgage. Even small actions can have a big impact on how the person reviewing your file sees your application.

  • Step 1: Settle old debts. Pay off any small unpaid bills or defaults immediately. While the mark stays on your record for five years, seeing that you have settled the debt makes a massive difference. It shows you take your current obligations seriously.
  • Step 2: Close unused accounts. Get rid of credit cards or high-interest store cards you don’t use. Lenders look at your total available credit limits as potential debt, even if the balance is zero. Closing them can actually increase the amount you are allowed to borrow.
  • Step 3: Show perfect account behaviour. Aim for at least three months of “clean” bank statements. This means no unarranged overdrafts and no missed automatic payments. It is about proving you have the discipline to manage your money every single week.

Telling Your Story

The final steps involve moving beyond the numbers and providing the human context that a computerised bank system would usually ignore. This is where your application for a first home loan with bad credit nz truly comes to life and stands out from the pile.

Step 4: Write a simple explanation. If a major default was caused by a one-off event like a medical emergency or a relationship breakup, you should explain that. Be honest and detail what has changed since then to ensure it won’t happen again. A human decision-maker appreciates this transparency and it helps them understand the person behind the paperwork.

Step 5: Partner with a specialist. You need an advocate who knows which lenders will be most sympathetic to your specific situation. We know how to package your application so it highlights your strengths. You can see how others in similar spots succeeded by reading our Client Reviews. If you are ready to start this process, contact our team at Mortgage Suite Ltd today to see how we can help you turn your situation around.

How Mortgage Suite Ltd Advocates for First Home Buyers

Securing a first home loan with bad credit nz isn’t just about finding a lender who will listen. It’s about having an advocate who knows how to translate your life story into a language that lenders understand. At Mortgage Suite Ltd, we know that your credit report is only one part of your financial identity. Krish Krishna uses over 20 years of banking experience to look past the numbers and focus on the person behind the application. We understand exactly how lenders think because we’ve spent decades on the other side of the desk. This insider knowledge allows us to anticipate their questions and address their concerns before they even ask.

We don’t just send off a digital application and hope for the best. We negotiate and argue your case directly with the people who make the final decisions. We also have access to a wide range of 2nd tier lenders that you often cannot deal with directly as a member of the public. Our goal is to find a solution that fits your actual life, not just a bank’s rigid spreadsheet. We believe everyone deserves a fair go at home ownership, and we work tirelessly to bridge the gap between your past hiccups and your future home.

The Power of Professional Negotiation

The way an application is packaged can make all the difference. We don’t just show the lender your defaults; we highlight your strengths, such as a stable job, a solid deposit, or your history of paying rent on time. This is like creating a professional CV for your finances. Having a veteran banker on your side gives the lender more confidence. They know that if we’re backing your application, we’ve already done the hard work to ensure you’re a reliable borrower. You can learn more about Krish’s background and our philosophy by visiting our About Us page.

Your Long-Term Home Loan Partner

Our relationship with you doesn’t end once you get the keys to your new house. We stay in touch to help you plan for the future. As we discussed earlier, the goal for many of our clients is to eventually move back to a mainstream bank once their credit record is clear. We’ll be there to help you recognise when the time is right to make that transition, ensuring you always have the most affordable option available.

Because we offer a national service, we can help you no matter where you’re looking to buy across New Zealand. Whether you’re just starting to think about buying or you’ve recently been declined by your own bank, we’re here to help. Reach out to us for a conversational, no-pressure chat about your options. We’ll give you honest advice and a clear path forward, helping you secure that first home loan with bad credit nz so you can finally stop renting and start owning.

Take the First Step Toward Your New Front Door

Owning your own home in 2026 is still within reach, even if your credit record has a few marks from the past. You’ve seen that while mainstream banks rely on rigid computer systems, there are flexible lenders who value your actual story. By tidying up your recent account conduct and presenting a clear explanation of past events, you can demonstrate that you’re a reliable borrower today. This preparation is the key to moving from a “no” to a “yes.”

Securing a first home loan with bad credit nz is often about finding the right bridge to get you into the market sooner. With over 20 years of banking expertise, our team at Mortgage Suite Ltd specialises in “outside the box” lending and provides national NZ-wide support to help you navigate this journey. We handle the tough conversations with lenders so you don’t have to. We believe in your potential and are dedicated to finding a solution that fits your life.

Book a friendly chat with our team to explore your home loan options

You don’t have to navigate this process alone. We’re here to support you and help turn your home ownership dreams into a reality.

Common Questions About Buying Your First Home With Bad Credit

Can I get a first home loan in NZ with a 500 credit score?

Yes, you can certainly secure a first home loan with bad credit nz even if your score is around the 500 mark. While mainstream banks usually look for scores above 700, 2nd tier lenders are far more interested in your current ability to manage money. They’ll look at your income, your deposit, and the story behind the low score. If you can show your habits have improved, many alternative lenders will consider your application.

How long does a default stay on my NZ credit record?

In New Zealand, a default stays on your credit record for five years from the date it was first listed. It doesn’t matter if you pay it off the next day or three years later; the mark remains visible to lenders for that full period. However, a “paid” default is much more attractive to a lender than an “unpaid” one. It shows you’ve taken responsibility for your past debts and resolved the issue.

Will I need a bigger deposit if I have bad credit?

You generally will need a larger deposit if your credit history isn’t perfect. While some buyers with clean credit can access loans with a 5% or 10% deposit, lenders often require at least 20% for those with credit issues. This extra equity reduces the risk for the lender. Having a larger deposit also demonstrates that you have the financial discipline to save, which helps build trust during the application process.

Are interest rates much higher for 2nd tier home loans?

Interest rates for 2nd tier loans carry a “risk premium,” so they are typically higher than mainstream bank rates. You can expect to pay between 1% and 3% more than the special rates advertised by the big banks. While major banks might offer rates around 5% in 2026, 2nd tier rates can range from 6.84% to over 11%. It’s a temporary cost to get you into the property market sooner.

Can I use my KiwiSaver for a deposit if I have bad credit?

Yes, you can still use your KiwiSaver funds for a deposit even if your credit history is less than perfect. The rules for withdrawing your KiwiSaver are set by the government and your provider, not by the mortgage lender. As long as you’ve been a member for at least three years, you can usually withdraw your balance. This is a vital tool for building the 20% deposit often required for alternative loans.

What happens if my bank has already declined my home loan application?

If your bank says no, it simply means you don’t fit their specific, narrow lending criteria. It isn’t a final judgement on your dream of home ownership. Many Kiwis successfully secure a first home loan with bad credit nz after being declined by their own bank. The key is to stop applying at other mainstream banks, which can further damage your score, and talk to a specialist who understands the alternative lending market.

How can a mortgage broker help me if my credit is poor?

A broker acts as your personal advocate and negotiator. We use our 20 years of banking experience to “package” your application so it highlights your current strengths rather than just your past mistakes. We also have access to a wide range of 2nd tier lenders that don’t deal with the public directly. We handle the hard conversations with underwriters and push for a “yes” when a bank’s computer system says “no.”

Is it possible to ‘fix’ my credit score quickly before applying?

You can’t instantly erase past defaults, but you can improve how you look to a lender in about three months. Start by paying off any small outstanding debts and closing down unused credit cards or store accounts. Most importantly, ensure your bank statements show at least 90 days of perfect conduct with no missed payments or unarranged overdrafts. This recent “clean” history is often more important to a human underwriter than an old mistake.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.