Debt Consolidation Mortgage NZ: How It Works and What to Weigh Up

What if one easier repayment came with a much longer journey to becoming debt-free? Keeping track of several debts and due dates can be stressful, so it’s understandable that a single, lower repayment sounds appealing. For Kiwis weighing up debt consolidation mortgage NZ options, though, the monthly amount is only part of the picture.

Rolling credit cards or personal loans into a mortgage may simplify repayments and reduce the interest rate on that debt. But it also means securing previously unsecured debt against your home. If you repay it over a longer mortgage term, you could pay interest for longer too. A simpler repayment helps only when the loan structure and your plan to repay it suit your circumstances.

This guide explains how mortgage-based consolidation works and what to compare with a personal loan or keeping debts separate. You’ll also learn what information to gather before discussing your options. Mortgage Suite helps borrowers explore debt consolidation and Refinance options across different lender channels, with advice that’s free of charge and comes with no obligation.

  • A debt consolidation mortgage NZ option may bring eligible debts together through a new or restructured home loan, subject to your circumstances.
  • Compare the regular repayment with the total interest over the full loan period to understand the longer-term impact.
  • Weigh up a mortgage and a personal loan by looking at security, repayment period, repayment structure and your current goals.
  • Before exploring options, list each debt, its current repayment and how long remains to repay it.
  • Mortgage Suite can discuss debt consolidation and Refinance options with your goals in mind.

What does debt consolidation through a mortgage mean in New Zealand?

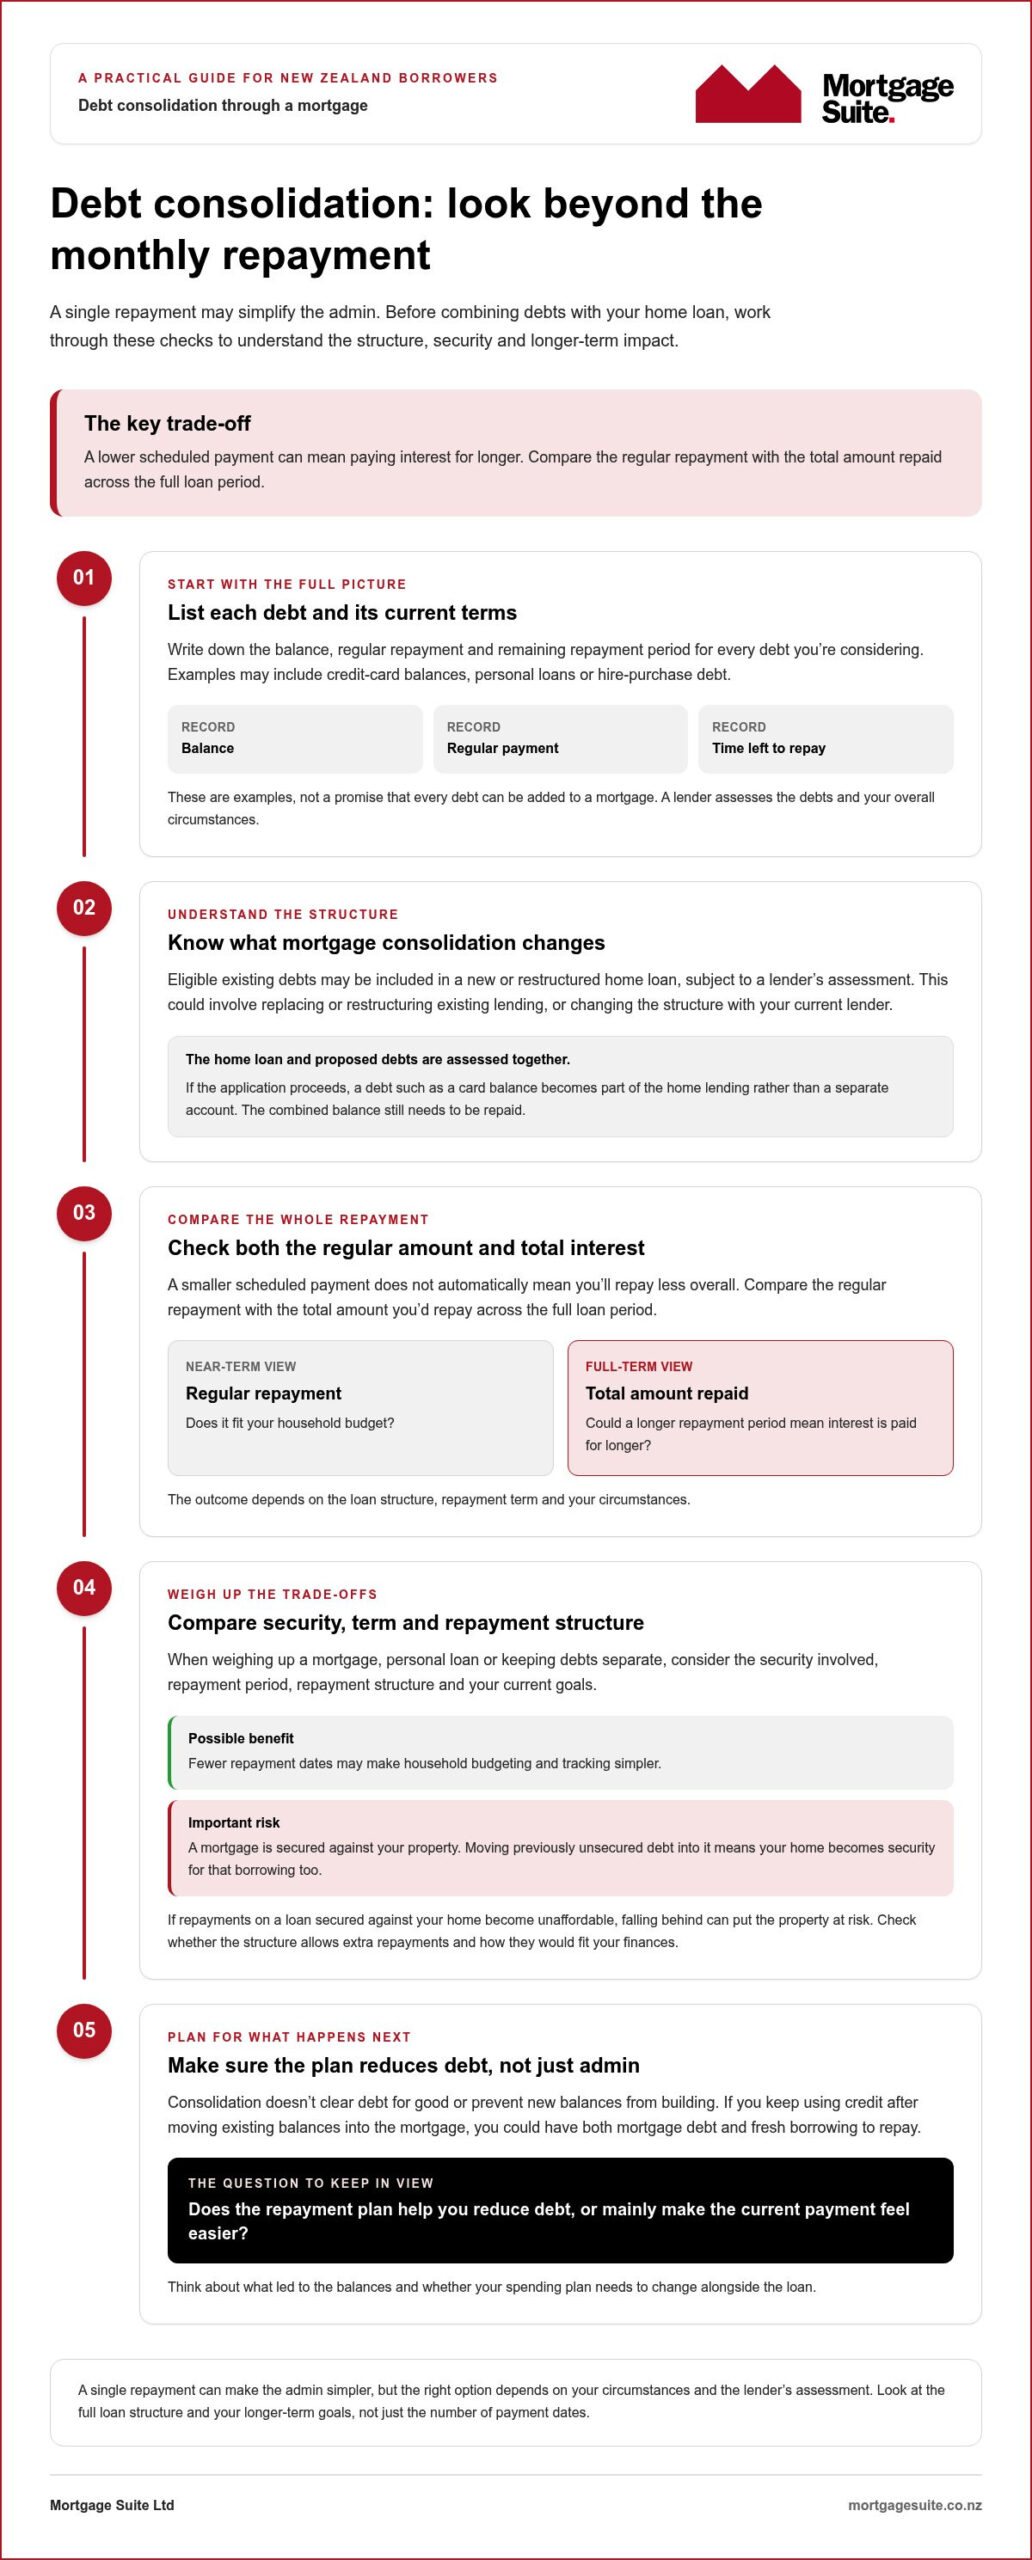
Keeping up with several balances, repayment dates and lenders can feel like a lot to manage. Bringing debts together may make the admin simpler, but the right choice depends on more than having one payment. Here’s how mortgage consolidation works, what a lender may assess and why a single repayment doesn’t automatically mean you’ll repay less overall.

Mortgage debt consolidation means including eligible existing debts in a new or restructured home loan, subject to a lender’s assessment. Unlike personal-loan consolidation, which combines debts through a personal loan, mortgage consolidation uses lending secured against your property. The wider What is debt consolidation? overview explains the general idea, but the mortgage option has its own trade-offs.

How mortgage debt consolidation works

A lender considers your existing mortgage alongside the debts you want to combine and assesses whether a revised loan structure may suit your circumstances. This could involve a Refinance, which means replacing or restructuring existing lending, or changing the structure of lending with your current lender. The details, including how the debt is repaid, depend on your situation and the lender’s assessment.

For example, if you have a home loan and separate credit-card debt, a lender may consider whether the proposed mortgage can cover both. If the application proceeds, the card balance becomes part of the home lending rather than a separate account. You may then have fewer repayments to manage, but the combined balance is still debt that needs to be repaid.

Consolidation can simplify administration, but it doesn’t erase what you owe or guarantee a lower total repayment. If the added debt is repaid over a longer period as part of the mortgage, you may pay interest for longer. The repayment plan should make sense for your budget and longer-term goals, not just reduce the number of dates in your calendar.

Which debts might a borrower consider combining?

People may ask about including credit-card balances, personal loans or hire-purchase debt. These are examples, not a promise that every debt can be added to a mortgage. A lender assesses the debts and the overall application, including whether the proposed lending fits your circumstances. Your existing home loan, property and intended repayment structure also matter.

Before exploring a debt consolidation mortgage NZ option, list what you owe and the repayment arrangements for each debt. Include the balance, regular payment and remaining repayment period. This gives you a practical starting point for comparing possible structures. Some debts may not suit mortgage consolidation, so assess the whole picture rather than assuming everything can be rolled in.

How can mortgage consolidation affect repayments and long-term interest?

Mortgage consolidation can make the regular payment feel more manageable, but that figure alone won’t tell you whether the arrangement works out better over time. Compare the repayment you’d need to make with the total amount you’d repay across the full loan period. The outcome depends on the loan structure, repayment term and your circumstances, so a lower scheduled payment isn’t guaranteed.

Potential benefits of bringing repayments together

Having fewer payment dates to track can make household budgeting simpler. A clear plan can also help you see how much you’re paying towards the combined debt and monitor your progress. Before agreeing to a new structure, check how repayments are set up and whether the plan fits your regular budget. Simpler administration can be useful, but it doesn’t reduce the debt by itself.

It may help to compare repayment estimates across different terms. A mortgage repayment calculator can help you explore how a change in term affects a scheduled payment. Treat the result as an estimate, not a lender decision or a full picture of the overall repayment.

Risks to weigh before adding debt to a mortgage

Mortgage lending is secured against your property. If you add debt that was previously unsecured, such as a personal loan, to your mortgage, your home becomes security for that borrowing too. If repayments become unaffordable, falling behind on a loan secured against your home can put the property at risk. That’s a serious trade-off to weigh alongside the convenience of one repayment.

Consider the repayment period as well. If the consolidated debt is repaid over a longer mortgage term than the original debt would have taken, you may pay interest for longer. A smaller regular payment could therefore come with a higher total amount repaid. Check whether the loan structure allows extra repayments and how those would fit your finances before relying on them to reduce the balance sooner.

Consolidation doesn’t clear debt for good or prevent new balances from building. If you keep using credit after moving existing balances into the mortgage, you could end up with both the mortgage debt and fresh borrowing to repay. Think about what led to the balances and whether your spending plan needs to change alongside the loan.

  • Potential upside: fewer repayment dates and a clearer way to track the debt.
  • Potential downside: interest may be paid for longer, and unsecured borrowing becomes secured against your home.
  • Key question: does the repayment plan help you reduce debt, or mainly make the current payment feel easier?

A debt consolidation mortgage NZ option is worth assessing against both your monthly budget and your longer-term goals. If you’re weighing up how a different mortgage structure could affect your repayments, Mortgage Suite can help you explore debt consolidation and Refinance options with your circumstances in mind.

Mortgage or personal loan for debt consolidation: what should you compare?

There isn’t one option that suits every borrower. A mortgage lets you review your home lending and other debts together, while a personal loan or separate repayments may keep borrowing on a distinct repayment plan. Compare the full structure and how it fits your goals, not just how many payment dates you’ll have.

What to compare Mortgage consolidation Personal loan or separate debts
Security The combined lending is secured against your property. A personal loan may be unsecured; separate debts keep their existing arrangements.
Repayment period Debt added to a mortgage may be repaid over a longer term. A personal loan may have a shorter, defined repayment period, depending on its terms.
Repayment structure Debt becomes part of your mortgage lending and its repayment structure. A personal loan has its own scheduled repayments; separate debts keep their individual schedules.
Fit with your goals May suit a homeowner reviewing existing mortgage lending alongside other debts. May suit someone who wants a separate repayment plan or to avoid securing that debt against their home.

When mortgage-based consolidation may be worth exploring

If you own a home and want to review your mortgage and several debts as one picture, mortgage-based consolidation may be worth discussing. A lender may consider available equity, your existing lending and whether the proposed repayments are affordable. Having equity doesn’t guarantee approval, and the lender’s decision depends on your full circumstances.

Interest is only one part of the comparison. The amount borrowed, repayment period and loan structure all affect what you repay over time. The mortgage repayment calculator can help you explore how changing a repayment term affects the regular payment, but it won’t show whether a particular option suits your full situation.

When a personal loan or separate repayments may fit better

A separate repayment plan may suit you if you want to pay a debt down over a defined period, subject to a lender’s assessment and the terms offered. Keeping a debt separate can also avoid securing that borrowing against your home. You’ll still need to manage its repayment alongside your other commitments.

Compare the proposed payment with what you currently pay across all debts, then consider the full repayment period and total interest. A smaller regular repayment can look appealing, but it doesn’t show the long-term impact on its own. Think about whether the structure supports your current goals, such as reducing debt steadily or keeping your mortgage arrangements straightforward.

A debt consolidation mortgage NZ option should be weighed against your priorities, property and overall affordability, not judged on one feature alone. Mortgage Suite can help you consider debt consolidation and Refinance options across lender channels, with your circumstances in view. Explore your lending options with advice that’s free of charge and comes with no obligation.
Debt Consolidation Mortgage NZ: How It Works and What to Weigh Up

What should you prepare before exploring debt consolidation in New Zealand?

A clear snapshot of your finances can make a debt consolidation mortgage NZ discussion more practical and less daunting. You don’t need to have a preferred loan structure worked out first. Start with the facts, then be ready to explain what you want a new arrangement to achieve.

Build a clear picture of your current borrowing

Gather your mortgage details and a summary of your other debts. Include what you owe, each repayment amount and date, and how long remains on each repayment plan. Add household income and regular commitments so you can see how borrowing fits alongside day-to-day expenses. If any repayments have become difficult to maintain, note that too. It’s useful context, not a reason to feel judged.

  1. List each debt. Record the lender or provider, balance, current repayment, due date and remaining repayment period. Include credit cards, personal loans and hire-purchase agreements if you have them.
  2. Gather your mortgage information. Note your current home-loan balance, repayment schedule and remaining term. Include relevant details about the property and any recent changes to your lending arrangements.
  3. Summarise household income and commitments. Write down income sources and regular expenses, as well as other repayments. This helps you consider whether a proposed payment could fit your usual budget.
  4. Mark any pressure points. Identify repayments that have become hard to keep up with, or months when several due dates fall close together. This can help focus the discussion on what needs to change.
  5. Set your priority. Decide whether you mainly want simpler administration, a manageable regular repayment or a clear plan to pay the debt down. You may value more than one outcome, but knowing your main priority helps you weigh up the trade-offs.

Set goals for a proposed new structure

Think beyond having one payment. What would a successful outcome look like for you? You might want predictable repayments, fewer accounts to manage or a clear plan to pay the consolidated debt down within a timeframe that fits your longer-term plans. Consider whether the proposed repayment period supports those plans, rather than focusing only on the amount due each time.

If you want to explore possible mortgage repayments, the Mortgage Suite mortgage calculator can help you model scenarios. Treat any result as an estimate, not a lender decision or a full assessment of your circumstances.

If a mainstream bank has declined your application, include that outcome and any reasons you were given in your summary. It may be a prompt to explore other lender channels, but it doesn’t guarantee a different decision. A lender will assess your full circumstances and the proposed structure.

Once your notes are ready, Mortgage Suite can help you consider debt consolidation and Refinance options with your goals in mind. Discuss your debt consolidation options and decide whether you’d like to take the next step.

How Mortgage Suite can help you explore debt consolidation mortgage options

Once you’ve weighed up the repayment structure, longer-term impact and security involved, it can help to talk through your situation with someone who understands lending. Mortgage Suite helps New Zealand borrowers explore debt consolidation and Refinance options, with your goals and circumstances at the centre of the discussion. The first step is to understand what you need the repayments to achieve, then consider possible lender routes and structures without assuming one answer fits everyone.

Mortgage Suite works with banks, private lenders and non-bank lenders. These different lender channels give you options to consider, but they don’t mean a particular loan will be available or approved. Each lender makes its own assessment of your circumstances and the proposed lending.

What a conversation about your options can cover

You can talk through your current borrowing, repayment priorities and wider lending goals. That might include reviewing your existing mortgage alongside other debts, discussing whether a Refinance or different loan structure could fit, and considering how proposed repayments may affect your plans. The focus is on weighing up the whole structure, not simply aiming for one repayment or a lower regular amount.

Mortgage Suite advocates and negotiates with lenders on your behalf, seeking the best possible deal for your circumstances. That is a goal, not a promise of approval or a particular outcome. You can read Mortgage Suite client reviews to hear about other borrowers’ experiences. Each person’s experience is different and doesn’t guarantee what will happen in your situation.

Founder Krish Krishna brings over two decades of banking experience to these conversations and has personally settled well over a billion dollars in residential, commercial and business loans. That experience provides useful context when considering a debt consolidation mortgage NZ option, while the right path still depends on your circumstances and the lender’s assessment.

A straightforward next step

Getting started doesn’t require you to commit to a new loan. Explain what you owe, what’s proving difficult to manage and what you’d like your repayments to achieve. If a mainstream bank has declined an application, that doesn’t have to be the end of the discussion. It may be a reason to explore other lender channels, though no outcome can be guaranteed.

If you’re ready to talk through your circumstances and possible next steps, talk through your loan options with Mortgage Suite and decide what feels right for you.

Take the next step with a clearer plan

You don’t need to decide on a new loan before asking whether consolidation could suit you. A useful next step is to talk through what you want to change, what repayments you can manage and how a proposed structure would fit your plans. That keeps the focus on finding a workable path, not combining debts simply to have one payment.

Mortgage Suite can consider debt consolidation and Refinance options across bank, private and non-bank lenders. Advice is free of charge with no obligation, and founder Krish Krishna brings over two decades of banking experience to the discussion. No lender outcome is guaranteed, but a conversation can help you understand what may be worth exploring based on your circumstances.

If you’re considering a debt consolidation mortgage NZ option, start by sharing your goals and the borrowing picture you’ve prepared. Talk through your loan options with Mortgage Suite and take a steady first step towards a plan that feels right for you.

Frequently Asked Questions

Is debt consolidation through a mortgage the same as refinancing?

No, they’re related but not identical. Refinance means replacing or restructuring existing lending, while mortgage consolidation means including eligible debts, such as a credit-card balance, in mortgage lending. A Refinance may be one way to arrange consolidation, but you can also restructure lending without changing lenders. The important point is to understand what changes in your loan and how the added debt will be repaid.

Can I consolidate debt into my mortgage if I have little equity?

Possibly, but having little equity can limit the amount a lender may be willing to add to your mortgage. The lender will consider the property’s value alongside the total lending you’re requesting and your ability to manage the repayments. For example, a small amount of available equity may not cover all the debts you hope to combine. A lender assessment determines whether a proposed structure may fit.

Does consolidating debt into a mortgage mean I pay less overall?

No, it doesn’t automatically mean a lower total amount repaid. The result depends on the loan’s interest, repayment amount and how long you take to repay the added debt. A lower scheduled payment could mean paying for longer. Compare the full repayment plan, not just the next payment due, and consider whether you can make progress on the balance within a timeframe that suits your plans.

Can I consolidate debt if a bank has declined my application?

You can still explore whether another lending structure or lender channel may suit, but a decline doesn’t mean another lender will approve the application. The reason for the decision matters. It could relate to affordability, property value, existing commitments or other parts of your circumstances. Mortgage Suite can discuss options across bank, private and non-bank lenders, but any lender will make its own assessment and no outcome is guaranteed.

Will my credit cards be closed when I consolidate their balances?

Not necessarily. Paying a card balance from mortgage funds doesn’t, by itself, tell you whether the card account will stay open or be closed. This depends on the lender’s requirements and the arrangements made for your application. If the account remains available, avoid building a new balance while repaying the amount through your mortgage. Otherwise, you could be managing the consolidated debt and fresh card borrowing at the same time.

What happens if my home value changes after consolidating debt?

A change in your home’s value doesn’t automatically alter your loan balance or scheduled repayments. It can, however, affect the equity you have and the relationship between the property value and the amount borrowed. If you later apply to borrow more or change lenders, the lender may assess the property and your overall circumstances again. Don’t rely on a future rise in value to make today’s repayment plan affordable.

Can I still explore mortgage consolidation if I have missed repayments?

Yes, you can discuss your situation, including missed repayments, but they may affect a lender’s assessment. Be upfront about which payments were missed, when this happened and whether the accounts are now up to date. That gives an adviser a clearer picture of the challenge and the options worth considering. A missed payment doesn’t define you, but approval will depend on the full application and lender decision.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

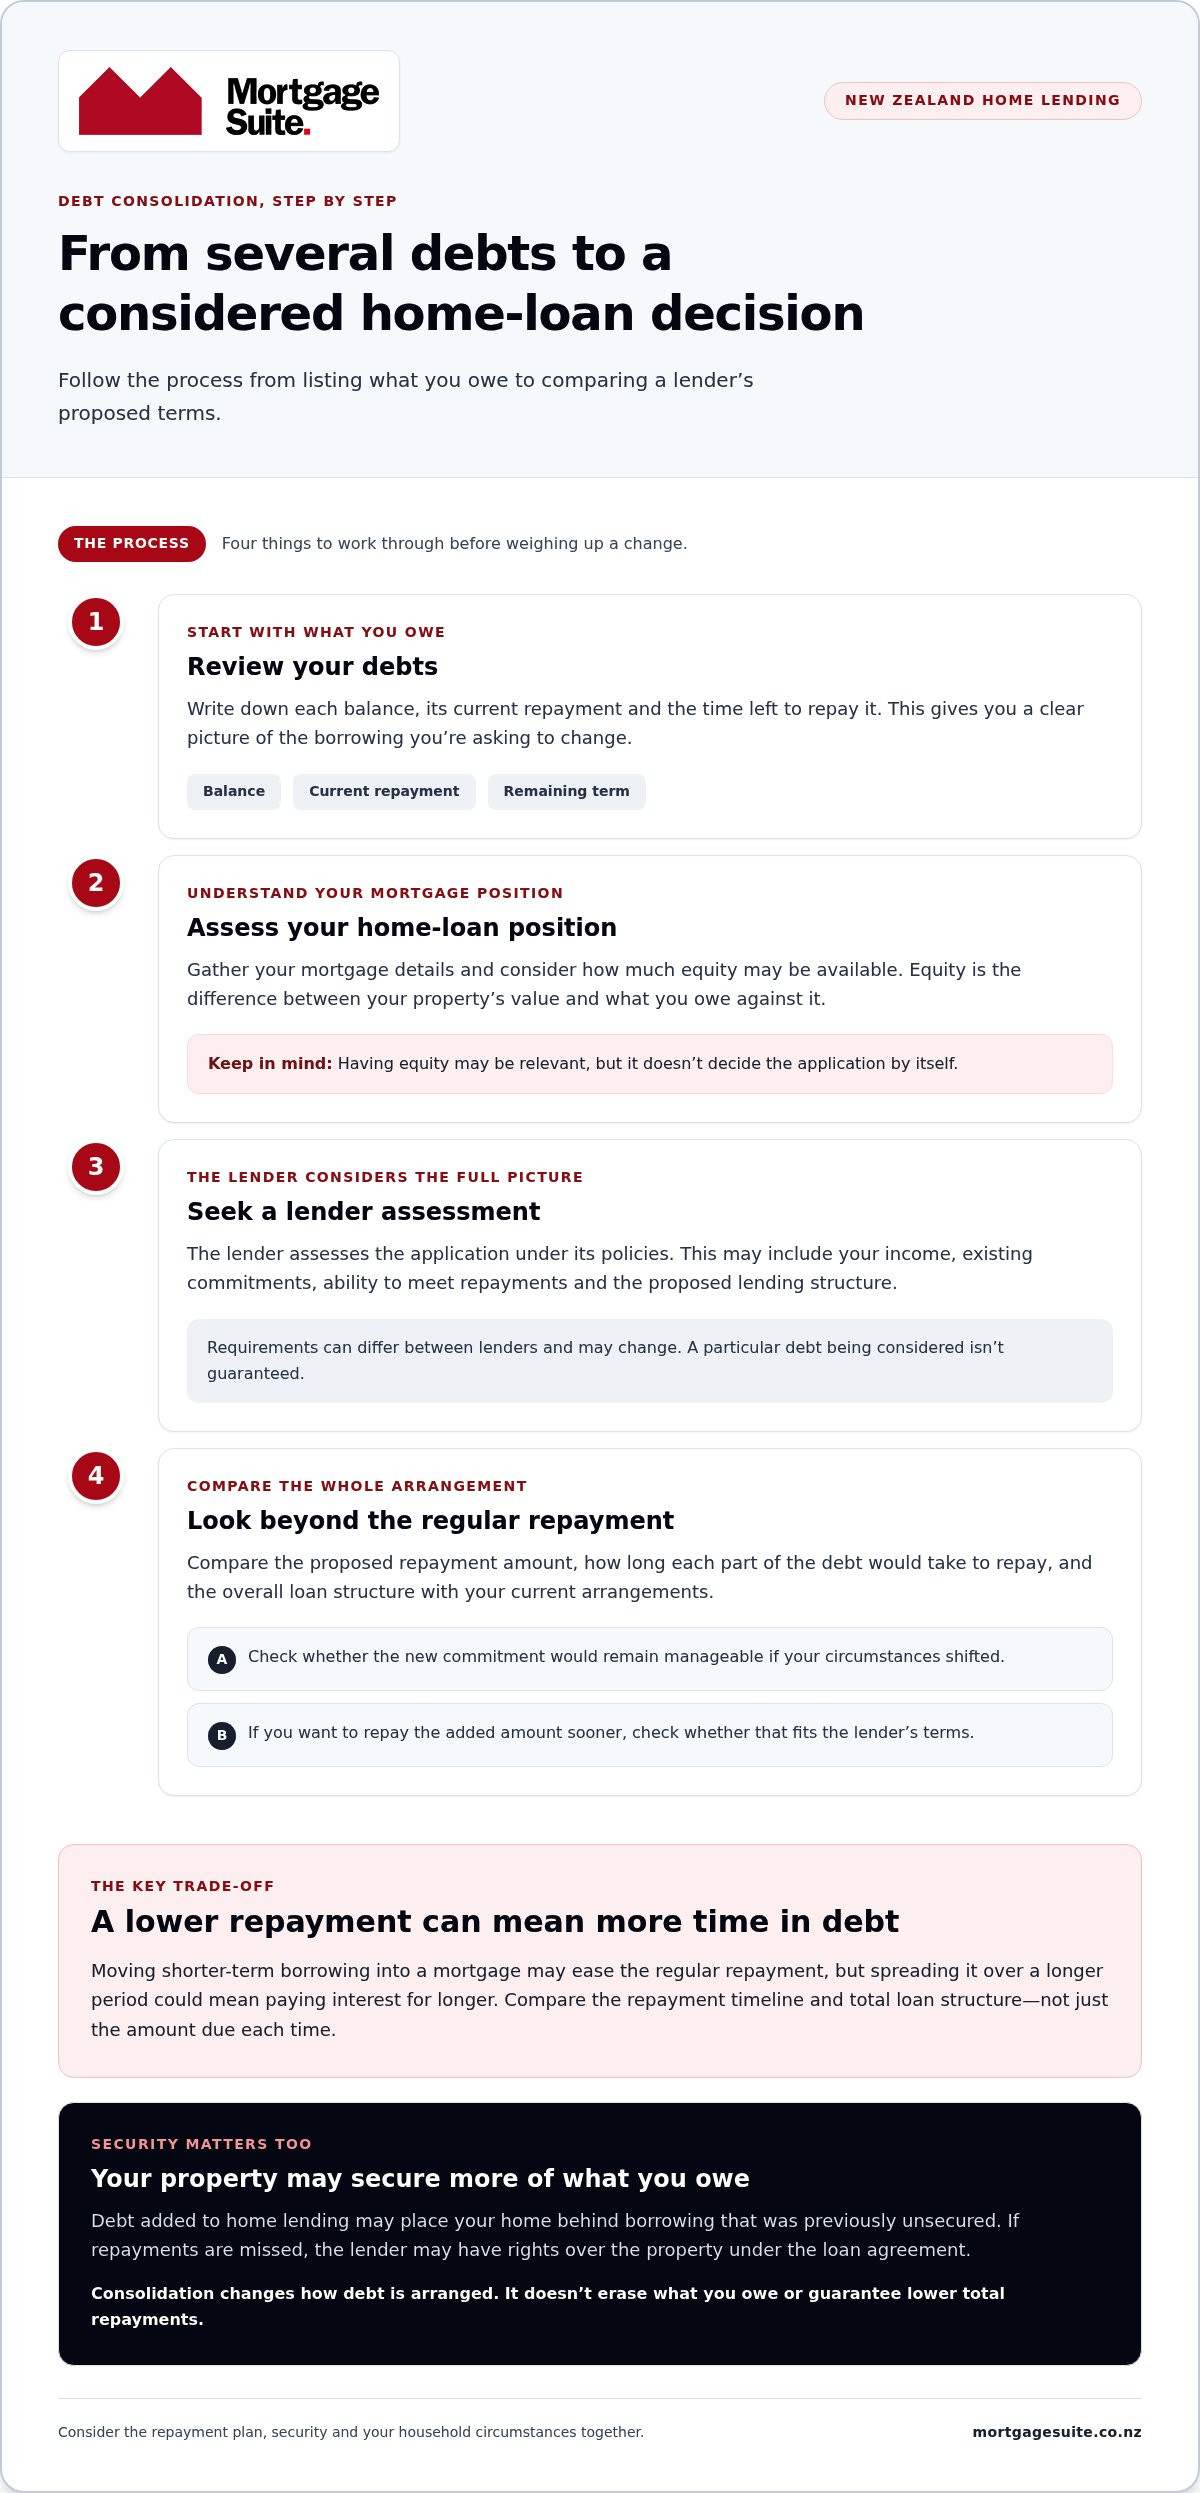
Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

What if the bank that recently said “no” to your renovation top-up isn’t actually the best place for your home loan anymore? It’s incredibly frustrating to watch high interest rates eat into your weekly budget while you feel stuck with a lender that doesn’t seem to value your loyalty. You aren’t alone in feeling this way, especially as you look to refinance mortgage nz in a 2026 market where the average one-year fixed rate is sitting around 5.89%.

We’re here to help you take back control. This guide shows you exactly how to swap your current loan for a better deal, unlock the value you’ve built up in your home, and save thousands of dollars in interest. We’ll cut through the confusion surrounding break fees and legal costs, giving you the confidence to make a move that actually benefits your bottom line. You’ll discover how to find a lender that fits your life now, whether you need extra cash for a kitchen makeover or simply want lower monthly repayments. We’ll preview the practical steps to switching and explain how having a seasoned pro in your corner makes the entire process feel like a breeze.

Key Takeaways

  • Learn why moving your home loan is similar to switching phone providers, but with the potential to save you thousands in interest over the long run.
  • Discover how to navigate break fees and secure a “cash carrot” from a new lender to help cover your legal and moving costs.
  • Find out how to refinance mortgage nz by using a pro to negotiate with both mainstream banks and flexible alternative lenders who are more likely to say “yes”.
  • Understand how to use your house wealth to tidy up high-interest debts like car loans and credit cards into one easier payment.
  • Get a straightforward look at the 2026 market outlook so you can time your switch perfectly for maximum monthly savings.

What exactly is refinancing and why should Kiwis bother?

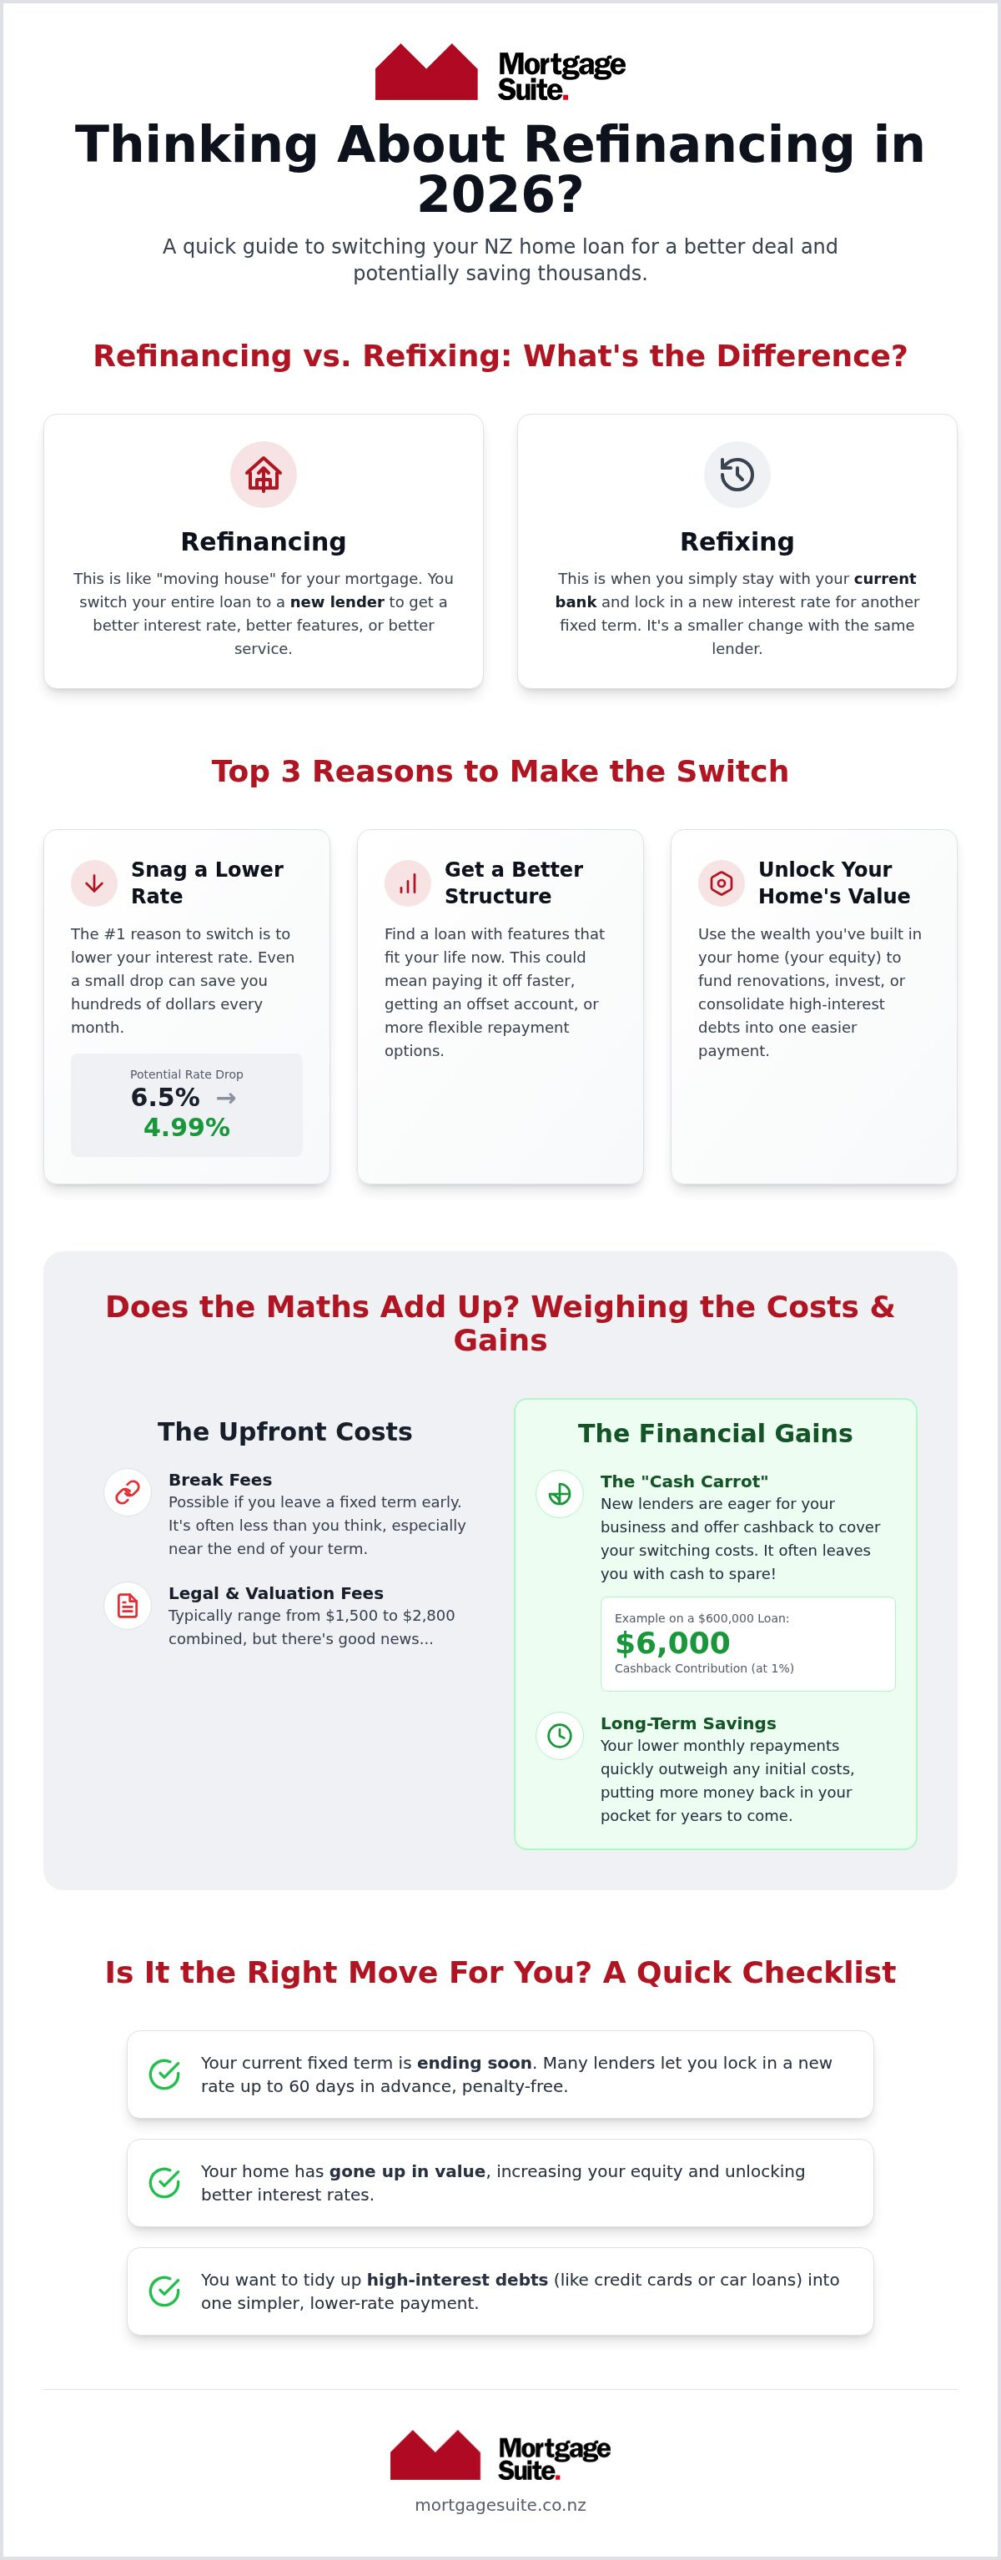
Think of your home loan like your mobile phone plan. Every year or two, you probably check if another provider has a better deal on data or a cheaper monthly cost. Refinancing is essentially the same thing, just with much bigger numbers and more zeros. When you decide to refinance mortgage nz, you’re simply moving your debt from one lender to another to get a better deal on your interest rate or loan features.

To understand the basics, you can look at What is refinancing to see how it works globally; however, for us here in New Zealand, it’s about making sure your bank is still working as hard as you are. Many people confuse this with “refixing”. Refixing is when you stay with your current bank and just choose a new interest rate for another year or two. Refinancing is “moving house” for your loan to find a more competitive partner that actually fits your current goals.

Right now, 2026 is a cracking time to look at your options. With the Official Cash Rate sitting at 3.25% and banks offering one-year fixed rates around 4.99%, the market has shifted significantly from the highs of previous years. If you’ve been stuck on a rate above 6.5% from a term you fixed in 2023 or 2024, switching now could save you a small fortune in interest costs over the next few years.

The main reasons to make the switch

Most homeowners move for one of three reasons. First, snagging a lower interest rate is the most common goal. Even a small drop can keep hundreds of dollars in your pocket every month. Second, you might want to change how you pay off the debt. You could switch to a structure that helps you become debt-free faster without increasing your stress levels. Finally, you might just want better service. If your current bank’s mobile app is clunky or they don’t offer offset accounts to help you save on interest, it’s time to look elsewhere. You can learn more about these different loan structures at our Mortgage School.

Is it the right move for you?

This path makes the most sense if your current fixed term is nearly up. If you’re within a few months of your rate expiring, you can start the conversation now to avoid being rolled onto a high floating rate. It’s also a winner if your home has gone up in value. This increase builds your equity, which is simply the bit of the house you actually own versus what the bank owns. If your house is worth $800,000 and you owe $500,000, you have $300,000 in equity. Having more equity often unlocks better rates and more flexible options for things like renovations or debt consolidation.

The real costs and savings of switching banks

Switching banks isn’t just about signing a new piece of paper; it involves a bit of maths to ensure the move actually makes sense for your wallet. While the goal is to save money, you have to account for the upfront costs to find your “break-even” point. This is the moment where your monthly interest savings finally outweigh the fees you paid to make the jump. For most Kiwis looking to refinance mortgage nz, this point arrives much sooner than they expect.

Understanding break fees and early exit costs

If you’re currently on a fixed-rate term, your bank might charge a break fee if you leave early. Banks charge this because they’ve already “bought” the money for your loan at a specific price. If market rates have dropped since you locked in, they lose money when you leave. To get an estimate, you can simply ask your current bank for a “break quote”. It’s often smaller than people fear, especially if you’re near the end of your term.

Timing is your best friend here. A helpful strategy is the “60-day rule”, where many lenders allow you to lock in a new interest rate up to two months before your current term expires. This lets you secure a better deal for the future without paying a cent in early exit fees today. By watching the market closely, you can time your move to avoid the biggest costs while still snagging a lower rate.

You also need to factor in the legal side. Because you’re moving your loan to a new lender, a lawyer must update the title of your property. These legal fees typically range from $800 to $1,600. In some cases, a bank might also ask for a registered valuation, which can cost between $700 and $1,200, though many lenders in 2026 now accept automated digital valuations for standard homes.

Cash incentives and legal subsidies

The good news is that banks are incredibly hungry for your business in 2026. To lure you away from their competitors, they often dangle a “cash carrot” in the form of a cashback offer. These incentives can be as much as 1% of your total loan amount. On a $600,000 mortgage, that’s $6,000 landing in your bank account, which easily covers your legal fees and any small break costs with plenty left over.

Just keep an eye on the “clawback” clause. Most banks require you to stay with them for a set period, usually three to four years, to keep that cash. If you move again too soon, they’ll ask for a portion of it back. You can use our mortgage calculator to see how these incentives and lower rates stack up against your current payments. Often, the savings are so significant that the move pays for itself in just a few months. If you’re feeling unsure about the numbers, talking to an expert can help you see if a switch is truly a winner for your specific situation.

Bank vs. Non-Bank lenders: finding your best fit

When you look to refinance mortgage nz, your first thought is probably your current bank or one of their big rivals. Mainstream banks love “standard” borrowers. If you have a steady salary, a large deposit, and a perfect credit history, they’ll usually roll out the red carpet. However, they aren’t the only game in town. In 2026, more Kiwis than ever are finding that alternative lenders, often called 2nd tier lenders, offer the flexibility they actually need.

These non-bank lenders are reliable, regulated, and often more approachable than the big institutions. They account for over 10% of new home loans in the current market because they don’t just rely on rigid computer algorithms to make decisions. Instead, they take a more human approach to your application. We help you navigate both worlds to ensure you aren’t just getting a loan, but finding a partner that suits your long-term goals.

When the big banks say “no”

Banks can be incredibly picky. If you’ve recently started a business, changed careers, or have a slightly “messy” bank statement, a mainstream lender might look at your application and simply say “no”. This is especially true for self-employed Kiwis who might have a healthy business but don’t have the two years of perfect financial records that big banks demand. 2nd tier lenders look at your real-life income and the bigger picture of your financial health. You can read more about how this works in our guide on 2nd tier lenders in NZ.

The benefits of a more flexible lender

Speed is a huge factor. If you’re in a rush to get your refinance mortgage nz sorted to secure a specific interest rate, these lenders can often move at a pace that big banks can’t match. Their approval processes are streamlined because they aren’t bogged down by the same corporate layers. They are also much more willing to lend on unique properties. If your home is a bit unconventional or has a smaller floor area than a standard suburb house, a big bank might shy away. Flexible lenders see the value where others don’t. We’ll negotiate with these providers on your behalf to make sure you get a fair dinkum deal that balances a competitive rate with the breathing room you need.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

Unlocking your home value: equity and debt consolidation

Equity is your greatest financial asset, often referred to as your “house wealth”. It’s simply the gap between what your property is worth in the current market and what you still owe the bank. With the national median dwelling value sitting at $808,187 in 2026, many Kiwis have built up significant equity without even realising it. When you refinance mortgage nz, you can tap into this wealth to improve your lifestyle or tidy up your finances.

Turning high-interest debt into low-interest mortgage debt

One of the smartest reasons to move your loan is to consolidate separate bills. It’s common to have a car loan at 12% or a credit card sitting at a painful 20% interest rate. By rolling these into your mortgage, which currently averages around 5.89% for a one-year fixed term, you can drastically reduce your monthly outgoings. Instead of juggling multiple due dates, you have one easy monthly payment.

There is a catch, though. While the interest rate is lower, you don’t want to pay off a holiday or a car over the next 25 years. We always recommend setting up a separate “slice” of your mortgage for this consolidated debt and paying it off as quickly as possible. This ensures you’re actually saving money rather than just spreading the cost over a longer period.

Using equity for investment or renovations

If you’ve been dreaming of a new kitchen or an extra bedroom, a home loan top-up is often much cheaper than taking out a personal loan. Refinancing allows you to borrow against your equity at home loan rates to fund these improvements. This not only makes your home more comfortable but can also increase its total value. For those looking even further ahead, you might have enough equity to start an investment portfolio. If you’re curious about how this works, check out our residential investment property guide.

While unlocking equity is exciting, it’s vital not to “stretch the friendship” with your budget. Borrowing more means higher repayments, so we always look at your long-term stability first. If you want to see how much equity you could safely unlock, reach out to our team for a personalised review of your numbers. We’ll help you understand exactly where you stand before you make any big decisions.

How to organise your refinance with a pro in 2026

Navigating the banking world alone is like trying to fix a complex plumbing issue without a wrench. You might get there eventually, but it’s often messy and far more stressful than it needs to be. When you choose to refinance mortgage nz in 2026, the market is moving at a rapid pace. The Reserve Bank held the Official Cash Rate at 3.25% recently, and while some economists think another small rise might pop up before Christmas, banks are currently hungry for your business with one-year rates sitting around 4.99%.

A professional broker doesn’t just look at the interest rates; they look at the bank’s “appetite” for your specific situation. Some lenders are currently leaning heavily into first-home buyers, while others are opening their doors wide for property investors. We know which doors are open and which ones are stuck, saving you hours of paperwork and the headache of a “no” that could have been a “yes” elsewhere. This insight is the most straightforward way to refinance mortgage nz and take control of your financial future.

The Mortgage Suite advantage

Our team brings over 20 years of banking and brokerage experience to the table. This means we’ve seen every possible market cycle, from the record highs of previous years to the recovery we’re seeing now. We act as your advocate and dedicated negotiator, ensuring the banks offer their absolute best “cash carrot” and interest rates. You don’t have to spend your lunch breaks on hold with a call centre. We handle the hard yards, providing a steady hand while you focus on your life. If you want to see how we’ve helped other Kiwis find a better deal, take a look at our reviews page.

Next steps to get your mortgage sorted

Getting started is a piece of cake. Before we have our first chat, it helps to have a few things ready to go. Gather your most recent payslips and three months of bank statements to show your current income and spending. It’s also a great idea to think about your big goals for the next three to five years. Are you planning to start a family, renovate the bathroom, or perhaps buy an investment property?

Once you have those bits and pieces together, simply book a chat with us to see what’s possible. We’ll review your situation, explain your options without any confusing jargon, and map out a clear path to your new loan. It really is that easy to see if we can keep more of your hard-earned money in your pocket this year.

Take the next step toward a better home loan

Refinancing isn’t just about chasing a lower number; it’s about making your money work harder for your family. Whether you’re looking to consolidate high-interest debt, fund a long-awaited renovation using your equity, or simply find a lender that understands your “real life” income, the current market provides a unique window to reset your finances. You now have the tools to refinance mortgage nz with confidence, knowing exactly what costs to watch for and how to spot a “cash carrot” that makes the move worthwhile.

You don’t have to navigate this shifting landscape alone. With over 20 years of expert banking and brokerage experience, we provide a steady hand and a personalised service that always puts you first. Our team has access to dozens of bank and non-bank lenders, ensuring you get a fair dinkum deal tailored to your big goals. Book a free chat with the Mortgage Suite team today to see how much you could be saving. It’s time to stop feeling stuck and start feeling supported.

Frequently Asked Questions

How much does it cost to refinance a mortgage in NZ?

To refinance mortgage nz, you’ll need to factor in three main costs: legal fees, valuation fees, and potential break fees. Lawyers typically charge between $800 and $1,600 to update your property title. A registered valuation usually costs between $700 and $1,200, though many lenders now accept digital estimates. Break fees vary based on your interest rate and remaining term. Often, a new bank’s cash-back offer covers these expenses entirely, making the switch cost-neutral for many.

Can I refinance if I have a low deposit or low equity?

Yes, you can still refinance with low equity, though your options at mainstream banks might be limited. The Reserve Bank recently proposed easing restrictions, allowing more lending to those with less than a 20% deposit. If a big bank says no, 2nd tier lenders are often more flexible. They look at your overall financial health rather than just a percentage. We help you find a lender that fits your specific equity level without the stress.

How long does the refinancing process actually take?

The entire process typically takes between two and four weeks from your first chat with us to the day the new loan starts. This includes the time needed to gather your documents, get the bank’s approval, and complete the legal paperwork with your lawyer. If you’re in a rush to secure a specific rate, some non-bank lenders can move even faster. Having your payslips and bank statements ready before we start helps speed things up significantly.

Do I need a lawyer to refinance my home loan?

Yes, you must use a lawyer or conveyancer when you move your mortgage to a new lender. They are responsible for the legal heavy lifting, which includes discharging your old mortgage and registering the new one on your property title. They also handle the transfer of funds between the banks on settlement day. While this adds a cost of roughly $800 to $1,600, it’s a legal requirement in New Zealand to ensure the title is correctly updated.

Will I get a cash-back offer if I switch banks in 2026?

Most New Zealand banks are offering competitive cash-back incentives in 2026 to attract new customers. These offers can be as high as 1% of your total loan amount. For a $500,000 mortgage, that’s $5,000 in your pocket. This cash is usually paid out on the day your new loan starts and is designed to help cover your legal and valuation costs. Just remember that most banks have a three to four-year stay period to keep it.

Can I refinance my mortgage if I am self-employed?

Absolutely. While big banks often demand two years of perfect financial records, many other lenders are happy to work with self-employed Kiwis. To refinance mortgage nz when you work for yourself, we focus on showing your real life income through recent bank statements and GST returns. If you don’t fit the rigid big-bank boxes, we’ll look at flexible 2nd tier options that value your business success and provide the funding you need.

What is the difference between refixing and refinancing?

Refixing is simply choosing a new interest rate with your current bank when your fixed term ends. It’s quick but doesn’t offer the benefits of a fresh start. Refinancing means moving your entire home loan to a different lender. This allows you to negotiate for a better rate, snag a cash-back offer, and change your loan features. It requires more effort and legal work, but the long-term interest savings are often much larger than staying put.

Is it a good idea to consolidate my debt into my mortgage?

Consolidating high-interest debts like credit cards or car loans into your mortgage can be a brilliant move to lower your monthly payments. You’ll drop from interest rates of 12% or 20% down to the current average home loan rate of around 5.89%. However, it’s vital to pay off that extra debt quickly rather than dragging it out for 25 years. We’ll help you structure your loan into separate slices to ensure you’re actually saving money.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.