Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Your business success should be your greatest mortgage asset, not the reason a bank says no. It’s a common frustration for New Zealand entrepreneurs who feel penalised for their drive and independence. You’ve likely heard that traditional low doc home loans nz are harder to find now that the Financial Markets Authority has taken over credit regulation, but that doesn’t mean your home ownership dreams are over. We understand that your business bank statements often tell a much more accurate story than a standard tax return ever could.

You deserve a clear path to approval that doesn’t involve a mountain of confusing paperwork or endless anxiety. In this guide, we’ll show you exactly how to handle the 2026 lending market to get your home loan sorted. We will explore the rise of alternative documentation options, explain how second-tier lenders operate, and provide a step-by-step strategy to move from a bank decline to a front door key in your hand.

Key Takeaways

  • Being self-employed is a major achievement, and we will show you how to use your business success as an asset rather than a hurdle when applying for a mortgage.
  • Learn how traditional low doc home loans nz have evolved into flexible alternative documentation options from safe, regulated lenders who actually understand your business story.
  • Discover the specific, simple paperwork you need to show your true income without the stress of overwhelming accounting jargon or complex bank requirements.
  • Get practical tips on how to tidy up your accounts and why paying yourself a consistent salary can significantly boost your chances of loan approval.
  • Find out how to partner with a veteran advocate who knows the non-bank market inside out and will fight to get you into a home when the big banks say no.

What does it mean to get a mortgage for self-employed NZ borrowers?

At its heart, a self-employed mortgage is just a standard home loan. It’s helpful to understand what is a mortgage in the broadest sense: a way to secure property using the equity you build over time. For you, the only real difference is how you prove you can afford the repayments. Banks often see your business as a risk, but we see it as a massive achievement. Whether you’re a tradie on the tools or a freelancer working from a home office, your drive shouldn’t be a hurdle to getting your own place.

Many Kiwis feel like they’re being penalised for their entrepreneurial spirit. If a mainstream bank has already said no, you might think you’re out of options. The market for low doc home loans nz has evolved significantly. While the big banks are often stuck in a cycle of strict criteria, other lenders are more interested in your actual business story and your ability to manage money. We help everyone from company directors and contractors to sole traders find a path forward.

Why the big banks treat you differently

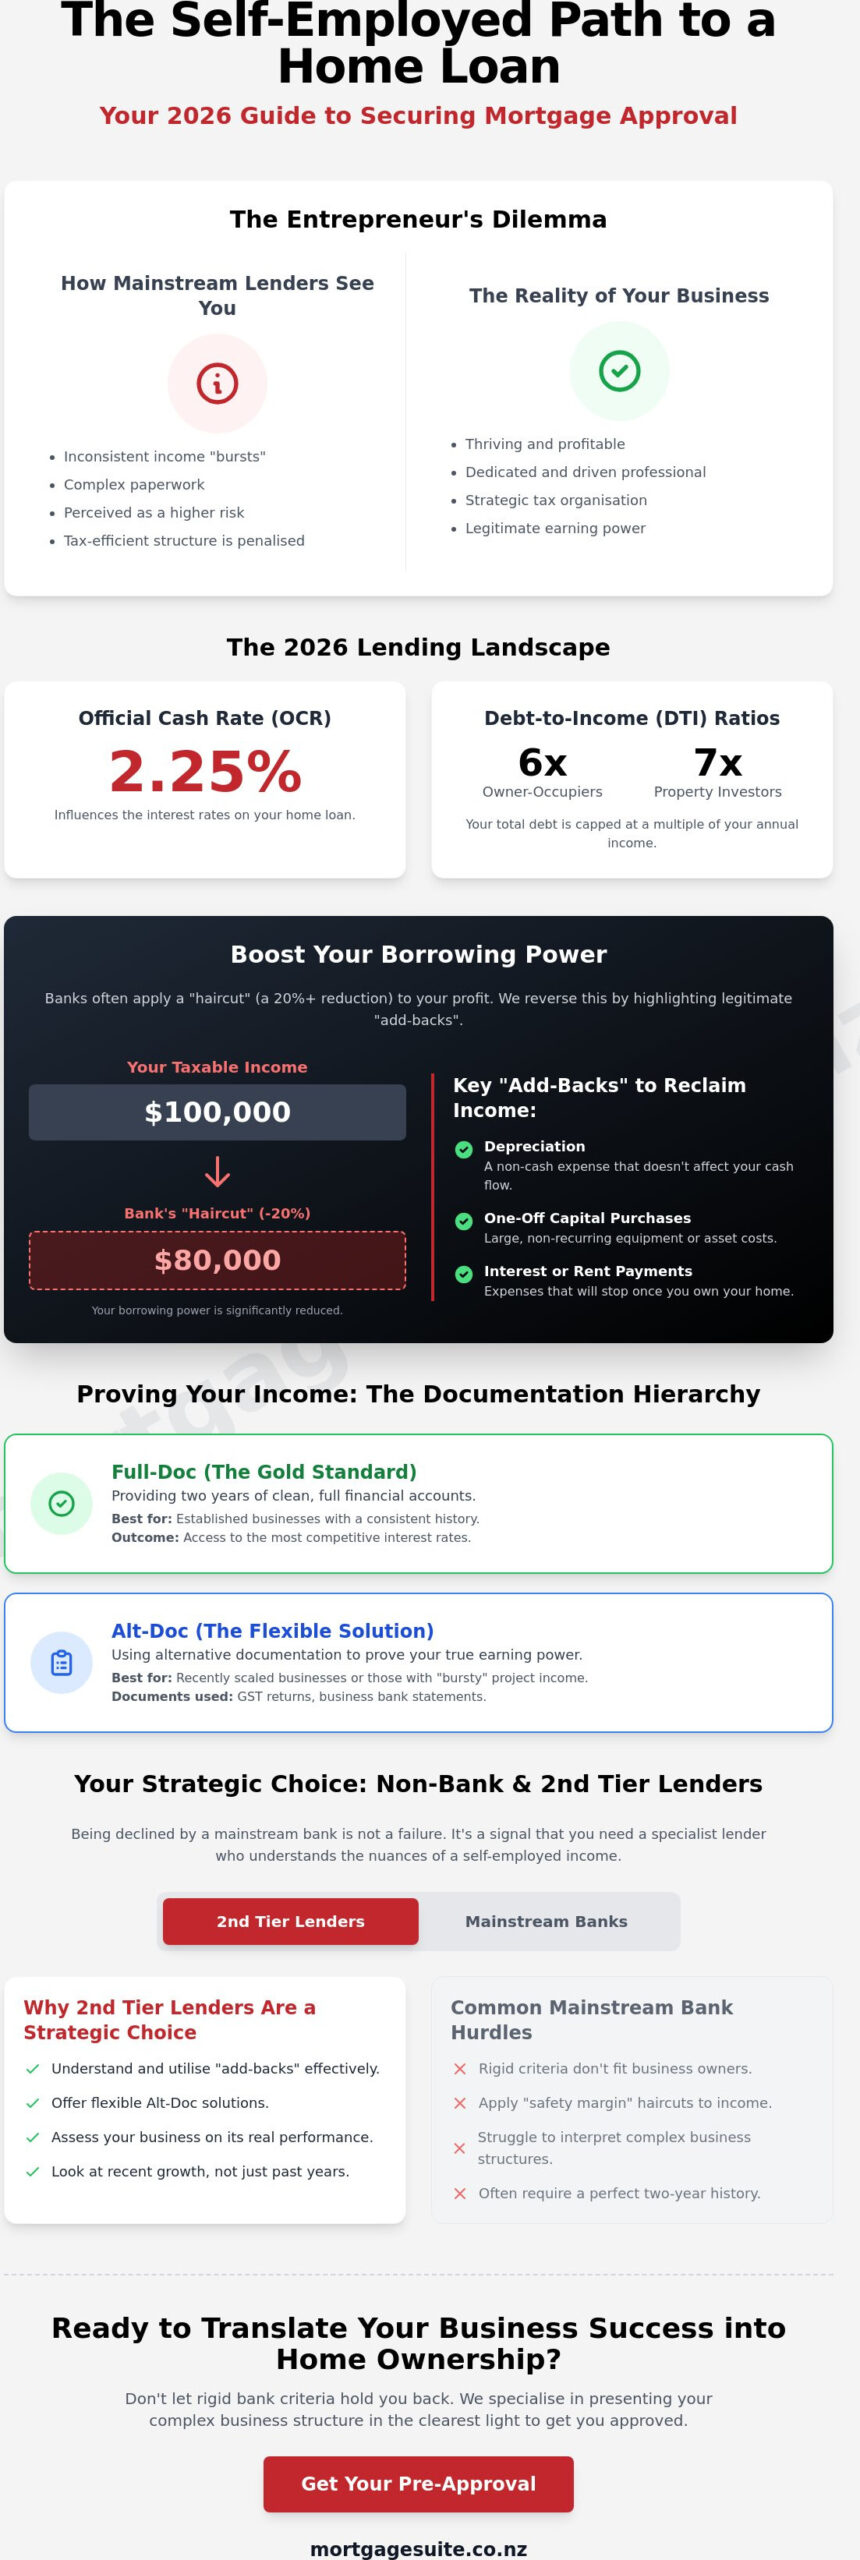
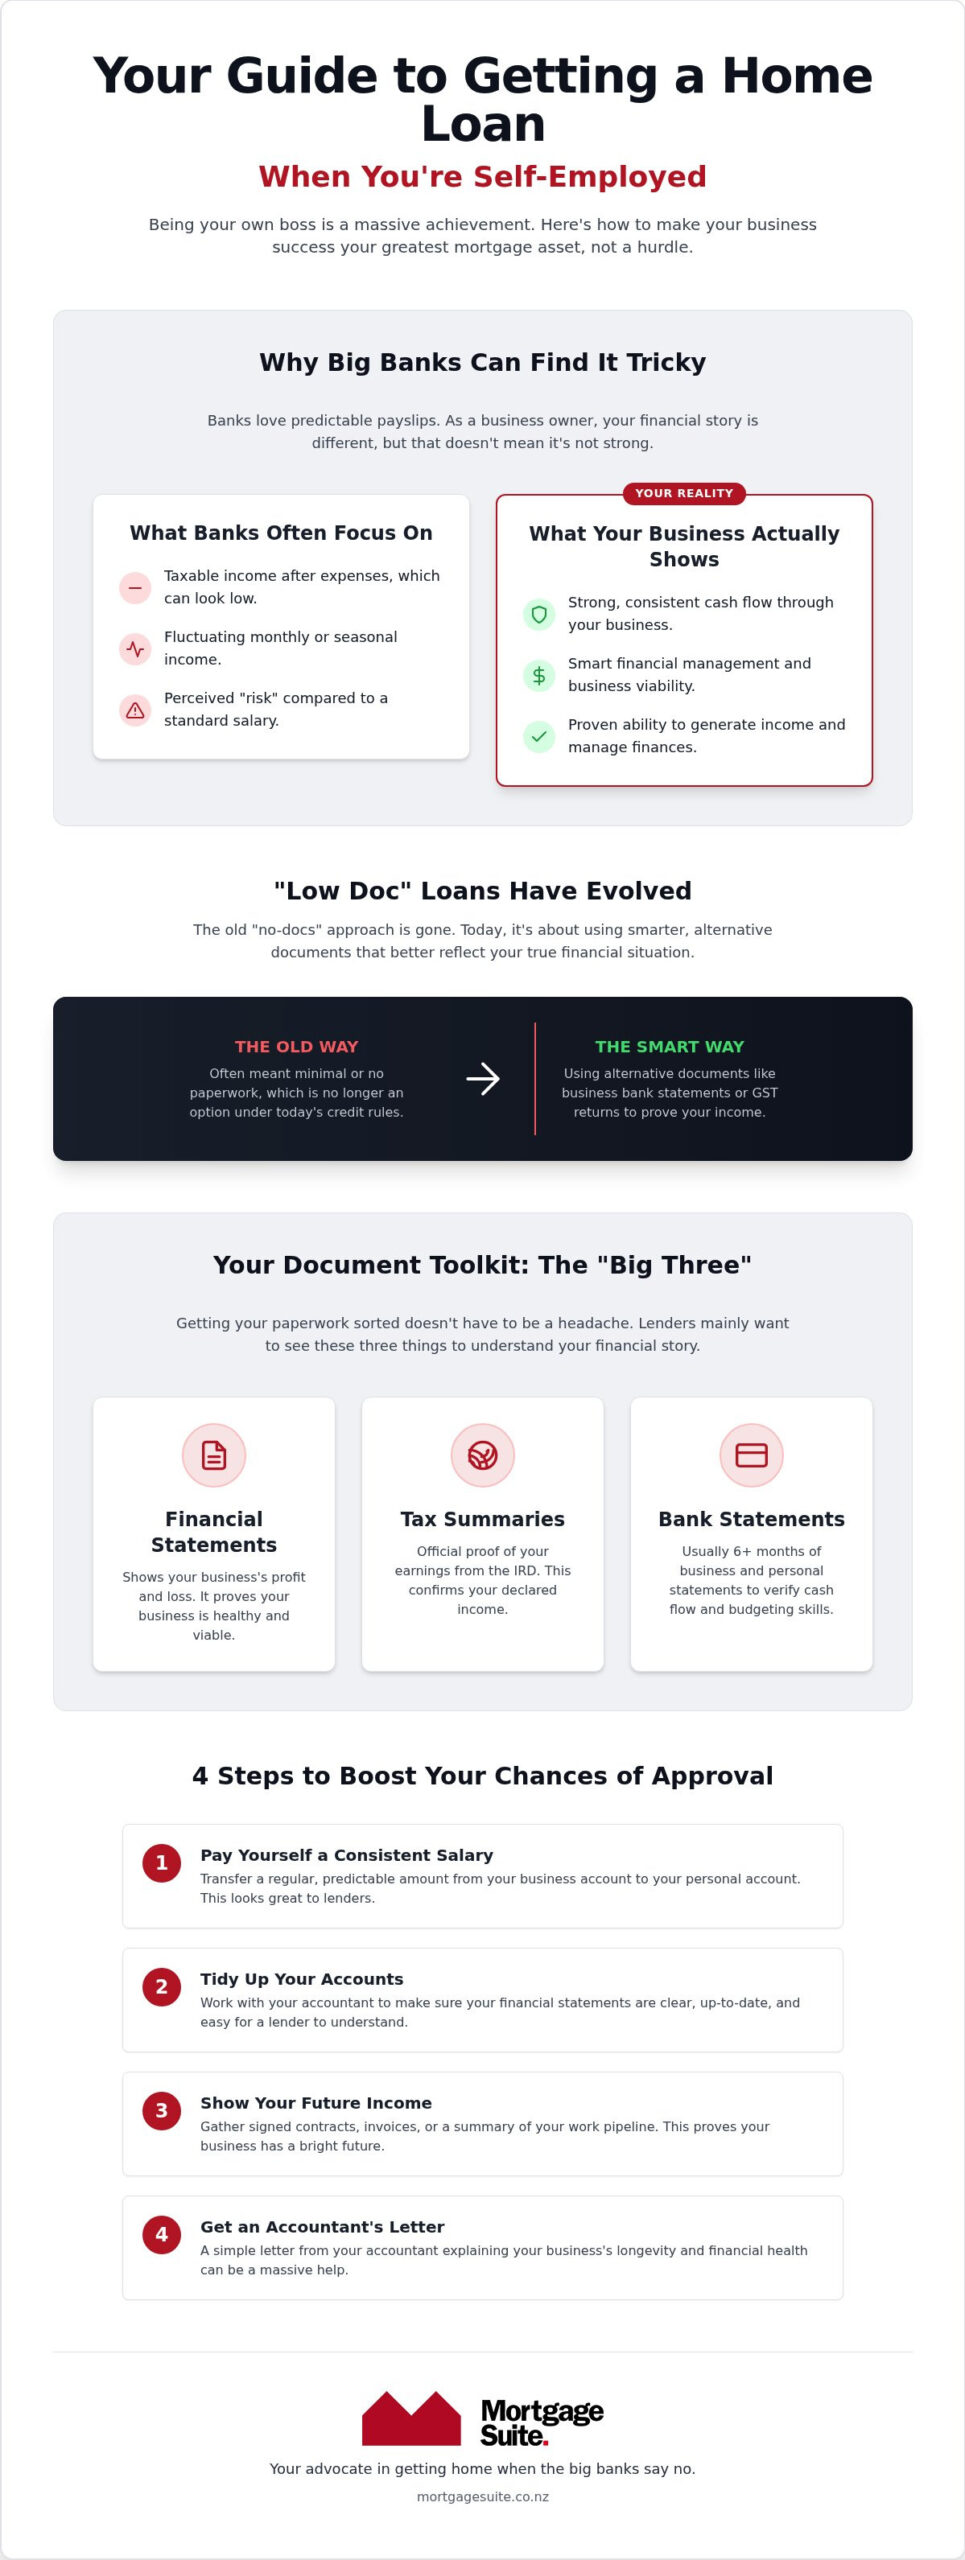
Banks love predictability. They want to see a payslip that looks exactly the same every fortnight. When you run your own show, your income might go up and down depending on the season or when a big contract finishes. Mainstream lenders also tend to focus purely on your taxable income. Because you likely work with an accountant to legally minimise your tax, your “on paper” profit might look much lower than the actual cash you have available to pay a mortgage. In 2026, banks are using test rates around 7% to see if you can handle repayments. For a business owner with fluctuating income, meeting that hurdle while staying under the debt-to-income (DTI) cap of 6 can feel impossible without an expert in your corner.

The different types of self-employed income

Not all self-employment is the same. A full-time contractor might have a steady stream of work from one source, while a small business owner manages staff and overheads. Sometimes, a one-off business expense, like a new piece of machinery or a vehicle, can confuse a bank’s computer system and make it look like your business is struggling. If you’re just starting out on this journey, our First Home Buyer Guide is a great place to see how the basics apply to you. Specialised low doc home loans nz or alternative documentation options can bridge this gap by looking at your GST returns or bank statements instead of just a standard tax summary.

The paperwork you will need to get sorted

Gathering a mountain of files can feel like a full-time job. It’s often the point where many entrepreneurs give up before they’ve even started. You might worry that your accounts aren’t perfect or that a single quiet month will ruin your chances. In 2026, the concept of low doc home loans nz has shifted. It no longer means “no documents” at all. Instead, it refers to alternative documentation that fits your life better than a standard payslip. We act as your mentor through this process, helping you pick out the right files to show your financial strength.

The Big Three documents

Lenders typically focus on three core areas to understand your situation. First, your financial statements tell the story of your business profit and loss. We keep this simple. It’s about showing that your business is a viable, living entity. Second, you’ll need tax summaries from the IRD to prove your official earnings. Finally, personal bank statements are vital. Under current regulations managed by the Financial Markets Authority, lenders often look for at least six months of business bank statements to verify your cash flow. These personal records show how you handle your household budget and prove you can manage the commitment of a home loan.

Proving your future income

Banks are naturally cautious, so showing them a bright future is just as important as showing a solid past. If you have a stack of signed contracts or a healthy pipeline of work for the coming year, these are massive assets for your approval. A simple letter from your accountant can also go a long way. They can explain the longevity of your business and why certain one-off expenses shouldn’t count against you. Essentially, income verification is just the process of proving you have the actual cash on hand to cover your repayments without struggle.

If you’re feeling overwhelmed by the requirements, it’s often helpful to see what others in your position have achieved. You can read through our client reviews to see how we’ve helped other self-employed Kiwis get their paperwork sorted and their loans approved.

When the bank says no: Exploring 2nd tier and alternative lenders

Hearing a “no” from a mainstream bank can feel like a punch in the gut. You’ve worked hard to build your business, and being told you aren’t “predictable” enough is discouraging. It’s important to remember that a bank’s rejection isn’t a reflection of your business success. It’s simply a sign that you don’t fit their very narrow, rigid box. This is where 2nd tier lenders come in. These are professional, safe, and fully regulated finance companies that operate without the big bank branding. They specialise in low doc home loans nz because they have the freedom to look at the person and the business story, not just a standard spreadsheet.

Using a non-bank lender isn’t a last resort. It’s a strategic move used by many of New Zealand’s most successful entrepreneurs. These lenders are solution-based. They understand that a business owner’s wealth is often tied up in growth and assets rather than a static salary. For a deeper dive into how these finance companies can help you, check out our 2nd Tier Lender Guide.

Mainstream Banks vs. 2nd Tier Lenders

The differences between these two worlds are significant. Mainstream banks offer lower interest rates, but their rules are incredibly strict and their processes are often slow. If you don’t have two years of perfect, steady tax returns, they’ll likely struggle to say yes. In contrast, 2nd tier lenders offer more flexible rules. As of mid-2026, while mainstream rates for one-year fixed terms sit around 4.8%, non-bank rates for alternative documentation loans typically start from about 6.35%.

A 2nd tier loan is often used as a vital stepping stone. You can secure your home now, build equity for 12 to 24 months, and then refinance with a mainstream bank once your accounts have settled into a pattern the banks recognise. This proactive approach gets you into the property market years sooner than waiting for a bank’s approval.

The benefit of a specialised negotiator

Because the non-bank world is diverse, having a veteran mentor on your side is vital. We don’t just pass on your paperwork. We act as your advocate, carefully presenting your business to the right lender to ensure they see your success rather than a risk. Krish Krishna’s 20 years of industry experience means he knows exactly which lenders are currently looking for businesses like yours. We know how to tell your story in a way that opens doors that might otherwise stay shut. Our goal is to remove the stress and provide a clear, confident path to your new home.
Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Steps to improve your chances of approval

Preparing for a mortgage when you’re your own boss is all about presentation. Think of it like dressing your business up for an interview. One of the most effective things you can do is keep your personal and business expenses completely separate. When your accounts are clean, it’s much easier for a lender to see that your business is thriving and that you have the cash flow to handle a home loan. This clarity is especially important when we’re looking at low doc home loans nz, as it allows the lender to trust the alternative documents we provide.

Another great move is to pay yourself a consistent salary. Even if you own 100% of the company, regular transfers into your personal account look fantastic to a lender. It mimics the predictability of a standard job, which banks find very reassuring. You should also look at managing your existing debt. Clearing a car loan or closing an unused credit card can significantly boost how much you’re allowed to borrow. Before you get too far down the track, it’s a smart idea to use our mortgage calculator to see what a realistic repayment looks like for your budget.

Clean up your personal bank statements

In the three months before you apply, try to avoid any unusual spending spikes. Lenders look closely at your day-to-day habits to see how you’ll handle a mortgage. This is also the time to pause any “buy now, pay later” schemes. While they’re handy for small purchases, lenders often view them as a line of credit that reduces your overall borrowing power. Being squeaky clean with your bill payments and regular outgoings shows that you’re disciplined and reliable.

Timing your application

Timing can be everything. If you’ve just made a massive business investment, like buying new machinery or a fleet of vehicles, your cash reserves might look a bit low. It’s often better to wait until those investments start showing a return. The sweet spot for many self-employed Kiwis is right after the end of the financial year on March 31st. This is when your latest figures are fresh and your accountant can provide the most up-to-date proof of your success. Loan readiness is about showing you are a safe pair of hands. If you’re ready to see what’s possible for your business, get in touch with us today to start the conversation.

How Mortgage Suite helps self-employed Kiwis get home

At Mortgage Suite Ltd, we don’t believe your business success should be a barrier to buying a home. We take an advocacy-led approach to every application. This means we don’t just bundle up your paperwork and hope for the best. We actively fight your corner with lenders to make sure they see the full value of what you’ve built. Because we are a business ourselves, we understand the long hours and the dedication it takes to be your own boss. We aren’t a cold corporate office; we are your partners in this process. Whether you’re looking for a property in the far north or the deep south, our national reach means we can help you secure a home anywhere in New Zealand.

If you’re curious about how this works in practice, we encourage you to read our client reviews. You’ll see stories from other Kiwis who thought their dream was over after a bank decline, only to find a path forward with us. We know that every business has a unique story, and we make it our mission to ensure that story is heard by the right people.

A personal approach from an industry veteran

Krish Krishna brings over two decades of banking and finance experience to the table. He uses this deep institutional knowledge to navigate the often complex world of low doc home loans nz and alternative lending. The Mortgage Suite Ltd way is about removing the weight from your shoulders. We aim to make a process that usually feels overwhelming into something that is sorted and stress-free. You can learn more about us and our philosophy of partnership. We believe in building long-term relationships, not just processing one-off transactions.

Your next steps to home ownership

Taking the next step doesn’t have to be scary. Our first conversation is simply about understanding your goals and where you want to go. There is absolutely no pressure and definitely no confusing jargon. We’ll look at your current situation and build a clear, actionable plan together. Our goal is to move you from a “declined” status to a firm approval. You’ve already done the hard work of building a successful business. Now, let’s work together to build your future in a home you actually own. Getting your low doc home loans nz sorted is much easier when you have a veteran mentor who knows exactly which levers to pull.

Take the lead on your home ownership journey

Building a business is a major achievement that proves you have the drive to succeed. While big banks might focus on rigid boxes, you now know that alternative documentation and second-tier lenders offer a professional, regulated path to your new home. Securing low doc home loans nz is about finding the right lender who understands your unique story and sees your success as an asset. By tidying your accounts and paying yourself a consistent salary, you’re already halfway there.

With over 20 years of banking expertise, our team at Mortgage Suite acts as your dedicated negotiator. We specialise in non-bank and second-tier lending, and we know exactly how to open doors that mainstream lenders often keep shut. We’ll handle the complex paperwork so you can focus on what you do best: running your business. Ready to get your mortgage sorted? Book a chat with the Mortgage Suite team today. Your entrepreneurial spirit has built your business, now let’s use it to build your future in a home of your own. You’ve got this.

Frequently Asked Questions

Can I get a mortgage if I’ve only been self-employed for one year?

Yes, you certainly can. While major banks typically look for two years of accounts, many second tier lenders only require six to twelve months of trading history. We focus on showing the strength of your business through GST returns and bank statements. If your industry experience is solid and your current cash flow is healthy, we can often find a solution that gets you into a home much sooner than a bank would allow.

Do I need a bigger deposit if I’m self-employed in NZ?

Not always, but it helps to be prepared. If you fit a bank’s standard criteria, a 20% deposit is the norm. For those using low doc home loans nz or alternative documentation, lenders might ask for 20% to 30%. This larger deposit acts as a safety net for the lender. However, we have seen cases where a smaller deposit is possible depending on the strength of your business story and the specific property you are buying.

What is a low doc loan and is it right for me?

In 2026, these are often called “alt doc” loans. They are designed for business owners who have a solid income but don’t have standard tax returns ready yet. Instead of IRD summaries, the lender looks at your bank statements or GST filings. It’s a great fit if you’ve recently invested back into your business or have a complex income structure that a standard bank computer doesn’t understand or recognise as stable.

Will I have to pay a higher interest rate because I work for myself?

Not necessarily. If you qualify for a standard bank loan, your rate will be the same as any other borrower. However, if you need the flexibility of a non-bank lender, you should expect to pay a bit more. As of mid-2026, non-bank rates for low doc home loans nz often start around 6.35%. Many of our clients see this as a temporary cost to get into the market before refinancing later on.

Can I use my business profit to help with my mortgage application?

Absolutely. Lenders focus on your net profit before tax. We also work with your accountant to identify “add-backs.” These are one-off business expenses, like a new vehicle purchase or depreciation, that shouldn’t count against your ability to pay a mortgage. By adding these back into your profit, we can often show a much stronger income than what appears on your final tax bill, which helps with your borrowing power.

What happens if my business had a bad year recently?

A single quiet year isn’t an automatic decline. We look at the reason behind the numbers. If you had a dip because of a strategic investment or a one-off event, we can explain that story to a lender. Many second tier lenders are happy to look at your most recent six months of trading to see that your business has recovered and is currently performing well. It’s about showing your current financial health.

How do I prove my income if I’m a contractor?

Proving income as a contractor is all about showing your track record. Lenders will want to see your current signed contracts, your GST returns, and at least six months of business bank statements. They look for a pattern of regular payments and a healthy pipeline of future work. If you’ve been in the same industry for a long time, that experience counts for a lot even if you are relatively new to contracting.

Why should I use a broker instead of going straight to my bank?

Your bank only has one set of rules and one list of products. If you don’t fit their box, they simply say no. A broker has access to dozens of lenders, including specialised second tier companies that don’t deal with the public directly. We act as your advocate, using over twenty years of experience to tell your business story to the right person. We find the “yes” that your bank might have missed.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

What if the bank that recently said “no” to your renovation top-up isn’t actually the best place for your home loan anymore? It’s incredibly frustrating to watch high interest rates eat into your weekly budget while you feel stuck with a lender that doesn’t seem to value your loyalty. You aren’t alone in feeling this way, especially as you look to refinance mortgage nz in a 2026 market where the average one-year fixed rate is sitting around 5.89%.

We’re here to help you take back control. This guide shows you exactly how to swap your current loan for a better deal, unlock the value you’ve built up in your home, and save thousands of dollars in interest. We’ll cut through the confusion surrounding break fees and legal costs, giving you the confidence to make a move that actually benefits your bottom line. You’ll discover how to find a lender that fits your life now, whether you need extra cash for a kitchen makeover or simply want lower monthly repayments. We’ll preview the practical steps to switching and explain how having a seasoned pro in your corner makes the entire process feel like a breeze.

Key Takeaways

  • Learn why moving your home loan is similar to switching phone providers, but with the potential to save you thousands in interest over the long run.
  • Discover how to navigate break fees and secure a “cash carrot” from a new lender to help cover your legal and moving costs.
  • Find out how to refinance mortgage nz by using a pro to negotiate with both mainstream banks and flexible alternative lenders who are more likely to say “yes”.
  • Understand how to use your house wealth to tidy up high-interest debts like car loans and credit cards into one easier payment.
  • Get a straightforward look at the 2026 market outlook so you can time your switch perfectly for maximum monthly savings.

What exactly is refinancing and why should Kiwis bother?

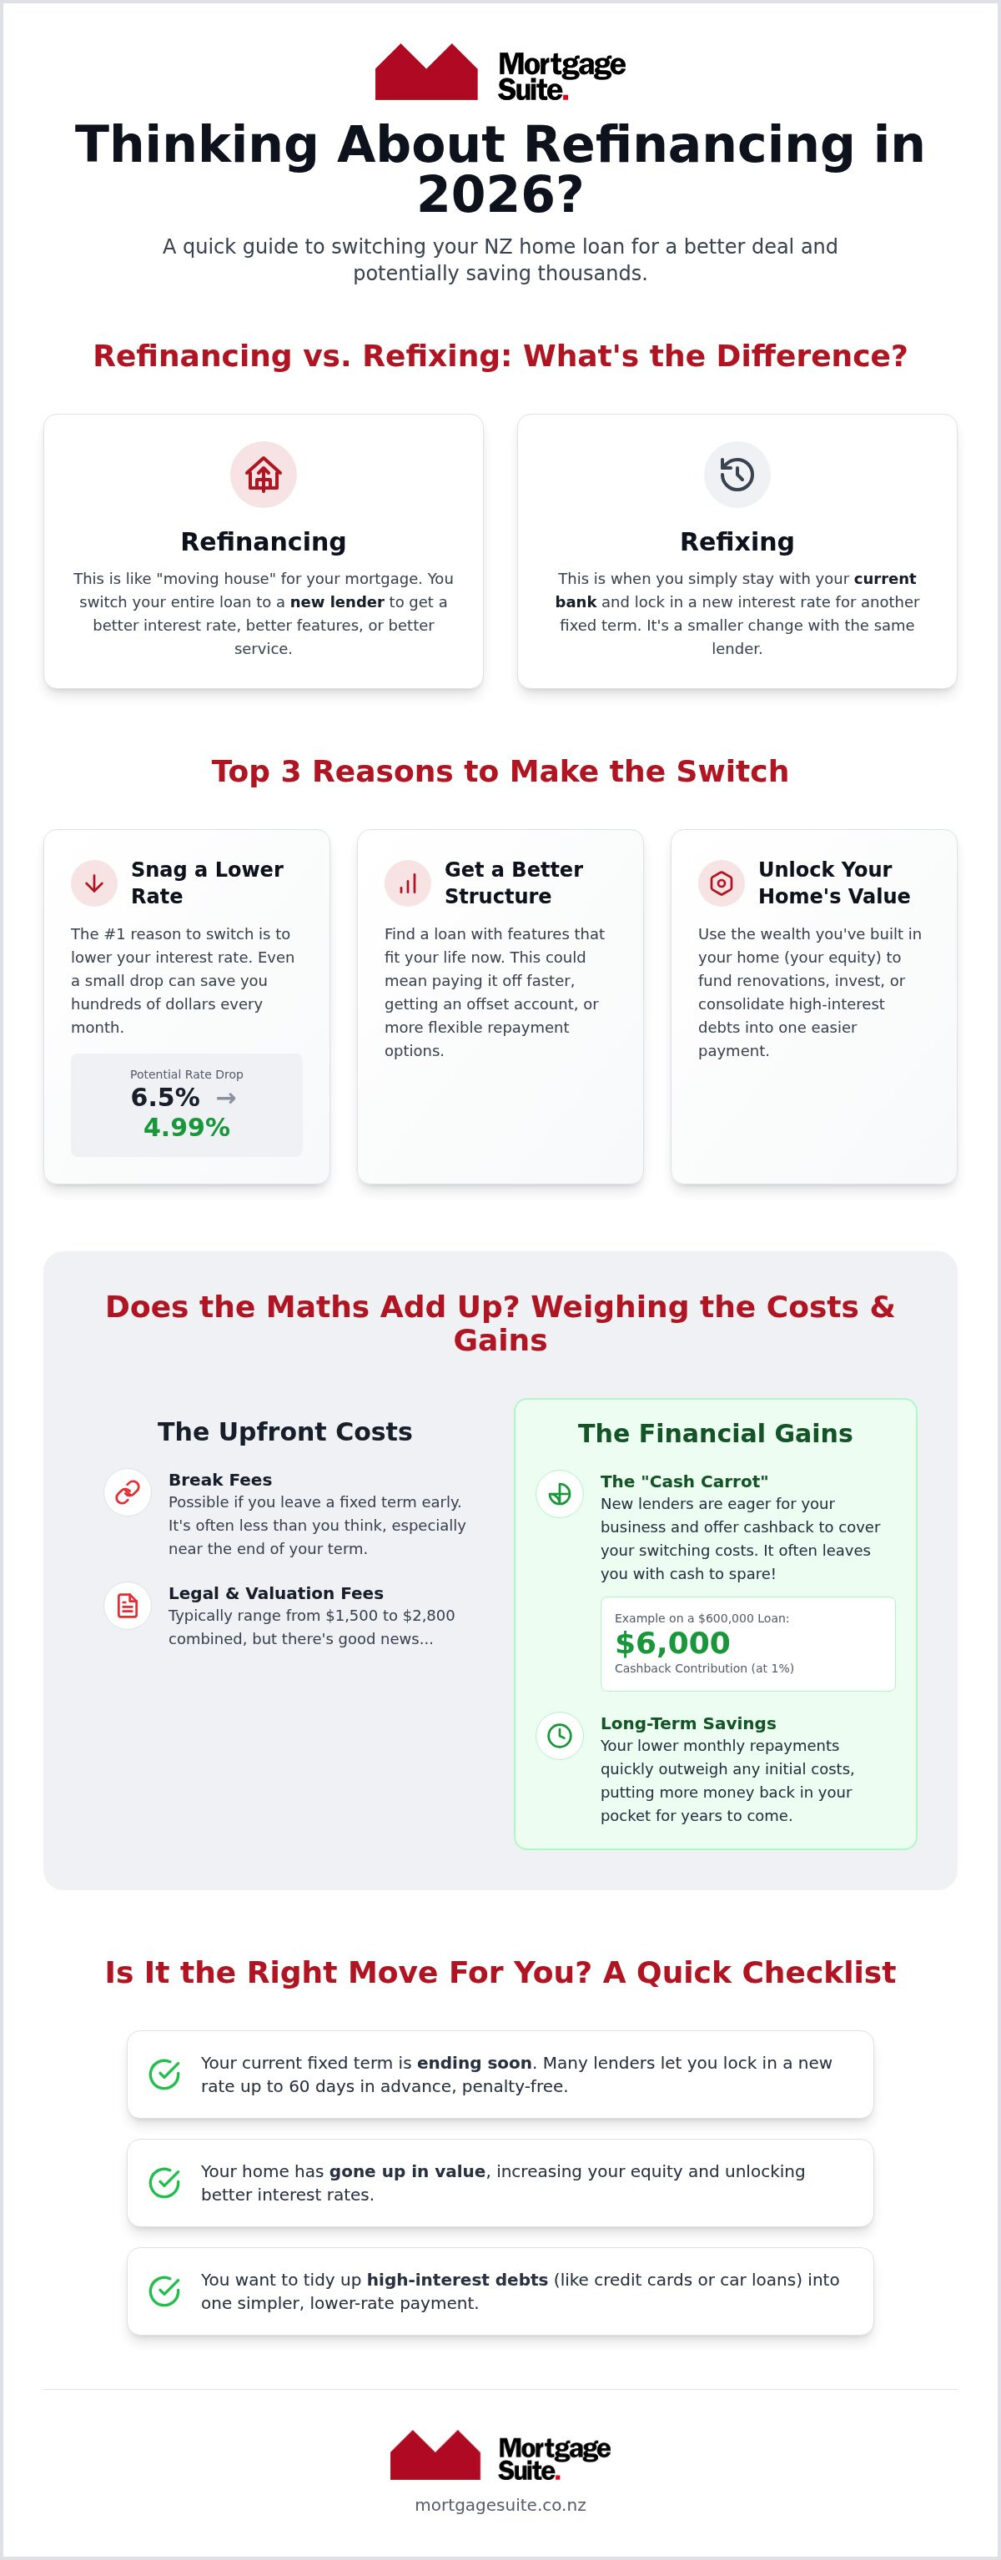
Think of your home loan like your mobile phone plan. Every year or two, you probably check if another provider has a better deal on data or a cheaper monthly cost. Refinancing is essentially the same thing, just with much bigger numbers and more zeros. When you decide to refinance mortgage nz, you’re simply moving your debt from one lender to another to get a better deal on your interest rate or loan features.

To understand the basics, you can look at What is refinancing to see how it works globally; however, for us here in New Zealand, it’s about making sure your bank is still working as hard as you are. Many people confuse this with “refixing”. Refixing is when you stay with your current bank and just choose a new interest rate for another year or two. Refinancing is “moving house” for your loan to find a more competitive partner that actually fits your current goals.

Right now, 2026 is a cracking time to look at your options. With the Official Cash Rate sitting at 3.25% and banks offering one-year fixed rates around 4.99%, the market has shifted significantly from the highs of previous years. If you’ve been stuck on a rate above 6.5% from a term you fixed in 2023 or 2024, switching now could save you a small fortune in interest costs over the next few years.

The main reasons to make the switch

Most homeowners move for one of three reasons. First, snagging a lower interest rate is the most common goal. Even a small drop can keep hundreds of dollars in your pocket every month. Second, you might want to change how you pay off the debt. You could switch to a structure that helps you become debt-free faster without increasing your stress levels. Finally, you might just want better service. If your current bank’s mobile app is clunky or they don’t offer offset accounts to help you save on interest, it’s time to look elsewhere. You can learn more about these different loan structures at our Mortgage School.

Is it the right move for you?

This path makes the most sense if your current fixed term is nearly up. If you’re within a few months of your rate expiring, you can start the conversation now to avoid being rolled onto a high floating rate. It’s also a winner if your home has gone up in value. This increase builds your equity, which is simply the bit of the house you actually own versus what the bank owns. If your house is worth $800,000 and you owe $500,000, you have $300,000 in equity. Having more equity often unlocks better rates and more flexible options for things like renovations or debt consolidation.

The real costs and savings of switching banks

Switching banks isn’t just about signing a new piece of paper; it involves a bit of maths to ensure the move actually makes sense for your wallet. While the goal is to save money, you have to account for the upfront costs to find your “break-even” point. This is the moment where your monthly interest savings finally outweigh the fees you paid to make the jump. For most Kiwis looking to refinance mortgage nz, this point arrives much sooner than they expect.

Understanding break fees and early exit costs

If you’re currently on a fixed-rate term, your bank might charge a break fee if you leave early. Banks charge this because they’ve already “bought” the money for your loan at a specific price. If market rates have dropped since you locked in, they lose money when you leave. To get an estimate, you can simply ask your current bank for a “break quote”. It’s often smaller than people fear, especially if you’re near the end of your term.

Timing is your best friend here. A helpful strategy is the “60-day rule”, where many lenders allow you to lock in a new interest rate up to two months before your current term expires. This lets you secure a better deal for the future without paying a cent in early exit fees today. By watching the market closely, you can time your move to avoid the biggest costs while still snagging a lower rate.

You also need to factor in the legal side. Because you’re moving your loan to a new lender, a lawyer must update the title of your property. These legal fees typically range from $800 to $1,600. In some cases, a bank might also ask for a registered valuation, which can cost between $700 and $1,200, though many lenders in 2026 now accept automated digital valuations for standard homes.

Cash incentives and legal subsidies

The good news is that banks are incredibly hungry for your business in 2026. To lure you away from their competitors, they often dangle a “cash carrot” in the form of a cashback offer. These incentives can be as much as 1% of your total loan amount. On a $600,000 mortgage, that’s $6,000 landing in your bank account, which easily covers your legal fees and any small break costs with plenty left over.

Just keep an eye on the “clawback” clause. Most banks require you to stay with them for a set period, usually three to four years, to keep that cash. If you move again too soon, they’ll ask for a portion of it back. You can use our mortgage calculator to see how these incentives and lower rates stack up against your current payments. Often, the savings are so significant that the move pays for itself in just a few months. If you’re feeling unsure about the numbers, talking to an expert can help you see if a switch is truly a winner for your specific situation.

Bank vs. Non-Bank lenders: finding your best fit

When you look to refinance mortgage nz, your first thought is probably your current bank or one of their big rivals. Mainstream banks love “standard” borrowers. If you have a steady salary, a large deposit, and a perfect credit history, they’ll usually roll out the red carpet. However, they aren’t the only game in town. In 2026, more Kiwis than ever are finding that alternative lenders, often called 2nd tier lenders, offer the flexibility they actually need.

These non-bank lenders are reliable, regulated, and often more approachable than the big institutions. They account for over 10% of new home loans in the current market because they don’t just rely on rigid computer algorithms to make decisions. Instead, they take a more human approach to your application. We help you navigate both worlds to ensure you aren’t just getting a loan, but finding a partner that suits your long-term goals.

When the big banks say “no”

Banks can be incredibly picky. If you’ve recently started a business, changed careers, or have a slightly “messy” bank statement, a mainstream lender might look at your application and simply say “no”. This is especially true for self-employed Kiwis who might have a healthy business but don’t have the two years of perfect financial records that big banks demand. 2nd tier lenders look at your real-life income and the bigger picture of your financial health. You can read more about how this works in our guide on 2nd tier lenders in NZ.

The benefits of a more flexible lender

Speed is a huge factor. If you’re in a rush to get your refinance mortgage nz sorted to secure a specific interest rate, these lenders can often move at a pace that big banks can’t match. Their approval processes are streamlined because they aren’t bogged down by the same corporate layers. They are also much more willing to lend on unique properties. If your home is a bit unconventional or has a smaller floor area than a standard suburb house, a big bank might shy away. Flexible lenders see the value where others don’t. We’ll negotiate with these providers on your behalf to make sure you get a fair dinkum deal that balances a competitive rate with the breathing room you need.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

Unlocking your home value: equity and debt consolidation

Equity is your greatest financial asset, often referred to as your “house wealth”. It’s simply the gap between what your property is worth in the current market and what you still owe the bank. With the national median dwelling value sitting at $808,187 in 2026, many Kiwis have built up significant equity without even realising it. When you refinance mortgage nz, you can tap into this wealth to improve your lifestyle or tidy up your finances.

Turning high-interest debt into low-interest mortgage debt

One of the smartest reasons to move your loan is to consolidate separate bills. It’s common to have a car loan at 12% or a credit card sitting at a painful 20% interest rate. By rolling these into your mortgage, which currently averages around 5.89% for a one-year fixed term, you can drastically reduce your monthly outgoings. Instead of juggling multiple due dates, you have one easy monthly payment.

There is a catch, though. While the interest rate is lower, you don’t want to pay off a holiday or a car over the next 25 years. We always recommend setting up a separate “slice” of your mortgage for this consolidated debt and paying it off as quickly as possible. This ensures you’re actually saving money rather than just spreading the cost over a longer period.

Using equity for investment or renovations

If you’ve been dreaming of a new kitchen or an extra bedroom, a home loan top-up is often much cheaper than taking out a personal loan. Refinancing allows you to borrow against your equity at home loan rates to fund these improvements. This not only makes your home more comfortable but can also increase its total value. For those looking even further ahead, you might have enough equity to start an investment portfolio. If you’re curious about how this works, check out our residential investment property guide.

While unlocking equity is exciting, it’s vital not to “stretch the friendship” with your budget. Borrowing more means higher repayments, so we always look at your long-term stability first. If you want to see how much equity you could safely unlock, reach out to our team for a personalised review of your numbers. We’ll help you understand exactly where you stand before you make any big decisions.

How to organise your refinance with a pro in 2026

Navigating the banking world alone is like trying to fix a complex plumbing issue without a wrench. You might get there eventually, but it’s often messy and far more stressful than it needs to be. When you choose to refinance mortgage nz in 2026, the market is moving at a rapid pace. The Reserve Bank held the Official Cash Rate at 3.25% recently, and while some economists think another small rise might pop up before Christmas, banks are currently hungry for your business with one-year rates sitting around 4.99%.

A professional broker doesn’t just look at the interest rates; they look at the bank’s “appetite” for your specific situation. Some lenders are currently leaning heavily into first-home buyers, while others are opening their doors wide for property investors. We know which doors are open and which ones are stuck, saving you hours of paperwork and the headache of a “no” that could have been a “yes” elsewhere. This insight is the most straightforward way to refinance mortgage nz and take control of your financial future.

The Mortgage Suite advantage

Our team brings over 20 years of banking and brokerage experience to the table. This means we’ve seen every possible market cycle, from the record highs of previous years to the recovery we’re seeing now. We act as your advocate and dedicated negotiator, ensuring the banks offer their absolute best “cash carrot” and interest rates. You don’t have to spend your lunch breaks on hold with a call centre. We handle the hard yards, providing a steady hand while you focus on your life. If you want to see how we’ve helped other Kiwis find a better deal, take a look at our reviews page.

Next steps to get your mortgage sorted

Getting started is a piece of cake. Before we have our first chat, it helps to have a few things ready to go. Gather your most recent payslips and three months of bank statements to show your current income and spending. It’s also a great idea to think about your big goals for the next three to five years. Are you planning to start a family, renovate the bathroom, or perhaps buy an investment property?

Once you have those bits and pieces together, simply book a chat with us to see what’s possible. We’ll review your situation, explain your options without any confusing jargon, and map out a clear path to your new loan. It really is that easy to see if we can keep more of your hard-earned money in your pocket this year.

Take the next step toward a better home loan

Refinancing isn’t just about chasing a lower number; it’s about making your money work harder for your family. Whether you’re looking to consolidate high-interest debt, fund a long-awaited renovation using your equity, or simply find a lender that understands your “real life” income, the current market provides a unique window to reset your finances. You now have the tools to refinance mortgage nz with confidence, knowing exactly what costs to watch for and how to spot a “cash carrot” that makes the move worthwhile.

You don’t have to navigate this shifting landscape alone. With over 20 years of expert banking and brokerage experience, we provide a steady hand and a personalised service that always puts you first. Our team has access to dozens of bank and non-bank lenders, ensuring you get a fair dinkum deal tailored to your big goals. Book a free chat with the Mortgage Suite team today to see how much you could be saving. It’s time to stop feeling stuck and start feeling supported.

Frequently Asked Questions

How much does it cost to refinance a mortgage in NZ?

To refinance mortgage nz, you’ll need to factor in three main costs: legal fees, valuation fees, and potential break fees. Lawyers typically charge between $800 and $1,600 to update your property title. A registered valuation usually costs between $700 and $1,200, though many lenders now accept digital estimates. Break fees vary based on your interest rate and remaining term. Often, a new bank’s cash-back offer covers these expenses entirely, making the switch cost-neutral for many.

Can I refinance if I have a low deposit or low equity?

Yes, you can still refinance with low equity, though your options at mainstream banks might be limited. The Reserve Bank recently proposed easing restrictions, allowing more lending to those with less than a 20% deposit. If a big bank says no, 2nd tier lenders are often more flexible. They look at your overall financial health rather than just a percentage. We help you find a lender that fits your specific equity level without the stress.

How long does the refinancing process actually take?

The entire process typically takes between two and four weeks from your first chat with us to the day the new loan starts. This includes the time needed to gather your documents, get the bank’s approval, and complete the legal paperwork with your lawyer. If you’re in a rush to secure a specific rate, some non-bank lenders can move even faster. Having your payslips and bank statements ready before we start helps speed things up significantly.

Do I need a lawyer to refinance my home loan?

Yes, you must use a lawyer or conveyancer when you move your mortgage to a new lender. They are responsible for the legal heavy lifting, which includes discharging your old mortgage and registering the new one on your property title. They also handle the transfer of funds between the banks on settlement day. While this adds a cost of roughly $800 to $1,600, it’s a legal requirement in New Zealand to ensure the title is correctly updated.

Will I get a cash-back offer if I switch banks in 2026?

Most New Zealand banks are offering competitive cash-back incentives in 2026 to attract new customers. These offers can be as high as 1% of your total loan amount. For a $500,000 mortgage, that’s $5,000 in your pocket. This cash is usually paid out on the day your new loan starts and is designed to help cover your legal and valuation costs. Just remember that most banks have a three to four-year stay period to keep it.

Can I refinance my mortgage if I am self-employed?

Absolutely. While big banks often demand two years of perfect financial records, many other lenders are happy to work with self-employed Kiwis. To refinance mortgage nz when you work for yourself, we focus on showing your real life income through recent bank statements and GST returns. If you don’t fit the rigid big-bank boxes, we’ll look at flexible 2nd tier options that value your business success and provide the funding you need.

What is the difference between refixing and refinancing?

Refixing is simply choosing a new interest rate with your current bank when your fixed term ends. It’s quick but doesn’t offer the benefits of a fresh start. Refinancing means moving your entire home loan to a different lender. This allows you to negotiate for a better rate, snag a cash-back offer, and change your loan features. It requires more effort and legal work, but the long-term interest savings are often much larger than staying put.

Is it a good idea to consolidate my debt into my mortgage?

Consolidating high-interest debts like credit cards or car loans into your mortgage can be a brilliant move to lower your monthly payments. You’ll drop from interest rates of 12% or 20% down to the current average home loan rate of around 5.89%. However, it’s vital to pay off that extra debt quickly rather than dragging it out for 25 years. We’ll help you structure your loan into separate slices to ensure you’re actually saving money.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Can Permanent Residents Get a Mortgage in NZ? Your 2026 Guide

What if the only thing standing between you and your first New Zealand home isn’t your savings, but a simple misunderstanding of your visa status? We know how stressful it feels to have your deposit ready while worrying that a lender might decline you just because of your residency category. One of the most common questions we’re asked is, can permanent residents get a mortgage in nz? The short answer is a resounding yes, but the path to approval depends on proving your life is firmly planted here.

You’ve worked hard to build a future in Aotearoa, and you deserve a clear way forward. This guide will show you exactly how to secure a home loan as a permanent resident, including the latest 2026 deposit rules and how to pass the “ordinarily resident” test. We’ll explain why you might qualify for a 5% deposit under current schemes and how to manage overseas funds under the latest AML rules. Whether you’re facing a flat market or a cautious bank, we’ll outline the steps to get your keys, even if the mainstream lenders haven’t been helpful.

Key Takeaways

  • Confirm your legal right to buy property and understand the “ordinarily resident” test that lenders use to assess your application.
  • Discover if you qualify for a low 5% deposit and find out how the answer to “can permanent residents get a mortgage in nz” changes based on how long you’ve lived here.
  • Learn why passing your work probation period is a critical milestone for bank approval and how your employment history impacts your borrowing power.
  • Get a clear checklist for using overseas savings so you can meet the latest anti-money laundering requirements without any unexpected delays.
  • Master the “KiwiSaver Catch” by confirming you’ve met the three-year membership rule before you start making offers on houses.

Yes, You Can Get a Mortgage as a Permanent Resident

You’ve done the hard work of settling in Aotearoa, and now you’re looking for a place to call your own. The great news is that yes, you can. Under the law, permanent residents have the same rights to buy property as citizens. However, while the government says you’re allowed to buy, the real question is often: can permanent residents get a mortgage in nz as easily as everyone else? The answer depends on how well you meet the banks’ specific criteria for stability and residency.

The legal framework governing this is the Overseas Investment Act. Historically, this act put up barriers for non-citizens, but as of 2026, we’ve seen updates that make the process smoother, especially for those on newer investor visa categories. These changes signal a more open market, reflecting the evolving landscape of Housing in New Zealand. Even with these legal paths open, you still need to bridge the gap between having permission to buy and getting a bank to lend you the money. Banks are in the business of managing risk, and they use your residency status as a key indicator of how likely you are to stay in the country long-term.

The “Ordinarily Resident” Rule Explained

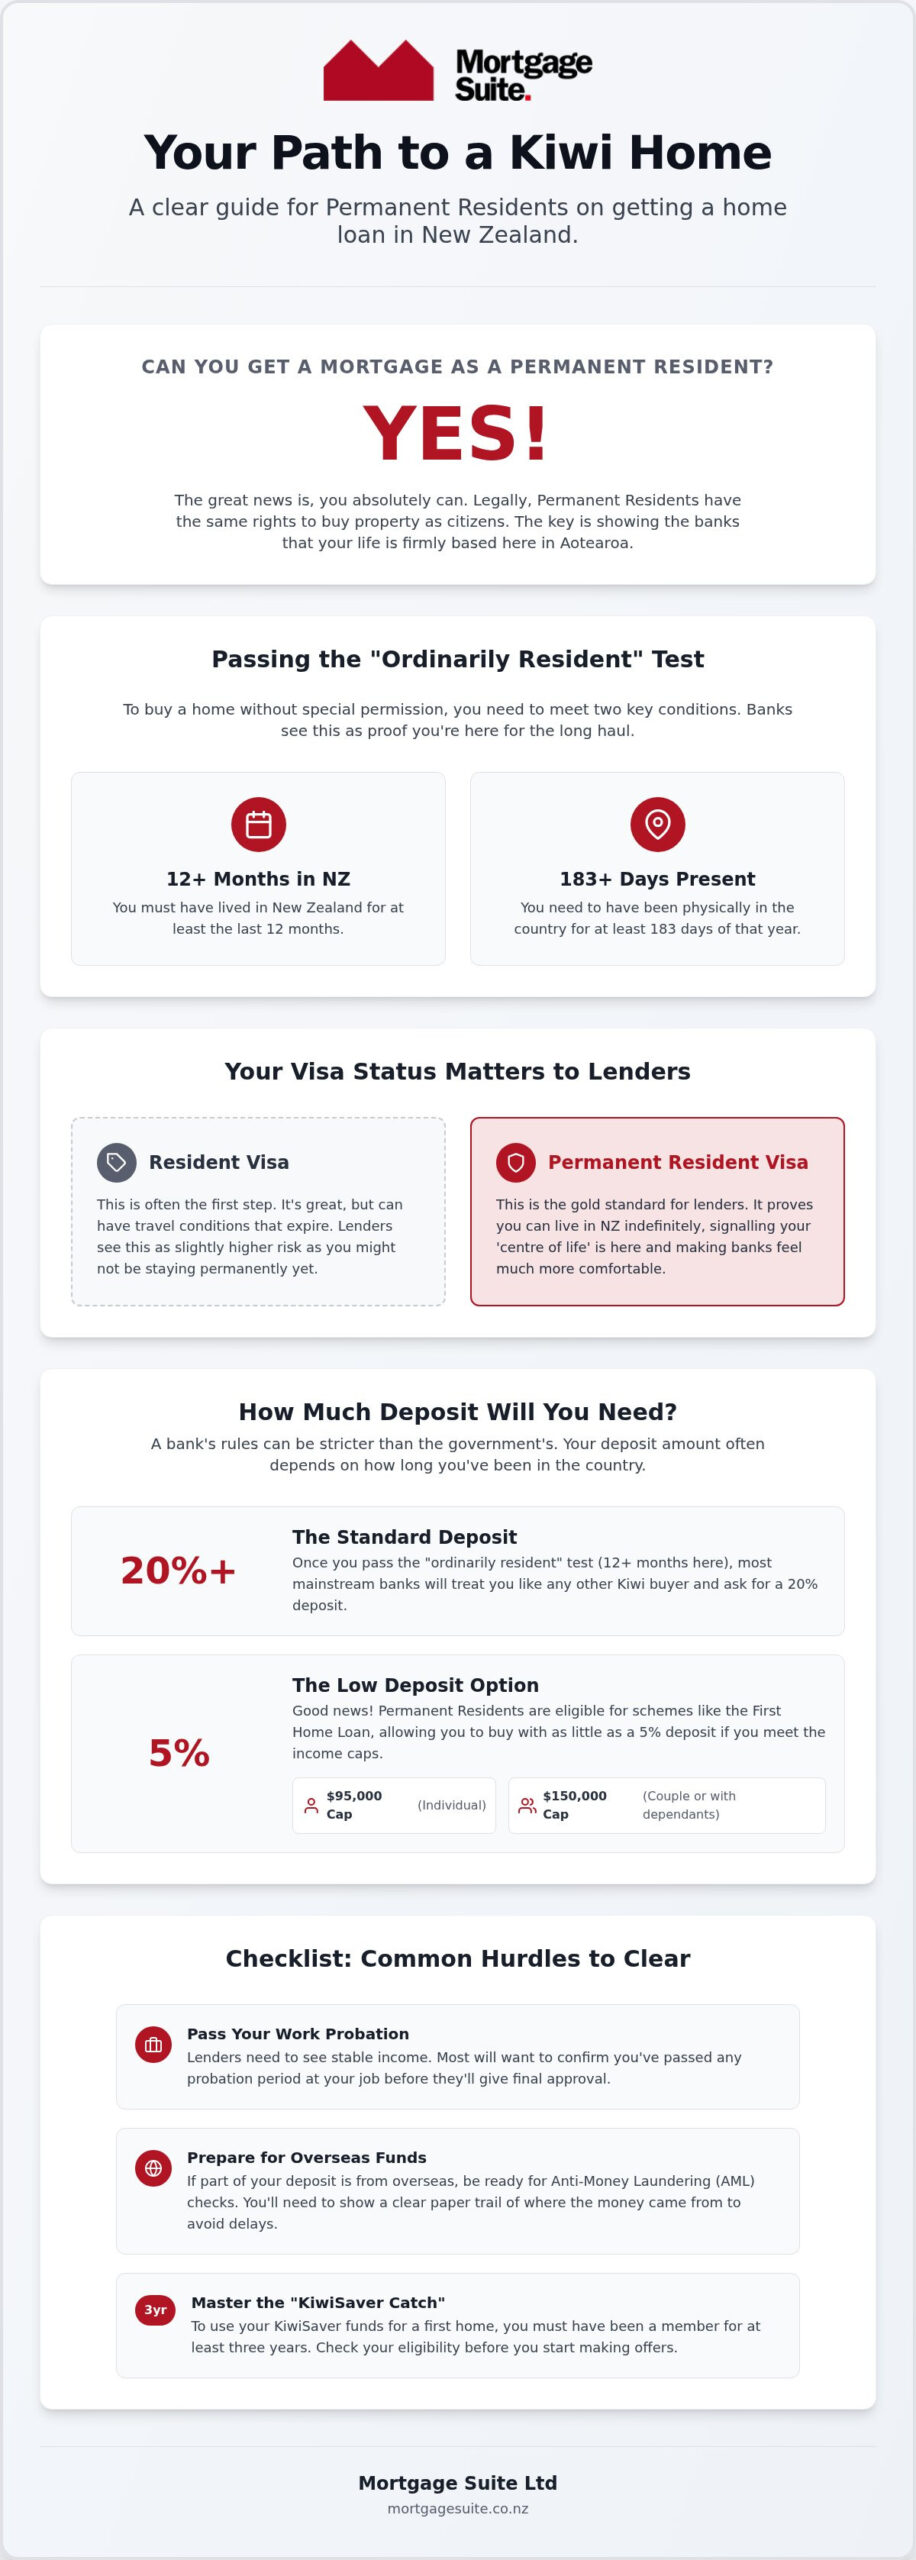
To buy a home without seeking special government permission, you need to be “ordinarily resident.” This means you’ve lived in the country for at least the last 12 months and have been physically present here for at least 183 days during that time. Banks love the 12-month mark because it proves you’re here for the long haul. If you’ve been here for less than a year, you might find mainstream banks a bit hesitant, often asking for a much larger deposit. In those cases, looking at 2nd tier lenders who understand the migrant journey is often the best path forward.

Resident Visa vs. Permanent Resident Visa

There’s a subtle but vital difference between a Resident Visa and a Permanent Resident Visa. Most people start on a Resident Visa, which usually has travel conditions that expire after two years. A Permanent Resident Visa is the “gold standard” for lenders because it allows you to stay indefinitely with no strings attached. While you can still get a mortgage on a standard Resident Visa, having that “Permanent” status makes banks feel much more relaxed. It tells them your centre of life is here, reducing their perceived risk and potentially opening up better interest rates.

Bank Rules vs. Government Rules: The Deposit Gap

It’s a common frustration. You’ve checked the official government rules and confirmed that your visa status allows you to buy property without a hitch. But when you walk into a local bank branch, you’re suddenly told you need a 35% or 40% deposit. This happens because there’s a significant difference between your legal right to own a home and a bank’s internal credit policy. While the law might see you as a resident, a bank might still view you as a “new arrival” until you’ve proven your roots are deep enough.

When asking can permanent residents get a mortgage in nz with a standard 20% deposit, the answer often hinges on the “centre of life” test. Lenders want to see that you aren’t just here for a short stint. They look at whether your family is here, if your children are enrolled in local schools, and how long you’ve been paying tax in the country. If you can show this stability, you’re much more likely to be treated like a citizen, opening the door to much lower deposit requirements.

Why Some Banks Ask for a 20% Deposit

Mainstream banks are naturally cautious. Their biggest fear is “flight risk,” the idea that a borrower might leave the country and stop making payments. If your visa has an expiry date, many lenders will try to match your loan term to that date, which makes the monthly repayments impossible. Even with a Permanent Resident visa, if you haven’t been here for the full 12 months required to be “ordinarily resident,” banks often stick to a strict 20% minimum to hedge their bets. However, we’ve seen cases where these rules are waived if your career is in a high-demand industry or you have a significant history of local savings.

Low Deposit Options for Permanent Residents

The good news is that you don’t always need a massive pile of cash. If you meet the income caps, which as of July 2026 are $95,000 for individuals without dependants or $150,000 for couples and those with dependants, you may be eligible for a First Home Loan. This scheme allows you to buy with just a 5% deposit, and permanent residents are absolutely eligible. You can find more details on these schemes in our first home buyer guide New Zealand. If the big banks are still saying no, we often look at 2nd tier lenders who have more flexible policies for those who are still building their local credit history. If you’re feeling stuck, getting professional advice can help you find a lender that sees your potential rather than just your visa date.

Proving Your Stability: Income and Employment

Once you’ve confirmed your legal standing, the next big hurdle isn’t about your visa. It’s about your paycheck. When banks ask can permanent residents get a mortgage in nz, they’re looking for proof that your income is as permanent as your residency. Your job title and the industry you work in carry a lot of weight. If you’re in a high-demand field like healthcare or IT, lenders often feel more confident about your future earning potential. However, if you’ve recently switched careers or started a new role, you might run into a few speed bumps.

Another vital piece of the puzzle is your local credit history. Even if you had a perfect credit score back home, you’re essentially starting from scratch here. Banks want to see a clean NZ credit profile. A simple way to start is by having a utility bill or a phone contract in your name and ensuring every payment is made on time. This helps build a “paper trail” of reliability that makes you look much better on paper. For a broader look at the steps involved, the government’s guide to buying property provides an excellent starting point for new arrivals.

The 90-Day Trial and Your Mortgage

Most mainstream banks have a strict rule about trial periods. If you’re currently on a 90-day trial or a probation period, they’ll usually ask you to wait until that period is over before they’ll approve a loan. They want to know your job is secure. If you’ve just moved to a new role in the same industry, we can sometimes argue for an exception by showing “continuous employment” proof from your previous country. It’s all about telling a story of stability that makes the bank feel safe.

Self-Employed Residents

If you’ve started your own business as a permanent resident, things get a bit more complex. Standard banks typically want to see at least two years of full New Zealand tax returns to prove your income is steady. This can be a massive roadblock for talented people who have just gone out on their own. We specialise in helping self-employed residents prove their “fair dinkum” income through other means, such as GST returns or bank statements. If the big banks aren’t willing to look at your current situation, exploring a 2nd tier lender New Zealand can often provide the flexibility you need to get into your home sooner.

Can Permanent Residents Get a Mortgage in NZ? Your 2026 Guide

Common Hurdles: KiwiSaver, AML, and Overseas Funds

Even when your income is steady and your visa is sorted, the actual cash you’re using for a deposit can trigger a fresh set of questions from lenders. When people ask can permanent residents get a mortgage in nz, they often forget that where the money comes from is just as important as how much you have. Banks and lawyers are now under strict rules to verify the source of every dollar. As of July 1, 2026, the Department of Internal Affairs has become the sole supervisor for these checks, making the process more centralised but also very thorough. You’ll need to show a clear path for your savings, especially if they’ve travelled across borders.

If your family back home is helping you out, you’ll need more than just a bank transfer. Lenders require a “gifting letter” to confirm the money isn’t a loan that needs to be repaid. This protects your ability to service your mortgage without extra debt hiding in the background. You should also keep the Bright-line property rule in mind. While it usually affects investors, it’s a good idea to talk to a professional about tax implications if there’s any chance you might sell the property within a few years of buying it.

Using Overseas Savings for Your Deposit

Proving the “origin of wealth” is a major part of the modern home-buying journey. You’ll need to provide bank statements from your overseas accounts, and potentially tax returns or sale agreements if the money came from selling a property abroad. It’s wise to move your funds into a New Zealand bank account as early as possible. This doesn’t just help with the paperwork; it also protects you from sudden exchange rate shifts that could shrink your home loan deposit right before you make an offer.

KiwiSaver for New Residents

KiwiSaver is a fantastic tool, but it has a specific “three-year rule.” You must be a member for at least three years before you can withdraw funds for your first home. If you’ve only been a resident for a year, you won’t be able to tap into those savings yet. The workaround is to focus on building your deposit through other savings or gifted funds while your KiwiSaver matures in the background. For those who have hit the three-year mark, you might also be eligible for the First Home Grant in 2026, provided you meet the latest income and residency criteria. If you’re unsure how to piece your deposit together, let’s chat about your options and find a path that works for your timeline.

How to Get Your NZ Home Loan Sorted

So, you’re ready to make your move. While the question of can permanent residents get a mortgage in nz has a clear ‘yes’, the actual process involves a bit of legwork to ensure you get the best deal. It isn’t just about showing a deposit; it’s about presenting a bulletproof case to the bank that shows you are here to stay. Following a structured plan will save you from the heartache of having an offer rejected because your residency paperwork wasn’t quite what the lender expected. To get started, follow these four essential steps:

  • Step 1: Check your residency clock. Confirm you meet the “ordinarily resident” test of 12 months in the country and 183 days present. This is the baseline for most standard bank offers.
  • Step 2: Secure a pre-approval. Don’t go house hunting and fall in love with a property before you know exactly what a lender will give you. A pre-approval gives you the confidence to bid when the right place pops up.
  • Step 3: Build your “centre of life” file. Gather local utility bills, set up your New Zealand bank accounts, and ensure your employment contract is finalised. These small details prove your commitment to Aotearoa.
  • Step 4: Partner with a specialist. Talk to a broker who understands the migrant journey and has access to loans that do not fit bank criteria.

Why a Mortgage Broker is Essential for PRs

Mainstream banks often have rigid, “one size fits all” checklists that don’t always account for the nuances of moving to a new country. We know which banks are migrant-friendly and which ones will put your application in the “too hard” basket. Our job is to package your application so it highlights your stability and career success rather than just your visa date. If you haven’t hit that 12-month residency mark yet, we can look at non-bank lenders who are more flexible with new arrivals, ensuring you don’t have to wait another year to start your life here.

Your Next Steps to Home Ownership

Getting your documents in order early is the best way to avoid stress later on. You’ll need your passport, your visa details, and at least six months of bank statements to show your saving habits. It’s also a good idea to keep an eye on the latest mortgage rates NZ for 2026 so you can factor the current interest environment into your budget. If you’re feeling overwhelmed by the rules or just want a straight-up assessment of your situation, book a chat with Krish Krishna. We’ll give you a clear path to approval and help you navigate the system with confidence.

Take the Next Step Toward Your New Zealand Home

Owning a home in Aotearoa is a milestone that’s well within your reach. We’ve explored how your status as a permanent resident gives you the legal right to buy, and why proving your “centre of life” through stable employment and local credit history is the key to unlocking bank approval. Whether you’re navigating the three-year KiwiSaver rule or organising a paper trail for overseas savings, the process is much smoother when you have an expert in your corner. If you’ve been asking can permanent residents get a mortgage in nz, you now have the clear roadmap you need to move forward with certainty.

At Mortgage Suite, we bring over 20 years of expert banking experience to your application. We specialise in 2nd tier and alternative lending, which means we can often find a path to approval even when the big banks say no. You’ll receive personalised service directly from our founder, Krish Krishna, who understands the unique challenges of the migrant journey. Talk to Mortgage Suite about your PR home loan today and let’s turn your residency into a permanent home. We’re here to make the complex simple and help you get those keys sooner than you think.

Frequently Asked Questions

Do I need to be a New Zealand citizen to buy a house?

No, you don’t need to be a citizen to buy property here. Permanent residents have the same legal rights to purchase a home as New Zealand citizens. The main thing to remember is that you must meet the “ordinarily resident” test to buy without restrictions. This involves living in the country for the preceding 12 months and being physically present for at least 183 days during that period.

Can I get a mortgage with only 12 months on my resident visa?

Yes, you can definitely secure a home loan once you’ve hit the 12-month mark. This one-year milestone is often the “magic number” for mainstream banks. It’s the point where lenders stop viewing you as a temporary arrival and start feeling confident that your life is firmly centred in New Zealand. Reaching this stage often makes the application process much smoother and more predictable.

What is the minimum deposit for a permanent resident in NZ?

You can potentially buy a home with as little as a 5% deposit through the First Home Loan scheme if you meet the 2026 income caps. While many banks prefer a 20% deposit for standard applications, the answer to can permanent residents get a mortgage in nz with less often depends on your specific visa and how long you’ve been working in your current industry.

Can I use my overseas income to qualify for an NZ mortgage?

Most New Zealand banks prefer to see income earned locally in New Zealand dollars. While it’s possible for some lenders to consider overseas earnings if you’re a high-net-worth individual, the majority of standard home loans are based on your NZ salary. Lenders want to be certain you can comfortably afford your repayments using the money landing in your local bank account every fortnight.

Does the Overseas Investment Act (OIA) affect permanent residents?

Yes, the Act sets the rules, but it actually protects your right to buy if you’re a permanent resident. If you meet the “ordinarily resident” criteria, you’re generally exempt from the restrictions that prevent non-residents from purchasing sensitive land or existing homes. The 2026 updates have further clarified these rules, making it easier for residents to understand their path to home ownership without needing special government consent.

What happens if a mainstream bank declines my resident mortgage application?

You still have plenty of options if a big bank says no. We specialise in 2nd tier and alternative loans for residents who don’t quite fit the standard “box” due to their time in the country or self-employment status. These lenders often take a more common-sense approach to your application, looking at your overall stability and career history rather than just following a rigid checklist.

How long does the mortgage pre-approval process take for residents?

You should allow roughly five to ten working days for a pre-approval to be finalised. Because residency-based applications require extra checks for anti-money laundering and visa verification, the paperwork can be a bit more intensive. It’s a great idea to get this sorted at least two weeks before you start visiting open homes so you can bid with absolute confidence.

Can I buy a house in NZ on a Work Visa?

Buying on a work visa is significantly more difficult than buying as a permanent resident. Under the current law, most work visa holders are restricted from buying existing homes unless they’re purchasing with a partner who is a citizen or PR. Banks are also very cautious about lending to those on temporary visas because they need to be sure you’ll be staying in the country long-term.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Low Doc Home Loans NZ: The 2026 Guide for Self-Employed Kiwis

What if the true value of your business wasn’t hidden behind a stack of two-year-old tax returns, but was found in the actual success you’re seeing right now? For many self-employed Kiwis, the dream of owning a home often feels like it’s on hold because mainstream banks refuse to look past rigid, traditional criteria. It’s frustrating to feel like your hard work doesn’t count just because your paperwork looks a bit different. While the market for low doc home loans nz has changed significantly under recent lending laws, the path to approval is still very much open if you know which doors to knock on.

I understand the anxiety that comes with a potential decline, which is why I’ve put together this updated 2026 guide to help you navigate the shift toward “Alt Doc” lending. You’ll discover how to secure a home loan using alternative proof like GST returns or bank statements, allowing you to move forward without waiting on the IRD. We’ll explore the specific documents that actually carry weight today and how to partner with lenders who appreciate business growth. By the end of this article, you’ll have a clear, stress-free strategy to get your application over the line and finally settle into your new home.

Key Takeaways

  • Understand why the shift from “Low Doc” to “Alt Doc” means you can now use alternative proof like GST returns to show your true business income.
  • Learn how to organise your bank statements and trading history to give lenders a clear, honest picture of your business’s success.
  • Discover why 2nd tier lenders often provide the flexibility you need, even if you only have a 20% deposit or a shorter trading history.
  • See how an expert broker acts as your advocate, packaging your application for low doc home loans nz to ensure it stands out to the right lenders.
  • Find out how to clear common hurdles like credit blips or a short time in business so you can move forward with confidence.

What is a Low Doc Home Loan in New Zealand Today?

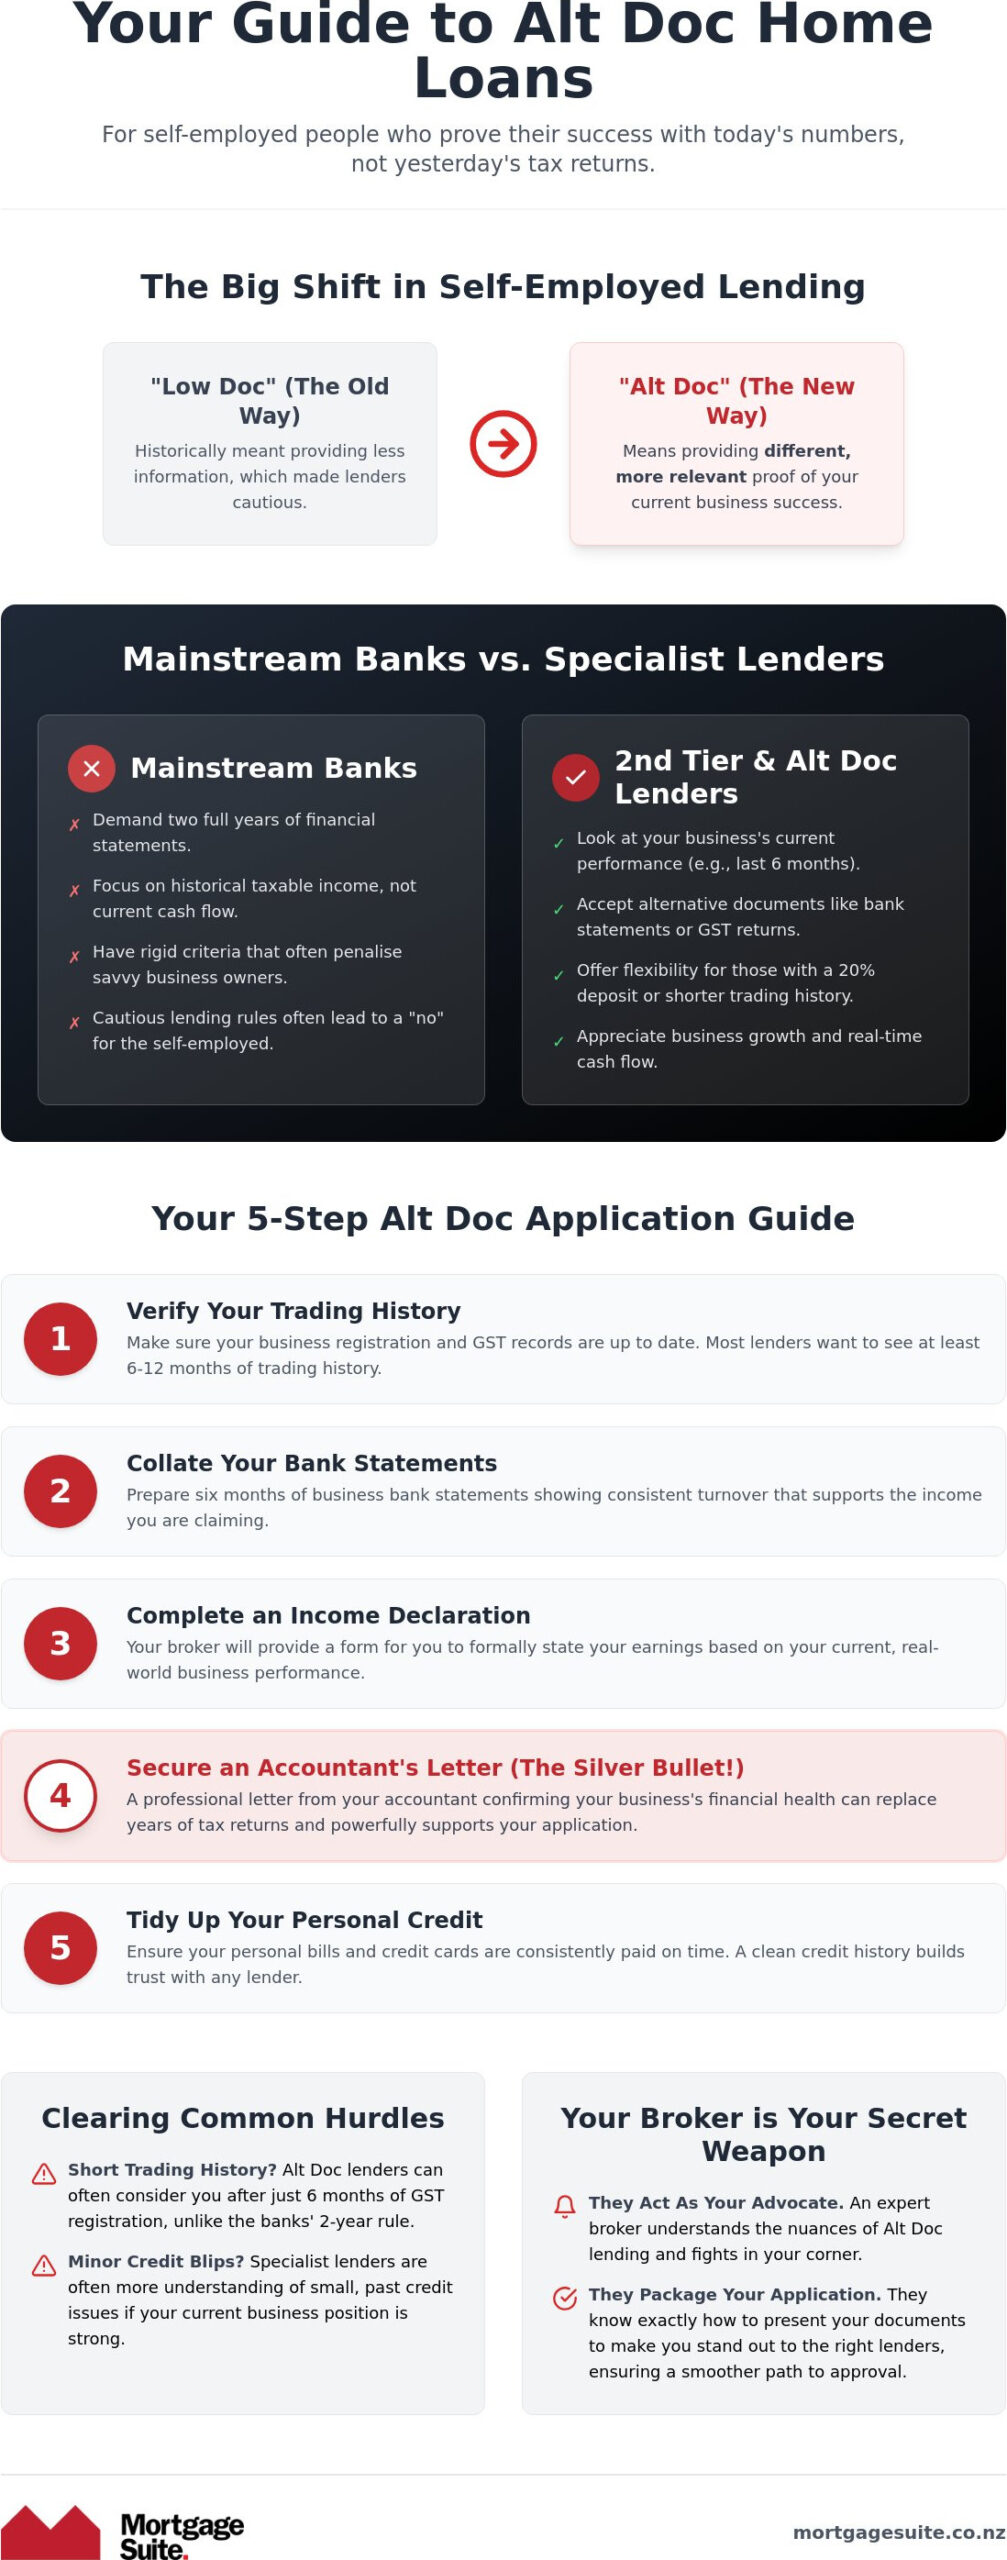
When you’re running your own show, your finances don’t always fit into a neat little box. A home loan for the self-employed shouldn’t depend on whether you have a perfect set of tax returns from two years ago. In the current market, low doc home loans nz have evolved into what we now call “Alt Doc” or alternative documentation loans. This doesn’t mean you’re providing “less” information; it means you’re providing “different” information that better reflects your current success. It is a way to prove your income using real-time data rather than historical tax records.

Historically, a low-documentation loan (low-doc) might have carried a different reputation, but in 2026, it’s a legitimate strategy for contractors, freelancers, and small business owners who have been GST registered for at least six months. It’s vital to understand that “low doc” is never “no doc”. Lenders still have a legal duty to ensure you can comfortably handle your repayments. They just use different tools to verify your income, such as your business bank statements or GST filings, to get a clear picture of your actual earnings.

Why traditional banks often say no

Most mainstream banks still cling to the “two-year rule”. They want to see two full years of financial statements and personal tax summaries before they even consider your application. The problem is that many savvy business owners use legal expenses to lower their taxable income. While this is great for your tax bill, it can make you look like you aren’t able to afford the repayments on paper when a bank calculates your borrowing power. Added to this is the impact of the CCCFA, which has forced banks to become incredibly cautious and rigid with their lending criteria, often leaving self-employed Kiwis out in the cold. If you’ve already experienced this firsthand, our guide for those declined by bank home loan NZ lenders explains exactly what your next steps should be.

The rise of Alt Doc lending in 2026

The rise of Alt Doc lending is the biggest change for low doc home loans nz in 2026. This is where 2nd tier lenders have stepped up to fill the gap. Instead of looking at what happened in 2024, these lenders focus on your business’s current cash flow. They prioritise your valid NZBN and active GST status over ancient paperwork. By looking at your last six months of trading, they get a real-time view of your ability to manage a loan. If you want to see how these lenders operate, our 2nd tier lender New Zealand guide provides more detail on how they bridge the gap between rigid bank rules and your reality.

How to Prepare Your Alt Doc Application: A 5-Step Guide

Getting your ducks in a row before you talk to a lender is the best way to avoid the stress of a back-and-forth process. While the term low doc home loans nz might suggest a lack of paperwork, the secret to a quick approval is having the right alternative documents ready from the start. Follow these five steps to present a professional, clear case for your business success.

  • Step 1: Verify your trading history. Ensure your NZBN is active and your GST records are up to date. Most lenders want to see you’ve been trading for at least six months to a year.
  • Step 2: Pull your bank statements. You’ll need six months of business bank statements. These should show a consistent turnover that matches the income you’re claiming.
  • Step 3: Complete a declaration form. Your broker will provide a “Self-Employed Declaration of Income”. This is a formal document where you state your earnings based on your current business performance.
  • Step 4: Secure an accountant’s letter. A professional letter from your accountant can be a powerful substitute for traditional tax returns.
  • Step 5: Tidy up your personal credit. Small blips can happen, but ensuring your personal bills and credit cards are paid on time helps build trust with the lender.

The “Accountant’s Letter” advantage

A well-drafted letter from your accountant is often the “silver bullet” for Alt Doc applications. It needs to clearly state that your business is financially healthy, stable, and that you can afford the loan repayments without any struggle. This one page can effectively replace a year’s worth of tax returns because it provides professional validation of your current financial position. When you speak to your accountant, explain your home loan goals so they can focus the letter on your business’s ability to generate steady cash flow. It’s about showing the lender that your business isn’t just surviving, it’s thriving.

Proving income through bank statements

Lenders look at your business account to see the “rhythm” of your money. They want to see regular deposits that prove your turnover is stable. One common concern is large, one-off expenses, like buying a new van or a specialised piece of equipment. Don’t worry about these; we can often treat these as “add-backs”. This means we explain to the lender that these were one-time costs or non-cash expenses like depreciation, which shouldn’t count against your ability to pay a mortgage. If you’re unsure how your statements look, talking to the team at Mortgage Suite Ltd early on can help you identify and explain any potential red flags before the lender ever sees them.

Mainstream Banks vs. 2nd Tier Lenders: Comparing Your Options

Choosing between a big bank and a 2nd tier lender isn’t just about comparing interest rates; it’s about finding a partner who actually wants to hear your business’s story. Mainstream banks often rely on rigid, computer-based systems that look for reasons to say no if your tax returns don’t meet their exact standards. In contrast, 2nd tier lenders are built for the complex reality of running a business. While you’ll generally need a 20% deposit for low doc home loans nz, the flexibility you gain is often the key to getting your house keys sooner rather than later.

The trade-off for this flexibility is usually a slightly higher interest rate. However, it’s vital to look at the bigger picture. Non-bank lenders often move much faster than the “big four” banks, with some approvals coming through in a matter of days. When you’re trying to secure a property in a competitive market, that speed is a massive advantage. You aren’t just paying for a loan; you’re paying for the ability to act quickly and bypass the bureaucracy that stalls so many other buyers.

Think of an alternative loan as a bridge. It’s a stepping stone that gets you into the property market today. Once you’ve built up some equity and have those two years of financial statements the big banks crave, we can look at refinancing you back to a mainstream lender at a lower rate. This strategy prevents you from being locked out of the market while property prices continue to climb. It’s about getting the house now and fixing the rate later down the track.

When the bank says no, who says yes?

This is where the world of non-bank lenders in NZ truly shines. These institutions use a human-led loan assessment, which means a real person looks at your application instead of a computer simply rejecting it. They are far more comfortable with diverse income streams and business “add-backs”. For example, if your profit looks low because you claimed significant depreciation or had a one-off equipment purchase, a 2nd tier lender will often count those amounts back into your income, giving you a much higher borrowing capacity.

Understanding the costs involved

It’s important to be clear about the costs from the start. Alternative loans sometimes come with an establishment fee that you wouldn’t typically see at a mainstream bank. You need to weigh this cost against the “cost of waiting”. If property prices rise significantly while you’re waiting a year to get your tax returns ready, that delay could cost you far more than a one-off fee. Working with a broker ensures you find the most competitive non-bank rate available, making sure the path to your new home is as affordable as possible.

Low Doc Home Loans NZ: The 2026 Guide for Self-Employed Kiwis

Common Hurdles for Self-Employed Borrowers (and How to Clear Them)

The journey to home ownership for a business owner often feels like an uphill battle against a system designed for employees. Even when your business is thriving, you might face obstacles that make a standard bank manager shake their head. Whether it’s a “messy” financial year or a lack of recent tax records, these challenges are common. The good news is that low doc home loans nz are specifically designed to clear these hurdles. By focusing on your current success rather than past setbacks, we can find a path forward that values your business’s potential.

One of the biggest roadblocks is a short trading history. While mainstream banks usually demand two full years of profitable tax returns, many alternative lenders are happy to consider your application if you’ve been in business for just six to twelve months. Another frequent concern is a rough patch in your business’s past. If an unexpected bill or a slow season caused a dip in your credit score, non-conforming home loans can provide a lifeline. These products are tailored for Kiwis who don’t fit the “perfect” borrower profile but have a solid plan to move forward.

Presenting your income correctly is also vital. You might pay yourself a mix of dividends and a small salary to be tax efficient. A bank might only look at the salary, but a specialist lender will look at the total business profit available to you. If you’re struggling with a deposit, remember that you can often use equity in other assets or even a gift from family to reach that 20% mark required for most Alt Doc products.

What if my tax returns aren’t filed yet?

It’s a common story; your business is flying, but your accountant hasn’t quite finished last year’s books. This isn’t the deal-breaker it used to be. We can use your latest GST returns as interim proof of income to show how your business is performing right now. Combined with management accounts from your software, like Xero or MYOB, we can tell a compelling story of your current financial health. Being behind on paperwork is a hurdle we can jump by using real-time data to prove you can afford the repayments.

The importance of a clean credit file

Small business owners often have “busy” credit files because they’re frequently applying for trade credit or equipment finance. This can sometimes look like a red flag to a computer, but a human lender understands the context. Before you apply, it’s a good idea to “polish” your file by ensuring all personal utilities and credit cards are paid on time. If there is a mark on your record, don’t panic. Often, a simple explanation of what happened and how you’ve fixed it is all a specialist lender needs to hear. If you’re ready to see how your business stacks up, you can explore your home loan options with us today.

Why a Mortgage Broker is Your Secret Weapon for Low Doc Loans

Applying for low doc home loans nz directly with a mainstream bank is often a recipe for disappointment. Banks rely on rigid systems that aren’t built to understand the ebbs and flows of business income. When you walk into a branch, you’re often met with a “computer says no” outcome simply because your tax returns aren’t current. This is where a broker becomes your most valuable asset. We don’t just pass on your documents; we act as your advocate, translating your business success into a language that lenders understand and respect.

Our role is to package your application so it highlights your strengths rather than your paperwork gaps. We know which 2nd tier lenders are “hungry” for new business and which ones are currently offering the most flexible terms for your specific industry. By having a seasoned negotiator in your corner, you avoid the stress of multiple declines and protect your credit file from unnecessary enquiries. We use our 20 plus years of industry experience to navigate the hurdles we’ve discussed, ensuring your application lands on the desk of a human underwriter who can see the real value in your business.

A personal approach to complex finance

Krish Krishna has spent over two decades helping Kiwis navigate the complexities of the lending market. At Mortgage Suite Ltd, we believe in a partnership that lasts well beyond your initial settlement. We don’t just get you a loan and walk away; we help you build a long-term strategy. As we mentioned earlier, an Alt Doc loan is often a stepping stone. We’ll work with you over the coming years to monitor your business growth and identify the perfect moment to refinance you back to a mainstream bank once you have the traditional records they require.

Getting started with Mortgage Suite Ltd

We know that the thought of hunting down bank statements and GST records can feel overwhelming when you’re already busy running a business. Our goal is to take that weight off your shoulders. It all starts with a relaxed, no-obligation chat to see where you stand and what your goals are. We’ll give you a clear, honest assessment of your options and handle the heavy lifting of the application process for you. Ready to talk about your self-employed home loan? Get in touch with Mortgage Suite Ltd today.

Take the First Step Toward Your New Home Today

Running a business is a significant achievement, and it shouldn’t be the reason you’re locked out of the property market. We’ve seen how the shift toward alternative documentation means you can use real-time proof, like your GST returns and bank statements, to show lenders you’re a safe bet. Securing low doc home loans nz in 2026 isn’t about having less proof; it’s about using the right proof to tell your story. Whether you’re dealing with a short trading history or complex income streams, there’s almost always a path forward when you have the right advocate in your corner.

At Mortgage Suite Ltd, we bring over 20 years of banking and brokerage experience to the table. We specialise in 2nd tier and non-bank lending, providing tailored solutions for complex self-employed income that mainstream banks often overlook. You don’t have to navigate this paperwork hunt alone. We’re here to help you bridge the gap between your business success and your home ownership goals. Book a free consultation with our self-employed loan experts and let’s get your application moving. You’ve done the hard work of building your business; now let us do the hard work of securing your home.

Frequently Asked Questions

Can I get a low doc loan with only a 10% deposit in NZ?

The short answer is usually no. Most lenders providing low doc home loans nz require at least a 20% deposit because they are taking on more risk by not seeing your full tax returns. While some mainstream bank loans allow for a 10% deposit, those almost always require two years of perfect financial statements, which is exactly what Alt Doc products help you avoid.

Do low doc home loans have higher interest rates?

Yes, you’ll generally find that interest rates are slightly higher than standard bank rates. For example, as of July 2026, some specialist floating rates start around 7.65% p.a., while prime Alt Doc options might start closer to 5.64% p.a. You’re essentially paying a small premium for the flexibility and speed that a non-bank lender provides when your paperwork isn’t ready for a traditional bank.

How long do I need to be self-employed before I can apply for an alt doc loan?

You typically need to have been trading and GST registered for at least six months. While traditional banks almost always demand a two-year history, many 2nd tier lenders are happy to look at your business once you’ve crossed that six-month mark. They’ll use your interim GST returns and bank statements to prove that your business is stable and growing.

Is a low doc loan the same as a bad credit loan?

No, they are two different things. A low doc loan is for business owners with a strong income who simply don’t have up-to-date tax returns. A bad credit, or non-conforming loan, is designed for people who have had defaults or missed payments in the past. It’s possible to have a loan that is both Alt Doc and non-conforming, but they solve two different problems for the borrower.

What documents replace a tax return in a low doc application?

Lenders usually look for three main things: six months of business bank statements, your most recent GST returns, and a signed declaration of your income. An accountant’s letter confirming your business is profitable and solvent is also a very powerful document that can speed up your approval. These pieces of evidence give the lender a real-time view of your actual cash flow.

Can I use a low doc loan to buy an investment property?

Yes, you can certainly use these loans for residential investment properties. The main difference is that the deposit requirements might be slightly higher than for a home you plan to live in. While 20% is standard for owner-occupiers, some lenders might ask for a 25% deposit for an investment property to offset the extra risk.

Will a low doc loan allow me to refinance later?

Refinancing is actually the goal for most of our self-employed clients. You can use an Alt Doc loan to get into your home now, and then once you have two years of clean tax returns, we can look at moving you to a mainstream bank. This “stepping stone” strategy allows you to stop paying rent and start building equity while you get your long-term paperwork in order.

Do I need an accountant to get a low doc home loan?

While it isn’t always a strict legal requirement, having an accountant makes the process much smoother. Many 2nd tier lenders will ask for an “Accountant’s Letter” to verify your earnings. If you don’t have an accountant, we can still work with your bank statements and GST filings, but a professional letter often provides the extra level of trust that secures a faster approval.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt to Income Ratio NZ: What the 2026 DTI Rules Mean for Your Mortgage

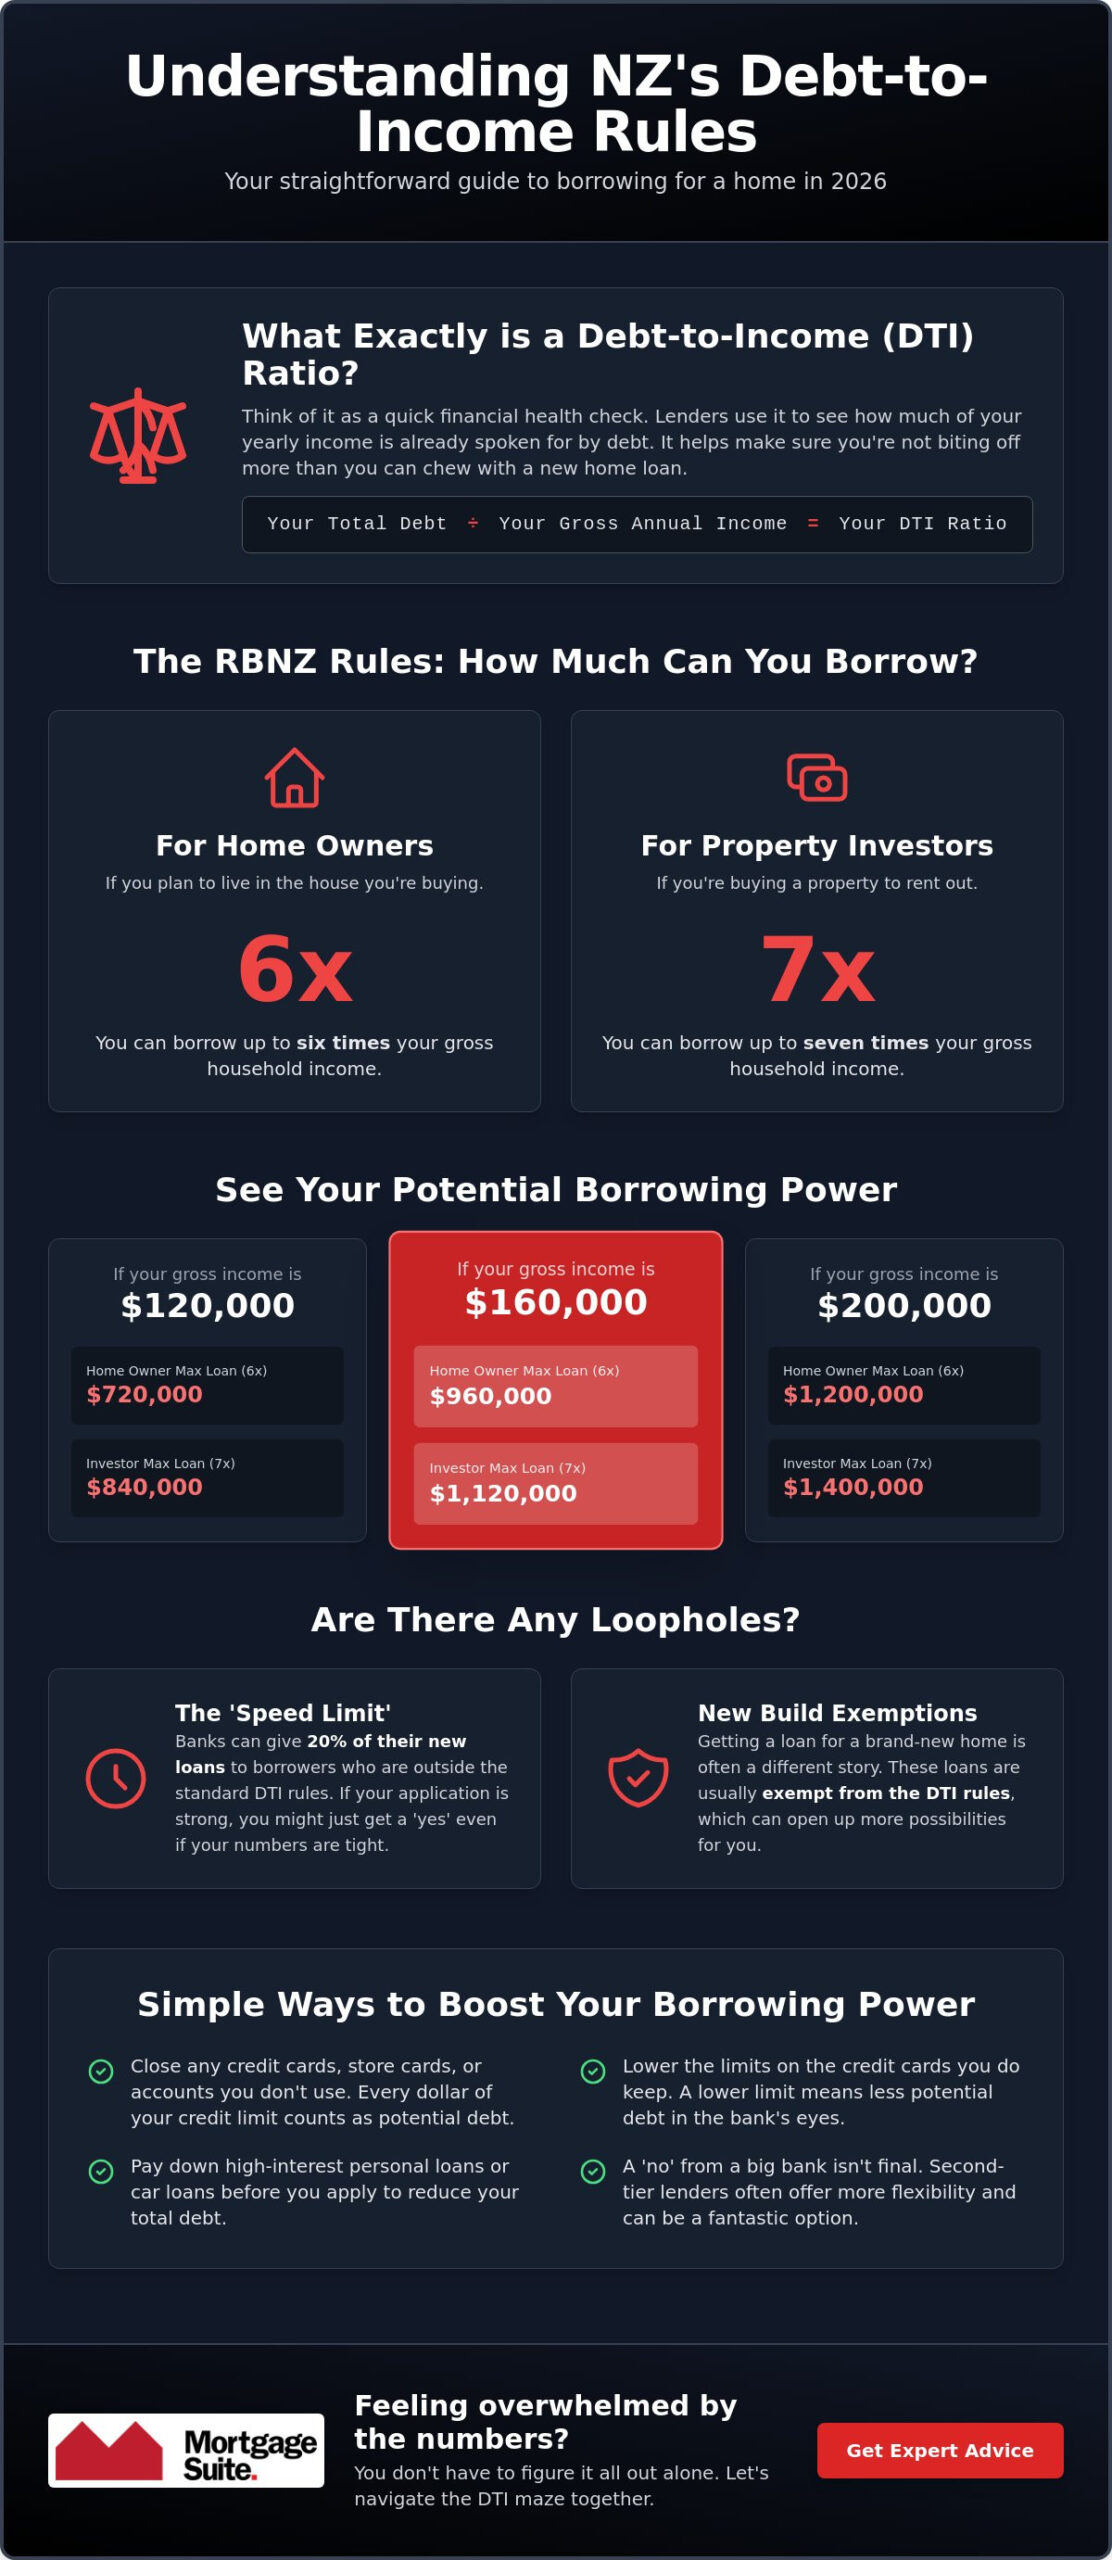
What if the size of your deposit isn’t actually the biggest hurdle to your next home loan anymore? It often feels like every time you get close to the finish line, the Reserve Bank shifts the goalposts; you’ve saved the deposit and found the house, only to worry that new regulations might stop you in your tracks. Understanding the debt to income ratio nz rules is now just as vital as having a solid credit score, especially as we navigate the 2026 property market.

We know how stressful it is to feel like your financial future is being decided by a complex spreadsheet. That’s why we’re here to clear up the confusion. You’ll learn exactly how these DTI limits affect your borrowing power and how to navigate them to secure your dream home or next investment. We’ll break down the specific maths behind the 6x and 7x thresholds, identify who qualifies for a “speed limit” exemption, and look at the path forward if your current bank says no. Whether you’re a first home buyer or a seasoned investor, there is always a way through the red tape when you have the right plan and a steady hand to guide you.

Key Takeaways

  • Get a clear grip on how the debt to income ratio nz measures what you owe against what you earn, and why it’s now a top priority for lenders.
  • Discover the specific 2026 borrowing limits for owner-occupiers and investors, so you know exactly where you stand before you start house hunting.
  • Learn about the “speed limit” and new build exemptions that could help you secure a loan even if you don’t fit the standard RBNZ box.
  • Find out how simple moves, like closing unused credit cards, can significantly improve your profile and increase your chances of a successful application.
  • Explore why a rejection from a big bank doesn’t have to be the end of the road, especially when looking at 2nd tier options that offer more flexibility.

What is the Debt to Income (DTI) ratio in NZ?

Think of the debt to income ratio nz as a financial health check that lenders use to see if you’re biting off more than you can chew. While we used to focus almost entirely on the size of your deposit, the rules have changed. Now, the banks are looking just as closely at the relationship between what you earn and what you owe. It isn’t just about your mortgage either. Lenders bundle in every bit of debt you have, from that credit card you keep for emergencies to the car loan you took out last year. If you’re curious about the global concept, you can read up on what the debt-to-income ratio is, but in the local context, it’s a strict guardrail designed to keep you and the economy safe.

In 2026, this ratio has become just as vital as your deposit size when you’re applying for a mortgage. It serves as a reality check for both you and the bank, making sure that your lifestyle isn’t entirely consumed by debt repayments. Living with a high ratio can be incredibly stressful, as it leaves very little room for error if your circumstances change. By understanding this number early on, you can take control of your financial story rather than letting the bank’s spreadsheet dictate your future. It’s about ensuring that you don’t end up taking on way too much debt, which can quickly turn the excitement of a new home into a constant worry about making ends meet.

The simple maths behind the ratio

Calculating this number is actually quite straightforward. To find your ratio, divide your total debt by your annual income before tax. For a practical example, let’s say your household brings in $100,000 a year before the taxman takes his share. If you’re looking to take on a $600,000 loan, your DTI would be 6. Banks prefer using your “gross” income, which is just the amount you earn before tax, because it provides a consistent starting point. It gives them a clear, standardised view of your total earning power before other expenses come into play.

Why the Reserve Bank brought these rules in

The Reserve Bank of New Zealand (RBNZ) introduced these limits to keep the housing market stable and prevent people from getting into too much hot water. By capping how much you can borrow relative to your income, they’re trying to stop the market from overheating and prevent people from getting in over their heads with repayments. These rules work alongside the existing Loan-to-Value (LVR) settings, which look at how much deposit you have. While LVR looks at your ownership stake, the DTI rules focus on your ability to actually live your life while paying back the debt. The ultimate goal is to make sure that even if interest rates wiggle or life throws you a surprise, you still have enough cash left over to keep the lights on and the fridge full. It’s about building a bit of a buffer so that a small change in your circumstances doesn’t become a massive financial headache. Understanding how the Reserve Bank sets its benchmark rate is equally important — our guide on OCR meaning and how the Official Cash Rate shapes your mortgage in 2026 explains exactly how these decisions flow through to your repayments.

The RBNZ rules: How much can you borrow in 2026?

The Reserve Bank doesn’t apply a one-size-fits-all approach to lending. Instead, they’ve set different benchmarks based on how you intend to use the property. If you’re looking for a place to call home, the standard debt to income ratio nz limit is 6. This means that for every dollar you earn before tax, the bank generally won’t let you borrow more than six dollars in total debt. It sounds strict, but it’s designed to ensure you aren’t stretched too thin when life happens.

For those looking to grow a portfolio, the rules are slightly more flexible. Investors generally have a DTI limit of 7. This extra wiggle room exists because rental income helps service the loan, providing a bit more security for the lender. However, even these limits aren’t set in stone. Banks have what we call “speed limits.” The Reserve Bank allows banks to allocate 20% of their new lending to borrowers who sit outside these standard ratios. If your case is strong, there’s still a chance to secure a “yes” even if the numbers are a bit tight.

Owner-occupier vs Investor limits

The gap between a DTI of 6 and 7 might seem small, but it makes a massive difference to your buying power. If you’re a first home buyer with a small deposit, you’ll likely need to stick closely to that 6x limit unless you qualify for a specific exemption. We’ve put together a quick guide to show how these limits translate into actual loan amounts based on your household income.

Gross Annual Income Max Loan (Owner-Occupier, DTI 6) Max Loan (Investor, DTI 7)
$120,000 $720,000 $840,000
$160,000 $960,000 $1,120,000
$200,000 $1,200,000 $1,400,000

What counts as “Debt” in the eyes of a lender?

This is where many people get caught out. When a bank calculates your ratio, they don’t just look at the mortgage you’re asking for. They include everything. Your student loan, that car finance from last year, and even personal loans are added to the pile. One of the biggest traps is credit card limits. Even if you have a zero balance, the bank counts the entire limit as potential debt because you could spend it tomorrow. “Buy Now, Pay Later” commitments are also under the microscope now. These small weekly payments can bloat your ratio and eat into your borrowing power faster than you’d think. If you’re worried about how your current setup looks, it’s a great idea to chat with a professional who can help you tidy things up before you apply.

Exemptions and speed limits: When the rules don’t apply

It’s easy to feel a bit overwhelmed when you hear about new lending restrictions, but here is a bit of a silver lining: the debt to income ratio nz rules aren’t a brick wall for everyone. In fact, the Reserve Bank has deliberately left some doors open to ensure the housing market keeps moving and that people can still get into homes. One of the most important things to realise is that these strict RBNZ regulations primarily apply to registered banks. If you are looking at non-bank lenders or 2nd tier options, you might find a lot more flexibility than you’d get at a traditional high-street branch because they don’t always have to play by the same rigid rulebook.

Specific types of lending are also carved out of the rules to help the country grow. For example, if you are planning to build a new home, you’ll often find that the DTI limits are much more relaxed. The government wants to encourage more housing supply, so they don’t want to penalise people who are adding to the total number of houses in NZ. Similarly, if you are just looking at moving your mortgage to another bank without borrowing any extra cash, you usually won’t have to go through a fresh DTI check. Even those temporary loans to cover the gap between houses, which help you manage the time between selling one place and buying another, are treated as a special case to keep the process as smooth as possible.

First Home Loan exemptions

If you’re just starting out, there is a massive advantage available through Kāinga Ora. Loans supported under the First Home Loan scheme are officially exempt from these DTI restrictions. This is a total game-changer for young Kiwis who might have a smaller deposit or are just starting to climb the career ladder. Because these loans are designed to help people get onto the property ladder, they focus more on your potential and your ability to meet repayments rather than a rigid multiple of your current salary. For a deeper look at how to navigate your first purchase, check out our Home Loans for First Home Buyers in New Zealand: The 2026 Comprehensive Guide.

The “Speed Limit” loophole

Even for standard bank loans, there’s a bit of a safety valve known as the “speed limit.” The Reserve Bank allows banks to give 20% of their new mortgage money to people who sit outside the standard 6x or 7x limits discussed earlier. This is where having a professional in your corner really pays off. A mortgage broker knows how to present your case so you’re seen as a high-quality borrower who deserves to be part of that lucky 20%. Lenders don’t just look at the raw numbers; they look at your overall financial character, your spending habits, and your career path. If you’ve got a clean record and a solid plan, we can often help you find a way through the red tape.

Debt to Income Ratio NZ: What the 2026 DTI Rules Mean for Your Mortgage

How to tidy up your finances before you apply

If you’ve crunched the numbers and your debt to income ratio nz looks a bit higher than you’d like, don’t throw in the towel just yet. We see this all the time. The good news is that your current ratio isn’t a permanent mark; it is just a snapshot of where you are today. With a bit of a tidy-up and some smart moves, you can often shift those numbers into a much better position before you even sit down with a lender. It is all about presenting the cleanest possible version of your financial life to the bank.

One of the most effective ways to lower your ratio is by putting all your small, high-interest debts into one manageable payment. Those little store cards and personal loans might not seem like much on their own, but they add up quickly when a bank is looking at your profile. By combining these, you simplify your outgoings and show that you have a disciplined grip on your money. It is also worth looking at your income from a fresh perspective. Improving your ratio isn’t only about cutting what you owe; it’s also about making sure the bank sees every cent you earn. Once you’ve tidied up your debt profile, you’ll also want to think carefully about your loan structure — understanding whether a fixed rate mortgage or a floating rate suits your situation can make a significant difference to your monthly repayments and overall financial comfort.

The “Credit Card Cleanse”

Lenders don’t just care about what you’ve spent; they care about what you could spend. If you have a credit card with a $10,000 limit sitting in your drawer, the bank treats that as $10,000 of potential debt, even if you haven’t spent a cent. They have to assume you might go out and max it out tomorrow. Dropping that limit or closing the account entirely can give your borrowing power a massive boost. We usually recommend doing this at least three months before you apply. This gives the credit reporting systems plenty of time to update and ensures the bank sees a nice, clean slate when they run their checks.

Boosting your income figure

When we talk about income, we’re looking at more than just your base salary. If you’ve been consistently earning overtime, bonuses, or commissions, we can often work with the bank to include these in your total figure. For those looking to grow their portfolio, the bank will also factor in the potential rental income from the property you’re buying. You can see how these numbers stack up by using our Investment Property Mortgage Calculator NZ. Don’t forget about boarder income either. If you plan to have a flatmate in your new home, many lenders will let us add a portion of that expected rent to your total income, which can make a huge difference to your final ratio. If you’re unsure which debts to tackle first or how to best show off your income, reach out to our team for a bit of a strategy session.

How Mortgage Suite Ltd navigates the DTI maze for you

We reckon that getting a “no” from a main bank is often just the start of the conversation, not the final word. It’s easy to feel like the goalposts have moved permanently when you’re faced with the current debt to income ratio nz rules. However, our job at Mortgage Suite Ltd is to act as your dedicated negotiator, looking past the rigid spreadsheets of institutional banking to find a path that works for your unique situation. We don’t just see a ratio; we see your potential and your hard work.

With over two decades of industry experience, our founder Krish Krishna has seen every market cycle and regulatory shift imaginable. This deep institutional knowledge means we don’t just guess which lenders might say yes. We know exactly how to present your case to the right people. We take the weight off your shoulders by handling the complex discussions with lenders, ensuring your application highlights your financial strengths and addresses any debt concerns head-on. We focus on building a partnership with you, making sure you feel supported rather than just processed by a system.

Beyond the Big Four: The power of 2nd Tier lending

One of the biggest advantages of working with our team is our access to 2nd tier loans. These non-bank lenders are often more flexible because they don’t always have to follow the same RBNZ bank rules that restrict the major players. If your DTI ratio is a bit high for a traditional bank, an alternative lender might be the perfect solution. We often use these loans as a strategic “stepping stone.” They get you into your dream home or investment property now, and as your equity grows or your income increases, we can help you transition back to a traditional mortgage later. We take the time to match your unique profile to the lender that offers the best fit for your long-term goals.

Expert negotiation for complex cases

With 20 years in the game, we know which lenders are currently under their DTI speed limits and are looking for quality borrowers. This isn’t just about filling out forms; it’s about expert packaging. We know how to frame your application to mitigate concerns about existing debt while shining a light on your career trajectory and overall stability. Our goal is to take the anxiety out of the process, giving you the confidence to focus on finding the right property while we handle the red tape. When you partner with Mortgage Suite Ltd, you’re not just getting a loan; you’re getting a steady hand to guide you through a fluctuating market. We’re committed to removing the obstacles that stand between you and your dream home.

Securing your future in a changing market

The 2026 lending landscape might feel more restrictive, but it is certainly not impossible to navigate. While the debt to income ratio nz rules have changed how banks view your borrowing power, you now have a clear roadmap to move forward. By tidying up your existing debts and understanding how to maximise your gross income, you put yourself in the best possible position for a “yes”. Remember, the big banks are only one part of the story; flexibility often lies with alternative lenders who value your overall potential.

With over 20 years of banking and brokerage experience, we specialise in finding those 2nd tier and non-bank solutions that mainstream lenders might miss. We provide national coverage across all of New Zealand, ensuring that no matter where you are looking to buy, you have a steady hand to guide you. If you’re ready to take the next step without the stress of rigid spreadsheets, we’re here to help. Book a chat with our expert team today to see how we can help you beat the DTI blues. Your dream home is still within reach; you just need the right plan to get there.

Common Questions About the 2026 DTI Rules

Does the DTI ratio apply to new builds in 2026?

No, construction loans for new builds are officially exempt from the RBNZ’s DTI restrictions. This is a deliberate move by the government to encourage more housing supply across New Zealand. If you’re building from scratch or buying a home off the plans, you won’t have to worry about the standard 6x or 7x limits. This gives you significantly more flexibility when planning your project and choosing your finishes.

Will my student loan affect my debt to income ratio?

Yes, your student loan is absolutely included when the bank calculates your debt to income ratio nz. Lenders look at your total debt obligations, which includes student loans, car finance, and personal loans. Even though your repayments are automatically deducted from your pay, the total balance still sits on the “debt” side of the ledger. It’s a good idea to factor this in early when working out your borrowing power.

Can I get a mortgage if my DTI is over 6?

Yes, you can still secure a mortgage even if your ratio sits above the standard limit of 6 for owner-occupiers. Banks are allowed a “speed limit” where 20% of their new lending can go to borrowers with higher ratios. Alternatively, we can look at 2nd tier lenders who don’t have to follow these specific Reserve Bank rules. This provides a clear path forward even when a big bank’s spreadsheet says no.

Do non-bank lenders have to follow the RBNZ DTI rules?

No, the Reserve Bank’s DTI restrictions primarily apply to registered banks. Non-bank or 2nd tier lenders often have their own internal criteria and aren’t bound by the same 6x or 7x caps. This makes them an excellent option if your income doesn’t quite stretch far enough for a traditional bank’s requirements but you have a solid plan and the ability to manage your repayments comfortably.

How is rental income counted towards my DTI ratio?

Rental income is added to your total gross annual income, though banks usually “shade” it by about 20% to account for vacancies and maintenance costs. This boosted income figure is what allows investors to have a higher debt to income ratio nz limit of 7. It’s a vital part of the calculation that helps reflect the true servicing power of an investment property and your ability to grow a portfolio.

What is the difference between DTI and LVR?

While they work together, they measure two different things. LVR (Loan-to-Value Ratio) looks at the size of your deposit compared to the property’s value. DTI (Debt-to-Income) looks at your total debt compared to what you earn before tax. Think of LVR as your “entry ticket” to get the loan and DTI as the bank’s way of checking you have enough left over each month to live your life.

Can I use boarder income to improve my DTI ratio?

Yes, many lenders will let us include a portion of your expected boarder income to boost your total earnings figure. This can be a real lifesaver for first home buyers trying to stay under the 6x limit. We’ll just need to show the bank that the property has enough space and that the income is realistic for your area. It’s a simple way to make the numbers work in your favour.

What happens to my DTI if interest rates go up?

Your actual DTI ratio won’t change just because interest rates move, as it’s based on the total debt amount rather than the interest cost. However, the bank’s “test rates” usually get tougher when market rates rise. This means that while you might technically fit the DTI box, the bank will look even closer at your ability to manage higher weekly repayments. Choosing the right loan structure — for example, deciding between a fixed rate mortgage versus a floating rate — becomes especially important in this environment, as locking in a rate can provide certainty around your repayments. It’s all about ensuring you have a safe financial buffer. Keeping a close eye on what the OCR means for your mortgage rate will help you time these decisions wisely and protect your repayment budget.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loans for Self Employed: 2026 Guide to Getting Approved

Imagine sitting across from a bank manager, presenting a thriving business you have built from the ground up, only to be told your "paper income" isn’t enough to buy a house. It is incredibly disheartening when mainstream lenders ignore your legitimate business add-backs or penalise you for the very expenses your accountant organised to reduce your tax bill. If you are searching for a home loan and are self employed, you have likely realised that traditional banks often view your entrepreneurial drive as a risk. They see inconsistent income "bursts" and mountains of paperwork, while we see a dedicated professional who deserves a steady hand to guide them through the finance process.

This 2026 guide provides the clear path to pre-approval you need, even with the Official Cash Rate at 2.25% and debt-to-income ratios capped at six times your earnings. You will learn exactly how to bypass rigid bank criteria by exploring non-bank lenders who offer flexible "alt-doc" solutions using GST returns or business bank statements. We will detail how to secure competitive interest rates and navigate the latest LVR restrictions, ensuring your business structure is properly understood so you can move forward with confidence.

Key Takeaways

  • Understand how lenders apply “safety margins” to your income and how to navigate the 2026 Debt-to-Income (DTI) restrictions.
  • Discover the documentation hierarchy and why alternative “Alt-Doc” methods like GST returns might be the key to proving your true earning power.
  • Learn why 2nd Tier lenders are a strategic choice for a self employed home loan nz rather than a last resort when mainstream banks decline your application.
  • Master a simple “pre-audit” process to organise your business drawings and personal expenses for maximum lender appeal.
  • Explore how professional advocacy and veteran negotiation can translate your complex business structure into a clear path for approval.

The Reality of Self-Employed Home Loans

For many business owners, the dream of home ownership feels like it is being held hostage by a spreadsheet. Getting a **self employed home loan ** in 2026 requires more than just a profitable business; it requires a deep understanding of how lenders interpret your financial health. While an employee with a standard salary provides a predictable data point for a bank, your income is often viewed through a lens of skepticism. Mainstream banks are currently operating with a conservative risk appetite, and they often struggle to reconcile the fluctuations of a growing business with their rigid lending criteria.

The lending environment in mid-2026 is heavily influenced by the Debt-to-Income (DTI) restrictions that became a permanent fixture in recent years. For owner-occupiers, the limit is generally six times your gross annual income, while investors are capped at seven times. When defining self-employment for a loan application, the bank does not just look at your turnover. They look at your drawings, your net profit, and your ability to service debt when the Official Cash Rate (OCR) is at 2.25%. If your income arrives in "bursts" rather than a steady drip, a traditional bank might simply put you in the "too hard" basket. However, being declined by a major bank is rarely the end of the road; it is often just the signal that you need a more sophisticated lending partner.

Understanding Your Income

Banks are notoriously cautious with business owners.

To overcome this, we focus on "add-backs." These are legitimate business expenses that don’t actually impact your ability to pay a mortgage, such as:

  • One-off capital purchases or equipment upgrades.
  • Non-cash expenses like depreciation.
  • Excessive home office claims or personal expenses run through the business.
  • Rent or interest payments that will cease once you buy your own property.

Regulatory Changes and DTI Ratios in 2026

The 2026 regulatory framework treats business debt and personal debt with equal scrutiny. Under the current Credit Contracts and Consumer Finance Act (CCCFA) requirements, lenders must be certain that your business debt—such as vehicle finance or an overdraft—does not compromise your home loan repayments. If your business carries significant debt, it can quickly eat into your DTI allowance, making it harder to reach the 80% LVR threshold required for standard owner-occupier loans. We work with you to clean up your debt profile, ensuring your personal and business liabilities are structured to maximise your approval chances without sacrificing your business’s cash flow.

Proving Your Income: Documentation That Actually Works

Securing a self employed home loan requires a strategic approach to your paperwork. While an employee simply hands over three months of payslips, your application must build a narrative of stability and growth. Many business owners find that their IRD Summary of Earnings tells a story of tax efficiency rather than true mortgage affordability. To bridge this gap, we look beyond the basic tax return to find the documents that reflect your business’s actual momentum.

The hierarchy of proof has shifted significantly in 2026. Traditional "Low-Doc" loans, which once required minimal evidence, have largely been replaced by "Alt-Doc" (alternative documentation) solutions. This is a direct result of the Credit Contracts and Consumer Finance Act (CCCFA), which mandates a robust assessment of affordability. If you have two years of clean financial accounts, you’ll likely qualify for "Full-Doc" rates. However, if your business has recently scaled or you have "bursty" income from project-based contracts, Alt-Doc allows us to use more recent data, such as GST returns, to prove you can comfortably service the debt.

The Essential Self-Employed Paperwork Checklist

Lenders want to see that your business is a reliable vehicle for income. Before submitting an application, ensure you have the following documents organised:

  • Financial Statements: Full Profit & Loss and Balance Sheets for the last two financial years.
  • Bank Statements: Six months of personal and business statements. Lenders look for regular drawings that match your stated income.
  • Tax Verification: Your most recent personal and business tax assessments, along with proof that all IRD obligations are being met.
  • Add-back Schedule: A clear list of non-cash or one-off expenses that shouldn’t count against your borrowing power.

If your business income is seasonal, we frame your application by showing a 12-month average rather than focusing on a quiet month. This context is vital for preventing a "decline" based on a temporary dip in cash flow. If you are unsure which documents best represent your current position, exploring tailored home loan options can help clarify your strategy before you approach a lender.

Alt-Doc Solutions for Newer Businesses

For those who have been trading for 12 to 18 months, or whose most recent tax return doesn’t reflect a recent surge in turnover, Alt-Doc is a game changer. Instead of waiting for the next financial year to end, some specialist lenders will accept an accountant’s declaration of your earnings or use your last six months of GST returns to verify your current capacity. This approach focuses on where your business is today, not where it was two years ago, providing a vital pathway for self employed home loan applicants who are currently in a high-growth phase.

Many business owners view 2nd tier lenders with a sense of hesitation, fearing they are only for those with significant financial trouble. This is a misconception that often prevents entrepreneurs from securing a self employed home loan when they are perfectly capable of servicing a mortgage. In the current 2026 market, non-bank lenders like Avanti Finance or Pepper Money act as sophisticated specialists. They fill the gap left by mainstream banks that rely on rigid automated systems. While a bank might see a complex trust structure or a single year of trading as a red flag, a 2nd tier lender employs human underwriters who look at the bigger picture.

The primary trade-off involves cost. Non-bank "Near Prime" rates typically start around 5.65% to 7.35%, which is higher than the special rates offered by ANZ or Westpac. You should also expect higher establishment fees, often ranging between 1% to 1.5% of the loan value. However, for a business owner, the value lies in the approval probability. These lenders aren’t bound by the Reserve Bank’s strict Debt-to-Income (DTI) thresholds in the same way as registered banks. This flexibility allows us to secure a **self employed home loan **for clients who have the cash flow but don’t fit the traditional "box."

When to Choose a Non-Bank Lender

Choosing a non-bank option is often the most strategic move if your business has undergone a recent transition. If you have moved from a sole trader to a company structure, or if a one-off capital investment skewed your net profit last year, traditional bank software will likely trigger an automatic decline. Specialist lenders are far more accommodating of short trading histories, sometimes considering applications with as little as 6 to 12 months of data if you have a strong industry background. They specialise in "Alt-Doc" solutions, allowing us to use recent GST returns to prove your current earning capacity rather than relying on outdated tax returns.

The Long-Term Strategy: Refinancing Back to a Bank

We often treat a 2nd tier loan as a temporary bridge rather than a forever home for your mortgage. By securing a loan now and maintaining a clean repayment history for 12 to 24 months, you "prime" yourself for a future bank application. This period allows your business to mature on paper and demonstrates your reliability as a borrower. Understanding how to qualify for a home loan in NZ involves planning this exit strategy from the start. Once your financial statements show two years of solid growth, we can assist you in refinancing back to a mainstream bank at a lower interest rate, having already secured the property you wanted.

Home Loans for Self Employed: 2026 Guide to Getting Approved

A Step-by-Step Guide to Polishing Your Mortgage Application

Successful lending outcomes are rarely the result of luck. They are the product of a disciplined staging process that begins months before you even attend an open home. When you apply for a self employed home loan, the bank isn’t just looking for profitability; they are searching for evidence of financial discipline. Think of your application like a house you are preparing for sale. You need to declutter the noise, fix the small leaks in your spending, and highlight the structural strengths of your business.

The first step is a rigorous pre-audit. Scour your business accounts for personal expenses that might look like high living costs to a lender. Second, ensure your drawings are regular. A bank prefers to see $1,500 transferred every week rather than a $20,000 lump sum once a quarter. Third, slash your credit limits. In the 2026 DTI environment, an unused $10,000 credit card or an active Buy Now, Pay Later (BNPL) account can reduce your borrowing power by tens of thousands of dollars. Finally, prepare a formal business commentary and engage a specialist who understands the nuances of business structures.

Framing Your Business Narrative

Lenders hate mystery. If your profit dipped recently because you invested in a new fleet of vehicles or a high-end server array, you must tell them. A written explanation transforms a "loss" on paper into a strategic investment in future growth. Highlight recurring revenue models or long-term contracts that prove your income isn’t just a series of lucky breaks. If you are a contractor in a niche field like IT or engineering, including a professional CV helps the underwriter understand your employability if your current contract ends. This narrative provides the context that raw numbers often lack.

Cleaning Up Your Personal Financial Conduct

You must adhere to the "three-month rule" of flawless account behaviour. Under the CCCFA, any unarranged overdraft or missed payment on a utility bill is a massive red flag. Banks interpret these as a lack of financial control, regardless of how much money is sitting in your business account. You also need a clear "deposit story." Be ready to prove exactly where your savings came from to satisfy Anti-Money Laundering (AML) requirements. If your deposit includes a gift from family or a business dividend, document the paper trail early. To ensure your application is truly bank-ready, you can apply for a home loan assessment to identify any potential hurdles before they become problems.

Why Mortgage Suite is Your Best Advocate for Approval

When you work for yourself, you don’t just need a loan; you need a dedicated negotiator who understands the intricacies of your business. Securing a **self employed home loan ** is often a battle of interpretation. It’s about how your depreciation is viewed, how your "bursty" income is averaged, and how your future potential is weighed against historical tax returns. We provide the steady hand and the institutional knowledge required to bridge the gap between your entrepreneurial success and the rigid requirements of a bank’s credit department.

We work with the mainstream banks in the first instance but our reach extends beyond the big four banks. We provide access to a comprehensive range of 2nd tier and alternative capital, allowing us to find solutions even when traditional lenders have said no. Our partnership approach includes:

  • Access to residential investment property loans and business finance.
  • Strategic planning to move from 2nd tier loans back to mainstream banks.
  • Proactive management of commercial and property development loans.
  • Expert structuring for first-home buyers with non-standard income.

The Advantage of a Seasoned Negotiator

Krish Krishna brings over 20 years of banking experience and 26 years as Financial Adviser to your side of the table. This isn’t about simply submitting a form; it’s about expert negotiation. Krish uses his deep understanding of credit policy to challenge rejections and present your financial story in a way that resonates with underwriters. We specialise in structuring complex deals that mainstream banks often overlook, ensuring your business structure is viewed as a strength rather than a liability. You aren’t just another file to us; you are a partner whose success is our priority.

We understand that as a business owner, your time is your most valuable asset. By utilising our veteran expertise, you gain an advocate who knows exactly which "add-backs" to fight for and which lenders have the highest risk appetite for your specific industry. This high-standard service is designed to remove obstacles and create a seamless bridge to your property goals.

Ready to Get Moving?

We simplify the process so you can stay focused on running your business. Instead of you spending hours chasing paperwork and deciphering banking jargon, we handle the heavy lifting. The first steps involve a consultative conversation where we identify your needs and outline a clear path to pre-approval. There is no need to feel overwhelmed by the volume of paperwork when you have a veteran expert managing the details. Enquire about your self-employed home loan today and take the first step toward a successful approval.

Your Path to Home Ownership Starts Here

Securing a self employed home loan in 2026 doesn’t have to be a source of constant anxiety. While the DTI restrictions and rigid bank criteria create hurdles, they are far from insurmountable when you have the right documentation and a strategic narrative to tackle the mainstream banks. Whether you are using Alt-Doc solutions to prove your recent momentum or utilising a 2nd tier lender as a tactical stepping stone, the goal remains the same: securing a home that reflects your hard work.

At Mortgage Suite, we leverage over two decades of banking and lending expertise to ensure your business structure is understood, not just processed. If you dont fit the mainstream banks lending criteris, we specialise in 2nd tier loans that mainstream banks often decline, providing a tailored, NZ-wide service for business owners and contractors alike. You have built your business with passion and discipline; we are here to apply that same dedication to your mortgage approval.

If you are ready to move past the frustration of bank rejections, book a consultation with our self-employed lending specialists today. Let us turn your complex financial profile into a clear path forward. Your entrepreneurial journey deserves a partner who values your vision as much as you do.

Frequently Asked Questions

Can I get a home loan if I’ve only been self-employed for one year?

Yes, you can secure a home loan with only one year of trading, though you will likely need to look beyond the major banks. While traditional lenders typically require two years of financial statements, many specialist lenders offer "Alt-Doc" solutions for those with 12 months of history. These lenders focus on your recent GST returns and industry background to assess your current earning capacity properly.

How much deposit do I need as a self-employed borrower in NZ?

Most self-employed borrowers need a 20% deposit for an owner-occupied property or 30% for an investment. If you are a first-home buyer, you may qualify for the Kāinga Ora First Home Loan, which allows for a deposit as low as 5%. Having a larger deposit often helps offset the perceived risk of variable income and can lead to more competitive interest rates from mainstream lenders.

Will my interest rate be higher because I work for myself?

Your interest rate won’t necessarily be higher if you meet the standard lending criteria of a mainstream bank. However, if you require a specialist or 2nd tier lender due to a short trading history or complex accounts, you should expect a margin above standard bank rates. These "Near Prime" rates often start from 5.85% and serve as a strategic bridge until you can refinance to a major bank.

What are "add-backs" and how do they help my mortgage application?

Add-backs are legitimate business expenses that we "add back" to your net profit to demonstrate your true mortgage repayment capacity. Common examples include depreciation, one-off equipment purchases, or interest on loans that will be repaid. By identifying these non-cash or non-recurring costs, we can significantly increase the income figure used for your **self employed home loan **application and improve your approval chances.

Can I use my KiwiSaver for a deposit if I am self-employed?

Yes, you can certainly use your KiwiSaver for a deposit, provided you have been a member for at least three years and are purchasing your first home. Being self-employed does not change your eligibility for a first-home withdrawal. It is essential to request your withdrawal pack early to ensure the funds are ready for settlement, especially if your business income fluctuates and documentation takes longer to organise.

What happens if my latest tax return shows a low profit due to expenses?

If your latest tax return shows a low profit due to high business expenses, we can often use alternative documentation to prove your actual income. Specialist lenders may look at your last six months of GST returns or bank statements to see your current cash flow. This approach helps bypass the "paper loss" created by tax-minimisation strategies, allowing your true earning power to be recognised by the lender.

Do I need a clean credit history to get a self-employed home loan?

You don’t necessarily need a perfect credit history to get approved for a self employed home loan. While mainstream banks are very strict about missed payments or defaults, 2nd tier lenders are more flexible and will often listen to the story behind a credit impairment. A clean record for the last 12 months is usually sufficient to access a wide range of alternative lending options that banks often overlook.

How do DTI ratios affect my ability to borrow for a home?

Debt-to-Income (DTI) ratios limit your total borrowing to a multiple of your gross annual income, typically set at six times for owner-occupiers. For business owners, this means your personal and business debts are weighed against your verified drawings and profit. If your DTI is too high for a major bank, we can often find non-bank solutions that aren’t bound by these specific Reserve Bank restrictions in 2026.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.