
Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

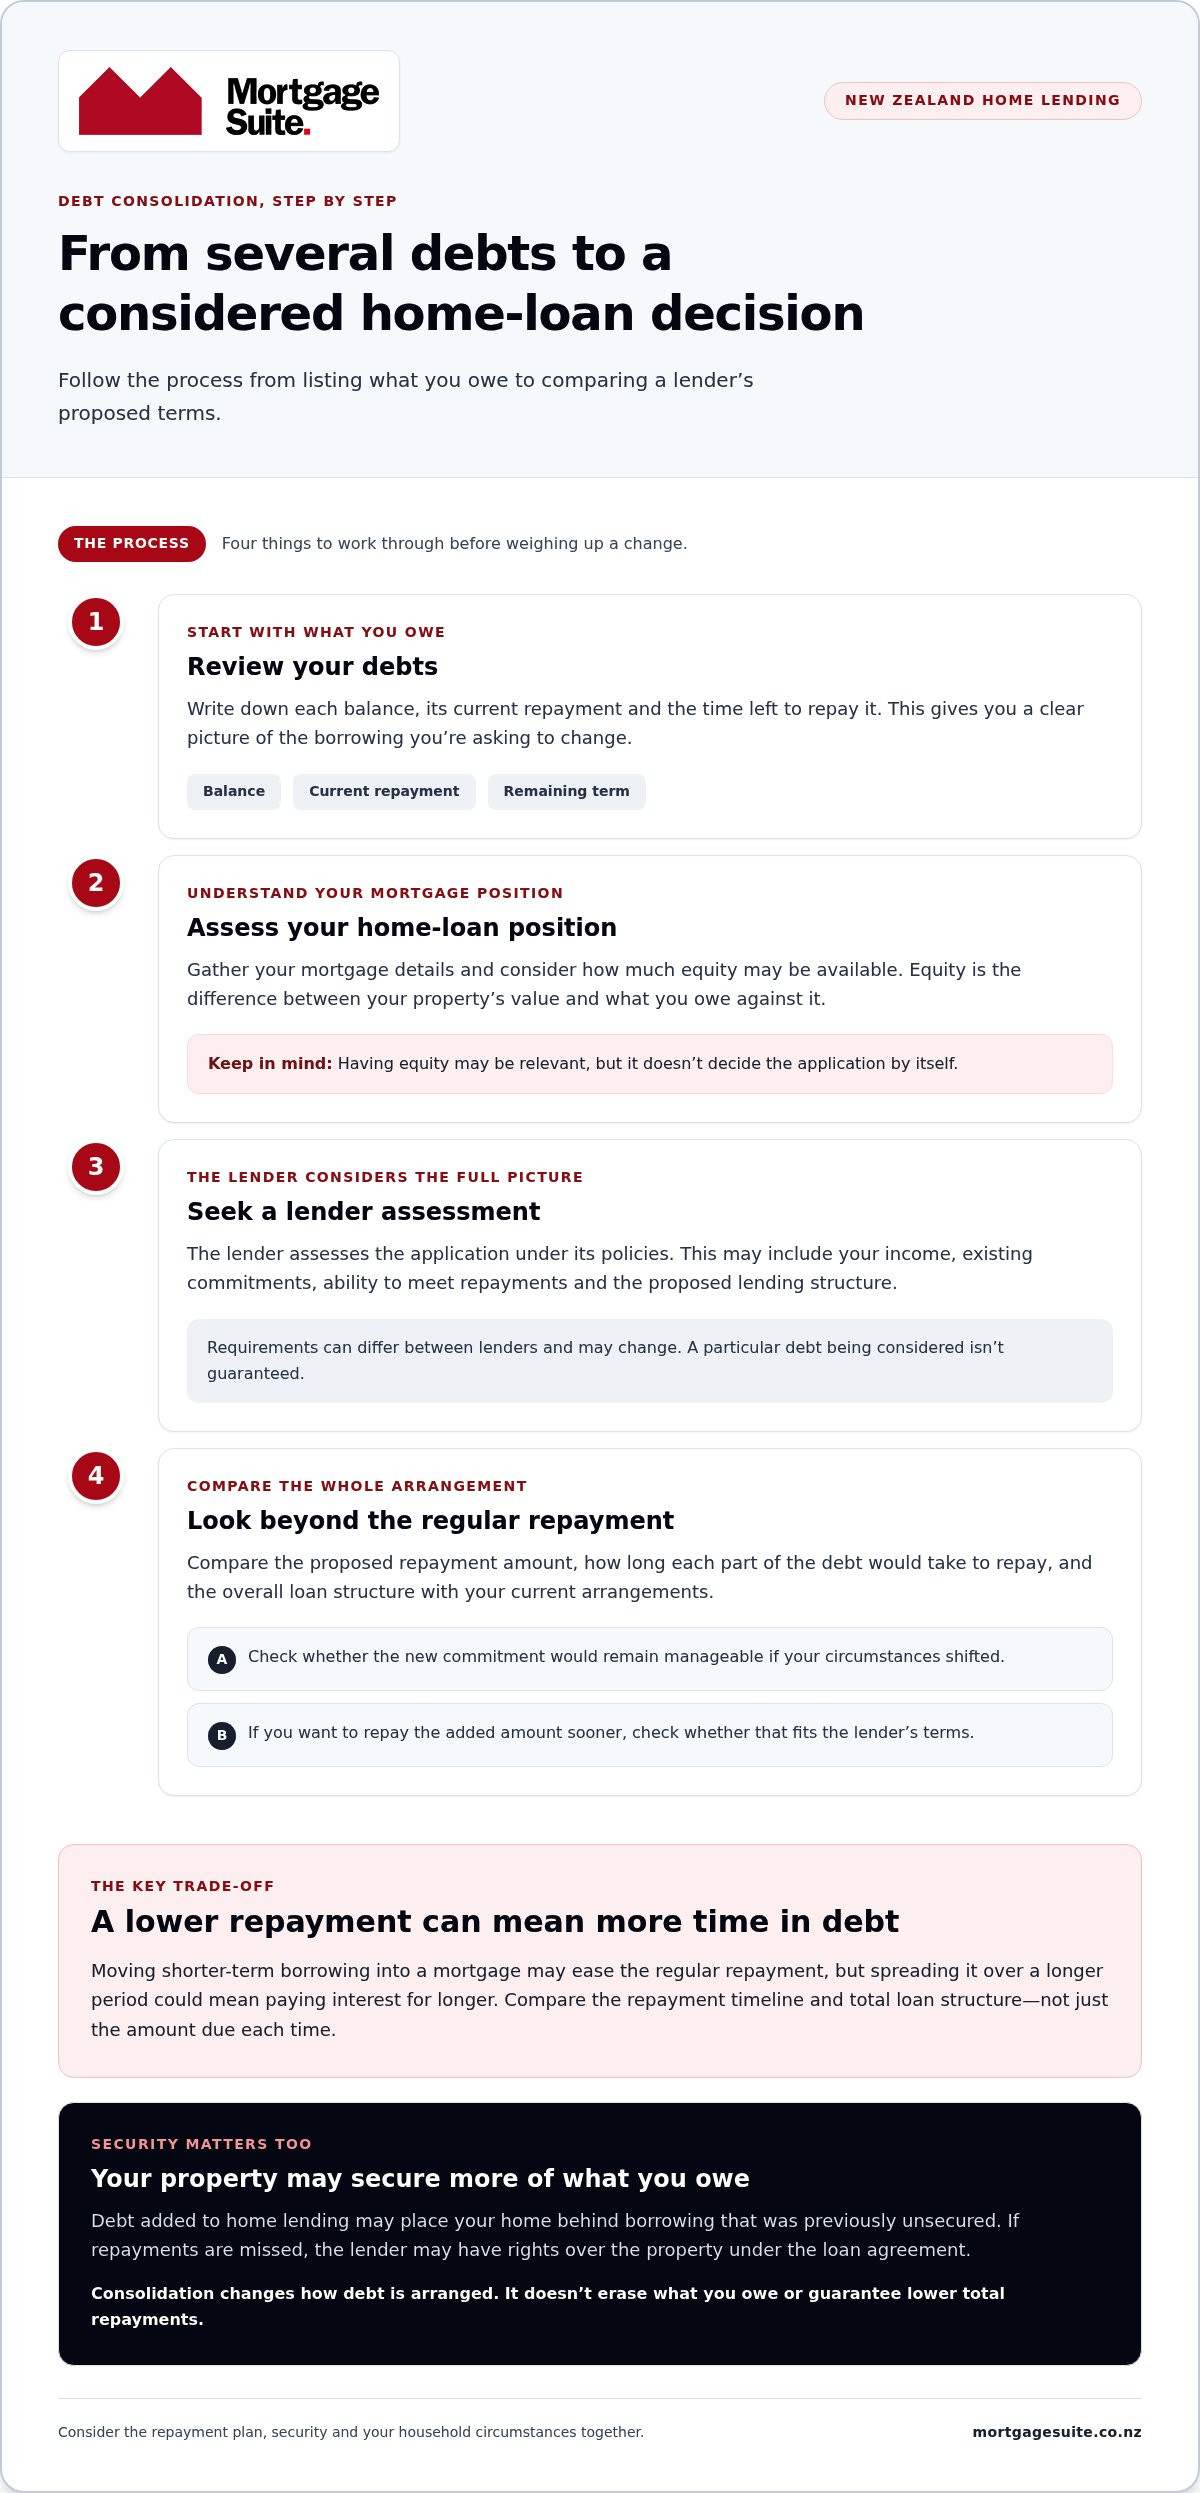
Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.
Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Best Way to Structure Your Mortgage in NZ: A 2026 Guide to Saving Thousands

What if the “standard” home loan your bank offered is actually the slowest possible way to own your home? It’s a common frustration for Kiwis who feel trapped by rising interest rates, especially with the OCR sitting at 2.50% and floating rates climbing above 6%. You might worry you’re missing out on a better deal or feel buried under terms like “offsetting” and “revolving credit.” Finding the best way to structure mortgage nz isn’t about picking a single product; it’s about creating a personalised mix that works for your specific lifestyle.

I understand that looking at your mortgage can feel overwhelming, but you don’t have to just accept the status quo. In this guide, I’ll show you exactly how to organise your loan to slash interest costs and pay off your debt years sooner using proven Kiwi strategies. We will look at how to balance the safety of fixed rates with the flexibility of floating accounts, giving you a clear plan to reduce interest and the freedom to make extra payments whenever you want. By the end, you will have the peace of mind that your mortgage is finally working as hard as you do.

Key Takeaways

  • Understand why finding the best way to structure mortgage nz can save you tens of thousands of dollars more than just hunting for the lowest advertised interest rate.
  • Master the “split loan” strategy to enjoy the security of fixed repayments while keeping the flexibility to smash your debt whenever you have extra cash.
  • Learn how to customise your home loan based on your current life stage, from first-home buyer budget safety to investor-focused tax benefits.
  • Explore how 2nd tier lenders can provide a path forward if mainstream banks have declined your application due to self-employment or complex finances.

Why the Way You Organise Your Mortgage Matters

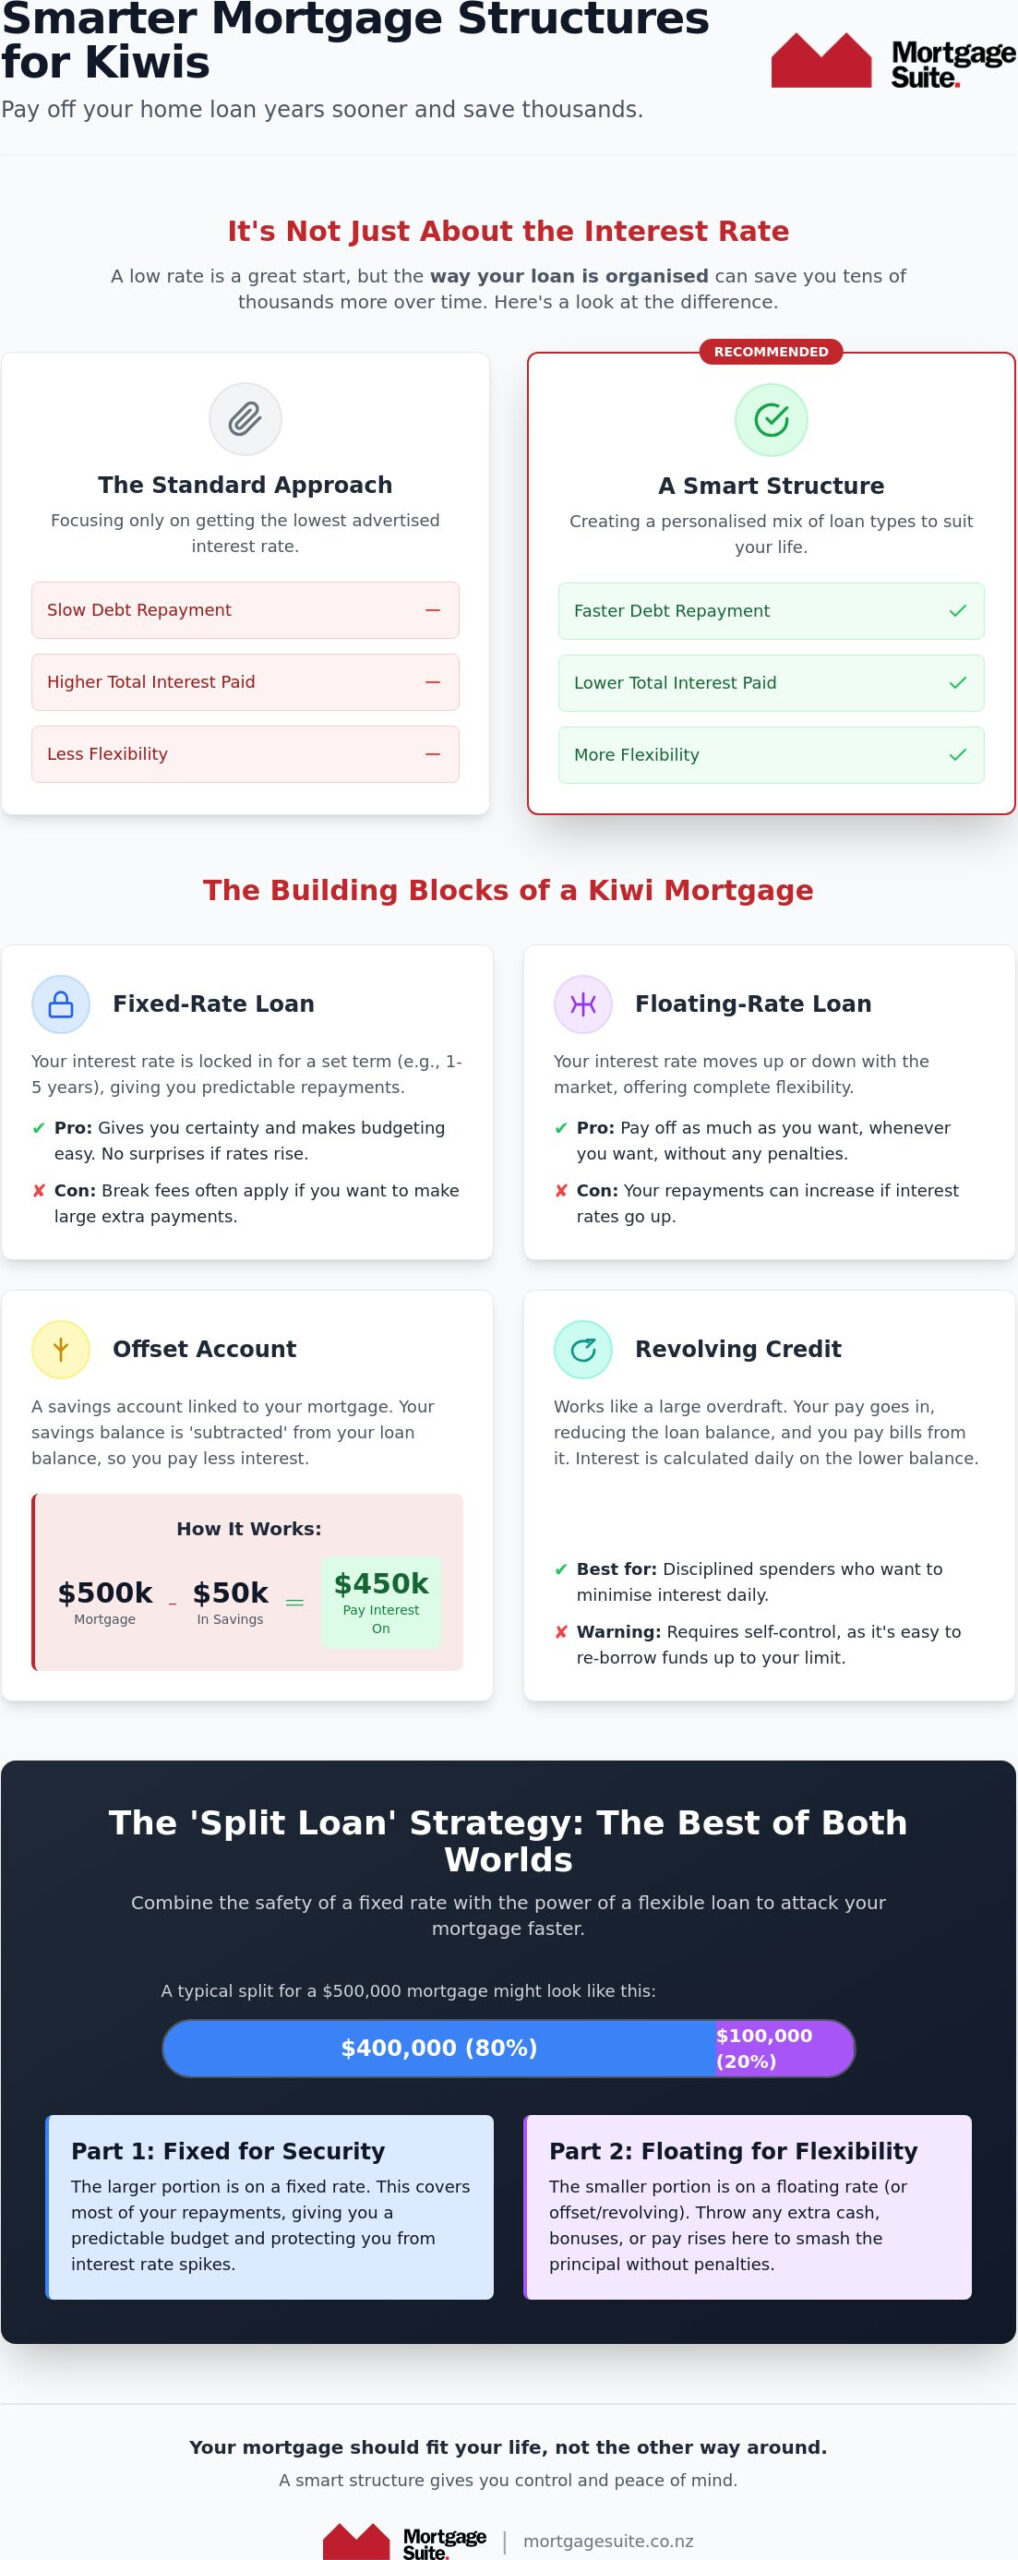
Most people start their home loan journey by hunting for the lowest interest rate they can find on a bank’s website. While a low rate is great, it’s only one piece of the puzzle. The best way to structure mortgage nz involves looking at the big picture of your finances rather than just the number on the front page. If your loan isn’t set up correctly, you could end up paying far more in interest over thirty years than someone with a slightly higher rate but a smarter structure.

A well-set-up loan can save you tens of thousands of dollars over the life of your mortgage. Think about it this way: even a small change in how you split your debt can shave years off your repayment term. It gives you the freedom to throw extra cash at your debt when you have a good month, without getting hit by nasty bank penalties. At the same time, it acts as a safety net. If interest rates suddenly jump, a solid structure protects you from “bill shock” by ensuring your repayments don’t all skyrocket at once. When you find the best way to structure mortgage nz for your specific situation, you gain genuine control over your financial future.

The Tug-of-War: Certainty vs. Flexibility

Choosing between fixed and floating rates often feels like a tug-of-war. Fixed rates are your safety blanket; they give you a predictable budget so you can sleep easy at night knowing exactly what’s going out of your account. Floating rates, on the other hand, give you the power to make extra repayments whenever you like without fees. This is where the role of a mortgage broker becomes so valuable, as they help you find the “sweet spot” between these two worlds. Finding that balance ensures you aren’t paying for flexibility you don’t use or getting locked into a rigid plan that doesn’t allow for life’s surprises.

How Structuring Affects Your Daily Life

Your mortgage should fit around your life, not the other way around. Simple moves like matching your repayments to your payday, whether that’s weekly or fortnightly, can make budgeting feel effortless. It’s also about making sure you have access to funds for emergencies without needing to go through a stressful new loan application. A great structure keeps your cash flow smooth and your stress levels low. Your mortgage structure is the blueprint for your financial freedom.

The Building Blocks of a Kiwi Mortgage

Think of your mortgage as a set of building blocks. You don’t have to use just one type of loan for your entire debt. In fact, the best way to structure mortgage nz often involves stacking different “blocks” together to get the right balance of safety and speed. Most Kiwis start with a table loan, which is the standard way to pay off a house. With a table loan, your repayments stay the same, but the mix of interest and principal changes over time. At the start, you’re mostly paying interest, but as the years go by, you start smashing the actual debt much faster.

To keep things predictable, you might choose a fixed-rate loan. This locks in your interest rate for a set time, usually between one and five years. With ASB recently offering a one year fixed rate of 4.65% p.a., many people find this a great way to keep their budget steady. On the flip side, floating or variable loans move up and down with the market. While Westpac’s floating rates currently sit around 6.14%, they offer total flexibility. You can pay off as much as you want, whenever you want, without any nasty break fees. If you’re unsure which combo fits your lifestyle, it’s worth having a chat about your home loan options with someone who knows the ropes.

The Power of Offsetting Your Savings

Offsetting is one of the smartest moves you can make if you have a bit of cash sitting in the bank. Instead of the bank paying you a tiny amount of interest on your savings (which then gets taxed), they “cancel out” that portion of your mortgage. If you have a $500,000 mortgage and $50,000 in savings, you only pay interest on $450,000. It’s essentially like earning a tax-free return on your savings at whatever your mortgage interest rate happens to be. It’s almost always better than a standard savings account because the interest you save on your debt is usually higher than the interest you’d earn on your deposits.

Revolving Credit: The Giant Overdraft

A revolving credit account works like a giant, flexible bucket of money. Your whole pay cheque goes into the account, which keeps the balance as low as possible for as long as possible, reducing the interest you pay every single day. You then draw money out for your groceries and bills as needed. It’s a brilliant tool for people who are disciplined with their spending or those who want an emergency buffer for things like home renovations. However, it does require a bit of self-control. Since you can “re-borrow” the money up to your limit at any time, it’s not the best choice if you’re tempted to spend every cent in your account.

The ‘Split Loan’ Strategy: A Step-by-Step Guide

Most savvy borrowers don’t put all their eggs in one basket. They know that the best way to structure mortgage nz is to split the debt into different parts. This strategy allows you to hedge your bets against interest rate changes while giving you a clear path to pay down debt aggressively. You won’t have to worry about “breaking” a fixed term and paying expensive fees just because you had a good month and want to make an extra payment. This method works regardless of which bank you’re with; it’s simply about how you choose to slice the pie.

Splitting your loan gives you the best of both worlds. You get the peace of mind that comes with fixed repayments and the freedom that comes with a floating account. It’s a proactive way to manage your money that puts you in the driver’s seat rather than leaving you at the mercy of market fluctuations. Let’s look at how to set this up in three simple steps.

Step 1: Determine Your ‘Safety’ Portion

Decide how much of your loan needs to be fixed for total budget certainty. For many, this is about 80% of the total debt. Rather than fixing that whole amount for a single term, consider “laddering” it. You might fix one portion for one year and another for three. This prevents your entire mortgage from coming up for renewal at the same time, which is vital if rates have climbed. To get a feel for what might work for you, take a look at our latest guide on mortgage rates NZ to see the current trends and where things might be heading.

Step 2: Calculate Your ‘Flexi’ Portion

Work out how much you can realistically pay off in the next year or two. This amount becomes your “flexi” portion, usually set up as a floating or revolving credit account. It’s a delicate balance. You don’t want to pay a higher floating rate on more money than you can actually pay down, but you also don’t want to be so restricted that you can’t use your extra savings to reduce your debt. It’s about finding that personal limit where your money works hardest for you.

Step 3: Review and Rebalance Annually

Your structure should never be “set and forget.” As your career grows or your family expands, your financial needs will shift. Treat your mortgage’s “anniversary” as a time for a quick check-up with your bank or broker. With the Reserve Bank recently lifting the Official Cash Rate to 2.50% in July 2026, staying on top of these changes ensures your structure still matches your lifestyle. A quick annual rebalance can often save you thousands in the long run.

Best Way to Structure Your Mortgage in NZ: A 2026 Guide to Saving Thousands

Matching Your Structure to Your Life Stage

Your financial needs don’t stay the same forever. The best way to structure mortgage nz when you’re just starting out is completely different from when you’re eyeing up retirement. Life happens; kids arrive, careers take off, or you might decide to build an investment portfolio. A structure that worked for you three years ago might be holding you back today. It is about making sure your debt fits your current lifestyle rather than forcing your life to fit a rigid bank product.

Stability is key for some, while others need every bit of flexibility they can get. As a seasoned expert, I’ve seen how a well-timed shift in your loan setup can alleviate the stress of a growing family or accelerate your path to being debt-free. It’s about being proactive. If your circumstances have changed, your mortgage should be the first thing you review to ensure it’s still helping you reach your goals.

Strategies for First-Home Buyers

For most first-home buyers, the priority is simple: keep the repayments manageable and ensure the budget stays predictable. Since the First Home Grant was discontinued on 22 May 2024, many buyers are now leaning on the Kāinga Ora First Home Loan scheme, which allows for a 5% deposit. In this stage, using a table loan is often the smartest move because it guarantees your debt actually goes down from day one. You want a structure that balances your deposit size with long-term certainty so you aren’t caught out by market shifts. You can dive deeper into these tactics in our First Home Buyer guide.

Structuring for Residential Investment

If you’re building a portfolio, your goals shift toward tax efficiency and cash flow. Interest-only terms are very common here because they keep your outgoings low, though they do come with the risk of not actually reducing your debt over time. It’s also vital to keep your investment debt separate from your personal home loan to make things much cleaner at tax time. For a full breakdown of how to set this up for success, check out our Investment Property Loans NZ guide.

Growing families often need a bit more “breathing room.” This might mean having a drawdown facility or a revolving credit portion to cover unexpected costs or that kitchen renovation you’ve been planning. On the other hand, if you’re nearing retirement, the focus usually shifts toward aggressive principal repayments. You want to enter those golden years with as little debt as possible. Whatever stage you’re in, I can help you find a tailored mortgage structure that fits your current life perfectly.

When the Banks Say No: Structuring for 2nd Tier Loans

It can be a real gut-punch when you’ve found your dream home only for your bank to say no. Mainstream banks have very rigid “boxes” for who they will lend to, and if you don’t fit their perfect profile, they often won’t budge. This is common for people who are self-employed, have complex income from multiple sources, or perhaps have a small mark on their credit history. Even in these situations, finding the best way to structure mortgage nz is still the key to your long-term success. You shouldn’t have to give up on your property goals just because a big bank’s computer system gave you a “no.”

Structuring a loan with a non-bank lender requires a different mindset. The interest rates and terms might not look exactly like the ones you see on the evening news, but the goal remains the same: getting you into your home with a plan to eventually move back to a mainstream bank. I see these situations as a puzzle that needs a specialised touch to solve. We focus on creating a structure that manages your current costs while building a clear path toward a more traditional loan in the future.

Why 2nd Tier Lending Isn’t ‘Second Best’

Many people worry that alternative lenders are a last resort, but they are often a smart “bridge” to get you where you want to be. These lenders have much more flexible criteria for those with non-standard financial histories. They look at the person and the property, not just a set of rigid checkboxes. Using these options allows you to secure your home now while you build up your “bank-ready” profile over a year or two. You can learn more about how we assist with 2nd tier lender NZ solutions to see if this path fits your needs.

The Role of a Seasoned Mortgage Broker

When you’re dealing with complex lending, you need an advocate who knows the “inside” of the industry. My 20 years of banking experience helps me navigate the “grey areas” that often confuse borrowers. A broker can see structures across multiple lenders that you simply can’t see on your own. I act as your negotiator, taking the stress out of the paperwork and the endless back-and-forth with lenders. It’s about finding a tailored solution that matches your unique financial profile, ensuring the best way to structure mortgage nz is working for you, no matter who is providing the funds. My job is to remove the obstacles so you can focus on moving into your new home.

Take Control of Your Financial Future

Owning your home sooner starts with a plan that fits your life, not just a bank’s generic product. We have explored how a “split loan” strategy can give you both budget certainty and the power to smash your debt with extra payments. Whether you are buying your first home or building an investment portfolio, the best way to structure mortgage nz is to ensure your loan setup evolves alongside your career and family. Even if the big banks have turned you away, there are still smart ways to organise your lending that keep your property goals on track.

With over 20 years of banking and brokerage expertise, I specialise in helping Kiwis find the right path through residential, investment, and 2nd tier loans. You don’t have to navigate the jargon or the stress of bank negotiations on your own. I provide a personalised service from founder Krish Krishna that puts your priorities first, ensuring you have a steady hand to guide you through a changing market. Let’s organise a chat about your mortgage structure today and start saving you thousands in interest. You’ve got this, and I am here to help you every step of the way.

Frequently Asked Questions

What is the most common way to structure a mortgage in New Zealand?

Table loans are the most common way Kiwis set up their debt, featuring set repayments over the life of the loan. However, many people now choose a “split loan” as the best way to structure mortgage nz. This involves dividing the debt between fixed and floating portions to get a mix of budget certainty and the freedom to pay off debt faster.

Is it better to fix my mortgage for 1 year or 5 years in 2026?

Choosing between a 1 year or 5 year term depends on your need for certainty versus cost. In July 2026, shorter terms like one year are sitting around 4.65% p.a., which is lower than the 5.59% p.a. offered for five years. While the shorter term saves you money now, the longer term protects you if the Reserve Bank continues to lift the OCR beyond its current 2.50%.

Can I change my mortgage structure if I’m already in a fixed term?

Yes, you can change your structure, but you will likely have to pay a “break fee” to the bank. These fees cover the bank’s loss when you end a contract early and can be quite expensive. It is usually best to wait until your fixed term is within 60 days of expiring, though we can help you calculate if breaking early actually saves you money in the long run.

How does an offset mortgage actually save me money on interest?

An offset mortgage links your savings and everyday accounts to your loan so you only pay interest on the difference. If you have a $500,000 loan and $50,000 in total savings, the bank only charges interest on $450,000. This is a brilliant way to use your cash to reduce interest costs without losing access to your money for emergencies.

What happens if I can’t afford my repayments under my current structure?

You should contact your broker or lender immediately to discuss a “hardship” variation or a temporary move to interest-only repayments. These options can lower your weekly outgoings while you get your finances back on track. Being proactive is vital; it’s much easier to adjust your structure before you miss a payment and protect your credit profile for the future.

Should I use a revolving credit account for my entire mortgage?

Using revolving credit for your entire mortgage is generally not the best way to structure mortgage nz because it requires extreme financial discipline. Since the account acts like a giant overdraft, it is very easy to spend your principal instead of paying it down. Most borrowers find it safer to fix the majority of their debt and keep a smaller portion as revolving credit.

How often should I review my home loan structure with a professional?

You should review your mortgage structure at least once a year or whenever your life circumstances change significantly. A new job, a growing family, or even a shift in the property market can mean your current setup is no longer the most efficient. An annual check-up ensures you are always using the most effective “mix” of loan types to save on interest.

Is it worth having a small floating portion if I don’t have much extra savings?

It is still worth having a small floating portion if you have the capacity to make extra repayments from your regular income. Even without a lump sum of savings, a floating portion gives you the flexibility to put an extra $50 or $100 toward your debt whenever you have a good month. Over twenty years, these small extra payments can shave years off your mortgage.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.