What if the finance for your build becomes difficult to manage as work progresses? It’s understandable to feel unsure about how funds are released, what a lender needs to see and whether the loan structure fits your building contract. If you’re looking at construction loans New Zealand borrowers can access, it helps to understand the funding process before making project commitments.
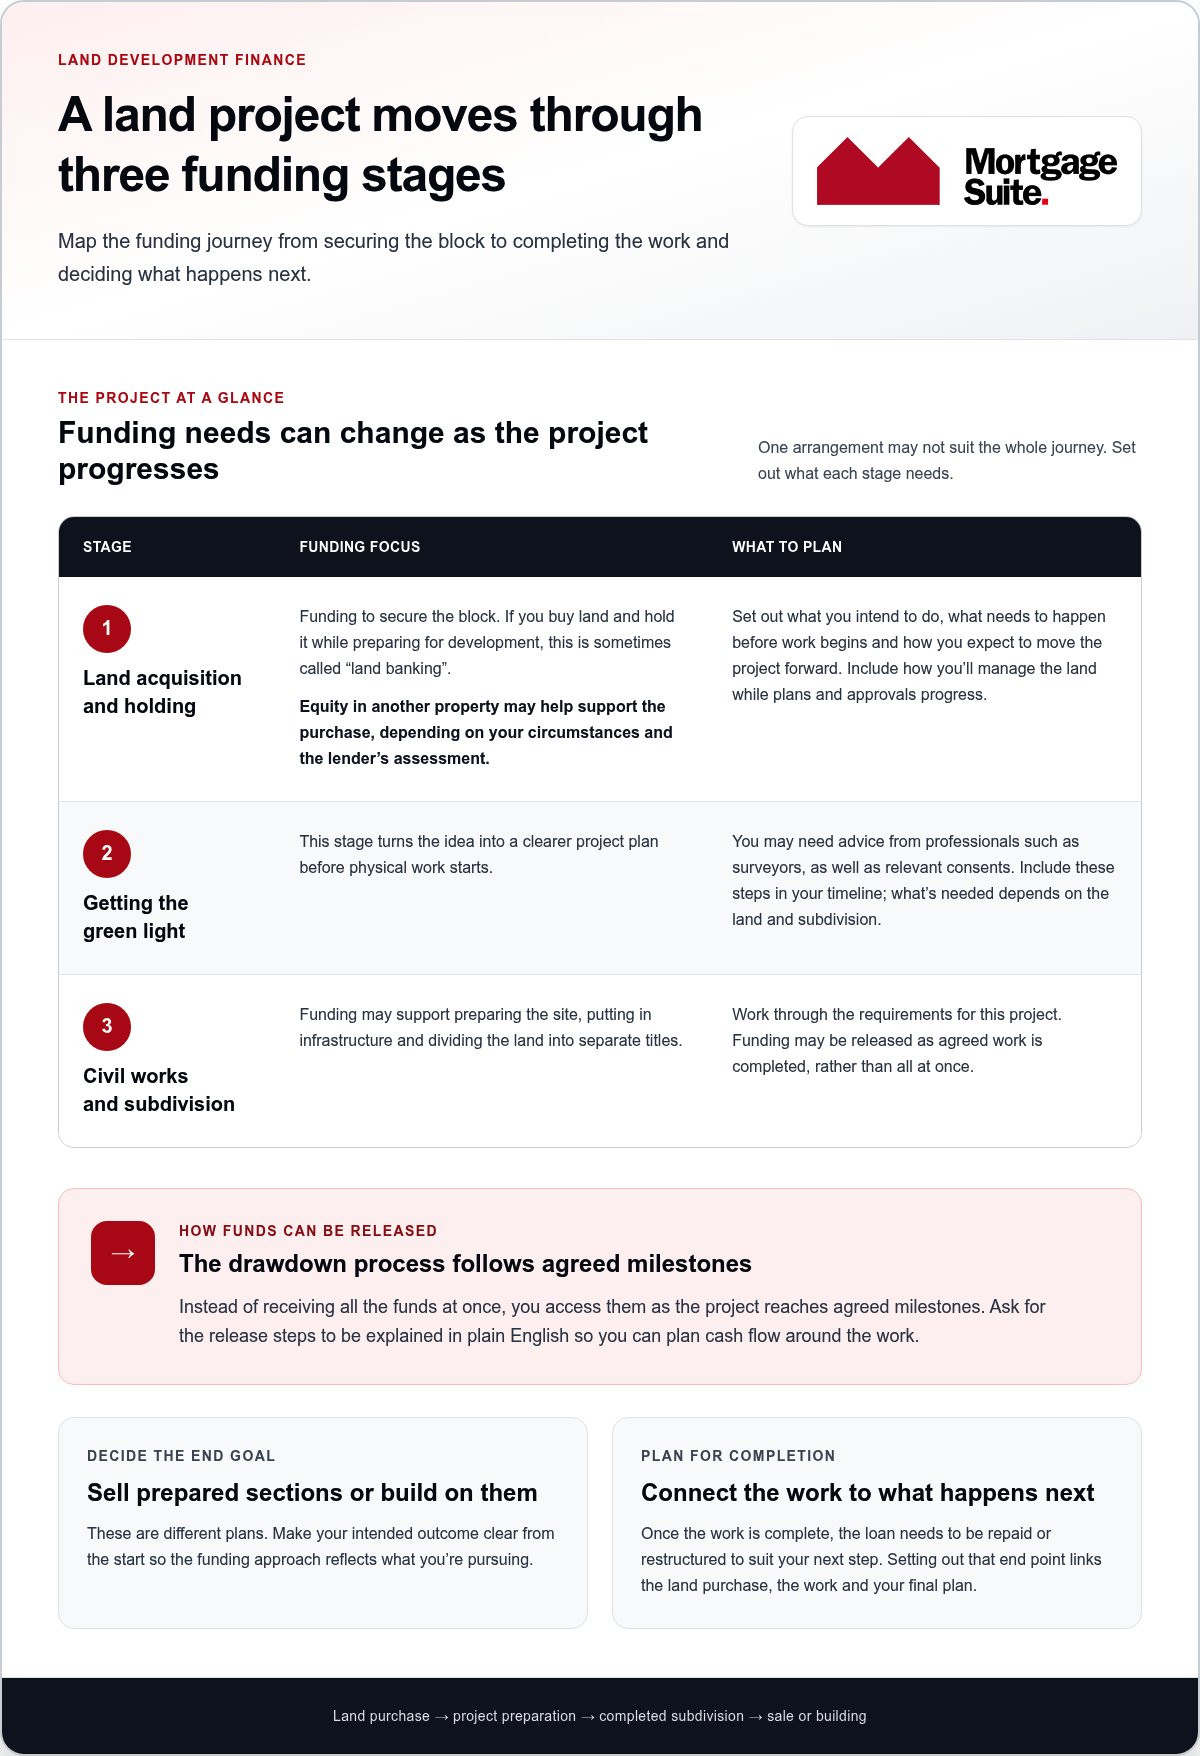
Construction funds are commonly released in stages as agreed building milestones are completed. This is called the drawdown process. Interest is generally charged on the amount already drawn rather than the full approved loan, so it’s worth understanding how the timing of releases fits your project.
This guide explains the usual stages of construction finance, what lenders may consider and what you can prepare before applying. The right structure depends on your contract, build plans and circumstances, and changes to the project can affect the funding plan. Mortgage Suite Ltd works with banks, private lenders and non-bank lenders to help structure and negotiate finance around your project. A decline from a mainstream bank doesn’t necessarily mean your options end there. Mortgage Suite Ltd’s advice is free of charge with no obligation, so you can discuss possible next steps without pressure.
Key Takeaways
- Compare build arrangements to understand how your contract and project plan may shape the finance structure.
- Gather your build plans, contract details and personal financial information so you can explain your funding request clearly.
- Ask what a lender may assess and what conditions could apply before relying on a particular construction-loan structure.
- Match the funding approach to your project and circumstances. No single lending route suits every borrower.
- Mortgage Suite Ltd can help you compare lending routes and negotiate finance around your project, including options beyond mainstream banks.
Construction loans in New Zealand: what they fund and how they differ
Planning a build involves coordinating the design, building work and finance. The way you borrow needs to fit the project stages, your contract and your financial circumstances. Construction finance can vary between lenders, so start by understanding what this type of funding is designed to do.
Construction finance is funding arranged for a building project, with loan funds commonly released in stages as the work progresses. When you buy a completed home, the purchase is generally funded around settlement. Build finance needs to account for when money is required throughout the project. That timing matters: payments and access to funds need to line up, so the agreed structure should reflect the actual project rather than assume every build follows the same pattern.
The lender, loan structure and project details all shape how an arrangement works. A home build and a larger development can have different funding needs, information requirements and ways of releasing funds. Your financial position matters too. There isn’t one construction-loan template that suits every Kiwi. The aim is to match the finance to the work and the people borrowing.
Which projects may need construction finance?
If you’re building a home, you may need funding that accounts for the build rather than a loan arranged solely to buy a finished property. A larger residential project can involve more moving parts, while development work may call for property development finance that considers the broader project. These categories can overlap, but they aren’t interchangeable by default. The right route depends on the project’s scope, the borrower and how the work is arranged.
For example, building a home to live in has a different purpose from seeking funding for a larger development. That difference alone doesn’t determine the right lending structure. The plans, contract, funding needs and lender’s assessment all shape the discussion. Mortgage Suite can help you consider the project as a whole and negotiate a structure around your circumstances.
What do staged funds mean for a borrower?
Staged funding means the entire amount isn’t necessarily available at the outset. Instead, funds are released at agreed points as the build advances. This affects how you plan for upcoming commitments: each release needs to fit the project schedule and contract. The lender and agreed loan structure determine the stages and requirements, so understand them before work is under way.
That’s the practical difference between arranging finance for a build and treating it like a standard purchase: the funding plan needs to follow the project. Start by getting clear on what you’re building, how the work is set up and when you expect to need funds. Then look at how the lender’s drawdown process works.
How the construction-loan drawdown process works
Construction finance involves a series of decisions, not just a single transfer of funds. A clear picture of the build helps the lender assess what you’re asking to borrow and how funding could match the work. Requirements depend on the lender and facility, so treat the steps below as a general guide, not a guaranteed pathway for every project.
What happens before construction finance is arranged?
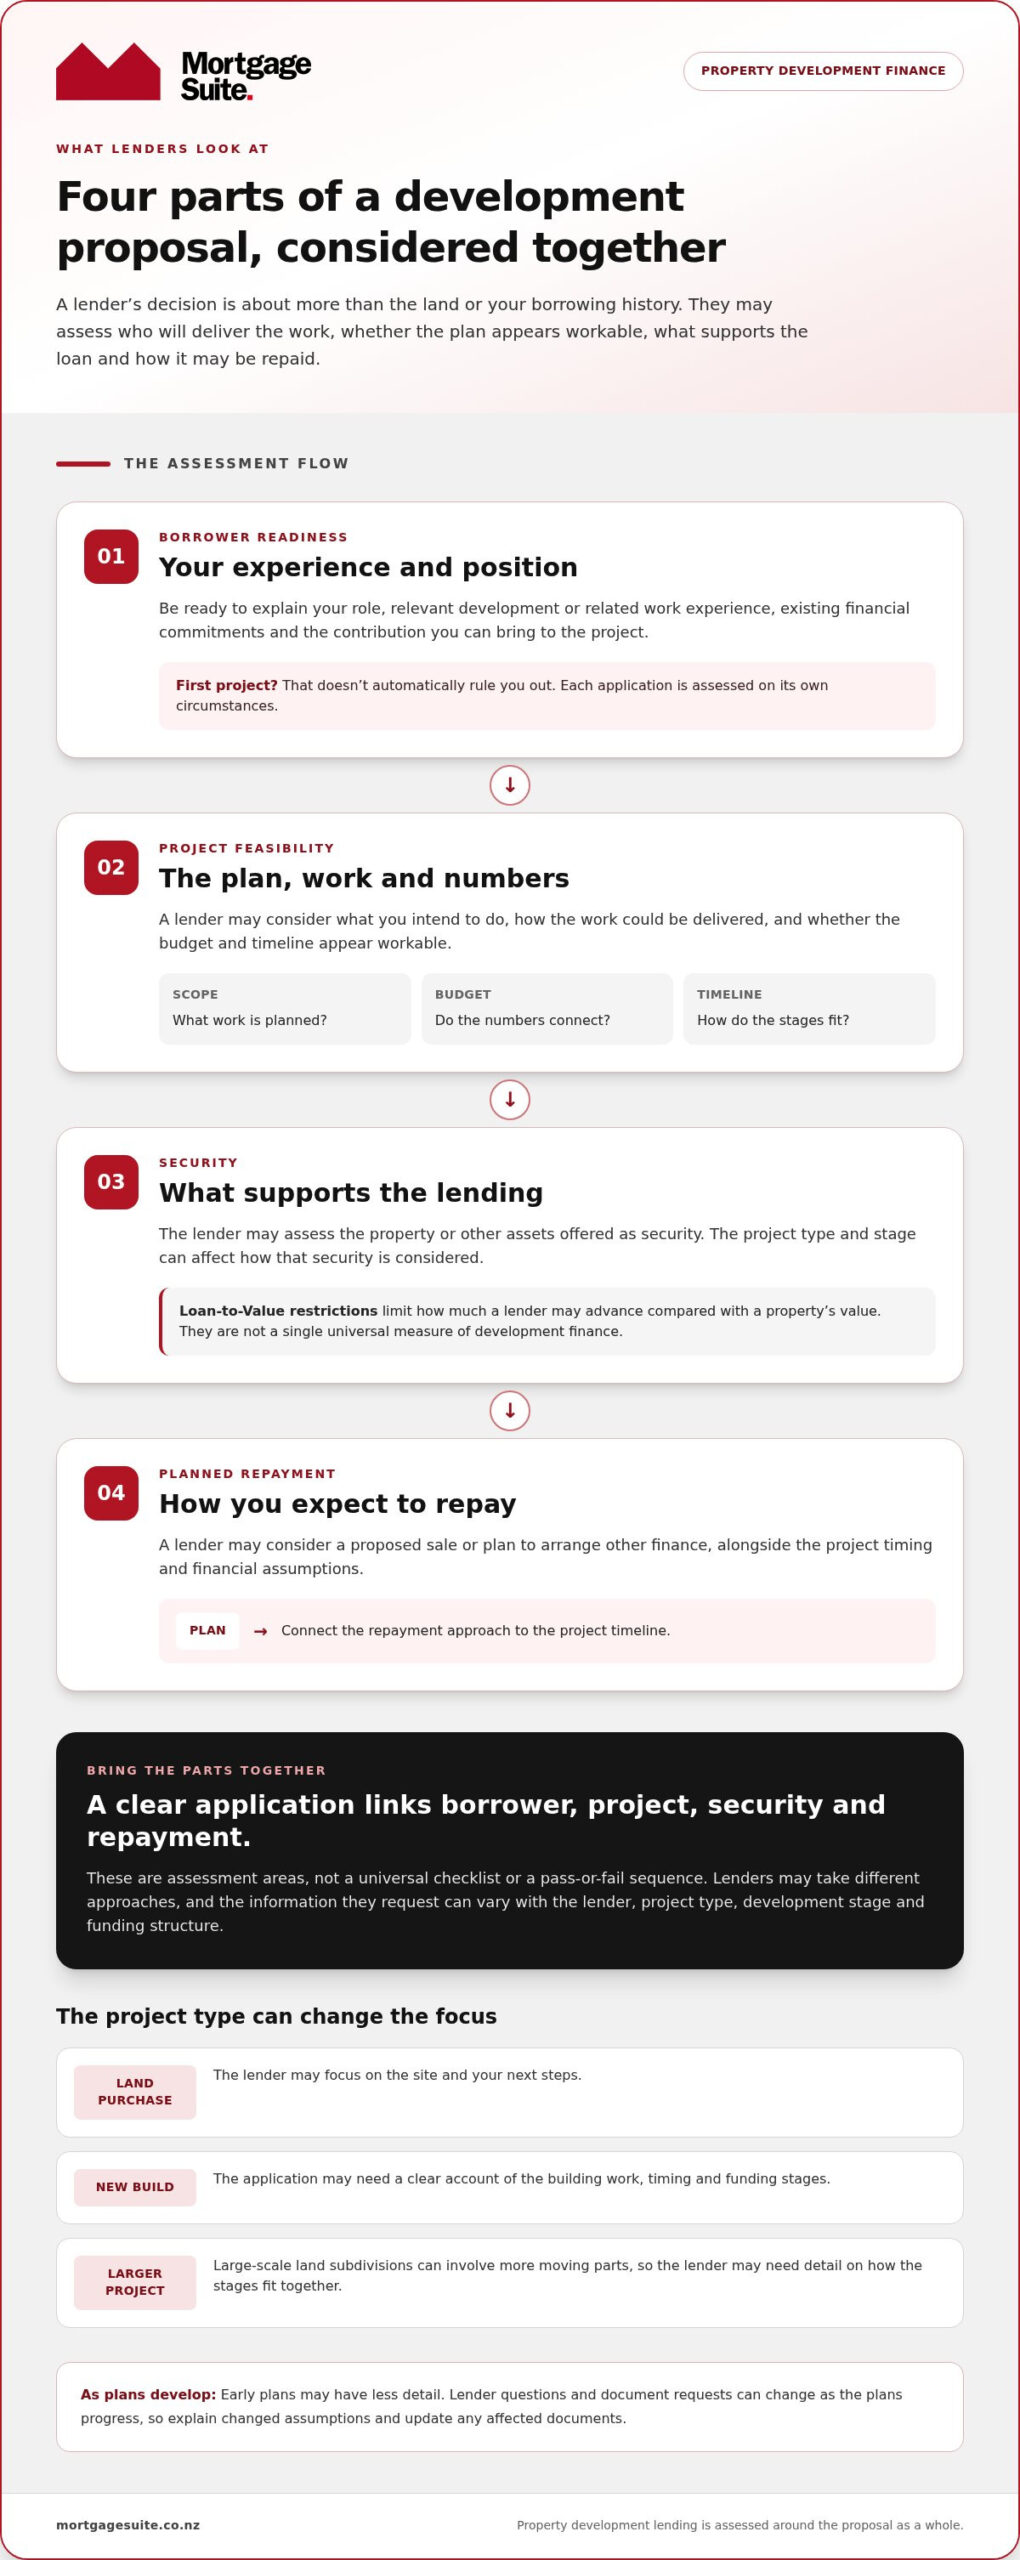
Before a lender assesses your request, bring together your financial details and a clear outline of the project. Be ready to explain what you plan to build, how the work is arranged and what information you have about the contract and expected progress. An early discussion can clarify what may be needed, but it isn’t a lender decision or approval.
A typical sequence looks like this:
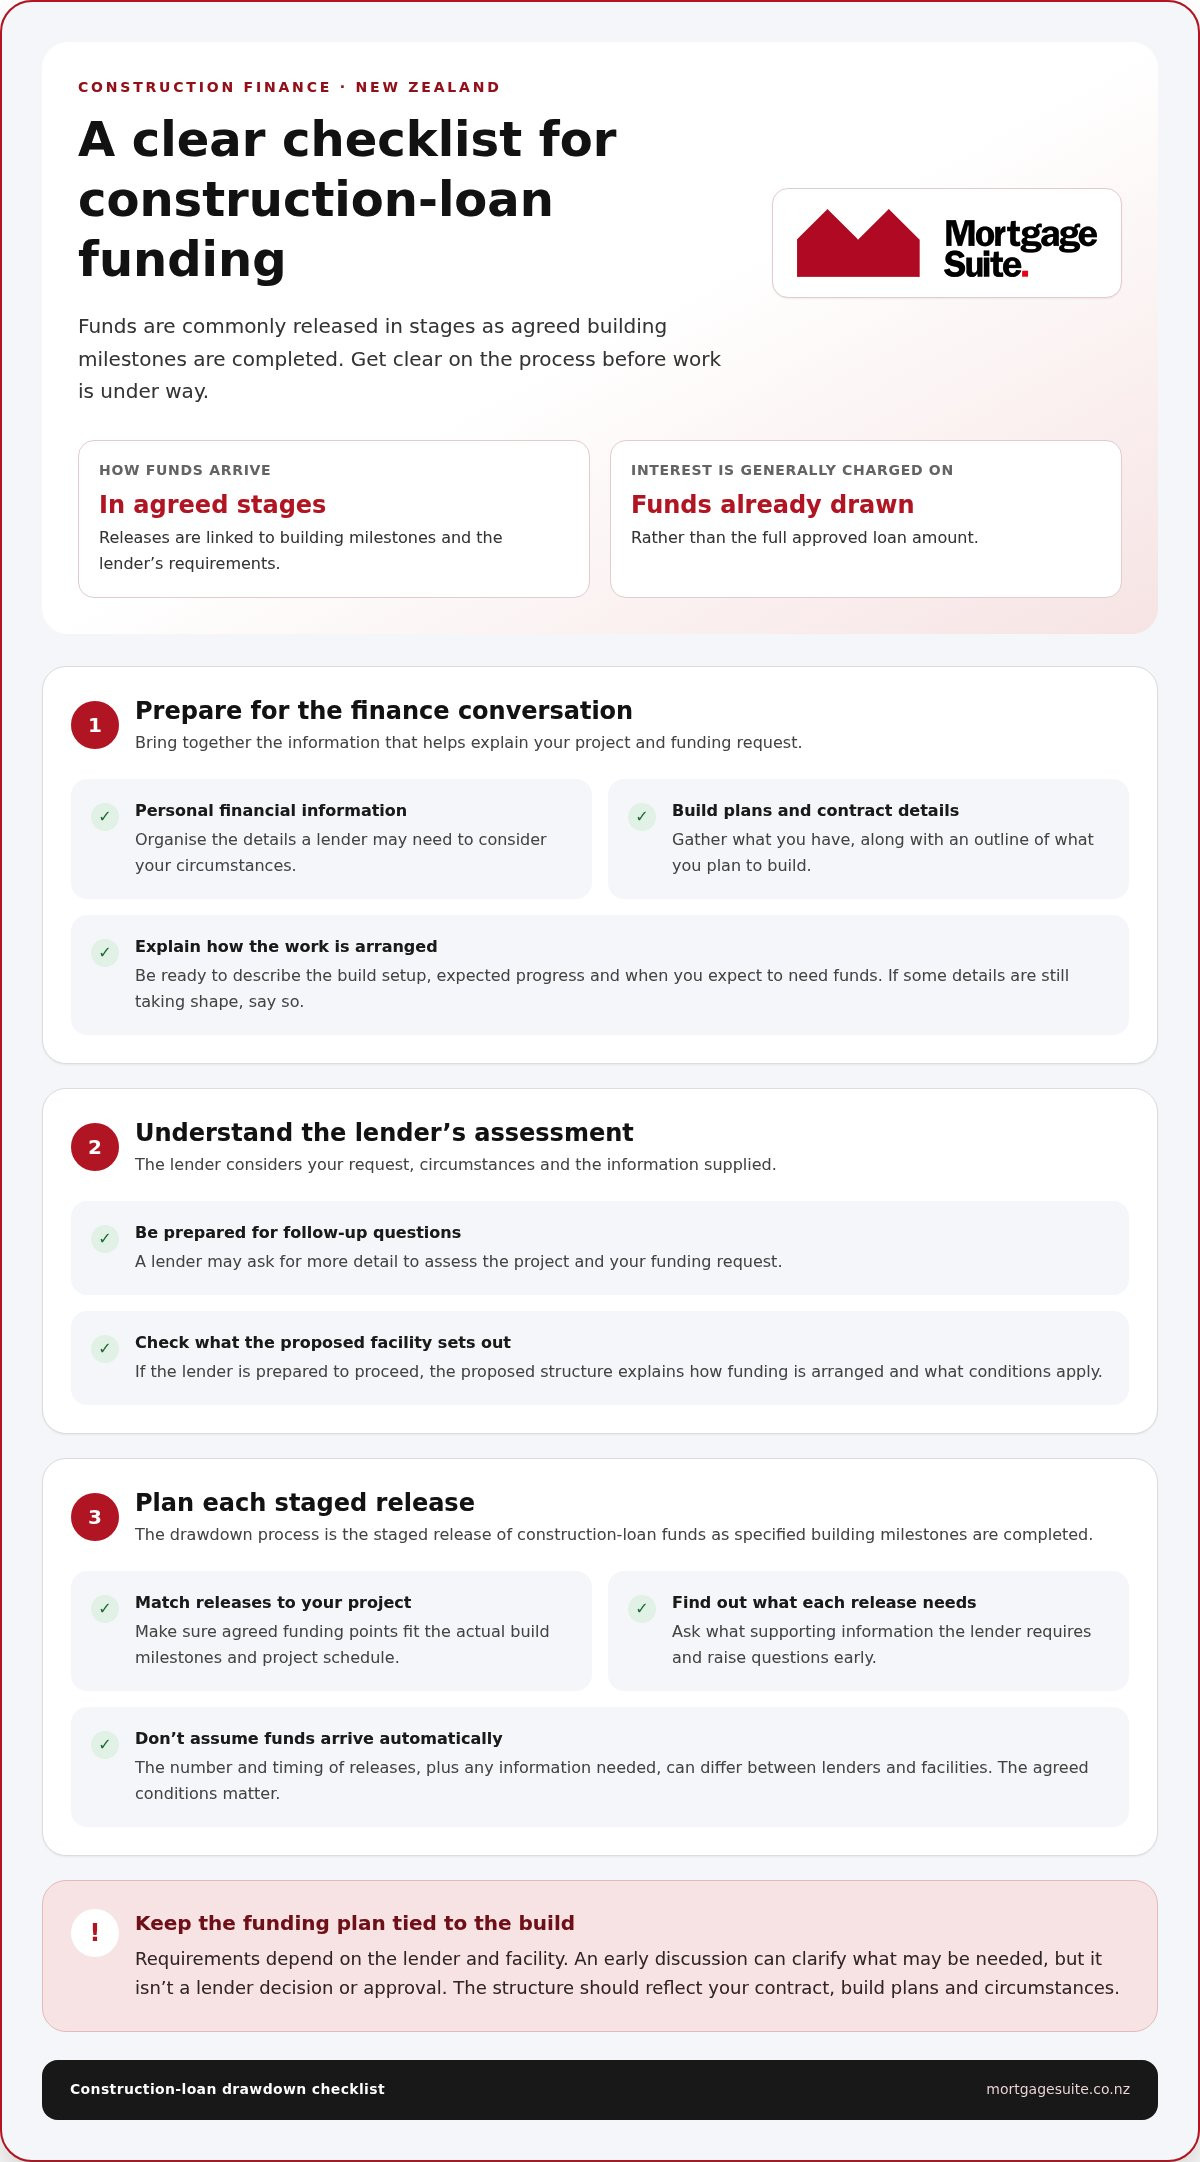
- Prepare: Organise your personal financial information and project documents, including the build plans and contract details you have available.
- Assessment: The lender considers your request, circumstances and the information supplied. It may ask for more detail to assess the project.
- Agree the structure: If the lender is prepared to proceed, the proposed facility sets out how funding is arranged and what conditions apply.
- Request staged releases: As the build advances, request funds in line with the agreed milestones and the lender’s release requirements.
Clarifying the build arrangement early makes the finance conversation more focused. For example, explain whether the request relates to a defined building contract or a project with a different setup. If some information is still taking shape, say so. A discussion can help identify what’s needed next, but only the lender can make a lending decision.
How are funds released as the build progresses?
The drawdown process is the staged release of construction-loan funds as specified building milestones are completed. The loan structure connects agreed funding points with progress on the project. Each lender sets the release conditions for its facility, so the number and timing of releases, and any supporting information required, can differ.
Make sure the funding plan reflects your project milestones instead of relying on a schedule that may not fit. If a payment commitment is coming up, find out what the lender requires for a release and raise questions early. Don’t assume funds will be available automatically at a particular point. The agreed conditions matter.
Put simply, staged drawdowns connect access to finance with agreed progress on the build. For construction loans Auckland borrowers are considering, understanding this link helps you discuss the project’s timing and funding needs. Mortgage Suite can help you prepare for that conversation and negotiate a structure around your circumstances. Explore construction finance support at a pace that feels right for you.
Construction finance options: compare build arrangements and lending routes
The way your build is contracted can affect how a lender understands the project and considers its funding needs. The same finance approach won’t necessarily suit every arrangement or borrower. When comparing construction finance, look at both the build format and the lender channel, then assess them against your plans and circumstances.
How can different build arrangements affect finance?
Build arrangements describe how the land, building work and completed home fit together. Each can raise different questions about the contract, timing and information a lender needs. Use the table as a starting point for discussion, not as a guide to automatic eligibility.
| Build arrangement | What it describes | Finance questions to consider |
|---|---|---|
| Turn-key | A building arrangement where the home is intended to be handed over in a completed state, as set out in the contract. | What does the contract say about progress, completion and when payments are due? |
| House-and-land | A purchase that combines a section with a plan to build a home on it. | How are the land and building parts arranged, and how does the funding need to align with each part? |
| Prefabricated | A home made partly or largely away from the building site, then transported or assembled there. | How does the contract describe work completed off-site, delivery and installation? |
These distinctions help make your funding request more precise. Off-site work, for example, may have different timing from work carried out at the property. A house-and-land arrangement may have separate parts that need to be reflected in the funding plan. The contract and project details give the lender a clearer basis for assessment. Don’t assume a familiar build label determines the outcome. Lender requirements and your circumstances still matter.
When might a borrower consider different lender types?
Banks, private lenders and non-bank lenders are different channels for seeking finance. Their approaches and criteria can vary, and the right one to explore depends on the project, your financial position and the information available. A mainstream-bank decline isn’t a final judgement on you or your plans, but it also doesn’t guarantee another lender will approve your request.
A tailored lender search can help if the project or your circumstances don’t fit neatly with one lender’s approach. Mortgage Suite works across banks, private lenders and non-bank lenders to structure and negotiate finance with both the project and borrower in view. That means the discussion can consider more than a headline rate, including whether the proposed structure fits your build plan.
Before weighing up options, gather the contract, plans and a clear account of how the project is organised. This makes it easier to compare the questions each arrangement raises and discuss a suitable route without assuming one type of finance fits everyone. Mortgage Suite’s advice is free of charge with no obligation. If you’d like support, you can talk through construction finance options without pressure.
How to prepare for a construction-loan conversation
Preparing to discuss finance can feel like another job on top of planning a build. You don’t need every detail finalised before starting a conversation, but a clear picture of the project and your borrowing needs helps make it useful. Focus on how the build is set up and what you need funding to do, rather than assuming a lender will approve it.
What project information should you organise?
Start with what you have: a project outline, the build arrangement and any available plans, contracts or supporting documents. There isn’t one document list for every project, and a lender may request more information during its assessment. Keeping your material together helps you explain the project consistently and respond to questions.
- Project outline: What are you planning to build, and what is the purpose of the project?
- Build arrangement: Is it a turn-key, house-and-land, prefabricated or another arrangement? Include the contract details you have.
- Plans and timing: Note the current plans, expected work sequence and any key dates or commitments you know about.
- Project changes or unknowns: Identify what is still being decided, such as parts of the scope or timing. Don’t present estimates as final.
A clear plan helps a lender see how the request relates to the build, where funds are needed and what may need clarification. If the project extends beyond a residential build into a wider development, explain the broader scope and the specific details of that project.
What should you clarify about your borrowing needs?
Think about what you want the finance to achieve, your existing financial commitments and how you expect funding to fit the project. Consider what you know about payment timing, and note where you need guidance. Raise uncertainties early. A lender or adviser can explain what information may help, but an early discussion isn’t an approval or a promise of an outcome.
A lender may also assess whether repayments appear manageable. A serviceability stress test is a hypothetical repayment assessment using a higher interest rate to test future affordability. The rate and assessment approach can vary by lender, so don’t treat a calculator result as a lending decision. Mortgage Suite’s mortgage calculator can provide an initial repayment estimate to help you frame your questions.
Bring your questions, even if your project is still taking shape. Mortgage Suite can help organise the discussion around the build and your circumstances, then negotiate across lender options. Talk through your construction-finance plans to get clearer on possible next steps.
Arrange construction finance with Mortgage Suite’s support
A build can involve a lot of moving parts, and working out how to fund it shouldn’t feel like a guessing game. Mortgage Suite helps shape construction finance around your project and personal circumstances, then supports you through the lender conversation. The aim is to help you understand the questions to work through and make informed decisions, without promising an outcome before a lender assesses your application.
How does a broker support a construction-loan application?
The conversation starts with your goals and the build itself. What are you planning, how is the work arranged and when might you need funding? Mortgage Suite considers these details alongside your financial position, so the discussion looks at the overall fit, not just a headline interest rate.
A broker can help present your circumstances clearly, identify questions a lender may raise and negotiate terms for consideration. The lender makes the final decision, and its requirements still apply. If a mainstream bank has declined your application, that doesn’t necessarily mean every option has closed. It may be worth reviewing how the project and your circumstances are presented.
Founder Krish Krishna brings over two decades of banking experience to these conversations. That background informs Mortgage Suite’s approach, but it isn’t a promise of approval. Each application is assessed on its own details, and the proposed finance needs to make sense for both the build and the borrower.
What is a simple next step for your build?
You don’t need a perfect plan before you start talking. Write down what you intend to build, how the project is arranged, what you know about timing and the finance questions you’d like answered. Include any details that are still uncertain. Being upfront helps keep the discussion practical and highlights what may need more thought.
An initial conversation gives you space to explain the project and consider possible next steps without pressure to proceed. It isn’t a lender approval, but it can help you get clearer on what to do next.
Ready to talk through your build and finance questions? Discuss your construction finance plans with Mortgage Suite.
Take your next build step with a clear plan
Before making your next project commitment, separate what’s settled from what’s still uncertain. Note any assumptions about the scope or timing and consider what changes could affect your funding needs. This gives you a practical way to keep the finance plan connected to the build as it develops.
You don’t need every answer before you start. A first conversation can help identify which decisions need attention and what information may help you move forward. The right approach depends on the project and the person behind it, so your next step should fit your circumstances rather than follow a one-size-fits-all formula.
If you’re ready to explore your options, talk through your construction finance needs with Mortgage Suite. Start with the plans you have and the questions on your mind, then work out a sensible path forward at your own pace.
Frequently Asked Questions
How does a construction loan work in New Zealand?
A construction loan provides finance for a build, with access to funds arranged under the lender’s terms. Compare the proposed timing with your building commitments. If your plans or contract change, raise that early to understand whether the finance arrangements need review. A discussion can clarify possible next steps, but only the lender can make a lending decision.
Can I get a construction loan for a prefabricated home?
It may be possible, but the finance approach depends on the project, contract and lender’s criteria. Explain how the home will be made and assembled, and how the contract sets out each part of the work. Note when off-site manufacture, delivery and on-site work are expected. This gives a lender useful context to assess your request without assuming another lender’s approach will apply.
How are construction-loan funds released?
Funds are generally released in stages under the lender’s agreed process, known as the drawdown process. The lender sets the timing and conditions for its facility, so don’t assume there’s a standard schedule. Keep a record of upcoming build commitments and the project milestones they relate to. This can help you ask about funding timing before a payment date is close.
Do I need finance approval before starting a build?
It’s sensible to discuss finance before making significant build commitments, but an early conversation isn’t approval. A lender’s decision depends on its assessment and any conditions it sets. Before progressing, make sure you understand the status of your application and what remains to be addressed. If your plans aren’t final, be clear about that so the discussion reflects what’s known and what could still change.
Can I use a non-bank lender for construction finance?
A non-bank lender may be worth considering if its approach fits your project and financial circumstances. Its criteria and proposed structure still need to be assessed on their own merits. Compare how the funding arrangement would work with your build plan, including any conditions that affect access to funds. A non-bank option isn’t automatically more suitable, and the lender must assess your application before making a decision.
What information should I prepare before discussing a construction loan?
Prepare a short project summary, the build arrangement and contract information you have, plus an outline of your borrowing needs. Note your existing financial commitments, income details and any parts of the plan that are still estimates. Keeping confirmed details separate from assumptions makes the conversation clearer. The lender may ask for more information depending on the project and facility.
Can a broker guarantee that my construction loan will be approved?
No. The lender decides whether to approve an application after assessing the borrower, project and its own requirements. A broker can help explain your circumstances, explore possible lender routes and negotiate terms, but can’t control the lender’s decision. If you’re unsure how a particular detail may affect your application, raise it early. That gives you a clearer view of the questions to resolve without treating approval as certain.
Ready to discuss your build and funding options? Talk with Mortgage Suite for free, no-obligation advice.