Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

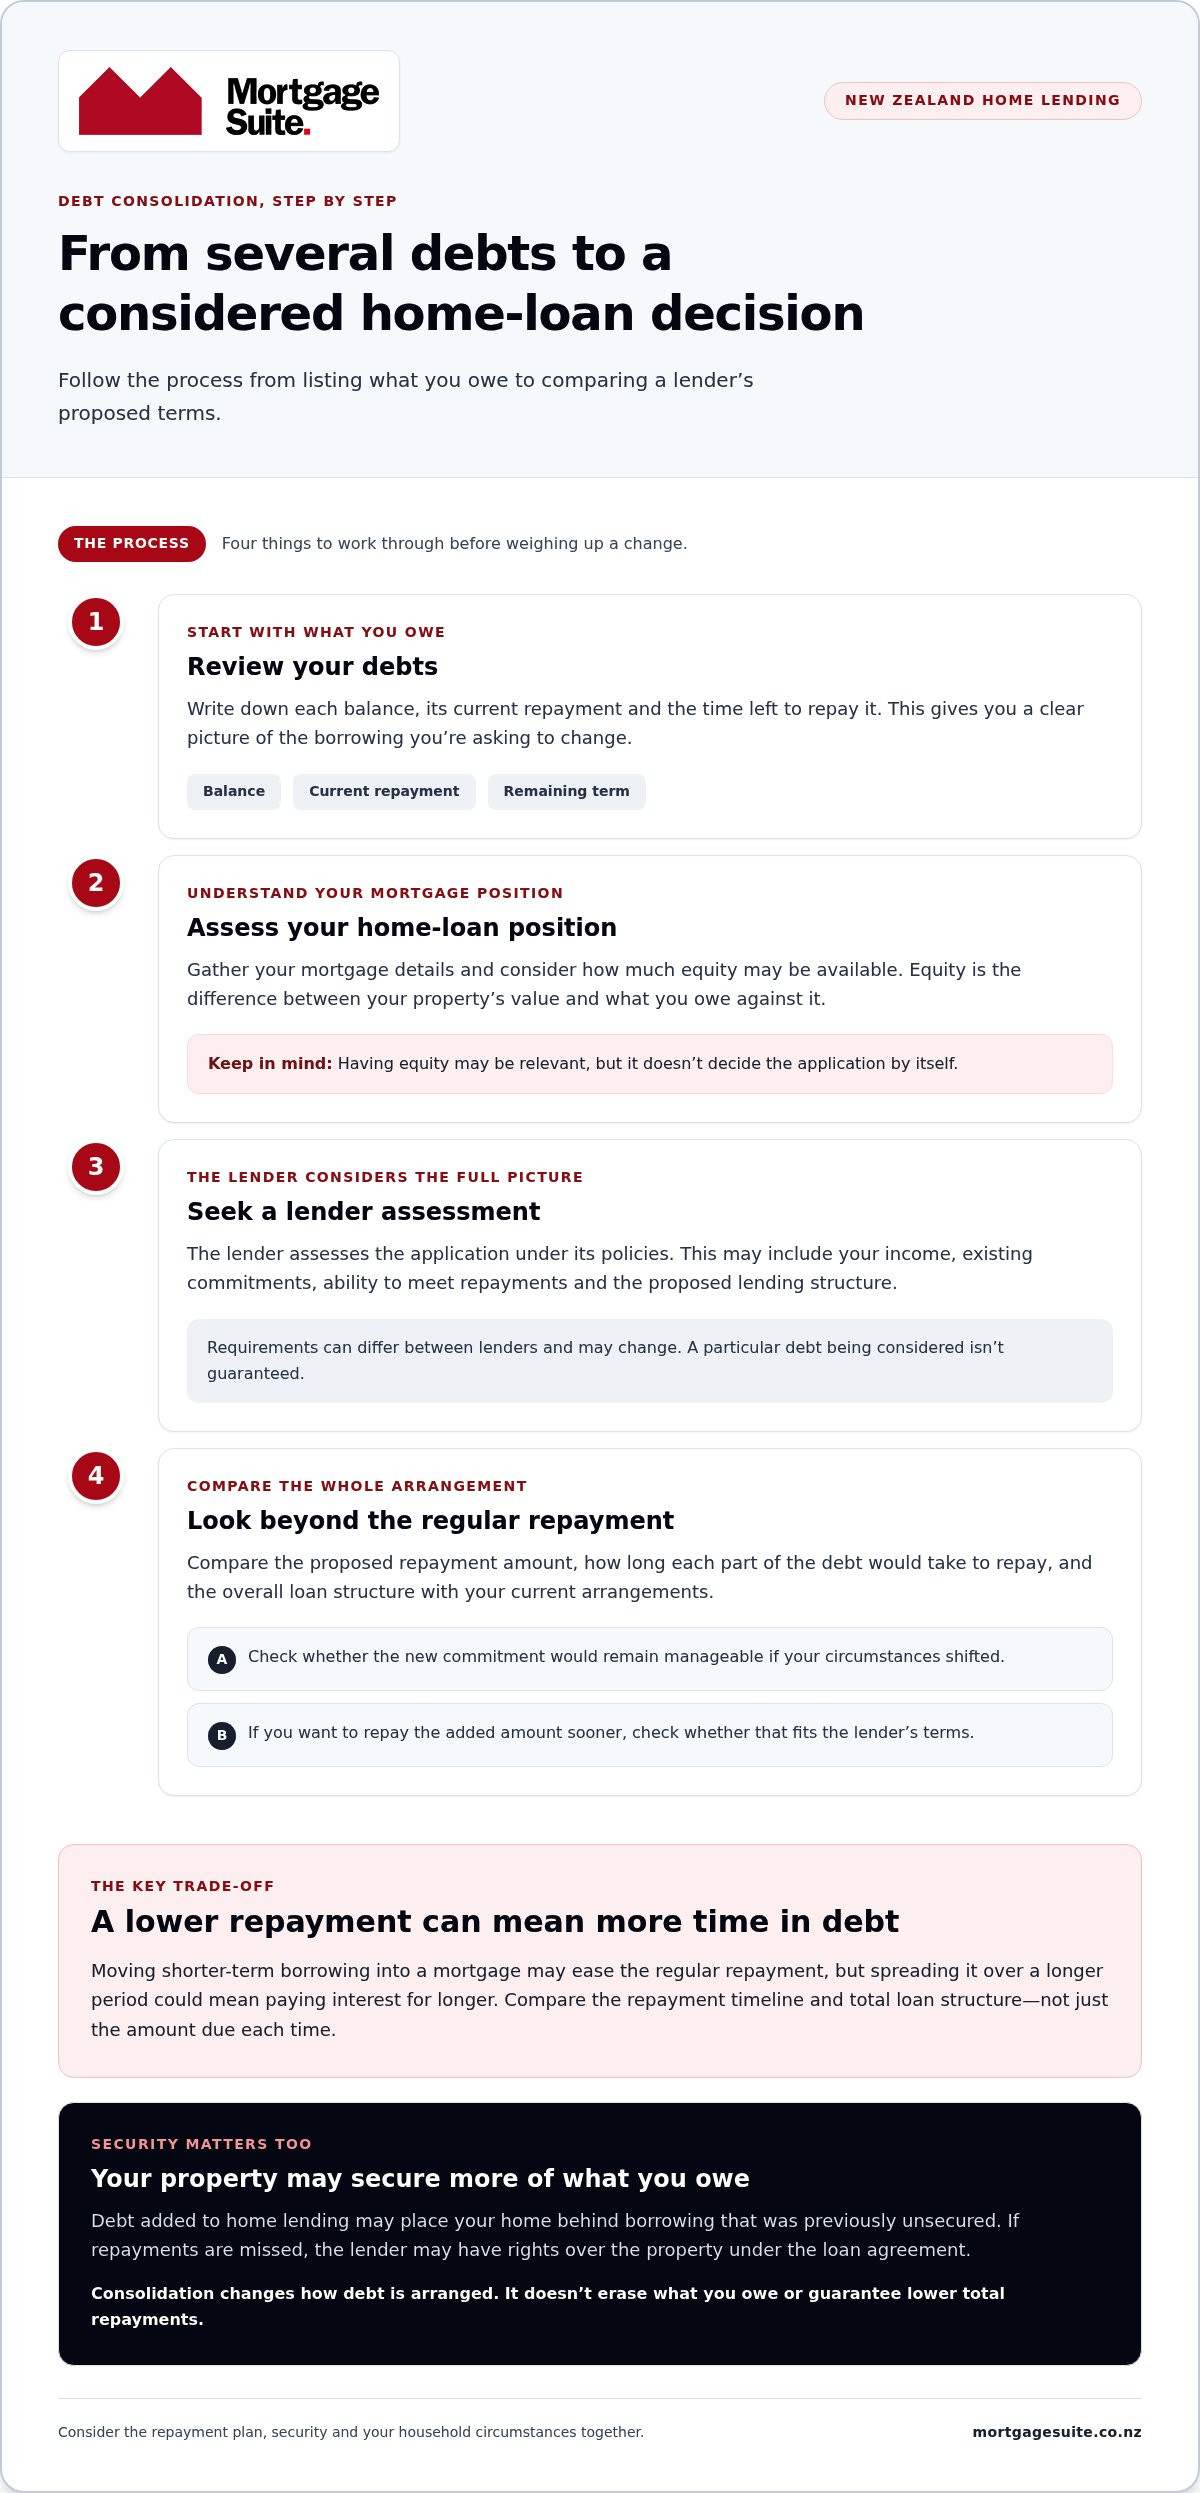
Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.
Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Cross-collateralisation and property loans in NZ: risks, options and next steps

A loan structure that looks simpler today can leave you with less control over your properties tomorrow. If you’re researching cross collateralization property loans nz, you may be weighing the convenience of linking properties against the risk that selling or refinancing one could affect another.

That uncertainty is understandable. When a lender uses more than one property as security, it may have a say in what happens to the linked properties, including how sale proceeds are used. The arrangement can sometimes help a loan proceed, but it may also limit your choices later.

This guide explains how linked property security works in New Zealand, what flexibility you could give up, and how it compares with keeping loans separate. You’ll also find practical questions to ask your lender before accepting a structure or changing an existing one, such as which properties secure each loan and what would happen if you sold or refinanced. With more than two decades of banking experience behind Mortgage Suite Ltd, the team understands how complex lending structures can feel. The aim is to help you make a considered choice that suits your wider property and borrowing plans.

Key Takeaways

  • With cross collateralization property loans nz, more than one property may secure lending, so check exactly which properties are linked to each loan.
  • Before selling or refinancing, ask your lender whether it needs to approve changes to the linked security and what conditions may apply.
  • Compare linked and separate loan arrangements against your plans, including how much flexibility you may want and how you prefer to manage your lending.
  • Use the article’s questions to prepare for a conversation with your lender or mortgage adviser, especially about releasing a property from linked security.
  • Mortgage Suite Ltd can help you assess how a proposed structure fits your wider property plans and negotiate with lenders, without promising a particular outcome.

What does cross-collateralisation mean for property loans in NZ?

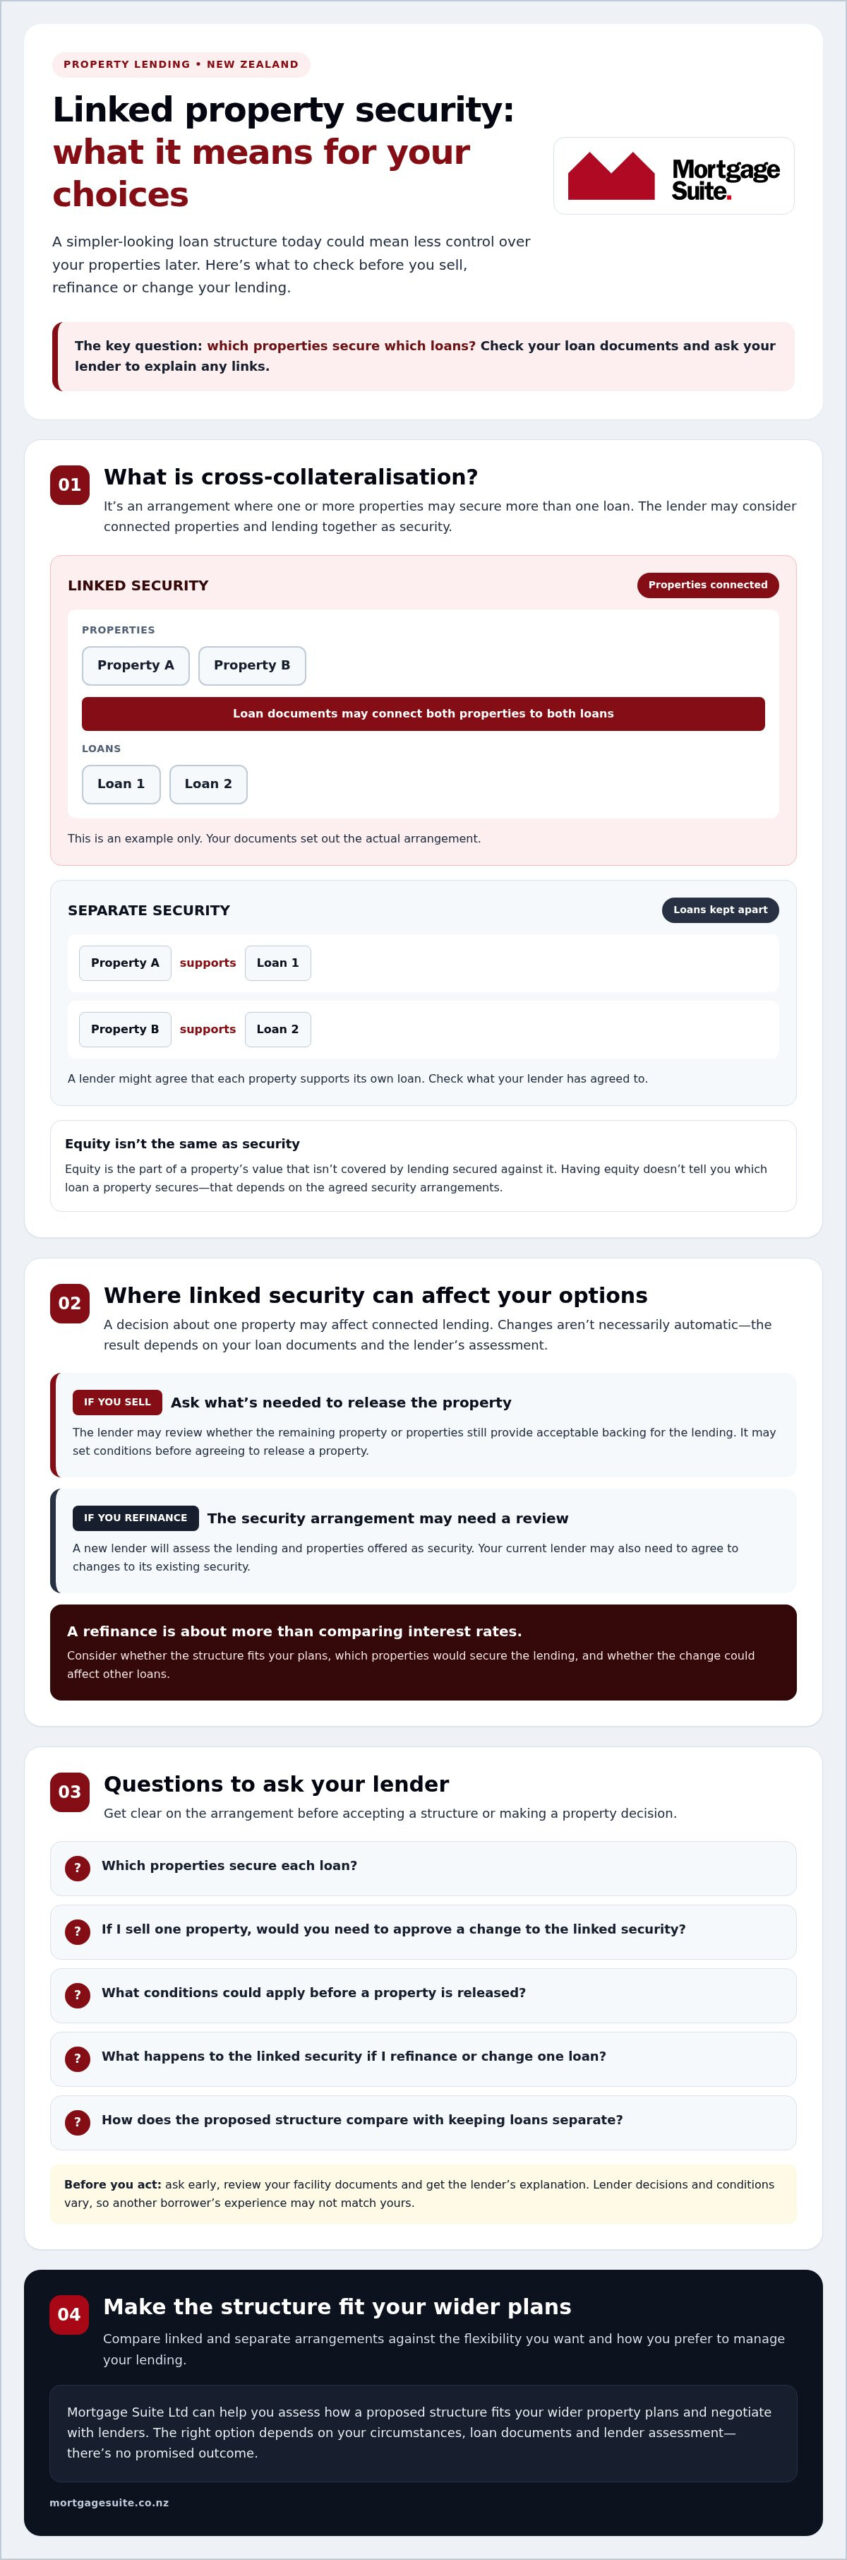
Cross-collateralisation is an arrangement where one or more properties may secure more than one loan. In everyday terms, a property gives the lender backing for the money it lends. If you’re looking up cross collateralization property loans nz, the key point is that the properties and loans may be connected, rather than each loan relying on just one property.

For a neutral overview of the underlying idea, see Cross-collateralization. The exact arrangement for your lending depends on your loan documents and what the lender has agreed to. Don’t assume that a property secures only the loan you associate it with; check the paperwork or ask your lender to explain it.

How can one property secure more than one loan?

Think of a borrower with two properties and two loans. The lender might agree that each property supports its own loan. Or the lending documents may connect both properties to both loans, so the lender considers them together as security. These are simple examples, not a guide to what your own documents say.

Linked security can involve more than one property, more than one lending facility, or both. Your loan documents set out the actual arrangement, so review them and ask the lender which properties support each loan if anything is unclear.

Is cross-collateralisation the same as using equity?

No. Equity is the part of a property’s value that isn’t covered by lending secured against it. A lender may consider available equity when assessing a borrowing request, but equity alone doesn’t tell you which property secures which loan. That depends on the agreed security arrangements.

For example, you may have equity in a property, but that doesn’t confirm whether it supports one loan or is linked to other lending as well. If you’re considering a residential property purchase or already have a rental property, the article Residential Investment Property Loans NZ offers wider context on borrowing for this purpose. For your own position, check the loan documents and ask the lender to clarify any links before making plans around a property.

How cross-collateralised property loans can affect your options

A property decision can affect connected lending because the lender may have agreed to rely on more than one property as security. If you want to sell, Refinance or change one loan, the lender may need to review the arrangement and approve a change to the linked security. The result depends on your facility documents and the lender’s assessment, so don’t assume a change will happen automatically.

What could happen if you sell one linked property?

Before you commit to a sale, ask the lender what must happen for the property to be released from the security arrangement. It may assess whether the remaining property or properties still provide acceptable backing for the lending. Depending on your loan terms and circumstances, the lender may set conditions before agreeing to release a property.

Ask for the requirements early, and check your facility documents alongside the lender’s explanation. Lender decisions and conditions vary, so another borrower’s experience may not match yours. Consumer Affairs also outlines How cross-collateralization works, including why connected security can affect a borrower’s choices.

Could linked security affect a refinance?

It can. If you’re considering moving your lending to another lender, the existing security arrangement may need to be reviewed as part of the process. The new lender will assess the lending it’s being asked to take on and the properties offered as security. Your current lender may also need to agree to changes to its existing security.

That means a Refinance involves more than comparing interest rates. Consider whether the proposed structure fits your plans, what properties would secure the lending, and whether you could manage the change without affecting other loans. If commercial lending is involved, Commercial Property Refinance NZ is a relevant topic to explore alongside advice from your lender or mortgage adviser.

In short, a decision about one property can affect connected loans, so confirm the conditions before you act. If you’re unsure how your current or proposed structure fits your plans, you can talk through your property lending options with Mortgage Suite Ltd. That conversation can help you identify what to ask your lender, without assuming a particular outcome.

Cross-collateralisation vs separate property loans: what should you compare?

There’s no single structure that suits every borrower. Linked security may make it simpler to manage several loans with one lender, while separate security can make each property’s role clearer. Your choice should reflect your plans and the lender’s assessment, not just how the arrangement looks on paper.

Use this table as a starting point. The practical details, including whether a property can be released or a loan changed, depend on the lender and your loan documents. Confirm each point for your own situation.

What to compare Linked security Separate security
Flexibility A change involving one property may require the lender to review the connected lending. Each property may have a clearer link to its own loan, but changes still depend on lender approval and loan terms.
Administration Coordinating lending with one lender may feel more straightforward, though the security links can be harder to keep track of. It may be easier to see which property supports which loan, but separate arrangements can mean dealing with more than one facility or lender.
Future plans Consider whether linked security fits your plans to sell, refinance or change a loan. Consider whether a more distinct arrangement fits plans to sell, refinance or change ownership of a property.
What to confirm Ask which properties secure each loan and what conditions apply to changing that arrangement. Ask whether separate security is available and what each loan would require.

Linked security can simplify how lending is arranged, but separate security may offer more clarity and control over each property. That’s the central trade-off to weigh up when comparing cross collateralization property loans nz.

When might linked security suit a borrower?

It may suit someone who values coordinating lending across several properties with one lender and expects to keep that structure in place. But convenience doesn’t guarantee approval or better terms. Suitability depends on your plans, the loan documents and the lender’s assessment. Ask what flexibility you would retain if your circumstances change.

When might separate security be worth discussing?

If you may sell, Refinance or change ownership of a property, ask whether separate arrangements could make each property’s role easier to understand. Separation may not be available or accepted in every case, so confirm the lender’s position before deciding. For questions about how lending documents relate to property matters, you can consult a property solicitor or find information through the New Zealand Law Society Property Law Section.

Cross-collateralisation and property loans in NZ: risks, options and next steps

Questions to ask before accepting or changing linked property security

Before you agree to link properties or change an existing arrangement, get a clear picture of what the lender is asking you to accept. If you’re comparing cross collateralization property loans nz, take these questions to your lender or mortgage adviser and ask for answers in plain English:

  1. Which properties secure each loan? Ask for a clear list of the properties and loans involved, including any lending facility you may have overlooked.
  2. What needs to happen to release a property? Ask what conditions apply, whether the lender must approve the release, and how it would assess the remaining security.
  3. What if I sell or Refinance? Find out how either step could affect the other loans and what you need to arrange before proceeding.
  4. How would future borrowing fit? Ask whether taking on another loan could change the security arrangement or affect your current lending.
  5. Can the security be changed later? Check the process and conditions for separating properties or changing which property supports a loan.
  6. Are there alternatives? Ask whether separate security is possible for your circumstances, and what trade-offs the lender sees.

What to check in your loan documents

Find the documents that describe your loans and the properties connected to them. Look for the sections covering security, changes, releases and lender consent. If a clause is unclear, ask the lender to explain what it means for your situation. Don’t rely on a verbal summary alone; make sure you understand what the documents say before agreeing to a change.

Who can help you assess the structure?

A mortgage adviser can help compare possible loan structures against your borrowing goals and future property plans. A solicitor can explain the legal obligations and property-security documents. These roles are different: an adviser can discuss lending options, while a solicitor can provide independent legal advice. This guidance isn’t a substitute for having a solicitor review documents that affect your property.

For straightforward mortgage learning, visit Mortgage Suite’s Mortgage School. If you’d like support weighing a proposed structure against your plans, explore your property loan options with Mortgage Suite. Getting clear answers first can help you make a considered decision and feel more confident about your next step.

How Mortgage Suite can help you assess property loan options in NZ

Linked security can feel hard to untangle, especially if you have several properties, existing loans and plans that may change. Mortgage Suite can help you look at the full picture: how your current lending is arranged, what you want to do with your properties, and whether you may need to borrow again later.

Mortgage Suite acts as your advocate and negotiator with lenders. It isn’t the lender or a guarantor, and no particular lending outcome can be promised. Depending on your circumstances, the team can consider options through mainstream and alternative lending channels, then help you understand what questions to put to the lender about the proposed structure. If you’re researching cross collateralization property loans nz, the aim is to make the options clearer before you decide what fits your plans.

What to prepare for a lending conversation

A few notes and documents can help make the discussion more useful. Gather what you have, and don’t worry if you’re still trying to find out how a particular loan is secured.

  • Loan documents and any recent lender correspondence that describe your current lending or security.
  • Basic details of each property involved, and which loans you think may be connected to it.
  • Your upcoming plans, such as buying another property, selling, refinancing or changing how a property is owned.
  • Questions about what the lender may require to change or release security, and what conditions need to be confirmed.

Being clear about both your current position and what you hope to do next gives an adviser a better starting point. Your lender’s requirements still need to be confirmed directly, and a solicitor can explain legal documents and obligations.

Explore your options with a mortgage adviser

A conversation can help you compare possible structures against your goals, identify trade-offs and work out which details still need an answer from your lender or solicitor. If your plans include a rental property, you may also want to read Residential Investment Property Loans NZ for related borrowing context.

Mortgage Suite was founded by Krish Krishna, who brings more than two decades of banking experience. If you’d like a calm discussion about how your existing lending and future property plans fit together, talk through your property lending options. There’s no need to have every detail sorted before you start.

Make your next property lending decision with clarity

Cross-collateralisation can make lending feel more straightforward, but linked security may affect your choices if you want to sell, Refinance or change a loan. Before deciding, check which properties secure each loan, what your lender requires to release a property, and whether the structure fits your future plans. Separate security may be worth discussing too, though it won’t suit every situation.

If you’re weighing up cross collateralization property loans nz, remember that the right structure depends on your circumstances and lender approval. Review your loan documents, ask for unclear terms to be explained, and seek independent legal advice about your obligations.

Mortgage Suite can help you compare lending options and prepare questions for lenders. Founded by Krish Krishna in 2000, the business draws on his more than two decades of banking experience and works with mainstream and alternative lending channels. Mortgage Suite can act as your advocate and negotiator, but it can’t promise a particular outcome.

Talk through your property lending options and take a considered next step. You don’t need every answer before starting the conversation.

Frequently Asked Questions

What is cross-collateralisation in property loans?

Cross-collateralisation is when a lender uses one or more properties as security for more than one loan. In plain English, the property gives the lender backing for the money it lends. For example, two properties could be linked to two loans rather than each property supporting only one loan. The actual arrangement depends on what you and the lender have agreed, so check your loan documents to see which properties secure each loan.

Is cross-collateralisation risky?

It can affect your flexibility, but the impact depends on your loan structure and plans. Linked security may help you coordinate lending with one lender, while reducing the independence of each property. A sale, refinance or change to one loan could involve a review of connected security. If you’re researching cross collateralization property loans nz, ask your lender what the arrangement means for your specific loans rather than assuming it will have the same effect for everyone.

Can I sell a property that is cross-collateralised?

You may be able to sell, but first check whether the lender needs to approve a change to the security arrangement. It may assess the remaining properties and lending before agreeing to release a property. What happens next depends on your loan documents, lender requirements and circumstances. Before committing to a sale, ask what conditions apply, what information the lender needs, and whether any connected loan arrangements could be affected.

Can I refinance one loan if my properties are cross-collateralised?

You can ask about refinancing one loan, but linked security may affect how the lender reviews the change. The existing lender may need to consider whether its security arrangement will change, and a new lender will assess the lending and security proposed. Requirements differ between lenders and loan structures. Before making plans, check your facility documents and ask both your current lender and mortgage adviser what steps or conditions may apply.

How can I find out which properties secure my loans?

Start with your loan documents and look for the sections that describe the security and the properties involved. If the wording isn’t clear, ask your lender to identify which property secures each loan and explain the arrangement in plain English. A mortgage adviser can help you understand the lending structure, while a solicitor can explain legal wording and obligations. Don’t rely on assumptions based on which property you associate with a particular loan.

Can I ask a lender to separate cross-collateralised loans?

Yes, you can ask whether the lender will separate the loans or change which properties secure them. Whether it agrees depends on the lender, your loan documents and your circumstances. The lender may assess the proposed structure and the security that would remain for each loan. Ask what information it needs, what conditions apply and whether the change could affect other lending. A mortgage adviser can help you compare options, but the lender makes the decision.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Second mortgage for business in NZ: how it works in 2026

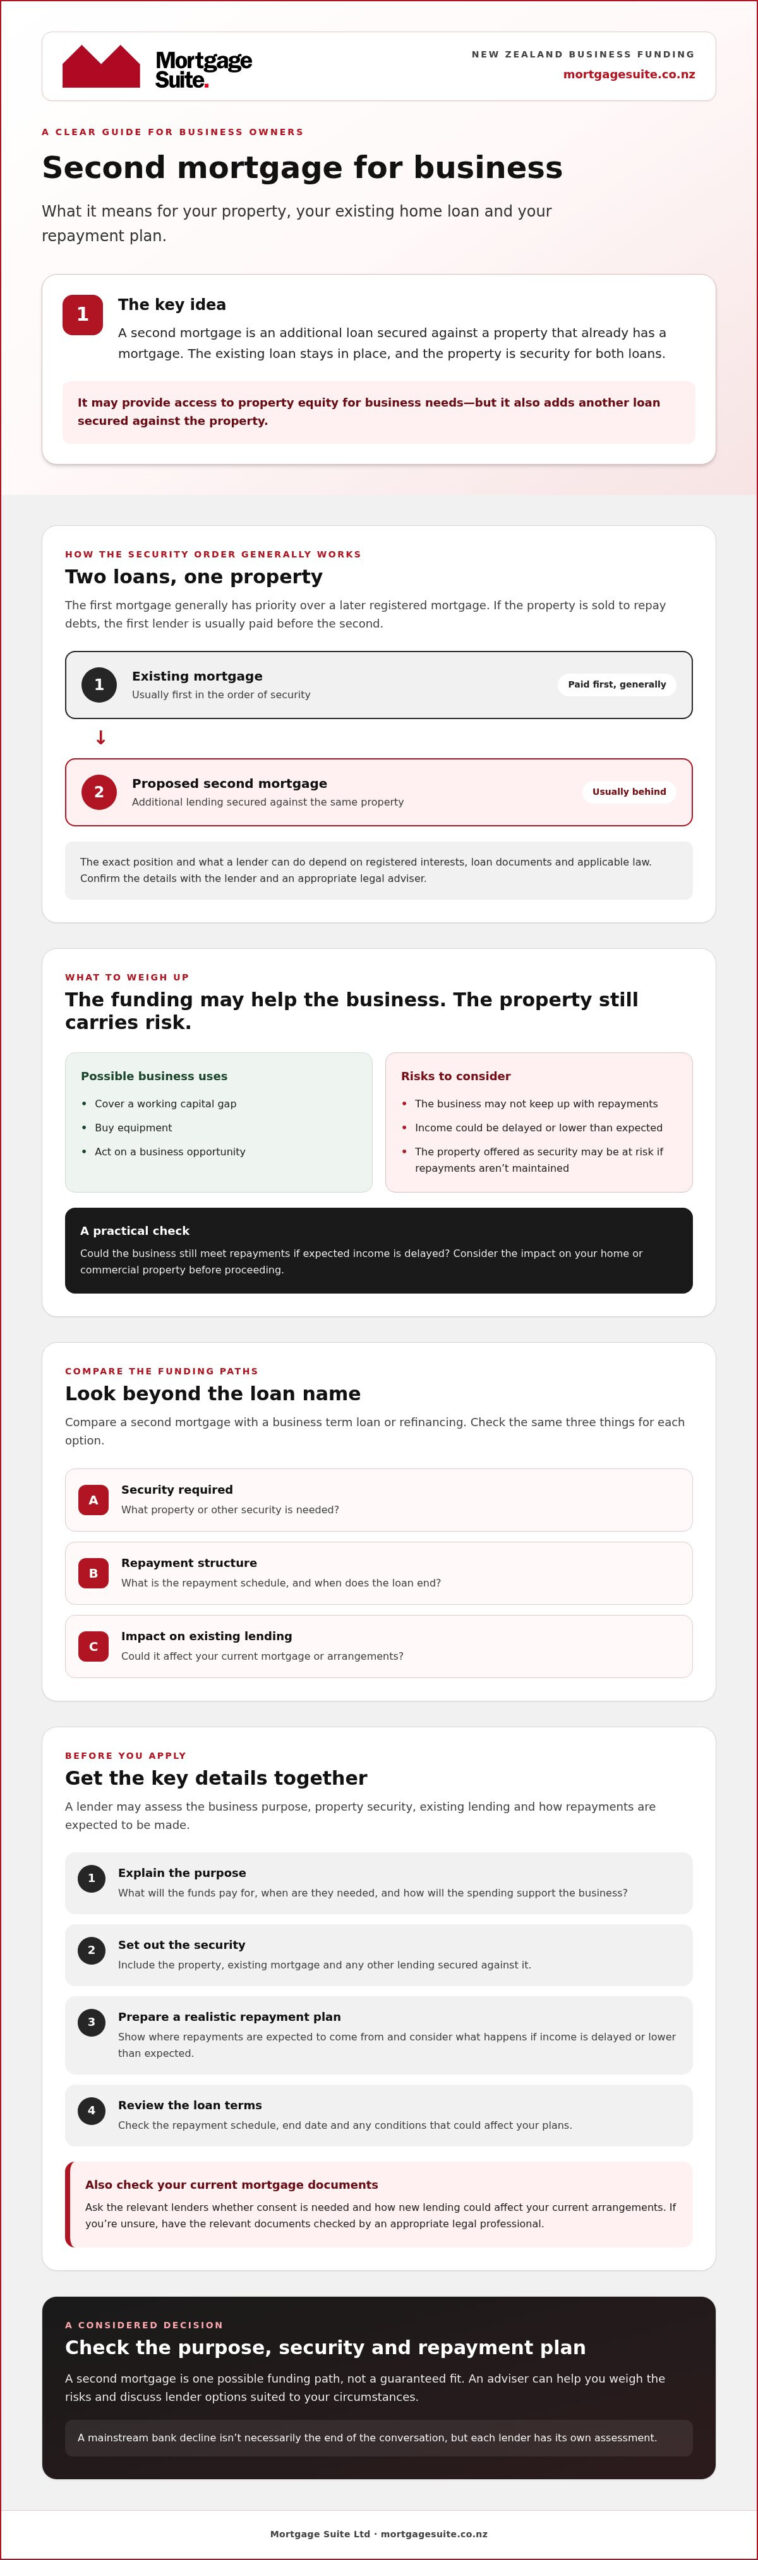
Could business funding put your home at risk, even if you already have a mortgage? For some Kiwis, a second mortgage for business NZ may provide access to property equity without replacing an existing home loan. But it adds another loan secured against the property, so weigh the funding need against the security and repayment risks.

It’s understandable to feel cautious. You may be comparing a second mortgage with a business loan or refinancing, while considering whether your business income and circumstances will meet a lender’s requirements. If the property has to be sold to repay debt, the first mortgage lender generally has priority over the second mortgage lender. Understand how that could affect your options and have a realistic repayment plan before proceeding.

This guide explains how a second mortgage works in 2026, what lenders may assess and what information to prepare. It also sets out questions to ask about repayments, property security and your plan to repay the loan, so you can compare funding paths and make a considered decision.

Key Takeaways

  • A second mortgage for business NZ adds lending secured against property that already has a mortgage, so check how the existing loan’s priority may affect your options.
  • Before proceeding, consider whether the business can manage repayments and what could happen to the property if it can’t.
  • Compare a second mortgage with a term loan or refinancing by checking the security required, repayment structure and impact on existing lending.
  • Prepare accurate business financial information, details of existing lending and a clear plan for repaying the loan.
  • An adviser can help you weigh up the risks and discuss lender options suited to your circumstances, without guaranteeing approval.

What is a second mortgage for business in NZ?

A second mortgage for business is an additional loan secured against property that already has a mortgage. The property could be a home or business property, and the funds are intended for business needs. The second mortgage sits behind the existing mortgage in the order of security. You can read a neutral overview of what a second mortgage is, then check how a particular lender would structure and secure the loan.

In general, the first mortgage has priority over a later registered mortgage. If the property had to be sold to repay debts, the first lender would usually be paid before the second mortgage lender. The exact position can depend on registered interests and the loan documents, so confirm the details with the lender and an appropriate legal adviser before proceeding.

Using the funds for a business doesn’t change the fact that the property is security for the loan. If repayments aren’t maintained, the property offered as security could be at risk. Weigh the business purpose against the possible impact on your home or commercial property, and consider whether the business could still meet repayments if expected income is delayed.

How does a second mortgage differ from a first mortgage?

A first mortgage is usually the main loan secured against a property. A second mortgage is separate lending added while that first mortgage remains in place. The second lender’s position behind the first may affect how it assesses the property, existing lending and available security. Ask how the proposed loan would be recorded and what could happen if repayments fall behind.

Don’t assume the order or enforcement process based on a general explanation alone. Ask the lender to explain its terms and have the relevant documents checked if you’re unsure.

What business needs might prompt this type of lending?

A business owner might explore a second mortgage to cover a working capital gap, buy equipment or act on a business opportunity. These are examples of possible purposes, not a promise that a lender will approve the application. The lender will consider what the funds are for alongside the property security and the borrower’s wider circumstances.

Business-purpose borrowing is different from a home loan taken out to buy or refinance a home, even if the home is offered as security. Be specific about how the funds will be used and where repayments are expected to come from. If a mainstream bank has declined, that isn’t necessarily the end of the conversation. Other lender pathways may be worth discussing, though each has its own assessment.

How does a business second mortgage work, and what is at risk?

Taking out a second mortgage involves more than showing that a property has equity. The lender needs to understand what the business will use the funds for, what property will secure the loan, how existing lending affects that security, and how repayments are expected to be made. Review the proposed terms carefully, including the repayment schedule and what happens if payments are missed.

When property secures business borrowing, the borrower remains responsible for repayments and the property may be at risk if they aren’t made. That’s true even when the loan is intended to support business growth rather than a personal purchase.

  • Explain the purpose: Be ready to describe what the funds will pay for, when they are needed and how the spending supports the business.
  • Review the security: Discuss the property, existing mortgage and any other lending secured against it.
  • Test the repayment plan: Consider how the business will meet repayments if income is delayed or lower than expected.
  • Check the terms: Ask about the repayment schedule, the loan’s end date and any conditions that could affect your plans.

How does the second mortgage sit alongside existing lending?

More than one loan can be secured against the same property. As a general guide, the first registered mortgage has priority over a later one. If the property is sold to repay debts, the first lender is generally paid before the second. The exact position and any steps a lender can take depend on the registered interests, loan documents and applicable law.

Check your existing mortgage documents and ask the relevant lenders whether consent is needed and how the new loan could affect your current arrangements. A qualified legal professional can explain the implications for your particular circumstances. Don’t rely on a general article to settle those details.

What happens if the business cannot keep up with repayments?

If repayments fall behind, arrears can build and the lender may take steps under the loan terms and applicable law. The outcome depends on the circumstances, so don’t assume every lender will respond in the same way. Because the property secures the borrowing, it could ultimately be at risk.

If repayment pressure appears, contact the lender or your adviser early to discuss the situation and possible next steps. For consumer credit, the Commerce Commission explains the transfer of responsibility for regulation of consumer credit. Whether a business-purpose loan falls under consumer credit rules depends on the circumstances, so confirm what applies to your loan.

If you’re weighing up a second mortgage for business NZ, Mortgage Suite can help you discuss the funding need and possible lender pathways. Its mortgage learning resources explain lending terms to help you prepare for a conversation.

Second mortgage vs business loan or refinance: which path fits?

The right option depends on what the business needs, whether property can be offered as security, your existing lending and how repayments could fit your cash flow. A second mortgage for business NZ is one path to discuss, but it isn’t automatically the best fit. Compare the security and repayment structure, the impact on current lending and the consequences of missed payments, not just the amount you may be able to borrow.

Option Security Common use Questions to ask
Second mortgage Property that already secures an existing mortgage. Seeking further business funds while keeping existing lending in place. How does it sit alongside the current mortgage? What property is at risk, and how will repayments work?
Business term loan Depends on the lender and loan terms. Ask whether property or other security is required. A business funding need with a lump sum and a defined repayment schedule and end date. What security is required? How often are repayments due, and when must the loan be repaid?
Refinance Usually involves new lending secured against property or other agreed security; confirm the proposed arrangement. Replacing or restructuring existing lending, often with a different deal or lender. What happens to the existing loan terms? Will the new structure meet the business need and repayment plan?

When might a second mortgage be worth exploring?

You might raise this option if you want to seek extra funds while keeping your current mortgage in place. That’s a discussion point, not a recommendation or a sign that you’ll qualify. Ask the lender to explain how the existing loan affects its assessment, and compare proposed repayments with the business’s expected cash flow. If a mainstream lender’s criteria don’t fit, the Mortgage School guide to lending options may provide further context.

When should you compare a business loan or Refinance instead?

Compare a business loan if you want to understand whether its security and repayment structure could suit your business without adding another mortgage to a property. Terms vary between lenders, so check the details rather than assuming the loan is unsecured. Refinance means replacing or restructuring existing lending, often with a different deal or lender. It may be worth comparing if you’re open to changing your current arrangement. Mortgage Suite can help you discuss business and commercial finance pathways, but the lender will assess your circumstances.

Before choosing, ask each lender to set out the security, repayment schedule, loan end date and implications for existing lending. Mortgage Suite’s Mortgage School learning resources offer plain-English explanations of lending terms to help you prepare those questions.

Second mortgage for business in NZ: how it works in 2026

How to prepare before applying for a business second mortgage

A clear application starts with a clear picture of the business need and how the loan could be repaid. Before discussing a second mortgage for business NZ, work through these steps:

  • Define the purpose: Set out what the funds would pay for and how the spending supports the business.
  • Gather your records: Collect current business accounts and income information, along with details of existing loans.
  • Review the property: Note which property may be offered as security and share relevant ownership or mortgage details.
  • Plan repayments: Map likely repayments against realistic business cash flow and consider how you’d manage if income changed.

Preparation helps a lender understand your request, but it doesn’t guarantee approval. The property, business income and lender criteria all need individual assessment. Accurate records make the discussion clearer, particularly if your income or business circumstances don’t fit a straightforward pattern.

What information should a business owner gather?

Start with up-to-date business accounts, income records and a short explanation of the funding purpose. Add details of current loans, repayments and any property you may offer as security. Be ready to explain how the business expects to use the funds and where repayments will come from. Requirements vary, so ask the lender or adviser for the exact document list before you apply.

Accuracy matters. If figures have changed or trading has been uneven, explain that rather than leaving gaps for the lender to interpret. A broker may help organise the information and discuss which lender pathways could suit your circumstances, though the lender makes its own assessment.

How can you test whether repayments are manageable?

Set out expected repayments alongside the business’s regular income and commitments. Allow for ordinary business needs, existing debt repayments and household commitments where relevant. Then test a less favourable scenario: what if a customer pays late, sales fall or an unexpected business expense arrives? If the plan only works when everything goes smoothly, revisit the amount or structure before proceeding.

The Mortgage Suite calculator may help with general repayment planning. It isn’t a quote or assessment for a business loan, so confirm actual terms and repayments with the lender.

For help discussing business funding needs and possible lending pathways, contact Mortgage Suite about business finance.

Choosing your next step with a New Zealand business finance adviser

Before moving ahead, check that the proposed borrowing matches a real business need and a repayment plan you can explain. Weigh up the security being offered, the risk to the property and alternatives such as a business loan or changing existing lending. A second mortgage for business NZ may be worth discussing, but the right path depends on your circumstances and the lender’s assessment.

An adviser can help organise the facts, present your situation clearly and discuss possible lender options. That support can be useful if your income or business history doesn’t fit a mainstream bank’s usual approach. But advice can’t guarantee a lender will make an offer, set particular terms or approve an application.

What should you ask before accepting an offer?

Take time to understand the offer before you commit. Ask which property secures the borrowing, how repayments are scheduled and when the loan ends. Make sure you understand the conditions and what the lender may do if repayments are missed. If any legal wording or implications are unclear, consider getting independent legal advice before signing.

Then compare the proposed structure with your business plan and other funding paths. Would the repayment plan still make sense if income is delayed? Does the loan solve the need you identified, or could another arrangement better fit your longer-term plans? Ask the lender to explain anything you’re unsure about.

How can Mortgage Suite help you assess possible pathways?

Mortgage Suite arranges business and commercial finance, as well as second-tier lending for situations that may not fit mainstream bank criteria. Its founder, Krish Krishna, has more than two decades of banking experience. A discussion can help you set out the funding purpose, existing lending and repayment plan, then consider which lender pathways may be worth exploring. Each lender makes its own assessment, so there’s no guaranteed outcome.

You can learn more about Mortgage Suite’s background and approach and read client reviews of Mortgage Suite as part of your research.

Before speaking with an adviser, it may help to have your funding purpose, current loan details and repayment plan to hand. You can then use the discussion to consider possible next steps without committing to proceed.

Make your next business funding decision with care

A second mortgage for business NZ may be one way to seek business funds, but it also puts property security and repayment commitments in the picture. Before proceeding, be clear about what the funds are for, how repayments could fit your business cash flow, and whether a business loan or refinance might better suit your needs.

Mortgage Suite facilitates business, commercial property and second-tier lending solutions, including for borrowers whose circumstances may not fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience to lending conversations. That experience can help you discuss your circumstances and possible lender pathways, but it can’t guarantee an offer, particular terms or approval.

If you’re ready to explore your options, talk through your business lending options with Mortgage Suite. A clear conversation can help you decide what to consider next, at a pace that feels right for you.

Frequently Asked Questions

What is a second mortgage for business in New Zealand?

A second mortgage for business in New Zealand is an additional loan secured against property that already has a mortgage. The property could be a home or business property, depending on the lender’s requirements. The existing mortgage generally has priority over the later one, but the details can depend on registered interests and loan documents. A second mortgage for business NZ still puts the property at risk if repayments aren’t maintained.

Can I use a second mortgage to fund my business?

Yes, a second mortgage may be used to fund a business purpose, such as working capital or a business opportunity, if a lender is willing to offer that structure. The lender will assess the purpose of the borrowing, the property offered as security and your circumstances, including how repayments are expected to be made. Using a home as security doesn’t make the borrowing a home loan, so ask the lender to explain the proposed terms.

Can I get a second mortgage if my bank has declined my business loan?

Possibly, but a bank decline doesn’t mean another lender will approve a second mortgage. Lenders may assess applications differently, and some specialist or second-tier lenders consider situations that don’t fit mainstream bank criteria. They’ll still assess the security, business purpose, repayment plan and your wider circumstances. A finance adviser can help you understand potential lender pathways, but can’t promise an offer or approval.

What property can be used as security for a business second mortgage?

A lender may consider residential or business property, but the type of property it accepts depends on its criteria and the details of the application. Existing mortgages and other claims registered against the property can affect the assessment. Before applying, gather information about the property and current lending, then ask the lender whether it may be acceptable security and whether any existing lender’s consent is needed.

Is a second mortgage riskier than a business loan?

It depends on the security and terms of each option. A second mortgage is secured against property, so missed repayments could put that property at risk. A business loan may have a different security arrangement, but it isn’t automatically unsecured or lower-risk. Compare the repayment schedule, loan end date, security and consequences of missed payments for each offer, and consider how the structure fits your business plan.

How much can I borrow with a second mortgage for business?

There’s no set amount that applies to every borrower. A lender will assess the property and existing lending, the business’s financial position, the requested purpose and its own criteria. The amount offered, if any, will depend on that individual assessment. Prepare accurate business income records and details of current loans, then ask the lender to explain how it arrived at any proposed amount and repayment terms.

What happens if I cannot repay a business second mortgage?

If you can’t make repayments, contact the lender as early as possible and explain what’s changed. Missed payments may lead to arrears and other steps under the loan terms and applicable rules. Because the loan is secured against property, that property could ultimately be at risk. Ask the lender or an adviser about your options and seek independent legal advice if you’re unsure what the loan documents mean.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

What if the bank that recently said “no” to your renovation top-up isn’t actually the best place for your home loan anymore? It’s incredibly frustrating to watch high interest rates eat into your weekly budget while you feel stuck with a lender that doesn’t seem to value your loyalty. You aren’t alone in feeling this way, especially as you look to refinance mortgage nz in a 2026 market where the average one-year fixed rate is sitting around 5.89%.

We’re here to help you take back control. This guide shows you exactly how to swap your current loan for a better deal, unlock the value you’ve built up in your home, and save thousands of dollars in interest. We’ll cut through the confusion surrounding break fees and legal costs, giving you the confidence to make a move that actually benefits your bottom line. You’ll discover how to find a lender that fits your life now, whether you need extra cash for a kitchen makeover or simply want lower monthly repayments. We’ll preview the practical steps to switching and explain how having a seasoned pro in your corner makes the entire process feel like a breeze.

Key Takeaways

  • Learn why moving your home loan is similar to switching phone providers, but with the potential to save you thousands in interest over the long run.
  • Discover how to navigate break fees and secure a “cash carrot” from a new lender to help cover your legal and moving costs.
  • Find out how to refinance mortgage nz by using a pro to negotiate with both mainstream banks and flexible alternative lenders who are more likely to say “yes”.
  • Understand how to use your house wealth to tidy up high-interest debts like car loans and credit cards into one easier payment.
  • Get a straightforward look at the 2026 market outlook so you can time your switch perfectly for maximum monthly savings.

What exactly is refinancing and why should Kiwis bother?

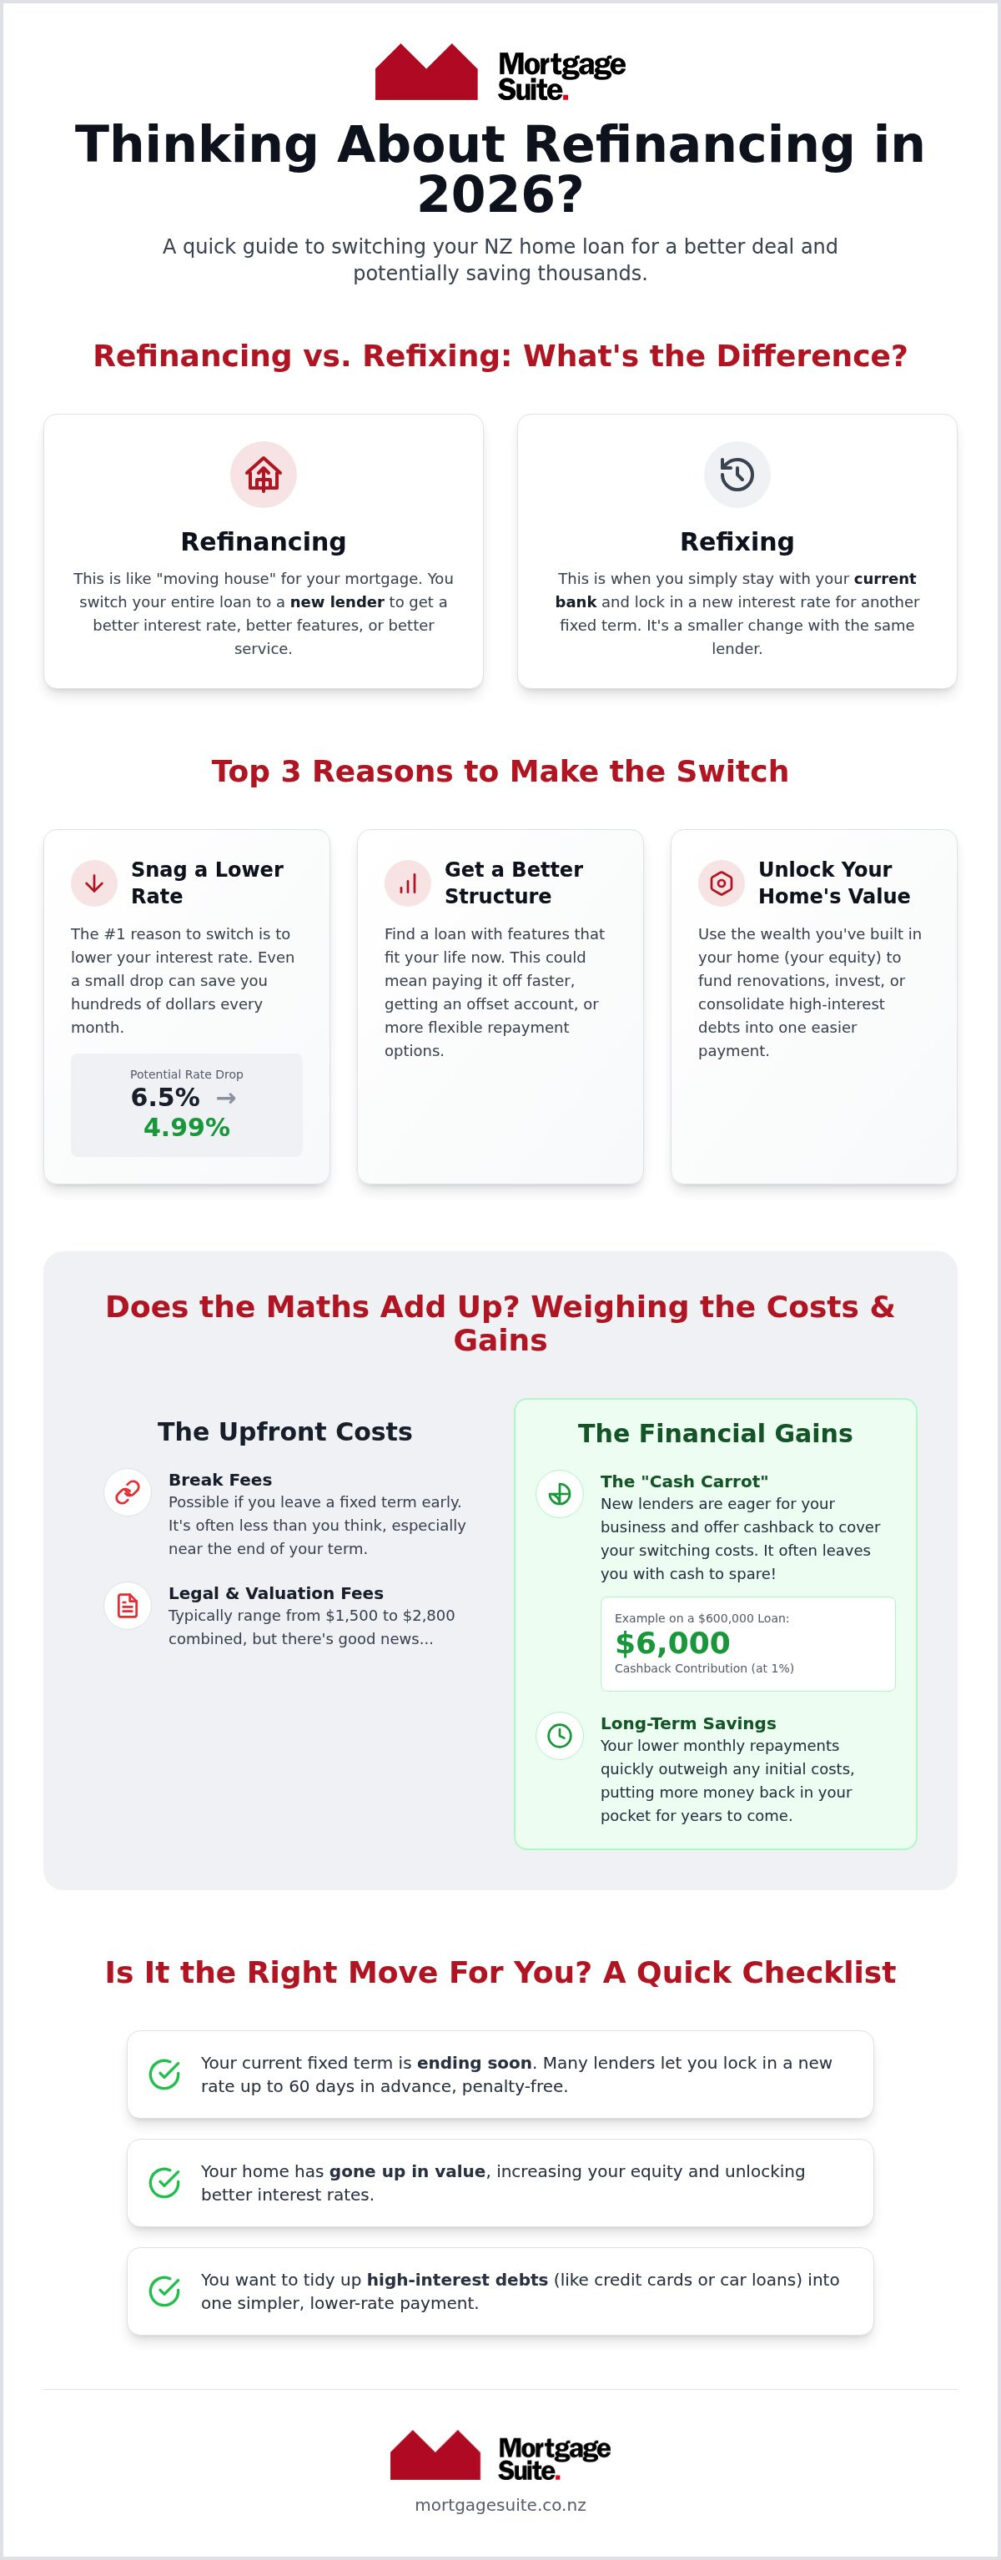
Think of your home loan like your mobile phone plan. Every year or two, you probably check if another provider has a better deal on data or a cheaper monthly cost. Refinancing is essentially the same thing, just with much bigger numbers and more zeros. When you decide to refinance mortgage nz, you’re simply moving your debt from one lender to another to get a better deal on your interest rate or loan features.

To understand the basics, you can look at What is refinancing to see how it works globally; however, for us here in New Zealand, it’s about making sure your bank is still working as hard as you are. Many people confuse this with “refixing”. Refixing is when you stay with your current bank and just choose a new interest rate for another year or two. Refinancing is “moving house” for your loan to find a more competitive partner that actually fits your current goals.

Right now, 2026 is a cracking time to look at your options. With the Official Cash Rate sitting at 3.25% and banks offering one-year fixed rates around 4.99%, the market has shifted significantly from the highs of previous years. If you’ve been stuck on a rate above 6.5% from a term you fixed in 2023 or 2024, switching now could save you a small fortune in interest costs over the next few years.

The main reasons to make the switch

Most homeowners move for one of three reasons. First, snagging a lower interest rate is the most common goal. Even a small drop can keep hundreds of dollars in your pocket every month. Second, you might want to change how you pay off the debt. You could switch to a structure that helps you become debt-free faster without increasing your stress levels. Finally, you might just want better service. If your current bank’s mobile app is clunky or they don’t offer offset accounts to help you save on interest, it’s time to look elsewhere. You can learn more about these different loan structures at our Mortgage School.

Is it the right move for you?

This path makes the most sense if your current fixed term is nearly up. If you’re within a few months of your rate expiring, you can start the conversation now to avoid being rolled onto a high floating rate. It’s also a winner if your home has gone up in value. This increase builds your equity, which is simply the bit of the house you actually own versus what the bank owns. If your house is worth $800,000 and you owe $500,000, you have $300,000 in equity. Having more equity often unlocks better rates and more flexible options for things like renovations or debt consolidation.

The real costs and savings of switching banks

Switching banks isn’t just about signing a new piece of paper; it involves a bit of maths to ensure the move actually makes sense for your wallet. While the goal is to save money, you have to account for the upfront costs to find your “break-even” point. This is the moment where your monthly interest savings finally outweigh the fees you paid to make the jump. For most Kiwis looking to refinance mortgage nz, this point arrives much sooner than they expect.

Understanding break fees and early exit costs

If you’re currently on a fixed-rate term, your bank might charge a break fee if you leave early. Banks charge this because they’ve already “bought” the money for your loan at a specific price. If market rates have dropped since you locked in, they lose money when you leave. To get an estimate, you can simply ask your current bank for a “break quote”. It’s often smaller than people fear, especially if you’re near the end of your term.

Timing is your best friend here. A helpful strategy is the “60-day rule”, where many lenders allow you to lock in a new interest rate up to two months before your current term expires. This lets you secure a better deal for the future without paying a cent in early exit fees today. By watching the market closely, you can time your move to avoid the biggest costs while still snagging a lower rate.

You also need to factor in the legal side. Because you’re moving your loan to a new lender, a lawyer must update the title of your property. These legal fees typically range from $800 to $1,600. In some cases, a bank might also ask for a registered valuation, which can cost between $700 and $1,200, though many lenders in 2026 now accept automated digital valuations for standard homes.

Cash incentives and legal subsidies

The good news is that banks are incredibly hungry for your business in 2026. To lure you away from their competitors, they often dangle a “cash carrot” in the form of a cashback offer. These incentives can be as much as 1% of your total loan amount. On a $600,000 mortgage, that’s $6,000 landing in your bank account, which easily covers your legal fees and any small break costs with plenty left over.

Just keep an eye on the “clawback” clause. Most banks require you to stay with them for a set period, usually three to four years, to keep that cash. If you move again too soon, they’ll ask for a portion of it back. You can use our mortgage calculator to see how these incentives and lower rates stack up against your current payments. Often, the savings are so significant that the move pays for itself in just a few months. If you’re feeling unsure about the numbers, talking to an expert can help you see if a switch is truly a winner for your specific situation.

Bank vs. Non-Bank lenders: finding your best fit

When you look to refinance mortgage nz, your first thought is probably your current bank or one of their big rivals. Mainstream banks love “standard” borrowers. If you have a steady salary, a large deposit, and a perfect credit history, they’ll usually roll out the red carpet. However, they aren’t the only game in town. In 2026, more Kiwis than ever are finding that alternative lenders, often called 2nd tier lenders, offer the flexibility they actually need.

These non-bank lenders are reliable, regulated, and often more approachable than the big institutions. They account for over 10% of new home loans in the current market because they don’t just rely on rigid computer algorithms to make decisions. Instead, they take a more human approach to your application. We help you navigate both worlds to ensure you aren’t just getting a loan, but finding a partner that suits your long-term goals.

When the big banks say “no”

Banks can be incredibly picky. If you’ve recently started a business, changed careers, or have a slightly “messy” bank statement, a mainstream lender might look at your application and simply say “no”. This is especially true for self-employed Kiwis who might have a healthy business but don’t have the two years of perfect financial records that big banks demand. 2nd tier lenders look at your real-life income and the bigger picture of your financial health. You can read more about how this works in our guide on 2nd tier lenders in NZ.

The benefits of a more flexible lender

Speed is a huge factor. If you’re in a rush to get your refinance mortgage nz sorted to secure a specific interest rate, these lenders can often move at a pace that big banks can’t match. Their approval processes are streamlined because they aren’t bogged down by the same corporate layers. They are also much more willing to lend on unique properties. If your home is a bit unconventional or has a smaller floor area than a standard suburb house, a big bank might shy away. Flexible lenders see the value where others don’t. We’ll negotiate with these providers on your behalf to make sure you get a fair dinkum deal that balances a competitive rate with the breathing room you need.

Refinance Mortgage NZ: Your 2026 Guide to Switching and Saving

Unlocking your home value: equity and debt consolidation

Equity is your greatest financial asset, often referred to as your “house wealth”. It’s simply the gap between what your property is worth in the current market and what you still owe the bank. With the national median dwelling value sitting at $808,187 in 2026, many Kiwis have built up significant equity without even realising it. When you refinance mortgage nz, you can tap into this wealth to improve your lifestyle or tidy up your finances.

Turning high-interest debt into low-interest mortgage debt

One of the smartest reasons to move your loan is to consolidate separate bills. It’s common to have a car loan at 12% or a credit card sitting at a painful 20% interest rate. By rolling these into your mortgage, which currently averages around 5.89% for a one-year fixed term, you can drastically reduce your monthly outgoings. Instead of juggling multiple due dates, you have one easy monthly payment.

There is a catch, though. While the interest rate is lower, you don’t want to pay off a holiday or a car over the next 25 years. We always recommend setting up a separate “slice” of your mortgage for this consolidated debt and paying it off as quickly as possible. This ensures you’re actually saving money rather than just spreading the cost over a longer period.

Using equity for investment or renovations

If you’ve been dreaming of a new kitchen or an extra bedroom, a home loan top-up is often much cheaper than taking out a personal loan. Refinancing allows you to borrow against your equity at home loan rates to fund these improvements. This not only makes your home more comfortable but can also increase its total value. For those looking even further ahead, you might have enough equity to start an investment portfolio. If you’re curious about how this works, check out our residential investment property guide.

While unlocking equity is exciting, it’s vital not to “stretch the friendship” with your budget. Borrowing more means higher repayments, so we always look at your long-term stability first. If you want to see how much equity you could safely unlock, reach out to our team for a personalised review of your numbers. We’ll help you understand exactly where you stand before you make any big decisions.

How to organise your refinance with a pro in 2026

Navigating the banking world alone is like trying to fix a complex plumbing issue without a wrench. You might get there eventually, but it’s often messy and far more stressful than it needs to be. When you choose to refinance mortgage nz in 2026, the market is moving at a rapid pace. The Reserve Bank held the Official Cash Rate at 3.25% recently, and while some economists think another small rise might pop up before Christmas, banks are currently hungry for your business with one-year rates sitting around 4.99%.

A professional broker doesn’t just look at the interest rates; they look at the bank’s “appetite” for your specific situation. Some lenders are currently leaning heavily into first-home buyers, while others are opening their doors wide for property investors. We know which doors are open and which ones are stuck, saving you hours of paperwork and the headache of a “no” that could have been a “yes” elsewhere. This insight is the most straightforward way to refinance mortgage nz and take control of your financial future.

The Mortgage Suite advantage

Our team brings over 20 years of banking and brokerage experience to the table. This means we’ve seen every possible market cycle, from the record highs of previous years to the recovery we’re seeing now. We act as your advocate and dedicated negotiator, ensuring the banks offer their absolute best “cash carrot” and interest rates. You don’t have to spend your lunch breaks on hold with a call centre. We handle the hard yards, providing a steady hand while you focus on your life. If you want to see how we’ve helped other Kiwis find a better deal, take a look at our reviews page.

Next steps to get your mortgage sorted

Getting started is a piece of cake. Before we have our first chat, it helps to have a few things ready to go. Gather your most recent payslips and three months of bank statements to show your current income and spending. It’s also a great idea to think about your big goals for the next three to five years. Are you planning to start a family, renovate the bathroom, or perhaps buy an investment property?

Once you have those bits and pieces together, simply book a chat with us to see what’s possible. We’ll review your situation, explain your options without any confusing jargon, and map out a clear path to your new loan. It really is that easy to see if we can keep more of your hard-earned money in your pocket this year.

Take the next step toward a better home loan

Refinancing isn’t just about chasing a lower number; it’s about making your money work harder for your family. Whether you’re looking to consolidate high-interest debt, fund a long-awaited renovation using your equity, or simply find a lender that understands your “real life” income, the current market provides a unique window to reset your finances. You now have the tools to refinance mortgage nz with confidence, knowing exactly what costs to watch for and how to spot a “cash carrot” that makes the move worthwhile.

You don’t have to navigate this shifting landscape alone. With over 20 years of expert banking and brokerage experience, we provide a steady hand and a personalised service that always puts you first. Our team has access to dozens of bank and non-bank lenders, ensuring you get a fair dinkum deal tailored to your big goals. Book a free chat with the Mortgage Suite team today to see how much you could be saving. It’s time to stop feeling stuck and start feeling supported.

Frequently Asked Questions

How much does it cost to refinance a mortgage in NZ?

To refinance mortgage nz, you’ll need to factor in three main costs: legal fees, valuation fees, and potential break fees. Lawyers typically charge between $800 and $1,600 to update your property title. A registered valuation usually costs between $700 and $1,200, though many lenders now accept digital estimates. Break fees vary based on your interest rate and remaining term. Often, a new bank’s cash-back offer covers these expenses entirely, making the switch cost-neutral for many.

Can I refinance if I have a low deposit or low equity?

Yes, you can still refinance with low equity, though your options at mainstream banks might be limited. The Reserve Bank recently proposed easing restrictions, allowing more lending to those with less than a 20% deposit. If a big bank says no, 2nd tier lenders are often more flexible. They look at your overall financial health rather than just a percentage. We help you find a lender that fits your specific equity level without the stress.

How long does the refinancing process actually take?

The entire process typically takes between two and four weeks from your first chat with us to the day the new loan starts. This includes the time needed to gather your documents, get the bank’s approval, and complete the legal paperwork with your lawyer. If you’re in a rush to secure a specific rate, some non-bank lenders can move even faster. Having your payslips and bank statements ready before we start helps speed things up significantly.

Do I need a lawyer to refinance my home loan?

Yes, you must use a lawyer or conveyancer when you move your mortgage to a new lender. They are responsible for the legal heavy lifting, which includes discharging your old mortgage and registering the new one on your property title. They also handle the transfer of funds between the banks on settlement day. While this adds a cost of roughly $800 to $1,600, it’s a legal requirement in New Zealand to ensure the title is correctly updated.

Will I get a cash-back offer if I switch banks in 2026?

Most New Zealand banks are offering competitive cash-back incentives in 2026 to attract new customers. These offers can be as high as 1% of your total loan amount. For a $500,000 mortgage, that’s $5,000 in your pocket. This cash is usually paid out on the day your new loan starts and is designed to help cover your legal and valuation costs. Just remember that most banks have a three to four-year stay period to keep it.

Can I refinance my mortgage if I am self-employed?

Absolutely. While big banks often demand two years of perfect financial records, many other lenders are happy to work with self-employed Kiwis. To refinance mortgage nz when you work for yourself, we focus on showing your real life income through recent bank statements and GST returns. If you don’t fit the rigid big-bank boxes, we’ll look at flexible 2nd tier options that value your business success and provide the funding you need.

What is the difference between refixing and refinancing?

Refixing is simply choosing a new interest rate with your current bank when your fixed term ends. It’s quick but doesn’t offer the benefits of a fresh start. Refinancing means moving your entire home loan to a different lender. This allows you to negotiate for a better rate, snag a cash-back offer, and change your loan features. It requires more effort and legal work, but the long-term interest savings are often much larger than staying put.

Is it a good idea to consolidate my debt into my mortgage?

Consolidating high-interest debts like credit cards or car loans into your mortgage can be a brilliant move to lower your monthly payments. You’ll drop from interest rates of 12% or 20% down to the current average home loan rate of around 5.89%. However, it’s vital to pay off that extra debt quickly rather than dragging it out for 25 years. We’ll help you structure your loan into separate slices to ensure you’re actually saving money.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial Property Refinance NZ: Your 2026 Guide to Unlocking Equity and Better Rates

What if the bank’s “no” isn’t actually a dead end, but a sign that your current loan has simply outgrown your business? Many Kiwi property owners feel stuck with high interest rates or rigid terms that were set years ago. It’s draining to feel like your growth is being held back by a lender who doesn’t understand your vision, especially when you’re trying to make sense of complex terms like repayment safety margins or loan-to-value limits. You deserve a financial partner who sees the potential in your portfolio rather than just the risks on a spreadsheet.

Securing a commercial property refinance NZ wide is about more than just finding a cheaper rate; it’s a strategic reset to align your debt with your 2026 goals. In this guide, you’ll learn how to restructure your debt to release equity for expansion and take advantage of the current 2.25% base interest rate environment. We’ll walk through how to navigate the latest financial regulations and show you how to trade cold, corporate interactions for a lending relationship that actually supports your long-term success. Whether you’re looking to lower your monthly repayments or access a lump sum for your next big move, we’ve got the roadmap to get you there.

Key Takeaways

  • Discover how a commercial property refinance NZ wide can help you break free from rigid bank structures and align your debt with your 2026 business goals.
  • Learn how to identify and unlock “lazy” equity in your property to fund your next stage of growth or expansion.
  • Compare the strict criteria of mainstream banks against the flexible, fair dinkum alternatives offered by 2nd tier lenders across New Zealand.
  • Get a clear roadmap for your refinance journey, from gathering your financial documents to securing a fresh valuation that reflects your asset’s true value.
  • Understand the value of having a dedicated advocate from Mortgage Suite Ltd who uses decades of industry experience to negotiate better terms on your behalf.

What is commercial property refinance and why consider it in 2026?

Refinancing is essentially the process of replacing your current commercial loan with a fresh one, often from a new lender who offers better terms. Think of it as a tactical move to improve your financial position or fuel business expansion. In the current market, many Kiwi business owners are finding that the “big four” banks have become a bit too rigid with their lending criteria. By looking at a commercial property refinance NZ wide, you can move away from those strict boxes and find a debt structure that actually breathes with your business.

To understand the basics, you might ask, what is a commercial mortgage and how does it differ when you’re swapping lenders? While the underlying asset stays the same, the rules of the game change based on the lender’s appetite for risk and their current interest rates. With the Reserve Bank’s base rate sitting at 2.25% in mid-2026, it’s a prime time to reorganise your debt to better suit your current cash flow needs. It’s about making your money work harder for you, rather than just serving the bank’s requirements.

Common reasons to trigger a refinance

Most people start looking at their options when they feel they’re paying too much or when their business needs have shifted. Here are the main drivers we see in the 2026 landscape:

  • Securing a lower interest rate: This is the most common reason. Reducing your monthly overheads puts more cash back into your daily operations.
  • Switching interest rate types: You might want to move between variable vs locked-in interest rates to find the right balance of flexibility and certainty based on current market trends.
  • Debt consolidation: You can often roll various business debts into one single commercial mortgage. This simplifies your life and usually lowers your total interest costs significantly.

Refinance vs. New Loan: What is the difference?

You might think a refinance is just as much hassle as buying a new property, but that’s rarely the case. Because you already own the asset, the assessment process can often be much faster than a new purchase. Lenders already have a track record of the property’s performance to look at. However, you do need to weigh up the costs for ending a contract early, often called break fees. We often find that if the long-term savings on a lower interest rate outweigh that initial cost, it’s a very smart move.

Your property’s updated 2026 valuation plays a massive role here too. If your building is worth more now than when you first bought it, your equity has grown. This updated value gives you much more leverage when talking to a commercial property refinance NZ specialist at Mortgage Suite Ltd, as it lowers the lender’s risk and can unlock better pricing tiers that weren’t available to you before. If you’re also considering expanding your portfolio, our guide on how to buy commercial property loan NZ requirements and processes can help you understand what’s involved in acquiring your next asset.

Unlocking the goldmine: Using equity release for business growth

Your commercial property is more than just a place for the team to work or a spot to store your inventory. If you have owned your building for a few years, there is a good chance it is sitting on a pile of what we call “lazy” equity. Choosing a commercial property refinance NZ wide allows you to tap into that increased value, effectively turning your bricks and mortar into liquid cash. You are essentially replacing your current loan with a larger one and using the difference to fund your next big move, whether that is a new location or a major upgrade.

Using the value in your property is often the most cost-effective way to fund a new business venture because interest rates backed by property are almost always lower than other types of finance. This capital works as a brilliant small business loan NZ alternative, giving you the funds you need for new machinery, hiring specialized staff, or even buying out a business partner. By leveraging an asset you already own, you avoid the high costs and strict terms often found with unsecured business credit lines.

Calculating your usable equity

Lenders decide how much you can borrow based on the percentage of the property’s total value. In the 2026 market, a solid rule of thumb is that most lenders will let you borrow up to 60% or 65% of what the building is currently worth. However, not every property is treated the same. While a standard office or warehouse is usually straightforward, specialised buildings like medical centres or cold storage units might have slightly tighter limits.

According to insights from the Property Institute of New Zealand, professional valuation trends are vital because a fresh appraisal can often reveal far more equity than you might have estimated yourself. You could even use this extra cash to fund the deposit for a residential investment property, allowing you to grow your personal wealth alongside your business without having to save a fresh deposit from your daily cash flow.

Servicing the new debt

While having equity is a great start, you also need to prove that your business can handle the larger repayments. Lenders will look closely at how well your profit covers your interest payments. Simply put, they want to see a healthy safety margin where your business income is significantly higher than the cost of the loan. They aren’t just looking at the building; they are looking at the health and sustainability of the business operating within it.

Most traditional banks prefer to see two years of steady, healthy profit in your financial records. If your recent history has been a bit more varied due to growth or market shifts, some lenders can be more flexible, provided you can show a clear plan for how the released cash will drive your future income. If you are wondering how much your specific property could unlock for your business, it is worth having a chat with the team at Mortgage Suite Ltd to see what is possible for your situation.

The Great Debate: Mainstream banks vs. 2nd tier lenders

Choosing between a mainstream bank and a non-bank lender is one of the most important decisions you’ll make when looking at a commercial property refinance NZ wide. Mainstream banks are often the first port of call because they offer the lowest interest rates. However, they can be incredibly fussy about your financial history. If your business doesn’t fit into their narrow “perfect” box, you might find yourself facing a frustrating rejection. This is where a 2nd tier lender New Zealand owners trust comes into play. They offer a fair dinkum alternative by looking at the bigger picture of your business potential rather than just ticking boxes on a checklist.

The landscape for a commercial mortgage New Zealand wide has evolved significantly by 2026. Non-bank lenders are no longer just a “last resort” for those with bad credit. They’ve become highly competitive, offering tailored solutions that the big banks simply aren’t set up to handle. For many, refinancing to a non-bank is a strategic bridge that helps them navigate a period of rapid growth or a temporary dip in cash flow without the rigid constraints of traditional banking.

When to choose a non-bank refinance

There are several scenarios where a non-bank lender is actually the better choice for your commercial property refinance NZ project:

  • Colourful financials: If you have a short trading history or your most recent tax returns don’t show the full strength of your business yet, a non-bank lender is much more likely to listen to your story and understand your future projections.
  • Need for speed: Big banks are notorious for taking weeks, or even months, to make a decision. If you need to move fast to secure a time-sensitive opportunity, a 2nd tier lender can often provide an answer and the funds in a matter of days.
  • Protecting your home: Many banks insist on “cross-collateralisation,” which means they use your family home as security for your business loan. Refinancing away from the bank can help you untangle these assets and keep your personal life separate from your business risks.

The path back to the bank

One thing many people don’t realise is that a non-bank loan doesn’t have to be a permanent fixture. We often view it as a temporary solution for 12 to 24 months. During this time, you can focus on stabilising your financials and building the “clean” track record that mainstream banks love. Once your business has matured and your books look more traditional, you can “graduate” back to a mainstream bank to secure those lower long-term rates. Having a seasoned advisor in your corner makes this transition much easier, as we know exactly what the big banks need to see before they’ll welcome you back. It’s about playing the long game to get the best result for your business.

Commercial Property Refinance NZ: Your 2026 Guide to Unlocking Equity and Better Rates

Your step-by-step roadmap to a successful refinance

Getting your commercial property refinance NZ project across the line doesn’t have to be a headache if you follow a clear path. By 2026, the lending environment has become more nuanced, requiring a bit more preparation than a standard residential top-up. The first step is always to gather your “ducks in a row.” This means having at least two years of clean financial statements, including profit and loss reports and balance sheets, alongside your current loan details. Lenders want to see that your business is stable and that you’ve been a reliable borrower so far.

Once your paperwork is sorted, the process typically follows this sequence:

  • Get a fresh valuation: With total commercial sales activity increasing by approximately $131 million in recent years, your property’s 2026 value is likely much higher than your last bank assessment.
  • Compare lender appetite: Not every lender wants to fund a suburban retail block or a large industrial warehouse. We help you find the one whose current “appetite” matches your specific asset type to ensure a higher chance of approval.
  • Negotiate the fine print: This is where we look at the General Security Agreements (GSA) and ensure the terms don’t pull your other business assets into the mix unnecessarily.
  • Settlement: Your lawyers will coordinate with the new lender to pay off your old debt. From here, your new journey with better rates or extra capital begins.

Navigating the valuation process

One common trap is thinking you can use a simple residential “app” estimate for a commercial deal. Commercial valuations are far more complex. The valuer will look closely at your “yield” and “cap rates,” which are essentially ways of measuring the property’s income potential against its market risk. If you have strong tenants on long-term leases, your valuation will likely be much stronger. It’s a good idea to tidy up the building and ensure all maintenance records are up to date before the valuer arrives. A well-presented property suggests a well-managed business, which gives the bank more confidence during the commercial property refinance NZ process.

Negotiating the “hidden” terms

It is a mistake to focus solely on the interest rate. While the 2.25% OCR has kept base rates attractive, banks often hide extra costs in “line fees” or strict “covenants.” Covenants are the rules you must follow, such as maintaining a certain level of profit. If these are too tight, they can stifle your growth. We often work to get application fees reduced or waived entirely, and we structure the loan to ensure you have the flexibility to make changes later without being hit by more charges. If you want someone to handle these tricky negotiations for you, reach out to Mortgage Suite Ltd to start your roadmap today.

Why partnering with Mortgage Suite makes the difference

When you are looking to secure a commercial property refinance NZ wide, having the right person in your corner changes everything. Krish Krishna and the team at Mortgage Suite bring over 20 years of deep banking experience directly to your side of the table. We reckon every business owner deserves an advocate who speaks the bank’s language and knows exactly how to navigate their internal systems. Instead of you spending hours on hold or deciphering complex credit policies, we handle the heavy lifting of the application. This leaves you free to stay focused on what really matters; looking after your customers and growing your business.

Our expertise isn’t limited to one specific sector. Whether you are managing a large industrial warehouse, a bustling retail suite, or a specialised medical facility, we know how to present your case. We understand the nuances of the 2026 market and how to highlight the strengths of your property and business cash flow to get the deal sorted. We don’t just submit papers; we tell your story in a way that makes lenders want to say yes.

A personal approach to business finance

We are not a “set and forget” brokerage that disappears once the loan is settled. We are here for the long haul, acting as a steady hand as your business evolves. Our reputation as dedicated negotiators helps us find the “green light” for complex deals that other brokers might find too difficult. We specialise in those “out of the box” scenarios that mainstream banks often struggle with, using our industry connections to find flexible solutions that align with your specific goals. If there is a way to make the numbers work, we will find it.

Ready to chat about your options?

The first conversation you have with us is always free and completely confidential. We take the time to listen to your 2026 goals and look at your current debt structure to see if there is a better deal waiting for you. There is no pressure and no confusing jargon; just honest, professional advice from people who have seen every possible scenario. Let’s see how a commercial property refinance NZ could unlock new opportunities for your portfolio. Get in touch with Mortgage Suite today to explore your refinance options and start your next chapter with confidence.

Ready to unlock your property’s true potential?

The 2026 market offers a unique window to turn your commercial asset into a springboard for future success. Whether you’re looking to lower your overheads or tap into equity for a new venture, a commercial property refinance NZ project gives you the control back. You don’t have to stay stuck with a lender who doesn’t see your vision or understand your specific industry needs. Refinancing is your chance to reset the terms and ensure your debt is working for you, not the other way around.

At Mortgage Suite, we bring over two decades of banking and brokerage expertise to ensure you aren’t just another number in a system. We specialise in finding the right path, whether that’s with a mainstream bank or a flexible 2nd tier lender who can move as fast as you do. Our team acts as your personal advocate, handling the tricky negotiations and paperwork so you can get back to what you do best. We believe in building long-term partnerships based on trust and real results.

If you’re ready to see what’s possible, book a free refinance strategy session with Krish and the team today. We’ll look at your goals and find a solution that fits your business perfectly. It’s time to move forward with a financial partner who is as committed to your success as you are.

Frequently Asked Questions

Is it harder to refinance commercial property than a residential home?

It is generally more complex because lenders look at the strength of your business and the quality of your tenants rather than just your personal income. While a home loan is based on a standard set of rules, commercial deals are assessed on their individual merits. This requires more detailed paperwork and a deeper look at your long-term stability, lease agreements, and the specific industry you operate in.

How much equity can I pull out of my commercial property in NZ?

Most lenders in the current market will allow you to borrow up to 60% or 65% of the property’s total value. If your property is worth more now than when you bought it, you can use a commercial property refinance NZ project to access that extra cash for business growth. This is a great way to fund expansion or new investments, provided your business can comfortably service the larger loan.

What are the typical break fees when refinancing a commercial loan?

Break fees vary between lenders, but you might see a flat fee around $33 or a calculation based on 30 days of interest. It is important to ask your current bank for a specific “break cost” quote before you switch. This helps you determine if the long-term savings from a lower interest rate will outweigh the immediate cost of leaving your current contract early.

Can I refinance if my business has had a “tough” year financially?

You certainly can, though you may need to look beyond the mainstream banks for a solution. If your most recent tax returns show a dip in profit, a non-bank lender will often look at your overall track record and future projections rather than just your last 12 months. This “big picture” approach is a great way to secure the funding you need while your business gets back on its feet.

How long does the commercial refinance process actually take?

You should typically allow between four and eight weeks from your first conversation to the final settlement. While some 2nd tier lenders can move much faster if you have all your documents ready, the process involves valuations and legal checks that take time to get right. Starting the process early ensures you aren’t rushed into a deal and gives us plenty of time to negotiate the best terms.

Do I need a new valuation when I refinance my commercial property?

Yes, almost every lender will require a fresh valuation to confirm the property’s current market value. Since the 2026 lending landscape relies heavily on accurate data, a new report ensures the bank is comfortable with the loan amount. It also gives you the best chance of unlocking the maximum amount of equity if the property has increased in value since you first took out your loan.

What is an “Interest Cover Ratio” and why does it matter for my refinance?

This is a tool lenders use to see if your business makes enough profit to pay the interest on the loan several times over. They want to see a safety margin so that even if your income drops slightly, you can still meet your repayments. A strong ratio makes you a much more attractive borrower and can often lead to more competitive interest rates and better terms.

Can I refinance a commercial property that has a vacant tenancy?

It is possible, but it usually requires a specialist lender who understands your specific market. Mainstream banks generally prefer properties with consistent income from long-term leases. If you have a vacancy, we can often find a commercial property refinance NZ solution that provides a bridge until you find a new tenant. Once the building is full again, we can then look at moving you back to a traditional bank. If you’re also planning to secure a buy commercial property loan NZ lenders will approve for your next acquisition, understanding the full lending landscape is key to making the right move at the right time.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.