
Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Your business success should be your greatest mortgage asset, not the reason a bank says no. It’s a common frustration for New Zealand entrepreneurs who feel penalised for their drive and independence. You’ve likely heard that traditional low doc home loans nz are harder to find now that the Financial Markets Authority has taken over credit regulation, but that doesn’t mean your home ownership dreams are over. We understand that your business bank statements often tell a much more accurate story than a standard tax return ever could.

You deserve a clear path to approval that doesn’t involve a mountain of confusing paperwork or endless anxiety. In this guide, we’ll show you exactly how to handle the 2026 lending market to get your home loan sorted. We will explore the rise of alternative documentation options, explain how second-tier lenders operate, and provide a step-by-step strategy to move from a bank decline to a front door key in your hand.

Key Takeaways

  • Being self-employed is a major achievement, and we will show you how to use your business success as an asset rather than a hurdle when applying for a mortgage.
  • Learn how traditional low doc home loans nz have evolved into flexible alternative documentation options from safe, regulated lenders who actually understand your business story.
  • Discover the specific, simple paperwork you need to show your true income without the stress of overwhelming accounting jargon or complex bank requirements.
  • Get practical tips on how to tidy up your accounts and why paying yourself a consistent salary can significantly boost your chances of loan approval.
  • Find out how to partner with a veteran advocate who knows the non-bank market inside out and will fight to get you into a home when the big banks say no.

What does it mean to get a mortgage for self-employed NZ borrowers?

At its heart, a self-employed mortgage is just a standard home loan. It’s helpful to understand what is a mortgage in the broadest sense: a way to secure property using the equity you build over time. For you, the only real difference is how you prove you can afford the repayments. Banks often see your business as a risk, but we see it as a massive achievement. Whether you’re a tradie on the tools or a freelancer working from a home office, your drive shouldn’t be a hurdle to getting your own place.

Many Kiwis feel like they’re being penalised for their entrepreneurial spirit. If a mainstream bank has already said no, you might think you’re out of options. The market for low doc home loans nz has evolved significantly. While the big banks are often stuck in a cycle of strict criteria, other lenders are more interested in your actual business story and your ability to manage money. We help everyone from company directors and contractors to sole traders find a path forward.

Why the big banks treat you differently

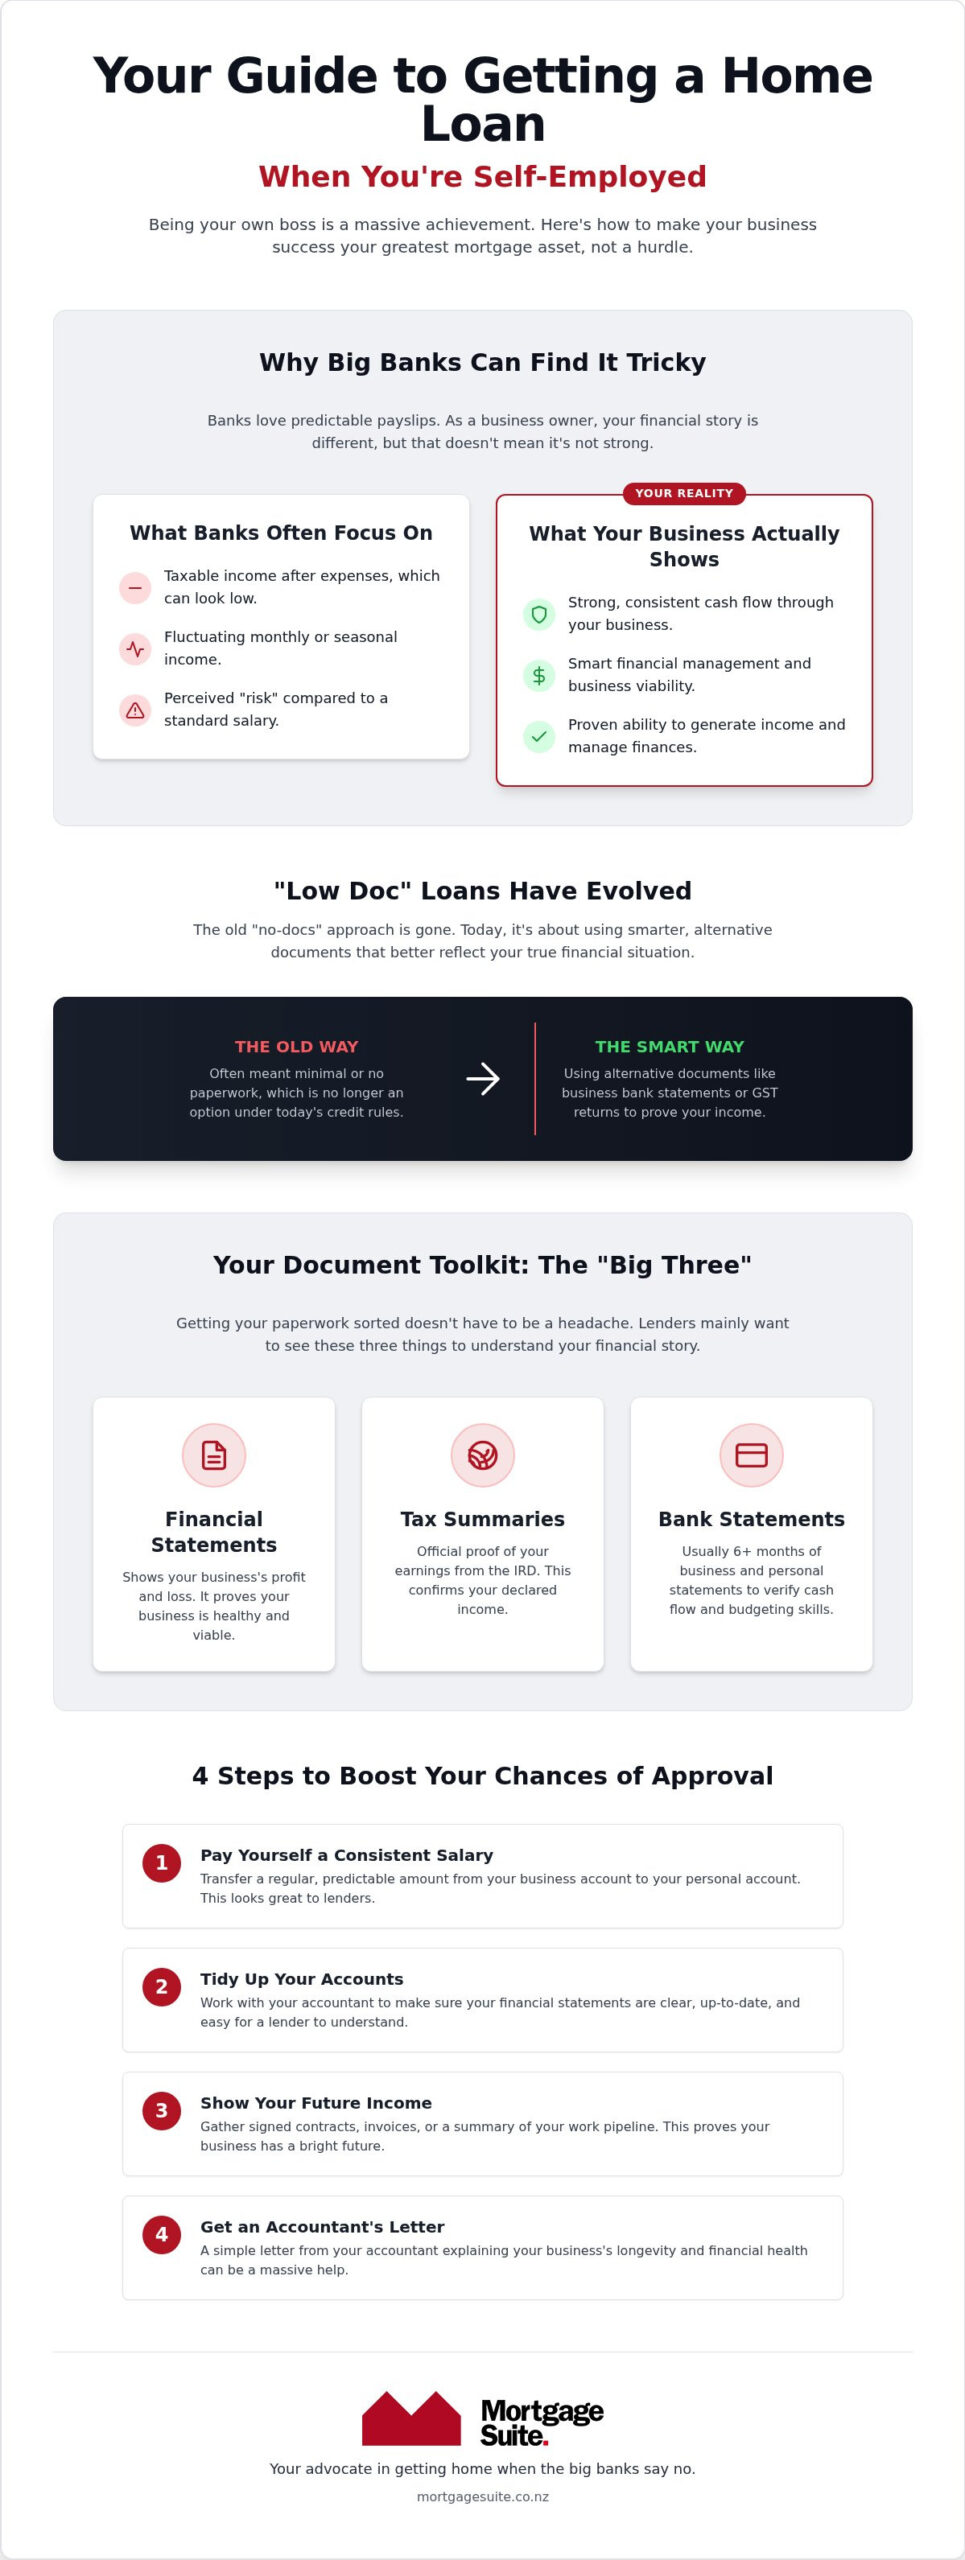
Banks love predictability. They want to see a payslip that looks exactly the same every fortnight. When you run your own show, your income might go up and down depending on the season or when a big contract finishes. Mainstream lenders also tend to focus purely on your taxable income. Because you likely work with an accountant to legally minimise your tax, your “on paper” profit might look much lower than the actual cash you have available to pay a mortgage. In 2026, banks are using test rates around 7% to see if you can handle repayments. For a business owner with fluctuating income, meeting that hurdle while staying under the debt-to-income (DTI) cap of 6 can feel impossible without an expert in your corner.

The different types of self-employed income

Not all self-employment is the same. A full-time contractor might have a steady stream of work from one source, while a small business owner manages staff and overheads. Sometimes, a one-off business expense, like a new piece of machinery or a vehicle, can confuse a bank’s computer system and make it look like your business is struggling. If you’re just starting out on this journey, our First Home Buyer Guide is a great place to see how the basics apply to you. Specialised low doc home loans nz or alternative documentation options can bridge this gap by looking at your GST returns or bank statements instead of just a standard tax summary.

The paperwork you will need to get sorted

Gathering a mountain of files can feel like a full-time job. It’s often the point where many entrepreneurs give up before they’ve even started. You might worry that your accounts aren’t perfect or that a single quiet month will ruin your chances. In 2026, the concept of low doc home loans nz has shifted. It no longer means “no documents” at all. Instead, it refers to alternative documentation that fits your life better than a standard payslip. We act as your mentor through this process, helping you pick out the right files to show your financial strength.

The Big Three documents

Lenders typically focus on three core areas to understand your situation. First, your financial statements tell the story of your business profit and loss. We keep this simple. It’s about showing that your business is a viable, living entity. Second, you’ll need tax summaries from the IRD to prove your official earnings. Finally, personal bank statements are vital. Under current regulations managed by the Financial Markets Authority, lenders often look for at least six months of business bank statements to verify your cash flow. These personal records show how you handle your household budget and prove you can manage the commitment of a home loan.

Proving your future income

Banks are naturally cautious, so showing them a bright future is just as important as showing a solid past. If you have a stack of signed contracts or a healthy pipeline of work for the coming year, these are massive assets for your approval. A simple letter from your accountant can also go a long way. They can explain the longevity of your business and why certain one-off expenses shouldn’t count against you. Essentially, income verification is just the process of proving you have the actual cash on hand to cover your repayments without struggle.

If you’re feeling overwhelmed by the requirements, it’s often helpful to see what others in your position have achieved. You can read through our client reviews to see how we’ve helped other self-employed Kiwis get their paperwork sorted and their loans approved.

When the bank says no: Exploring 2nd tier and alternative lenders

Hearing a “no” from a mainstream bank can feel like a punch in the gut. You’ve worked hard to build your business, and being told you aren’t “predictable” enough is discouraging. It’s important to remember that a bank’s rejection isn’t a reflection of your business success. It’s simply a sign that you don’t fit their very narrow, rigid box. This is where 2nd tier lenders come in. These are professional, safe, and fully regulated finance companies that operate without the big bank branding. They specialise in low doc home loans nz because they have the freedom to look at the person and the business story, not just a standard spreadsheet.

Using a non-bank lender isn’t a last resort. It’s a strategic move used by many of New Zealand’s most successful entrepreneurs. These lenders are solution-based. They understand that a business owner’s wealth is often tied up in growth and assets rather than a static salary. For a deeper dive into how these finance companies can help you, check out our 2nd Tier Lender Guide.

Mainstream Banks vs. 2nd Tier Lenders

The differences between these two worlds are significant. Mainstream banks offer lower interest rates, but their rules are incredibly strict and their processes are often slow. If you don’t have two years of perfect, steady tax returns, they’ll likely struggle to say yes. In contrast, 2nd tier lenders offer more flexible rules. As of mid-2026, while mainstream rates for one-year fixed terms sit around 4.8%, non-bank rates for alternative documentation loans typically start from about 6.35%.

A 2nd tier loan is often used as a vital stepping stone. You can secure your home now, build equity for 12 to 24 months, and then refinance with a mainstream bank once your accounts have settled into a pattern the banks recognise. This proactive approach gets you into the property market years sooner than waiting for a bank’s approval.

The benefit of a specialised negotiator

Because the non-bank world is diverse, having a veteran mentor on your side is vital. We don’t just pass on your paperwork. We act as your advocate, carefully presenting your business to the right lender to ensure they see your success rather than a risk. Krish Krishna’s 20 years of industry experience means he knows exactly which lenders are currently looking for businesses like yours. We know how to tell your story in a way that opens doors that might otherwise stay shut. Our goal is to remove the stress and provide a clear, confident path to your new home.
Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Steps to improve your chances of approval

Preparing for a mortgage when you’re your own boss is all about presentation. Think of it like dressing your business up for an interview. One of the most effective things you can do is keep your personal and business expenses completely separate. When your accounts are clean, it’s much easier for a lender to see that your business is thriving and that you have the cash flow to handle a home loan. This clarity is especially important when we’re looking at low doc home loans nz, as it allows the lender to trust the alternative documents we provide.

Another great move is to pay yourself a consistent salary. Even if you own 100% of the company, regular transfers into your personal account look fantastic to a lender. It mimics the predictability of a standard job, which banks find very reassuring. You should also look at managing your existing debt. Clearing a car loan or closing an unused credit card can significantly boost how much you’re allowed to borrow. Before you get too far down the track, it’s a smart idea to use our mortgage calculator to see what a realistic repayment looks like for your budget.

Clean up your personal bank statements

In the three months before you apply, try to avoid any unusual spending spikes. Lenders look closely at your day-to-day habits to see how you’ll handle a mortgage. This is also the time to pause any “buy now, pay later” schemes. While they’re handy for small purchases, lenders often view them as a line of credit that reduces your overall borrowing power. Being squeaky clean with your bill payments and regular outgoings shows that you’re disciplined and reliable.

Timing your application

Timing can be everything. If you’ve just made a massive business investment, like buying new machinery or a fleet of vehicles, your cash reserves might look a bit low. It’s often better to wait until those investments start showing a return. The sweet spot for many self-employed Kiwis is right after the end of the financial year on March 31st. This is when your latest figures are fresh and your accountant can provide the most up-to-date proof of your success. Loan readiness is about showing you are a safe pair of hands. If you’re ready to see what’s possible for your business, get in touch with us today to start the conversation.

How Mortgage Suite helps self-employed Kiwis get home

At Mortgage Suite Ltd, we don’t believe your business success should be a barrier to buying a home. We take an advocacy-led approach to every application. This means we don’t just bundle up your paperwork and hope for the best. We actively fight your corner with lenders to make sure they see the full value of what you’ve built. Because we are a business ourselves, we understand the long hours and the dedication it takes to be your own boss. We aren’t a cold corporate office; we are your partners in this process. Whether you’re looking for a property in the far north or the deep south, our national reach means we can help you secure a home anywhere in New Zealand.

If you’re curious about how this works in practice, we encourage you to read our client reviews. You’ll see stories from other Kiwis who thought their dream was over after a bank decline, only to find a path forward with us. We know that every business has a unique story, and we make it our mission to ensure that story is heard by the right people.

A personal approach from an industry veteran

Krish Krishna brings over two decades of banking and finance experience to the table. He uses this deep institutional knowledge to navigate the often complex world of low doc home loans nz and alternative lending. The Mortgage Suite Ltd way is about removing the weight from your shoulders. We aim to make a process that usually feels overwhelming into something that is sorted and stress-free. You can learn more about us and our philosophy of partnership. We believe in building long-term relationships, not just processing one-off transactions.

Your next steps to home ownership

Taking the next step doesn’t have to be scary. Our first conversation is simply about understanding your goals and where you want to go. There is absolutely no pressure and definitely no confusing jargon. We’ll look at your current situation and build a clear, actionable plan together. Our goal is to move you from a “declined” status to a firm approval. You’ve already done the hard work of building a successful business. Now, let’s work together to build your future in a home you actually own. Getting your low doc home loans nz sorted is much easier when you have a veteran mentor who knows exactly which levers to pull.

Take the lead on your home ownership journey

Building a business is a major achievement that proves you have the drive to succeed. While big banks might focus on rigid boxes, you now know that alternative documentation and second-tier lenders offer a professional, regulated path to your new home. Securing low doc home loans nz is about finding the right lender who understands your unique story and sees your success as an asset. By tidying your accounts and paying yourself a consistent salary, you’re already halfway there.

With over 20 years of banking expertise, our team at Mortgage Suite acts as your dedicated negotiator. We specialise in non-bank and second-tier lending, and we know exactly how to open doors that mainstream lenders often keep shut. We’ll handle the complex paperwork so you can focus on what you do best: running your business. Ready to get your mortgage sorted? Book a chat with the Mortgage Suite team today. Your entrepreneurial spirit has built your business, now let’s use it to build your future in a home of your own. You’ve got this.

Frequently Asked Questions

Can I get a mortgage if I’ve only been self-employed for one year?

Yes, you certainly can. While major banks typically look for two years of accounts, many second tier lenders only require six to twelve months of trading history. We focus on showing the strength of your business through GST returns and bank statements. If your industry experience is solid and your current cash flow is healthy, we can often find a solution that gets you into a home much sooner than a bank would allow.

Do I need a bigger deposit if I’m self-employed in NZ?

Not always, but it helps to be prepared. If you fit a bank’s standard criteria, a 20% deposit is the norm. For those using low doc home loans nz or alternative documentation, lenders might ask for 20% to 30%. This larger deposit acts as a safety net for the lender. However, we have seen cases where a smaller deposit is possible depending on the strength of your business story and the specific property you are buying.

What is a low doc loan and is it right for me?

In 2026, these are often called “alt doc” loans. They are designed for business owners who have a solid income but don’t have standard tax returns ready yet. Instead of IRD summaries, the lender looks at your bank statements or GST filings. It’s a great fit if you’ve recently invested back into your business or have a complex income structure that a standard bank computer doesn’t understand or recognise as stable.

Will I have to pay a higher interest rate because I work for myself?

Not necessarily. If you qualify for a standard bank loan, your rate will be the same as any other borrower. However, if you need the flexibility of a non-bank lender, you should expect to pay a bit more. As of mid-2026, non-bank rates for low doc home loans nz often start around 6.35%. Many of our clients see this as a temporary cost to get into the market before refinancing later on.

Can I use my business profit to help with my mortgage application?

Absolutely. Lenders focus on your net profit before tax. We also work with your accountant to identify “add-backs.” These are one-off business expenses, like a new vehicle purchase or depreciation, that shouldn’t count against your ability to pay a mortgage. By adding these back into your profit, we can often show a much stronger income than what appears on your final tax bill, which helps with your borrowing power.

What happens if my business had a bad year recently?

A single quiet year isn’t an automatic decline. We look at the reason behind the numbers. If you had a dip because of a strategic investment or a one-off event, we can explain that story to a lender. Many second tier lenders are happy to look at your most recent six months of trading to see that your business has recovered and is currently performing well. It’s about showing your current financial health.

How do I prove my income if I’m a contractor?

Proving income as a contractor is all about showing your track record. Lenders will want to see your current signed contracts, your GST returns, and at least six months of business bank statements. They look for a pattern of regular payments and a healthy pipeline of future work. If you’ve been in the same industry for a long time, that experience counts for a lot even if you are relatively new to contracting.

Why should I use a broker instead of going straight to my bank?

Your bank only has one set of rules and one list of products. If you don’t fit their box, they simply say no. A broker has access to dozens of lenders, including specialised second tier companies that don’t deal with the public directly. We act as your advocate, using over twenty years of experience to tell your business story to the right person. We find the “yes” that your bank might have missed.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loans for Self Employed: 2026 Guide to Getting Approved

Imagine sitting across from a bank manager, presenting a thriving business you have built from the ground up, only to be told your "paper income" isn’t enough to buy a house. It is incredibly disheartening when mainstream lenders ignore your legitimate business add-backs or penalise you for the very expenses your accountant organised to reduce your tax bill. If you are searching for a home loan and are self employed, you have likely realised that traditional banks often view your entrepreneurial drive as a risk. They see inconsistent income "bursts" and mountains of paperwork, while we see a dedicated professional who deserves a steady hand to guide them through the finance process.

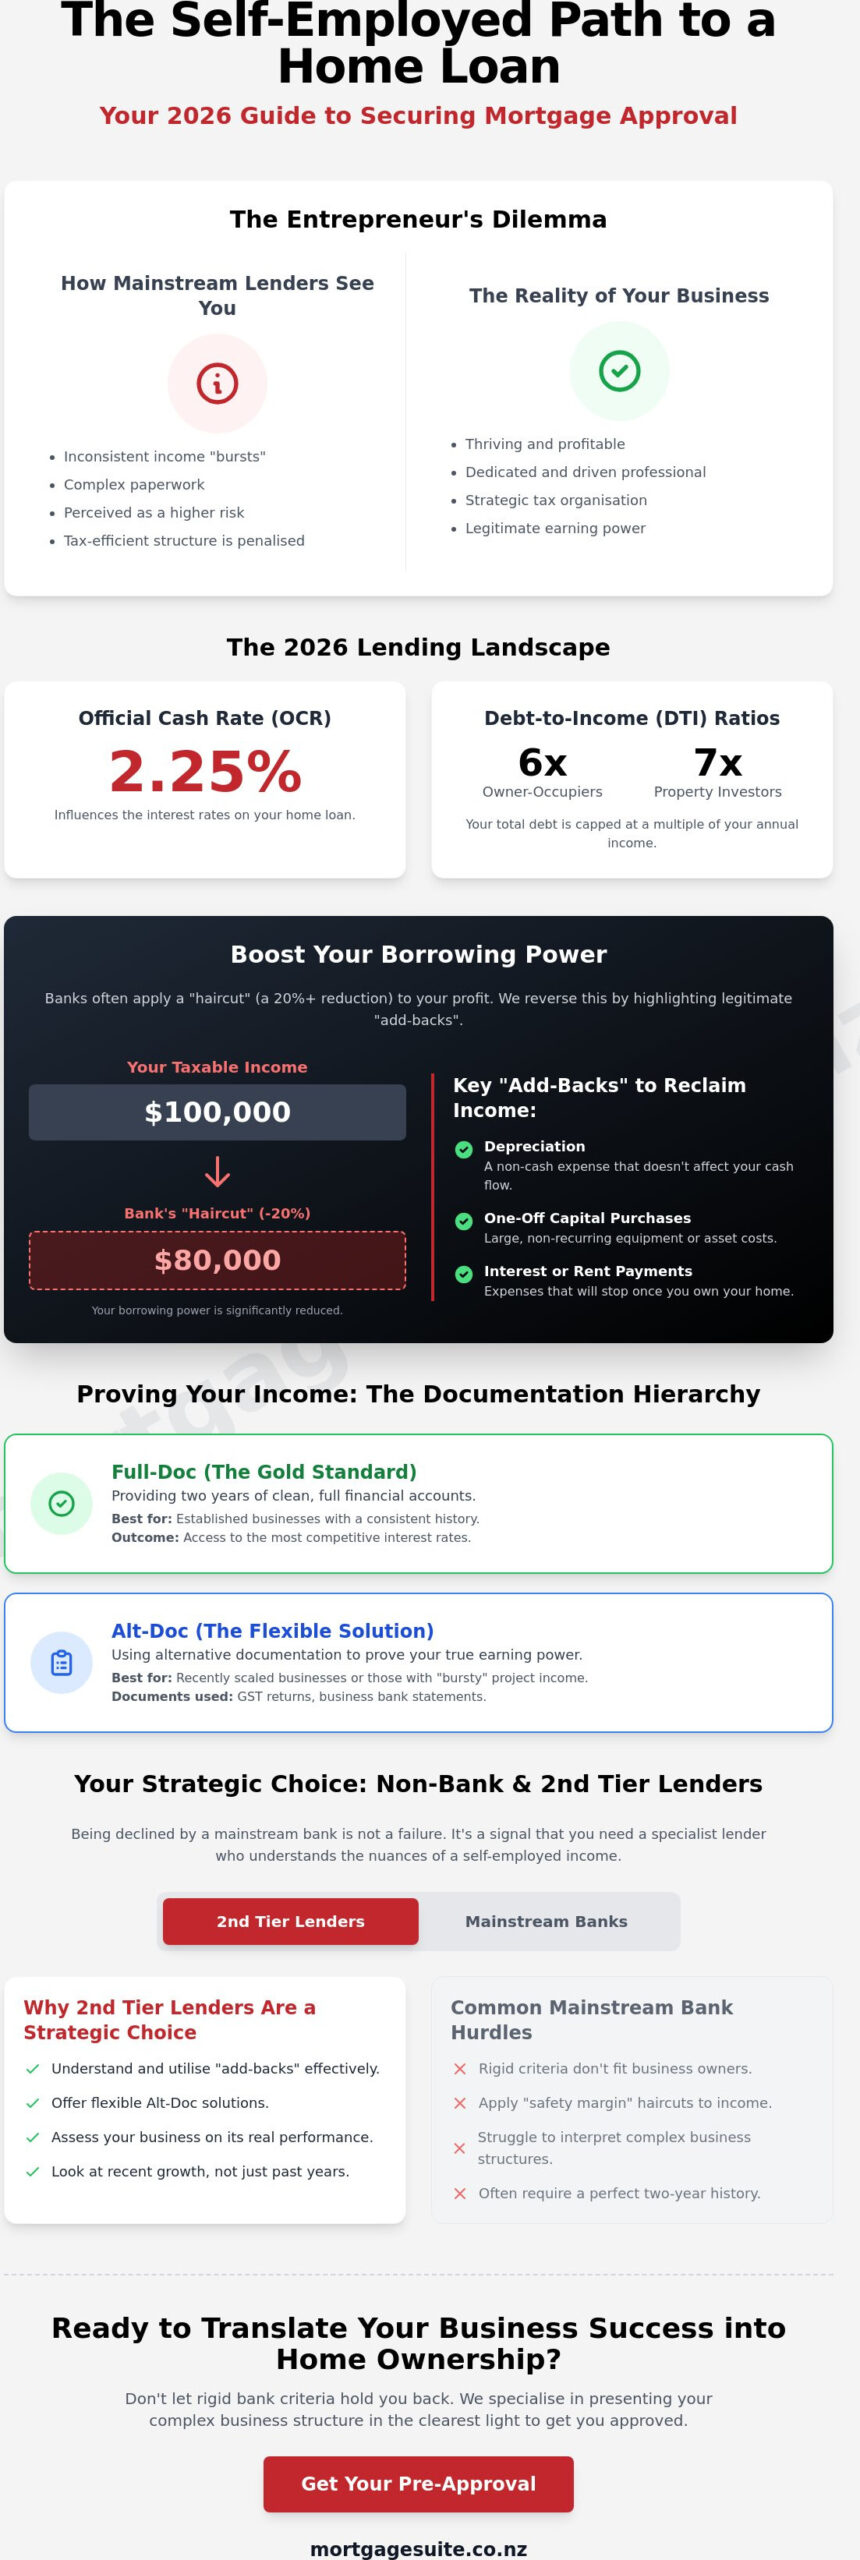
This 2026 guide provides the clear path to pre-approval you need, even with the Official Cash Rate at 2.25% and debt-to-income ratios capped at six times your earnings. You will learn exactly how to bypass rigid bank criteria by exploring non-bank lenders who offer flexible "alt-doc" solutions using GST returns or business bank statements. We will detail how to secure competitive interest rates and navigate the latest LVR restrictions, ensuring your business structure is properly understood so you can move forward with confidence.

Key Takeaways

  • Understand how lenders apply “safety margins” to your income and how to navigate the 2026 Debt-to-Income (DTI) restrictions.
  • Discover the documentation hierarchy and why alternative “Alt-Doc” methods like GST returns might be the key to proving your true earning power.
  • Learn why 2nd Tier lenders are a strategic choice for a self employed home loan nz rather than a last resort when mainstream banks decline your application.
  • Master a simple “pre-audit” process to organise your business drawings and personal expenses for maximum lender appeal.
  • Explore how professional advocacy and veteran negotiation can translate your complex business structure into a clear path for approval.

The Reality of Self-Employed Home Loans

For many business owners, the dream of home ownership feels like it is being held hostage by a spreadsheet. Getting a **self employed home loan ** in 2026 requires more than just a profitable business; it requires a deep understanding of how lenders interpret your financial health. While an employee with a standard salary provides a predictable data point for a bank, your income is often viewed through a lens of skepticism. Mainstream banks are currently operating with a conservative risk appetite, and they often struggle to reconcile the fluctuations of a growing business with their rigid lending criteria.

The lending environment in mid-2026 is heavily influenced by the Debt-to-Income (DTI) restrictions that became a permanent fixture in recent years. For owner-occupiers, the limit is generally six times your gross annual income, while investors are capped at seven times. When defining self-employment for a loan application, the bank does not just look at your turnover. They look at your drawings, your net profit, and your ability to service debt when the Official Cash Rate (OCR) is at 2.25%. If your income arrives in "bursts" rather than a steady drip, a traditional bank might simply put you in the "too hard" basket. However, being declined by a major bank is rarely the end of the road; it is often just the signal that you need a more sophisticated lending partner.

Understanding Your Income

Banks are notoriously cautious with business owners.

To overcome this, we focus on "add-backs." These are legitimate business expenses that don’t actually impact your ability to pay a mortgage, such as:

  • One-off capital purchases or equipment upgrades.
  • Non-cash expenses like depreciation.
  • Excessive home office claims or personal expenses run through the business.
  • Rent or interest payments that will cease once you buy your own property.

Regulatory Changes and DTI Ratios in 2026

The 2026 regulatory framework treats business debt and personal debt with equal scrutiny. Under the current Credit Contracts and Consumer Finance Act (CCCFA) requirements, lenders must be certain that your business debt—such as vehicle finance or an overdraft—does not compromise your home loan repayments. If your business carries significant debt, it can quickly eat into your DTI allowance, making it harder to reach the 80% LVR threshold required for standard owner-occupier loans. We work with you to clean up your debt profile, ensuring your personal and business liabilities are structured to maximise your approval chances without sacrificing your business’s cash flow.

Proving Your Income: Documentation That Actually Works

Securing a self employed home loan requires a strategic approach to your paperwork. While an employee simply hands over three months of payslips, your application must build a narrative of stability and growth. Many business owners find that their IRD Summary of Earnings tells a story of tax efficiency rather than true mortgage affordability. To bridge this gap, we look beyond the basic tax return to find the documents that reflect your business’s actual momentum.

The hierarchy of proof has shifted significantly in 2026. Traditional "Low-Doc" loans, which once required minimal evidence, have largely been replaced by "Alt-Doc" (alternative documentation) solutions. This is a direct result of the Credit Contracts and Consumer Finance Act (CCCFA), which mandates a robust assessment of affordability. If you have two years of clean financial accounts, you’ll likely qualify for "Full-Doc" rates. However, if your business has recently scaled or you have "bursty" income from project-based contracts, Alt-Doc allows us to use more recent data, such as GST returns, to prove you can comfortably service the debt.

The Essential Self-Employed Paperwork Checklist

Lenders want to see that your business is a reliable vehicle for income. Before submitting an application, ensure you have the following documents organised:

  • Financial Statements: Full Profit & Loss and Balance Sheets for the last two financial years.
  • Bank Statements: Six months of personal and business statements. Lenders look for regular drawings that match your stated income.
  • Tax Verification: Your most recent personal and business tax assessments, along with proof that all IRD obligations are being met.
  • Add-back Schedule: A clear list of non-cash or one-off expenses that shouldn’t count against your borrowing power.

If your business income is seasonal, we frame your application by showing a 12-month average rather than focusing on a quiet month. This context is vital for preventing a "decline" based on a temporary dip in cash flow. If you are unsure which documents best represent your current position, exploring tailored home loan options can help clarify your strategy before you approach a lender.

Alt-Doc Solutions for Newer Businesses

For those who have been trading for 12 to 18 months, or whose most recent tax return doesn’t reflect a recent surge in turnover, Alt-Doc is a game changer. Instead of waiting for the next financial year to end, some specialist lenders will accept an accountant’s declaration of your earnings or use your last six months of GST returns to verify your current capacity. This approach focuses on where your business is today, not where it was two years ago, providing a vital pathway for self employed home loan applicants who are currently in a high-growth phase.

Many business owners view 2nd tier lenders with a sense of hesitation, fearing they are only for those with significant financial trouble. This is a misconception that often prevents entrepreneurs from securing a self employed home loan when they are perfectly capable of servicing a mortgage. In the current 2026 market, non-bank lenders like Avanti Finance or Pepper Money act as sophisticated specialists. They fill the gap left by mainstream banks that rely on rigid automated systems. While a bank might see a complex trust structure or a single year of trading as a red flag, a 2nd tier lender employs human underwriters who look at the bigger picture.

The primary trade-off involves cost. Non-bank "Near Prime" rates typically start around 5.65% to 7.35%, which is higher than the special rates offered by ANZ or Westpac. You should also expect higher establishment fees, often ranging between 1% to 1.5% of the loan value. However, for a business owner, the value lies in the approval probability. These lenders aren’t bound by the Reserve Bank’s strict Debt-to-Income (DTI) thresholds in the same way as registered banks. This flexibility allows us to secure a **self employed home loan **for clients who have the cash flow but don’t fit the traditional "box."

When to Choose a Non-Bank Lender

Choosing a non-bank option is often the most strategic move if your business has undergone a recent transition. If you have moved from a sole trader to a company structure, or if a one-off capital investment skewed your net profit last year, traditional bank software will likely trigger an automatic decline. Specialist lenders are far more accommodating of short trading histories, sometimes considering applications with as little as 6 to 12 months of data if you have a strong industry background. They specialise in "Alt-Doc" solutions, allowing us to use recent GST returns to prove your current earning capacity rather than relying on outdated tax returns.

The Long-Term Strategy: Refinancing Back to a Bank

We often treat a 2nd tier loan as a temporary bridge rather than a forever home for your mortgage. By securing a loan now and maintaining a clean repayment history for 12 to 24 months, you "prime" yourself for a future bank application. This period allows your business to mature on paper and demonstrates your reliability as a borrower. Understanding how to qualify for a home loan in NZ involves planning this exit strategy from the start. Once your financial statements show two years of solid growth, we can assist you in refinancing back to a mainstream bank at a lower interest rate, having already secured the property you wanted.

Home Loans for Self Employed: 2026 Guide to Getting Approved

A Step-by-Step Guide to Polishing Your Mortgage Application

Successful lending outcomes are rarely the result of luck. They are the product of a disciplined staging process that begins months before you even attend an open home. When you apply for a self employed home loan, the bank isn’t just looking for profitability; they are searching for evidence of financial discipline. Think of your application like a house you are preparing for sale. You need to declutter the noise, fix the small leaks in your spending, and highlight the structural strengths of your business.

The first step is a rigorous pre-audit. Scour your business accounts for personal expenses that might look like high living costs to a lender. Second, ensure your drawings are regular. A bank prefers to see $1,500 transferred every week rather than a $20,000 lump sum once a quarter. Third, slash your credit limits. In the 2026 DTI environment, an unused $10,000 credit card or an active Buy Now, Pay Later (BNPL) account can reduce your borrowing power by tens of thousands of dollars. Finally, prepare a formal business commentary and engage a specialist who understands the nuances of business structures.

Framing Your Business Narrative

Lenders hate mystery. If your profit dipped recently because you invested in a new fleet of vehicles or a high-end server array, you must tell them. A written explanation transforms a "loss" on paper into a strategic investment in future growth. Highlight recurring revenue models or long-term contracts that prove your income isn’t just a series of lucky breaks. If you are a contractor in a niche field like IT or engineering, including a professional CV helps the underwriter understand your employability if your current contract ends. This narrative provides the context that raw numbers often lack.

Cleaning Up Your Personal Financial Conduct

You must adhere to the "three-month rule" of flawless account behaviour. Under the CCCFA, any unarranged overdraft or missed payment on a utility bill is a massive red flag. Banks interpret these as a lack of financial control, regardless of how much money is sitting in your business account. You also need a clear "deposit story." Be ready to prove exactly where your savings came from to satisfy Anti-Money Laundering (AML) requirements. If your deposit includes a gift from family or a business dividend, document the paper trail early. To ensure your application is truly bank-ready, you can apply for a home loan assessment to identify any potential hurdles before they become problems.

Why Mortgage Suite is Your Best Advocate for Approval

When you work for yourself, you don’t just need a loan; you need a dedicated negotiator who understands the intricacies of your business. Securing a **self employed home loan ** is often a battle of interpretation. It’s about how your depreciation is viewed, how your "bursty" income is averaged, and how your future potential is weighed against historical tax returns. We provide the steady hand and the institutional knowledge required to bridge the gap between your entrepreneurial success and the rigid requirements of a bank’s credit department.

We work with the mainstream banks in the first instance but our reach extends beyond the big four banks. We provide access to a comprehensive range of 2nd tier and alternative capital, allowing us to find solutions even when traditional lenders have said no. Our partnership approach includes:

  • Access to residential investment property loans and business finance.
  • Strategic planning to move from 2nd tier loans back to mainstream banks.
  • Proactive management of commercial and property development loans.
  • Expert structuring for first-home buyers with non-standard income.

The Advantage of a Seasoned Negotiator

Krish Krishna brings over 20 years of banking experience and 26 years as Financial Adviser to your side of the table. This isn’t about simply submitting a form; it’s about expert negotiation. Krish uses his deep understanding of credit policy to challenge rejections and present your financial story in a way that resonates with underwriters. We specialise in structuring complex deals that mainstream banks often overlook, ensuring your business structure is viewed as a strength rather than a liability. You aren’t just another file to us; you are a partner whose success is our priority.

We understand that as a business owner, your time is your most valuable asset. By utilising our veteran expertise, you gain an advocate who knows exactly which "add-backs" to fight for and which lenders have the highest risk appetite for your specific industry. This high-standard service is designed to remove obstacles and create a seamless bridge to your property goals.

Ready to Get Moving?

We simplify the process so you can stay focused on running your business. Instead of you spending hours chasing paperwork and deciphering banking jargon, we handle the heavy lifting. The first steps involve a consultative conversation where we identify your needs and outline a clear path to pre-approval. There is no need to feel overwhelmed by the volume of paperwork when you have a veteran expert managing the details. Enquire about your self-employed home loan today and take the first step toward a successful approval.

Your Path to Home Ownership Starts Here

Securing a self employed home loan in 2026 doesn’t have to be a source of constant anxiety. While the DTI restrictions and rigid bank criteria create hurdles, they are far from insurmountable when you have the right documentation and a strategic narrative to tackle the mainstream banks. Whether you are using Alt-Doc solutions to prove your recent momentum or utilising a 2nd tier lender as a tactical stepping stone, the goal remains the same: securing a home that reflects your hard work.

At Mortgage Suite, we leverage over two decades of banking and lending expertise to ensure your business structure is understood, not just processed. If you dont fit the mainstream banks lending criteris, we specialise in 2nd tier loans that mainstream banks often decline, providing a tailored, NZ-wide service for business owners and contractors alike. You have built your business with passion and discipline; we are here to apply that same dedication to your mortgage approval.

If you are ready to move past the frustration of bank rejections, book a consultation with our self-employed lending specialists today. Let us turn your complex financial profile into a clear path forward. Your entrepreneurial journey deserves a partner who values your vision as much as you do.

Frequently Asked Questions

Can I get a home loan if I’ve only been self-employed for one year?

Yes, you can secure a home loan with only one year of trading, though you will likely need to look beyond the major banks. While traditional lenders typically require two years of financial statements, many specialist lenders offer "Alt-Doc" solutions for those with 12 months of history. These lenders focus on your recent GST returns and industry background to assess your current earning capacity properly.

How much deposit do I need as a self-employed borrower in NZ?

Most self-employed borrowers need a 20% deposit for an owner-occupied property or 30% for an investment. If you are a first-home buyer, you may qualify for the Kāinga Ora First Home Loan, which allows for a deposit as low as 5%. Having a larger deposit often helps offset the perceived risk of variable income and can lead to more competitive interest rates from mainstream lenders.

Will my interest rate be higher because I work for myself?

Your interest rate won’t necessarily be higher if you meet the standard lending criteria of a mainstream bank. However, if you require a specialist or 2nd tier lender due to a short trading history or complex accounts, you should expect a margin above standard bank rates. These "Near Prime" rates often start from 5.85% and serve as a strategic bridge until you can refinance to a major bank.

What are "add-backs" and how do they help my mortgage application?

Add-backs are legitimate business expenses that we "add back" to your net profit to demonstrate your true mortgage repayment capacity. Common examples include depreciation, one-off equipment purchases, or interest on loans that will be repaid. By identifying these non-cash or non-recurring costs, we can significantly increase the income figure used for your **self employed home loan **application and improve your approval chances.

Can I use my KiwiSaver for a deposit if I am self-employed?

Yes, you can certainly use your KiwiSaver for a deposit, provided you have been a member for at least three years and are purchasing your first home. Being self-employed does not change your eligibility for a first-home withdrawal. It is essential to request your withdrawal pack early to ensure the funds are ready for settlement, especially if your business income fluctuates and documentation takes longer to organise.

What happens if my latest tax return shows a low profit due to expenses?

If your latest tax return shows a low profit due to high business expenses, we can often use alternative documentation to prove your actual income. Specialist lenders may look at your last six months of GST returns or bank statements to see your current cash flow. This approach helps bypass the "paper loss" created by tax-minimisation strategies, allowing your true earning power to be recognised by the lender.

Do I need a clean credit history to get a self-employed home loan?

You don’t necessarily need a perfect credit history to get approved for a self employed home loan. While mainstream banks are very strict about missed payments or defaults, 2nd tier lenders are more flexible and will often listen to the story behind a credit impairment. A clean record for the last 12 months is usually sufficient to access a wide range of alternative lending options that banks often overlook.

How do DTI ratios affect my ability to borrow for a home?

Debt-to-Income (DTI) ratios limit your total borrowing to a multiple of your gross annual income, typically set at six times for owner-occupiers. For business owners, this means your personal and business debts are weighed against your verified drawings and profit. If your DTI is too high for a major bank, we can often find non-bank solutions that aren’t bound by these specific Reserve Bank restrictions in 2026.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.