
Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Your business success should be your greatest mortgage asset, not the reason a bank says no. It’s a common frustration for New Zealand entrepreneurs who feel penalised for their drive and independence. You’ve likely heard that traditional low doc home loans nz are harder to find now that the Financial Markets Authority has taken over credit regulation, but that doesn’t mean your home ownership dreams are over. We understand that your business bank statements often tell a much more accurate story than a standard tax return ever could.

You deserve a clear path to approval that doesn’t involve a mountain of confusing paperwork or endless anxiety. In this guide, we’ll show you exactly how to handle the 2026 lending market to get your home loan sorted. We will explore the rise of alternative documentation options, explain how second-tier lenders operate, and provide a step-by-step strategy to move from a bank decline to a front door key in your hand.

Key Takeaways

  • Being self-employed is a major achievement, and we will show you how to use your business success as an asset rather than a hurdle when applying for a mortgage.
  • Learn how traditional low doc home loans nz have evolved into flexible alternative documentation options from safe, regulated lenders who actually understand your business story.
  • Discover the specific, simple paperwork you need to show your true income without the stress of overwhelming accounting jargon or complex bank requirements.
  • Get practical tips on how to tidy up your accounts and why paying yourself a consistent salary can significantly boost your chances of loan approval.
  • Find out how to partner with a veteran advocate who knows the non-bank market inside out and will fight to get you into a home when the big banks say no.

What does it mean to get a mortgage for self-employed NZ borrowers?

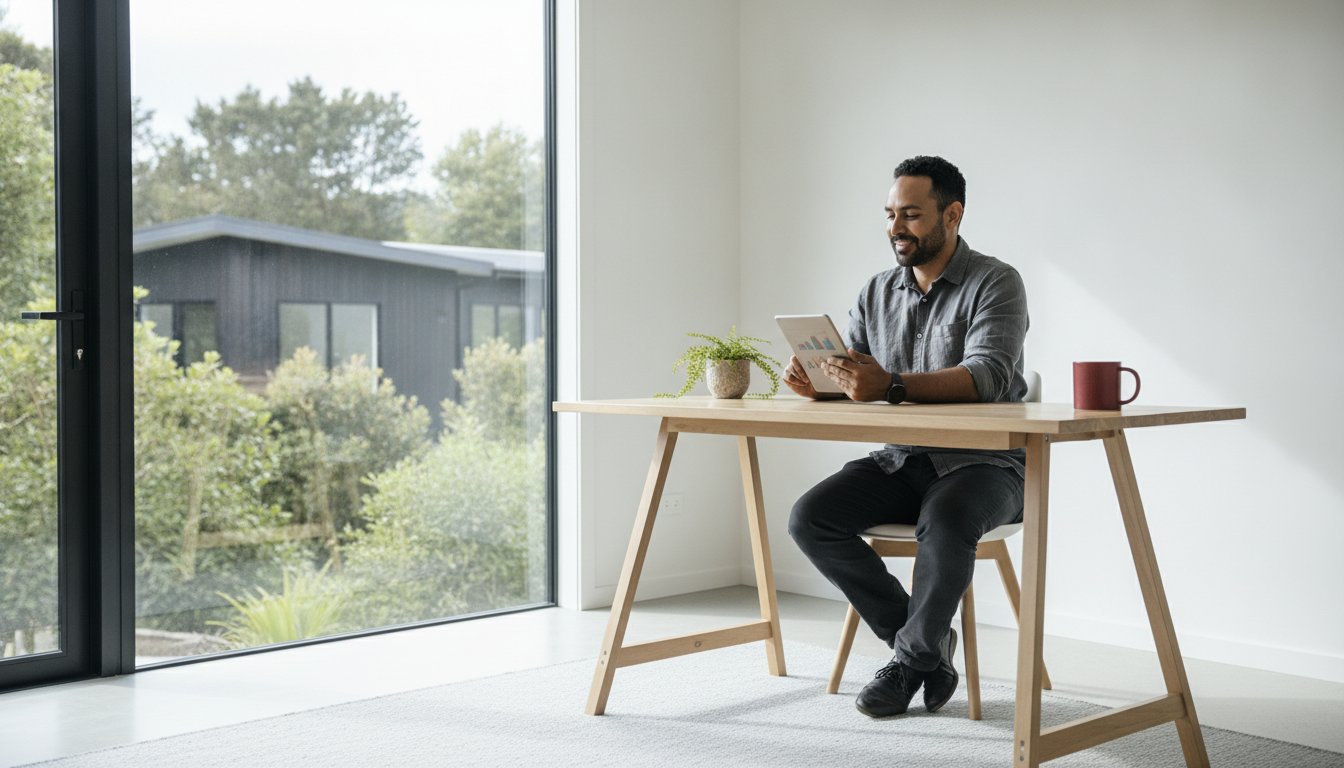
At its heart, a self-employed mortgage is just a standard home loan. It’s helpful to understand what is a mortgage in the broadest sense: a way to secure property using the equity you build over time. For you, the only real difference is how you prove you can afford the repayments. Banks often see your business as a risk, but we see it as a massive achievement. Whether you’re a tradie on the tools or a freelancer working from a home office, your drive shouldn’t be a hurdle to getting your own place.

Many Kiwis feel like they’re being penalised for their entrepreneurial spirit. If a mainstream bank has already said no, you might think you’re out of options. The market for low doc home loans nz has evolved significantly. While the big banks are often stuck in a cycle of strict criteria, other lenders are more interested in your actual business story and your ability to manage money. We help everyone from company directors and contractors to sole traders find a path forward.

Why the big banks treat you differently

Banks love predictability. They want to see a payslip that looks exactly the same every fortnight. When you run your own show, your income might go up and down depending on the season or when a big contract finishes. Mainstream lenders also tend to focus purely on your taxable income. Because you likely work with an accountant to legally minimise your tax, your “on paper” profit might look much lower than the actual cash you have available to pay a mortgage. In 2026, banks are using test rates around 7% to see if you can handle repayments. For a business owner with fluctuating income, meeting that hurdle while staying under the debt-to-income (DTI) cap of 6 can feel impossible without an expert in your corner.

The different types of self-employed income

Not all self-employment is the same. A full-time contractor might have a steady stream of work from one source, while a small business owner manages staff and overheads. Sometimes, a one-off business expense, like a new piece of machinery or a vehicle, can confuse a bank’s computer system and make it look like your business is struggling. If you’re just starting out on this journey, our First Home Buyer Guide is a great place to see how the basics apply to you. Specialised low doc home loans nz or alternative documentation options can bridge this gap by looking at your GST returns or bank statements instead of just a standard tax summary.

The paperwork you will need to get sorted

Gathering a mountain of files can feel like a full-time job. It’s often the point where many entrepreneurs give up before they’ve even started. You might worry that your accounts aren’t perfect or that a single quiet month will ruin your chances. In 2026, the concept of low doc home loans nz has shifted. It no longer means “no documents” at all. Instead, it refers to alternative documentation that fits your life better than a standard payslip. We act as your mentor through this process, helping you pick out the right files to show your financial strength.

The Big Three documents

Lenders typically focus on three core areas to understand your situation. First, your financial statements tell the story of your business profit and loss. We keep this simple. It’s about showing that your business is a viable, living entity. Second, you’ll need tax summaries from the IRD to prove your official earnings. Finally, personal bank statements are vital. Under current regulations managed by the Financial Markets Authority, lenders often look for at least six months of business bank statements to verify your cash flow. These personal records show how you handle your household budget and prove you can manage the commitment of a home loan.

Proving your future income

Banks are naturally cautious, so showing them a bright future is just as important as showing a solid past. If you have a stack of signed contracts or a healthy pipeline of work for the coming year, these are massive assets for your approval. A simple letter from your accountant can also go a long way. They can explain the longevity of your business and why certain one-off expenses shouldn’t count against you. Essentially, income verification is just the process of proving you have the actual cash on hand to cover your repayments without struggle.

If you’re feeling overwhelmed by the requirements, it’s often helpful to see what others in your position have achieved. You can read through our client reviews to see how we’ve helped other self-employed Kiwis get their paperwork sorted and their loans approved.

When the bank says no: Exploring 2nd tier and alternative lenders

Hearing a “no” from a mainstream bank can feel like a punch in the gut. You’ve worked hard to build your business, and being told you aren’t “predictable” enough is discouraging. It’s important to remember that a bank’s rejection isn’t a reflection of your business success. It’s simply a sign that you don’t fit their very narrow, rigid box. This is where 2nd tier lenders come in. These are professional, safe, and fully regulated finance companies that operate without the big bank branding. They specialise in low doc home loans nz because they have the freedom to look at the person and the business story, not just a standard spreadsheet.

Using a non-bank lender isn’t a last resort. It’s a strategic move used by many of New Zealand’s most successful entrepreneurs. These lenders are solution-based. They understand that a business owner’s wealth is often tied up in growth and assets rather than a static salary. For a deeper dive into how these finance companies can help you, check out our 2nd Tier Lender Guide.

Mainstream Banks vs. 2nd Tier Lenders

The differences between these two worlds are significant. Mainstream banks offer lower interest rates, but their rules are incredibly strict and their processes are often slow. If you don’t have two years of perfect, steady tax returns, they’ll likely struggle to say yes. In contrast, 2nd tier lenders offer more flexible rules. As of mid-2026, while mainstream rates for one-year fixed terms sit around 4.8%, non-bank rates for alternative documentation loans typically start from about 6.35%.

A 2nd tier loan is often used as a vital stepping stone. You can secure your home now, build equity for 12 to 24 months, and then refinance with a mainstream bank once your accounts have settled into a pattern the banks recognise. This proactive approach gets you into the property market years sooner than waiting for a bank’s approval.

The benefit of a specialised negotiator

Because the non-bank world is diverse, having a veteran mentor on your side is vital. We don’t just pass on your paperwork. We act as your advocate, carefully presenting your business to the right lender to ensure they see your success rather than a risk. Krish Krishna’s 20 years of industry experience means he knows exactly which lenders are currently looking for businesses like yours. We know how to tell your story in a way that opens doors that might otherwise stay shut. Our goal is to remove the stress and provide a clear, confident path to your new home.
Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Steps to improve your chances of approval

Preparing for a mortgage when you’re your own boss is all about presentation. Think of it like dressing your business up for an interview. One of the most effective things you can do is keep your personal and business expenses completely separate. When your accounts are clean, it’s much easier for a lender to see that your business is thriving and that you have the cash flow to handle a home loan. This clarity is especially important when we’re looking at low doc home loans nz, as it allows the lender to trust the alternative documents we provide.

Another great move is to pay yourself a consistent salary. Even if you own 100% of the company, regular transfers into your personal account look fantastic to a lender. It mimics the predictability of a standard job, which banks find very reassuring. You should also look at managing your existing debt. Clearing a car loan or closing an unused credit card can significantly boost how much you’re allowed to borrow. Before you get too far down the track, it’s a smart idea to use our mortgage calculator to see what a realistic repayment looks like for your budget.

Clean up your personal bank statements

In the three months before you apply, try to avoid any unusual spending spikes. Lenders look closely at your day-to-day habits to see how you’ll handle a mortgage. This is also the time to pause any “buy now, pay later” schemes. While they’re handy for small purchases, lenders often view them as a line of credit that reduces your overall borrowing power. Being squeaky clean with your bill payments and regular outgoings shows that you’re disciplined and reliable.

Timing your application

Timing can be everything. If you’ve just made a massive business investment, like buying new machinery or a fleet of vehicles, your cash reserves might look a bit low. It’s often better to wait until those investments start showing a return. The sweet spot for many self-employed Kiwis is right after the end of the financial year on March 31st. This is when your latest figures are fresh and your accountant can provide the most up-to-date proof of your success. Loan readiness is about showing you are a safe pair of hands. If you’re ready to see what’s possible for your business, get in touch with us today to start the conversation.

How Mortgage Suite helps self-employed Kiwis get home

At Mortgage Suite Ltd, we don’t believe your business success should be a barrier to buying a home. We take an advocacy-led approach to every application. This means we don’t just bundle up your paperwork and hope for the best. We actively fight your corner with lenders to make sure they see the full value of what you’ve built. Because we are a business ourselves, we understand the long hours and the dedication it takes to be your own boss. We aren’t a cold corporate office; we are your partners in this process. Whether you’re looking for a property in the far north or the deep south, our national reach means we can help you secure a home anywhere in New Zealand.

If you’re curious about how this works in practice, we encourage you to read our client reviews. You’ll see stories from other Kiwis who thought their dream was over after a bank decline, only to find a path forward with us. We know that every business has a unique story, and we make it our mission to ensure that story is heard by the right people.

A personal approach from an industry veteran

Krish Krishna brings over two decades of banking and finance experience to the table. He uses this deep institutional knowledge to navigate the often complex world of low doc home loans nz and alternative lending. The Mortgage Suite Ltd way is about removing the weight from your shoulders. We aim to make a process that usually feels overwhelming into something that is sorted and stress-free. You can learn more about us and our philosophy of partnership. We believe in building long-term relationships, not just processing one-off transactions.

Your next steps to home ownership

Taking the next step doesn’t have to be scary. Our first conversation is simply about understanding your goals and where you want to go. There is absolutely no pressure and definitely no confusing jargon. We’ll look at your current situation and build a clear, actionable plan together. Our goal is to move you from a “declined” status to a firm approval. You’ve already done the hard work of building a successful business. Now, let’s work together to build your future in a home you actually own. Getting your low doc home loans nz sorted is much easier when you have a veteran mentor who knows exactly which levers to pull.

Take the lead on your home ownership journey

Building a business is a major achievement that proves you have the drive to succeed. While big banks might focus on rigid boxes, you now know that alternative documentation and second-tier lenders offer a professional, regulated path to your new home. Securing low doc home loans nz is about finding the right lender who understands your unique story and sees your success as an asset. By tidying your accounts and paying yourself a consistent salary, you’re already halfway there.

With over 20 years of banking expertise, our team at Mortgage Suite acts as your dedicated negotiator. We specialise in non-bank and second-tier lending, and we know exactly how to open doors that mainstream lenders often keep shut. We’ll handle the complex paperwork so you can focus on what you do best: running your business. Ready to get your mortgage sorted? Book a chat with the Mortgage Suite team today. Your entrepreneurial spirit has built your business, now let’s use it to build your future in a home of your own. You’ve got this.

Frequently Asked Questions

Can I get a mortgage if I’ve only been self-employed for one year?

Yes, you certainly can. While major banks typically look for two years of accounts, many second tier lenders only require six to twelve months of trading history. We focus on showing the strength of your business through GST returns and bank statements. If your industry experience is solid and your current cash flow is healthy, we can often find a solution that gets you into a home much sooner than a bank would allow.

Do I need a bigger deposit if I’m self-employed in NZ?

Not always, but it helps to be prepared. If you fit a bank’s standard criteria, a 20% deposit is the norm. For those using low doc home loans nz or alternative documentation, lenders might ask for 20% to 30%. This larger deposit acts as a safety net for the lender. However, we have seen cases where a smaller deposit is possible depending on the strength of your business story and the specific property you are buying.

What is a low doc loan and is it right for me?

In 2026, these are often called “alt doc” loans. They are designed for business owners who have a solid income but don’t have standard tax returns ready yet. Instead of IRD summaries, the lender looks at your bank statements or GST filings. It’s a great fit if you’ve recently invested back into your business or have a complex income structure that a standard bank computer doesn’t understand or recognise as stable.

Will I have to pay a higher interest rate because I work for myself?

Not necessarily. If you qualify for a standard bank loan, your rate will be the same as any other borrower. However, if you need the flexibility of a non-bank lender, you should expect to pay a bit more. As of mid-2026, non-bank rates for low doc home loans nz often start around 6.35%. Many of our clients see this as a temporary cost to get into the market before refinancing later on.

Can I use my business profit to help with my mortgage application?

Absolutely. Lenders focus on your net profit before tax. We also work with your accountant to identify “add-backs.” These are one-off business expenses, like a new vehicle purchase or depreciation, that shouldn’t count against your ability to pay a mortgage. By adding these back into your profit, we can often show a much stronger income than what appears on your final tax bill, which helps with your borrowing power.

What happens if my business had a bad year recently?

A single quiet year isn’t an automatic decline. We look at the reason behind the numbers. If you had a dip because of a strategic investment or a one-off event, we can explain that story to a lender. Many second tier lenders are happy to look at your most recent six months of trading to see that your business has recovered and is currently performing well. It’s about showing your current financial health.

How do I prove my income if I’m a contractor?

Proving income as a contractor is all about showing your track record. Lenders will want to see your current signed contracts, your GST returns, and at least six months of business bank statements. They look for a pattern of regular payments and a healthy pipeline of future work. If you’ve been in the same industry for a long time, that experience counts for a lot even if you are relatively new to contracting.

Why should I use a broker instead of going straight to my bank?

Your bank only has one set of rules and one list of products. If you don’t fit their box, they simply say no. A broker has access to dozens of lenders, including specialised second tier companies that don’t deal with the public directly. We act as your advocate, using over twenty years of experience to tell your business story to the right person. We find the “yes” that your bank might have missed.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage for Self Employed NZ: The 2026 Guide to Getting Approved

You’ve spent years building a successful business, only to have a bank manager look at your tax returns and tell you that you don’t earn enough to buy a family home. It’s a frustrating irony. While you’re contributing to the 17% of New Zealand’s GDP generated by the self-employed, the traditional lending system often makes you feel like a second-class citizen. Securing a mortgage for self employed NZ business owners shouldn’t feel like a battle against your own success, especially when your accountant is doing their job by minimising your taxable income.

We know that your bank statements tell a much richer story than a single line on a tax summary. It’s completely normal to feel overwhelmed by the endless paperwork or anxious about how a fluctuating income looks to a rigid credit department. This guide is designed to cut through that confusion and show you exactly how to present your finances to get a “yes”. You’ll learn how to navigate 2026 bank requirements, understand the “add-backs” that boost your borrowing power, and discover why a non-bank lender might be the partner your business actually deserves.

Key Takeaways

  • Discover how to tidy up your personal and business bank statements 90 days before you apply so the bank sees exactly what they want.
  • Learn the hidden ways lenders calculate your income and how to protect your borrowing power even if your accountant has reduced your taxable profit.
  • Find out why 2nd tier lenders are often the best choice for a mortgage for self employed NZ business owners who don’t fit into a standard bank box.
  • Understand the “add-back” process that lets you count certain business expenses as income to help you qualify for a larger loan.
  • Gain a clear path to approval by using two decades of banking expertise to negotiate with lenders on your behalf.

Why being your own boss makes banks nervous (and how to fix it)

Being your own boss is the ultimate Kiwi dream. You have the freedom to call the shots and build something of your own. However, for a bank, that freedom often looks like “risk”. Mainstream lenders are built on a foundation of predictability. They love seeing a steady salary hit a bank account every fortnight. When you’re self-employed, your income might go up and down depending on the season or a big project. This fluctuation makes credit departments nervous because they can’t easily put you into a standard box.

The reality is that the problem usually isn’t how much you earn. It’s how that income is presented. Getting a What is a mortgage? approved as a business owner isn’t impossible; it just requires a different strategy. You can’t just hand over a few payslips and call it a day. Securing a mortgage for self employed NZ requires showing the bank that your business is a reliable engine that can support a long-term commitment. You can learn more about how banks think and how to prepare your finances at our mortgage school.

The difference between how you and the bank see profit

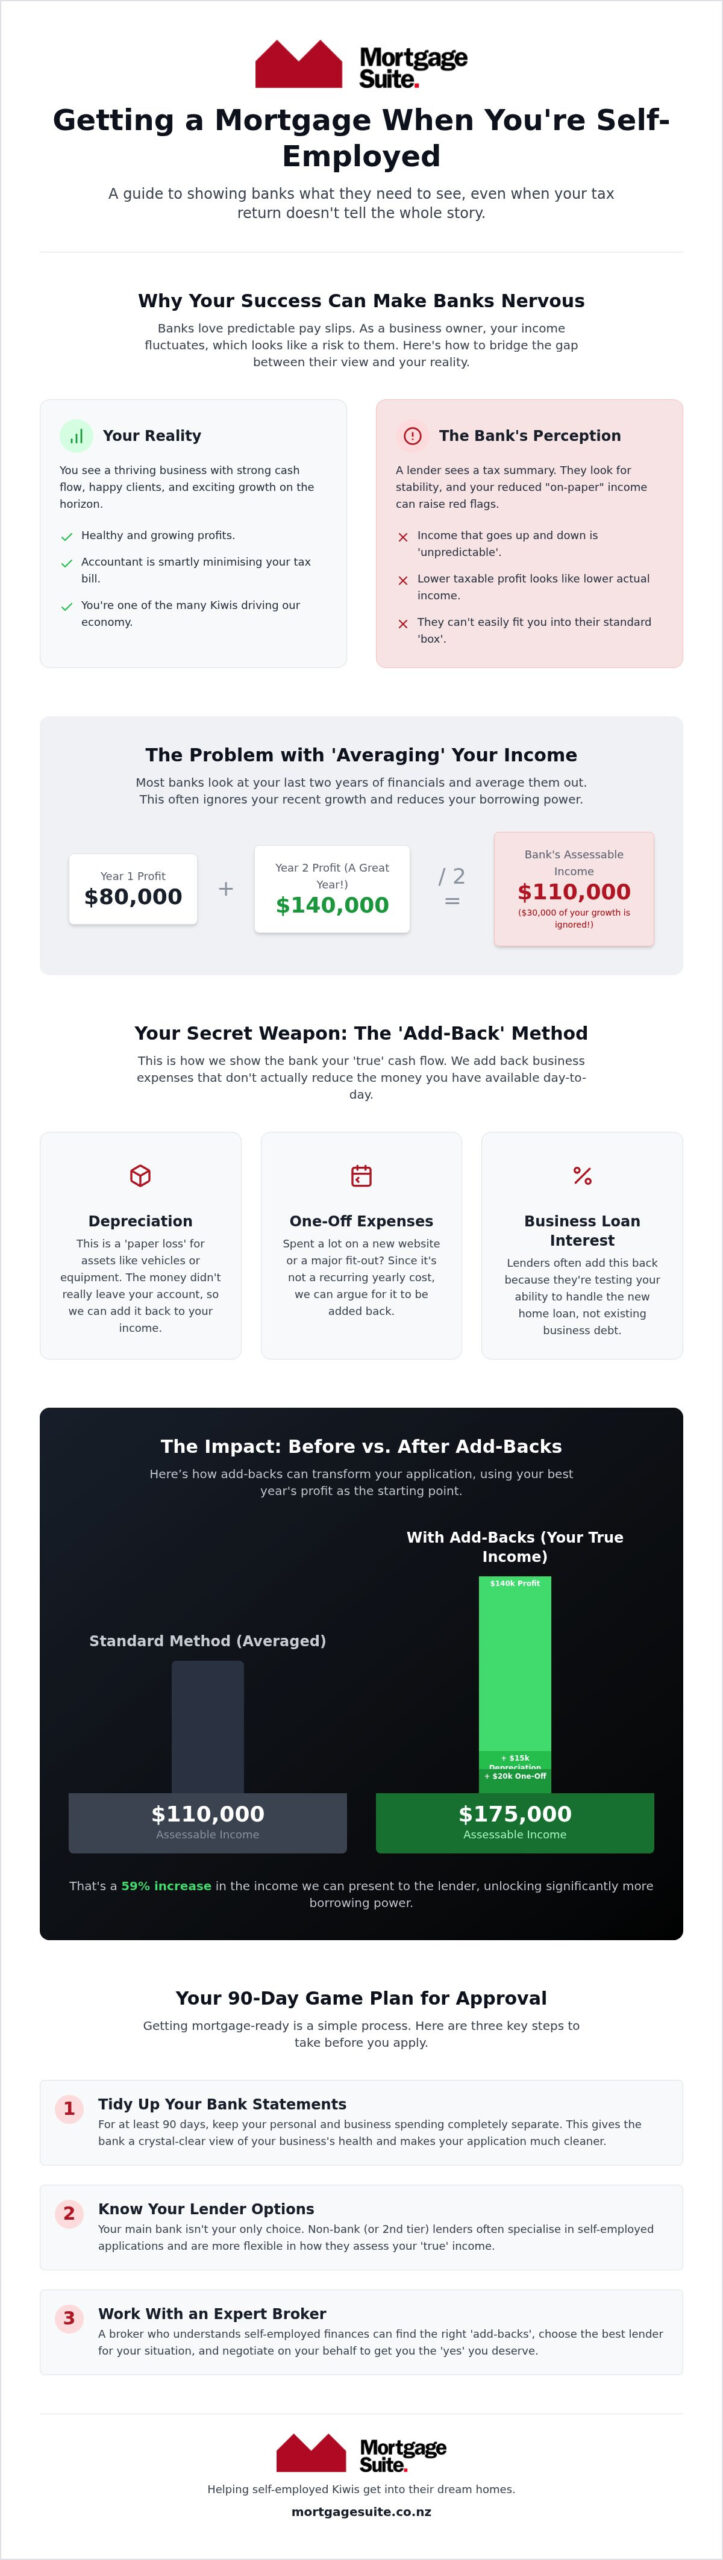
You likely look at your business and see a growing venture with healthy cash flow and happy clients. The bank looks at your financial statements and sees a list of potential liabilities. Your accountant’s job is often to reduce your taxable income to save you money at tax time. While that’s great for your pocket, it can hurt your borrowing power. Lenders apply a “stability test” to see if your profit is consistent. They want to know that if the market dips, you can still meet your repayments without stress.

The common hurdles for sole traders and company directors

If you’re a sole trader, the biggest hurdle is usually mixing your personal and business money. Banks will scrutinise your bank statements to see if your business is actually funding your lifestyle or if it’s struggling to stay afloat. It’s a common trap that’s easily fixed with a bit of organisation. By keeping these accounts separate, you provide a clear window into the business’s actual health.

Company directors face a different set of questions. The bank will look closely at your shareholder salary and any earnings you’ve kept in the business. They want to see that the company is strong enough to keep paying you even during quiet months. To improve your chances, start thinking like a bank manager. Look for patterns of growth and keep your records tidy. If you can prove your business has a steady pulse, you’re halfway to a “yes”. We see the hard work behind the mortgage for self employed NZ application and know how to present that value to the right lender.

Cracking the code: How lenders actually calculate your income

Most banks in New Zealand want to see your last two years of financial statements to get a handle on your earnings. They typically take the profit from year one and year two, then average them out to find a middle ground. This is their way of checking for stability, but it can be incredibly frustrating if your most recent year was much better than the one before. If you earned $80,000 in 2024 but jumped to $140,000 in 2025, a standard bank might still only “count” you as earning $110,000. It feels like they are ignoring your hard-earned growth and punishing your success.

This is where the “Add-back” method becomes your secret weapon. Add-backs are non-cash expenses or one-off costs that increase your real borrowing power. By identifying these specific items, we can often show the lender that your actual cash flow is much higher than what your tax return suggests. It’s about bridging the gap between what your accountant says to the IRD and what the bank needs to see to approve your mortgage for self employed NZ application.

The magic of “Add-backs” explained simply

Banks are looking for your “true” income, so they allow us to add back certain expenses that don’t actually affect your daily cash flow. We look for these three common items first:

  • Depreciation: This is a “paper loss” for things like vehicles or equipment. It reduces your tax bill, but the money didn’t actually leave your bank account this month.
  • One-off expenses: If you spent $20,000 on a new website, a major office move, or a specific piece of machinery, that’s a one-time cost. It won’t happen again next year, so the bank can often ignore it.
  • Interest on business loans: Lenders often add this back because they are testing your ability to handle your new home loan, not your old business debt.

What if you only have one year of accounts?

Sometimes a business is too new for the two-year rule, or perhaps you’ve recently changed your business structure from a sole trader to a company director. While the big banks might show you the door, certain flexible lenders are happy to look at just one year of accounts if the business is performing well. This is common for high-growth sectors where the first year was spent setting up and the second year is where the real profit kicked in.

You can use our mortgage calculator to see how these different income figures change what you might be able to borrow. Understanding these nuances is the difference between a decline and an approval. If you want to see how your specific business numbers stack up, it’s a good idea to talk to an expert who can present your mortgage for self employed NZ case to the right lender.

Bank vs Non-Bank: Finding the right fit for your business

Most Kiwis head straight to the “Big Four” banks when they want a home loan. It’s a natural first step, but for a business owner, it can be a disheartening one. These mainstream lenders are set up for simplicity. They prefer applicants with a fixed salary and a tidy PAYE history. If your situation is even slightly complex, you might find yourself facing a brick wall. However, a “no” from a major bank isn’t the end of the road. It’s often just a sign that you need a different path to secure a mortgage for self employed NZ business owners.

This is where 2nd tier lenders, or non-bank lenders, come into play. These institutions specialise in borrowers who don’t fit into a standard box. They have the flexibility to look at the “why” behind your numbers rather than just the “what”. They understand that a dip in profit might mean you were reinvesting in growth, not that your business is failing. Learn more about 2nd tier lender New Zealand options to see how they differ from the traditional banks.

When to choose a 2nd tier lender

There are several scenarios where a non-bank lender is actually the smarter first choice. If you have been in business for less than two years, or if your company structure is particularly complex, 2nd tier lenders are far more likely to listen. They are also the primary providers of “Low Doc” (low documentation) loans. These are perfect if your full financial statements aren’t ready but you have other ways to prove your income, such as GST returns or business bank statements.

It’s important to be realistic about the trade-off. Because these lenders take on more perceived risk, their interest rates are typically higher than the “special” rates offered by mainstream banks. As of mid-2026, rates for these alternative loans often start around 6.35% and can go higher depending on your specific profile. You might also expect an establishment fee of 1% to 2%, but for many, this is a small price to pay for the keys to a new home.

The “Bridge” strategy: Moving back to the bank

You don’t have to stay with a non-bank lender for the entire life of your loan. We often use them as a “bridge”. This strategy involves getting you into your home now using a 2nd tier lender, then spending the next 12 to 24 months tidying up your financials. Once you have a clean track record of repayments and two years of solid accounts, we can look at refinancing you back to a mainstream bank with lower rates.

This approach is a particularly smart move for home loans for first home buyers who are self-employed. It allows you to get onto the property ladder while house prices are moving, rather than waiting years for your paperwork to be “perfect” for a big bank. We act as your partner throughout this entire transition, ensuring you always have a clear path toward the best possible deal for your mortgage for self employed NZ.

Mortgage for Self Employed NZ: The 2026 Guide to Getting Approved

The 90-day game plan to get your application mortgage-ready

Preparation is the difference between an immediate “yes” and a long, drawn-out “maybe”. When you apply for a home loan, the bank isn’t just looking at your business profit; they are looking at your personal financial habits. They will scrutinise every line of your personal and business bank statements to see how you handle money. The goal is to show a clear, consistent pattern of saving and spending that proves you can handle the responsibility of a mortgage for self employed NZ borrowers.

Getting your ducks in a row before you even talk to a lender is the best way to avoid unnecessary stress. Think of this 90-day window as a chance to present the absolute best version of your financial life to the credit manager. It’s about removing any “red flags” that might give a bank an excuse to decline your application.

Tidying up your bank statements

In the three months leading up to your application, you need to be on your best behaviour. Avoid “un-arranged overdrafts” or late fees at all costs. To a bank manager, a $15 overdraft fee looks like a sign of poor cash flow management, even if it was just an oversight. It’s also vital to keep your business and personal spending strictly separate. If you’re constantly dipping into the business account to pay for groceries, it makes the bank’s job much harder and can slow down your approval significantly.

You should also look at reducing “discretionary” spending where possible. Those daily café runs or weekend shopping trips might not seem like much, but they can lower your “affordability score”. Banks calculate how much you can borrow based on what’s left over after your daily living costs. By tightening the belt for 90 days, you show the lender that you have the discipline to manage a larger commitment and a successful mortgage for self employed NZ.

The paperwork checklist for self-employed Kiwis

Having a tidy folder makes for a much smoother application process. Banks have a zero-tolerance policy for tax debt, so ensure your GST and income tax payments are completely up to date before you submit anything. To get started, you will need to gather the following:

  • Your IR3 summaries for the last two financial years.
  • A full set of financial accounts, including your Profit & Loss and Balance Sheet.
  • Confirmation from your accountant that your tax affairs are in order.

If you’re feeling unsure about which documents you need or how to present them, check out our Mortgage School for more tips on document prep. We’ve seen every possible scenario and know exactly what a credit manager is looking for. To ensure your application is as strong as it can be, you can start your 90-day preparation with us today.

How an expert broker negotiates a “Yes” for you

A mortgage broker isn’t just a middleman who passes papers from one person to another. When you are looking for a mortgage for self employed NZ, a broker acts as your advocate and chief negotiator. We don’t just “submit” an application and hope for the best. Instead, we build a comprehensive case that highlights why you are a fantastic borrower, even if your tax returns don’t tell the whole story. With over 20 years of banking experience, Krish Krishna knows exactly how to speak the bank’s language and what buttons to push to get a deal over the line.

Understanding the “inside” of a bank’s decision-making process is a massive advantage for our clients. We know the specific criteria each lender uses and, more importantly, we know their current appetites. Some banks might be wary of certain industries, while others are actively looking to grow their small business portfolio. You can read our client reviews to see how this insider knowledge has turned a “no” into a “yes” for countless Kiwi business owners.

The power of the “Cover Letter”

The numbers on a Profit & Loss statement are just data points. They don’t show your personal passion, your 15 years of industry expertise, or the major contract you just signed for the coming year. That’s why every application we send includes a detailed cover letter. We tell the “story” behind your business numbers. If there was a dip in profit because you moved offices or upgraded your fleet, we explain that clearly so the bank manager sees it as an investment in growth rather than a sign of struggle.

Our goal is to remove obstacles before the bank even has a chance to bring them up. By pre-empting their questions and providing the answers upfront, we make it much easier for a credit manager to approve the loan. We highlight your business’s future potential and your proven track record, ensuring the mortgage for self employed NZ process feels like a partnership rather than a confrontation.

Your partner in property

Running a business is a full-time job, and you don’t have the hours to waste on a constant back-and-forth with a bank. We handle the stress, the follow-up calls, and the technical queries so you can stay focused on your clients. We aren’t interested in one-off transactions; we want to be your steady hand in a fluctuating market for years to come.

You can learn more about us and our passion for helping Kiwis get ahead. We’re here to ensure that being your own boss helps you get into a home, not holds you back. Whether you are buying your first place or growing an investment portfolio, we provide the seasoned professionalism you need to succeed.

Take the next step toward your new home

Securing a mortgage for self employed NZ business owners doesn’t have to be a source of stress. By understanding how lenders view your income and using strategies like “add-backs” or 2nd tier lending as a bridge, you can overcome the hurdles that often stop others. A bank’s rigid rules aren’t the final word on your financial success. With the right preparation and a clear 90-day plan, you can present a case that even the toughest credit manager will respect.

At Mortgage Suite Ltd, we aren’t just processing applications; we’re building partnerships. Krish Krishna uses over 20 years of expert banking experience to navigate complex loan profiles and find the right fit for your unique business. As a passionate Kiwi-owned and operated brokerage, we specialise in finding solutions when mainstream banks say no. Don’t let your business success hold back your home ownership dreams. Book a free, honest chat with Krish to sort your mortgage today. We are ready to help you move forward with confidence.

Frequently Asked Questions

Can I get a mortgage if I have been self-employed for less than two years?

Yes, you certainly can, though mainstream banks usually prefer a 24-month history. If your business is performing well after just one year, we can look at specialist lenders who prioritise current cash flow over long-term history. These lenders often use your GST returns or latest bank statements to verify your income. This flexibility allows you to secure a home loan without waiting for multiple years of tax returns to be finalised.

How much deposit do I need for a self-employed home loan in NZ?

Most self-employed borrowers will need a 20% deposit for an existing owner-occupied home. While some first-home schemes allow for 5%, these have strict income caps that many business owners exceed. If you are looking at an investment property, you will generally need 30%. Having a solid 20% deposit is often the “hard rule” for 2nd tier lenders in 2026, as it offsets the perceived risk of fluctuating business income.

What documents do I need to provide if I do not have a formal accountant?

If you manage your own books, you can still apply by providing your IR3 summaries directly from myIR. You will also need to provide at least six months of business bank statements and your most recent GST returns. These documents help the lender see the “real-time” health of your business. We specialise in helping business owners organise this paperwork to ensure it meets the strict requirements for a mortgage for self employed NZ.

Can I use my business profit to pay for my house deposit?

Yes, you can use retained earnings or business profit for your deposit, usually by paying yourself a dividend or a director’s salary. The lender will want to see that withdrawing this cash won’t negatively impact your business’s ability to pay its bills or trade effectively. It is a good idea to chat with us early so we can help you time this withdrawal correctly without making the bank nervous about your cash flow.

What happens if the bank declines my self-employed mortgage application?

A decline from a mainstream bank is often just a “not today” rather than a “never”. We start by reviewing the bank’s feedback to see if the issue was your income calculation, deposit size, or account conduct. Often, we can move the application to a 2nd tier lender who has more flexible rules. Alternatively, we can create a 90-day plan to fix the specific issues and reapply once your financial profile is stronger.

Is the interest rate higher for self-employed borrowers?

If you meet the standard criteria of a mainstream bank, your interest rate will be the same as any other borrower. However, if you require a “Low Doc” or specialist loan because your financials are complex, the rates are typically higher. In 2026, these alternative rates often start from 6.35%. While this is higher than a standard “special” rate, it provides the flexibility needed to get you into a home sooner.

Can I get a mortgage if I have some tax debt with the IRD?

Mainstream banks have a zero-tolerance policy for tax debt, but specialist lenders are often more pragmatic. If you have a formal repayment plan in place with the IRD and a history of making those payments on time, we can often find a solution. In some cases, we can even structure the new mortgage to pay off the tax debt entirely. This clears your record and simplifies your monthly outgoing payments into one manageable loan.

How does a 2nd tier loan help me get into a house sooner?

2nd tier lenders focus on your ability to afford the loan today rather than sticking to rigid historical rules. They are far more likely to accept a shorter business history or alternative proof of income, such as six months of bank statements. This means you don’t have to wait years for your tax returns to catch up with your actual business success. It is a faster path to securing a mortgage for self employed NZ when banks say no.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.