What if your deposit isn’t the only number shaping your investment property borrowing options? For Kiwis, the investment property loan to value ratio nz is a useful starting point, but it doesn’t decide the whole application. The lender’s valuation, your income and your existing debts can all affect how much it may be willing to lend.
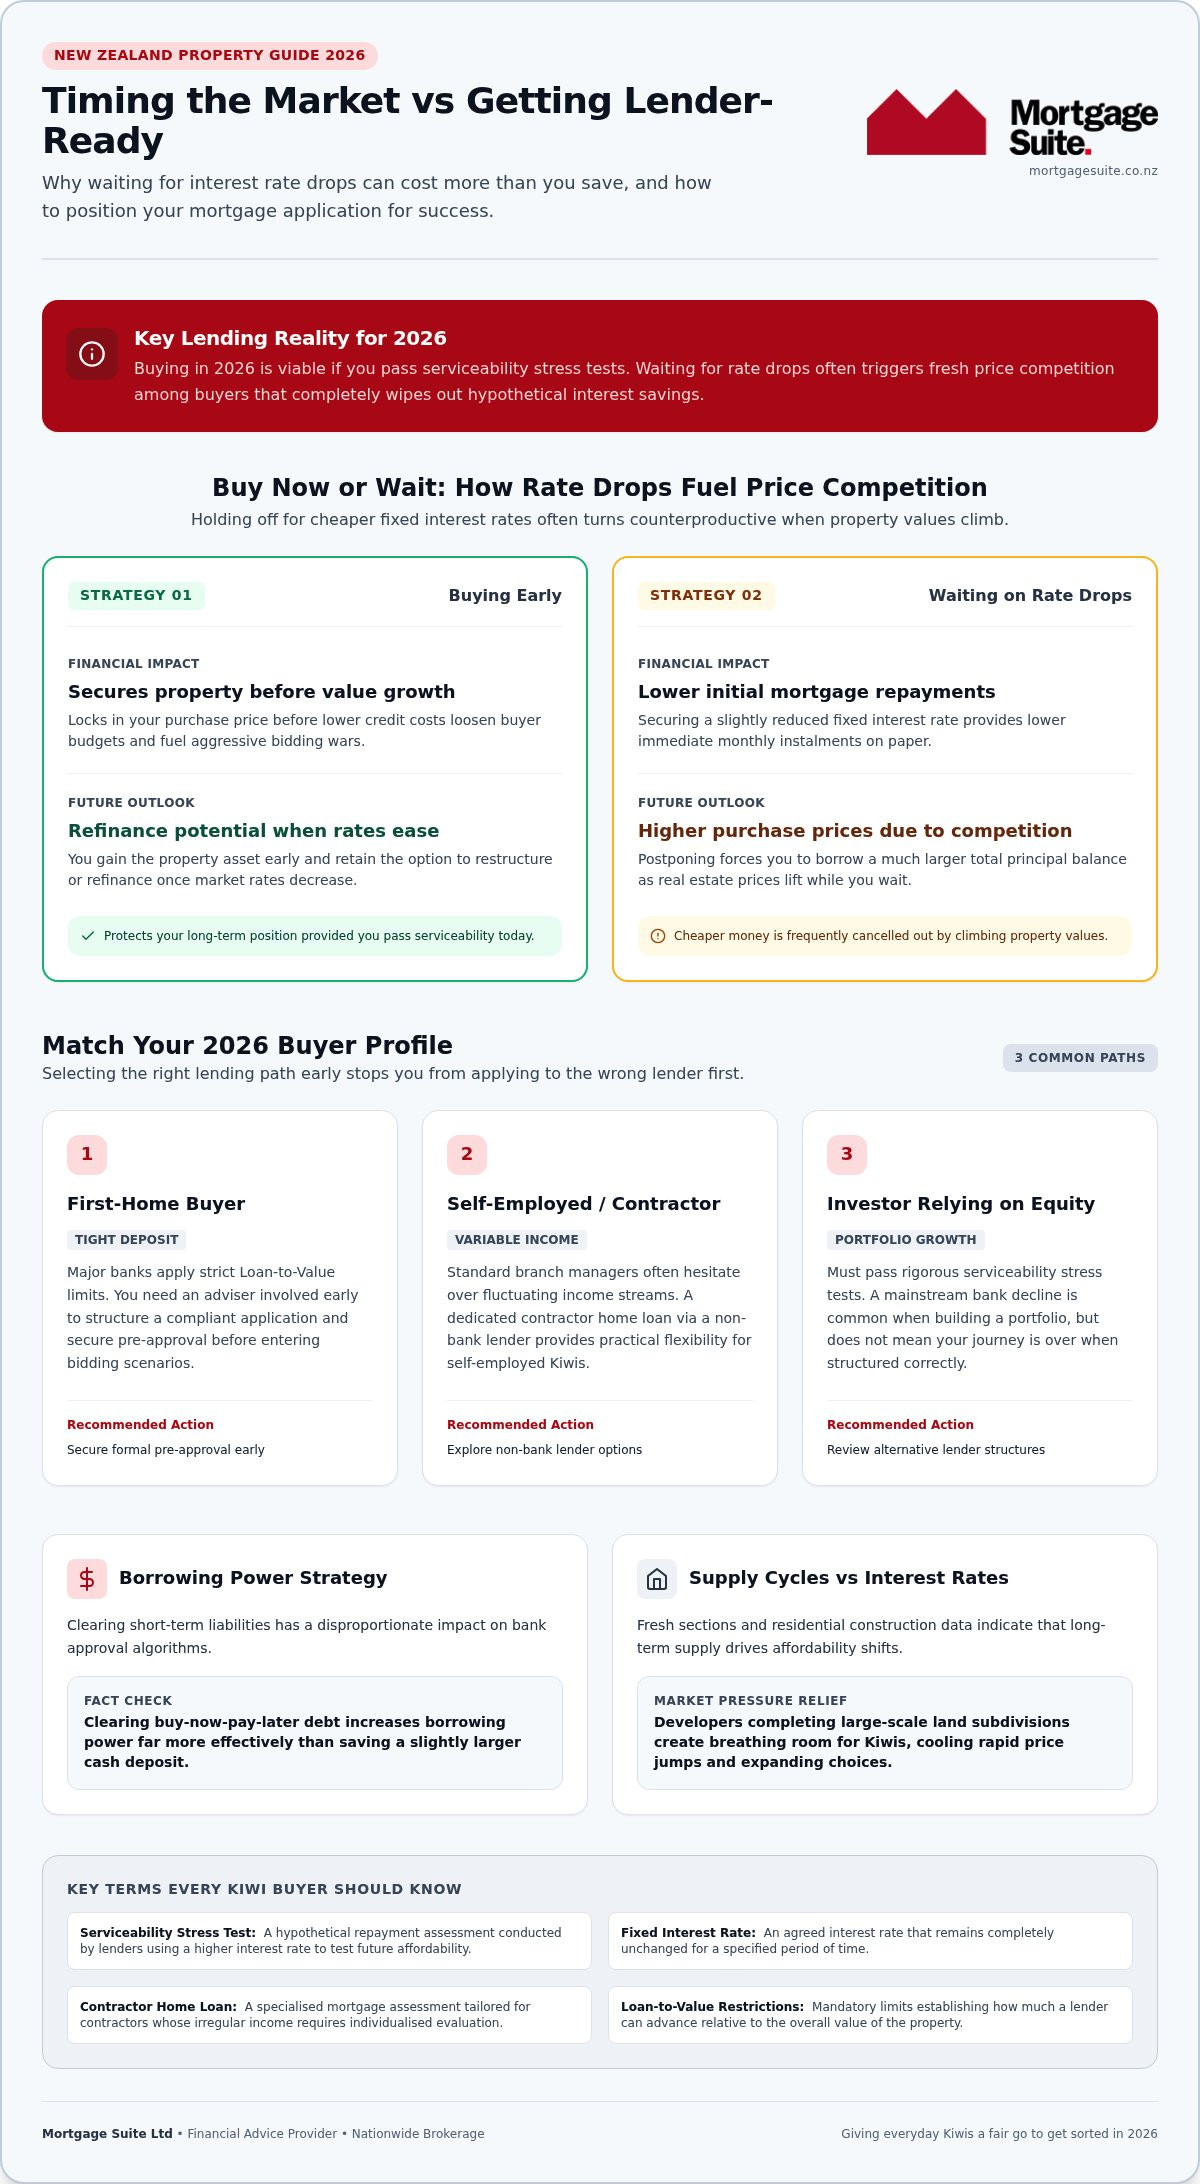
For an existing investment property, the Reserve Bank’s standard Loan-to-Value restrictions generally set a 70% LVR, meaning a 30% deposit. That’s separate from a lender’s own criteria, and limited high-LVR lending doesn’t guarantee an offer. Lenders also assess whether your income can support repayments, including through a serviceability stress test.
This guide explains how to calculate LVR, how a valuation could affect your plans, and how Reserve Bank restrictions differ from individual lender decisions. You’ll also learn what to discuss before making an offer and how a new-build property or alternative lending pathway may affect your options. Mortgage Suite Ltd can help you consider the full picture and compare possible routes, while the lender makes the final decision.
Key Takeaways
- Learn how to calculate the investment property loan to value ratio nz lenders consider, using the loan amount and lender-assessed property value.
- See why Reserve Bank Loan-to-Value restrictions and a lender’s own assessment are separate parts of the lending picture.
- Gather details about your deposit or available equity, income, debts and expected rent before discussing finance.
- Understand how the property itself, including its valuation and rental information, may form part of the lender’s assessment.
- Explore how Mortgage Suite can help compare mainstream and alternative lending options based on your circumstances. The lender decides whether to approve an application.
What does investment property loan to value ratio mean in NZ?
Loan-to-value ratio, usually shortened to LVR, can sound technical when you’re planning an investment property purchase and weighing up the property, deposit and loan. Put simply, the investment property loan to value ratio nz is the loan amount divided by the value the lender accepts for the property, expressed as a percentage. It shows how large the loan is compared with the assessed value, but it doesn’t tell you by itself whether a lender will approve your application.
The Loan-to-value ratio is a common way to describe the relationship between borrowing and property value. Understanding the calculation helps you make sense of the figures. Remember, though, that a lender considers more than this one measure.
How is an investment property LVR calculated?
Use this formula:
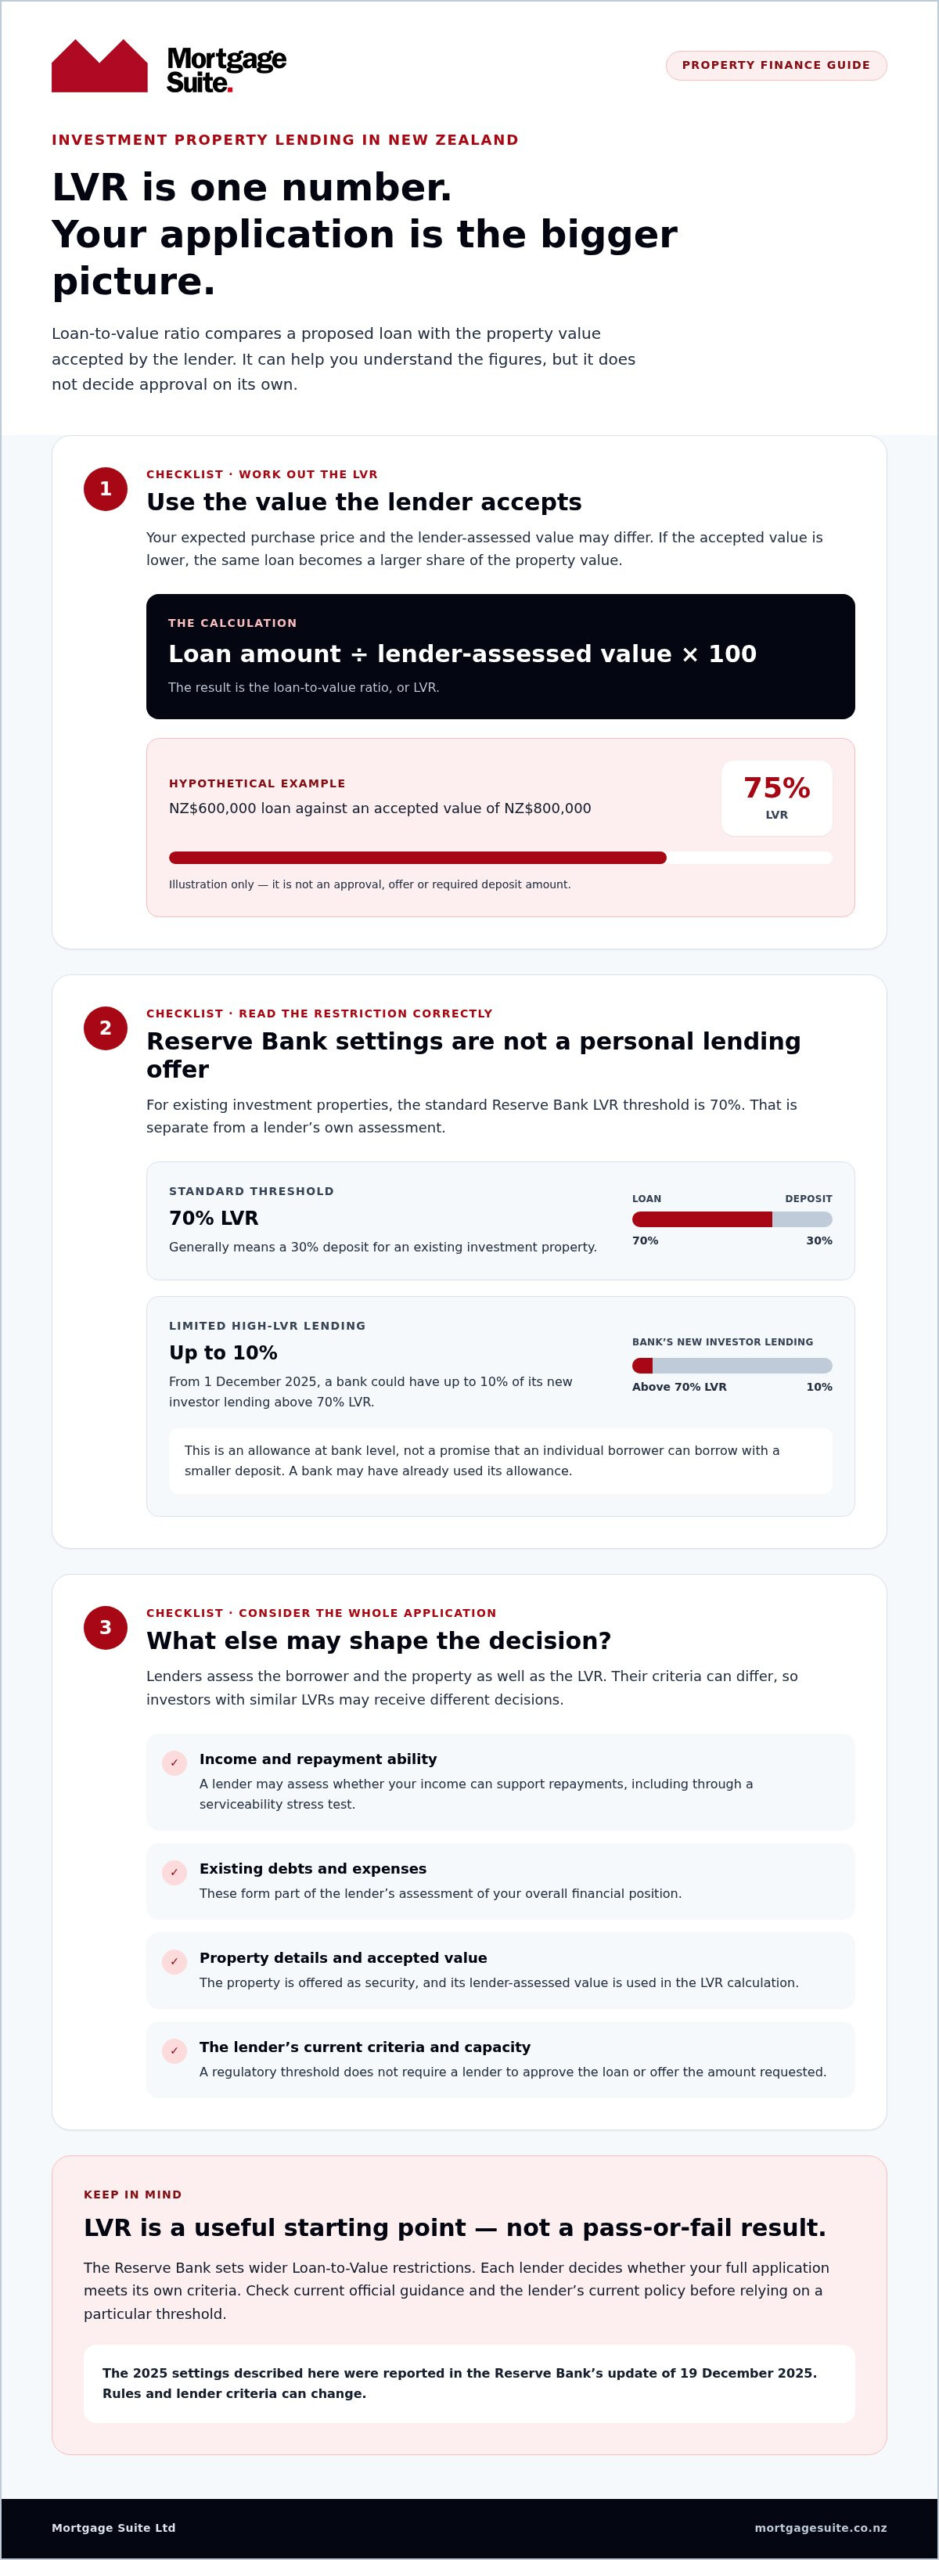
LVR = loan amount ÷ lender-assessed property value × 100
Hypothetical calculation, not an approval or offer: If a lender accepts a property value of NZ$800,000 and the proposed loan is NZ$600,000, the calculation is NZ$600,000 ÷ NZ$800,000 × 100, giving an LVR of 75%. These figures are for illustration only. They don’t suggest a required deposit or indicate what a lender would offer in a real application.
The value used in the calculation matters. Your expected purchase price and the value accepted by the lender may differ. If the accepted value is lower than you anticipated, the same loan amount represents a larger share of the property’s value, resulting in a higher LVR. Treat your own estimate as a planning guide rather than assuming the lender will use the same figure.
What does a lower or higher LVR tell you?
A lower LVR means the loan is smaller relative to the property’s assessed value. It generally also means you have more equity in the property, based on that value and loan amount. Equity is the part of the property’s value not covered by the loan, although other lending secured against the property can affect the overall picture. A higher LVR means the loan makes up a larger share of the assessed value.
Think of LVR as one part of the discussion, not a pass-or-fail result. It doesn’t account for your full financial position, including income, existing debts or ability to manage repayments. Lenders consider the wider application, and their criteria can differ. A figure that looks workable on paper isn’t a promise of approval. Equally, a higher LVR doesn’t tell the whole story about your circumstances.
LVR measures the loan against the property’s assessed value. A lending decision also considers the borrower and the full application. Keeping that distinction in mind helps you understand what the percentage shows and what it can’t tell you.
How do New Zealand LVR restrictions affect investment loans?
Understanding the investment property loan to value ratio nz rules means separating two things: restrictions set by the Reserve Bank of New Zealand (RBNZ) and the lending decision made by an individual bank. The restrictions can shape how much high-LVR residential lending banks may make. They don’t set a personal borrowing limit for every investor, and they don’t require a bank to approve a loan just because an application fits within a regulatory setting.
For existing investment properties, the RBNZ’s published settings, as reported in its update of 19 December 2025, set a standard 70% LVR threshold for investor lending. Banks can make a limited share of new lending above that threshold: from 1 December 2025, up to 10% of a bank’s new lending to investors could be above 70% LVR. This is a bank-level allowance, not a promise that a particular borrower can borrow with a smaller deposit. A bank may also have already used its available high-LVR lending allowance.
What is the difference between a Reserve Bank restriction and lender policy?
The RBNZ sets Loan-to-Value restrictions that influence how banks can lend against residential property. Each lender then assesses the borrower and property under its own credit criteria. That assessment may consider the full application, including income, debts, expenses and the property offered as security. Meeting a regulatory threshold is only one part of the picture. It doesn’t guarantee that a lender will offer finance or accept the amount requested.
Two investors with similar LVRs may receive different decisions. Their income, existing commitments, property details and overall applications can differ, and lenders may apply different policies. A bank’s willingness to consider lending above the standard threshold can also depend on its available high-LVR lending allowance.
Why can investor LVR settings change?
The RBNZ reviews restrictions as conditions and risks change, and lenders can also adjust their own criteria. The 2025 settings provide a dated reference point, not a guarantee that rules will stay the same. Before basing plans on a particular threshold, check the RBNZ’s current official guidance and the relevant lender’s current policy. This is especially useful when comparing lending options or preparing to make a purchase.
Reserve Bank restrictions set the wider rules for bank lending, while each lender decides whether your application meets its own criteria. Keeping those decisions separate can make a decline easier to understand. It may reflect a lender’s assessment or current lending capacity, rather than a final judgement on your plans. Other lending channels may assess applications differently, but no pathway guarantees approval.
If you’re weighing up an investment purchase, Mortgage Suite can help you understand how the rules and your circumstances fit together. Discuss your investment property lending options with a personal advocate who can help compare mainstream and alternative lending pathways.
What else can affect an investment property loan beyond LVR?
LVR shows how the proposed loan compares with the property’s accepted value, but it doesn’t show whether the repayments look manageable. A lender may also assess your income, regular expenses, existing debts and other borrowing. Together, these details provide a fuller picture of your finances and whether the proposed loan fits your circumstances.
For an investment property, expected rent and property details may also form part of the assessment. Rental income can be considered alongside other income, while the property is assessed as security for the loan. The lender’s view may differ from your expectations, so allow for uncertainty when planning rather than relying on a particular rent figure or valuation.
How does affordability fit alongside LVR?
Affordability is about whether repayments appear manageable after the lender considers the money coming in and the commitments going out. That can include your income, regular household and financial expenses, existing loans and credit commitments, as well as the proposed investment borrowing. A deposit that supports a particular LVR doesn’t, on its own, show that the repayments will suit your overall position.
A lender may also use a serviceability stress test, which checks whether repayments could remain manageable if calculated using a higher interest rate than the rate you may initially pay. It tests your ability to cope with changes. It isn’t a prediction of your future rate or repayment. The lender determines the rate and method, so a calculator estimate can’t reproduce the full assessment.
Use the mortgage calculator to explore possible repayments and see how different loan amounts or terms may affect them. Treat the result as a planning tool, not a lending decision or confirmation that a lender will offer the loan.
Why can the property and valuation change the picture?
The LVR calculation depends on the value the lender accepts, which may differ from the price you expect to pay or your own estimate of the property’s worth. If the accepted value is lower than expected, a proposed loan represents a larger share of that value, which can change the LVR. If you’re planning an offer, consider how a different valuation could affect the amount you need to borrow and your next steps.
The lender may also look at the property’s type, condition and likely saleability when deciding whether it is suitable security. The property supports the loan, so the lender assesses the asset as well as your ability to repay. The weight given to each detail can vary between lenders and applications.
That’s why the investment property loan to value ratio nz is only one part of the decision. Looking at your finances, expected rental information and the property together can help you prepare a more realistic borrowing plan. A particular valuation or repayment estimate doesn’t guarantee approval.
How can you prepare before applying for investment property finance?
Getting organised before you discuss a purchase can make the lending conversation clearer and help you spot unanswered questions early. Start with a simple plan, then gather details about your finances and the property. This gives you a more useful starting point than focusing on a single LVR figure or assuming every lender will take the same view.
- Outline your plan. Note what you hope to buy, why it suits your longer-term plans and when you expect to proceed. Separate confirmed details from estimates.
- Gather a financial snapshot. Record your available deposit or equity, income, existing loans and regular commitments.
- Clarify the property. Collect the details you have, such as the expected purchase price, property type, condition and realistic rental information.
- Discuss lending options. Use the information to talk through possible borrowing structures, lender requirements and what needs to happen before you make a firm commitment.
What information should an investor organise?
A concise summary is a practical first step. Include income sources, current borrowing, regular financial commitments and funds available for the purchase. For the property, note its key details and any rental estimate you’re using. Make clear which figures are confirmed and which are your best estimate. Keep sensitive financial documents secure and provide them through an appropriate process rather than sharing them in a public comment or post.
Before a conversation, it can help to understand the basic terms and write down what you want to know. That makes it easier to explain your plans and ask focused questions about your investment property loan to value ratio nz and the wider application.
What questions help clarify the lending pathway?
Use your discussion to understand how the lender may assess the property’s value and the borrowing you’re proposing. Ask what information could affect that assessment, how expected rent fits into the application, and what repayment structure may suit your plans. Consider how long you intend to hold the property and whether your plans could change. The lending structure needs to be considered alongside your wider goals.
Before making an offer, get clear on any finance conditions, key dates and what must be in place before those dates. A solicitor or other appropriate property professional can help you understand the conditions and timing in an offer. A mortgage broker can help present your application and negotiate with suitable lenders, including across mainstream and alternative lending channels. That support can help you understand your options, but it can’t guarantee a lender’s decision.
If you’re ready to talk through your plans, talk through your investment property finance options with Mortgage Suite and consider the next steps with a personal advocate.
How can Mortgage Suite help you assess investment property lending options?
It can be hard to know what to do next when the numbers, property details and lender requirements don’t seem to line up. Mortgage Suite can help you consider these pieces together: your goals, financial position, the property and its LVR. This wider view helps frame the questions to discuss and the possible lending paths to explore, without treating one percentage as the whole answer.
Mortgage Suite works across mainstream and alternative lending channels, supporting borrowers as a personal advocate and negotiator. Founder Krish Krishna brings more than two decades of banking experience to the business. That experience can help make a complex lending conversation easier to follow, while each lender still makes its own assessment and no particular outcome is guaranteed.
When might a tailored lending discussion be useful?
A tailored discussion may help if you’re unsure which lender’s criteria could suit your circumstances, or if your income, existing commitments or property plans make the application less straightforward. It can also help you understand how your investment property loan to value ratio nz fits with the rest of your position, rather than focusing on LVR alone.
If a mainstream bank has declined your application, that isn’t necessarily the end of the discussion. Different lending channels may assess an application in different ways, and an adviser can help you understand whether another path may be worth exploring. That doesn’t mean every application or property will qualify, so approach the conversation with realistic expectations.
What should you expect from the next conversation?
The discussion starts with what you’re aiming to do and the financial circumstances behind your plan. You can talk through the property, available deposit or equity, income, existing borrowing and any concerns about valuation or repayments. From there, Mortgage Suite can help explain how those details may fit different lenders’ requirements and what information could help present your application clearly.
Possible pathways depend on the lender’s assessment, the property and the requirements that apply at the time. A conversation can clarify likely next steps and points that need attention, but it isn’t an approval or a guarantee of finance. If your plans or circumstances are complex, explaining them early can keep the discussion focused on what matters to you.
You don’t need to have every answer before asking questions. For a calm, practical discussion about your circumstances and possible next steps, discuss your investment property loan options with Mortgage Suite.
Take your next step with a clear plan
A property purchase can move quickly, but taking time to understand your position before you commit can help you make decisions with greater confidence. Use your next step to turn the numbers you’ve gathered into a conversation about what matters to you: your plans for the property, the borrowing you’re considering and the questions still to be answered.
The investment property loan to value ratio nz is one part of that discussion, not a verdict on your plans. If your situation feels complicated, or a lender’s response has left you unsure where to turn, you don’t have to work through the options alone. Mortgage Suite was founded by Krish Krishna in 2000 and supports borrowers as they consider possible lending pathways. Any option depends on the lender’s assessment, so approval can’t be promised.
When you’re ready, talk with us about your investment property loan options. A calm, focused conversation with Mortgage Suite can help you identify practical next steps and move forward with a clearer sense of direction.
Frequently Asked Questions
Can I use equity in another property towards an investment property loan?
Yes, equity may contribute to the funds available, but it isn’t the same as cash already approved for your deposit. For example, owning a property with substantial equity doesn’t automatically mean a lender will let you borrow against it for another purchase. The lender will assess the property offered as security, any lending already attached to it and your wider finances. Get an assessment before relying on equity in your purchase plan.
Does a bank valuation always match the investment property’s purchase price?
No, the lender’s accepted value may differ from the agreed purchase price or an online estimate. If you agree to buy at one value but the lender uses a lower figure, the borrowing being considered may need to be reviewed. Ask which valuation or report the lender will use and how it affects your application. Don’t assume the sale price alone sets the value used for the LVR calculation.
Can I get an investment property loan with a small deposit?
It may be possible, but a smaller deposit can mean a higher LVR, and that’s only one part of the decision. For investment property loan to value ratio nz planning, consider current Loan-to-Value restrictions alongside lender policy, your finances and the property details. Rules can change, so avoid basing an offer on old information. A mortgage adviser can help you understand what a lender may need to assess your situation.
Do all lenders use the same investment property LVR rules?
No. Reserve Bank restrictions can affect banks, while lenders also set their own criteria and assess applications individually. One lender’s response doesn’t necessarily predict another’s. If you’re comparing options, look beyond the headline LVR and consider the proposed repayments, loan structure and conditions too. Mortgage Suite can help you compare mainstream and alternative lending pathways, though each lender makes its own decision and may apply different requirements.
Can a high rental income make up for a high LVR?
Rental income may support an application, but it doesn’t automatically offset a high LVR or secure approval. A lender may assess it alongside your other income, existing debt, regular expenses and the property’s value. For example, a rent estimate based on current listings may not be treated the same as confirmed rental information. Use realistic figures and make clear which details are estimates so the lender can consider the full picture.
Is LVR the same as a deposit percentage?
No. LVR compares the loan with the property value, while a deposit is your contribution towards the purchase. In a simple example, those percentages may appear to add up to the full property value, but a real transaction can include other funds, existing lending and a lender valuation that differs from the purchase price. Treat the maths as a guide to the relationship between borrowing and value, not as a decision on finance.