Most Kiwi investors believe the interest rate is the most important part of their mortgage, but in 2026, a “cheap” rate won’t save you if your loan structure is actually blocking your next purchase. If you’ve ever felt stuck after buying just one or two properties, it’s usually not a lack of equity or income holding you back. It’s often the way your debt is organised. Getting the right advice on structuring investment property loans nz is now the difference between a stagnant portfolio and a growing one, especially with the current debt-to-income (DTI) limits of seven times your income.
We understand that the fear of the bank taking your family home if an investment fails is a heavy burden to carry. It’s a common worry that keeps many people from taking the next step. You want to build a legacy for your family, not put their roof at risk. This guide will show you exactly how to set up your property loans to protect your personal assets, maximise your borrowing power, and move your portfolio forward at a faster pace. We’ll explore how to navigate the 2026 lending environment, from managing DTI rules to using lenders that look beyond the standard bank boxes.
Key Takeaways
- Discover why the way you organise your debt matters far more than snagging the lowest interest rate when it comes to your long-term wealth.
- Find out how to separate your personal home from your rentals so you never have to worry about the bank having too much control over your family’s future.
- Learn why thinking beyond the big banks and properly structuring investment property loans nz can help you bypass rigid debt-to-income limits.
- Get clear on whether paying only the interest or chipping away at the loan itself is the best move for your 2026 cash flow goals.
- Understand why a strategic property plan is a marathon rather than a sprint and how the right expert help can unlock your future borrowing power.
Why the way you set up your loan matters more than the interest rate
It’s easy to get fixated on the numbers at the bottom of a bank’s flyer. Most investors spend hours comparing interest rates, hoping to shave a tiny fraction off their monthly repayments. While that’s understandable, it’s often a distraction from a much bigger risk. A low rate on a poorly organised loan can actually end up costing you hundreds of thousands of dollars in lost capital growth. If you can’t borrow for that third or fourth property because your bank says “no”, you miss out on the compounding gains of those assets over the next decade. That’s a massive price to pay for a slightly lower rate today.
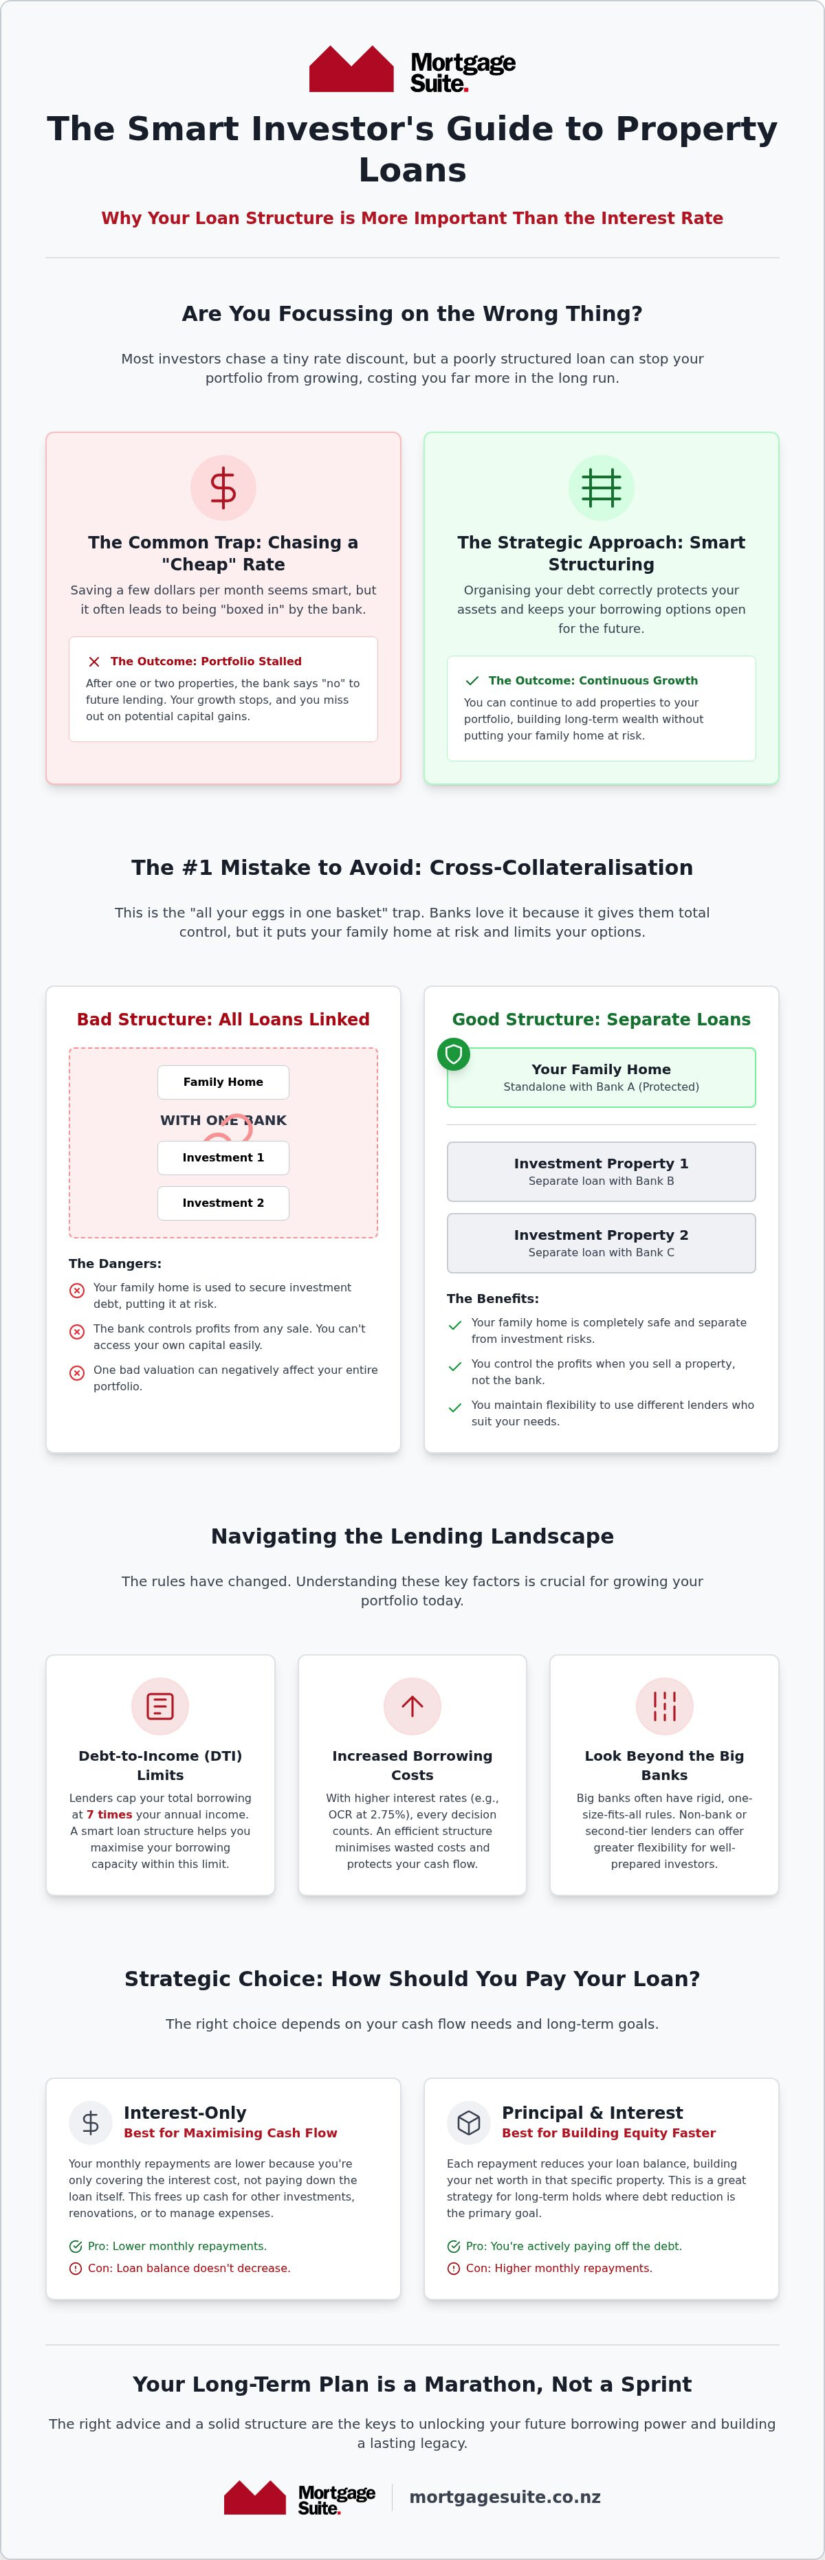
When we talk about structuring investment property loans nz, we’re really talking about protecting your future borrowing power. If you set things up the wrong way, you might find yourself “stuck” after your first or second property because you’ve accidentally handed all the control to the bank. This happens when the bank uses your family home to secure everything, leaving you with very little room to move when you want to expand your portfolio.
What exactly is loan structuring?
In simple terms, loan structuring is the way your debt is organised across different banks and properties. It’s about deciding which assets secure which loans and whether those loans are linked together. Think of it as building a house. You wouldn’t spend all your money on expensive taps if the foundation was built on shifting sand. Good structure provides a solid foundation. It involves Avoiding cross-collateralisation, which keeps your family home safe from your investment risks. When your loans are structured correctly, you maintain “options” that allow you to pivot when the market or your life changes. You can learn more about these mechanics in our Mortgage School, where we break down how lending actually works behind the scenes.
The 2026 context: Why things have changed
The rules of the game have shifted significantly. In 2026, banks are being more careful than ever. With the Debt-to-Income (DTI) limits introduced a couple of years ago, your ability to borrow isn’t just about how much your house is worth; it’s about how your income is viewed by the lender. Since the Reserve Bank raised the OCR to 2.75% in September 2026, the cost of borrowing has increased, making every decision more impactful. We see many clients who have plenty of equity but can’t buy their next property because their current bank has “boxed them in” with rigid rules. By looking at the big picture, we help you protect your borrowing power so you can keep growing even when the big banks are tightening their belts.
The ‘all your eggs in one basket’ trap: Avoiding cross-collateralisation
Banks love it when you keep all your loans in one place. They often frame it as a way to “simplify” your life, but the reality is much more one-sided. This setup, often called cross-collateralisation, means the bank uses every property you own to secure every loan you have. It gives them maximum security and leaves you with very little control. When you’re structuring investment property loans nz, this is the number one trap to avoid if you want to keep your family home safe and your investment options open.
One of the biggest risks is the “Sale of Property” clause hidden in the fine print. If your loans are linked and you decide to sell one investment property, the bank can step in and take all the profit to pay down your other debts. You might have been counting on that cash for a new deposit or a renovation, but the bank gets to decide where that money goes first. By keeping your properties separate, you ensure that you, not the bank, decide how to spend your hard-earned capital.
How the ‘linking’ trap works in real life
If your home and your rentals are tied together, your entire financial life is at the mercy of a single bank’s valuation. If the market dips and one property loses value, the bank might suddenly view your whole portfolio as “risky.” They could freeze your credit limits or demand you pay back more of the principal. This is why we always recommend keeping your personal home as a standalone asset, completely separate from your investment debt. Cross-collateralisation is essentially the bank using all your properties to back every loan, which is a position you never want to be in.
Steps to un-link your properties
Breaking free from this trap is a process, but it’s worth the effort for the peace of mind it brings. Here is how you can start to untangle your finances:
- Use different lenders: The most effective way to protect your home is to have your home loan at one bank and your investment loans at another.
- Demand standalone security: When setting up a new loan, ensure the documentation only lists the specific property being purchased as security.
- Refinance away from all-in-one facilities: Many older loan structures use a single “limit” backed by multiple houses. Moving to separate, fixed-term loans is often a smarter move.
You can use our mortgage calculator to see how much equity you currently have. This is a great first step in working out if you have enough leverage to move your investment loans to a different lender. Deciding between Interest-only or paying off the principal is also much easier when your loans aren’t all tangled together. If you’re not sure how your current loans are set up, having a quick chat with someone who knows the system can clarify things quickly.
Interest-only or paying off the principal: Which path is right for you?
Deciding how to pay back your bank is a massive part of structuring investment property loans nz. You have two main choices: paying just the interest or paying both the interest and the loan amount together. In 2026, “Cash Flow is King” has become the mantra for successful investors. With the Official Cash Rate at 2.75% and Debt-to-Income (DTI) limits generally capped at seven times your income, every dollar that leaves your account needs to be justified. Choosing the wrong repayment path can quickly dry up your cash reserves and stop your growth in its tracks.
A smart strategy many seasoned investors use is to focus on paying off their own home first while keeping their investments on interest-only terms. Since the interest on your family home isn’t tax-deductible, it makes sense to clear that debt as fast as possible. By keeping your investment debt separate and paying only the interest, you maximise your tax efficiency. It’s a winning move that helps you get rid of “bad” debt while your “good” investment debt works for you. Just make sure you chat with your accountant to ensure this setup fits your specific tax situation.
When interest-only makes sense
Interest-only payments keep your monthly “out-of-pocket” costs as low as possible. This is vital when you’re trying to grow a portfolio because it leaves more cash in your pocket at the end of each week. That extra money can be funnelled into a separate account to build a deposit for your next property faster. It’s important to remember that in 2026, most big banks will only let you stay on interest-only for a set period, often five years, before they want you to start paying back the principal. You need a plan for when that term ends so you don’t get a nasty surprise.
The argument for paying it all down
There is a lot to be said for the peace of mind that comes with seeing your debt balance actually drop. Paying off the principal means you are building equity in your properties every single month, regardless of what the market is doing. This extra equity can then be used as security for more loans later on. The trick is to find a “sweet spot” between growth and security. You want enough cash to live comfortably and keep buying, but you also want to know that you’re slowly becoming debt-free. If you’re unsure where you stand, you can check your current equity levels with our mortgage calculator.
Thinking outside the big banks: When a second-tier lender makes sense
Many people assume that 2nd tier lenders are only for those who’ve made financial mistakes. That’s a huge misconception. In the current market, these lenders are often the secret weapon for smart investors who are structuring investment property loans nz to keep growing. When the big four banks start tightening their belts, a non-bank lender can offer the oxygen your portfolio needs to survive and thrive. It’s not about being a “bad” borrower; it’s about being a strategic one.
Mainstream banks are often bound by very strict, “one-size-fits-all” rules. If you don’t fit perfectly into their box, they simply say no. Non-bank lenders, on the other hand, often have more practical ways of looking at your situation. They might be more willing to accept a higher percentage of your rental income or look at your business earnings with a bit more common sense. This is often the “key” that unlocks property number three or four when a big bank has slammed the door shut. At Mortgage Suite, we pride ourselves on knowing exactly which non-bank door to knock on for your specific needs.
The flexibility of non-bank lenders
These lenders often look at your “real-world” income differently. While a big bank might use a very conservative “stress test” on your interest rates, a non-bank might use a more realistic figure. This can significantly increase your borrowing capacity under the current DTI rules. They are also fantastic for short-term needs, like bridging finance if you’ve bought before selling, or funding a quick renovation to add value. Simply put, 2nd tier lending is a professional alternative to mainstream banking that prioritises results over rigid paperwork. You can find out more in our 2nd tier lender new zealand your 2026 guide to alternative home loans.
Is a non-bank loan more expensive?
Let’s be honest about the numbers. Yes, the interest rates at a second-tier lender might be slightly higher than what you’d see on a billboard for a major bank. However, you have to weigh that against the “cost of doing nothing.” If a slightly higher rate allows you to secure a property that grows in value by fifty thousand dollars in a year, that small extra interest cost is a drop in the ocean. You aren’t just paying for money; you’re paying for the opportunity to grow.
We often use a “stepping stone” strategy with our clients. This involves using a non-bank lender to get the deal done now, then moving the loan back to a big bank once your equity has grown or your income has increased. It’s about being proactive and finding a path forward when others see a dead end. You can read through our Mortgage Suite reviews to see how other Kiwi investors have used this exact path to build their wealth. If you’re feeling stuck with your current bank, reach out for a consultation so we can explore the alternatives together.
Creating your long-term property plan with a bit of expert help
Successfully structuring investment property loans nz is a marathon, not a sprint. It’s about looking five or ten years down the track, not just at next month’s repayment. If you only talk to a bank teller, you’re getting a product that fits their sales target today. A teller isn’t there to help you buy your fourth house in three years. You need a partner who understands the long game and how each choice today impacts your options tomorrow. We’re here to make sure you don’t just get a loan, but a strategy that supports your life goals.
The rules in New Zealand change fast. We’ve seen the Bright-line test shift to two years and the OCR climb to 2.75% in September 2026. Because the environment is always moving, your strategy for structuring investment property loans nz needs to move with it. We recommend a full review every 12 to 24 months. This ensures you’re still protected and still have the best possible path to your next purchase. If you’re curious about how we work and why we’re so passionate about this, you can learn more about us and our client-first philosophy.
The value of a veteran negotiator
Krish Krishna brings over 20 years of banking experience to your side of the table. He’s seen every market cycle and knows exactly how banks think. At Mortgage Suite, we act as a steady hand for our clients through every hurdle. We don’t just take the easiest offer the bank gives us; we fight for the structure that actually works for you. Our job is to clear the path and remove the obstacles, so you can focus on finding the right property to add to your collection. We handle the complex negotiations so you don’t have to deal with the stress.
Your next steps to a better structure
Getting started is easier than you think. First, gather your current loan documents for a quick health check. You might be surprised at how a few small tweaks can unlock a lot of potential. We also encourage you to keep learning through our Mortgage School resources. It’s packed with information to help you stay ahead of the curve. Let’s get your property investment journey sorted for 2026 and beyond. We’re here to help you build a portfolio that truly lasts. Give us a call for a no-worries chat whenever you’re ready to take that next step.
Take the next step toward your property goals
Building a successful portfolio in 2026 isn’t just about finding the right house; it’s about having the solid foundation that only a smart strategy can provide. By avoiding the trap of linking your family home to your investments and choosing a repayment path that protects your cash flow, you keep the power in your hands. Mastering the art of structuring investment property loans nz ensures that you’re never “stuck” when the next great opportunity comes along.
With over 20 years of banking and mortgage expertise, Mortgage Suite acts as your steady hand in a fluctuating market. We offer access to both mainstream banks and 2nd tier lenders, specialising in the complex investment and development finance that often stumps the big banks. Our mission is to remove the obstacles standing in your way so you can focus on growing your wealth. Book a friendly chat with the Mortgage Suite team today to get your structure sorted. We’re here to help you move forward with confidence.
Frequently Asked Questions
What is the best way to structure an investment property loan in NZ?
The most effective approach is to keep your loans standalone and separate from your family home. This protects your personal assets and keeps your options open for future growth. Many successful investors use a mix of interest-only terms for their rentals while aggressively paying off their own home. This keeps cash flow high and debt manageable. Every situation is unique, so it’s vital to have a plan that matches your long-term goals.
How much deposit do I need for an investment property in 2026?
In 2026, you generally need a 30% deposit for an existing investment property, which means a 70% loan-to-value ratio. However, if you’re looking at a new build, the requirement is often lower at 20%. Some non-bank lenders might offer more flexibility depending on your overall financial position. It’s also possible for banks to lend to a small number of investors with less than a 30% deposit, though these spots are limited and highly competitive.
Can I use the equity in my own home to buy a rental property?
Yes, using the equity in your own home is a very common way to fund a rental property deposit. You can often top up your current home loan to release cash, which then acts as the deposit for your new investment. The key is to ensure the new investment loan is kept at a separate bank where possible. This prevents the properties from being linked together, which keeps your family home much safer if the market changes.
What are DTI ratios and how do they affect my property investment?
Debt-to-income (DTI) ratios limit how much you can borrow based on your yearly earnings. In 2026, investors are generally capped at borrowing seven times their total income. This rule makes structuring investment property loans nz even more critical because you need to ensure every dollar of income is counted correctly by the lender. If your big bank says your DTI is too high, we can often find second-tier lenders who look at your income with more flexibility.
Is it better to have all my loans with one bank or spread them out?
Spreading your loans across different banks is usually the smarter move for investors. While having everything in one place might seem easier, it gives that single bank too much control over your life. If they decide to change their rules or lower your credit limits, your whole portfolio is affected. By using multiple lenders, you maintain your borrowing power and ensure that a problem at one bank doesn’t stop your entire property journey.
Can I get an investment loan if the big banks have already said no?
If the big banks have turned you down, it doesn’t mean your journey is over. We specialise in 2nd tier loans that don’t fit the standard bank boxes. These lenders often have different rules for things like income, age, or property types. Using a non-bank lender can be a great stepping stone to get a deal done now, with the plan to move back to a mainstream bank once your equity or income has grown.
What is cross-collateralisation and why should I avoid it?
Cross-collateralisation is when a bank uses all your properties to secure every one of your loans. You should avoid it because it gives the bank the right to take the profit from any property sale to pay down your other debts. It also means your family home is at risk if an investment fails. Keeping your loans standalone ensures that you stay in the driver’s seat and can make your own decisions about your money.
How often should I review my loan structure?
You should review your loan structure every 12 to 24 months. Lending rules, interest rates, and your own life goals can change quickly, so what worked two years ago might be holding you back today. A regular health check ensures you’re still on the best rates and that your structure is still protecting your home and maximising your growth. It’s also a good time to check your equity levels as the market moves.