Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

What if the biggest hurdle to your next purchase isn’t the bank’s ‘no’, but the way your current loans are tied together? For many Kiwi investors, the challenge of financing multiple investment properties nz has become a bit of a puzzle lately. You’ve probably noticed that mainstream banks are getting sticky about further lending; meanwhile, with the Official Cash Rate at 2.75% as of September 2026, those interest rates are likely putting a squeeze on your rental yields. It’s frustrating when you know the equity is there, but the red tape feels like it’s tightening around your long-term goals.

I know it’s confusing to deal with the new 7x debt-to-income (DTI) limits while trying to keep your cash flow healthy. This guide is here to help you restructure your existing debt to unlock that trapped equity and regain control. We’ll look at how to organise a loan structure that stays flexible for the next five years, focusing on lower monthly repayments and a clear path to your next deposit. You’ll discover how to move forward with your New Zealand portfolio with the confidence of someone who knows exactly how the banking system works.

Key Takeaways

  • Learn why a full portfolio audit is the first step to ensuring your current loan setup aligns with your 2026 financial goals.
  • Discover how to calculate your “useable” equity to release cash for your next deposit without needing to sell any of your existing properties.
  • Understand why the big banks might be saying no and how 2nd tier lenders can provide the flexibility you need to keep growing.
  • Follow a clear, step-by-step process for financing multiple investment properties nz that prioritises healthy cash flow and long-term stability.
  • Gain an insider’s perspective on how to structure your debt so it remains adaptable to market changes over the next five years.

What Does Refining Multiple Investment Properties Actually Mean?

Most people think refinancing is just a fancy way to say you’re looking for a lower interest rate. While a better rate is always a win, refining your portfolio goes a lot deeper. If you’re financing multiple investment properties nz, a simple rate-switch doesn’t look at how your loans interact with each other. A true refinement is a full audit of your debt setup. It’s about making sure your current structure actually matches what you want to achieve in 2026 rather than just sticking with what worked three years ago.

The way the market looks in 2026 has changed significantly. With the Official Cash Rate at 2.75% and debt-to-income (DTI) limits capped at seven times what you earn, the old ‘top-up’ method often hits a wall. A top-up just piles more debt on the existing heap. A structural refinement, however, might involve moving loans between different lenders or changing how your equity is split to give you more freedom. Understanding New Zealand property market dynamics is vital here; as rules shift, your structure has to evolve to keep your portfolio healthy.

The Three Pillars of a Refined Loan

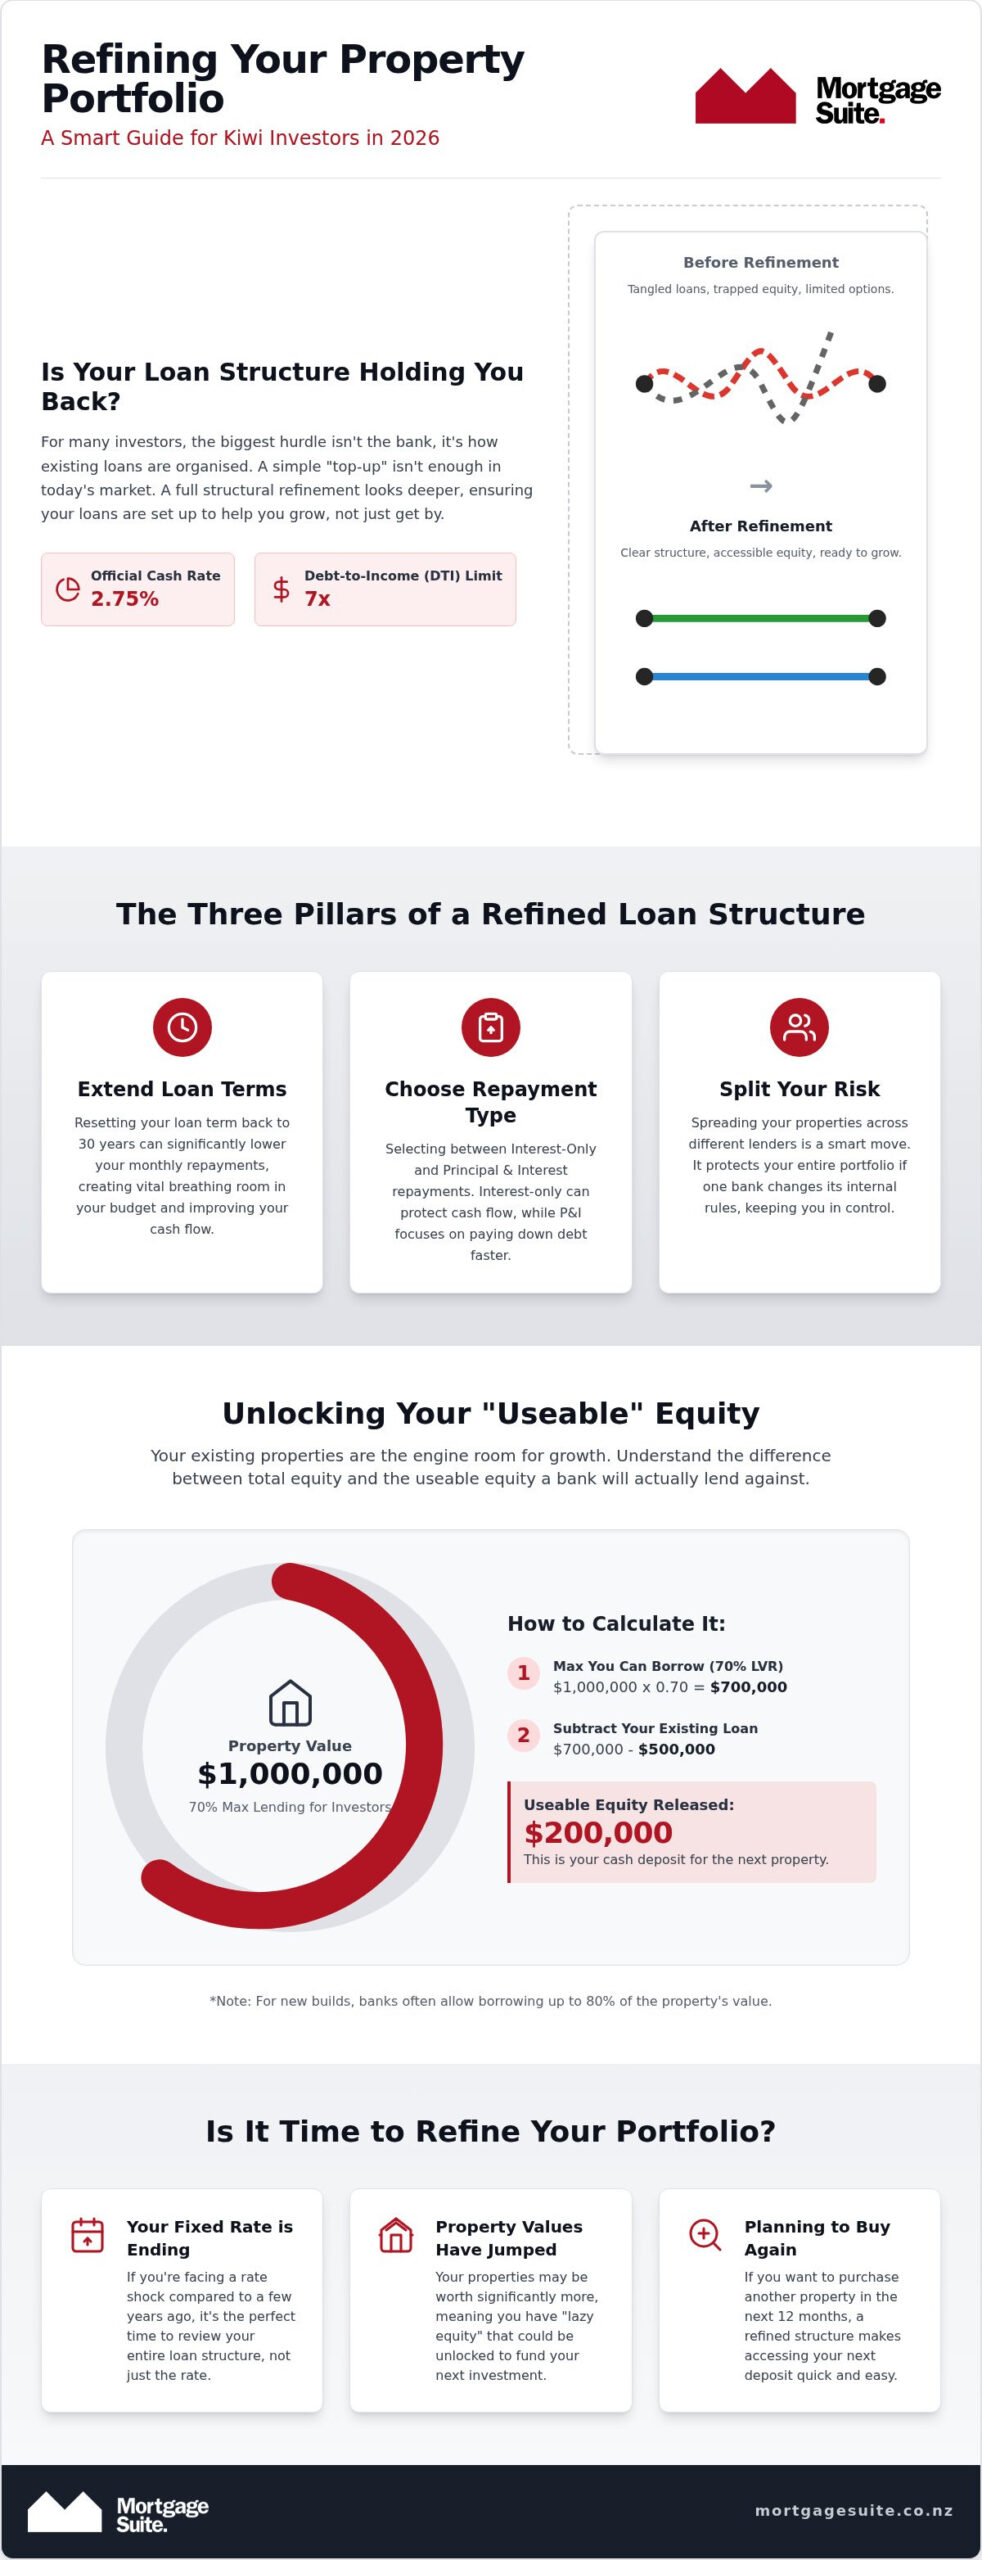
A well-organised portfolio usually rests on three specific choices that impact your daily life and your ability to buy again:

  • Interest-only vs Principal and Interest: We check which one fits your current rental income. In a higher interest environment, interest-only terms can protect your daily cash flow, while principal and interest might be better if you’re focusing on paying down debt.
  • Extending loan terms: Resetting your loan back to a 30-year term gives your monthly budget some vital breathing room, even if you’ve already been paying it down for a few years.
  • Splitting your risk: Putting all your properties with one bank is risky. If they change their internal rules, your whole portfolio gets squeezed. Spreading your loans across different lenders keeps you in the driver’s seat.

Signs It Is Time to Refine Your Portfolio

You don’t have to wait for a problem to check your numbers. If your fixed-rate term is ending soon, you’re probably facing a bit of a shock compared to what you paid a few years ago. This is the perfect time to look at the whole picture. Another sign is a jump in property values. If you reckon your properties are worth significantly more now, you might have “lazy equity” that could be working harder for you. Finally, if you’re planning to buy another investment property within the next 12 months, you’ll need a structure that makes getting that next deposit easy to access without a bank audit slowing you down.

Unlocking Equity: The Engine Room of Your Property Growth

Growth doesn’t always require a huge pile of cash sitting in a savings account. For most Kiwi investors, the fuel for their next purchase is already sitting right under their feet. When you’re looking at financing multiple investment properties nz, your existing portfolio is usually your best source of funding. However, there’s a big difference between the total equity you see on paper and the “useable” equity a bank will actually let you touch. Understanding this distinction is the secret to growing your portfolio without having to sell a single asset.

As of late 2026, the Reserve Bank settings require a 30% deposit for existing investment properties, meaning you can generally borrow up to 70% of the property’s value. For new builds, that requirement often drops to a 20% deposit. By refining your current loans, you can often release this equity as a cash deposit for your next move. You can use our mortgage calculator to get a rough idea of what your current numbers look like before you start the formal process.

Calculating Your Useable Equity

Equity is simply the gap between what your property is worth and what you owe the bank. While you might be able to borrow up to 80% against the value of your own home, the rules for rental properties are stricter. Banks generally cap lending at 70% for existing rentals to stay within current rules. This is why getting a fresh, professional appraisal is the first step in any refinement. If your properties have gone up in value, that “lazy equity” can be unlocked to form the deposit for your next purchase. It’s about making your current assets work harder so you don’t have to.

Refining Your Loan to Buy Again

Once you’ve identified your useable equity, you can use it as a virtual deposit. This means the bank uses the value in your current properties to secure the loan for the new one. A common trap many investors fall into is having the bank tie all your properties together as one big security. This gives the bank a lot of power but leaves you with very little flexibility. A smart refinement strategy keeps your home and your rentals separate. This ensures that if you decide to sell one property later, the bank can’t automatically grab all the money to pay down your other loans. If you want to see how we’ve helped others navigate these structures, feel free to read our client reviews to see the results of a tailored approach.

Mainstream Banks vs 2nd Tier Lenders: Choosing Your Path

It’s a common story in the current market: you’ve built a solid portfolio, your equity is high, but the ‘Big Four’ banks simply won’t budge. This usually happens because mainstream banks operate with very rigid templates. If your situation is slightly outside the box, perhaps you’re self-employed or have complex income streams, you might find yourself stuck. When you’re financing multiple investment properties nz, hitting a wall with your primary bank doesn’t have to be the end of the road. It’s often just a sign that you need to look beyond the high-street branches to find a lender that prioritises your potential over their paperwork.

The rise of non-bank and 2nd tier lenders has changed the game for New Zealand investors. These lenders often have a more common-sense approach to lending. They’re willing to look at the bigger picture of your portfolio’s performance rather than just ticking boxes. Krish Krishna spent over two decades inside the banking system, and he uses that insider knowledge to negotiate directly with these lenders on your behalf. You can learn more about our approach on our about us page, where we explain how we bridge the gap between rigid bank rules and your personal goals.

When a 2nd Tier Lender Makes Sense

A 2nd tier lender isn’t just a fallback option; it’s a strategic tool. You might find this path useful if your debt-to-income (DTI) ratio is slightly over the current 7x limit set for mainstream banks. It’s also a fantastic solution if you need a short-term ‘bridge’ to get a renovation or a small development project finished before you move to long-term finance. If you’re curious about how these alternatives work, check out our 2nd tier lender New Zealand guide for a deeper look at your options.

The Exit Strategy: Moving Back to the Bank

We rarely suggest using a non-bank lender as a forever home for your loan. Instead, we view it as a stepping stone. The goal is to use the flexibility of a 2nd tier lender to secure your property, then refine your financial profile over 12 to 24 months to become ‘bank-ready’ again. This involves maintaining a clean credit history and organising your income records so that a mainstream bank will eventually welcome you back with open arms. By treating this as a journey, you can keep financing multiple investment properties nz without getting permanently sidelined by a single ‘no’ from a mainstream manager.
Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

A Step-by-Step Guide to Refining Your Portfolio in 2026

Refining your portfolio isn’t a weekend DIY project, but it also shouldn’t feel like a mountain of paperwork. Since the 2026 market involves stricter debt limits and a shifting interest rate cycle, the process for financing multiple investment properties nz requires a methodical approach. It’s about moving from a reactive state to a proactive one. Here is the path we take to get your portfolio back in peak condition.

  • Step 1: The Portfolio Audit. We start by gathering your latest mortgage statements and estimated property values. This shows us exactly where your equity is hiding.
  • Step 2: Goal Setting. Are you prioritising monthly cash flow to offset the 2.75% OCR, or are you chasing aggressive growth? Your goals dictate the structure.
  • Step 3: The Broker Chat. This is where we shop the market for you. We compare mainstream banks against 2nd tier lenders to find the best fit for financing multiple investment properties nz.
  • Step 4: The Application. We help you prep a “financial CV” that highlights your strengths to 2026 lenders.
  • Step 5: The Settlement. We handle the transition to your new, refined structure so you can start seeing the benefits.

Preparing Your Financial Paperwork

Lenders in 2026 are obsessed with the spare cash you have left over each month. This is the money you have left after all your living expenses and debts are paid. Banks now use open banking systems to see your real spending habits directly from your accounts. Because of this, tidying up small personal debts like car loans or credit cards before you apply makes the whole process a piece of cake. It clears the path for your investment loans to take centre stage and shows the bank you’re a disciplined borrower.

Navigating the 2026 Interest Rate Cycle

With the OCR at 2.75% as of September 2026, choosing between fixed and floating rates is a balancing act. Refining your portfolio might mean fixing for shorter periods, such as six or twelve months, to stay agile while the market settles. You can dive deeper into these strategies in our Mortgage Rates NZ 2026 Guide to see how different terms affect your bottom line. If you’re ready to see how these steps apply to your specific properties, we invite you to reach out for a consultative chat with our team.

The Mortgage Suite Difference: Mentorship Over Transactions

Finding a lender for financing multiple investment properties nz is one thing, but building a sustainable financial future is quite another. Most people go to a bank and receive a one-off transaction. They get a loan, a rate, and a thank you. At Mortgage Suite Ltd, we believe that serious investors deserve more than just a signature on a page. We approach our work as mentors, guiding you through the complexities of debt structure to ensure your portfolio doesn’t just grow, but thrives over the long term.

This approach is built on a foundation of deep institutional knowledge. Krish Krishna spent over two decades working inside the banking system, which means he knows exactly how the credit teams on the other side of the desk think. He understands the hidden triggers that cause a mainstream bank to say no and, more importantly, how to present your case so they say yes. We often take on the “hard cases” that other brokers might avoid, using our experience to find solutions for self-employed Kiwis or those with complex income streams that don’t fit a standard bank template.

Real Stories, Real Results

Our success isn’t just measured by the loans we settle, but by the wealth our clients build. We act as your dedicated negotiator, standing between you and the lenders to fight for the best possible terms. If you want to see the impact this personal touch has made, you can read through our client reviews. You’ll see stories of investors who were stuck at a dead end until we helped them refine their path. We don’t just focus on the next purchase; we focus on how that purchase fits into your life five or ten years from now. Our commitment is to provide a conversational, jargon-free experience that leaves you feeling empowered rather than overwhelmed.

Your Next Step to a Better Portfolio

Refining your property loans shouldn’t feel like a chore. With the right guide, it’s actually a piece of cake. Whether you’re feeling the “rate shock” of 2026 or you’re ready to unlock equity for your next big move, we’re here to help you organise your next steps with confidence. We invite you to learn more about us and how we operate nationally across New Zealand. When you’re ready, reach out for a no-obligation chat about your current property setup. Let’s take a look at your numbers together and find a way to make financing multiple investment properties nz work for your unique situation.

Take Charge of Your Property Future

Building a successful portfolio in 2026 requires more than just luck; it requires a debt structure that is built to last. You now understand how a strategic audit can turn stagnant equity into a fresh deposit and why non-bank lenders are a practical way to bypass rigid bank templates. By refining your current setup, you ensure your monthly budget has breathing room while keeping your growth plans on track.

Navigating the path of financing multiple investment properties nz is a piece of cake when you have a seasoned mentor by your side. With over two decades of banking experience and a specialty in complex loan scenarios, we offer national service to help Kiwi investors succeed. We invite you to book a conversational chat with Krish to refine your portfolio today. Let’s work together to unlock your equity and build a structure that gives you total confidence for the next five years. Your next big move is closer than you think.

Frequently Asked Questions

Is it worth refining my investment property loan if interest rates are high?

Yes, it is often more important when rates are high. Refining is about managing your monthly cash flow and yields, not just chasing a low rate. By adjusting your loan terms or switching to interest-only, you can create breathing room in your budget. This strategic approach to financing multiple investment properties nz ensures your portfolio remains sustainable even when market conditions are challenging. It’s about long-term stability rather than short-term fixes.

How much equity do I need to release to buy another investment property in NZ?

To buy an existing investment property, you generally need a 30% deposit, while new builds typically require 20%. You can release this deposit from your current properties by calculating your useable equity. This is the difference between your property’s market value and what you owe, usually capped at a 70% loan-to-value ratio for rentals. Getting a fresh appraisal is the best way to see how much “lazy equity” you can actually put to work.

What is the difference between refinancing and refining a mortgage?

Refinancing is usually a simple transaction, like moving to a new bank for a slightly better interest rate. Refining is a much more thorough process. It involves a full audit of your entire portfolio to ensure your loan terms, lender types, and repayment structures align with your 2026 goals. Refining looks at the big picture of your wealth, whereas refinancing is often just a one-off attempt to save a few dollars each month.

Can I refine my loan if I am self-employed or have a complex income?

Absolutely. We specialise in helping self-employed investors and those with non-standard income streams who don’t fit the rigid templates of mainstream banks. Because Krish has over two decades of banking experience, he knows how to package your application to highlight your strengths. We often use 2nd tier lenders who take a more common-sense approach to complex income, ensuring you can keep growing your portfolio without being held back by paperwork.

How long does the process of refining a property loan typically take?

The timeframe can vary, but you should generally allow between four and six weeks from start to finish. This period includes your initial portfolio audit, getting property appraisals, and comparing different lender options. Once we’ve chosen the best path, the formal application and settlement usually move quite quickly. We manage the entire process for you to ensure it’s a piece of cake and stays on track for your next purchase when financing multiple investment properties nz.

Will I have to pay break fees if I switch lenders mid-term?

You might face break fees if you’re currently in a fixed-rate term and decide to switch lenders. However, we don’t just look at the fee in isolation. We run the numbers to see if the long-term savings or the equity you unlock will outweigh that initial cost. Often, a more flexible structure or a better cash flow position makes paying a small fee now a very smart investment for your future.

What happens if a mainstream bank has already declined my application?

A decline from a mainstream bank is often just a sign that you don’t fit their specific internal rules. It doesn’t mean you can’t get a loan. We specialise in 2nd tier lending and alternative finance for exactly these scenarios. By looking at your portfolio through a different lens, we can often find a lender that is happy to support your goals, even if the “Big Four” have already said no.

How does the Official Cash Rate (OCR) affect my decision to refine now?

The OCR, which sits at 2.75% as of September 2026, directly impacts the interest rates banks offer. When the OCR moves, it’s the perfect time to review your structure. Refining now allows you to hedge your bets by choosing the right mix of fixed and floating terms. This keeps you agile, allowing you to take advantage of future market shifts while protecting your current rental yields from unexpected rate shocks.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Structuring Investment Property Loans NZ: The 2026 Strategy Guide

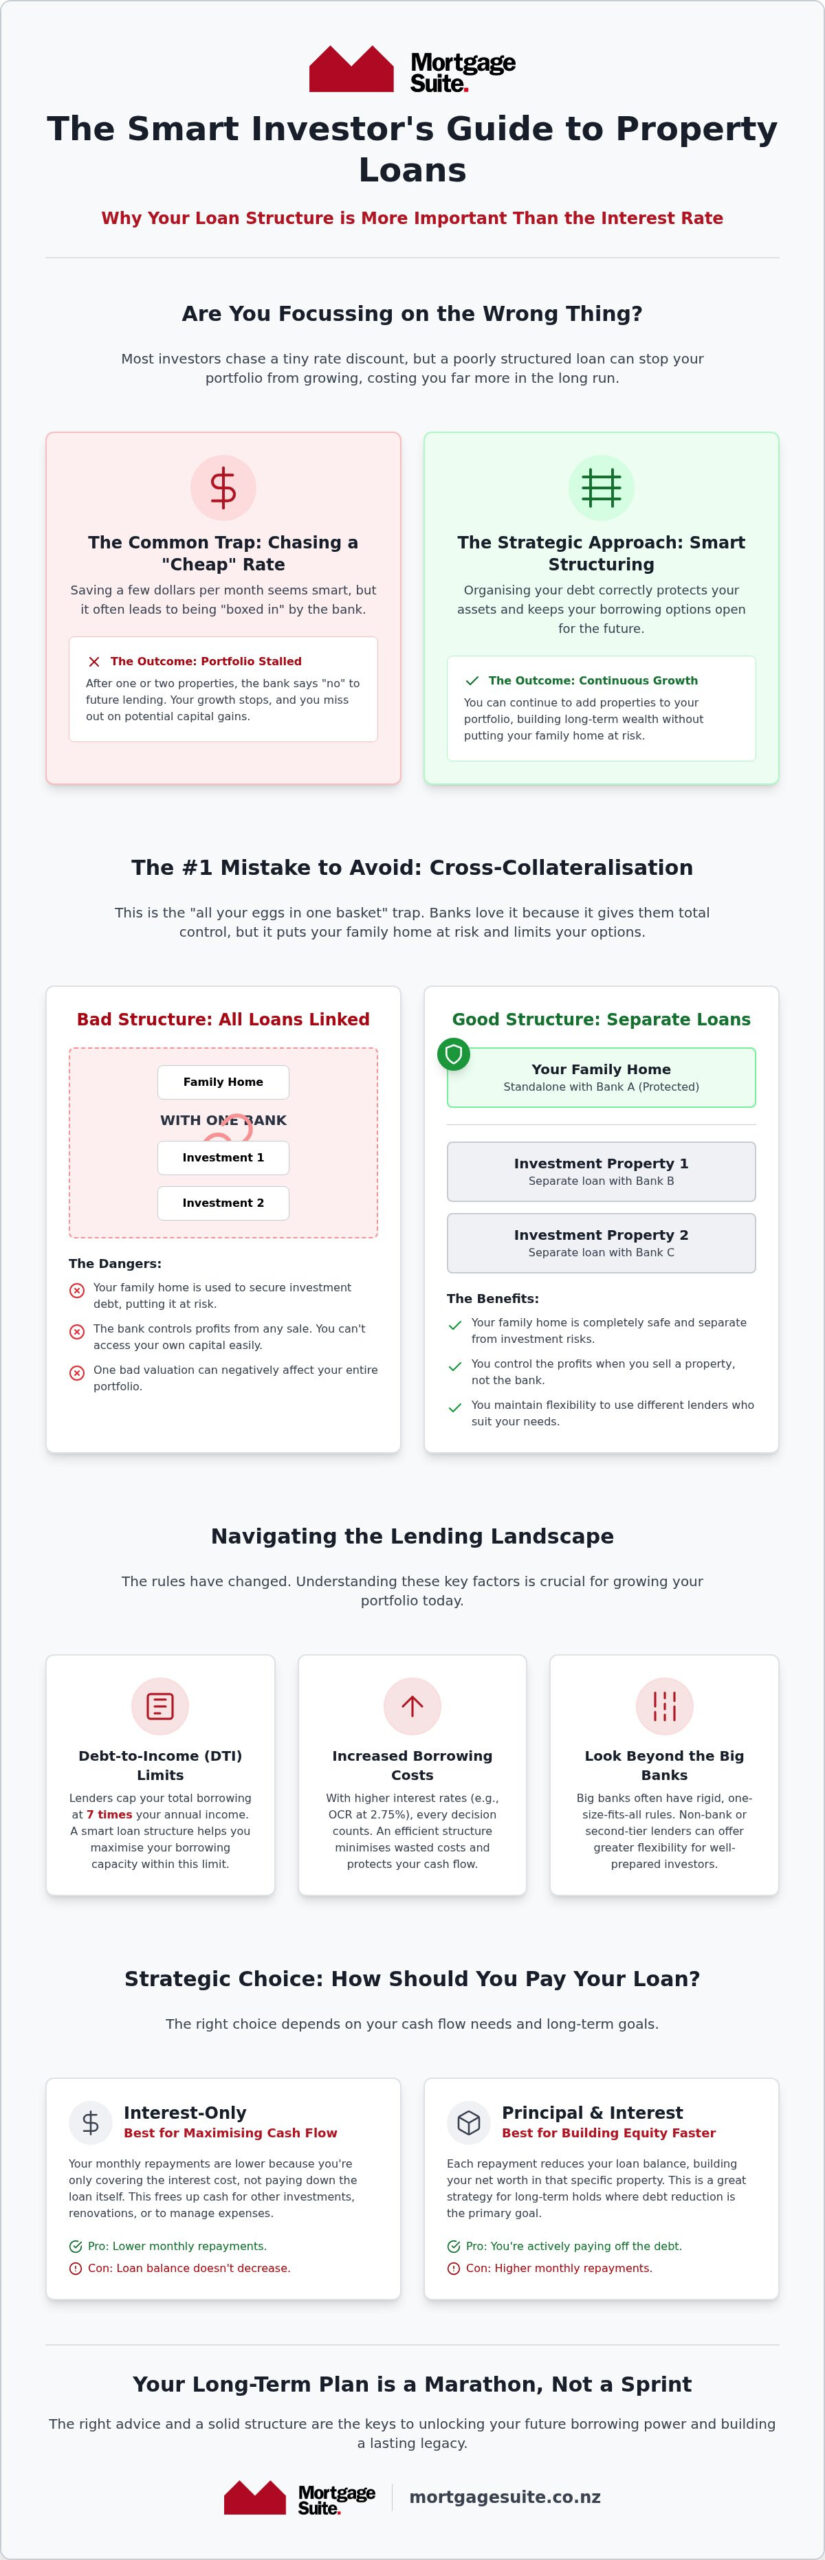
Most Kiwi investors believe the interest rate is the most important part of their mortgage, but in 2026, a “cheap” rate won’t save you if your loan structure is actually blocking your next purchase. If you’ve ever felt stuck after buying just one or two properties, it’s usually not a lack of equity or income holding you back. It’s often the way your debt is organised. Getting the right advice on structuring investment property loans nz is now the difference between a stagnant portfolio and a growing one, especially with the current debt-to-income (DTI) limits of seven times your income.

We understand that the fear of the bank taking your family home if an investment fails is a heavy burden to carry. It’s a common worry that keeps many people from taking the next step. You want to build a legacy for your family, not put their roof at risk. This guide will show you exactly how to set up your property loans to protect your personal assets, maximise your borrowing power, and move your portfolio forward at a faster pace. We’ll explore how to navigate the 2026 lending environment, from managing DTI rules to using lenders that look beyond the standard bank boxes.

Key Takeaways

  • Discover why the way you organise your debt matters far more than snagging the lowest interest rate when it comes to your long-term wealth.
  • Find out how to separate your personal home from your rentals so you never have to worry about the bank having too much control over your family’s future.
  • Learn why thinking beyond the big banks and properly structuring investment property loans nz can help you bypass rigid debt-to-income limits.
  • Get clear on whether paying only the interest or chipping away at the loan itself is the best move for your 2026 cash flow goals.
  • Understand why a strategic property plan is a marathon rather than a sprint and how the right expert help can unlock your future borrowing power.

Why the way you set up your loan matters more than the interest rate

It’s easy to get fixated on the numbers at the bottom of a bank’s flyer. Most investors spend hours comparing interest rates, hoping to shave a tiny fraction off their monthly repayments. While that’s understandable, it’s often a distraction from a much bigger risk. A low rate on a poorly organised loan can actually end up costing you hundreds of thousands of dollars in lost capital growth. If you can’t borrow for that third or fourth property because your bank says “no”, you miss out on the compounding gains of those assets over the next decade. That’s a massive price to pay for a slightly lower rate today.

When we talk about structuring investment property loans nz, we’re really talking about protecting your future borrowing power. If you set things up the wrong way, you might find yourself “stuck” after your first or second property because you’ve accidentally handed all the control to the bank. This happens when the bank uses your family home to secure everything, leaving you with very little room to move when you want to expand your portfolio.

What exactly is loan structuring?

In simple terms, loan structuring is the way your debt is organised across different banks and properties. It’s about deciding which assets secure which loans and whether those loans are linked together. Think of it as building a house. You wouldn’t spend all your money on expensive taps if the foundation was built on shifting sand. Good structure provides a solid foundation. It involves Avoiding cross-collateralisation, which keeps your family home safe from your investment risks. When your loans are structured correctly, you maintain “options” that allow you to pivot when the market or your life changes. You can learn more about these mechanics in our Mortgage School, where we break down how lending actually works behind the scenes.

The 2026 context: Why things have changed

The rules of the game have shifted significantly. In 2026, banks are being more careful than ever. With the Debt-to-Income (DTI) limits introduced a couple of years ago, your ability to borrow isn’t just about how much your house is worth; it’s about how your income is viewed by the lender. Since the Reserve Bank raised the OCR to 2.75% in September 2026, the cost of borrowing has increased, making every decision more impactful. We see many clients who have plenty of equity but can’t buy their next property because their current bank has “boxed them in” with rigid rules. By looking at the big picture, we help you protect your borrowing power so you can keep growing even when the big banks are tightening their belts.

The ‘all your eggs in one basket’ trap: Avoiding cross-collateralisation

Banks love it when you keep all your loans in one place. They often frame it as a way to “simplify” your life, but the reality is much more one-sided. This setup, often called cross-collateralisation, means the bank uses every property you own to secure every loan you have. It gives them maximum security and leaves you with very little control. When you’re structuring investment property loans nz, this is the number one trap to avoid if you want to keep your family home safe and your investment options open.

One of the biggest risks is the “Sale of Property” clause hidden in the fine print. If your loans are linked and you decide to sell one investment property, the bank can step in and take all the profit to pay down your other debts. You might have been counting on that cash for a new deposit or a renovation, but the bank gets to decide where that money goes first. By keeping your properties separate, you ensure that you, not the bank, decide how to spend your hard-earned capital.

How the ‘linking’ trap works in real life

If your home and your rentals are tied together, your entire financial life is at the mercy of a single bank’s valuation. If the market dips and one property loses value, the bank might suddenly view your whole portfolio as “risky.” They could freeze your credit limits or demand you pay back more of the principal. This is why we always recommend keeping your personal home as a standalone asset, completely separate from your investment debt. Cross-collateralisation is essentially the bank using all your properties to back every loan, which is a position you never want to be in.

Steps to un-link your properties

Breaking free from this trap is a process, but it’s worth the effort for the peace of mind it brings. Here is how you can start to untangle your finances:

  • Use different lenders: The most effective way to protect your home is to have your home loan at one bank and your investment loans at another.
  • Demand standalone security: When setting up a new loan, ensure the documentation only lists the specific property being purchased as security.
  • Refinance away from all-in-one facilities: Many older loan structures use a single “limit” backed by multiple houses. Moving to separate, fixed-term loans is often a smarter move.

You can use our mortgage calculator to see how much equity you currently have. This is a great first step in working out if you have enough leverage to move your investment loans to a different lender. Deciding between Interest-only or paying off the principal is also much easier when your loans aren’t all tangled together. If you’re not sure how your current loans are set up, having a quick chat with someone who knows the system can clarify things quickly.

Interest-only or paying off the principal: Which path is right for you?

Deciding how to pay back your bank is a massive part of structuring investment property loans nz. You have two main choices: paying just the interest or paying both the interest and the loan amount together. In 2026, “Cash Flow is King” has become the mantra for successful investors. With the Official Cash Rate at 2.75% and Debt-to-Income (DTI) limits generally capped at seven times your income, every dollar that leaves your account needs to be justified. Choosing the wrong repayment path can quickly dry up your cash reserves and stop your growth in its tracks.

A smart strategy many seasoned investors use is to focus on paying off their own home first while keeping their investments on interest-only terms. Since the interest on your family home isn’t tax-deductible, it makes sense to clear that debt as fast as possible. By keeping your investment debt separate and paying only the interest, you maximise your tax efficiency. It’s a winning move that helps you get rid of “bad” debt while your “good” investment debt works for you. Just make sure you chat with your accountant to ensure this setup fits your specific tax situation.

When interest-only makes sense

Interest-only payments keep your monthly “out-of-pocket” costs as low as possible. This is vital when you’re trying to grow a portfolio because it leaves more cash in your pocket at the end of each week. That extra money can be funnelled into a separate account to build a deposit for your next property faster. It’s important to remember that in 2026, most big banks will only let you stay on interest-only for a set period, often five years, before they want you to start paying back the principal. You need a plan for when that term ends so you don’t get a nasty surprise.

The argument for paying it all down

There is a lot to be said for the peace of mind that comes with seeing your debt balance actually drop. Paying off the principal means you are building equity in your properties every single month, regardless of what the market is doing. This extra equity can then be used as security for more loans later on. The trick is to find a “sweet spot” between growth and security. You want enough cash to live comfortably and keep buying, but you also want to know that you’re slowly becoming debt-free. If you’re unsure where you stand, you can check your current equity levels with our mortgage calculator.

Structuring Investment Property Loans NZ: The 2026 Strategy Guide

Thinking outside the big banks: When a second-tier lender makes sense

Many people assume that 2nd tier lenders are only for those who’ve made financial mistakes. That’s a huge misconception. In the current market, these lenders are often the secret weapon for smart investors who are structuring investment property loans nz to keep growing. When the big four banks start tightening their belts, a non-bank lender can offer the oxygen your portfolio needs to survive and thrive. It’s not about being a “bad” borrower; it’s about being a strategic one.

Mainstream banks are often bound by very strict, “one-size-fits-all” rules. If you don’t fit perfectly into their box, they simply say no. Non-bank lenders, on the other hand, often have more practical ways of looking at your situation. They might be more willing to accept a higher percentage of your rental income or look at your business earnings with a bit more common sense. This is often the “key” that unlocks property number three or four when a big bank has slammed the door shut. At Mortgage Suite, we pride ourselves on knowing exactly which non-bank door to knock on for your specific needs.

The flexibility of non-bank lenders

These lenders often look at your “real-world” income differently. While a big bank might use a very conservative “stress test” on your interest rates, a non-bank might use a more realistic figure. This can significantly increase your borrowing capacity under the current DTI rules. They are also fantastic for short-term needs, like bridging finance if you’ve bought before selling, or funding a quick renovation to add value. Simply put, 2nd tier lending is a professional alternative to mainstream banking that prioritises results over rigid paperwork. You can find out more in our 2nd tier lender new zealand your 2026 guide to alternative home loans.

Is a non-bank loan more expensive?

Let’s be honest about the numbers. Yes, the interest rates at a second-tier lender might be slightly higher than what you’d see on a billboard for a major bank. However, you have to weigh that against the “cost of doing nothing.” If a slightly higher rate allows you to secure a property that grows in value by fifty thousand dollars in a year, that small extra interest cost is a drop in the ocean. You aren’t just paying for money; you’re paying for the opportunity to grow.

We often use a “stepping stone” strategy with our clients. This involves using a non-bank lender to get the deal done now, then moving the loan back to a big bank once your equity has grown or your income has increased. It’s about being proactive and finding a path forward when others see a dead end. You can read through our Mortgage Suite reviews to see how other Kiwi investors have used this exact path to build their wealth. If you’re feeling stuck with your current bank, reach out for a consultation so we can explore the alternatives together.

Creating your long-term property plan with a bit of expert help

Successfully structuring investment property loans nz is a marathon, not a sprint. It’s about looking five or ten years down the track, not just at next month’s repayment. If you only talk to a bank teller, you’re getting a product that fits their sales target today. A teller isn’t there to help you buy your fourth house in three years. You need a partner who understands the long game and how each choice today impacts your options tomorrow. We’re here to make sure you don’t just get a loan, but a strategy that supports your life goals.

The rules in New Zealand change fast. We’ve seen the Bright-line test shift to two years and the OCR climb to 2.75% in September 2026. Because the environment is always moving, your strategy for structuring investment property loans nz needs to move with it. We recommend a full review every 12 to 24 months. This ensures you’re still protected and still have the best possible path to your next purchase. If you’re curious about how we work and why we’re so passionate about this, you can learn more about us and our client-first philosophy.

The value of a veteran negotiator

Krish Krishna brings over 20 years of banking experience to your side of the table. He’s seen every market cycle and knows exactly how banks think. At Mortgage Suite, we act as a steady hand for our clients through every hurdle. We don’t just take the easiest offer the bank gives us; we fight for the structure that actually works for you. Our job is to clear the path and remove the obstacles, so you can focus on finding the right property to add to your collection. We handle the complex negotiations so you don’t have to deal with the stress.

Your next steps to a better structure

Getting started is easier than you think. First, gather your current loan documents for a quick health check. You might be surprised at how a few small tweaks can unlock a lot of potential. We also encourage you to keep learning through our Mortgage School resources. It’s packed with information to help you stay ahead of the curve. Let’s get your property investment journey sorted for 2026 and beyond. We’re here to help you build a portfolio that truly lasts. Give us a call for a no-worries chat whenever you’re ready to take that next step.

Take the next step toward your property goals

Building a successful portfolio in 2026 isn’t just about finding the right house; it’s about having the solid foundation that only a smart strategy can provide. By avoiding the trap of linking your family home to your investments and choosing a repayment path that protects your cash flow, you keep the power in your hands. Mastering the art of structuring investment property loans nz ensures that you’re never “stuck” when the next great opportunity comes along.

With over 20 years of banking and mortgage expertise, Mortgage Suite acts as your steady hand in a fluctuating market. We offer access to both mainstream banks and 2nd tier lenders, specialising in the complex investment and development finance that often stumps the big banks. Our mission is to remove the obstacles standing in your way so you can focus on growing your wealth. Book a friendly chat with the Mortgage Suite team today to get your structure sorted. We’re here to help you move forward with confidence.

Frequently Asked Questions

What is the best way to structure an investment property loan in NZ?

The most effective approach is to keep your loans standalone and separate from your family home. This protects your personal assets and keeps your options open for future growth. Many successful investors use a mix of interest-only terms for their rentals while aggressively paying off their own home. This keeps cash flow high and debt manageable. Every situation is unique, so it’s vital to have a plan that matches your long-term goals.

How much deposit do I need for an investment property in 2026?

In 2026, you generally need a 30% deposit for an existing investment property, which means a 70% loan-to-value ratio. However, if you’re looking at a new build, the requirement is often lower at 20%. Some non-bank lenders might offer more flexibility depending on your overall financial position. It’s also possible for banks to lend to a small number of investors with less than a 30% deposit, though these spots are limited and highly competitive.

Can I use the equity in my own home to buy a rental property?

Yes, using the equity in your own home is a very common way to fund a rental property deposit. You can often top up your current home loan to release cash, which then acts as the deposit for your new investment. The key is to ensure the new investment loan is kept at a separate bank where possible. This prevents the properties from being linked together, which keeps your family home much safer if the market changes.

What are DTI ratios and how do they affect my property investment?

Debt-to-income (DTI) ratios limit how much you can borrow based on your yearly earnings. In 2026, investors are generally capped at borrowing seven times their total income. This rule makes structuring investment property loans nz even more critical because you need to ensure every dollar of income is counted correctly by the lender. If your big bank says your DTI is too high, we can often find second-tier lenders who look at your income with more flexibility.

Is it better to have all my loans with one bank or spread them out?

Spreading your loans across different banks is usually the smarter move for investors. While having everything in one place might seem easier, it gives that single bank too much control over your life. If they decide to change their rules or lower your credit limits, your whole portfolio is affected. By using multiple lenders, you maintain your borrowing power and ensure that a problem at one bank doesn’t stop your entire property journey.

Can I get an investment loan if the big banks have already said no?

If the big banks have turned you down, it doesn’t mean your journey is over. We specialise in 2nd tier loans that don’t fit the standard bank boxes. These lenders often have different rules for things like income, age, or property types. Using a non-bank lender can be a great stepping stone to get a deal done now, with the plan to move back to a mainstream bank once your equity or income has grown.

What is cross-collateralisation and why should I avoid it?

Cross-collateralisation is when a bank uses all your properties to secure every one of your loans. You should avoid it because it gives the bank the right to take the profit from any property sale to pay down your other debts. It also means your family home is at risk if an investment fails. Keeping your loans standalone ensures that you stay in the driver’s seat and can make your own decisions about your money.

How often should I review my loan structure?

You should review your loan structure every 12 to 24 months. Lending rules, interest rates, and your own life goals can change quickly, so what worked two years ago might be holding you back today. A regular health check ensures you’re still on the best rates and that your structure is still protecting your home and maximising your growth. It’s also a good time to check your equity levels as the market moves.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Investment Property Mortgage Calculator NZ: How to Calculate Repayments for Your 2026 Portfolio

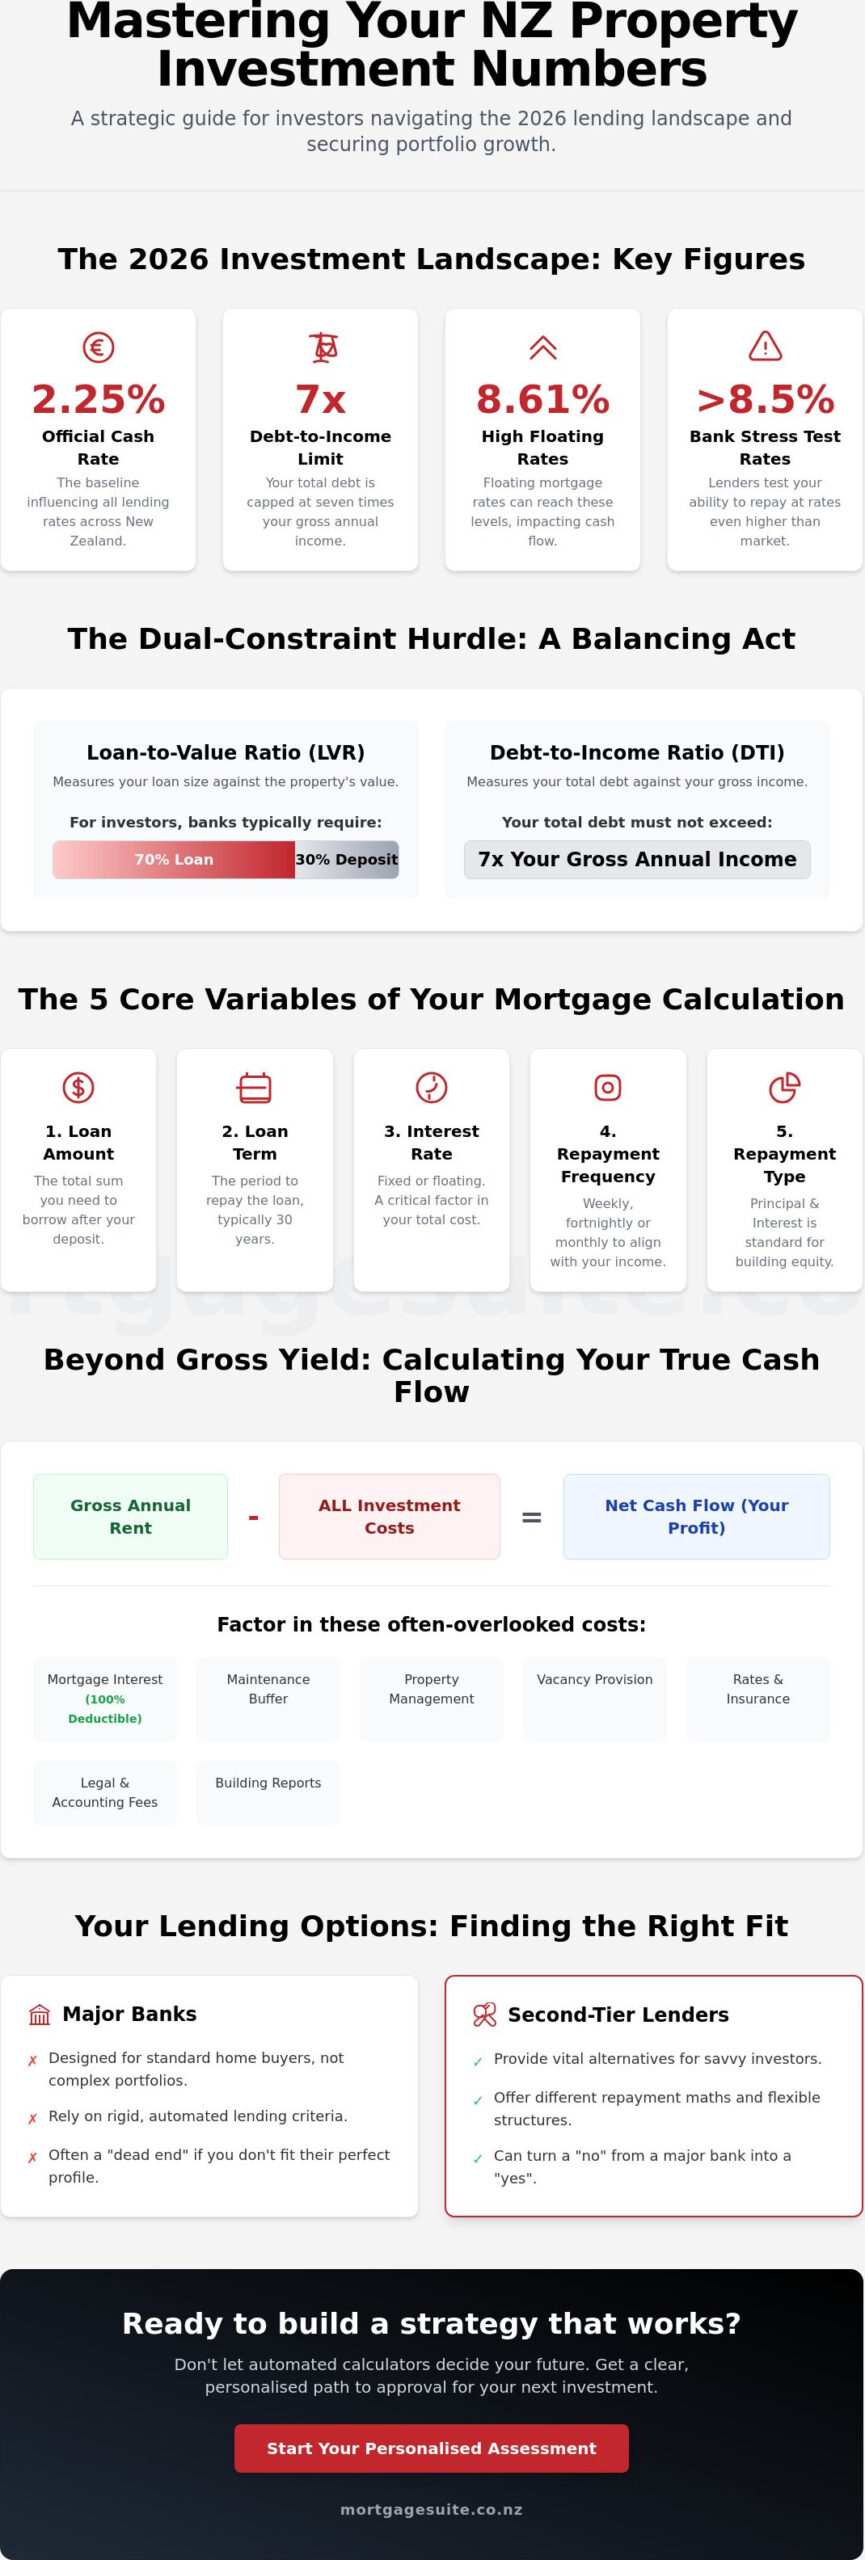
What if your next property investment approval didn’t depend on a bank’s rigid checklist, but on your ability to master the numbers before you even apply? With the Official Cash Rate sitting at 2.25% and DTI limits of seven times your gross income now firmly in place, using an investment property mortgage calculator nz is no longer just about checking repayments. It is about understanding how your total debt profile fits within the Reserve Bank’s 2026 framework to ensure your portfolio remains viable.

We understand the frustration of finding a perfect property only to be met with confusion over 2nd tier lending rates or the complexities of the current dual-constraint system. It is natural to feel a bit of pressure when trying to organise your cash flow while floating rates sit as high as 8.61%. This guide promises to clear that fog, providing you with a clear understanding of your monthly costs and a path to approval even if mainstream lenders hesitate. We will preview the latest LVR restrictions, explain the impact of 100% interest deductibility, and give you the confidence to execute a property strategy that works for your specific financial goals.

Key Takeaways

  • Identify the five core variables, including interest rates and repayment frequency, to accurately forecast your portfolio’s monthly cash flow.
  • Master the dual-constraint system of LVR and DTI limits by using an investment property mortgage calculator nz to determine your true borrowing capacity in the 2026 market.
  • Learn why calculating for investment requires a focus on yield and serviceability rather than just simple home loan affordability.
  • Discover how 2nd tier loans provide a vital alternative for investors who find themselves outside the strict lending criteria of the major banks.
  • Follow our step-by-step template to account for often-overlooked costs like legal fees and building reports when establishing your total loan requirement.

Successful property investment in New Zealand starts long before you visit an open home. It begins at your desk, crunching numbers to ensure a deal actually stacks up in the current 2026 economic environment. While many people use a basic tool to see what they can borrow, a dedicated investment property mortgage calculator nz serves a much more strategic purpose. It acts as your first line of defence against over-leveraging. It is about moving beyond "can I afford this?" to "does this asset work for me?"

In 2026, the landscape has shifted. With the Official Cash Rate at 2.25%, banks are looking closer than ever at your total debt-to-income (DTI) ratio. Calculating your repayments isn’t just about finding a monthly figure; it is about stress testing your strategy against potential interest rate hikes. If you can’t show a clear path to serviceability when banks apply their "test" rates, which often exceed 8.5%, your application will likely end up in the declined pile. Accurate preparation ensures you present a professional, viable case to lenders from the outset.

The Difference Between Yield and Cash Flow

Gross yield is a helpful starting point, but it’s often a vanity metric that can lead investors astray. It simply measures the annual rent against the purchase price. To build a sustainable portfolio, you must focus on net cash flow. This is where your mortgage repayment is just one piece of the puzzle. You need to account for the fact that 100% of your interest is now deductible, which significantly aids your bottom line compared to previous years. However, savvy investors also calculate a "buffer" for maintenance, property management, and potential vacancies. Understanding how mortgage calculators work helps you see how these variables interact with your loan principal to create a true picture of your weekly outgoings.

Why ‘Big Bank’ Calculators Often Fall Short

Most mainstream banking tools are designed for the average home buyer with a standard salary and a perfect credit score. They rarely account for the complexities of an investment portfolio, such as the nuances of 2nd tier lending or the specific 70% LVR requirements for investors. If your situation doesn’t fit the rigid "Big Four" criteria, their automated algorithms might suggest you’re at a dead end. We believe in personalised advocacy over automated results. 2nd tier lenders often offer different repayment maths that can turn a "no" into a "yes," provided you have organised your figures correctly using an investment property mortgage calculator nz that reflects the real-world market.

Understanding the Variables: What Actually Goes Into Your Repayment Calculation?

Calculating repayments isn’t a guessing game; it’s a precise exercise in financial forecasting. To get a reliable result from an investment property mortgage calculator nz, you must look beyond the sticker price of the house. There are five core variables that dictate your success: the loan amount, the loan term, the interest rate, the payment frequency, and the repayment type. Your deposit size is the first hurdle. While the Reserve Bank generally requires a 30% deposit for investors, having a larger equity stake can often unlock more competitive interest rate tiers. If you find the big banks are being too restrictive with their terms, exploring residential investment property loans can provide the tailored approach you need to keep your portfolio growing.

Local investors have the choice of weekly, fortnightly, or monthly instalments. Matching your repayment frequency to your rental income cycle can make your cash flow much easier to organise. Principal and Interest is the standard method for building equity over a 30-year term. However, the type of debt you choose significantly shifts the math. For example, a 30-year term is standard, but some 2nd tier lenders might offer different structures that suit a short-term development or a rapid equity-build strategy.

Fixed vs. Floating Rates: Which Number Should You Use?

Choosing an interest rate for your calculation requires a balanced view of the 2026 market. Fixed rate mortgage options currently range from approximately 4.65% for a one-year term to 5.86% for three years, providing the budget certainty many investors crave. Floating rates, while averaging around 6.15%, offer the flexibility to make extra payments without penalty. When using an investment property mortgage calculator nz, don’t just use today’s advertised specials. It’s wise to use a "test rate" of around 8.5% to ensure your portfolio remains robust even if the Reserve Bank raises the OCR again.

The Interest-Only Strategy for Investors

Interest-only repayments remain a popular choice for Kiwi investors looking to maximise tax efficiency. With 100% interest deductibility fully restored as of April 2025, this strategy helps keep immediate outgoings low while you focus on capital growth or paying down your non-deductible home loan. While this improves your short-term cash flow, it’s vital to calculate the "cliff"; the moment your interest-only period ends and your repayments jump to include principal. Planning for this transition ensures you aren’t caught off guard by a sudden increase in your weekly commitments.

The LVR and DTI Hurdle: Calculating Your Real Borrowing Power

Having a healthy deposit is only half the battle in the 2026 lending environment. While earlier sections focused on the mechanics of repayments, you must also clear the dual hurdles of Loan-to-Value Ratio (LVR) and Debt-to-Income (DTI) restrictions. Currently, the Reserve Bank requires most investors to provide a 30% deposit, meaning your LVR cannot exceed 70%. However, even with a massive pile of cash, your "real" borrowing power is now firmly capped by DTI limits. For most mainstream banks, your total debt cannot exceed seven times your gross annual income. This creates a hard ceiling that an investment property mortgage calculator nz can help you identify before you spend money on building reports or valuations.

Many investors feel the sting of "rental shading" during the application process. Banks rarely count 100% of your projected rental income when calculating serviceability. Instead, they typically recognise only 75% to 80% of the rent to account for costs like rates, insurance, and property management. If you have plenty of equity but the bank says your income is too low, this shading is often the culprit. It’s a common point of frustration, but understanding these internal bank formulas allows you to adjust your strategy and look for properties with higher yields that can offset the income gap. To fully understand how the 6x and 7x thresholds affect your specific situation, our detailed guide on the debt to income ratio NZ rules and what they mean for your 2026 mortgage breaks down the exact maths lenders use.

Unlocking Equity in Your Existing Portfolio

You don’t always need cash in the bank to fund your next move. Usable equity is the secret weapon for growing a portfolio, calculated as the difference between your current mortgage and 80% of your property’s value. For those who have seen significant capital gains since they first secured home loans for first home buyers New Zealand, this equity can often cover the entire 30% deposit for an investment. It’s a methodical way to leverage your existing assets without draining your personal savings, provided you maintain a steady hand on your total debt levels.

When the Mainstream Banks Say No

If your DTI ratio sits slightly above the "Big Four" threshold of seven, it doesn’t mean your investment journey is over. 2nd tier lenders often provide a vital alternative, as they can be more flexible with complex income structures or higher debt levels. When you use an investment property mortgage calculator nz to model these scenarios, you should account for slightly higher interest rates, often 0.5% to 1.5% above standard bank rates. This is where professional advocacy becomes essential. We specialise in finding the bridge between a rigid bank "no" and a structured approval that keeps your 2026 portfolio on track.

Investment Property Mortgage Calculator NZ: How to Calculate Repayments for Your 2026 Portfolio

A Step-by-Step Template to Forecast Your Investment Cash Flow

While an investment property mortgage calculator nz provides a quick answer, knowing the manual steps behind the math gives you true control over your strategy. It allows you to spot a bad deal before you ever talk to a bank. Follow this template to organise your forecast for any 2026 acquisition.

  • Step 1: Determine the total entry cost. Start with the purchase price and add an allowance for legal fees, building inspections, and valuations. These often total between $3,000 and $6,000 depending on the property’s complexity.
  • Step 2: Establish your loan requirement. Subtract your cash deposit or the usable equity you’ve unlocked from your home. This leaves you with the core debt figure.
  • Step 3: Select your structure. Decide if you’ll use an interest-only period to maximise immediate cash flow or start with principal and interest to build equity from day one.
  • Step 4: Use realistic rates. Don’t just use the lowest rate on the market. Apply a standard 2026 fixed rate, such as the 5.19% two-year average, to keep your figures grounded in reality.
  • Step 5: Run the serviceability check. Calculate your monthly repayment and compare it against 80% of your projected gross rent. If the rent doesn’t cover the mortgage at this "shaded" level, you’ll need to contribute from your personal income.

If these steps feel overwhelming or the numbers aren’t quite stacking up, we can help you find a path forward. Our team specialises in securing residential investment property loans that align with your long-term wealth goals.

The ‘Stress Test’ Calculation

Bank managers don’t look at what you can pay today; they look at what you can pay if the market shifts. You should do the same. Recalculate your repayments with an interest rate that is 1% or 2% higher than current offers. This "worst-case" figure is the most vital number in your entire spreadsheet because it defines your safety margin. A robust investment plan should survive a 2% interest rate hike without requiring external capital. If your portfolio can’t weather that storm, it might be time to reconsider the purchase price or your deposit size. Understanding the difference between fixed rate mortgage vs floating rate options is essential when stress testing your portfolio against potential rate movements.

Accounting for the ‘Hidden’ Costs

Many novice investors make the mistake of thinking the mortgage is their only expense. In reality, rates, insurance, and property management fees usually consume about 20% of your gross rental income. These are the "forgotten" costs that can turn a cash-flow positive property into a monthly liability. When you’re using an investment property mortgage calculator nz, always deduct these outgoings from your rental income before comparing it to your loan repayments. Remember that "set and forget" is a myth in property investment. Staying on top of these shifting costs ensures your portfolio remains a source of wealth rather than a source of stress.

Beyond the Calculator: How Tailored Financing Secures Your Portfolio

While an investment property mortgage calculator nz provides the essential coordinates for your journey, it cannot navigate the roadblocks that often appear during a bank’s assessment process. Think of the calculator as your map; it shows you the destination, but a seasoned advocate acts as your guide through the terrain. At Mortgage Suite Ltd, we specialise in residential investment property loans that don’t always fit the rigid, automated criteria of the "Big Four" banks. We understand that your financial story is more than just a credit score or a debt-to-income ratio.

Securing a "fair go" from lenders in 2026 requires more than just submitting an application. It involves presenting a case that highlights the strength of your strategy. For many investors, 2nd tier lending serves as a strategic bridge. It allows you to secure a property and build equity today, rather than waiting for mainstream banks to ease their restrictions. This proactive approach turns a potential "no" into a structured path toward long-term wealth, ensuring you don’t miss out on opportunities while waiting for the perfect market conditions.

The Power of a Specialised Advocate

Krish Krishna brings over two decades of banking experience to your corner, ensuring your application is seen by human eyes rather than just an algorithm. There is a profound difference between a "computer says no" interaction at a local branch and a solution brokered through deep institutional knowledge. When your finances are non-standard or your portfolio is complex, personal connection and a reputation for integrity matter. We act as your dedicated negotiator, removing obstacles and finding the bridge between institutional requirements and your personal goals. Our experience allows us to anticipate lender objections before they arise, saving you time and reducing the stress of the approval process.

Next Steps: From Calculation to Pre-Approval

To move from a theoretical calculation to a formal pre-approval, you’ll need to organise your documentation. This typically includes recent payslips, bank statements, and rental appraisals for your existing or prospective properties. Having these ready allows for a much smoother transition from the research phase to the acquisition phase. We also recommend a "health check" on your current portfolio equity to ensure you are leveraging your assets as efficiently as possible. When you’re ready to turn your data into a concrete offer, organise a consultation with Mortgage Suite Ltd to find the right loan for your next investment. We are here to ensure your 2026 strategy is built on a foundation of professional certainty and personalised care.

Mastering Your Path to Property Success

Mastering the numbers is the first step toward building a resilient property portfolio. By now, you understand that an investment property mortgage calculator nz is a powerful starting point for assessing yield and cash flow. However, clearing the high bars of DTI limits and LVR restrictions requires more than just a digital tool. It demands a strategic approach that accounts for 2026 market realities and the nuances of non-bank lending. Success in this environment comes from preparing for the transition of interest-only periods and ensuring your strategy can weather potential interest rate shifts with a calculated safety margin.

With over 20 years of banking and brokerage experience, Mortgage Suite Ltd provides the seasoned advocacy needed to turn complex financial scenarios into approvals. We specialise in 2nd tier and non-bank lending, offering a nationwide service for all New Zealand investors who want a steady hand in a fluctuating market. You don’t have to navigate these hurdles alone. Secure your investment future with a tailored mortgage strategy from Mortgage Suite Ltd. We are ready to help you move beyond the spreadsheet and into your next successful acquisition with absolute confidence.

Frequently Asked Questions

How much deposit do I need for an investment property in NZ in 2026?

You generally need a 30% deposit for an existing residential investment property in 2026. This requirement aligns with the Reserve Bank’s LVR restrictions, which limit most investor lending to a 70% threshold. If you are purchasing a new build, you may be able to secure a loan with as little as a 20% deposit. Using an investment property mortgage calculator nz helps you determine the exact amount of cash or equity required to meet these criteria.

Can I use my KiwiSaver to buy an investment property?

No, you cannot withdraw KiwiSaver funds to purchase a property intended solely for investment. KiwiSaver withdrawals are strictly reserved for buying your first home to live in, or for cases of significant financial hardship. However, once you have used KiwiSaver to secure your first home, the equity you build in that property can eventually be leveraged to fund a deposit for a future investment property.

What is a ‘good’ DTI ratio for a property investor?

A healthy DTI ratio for an investor is typically considered to be below six. As of mid-2024, the Reserve Bank implemented a formal DTI cap of seven for most investor lending. If your total debt exceeds seven times your gross annual income, mainstream banks will likely decline your application. Maintaining a lower ratio ensures your portfolio remains resilient and gives you more flexibility when interest rates fluctuate.

Are interest rates higher for investment properties than for my own home?

No Interest rates are generally the same. For investors up to 6 investment properties, you can obtain the rate as normal housing rates. For investors with more than 6 properties, some lenders will view you as commercial investors and may apply a slightly higer rate.

What happens if my investment property is vacant for a month?

If your property is vacant, you must be able to cover the full mortgage repayment from your other income sources. This is why banks "shade" your rental income, often only counting 80% of the projected rent in their serviceability tests. We always recommend keeping a cash buffer equivalent to at least four weeks of rent to manage these inevitable vacancy periods without putting undue stress on your personal finances.

Should I choose a 2nd tier lender if my bank declines my application?

Choosing a 2nd tier lender is a very effective strategy if a mainstream bank declines your application due to rigid DTI or LVR rules. These lenders often provide a vital bridge for investors with complex income structures or those who sit just outside the "Big Four" criteria. While the interest rates may be slightly higher, the flexibility they offer can be the difference between growing your portfolio or stalling your investment journey.

How do I calculate the equity in my current home?

To calculate your usable equity, take 80% of your home’s current market value and subtract your remaining mortgage balance. For example, if your home is worth $1,000,000 and your mortgage is $500,000, your usable equity is $300,000. This is calculated as $800,000 minus $500,000. This figure represents the maximum amount you can potentially borrow against to fund a deposit for a new investment property without needing extra cash.

Is interest-only always better for rental properties?

Interest-only is not always the best choice; it depends on your specific financial goals. Many investors prefer interest-only to maximise tax deductibility and keep monthly outgoings low, which is excellent for immediate cash flow. However, Principal and Interest repayments are better if your goal is to build equity and pay off the debt over a 30-year term. It’s about balancing your immediate flexibility against your long-term debt reduction strategy.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.