How to Present a Business Loan Application in New Zealand

A lender’s decision depends on more than whether your finances look perfect. If you’re unsure how to present a business loan application, you’re not alone. Gathering financial records, explaining what you need the funds for and showing how you’ll manage repayments can feel like a lot, especially if income has changed, the business already has debt or an earlier application was declined.

A clear application gives the lender a consistent picture of your business: what you need, how you’ll use the funds and how repayments may fit your cash flow. This guide covers the information and supporting documents that can help a lender assess your request, along with ways to explain your plans in plain English. You’ll also learn how to describe unusual circumstances honestly without letting them define your whole application.

The right funding route depends on your business needs, the evidence you can provide and the lender’s assessment. Mortgage Suite supports business finance applications by helping shape and negotiate the request. Founder Krish Krishna brings more than two decades of banking experience and a practical understanding of how lenders review funding proposals.

Key Takeaways

  • Present your funding need, business position and repayment plan as one clear account.
  • Prepare financial records that support your case, keeping in mind that document requests vary between lenders and applications.
  • Compare funding routes by how you’ll use the money, make repayments and access funds, including how a term loan works.
  • Check your figures, update your records and explain unusual circumstances clearly before applying.
  • Mortgage Suite can help shape and negotiate your funding request, but no particular lending decision is guaranteed.

Why a well-presented business loan application matters

Applying for business finance can feel demanding, especially if sales have shifted, costs have risen or cash flow looks different from last year. You may be keeping day-to-day work moving while also gathering records and explaining a decision that feels obvious to you. A well-presented application brings those details together, helping a lender understand what the business needs and how the proposed repayments may fit.

Good presentation isn’t about dressing up the numbers or hiding a difficult period. It means giving a consistent, straightforward account of the business, the funding request and the repayment plan. This can help a lender assess your request, but it can’t guarantee approval. Each lender makes its own assessment, and the right finance route depends on your business and its circumstances.

What does a business loan application need to communicate?

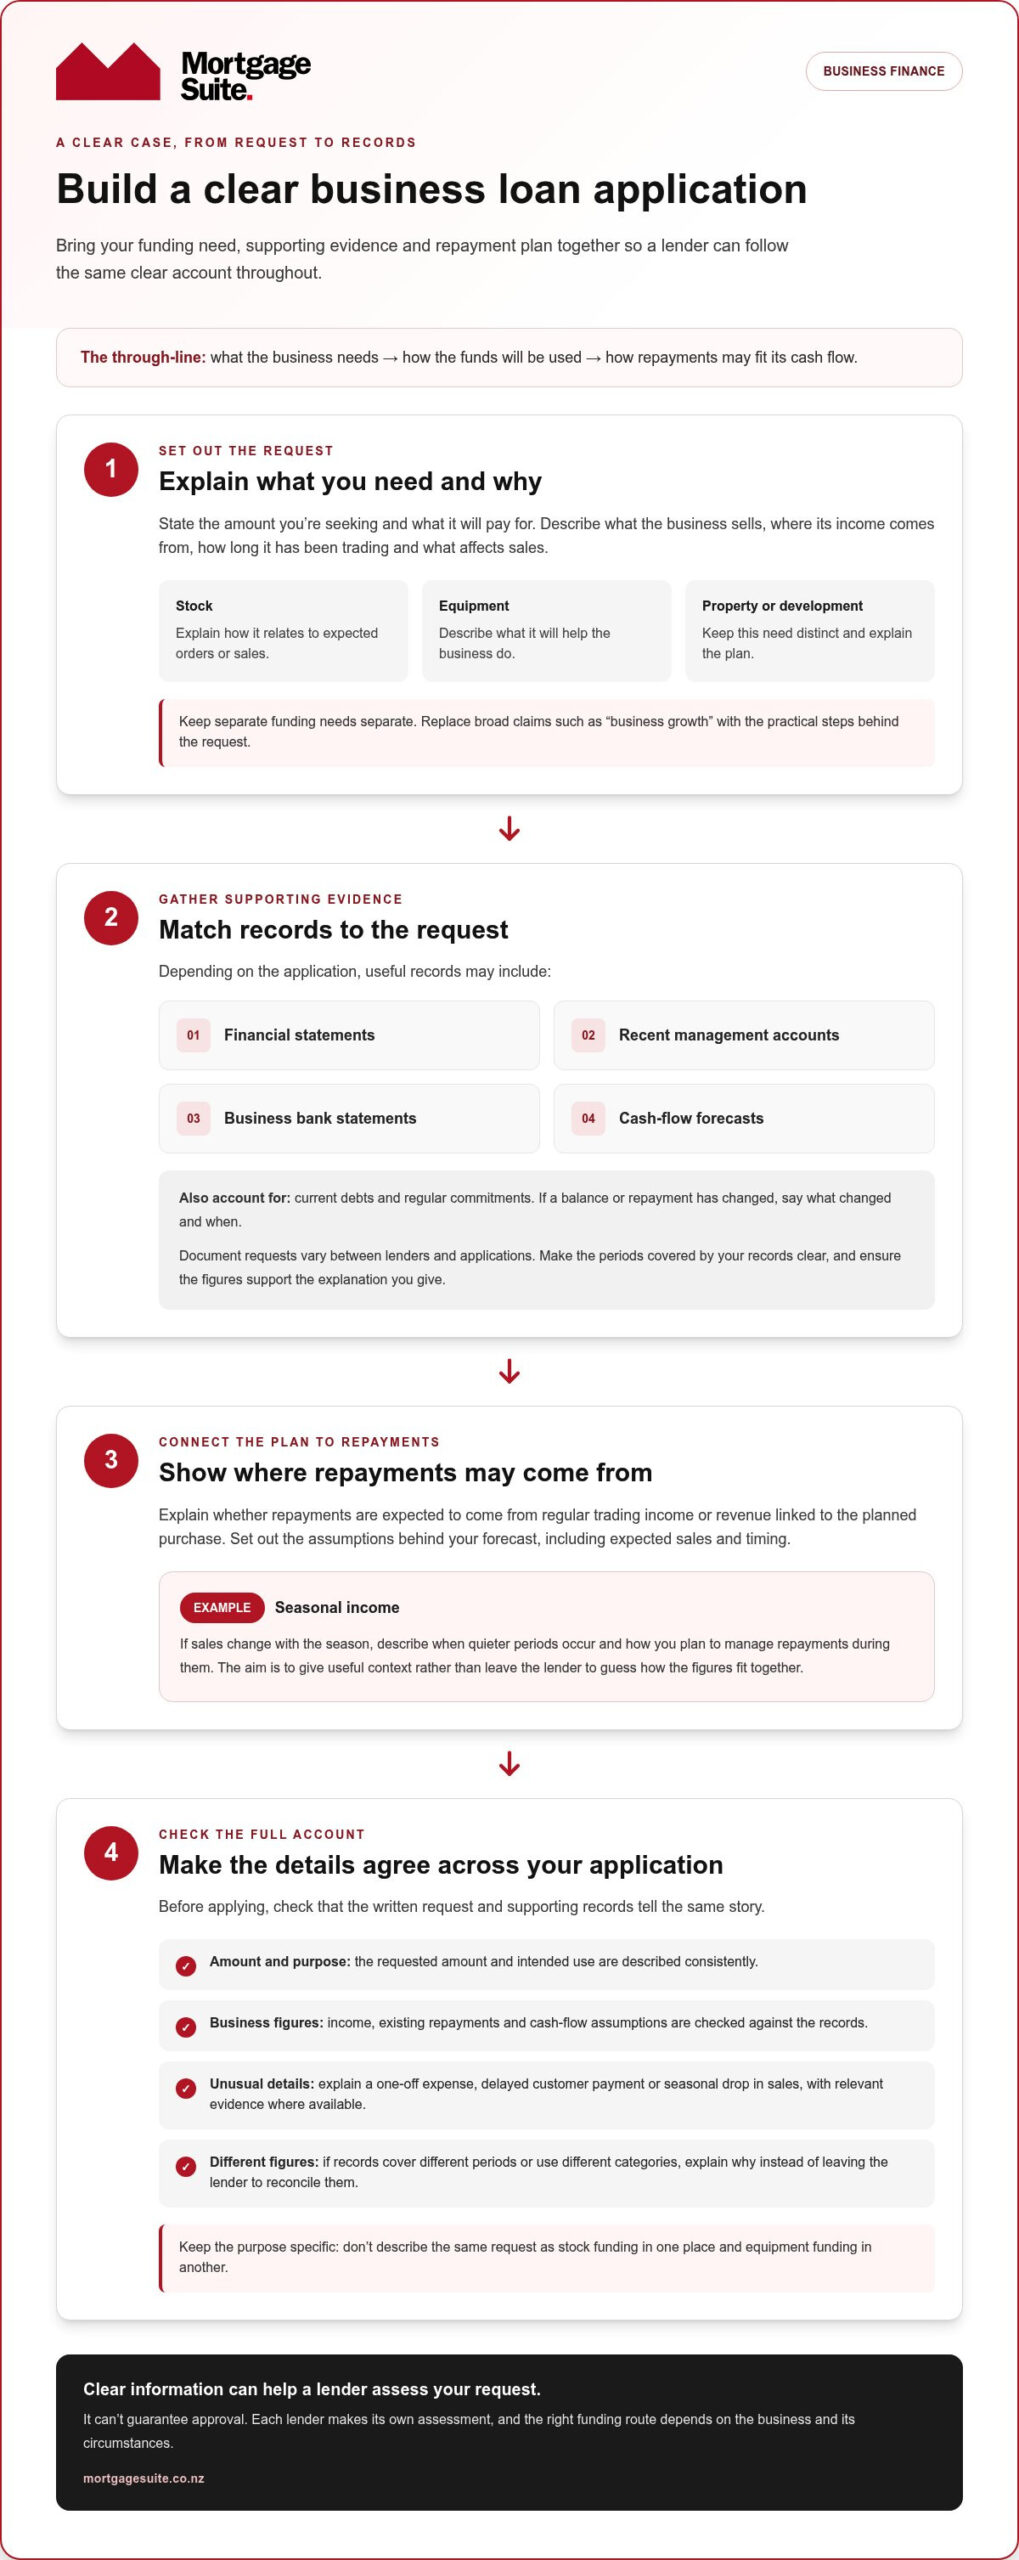
Start by stating the amount you’re seeking and what it will pay for. Keep separate needs distinct rather than grouping unrelated expenses under a broad label such as “business growth”. Briefly describe how the business operates, where its income comes from and how it manages existing commitments.

Then connect those details to your repayment plan. Explain how the business expects to meet repayments from its cash flow and what assumptions that expectation relies on. If income varies with seasonal demand, for example, describe when quieter periods occur and how you plan to manage repayments then. This gives the lender useful context instead of leaving them to guess how the figures fit together.

Why clarity and consistency matter

Figures that agree across your application and supporting records are easier to follow. If your written request describes one use for the funds but your forecast suggests another, the lender may need clarification. That doesn’t automatically determine the outcome, but it can make the assessment less direct and create extra work for you.

Check the key details across your documents: the amount requested, intended use, income figures, existing repayments and cash-flow assumptions. If figures differ because records cover different periods or use different categories, explain why rather than leaving the lender to reconcile them.

For instance, if you’re seeking funding to buy stock, say so clearly and show how the stock supports expected sales. Don’t describe the same request as equipment funding in one part of the application and working capital in another. A lender needs to see a clear connection between the funds and the business purpose. For general background on types of business loans and assessment criteria, you can also review an overview of how business loans may be structured and assessed.

In practice, how to present a business loan application comes down to making your case easy to understand and checking that each part supports the same account. Clear explanations won’t remove every concern, but they help a lender assess your request with a better understanding of the business.

Build a clear business loan case with evidence

A lender needs more than a stack of records. They need to understand how the business operates, why it needs funding and how the request connects to a realistic repayment plan. Arrange your explanation and evidence so each supports the same account. Document requests vary between lenders and applications, so use the examples below as a starting point and follow the requirements for your application.

Explain the business and the reason for borrowing

Give a short picture of your business: what it sells, how it earns income, how long it has been trading and what affects sales. Then describe the funding purpose in practical terms. For example, explain whether the request is for stock to meet expected orders, equipment to support operations, or a property or development plan. Keep different needs separate, as they may call for different funding structures and supporting evidence.

Be specific about how the funds relate to the business need. If you’re seeking finance for equipment, explain what it will allow the business to do and how that supports income or day-to-day operations. Avoid broad claims such as “this will grow the business” unless you can explain the steps behind them.

Prepare records that support the request

Depending on the application, useful evidence may include financial statements, recent management accounts, business bank statements and cash-flow forecasts. These records can help show both past performance and what you expect ahead. Check that the periods covered are clear and that the figures in your written explanation appear in the relevant records.

List current debts and other regular commitments accurately. If a balance or repayment has changed, explain what changed and when. Do the same for unusual figures: a one-off expense, delayed customer payment or seasonal drop in sales may need a brief explanation and relevant supporting evidence. Don’t leave a lender to guess, but avoid over-explaining ordinary fluctuations. Focus on the details that make the business’s position clearer.

Mortgage Suite’s business finance support can help you organise information around your funding request and shape the case you present.

Make the repayment plan understandable

Explain where repayments are expected to come from, such as regular trading income or revenue linked to the planned purchase. Set out the assumptions behind your forecast, including expected sales, costs and timing. If income changes with the season or depends on work being completed, show how that timing affects the cash available for repayments.

Think through a quieter period or delayed income. Explain how the business could manage that change, and make sure the plan accounts for existing commitments as well as the new borrowing. Forecasts are estimates, not guaranteed results, so label assumptions clearly and keep them realistic. Evidence and a measured explanation help support the request without overstating what the business can achieve.

Compare funding routes and address concerns before applying

The right finance structure depends on what the business needs, when it needs the funds and how it expects to repay them. A facility that suits regular operating expenses may not suit a property purchase or development project. Compare the purpose, repayment pattern, security and access to funds before framing your request. The options below are broad categories, and a lender’s assessment determines what may be available for a particular application.

Match the funding structure to the business need

Funding route How it works May suit
Term loan A loan provided as a lump sum with a defined repayment schedule and end date. A planned purchase or one-off business expense where the amount and purpose are known.
Revolving facility Access to funds up to an agreed limit, with repayments and access working according to the facility’s terms. Changing short-term cash-flow needs where the business may need to draw funds at different times.
Property-related finance Funding assessed in relation to a commercial property purchase or development plan. A property or development project, rather than general day-to-day business needs.

Security, timing and cash flow can all affect which route may fit. A business buying a commercial property has a different funding purpose from one managing uneven trading income. Property or development finance is shaped around the project and its supporting information, while general business funding relates to other operating needs. Set out the intended use clearly so the request can be considered in context.

What if the business has been declined or has a complex profile?

A decline from a mainstream bank can be discouraging, but it’s a decision on that application, not a judgement of your worth or the value of your business. Before applying again, review any reasons the lender gave. Was the concern about cash flow, existing commitments, proposed security or information that needed more explanation? Address the specific issue rather than sending the same request unchanged.

If income varies, trading history is unusual or a past event affected the figures, explain the circumstances plainly and support them with relevant records. A different lender or finance route may suit some applications, including options outside mainstream banks, but each lender makes its own assessment and approval can’t be assured. Changing the structure or strengthening the evidence may help present your request more clearly, though it won’t remove every concern.

Knowing how to present a business loan application also means choosing a funding route that fits your business, rather than focusing on a headline rate alone. Mortgage Suite can help shape and negotiate a business finance request around its purpose and supporting case. For a personal discussion of your funding needs, talk with Mortgage Suite about business finance.
How to Present a Business Loan Application in New Zealand

Prepare and present your application in practical steps

Once you’ve settled on the funding need, turn your notes and records into a pack that’s easy to review. Organisation can make the process feel more manageable and help you spot gaps before you submit. Use this sequence as a guide, adapting it to the lender’s document requests and your business circumstances.

A step-by-step application preparation process

  1. Set out the request. Write down the amount you’re seeking, what the funds will be used for and when you expect to need them. Be specific: describe the planned purchase or business need rather than relying on a broad phrase such as “business growth”.
  2. Gather relevant records. Collect the business information and financial documents that support the request. Check that figures agree across records, and note the period each document covers. Keep files in clearly named folders so you can find the right evidence without searching through a jumble of attachments.
  3. Draft a short business summary and repayment explanation. Describe how the business earns income and what the funding will help it do. Then explain the expected source of repayments, the assumptions behind your forecast and how you’ve allowed for existing commitments or changes in income.
  4. Review the application pack. Read the written explanation alongside the supporting records. Check that dates, figures and the stated use of funds match. Add a brief explanation where a lender might otherwise be left wondering about a gap or unusual change.

Keep a copy of what you submit and note which records you included. If the lender asks a follow-up question, respond clearly and provide the relevant information. An organised reply can help keep the discussion focused, although the lender may still need to make further enquiries while assessing the application.

Common presentation mistakes to avoid

Before sending your application, watch for these avoidable issues:

  • Unexplained differences. If a forecast doesn’t match recent bank activity or a written claim, explain the reason and point to the information that supports it.
  • A vague funding purpose. “Business growth” doesn’t tell a lender what you plan to do. Name the intended use and connect it to the business need.
  • Missing commitments. Include existing debts and regular obligations accurately. Leaving them out can create a different picture from the one shown in your records.
  • Overconfident forecasts. Present expected income as an estimate, not a sure thing. Make the assumptions clear, especially if sales or payment timing can change.

Knowing how to present a business loan application means making it straightforward for someone unfamiliar with your business to follow the request and its supporting information. If you’d like help organising and presenting your funding case, discuss your business funding needs with Mortgage Suite.

How Mortgage Suite can help with a business loan application

Putting together a business finance request can take time, especially if your income has changed, your funding need is unusual or a lender has already declined an application. You don’t have to work through every detail alone. An adviser can help organise the request, consider finance routes that may fit and make sure the supporting information explains the business case clearly.

What support can an adviser provide?

Start with the purpose. An adviser can help you describe what the funds are for, what the business needs to achieve and what information best supports that explanation. They can also help make sense of your circumstances, such as changing income, existing commitments or a previous lender decision, so relevant context isn’t lost in a bundle of documents.

From there, an adviser can discuss funding routes that may suit the request and help present it to a lender. Mortgage Suite acts as a personal advocate and negotiator, working to shape the application around your business needs and supporting evidence. Founder Krish Krishna brings more than two decades of banking experience.

That support can help organise and discuss a request, but it can’t determine the outcome. Lenders make their own assessments and may ask for more information. A well-prepared application can make the business’s position easier to understand, but no adviser can promise approval or remove every lending concern.

Take the next step with a clear funding brief

You don’t need a polished presentation to start a useful conversation. A short brief can explain what the business does, what funding you’re seeking, how you plan to use it and where repayments are expected to come from. Include known changes to trading or cash flow, along with relevant lender feedback if you’ve already applied.

Being upfront about a decline or a complex circumstance gives an adviser a clearer picture of the request. It also helps identify which parts of the case may need more explanation or supporting information before it goes to a lender. If you’re still gathering records, the next step is to work out what information is relevant and how to present it consistently.

If you’re ready to talk through your business finance needs, start a conversation with Mortgage Suite. Explain what the business needs and where you’d like help. Together, you can consider how to present a business loan application that gives a lender a clear view of the request, without assuming what the decision will be.

Take your next funding step with a clear plan

A funding request can help you look ahead as well as meet an immediate need. Before you submit, consider what you want the business to do next and whether the proposed repayments leave room for everyday commitments if trading changes. That forward view can help you discuss the request in practical terms and keep your longer-term business goals in mind.

Understanding how to present a business loan application is a strong starting point, but you don’t have to shape the case on your own. Mortgage Suite can help organise and negotiate a request that reflects your business’s needs and circumstances. Lenders make their own decisions, so there’s no promise of a particular result. The aim is to help you approach the conversation prepared and clear about what you’re asking for.

Have a funding need in mind, even if some details are still taking shape? Talk with Mortgage Suite about your business finance needs and take the next step at a pace that feels right for your business.

Frequently Asked Questions

How much should I ask for in a business loan application?

Ask for an amount you can explain and support with a clear breakdown of its intended use. For example, list the equipment, stock or project expenses the funding would cover, using relevant quotes or forecasts where available. Include a cash-flow estimate showing when the funds are needed. This makes it easier to present your request clearly and avoid asking for more than the business case supports.

Can a new business apply for a business loan without a long trading history?

Yes, a new business can apply, although a short trading history may leave less past performance for a lender to review. You may need to explain the business model, your experience in the industry, expected customers and how you arrived at your income forecasts. Evidence such as confirmed work or customer interest may help give context, but the lender decides what it needs and whether the request suits its lending approach.

Do I need a business plan to apply for a business loan?

A formal business plan isn’t always required, but a clear written outline can help explain what the business does and why it needs finance. Keep it practical: describe your customers, how the business earns income, what you’ll use the funds for and how you expect to make repayments. For a new venture, explain the assumptions behind projected sales and costs so they aren’t presented as established results.

Can I apply for a business loan if my business already has debt?

Yes, existing debt doesn’t automatically prevent you from applying. Be ready to outline current balances, regular repayments and any changes, such as a facility that has recently been reduced or repaid. A lender may consider how the new repayments sit alongside those commitments and the business’s available cash flow. If you’re seeking extra funding to manage debt pressure, explain the underlying cause as well as the immediate need.

Will a business loan application affect my personal credit file?

It may, depending on the lender, the type of credit check and whether the application involves a personal guarantee. A lender may review an owner’s personal credit information as part of its assessment, but checks aren’t all handled in the same way. Before authorising a check, ask how it will be carried out and whether an enquiry may appear on your file. Be open about any past credit issues and relevant context.

What happens after I submit a business loan application?

After submission, the lender reviews the information and may ask questions or request further documents to clarify parts of the application. For example, it may need an updated cash-flow forecast or more detail about a particular transaction. Keep your records accessible and respond accurately. The lender then communicates its decision and any proposed terms, if applicable. Processes and timing vary, so avoid making business plans that depend on an assumed decision date.

Can a business loan be secured against commercial property?

Yes, some business borrowing may be secured against commercial property, but this depends on the lender, the property and the wider application. The lender may consider the property’s value and the existing lending attached to it, alongside the business’s ability to repay. Offering property as security can put it at risk if repayments aren’t met, so understand the proposed terms and obligations before agreeing to use it as security.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Business Loan Requirements NZ: Your 2026 Guide to Getting Funded

What if the reason your funding feels out of reach isn’t your bank balance, but simply the way you’ve packaged your story? Most Kiwi business owners feel a sense of dread when they start looking into business loan requirements NZ, fearing that a single slip-up in their paperwork will lead to an instant decline. It’s exhausting to feel like you’re speaking a different language than the person sitting across the desk at a big bank.

We understand that your business is more than just a set of numbers on a page. You deserve a clear path to the capital you need to grow, whether you’re looking for a standard bank loan or a more flexible second-tier option. This guide is here to give you back your confidence by laying out exactly what lenders are looking for in 2026. We’ll help you tick every box, from preparing financials that tell the right story to finding a lender that actually values your hard work.

You’ll find a straightforward checklist of the documents you need, tips on valuing your assets for security, and a look at alternative funding sources that might be the perfect partner for your next big move.

Key Takeaways

  • Learn why lenders care most about your ability to repay comfortably rather than just your current bank balance.
  • Discover the three main business loan requirements NZ lenders check, including how to use your assets as a solid backup plan.
  • Understand why being turned down by a big bank isn’t the end of the road and how flexible lenders look at your whole story.
  • Find out how to tidy up your credit score and tax records to make your application look professional and ready for approval.
  • See how having a mentor with 20 years of banking experience can act as a shortcut to getting your funding secured.

Understanding the Basics of Business Loan Requirements in NZ

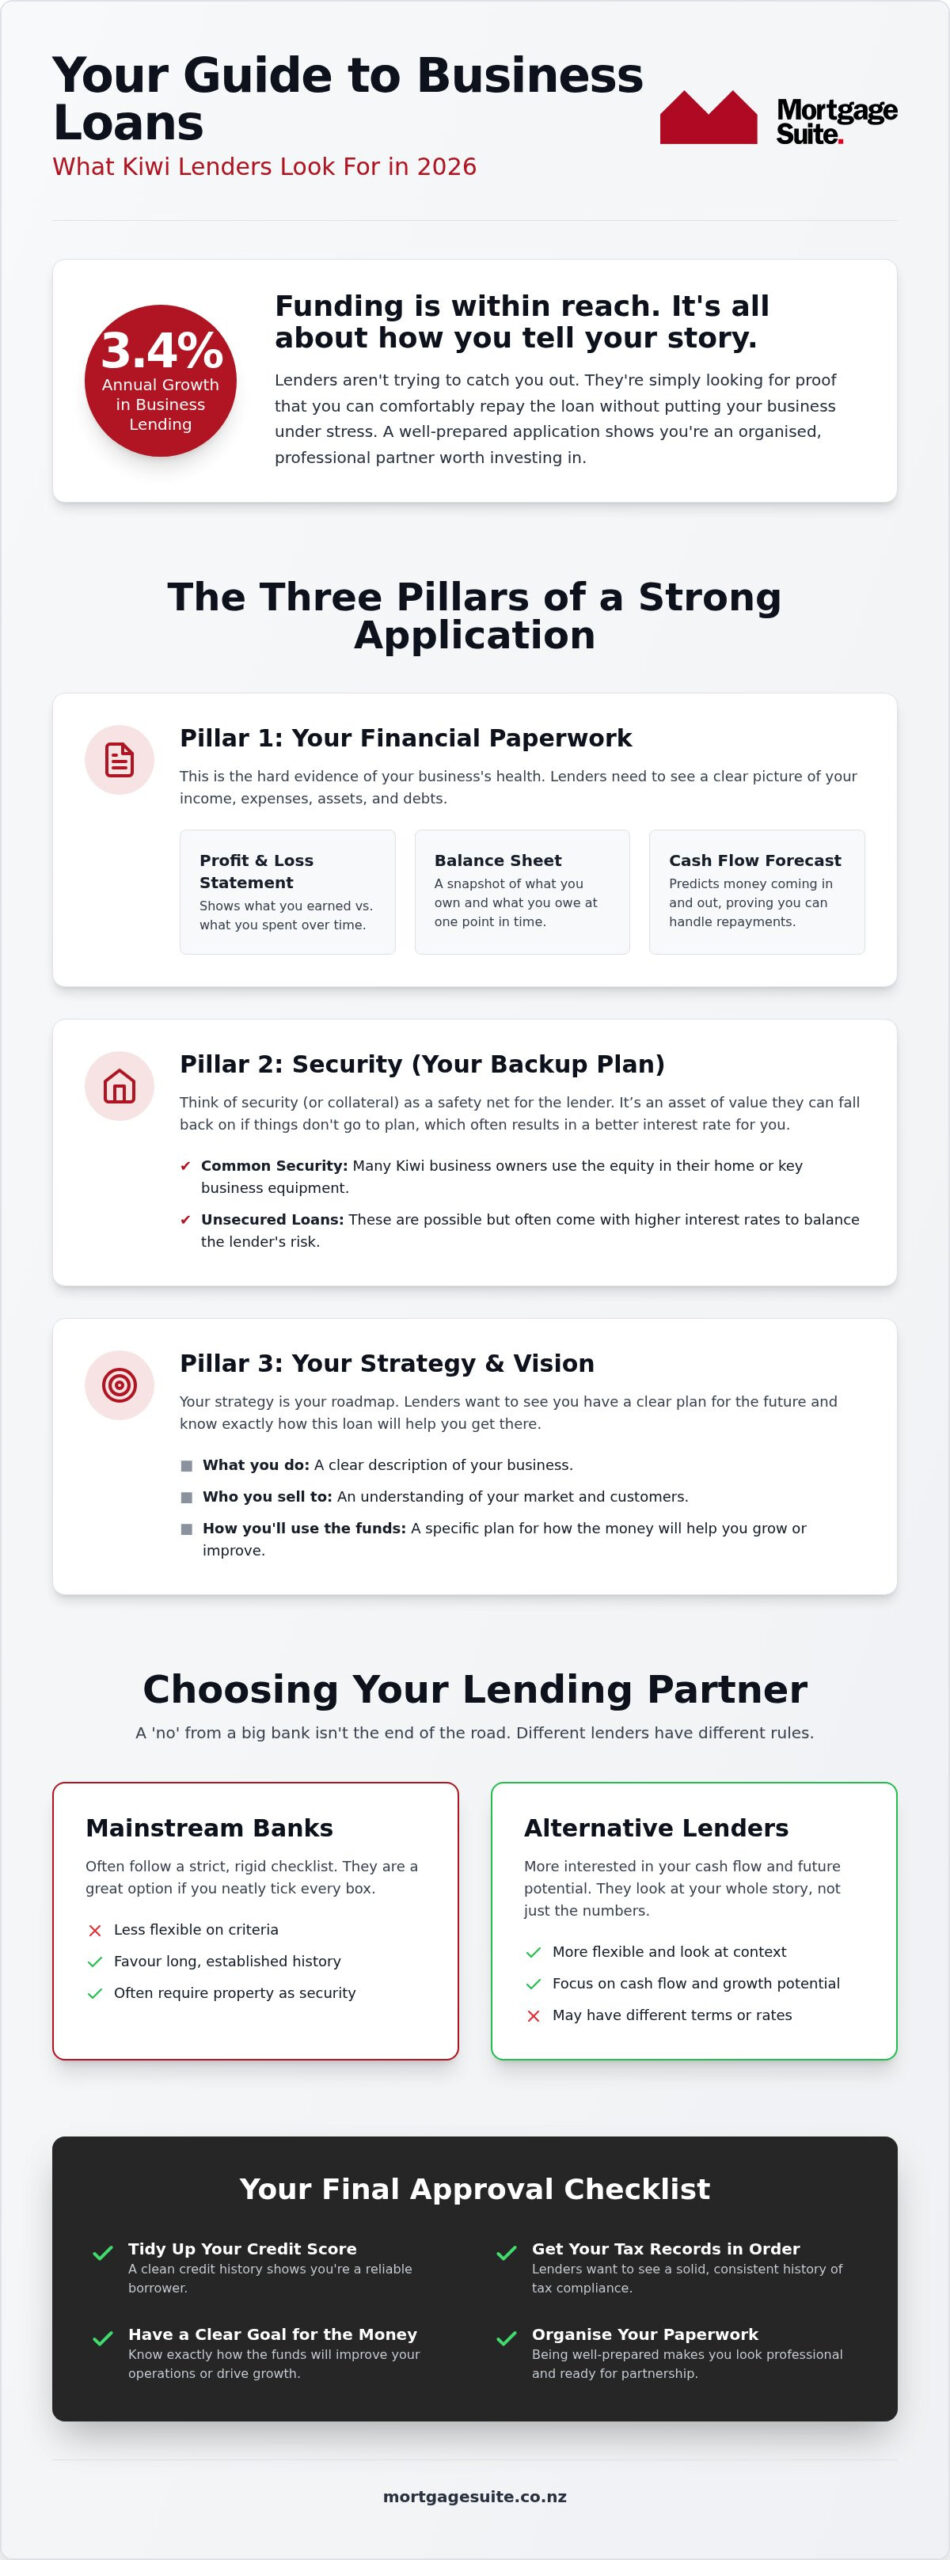
Think of business loan requirements NZ as a professional introduction. These aren’t just boxes to tick to make life difficult; they’re a set of standards that prove your venture is a safe bet for a lender. Lenders aren’t looking for reasons to say no. They’re searching for evidence that you can pay the money back comfortably without putting your business under stress. With business lending showing a 3.4% annual growth in 2026, the money is certainly available for those who can present a solid case.

These rules aren’t the same across the board. They shift depending on your situation. If you’re buying an existing company, the lender wants to see the previous owner’s numbers. If you’re starting fresh, they’ll look at your vision and your personal financial habits. Every lender has their own ‘rule book’ too. A big bank might follow a strict, rigid checklist, while a non-bank lender might be more interested in your cash flow and future potential.

Why Do Lenders Ask for So Much Information?

It often feels like a hurdle, but this process is actually about building a partnership. Lenders take on risk when they fund you, so they need to understand the full picture to feel confident. Your character as a business owner matters just as much as your bank balance. They want to see that you’re organised, honest, and capable of handling challenges. When you’re well-prepared, you look like a professional partner rather than a risky gamble. Given that the non-performing loan ratio for business loans sits at 1.1% in 2026, lenders are naturally careful about who they trust. Having a mentor who understands the ‘inside secrets’ of bank approvals can make this whole process feel much less daunting.

New Business vs. Established Business Requirements

Startups have a different mountain to climb. Since there’s no history to look at, lenders rely heavily on your business plan and financial forecasts. They need to see that you’ve done your homework and understand your market. For established businesses, the focus shifts to your track record. They’ll want to see steady earnings and solid tax records from the last few years. Regardless of your stage, you must have a clear goal for the money. Lenders want to know exactly how those funds will help you grow or improve your operations. If you want to dive deeper into how these processes work, you can check out our mortgage school for more insights.

The Three Pillars of Your Loan Application: Financials, Security, and Strategy

Success with a lender usually comes down to three main areas. These form the backbone of most business loan requirements NZ banks or private lenders look for. It’s not just about having a high turnover; it’s about showing that you have a clear grip on your money, a backup plan for the unexpected, and a sharp vision for the future. When you can present these three pillars clearly, you move from being just another applicant to being a professional partner worth investing in.

Sorting Your Financial Paperwork

Your financials are the hard evidence of how your business is actually doing. Lenders will typically ask for a Profit and Loss statement, which is a simple summary of what you made versus what you spent over a set period. They will also want to see a Balance Sheet. Think of this as a snapshot of what you own and what you owe at a specific point in time. A cash flow forecast is a prediction of the money coming in and out over the next year. This is vital because it proves you can afford the loan repayments even during slower months. To get a better handle on your potential numbers, try using the Mortgage Suite calculator to see how different loan amounts might fit your budget.

Understanding Security and Collateral

Think of security as a safety net for the lender. It is something of value they can fall back on if things don’t go to plan. Many Kiwi business owners use the equity in their home or specific business equipment to secure a loan. This often helps you get a better interest rate because the lender feels more protected. While some lenders offer unsecured options where you don’t need to put up a physical asset, these often come with different terms or higher interest rates to balance the risk. If you’re unsure how to value your assets, our team can help you look at the options that best suit your situation.

Crafting a Strategy That Wins Approvals

Your strategy is your roadmap. Lenders want to know what you do, who you sell to, and exactly how you’ll use the borrowed money to grow. They also want to see your “Plan B” for tough times. This shows them you’re a proactive leader who thinks ahead. Remember, the person behind the business is just as important as the numbers. Your experience and reputation act like a professional CV that builds trust. If you want more tips on how to present your case effectively, our Mortgage School is a great place to start learning the ropes.

Mainstream Banks vs. Alternative Lenders: Choosing the Right Path

Selecting the right lender is often the most critical decision you’ll make in your funding journey. Mainstream banks generally operate with a one-size-fits-all approach. They have rigid checklists, and if your situation doesn’t perfectly align with their internal rules, you might find your application stalled. In contrast, alternative or non-bank lenders are often more flexible. They tend to look at the bigger picture, focusing on your current cash flow and future potential rather than just your past paperwork. This flexibility is a key part of why understanding the full range of business loan requirements NZ has to offer is so important.

At Mortgage Suite, we specialise in 2nd tier lenders in New Zealand. We know that every business has a unique story, and sometimes that story needs a different type of listener than a traditional bank manager. Having a guide who knows the inside secrets of how different lenders think can save you months of frustration.

When the Bank Says “No”: Why It’s Not the End

Being turned down by a big bank can feel like a major setback, but it’s rarely the end of the road. Banks often decline applications for reasons that have nothing to do with the quality of your business. Common hurdles include having a trading history shorter than two years, using security that doesn’t involve a family home, or having a recent period of lower profit due to expansion costs. A “no” from a mainstream bank is often just a “not here” rather than a “not ever.” An expert mentor can often re-package your application to highlight your strengths to a lender that values your specific industry or growth stage.

The Pros and Cons of Non-Bank Funding

Alternative funding is a powerful tool, but it’s important to be clear about the trade-offs. The biggest advantage is speed. While a bank might take weeks to process a file, some alternative lenders can offer a decision within 24 to 48 hours. This speed allows you to jump on opportunities that won’t wait. However, you should expect different fee structures or higher interest rates. For many Kiwis, these loans act as a stepping stone. You use the funds to reach your next milestone, improve your financial position, and eventually move back to a mainstream bank when your business meets their more traditional business loan requirements NZ criteria.

Business Loan Requirements NZ: Your 2026 Guide to Getting Funded

How to Organise Your Application for the Best Chance of Approval

Preparing your application is often where the real work happens. It is not just about gathering papers; it is about presenting a clear, professional story that makes a lender want to say yes. When you approach business loan requirements NZ with an organised mindset, you demonstrate that you are a reliable partner who takes their finances seriously. A well-prepared file can be the difference between a quick approval and a long, drawn-out decline.

Follow these five practical steps to get your application ready for a lender’s desk:

  • Step 1: Check your credit score. Surprises are for birthdays, not loan applications. Knowing your score early allows you to fix any errors before a lender sees them.
  • Step 2: Tidy your tax and GST filings. Lenders look for stability. If your tax records are messy or behind, it suggests your business might be under pressure.
  • Step 3: Separate your bank accounts. Mixing personal and business money makes it difficult for a lender to see your true profit. Keep things clean and distinct.
  • Step 4: Explain the “why” in plain English. You don’t need fancy words. Just explain exactly how the money will help your business grow or become more efficient.
  • Step 5: Let a broker review it first. We act as a second pair of eyes to catch small mistakes that could lead to a decline.

Cleaning Up Your Financial Habits

Lenders love consistent, clean bank statements. In the months leading up to your application, try to avoid “buy now, pay later” schemes. While these are convenient, some lenders view them as a sign that your cash flow is tight. Reducing unnecessary personal spending and paying down small personal debts can also significantly boost your borrowing power. It shows you have the discipline to manage your money well, which gives the lender confidence that you’ll handle their funds with the same care.

The Power of a Professional Presentation

First impressions matter in the world of lending. A tidy, well-organised folder of documents shows that you are prepared and professional. If you have had a bad credit patch or a difficult trading period in the past, be honest about it. Lenders appreciate transparency, and explaining how you’ve moved past those challenges is far better than trying to hide them. You can read our Mortgage Suite reviews to see how other Kiwi business owners have successfully shared their stories to get the funding they needed. If you are ready to start your journey, contact our team to discuss how we can help you package your application for success.

Partnering with a Specialist to Secure Your Business Funding

Meeting the various business loan requirements NZ lenders set out can feel like a full-time job. This is where having a seasoned mentor makes all the difference. Krish Krishna brings over two decades of banking and brokerage experience to your side of the table. This isn’t just about filling out forms; it’s about using those years of “inside secrets” to act as a shortcut for your application. Instead of guessing what a credit manager wants to see, you have someone who has been in that seat and knows exactly how to frame your story for success.

A specialist broker acts as your advocate and negotiator. We don’t just pass on your papers; we fight for the best possible terms on your behalf. One of the biggest advantages is the sheer breadth of choice. With just one application, you gain access to dozens of different lenders, from the big name banks to flexible 2nd tier options. This saves you from having to repeat your story over and over again to different institutions, letting you stay focused on what really matters: running your company.

Why Experience Matters in a Fluctuating Market

The financial world doesn’t stand still. With the Official Cash Rate held at 2.25% in late 2026, interest rates and lending rules are constantly shifting. Navigating these changes requires a steady hand and deep institutional knowledge. A broker knows which lenders are “hungry” for new business in your specific industry at any given time. This real-time insight is invaluable when you’re looking for competitive rates or more flexible terms. You can learn more about our background and how we support Kiwi businesses on our About Us page.

Taking the Next Step with Confidence

Getting started doesn’t have to be a daunting process. It usually begins with a quick, no-obligation chat where we look at where your business stands today. From there, we build a tailored plan that matches your goals with the right lender. We handle the heavy lifting, the follow-up calls, and the complex negotiations so you don’t have to. Our goal is to move you through the process with ease and transparency. Your business has a bright future, and we’re here to help you secure the capital needed to reach that next milestone. Let’s work together to turn those growth plans into a reality.

Take the Next Step Toward Your Business Goals

Securing the capital you need to grow shouldn’t feel like an uphill battle. By focusing on clear financials and a sharp strategy, you have already laid the groundwork for a successful application. It is important to remember that meeting the business loan requirements NZ lenders expect is often about how you tell your story. If a mainstream bank isn’t the right fit, alternative and 2nd tier lenders offer the flexibility and speed that many Kiwi businesses need to thrive in a changing market.

With over 20 years of banking expertise, we act as your steady hand and dedicated negotiator. We specialise in 2nd tier and alternative lending, ensuring you have access to a wide range of options with just one conversation. You deserve a personalised service that removes the hurdles and focuses on your success. Talk to Krish and the team about your business loan today to see exactly where you stand. We are here to help you move forward with confidence and look forward to being part of your growth journey.

Frequently Asked Questions

What are the minimum requirements for a business loan in NZ?

Minimum business loan requirements NZ usually include a solid business plan, financial statements from the last two years, and proof that your cash flow can cover repayments. Lenders want to see that you understand your market and have a clear goal for the money. While mainstream banks have rigid checklists, alternative lenders might focus more on your current turnover and future potential. Being prepared with tidy records is always the best way to start.

Can I get a business loan if I have bad credit?

You can certainly secure funding with a less than perfect credit history by looking beyond mainstream banks. We specialise in 2nd tier loans for those who don’t fit standard criteria, focusing on your business’s current performance rather than past mistakes. A dedicated negotiator can help explain the context of your credit score to a lender. This approach often helps you get the capital you need while you work on rebuilding your financial reputation.

How much deposit do I need for a business loan in New Zealand?

Most lenders in New Zealand look for a deposit or equity contribution between 20% and 50% of the total loan value. The exact amount depends on the type of asset you’re buying and the level of risk the lender sees in your industry. If you are using existing property as security, you might not need a cash deposit at all. Every situation is unique, so it’s best to discuss your specific assets with a specialist.

Do I have to use my house as security for a business loan?

You don’t always have to use your family home as a backup for a business loan. While banks often prefer the security of residential property, many alternative lenders allow you to use business equipment, vehicles, or commercial property instead. Some even offer unsecured loans based on your revenue trends and cash flow. Choosing the right security depends on your comfort level and the specific terms offered by different lenders across the market.

How long does it take to get a business loan approved?

The time it takes to get an answer depends entirely on the type of lender you choose. Mainstream banks are often thorough and can take several weeks to process an application. On the other hand, many non-bank lenders specialise in speed and can provide an approval within 24 to 48 hours. Having all your documents organised and ready to go before you apply is the most effective way to speed up the entire process.

What documents do I need to show my lender?

You will generally need to provide your latest profit and loss statement, a balance sheet, and at least six months of bank statements. Lenders also want to see your recent GST and income tax filings to ensure your records are up to date. A clear business plan and a cash flow forecast are vital for showing how the loan will be repaid. Keeping these documents in a tidy, digital folder makes the application much smoother.

Is it better to go to a bank or a broker for a business loan?

A broker is often the better choice because they offer you access to dozens of lenders with just one application. While a bank can only sell you its own products, a broker acts as your advocate and negotiator to find a deal that actually fits your business needs. With over 20 years of experience, we know which lenders are most likely to say yes to your specific scenario, saving you time and stress.

Can I get a loan for a startup business with no trading history?

Getting a loan for a startup is possible, but the focus shifts from your history to your future potential. Since you don’t have past trading figures, you’ll need a very strong business plan and detailed financial forecasts. Lenders will also look closely at your personal credit history and professional experience in the industry. You might need to provide some form of security or a personal guarantee to give the lender the confidence they need.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial Property Loan Requirements NZ: Your 2026 Essential Checklist

What if the biggest hurdle to your next commercial investment isn’t the size of your deposit, but how you tell your story to the lender? If you’ve spent any time looking at the current market, you’ll know that meeting the commercial property loan requirements nz lenders expect can feel like a moving target. With the official interest rate set by the Reserve Bank sitting at 2.50% and market rates stabilising between 6.5% and 7.5%, the opportunity is certainly there; however, the path to approval isn’t always straightforward.

It’s completely normal to feel a bit anxious about the complexity of commercial leases or frustrated by the rigid rules mainstream banks often enforce. You likely want to grow your portfolio or secure a permanent home for your business without getting lost in a sea of paperwork and technical talk. We’ve spent years helping Kiwis navigate these hurdles, and we know that a “no” from a big bank is often just the start of a much more productive conversation with a different lender.

This guide gives you a clear, jargon-free breakdown of exactly what you need to secure a commercial property loan in New Zealand this year. We’ll walk you through a simple list of documents to prepare, explain the crucial differences between bank and non-bank lenders, and map out a clear path to getting your application approved.

Key Takeaways

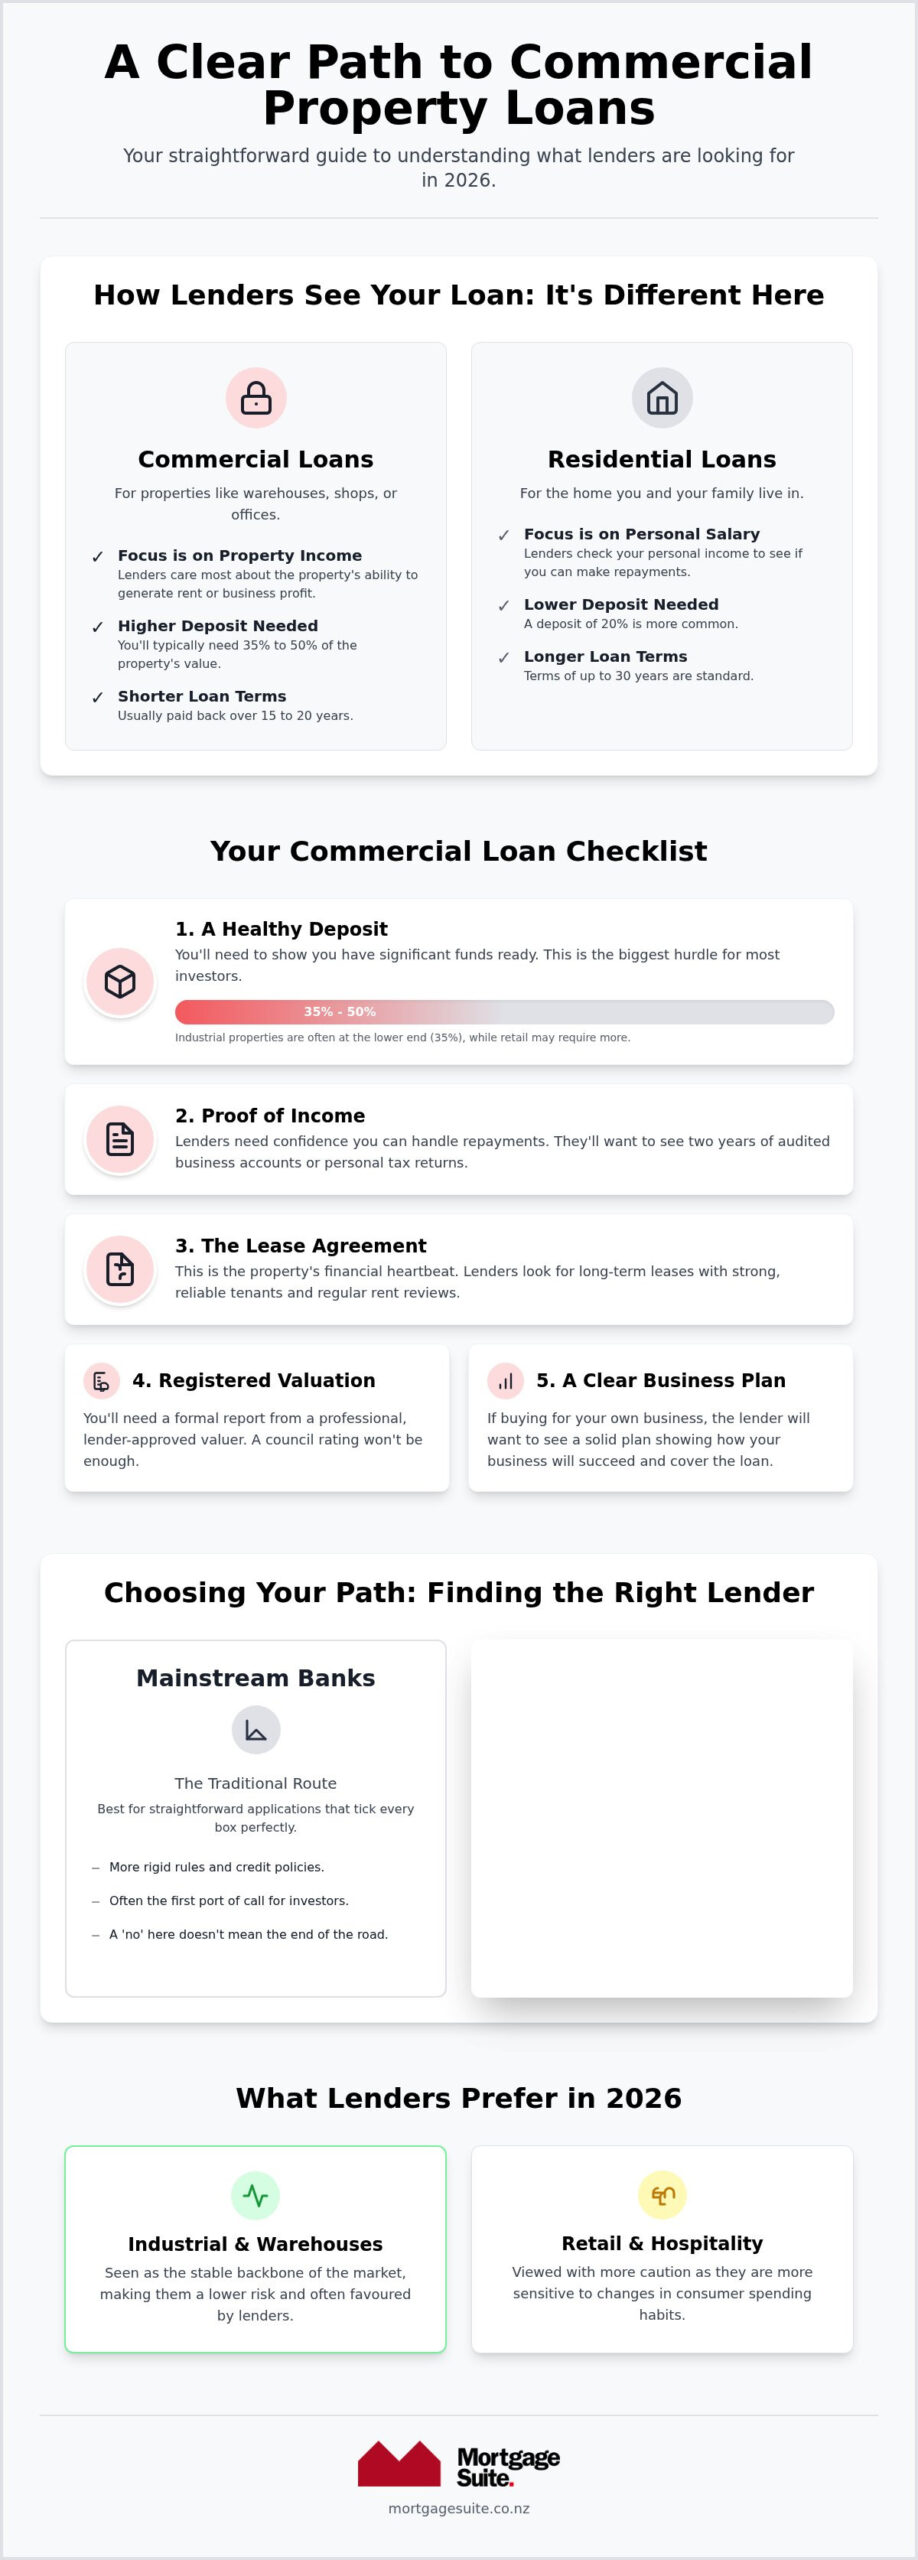
  • Learn why commercial lenders prioritise a property’s ability to generate income over your personal salary when assessing your application.
  • Get a clear breakdown of the documents and deposit levels, typically between 35% and 50%, needed to meet commercial property loan requirements nz standards in 2026.
  • Discover how 2nd tier lenders can offer a flexible alternative when mainstream banks’ rigid rules don’t quite fit your situation.
  • Understand why a solid due diligence period and a specialised legal team are your best defences against hidden property issues.
  • Find out how a mentor with 20 years of banking experience can help you navigate complex negotiations to secure a “yes” from the right lender.

What is a commercial property loan and how does it differ?

Imagine you’re looking to buy a warehouse or a central city office space instead of a three-bedroom house in the suburbs. The way a bank looks at these two scenarios is worlds apart. A Commercial mortgage is a loan specifically for properties used for business purposes; think industrial sheds, retail shops, or professional suites. While a standard home loan is usually based on your personal salary, the commercial property loan requirements nz lenders set are much more focused on the property itself. They want to know if the building can pay for itself through rental income or business profit. This means the bank will look at the history of the building and the strength of the businesses operating within it before they even consider your own bank statements.

Because these properties are closely tied to the health of the economy, banks see them as a bit more of a gamble than a residential home. If a business closes down, it’s often harder to find a new tenant for a specialised warehouse than it is to find a renter for a family home. This risk factor means you’ll usually see interest rates that sit a bit higher than what you’d pay for a house. You also won’t have the luxury of a 30 year term to pay it off. Most lenders in New Zealand will want the loan cleared in 15 to 20 years, which means your monthly repayments will be higher from the start.

Key differences you need to know

The biggest shock for many first-time commercial buyers is the deposit. While you might secure a home with a 20% deposit, commercial deals often have much stricter borrowing limits, requiring you to bring 35% to 50% of the property’s value to the table. To meet the specific commercial property loan requirements nz banks expect, you’ll need to show you have significant funds ready to go. Lenders also treat the lease as king. They don’t just look at the bricks and mortar; they look at who is inside the building and how long they’ve committed to stay. A long-term tenant with a strong reputation makes your application look much safer. If you’re borrowing through a company, you should also expect to provide a personal guarantee. This means you’re personally responsible for the debt if the business or the property’s income can’t cover it, ensuring you have just as much skin in the game as the lender.

Why the purpose of the property matters

How you plan to use the building changes the entire conversation with the lender. An owner-occupied property is a business owner buying their own premises to escape the rent trap. For these buyers, the bank focuses on the health of the business that will be living there. On the flip side, an investment property is one you buy purely to lease out to another business. In 2026, we’re seeing a clear trend where lenders favour industrial sheds and warehouses because they’re seen as the stable backbone of the market. Retail and hospitality spaces are often viewed with more caution because they are more sensitive to changes in how people spend their money. Knowing these preferences early on allows us to match your specific goals with the right lender’s appetite.

The 2026 Commercial Loan Requirements Checklist

Getting your ducks in a row before you talk to a lender saves a lot of back and forth. Think of this checklist as your roadmap to a faster “yes”. While every deal has its own quirks, there are five non-negotiables you’ll need to satisfy the commercial property loan requirements nz lenders have in place this year. Being prepared shows the bank you’re a serious professional who understands the market.

  • A healthy deposit: Expect to put down between 35% and 50% of the property value. As we touched on earlier, industrial sheds usually sit at the lower end of this range, while retail spaces often require a bit more upfront.
  • Proof of income: Lenders typically want to see two years of audited accounts for your business or personal tax returns to prove you can handle the repayments.
  • The Lease Agreement: This is the building’s heartbeat. Lenders look for long terms, regular rent reviews, and a tenant with a solid history of paying on time.
  • A Registered Valuation: You’ll need a professional report from a lender-approved valuer. A council rating just won’t cut it here.
  • A clear business plan: If you’re buying the premises to run your own show, the bank needs to see that your business is stable and growing.

Financial documents you’ll need to organise

Your financial history tells the lender how you handle money under pressure. You’ll need to gather your Profit and Loss statements and Balance Sheets from the last two financial years. It’s also helpful to have a clear list of any existing debts or other mortgages you’re currently paying off. Banks are particularly interested in seeing where your deposit is coming from, so have your bank statements ready to show that the funds are sitting there, ready to go. If you’re unsure if your financials are “bank-ready”, it might be worth talking to a specialist at Mortgage Suite Ltd who can help polish your application before it hits a credit manager’s desk.

Property-specific requirements

In New Zealand, the physical state of the building is just as important as the numbers. You’ll need to provide details on “outgoings” like rates, insurance, and maintenance costs so the lender can calculate the true net income. A Detailed Building Report or a professional earthquake safety rating is vital. Lenders are much more comfortable with properties that have a high safety score, as it lowers their long-term risk. You can find more about how these factors influence decisions in the Banking Ombudsman Scheme’s guide to lending restrictions. Finally, don’t forget the “Warrant of Fitness” for the building’s essential services like fire alarms and lifts; if these aren’t up to scratch, it could stall your loan.

Mainstream Banks vs. 2nd Tier Lenders: Choosing your path

Deciding between a mainstream bank and a non-bank lender is often the most critical choice you’ll make in your investment journey. The “Big Four” banks in New Zealand generally offer the most competitive interest rates; however, they also have the most rigid “hoops” to jump through. If your situation doesn’t fit their perfect box, you might find yourself facing a frustrating dead end. This is where 2nd tier or non-bank lenders come into the picture. These providers are often much more flexible with how they assess your income or credit history. At Mortgage Suite Ltd, we specialise in finding 2nd tier lender New Zealand solutions for those tricky cases that mainstream banks might turn away. One major advantage of non-banks is the ability to offer “interest-only” periods. This can be a massive help for your cash flow during those early months when you’re still settling into a new property or waiting for a tenant’s business to ramp up.

When to stick with a big bank

If you have a substantial deposit of 50% or more and a spotless financial history, a mainstream bank is likely your best bet. They are the go-to choice if you’re chasing the absolute lowest interest rate and don’t mind providing a mountain of paperwork to get there. Often, if you’ve had a long-standing relationship with a bank and run all your business accounts through them, they may be slightly more willing to work with you on the specific commercial property loan requirements nz lenders demand. It’s about weighing up the cost savings against the time and effort required to meet their strict criteria.

When a non-bank lender is a smarter play

Sometimes, the traditional path isn’t the fastest or the most effective. A non-bank lender is often a smarter play if your business financials are a bit complex or if you’ve only been trading for a short time. They are also far more open to “non-standard” properties. If you’re looking at a specialised cold-storage facility, a rural workshop, or a building with a lower seismic rating, a mainstream bank might say no, but a 2nd tier lender will often look at the bigger picture. Speed is another huge factor. If you need a fast approval to snap up a prime property before a competitor does, non-bank lenders can often move much quicker than the big institutions. They focus on the value of the asset and the logic of the deal rather than just ticking boxes.

Commercial Property Loan Requirements NZ: Your 2026 Essential Checklist

The due diligence process: Don’t skip these steps

Once you’ve found a property that seems to fit the commercial property loan requirements nz lenders look for, the real work begins. Due diligence is essentially your “get out of jail free” period. It’s the time to peel back the layers and see if the deal is as good as it looks on paper. You’ll want a lawyer who lives and breathes commercial law on your side. Residential conveyancing is a different beast entirely; you need someone who understands complex leases and land use. They’ll help you dig into the “Title” to find any easements or restrictions that could stop you from building that extra warehouse space or adding a second floor in five years’ time.

You also need to verify the rental yield with your own eyes. It’s not just about the optimistic number on the real estate flyer. You need to be certain the rent hitting your account actually covers the mortgage, rates, and insurance with a healthy buffer left over. If the tenant’s business is struggling or the lease is about to expire, the bank’s appetite for the deal will change instantly. If the numbers don’t stack up during this phase, you can walk away without losing your shirt.

Getting your pre-approval sorted

Talk to a broker early to find out your true borrowing power before you start window shopping. Knowing exactly what you can afford gives you the confidence to negotiate hard on the purchase price. It’s worth remembering that pre-approval for a commercial project is often “indicative” rather than a blanket guarantee. The final “yes” depends heavily on the specific building, the quality of the tenant, and how the property fits into the lender’s current portfolio. Ready to see what you can actually borrow? Get in touch with us today to start your pre-approval process and shop with confidence.

Environmental and seismic checks

For industrial sites in New Zealand, land contamination is a massive risk that many buyers overlook. If the soil is dirty from previous chemical use or heavy manufacturing, the cleanup costs could be yours to bear. Then there’s the NBS (National Building Standard) rating. Meeting the commercial property loan requirements nz banks set often hinges on this score. Anything under 34% is officially earthquake-prone. Most mainstream banks won’t touch these properties, or they’ll demand a significantly higher deposit and a clear, funded plan to fix the building immediately. Don’t forget to look for outstanding maintenance like roofing or electrical issues that could bite your budget in the first twelve months of ownership.

How Mortgage Suite Ltd helps you cross the finish line

At Mortgage Suite Ltd, we believe that securing finance should be a partnership rather than a transaction. We know that getting a loan approved is about more than just ticking boxes on a checklist. While meeting the basic commercial property loan requirements nz lenders set is a necessary start, the real success lies in how we present your business case to the right people. We don’t just fill in forms and hope for the best. Instead, we take the time to understand your unique situation and tell your story to the lender in a way that highlights your strengths and mitigates their concerns. Krish Krishna brings over 20 years of deep banking experience to the table. This means he knows exactly how to navigate those tricky “grey areas” that often trip up other applications. Our goal is to make this entire process feel like a friendly, productive chat over coffee, rather than a cold or clinical trip to the principal’s office.

A personal approach to professional finance

We take on the heavy lifting and the tough negotiations so you can stay focused on what you do best: running your business and growing your wealth. Meeting the commercial property loan requirements nz lenders expect doesn’t have to be a solo mission. Whether you are looking at a simple shop-front purchase for your own firm or a complex commercial property refinance NZ to unlock equity, we have likely seen a similar scenario before. Our network is extensive and covers the entire market. This includes everyone from the traditional big four banks to specialised property development loans NZ providers and private lenders. We don’t just hand you an indicative offer and walk away; Mortgage Suite Ltd acts as your advocate and guide from that very first enquiry through to the day you finally get the keys in your hand.

Ready to take the next step?

No matter where you are based in New Zealand, Mortgage Suite Ltd is here to help you figure out your best move in the current market. Every commercial journey is different, and we take genuine pride in offering advice that is tailored specifically to your long-term goals. We value personal connection and long-term relationships over quick transactional wins. Give us a bell for a no-obligation chat about your plans and let’s see how we can make them a reality. Let’s get your commercial property journey sorted without the usual stress, jargon, or unnecessary hurdles. We are ready when you are.

Take the next step in your property journey

Stepping into the commercial market is a bold move that can set you up for long-term success. By now, you’ve got a much clearer picture of how commercial property loan requirements nz lenders set differ from standard residential rules. It’s vital to remember that a solid lease and a healthy seismic rating are just as important as your financial history. Whether you’re aiming for a big bank or need the flexibility of a non-bank lender; the way you present your story is what ultimately secures that approval.

You don’t have to navigate these complex waters alone. With over 20 years of banking expertise, we specialise in finding solutions for non-standard scenarios that others might find too difficult. As a trusted Kiwi broker, we offer a personalised service that puts your business goals first. If you’re ready to move past the paperwork and find a clear path forward, Book a free consultation with Krish and the team at Mortgage Suite today. We’re here to help you turn your investment plans into a reality with confidence and ease.

Frequently Asked Questions

How much deposit do I need for a commercial property in NZ?

You will typically need a deposit of between 35% and 50% for a commercial property in New Zealand. Mainstream banks generally lend up to 65% of the property’s value, while some non-bank lenders might push this to 70% for the right deal. The exact amount depends on the property type; industrial warehouses often require smaller deposits than retail shops or specialised buildings.

Can I use equity from my home to buy a commercial property?

Yes, you can certainly use the equity in your residential home to help fund a commercial purchase. This is a common strategy for business owners looking to expand without needing a large cash deposit. We can help you structure the loan so that your home provides the necessary security to meet the commercial property loan requirements nz lenders expect for a successful application.

Is it harder to get a commercial loan than a residential one?

Commercial loans are generally considered more complex because lenders focus on the property’s income potential rather than just your personal salary. They look closely at lease terms, tenant quality, and building safety ratings. While the commercial property loan requirements nz lenders set are different from residential ones, having a clear business case and the right documents ready makes the entire process much more manageable.

What is the typical interest rate for commercial property in 2026?

As of August 2026, interest rates for commercial properties have stabilised and typically sit between 6.5% and 7.5%. These rates are influenced by the Reserve Bank’s Official Cash Rate, which was set at 2.50% in July 2026. Your specific rate will depend on factors like the strength of your tenant’s lease, the property type, and your overall financial position at the time of your application.

How long does the approval process take for a commercial loan?

You should expect the approval process to take anywhere from two to four weeks from the time you submit all your documents. Mainstream banks often take longer due to their strict internal committees and rigid processes, while non-bank lenders can sometimes move faster. Being organised with your profit and loss statements and registered valuations early on will help speed things up significantly.

Do I need a business plan to get a commercial mortgage?

Yes, a clear business plan is almost always required if you plan to run your own business from the premises. Lenders want to see that your company is stable and has a clear path for future growth to cover the loan repayments. For pure investment properties, the focus shifts more toward the strength of the existing lease agreement, the tenant’s track record, and the building’s maintenance history.

What happens if a bank declines my commercial loan application?

If a mainstream bank says no, it doesn’t mean your journey is over. Many successful investors turn to 2nd tier or non-bank lenders who have a higher appetite for “non-standard” deals or complex financials that don’t fit the big banks’ boxes. We specialise in taking those “no” results and finding a lender whose criteria actually match your specific situation and property type.

Can I get an interest-only commercial loan in New Zealand?

Yes, interest-only periods are quite common in the commercial sector, particularly with non-bank lenders in New Zealand. These periods can last for a few years and are a great tool for managing your cash flow while you settle into a new building or wait for rent reviews. It’s a flexible option that helps you grow your business without the immediate pressure of full principal repayments.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.