
Subdivision Finance NZ: Your 2026 Guide to Funding Your Land Project

What if the “No” you just received from your bank is actually the best thing that could happen to your development? It’s a common story in the 2026 market. You have the land and the vision, but the big banks are tightening their belts and drowning you in talk of pre-sales and drawdowns. Securing subdivision finance nz doesn’t have to be a roadblock that stops your project before the first spade hits the dirt.

Most landowners find the process of funding a project incredibly stressful, especially when faced with hidden civil costs and confusing council fees. We agree that it’s a lot to handle on your own. This guide promises to give you the clarity you need to move forward with confidence. You’ll discover how to bypass mainstream bank hurdles, understand the non-bank options available to you, and learn the best ways to maximise your profit in this changing regulatory environment. We will walk you through the entire path from your initial application to the final settlement, ensuring you have a steady hand to guide you.

Key Takeaways

  • Understand why a standard home loan won’t work for development and how the right funding structure turns one piece of land into multiple titles.
  • Compare the major banks with private lenders to find a path that avoids endless red tape and keeps your project moving.
  • Uncover the hidden costs like council fees and civil works that you must account for when securing subdivision finance nz.
  • Learn how to build a rock-solid case for approval by focusing on the one document every lender considers a “must-have.”
  • Discover how professional negotiation and years of banking experience can help you bridge the gap between a “no” and a successful project.

What is Subdivision Finance and Why Does it Matter?

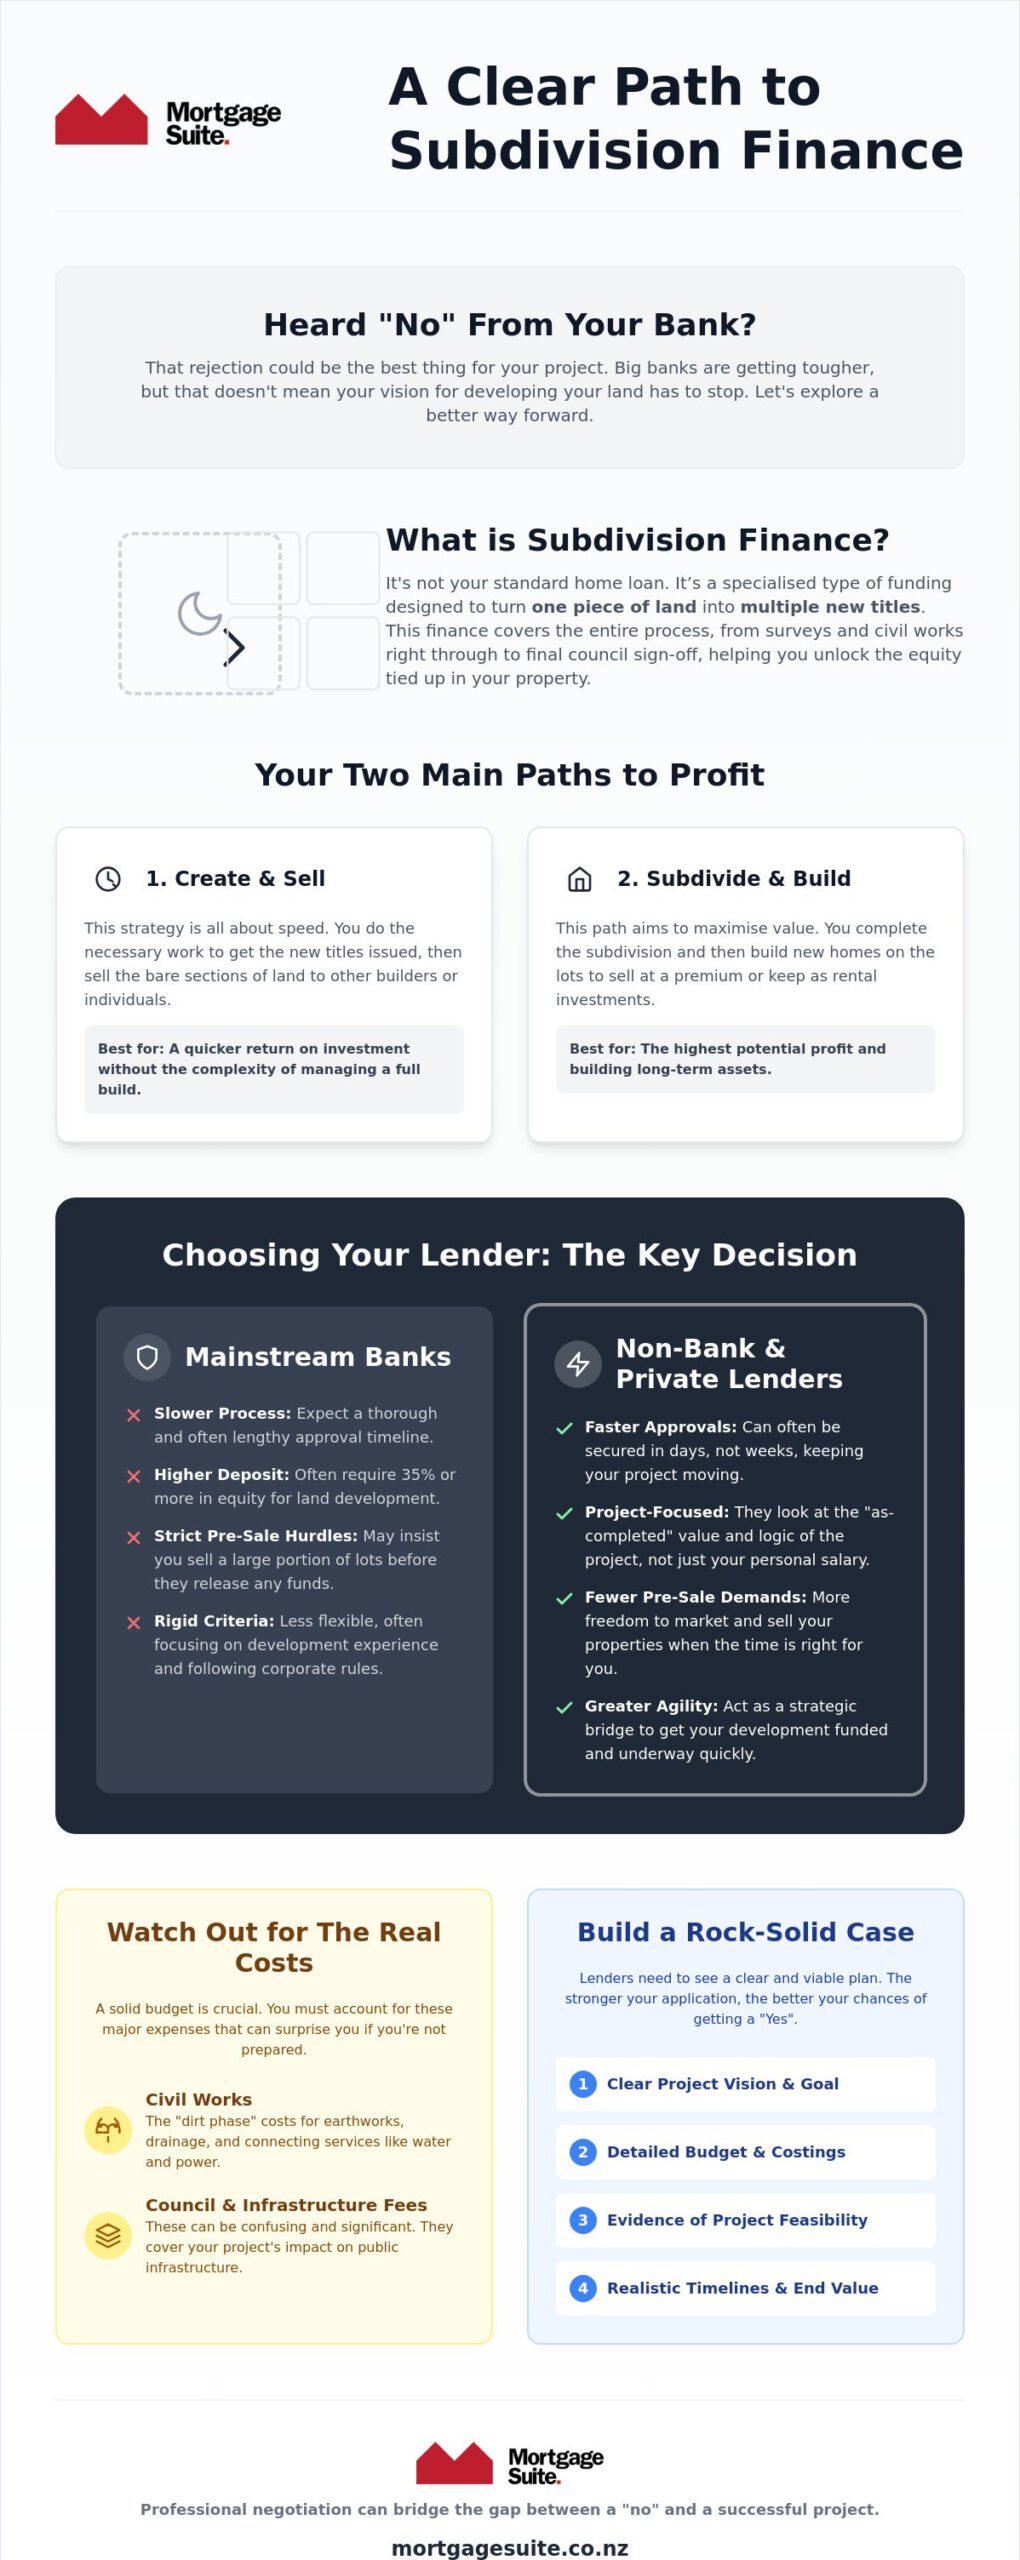
Think of subdivision finance nz as the specialised engine that powers your project from a simple idea to a profitable reality. It isn’t just a standard mortgage with a different name. This is a specific type of funding designed to handle the transition of one piece of land into multiple legal titles. While your everyday home loan is great for buying a finished house, it isn’t built to handle the complexities of a development site. You need money that works as hard as you do, covering everything from the first survey to the final council sign-off.

The goal here is simple: you want to unlock the equity sitting in your land. By dividing the property, you create new assets that didn’t exist before. This process, formally known as Subdivision (land), requires a lender who understands that you aren’t just buying a home; you’re running a business venture. The right subdivision finance nz package stays with you through the “dirt” phase, the civil works, and right up until you receive your Statement of Compliance from the local council.

The Two Main Ways to Profit from Your Land

Most of our clients choose one of two paths. The “Create and Sell” strategy is popular because it’s often faster. You do the work to get the new titles and then sell the bare land to someone else. It’s a great way to get a quick return without the stress of a full build. On the other hand, the “Subdivide and Build” strategy offers the most long-term value. You keep the land, build new homes, and either sell them for a premium or keep them as rentals. Because these paths have different risks and timelines, the type of loan you need will change depending on your final goal. If you plan to build on your new lots, understanding how a construction loan NZ works alongside your subdivision funding is an essential next step.

Why Your Current Bank Might Say No

It’s incredibly frustrating to be turned down by a bank you’ve been with for years. Mainstream banks often see vacant or “unimproved” land as a high-risk gamble. They might demand that you have years of development experience or insist on pre-sales before they’ll even look at your application. If you find yourself hitting a brick wall, it’s time to look at 2nd tier lender New Zealand options. These lenders are often more interested in the actual feasibility of your project than just following a rigid set of corporate rules. Having this backup plan ensures your project doesn’t stall just because a big bank didn’t see the potential you do.

Bank Loans vs. Non-Bank Lenders: Choosing Your Path

Deciding where to source your capital is the most critical choice you’ll make for your development. While many Kiwis naturally head to the “Big Four” banks first, the 2026 lending landscape for subdivision finance nz is much broader than it used to be. The right choice depends entirely on your timeline, your cash flow, and how much “red tape” you’re willing to handle. While banks offer the most attractive interest rates on paper, their rigid criteria can often stall a promising project before it even gets off the ground.

Non-bank lenders, on the other hand, operate with a different level of flexibility. They tend to focus on the logic of the project itself rather than just your personal salary or background. This shift in focus is why many successful developers use alternative funding to keep their projects moving when a traditional bank says no. 2nd tier lending acts as a strategic bridge for developers who need speed and fewer pre-sale hurdles to reach their goals.

The Mainstream Bank Approach

If you choose a traditional bank, you should expect a thorough and often slow process. Banks typically demand significantly higher deposits for land development, often asking for 35% or more in equity. Their biggest hurdle is the “pre-sale” requirement. A bank might insist that you sell a large portion of your lots before they release any funds. This cautiousness stems from the complex legal requirements found in the Resource Management Act 1991, as banks want to be certain the project is financially viable before they take on the risk.

The Non-Bank and Private Advantage

Non-bank and private lenders offer a level of agility that mainstream banks simply can’t match. Approvals can often be secured in a matter of days rather than weeks, which is vital when you’re trying to settle on a property or start civil works. These lenders often look at the “as-completed” value of your project. Instead of just looking at what the dirt is worth today, they consider the value of the new titles you’re creating. This approach, combined with fewer pre-sale requirements, allows you to market your property when the timing is right for you, not just when the bank says so. If you’re unsure which route fits your specific project, the team at Mortgage Suite Ltd can help you weigh up these options to find the most profitable path forward.

The Real Costs: Infrastructure, Fees, and the ‘Money Pit’

On paper, turning one lot into two or three looks like a guaranteed win. However, the reality of subdivision finance nz is that the most significant costs often hide beneath the surface. It isn’t just about the purchase price; it’s about the “hard costs” that turn a piece of dirt into a buildable site. Many first-time developers are caught off guard by the sheer scale of investment required before a single house frame even goes up. This is where a project can easily become a “money pit” if you haven’t planned for the specific expenses that councils and contractors will demand.

Because these costs are so front-heavy, property development loans NZ are structured differently than a standard mortgage. Instead of getting all the money at once, you use “progressive drawdowns.” This means your lender releases funds in stages as you hit specific milestones, such as completing the drainage or finishing the roading. We always recommend setting aside a contingency fund of at least 10% to 15% of your total budget. Whether it’s hitting unexpected rock during excavation or a sudden change in council requirements, having that buffer prevents your project from grinding to a halt.

Council Fees and Civil Works

In 2026, council fees remain a major hurdle. In Auckland, for example, development contributions can range from approximately $20,400 to $49,000 per new lot depending on the area. You also have to account for the Watercare infrastructure growth charge, which is now roughly $29,300 per unit. These “entry fees” simply give you the right to subdivide. On top of that, you must pay for the physical work to connect every new lot to power, water, and sewage. These civil works are often the biggest drain on your cash flow, but they are essential for creating a valuable asset.

Managing Your Cash Flow During the Build

One of the best ways to protect your sanity during a project is through “capitalised interest.” This is a common feature in subdivision finance nz where the interest payments are added to the loan balance instead of you paying them out of your pocket every month. It keeps your cash free for the actual work. To make sure everything stays on track, lenders often use a Quantity Surveyor (QS) to check the progress. The QS visits the site, confirms the work is done, and gives the green light for the next drawdown. If you find a perfect new site while your current project is still finishing, you might consider bridging finance nz to secure the next opportunity without waiting for your current lots to settle.
Subdivision Finance NZ: Your 2026 Guide to Funding Your Land Project

The Approval Checklist: What Lenders Need to See

Getting a “yes” for subdivision finance nz isn’t just about owning a great piece of land. It’s about showing you have a solid plan to turn that dirt into a profit. Lenders are naturally a bit cautious, and they want to see that you have done your homework before they hand over any money. You need to put together a professional package that shows you understand the risks and have a clear way to handle them. A lender’s confidence is built on the strength of your planning, not just the size of your property.

Before you pick up the phone to talk to a broker, start gathering your essential papers. This includes your personal money statements, a clear copy of your ownership papers, and any letters you’ve had from the council about planning permission. Having these ready to go shows that you are a serious developer who understands the process. It makes the whole conversation much smoother from the very first day.

Proving the Project Works (The Feasibility)

Your feasibility study is the most important part of your toolkit. It is basically the story of how your project will actually make money. It needs to break down every single cost, what you expect to sell the new lots for, and your final profit. One common mistake is being a bit too optimistic about those final sale prices. If your numbers look too high compared to what’s actually selling nearby, a lender will lose trust in your whole plan. You also need to account for GST, which can take a big bite out of your budget if you haven’t planned for it properly. Understanding exactly how to obtain development funding from the right lender starts with getting this feasibility document right.

Your Experience and Your Team

If this is your first time doing a project like this, don’t worry. You can use the experience of your team to reassure the lender. Having a seasoned planner or a project manager with a great track record makes a massive difference to your application. Lenders also look much more favourably on projects that have fixed-price contracts for the work in the ground. This locks in your costs and prevents the “money pit” scenario we talked about earlier. Securing subdivision finance nz is much easier when you have a specialist broker to help package your story. If you’re ready to get moving, reach out to the team at Mortgage Suite Ltd to see how we can help you secure the funding you need.

How Mortgage Suite Ltd Navigates the Subdivision Maze

Krish Krishna brings over 20 years of big bank experience to your side of the table. It is your secret weapon when you are talking to lenders. When you are dealing with the tricky world of subdivision finance nz, you don’t just need someone to fill out forms. You need a veteran who knows exactly how those big banks think and what they want to see in a successful plan. Mortgage Suite Ltd acts as a bridge between your vision and the money needed to build it. Our goal is to take the stress out of the money side of things, especially when the usual banks make it feel like you are hitting a brick wall.

We believe in a partnership that stays away from confusing business talk. You won’t find us using complex terms that make your head spin. Instead, we focus on clear, honest chats about what your project needs to get across the finish line. Because we have built strong connections all over New Zealand, we can find private funding options that you won’t find by just walking into a local branch. We know which lenders are actually looking for development projects right now, which saves you a lot of time and hassle. Our team can also walk you through property development funding strategies that match your specific project goals and timeline.

A Personal Approach to Complex Finance

At Mortgage Suite Ltd, we don’t just “process” paperwork. We mentor you through the whole process of getting your loan. Whether you are in a big city or a smaller regional centre, our national reach means we help Kiwis everywhere unlock what their land is worth. We handle those tough talks with lenders so you don’t have to. If a lender has questions about your timeline, we are the ones who step in and stick up for you. We use our reputation to find solutions that keep your project moving and protect your profit. You are never just a number to us; you are a partner whose success is our priority.

Getting Started with Mortgage Suite Ltd

The first step is always the easiest. It starts with a simple, friendly chat to see if your project has “legs.” We will listen to your goals and help you decide which path makes the most sense for you. From there, we help you get your plan and your team organised so you have the best shot at getting a “yes.” We know exactly what lenders need to see to feel good about your project. Ready to see what your land is really worth? Let’s chat about your subdivision goals today.

Ready to Unlock Your Land’s Potential?

Turning a single plot of land into multiple titles is a major project, but it remains one of the most effective ways to build wealth in the 2026 market. Success depends on choosing the right path between traditional banks and more agile non-bank lenders. You now understand the need to account for those hidden infrastructure costs and why a rock-solid feasibility study is your best tool for approval. Getting the right subdivision finance nz is the foundation for your entire project.

With over two decades of banking and brokerage experience, Krish Krishna and the team are ready to help you move forward. We specialise in 2nd tier and non-bank lending solutions that often provide the flexibility you won’t find on the high street. Our national service covers all of New Zealand, ensuring you have a seasoned mentor by your side regardless of where your land is located. We handle the tough negotiations so you can focus on the build.

Don’t let red tape or a bank’s “no” stop your progress. Book a consultation with Krish and the team at Mortgage Suite today. We are here to help you turn your vision into a profitable reality.

Frequently Asked Questions

Can I get a land development loan if I’ve been declined by my bank?

Yes, you absolutely can. Traditional banks often have very narrow “boxes” that many profitable projects simply don’t fit into. We specialise in connecting developers with 2nd tier and private lenders who prioritise the actual feasibility and logic of your project over a rigid computer-generated credit score. If your land has value and your plan is solid, there is almost always a funding path available.

How much deposit do I need for a subdivision in New Zealand?

While mainstream banks typically ask for a deposit of 35% or more, non-bank options can be much more flexible. These lenders often look at the “as-completed” value of your project rather than just the current price of the land. This means if you already own the property, the equity you’ve built up over time could potentially cover the entire deposit for your civil works.

What are ‘pre-sales’ and do I always need them to get funding?

Pre-sales involve selling your new lots to buyers before the final titles have been issued. Big banks often demand these to prove there is a market for your project before they release any funds. However, many private lenders don’t require them at all. This gives you the freedom to finish the project first and sell when the market is stronger, potentially increasing your final profit margin.

Can I use the equity in my current home to fund a subdivision?

Yes, using the equity in your existing property is one of the most common ways to kickstart a development. By securing your subdivision finance nz against your home, you can often access the cash needed for those early council fees and civil works. It’s a smart way to get the project moving without needing to have a large amount of cash sitting in the bank.

How long does it usually take to get subdivision finance approved?

If you are working with a non-bank or private lender, you can often get an approval in just a few days. Mainstream banks are much slower and can take several weeks to process the same application because of their internal red tape. Speed is often vital when you are trying to secure a site or book a contractor who has a limited window of availability.

Is it better to subdivide and sell bare land or build houses first?

The best choice depends on your personal goals and your tolerance for risk. Selling bare land is generally faster and requires less capital, which makes it a lower-risk option. Building houses on the new lots involves more work and a longer timeline, but it usually offers a significantly higher profit. If you decide to build, exploring your construction loan NZ options early will help you understand the full funding picture. We can help you look at the numbers for both strategies to see which fits your situation.

What happens if my infrastructure costs go over budget?

If you hit an unexpected hurdle that pushes costs up, the first step is to talk to your lender immediately. This is why we build a contingency buffer into your initial budget. If you’ve already used that buffer, we can often negotiate a “top-up” or look at alternative subdivision finance nz options to ensure the project reaches completion. The key is having a specialist who can manage those tough conversations for you.

Do I need to pay the loan back monthly while the subdivision is happening?

Not necessarily. Many development loans offer “capitalised interest,” which means you don’t have to make monthly repayments while the work is being done. The interest is simply added to the total loan balance and paid back in full once the new lots are sold and settled. This is a huge help for your cash flow, as it keeps your money free for the actual development costs.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Property Development Loans NZ: Your 2026 Guide to Funding Your Next Project

What if the success of your next build depended less on your bank balance and more on the way you pitch your story to a lender? If you’ve been trying to secure property development loans NZ wide lately, you’ve likely noticed that the big banks aren’t making things easy. With bank stress tests still sitting around 8.5% and pre-sale requirements feeling more like a mountain than a hurdle, it’s easy to feel like your project is stuck in the mud before the first shovel even hits the ground.

We know how draining it is to have a viable site ready to go, only to be held back by rigid lending criteria that doesn’t account for your track record. You deserve a financial partner who sees the potential in your plans rather than just a list of risks. This guide is here to give you a clear path forward, showing you how to secure the right development finance by looking at both mainstream banks and more flexible second-tier options that actually want to help you build.

We will walk through the specific documents you need to prepare to impress any lender and explain the key differences between bank and non-bank funding. By the end, you’ll know exactly how to navigate the 2026 market and which doors to knock on to get your project moving.

Key Takeaways

  • Understand how property development loans NZ work through staged payments to keep your build costs under control.
  • Compare the lower rates of big banks with the flexibility of second-tier lenders to see which one fits your project best.
  • Find out what lenders are really looking for, from your own track record to having a solid equity position.
  • Get a clear roadmap for organising your feasibility study so you can prove your project is a winner.
  • Discover how having a seasoned expert on your side can help translate your project into a plan that lenders love.

What Exactly Are Property Development Loans and How Do They Work?

Think of a property development loan as a specialised toolkit designed for one specific job: getting your project from a set of blueprints to a finished set of keys. These are specialised funds used for building new dwellings or tackling major renovations that go far beyond a simple kitchen refresh. Essentially, a property development loan is a short-term, interest-only facility designed specifically for the construction phase of a project. Whether you’re a first-timer building a duplex in your backyard or a seasoned pro doing a small townhouse block, these tools are built to handle the unique rhythm of a construction site.

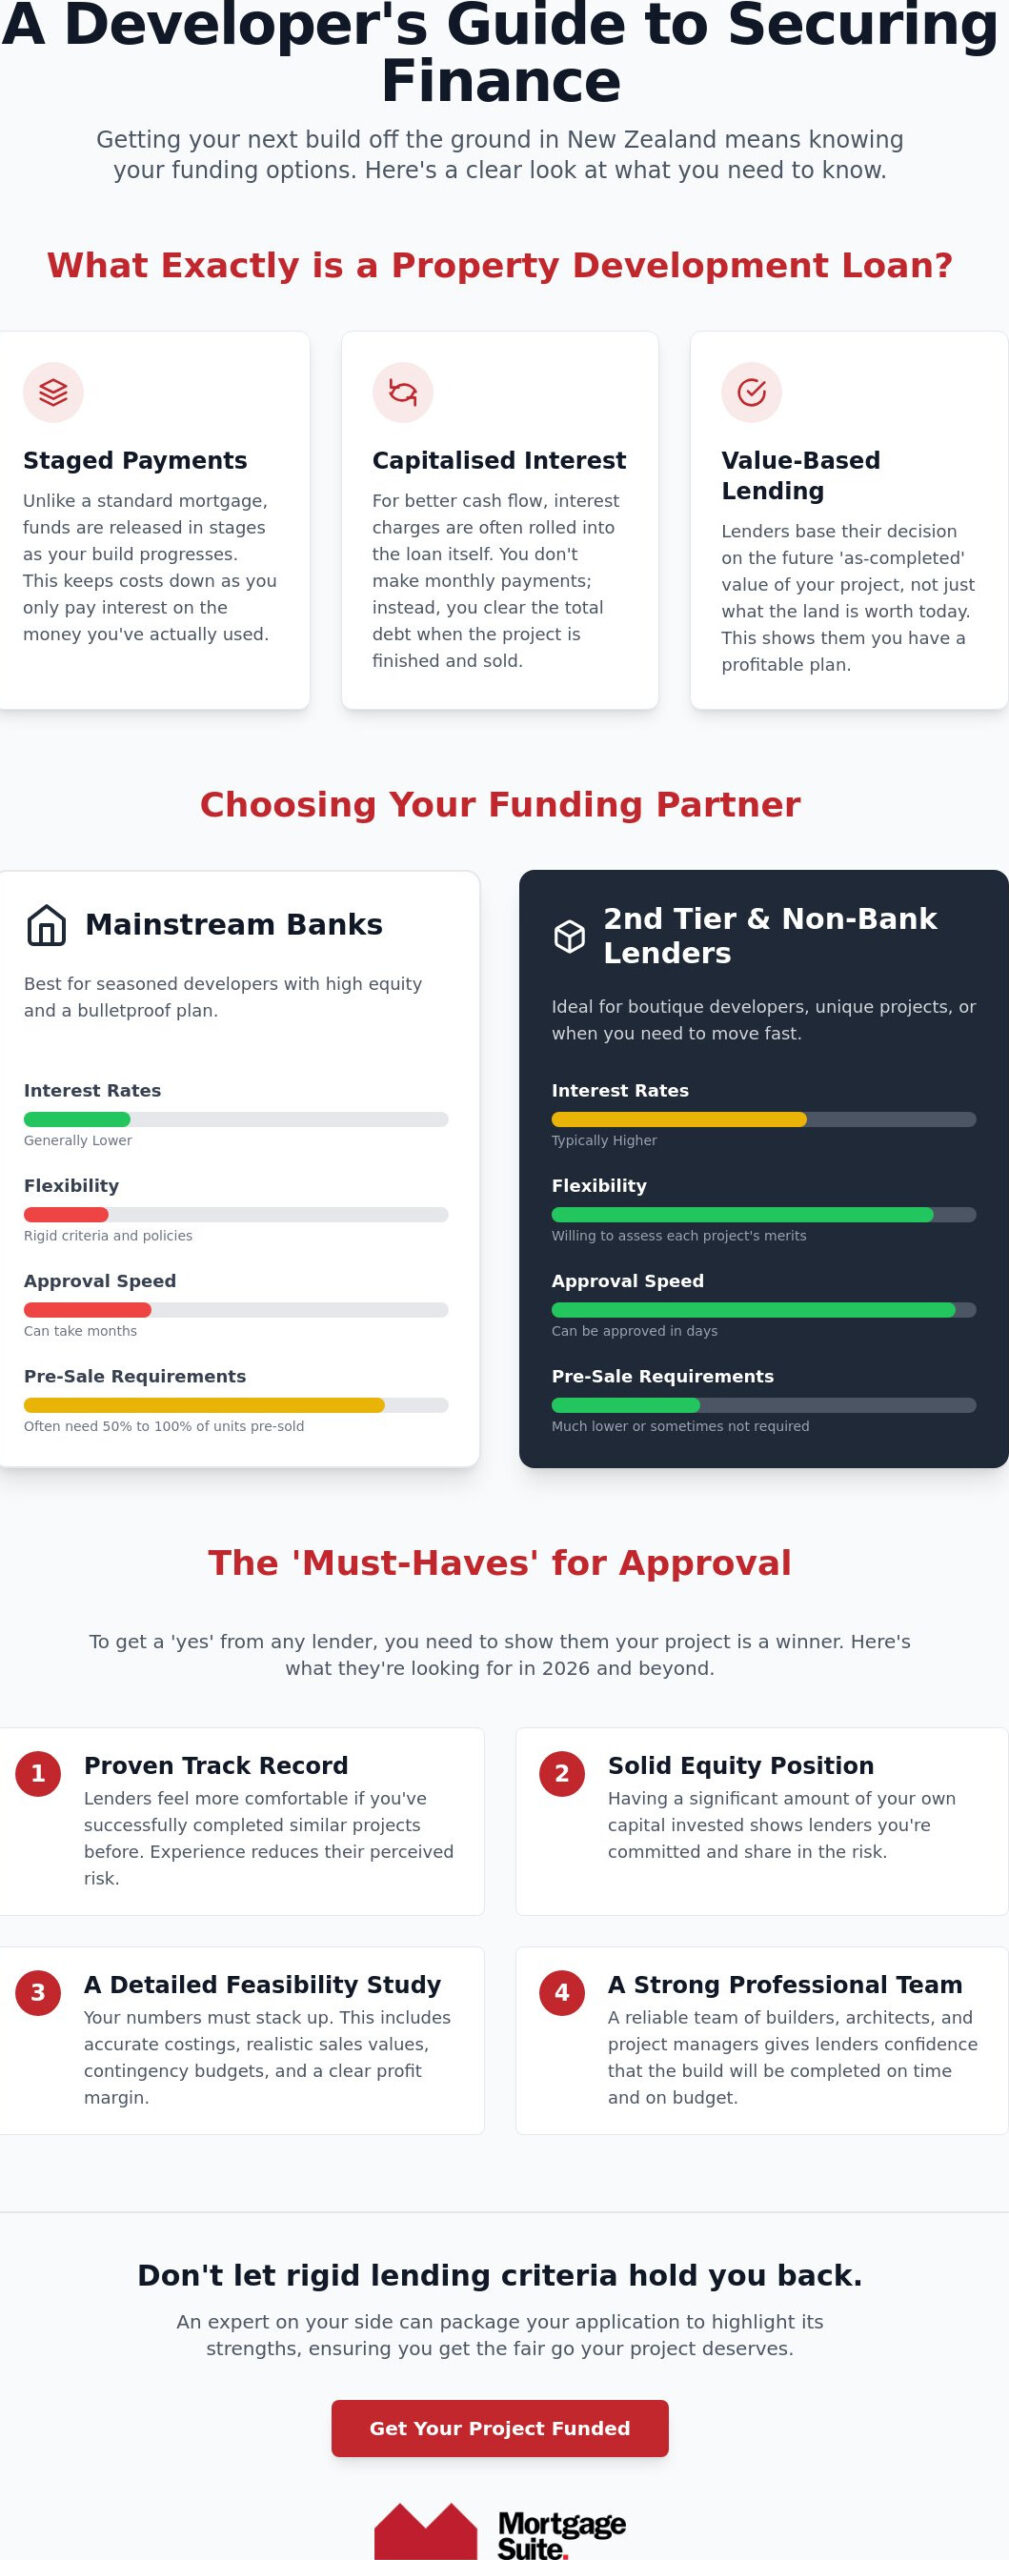
Unlike a standard home loan where you get the money upfront to buy an existing house, these loans are usually drawn down in stages, often called progress payments. This means you only pay interest on the money you’ve actually used at each point of the build, which helps keep your costs down while the foundations are being poured. To make this work, the lender doesn’t just look at what your patch of dirt is worth today. They base their lending on the “as-completed” value, which is what the finished project will likely sell for in the current market. Understanding the wider real estate development process is vital here, as it helps you see why lenders are so focused on your exit strategy and the final valuation before they’ll ever release a cent.

The Difference Between a Mortgage and Development Finance

A standard mortgage is all about you: your salary, your spending habits, and your ability to make monthly payments. Property development loans NZ lenders offer are different because they focus almost entirely on project feasibility. They want to know if the numbers actually stack up and if the project makes sense in the current climate. One of the best parts for your cash flow is a feature called capitalised interest. In plain English, this means the bank lets the interest bill grow alongside the building, and you clear the debt in one go at the finish line. You don’t have to worry about finding the cash for monthly interest payments while you’re still waiting for the roof to go on.

Why a “Fair Go” from a Bank Can Be Hard to Get

Banks are naturally cautious. They see a new build as a bundle of risks, from rising material costs to potential labour shortages. In 2026, with the Official Cash Rate at 2.25% and inflation sitting around 3.10%, banks have tightened their belts significantly. Even if your project is solid, you might find them asking for a high number of pre-sales or testing your ability to pay at rates as high as 9%. Understanding how mortgage rates NZ are structured in 2026 can help you anticipate exactly how lenders will stress-test your application and what benchmarks you need to meet. This is where having a professional broker becomes your secret weapon. We know how to package your application so it speaks the bank’s language, highlighting the strengths they might otherwise miss. We ensure you aren’t just another number in a spreadsheet but a developer with a plan that deserves a fair go.

Mainstream Banks vs. 2nd Tier Lenders: Choosing Your Funding Partner

Deciding who will fund your project is one of the biggest calls you’ll make. In the world of property development loans NZ, you’ve essentially got two paths: the big mainstream banks or the flexible non-bank lenders. While the big banks often have the flashiest offices and the lowest interest rates, they also come with the longest lists of demands. If you’re a boutique developer working on a smaller project, you might find that the “big four” aren’t actually the best fit for your needs. Most bank products are built for massive multi-million dollar schemes, leaving the smaller, high-quality projects feeling a bit left out in the cold.

The speed of approval is often the dealbreaker. Banks can take months to process a complex application, often getting bogged down in committee meetings and endless requests for more data. In contrast, a 2nd tier lender can often give you a green light in just a few days. This speed is crucial when you’re trying to secure a prime site in a competitive market before someone else snaps it up. When timing is everything and you need to move on a site before your existing property is sold, bridging finance NZ can be a powerful tool to bridge that gap and keep your development pipeline moving. This rapid pace of construction actually aligns with the goals of the NZ housing and urban development work programme, which aims to get more quality homes built faster across our communities to meet growing demand.

When to Stick with the Big Banks

Mainstream banks are perfect for developers who have plenty of runs on the board. If you’ve got high equity, a spotless credit history, and you’ve already secured pre-sales for 50% to 100% of your units, the bank’s lower interest rates make a lot of sense. You’ll pay less for your money, but you’ll pay for it in “red tape” and administrative hurdles. They’ll want to see every tiny detail of your professional team and your business before they say yes. It’s a low-cost option, but only if you’ve got the time and the patience to jump through every single hoop they hold up.

The Advantages of Non-Bank (2nd Tier) Funding

For many, especially those on their first or second project, a 2nd tier lender New Zealand offers a much smoother ride. They are far more flexible when it comes to pre-sales. In some cases, they might not require any at all. This allows you to start building sooner and potentially sell your units for a better price once they are finished and people can actually walk through them. While the interest rates are higher, usually 2-6% above bank rates, the trade-off is higher LVRs and interest-only periods that protect your cash flow. Many developers use this as a stepping stone, finishing the build with a non-bank lender and then refinancing to a cheaper bank loan once the project is finished. If you’re feeling stuck between these two worlds, chatting with an expert can help you see which path actually leads to a finished build.

The ‘Must-Haves’ for Approval: What NZ Lenders Are Looking For in 2026

When you apply for property development loans NZ lenders aren’t just looking at a patch of dirt or a set of drawings. They’re looking at you. Think of it like a job interview where the stakes are hundreds of thousands, or even millions, of dollars. Lenders fund the people behind the project as much as the project itself. They want to know that when things get tough, you’ve got the grit and the team to see the build through to the end. This means your personal track record and your financial “skin in the game” are the very first things they’ll check.

A clean credit history is non-negotiable for the big banks, and even second-tier lenders will look closely at any past hiccups. Beyond your credit, your equity position needs to be solid. Most lenders expect you to contribute at least 20% to 35% of the project’s total cost. They want to see that you’re just as committed to the success of the build as they are. Pre-sales remain the biggest hurdle for many developers in 2026. While some flexible lenders might let you start without them, mainstream banks often demand that 50% to 70% of the units are sold before they’ll release the first cent of funding. Managing this requirement often means working closely with a real estate agent early on to prove there’s genuine demand for what you’re building.

Organising Your Development Team

Lenders often care more about your builder than your architect. A beautiful design is great, but a builder with a reputation for finishing on time and within budget is what keeps a bank manager calm. You’ll also need a Quantity Surveyor (QS) on your side. The QS acts as the bank’s eyes and ears, verifying that the costs you’ve listed are realistic and that the work has actually been done before a progress payment is made. If this is your first project, don’t be afraid to bring in a mentor or a project manager with runs on the board. Citing resources like the Property Council New Zealand can help you stay up to date with industry standards and show lenders you’re serious about following best practices.

Financial Ratios You Need to Know

You’ll hear a lot of talk about LTC (Loan-to-Cost) and LVR (Loan-to-Value). LTC is simply how much the bank will lend against the total cost of the build, while LVR is the percentage they’ll lend against the final value of the completed project. Gross Realisation Value (GRV) is the total expected sales price of all units including GST. Lenders use this figure to work out their overall risk. It’s also vital to include a contingency fund in your budget. We always recommend planning for a 10-15% cost blowout. Having this buffer built-in doesn’t just protect you from surprises; it shows the lender you’re a professional who understands that construction rarely goes perfectly to plan.

Property Development Loans NZ: Your 2026 Guide to Funding Your Next Project

Your Roadmap to Funding: How to Organise Your Application

Getting your paperwork in order for property development loans NZ can feel like a project in itself. If you’ve ever felt overwhelmed by the sheer volume of documents requested, you aren’t alone. The secret is to stop thinking of it as a loan application and start viewing it as a business proposal. Lenders want to see that you’ve thought through every possible scenario, from the first digger on site to the final sale. Following a structured roadmap ensures you don’t miss the small details that could stall your funding.

The journey usually follows these five clear steps:

  • Step 1: The Feasibility Study. This is your foundation. You need to prove the numbers actually stack up before you even think about approaching a bank.
  • Step 2: Broker Consultation. Instead of knocking on every door yourself, we scout the market to find the lender whose current “appetite” matches your specific project.
  • Step 3: The Pitch Deck. You’ll need your resource consents, builder contracts, and professional bios ready to go. This is where you sell the “story” of your project.
  • Step 4: The Funding Offer. Once a lender says yes, you’ll get an offer with “conditions precedent.” These are things like a final valuation or reaching a certain number of pre-sales.
  • Step 5: Settlement and First Draw. This is the finish line. Your legal team handles the settlement, and you get your first progress payment to start the work.

The Power of a Feasibility Study

A good feasibility study is more than just a budget. It needs to account for the GST on your sales, council levies, and the marketing costs required to find buyers. If your plan is to keep the units once they’re built, you should use residential investment property loans NZ as a baseline for your long-term exit strategy. This shows the lender you’ve considered how you’ll move from a high-interest construction loan into a more sustainable long-term mortgage once the build is complete.

Avoiding Common Application Blunders

One of the biggest mistakes we see is underestimating “soft costs.” It’s easy to remember the timber and the concrete, but it’s the interest payments, legal fees, and professional consultants that often catch people out. You also need a rock-solid exit strategy. Lenders hate uncertainty, so you must be clear about whether you intend to sell the units or hold them as rentals. If your project involves splitting a larger block of land into separate titles, understanding your options for subdivision finance NZ can help you structure the funding for each stage of the land project correctly. If you’re planning to hold completed units as part of a growing portfolio, exploring a commercial property refinance NZ strategy can help you restructure your debt and unlock equity for your next development. Finally, always be honest about your credit history. It’s much easier for us to work through a past issue if we know about it upfront rather than having the lender discover it during their final checks. If you want to make sure your application is bulletproof from day one, let’s talk about your project today.

Securing property development loans NZ isn’t just about spreadsheets; it’s about the people who represent you. At Mortgage Suite, we don’t just pass your papers across a desk and hope for the best. Our director, Krish Krishna, brings over 20 years of deep banking experience to every project we handle. Having spent two decades on the other side of the lending fence, Krish knows exactly how credit managers think. He understands what makes them nervous and, more importantly, what gives them the confidence to say “yes.” This insider knowledge is your secret weapon when you’re trying to fund a project in a fluctuating market.

We act as your translator. Often, a great project gets rejected simply because it wasn’t presented in a language the bank understands. We take your vision, your numbers, and your track record, and we package them into a professional proposal that highlights the strengths of your deal. We specialise in those “tough” deals that mainstream banks might put in the “too hard” basket. Where a big bank might see a problem with a lack of pre-sales or a unique site, we see a solution through our network of flexible 2nd tier lenders. Our commitment is to a partnership that goes beyond just signing a loan document; we’re here to see your project through to completion.

From First Home to First Development

Many of the successful developers we work with didn’t start with a multi-unit block. They started with a single property and a dream. We love helping investors transition from being passive owners to active developers. By linking your current portfolio to new funding opportunities, we can help you unlock equity you might not even realise you have. Even if you’re just starting out, we can help first home buyers in New Zealand lay the groundwork today for a future in development. It’s about building a long-term plan where your success is our priority.

Ready to Get Cracking on Your Next Project?

With the Official Cash Rate sitting at 2.25% as of May 2026 and new housing targets always on the horizon, this year is full of opportunity for those who have their finance ready to go. Don’t let a “no” from a big bank be the end of your development dreams. The value of a no-obligation chat is that it gives you a clear picture of where you stand right now and what you need to do to get where you want to be. It’s about removing the obstacles so you can focus on what you do best: building.

We’re more than just brokers; we’re your advocates and negotiators. We stay with you from the first application until the final unit is sold and the loan is cleared. If you’re ready to get your project off the ground with a team that truly cares about your results, get in touch with us today. Let’s find the right path to fund your next build together.

Build Your Future with Confidence

Securing the right funding is the foundation of any successful build. Success in this market involves more than just finding a good site; it requires a bulletproof feasibility study and a development team that lenders can trust. Whether you’re aiming for the lower rates of a mainstream bank or the speed and flexibility of a second tier lender, the key is to present your project in a way that makes sense to the credit managers holding the purse strings.

Navigating the various property development loans NZ has to offer can feel complex, but you don’t have to do it alone. With over 20 years of banking and mortgage expertise, we specialise in handling the tough, complex commercial deals that others often avoid. We take pride in being your personal advocate, using our deep industry knowledge to negotiate directly with all NZ lenders on your behalf.

If you’re ready to get your project moving, talk to Krish Krishna about your property development funding today. We’re here to provide the steady hand and seasoned advice you need to see your project through to completion. Your next project is closer than you think, and we’re ready to help you make it happen.

Frequently Asked Questions

Can I get a property development loan with no experience?

Yes, you can, but you’ll need to surround yourself with a professional team that has plenty of runs on the board. Lenders look at the experience of your builder and project manager to offset your lack of history. If your team is solid and your feasibility study is airtight, a lender is much more likely to give you a fair go on your first project.

How much deposit do I need for a development loan in NZ?

Lenders generally expect you to contribute between 25% and 40% of the total project cost. While mainstream banks typically fund 60-75% of the build, some flexible 2nd tier lenders might allow a smaller deposit if the project shows a very strong profit margin. Using existing equity in other properties is a common way to cover this requirement without needing cash.

What are the current interest rates for property development loans?

Interest rates for property development loans NZ vary depending on the lender’s risk assessment. Mainstream banks usually charge between 1% and 4% above their standard mortgage rates. For 2nd tier or private lenders, you should expect total interest costs to range from 8% to 15% given the extra flexibility and speed they provide compared to traditional banks. Understanding how mortgage rates NZ are calculated across different lender types can help you budget more accurately for your total financing costs.

Do I need pre-sales to get a development loan?

It depends on which lender you approach. Mainstream banks often demand that 50% to 70% of the units are sold before they’ll release any funding for construction. However, many non-bank lenders don’t require any pre-sales at all. This allows you to start building immediately and potentially sell the finished units for a higher price once the project is complete.

How do progress payments work during construction?

Money is released in stages as your build hits specific milestones, such as the floor slab being poured or the roof being installed. A Quantity Surveyor will visit the site to check the work is done correctly before the bank releases the next payment. This ensures the funds are only used for actual progress, keeping both you and the lender protected throughout the build.

Can I use my existing home equity for a development project?

Yes, leveraging the equity in your current home or investment portfolio is one of the most effective ways to fund a project. By using the value you’ve already built up, you can often cover the required deposit without having to find a large amount of physical cash. This makes it much easier for established homeowners to transition into property development. If you need to act quickly on a new site before selling your existing property, a bridging finance NZ solution can help you access that equity and secure your next opportunity without delay.

What happens if my construction costs go over budget?

If your costs increase, you’ll first tap into your contingency fund, which we always recommend setting at 10% to 15% of the total build cost. If you go beyond this buffer, you’ll need to either provide more of your own cash or talk to us about negotiating a loan increase. Having a professional advocate helps when presenting these cost changes to your lender.

Is it better to use a bank or a non-bank lender for my first project?

For a first project, a non-bank lender is often the better choice despite the higher interest rates. Their flexibility and willingness to fund projects without pre-sales mean you can get started faster and build your track record. Once you’ve successfully finished a few projects, you’ll find it much easier to meet the stricter criteria and lower rates offered by mainstream banks.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.