
What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

You’ve spent months searching for the right property, only to have your long-term bank turn you down at the final hurdle. It’s a frustrating, anxious experience that makes you feel like the system is working against you, especially with the strict debt-to-income rules currently in play. If you’re wondering what to do when bank declines mortgage nz, the first thing to remember is that a “no” from a mainstream lender isn’t the end of your journey. It’s often just a sign that you need a more flexible, expert approach to get the deal across the line.

We understand the sting of being rejected by a bank you’ve been loyal to for years. This guide shows you how to turn that setback into a successful purchase by using 2nd tier lenders as a strategic bridge. You’ll learn how these specialist providers work outside the rigid boxes of traditional banks and why a smart exit strategy is your ticket back to mainstream rates in a year or two. We’ll walk through the 2026 market conditions and give you a clear, professional plan to secure your loan and move into your new home with confidence.

Key Takeaways

  • A rejection from a main bank doesn’t mean your home-buying dreams are over; it’s simply a signal to switch to a more flexible 2nd tier lender.
  • Discover exactly what to do when bank declines mortgage nz by shifting the focus to your unique “borrower story” and long-term potential.
  • Learn why matching your specific financial situation to a specialist lender’s unique criteria is the secret to turning a decline into an approval.
  • Get a clear view of the temporary costs involved and how these non-bank options serve as a vital bridge to your property goals.
  • Master the exit strategy that allows you to “graduate” back to a mainstream bank within 12 to 24 months once your situation has stabilised.

What is a 2nd Tier Loan and Why is it Your Best Plan B?

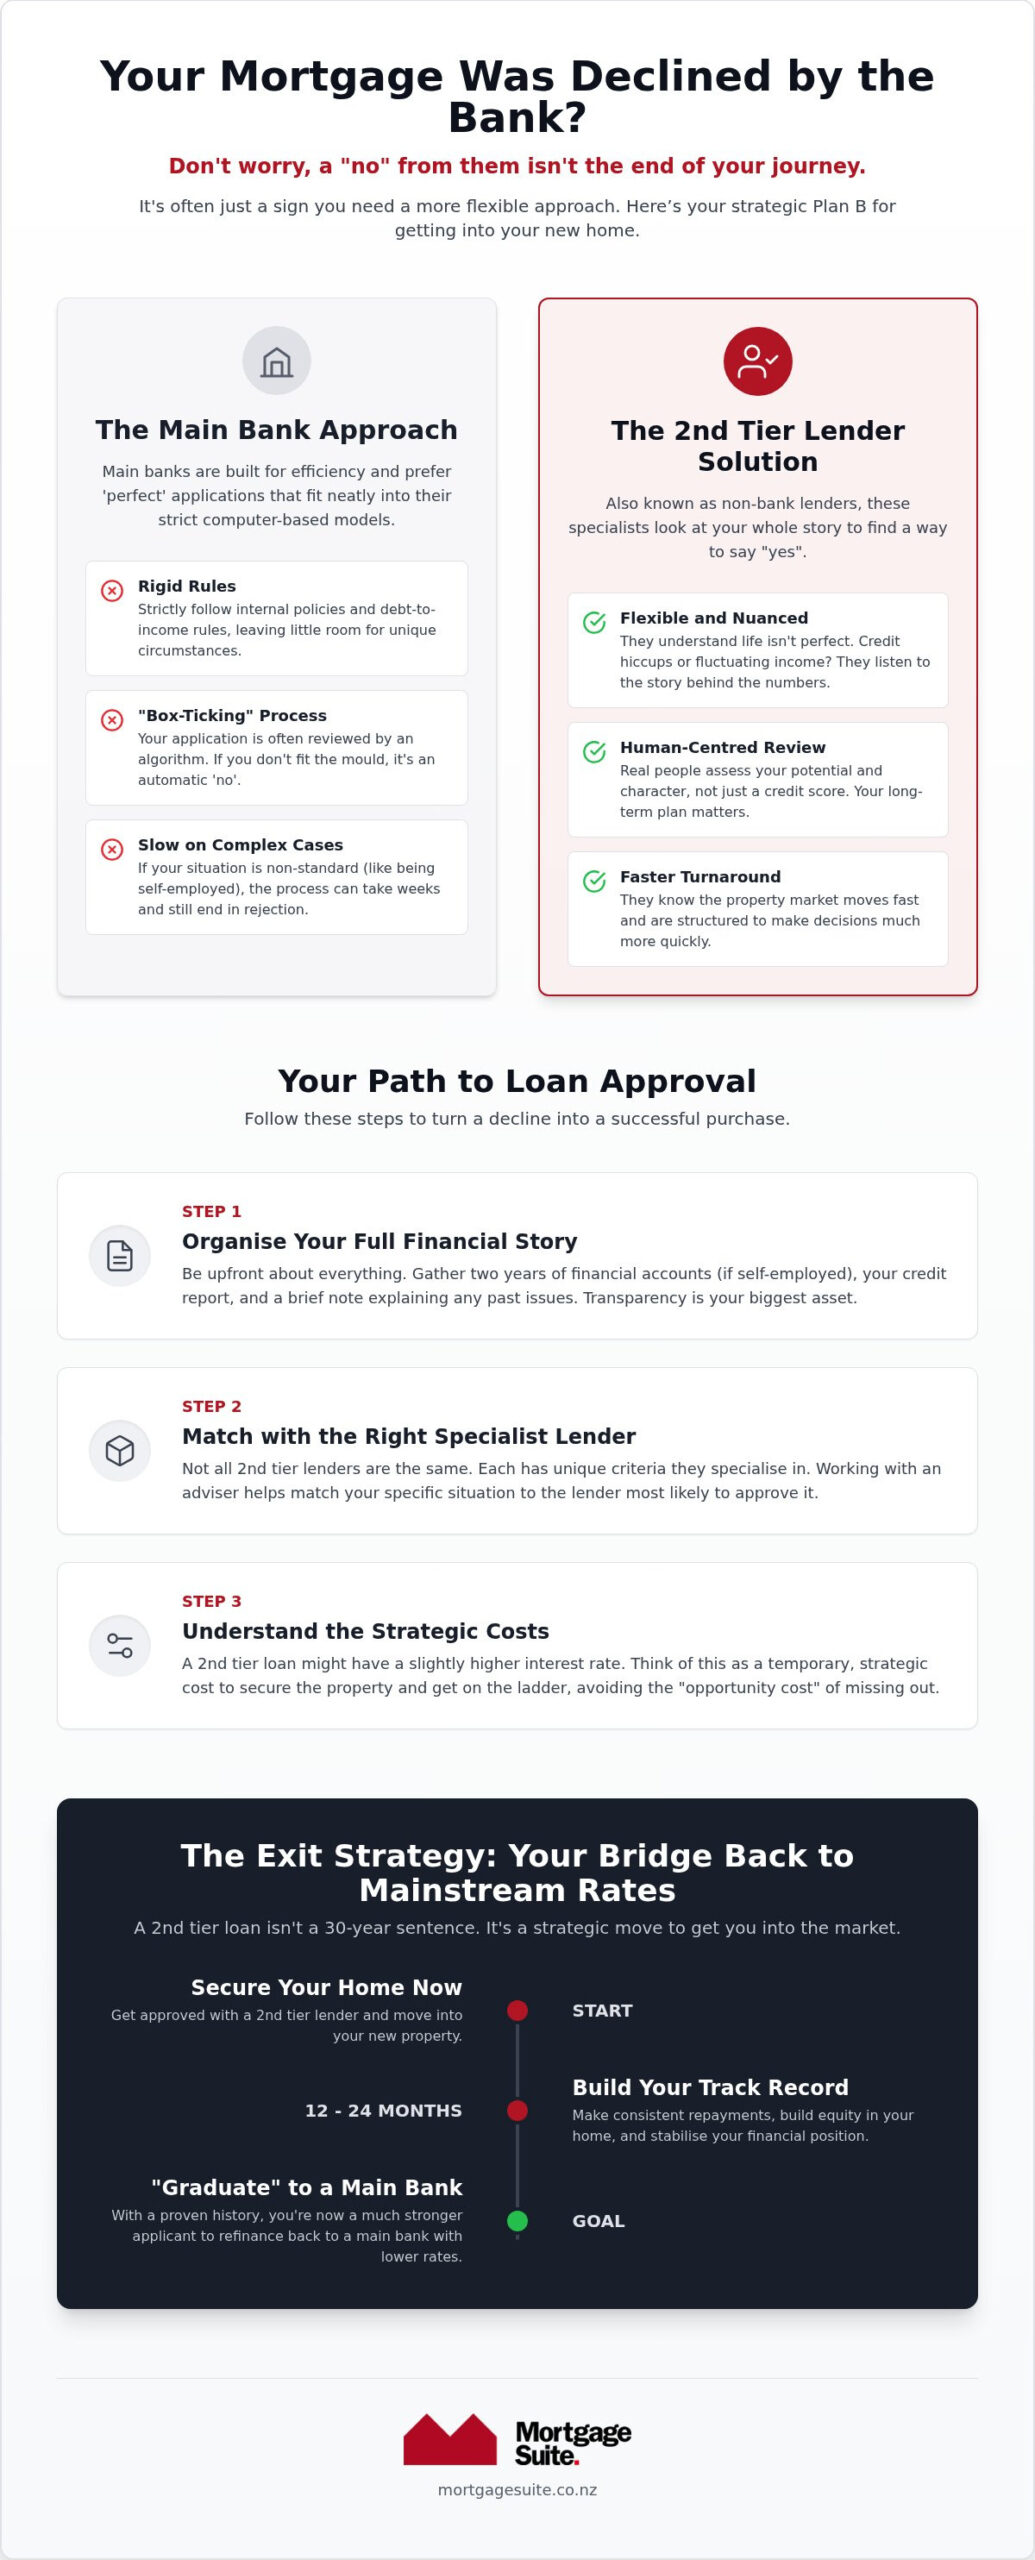
Getting a “no” from a main bank feels like a dead end, but in the New Zealand property market, it’s often just the start of a different conversation. Most people are taught that if the big four banks won’t help, nobody will. That isn’t true. A 2nd tier loan is a flexible, regulated alternative for unique financial situations. These lenders operate differently from the high-street names you see in every shopping centre. They provide a vital path forward when you’re figuring out what to do when bank declines mortgage nz.

Second-tier lenders are often called “non-bank” lenders. They don’t take deposits from the public like a traditional bank does. Instead, they raise their own capital to lend out. Because they aren’t bound by the same rigid internal rules as the main banks, they can look at your application with much more nuance. They are specialists in finding ways to say “yes” when a computer algorithm at a main bank has already said “no”.

The Difference Between Main Banks and Alternative Lenders

Main banks are designed for efficiency. They love “perfect” applications where every piece of data fits into a pre-defined box. If you’re self-employed with a fluctuating income, or if you have a slightly smaller deposit than the current 2026 regulations prefer, you might not fit that box. This is where a non-bank financial institution shines. They take the time to look at your whole story rather than just your credit score.

Speed is another major factor. While a main bank might take weeks to process a complex application, alternative lenders are often much faster. They understand that property deals move quickly and that you can’t afford to wait. The trade-off is usually a slightly higher interest rate or different fee structure, but for many Kiwis, this is a small price to pay to secure a home in a competitive market. To understand how these different options affect your long-term plans, you can explore the resources in our mortgage school.

Dispelling the Myths About Non-Bank Lending

There’s a common misconception that anything outside a main bank is risky or untrustworthy. It’s time to clear that up. These lenders are reputable, highly regulated businesses that must follow the same consumer protection laws as any other financial provider. They aren’t “loan sharks”; they are professional advocates for borrowers who need a bit more flexibility.

Think of a 2nd tier loan as a strategic stepping stone. It isn’t necessarily a thirty-year commitment. Instead, it’s a way to get into the market now, build equity, and prove your reliability. By the time you’ve held the loan for a year or two, you’ll often be in a much stronger position to “graduate” back to a main bank. Knowing what to do when bank declines mortgage nz often starts with embracing this tactical “Plan B” to keep your home-ownership goals on track.

How to Prepare Your 2nd Tier Loan Application

Preparing for a non-bank application is quite different from a standard bank meeting. It’s about building a comprehensive case for yourself. When you’re stuck on what to do when bank declines mortgage nz, your first move should be gathering every detail of your financial life, even the bits you’re worried about. Being upfront is your greatest asset in this process. If there’s a skeleton in the closet, it’s better to bring it out now rather than let a lender find it later. 2nd tier lenders invest in people and their potential, not just a credit score, so they value transparency and a clear plan over a perfect history.

The Essential Paperwork You Will Need to Organise

You’ll need to look beyond the standard documents a main bank asks for. If you’re self-employed, gather your full financial accounts and tax returns for the last two years. Lenders want to see the real-world consistency of your earnings, even if they don’t fit a standard salary pattern. If you’ve had a credit hiccup in the past, get a copy of your credit report and prepare a brief, honest note explaining the circumstances. These lenders are professional, regulated, and often belong to independent dispute resolution bodies, which ensures you’re treated with fairness throughout the application. You should also have the specific details of the property you’re eyeing ready, as the type of dwelling often impacts the lender’s risk assessment.

Telling Your Story to the Lender

This is where you move beyond the columns of a spreadsheet. A main bank might see a dip in your income from eighteen months ago and decline you without a second thought. A 2nd tier lender will listen if you explain that the dip was a one-off event, such as a temporary illness or a strategic business pivot. You need to show them that your plan for future financial stability is robust and well-thought-out. This is exactly why having a veteran negotiator on your side is a game-changer. We know how to “translate” your unique life situation into the specific language that non-bank lenders understand. If you’re ready to start building your case and want to work with a partner who knows the system, you can learn more about us and how we advocate for our clients. Knowing what to do when bank declines mortgage nz is all about presenting your future potential as clearly as your financial past.

Choosing the Right Lender for Your Specific Situation

Every non-bank lender in New Zealand has its own “personality” and set of rules. Unlike the main banks, which all tend to follow very similar guidelines, 2nd tier lenders often specialise in specific types of borrowers. One might have a high appetite for helping people buy existing family homes with smaller deposits, while another might focus almost entirely on business owners with complex tax structures. Finding what to do when bank declines mortgage nz often comes down to knowing which of these hundreds of options is the right fit for your specific hurdle.

The challenge for most Kiwis is that these lenders don’t usually advertise on television or have branches on the high street. They work primarily through specialist brokers who understand their unique criteria. Matching your situation to the right lender is a bit like solving a puzzle. It requires a deep understanding of how each provider views risk and what kind of “borrower story” they find most compelling. This is where Mortgage Suite Ltd and our 20-plus years of expertise become your biggest advantage, as we know exactly which door to knock on to get your deal across the line.

Lenders Who Favour the Self-Employed

If you run your own business, you’ve likely discovered that main banks struggle with income that isn’t a steady, fortnightly salary. Many 2nd tier lenders were built specifically to solve this problem. They offer what we call “low-doc” options. In plain English, this simply means they use alternative ways to verify your income, such as looking at your business bank statements or a simple letter from your accountant, rather than demanding years of perfect tax returns. They focus on your current ability to manage repayments and the overall health of your business, giving you the credit you deserve for your hard work.

Options for Credit Hiccups or Smaller Deposits

A past financial setback or a deposit that doesn’t quite hit the 20 per cent mark for an existing home can lead to an instant decline from a main bank. However, some lenders specialise in “recovery” loans. They look at your “risk grade”-a professional assessment of your current reliability-and offer a path forward even if your history isn’t spotless. Unlike some competitors who suggest that new builds are the only way to buy with a small deposit, we find lenders who are happy to support you in buying an existing property. These loans act as a vital bridge, allowing you to secure your home now while you work on improving your financial position for the future.

Knowing what to do when bank declines mortgage nz is about looking beyond the surface and finding a partner who sees the value in your specific situation. With the right lender, that initial rejection becomes nothing more than a temporary detour on your way to home ownership.
What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

Understanding the Costs: Rates, Fees, and the “Opportunity Cost”

When you’re trying to figure out what to do when bank declines mortgage nz, the numbers on the page can feel a bit heavy. It’s true that 2nd tier lenders charge higher interest rates than the main banks. This is because they’re taking on more risk by looking at applications that don’t fit the standard criteria. However, it’s vital to view these costs as a tactical investment rather than a permanent burden. You can use our Mortgage Calculator to see how these different rates look in reality and how they might fit into your monthly budget.

Interest Rates vs. The Cost of Missing Out

The real question isn’t just “how much is the interest?” but “how much will it cost me to wait?”. With inflation currently sitting at 3 per cent and the property market constantly shifting, staying on the sidelines can be expensive. If house prices rise while you’re spending another year or two saving for a larger deposit, you might find yourself priced out of the very suburb you want to live in. Most of our clients don’t stay on a 2nd tier rate forever. We view these loans as a 12-to-24-month bridge. When you calculate the “real” cost over this short period, the extra interest is often far less than the potential growth in your home’s value during that same time.

Think of it as a temporary premium for speed and flexibility. By getting into the market now, you start building equity immediately. You’re no longer paying rent to someone else, and you’re finally on the property ladder. This strategic move allows you to “graduate” back to a main bank once your financial situation has stabilised or you’ve proven your repayment history to the wider market.

Upfront Fees and Budgeting

Beyond the interest rate, you’ll need to budget for specific upfront costs. These typically include establishment or application fees, which cover the intensive manual assessment required for alternative lending. You’ll also need to factor in valuation reports from approved professionals and legal costs that might be slightly higher due to the complexity of the contracts. It’s also worth checking the early exit terms. Since the goal is to move back to a main bank as soon as possible, you want to ensure your loan structure allows for that transition without heavy penalties. If you want a clear, honest breakdown of how these costs apply to your situation, get in touch with us today for a professional assessment. We’re here to ensure there are no surprises on your journey to home ownership.

The Exit Strategy: How to Move Back to a Main Bank

Securing a 2nd tier loan is a massive win, but it’s rarely the final stop on your home ownership journey. We always encourage our clients to view this as a temporary bridge rather than a thirty-year commitment. The goal is simple: use this period to stabilise your finances and build a solid track record. When you’re considering what to do when bank declines mortgage nz, the long-term plan is just as important as the immediate approval. We work with you to set a clear 12-to-24-month target to “graduate” back to a main bank, where you can access lower interest rates and standard terms.

Cleaning Up Your Financial Profile

Your time with a 2nd tier lender is your chance to prove to the main banks that you’re a reliable borrower. The most critical factor here is maintaining a perfect repayment history. Every single payment on your new loan must be on time, without exception. This shows future lenders that your previous credit hiccup is firmly in the past. At the same time, focus on reducing other liabilities. Paying down credit cards or clearing car finance can significantly improve your debt-to-income ratio, which is a key metric for banks in 2026. If you’re a first-time owner, our Home Loans for First Home Buyers Guide offers deeper insights into how these factors influence bank decisions.

Don’t forget that as property values potentially grow, your equity increases. A higher equity position naturally lowers the bank’s risk, making it much easier to qualify for those competitive rates you missed out on initially. We’ll keep an eye on the market with you to identify the best moment to make your move.

Working with Your Broker on the Move

You shouldn’t wait until your fixed term is nearly over to start thinking about the switch. We usually begin the conversation about six months before your target graduation date. This gives us enough time to review your polished profile and identify any final adjustments needed. Re-applying with a year of perfect mortgage history and a cleaner debt profile allows you to walk into a main bank with genuine confidence. We don’t just secure your first loan and disappear; we stay with you for the whole journey. Our reputation is built on these long-term partnerships, helping Kiwis navigate what to do when bank declines mortgage nz and eventually seeing them successfully refinance into the mainstream banking system.

Take the Next Step Toward Your New Home

A bank decline is often just a nudge toward a more flexible path. By choosing a 2nd tier loan as a strategic bridge, you can secure your property now and build a solid foundation for a future return to a main bank. Knowing what to do when bank declines mortgage nz means looking past the initial rejection and focusing on your long-term potential. We’ve seen how a clear exit strategy and professional advocacy can transform an anxious situation into a successful purchase.

With over 20 years of expert banking and brokerage experience, we specialise in finding “outside the box” lending solutions that the big banks often ignore. You can read our client reviews to see how we’ve helped other Kiwis succeed where they once felt stuck. If you’re ready to move forward, book a friendly chat with Mortgage Suite to find your path forward. Your home ownership goals are still within reach, and we’re here to help you navigate the system with confidence.

Frequently Asked Questions

Is it harder to get a 2nd tier loan than a main bank loan?

Getting a 2nd tier loan is often more straightforward than a main bank loan because these lenders have more flexible criteria. While main banks rely on rigid “yes” or “no” computer models, alternative lenders take a manual approach to understand your whole financial story. They are specialists in finding ways to approve applications that don’t fit the standard box, making them a reliable path when you’re stuck on what to do when bank declines mortgage nz.

Can I still get a home loan if I have a bad credit history?

You can absolutely secure a home loan with a less-than-perfect credit history by working with a specialist non-bank lender. These providers are designed to help borrowers who have had past financial setbacks. Instead of a flat rejection, they look at your current stability and your plan for the future. They assess the “risk grade” of your application and offer a loan structure that reflects your specific recovery journey, helping you move forward with confidence.

What are the typical interest rates for non-bank lenders in 2026?

In the 2026 market, interest rates for non-bank lenders vary based on your specific situation. For “near-prime” borrowers with good credit, rates are typically 1 to 2 per cent higher than mainstream bank rates. If your application is more complex or involves significant credit issues, specialist rates can range between 10 per cent and 14.5 per cent. These higher rates reflect the extra risk the lender takes on to help you get into the property market.

How long does the 2nd tier loan application process take?

The application process with a 2nd tier lender is often significantly faster than a main bank, sometimes taking just a few days for an initial approval. Because these lenders aren’t bogged down by the same massive institutional layers, they can make decisions quickly once they have your full paperwork. This speed is a huge advantage when you’re competing for a property and need a clear answer on what to do when bank declines mortgage nz.

Do I really need a mortgage broker to access these lenders?

While you can technically approach some lenders yourself, most 2nd tier providers in New Zealand deal exclusively through professional mortgage brokers. A broker acts as your advocate, translating your “borrower story” into the specific format these lenders require. We have access to hundreds of different criteria sets and know exactly which specialist provider is most likely to say yes to your unique situation, saving you time and protecting your credit score.

What happens if I want to pay off my 2nd tier loan earlier than planned?

You can pay off your 2nd tier loan early, but you should always check the specific terms for early exit fees. Since these loans are often intended as a temporary bridge, many are structured with flexibility in mind. However, some lenders include a minimum term or a set fee to cover their setup costs. We ensure you understand these details upfront so your plan to move back to a bank remains cost-effective and clear.

Will a 2nd tier loan affect my ability to get a bank loan later?

Holding a 2nd tier loan actually strengthens your future bank application, provided you maintain a perfect repayment history. Successfully managing a non-bank loan proves to mainstream lenders that you are a reliable, low-risk borrower. This track record is exactly what banks look for when they consider taking you back. It serves as a professional “graduation” certificate that demonstrates your financial stability has been fully restored after your initial hurdle.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt to Income Ratio NZ: What the 2026 DTI Rules Mean for Your Mortgage

What if the size of your deposit isn’t actually the biggest hurdle to your next home loan anymore? It often feels like every time you get close to the finish line, the Reserve Bank shifts the goalposts; you’ve saved the deposit and found the house, only to worry that new regulations might stop you in your tracks. Understanding the debt to income ratio nz rules is now just as vital as having a solid credit score, especially as we navigate the 2026 property market.

We know how stressful it is to feel like your financial future is being decided by a complex spreadsheet. That’s why we’re here to clear up the confusion. You’ll learn exactly how these DTI limits affect your borrowing power and how to navigate them to secure your dream home or next investment. We’ll break down the specific maths behind the 6x and 7x thresholds, identify who qualifies for a “speed limit” exemption, and look at the path forward if your current bank says no. Whether you’re a first home buyer or a seasoned investor, there is always a way through the red tape when you have the right plan and a steady hand to guide you.

Key Takeaways

  • Get a clear grip on how the debt to income ratio nz measures what you owe against what you earn, and why it’s now a top priority for lenders.
  • Discover the specific 2026 borrowing limits for owner-occupiers and investors, so you know exactly where you stand before you start house hunting.
  • Learn about the “speed limit” and new build exemptions that could help you secure a loan even if you don’t fit the standard RBNZ box.
  • Find out how simple moves, like closing unused credit cards, can significantly improve your profile and increase your chances of a successful application.
  • Explore why a rejection from a big bank doesn’t have to be the end of the road, especially when looking at 2nd tier options that offer more flexibility.

What is the Debt to Income (DTI) ratio in NZ?

Think of the debt to income ratio nz as a financial health check that lenders use to see if you’re biting off more than you can chew. While we used to focus almost entirely on the size of your deposit, the rules have changed. Now, the banks are looking just as closely at the relationship between what you earn and what you owe. It isn’t just about your mortgage either. Lenders bundle in every bit of debt you have, from that credit card you keep for emergencies to the car loan you took out last year. If you’re curious about the global concept, you can read up on what the debt-to-income ratio is, but in the local context, it’s a strict guardrail designed to keep you and the economy safe.

In 2026, this ratio has become just as vital as your deposit size when you’re applying for a mortgage. It serves as a reality check for both you and the bank, making sure that your lifestyle isn’t entirely consumed by debt repayments. Living with a high ratio can be incredibly stressful, as it leaves very little room for error if your circumstances change. By understanding this number early on, you can take control of your financial story rather than letting the bank’s spreadsheet dictate your future. It’s about ensuring that you don’t end up taking on way too much debt, which can quickly turn the excitement of a new home into a constant worry about making ends meet.

The simple maths behind the ratio

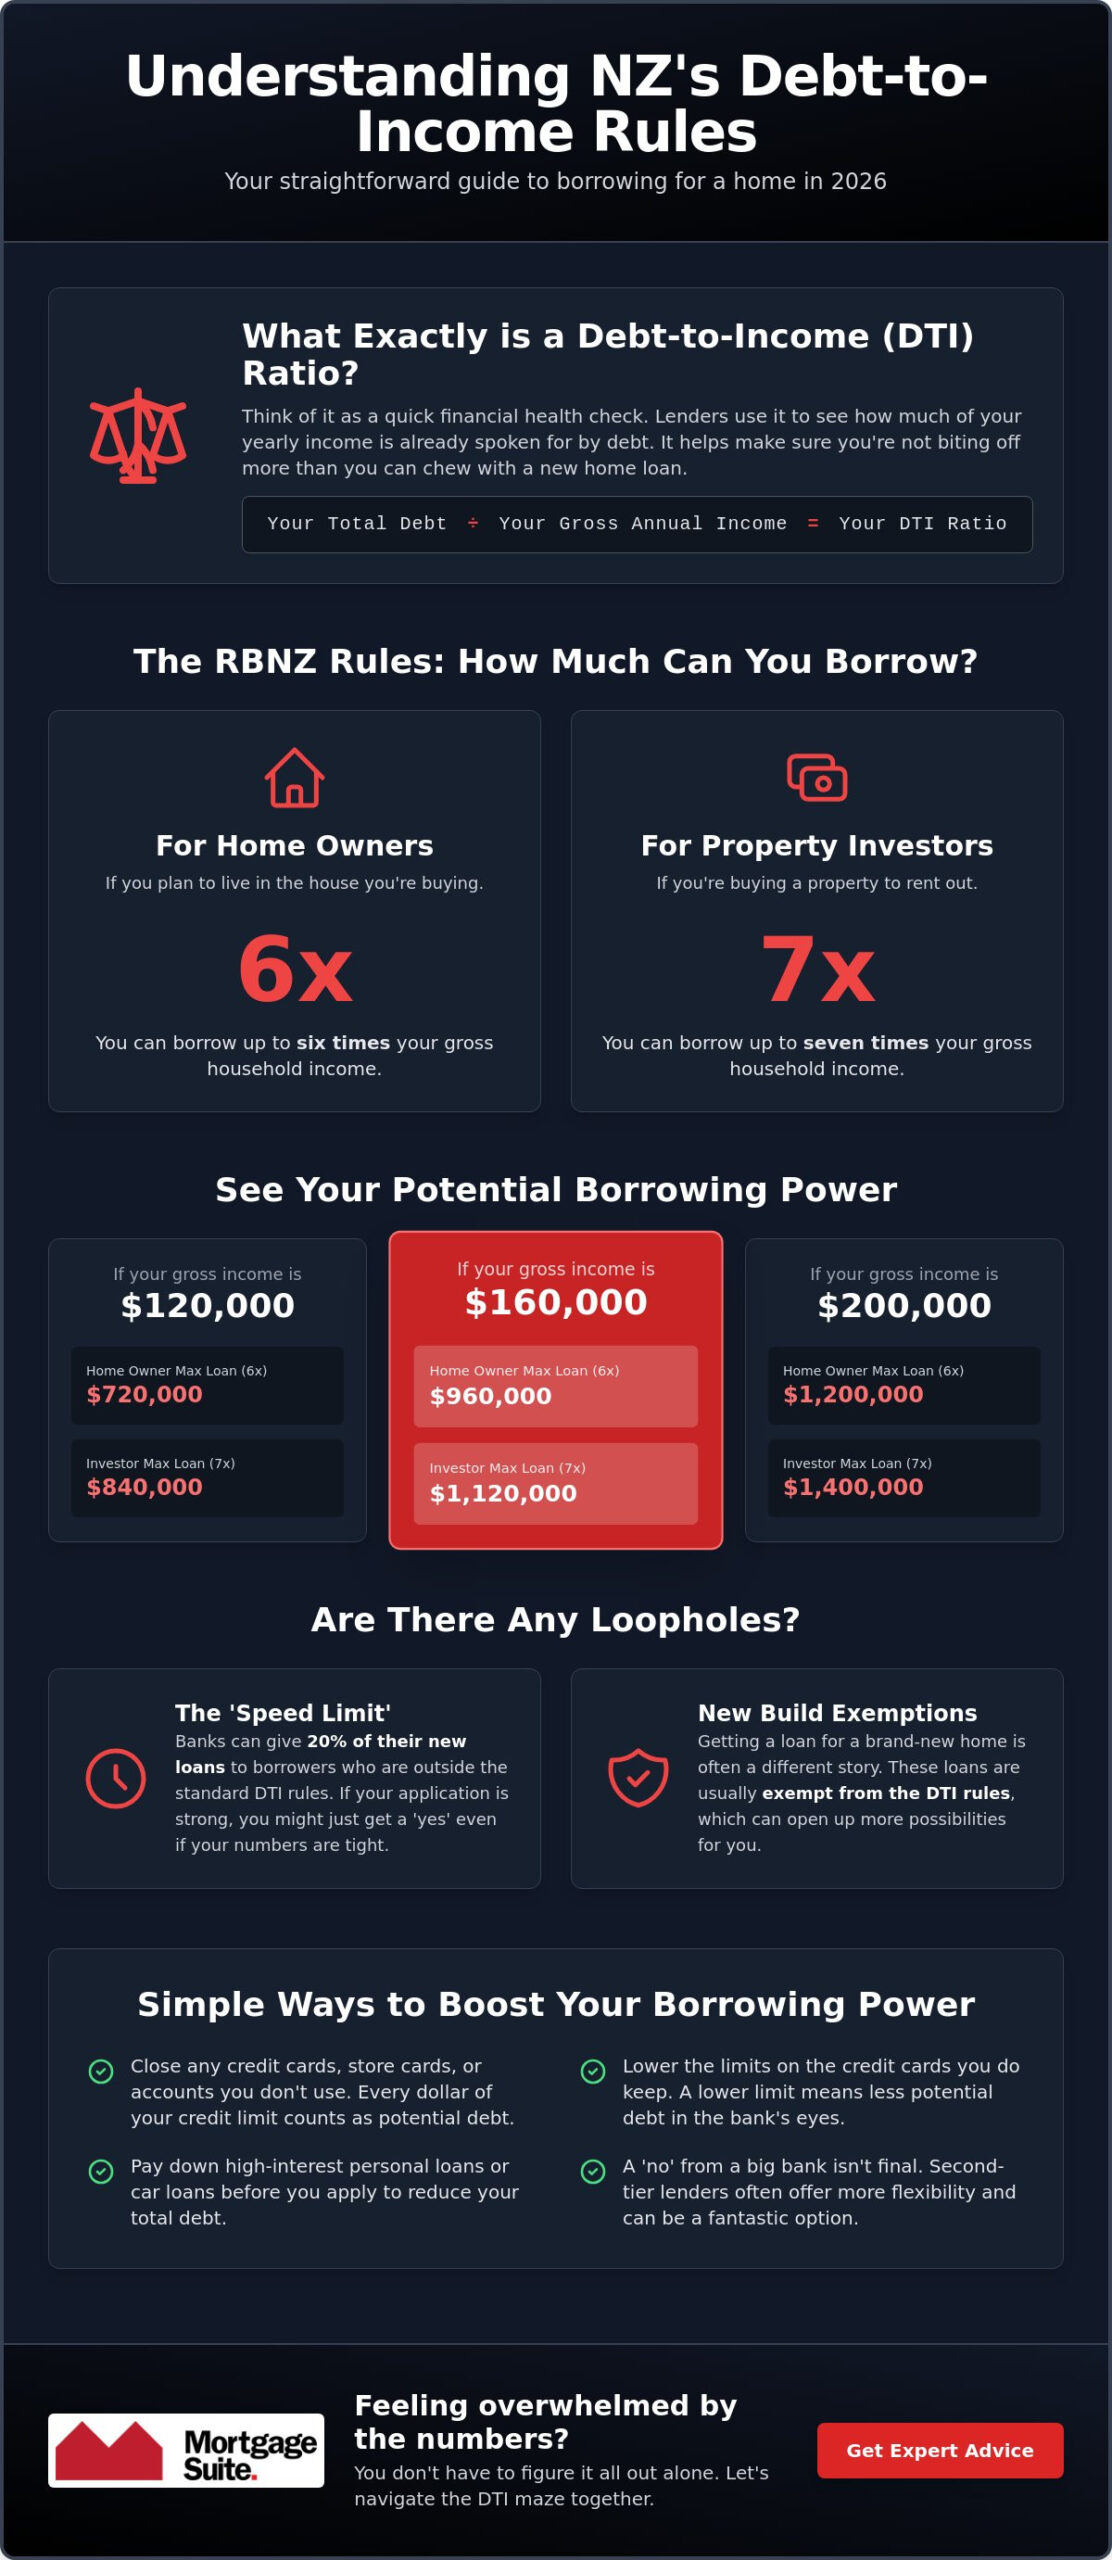
Calculating this number is actually quite straightforward. To find your ratio, divide your total debt by your annual income before tax. For a practical example, let’s say your household brings in $100,000 a year before the taxman takes his share. If you’re looking to take on a $600,000 loan, your DTI would be 6. Banks prefer using your “gross” income, which is just the amount you earn before tax, because it provides a consistent starting point. It gives them a clear, standardised view of your total earning power before other expenses come into play.

Why the Reserve Bank brought these rules in

The Reserve Bank of New Zealand (RBNZ) introduced these limits to keep the housing market stable and prevent people from getting into too much hot water. By capping how much you can borrow relative to your income, they’re trying to stop the market from overheating and prevent people from getting in over their heads with repayments. These rules work alongside the existing Loan-to-Value (LVR) settings, which look at how much deposit you have. While LVR looks at your ownership stake, the DTI rules focus on your ability to actually live your life while paying back the debt. The ultimate goal is to make sure that even if interest rates wiggle or life throws you a surprise, you still have enough cash left over to keep the lights on and the fridge full. It’s about building a bit of a buffer so that a small change in your circumstances doesn’t become a massive financial headache. Understanding how the Reserve Bank sets its benchmark rate is equally important — our guide on OCR meaning and how the Official Cash Rate shapes your mortgage in 2026 explains exactly how these decisions flow through to your repayments.

The RBNZ rules: How much can you borrow in 2026?

The Reserve Bank doesn’t apply a one-size-fits-all approach to lending. Instead, they’ve set different benchmarks based on how you intend to use the property. If you’re looking for a place to call home, the standard debt to income ratio nz limit is 6. This means that for every dollar you earn before tax, the bank generally won’t let you borrow more than six dollars in total debt. It sounds strict, but it’s designed to ensure you aren’t stretched too thin when life happens.

For those looking to grow a portfolio, the rules are slightly more flexible. Investors generally have a DTI limit of 7. This extra wiggle room exists because rental income helps service the loan, providing a bit more security for the lender. However, even these limits aren’t set in stone. Banks have what we call “speed limits.” The Reserve Bank allows banks to allocate 20% of their new lending to borrowers who sit outside these standard ratios. If your case is strong, there’s still a chance to secure a “yes” even if the numbers are a bit tight.

Owner-occupier vs Investor limits

The gap between a DTI of 6 and 7 might seem small, but it makes a massive difference to your buying power. If you’re a first home buyer with a small deposit, you’ll likely need to stick closely to that 6x limit unless you qualify for a specific exemption. We’ve put together a quick guide to show how these limits translate into actual loan amounts based on your household income.

Gross Annual Income Max Loan (Owner-Occupier, DTI 6) Max Loan (Investor, DTI 7)
$120,000 $720,000 $840,000
$160,000 $960,000 $1,120,000
$200,000 $1,200,000 $1,400,000

What counts as “Debt” in the eyes of a lender?

This is where many people get caught out. When a bank calculates your ratio, they don’t just look at the mortgage you’re asking for. They include everything. Your student loan, that car finance from last year, and even personal loans are added to the pile. One of the biggest traps is credit card limits. Even if you have a zero balance, the bank counts the entire limit as potential debt because you could spend it tomorrow. “Buy Now, Pay Later” commitments are also under the microscope now. These small weekly payments can bloat your ratio and eat into your borrowing power faster than you’d think. If you’re worried about how your current setup looks, it’s a great idea to chat with a professional who can help you tidy things up before you apply.

Exemptions and speed limits: When the rules don’t apply

It’s easy to feel a bit overwhelmed when you hear about new lending restrictions, but here is a bit of a silver lining: the debt to income ratio nz rules aren’t a brick wall for everyone. In fact, the Reserve Bank has deliberately left some doors open to ensure the housing market keeps moving and that people can still get into homes. One of the most important things to realise is that these strict RBNZ regulations primarily apply to registered banks. If you are looking at non-bank lenders or 2nd tier options, you might find a lot more flexibility than you’d get at a traditional high-street branch because they don’t always have to play by the same rigid rulebook.

Specific types of lending are also carved out of the rules to help the country grow. For example, if you are planning to build a new home, you’ll often find that the DTI limits are much more relaxed. The government wants to encourage more housing supply, so they don’t want to penalise people who are adding to the total number of houses in NZ. Similarly, if you are just looking at moving your mortgage to another bank without borrowing any extra cash, you usually won’t have to go through a fresh DTI check. Even those temporary loans to cover the gap between houses, which help you manage the time between selling one place and buying another, are treated as a special case to keep the process as smooth as possible.

First Home Loan exemptions

If you’re just starting out, there is a massive advantage available through Kāinga Ora. Loans supported under the First Home Loan scheme are officially exempt from these DTI restrictions. This is a total game-changer for young Kiwis who might have a smaller deposit or are just starting to climb the career ladder. Because these loans are designed to help people get onto the property ladder, they focus more on your potential and your ability to meet repayments rather than a rigid multiple of your current salary. For a deeper look at how to navigate your first purchase, check out our Home Loans for First Home Buyers in New Zealand: The 2026 Comprehensive Guide.

The “Speed Limit” loophole

Even for standard bank loans, there’s a bit of a safety valve known as the “speed limit.” The Reserve Bank allows banks to give 20% of their new mortgage money to people who sit outside the standard 6x or 7x limits discussed earlier. This is where having a professional in your corner really pays off. A mortgage broker knows how to present your case so you’re seen as a high-quality borrower who deserves to be part of that lucky 20%. Lenders don’t just look at the raw numbers; they look at your overall financial character, your spending habits, and your career path. If you’ve got a clean record and a solid plan, we can often help you find a way through the red tape.

Debt to Income Ratio NZ: What the 2026 DTI Rules Mean for Your Mortgage

How to tidy up your finances before you apply

If you’ve crunched the numbers and your debt to income ratio nz looks a bit higher than you’d like, don’t throw in the towel just yet. We see this all the time. The good news is that your current ratio isn’t a permanent mark; it is just a snapshot of where you are today. With a bit of a tidy-up and some smart moves, you can often shift those numbers into a much better position before you even sit down with a lender. It is all about presenting the cleanest possible version of your financial life to the bank.

One of the most effective ways to lower your ratio is by putting all your small, high-interest debts into one manageable payment. Those little store cards and personal loans might not seem like much on their own, but they add up quickly when a bank is looking at your profile. By combining these, you simplify your outgoings and show that you have a disciplined grip on your money. It is also worth looking at your income from a fresh perspective. Improving your ratio isn’t only about cutting what you owe; it’s also about making sure the bank sees every cent you earn. Once you’ve tidied up your debt profile, you’ll also want to think carefully about your loan structure — understanding whether a fixed rate mortgage or a floating rate suits your situation can make a significant difference to your monthly repayments and overall financial comfort.

The “Credit Card Cleanse”

Lenders don’t just care about what you’ve spent; they care about what you could spend. If you have a credit card with a $10,000 limit sitting in your drawer, the bank treats that as $10,000 of potential debt, even if you haven’t spent a cent. They have to assume you might go out and max it out tomorrow. Dropping that limit or closing the account entirely can give your borrowing power a massive boost. We usually recommend doing this at least three months before you apply. This gives the credit reporting systems plenty of time to update and ensures the bank sees a nice, clean slate when they run their checks.

Boosting your income figure

When we talk about income, we’re looking at more than just your base salary. If you’ve been consistently earning overtime, bonuses, or commissions, we can often work with the bank to include these in your total figure. For those looking to grow their portfolio, the bank will also factor in the potential rental income from the property you’re buying. You can see how these numbers stack up by using our Investment Property Mortgage Calculator NZ. Don’t forget about boarder income either. If you plan to have a flatmate in your new home, many lenders will let us add a portion of that expected rent to your total income, which can make a huge difference to your final ratio. If you’re unsure which debts to tackle first or how to best show off your income, reach out to our team for a bit of a strategy session.

How Mortgage Suite Ltd navigates the DTI maze for you

We reckon that getting a “no” from a main bank is often just the start of the conversation, not the final word. It’s easy to feel like the goalposts have moved permanently when you’re faced with the current debt to income ratio nz rules. However, our job at Mortgage Suite Ltd is to act as your dedicated negotiator, looking past the rigid spreadsheets of institutional banking to find a path that works for your unique situation. We don’t just see a ratio; we see your potential and your hard work.

With over two decades of industry experience, our founder Krish Krishna has seen every market cycle and regulatory shift imaginable. This deep institutional knowledge means we don’t just guess which lenders might say yes. We know exactly how to present your case to the right people. We take the weight off your shoulders by handling the complex discussions with lenders, ensuring your application highlights your financial strengths and addresses any debt concerns head-on. We focus on building a partnership with you, making sure you feel supported rather than just processed by a system.

Beyond the Big Four: The power of 2nd Tier lending

One of the biggest advantages of working with our team is our access to 2nd tier loans. These non-bank lenders are often more flexible because they don’t always have to follow the same RBNZ bank rules that restrict the major players. If your DTI ratio is a bit high for a traditional bank, an alternative lender might be the perfect solution. We often use these loans as a strategic “stepping stone.” They get you into your dream home or investment property now, and as your equity grows or your income increases, we can help you transition back to a traditional mortgage later. We take the time to match your unique profile to the lender that offers the best fit for your long-term goals.

Expert negotiation for complex cases

With 20 years in the game, we know which lenders are currently under their DTI speed limits and are looking for quality borrowers. This isn’t just about filling out forms; it’s about expert packaging. We know how to frame your application to mitigate concerns about existing debt while shining a light on your career trajectory and overall stability. Our goal is to take the anxiety out of the process, giving you the confidence to focus on finding the right property while we handle the red tape. When you partner with Mortgage Suite Ltd, you’re not just getting a loan; you’re getting a steady hand to guide you through a fluctuating market. We’re committed to removing the obstacles that stand between you and your dream home.

Securing your future in a changing market

The 2026 lending landscape might feel more restrictive, but it is certainly not impossible to navigate. While the debt to income ratio nz rules have changed how banks view your borrowing power, you now have a clear roadmap to move forward. By tidying up your existing debts and understanding how to maximise your gross income, you put yourself in the best possible position for a “yes”. Remember, the big banks are only one part of the story; flexibility often lies with alternative lenders who value your overall potential.

With over 20 years of banking and brokerage experience, we specialise in finding those 2nd tier and non-bank solutions that mainstream lenders might miss. We provide national coverage across all of New Zealand, ensuring that no matter where you are looking to buy, you have a steady hand to guide you. If you’re ready to take the next step without the stress of rigid spreadsheets, we’re here to help. Book a chat with our expert team today to see how we can help you beat the DTI blues. Your dream home is still within reach; you just need the right plan to get there.

Common Questions About the 2026 DTI Rules

Does the DTI ratio apply to new builds in 2026?

No, construction loans for new builds are officially exempt from the RBNZ’s DTI restrictions. This is a deliberate move by the government to encourage more housing supply across New Zealand. If you’re building from scratch or buying a home off the plans, you won’t have to worry about the standard 6x or 7x limits. This gives you significantly more flexibility when planning your project and choosing your finishes.

Will my student loan affect my debt to income ratio?

Yes, your student loan is absolutely included when the bank calculates your debt to income ratio nz. Lenders look at your total debt obligations, which includes student loans, car finance, and personal loans. Even though your repayments are automatically deducted from your pay, the total balance still sits on the “debt” side of the ledger. It’s a good idea to factor this in early when working out your borrowing power.

Can I get a mortgage if my DTI is over 6?

Yes, you can still secure a mortgage even if your ratio sits above the standard limit of 6 for owner-occupiers. Banks are allowed a “speed limit” where 20% of their new lending can go to borrowers with higher ratios. Alternatively, we can look at 2nd tier lenders who don’t have to follow these specific Reserve Bank rules. This provides a clear path forward even when a big bank’s spreadsheet says no.

Do non-bank lenders have to follow the RBNZ DTI rules?

No, the Reserve Bank’s DTI restrictions primarily apply to registered banks. Non-bank or 2nd tier lenders often have their own internal criteria and aren’t bound by the same 6x or 7x caps. This makes them an excellent option if your income doesn’t quite stretch far enough for a traditional bank’s requirements but you have a solid plan and the ability to manage your repayments comfortably.

How is rental income counted towards my DTI ratio?

Rental income is added to your total gross annual income, though banks usually “shade” it by about 20% to account for vacancies and maintenance costs. This boosted income figure is what allows investors to have a higher debt to income ratio nz limit of 7. It’s a vital part of the calculation that helps reflect the true servicing power of an investment property and your ability to grow a portfolio.

What is the difference between DTI and LVR?

While they work together, they measure two different things. LVR (Loan-to-Value Ratio) looks at the size of your deposit compared to the property’s value. DTI (Debt-to-Income) looks at your total debt compared to what you earn before tax. Think of LVR as your “entry ticket” to get the loan and DTI as the bank’s way of checking you have enough left over each month to live your life.

Can I use boarder income to improve my DTI ratio?

Yes, many lenders will let us include a portion of your expected boarder income to boost your total earnings figure. This can be a real lifesaver for first home buyers trying to stay under the 6x limit. We’ll just need to show the bank that the property has enough space and that the income is realistic for your area. It’s a simple way to make the numbers work in your favour.

What happens to my DTI if interest rates go up?

Your actual DTI ratio won’t change just because interest rates move, as it’s based on the total debt amount rather than the interest cost. However, the bank’s “test rates” usually get tougher when market rates rise. This means that while you might technically fit the DTI box, the bank will look even closer at your ability to manage higher weekly repayments. Choosing the right loan structure — for example, deciding between a fixed rate mortgage versus a floating rate — becomes especially important in this environment, as locking in a rate can provide certainty around your repayments. It’s all about ensuring you have a safe financial buffer. Keeping a close eye on what the OCR means for your mortgage rate will help you time these decisions wisely and protect your repayment budget.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.