
Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026

You might assume that the lowest advertised interest rate from a major bank is the gold standard for your next commercial mortgage New Zealand, but for many savvy investors in 2026, the obvious choice is no longer the most profitable one. While the Official Cash Rate has held steady at 2.25 per cent, the reality of securing finance has become a hurdle of rigid serviceability tests and opaque rate structures. We understand how exhausting it is to present a strong business case only to be met with a clinical checklist that ignores your true commercial potential.

This expert comparison is designed to help you master the complexities of the current lending environment. You’ll learn how to weigh the stability of mainstream institutions against the agility of second-tier lenders who often prioritise business vision over historical paperwork. We’ll break down the critical LVR differences between asset types and show you how to structure a deal that secures flexible terms. By the end of this guide, you’ll have the clarity needed to choose a partner that supports your long-term success rather than just processing another transaction.

Key Takeaways

  • Learn how to select a commercial mortgage New Zealand that balances competitive rates with the flexibility your business needs to thrive.
  • Evaluate the hidden costs of mainstream bank criteria and see how second-tier lenders offer a faster path to settlement.
  • Grasp the specific documentation requirements, including the Information Memorandum, to present a professional case that credit managers can’t ignore.
  • Identify the structural differences between owner-occupied and investment loans to maximise your borrowing capacity and long-term capital growth.
  • Gain insights into how seasoned banking expertise can help you find a clear path forward even when traditional lenders say no.

Understanding the Commercial Mortgage Landscape in New Zealand

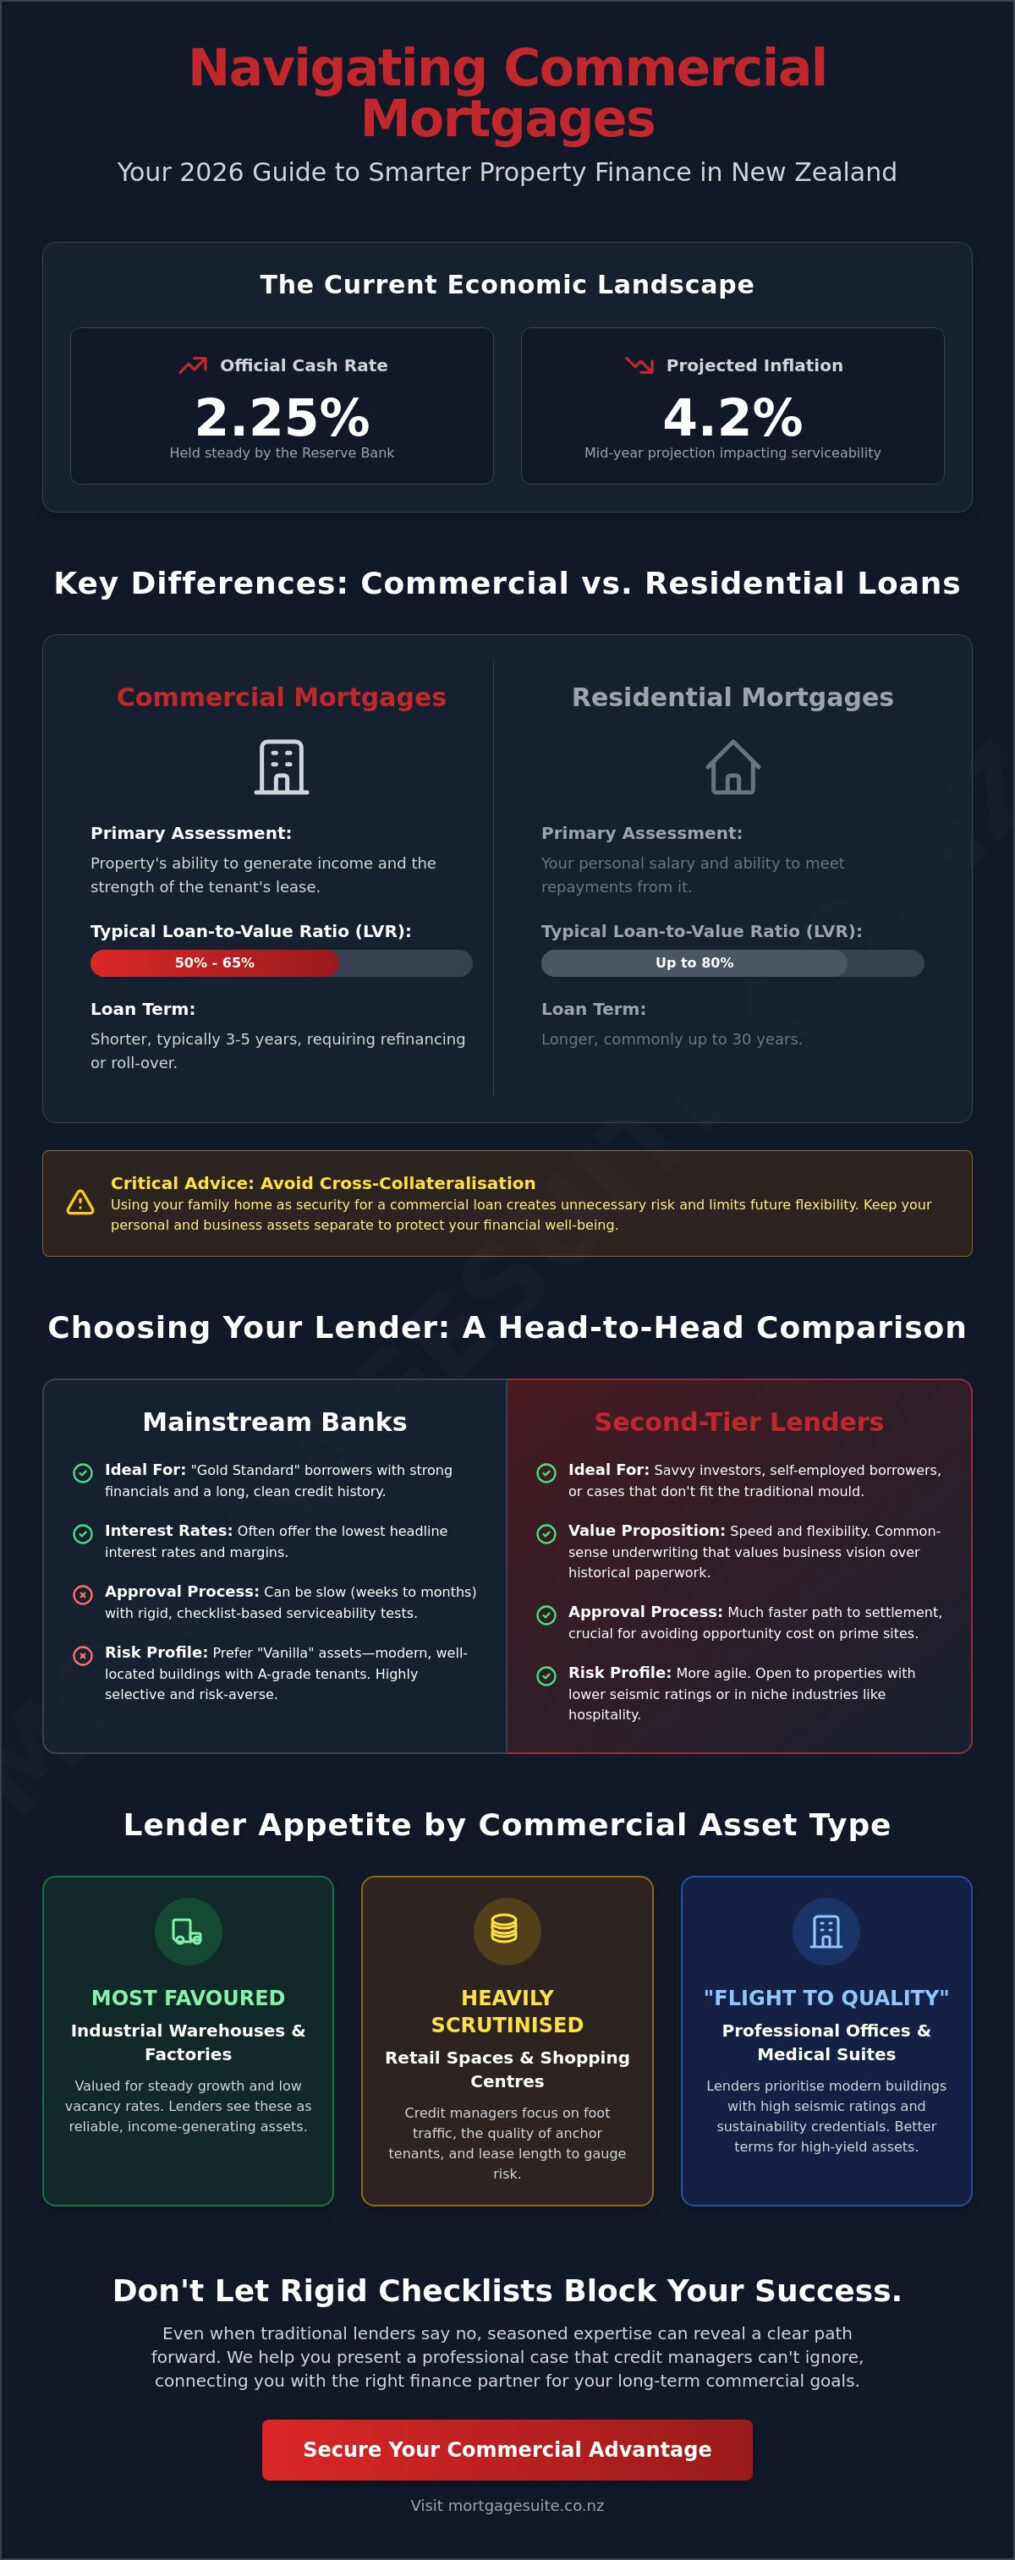
A What is a Commercial Mortgage? is fundamentally a loan secured by non-residential real estate, but the mechanics differ vastly from the home loan you might have for your family residence. While residential lending focuses on your personal ability to meet repayments from your salary, a commercial mortgage New Zealand is judged on the property’s capacity to generate income. In 2026, the lending environment has become more sophisticated. With the Reserve Bank holding the Official Cash Rate at 2.25 per cent and inflation projected to reach 4.2 per cent by mid-year, banks are looking beyond historical data to assess future serviceability. They want to see a clear “intended use” that aligns with current market strengths, such as the robust industrial sector.

The structural differences are significant. Unlike residential loans where you might see Loan-to-Value Ratios (LVR) of 80 per cent, commercial deals usually sit between 50 and 65 per cent. Interest rate margins are also wider, reflecting the higher risk profile of business-related assets. Term lengths are typically shorter, often requiring a refinance or “roll-over” every three to five years. This requires a proactive approach to your portfolio management and a steady hand to navigate the fluctuating margins offered by different institutions.

Asset Types Covered Under Commercial Finance

Lenders categorise risk based on the specific asset you’re purchasing. For retail spaces and shopping centres, credit managers scrutinise foot traffic and the reliability of anchor tenants. Industrial warehouses and factories are currently the most favoured assets in the New Zealand market because of their steady growth and low vacancy rates. If you’re eyeing professional offices or medical suites, be prepared for a “flight to quality” assessment. Lenders in 2026 prioritise modern buildings with high seismic resilience and sustainability credentials, often offering better terms for high-yield, high-quality assets.

Why Residential and Commercial Loans Don’t Mix

The biggest mistake investors make is assuming their residential equity will easily bridge the gap to a commercial purchase. Commercial lending uses a “weighted lease” analysis, where the length and strength of the tenant’s lease are more important than your personal salary. You must also account for GST, which can significantly impact your initial deposit requirements and borrowing power. We often advise against cross-collateralisation, where your home is used as security for a commercial loan. This creates unnecessary risk and can limit your future flexibility if the commercial market fluctuates. Keeping these two worlds separate ensures your personal assets remain protected while your business ventures grow.

Mainstream Banks vs. 2nd Tier Lenders: A Direct Comparison

In the New Zealand market, the “Big Four” (ANZ, ASB, BNZ, and Westpac) traditionally dominate the landscape. However, choosing a commercial mortgage New Zealand based purely on the lowest headline interest rate can be a trap. While a major bank might offer a floating base rate around 4.14 per cent, the rigid serviceability tests often mean your application stalls for weeks. This is where the concept of “opportunity cost” becomes vital. If a bank takes three months to approve a loan while a competitor snaps up a prime industrial site, that lower interest rate hasn’t saved you money; it’s cost you the entire investment.

According to the Property Council New Zealand, the commercial sector is a massive driver of the local economy, yet bank “credit appetite” remains highly selective. Mainstream lenders often shy away from buildings with lower seismic ratings or industries they deem “high risk,” such as hospitality or specific retail niches. Second-tier lenders, by contrast, use common-sense underwriting. They are far more likely to support self-employed borrowers who have strong cash flow but don’t necessarily fit the “perfect” historical tax profile that a major bank demands. Business owners in this position may also benefit from exploring a small business loan NZ to understand the full range of funding options available alongside commercial property finance.

When to Choose a Mainstream Bank

Mainstream banks are the ideal choice for “Gold Standard” borrowers. If you have a clean credit history, two years of strong financial statements, and a property with a long-term lease to a reputable tenant, you should prioritise these institutions. You’ll benefit from lower margins and a full suite of integrated business banking tools. Banks love “Vanilla” assets, which are modern, well-located buildings in major centres like Auckland or Christchurch. If your deal fits this neat box, the major banks offer the stability you need.

The 2nd Tier Advantage: Flexibility and Speed

Second-tier lenders excel where the majors hesitate. They are the go-to for “Vacant Possession” purchases or properties with short-term leases where a bank sees too much risk. These lenders often provide interest-only options or capitalised interest for development projects, allowing you to preserve cash flow during the critical early stages of a project. Second-tier lending serves as the essential bridge for borrowers who do not fit into the rigid boxes of institutional banking. If you find yourself in a complex situation, exploring non-mainstream options can often be the difference between a rejected application and a successful settlement.

Owner-Occupied vs. Investment Commercial Mortgages

The strategy behind your commercial mortgage New Zealand depends entirely on who will be occupying the four walls of your property. Lenders categorise these applications into two distinct buckets: owner-occupied and investment. While they may look similar on a title deed, the credit assessment behind them is world’s apart. If you’re buying a premise to run your own engineering firm or retail boutique, the lender is essentially backing your business’s ability to pay rent to itself. If you’re an investor, they’re backing the strength of your tenants and the lease agreements they’ve signed.

Risk assessment often hinges on the “single-tenant” versus “multi-tenant” factor. Multi-tenant assets, like a block of five shops, are generally viewed as lower risk because a single vacancy won’t stop the mortgage repayments. However, a single-tenant building with a high Weighted Average Lease Expiry (WALE) can be just as attractive. In the 2026 market, a WALE of five years or more is often the “magic number” that unlocks more competitive interest rate margins and longer interest-only periods. Lenders want to see that your income stream is secured well into the future before they commit to a long-term facility.

Financing for Owner-Occupiers

When you buy for your own business, the lender will scrutinise your company’s P&L and balance sheets rather than just the property’s market rent. One significant advantage here is the potential for higher LVRs. Some lenders are willing to stretch beyond the standard 65 per cent if the business is exceptionally robust and has a long history of profitable trading. Owning your own premises also provides significant tax advantages in New Zealand, such as the ability to claim depreciation on certain fit-outs and the deductibility of interest costs, which can turn a monthly expense into a long-term wealth-building tool.

The Investor’s Perspective: Yield and Security

For investors, the focus shifts to “Net” versus “Gross” lease income. A Net lease, where the tenant pays for outgoings like rates and insurance, is far more favourable for loan serviceability than a Gross lease. Lenders also place immense value on “tenant covenant.” A property leased to a government department or a national supermarket chain is viewed as “bankable” security, whereas a lease to a brand-new startup may require a larger deposit or a lower LVR. You must also forecast for “Capex” (capital expenditure) and potential vacancy periods, as lenders will often “stress test” your ability to cover the mortgage even if the building sits empty for six months.
Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026

The Application Process: Organising Your Commercial Case

Securing a commercial mortgage New Zealand requires more than just a decent credit score and a deposit. It demands a narrative that convinces a credit manager your project is a calculated success rather than a speculative risk. The centrepiece of this process is the Information Memorandum (IM). Think of the IM as a professional pitch deck for your loan. It should clearly outline the property’s merits, the strength of the tenants, and your own experience as an operator or investor. When a credit manager receives a messy pile of bank statements, they see work; when they receive a polished IM, they see a professional partner.

Your financial documentation must go deeper than basic year-end accounts. Lenders in 2026 expect to see up-to-date GST returns and detailed Debtors and Creditors lists to verify the real-time health of your cash flow. They also want to see a clear “Exit Strategy.” Whether you plan to refinance with a mainstream bank after three years or sell the asset once the lease is renewed, the lender needs to know exactly how they’ll be repaid. A vague plan is a fast track to a declined application.

Technical Reports You Cannot Ignore

In the New Zealand market, the “IEP” or earthquake rating is often the factor that makes or breaks a deal. Most mainstream banks won’t touch a building with an Initial Evaluation Procedure rating below 34 per cent of the New Building Standard (NBS), as these are deemed “earthquake prone.” If you’re eyeing an industrial site, environmental reports are equally non-negotiable. You must prove the land isn’t contaminated from previous heavy use. Finally, remember that your Loan-to-Value Ratio is always determined by a Registered Valuation from a lender-approved panel valuer, not the purchase price or the CV.

Navigating the Credit Committee

The credit committee evaluates your case based on the “Three Cs”: Character, Capacity, and Collateral. They want to know who you are, your ability to service the debt, and the quality of the asset itself. A well-organised application can reduce your interest margin by 0.5% or more. This is where an expert hand is invaluable; we don’t just submit paperwork, we “shop” your deal to multiple tiers to find the lender whose current appetite matches your specific scenario. If you’re ready to present your strongest possible case, reach out to us today and let’s get your application moving.

Why Mortgage Suite is Your Commercial Finance Partner

Choosing the right partner for your commercial mortgage New Zealand often comes down to who has the deepest understanding of the credit committee’s mindset. At Mortgage Suite, we leverage over 20 years of institutional banking experience to give our clients a distinct advantage in every negotiation. We don’t just act as a middleman; we act as your dedicated advocate. Krish Krishna personally handles complex commercial files, ensuring that your business potential is communicated with the same level of authority that the banks themselves use. This high-level expertise allows us to anticipate the concerns of lenders before they even arise, smoothing the path to a successful settlement.

Whether you are looking at an industrial site in Christchurch or a retail block in Auckland, our national reach ensures we understand the local nuances of the diverse New Zealand property market. We specialise in finding a clear path forward when mainstream banks say no. Our experience has taught us that a “decline” from a major bank is rarely the end of the road. It is often just a sign that your scenario requires a more tailored, non-mainstream approach. We pride ourselves on being a steady hand in a fluctuating market, prioritising long-term partnerships over simple transactional lending. This commitment to your success means we stay involved long after the initial loan is approved, helping you navigate future refinances and portfolio growth.

Expertise in 2nd Tier and Structured Finance

Our clients gain access to a wide panel of alternative lenders that you simply won’t find on the high street. These second-tier institutions offer structured finance solutions that are essential for large-scale property developments and complex business acquisitions. We understand how to piece together these intricate deals, ensuring that the terms align with your project’s specific cash flow requirements and timelines. If your project involves interest-only periods or capitalised interest, we know exactly which lenders have the appetite for that level of flexibility and how to present your case to secure those terms.

Take the Next Step in Your Commercial Journey

A bank decline shouldn’t be the roadblock that stops your business growth or investment plans. We have a proven track record of turning “no” into “yes” by restructuring deals and finding the right lender tier for each unique situation. We have spent years helping first home buyers enter the residential market, and we apply those same principles of tireless advocacy to our commercial clients. We understand the stress that comes with large-scale financial decisions, and our goal is to alleviate that pressure through clear communication and reliable results. Contact us today for a confidential review of your commercial financing needs and let us help you secure the future of your business.

Securing Your Commercial Future in 2026

Your journey toward a successful commercial mortgage New Zealand shouldn’t be defined by the rigid boxes of institutional banking. We’ve explored how the right lender tier can determine your project’s viability, from the stability of the Big Four to the common-sense flexibility of second-tier options. Success in this market requires more than just a property; it requires a professional presentation that anticipates credit hurdles before they become roadblocks.

With over 20 years of institutional banking experience and national coverage, we specialise in navigating the complexities of 2nd tier lending and structured finance. We’re here to act as your dedicated advocate, ensuring your business potential is seen and valued by the right financial partners. Don’t let a complex scenario or a traditional bank decline slow your momentum. Contact Mortgage Suite for a specialised commercial finance consultation today and let’s build a clear path forward for your next acquisition or development. We’re ready to help you turn your commercial vision into a reality.

Frequently Asked Questions

What is the typical LVR for a commercial mortgage in New Zealand?

Most lenders provide a Loan-to-Value Ratio (LVR) between 50 and 65 per cent for a commercial mortgage New Zealand. While residential loans often reach 80 per cent or higher, commercial assets require a larger deposit to offset the increased risk and potential for longer vacancy periods. Some second-tier lenders may stretch these limits slightly for high-quality industrial assets or exceptionally strong owner-occupied business cases.

How do commercial interest rates compare to residential rates?

Commercial interest rates are almost always higher than residential rates because they include a wider risk margin. In 2026, while home loans might hover at lower levels, commercial floating rates can range from 4 per cent to over 10 per cent depending on the lender tier. Banks charge this premium to account for the complexity of the security and the shorter term of the facility.

Can I use KiwiSaver for a commercial property purchase?

No, you generally cannot use KiwiSaver funds to purchase a commercial property. KiwiSaver withdrawal rules are strictly designed for first-home residential purchases or retirement. If you’re looking to fund a commercial venture, you’ll need to rely on business capital, personal savings, or equity from existing residential property rather than your retirement savings. This ensures the funds remain dedicated to their intended purpose.

What is an IEP rating and why does it affect my commercial loan?

An Initial Evaluation Procedure (IEP) rating measures a building’s seismic strength relative to the New Building Standard (NBS). Lenders are extremely cautious about buildings rated below 34 per cent NBS because they’re legally classified as earthquake-prone. A low rating can make a property unbankable or require significant capital expenditure to upgrade before a loan is approved, as it represents a major collateral risk.

How long is the term for a typical commercial mortgage?

Commercial loan terms are significantly shorter than the 30-year terms common in residential lending. Most commercial facilities are structured for three to five years. At the end of this period, the loan is usually reviewed and rolled over or refinanced based on the current market value of the property and the strength of the existing leases. This allows lenders to adjust their exposure periodically.

Do I need a business plan to get a commercial mortgage approved?

Yes, a clear business plan or an Information Memorandum is essential for most commercial applications. Lenders want to understand your operational experience, the property’s income potential, and your long-term strategy for the asset. A well-structured plan demonstrates to the credit committee that you’ve accounted for risks like tenant vacancy or rising maintenance costs, making your case much more compelling for approval.

What happens if my business has a “bad credit” history but strong assets?

Strong assets can often bridge the gap if your historical credit is less than perfect. While mainstream banks might decline the application, second-tier lenders specialise in these non-mainstream scenarios. They often prioritise the value of the collateral and your current cash flow over past credit events, providing a pathway to secure a commercial mortgage New Zealand when traditional institutions are unable to help.

Are there specialised loans for property development in NZ?

Yes, property development loans are specific facilities designed for construction or major renovations. These loans often feature drawdowns where funds are released in stages as work is completed and verified. They may also allow for capitalised interest, meaning you don’t make repayments until the project is finished or the units are sold, which preserves your cash flow during the critical building phase.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loans for Self Employed: 2026 Guide to Getting Approved

Imagine sitting across from a bank manager, presenting a thriving business you have built from the ground up, only to be told your "paper income" isn’t enough to buy a house. It is incredibly disheartening when mainstream lenders ignore your legitimate business add-backs or penalise you for the very expenses your accountant organised to reduce your tax bill. If you are searching for a home loan and are self employed, you have likely realised that traditional banks often view your entrepreneurial drive as a risk. They see inconsistent income "bursts" and mountains of paperwork, while we see a dedicated professional who deserves a steady hand to guide them through the finance process.

This 2026 guide provides the clear path to pre-approval you need, even with the Official Cash Rate at 2.25% and debt-to-income ratios capped at six times your earnings. You will learn exactly how to bypass rigid bank criteria by exploring non-bank lenders who offer flexible "alt-doc" solutions using GST returns or business bank statements. We will detail how to secure competitive interest rates and navigate the latest LVR restrictions, ensuring your business structure is properly understood so you can move forward with confidence.

Key Takeaways

  • Understand how lenders apply “safety margins” to your income and how to navigate the 2026 Debt-to-Income (DTI) restrictions.
  • Discover the documentation hierarchy and why alternative “Alt-Doc” methods like GST returns might be the key to proving your true earning power.
  • Learn why 2nd Tier lenders are a strategic choice for a self employed home loan nz rather than a last resort when mainstream banks decline your application.
  • Master a simple “pre-audit” process to organise your business drawings and personal expenses for maximum lender appeal.
  • Explore how professional advocacy and veteran negotiation can translate your complex business structure into a clear path for approval.

The Reality of Self-Employed Home Loans

For many business owners, the dream of home ownership feels like it is being held hostage by a spreadsheet. Getting a **self employed home loan ** in 2026 requires more than just a profitable business; it requires a deep understanding of how lenders interpret your financial health. While an employee with a standard salary provides a predictable data point for a bank, your income is often viewed through a lens of skepticism. Mainstream banks are currently operating with a conservative risk appetite, and they often struggle to reconcile the fluctuations of a growing business with their rigid lending criteria.

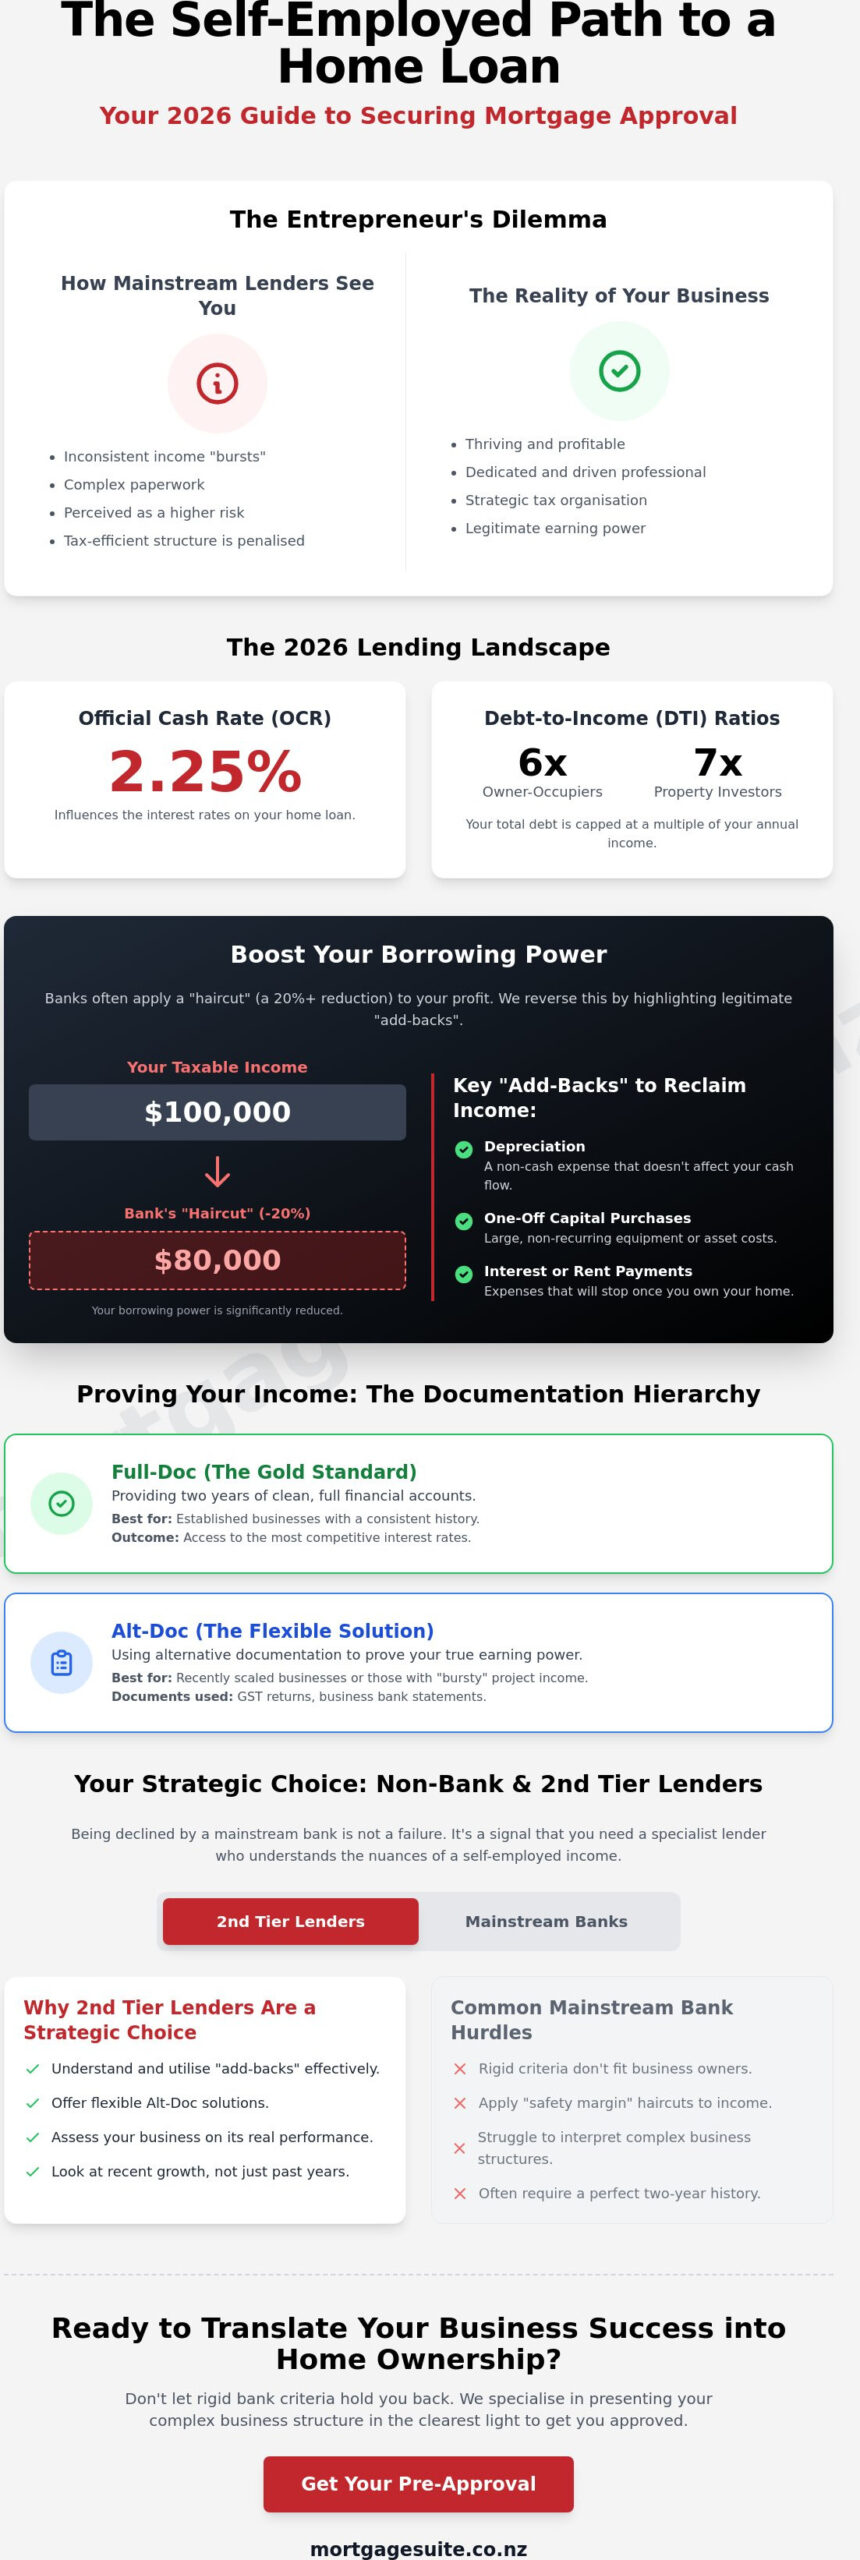
The lending environment in mid-2026 is heavily influenced by the Debt-to-Income (DTI) restrictions that became a permanent fixture in recent years. For owner-occupiers, the limit is generally six times your gross annual income, while investors are capped at seven times. When defining self-employment for a loan application, the bank does not just look at your turnover. They look at your drawings, your net profit, and your ability to service debt when the Official Cash Rate (OCR) is at 2.25%. If your income arrives in "bursts" rather than a steady drip, a traditional bank might simply put you in the "too hard" basket. However, being declined by a major bank is rarely the end of the road; it is often just the signal that you need a more sophisticated lending partner.

Understanding Your Income

Banks are notoriously cautious with business owners.

To overcome this, we focus on "add-backs." These are legitimate business expenses that don’t actually impact your ability to pay a mortgage, such as:

  • One-off capital purchases or equipment upgrades.
  • Non-cash expenses like depreciation.
  • Excessive home office claims or personal expenses run through the business.
  • Rent or interest payments that will cease once you buy your own property.

Regulatory Changes and DTI Ratios in 2026

The 2026 regulatory framework treats business debt and personal debt with equal scrutiny. Under the current Credit Contracts and Consumer Finance Act (CCCFA) requirements, lenders must be certain that your business debt—such as vehicle finance or an overdraft—does not compromise your home loan repayments. If your business carries significant debt, it can quickly eat into your DTI allowance, making it harder to reach the 80% LVR threshold required for standard owner-occupier loans. We work with you to clean up your debt profile, ensuring your personal and business liabilities are structured to maximise your approval chances without sacrificing your business’s cash flow.

Proving Your Income: Documentation That Actually Works

Securing a self employed home loan requires a strategic approach to your paperwork. While an employee simply hands over three months of payslips, your application must build a narrative of stability and growth. Many business owners find that their IRD Summary of Earnings tells a story of tax efficiency rather than true mortgage affordability. To bridge this gap, we look beyond the basic tax return to find the documents that reflect your business’s actual momentum.

The hierarchy of proof has shifted significantly in 2026. Traditional "Low-Doc" loans, which once required minimal evidence, have largely been replaced by "Alt-Doc" (alternative documentation) solutions. This is a direct result of the Credit Contracts and Consumer Finance Act (CCCFA), which mandates a robust assessment of affordability. If you have two years of clean financial accounts, you’ll likely qualify for "Full-Doc" rates. However, if your business has recently scaled or you have "bursty" income from project-based contracts, Alt-Doc allows us to use more recent data, such as GST returns, to prove you can comfortably service the debt.

The Essential Self-Employed Paperwork Checklist

Lenders want to see that your business is a reliable vehicle for income. Before submitting an application, ensure you have the following documents organised:

  • Financial Statements: Full Profit & Loss and Balance Sheets for the last two financial years.
  • Bank Statements: Six months of personal and business statements. Lenders look for regular drawings that match your stated income.
  • Tax Verification: Your most recent personal and business tax assessments, along with proof that all IRD obligations are being met.
  • Add-back Schedule: A clear list of non-cash or one-off expenses that shouldn’t count against your borrowing power.

If your business income is seasonal, we frame your application by showing a 12-month average rather than focusing on a quiet month. This context is vital for preventing a "decline" based on a temporary dip in cash flow. If you are unsure which documents best represent your current position, exploring tailored home loan options can help clarify your strategy before you approach a lender.

Alt-Doc Solutions for Newer Businesses

For those who have been trading for 12 to 18 months, or whose most recent tax return doesn’t reflect a recent surge in turnover, Alt-Doc is a game changer. Instead of waiting for the next financial year to end, some specialist lenders will accept an accountant’s declaration of your earnings or use your last six months of GST returns to verify your current capacity. This approach focuses on where your business is today, not where it was two years ago, providing a vital pathway for self employed home loan applicants who are currently in a high-growth phase.

Many business owners view 2nd tier lenders with a sense of hesitation, fearing they are only for those with significant financial trouble. This is a misconception that often prevents entrepreneurs from securing a self employed home loan when they are perfectly capable of servicing a mortgage. In the current 2026 market, non-bank lenders like Avanti Finance or Pepper Money act as sophisticated specialists. They fill the gap left by mainstream banks that rely on rigid automated systems. While a bank might see a complex trust structure or a single year of trading as a red flag, a 2nd tier lender employs human underwriters who look at the bigger picture.

The primary trade-off involves cost. Non-bank "Near Prime" rates typically start around 5.65% to 7.35%, which is higher than the special rates offered by ANZ or Westpac. You should also expect higher establishment fees, often ranging between 1% to 1.5% of the loan value. However, for a business owner, the value lies in the approval probability. These lenders aren’t bound by the Reserve Bank’s strict Debt-to-Income (DTI) thresholds in the same way as registered banks. This flexibility allows us to secure a **self employed home loan **for clients who have the cash flow but don’t fit the traditional "box."

When to Choose a Non-Bank Lender

Choosing a non-bank option is often the most strategic move if your business has undergone a recent transition. If you have moved from a sole trader to a company structure, or if a one-off capital investment skewed your net profit last year, traditional bank software will likely trigger an automatic decline. Specialist lenders are far more accommodating of short trading histories, sometimes considering applications with as little as 6 to 12 months of data if you have a strong industry background. They specialise in "Alt-Doc" solutions, allowing us to use recent GST returns to prove your current earning capacity rather than relying on outdated tax returns.

The Long-Term Strategy: Refinancing Back to a Bank

We often treat a 2nd tier loan as a temporary bridge rather than a forever home for your mortgage. By securing a loan now and maintaining a clean repayment history for 12 to 24 months, you "prime" yourself for a future bank application. This period allows your business to mature on paper and demonstrates your reliability as a borrower. Understanding how to qualify for a home loan in NZ involves planning this exit strategy from the start. Once your financial statements show two years of solid growth, we can assist you in refinancing back to a mainstream bank at a lower interest rate, having already secured the property you wanted.

Home Loans for Self Employed: 2026 Guide to Getting Approved

A Step-by-Step Guide to Polishing Your Mortgage Application

Successful lending outcomes are rarely the result of luck. They are the product of a disciplined staging process that begins months before you even attend an open home. When you apply for a self employed home loan, the bank isn’t just looking for profitability; they are searching for evidence of financial discipline. Think of your application like a house you are preparing for sale. You need to declutter the noise, fix the small leaks in your spending, and highlight the structural strengths of your business.

The first step is a rigorous pre-audit. Scour your business accounts for personal expenses that might look like high living costs to a lender. Second, ensure your drawings are regular. A bank prefers to see $1,500 transferred every week rather than a $20,000 lump sum once a quarter. Third, slash your credit limits. In the 2026 DTI environment, an unused $10,000 credit card or an active Buy Now, Pay Later (BNPL) account can reduce your borrowing power by tens of thousands of dollars. Finally, prepare a formal business commentary and engage a specialist who understands the nuances of business structures.

Framing Your Business Narrative

Lenders hate mystery. If your profit dipped recently because you invested in a new fleet of vehicles or a high-end server array, you must tell them. A written explanation transforms a "loss" on paper into a strategic investment in future growth. Highlight recurring revenue models or long-term contracts that prove your income isn’t just a series of lucky breaks. If you are a contractor in a niche field like IT or engineering, including a professional CV helps the underwriter understand your employability if your current contract ends. This narrative provides the context that raw numbers often lack.

Cleaning Up Your Personal Financial Conduct

You must adhere to the "three-month rule" of flawless account behaviour. Under the CCCFA, any unarranged overdraft or missed payment on a utility bill is a massive red flag. Banks interpret these as a lack of financial control, regardless of how much money is sitting in your business account. You also need a clear "deposit story." Be ready to prove exactly where your savings came from to satisfy Anti-Money Laundering (AML) requirements. If your deposit includes a gift from family or a business dividend, document the paper trail early. To ensure your application is truly bank-ready, you can apply for a home loan assessment to identify any potential hurdles before they become problems.

Why Mortgage Suite is Your Best Advocate for Approval

When you work for yourself, you don’t just need a loan; you need a dedicated negotiator who understands the intricacies of your business. Securing a **self employed home loan ** is often a battle of interpretation. It’s about how your depreciation is viewed, how your "bursty" income is averaged, and how your future potential is weighed against historical tax returns. We provide the steady hand and the institutional knowledge required to bridge the gap between your entrepreneurial success and the rigid requirements of a bank’s credit department.

We work with the mainstream banks in the first instance but our reach extends beyond the big four banks. We provide access to a comprehensive range of 2nd tier and alternative capital, allowing us to find solutions even when traditional lenders have said no. Our partnership approach includes:

  • Access to residential investment property loans and business finance.
  • Strategic planning to move from 2nd tier loans back to mainstream banks.
  • Proactive management of commercial and property development loans.
  • Expert structuring for first-home buyers with non-standard income.

The Advantage of a Seasoned Negotiator

Krish Krishna brings over 20 years of banking experience and 26 years as Financial Adviser to your side of the table. This isn’t about simply submitting a form; it’s about expert negotiation. Krish uses his deep understanding of credit policy to challenge rejections and present your financial story in a way that resonates with underwriters. We specialise in structuring complex deals that mainstream banks often overlook, ensuring your business structure is viewed as a strength rather than a liability. You aren’t just another file to us; you are a partner whose success is our priority.

We understand that as a business owner, your time is your most valuable asset. By utilising our veteran expertise, you gain an advocate who knows exactly which "add-backs" to fight for and which lenders have the highest risk appetite for your specific industry. This high-standard service is designed to remove obstacles and create a seamless bridge to your property goals.

Ready to Get Moving?

We simplify the process so you can stay focused on running your business. Instead of you spending hours chasing paperwork and deciphering banking jargon, we handle the heavy lifting. The first steps involve a consultative conversation where we identify your needs and outline a clear path to pre-approval. There is no need to feel overwhelmed by the volume of paperwork when you have a veteran expert managing the details. Enquire about your self-employed home loan today and take the first step toward a successful approval.

Your Path to Home Ownership Starts Here

Securing a self employed home loan in 2026 doesn’t have to be a source of constant anxiety. While the DTI restrictions and rigid bank criteria create hurdles, they are far from insurmountable when you have the right documentation and a strategic narrative to tackle the mainstream banks. Whether you are using Alt-Doc solutions to prove your recent momentum or utilising a 2nd tier lender as a tactical stepping stone, the goal remains the same: securing a home that reflects your hard work.

At Mortgage Suite, we leverage over two decades of banking and lending expertise to ensure your business structure is understood, not just processed. If you dont fit the mainstream banks lending criteris, we specialise in 2nd tier loans that mainstream banks often decline, providing a tailored, NZ-wide service for business owners and contractors alike. You have built your business with passion and discipline; we are here to apply that same dedication to your mortgage approval.

If you are ready to move past the frustration of bank rejections, book a consultation with our self-employed lending specialists today. Let us turn your complex financial profile into a clear path forward. Your entrepreneurial journey deserves a partner who values your vision as much as you do.

Frequently Asked Questions

Can I get a home loan if I’ve only been self-employed for one year?

Yes, you can secure a home loan with only one year of trading, though you will likely need to look beyond the major banks. While traditional lenders typically require two years of financial statements, many specialist lenders offer "Alt-Doc" solutions for those with 12 months of history. These lenders focus on your recent GST returns and industry background to assess your current earning capacity properly.

How much deposit do I need as a self-employed borrower in NZ?

Most self-employed borrowers need a 20% deposit for an owner-occupied property or 30% for an investment. If you are a first-home buyer, you may qualify for the Kāinga Ora First Home Loan, which allows for a deposit as low as 5%. Having a larger deposit often helps offset the perceived risk of variable income and can lead to more competitive interest rates from mainstream lenders.

Will my interest rate be higher because I work for myself?

Your interest rate won’t necessarily be higher if you meet the standard lending criteria of a mainstream bank. However, if you require a specialist or 2nd tier lender due to a short trading history or complex accounts, you should expect a margin above standard bank rates. These "Near Prime" rates often start from 5.85% and serve as a strategic bridge until you can refinance to a major bank.

What are "add-backs" and how do they help my mortgage application?

Add-backs are legitimate business expenses that we "add back" to your net profit to demonstrate your true mortgage repayment capacity. Common examples include depreciation, one-off equipment purchases, or interest on loans that will be repaid. By identifying these non-cash or non-recurring costs, we can significantly increase the income figure used for your **self employed home loan **application and improve your approval chances.

Can I use my KiwiSaver for a deposit if I am self-employed?

Yes, you can certainly use your KiwiSaver for a deposit, provided you have been a member for at least three years and are purchasing your first home. Being self-employed does not change your eligibility for a first-home withdrawal. It is essential to request your withdrawal pack early to ensure the funds are ready for settlement, especially if your business income fluctuates and documentation takes longer to organise.

What happens if my latest tax return shows a low profit due to expenses?

If your latest tax return shows a low profit due to high business expenses, we can often use alternative documentation to prove your actual income. Specialist lenders may look at your last six months of GST returns or bank statements to see your current cash flow. This approach helps bypass the "paper loss" created by tax-minimisation strategies, allowing your true earning power to be recognised by the lender.

Do I need a clean credit history to get a self-employed home loan?

You don’t necessarily need a perfect credit history to get approved for a self employed home loan. While mainstream banks are very strict about missed payments or defaults, 2nd tier lenders are more flexible and will often listen to the story behind a credit impairment. A clean record for the last 12 months is usually sufficient to access a wide range of alternative lending options that banks often overlook.

How do DTI ratios affect my ability to borrow for a home?

Debt-to-Income (DTI) ratios limit your total borrowing to a multiple of your gross annual income, typically set at six times for owner-occupiers. For business owners, this means your personal and business debts are weighed against your verified drawings and profit. If your DTI is too high for a major bank, we can often find non-bank solutions that aren’t bound by these specific Reserve Bank restrictions in 2026.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.