Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

What if the biggest hurdle to your next purchase isn’t the bank’s ‘no’, but the way your current loans are tied together? For many Kiwi investors, the challenge of financing multiple investment properties nz has become a bit of a puzzle lately. You’ve probably noticed that mainstream banks are getting sticky about further lending; meanwhile, with the Official Cash Rate at 2.75% as of September 2026, those interest rates are likely putting a squeeze on your rental yields. It’s frustrating when you know the equity is there, but the red tape feels like it’s tightening around your long-term goals.

I know it’s confusing to deal with the new 7x debt-to-income (DTI) limits while trying to keep your cash flow healthy. This guide is here to help you restructure your existing debt to unlock that trapped equity and regain control. We’ll look at how to organise a loan structure that stays flexible for the next five years, focusing on lower monthly repayments and a clear path to your next deposit. You’ll discover how to move forward with your New Zealand portfolio with the confidence of someone who knows exactly how the banking system works.

Key Takeaways

  • Learn why a full portfolio audit is the first step to ensuring your current loan setup aligns with your 2026 financial goals.
  • Discover how to calculate your “useable” equity to release cash for your next deposit without needing to sell any of your existing properties.
  • Understand why the big banks might be saying no and how 2nd tier lenders can provide the flexibility you need to keep growing.
  • Follow a clear, step-by-step process for financing multiple investment properties nz that prioritises healthy cash flow and long-term stability.
  • Gain an insider’s perspective on how to structure your debt so it remains adaptable to market changes over the next five years.

What Does Refining Multiple Investment Properties Actually Mean?

Most people think refinancing is just a fancy way to say you’re looking for a lower interest rate. While a better rate is always a win, refining your portfolio goes a lot deeper. If you’re financing multiple investment properties nz, a simple rate-switch doesn’t look at how your loans interact with each other. A true refinement is a full audit of your debt setup. It’s about making sure your current structure actually matches what you want to achieve in 2026 rather than just sticking with what worked three years ago.

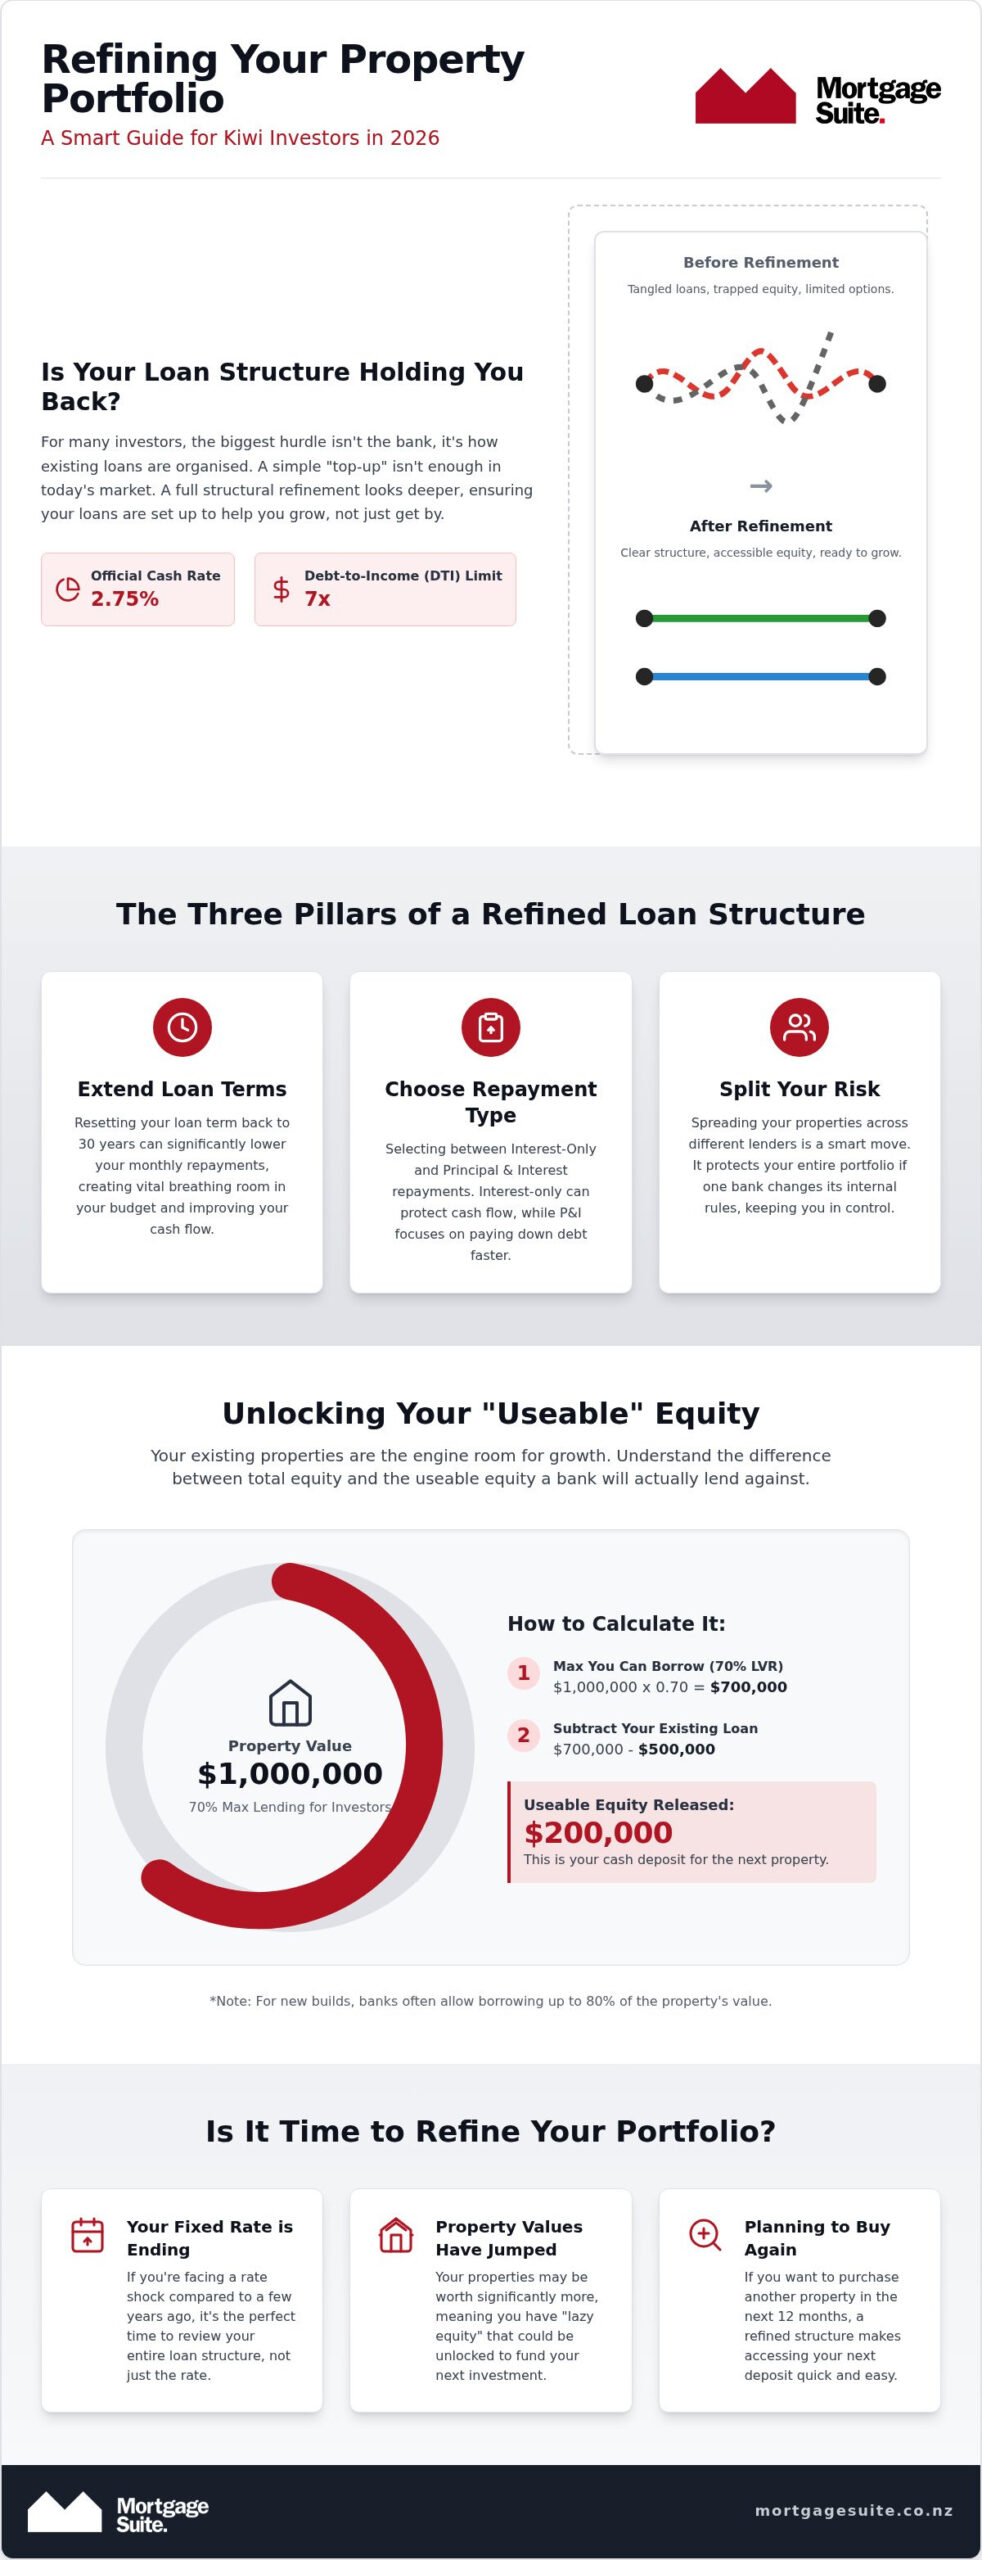
The way the market looks in 2026 has changed significantly. With the Official Cash Rate at 2.75% and debt-to-income (DTI) limits capped at seven times what you earn, the old ‘top-up’ method often hits a wall. A top-up just piles more debt on the existing heap. A structural refinement, however, might involve moving loans between different lenders or changing how your equity is split to give you more freedom. Understanding New Zealand property market dynamics is vital here; as rules shift, your structure has to evolve to keep your portfolio healthy.

The Three Pillars of a Refined Loan

A well-organised portfolio usually rests on three specific choices that impact your daily life and your ability to buy again:

  • Interest-only vs Principal and Interest: We check which one fits your current rental income. In a higher interest environment, interest-only terms can protect your daily cash flow, while principal and interest might be better if you’re focusing on paying down debt.
  • Extending loan terms: Resetting your loan back to a 30-year term gives your monthly budget some vital breathing room, even if you’ve already been paying it down for a few years.
  • Splitting your risk: Putting all your properties with one bank is risky. If they change their internal rules, your whole portfolio gets squeezed. Spreading your loans across different lenders keeps you in the driver’s seat.

Signs It Is Time to Refine Your Portfolio

You don’t have to wait for a problem to check your numbers. If your fixed-rate term is ending soon, you’re probably facing a bit of a shock compared to what you paid a few years ago. This is the perfect time to look at the whole picture. Another sign is a jump in property values. If you reckon your properties are worth significantly more now, you might have “lazy equity” that could be working harder for you. Finally, if you’re planning to buy another investment property within the next 12 months, you’ll need a structure that makes getting that next deposit easy to access without a bank audit slowing you down.

Unlocking Equity: The Engine Room of Your Property Growth

Growth doesn’t always require a huge pile of cash sitting in a savings account. For most Kiwi investors, the fuel for their next purchase is already sitting right under their feet. When you’re looking at financing multiple investment properties nz, your existing portfolio is usually your best source of funding. However, there’s a big difference between the total equity you see on paper and the “useable” equity a bank will actually let you touch. Understanding this distinction is the secret to growing your portfolio without having to sell a single asset.

As of late 2026, the Reserve Bank settings require a 30% deposit for existing investment properties, meaning you can generally borrow up to 70% of the property’s value. For new builds, that requirement often drops to a 20% deposit. By refining your current loans, you can often release this equity as a cash deposit for your next move. You can use our mortgage calculator to get a rough idea of what your current numbers look like before you start the formal process.

Calculating Your Useable Equity

Equity is simply the gap between what your property is worth and what you owe the bank. While you might be able to borrow up to 80% against the value of your own home, the rules for rental properties are stricter. Banks generally cap lending at 70% for existing rentals to stay within current rules. This is why getting a fresh, professional appraisal is the first step in any refinement. If your properties have gone up in value, that “lazy equity” can be unlocked to form the deposit for your next purchase. It’s about making your current assets work harder so you don’t have to.

Refining Your Loan to Buy Again

Once you’ve identified your useable equity, you can use it as a virtual deposit. This means the bank uses the value in your current properties to secure the loan for the new one. A common trap many investors fall into is having the bank tie all your properties together as one big security. This gives the bank a lot of power but leaves you with very little flexibility. A smart refinement strategy keeps your home and your rentals separate. This ensures that if you decide to sell one property later, the bank can’t automatically grab all the money to pay down your other loans. If you want to see how we’ve helped others navigate these structures, feel free to read our client reviews to see the results of a tailored approach.

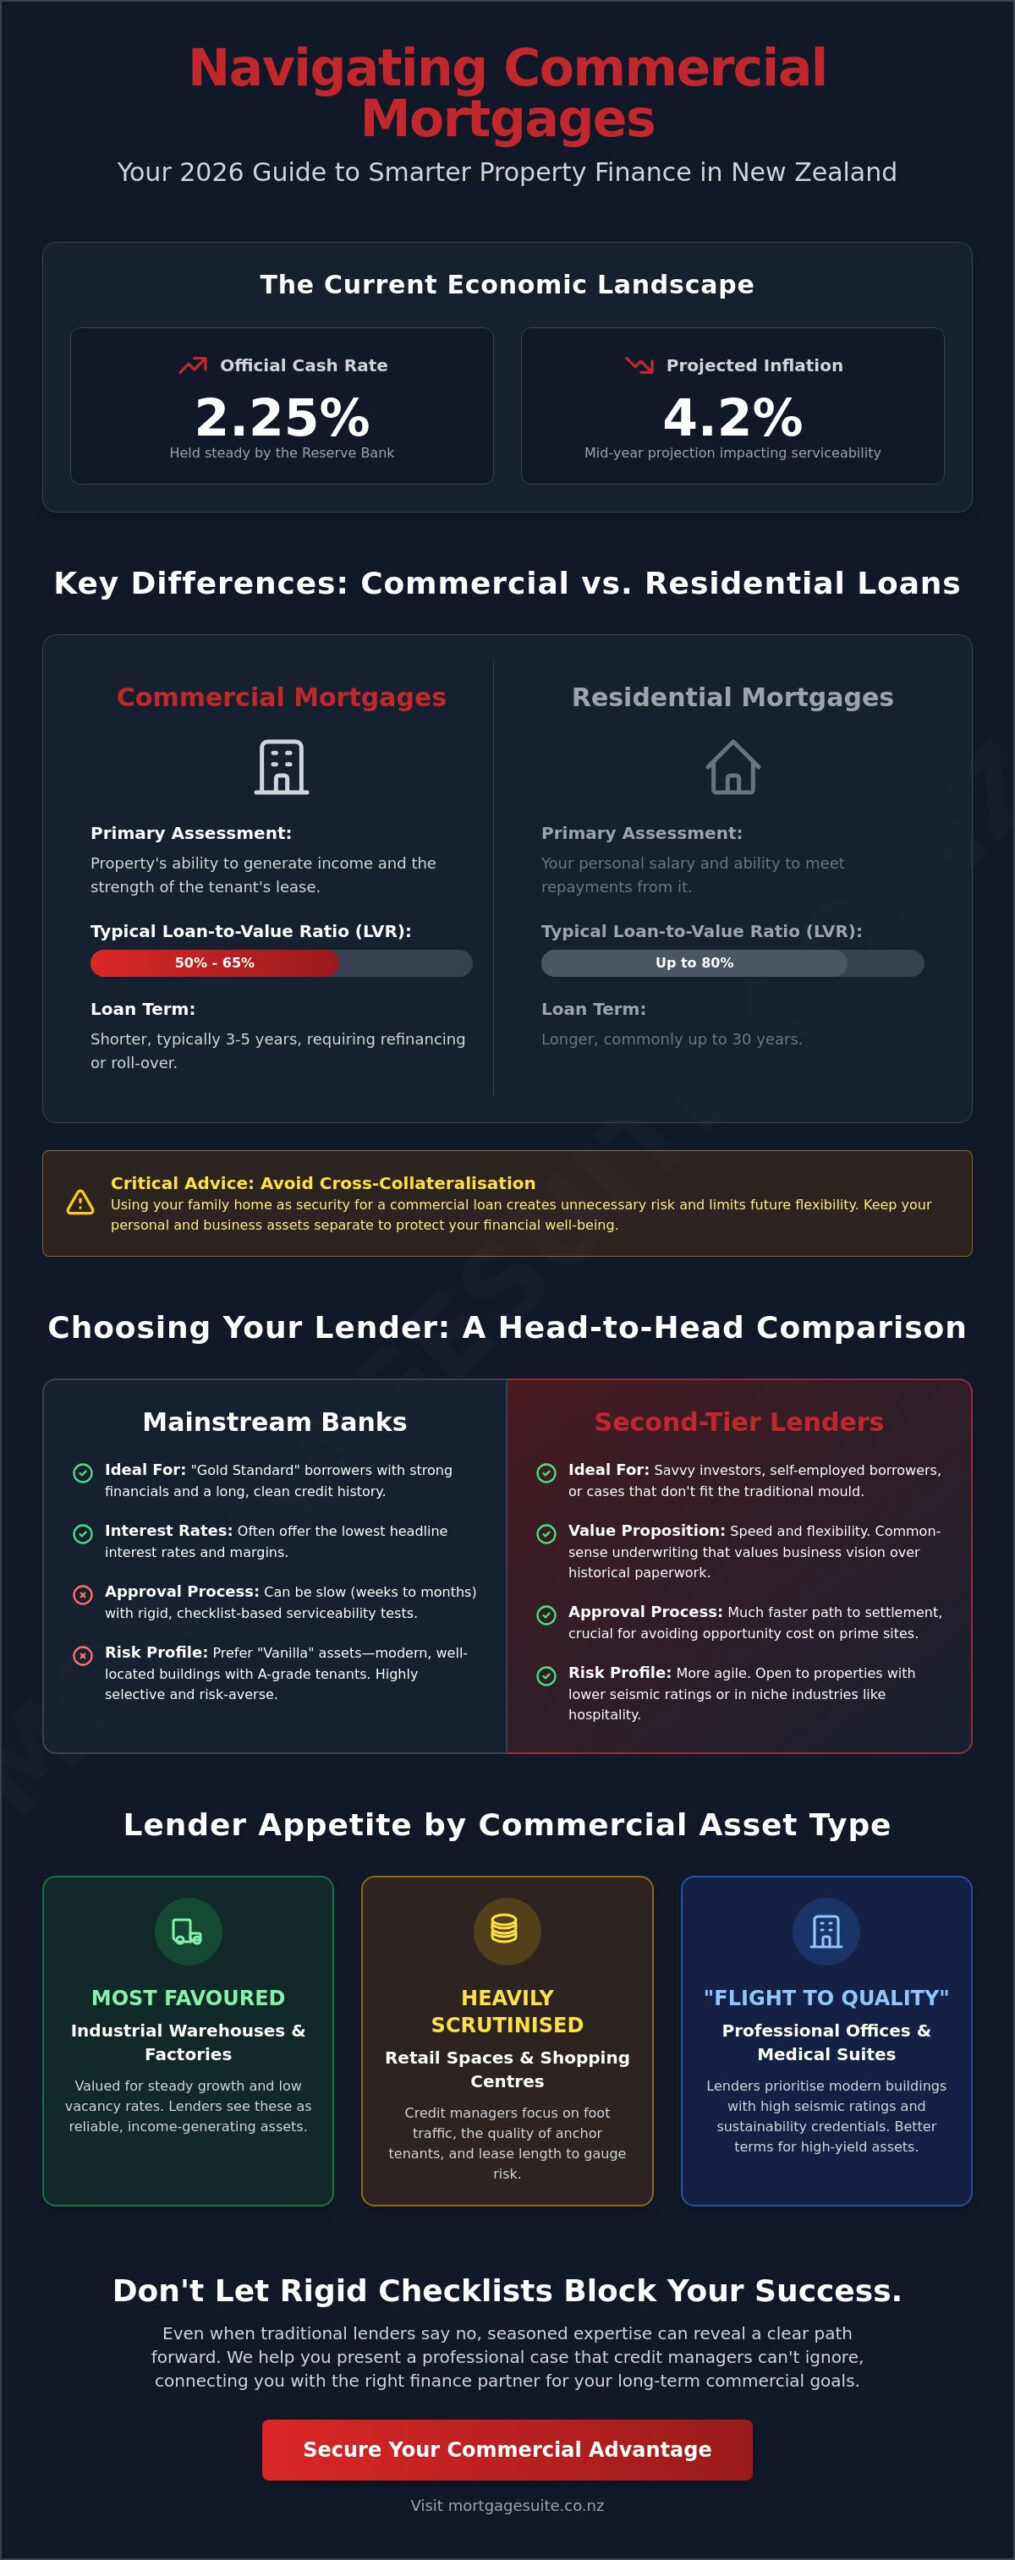
Mainstream Banks vs 2nd Tier Lenders: Choosing Your Path

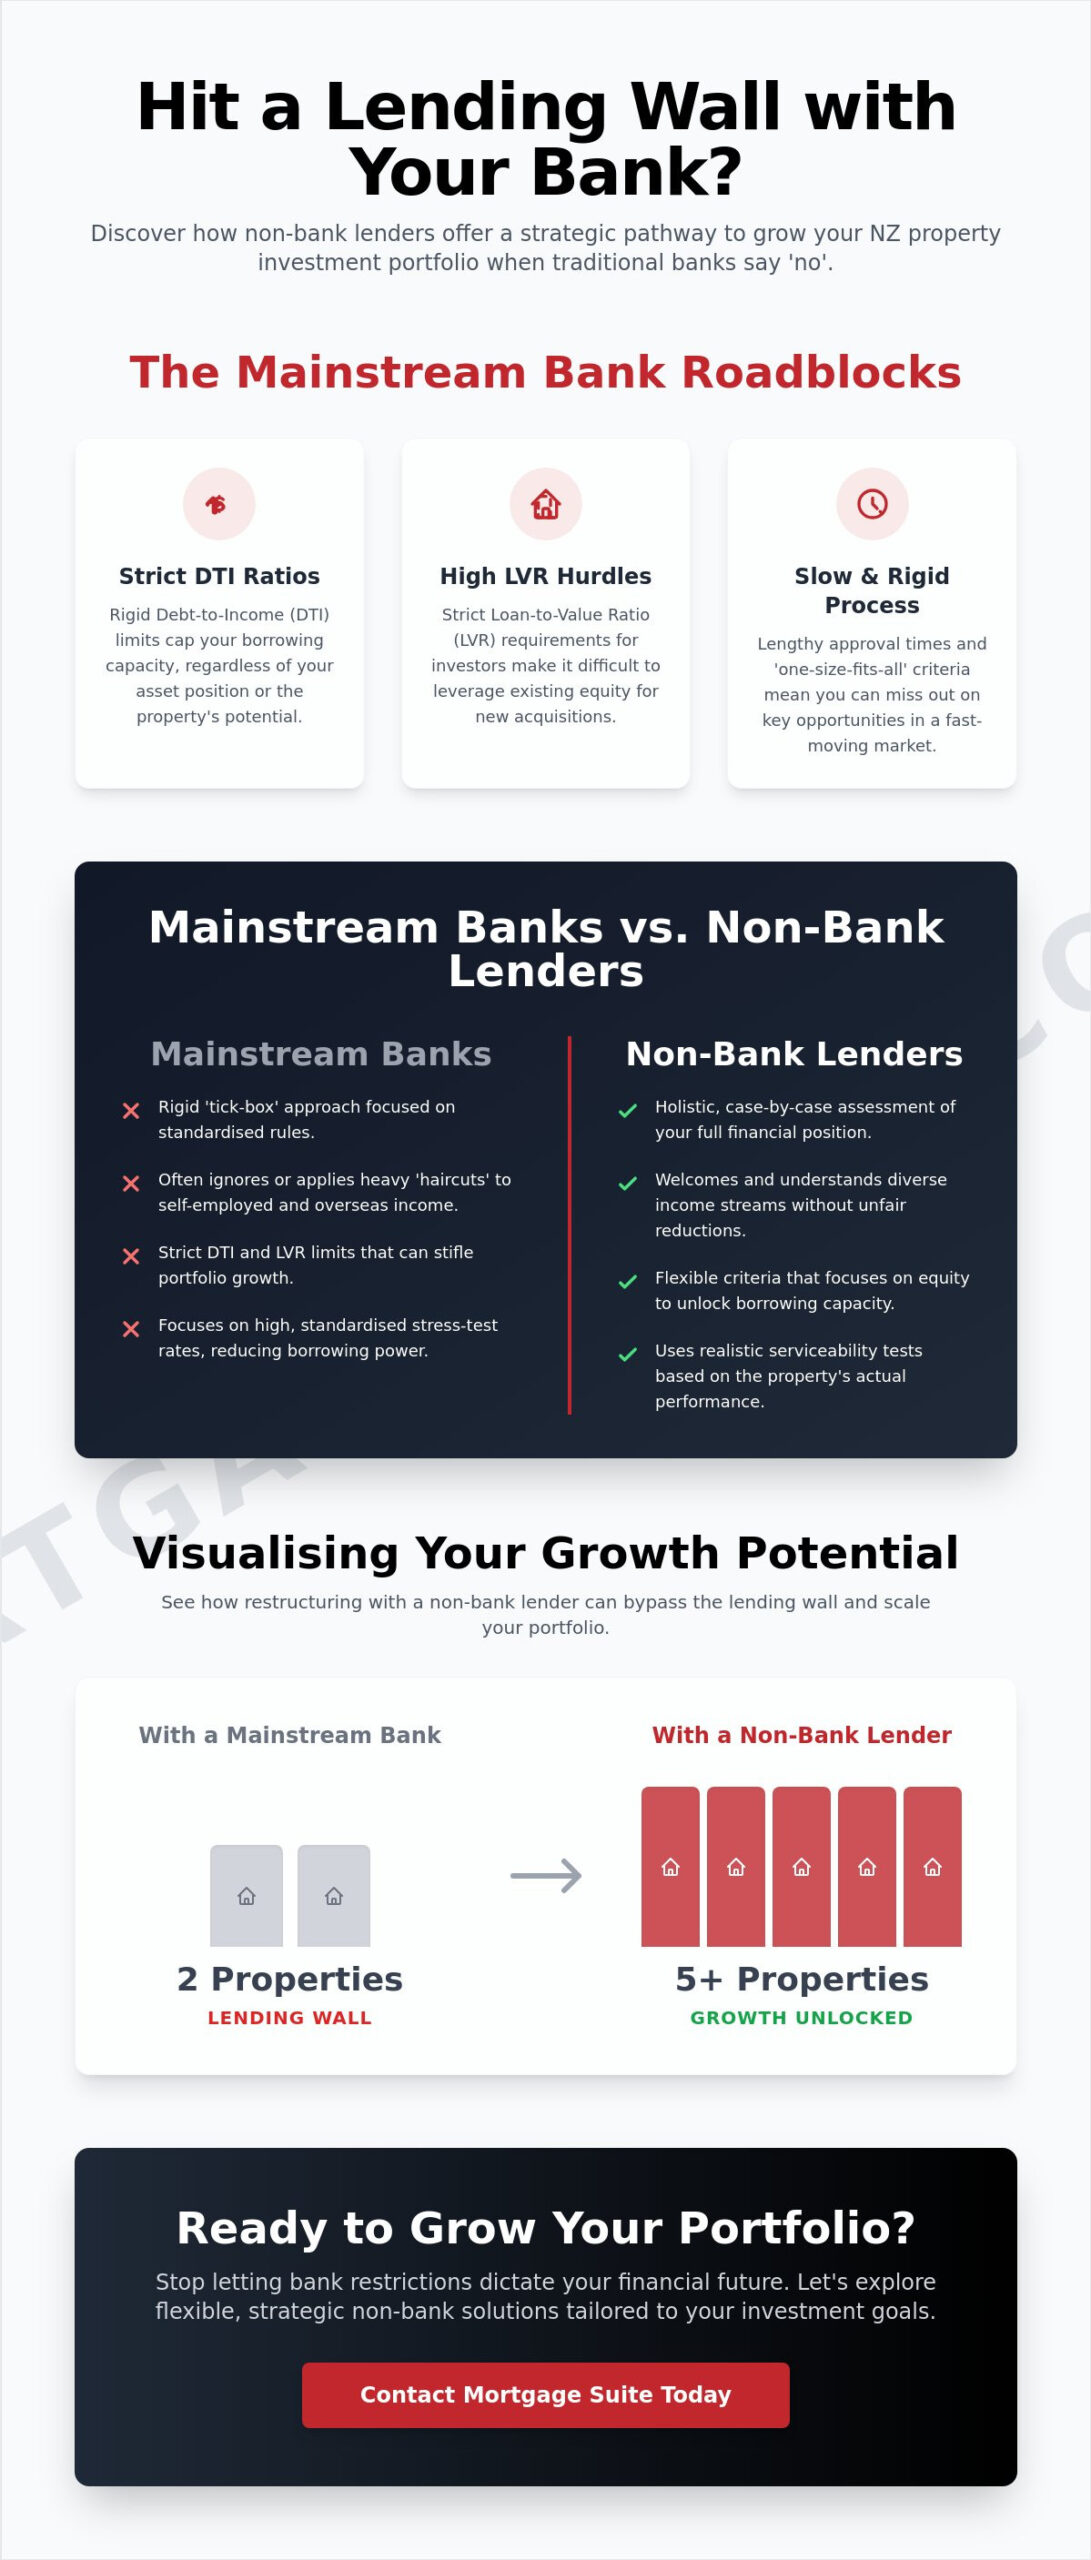
It’s a common story in the current market: you’ve built a solid portfolio, your equity is high, but the ‘Big Four’ banks simply won’t budge. This usually happens because mainstream banks operate with very rigid templates. If your situation is slightly outside the box, perhaps you’re self-employed or have complex income streams, you might find yourself stuck. When you’re financing multiple investment properties nz, hitting a wall with your primary bank doesn’t have to be the end of the road. It’s often just a sign that you need to look beyond the high-street branches to find a lender that prioritises your potential over their paperwork.

The rise of non-bank and 2nd tier lenders has changed the game for New Zealand investors. These lenders often have a more common-sense approach to lending. They’re willing to look at the bigger picture of your portfolio’s performance rather than just ticking boxes. Krish Krishna spent over two decades inside the banking system, and he uses that insider knowledge to negotiate directly with these lenders on your behalf. You can learn more about our approach on our about us page, where we explain how we bridge the gap between rigid bank rules and your personal goals.

When a 2nd Tier Lender Makes Sense

A 2nd tier lender isn’t just a fallback option; it’s a strategic tool. You might find this path useful if your debt-to-income (DTI) ratio is slightly over the current 7x limit set for mainstream banks. It’s also a fantastic solution if you need a short-term ‘bridge’ to get a renovation or a small development project finished before you move to long-term finance. If you’re curious about how these alternatives work, check out our 2nd tier lender New Zealand guide for a deeper look at your options.

The Exit Strategy: Moving Back to the Bank

We rarely suggest using a non-bank lender as a forever home for your loan. Instead, we view it as a stepping stone. The goal is to use the flexibility of a 2nd tier lender to secure your property, then refine your financial profile over 12 to 24 months to become ‘bank-ready’ again. This involves maintaining a clean credit history and organising your income records so that a mainstream bank will eventually welcome you back with open arms. By treating this as a journey, you can keep financing multiple investment properties nz without getting permanently sidelined by a single ‘no’ from a mainstream manager.
Financing Multiple Investment Properties NZ: The 2026 Guide to Portfolio Refinement

A Step-by-Step Guide to Refining Your Portfolio in 2026

Refining your portfolio isn’t a weekend DIY project, but it also shouldn’t feel like a mountain of paperwork. Since the 2026 market involves stricter debt limits and a shifting interest rate cycle, the process for financing multiple investment properties nz requires a methodical approach. It’s about moving from a reactive state to a proactive one. Here is the path we take to get your portfolio back in peak condition.

  • Step 1: The Portfolio Audit. We start by gathering your latest mortgage statements and estimated property values. This shows us exactly where your equity is hiding.
  • Step 2: Goal Setting. Are you prioritising monthly cash flow to offset the 2.75% OCR, or are you chasing aggressive growth? Your goals dictate the structure.
  • Step 3: The Broker Chat. This is where we shop the market for you. We compare mainstream banks against 2nd tier lenders to find the best fit for financing multiple investment properties nz.
  • Step 4: The Application. We help you prep a “financial CV” that highlights your strengths to 2026 lenders.
  • Step 5: The Settlement. We handle the transition to your new, refined structure so you can start seeing the benefits.

Preparing Your Financial Paperwork

Lenders in 2026 are obsessed with the spare cash you have left over each month. This is the money you have left after all your living expenses and debts are paid. Banks now use open banking systems to see your real spending habits directly from your accounts. Because of this, tidying up small personal debts like car loans or credit cards before you apply makes the whole process a piece of cake. It clears the path for your investment loans to take centre stage and shows the bank you’re a disciplined borrower.

Navigating the 2026 Interest Rate Cycle

With the OCR at 2.75% as of September 2026, choosing between fixed and floating rates is a balancing act. Refining your portfolio might mean fixing for shorter periods, such as six or twelve months, to stay agile while the market settles. You can dive deeper into these strategies in our Mortgage Rates NZ 2026 Guide to see how different terms affect your bottom line. If you’re ready to see how these steps apply to your specific properties, we invite you to reach out for a consultative chat with our team.

The Mortgage Suite Difference: Mentorship Over Transactions

Finding a lender for financing multiple investment properties nz is one thing, but building a sustainable financial future is quite another. Most people go to a bank and receive a one-off transaction. They get a loan, a rate, and a thank you. At Mortgage Suite Ltd, we believe that serious investors deserve more than just a signature on a page. We approach our work as mentors, guiding you through the complexities of debt structure to ensure your portfolio doesn’t just grow, but thrives over the long term.

This approach is built on a foundation of deep institutional knowledge. Krish Krishna spent over two decades working inside the banking system, which means he knows exactly how the credit teams on the other side of the desk think. He understands the hidden triggers that cause a mainstream bank to say no and, more importantly, how to present your case so they say yes. We often take on the “hard cases” that other brokers might avoid, using our experience to find solutions for self-employed Kiwis or those with complex income streams that don’t fit a standard bank template.

Real Stories, Real Results

Our success isn’t just measured by the loans we settle, but by the wealth our clients build. We act as your dedicated negotiator, standing between you and the lenders to fight for the best possible terms. If you want to see the impact this personal touch has made, you can read through our client reviews. You’ll see stories of investors who were stuck at a dead end until we helped them refine their path. We don’t just focus on the next purchase; we focus on how that purchase fits into your life five or ten years from now. Our commitment is to provide a conversational, jargon-free experience that leaves you feeling empowered rather than overwhelmed.

Your Next Step to a Better Portfolio

Refining your property loans shouldn’t feel like a chore. With the right guide, it’s actually a piece of cake. Whether you’re feeling the “rate shock” of 2026 or you’re ready to unlock equity for your next big move, we’re here to help you organise your next steps with confidence. We invite you to learn more about us and how we operate nationally across New Zealand. When you’re ready, reach out for a no-obligation chat about your current property setup. Let’s take a look at your numbers together and find a way to make financing multiple investment properties nz work for your unique situation.

Take Charge of Your Property Future

Building a successful portfolio in 2026 requires more than just luck; it requires a debt structure that is built to last. You now understand how a strategic audit can turn stagnant equity into a fresh deposit and why non-bank lenders are a practical way to bypass rigid bank templates. By refining your current setup, you ensure your monthly budget has breathing room while keeping your growth plans on track.

Navigating the path of financing multiple investment properties nz is a piece of cake when you have a seasoned mentor by your side. With over two decades of banking experience and a specialty in complex loan scenarios, we offer national service to help Kiwi investors succeed. We invite you to book a conversational chat with Krish to refine your portfolio today. Let’s work together to unlock your equity and build a structure that gives you total confidence for the next five years. Your next big move is closer than you think.

Frequently Asked Questions

Is it worth refining my investment property loan if interest rates are high?

Yes, it is often more important when rates are high. Refining is about managing your monthly cash flow and yields, not just chasing a low rate. By adjusting your loan terms or switching to interest-only, you can create breathing room in your budget. This strategic approach to financing multiple investment properties nz ensures your portfolio remains sustainable even when market conditions are challenging. It’s about long-term stability rather than short-term fixes.

How much equity do I need to release to buy another investment property in NZ?

To buy an existing investment property, you generally need a 30% deposit, while new builds typically require 20%. You can release this deposit from your current properties by calculating your useable equity. This is the difference between your property’s market value and what you owe, usually capped at a 70% loan-to-value ratio for rentals. Getting a fresh appraisal is the best way to see how much “lazy equity” you can actually put to work.

What is the difference between refinancing and refining a mortgage?

Refinancing is usually a simple transaction, like moving to a new bank for a slightly better interest rate. Refining is a much more thorough process. It involves a full audit of your entire portfolio to ensure your loan terms, lender types, and repayment structures align with your 2026 goals. Refining looks at the big picture of your wealth, whereas refinancing is often just a one-off attempt to save a few dollars each month.

Can I refine my loan if I am self-employed or have a complex income?

Absolutely. We specialise in helping self-employed investors and those with non-standard income streams who don’t fit the rigid templates of mainstream banks. Because Krish has over two decades of banking experience, he knows how to package your application to highlight your strengths. We often use 2nd tier lenders who take a more common-sense approach to complex income, ensuring you can keep growing your portfolio without being held back by paperwork.

How long does the process of refining a property loan typically take?

The timeframe can vary, but you should generally allow between four and six weeks from start to finish. This period includes your initial portfolio audit, getting property appraisals, and comparing different lender options. Once we’ve chosen the best path, the formal application and settlement usually move quite quickly. We manage the entire process for you to ensure it’s a piece of cake and stays on track for your next purchase when financing multiple investment properties nz.

Will I have to pay break fees if I switch lenders mid-term?

You might face break fees if you’re currently in a fixed-rate term and decide to switch lenders. However, we don’t just look at the fee in isolation. We run the numbers to see if the long-term savings or the equity you unlock will outweigh that initial cost. Often, a more flexible structure or a better cash flow position makes paying a small fee now a very smart investment for your future.

What happens if a mainstream bank has already declined my application?

A decline from a mainstream bank is often just a sign that you don’t fit their specific internal rules. It doesn’t mean you can’t get a loan. We specialise in 2nd tier lending and alternative finance for exactly these scenarios. By looking at your portfolio through a different lens, we can often find a lender that is happy to support your goals, even if the “Big Four” have already said no.

How does the Official Cash Rate (OCR) affect my decision to refine now?

The OCR, which sits at 2.75% as of September 2026, directly impacts the interest rates banks offer. When the OCR moves, it’s the perfect time to review your structure. Refining now allows you to hedge your bets by choosing the right mix of fixed and floating terms. This keeps you agile, allowing you to take advantage of future market shifts while protecting your current rental yields from unexpected rate shocks.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

LVR for NZ Investment Property: 2026 Deposit Rules

Most investors see a 30% deposit requirement as a brick wall, but the truth is that the latest rules are more like speed limits that can be navigated with the right guidance. It’s completely normal to feel a bit overwhelmed by the constant talk of 70% limits and those new debt-to-income ratios. Hearing that you might need a massive deposit or that your income might not stretch far enough is enough to make anyone second-guess their next move. Understanding the current LVR for investment property NZ is the first step toward taking back control of your financial future.

We know how frustrating it is to deal with confusing bank talk and the fear of being turned down. You deserve a clear path forward that doesn’t involve jumping through impossible hoops. In this guide, you’ll discover how to navigate the latest 2026 rules and use your existing equity to grow your property portfolio without the usual stress. We’ll look at how new builds can get you in the door with a smaller deposit and show you how a seasoned hand can help you find a way through, even if the big banks have said no.

Key Takeaways

  • Learn why a 30% deposit requirement doesn’t have to stop your plans and how to work around the standard bank limits.
  • Discover why non-bank lenders might be the key to getting your loan approved if the major banks are being too strict.
  • Find out how to put the value in your current home to work so you can grow your portfolio without needing a massive pile of savings.
  • Understand exactly how the 2026 rules for LVR for investment property NZ change what you can borrow and where you should look for a deal.
  • See how expert help can turn a “no” into a “yes” by navigating the complex world of lending rules on your behalf.

Understanding LVR: The “Speed Limit” for Your Investment Journey

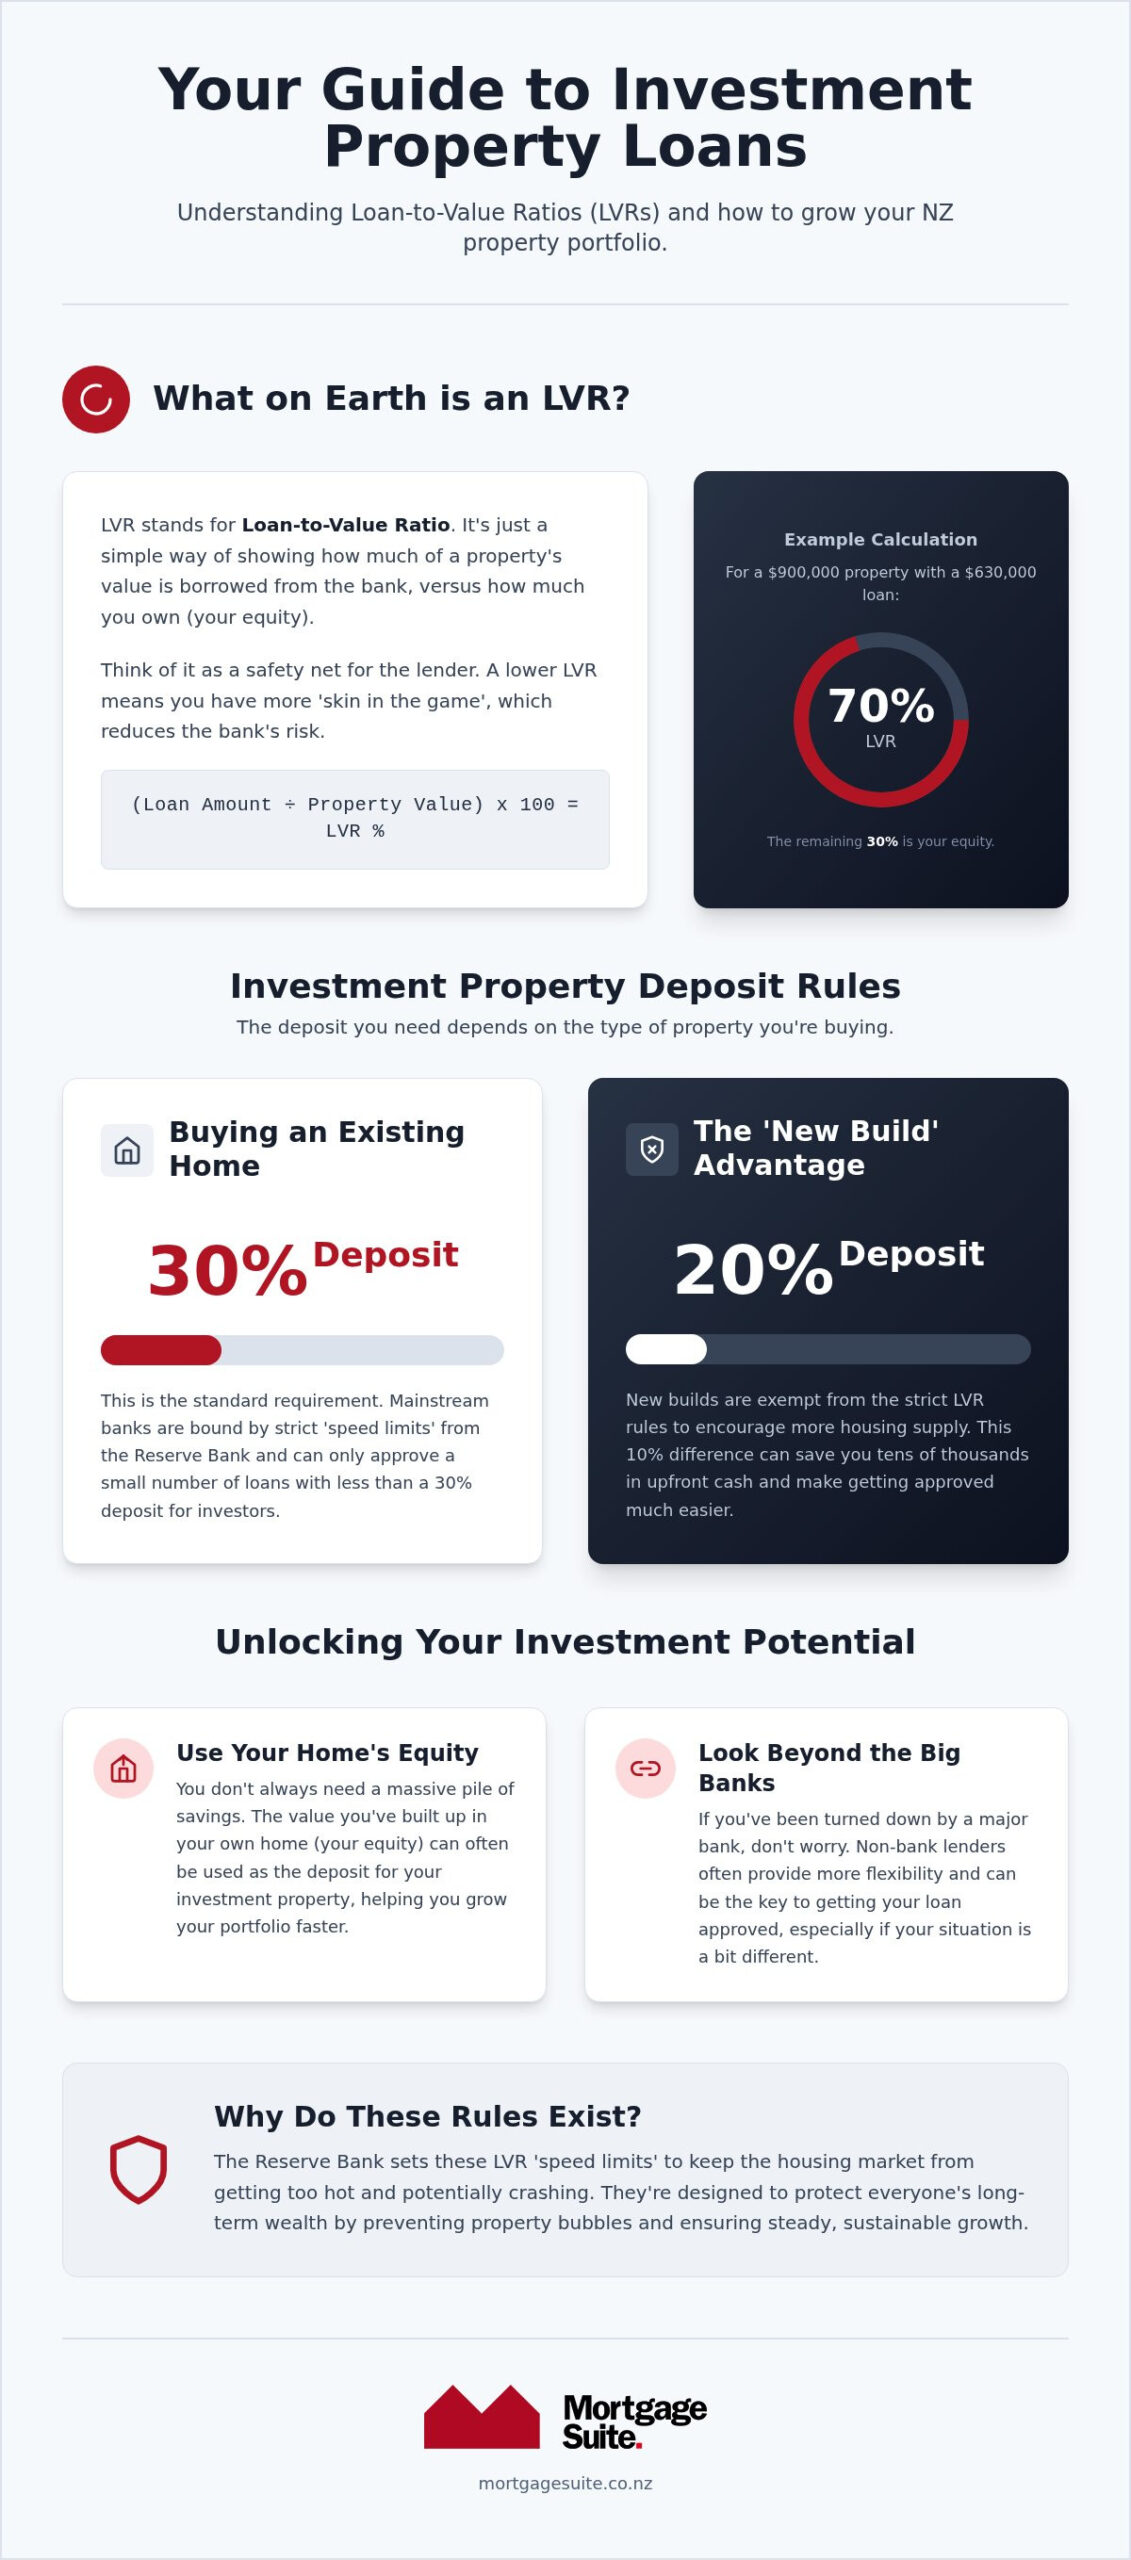
LVR is essentially a measure of how much risk the bank is taking compared to how much skin you have in the game. It stands for Loan-to-Value Ratio; it is just a simple way of saying how much of the property the bank owns versus you. If you have a property worth one million dollars and you owe seven hundred thousand, your LVR is 70%. The remaining 30% is your equity, which acts as a safety net for the lender. Understanding the LVR for investment property NZ is the foundation of building a successful portfolio.

Think of these rules as a speed limit set by the Reserve Bank. Their job is to keep the New Zealand housing market from over-cooking and potentially crashing. When the market gets too hot, the Reserve Bank steps in and tells the commercial banks they need to demand higher deposits. This slows down the flow of money and keeps the economy stable. It might feel like a hurdle when you are trying to buy, but it is actually designed to protect everyone’s long-term wealth. It ensures that the market doesn’t grow faster than people can actually afford.

Investors often face different limits than first-home buyers. This is because banks generally view investment properties as slightly higher risk. If the economy takes a turn, people usually fight harder to keep the roof over their own heads than they do for a rental property. Because of this, the LVR for investment property NZ is typically capped at a lower level, meaning you need a larger deposit to get the green light from a mainstream lender.

How to work out your LVR without a degree in maths

Calculating your position is much simpler than the banks make it sound. LVR is the percentage of a property’s value that is borrowed as debt. To find your number, just use this simple formula: (Loan Amount ÷ Property Value) x 100. For example, if you want to borrow $630,000 for a house valued at $900,000, your LVR is 70%.

In the current market, 70% LVR is the magic number for most Kiwi investors. This means you generally need a 30% deposit for an existing property. While we will chat about exceptions like new builds later on, aiming for that 30% mark puts you in a very strong position with almost any lender. It gives you the best chance of getting an approval quickly.

Why the Reserve Bank keeps changing the rules

The Reserve Bank isn’t trying to be difficult; they are trying to keep the economy on an even keel. By adjusting deposit restrictions, they can control how much debt is floating around the country. In 2026, we have seen a shift toward balancing these deposit rules with new income-to-debt rules. This double-layer of protection ensures that people aren’t just bringing enough cash to the table, but can also actually afford the weekly repayments if interest rates climb.

While these shifting goalposts can be frustrating, they are actually a good thing for property values. They prevent bubbles from forming, which means your investment is more likely to grow steadily over time rather than crashing overnight. Having a steady hand at Mortgage Suite Ltd to guide you through these changes makes all the difference when the rules feel like they are moving under your feet.

The 2026 LVR Landscape for NZ Residential Investors

The lending environment for 2026 is quite clear. If you are looking at an existing property, you will generally need to bring a 30% deposit to the table. This is the current standard for the LVR for investment property NZ as set by the Reserve Bank. It might feel like a high bar, but it is the reality most investors are working with right now. Even if you have a great income and a clean credit history, the banks are bound by these rules to ensure the market stays stable.

The 30% deposit hurdle for existing homes

Existing homes are often viewed as a higher risk because they don’t help solve the housing shortage. Banks are restricted by a “speed limit” which only allows about 10% of their new lending to go to investors with less than a 30% deposit. This creates a bit of a bank lottery. If you only have a 20% deposit, your chances depend on whether the bank has already used up its monthly quota for high-limit loans. If they have, you will likely be declined regardless of how good your application looks. It isn’t necessarily a reflection of your financial health; it is just a matter of timing and regulation.

The “New Build” loophole: Buying with just 20%

There is a clever way to get around the 30% rule. Buying a brand-new property is currently exempt from these strict LVR limits. The government wants to encourage more housing supply, so they allow investors to buy new builds with a lower deposit, typically 20%. This 10% difference can save you tens of thousands of dollars in upfront cash. Under the 2026 rules, new construction is exempt because it adds to the total number of homes available in New Zealand. It is a fantastic option for those who want to enter the market sooner rather than later without waiting to save a massive deposit.

If you already own a home, these rules still apply, but you might not need to save a pile of cash. You can often use the equity built up in your current house to cover that 30% requirement. This involves using the value of your own home as security for the new loan. It is a smart way to grow your portfolio without draining your bank account. You can use a mortgage calculator to see how much you might be able to borrow based on your current position. Understanding these nuances is exactly where a steady hand can help you find the right path forward.

Banks vs. Non-Bank Lenders: Finding the Flexibility You Need

Mainstream banks are like the strict teachers of the financial world. They have to follow the Reserve Bank’s rulebook exactly, which means they have very little room to move. If you don’t have that 30% deposit for an existing rental, they often can’t help you even if they wanted to. Non-bank lenders, or 2nd tier lenders, are different. They don’t have the same rigid shackles, which gives them the freedom to offer a “fair go” to investors who are doing well but don’t fit the standard bank mould. For many Kiwis, these alternative lenders are the key to breaking through the usual barriers.

When the bank says “no,” we look for a “yes”

It’s common to feel stuck when a big bank declines your application because of the strict LVR for investment property NZ limits or the new income-to-debt limits. Banks love a simple life; they want borrowers with a standard salary and a massive deposit. If your income comes from a business, commissions, or if you are simply bumping up against those new rules that cap how much you can borrow based on your earnings, the big banks might look the other way. Non-bank lenders take a more human approach. They look at the whole picture of what you own and what you earn rather than just scanning a checklist. While the interest rates might be a little higher, the flexibility they offer can be the difference between buying a property now or waiting years for the rules to change.

The non-bank advantage for portfolio growth

Many successful investors use a 2nd tier lender New Zealand as a strategic stepping stone. Instead of letting your growth stall because a bank won’t budge on their deposit rules, you can use a non-bank lender to secure the property and get your foot in the door. As your property value grows and you pay down the loan, your position improves. Once you meet the standard bank criteria, the team at Mortgage Suite Ltd can help you move that loan back to a mainstream bank to take advantage of lower rates. This path keeps your momentum going and ensures you aren’t left behind while the market continues to move. It’s about using the right tool for the right stage of your journey.

LVR for NZ Investment Property: 2026 Deposit Rules

Using Your Home Equity to Smash LVR Barriers

Many people believe they need to spend years saving a massive pile of cash before they can even think about buying a rental. In reality, your current home is likely your biggest financial asset, and it can do the heavy lifting for you. By tapping into the value already sitting in your house, you can often cover the deposit for a new purchase without touching your savings account. This is a common strategy when navigating the LVR for investment property NZ, as it allows you to use paper wealth to build real-world results.

It is vital to understand the difference between your total equity and your usable equity. While your total equity is the full value of your home minus what you owe, banks won’t let you borrow against every single dollar of it. They want a buffer to protect themselves. If you are looking for Residential Investment Property Loans NZ, knowing exactly how much you can actually touch is the first step in planning your next move.

Step-by-step: Calculating your usable equity

Calculating your position doesn’t have to be complicated. Follow these steps to see where you stand:

  • Step 1: Get an up-to-date valuation of your current home. Market prices change, so don’t rely on an old estimate.
  • Step 2: Calculate 80% of that value. This is the maximum amount most mainstream banks are willing to lend against your primary residence.
  • Step 3: Subtract your existing mortgage from that 80% figure.
  • Step 4: The leftover amount is your “usable equity.” This is the fund you can use as a deposit for your investment.

The trap of linking all your properties to one bank

One mistake many investors make is using one bank for everything and linking all their properties together. While it might seem convenient, it gives the bank a lot of power over your assets. If one property runs into trouble, the bank could potentially look at your family home to settle the debt. It also makes it much harder to sell one property without the bank demanding you pay down the loans on the others. This can severely limit your options when the LVR for investment property NZ rules change.

To keep your family home safe while growing your rentals, it is often better to use different lenders for different properties. This creates a “firewall” between your home and your investments. If you want to see how this strategy fits your specific goals, you can talk to the team at Mortgage Suite Ltd today for a personalised plan. Having a steady hand to manage these moving parts ensures you can grow your wealth without putting your most important asset at risk.

Trying to find the best way forward on your own often leads to missed opportunities or paying much more than you need to. The lending market is a bit of a maze, especially with the 2026 rules making things more complex for everyone. Having a veteran like Krish Krishna and the team at Mortgage Suite Ltd in your corner changes the game entirely. We take the weight off your shoulders by organising the paperwork and negotiating directly with lenders so you don’t have to. You shouldn’t have to spend your weekends stressed about bank criteria when you could be out looking for your next property. Ready to see what is possible? You can check out our mortgage calculator to start running the numbers on your next investment.

Why a seasoned broker beats a bank manager

A bank manager is naturally limited by what their specific employer allows. They can only sell you one brand, even if that brand’s current policy isn’t the best fit for your specific goals. At Mortgage Suite Ltd, we work differently because we have access to the whole market, from the big names to the flexible 2nd tier lenders we discussed earlier. Our team brings over 20 years of experience to the table, which means we have seen every type of rule change and market shift you can imagine. We know the shortcuts and the specific lender appetites that banks won’t tell you about.

This longevity in the industry means we aren’t just looking for a one-off transaction. We focus on building long-term partnerships that help you grow your portfolio year after year. We understand how a decision today affects your ability to borrow two or three years down the track. By managing the LVR for investment property NZ strategically across different lenders, we ensure you stay in the driver’s seat of your financial future.

Your next steps to property success

The first step is always a simple, jargon-free chat about where you are right now and where you want to go. We will help you get a clear handle on your position regarding the LVR for investment property NZ and your debt-to-income limits before you even start talking to a vendor. This preparation puts you in a much stronger position to negotiate because you’ll know exactly what you can afford and which lenders are likely to say yes. It removes the guesswork and the fear of being declined at the last minute.

If you want to keep learning at your own pace, our Mortgage School articles are packed with tips and insights to help you stay ahead of the curve. We believe that an informed investor is a successful one. Whether you are looking to buy your first rental or your tenth, having Mortgage Suite Ltd to guide you through the process makes all the difference. Being declined by a big bank isn’t the end of the road; it is often just the beginning of a much better, more personalised strategy.

Take the Next Step Toward Your Property Goals

Building a property portfolio in 2026 requires a smart strategy and a clear understanding of the latest rules. While the standard 30% deposit for existing homes feels like a high bar, we’ve seen how new builds and tapping into your usable equity can provide a much easier path forward. The key is to remember that the LVR for investment property NZ is a guideline for banks, not a brick wall for your ambitions. If the big banks have already used up their monthly lending limits or turned you away, there are still plenty of flexible options available.

With over 20 years of banking and brokerage expertise, Mortgage Suite Ltd specialises in finding the “yes” that the mainstream lenders might have missed. You can read our client reviews to see how we’ve helped Kiwis navigate these hurdles and come out on top. You don’t have to tackle this complex market alone. We are here to act as your steady hand and advocate every step of the way. If you’re ready to see what’s actually possible for your situation, book a jargon-free chat with the Mortgage Suite Ltd team today. Your next investment is closer than you think.

Frequently Asked Questions

What is the current LVR for investment property in NZ for 2026?

The current standard LVR for investment property NZ is 70% for existing houses, which means you will usually need a 30% deposit. This rule was confirmed by the Reserve Bank in their August 2026 review to help keep the housing market stable. However, if you are buying a brand-new home, the limit is generally 80%. This allows you to get started with a smaller 20% deposit while supporting the growth of new housing supply.

Can I buy an investment property with a 20% deposit?

You can certainly buy with a 20% deposit if you choose a new build, as these are exempt from the standard 30% requirement. Another option is to secure one of the high-limit loans that banks are allowed to offer each month under current speed limits. If the main banks say no, non-bank lenders often provide the flexibility needed to approve a 20% deposit loan for strong candidates who don’t fit the standard bank checklist.

What counts as a “new build” for LVR exemptions?

A new build is generally defined as a property that has been completed within the last six months and is bought directly from the developer. The main goal of this exemption is to encourage the construction of more homes across the country. By adding to the total housing supply, you are rewarded with a lower deposit requirement. This makes new builds a very popular choice for investors looking to grow their portfolios with less upfront cash.

How does the Debt-to-Income (DTI) ratio affect my LVR?

DTI ratios act as a second gatekeeper alongside your LVR. While LVR looks at the property’s value, the DTI ratio looks at your total debt compared to your gross annual income. For investors in 2026, the cap is seven times your income. This means even if you have a massive 50% deposit, a bank might still decline your application if your total debt exceeds that seven-times limit. It is about proving you can comfortably handle the repayments.

Can I use my KiwiSaver for an investment property deposit?

No, you cannot use your KiwiSaver funds to buy an investment property. These funds are strictly reserved for purchasing your very first home to live in or for your retirement. While it might be tempting to look at that balance as a potential deposit, you will need to use other sources like cash savings or the equity built up in your current home. We specialise in helping you find those alternative deposit sources to keep your plans moving forward.

What happens if the value of my investment property goes down?

If your property value drops, your LVR will naturally increase because your debt stays the same while the asset’s worth falls. Generally, banks won’t ask you to pay back the difference immediately as long as you keep up with your regular mortgage repayments. The main challenge arises if you want to sell the property or refinance to a different lender. In those cases, a higher LVR might make it harder to get a new deal or move your loan.

Do 2nd tier lenders have different LVR rules than banks?

Yes, 2nd tier lenders operate outside the strict Reserve Bank speed limits that bind the major banks. This means they can often be much more flexible with their deposit requirements and how they view your income. While they still want to see a solid plan, they are often a great solution for investors who have plenty of equity but don’t quite fit the rigid 2026 bank criteria. They look at the whole picture of your financial life rather than just a checklist.

Is it better to have a higher or lower LVR?

It depends on your personal goals. A lower LVR is generally safer and often gives you access to the very best interest rates because the bank sees you as a low-risk borrower. On the other hand, a higher LVR allows you to control a more expensive asset with less of your own cash. This can lead to faster portfolio growth if property values rise, but it also means your weekly repayments will be higher and you will have less of a safety net.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Best NZ Investment Property Mortgage Rates: 2026 Guide

What if the bank offering you the lowest headline rate is actually the one most likely to stall your portfolio’s growth? It’s easy to feel overwhelmed by the constant stream of conflicting offers, especially when you’re also trying to figure out how the current Debt-to-Income (DTI) rules, capped at seven times your income for investors, affect your borrowing power. You probably feel frustrated when mainstream banks say no, even when you know your strategy is solid. Finding the best mortgage rates for investment property nz should be about more than just a lucky number; it’s about securing your financial future.

We agree that the current market feels like a maze of shifting regulations and “special” offers that don’t always apply to your specific situation. We’ll show you how to look past the flashy headlines to find an investment loan that actually helps you build wealth in today’s New Zealand market. In this 2026 guide, we’ll explore how to keep your property cash-flow positive, how to structure your loan to save on tax now that interest is fully deductible, and how to finally get that “yes” from a lender who understands your long-term goals.

Key Takeaways

  • Learn why the lowest advertised interest rate isn’t always the smartest choice for the long-term health of your property portfolio.
  • Understand how the latest Debt-to-Income limits and your deposit size directly influence the specific offers you’ll receive from lenders.
  • Discover how to secure the best mortgage rates for investment property nz by focusing on a loan structure that keeps your cash flow positive.
  • Master the art of “grooming” your bank statements months in advance to make your application look far more attractive to banks.
  • Find out how a professional partner can negotiate better terms on your behalf and take the stress out of the application process.

Finding the best mortgage rates for your NZ investment property in 2026

Let’s be honest: the NZ property market has seen a fair bit of change lately. We’ve moved through the highs of the New Zealand property bubble into a more calculated and cautious era. For anyone hunting for the best mortgage rates for investment property nz, the game has shifted significantly. It’s no longer just about which bank has the flashiest billboard or the most aggressive marketing campaign. Banks now look at investors through a much sharper lens than they do owner-occupiers. They view investment properties as higher risk because, if things go pear-shaped, people usually fight harder to keep the roof over their kids’ heads than they do for a rental property. This perceived risk is why investment rates often come with stricter equity requirements or slightly different pricing structures than a standard home loan.

Why ‘cheap’ isn’t always ‘best’

It’s incredibly tempting to grab the lowest number you see on a comparison website. However, that “cheap” rate often comes with strings attached that can trip you up later. You might find yourself locked into a contract with massive break fees or a total lack of offset facilities that could have saved you more in the long run. If you plan to renovate or sell the property in the next eighteen months, a rigid, low-rate fixed term could actually end up costing you thousands more than a slightly higher, more flexible option. Loan value is the total cost of ownership over the entire life of the debt, accounting for every fee and the price of lost flexibility. Don’t let a small saving today lead to a massive bill tomorrow when your circumstances change.

The 2026 New Zealand lending landscape

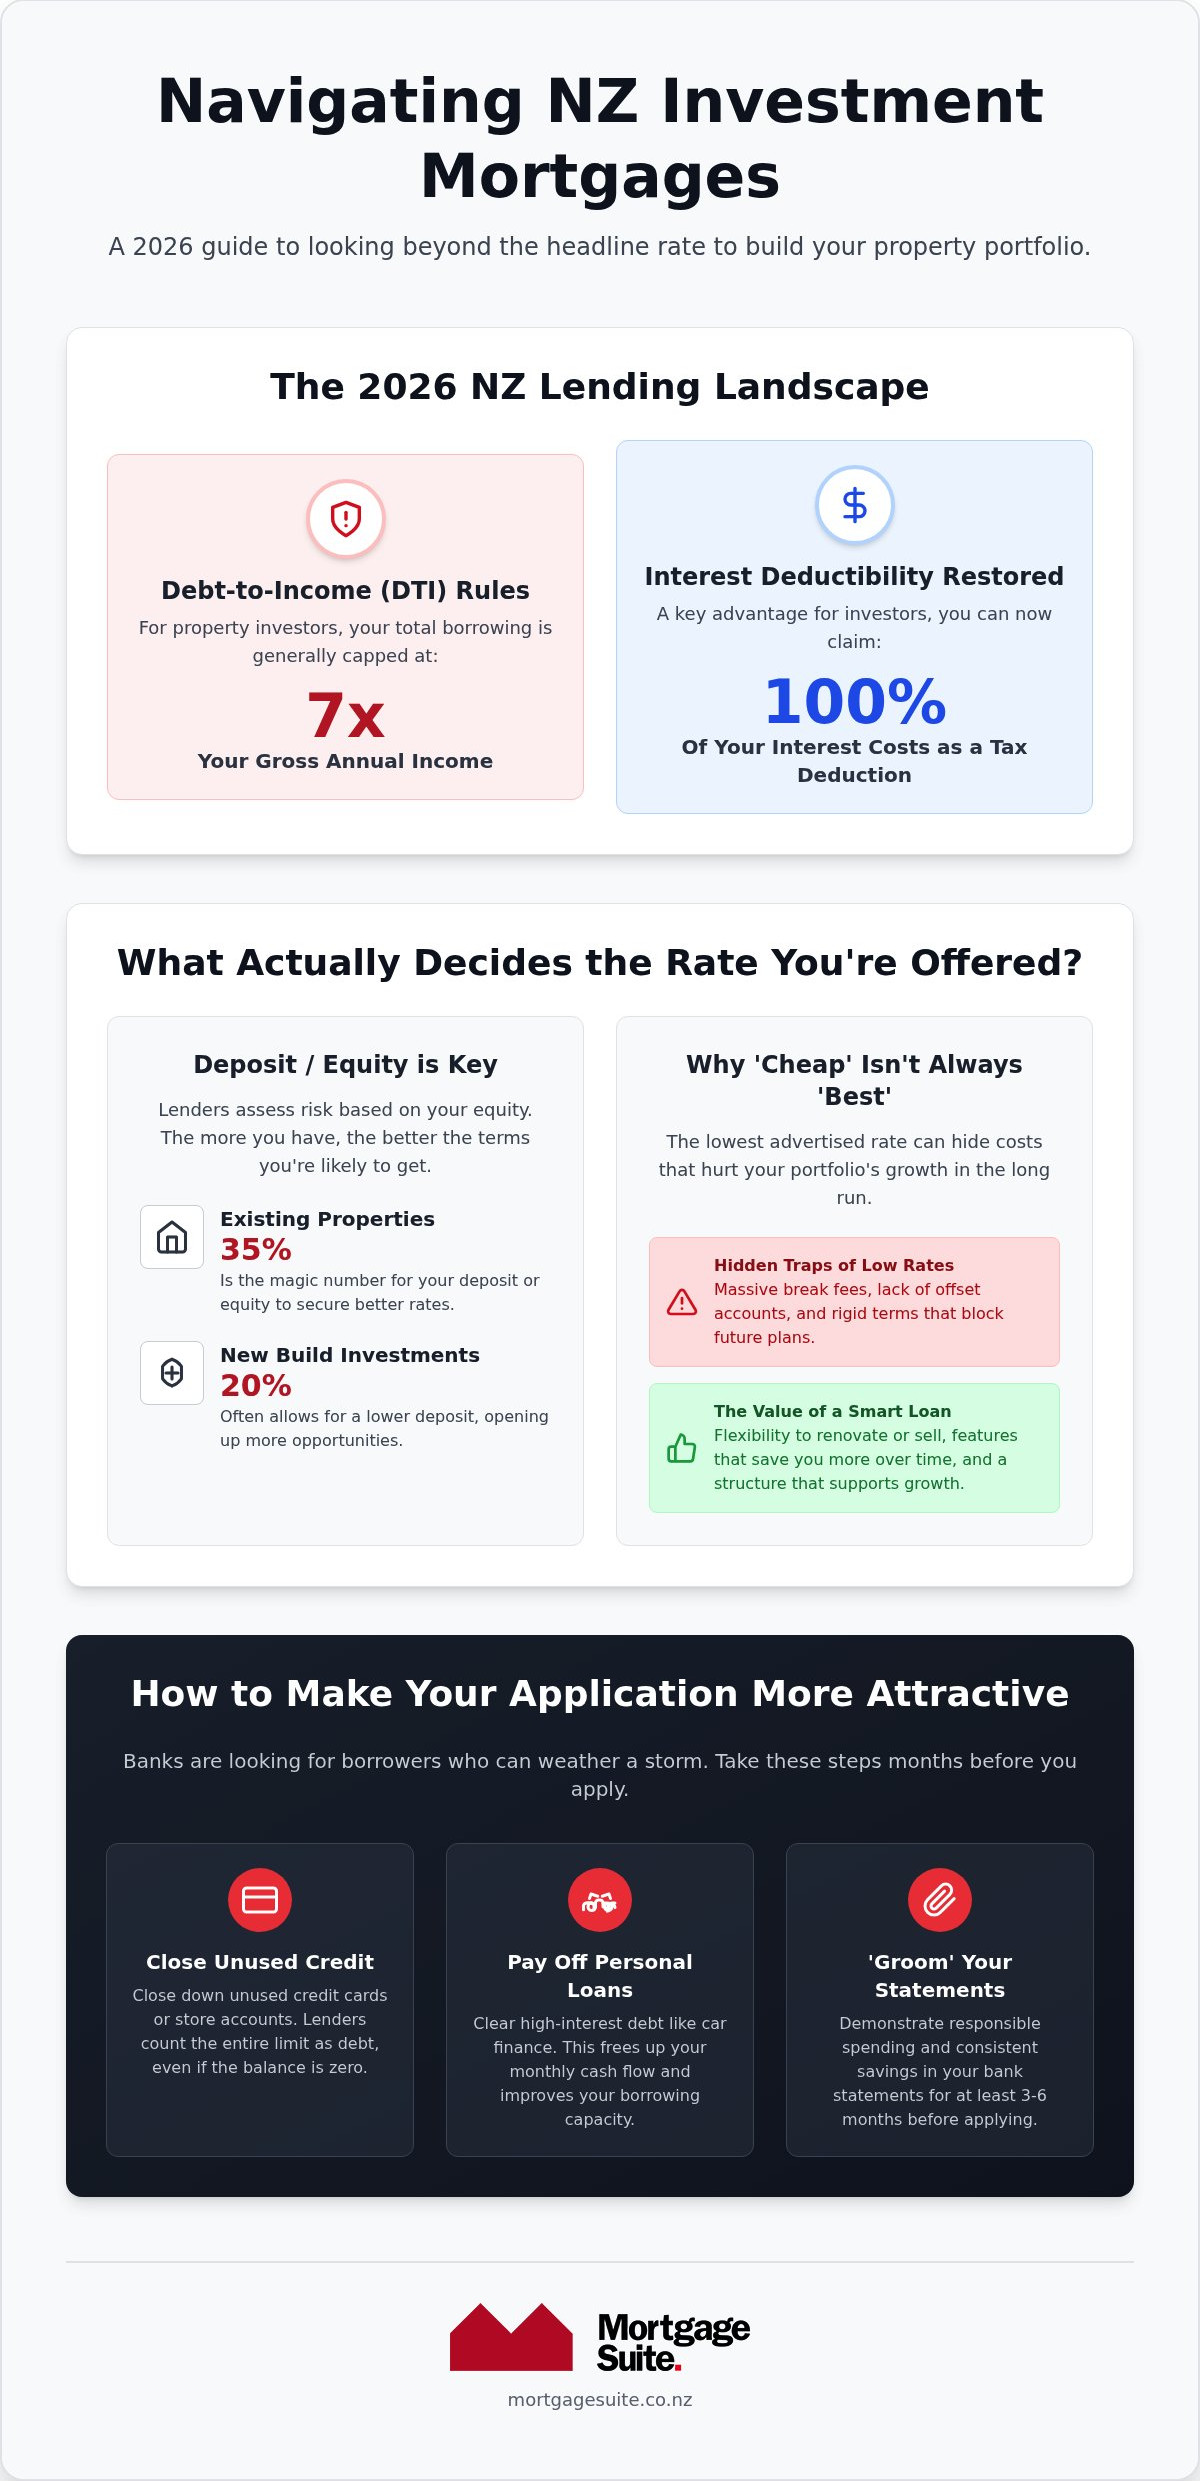
In 2026, the lending climate is defined by a renewed focus on stability. While interest deductibility is now fully back at 100 percent, the Reserve Bank’s Debt-to-Income (DTI) rules mean your income is under the microscope like never before. For investors, this limit is generally capped at seven times your annual income. The Official Cash Rate (OCR) continues to dictate what hits your hip pocket each month, making it vital to understand the mechanics behind these shifts. You can find a more detailed breakdown of these interest drivers in our guide to mortgage rates nz. Banks are being choosy because they have to be. They aren’t just looking for a 35 percent deposit on existing properties; they’re looking for a borrower who can weather a storm without missing a beat. Securing the best mortgage rates for investment property nz now requires a strategy that balances these regulatory hurdles with your personal financial goals.

What actually decides the rate you’re offered?

Lenders don’t just have one set rate that they hand out to everyone who walks through the door. Instead, they use their own ways of calculating how safe a loan is to decide how much they’ll charge you. Your personal financial health acts as a blueprint for the interest rate you’ll eventually pay. While you might be looking for the best mortgage rates for investment property nz, the bank is looking at how likely you are to pay them back without a struggle. Your ability to show you can afford the repayments is now often more important than the actual house you’re buying. If the bank’s stress test suggests you’d struggle if rates rose by another 2 percent, they’ll either decline the loan or offer less attractive terms.

Understanding LVR and DTI in 2026

The factors that dictate your offer are your deposit size and your debt levels. For most existing investment properties in New Zealand, 35 percent equity is the magic number. If you have less than this, you’ll likely face higher interest costs or extra fees. You can find more details on these requirements in the official government guide to buying property.

The Debt-to-Income rules are the real game-changers for 2026. For investors, the limit is generally seven times your annual gross income. If you own several properties, this calculation includes the debt on every single one of them. To improve your position before you apply, consider these steps:

  • Close down unused credit cards or store limits. Banks count the full limit as debt even if you owe nothing.
  • Pay off high-interest car finance to free up your monthly cash flow.
  • Look into a new build investment, which often allows for a lower 20 percent deposit and different rules.

Mainstream banks vs. 2nd tier lenders

If a mainstream bank says no because your situation is a bit different, don’t worry. Mainstream banks love simple applications with a standard salary or wages. However, if you’re self-employed or have a more complex setup, a 2nd tier lender New Zealand might be a better fit. These alternative lenders are often more flexible with how they look at your money. For example, while a big bank might only count 75 percent of your rental income toward your ability to pay, an alternative lender might count the full 100 percent. This can be the difference between getting the green light or being stuck on the sidelines. If you’re unsure where you fit, reaching out to the team at Mortgage Suite Ltd can help you find the right path forward without the stress of multiple bank declines.

Comparing your options: Fixed, floating, and interest-only

Choosing the right structure for your loan is where the real money is made or lost in property investing. While everyone wants the absolute lowest number, the best mortgage rates for investment property nz are only as good as the flexibility they offer your portfolio. In a 2026 market where rates have shown some volatility, locking in a fixed rate provides a much-needed shield of certainty. For example, several major banks are currently offering one-year fixed terms around the 4.75 percent to 4.99 percent mark for those with enough equity. This allows you to forecast your expenses with precision, knowing exactly what your outgoings will be for the next twelve months regardless of what happens in the global economy.

Floating rates usually sit higher, often between 6.04 percent and 6.64 percent, but they serve a specific purpose. They’re perfect for investors who expect a lump sum of cash or want the freedom to make extra repayments without facing heavy fees for breaking a contract. If you’re looking for a balance between stability and freedom, interest-only terms can be a powerful tool. By only paying the interest, you lower your monthly commitment, which can be essential for keeping your rental income higher than your expenses while you’re growing your assets.

Fixed vs. Floating: Which way should you jump?

Many successful investors choose to split their loans into different fixed terms. You might put half on a one-year fixed rate and the other half on a two-year term. This strategy of staggering your loan end dates ensures that your entire debt doesn’t come up for renewal at the same time, protecting you from a sudden spike in market rates. Rate locking is simply the process of securing a specific interest rate for a set period so that your repayments stay the same even if market rates climb. Having a small floating portion is also a smart move if you want to use an offset account. This allows your rental income or personal savings to reduce the debt the bank charges interest on, meaning you only pay for the difference, which can save you thousands over the life of the loan.

The power of interest-only terms

Interest-only is often called the investor’s secret weapon because it helps your monthly cash flow. Since mortgage interest is now 100 percent deductible for tax purposes, many investors prefer to keep their debt levels higher on their rentals while using their spare cash to pay down the debt on their own family home. However, you need to be aware of the “sunset” period. This is the point where your interest-only term ends and the loan changes so you have to start paying back both the interest and the original amount borrowed. When this happens, your monthly costs can jump significantly. It’s vital to plan for this change well in advance. For a deeper look at how to manage these terms, check out our guide on residential investment property loans NZ. Securing the best mortgage rates for investment property nz is only the first step; the real success comes from a setup that supports your long-term growth.

Best NZ Investment Property Mortgage Rates: 2026 Guide

How to snag a better deal than the advertised rates

Reckon the rate on the website is the final word? Think again. Most banks treat those advertised numbers as a starting point for negotiation, especially for investors with a solid track record. To secure the best mortgage rates for investment property nz, you need to present an application that’s so clean the bank’s credit team can’t find a reason to say no. This process is often called “grooming” your accounts. For at least six months before you apply, you want your bank statements to show disciplined spending and consistent savings. It’s about making the bank’s job easy so they see you as a low-risk partner rather than just another file on their desk.

Step-by-step: Preparing your application

Getting your financial house in order before you approach a lender is essential. It’s not just about what you earn, but how you manage what you have. Follow these steps to make your application stand out:

  • Step 1: Minimise your ‘uncommitted’ credit. Banks look at the total limit on your credit cards and store accounts, not just what you owe. If you have a $15,000 limit but only use $500, they still factor in that full $15,000 as potential debt. Closing these unused accounts can instantly boost your borrowing power.
  • Step 2: Consolidate your debts. If you have a car loan and a separate personal loan, rolling them together can show better servicing ability by reducing your total monthly outgoings and simplifying your financial profile.
  • Step 3: Organise your rental appraisals and tax records early. Having your paperwork ready to go shows you’re a professional who knows the market. This builds trust with the lender from day one and ensures there are no dramas during the approval process.

The ‘Broker Advantage’ in rate negotiations

This is where having a veteran negotiator in your corner changes the game. We don’t just send an application to one bank and hope for the best. Instead, we pit the banks against each other to see who blinks first. Our 20 plus years of experience in the New Zealand market means we know which buttons to push and which lenders are currently hungry for investment business. Sometimes the absolute best mortgage rates for investment property nz aren’t with the big four, but with smaller lenders you might never have heard of.

We handle the hard yakka of the paperwork and the back and forth negotiation, ensuring you get a “yes” that actually helps you build wealth. We’ve seen every market cycle since 2000 and know how to navigate this one to your advantage. If you’re ready to see what’s possible beyond the standard bank offers, talk to our team of expert mortgage brokers today and let us do the heavy lifting for you.

Why Mortgage Suite makes the hard yakka easy

Finding the best mortgage rates for investment property nz shouldn’t feel like a second job. We know that the paperwork, the constant emails, and the worry about whether you’re getting a fair deal can be exhausting. That’s why we’ve built a service that takes the weight off your shoulders. We’ve seen every market cycle since 2000, from the boom times to the more challenging years. We know how to navigate the current 2026 landscape because we’ve been here before. Our approach isn’t about a quick transaction; it’s about building a long-term partnership where we help you grow your wealth property by property. We handle the tricky bits so you can focus on finding your next great investment.

We understand that every investor’s situation is unique, and we take the time to listen before we act. This isn’t just about a one-off loan; it’s about having a steady hand to guide you through the fluctuating New Zealand market. We speak plain English, not bank-talk. Our goal is to give you straightforward advice that gets results, ensuring there are no dramas along the way. Whether you’re looking for your very first rental or you’re a seasoned pro with a massive portfolio, we have the expertise to help you move forward with confidence.

Meet Krish and the team

Krish Krishna leads the team with over two decades of banking experience. This deep understanding of how banks operate is your secret weapon for securing the best mortgage rates for investment property nz. Because Krish has sat on the other side of the desk, he knows exactly how banks think and what they need to see to say “yes.” We’ve earned a reputation as dedicated negotiators who won’t take no for an answer. If a mainstream bank turns you down, we don’t just give up. We look at alternative options, including 2nd tier loans, to find a way forward that keeps your investment goals on track. We offer a national service across New Zealand, so no matter where your next property is, we’re here to help.

Ready to get your investment sorted?

Getting started is as easy as a quick, no-obligation chat. In our first conversation, we won’t just talk about numbers. We’ll talk about your strategy, your timeline, and what you’re hoping to achieve. It’s a consultative process designed to make you feel supported and confident. We’ll answer your questions, clear up any confusion about the current rules, and start mapping out a plan that works for you. There’s no pressure and no complex jargon; just professional guidance from people who genuinely care about your success. Let’s find the best rate for your investment property together and get your portfolio moving in the right direction.

Secure your property future today

Building a profitable property portfolio in 2026 requires more than just picking the lowest number on a bank’s website. Success comes from looking beyond the headline interest rate to find a structure that truly supports your specific goals. Whether that means using interest-only terms to maximise your cash flow or carefully grooming your accounts to impress a lender, a proactive strategy is your best asset. Finding the best mortgage rates for investment property nz is a journey that involves strategic positioning and expert negotiation.

Accessing both mainstream and 2nd tier lenders is much simpler when you have a partner who understands the nuances of complex investor portfolios. With 20+ years of industry experience, we handle the hard yakka and the paperwork to ensure the process is no dramas for you. We’ll do the heavy lifting. Book a free chat with our investment loan experts today and let’s get your next move sorted. You’ve done the research; now it’s time to take the next step toward building your wealth with confidence.

Frequently Asked Questions

What is the average interest rate for an investment property in NZ right now?

As of August 2026, one-year fixed rates for investment properties generally sit between 4.75 percent and 4.99 percent among the major banks. Variable or floating rates are significantly higher, often ranging from 6.04 percent to 6.64 percent. These figures change frequently based on wholesale funding costs, so it is always best to check the latest offers before making a final decision on your loan structure.

Can I use the equity in my own home to buy an investment property?

Yes, you can certainly use the equity built up in your family home to fund the deposit for an investment property. This is a common strategy for Kiwi investors to avoid using their own cash. By re-mortgaging a portion of your home’s value, you can create the 35 percent deposit required for an existing rental property without needing to save for years.

Do investment properties always have higher interest rates than home loans?

Investment properties do often have slightly higher rates because banks reserve their “special” discounts for owner-occupiers with at least 20 percent equity. While the base rates might look similar, investors sometimes face additional margins or fewer fee waivers. Securing the best mortgage rates for investment property nz requires looking past standard home loan advertisements to find products specifically designed for rental portfolios.

How much deposit do I really need for an investment property in 2026?

In 2026, you generally need a 35 percent deposit for an existing residential investment property. This means you can borrow up to 65 percent of the property’s value. However, if you are looking at a new build, the rules are often more relaxed, usually requiring only a 20 percent deposit. These limits are set by the Reserve Bank to manage risk in the housing market.

What happens if my bank declines my investment loan application?

If a mainstream bank declines your application, you still have several options through 2nd tier or alternative lenders. These lenders often have more flexible criteria and might look more favourably on self-employed income or complex financial situations. While their interest rates can be slightly higher, they provide a vital bridge for investors who don’t fit the rigid boxes of the major institutional banks.

Is it better to fix my investment loan for one year or five years?

Most investors in the current 2026 market are choosing shorter terms like one or two years to maintain flexibility. Fixing for five years provides long-term certainty but can be risky if market rates drop significantly during that time. A shorter term allows you to review your strategy more frequently and adjust your portfolio as the economy shifts or your personal circumstances change.

How do the new DTI rules affect my ability to get a good rate?

The Debt-to-Income (DTI) rules limit your total borrowing to seven times your annual gross income for investment purposes. This means that even if you have a massive deposit, your income might prevent you from getting the best mortgage rates for investment property nz if your total debt is too high. It forces a focus on your actual ability to pay the loan back comfortably.

Can a mortgage broker really get a better rate than I can get myself?

A mortgage broker can often secure a better deal because they have the power to negotiate with multiple lenders simultaneously. We know which banks are currently under quota and more likely to offer a discount to win your business. Beyond just the interest rate, we also negotiate for better terms and cash-back offers that you might not get by walking into a branch yourself.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Residential Investment Property Loans NZ: The 2026 Investor’s Reference Guide

What if a “no” from your bank was actually the best thing that could happen to your property portfolio? Many Kiwi investors feel stuck right now, watching great opportunities pass them by because securing residential investment property loans NZ feels harder than ever. It’s incredibly frustrating when you know you have the equity to grow, but the calculations on a bank’s spreadsheet just won’t budge due to strict LVR restrictions and debt-to-income caps.

We agree that the current market requires more than just a standard application; it requires a genuine strategy. In this guide, we’ll show you how to navigate the 2026 lending landscape with confidence and professional insight. You’ll learn how to unlock your existing equity to fund your next purchase, even when mainstream banks say no, and how to structure your debt to make the most of the 100% interest deductibility rules. We’re going to break down the move toward second-tier lenders and interest-only options that can help you organise your finances to prioritise cash flow and long-term growth.

Key Takeaways

  • Get a clear picture of the 2026 market and why a custom strategy for residential investment property loans NZ is the key to building real wealth.
  • Learn how to work around the 30% deposit hurdle by unlocking the value already sitting in your current property.
  • Explore the flexible options offered by second-tier lenders that often say “yes” when the big banks have too many rules.
  • Discover how to structure your loans with interest-only periods to keep your cash flow healthy and make the most of tax benefits.
  • Understand how an expert advocate can handle the hard work and negotiations to ensure you get the best possible outcome for your portfolio.

Exploring the NZ Residential Investment Landscape in 2026

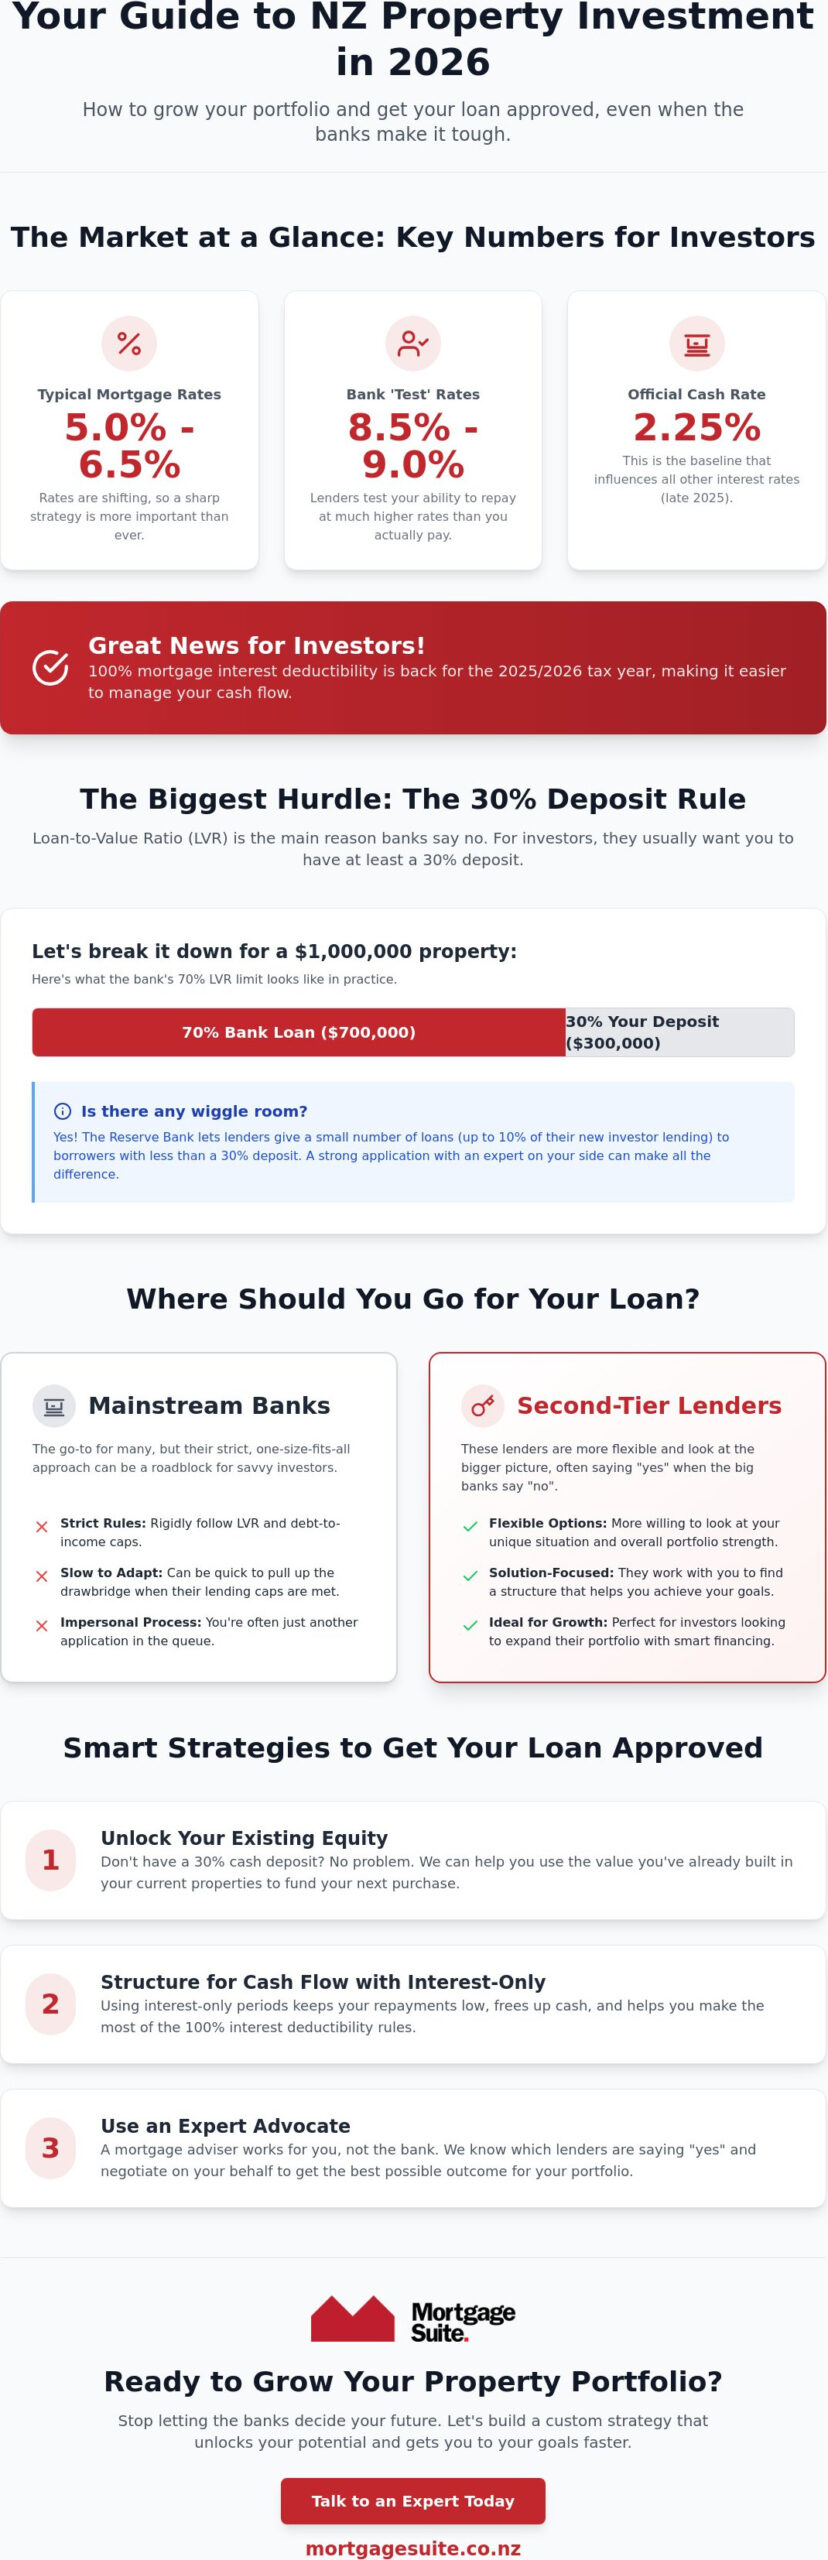
By 2026, the New Zealand property market has found its feet again, but it is certainly not the same game it was five years ago. Investors are now looking at residential investment property loans NZ with a fresh set of eyes. With the Official Cash Rate sitting at 2.25% in late 2025 and mortgage rates hovering between 5% and 6.5% for most of 2026, the “set and forget” mortgage is officially a relic of the past. Banks are constantly tweaking their appetites; one week they are hungry for new business, and the next, they have pulled up the drawbridge based on their internal caps.

The regulatory environment has also shifted significantly. For the 2025/2026 tax year, the return of 100% interest deductibility has breathed new life into the sector. This change makes it much easier to balance the books, especially for seasoned investors looking to expand their portfolios. However, you cannot just rely on the rules being in your favour. Success in this market requires staying ahead of fluctuating interest rates and understanding that bank criteria can change without warning. It is a more active, hands-on era for property owners.

Why Property Still Holds Its Value

Property remains a top choice for Kiwis building long-term wealth because it provides a tangible asset in an uncertain world. While we have seen plenty of headlines about the New Zealand property bubble, the underlying reality is a chronic shortage of quality housing in our major centres. Even when market conditions feel a bit patchy, the long-term capital growth trends across the country have historically rewarded those who stay the course.

  • Capital Gains: Long-term value increases remain a primary driver for wealth building.
  • Rental Yield: In 2026, many investors are prioritising higher yields to help cover bank test rates, which are currently sitting between 8.5% and 9%.
  • Strategic Resilience: A well-chosen rental property provides a steady income stream and a hedge against inflation that other investments struggle to match.

The Role of Professional Advice

This is where having a seasoned pro in your corner makes all the difference. A standard bank manager is often just processing an application, but a long-term mortgage partner is looking at your entire financial future. Talking to a broker is spot on for those wanting to save time and avoid the stress of being declined by a mainstream lender. We know which banks are currently “open for business” for residential investment property loans NZ and which ones have tightened their belts.

We advocate for you to ensure you get a fair go from lenders. This might mean negotiating a discount on advertised rates; mortgage brokers in early 2026 were able to secure average discounts of around 0.13% on 6-month fixed terms. More importantly, we help you navigate the bridge between rigid institutional banking and your personal goals, making sure your loan structure works for you, not just the bank.

Decoding LVR Restrictions and Deposit Requirements for Kiwis

LVR is the percentage of a property’s value that you borrow, acting as a key risk measure for New Zealand lenders. For most people looking at residential investment property loans NZ, this three-letter acronym is the single biggest hurdle between them and their next title deed. While you might have bought your own home with a small deposit, the rules for rentals are historically much tighter. Banks generally view investment properties as slightly higher risk, which is why they ask you to have more skin in the game.

The “30% Rule” has been the standard for some time now. In simple terms, if you want to buy a rental, the bank usually wants you to provide 30% of the purchase price upfront. This ensures that even if the market takes a dip, the bank’s loan is well-covered. However, as of December 2025, there is a bit of breathing room. The Reserve Bank now allows banks to allocate up to 10% of their new investor lending to those with less than a 30% deposit. It isn’t much, but it means a “no” isn’t always final if your overall profile is strong.

How the 70% LVR Limit Works

Getting your head around the math is the first step. If you’re eyeing up a property worth $1 million, a 70% LVR limit means the bank will only lend you $700,000. You need to find the other $300,000 yourself. The Reserve Bank keeps these “speed limits” in place to prevent the economy from overheating and to protect the banking system from sudden shocks. If property values drop, a high LVR could mean you owe more than the house is worth. That is a position no investor wants to be in, so these rules actually provide a bit of a safety net for your portfolio.

Exemptions You Should Know About

Not every deal requires a massive cash deposit. The most common way around the 30% rule is the “New Build” exemption. To encourage more housing supply, the government often allows investors to get into brand-new properties with as little as a 20% deposit. This can be a game-changer for someone starting out. Another powerful strategy is using home equity for investment NZ. Instead of saving cash, you use the value built up in your own home to act as the deposit for the new rental.

You also need to consider your long-term hold strategy in light of the Bright-line test. While the rules have fluctuated, your intention for the property impacts how lenders view your stability. If you are feeling stuck on the numbers, we can help you work out your next move with a quick, no-pressure chat to see what is possible for your situation.

Mainstream Banks vs. 2nd Tier Lenders: Choosing Your Path

Most Kiwis grow up believing that the “Big Four” banks are the only place to go for a mortgage. While they are a solid choice for a standard home loan, they can be incredibly rigid when it comes to residential investment property loans NZ. These major institutions often use a “cookie-cutter” approach. If your financial situation doesn’t fit their specific mould, you might find yourself facing a flat refusal. In 2026, with Debt-to-Income (DTI) restrictions limiting high-debt lending, many investors are being turned away simply because they already have a few properties under their belt.

Being declined by a mainstream bank isn’t the end of your journey; it’s often just the beginning of a much better deal. This is where second-tier and non-bank lenders become a secret weapon for successful investors. These lenders aren’t just a backup plan. They are a strategic alternative for those who need a bit more flexibility than a traditional bank can offer. At Mortgage Suite, we specialise in non bank investment property loans NZ because we know that a “no” from a bank manager usually just means they don’t have the right product for your specific goals.

When the Bank Says No

There are plenty of reasons a bank might say no. Since July 2024, banks have been restricted in how much high-DTI lending they can do. For an investor in 2026, a DTI of 7 is considered high. If your total debt is seven times your gross annual income, a mainstream bank might struggle to approve you. Other common hurdles include being self-employed without two years of perfect tax records or trying to buy a non-standard property. Non-bank lenders take a more “human” approach to your numbers. They are legitimate, safe alternatives that look at the big picture rather than just ticking boxes on a spreadsheet.

Comparing Your Options

When you look beyond the big banks, you’re often trading a slightly higher interest rate for significantly more flexibility and speed. While a major bank might take weeks to process a complex investment application, a second-tier lender can often give you an answer in a matter of days. This speed can be the difference between securing a great deal and missing out entirely. We help you compare these options side-by-side. We’ll show you the true cost of the loan versus the potential growth of your portfolio, ensuring you get a fair go and a loan that actually helps you move forward.

Residential Investment Property Loans NZ: The 2026 Investor’s Reference Guide

Strategic Loan Structures: Interest-Only and Equity Unlocking

While everyone chases the lowest interest rate, savvy investors know that the way you set up your debt is what actually builds wealth. Choosing the right structure for your residential investment property loans NZ can be the difference between a portfolio that grows and one that stays stagnant. In 2026, the strategy is all about flexibility. With the 100% interest deductibility rules fully restored, many of our clients are opting for an interest only investment property loan nz to keep their monthly costs down and make the most of their tax benefits.

This approach allows you to focus your spare cash on paying down the mortgage on your own home first. It is a classic move that we often recommend because it puts money back in your pocket while your investment property hopefully gains value in the background. The goal is to make your money work harder for you, not the other way around. By only paying the interest, you’re keeping your outgoings low and your cash flow healthy, which is vital when bank stress tests are still quite high.

Unlocking Your “Lazy Equity”

Many people are sitting on a goldmine without even realising it. Equity is simply the difference between what your property is worth and what you owe the bank. You don’t always need a formal valuation to get a rough idea; looking at recent sales in your street is a great place to start. If your home is worth $1.2 million and your mortgage is $500,000, you have $700,000 in equity. Banks won’t let you use all of it, but they might let you borrow up to 80% of your home’s value to fund your next move.

The process of an equity release home loan NZ allows you to pull that value out and use it as a deposit for a rental. This means you can buy your next investment without needing to save a single cent in cash. It is the fastest way to scale your portfolio, provided you have the income to support the new lending. If you want to see how much you could potentially tap into, talk to us about your loan structure today to get a clear picture of your options.

Cash Flow Management Strategies

Managing a rental in 2026 isn’t just about collecting rent; you need to be smart with how that money moves. While interest-only loans are popular for their tax benefits, some investors prefer the traditional route of paying back the loan plus interest to slowly chip away at the debt. It really depends on whether you’re chasing immediate cash flow or long-term debt reduction. We also see a lot of success with offset accounts. By keeping your savings in an account linked to your loan, you only pay interest on the difference, which can save you thousands over the years.

Revolving credit is another handy tool for the modern investor. It acts like a giant overdraft, giving you instant access to funds when a great property deal pops up. Having these structures in place before you start house hunting means you can move quickly when the right opportunity arises. For investors looking to take things further, understanding how property development loans NZ work can open up even more avenues for growing your portfolio through new builds and development projects. It is all about being organised and ready to strike when the market is in your favour with Mortgage Suite Ltd in your corner.

Securing Your Investment Loan with Mortgage Suite Ltd

Securing residential investment property loans NZ shouldn’t feel like a solo battle against a giant machine. When you work with Krish Krishna and the team at Mortgage Suite Ltd, you’re putting over 20 years of deep banking experience in your corner. We know exactly how the big lenders think because we’ve spent decades on the other side of the desk. This insider knowledge is what allows us to fight for your approval, finding the specific path that leads to a “yes” when other brokers might have already thrown in the towel. We don’t just fill out forms; we build a case for your success.

Our process is designed to take the weight off your shoulders. From that very first chat where we map out your goals, all the way through to the day the deal is finalised, we handle the heavy lifting. We don’t just want to get you a loan; we want to ensure it’s the right setup for your long-term wealth. We’re here to build a relationship, acting as your steady hand in a market that can sometimes feel quite unpredictable. Our commitment doesn’t end when the papers are signed; we stay in touch to ensure your finance structure still fits as your life and the market change.

The Mortgage Suite Ltd Advantage

What sets us apart is our ability to look beyond the standard bank offerings. We have access to a huge range of lenders, from the household names to specialist providers that many people don’t even know exist. This means we can find a home for almost any deal, no matter how complex your situation might seem. You’re never just a number to us. We treat every client as a partner, providing a personalised service that focuses on removing obstacles and creating a clear run toward your investment goals. We have a reputation for getting those tricky, non-standard deals across the line because we aren’t afraid to roll up our sleeves and negotiate hard on your behalf.

We act as a bridge between the rigid world of institutional banking and your personal needs. Our proactive attitude and dedication to overcoming challenges have made us a trusted mentor for investors across the country. Whether you’re dealing with self-employment income or a property that doesn’t fit the usual mould, we know how to present your story to the right lender to get the result you need.

Your Next Steps

Ready to see what is possible for your portfolio? To get the ball rolling, it helps to gather a few essentials. Having your income proof, current mortgage details, and a clear idea of your investment goals ready will make our first conversation even more productive. We invite you to book a consultation where we can look at your numbers and show you exactly how to grow your portfolio in 2026. It is about more than just a transaction; it is about setting you up for a future of financial freedom. Get started with Mortgage Suite Ltd and secure your investment future today and let’s turn your property plans into a reality.

Take the Next Step Toward Your Property Goals

Building a property portfolio in today’s market doesn’t have to be a stressful uphill battle. By now, you’ve seen that the right strategy for residential investment property loans NZ is about much more than just chasing the lowest interest rate. It’s about having the flexibility to move quickly, the insight to unlock your existing equity, and the grit to look beyond the big banks when their rigid rules don’t fit your situation. Whether you are a first-time investor or a seasoned pro, the key is to stay proactive and keep your loan structures working as hard as you do.

We’re here to help you navigate these choices with confidence and clarity. With over 20 years of banking and brokerage experience, we specialise in 2nd tier and alternative lending solutions that mainstream banks often overlook. We provide a nationwide service across New Zealand, ensuring every investor gets a fair go and a dedicated advocate in their corner. We know the hurdles, but we also know the way around them.

Your next investment is waiting, and we’d love to help you reach it. Talk to Krish and the team at Mortgage Suite to secure your investment loan today. Let’s get your financing sorted so you can focus on growing your wealth and securing your financial future. You’ve got the vision, and we have the expertise to help you make it happen.

Frequently Asked Questions

How much deposit do I really need for an investment property in NZ in 2026?

You generally need a 30% deposit for most residential investment property loans NZ. While the Reserve Bank allows banks to lend to a small number of investors with less than this, those spots are limited and usually go to the strongest applicants. If you are looking at a brand-new build, you can often still get started with a 20% deposit.

Can I use my KiwiSaver for an investment property loan?

No, you cannot use your KiwiSaver funds to purchase an investment property. KiwiSaver withdrawals are strictly reserved for buying your very first home to live in or for your retirement. However, once you’ve used KiwiSaver to get into your first home and built up some equity, you can eventually use that equity as a deposit for a rental.

What is a 2nd tier lender and are they safe for property investors?

A second-tier lender is a non-bank financial institution that offers property loans outside the traditional “Big Four” banks. They are a perfectly safe and regulated alternative for Kiwis. These lenders often have more flexible criteria, making them ideal for investors who might be self-employed or have complex income structures that mainstream banks struggle to process.

How does the Bright-line test affect my investment loan decision?

The Bright-line test affects your tax obligations rather than the loan itself, but it’s a vital part of your long-term strategy. It determines whether you’ll pay tax on any profit if you sell the property within a certain timeframe. Lenders will want to see that you have a stable plan for the property, as your intention to hold or sell can impact your overall financial position.

Can I get an interest-only loan for my residential investment property?

Yes, interest-only terms are a very common choice for residential investment property loans NZ in 2026. Because 100% of the interest is now tax-deductible for the 2025/2026 tax year, this structure helps you maximise your cash flow. Most lenders will offer interest-only periods for up to five years, though some specialist lenders can provide even longer terms.

What is the maximum LVR for an investment property in New Zealand?

The standard maximum LVR for an existing investment property is 70%, meaning you need a 30% deposit. If you’re buying a new build, the maximum LVR often increases to 80%, allowing you to get in with a 20% deposit. Banks are restricted by “speed limits” that cap how much high-LVR lending they can do each month.

How do I calculate how much equity I can use for a new loan?

You can usually use up to 80% of your current home’s value, minus your existing mortgage. For example, if your home is worth $1 million and you owe $500,000, 80% of the value is $800,000. Subtract your $500,000 mortgage, and you have $300,000 in usable equity. This amount can act as the 30% deposit for a new $1 million investment property.

What should I do if my bank declines my investment property loan application?

Don’t assume a “no” from your bank is the end of the road. Banks often decline applications because of rigid internal rules or high debt-to-income ratios, which currently sit at a cap of 7 for most investors. Your next step should be to look at non-bank lenders who take a more personal approach to your numbers and can often find a way to say “yes”.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026

You might assume that the lowest advertised interest rate from a major bank is the gold standard for your next commercial mortgage New Zealand, but for many savvy investors in 2026, the obvious choice is no longer the most profitable one. While the Official Cash Rate has held steady at 2.25 per cent, the reality of securing finance has become a hurdle of rigid serviceability tests and opaque rate structures. We understand how exhausting it is to present a strong business case only to be met with a clinical checklist that ignores your true commercial potential.

This expert comparison is designed to help you master the complexities of the current lending environment. You’ll learn how to weigh the stability of mainstream institutions against the agility of second-tier lenders who often prioritise business vision over historical paperwork. We’ll break down the critical LVR differences between asset types and show you how to structure a deal that secures flexible terms. By the end of this guide, you’ll have the clarity needed to choose a partner that supports your long-term success rather than just processing another transaction.

Key Takeaways

  • Learn how to select a commercial mortgage New Zealand that balances competitive rates with the flexibility your business needs to thrive.
  • Evaluate the hidden costs of mainstream bank criteria and see how second-tier lenders offer a faster path to settlement.
  • Grasp the specific documentation requirements, including the Information Memorandum, to present a professional case that credit managers can’t ignore.
  • Identify the structural differences between owner-occupied and investment loans to maximise your borrowing capacity and long-term capital growth.
  • Gain insights into how seasoned banking expertise can help you find a clear path forward even when traditional lenders say no.

Understanding the Commercial Mortgage Landscape in New Zealand

A What is a Commercial Mortgage? is fundamentally a loan secured by non-residential real estate, but the mechanics differ vastly from the home loan you might have for your family residence. While residential lending focuses on your personal ability to meet repayments from your salary, a commercial mortgage New Zealand is judged on the property’s capacity to generate income. In 2026, the lending environment has become more sophisticated. With the Reserve Bank holding the Official Cash Rate at 2.25 per cent and inflation projected to reach 4.2 per cent by mid-year, banks are looking beyond historical data to assess future serviceability. They want to see a clear “intended use” that aligns with current market strengths, such as the robust industrial sector.

The structural differences are significant. Unlike residential loans where you might see Loan-to-Value Ratios (LVR) of 80 per cent, commercial deals usually sit between 50 and 65 per cent. Interest rate margins are also wider, reflecting the higher risk profile of business-related assets. Term lengths are typically shorter, often requiring a refinance or “roll-over” every three to five years. This requires a proactive approach to your portfolio management and a steady hand to navigate the fluctuating margins offered by different institutions.

Asset Types Covered Under Commercial Finance

Lenders categorise risk based on the specific asset you’re purchasing. For retail spaces and shopping centres, credit managers scrutinise foot traffic and the reliability of anchor tenants. Industrial warehouses and factories are currently the most favoured assets in the New Zealand market because of their steady growth and low vacancy rates. If you’re eyeing professional offices or medical suites, be prepared for a “flight to quality” assessment. Lenders in 2026 prioritise modern buildings with high seismic resilience and sustainability credentials, often offering better terms for high-yield, high-quality assets.

Why Residential and Commercial Loans Don’t Mix

The biggest mistake investors make is assuming their residential equity will easily bridge the gap to a commercial purchase. Commercial lending uses a “weighted lease” analysis, where the length and strength of the tenant’s lease are more important than your personal salary. You must also account for GST, which can significantly impact your initial deposit requirements and borrowing power. We often advise against cross-collateralisation, where your home is used as security for a commercial loan. This creates unnecessary risk and can limit your future flexibility if the commercial market fluctuates. Keeping these two worlds separate ensures your personal assets remain protected while your business ventures grow.

Mainstream Banks vs. 2nd Tier Lenders: A Direct Comparison

In the New Zealand market, the “Big Four” (ANZ, ASB, BNZ, and Westpac) traditionally dominate the landscape. However, choosing a commercial mortgage New Zealand based purely on the lowest headline interest rate can be a trap. While a major bank might offer a floating base rate around 4.14 per cent, the rigid serviceability tests often mean your application stalls for weeks. This is where the concept of “opportunity cost” becomes vital. If a bank takes three months to approve a loan while a competitor snaps up a prime industrial site, that lower interest rate hasn’t saved you money; it’s cost you the entire investment.

According to the Property Council New Zealand, the commercial sector is a massive driver of the local economy, yet bank “credit appetite” remains highly selective. Mainstream lenders often shy away from buildings with lower seismic ratings or industries they deem “high risk,” such as hospitality or specific retail niches. Second-tier lenders, by contrast, use common-sense underwriting. They are far more likely to support self-employed borrowers who have strong cash flow but don’t necessarily fit the “perfect” historical tax profile that a major bank demands. Business owners in this position may also benefit from exploring a small business loan NZ to understand the full range of funding options available alongside commercial property finance.

When to Choose a Mainstream Bank

Mainstream banks are the ideal choice for “Gold Standard” borrowers. If you have a clean credit history, two years of strong financial statements, and a property with a long-term lease to a reputable tenant, you should prioritise these institutions. You’ll benefit from lower margins and a full suite of integrated business banking tools. Banks love “Vanilla” assets, which are modern, well-located buildings in major centres like Auckland or Christchurch. If your deal fits this neat box, the major banks offer the stability you need.

The 2nd Tier Advantage: Flexibility and Speed

Second-tier lenders excel where the majors hesitate. They are the go-to for “Vacant Possession” purchases or properties with short-term leases where a bank sees too much risk. These lenders often provide interest-only options or capitalised interest for development projects, allowing you to preserve cash flow during the critical early stages of a project. Second-tier lending serves as the essential bridge for borrowers who do not fit into the rigid boxes of institutional banking. If you find yourself in a complex situation, exploring non-mainstream options can often be the difference between a rejected application and a successful settlement.

Owner-Occupied vs. Investment Commercial Mortgages

The strategy behind your commercial mortgage New Zealand depends entirely on who will be occupying the four walls of your property. Lenders categorise these applications into two distinct buckets: owner-occupied and investment. While they may look similar on a title deed, the credit assessment behind them is world’s apart. If you’re buying a premise to run your own engineering firm or retail boutique, the lender is essentially backing your business’s ability to pay rent to itself. If you’re an investor, they’re backing the strength of your tenants and the lease agreements they’ve signed.

Risk assessment often hinges on the “single-tenant” versus “multi-tenant” factor. Multi-tenant assets, like a block of five shops, are generally viewed as lower risk because a single vacancy won’t stop the mortgage repayments. However, a single-tenant building with a high Weighted Average Lease Expiry (WALE) can be just as attractive. In the 2026 market, a WALE of five years or more is often the “magic number” that unlocks more competitive interest rate margins and longer interest-only periods. Lenders want to see that your income stream is secured well into the future before they commit to a long-term facility.

Financing for Owner-Occupiers

When you buy for your own business, the lender will scrutinise your company’s P&L and balance sheets rather than just the property’s market rent. One significant advantage here is the potential for higher LVRs. Some lenders are willing to stretch beyond the standard 65 per cent if the business is exceptionally robust and has a long history of profitable trading. Owning your own premises also provides significant tax advantages in New Zealand, such as the ability to claim depreciation on certain fit-outs and the deductibility of interest costs, which can turn a monthly expense into a long-term wealth-building tool.

The Investor’s Perspective: Yield and Security

For investors, the focus shifts to “Net” versus “Gross” lease income. A Net lease, where the tenant pays for outgoings like rates and insurance, is far more favourable for loan serviceability than a Gross lease. Lenders also place immense value on “tenant covenant.” A property leased to a government department or a national supermarket chain is viewed as “bankable” security, whereas a lease to a brand-new startup may require a larger deposit or a lower LVR. You must also forecast for “Capex” (capital expenditure) and potential vacancy periods, as lenders will often “stress test” your ability to cover the mortgage even if the building sits empty for six months.

Commercial Mortgage New Zealand: Comparing Mainstream Banks vs 2nd Tier Lenders in 2026

The Application Process: Organising Your Commercial Case

Securing a commercial mortgage New Zealand requires more than just a decent credit score and a deposit. It demands a narrative that convinces a credit manager your project is a calculated success rather than a speculative risk. The centrepiece of this process is the Information Memorandum (IM). Think of the IM as a professional pitch deck for your loan. It should clearly outline the property’s merits, the strength of the tenants, and your own experience as an operator or investor. When a credit manager receives a messy pile of bank statements, they see work; when they receive a polished IM, they see a professional partner.

Your financial documentation must go deeper than basic year-end accounts. Lenders in 2026 expect to see up-to-date GST returns and detailed Debtors and Creditors lists to verify the real-time health of your cash flow. They also want to see a clear “Exit Strategy.” Whether you plan to refinance with a mainstream bank after three years or sell the asset once the lease is renewed, the lender needs to know exactly how they’ll be repaid. A vague plan is a fast track to a declined application.

Technical Reports You Cannot Ignore

In the New Zealand market, the “IEP” or earthquake rating is often the factor that makes or breaks a deal. Most mainstream banks won’t touch a building with an Initial Evaluation Procedure rating below 34 per cent of the New Building Standard (NBS), as these are deemed “earthquake prone.” If you’re eyeing an industrial site, environmental reports are equally non-negotiable. You must prove the land isn’t contaminated from previous heavy use. Finally, remember that your Loan-to-Value Ratio is always determined by a Registered Valuation from a lender-approved panel valuer, not the purchase price or the CV.

Navigating the Credit Committee

The credit committee evaluates your case based on the “Three Cs”: Character, Capacity, and Collateral. They want to know who you are, your ability to service the debt, and the quality of the asset itself. A well-organised application can reduce your interest margin by 0.5% or more. This is where an expert hand is invaluable; we don’t just submit paperwork, we “shop” your deal to multiple tiers to find the lender whose current appetite matches your specific scenario. If you’re ready to present your strongest possible case, reach out to us today and let’s get your application moving.

Why Mortgage Suite is Your Commercial Finance Partner

Choosing the right partner for your commercial mortgage New Zealand often comes down to who has the deepest understanding of the credit committee’s mindset. At Mortgage Suite, we leverage over 20 years of institutional banking experience to give our clients a distinct advantage in every negotiation. We don’t just act as a middleman; we act as your dedicated advocate. Krish Krishna personally handles complex commercial files, ensuring that your business potential is communicated with the same level of authority that the banks themselves use. This high-level expertise allows us to anticipate the concerns of lenders before they even arise, smoothing the path to a successful settlement.

Whether you are looking at an industrial site in Christchurch or a retail block in Auckland, our national reach ensures we understand the local nuances of the diverse New Zealand property market. We specialise in finding a clear path forward when mainstream banks say no. Our experience has taught us that a “decline” from a major bank is rarely the end of the road. It is often just a sign that your scenario requires a more tailored, non-mainstream approach. We pride ourselves on being a steady hand in a fluctuating market, prioritising long-term partnerships over simple transactional lending. This commitment to your success means we stay involved long after the initial loan is approved, helping you navigate future refinances and portfolio growth.

Expertise in 2nd Tier and Structured Finance

Our clients gain access to a wide panel of alternative lenders that you simply won’t find on the high street. These second-tier institutions offer structured finance solutions that are essential for large-scale property developments and complex business acquisitions. We understand how to piece together these intricate deals, ensuring that the terms align with your project’s specific cash flow requirements and timelines. If your project involves interest-only periods or capitalised interest, we know exactly which lenders have the appetite for that level of flexibility and how to present your case to secure those terms.

Take the Next Step in Your Commercial Journey

A bank decline shouldn’t be the roadblock that stops your business growth or investment plans. We have a proven track record of turning “no” into “yes” by restructuring deals and finding the right lender tier for each unique situation. We have spent years helping first home buyers enter the residential market, and we apply those same principles of tireless advocacy to our commercial clients. We understand the stress that comes with large-scale financial decisions, and our goal is to alleviate that pressure through clear communication and reliable results. Contact us today for a confidential review of your commercial financing needs and let us help you secure the future of your business.

Securing Your Commercial Future in 2026

Your journey toward a successful commercial mortgage New Zealand shouldn’t be defined by the rigid boxes of institutional banking. We’ve explored how the right lender tier can determine your project’s viability, from the stability of the Big Four to the common-sense flexibility of second-tier options. Success in this market requires more than just a property; it requires a professional presentation that anticipates credit hurdles before they become roadblocks.

With over 20 years of institutional banking experience and national coverage, we specialise in navigating the complexities of 2nd tier lending and structured finance. We’re here to act as your dedicated advocate, ensuring your business potential is seen and valued by the right financial partners. Don’t let a complex scenario or a traditional bank decline slow your momentum. Contact Mortgage Suite for a specialised commercial finance consultation today and let’s build a clear path forward for your next acquisition or development. We’re ready to help you turn your commercial vision into a reality.

Frequently Asked Questions

What is the typical LVR for a commercial mortgage in New Zealand?

Most lenders provide a Loan-to-Value Ratio (LVR) between 50 and 65 per cent for a commercial mortgage New Zealand. While residential loans often reach 80 per cent or higher, commercial assets require a larger deposit to offset the increased risk and potential for longer vacancy periods. Some second-tier lenders may stretch these limits slightly for high-quality industrial assets or exceptionally strong owner-occupied business cases.

How do commercial interest rates compare to residential rates?

Commercial interest rates are almost always higher than residential rates because they include a wider risk margin. In 2026, while home loans might hover at lower levels, commercial floating rates can range from 4 per cent to over 10 per cent depending on the lender tier. Banks charge this premium to account for the complexity of the security and the shorter term of the facility.

Can I use KiwiSaver for a commercial property purchase?

No, you generally cannot use KiwiSaver funds to purchase a commercial property. KiwiSaver withdrawal rules are strictly designed for first-home residential purchases or retirement. If you’re looking to fund a commercial venture, you’ll need to rely on business capital, personal savings, or equity from existing residential property rather than your retirement savings. This ensures the funds remain dedicated to their intended purpose.

What is an IEP rating and why does it affect my commercial loan?

An Initial Evaluation Procedure (IEP) rating measures a building’s seismic strength relative to the New Building Standard (NBS). Lenders are extremely cautious about buildings rated below 34 per cent NBS because they’re legally classified as earthquake-prone. A low rating can make a property unbankable or require significant capital expenditure to upgrade before a loan is approved, as it represents a major collateral risk.

How long is the term for a typical commercial mortgage?

Commercial loan terms are significantly shorter than the 30-year terms common in residential lending. Most commercial facilities are structured for three to five years. At the end of this period, the loan is usually reviewed and rolled over or refinanced based on the current market value of the property and the strength of the existing leases. This allows lenders to adjust their exposure periodically.

Do I need a business plan to get a commercial mortgage approved?

Yes, a clear business plan or an Information Memorandum is essential for most commercial applications. Lenders want to understand your operational experience, the property’s income potential, and your long-term strategy for the asset. A well-structured plan demonstrates to the credit committee that you’ve accounted for risks like tenant vacancy or rising maintenance costs, making your case much more compelling for approval.

What happens if my business has a “bad credit” history but strong assets?

Strong assets can often bridge the gap if your historical credit is less than perfect. While mainstream banks might decline the application, second-tier lenders specialise in these non-mainstream scenarios. They often prioritise the value of the collateral and your current cash flow over past credit events, providing a pathway to secure a commercial mortgage New Zealand when traditional institutions are unable to help.

Are there specialised loans for property development in NZ?

Yes, property development loans are specific facilities designed for construction or major renovations. These loans often feature drawdowns where funds are released in stages as work is completed and verified. They may also allow for capitalised interest, meaning you don’t make repayments until the project is finished or the units are sold, which preserves your cash flow during the critical building phase.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Non-Bank Investment Property Loans : A Strategic Guide for Investors in 2026

What if the bank’s "no" isn’t the end of your investment journey, but actually the signal to start scaling your portfolio with more precision? Many New Zealand investors feel sidelined by the RBNZ’s strict 70% LVR requirements and the DTI limit of 7, which often makes it feel like the big banks are working against your growth. It’s incredibly frustrating when a high-yield opportunity is right in front of you, yet rigid, one-size-fits-all criteria stop you in your tracks. Exploring **non bank investment property loans ** provides a strategic path forward for those who refuse to let traditional restrictions dictate their financial future.

We understand that you’re looking for more than just a loan; you’re looking for a way to secure your next property without the slow processing times and restrictive hurdles of the main street lenders. This guide will show you how to bypass these barriers to grow your portfolio faster and more flexibly. You’ll learn to weigh the total cost versus the benefit of 2nd tier lending and find a reliable finance partner who views your success as a priority. We will examine how these tailored solutions work in the 2026 market, ensuring you have the tools to make confident, informed decisions.

Key Takeaways

  • Understand how 2nd tier lenders utilise private capital to provide flexible funding options that bypass traditional bank constraints.
  • Discover how to overcome restrictive Debt-to-Income (DTI) ratios by partnering with lenders who recognise diverse income streams, including self-employed or overseas earnings.
  • Learn why the realistic serviceability stress tests used for non bank investment property loans can unlock significant borrowing capacity for your next acquisition.
  • Master the strategic preparation required to secure a loan, including how to present rental yields and property potential to satisfy alternative criteria.
  • Explore the benefits of professional advocacy to ensure you find a reliable finance partner who understands the nuances of the New Zealand property market.

What Are Non-Bank Investment Property Loans in the NZ Market?

To understand the current market, we first need to define the terminology. Unlike retail banks that rely on customer deposits to fund their lending, non-bank lenders use private capital or wholesale funding. What Are Non-Bank Investment Property Loans basically refers to a robust sector of financial institutions that provide credit without holding a full banking licence. In the local context, these are frequently called 2nd tier lenders. They serve as a critical alternative for investors who find themselves restricted by the rigid frameworks of the big four banks.

Safety is a primary concern for many, but the "non-bank" label is often misunderstood by retail investors. These lenders aren’t operating in a regulatory vacuum. They are strictly governed by the Credit Contracts and Consumer Finance Act (CCCFA). This legislation ensures borrower protection and mandates responsible lending practices. Choosing this route doesn’t mean sacrificing security; it means gaining a partner who can look past the standard "tick-box" approach to finance. We see this as a bridge between rigid institutional rules and the personal needs of a growing portfolio.

The Rise of Alternative Lending in New Zealand

The demand for **non bank investment property loans ** have surged as RBNZ regulations have become more complex. With the OCR held at 2.25% in mid-2026, mainstream banks have become increasingly risk-averse. This shift has transformed the 2nd tier sector from a "last resort" into a strategic tool for professional portfolio scaling. Investors now utilise these lenders to bypass the slow, cumbersome application processes that often lead to missed opportunities in a fast-moving market. It’s about agility and the ability to act when a high-yield property hits the market.

Key Differences in Funding Sources

The flexibility of **non bank investment property loans **stems directly from their funding models. Because they don’t have the same RBNZ capital restrictions as traditional banks, they can recognise diverse income sources, such as self-employed earnings or overseas income. This stability is a hallmark of the NZ sector in 2026. Common myths about non-bank reliability are easily debunked when you look at the institutional backing behind these firms. They offer a steady, reliable source of capital that allows for realistic serviceability testing, focusing on the actual performance of your investment property rather than just a standardised stress-test rate.

Why Savvy Investors Choose 2nd Tier Lending for Portfolio Growth

If you’ve ever felt like you’ve hit a ‘lending wall’ with your current bank, you aren’t alone. Mainstream banks often rely on rigid Debt-to-Income (DTI) ratios that can stifle even the most promising expansion plans. Since the introduction of the DTI ratio of 7 in mid-2024, many seasoned investors have found their borrowing capacity suddenly capped. This is where non bank investment property loans offer a distinct tactical advantage. These lenders provide the flexibility and faster approval turnarounds needed to move quickly when high-demand listings appear; they ensure you don’t miss out while waiting for a bank’s slow bureaucracy.

Unlike the big four, 2nd tier lenders are often more willing to recognise diverse income sources. If you’re self-employed or receive overseas income, you’ve likely experienced the frustration of a bank ‘haircutting’ your earnings until they no longer support the loan you need. Non-bank lenders tend to take a more holistic view of your financial position. They prioritise the actual performance and potential of the security property rather than just sticking to a standardised formula. This pragmatic approach is supported by the Reserve Bank of New Zealand’s definition of non-bank lenders, which highlights their role in providing credit to sectors that might not fit the narrow criteria of registered banks.

Bypassing the ‘Lending Wall’

The big four banks often focus heavily on your income-to-debt ratio, but non-banks often view equity as a more significant lever for growth. We’ve helped clients who were stuck with two properties and a ‘no’ from their bank successfully scale to five properties by restructuring their debt through alternative finance. This strategy bridges the gap between your current portfolio and your long-term goals. It allows you to use existing equity to fund new acquisitions without being penalised by restrictive DTI caps that don’t account for the true value of your assets. For investors who are asset-rich but want to unlock that value more strategically, understanding how a Home Equity Loan works can open up additional pathways to fund your next acquisition. If you want to explore this approach in greater depth, our comprehensive guide on using home equity for investment NZ walks through exactly how to identify your usable equity and navigate the 2026 lending landscape.

Interest-Only and Cashflow Advantages

Cashflow is the lifeblood of any property portfolio, especially as rates remain a key focus for the RBNZ. Non-bank lenders are typically more investor-friendly regarding repayment structures, often offering longer interest-only terms than retail banks. This helps preserve your liquidity and can maximise tax deductibility benefits. If you’re looking for residential investment property loans that offer this level of customisation, it’s vital to partner with a lender that understands the nuances of investor cashflow. These tailored terms ensure your portfolio remains sustainable while you wait for the next market cycle to drive capital gains.

Mainstream Banks vs. Non-Bank Lenders: Comparing Investment Criteria

When you sit down with a traditional bank, you’re essentially being measured against a rigid, automated checklist. Mainstream lenders in New Zealand are currently bound by strict RBNZ capital requirements, which forces them to maintain a conservative stance on risk. For most investors, this means a mandatory 30% deposit for existing properties. If your application doesn’t fit their specific mould, the answer is a quick "no". In contrast, non bank investment property loans are assessed with a more human touch. These lenders have the autonomy to look at the "why" behind your numbers, offering a pragmatic alternative when the big banks’ tick-box exercise fails you.

Transparency is vital when stepping away from the big four. While banks are overseen by the RBNZ, many non-bank deposit takers operate under Financial Markets Authority (FMA) regulations, providing a structured layer of protection for Kiwis who step outside the traditional banking system. You’ll find that while interest rates for 2nd tier lending can be slightly higher, often starting around 5.65% for near-prime borrowers, the real cost of finance must be weighed against the opportunity cost of a lost deal. The fee structures are different, usually involving an establishment fee, but the flexibility you gain often outweighs these initial costs.

The Serviceability Gap

The biggest hurdle at a mainstream bank isn’t always the deposit; it’s the "stress test". Banks often test your ability to pay at rates of 7% or 8%, even if the actual rate is much lower. Non-bank lenders use more realistic serviceability buffers that reflect the actual market conditions of 2026. In the 2026 NZ market, serviceability stress tests are the hypothetical interest rates lenders use to ensure a borrower can still afford repayments if market rates climb significantly higher than their current fixed term. By using a lower, more realistic test rate, 2nd tier lenders can often approve a loan that a bank would reject purely on paper.

LVR and Deposit Flexibility

Can you still secure a loan with a 20% deposit in 2026? At a mainstream bank, it’s nearly impossible for an existing investment property. However, **non bank investment property loans **often allow for higher Loan-to-Value Ratios (LVR), sometimes accepting a 20% deposit if the overall deal is strong. They’re also far more adept at recognising "unburnished" income, such as seasonal bonuses or secondary business earnings that banks might ignore. For investors with significant equity in other assets, non-banks can even facilitate second mortgages to unlock that capital, providing the bridge you need to fund your next acquisition without selling down your current portfolio. This approach to leveraging existing property wealth shares similarities with how an equity release home loan can help New Zealand homeowners access the value tied up in their property.

Non-Bank Investment Property Loans : A Strategic Guide for Investors in 2026

Strategic Structuring: How to Secure a Non-Bank Loan for Your Next Rental

Securing non bank investment property loans requires a shift in mindset. You aren’t just applying for a mortgage; you’re presenting a professional business case for a property asset. The process begins with a thorough cleanup of your personal credit profile. Even small, overlooked debts can influence the interest rate you’re offered, so ensure your accounts are in perfect order. From there, you must gather robust evidence of the property’s potential. This involves more than a basic rental appraisal. You need to demonstrate the yield and the long-term viability of the investment to show the lender that the property is a self-sustaining asset.

Once your data is ready, you need to work with a specialist who understands the nuances of the 2nd tier market. Not all non-bank lenders are the same; some specialise in near-prime residential deals while others focus on more complex, specialist scenarios. Identifying the right fit for your specific niche is the difference between a frustrating decline and a swift approval. Finally, you must design a clear ‘Exit Strategy’. This is the roadmap that outlines how you will eventually transition the loan back to a mainstream bank when your circumstances or market conditions align with their criteria.

The Importance of the Exit Strategy

A common mistake is viewing 2nd tier lending as a permanent home for your debt. For most savvy investors, it’s a tactical bridge used to secure an asset that would otherwise be out of reach. You shouldn’t stay with a non-bank lender forever if your goal is to minimise interest costs over thirty years. We recommend setting firm 12-month and 24-month financial goals. Your 12-month goal might be to increase equity through a minor renovation, while your 24-month goal focuses on stabilising business income. Meeting these milestones allows you to ‘graduate’ back to a mainstream bank interest rate once you fit their standard box.

Organising Your Application for Success

Your application needs to include documents that retail banks often overlook, such as detailed cashflow forecasts or proof of secondary income streams. Presenting your investment as a business case to a private lender requires transparency and a proactive attitude. We take the stress out of this process by pre-vetting your application before it ever reaches a lender’s desk. This ensures that every potential hurdle is addressed early. If you want to ensure your portfolio growth doesn’t stall, you can apply for residential investment property loans through our seasoned team to get your application right the first time.

Partnering with Mortgage Suite: Your Steerage Through Alternative Finance

Success in property investment often hinges on the quality of your financial advocacy. While a big bank might treat you as just another number in a processing queue, we view our relationship as a professional partnership. Krish Krishna brings over 20 years of deep-seated banking experience to every deal, giving you a distinct advantage when approaching 2nd tier lenders. This insider knowledge allows us to anticipate a lender’s concerns before they arise, ensuring your application for **non bank investment property loans **is positioned for a "yes" from the outset.

We’ve earned a reputation as a dedicated negotiator with New Zealand’s top non-bank lenders. We don’t just pass on a rate; we fight for the terms that will best serve your portfolio’s growth. Having a steady hand to guide you through complex 2nd tier structures is invaluable, especially when you’re trying to move quickly on a high-yield opportunity. This personalised approach beats a transactional bank relationship every time, as we focus on the nuances of your specific financial goals rather than a rigid, one-size-fits-all policy.

Seasoned Professionalism in a Fluctuating Market

Navigating the 2026 property market requires a level of confidence that only comes from having seen every possible market cycle. With the OCR currently sitting at 2.25%, the environment for non bank investment property loans is fierce but requires careful navigation to avoid hidden costs. We specialise in removing the obstacles that stop other investors in their tracks, whether that’s a restrictive DTI limit or a complex income structure. Our commitment to your long-term success and portfolio stability always takes precedence over quick commissions.

Your Next Step Toward Portfolio Growth

Our consultative process is designed for ease and transparency, moving you seamlessly from an initial chat through to final settlement. Investors across the country trust Mortgage Suite Ltd because we handle the intricate details of alternative finance, allowing them to focus on finding their next property. We act as the bridge between the rigid world of institutional banking and your personal need for flexibility. If you’re ready to bypass traditional restrictions and scale your holdings, Book a consultation with our investment specialists today and let’s get your portfolio moving again.

Take the Next Step in Scaling Your Property Portfolio

The New Zealand property market in 2026 demands agility and a departure from traditional "tick-box" banking. You’ve seen how 2nd tier lenders provide the necessary flexibility to bypass restrictive DTI caps and realistic serviceability buffers that retail banks simply cannot match. By focusing on strategic structuring and a robust exit strategy, you can use non bank investment property loans to secure high-yield assets and keep your growth momentum moving forward. It’s about looking beyond the standard constraints to find a path that actually fits your long-term vision.

At Mortgage Suite, we provide the steady hand and seasoned professionalism you need to navigate these complex financial structures. With over two decades of institutional banking experience and national coverage across all of New Zealand, we are specialists in 2nd tier lending for complex portfolios. We act as your dedicated negotiator, ensuring you find a reliable finance partner who understands the nuances of the local market. Don’t let a "no" from a mainstream bank be the end of your investment journey.

Secure your next investment property with Mortgage Suite’s expert non-bank solutions. We look forward to helping you build a legacy of success through personalised, expert guidance and a proactive approach to your financial future.

Frequently Asked Questions

Are non-bank investment property loans safe in New Zealand?

Yes, non-bank loans are safe and strictly regulated under the Credit Contracts and Consumer Finance Act (CCCFA). These lenders must adhere to the same responsible lending codes as traditional banks, ensuring borrower protection. They are professional financial institutions, often backed by significant private capital or wholesale funding, providing a secure and legitimate alternative to the big four banks for your property portfolio.

How much higher are non-bank interest rates compared to mainstream banks?

Non-bank interest rates typically sit between 1% and 3% higher than mainstream bank rates, depending on your specific risk profile and the complexity of the deal. While the headline rate is higher, the flexibility they offer often offsets this cost. It allows you to secure high-yield properties that banks might reject, making it a strategic trade-off where you pay for agility and realistic serviceability testing.

Can I get a non-bank loan if I have bad credit?

Yes, many 2nd tier lenders specialise in "near-prime" or specialist loans for borrowers with imperfect credit histories. Unlike mainstream banks that often have a zero-tolerance policy for credit issues, non-bank lenders take a more holistic view of your current financial position. They focus on the quality of the property and your current ability to service the debt rather than being restricted by past financial hurdles.

Do non-bank lenders require a 40% deposit for investment properties?

No, non-bank lenders are not directly bound by the RBNZ’s LVR restrictions, which often allows for much lower deposit requirements. While mainstream banks generally require a 30% deposit for existing investment properties, **non bank investment property loans **can sometimes be secured with a 20% deposit. This flexibility is a primary reason why many savvy investors use these lenders to bridge the gap during rapid portfolio expansion.

How long does it take to get a non-bank loan approved?

Approval times for non bank investment property loans are significantly faster than mainstream banks, often taking just 48 to 72 hours for an initial assessment. Because these lenders have streamlined decision-making processes and aren’t bogged down by retail banking bureaucracy, you can move from application to settlement much faster. This speed is crucial when you’re competing for high-demand listings in a fast-moving market.

Can I use a non-bank lender for a property development project?

Yes, non-bank lenders are a preferred choice for property development loans because they offer more flexible terms than traditional banks. They are often more willing to fund projects based on the gross realisation value (GRV) rather than just the cost of construction. This allows developers to manage cashflow more effectively and take on projects that might not meet the rigid pre-sale or equity criteria of retail banks.

What happens if I want to switch back to a mainstream bank later?

Switching back to a mainstream bank is a common exit strategy that we help our clients manage through careful planning. Once your financial situation stabilises or the property’s equity increases, you can refinance your debt back to a Tier 1 lender to secure lower interest rates. This "graduation" process is a key part of long-term portfolio management and ensures you aren’t paying a premium rate for longer than necessary.

Is a non-bank loan the same as a ‘loan shark’?

No, non-bank lenders are professional financial institutions, not unregulated "loan sharks." They are legitimate businesses that must adhere to the Responsible Lending Code and Financial Markets Authority (FMA) guidelines. While their rates are higher than retail banks to reflect the increased risk or flexibility provided, they offer a transparent and legal service that serves as a vital alternative for borrowers who don’t fit narrow bank criteria.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.