Equity Release for Investment NZ: How to Fund Your Next Property in 2026

Borrowing the absolute maximum against your family home is the quickest way to stall your property plans before they begin. When looking into equity release for investment NZ buyers often assume that getting the green light from a bank manager is the hardest hurdle. Yet between tough serviceability stress tests and shifting Loan-to-Value restrictions, many Kiwis worry about risking the family home through messy cross-securitisation. If the borrowing process feels daunting, that hesitation is completely natural.

Fortunately, growing your portfolio does not mean putting your personal security at risk. You can access your built-up equity safely to fund a residential rental purchase while keeping your own home protected. We will walk you through how to calculate your usable equity accurately, structure your lending cleanly, and secure finance approval so you can get sorted without the guesswork.

Key Takeaways

  • Discover how equity release for investment NZ works, turning built-up property value into a usable deposit for your next residential rental purchase.
  • Learn how to calculate your true borrowing capacity by keeping a twenty percent equity safety net on your primary residence.
  • Protect your family home from risky cross-securitisation by structuring separate loan facilities across your properties.
  • Prepare the right documentation, including certified accounts and expenditure records, to satisfy lender serviceability stress tests.
  • Keep your investment momentum going with 2nd tier lenders if your regular bank turns down your application.

What Equity Release for Investment Means for Kiwi Homeowners

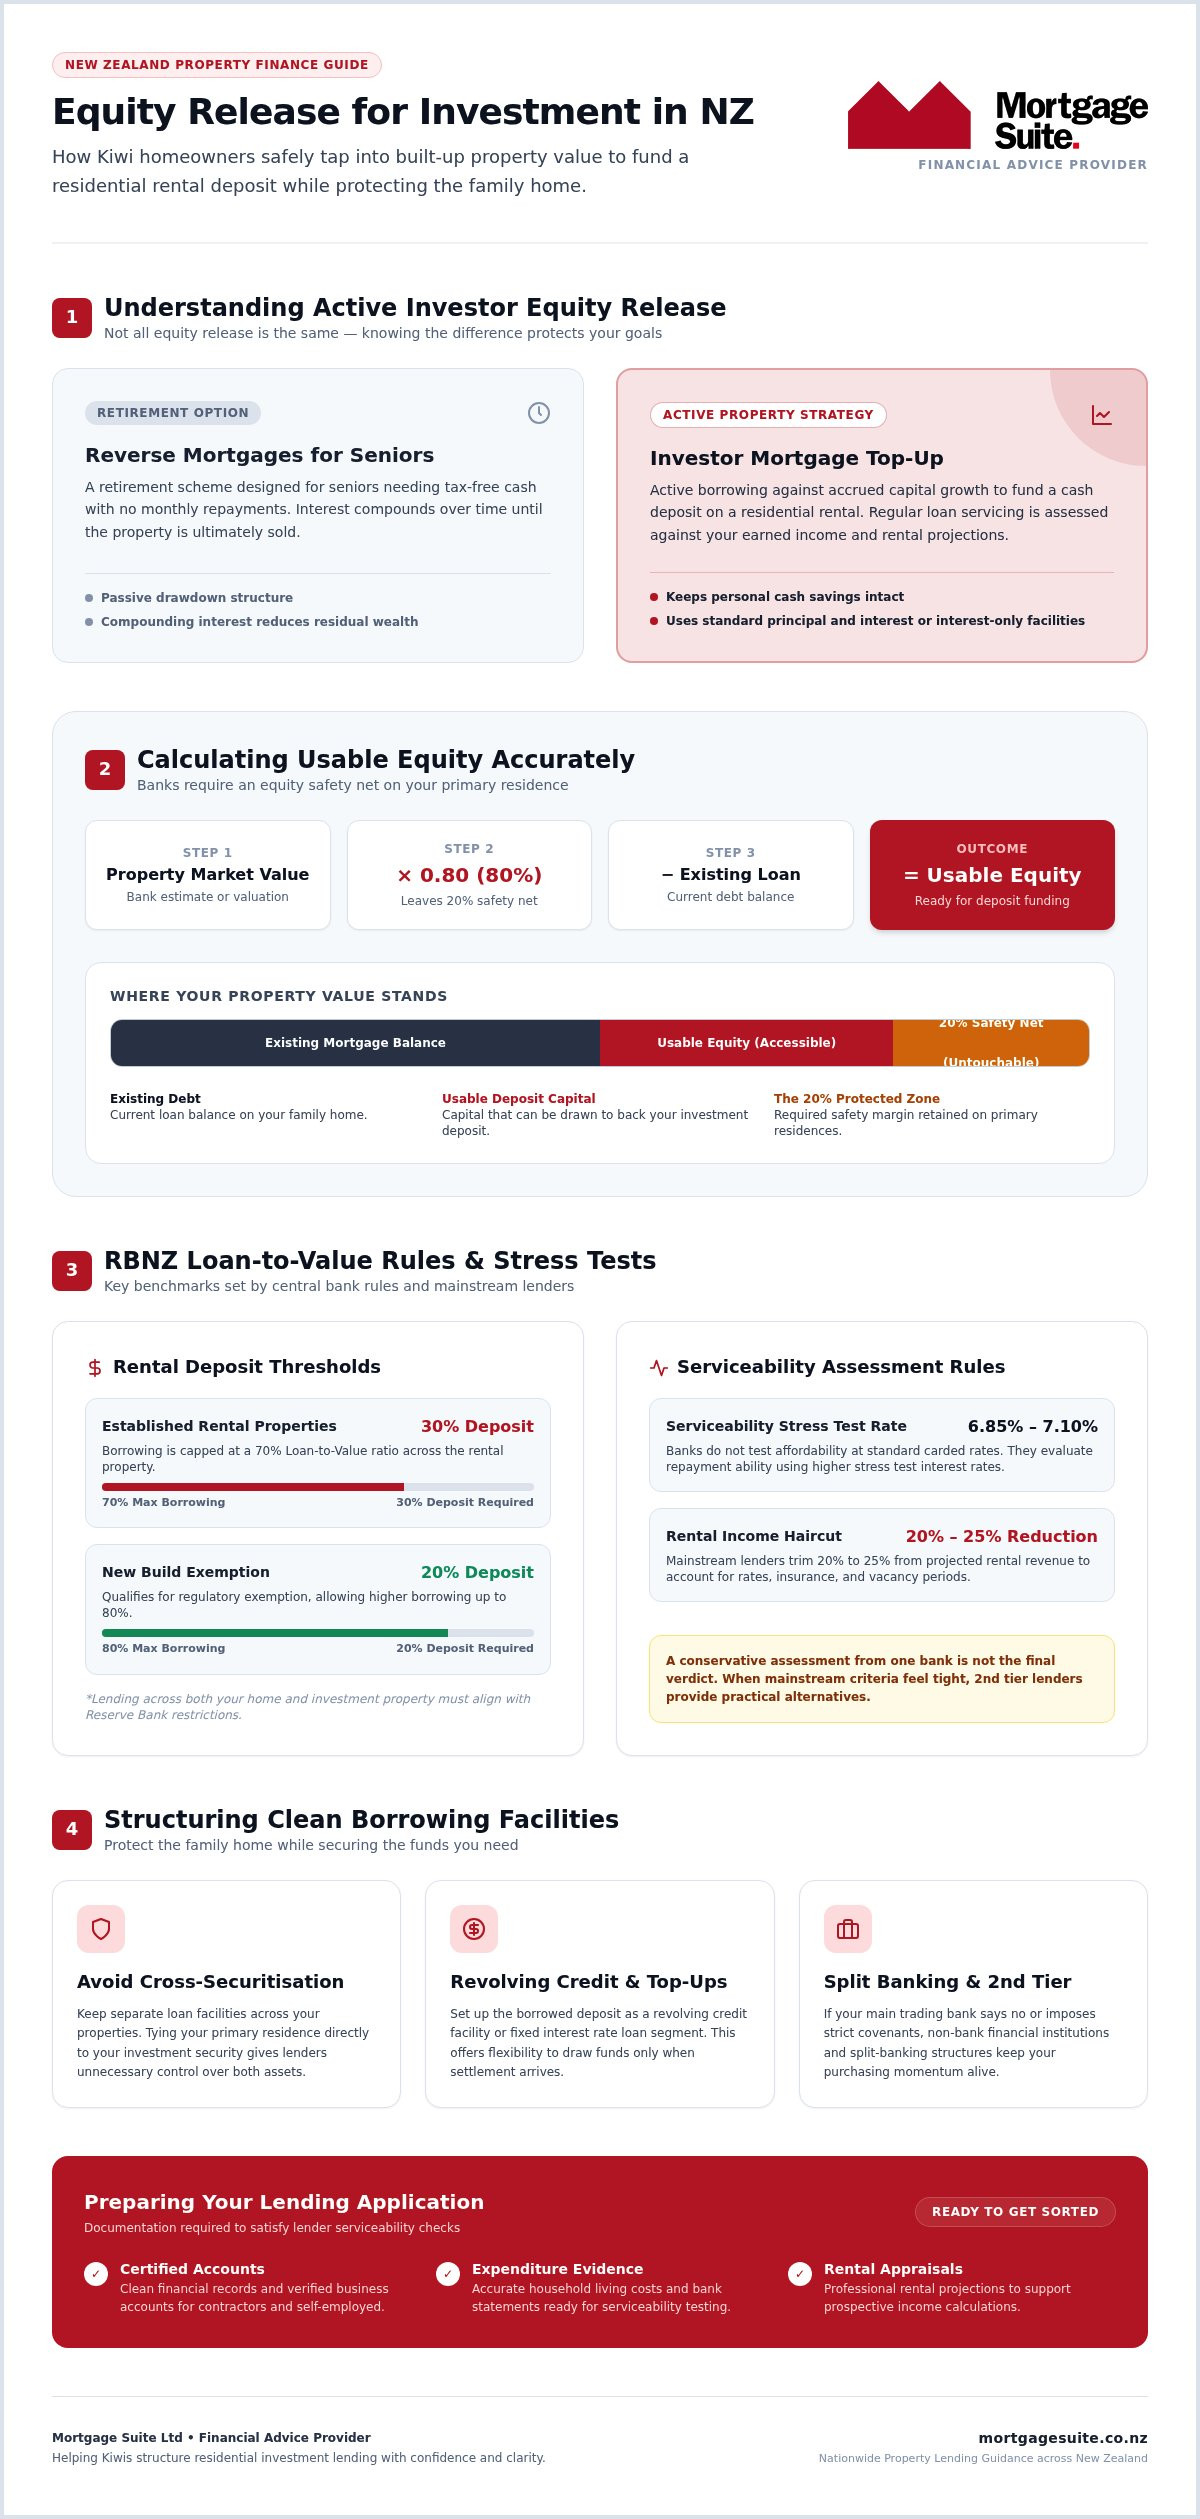
Many online guides define equity release purely as a retirement scheme for seniors wanting cash in their golden years. That narrow definition leaves working Kiwis in the dark. For active property buyers, what is home equity really comes down to? Simply put, it is the difference between your property’s current market value and the debt you owe against it. Using equity release for investment NZ wide is about borrowing against that built-up value to fund a deposit on a residential rental property.

Instead of waiting years to save a massive cash deposit from your salary, you tap into the capital gain your current home has earned. You keep your cash savings intact while your existing property acts as financial backing for the new purchase.

Investor Mortgage Top-Ups vs Retirement Reverse Mortgages

A reverse mortgage suits seniors who want tax-free cash without making monthly payments, with the interest compounding until the house sells. In contrast, an investor mortgage top-up is active borrowing. Lenders assess your current earned income and rental projections to ensure you can manage regular payments. Rather than eroding your wealth, this approach lets you take out residential investment property loans using standard principal and interest or interest-only facilities.

How Built-Up Property Value Serves as a Cash Deposit

Securing a rental deposit does not require emptying your bank account. Here is how your home’s value steps in:

  • Security over cash: The lender uses the equity safety net in your primary residence to establish a new loan segment.
  • Deposit funding: That new borrowing acts as the cash deposit for the investment property, meeting standard purchase requirements.
  • Flexible options: You can set up the borrowed deposit as a revolving credit facility or a fixed interest rate loan to suit your strategy.

This process gives everyday Kiwi homeowners a fair go at expanding their wealth. You can learn more about how mortgage structures operate by visiting the Mortgage Suite educational resources. With the right foundation in place, you can move forward with confidence and get sorted for your next investment.

Calculating Your Usable Equity Under Reserve Bank Rules

Working out how much you can borrow often brings a sharp reality check. Total equity is simply your home’s estimated market value minus your outstanding home loan. However, usable equity release for investment NZ homeowners can actually access is quite different. Banks do not allow you to borrow every dollar of value, as regulations and internal risk policies step in to maintain financial stability.

Calculating Usable Equity Beyond the Eighty Percent Line

Lenders insist on keeping an equity safety net of twenty percent on your primary residence. To find your usable portion, take the current bank desktop estimate or registered valuation of your home and multiply it by 0.80. Next, subtract your current home loan balance from that figure. The remaining sum represents the capital you can draw against your home to fund your investment plans.

Understanding Reserve Bank Loan-to-Value Restrictions for Rentals

The Reserve Bank of New Zealand enforces Loan-to-Value restrictions to manage lending risks across the housing market. For established residential rental properties, mainstream banks generally require a thirty percent deposit, meaning borrowing is capped at a seventy percent ratio on the investment property. While new builds qualify for an exemption that allows a twenty percent deposit, buying an existing house requires significant backing. Your borrowing across both properties must align neatly with these central bank guidelines.

If you want to run the numbers on your own home and test different scenarios, you can test your numbers using an online mortgage calculator to see where you stand.

Passing the Serviceability Stress Test with Mainstream Banks

Having enough equity is only half the battle; proving you can afford the repayments is the other. Even if actual carded mortgage rates sit lower, mainstream banks assess your borrowing capacity using a serviceability stress test rate between 6.85% and 7.10%. Lenders also apply haircuts to your numbers, often shaving 20% to 25% off projected rental income to allow for rates, insurance, and vacancies.

Facing strict bank criteria can feel discouraging, but remember that a conservative calculation from one lender is not the final word on your borrowing journey.

Structuring Your Facility: Revolving Credit, Top-Ups, and Split Banking

How you arrange your borrowing matters just as much as how much you borrow. A poorly structured loan can tie your hands financially, complicate your tax accounting, and leave your primary residence exposed. Getting equity release for investment NZ right means creating a deliberate borrowing architecture that separates your personal living costs from your investment activity.

Revolving Credit Facilities vs Fixed Term Loan Top-Ups

Setting up your borrowed deposit as a revolving credit facility gives you practical flexibility. Think of it as a pre-approved line of credit secured against your home. You do not pay a cent of interest until you actually draw down funds to pay a purchase deposit at an auction or signing. Once your residential rental purchase settles, you can choose to convert that drawn balance into a fixed interest rate term loan for repayment certainty, or keep a portion floating for quick repayment.

Why Split Banking Protects Your Family Home

Mainstream banks love cross-collateralisation because it bundles all your securities under one roof. If your family home and rental property secure every loan jointly, the bank controls the proceeds if you ever sell. Should market values drop or rental income dip, the bank can freeze funds or dictate terms across both assets.

Split banking breaks this stranglehold. Here is why savvy Kiwis use it:

  • Asset isolation: You release equity from Bank A to secure the deposit, then take the remaining seventy percent mortgage with Bank B.
  • Control over sales: If you sell the rental down the track, Bank B cannot demand you use surplus profits to pay down the mortgage on your family home.
  • Negotiating strength: Working across different lenders gives you options if one bank suddenly tightens its serviceability rules.

Using an Offset Account for Cashflow and Interest Management

An offset account links your everyday operational savings directly to a floating loan portion. Instead of earning taxable interest on rental income or maintenance reserves, the balance reduces the total loan amount used to calculate your daily interest charge. Keeping extra cash sitting against floating debt lowers your monthly costs without locking away your reserves.

Structuring these facilities properly protects your lifestyle while funding your property goals. You can explore how these banking setups work in detail through our mortgage school guides.
Equity Release for Investment NZ: How to Fund Your Next Property in 2026

Steps to Secure Your Property Investment Finance

Securing approval for equity release for investment NZ lenders require thorough groundwork. Mainstream banks enforce detailed scrutiny on every application, but taking an organised approach removes much of the friction and helps you present a clean financial profile.

Preparing Financial Documentation for Lender Assessment

Banks assess your bank statements line by line, evaluating discretionary spending and regular commitments under responsible lending guidelines. If you run a business or work on contract, lenders will want to see two full years of finalised, certified accounts alongside your personal tax summaries. Before approaching any lender, check your borrowing capacity by testing your figures on our mortgage calculator to ensure your budget holds up.

Due Diligence: Valuation and Professional Building Report Checks

Once you hold a conditional mortgage pre-approval, protecting your capital becomes the priority. Lenders often insist on an independent registered valuation to verify the property’s security value before confirming final loan release. At the same time, always commission an experienced inspector to inspect the property and supply a detailed building report. This check uncovers deferred maintenance, moisture issues, or structural defects that could affect bank appetite or trigger the Small Apartment Rule on smaller units.

Navigating Alternative Options with a 2nd Tier Lender

Getting a decline from a traditional high-street bank can feel like a setback, but it does not mean your investment journey is over. If your income includes contracting, irregular company distributions, or recent self-employment, a non-bank financial institution can assess your real-world affordability rather than relying on an inflexible automated scorecard.

You can explore how these alternative pathways work in our guide on 2nd tier lender New Zealand solutions. If you are ready to put an effective borrowing structure together, talk to our team to get your property finance on track.

Partnering with Mortgage Suite to Fund Your Investment

Securing the right loan is rarely about filling in an automated online form and hoping for the best. When managing equity release for investment NZ property buyers need a dedicated partner who understands how credit committees think. That is where Mortgage Suite steps in. As an accredited Financial Advice Provider, we serve as your personal advocate across major retail banks and specialist lenders, ensuring your lending structure protects your lifestyle from day one.

Our founder, Krish Krishna, brings over twenty years of banking and mortgage advisory experience to your corner. Having worked inside mainstream institutions, he knows how to position borrowing requests to gain approvals that standard channels often miss. You can discover more about us and our independent philosophy to see why Kiwi property owners rely on our steady guidance.

Personalised Advocacy and Dedicated Lender Negotiation

Every borrower’s situation is different, and one-size-fits-all algorithms rarely do justice to ambitious investors. We take the time to map out your long-term wealth goals before presenting a clean, compelling case to credit underwriters. Our focus remains on securing flexible loan structures, negotiating policy exceptions, and making sure you get a fair go.

You do not have to take our word for it either. Read through genuine client reviews to see how our hands-on advocacy has helped Kiwis navigate complex borrowing decisions with confidence.

Solutions for Complex Borrowers and 2nd Tier Lending

If you work as an independent contractor, run a young business, or have multiple income streams, mainstream bank branch managers often push back. We believe a conservative bank assessment should never halt your property goals. Mortgage Suite works closely with trusted non-bank financial institutions to secure 2nd tier loans that do not fit mainstream banks.

Whether you require standard bank finance or an alternative lending structure, our team arranges the right facilities to match your growth. Explore our guidance on residential investment property loans NZ to see how strategic funding can turn your home equity into long-term financial security.

Take the Next Step Toward Growing Your Property Portfolio

Building wealth through residential rental property does not require waiting decades to save a separate cash deposit or risking the family home. By understanding how equity release for investment NZ works, you can tap into accrued capital while maintaining a twenty percent equity safety net. Structuring your debt with split banking isolates your assets, keeps your accounting clean, and ensures you retain full control over your future sales proceeds.

You do not have to tackle lender stress tests or strict criteria on your own. As an accredited Financial Advice Provider delivering nationwide New Zealand service, Mortgage Suite brings over two decades of hands-on institutional banking expertise to your corner. Whether negotiating mainstream bank terms or securing non-bank financial institution lending for complex profiles, our focus is on finding the right fit for your situation. Talk with Krish and the team at Mortgage Suite to get your investment finance sorted and start planning your next property move today.

Frequently Asked Questions

How much equity do I need to buy an investment property in NZ?

You generally need enough equity to cover a thirty percent deposit for an existing residential rental property, while maintaining a twenty percent equity buffer on your personal home. For new builds, the required deposit drops to twenty percent under Reserve Bank rules. To assess your capacity, calculate eighty percent of your property’s value, subtract your existing mortgage, and see if the remaining usable equity covers your intended purchase deposit.

Is equity release for investment the same as a reverse mortgage?

No, equity release for investment NZ property buyers use is completely different from a retirement reverse mortgage. A reverse mortgage is tailored for seniors looking to draw cash without making monthly payments, allowing debt to compound over time. In contrast, investor equity release involves standard active borrowing based on your current earned income and rental projections, requiring ongoing principal and interest or interest-only repayments.

Can I release equity if my income is from contractor or self-employed work?

Yes, contractors and self-employed Kiwis can certainly access built-up equity to fund rental purchases. While mainstream banks often apply rigid criteria and demand multiple years of certified accounts, specialist non-bank lenders take a more practical view. They assess your real cashflow and recent business performance rather than relying on automated scoring systems, ensuring self-employed borrowers get a fair go.

What happens if a mainstream bank declines my equity release application?

A decline from a mainstream bank simply means your scenario did not fit their automated credit criteria, not that your property plans are finished. Retail banks use conservative affordability stress tests that penalise complex income or multiple debt facilities. In many cases, we can restructure your application or secure approval through a non-bank financial institution that provides flexible 2nd tier loans.

How does split banking help protect my home when releasing equity?

Split banking protects your family home by keeping your personal residence and investment property financed through separate lenders. If you place everything with a single bank, they hold cross-collateralised security across both properties and can control the sale proceeds if you sell. Dividing your lending isolates risk, giving you peace of mind when executing an equity release for investment NZ strategy.

Do I have to pay interest on my released equity immediately?

Not if you structure the borrowed deposit as a revolving credit facility or an offset account. With a revolving facility, you only pay interest on the money you actually draw down to pay auction deposits or settlement funds. Until you find a property and sign a contract, your pre-approved limit sits waiting without accruing unnecessary interest charges.

Will I need a registered valuation to access my home equity?

You might not need one if your lender accepts an automated desktop estimate, but higher borrowing levels usually require a full registered valuation. Mainstream banks frequently accept electronic valuations when your debt level is conservative. However, when you are accessing usable equity near the eighty percent threshold, lenders require an independent registered valuer to verify the property’s security value.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Bank Declined Your Mortgage? Next Steps & Options

What if a “no” from your bank isn’t actually the end of your home-buying journey, but just a sign that you’re knocking on the wrong door? If you’ve just had your bank declined mortgage what next nz is likely the only question on your mind, especially if you’re worried about losing a deposit or feeling stuck because of a complex credit history. It’s a tough spot to be in, and it’s completely natural to feel frustrated when a rigid lending policy stands between you and your new home.

I understand that sense of rejection, but I also know from years of experience that there’s almost always a way forward. You deserve a clear path to home ownership that doesn’t involve jumping through impossible hoops. This article will show you exactly how to turn things around by exploring the practical steps you can take right now to secure your finance. We’ll look at why banks say no, how to polish your application, and the alternative lending options that specialise in helping people who don’t fit the standard banking box.

Key Takeaways

  • Understand why a “no” from a big bank is often just about their narrow criteria rather than your actual ability to buy a home.
  • Learn how to address the most common reasons for a bank declined mortgage what next nz, from improving your credit history to proving your income.
  • Discover how 2nd tier lenders act as a legitimate stepping stone to help you secure a home loan when mainstream banks won’t budge.
  • Follow a practical five-step plan to clean up your financial backyard and prepare a stronger application that lenders can’t ignore.
  • Find out how 20 years of banking experience can help you navigate the system and access lenders that aren’t available to the general public.

Why Being Declined by the Bank Isn’t the End of the Road

Opening a letter or email to find your mortgage application has been declined feels like a punch in the gut. After weeks of collecting bank statements, proving your income, and dreaming of your new lounge, that single “no” can make the whole process feel like a waste of time. If you’ve found yourself with a bank declined mortgage what next nz is the question that needs a calm, strategic answer. It is important to realise that a decline isn’t a reflection of your worth or even necessarily your ability to pay back a loan. It’s often just a sign that you didn’t fit into one specific bank’s very small, very rigid box.

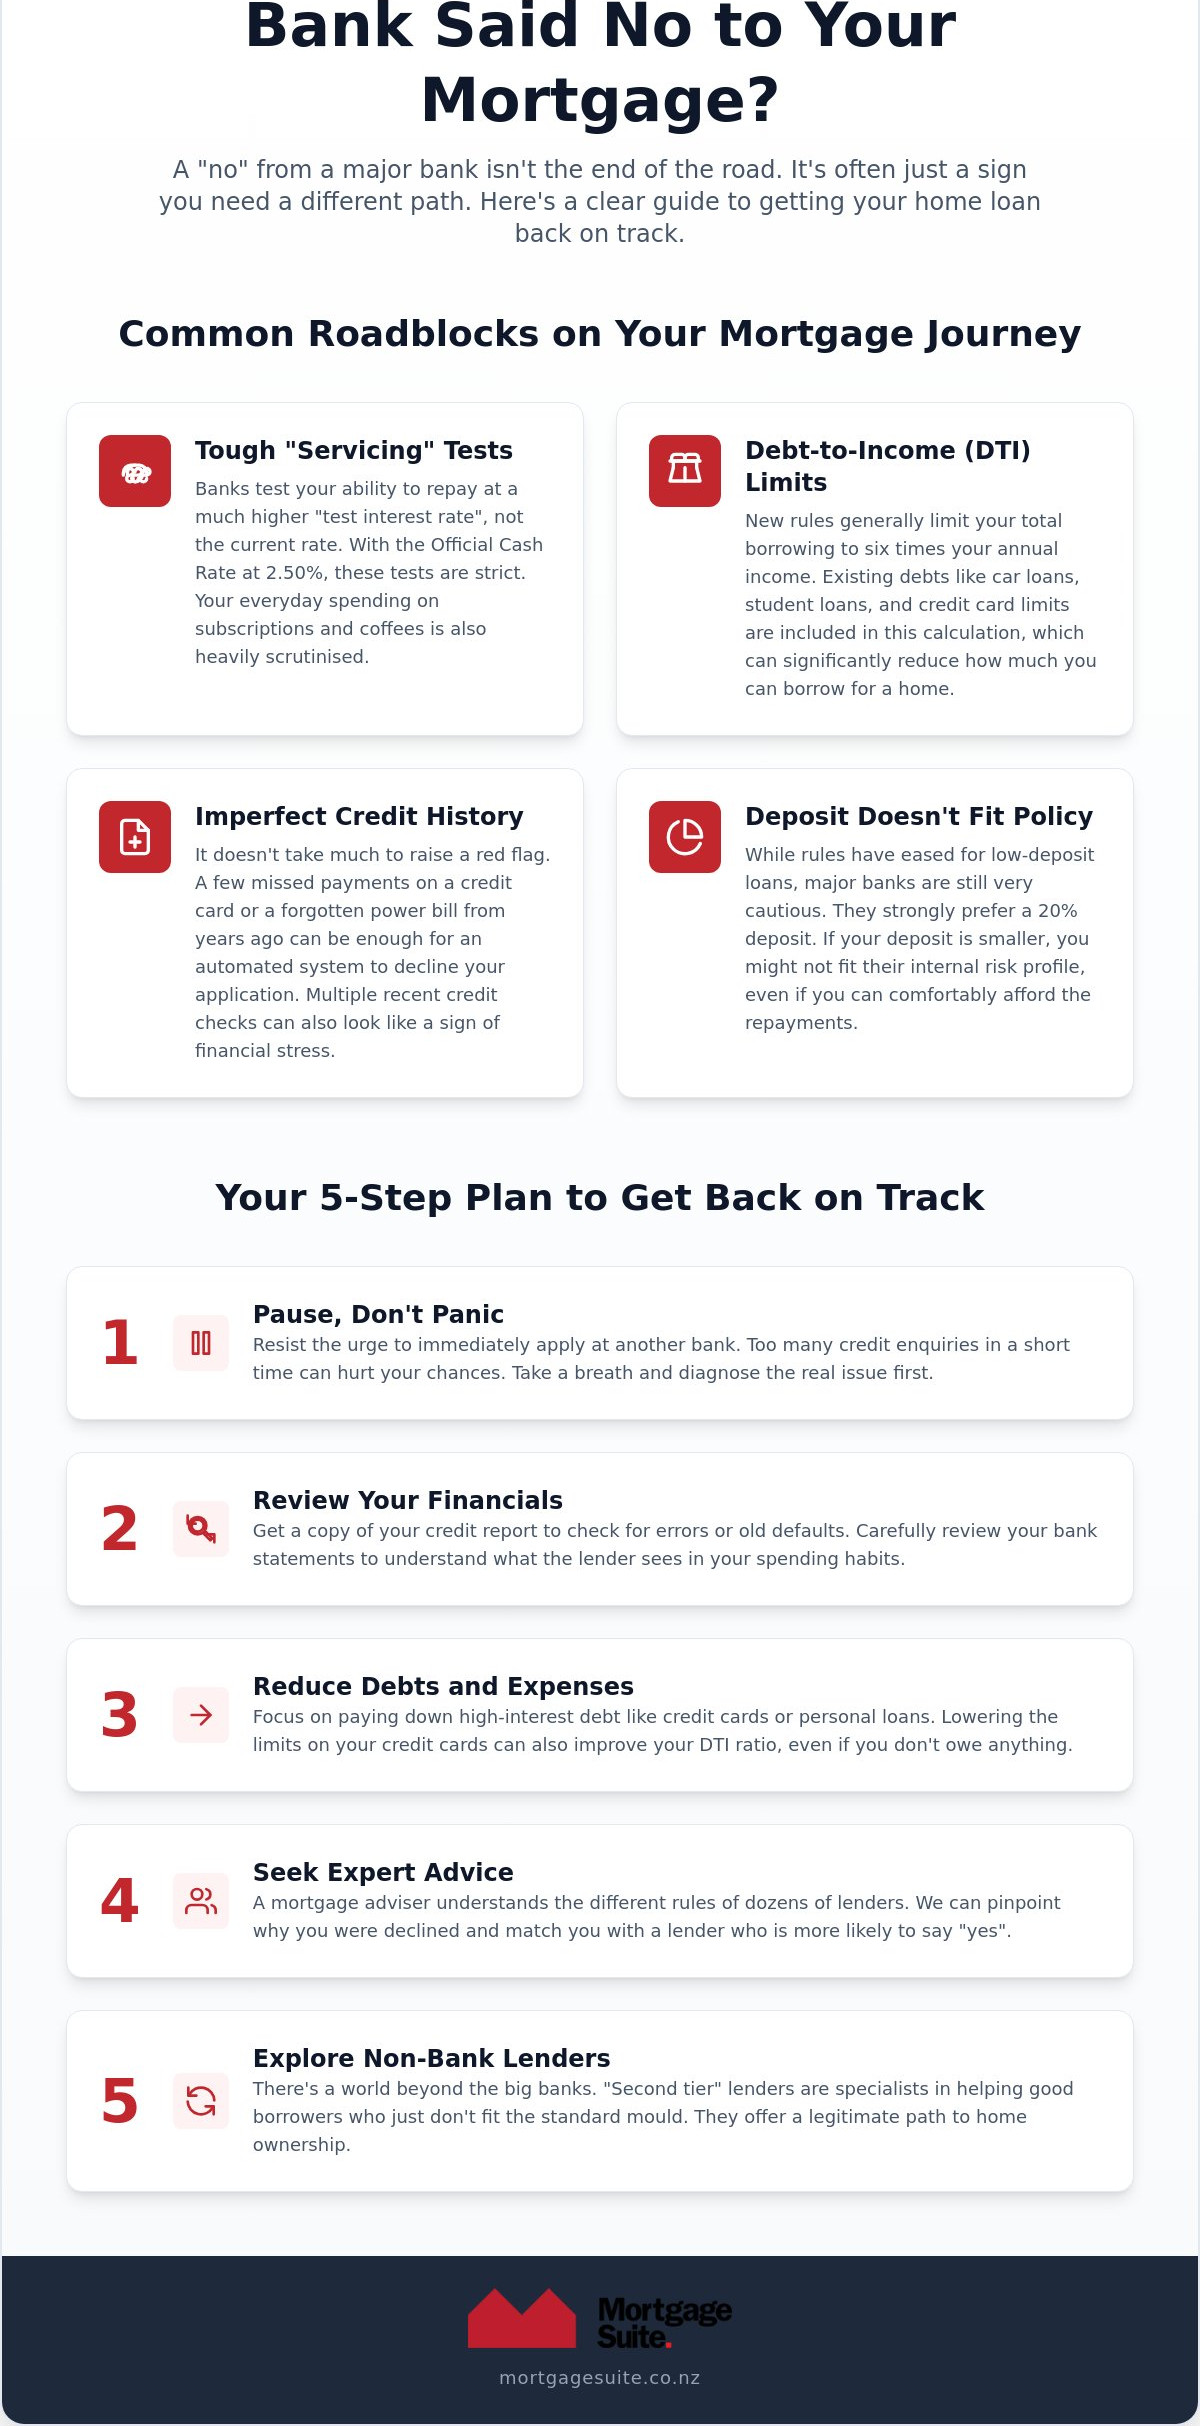
Mainstream banks in New Zealand operate on high volumes and low risk. They use automated systems to filter applications, and if your situation has even one minor detail that doesn’t align with their current policy, the system may reject it automatically. This is a standard part of the mortgage underwriting process, where lenders assess risk based on strict formulas. In 2026, these formulas have become even tighter. With the Official Cash Rate (OCR) sitting at 2.50% as of July 2026, banks are being incredibly cautious about how they test your ability to handle interest rates.

Understanding the New Zealand Lending Landscape

The Reserve Bank of New Zealand (RBNZ) sets the boundaries that all major banks must play within. Even though LVR restrictions eased slightly in late 2025, allowing banks to give more loans to people with deposits under 20 percent, the introduction of Debt-to-Income (DTI) limits has created a new hurdle. Currently, owner-occupiers are generally limited to borrowing six times their annual income. If your dream home costs just a bit more than that calculation allows, a mainstream bank will likely say no, even if you have a spotless spending record and a great career. This is why alternative lending has become such a vital part of the market for regular Kiwis who just need a bit more flexibility.

Taking a Breath Before Your Next Move

When you get a decline, your first instinct might be to rush to the bank across the street to try again. I strongly suggest you pause. Every time you submit a formal application, the lender performs a credit check that leaves a “footprint” on your credit report. If other lenders see four or five enquiries in a single month, it can look like you’re in financial distress, which might lead to further declines. Instead of guessing what went wrong, this is the time to get an expert to look at your file. We can identify if the issue was your deposit, your debt levels, or simply that specific bank’s internal appetite for risk at that moment. A “no” from one bank is often just a prompt to change your strategy, not to give up on the property altogether.

Common Reasons for a Declined Home Loan in NZ

When a bank turns you down, they often provide a vague explanation that leaves you more confused than when you started. Most declines boil down to a few specific areas where your financial life didn’t quite line up with their current rulebook. Identifying which hurdle tripped you up is the first step in figuring out your bank declined mortgage what next nz strategy. It’s rarely about one single mistake; rather, it’s about how the bank’s computer perceives the risk of your overall situation.

One of the biggest reasons for a decline today is “servicing,” which is just a fancy way of saying the bank isn’t sure you can comfortably afford the monthly payments. Since the Reserve Bank raised the OCR to 2.50% in July 2026, banks have increased their “test rates.” This means they don’t just check if you can afford the current interest rate, but whether you could still pay if rates climbed much higher. They also look closely at your daily habits. Regular spending on gym memberships, streaming services, or even that daily flat white can sometimes be enough to tip your debt levels over the edge in the bank’s eyes.

The “Unseen” Factors: DTI and Expenses

Debt-to-Income (DTI) ratios have become a major factor in New Zealand lending recently. Debt-to-Income is the balance between what you earn and what you owe. Under current rules, most owner-occupiers are restricted to borrowing up to six times their annual income. If you have existing car loans or credit card limits, these are added to your total debt, which can quickly shrink the amount the bank is willing to lend you for a home.

Credit history is another common sticking point. You don’t need a massive bankruptcy to get a “no.” Something as small as a forgotten power bill from three years ago or a few missed credit card payments can flag you as a risky borrower. Similarly, the size of your deposit matters immensely. While the Reserve Bank eased rules in December 2025 to allow more low-deposit lending, many banks still prefer the safety of a 20 percent deposit and will decline applications that don’t meet their internal equity targets.

The property itself can also be the problem. Banks are often wary of apartments smaller than 40 or 50 square metres, or lifestyle blocks with “quirky” titles. They want to know that if they ever had to sell the house, it would be easy to find a buyer.

Income Issues for the Self-Employed

If you work for yourself, you’ve likely noticed that banks treat you differently than someone with a standard payslip. Most mainstream lenders demand at least two full years of finalised accounts to prove your income is stable. This is a massive barrier for new business owners or those who have had a fluctuating year. Because of this, self-employed home loans require a much more personalised approach to show the lender the true strength of your business. If you’re feeling stuck, it might be time to chat with an expert who can help tell your story to the right lender.

The Non-Bank Option: Exploring 2nd Tier Lenders

If your bank declined mortgage what next nz is likely the big question keeping you up at night. While it feels like the end of the road, it is actually just an invitation to look at the non-bank sector. These lenders, often called 2nd tier lenders, are a legitimate and safe alternative for Kiwis who don’t meet the strict, computer-generated criteria of the big four banks. They are regulated under the same Responsible Lending Code, meaning they have a legal duty to ensure you can afford the loan without hardship.

The biggest difference is that alternative lenders are willing to listen to your story. If you had a rough patch with a business or a minor credit issue three years ago, a mainstream bank might automatically reject you. A non-bank lender looks at the context. They want to see that you’re back on your feet now and can handle the repayments. This human-led approach is why 2nd tier lenders in NZ are becoming a go-to option for regular families who just need someone to look at the bigger picture rather than just a credit score.

The trade-off for this flexibility is usually a slightly higher interest rate. For example, while major banks in July 2026 might offer one-year fixed rates around 5.28 percent, a non-bank like Avanti Finance might start their rates from 6.35 percent. It is important to view this extra cost as a temporary investment. For many of my clients, a 2nd tier loan is a bridge. It allows you to buy the house today, prove your reliability for a year or two, and then move back to a mainstream bank once your credit history is clean or your business accounts show more consistency.

Mainstream Banks vs. 2nd Tier Lenders

Mainstream banks want the perfect borrower. They look for stable PAYE income, a 20 percent deposit, and a spotless credit report. 2nd tier lenders are much more comfortable with near-prime situations. They are also often more willing to finance properties that banks shy away from, such as apartments under 40 square metres or rural properties that don’t fit standard residential categories. They aren’t loan sharks; they are professional financial institutions that simply have a higher appetite for complex cases.

Is an Alternative Loan Right for You?

If you are trying to buy your first home and have been told no because of a small credit blip, this could be your best path forward. The key is having a solid exit strategy. We don’t just get you the loan; we plan for how you’ll eventually move to a lower-rate lender. This might involve cleaning up your spending habits or waiting for an old credit default to drop off your record. By using a non-bank loan as a stepping stone, you can get into the market now rather than waiting years to save a larger deposit while house prices potentially move further out of reach.

Bank Declined Your Mortgage? Next Steps & Options

Your 5-Step Plan to Get Your Mortgage Back on Track

Once the initial shock of a rejection wears off, it is time to shift into problem-solving mode. If you are wondering about a bank declined mortgage what next nz based strategies, you need a methodical approach to transform your financial profile into something a lender will find irresistible. This isn’t about hiding the truth; it is about presenting your strongest possible case. Following a structured plan helps remove the emotion from the situation and puts you back in the driver’s seat of your property journey.

  • Step 1: Ask for the specific reason. You have a right to know why your application was turned down. Don’t settle for “you didn’t meet our criteria.” Ask if it was your income, your credit history, or perhaps the property itself. This information is the foundation of your comeback.
  • Step 2: Clean up your financial backyard. Lenders typically look at your last 90 days of spending. Commit to three months of “clean” living where your bank statements show discipline, regular savings, and no red flags.
  • Step 3: Check your credit report. Errors on credit files are more common than you might think. Grab a copy of your report from providers like Equifax or Centrix and ensure every entry is accurate. If there’s a mistake, get it fixed immediately.
  • Step 4: Lower your debt. Even if you don’t pay off a loan entirely, closing unused credit cards or reducing your limits can significantly improve your borrowing power under current rules.
  • Step 5: Partner with a specialist. A mainstream bank manager can only offer you their own bank’s products. A specialist broker has the freedom to shop your application around to lenders who actually want your business.

Cleaning Up Your Bank Statements

Think of your bank statements as a CV for your money. To “dress up” your spending habits, you should pause any “Buy Now Pay Later” services like Afterpay or Laybuy. Even if you pay them on time, banks often view these as a sign of poor budgeting. You should also ensure that your accounts show a clear, consistent pattern of savings. Moving a set amount to a separate account every payday proves you can handle the commitment of a mortgage. It is about showing the lender that you have a surplus at the end of the month, not just that you’re surviving until the next payday.

Finding the Right Specialist

When a bank says no, a standard bank manager’s hands are tied by their head office policy. They simply cannot help you further. This is where a broker with deep banking experience becomes your greatest asset. I use my 20 years of “inside” knowledge to act as a negotiator on your behalf. I know which lenders are currently looking for more business and which ones are likely to be flexible with your specific situation. Having a veteran in your corner means your application is positioned correctly from the start, saving you time and protecting your credit score from unnecessary enquiries. If you’re ready to find a solution that works for you, get in touch with Mortgage Suite Ltd today and let’s look at your options together.

How Mortgage Suite Ltd Turns a “No” into a “Yes”

When you’ve had a bank declined mortgage what next nz is usually the query that brings you to a specialist who knows the system from the inside. This is where Mortgage Suite Ltd steps in. Krish Krishna brings over 20 years of banking experience to your corner, which means he doesn’t just guess what a lender wants; he knows exactly how they think. Having spent two decades inside the very institutions that might be saying no to you right now, Krish understands the hidden levers that can be pulled to get an application across the line.

We have built strong relationships with a wide range of lenders, including many that the general public cannot approach directly. These institutions often reserve their best products for trusted partners who can present a high-quality, well-packaged case. Our process involves more than just filling out forms. We take the time to build a comprehensive narrative around your finances, highlighting your strengths and providing clear, honest context for any past hurdles. We don’t just want to get you a one-off loan; we want to set you up for long-term success so you can eventually move back to mainstream banking on your own terms.

A Personal Approach to Complex Loans

At Mortgage Suite Ltd, we treat you like a partner rather than just another file on a desk. We know that your situation is unique, especially if you are looking into residential investment property loans or have a complex income structure. Handling the heavy lifting and negotiation is what we do best. We take over the stressful conversations with lenders and credit managers, using our reputation and expertise to advocate for your future. This proactive approach allows you to focus on finding the right property while we handle the technicalities of the finance.

Ready to See What’s Possible?

If you’re feeling stuck after a rejection, remember that your search for a bank declined mortgage what next nz has brought you to a team that specialises in second chances. The first step in our process is a simple, friendly chat. There is absolutely no jargon and no judgement regarding your past credit issues or business fluctuations. We are only interested in where you want to go and how we can help you get there. You’re invited to take the first step toward your new home by reaching out for a no-obligation conversation today.

Taking Control of Your Home Ownership Journey

Getting a “no” from a major bank is a setback, but it certainly doesn’t have to be the end of your property dreams. By understanding that banks have very narrow boxes, you can start looking at the bigger picture. Whether it’s exploring 2nd tier lenders as a temporary bridge or spending a few months cleaning up your spending habits, there is always a path forward. If you have been left wondering about a bank declined mortgage what next nz, the answer is to stop guessing and start strategising with someone who knows the system from the inside.

You deserve a partner who will advocate for your success rather than just processing a form. With over 20 years of banking and lending expertise, I specialise in finding 2nd tier and non-bank solutions for Kiwis who don’t fit the standard mould. I act as a dedicated NZ negotiator to ensure your story is heard by the right people. Talk to Krish today about your alternative mortgage options and let’s find the right door to knock on. Your future home is still within reach; you just need the right guide to help you get there.

Frequently Asked Questions

Can I apply at another bank if one has already declined me?

Yes, you certainly can, but you should avoid doing so immediately without a plan. Every bank in New Zealand has its own internal rules and “appetite” for risk, so a “no” from one doesn’t automatically mean a “no” from all. However, rushing to another bank can lead to multiple credit enquiries in a short space of time, which can actually lower your credit score and make future approvals even harder to get.

How long do I have to wait to reapply after a mortgage decline in NZ?

There is no official waiting period, but the right timing depends on why you were turned down. If the bank declined your application because of your recent spending habits, you should wait at least three months to show a new, cleaner set of bank statements. If the decline was simply because that specific bank doesn’t like the type of property you are buying, you could potentially apply elsewhere much sooner with expert help.

Will a declined mortgage application stay on my credit record?

The fact that you were declined is not recorded, but the enquiry itself will show up on your credit report. Lenders can see that you applied for a home loan and which company you applied with. If a new lender sees several enquiries but no new mortgage account appearing on your file, they may conclude that you were declined elsewhere, which can flag you as a higher risk borrower.

Are interest rates much higher with 2nd tier lenders?

Yes, interest rates are typically higher with non-bank lenders because they take on borrowers that mainstream banks consider too risky. As of July 2026, while a major bank might offer a one-year fixed rate around 5.28 percent, a 2nd tier lender like Avanti Finance may start their rates from 6.35 percent. Most Kiwis view this extra cost as a temporary bridge to get into a home while they work toward meeting bank criteria again.

What is the most common reason for a mortgage decline in 2026?

The most frequent reason for a bank declined mortgage what next nz in 2026 is “servicing” issues related to Debt-to-Income (DTI) limits. With the OCR currently at 2.50 percent, banks are using very high test rates to ensure you can afford repayments if interest rates climb. Many applicants find they are declined because their total debt, including credit cards and car loans, exceeds six times their annual before-tax income.

Can a mortgage broker really help if the bank already said no?

A specialist broker is often the only way to secure an approval after a bank decline. We have access to a wide range of alternative lenders that do not deal with the general public directly. By using 20 years of banking experience, we can often find a “policy fit” that the big banks missed or suggest a 2nd tier lender that is happy to look at your personal story rather than just a computer score.

Do I need a bigger deposit if I use a non-bank lender?

Not necessarily, though having more equity always helps your case. Many 2nd tier lenders are comfortable with a 20 percent deposit, and some may even consider lower amounts depending on the strength of your income. However, if your credit history has significant issues, a lender might ask for a larger deposit to offset the risk. We can help you identify which lenders are currently the most flexible with deposit requirements.

What should I say to the bank when they tell me I am declined?

You should calmly ask for the specific reason for the decline in writing, as this is your right as a consumer. Ask them to be precise about whether the issue was your income level, your credit report, or the specific property you wanted to buy. This information is vital because it allows us to fix the exact problem before we approach a different lender, ensuring your next application has a much higher chance of success.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

2nd Tier Lender New Zealand: Your 2026 Guide to Alternative Home Loans

What if the bank’s “no” isn’t actually the end of your home-buying journey, but just a sign you’re looking in the wrong place? It is incredibly disheartening to feel like a mere tick-box on a spreadsheet, especially when a slightly messy credit history or self-employed income makes you “too hard” for traditional lenders. Finding a 2nd tier lender New Zealand wide can be the breakthrough you need, offering a common-sense approach that looks at your whole financial picture rather than just a computer-generated score.

We understand the anxiety that comes with being turned away, but these alternative options are designed for people who need a partner, not just a processor. This guide explores how to secure a flexible home loan that respects your unique situation, providing a fair go when the big banks won’t budge. You will discover exactly how these lenders operate in 2026, the specific benefits they offer for non-standard financial profiles, and how to create a clear strategy for eventually refinancing back to a mainstream bank once your circumstances settle.

Key Takeaways

  • Understand that 2nd tier lenders are professional, legitimate institutions that offer a genuine alternative when big banks won’t help.
  • Discover how a 2nd tier lender New Zealand wide uses a common-sense approach to look at your whole financial picture rather than just ticking boxes.
  • Learn why flexibility often comes with a slightly higher interest rate and how the speed of these lenders can save your property deal.
  • Find out how to organise a professional paper trail and why being upfront about your history helps secure a faster approval.
  • Explore how seasoned expertise can bridge the gap between rigid banking rules and your personal goal of home ownership.

What is a 2nd Tier Lender in New Zealand?

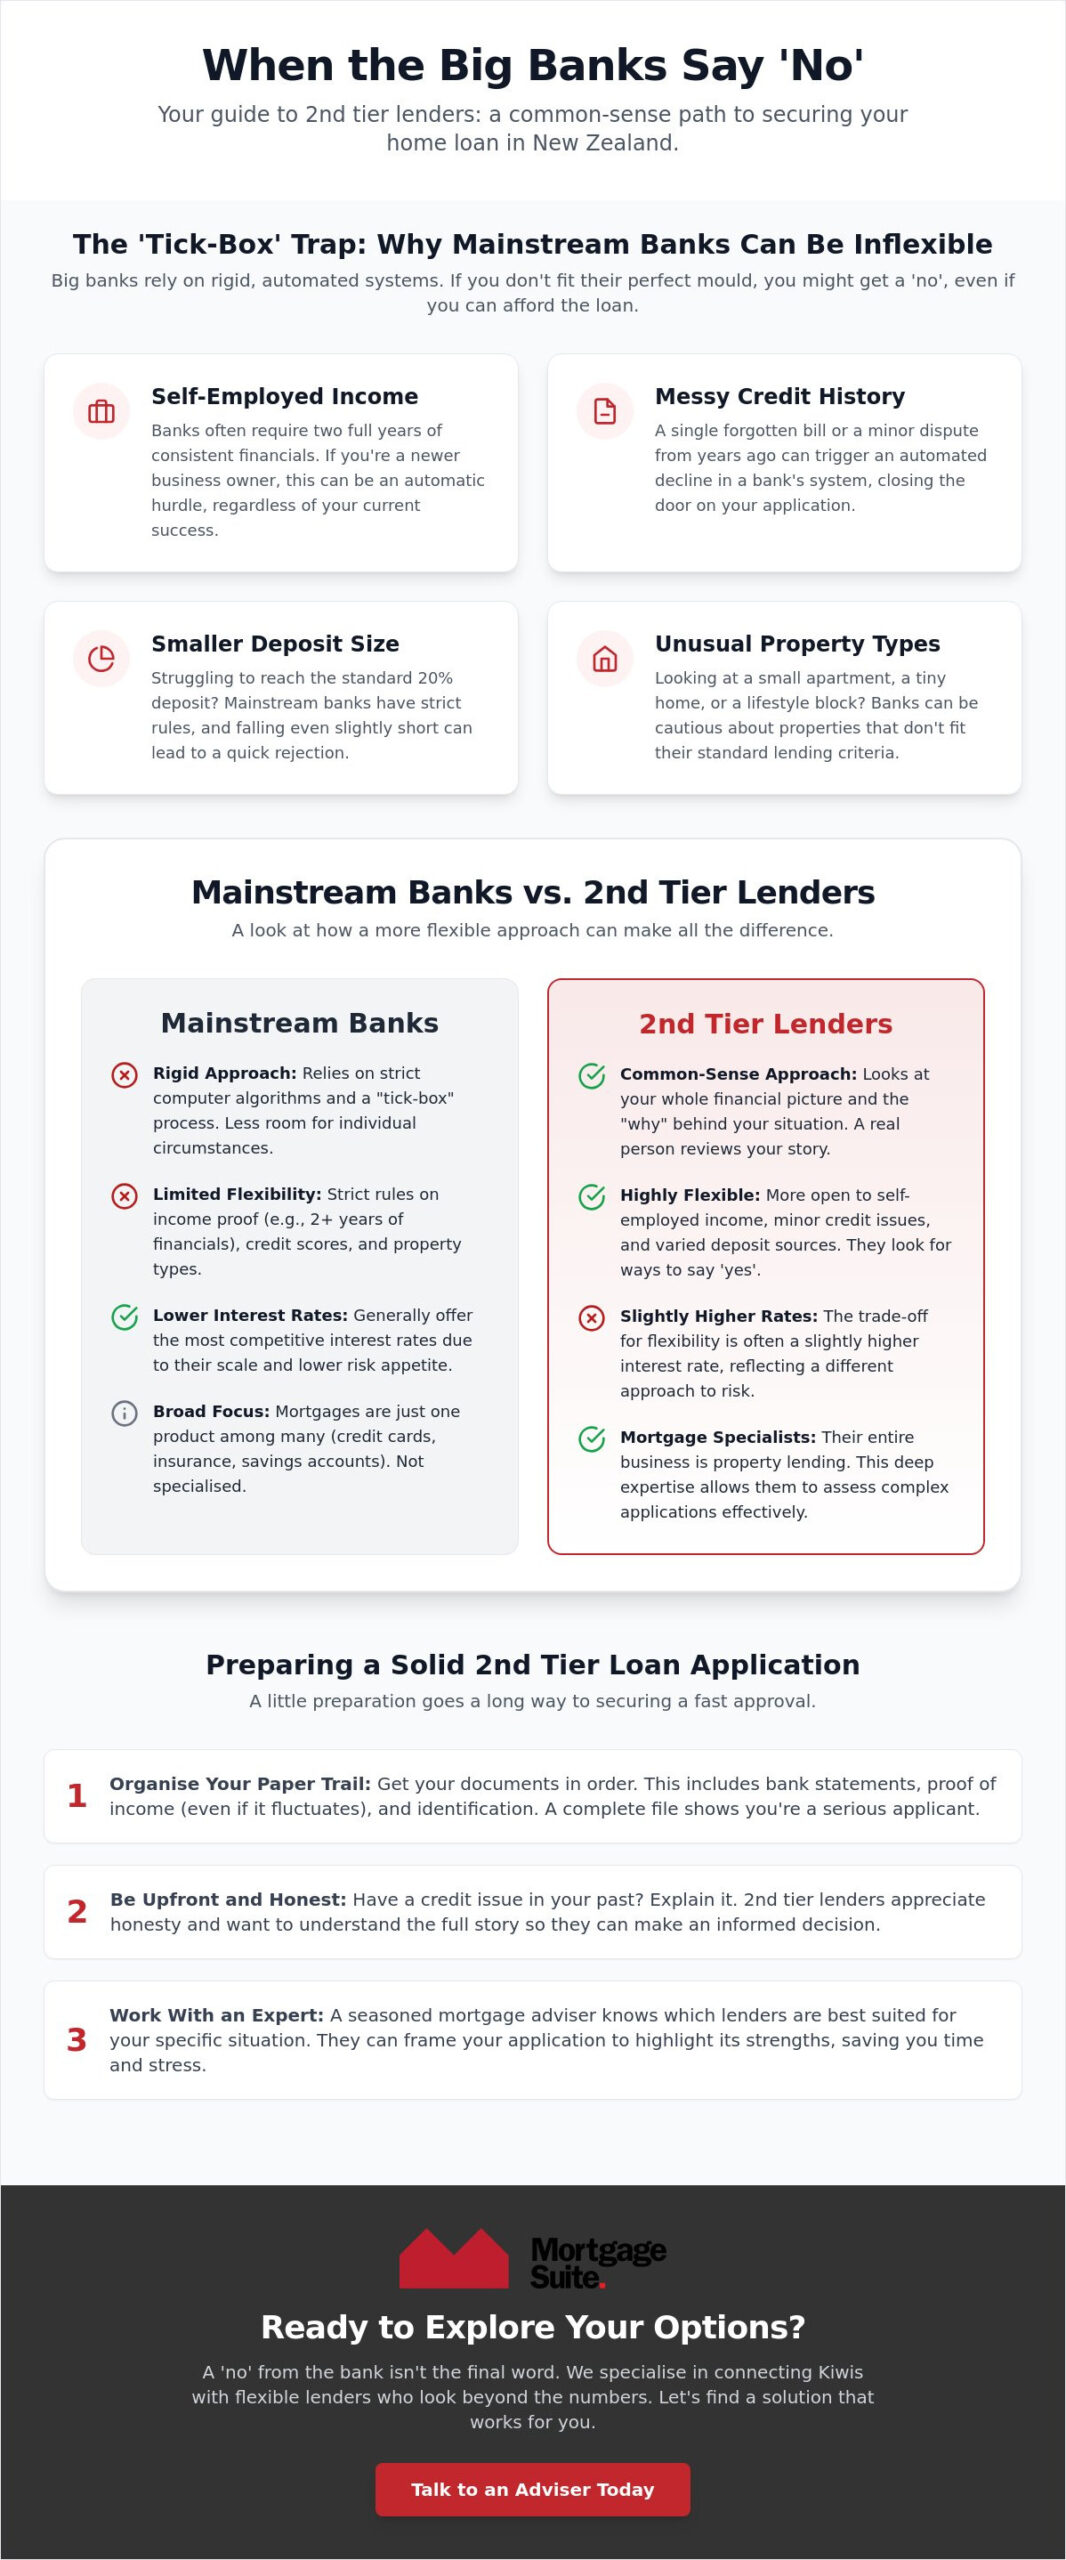
Think of a 2nd tier lender as a specialised financial institution that focuses purely on helping people secure property. Unlike the big banks you see on every street corner, these organisations don’t offer everyday savings accounts, credit cards, or travel insurance. They aren’t “retail banks” in the traditional sense; instead, they are professional lenders who use their own capital or institutional funds to provide mortgages. This narrow focus is actually their greatest strength because it allows them to be far more flexible than a bank that’s trying to be everything to everyone.

The main difference you’ll notice is the way they look at your application. While big banks often rely on rigid computer algorithms that spit out a “yes” or “no” based on strict “tick-box” criteria, a 2nd tier lender New Zealand homeowners use often applies a common-sense approach. They’re interested in the “why” behind your financial situation. If you’re self-employed and your income fluctuates, or if you had a minor credit hiccup a few years ago, these lenders are more likely to look at the big picture rather than just the numbers on a screen. They provide a vital alternative for Kiwis who have the ability to pay a mortgage but don’t quite fit the narrow mould of mainstream banking.

Non-Bank vs. 2nd Tier: Is there a difference?

No worries if you’re a bit confused by the different names; they basically mean the same thing in our local market. “Non-bank” describes their legal structure, meaning they are a non-bank financial institution that doesn’t hold a full banking licence from the Reserve Bank. “2nd tier” describes their position as a secondary option to the “Big Four” banks. Whether you call them non-banks or 2nd tier, the result is the same: a professional lender that offers a different path to home ownership.

Why they are a safe bet for Kiwis

Some people worry that stepping away from a big bank means less protection, but that isn’t the case. Every 2nd tier lender New Zealand has must follow the Credit Contracts and Consumer Finance Act (CCCFA). This means they are legally required to be responsible lenders, just like the household names. These institutions have been a solid part of our property market for decades. Many are backed by massive global investment firms or well-known local institutions, ensuring they have the stability and reputation to support your long-term goals. They aren’t “last resorts” but rather strategic partners for those who need a more personalised touch.

Why the Mainstream Banks Might Say ‘No’

It’s a sinking feeling when you’ve done everything right, saved your deposit, and found the perfect home, only to have a bank manager shake their head. The reality is that the Big Four banks are massive machines built for speed and volume. To keep things moving, they rely on rigid, one-size-fits-all rules. If your financial situation has even a tiny bit of “colour” or complexity, you often fall outside their very narrow appetite for risk. A “no” from a mainstream lender usually isn’t a reflection of your ability to pay; it’s simply a sign that you don’t fit their specific, pre-programmed mould.

This is where a 2nd tier lender New Zealand wide provides a much-needed alternative. While banks look for reasons to say no to protect their high-volume systems, 2nd tier lenders look for reasons to say yes. They take the time to understand the story behind the numbers. They recognise that modern lives are rarely tidy, and they’re willing to look at the big picture of your financial health rather than just a computer-generated score.

Common hurdles for the ‘Big Four’

There are several reasons why a perfectly capable borrower might get a “thanks, but no thanks” from a traditional bank. These hurdles are often non-negotiable for mainstream lenders:

  • Self-employed income: Banks usually demand two full years of perfect financial records. If you’ve been in business for 12 months and are doing well, a bank might still decline you simply because you haven’t reached that two-year mark.
  • Deposit size: With government rules often requiring a 20% deposit for owner-occupiers, many Kiwis find themselves just a few thousand dollars short.
  • Credit history: A forgotten power bill from three years ago or a minor credit card dispute can stay on your file and trigger an automatic decline in a bank’s system.
  • Property types: Banks are often wary of apartments under a certain size, tiny homes, or lifestyle blocks with unusual titles.

The ‘Tick-Box’ trap

Modern banking relies heavily on automated software. When you submit an application, an algorithm scans for specific data points. If one “box” isn’t ticked, the system can auto-decline the application before a person even looks at it. In contrast, the 2nd tier space relies on a human-led decision-making process. These are experienced professionals who can see that a past credit hiccup was a one-off event or that your self-employment income is stable and growing. This approach is the foundation for non-conforming loans, which are specialised products designed specifically for “out-of-the-box” situations that don’t meet standard bank criteria. If you’re feeling stuck in this tick-box trap, it might be time to talk to an expert who knows how to present your case to the right people. If you’ve already received a formal rejection, our comprehensive guide for those declined by bank home loan NZ applicants explains exactly what steps to take next to recover and find a path to approval.

Comparing 2nd Tier Lenders vs. Mainstream Banks

Choosing between a big bank and a 2nd tier option isn’t about finding a “better” lender, but rather the right lender for your current situation. Mainstream banks are great for people who fit a very specific profile and want the lowest possible interest rate. However, that low rate often comes with a lack of flexibility and a slow, complicated process. If you need a lender who can look past a messy bank statement or move quickly to secure a property, a 2nd tier lender New Zealand wide offers a level of service the big banks simply aren’t built to provide.

One of the biggest advantages is the personalised approach. You won’t find yourself stuck in a massive call centre queue or waiting weeks for a computer to process your paperwork. Instead, you’re working with people who understand that every borrower has a unique story. They can be far more creative with loan structures, such as offering longer periods where you only pay the interest. This can help with your cash flow while you’re getting established or finishing a renovation. It’s about finding a solution that fits your life, not forcing your life to fit their rules. For property investors in particular, this flexibility extends to residential investment property loans NZ borrowers use to grow their portfolios when mainstream banks won’t budge on LVR restrictions.

Interest rates and fees: The real story

Let’s be upfront about the trade-offs. Because these lenders take on more complex cases, their interest rates are generally higher than the “special” rates advertised by the Big Four. For many Kiwis, the slightly higher cost is a small price to pay for the value of actually getting into a home. It’s often a short-term strategy to get into the market now rather than waiting years to save a larger deposit. To help with the initial costs, many of these lenders allow you to add the setup fees to your total loan balance, meaning you don’t need even more cash upfront to get the deal across the line.

Flexibility and Speed

Speed is where these lenders truly shine. While a big bank might take weeks to give you a definitive answer, a 2nd tier lender can often organise a conditional approval in as little as 48 hours. This is a game-changer if you’re trying to secure a property at auction or need a short-term loan to cover the gap between selling one home and buying another. They are experts in providing non-conforming home loans New Zealand families use to navigate tricky transitions. Whether it’s a short-term fix or a long-term plan, their ability to move fast ensures you don’t miss out on the right opportunity just because a bank’s internal rules changed overnight. This same speed and flexibility makes them a natural fit for those seeking property development loans NZ wide, where tight project timelines and complex income structures often rule out the big banks entirely.

2nd Tier Lender New Zealand: Your 2026 Guide to Alternative Home Loans

How to Prepare a Solid 2nd Tier Loan Application

Getting your ducks in a row before you talk to a lender makes a world of difference. When you apply with a 2nd tier lender New Zealand wide, you aren’t just submitting a pile of numbers; you’re telling a story. These lenders are looking for a reason to say yes, but they need to see that you’re professional and organised. Gathering a clear paper trail is the first step to proving you’re a reliable partner who takes their finances seriously. It shows you’ve moved past the “too hard” basket and are ready to take control of your property journey.

Honesty is your best policy here. We always tell our clients that lenders hate surprises but they love honesty. If you have a bit of a colourful credit history or a period of low income, it’s much better to be upfront about it. When you explain the “why” behind a past mistake, it allows the lender to focus on your current ability to afford the repayments. They want to see that you have a stable income now and a clear plan for the future. This is where a mortgage broker becomes your best mate. We know exactly which lenders are comfortable with your specific situation and how to present your case so it stands out for the right reasons. If you’re unsure what went wrong with a previous application, our step-by-step recovery guide for Kiwis declined by bank home loan NZ wide can help you understand the reasons behind the rejection and how to address them before reapplying.

The ‘Exit Strategy’: Planning your return to the bank

Think of this loan as a bridge, not a destination. You don’t necessarily need a 2nd tier loan for a full 30-year term. Instead, many Kiwis use these products for 12 to 24 months to “clean up” their financial profile. During this time, you can prove a stable income or wait for old credit marks to fall off your record. Once your situation has settled, Mortgage Suite Ltd can help you refinance back to a mainstream bank with a lower rate. You can learn more about how this transition works in our guide to non-bank lenders nz.

The documentation you’ll need

To give yourself the best chance of a fast approval, you’ll need to have your paperwork ready to go. Lenders will look closely at your recent bank statements to check how you manage your bank accounts. They want to see that you’re handling your money well, without unarranged overdrafts or missed payments. You’ll also need to prepare:

  • Proof of deposit: This could be your savings, a gift from family, or equity you’ve built up in another property.
  • Income verification: For those who work for themselves, this might include recent sets of accounts or GST returns to show your business is healthy. Self-employed borrowers who struggle to meet traditional documentation requirements may also want to explore low doc home loans NZ lenders offer as an alternative path to approval.
  • A written explanation: A short, honest note explaining any past credit issues helps you get ahead of the lender’s questions and shows you’re proactive.

If you’re ready to stop guessing and start moving forward with a plan tailored to you, the best next step is to get in touch for a personalised chat about your options.

How Mortgage Suite Ltd Connects You to Alternative Funding

At Mortgage Suite Ltd, we believe everyone deserves a fair go at owning a home. Our founder, Krish Krishna, brings more than 20 years of deep banking experience to your side of the table. This isn’t just a number on a CV; it’s your secret weapon. Because Krish has spent two decades understanding the inner workings of the financial world, he knows exactly how to navigate the systems that often feel like a maze to everyday Kiwis. He has seen the process from both sides and knows what it takes to get a deal across the line.

Our role is to act as a bridge between you and the right 2nd tier lender New Zealand has available. We take your complex situation, whether you’re self-employed, have a non-standard income, or a few credit marks, and ‘translate’ it into a language that lenders understand and respect. We don’t just pass on your paperwork. Mortgage Suite Ltd builds a professional case for you, highlighting your strengths and providing clear context for any past hurdles. This hands-on approach often makes the difference between a quick decline and a solid approval. Our process is built on several key advantages:

  • Direct access to a wide range of lenders you won’t find on the high street.
  • Deep knowledge of “hidden” lending criteria that changes from month to month.
  • A proactive attitude toward overcoming obstacles that stop big banks in their tracks.
  • A long-term commitment to your financial success, not just a one-off transaction.

Expert negotiation on your behalf

We don’t just stop at the first “yes” we receive. Our goal is to fight for the best possible terms for your specific needs. Because Mortgage Suite Ltd has established relationships with a huge range of lenders across the country, we have access to options that the general public cannot reach directly. Every lender has its own unique appetite for risk at any given time. We know which ones are looking for your type of deal right now. From the top of the North Island to the bottom of the South, we provide national reach for all types of property loans, including residential investment property loans NZ investors need to unlock equity and grow their portfolios in 2026, ensuring you get a solution that works for your long-term goals.

Ready for a fair go?

If you’ve been turned away by your bank, please remember that it’s just a detour, not the end of the road. We invite you to reach out for a confidential, judgment-free chat about your situation. Mortgage Suite Ltd has seen every possible scenario and we know how to find a path forward. Our commitment is to partner with you for your long-term financial success, helping you get into your home now while planning for your eventual return to a mainstream bank. When you’re ready to explore what’s possible, you can book a consultation with our team. Let’s get to work on making your home ownership goals a reality.

Your Path to Home Ownership Starts Here

Securing a mortgage doesn’t have to be a stressful battle against a bank’s rigid computer system. Alternative options provide the flexibility and common-sense approach that modern Kiwis need to move forward. Whether you’re navigating self-employment income or a non-standard credit history, finding the right 2nd tier lender New Zealand wide can be the bridge that gets you into your home sooner rather than later. By focusing on a clear exit strategy and preparing a professional application, you can turn a bank’s decline into a successful new beginning.

With over 20 years of banking and mortgage expertise, Mortgage Suite Ltd specialises in these complex, non-conforming loans. Our founder-led service ensures you receive personalised attention from someone who truly knows how to negotiate with alternative lenders to get the best possible result for your situation. You don’t have to figure this out on your own. Chat with Mortgage Suite Ltd about your 2nd tier loan options today and let us help you find a fair go in the property market. Your dream home is still within reach, and we’re here to help you secure it.

Frequently Asked Questions

Is a 2nd tier lender safe to use in New Zealand?

Yes, they are completely safe and professional organisations. Every 2nd tier lender New Zealand has must comply with the Credit Contracts and Consumer Finance Act (CCCFA). This ensures they follow strict responsible lending rules just like the big banks. Many are backed by large investment firms; providing a secure and regulated environment for your home loan. You can feel confident that your rights are protected under New Zealand law.

Will my interest rate be much higher with a 2nd tier lender?

Generally, yes, the interest rates are slightly higher than those offered by mainstream banks. This reflects the extra flexibility they provide and the higher risk they take on. However, for many people, the small increase in cost is a fair trade for actually getting into a home. It is often a short-term solution while you work toward qualifying for a standard bank rate in the future.

Can I move back to a mainstream bank later on?

Absolutely, and for most clients, this is the ultimate goal. We often set up these loans with a 12 to 24 month plan in mind. Once you have built up more equity or cleaned up your credit history, we can help you refinance back to a mainstream bank. This “exit strategy” ensures you aren’t paying a higher rate for any longer than you actually need to.

Do 2nd tier lenders require a bigger deposit?

Not necessarily. In some cases, a 2nd tier lender New Zealand wide might actually be more flexible with deposit sizes than a big bank. While banks are often restricted by tight government rules on low-deposit lending, alternative lenders have more freedom to look at your individual situation. They focus more on your ability to make the repayments rather than just the cash you have upfront.

How long does it take to get a 2nd tier loan approved?

These lenders are typically much faster than traditional banks. You can often get a conditional approval within 48 hours, whereas a big bank might take two weeks or more. Because they are smaller and more focused, they don’t have the same layers of bureaucracy. This speed is a huge advantage if you are trying to buy a property at auction or have a tight deadline.

Can I get a 2nd tier loan if I’m self-employed?

Yes, they are often the best option for business owners and contractors. Banks often demand two years of perfect financial records, which many self-employed Kiwis don’t have. Alternative lenders are happy to look at other proof of income, such as GST returns or recent bank statements. They understand how business income works and won’t penalise you for having a complex financial structure. If you want to understand all the options available to you as a business owner, our detailed guide to low doc home loans NZ self-employed borrowers use in 2026 covers exactly how alternative documentation can work in your favour.

What happens if I have bad credit history?

They take a common-sense approach to your past. Instead of an automatic “no” from a computer, a human will look at why the credit issue happened and what has changed since then. If you can show that you are back on track and can afford the loan now, they are often willing to help. It’s about your current character and ability to pay, not just a past mistake.

Are 2nd tier lenders the same as ‘payday’ lenders?

No, they are completely different. Payday lenders offer very small, high-interest loans for a few weeks. In contrast, 2nd tier lenders provide long-term property finance and mortgages. They are professional financial institutions that offer competitive alternatives to the big banks. They are a legitimate part of the New Zealand property market and help thousands of families secure their own homes every year.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.