Mortgage refixing strategy NZ: Compare rates and loan types

A mortgage refixing strategy in NZ starts with reviewing your loan six to twelve months before a key fixed term expires. Compare more than the headline rate: consider the loan structure, flexibility and how repayments fit your plans. Staggering fixed-term dates can also help avoid having all your lending refix at once.

It’s understandable to feel unsure when rates and your circumstances can change. A lower rate may look appealing, but the right choice also depends on how much certainty or flexibility you need and when you might need access to funds.

This guide explains how to compare banks and non-bank lenders, weigh fixed, floating and split options, and prepare for a review before your term expires. You’ll also learn how staggered expiry dates can spread decisions over time, helping you plan your mortgage with care.

Key Takeaways

  • Compare lenders on structure and flexibility as well as the interest rate, so the loan fits your plans.
  • Choose between fixed, floating or split lending by weighing repayment certainty against access to flexibility.
  • Start reviewing your mortgage six to twelve months before a key fixed term expires to give yourself time to consider your options.
  • Staggering fixed-term dates can prevent all your lending from needing to refix at once.
  • Compare current rates by lender and fixed term, then consider how each option affects your repayments and future plans.

1. Comparing banks and non-bank lenders

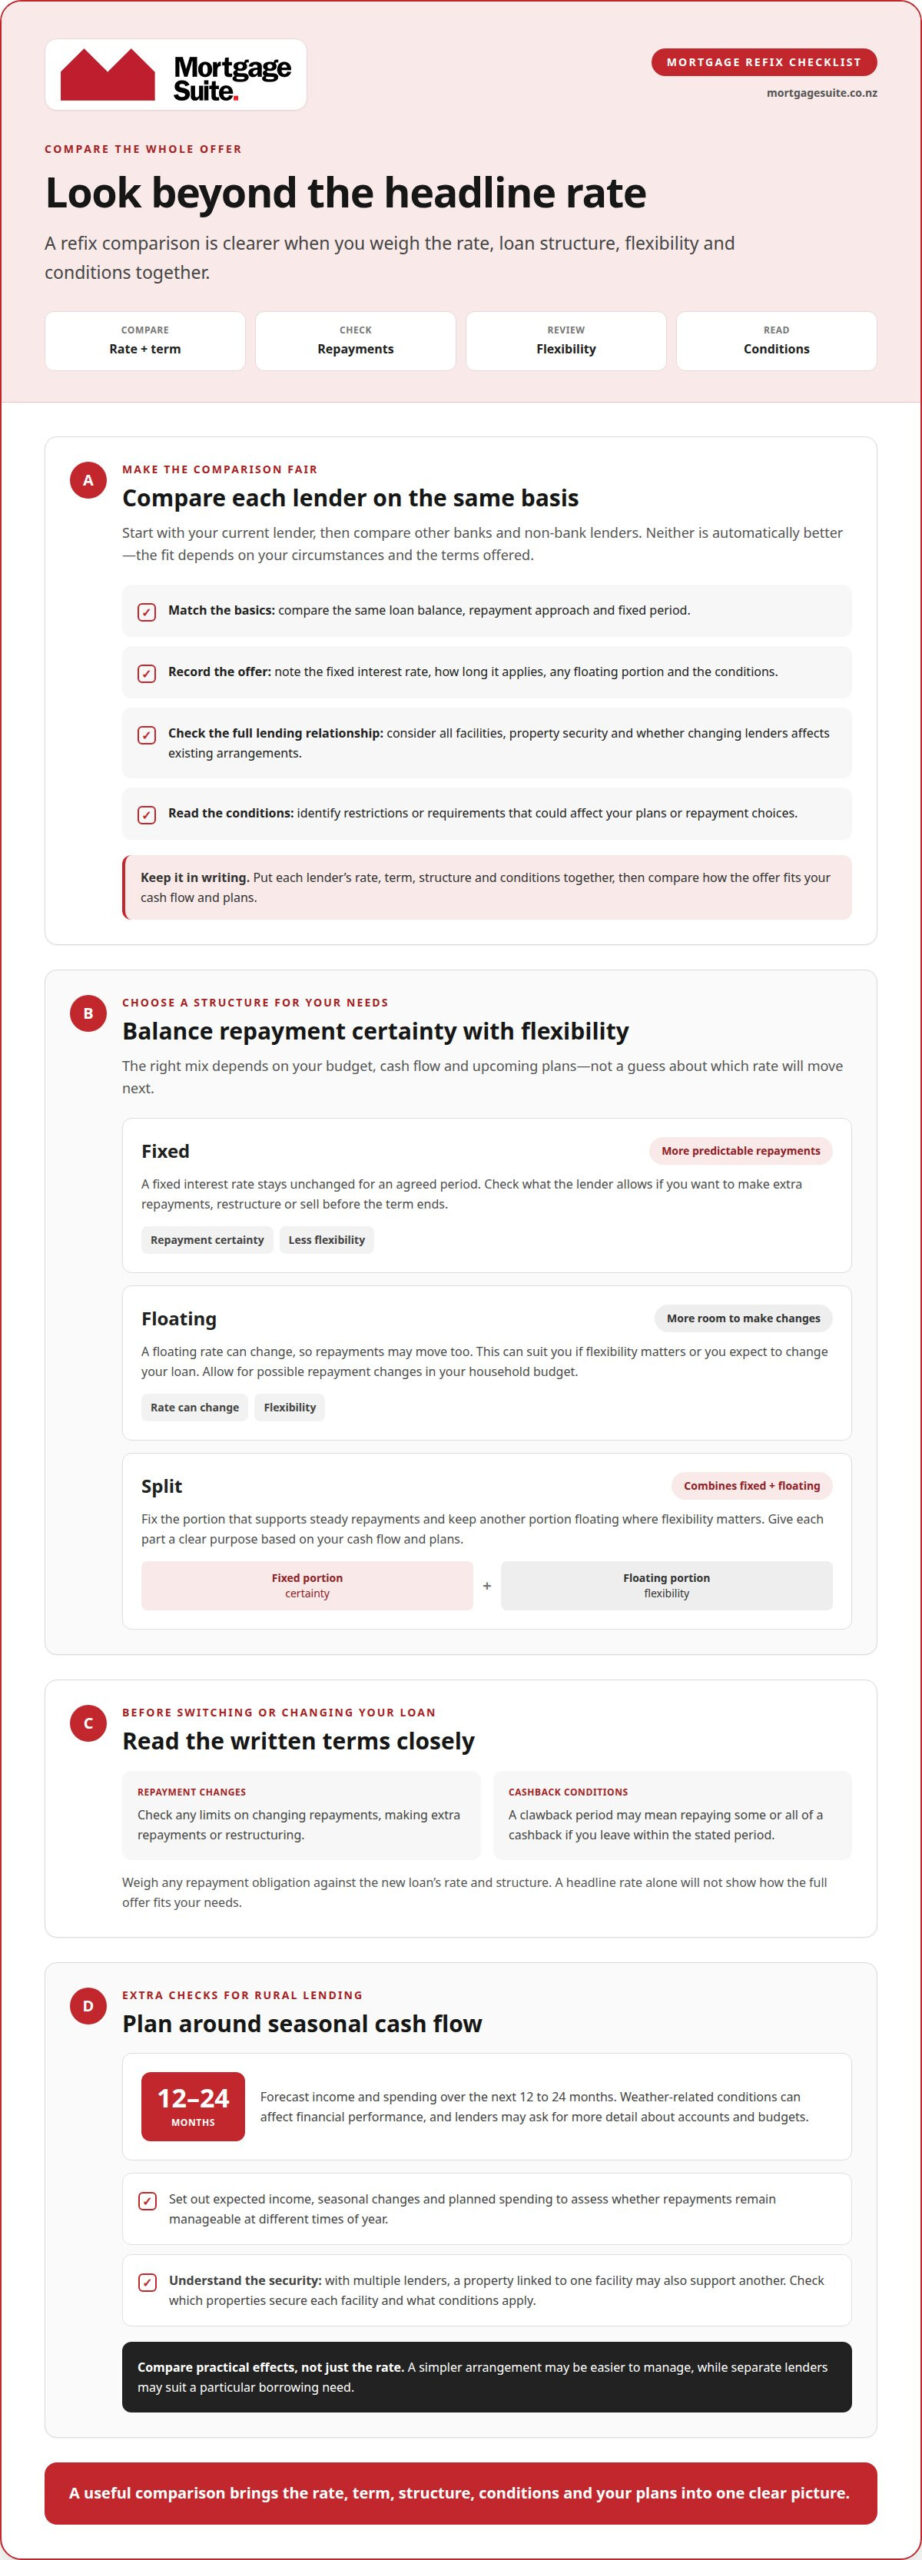
Compare your bank’s refix offer with alternatives by looking beyond the advertised rate. Assess the rate, fixed period, repayment options and conditions together. A lower rate may not suit you if the structure limits flexibility you need. Use the same loan balance and repayment approach when comparing offers, so you can make a like-for-like assessment.

Start with your current lender’s offer, then compare other banks and non-bank lenders. Ask how each option would affect your repayments and loan structure. A non-bank lender may be worth considering when mainstream bank criteria don’t fit your circumstances. Neither type of lender is automatically better: the right comparison depends on your income, security, plans and the terms available.

Use the same checklist for each lender. Record the fixed interest rate, how long it applies, any floating portion and conditions that affect how you manage the loan. Consider whether changing lenders would affect your existing lending arrangements. A headline rate won’t show the full picture if the offer changes your flexibility or requires a different security setup.

  • Compare like with like: Match the loan balance, repayment approach and fixed period across offers.
  • Read the conditions: Note restrictions or requirements that could affect your plans.
  • Review the structure: Check whether fixed and floating portions suit your need for certainty and access.
  • Consider the whole lending relationship: Look at how each lender treats all facilities and property security.

Rural borrowers have extra cash-flow factors to weigh. Forecast income and spending over the next 12 to 24 months before choosing a refix. Weather-related conditions can affect financial performance, and lenders may request more detail about accounts and budgets. Prepare a clear view of expected income, seasonal changes and planned spending. This helps you assess whether repayments remain manageable through different parts of the year.

Using multiple lenders for rural lending can also create complex security arrangements, including cross-collateralisation. This means a property linked to one facility may also support another. Before splitting lending across lenders, understand which properties secure each facility and what conditions apply. A simpler arrangement may be easier to manage, while separate lenders may suit a particular borrowing need. Compare the practical effects, not just the rate.

Keep your comparison in writing. Set out each lender’s rate, term, structure and conditions in one place, then identify the option that best fits your cash flow and plans. For rural lending, include the 12 to 24-month forecast. This turns a stressful choice into a clearer decision based on your actual circumstances.

2. Fixed, floating and split mortgage structures

Compare fixed mortgage rates and fees by matching the loan balance, fixed period and repayment type. Read each written offer for rate conditions, fee details and any limits on changing repayments. A headline rate is useful only when the surrounding terms also suit your needs.

A fixed interest rate stays unchanged for an agreed period, making repayments more predictable during that term. That certainty can help if your household budget has little room for unexpected changes. The trade-off is less flexibility: check what the lender allows if you want to make extra repayments, restructure or sell before the term ends.

A floating rate can change, so repayments may move when the lender changes its rate. This option can suit borrowers who value flexibility or expect to make changes to their loan. Factor the possibility of changing repayments into your household budget rather than assuming the current amount will stay the same.

A split structure combines fixed and floating portions. For example, you could fix the part of your loan that supports steady repayments and keep another portion floating for flexibility. Base the split on your cash flow and upcoming plans, not a guess about which rate will move next.

For rural borrowers, a split mortgage can combine a fixed portion of core term debt, a floating portion for flexibility and seasonal facilities for short-term cash-flow swings. This links different parts of the lending to different needs. Consider when income arrives, when expenses fall due and which funds need to remain accessible.

What mortgage refixing strategy suits changing interest rates and household budgets in New Zealand? Choose a fixed portion for repayment certainty and a floating portion where flexibility matters. The balance depends on your cash-flow needs and how much change your budget can absorb.

Cashbacks can affect a decision to refinance, but compare the offer with its conditions. A clawback period may require you to repay some or all of a cashback if you leave within the stated period. Read the written terms before switching, and weigh any repayment obligation against the new loan’s structure and rate.

Keep the comparison practical. Write down each portion’s purpose, rate type, repayment conditions and any relevant fee or cashback terms. Then assess the structure against your budget and plans. A suitable split gives each part of the loan a clear purpose, rather than dividing lending without a reason.

A rural mortgage refix in New Zealand can involve renegotiating the rate and loan structure with your current lender or splitting lending across multiple lenders. In either case, compare how each arrangement serves your cash-flow needs and preserves the flexibility your plans require.

3. Reviewing a mortgage before the fixed term expires

Yes, you can ask your bank to review the rate it offers for your next fixed term. Make a specific request, such as asking whether it can improve the rate or adjust the loan structure. Have your current loan details and preferred terms ready. A clear request gives the bank something practical to respond to.

Before speaking with your lender, prepare a concise snapshot of your mortgage. Include each loan portion, its balance, repayment type and current conditions. Note what you want to change, such as the repayment frequency or the amount you’d like to keep flexible. This helps keep the discussion focused on your needs.

Break fees are charges for ending or changing a fixed loan before its agreed term expires. Early repayment costs may also apply if you repay more than the loan terms allow. Read your loan documents and ask the lender for a written breakdown before making an early change. The terms and calculation determine the amount.

Use the review to check whether your current setup still reflects your circumstances. For example, a change in household income could affect what repayment amount feels manageable. List any planned property or borrowing changes, then consider how they might affect your loan structure. This gives you a practical basis for discussing options with your lender.

You can switch lenders when your fixed term expires. Compare the new lender’s written terms with your existing arrangement, including the steps needed to transfer the loan. Switching can involve charges or other costs, depending on the lending and transfer requirements. Ask for a clear breakdown before deciding, and compare the overall implications rather than focusing only on the rate.

Keep your review notes together. Record the lender’s offer, when it was provided, any conditions and questions that still need answers. If you discuss changes by phone, check the written terms afterwards. This makes it easier to compare what was discussed with the offer you’re being asked to accept.

Before agreeing to a new term, check how the proposed repayments fit your current budget. Consider whether you need the option to make extra repayments or change the structure later. A useful review ends with a clear record of the agreed rate, term, repayment arrangement and applicable conditions.

For rural borrowers in New Zealand, begin reviewing your mortgage six to twelve months before key fixed terms expire. Use that time to gather your loan details, preferred terms and planned changes, then identify what you need the lender to clarify. Setting out these points early can keep the review focused on the choices that matter to your household.

As expiry approaches, revisit the written offer alongside your notes. Check the rate, term, repayment arrangement, conditions and any costs tied to a change or transfer. If anything remains unclear, ask for an explanation in writing before deciding. Keep your decision grounded in what your budget can manage and whether the arrangement provides the flexibility you want.
Mortgage refixing strategy NZ: Compare rates and loan types

4. Staggering fixed-term expiry dates

Staggering means arranging fixed loan portions so they expire at different times. Instead of facing a single decision for the whole mortgage, you review each portion as its term ends. This can reduce the impact of a rate rise by preventing all your lending from refixing at once.

The main benefit is spreading rate changes across separate review points. If rates rise before one portion expires, that portion may refix at a higher rate while the others remain on their agreed terms. If rates fall, later expiry dates give you opportunities to consider the rates available then. Staggering spreads exposure; it doesn’t predict or prevent rate movements.

Decide how much of your mortgage to put in each portion by considering your budget and tolerance for repayment changes. A larger portion expiring at once can cause a more noticeable change to repayments. Smaller portions can spread that effect, but mean managing more individual dates and decisions. The right balance is personal, not a standard formula.

Before changing your schedule, map your existing loan portions and their expiry dates. Mark the portion that expires first, then consider whether the next expiry coincides with a planned change in household finances. For instance, if you expect a change in regular income, consider how a refix decision around that time could affect your available budget.

Staggering also has practical trade-offs. Each portion has its own rate, term and review point, so you’ll need to keep clear records. Maintain a loan schedule showing each portion, its expiry date, repayment arrangement and lender terms. A calendar reminder for each review can help you keep decisions distinct and avoid treating the mortgage as one undivided loan.

When a portion approaches expiry, assess it on its own merits. Consider the rate and terms available then, how its repayments fit your budget and whether the remaining portions still have the right schedule. A decision about one portion doesn’t have to dictate the next. Review the whole plan when circumstances change, but tie each refix choice to the portion reaching expiry.

Staggered dates are most useful when you can manage the extra administration and want to avoid concentrating every refix decision at one point. They won’t guarantee a lower rate or smoother repayments in every market. The practical aim is to make each decision manageable and keep future expiry dates visible, so you can approach them with a clear view of your mortgage.

5. What are current NZ mortgage refix rates by bank and fixed term?

Mortgage rates change, so a useful comparison needs the lender’s current offer and the fixed term you’re considering. Rather than relying on a single rate figure, compare the terms available for your loan and confirm how each offer applies to your circumstances. The rate alone won’t show whether the structure suits your budget.

Start with your bank’s current refix offer. Record the rate, fixed period, repayment conditions and date the offer applies. Then compare it with other available offers for the same loan balance and repayment approach. This keeps the comparison fair and helps you spot differences beyond the headline rate.

Fixed terms can have different rates at the same lender. Compare the options side by side using the same loan details. For example, look at the shorter and longer fixed periods available, then consider how each fits your expected budget and plans. Don’t assume a rate for one term applies to another.

A bank’s advertised rate may not be the final offer for every borrower. Your loan details and the lender’s terms affect what you’re offered. Ask for the rate and conditions that apply to your mortgage in writing. Note the date of each offer, so an older figure doesn’t distort your comparison.

Use a simple comparison record with these details:

  • Lender: Record which bank or lender made the offer.
  • Fixed period: Note the term linked to that rate.
  • Loan structure: Include any fixed and floating portions.
  • Conditions: Record repayment limits and any relevant offer terms.
  • Offer date: Write down when the lender provided the information.

For a clear decision, compare the same fixed period across lenders first, then compare other terms separately. If one offer has a lower rate but tighter repayment conditions, consider whether those limits fit your plans. A household expecting an income change may value flexibility differently from one seeking steady repayments.

Check whether your comparison includes any cashback terms or conditions associated with changing lenders. Read how long those conditions apply and what could happen if you move the loan again. Keep these details separate from the interest rate, so an upfront offer doesn’t distract from the ongoing loan terms.

Before accepting a refix, confirm that the rate, term and conditions match the lender’s written offer. If your current bank’s offer doesn’t meet your needs, use comparable written terms to discuss alternatives. A careful, dated comparison gives you a practical basis for choosing a mortgage structure that fits your budget.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd offers Home Loans to First Home Buyers, helping you consider your borrowing needs and mortgage structure. If reviewing your finances has raised questions about buying your first home, or you’re weighing a new loan against your household budget, this can be a useful next step.

Bring together your income, regular spending, existing lending and property plans before discussing your options. A clear picture of your finances can help you explore a loan structure suited to your circumstances, rather than focusing only on a headline rate. If a mainstream bank’s decision has left you unsure what to do next, you can explore alternative lending options.

Contact Mortgage Suite Ltd to discuss your home loan needs and possible next steps.

Make your next mortgage decision with confidence

Your next mortgage decision is a chance to make your borrowing fit the priorities ahead. A mortgage refixing strategy in NZ should reflect what you need from your loan and the changes you expect in your household plans. Take a moment to identify what matters most before deciding on your next step.

If you’d value a conversation about your options, discuss your situation and prepare for the decisions ahead. A clear discussion can help you frame the questions that matter and consider a path forward.

Talk through your mortgage options. A thoughtful next step can help you feel more prepared and in control.

Frequently Asked Questions

How does mortgage refixing work in New Zealand?

Refixing means agreeing a new fixed rate and term as your existing fixed term ends. Your lender presents the available options, and you choose a rate period and loan arrangement for the next term. For example, if your home loan has separate portions, you can decide on each as its term comes up. Check the new repayment amount and terms before accepting.

When should I refix my NZ mortgage before the fixed term expires?

Begin reviewing your mortgage six to twelve months before a key fixed term expires. Use that time to gather current loan details, note any changes to income or spending, and consider what repayment amount your budget can manage. For a rural household, include a cash-flow forecast for the next 12 to 24 months. This preparation gives you time to compare options before deciding.

Should I choose a short or long fixed term for a NZ home loan?

Choose a term based on how long you want repayment certainty and whether your plans may change. A longer term keeps the agreed rate in place for longer, while a shorter one brings the next review sooner. For example, if you expect a change in household income or property plans, consider how either term affects your flexibility and budget before choosing.

How do floating, fixed, and split mortgage strategies compare in NZ?

A fixed rate keeps the agreed rate in place for its term; a floating rate can change. A split arrangement combines both, so different loan portions serve different needs. For example, a household seeking predictable repayments could fix most of its lending while keeping a smaller portion flexible for planned changes. Compare repayment conditions and your capacity to manage changing payments before settling on a structure.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial Property Mortgage Rates: 2026 Aussie Guide

A higher quote isn’t always the only option. Commercial property mortgage rates are usually built around a base rate plus a lender’s margin, and the final offer can depend on the property, your business’s financial position and how you plan to repay the loan.

It’s understandable to compare a commercial loan with a home loan and wonder why the rate is higher. Commercial lending is assessed differently. A lender’s serviceability stress test can also affect how much you can borrow, particularly if your income or property doesn’t fit its usual criteria. A decline can feel like a dead end, but it doesn’t necessarily mean you’re out of options.

This guide explains what can shape a commercial loan rate, what lenders may look at and how to prepare for a clear conversation about your options. You’ll also learn how to compare loan structures against your business goals and consider lenders beyond mainstream banks. Mortgage Suite Ltd helps borrowers understand their options and negotiate with their interests in mind.

Key Takeaways

  • Commercial property mortgage rates depend on the property, your business profile and the lender’s view of risk. Compare the full loan structure, not just the headline rate.
  • Understand how a lender’s base rate and margin combine, and how a serviceability stress test may affect your borrowing capacity.
  • A decline from a mainstream bank isn’t necessarily the end of the road. 2nd tier lending may offer another path when your property or income falls outside standard criteria.
  • A building report can clarify a property’s condition for a lender. An offset account may reduce the loan balance used to calculate interest.
  • Mortgage Suite Ltd can help you present your business and property plans clearly and negotiate with lenders around a deal that suits your needs.

What Determines Commercial Property Mortgage Rates in 2026?

Commercial property mortgage rates are often higher than residential rates because the lending risks differ. A home may appeal to a broad pool of buyers, while a warehouse or specialised premises can take longer to sell if a lender needs to recover its money. Lenders also assess the property alongside the business using it. A commercial mortgage is secured against commercial property, but its rate and terms depend on the details of the deal.

The Reserve Bank of New Zealand’s Official Cash Rate (OCR) can influence the wider cost of lending. It is the rate the Reserve Bank charges registered banks for overnight lending, and changes can flow through to banks’ funding and lending decisions. On 2 September 2026, the Reserve Bank increased the OCR to 2.75%. This is a market-wide influence, not a direct quote for your loan. Lenders still assess the borrower, property and loan structure before setting terms.

Your industry and trading pattern can also affect how a lender views the application. Steady trading and predictable demand may present a different picture from seasonal income or an uncertain outlook. No sector automatically receives a better rate. Lenders consider whether the business can support repayments and whether the premises could suit another use if the business moves on.

Commercial vs. Residential: Why the Gap?

Homes generally have a wider pool of potential buyers than specialised commercial buildings, which can make them easier to sell. That difference in how quickly a property might be sold can affect a lender’s view of risk. Loan-to-Value restrictions may also be tighter for commercial assets, limiting how much a lender will advance against the property’s value. Lease terms matter too: a long, reliable lease can give lenders greater confidence in rental income than a short lease or a vacant building.

The 2026 Economic Outlook for Kiwi Borrowers

New Zealand’s commercial lending market has entered a more stable, balanced phase in 2026, with confidence gradually returning after the slowdown that followed the 2022 peak. Inflation and Reserve Bank policy still shape lenders’ funding conditions and appetite for risk. A changing OCR can influence the wider lending environment without setting every borrower’s rate.

For small and medium-sized businesses, a fixed interest rate can make repayments more predictable for an agreed period. The trade-off is that the loan’s flexibility and timing still need to fit your plans. Compare the certainty a fixed rate offers with other available structures, and consider the property, lease and business income together rather than judging a deal by its headline rate alone.

How Lenders Build Your Custom Interest Rate

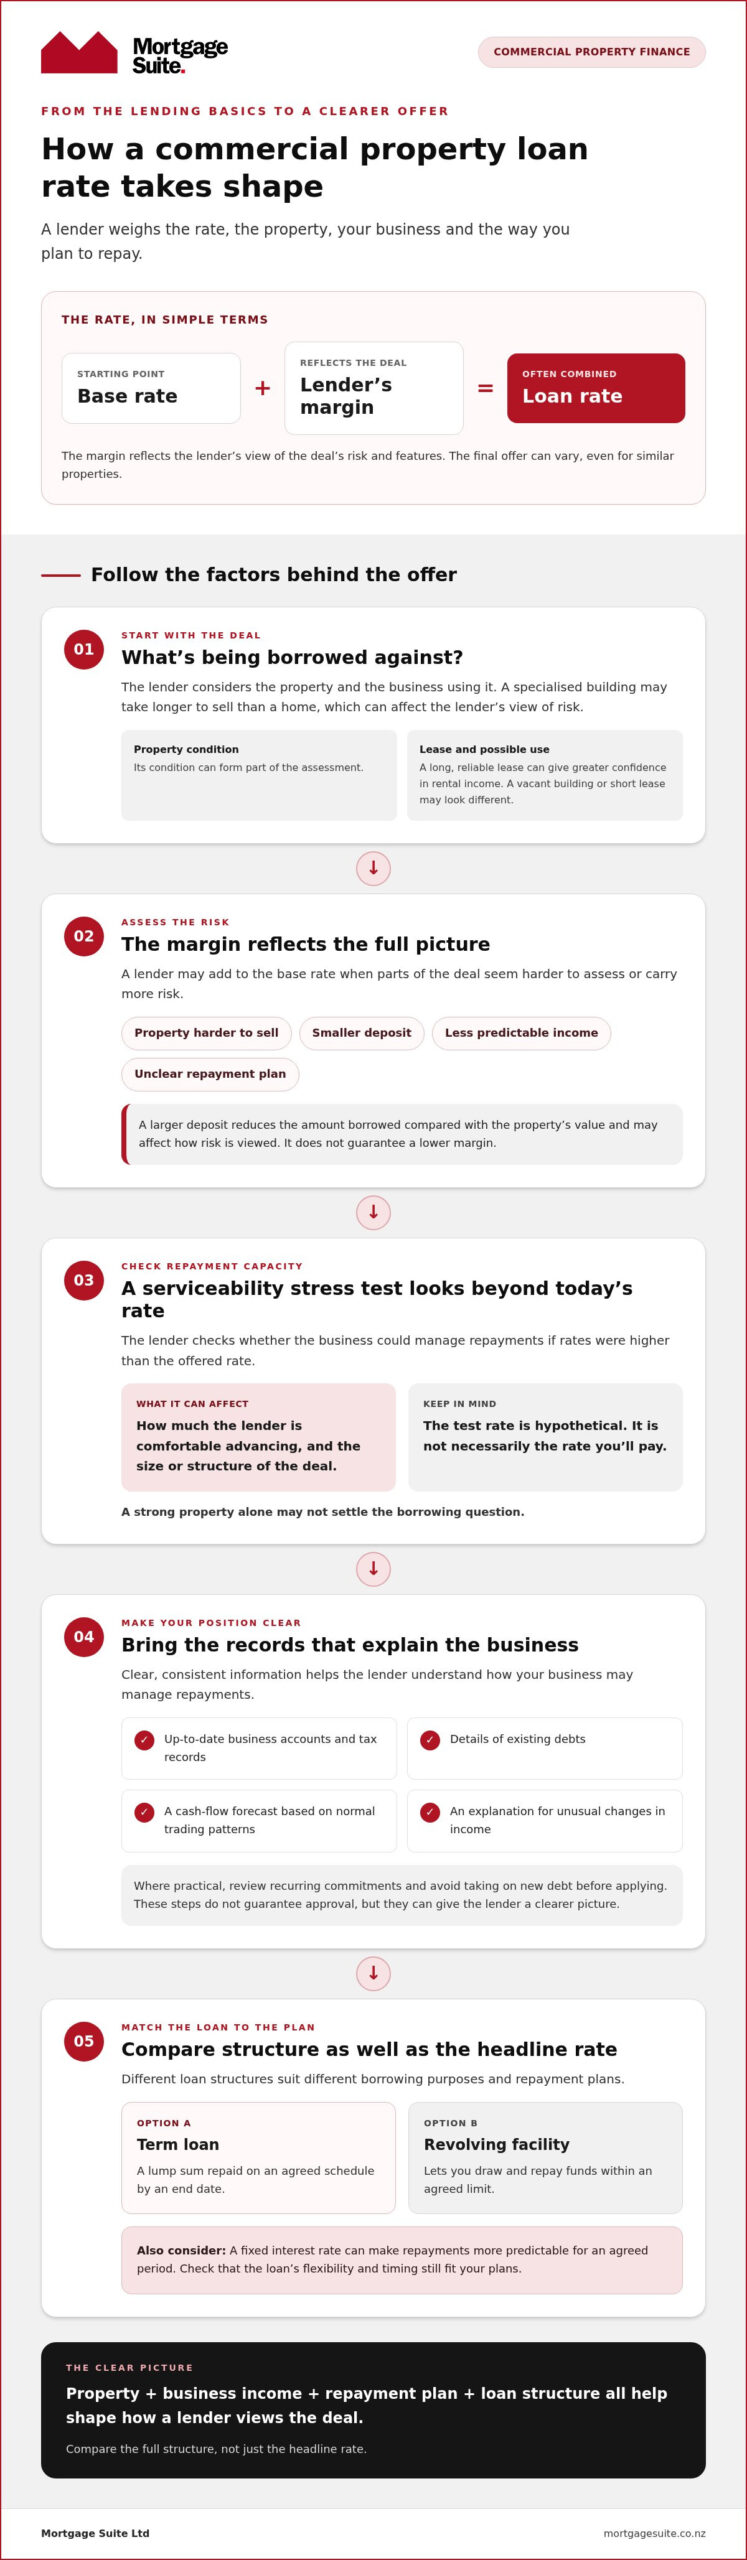
A commercial loan rate often has two parts: a base rate and a margin. The base rate is the starting point, while the margin reflects the lender’s assessment of the risk and features of your deal. That’s why commercial property mortgage rates can differ between borrowers seeking finance for similar properties.

A lender may consider the property’s condition, how much you’re borrowing compared with its value, the strength of your business income and your repayment plan. A larger deposit reduces the amount borrowed relative to the property’s value, which may affect how the lender views the risk. It doesn’t guarantee a lower margin, because the full application still matters.

Your business history helps explain how you’ll manage repayments. Consistent trading, clear accounts and a realistic repayment plan can support a lender’s understanding of your position. If income varies, explain what drives the changes and provide records that show how the business has performed over time.

Understanding the Risk Margin

A lender may add to the base rate if the security is harder to sell, the deposit is smaller, income is less predictable or the repayment plan is uncertain. With joint and several liability, each borrower can be responsible for the entire shared debt, not just a set share. Every borrower should understand that responsibility before agreeing to a shared loan.

The loan structure matters too. A term loan is a lump sum repaid on an agreed schedule by an end date. A revolving facility lets a borrower draw and repay funds within an agreed limit. These structures work differently, so consider which one fits the purpose of the borrowing and how you expect to repay it.

The Serviceability Stress Test Explained

A serviceability stress test checks whether the business could manage repayments if rates were higher than the offered rate. The test rate is hypothetical, not necessarily the rate you’ll pay. The result can limit the amount a lender is comfortable advancing and affect the size or structure of the deal. A strong property alone may not settle the borrowing question.

Make your position easier to assess. Prepare up-to-date business accounts, tax records, details of existing debts and a cash-flow forecast that reflects normal trading patterns. Present income and liabilities consistently, and explain unusual changes rather than leaving the lender to guess. Where practical, review recurring commitments and avoid taking on new debt before applying. These steps don’t guarantee approval, but they can give the lender a clearer picture of your capacity.

If the figures are difficult to present or the lender’s assessment is hard to interpret, Mortgage Suite Ltd’s commercial finance team can help you understand what’s shaping the offer and put your position forward.

Mainstream Banks vs. 2nd Tier Lenders: Finding a Fair Go

A decline from a mainstream bank can feel personal, especially after you’ve spent time preparing an application. Often, though, it reflects that lender’s criteria and appetite for particular properties, income patterns or loan structures. Another lender may assess the same deal differently. That doesn’t guarantee approval, but a bank’s answer isn’t a final judgement on your business.

2nd tier lending may be worth exploring if your property or financial situation doesn’t fit standard bank criteria. A specialised commercial building, uneven self-employed income or a time-sensitive purchase may call for a different lending approach. Mortgage Suite Ltd specialises in 2nd tier lending options for borrowers who don’t fit mainstream criteria, helping present the details of the deal clearly.

When to Look Beyond the Big Four

Lenders can assess self-employed income in different ways. One may focus closely on reported profit, while another may consider the wider trading picture and supporting records. Alternative lenders may also consider non-standard property or loan structures, though flexibility varies and the lender still assesses whether repayments are manageable. Interest-only periods may be available in some 2nd tier arrangements, but they aren’t automatic. During such a period, scheduled payments generally don’t reduce the principal, so plan how and when you’ll repay it.

The Trade-off: Rate vs. Flexibility

A flexible structure or a decision that fits your purchase timeline may matter more than the lowest headline rate. Commercial property mortgage rates are only one part of the comparison. Look at the repayment plan, loan term, conditions and what happens when the facility ends. For short-term finance, set out a realistic exit plan, such as selling an asset or refinancing, and consider what you’ll do if that takes longer than expected.

Moving back to a mainstream bank may be possible later if your financial position and deal fit its criteria at that time. You can work towards that by keeping business accounts organised, meeting repayments, reducing debt where practical and tracking changes in income or equity. Before accepting an offer, weigh the rate against the value of the structure to your business. A higher rate may be a reasonable trade-off when the terms address a genuine timing or eligibility challenge, provided the repayments and exit plan remain workable.

Compare offers on the same basis, not just by their headline figures:

  • Fit: Does the lender understand the property and your income pattern?
  • Structure: Do the repayment terms match your business plans?
  • Next step: Is there a practical path to repay or refinance the loan?

A bank decline is stressful, but you can still take a measured next step. Understand the reason for the decision, identify what could strengthen the application and consider whether a different lending approach better fits your goals.

Commercial Property Mortgage Rates: 2026 Aussie Guide

Strategies to Organise a Better Commercial Deal

A well-prepared application helps a lender understand the property, your business and why the finance makes sense. It won’t guarantee approval or a particular rate, but it can reduce uncertainty and make it easier to discuss a structure that fits your plans. Compare commercial property mortgage rates alongside flexibility and repayment terms, not in isolation.

Start with the property. A building report gives a professional assessment of its condition and defects. It can help you understand what you’re buying and give the lender clearer information about the security. If the report identifies issues, explain how you’ve accounted for them in your plans rather than leaving questions unanswered.

Think about cash flow too. If your lending includes an offset account, the balance in that account reduces the loan balance used to calculate interest. Keeping business funds there may help reduce the interest burden, but the benefit depends on the account and loan terms. Compare this with keeping funds available for wages, tax and day-to-day operations.

Cleaning Up Your Financial Profile

Before speaking with a broker, bring together your certified accounts, current details of business debts and a clear summary of income and expenses. Prepare a business plan explaining what the property will be used for, how it supports trading and where repayments will come from. A mortgage calculator can help you model repayment scenarios, but treat the results as a guide, not a lender decision.

Good timing can help the process run smoothly. If your accounts are being finalised, have interim figures ready and explain what has changed since the last reporting period. Lenders may review applications according to their own reporting and assessment processes, so allow time to answer questions and provide updated documents. A current, organised application is easier to assess than one assembled in a rush.

The Power of Refinancing

Refinancing may be worth considering if your business needs funds for growth, your property equity has changed or your current loan no longer suits your plans. A commercial property refinance replaces or restructures existing commercial lending. Before switching, compare the proposed terms with your current agreement, including any applicable break fees, and account for the time and conditions involved.

As your equity safety net grows, you may have more room to discuss the amount, structure or purpose of borrowing. Equity isn’t the same as available cash, and a lender will still assess affordability and the property. Set out how any released funds would support the business and how the revised repayments would fit your cash flow.

Mortgage Suite Ltd can help organise your application and negotiate with lenders around your business goals. Talk with Mortgage Suite Ltd about your commercial finance options.

How Mortgage Suite Gets Your Finance Sorted

Commercial lending can feel like a maze of forms, lender rules and unfamiliar terms. Mortgage Suite Ltd offers a personal, steady hand through the process. Founder and director Krish Krishna draws on over two decades of banking experience to help bridge the gap between lenders and borrowers, especially when a commercial deal doesn’t fit a standard mould.

That experience helps make sense of how a lender may assess your property, business income, repayment plan and loan structure together. The aim isn’t to chase a headline rate at any cost. It’s to understand your goals, explain options in plain English and negotiate a deal that makes sense for your business over the longer term. Commercial property mortgage rates matter, but so do the loan conditions and how well repayments fit your plans.

A Consultative Approach to Lending

We start by learning what you want the finance to achieve, then work through the details that could affect a lender’s decision. That may include gaps in your documents, unclear income patterns or questions about how the property supports your business. Raising these early gives you time to prepare a clearer application and address concerns before they become obstacles.

You’re not just a set of figures to process. We want you to feel comfortable asking questions, understanding the trade-offs and making informed decisions at your own pace. For clients dealing with a complex application, that supportive approach can make the process feel more manageable. You can also read Mortgage Suite Ltd client reviews to hear about other borrowers’ experiences.

Taking the Stress Out of the Process

Lender communication can take time and attention away from running your business. Mortgage Suite Ltd can act as your advocate, helping present your circumstances clearly, liaise with lenders and negotiate on your behalf. If a bank says no, we can help you understand why and consider whether another lender or second-tier option may suit the deal. There’s no promise that every application will be approved, but one lender’s decision doesn’t automatically close every door.

We take a methodical approach: looking at your objectives, the property, your financial information and a suitable structure, then helping prepare your case for lenders. As offers come in, we help you compare more than the rate, including repayment terms, flexibility and how the loan fits your next business steps.

To get started, gather a brief outline of your plans, recent business accounts and details of the property or finance you’re considering. Then arrange a conversation with Mortgage Suite Ltd about your commercial finance goals. We’ll work through the key questions with you and help map out a practical next step, without treating a complicated situation as a reason to give up.

Make Your Next Finance Move With Confidence

Your next step doesn’t have to be a full loan application. Start by getting clear on what the property needs to do for your business, what repayment structure feels manageable and which parts of your finances need explaining. That gives you a stronger foundation for a practical discussion about your options.

Commercial property mortgage rates are only one part of the decision. A suitable deal should also fit your plans, cash flow and timeframe. If your situation is complex or a lender has already said no, you can still explore whether another approach may fit. There’s no guaranteed outcome, but a clear plan and experienced support can help you make an informed choice.

Mortgage Suite is an Accredited Financial Advice Provider, offering a personal approach to commercial finance and lender discussions. The advice is free of charge with no obligation. Talk with Mortgage Suite about your commercial finance options.

You don’t have to work through the choices alone. With the right guidance, you can move forward with a clearer view of your options and a plan shaped around your business goals.

Frequently Asked Questions

Are commercial property mortgage rates fixed or floating?

They may be fixed or floating, depending on the lender and the loan structure offered. A fixed interest rate stays unchanged for an agreed period, while a floating rate can move as the lender’s pricing changes. Consider how each option fits your cash flow: a business that values predictable repayments may prefer certainty, while another may prioritise flexibility. Compare the full terms, not just the starting rate.

How much deposit do I need for a commercial property in NZ?

There’s no single deposit that applies to every commercial property purchase. The amount can vary with the property, lender and borrower’s circumstances. A specialised or harder-to-sell building may be assessed differently from standard commercial premises. Consider how the deposit affects both the proposed loan structure and the amount you may be able to borrow.

Can I get a commercial loan if I am self-employed?

Yes, being self-employed doesn’t automatically rule you out of commercial finance. Lenders will want to understand how your business earns income and whether it can support repayments. Clear accounts and records showing trading over time can help explain your position. If income varies by season or contract, include context so the lender can assess the wider picture rather than relying on one unusual period.

What happens if a mainstream bank declines my commercial loan?

A decline doesn’t automatically end your options. First, understand which part of the application concerned the bank, such as the property, income evidence or loan structure. That can help show whether a change to the application or a different lender may be worth considering. Mortgage Suite specialises in 2nd tier lending for borrowers outside mainstream criteria, though every lender makes its own assessment and approval isn’t guaranteed.

How long is a typical commercial property loan term?

Commercial loan terms vary, so there isn’t one duration that suits every borrower and property. The agreed term may depend on the loan’s purpose, repayment plan and lender’s offer. Finance for a property your business plans to hold long term may need a different structure from short-term funding with a planned sale or refinance. Check the end date and what you’ll need to do when the loan term finishes.

What is a serviceability stress test for business loans?

A serviceability stress test checks whether your business could manage repayments if interest rates were higher than the rate offered. It can affect the amount the lender is willing to advance, even if you can meet repayments at today’s rate. Before applying, review cash flow under less favourable conditions, including quieter trading periods, so you can see where repayments might put pressure on the business.

Does Mortgage Suite charge an hourly fee for advice?

No. Mortgage Suite’s advice is free of charge with no obligation. You can discuss your commercial finance needs and the lending options that may fit your circumstances without committing to proceed. A lender will still assess any loan application on its own merits, and Mortgage Suite can’t guarantee approval. The aim is to help you understand your options and next steps.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Best NZ Investment Property Mortgage Rates: 2026 Guide

What if the bank offering you the lowest headline rate is actually the one most likely to stall your portfolio’s growth? It’s easy to feel overwhelmed by the constant stream of conflicting offers, especially when you’re also trying to figure out how the current Debt-to-Income (DTI) rules, capped at seven times your income for investors, affect your borrowing power. You probably feel frustrated when mainstream banks say no, even when you know your strategy is solid. Finding the best mortgage rates for investment property nz should be about more than just a lucky number; it’s about securing your financial future.

We agree that the current market feels like a maze of shifting regulations and “special” offers that don’t always apply to your specific situation. We’ll show you how to look past the flashy headlines to find an investment loan that actually helps you build wealth in today’s New Zealand market. In this 2026 guide, we’ll explore how to keep your property cash-flow positive, how to structure your loan to save on tax now that interest is fully deductible, and how to finally get that “yes” from a lender who understands your long-term goals.

Key Takeaways

  • Learn why the lowest advertised interest rate isn’t always the smartest choice for the long-term health of your property portfolio.
  • Understand how the latest Debt-to-Income limits and your deposit size directly influence the specific offers you’ll receive from lenders.
  • Discover how to secure the best mortgage rates for investment property nz by focusing on a loan structure that keeps your cash flow positive.
  • Master the art of “grooming” your bank statements months in advance to make your application look far more attractive to banks.
  • Find out how a professional partner can negotiate better terms on your behalf and take the stress out of the application process.

Finding the best mortgage rates for your NZ investment property in 2026

Let’s be honest: the NZ property market has seen a fair bit of change lately. We’ve moved through the highs of the New Zealand property bubble into a more calculated and cautious era. For anyone hunting for the best mortgage rates for investment property nz, the game has shifted significantly. It’s no longer just about which bank has the flashiest billboard or the most aggressive marketing campaign. Banks now look at investors through a much sharper lens than they do owner-occupiers. They view investment properties as higher risk because, if things go pear-shaped, people usually fight harder to keep the roof over their kids’ heads than they do for a rental property. This perceived risk is why investment rates often come with stricter equity requirements or slightly different pricing structures than a standard home loan.

Why ‘cheap’ isn’t always ‘best’

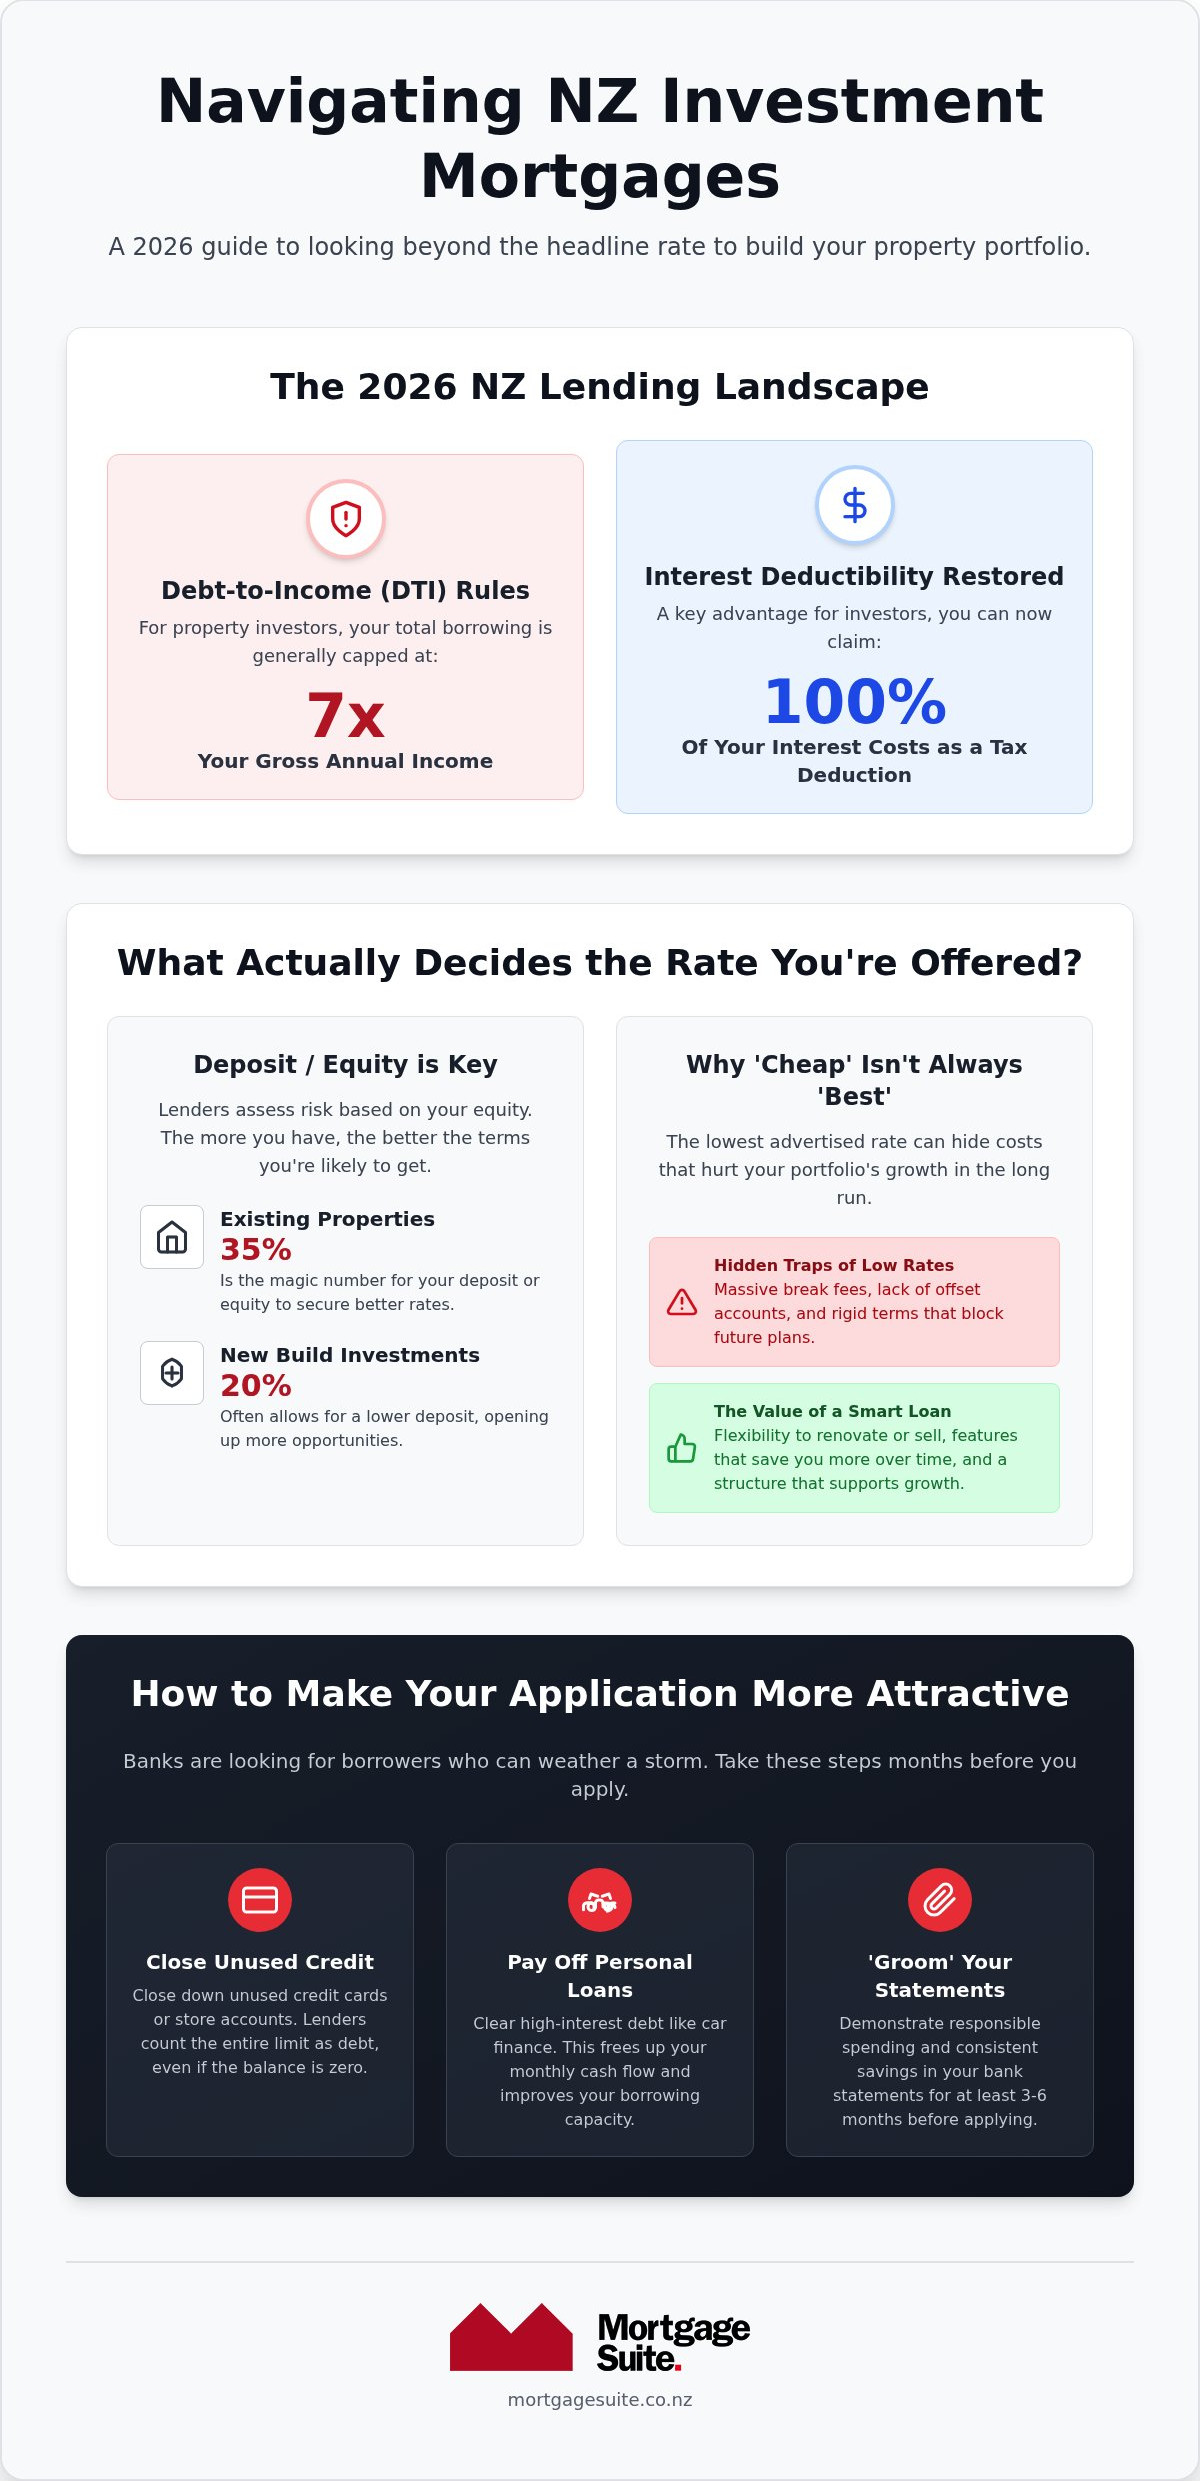
It’s incredibly tempting to grab the lowest number you see on a comparison website. However, that “cheap” rate often comes with strings attached that can trip you up later. You might find yourself locked into a contract with massive break fees or a total lack of offset facilities that could have saved you more in the long run. If you plan to renovate or sell the property in the next eighteen months, a rigid, low-rate fixed term could actually end up costing you thousands more than a slightly higher, more flexible option. Loan value is the total cost of ownership over the entire life of the debt, accounting for every fee and the price of lost flexibility. Don’t let a small saving today lead to a massive bill tomorrow when your circumstances change.

The 2026 New Zealand lending landscape

In 2026, the lending climate is defined by a renewed focus on stability. While interest deductibility is now fully back at 100 percent, the Reserve Bank’s Debt-to-Income (DTI) rules mean your income is under the microscope like never before. For investors, this limit is generally capped at seven times your annual income. The Official Cash Rate (OCR) continues to dictate what hits your hip pocket each month, making it vital to understand the mechanics behind these shifts. You can find a more detailed breakdown of these interest drivers in our guide to mortgage rates nz. Banks are being choosy because they have to be. They aren’t just looking for a 35 percent deposit on existing properties; they’re looking for a borrower who can weather a storm without missing a beat. Securing the best mortgage rates for investment property nz now requires a strategy that balances these regulatory hurdles with your personal financial goals.

What actually decides the rate you’re offered?

Lenders don’t just have one set rate that they hand out to everyone who walks through the door. Instead, they use their own ways of calculating how safe a loan is to decide how much they’ll charge you. Your personal financial health acts as a blueprint for the interest rate you’ll eventually pay. While you might be looking for the best mortgage rates for investment property nz, the bank is looking at how likely you are to pay them back without a struggle. Your ability to show you can afford the repayments is now often more important than the actual house you’re buying. If the bank’s stress test suggests you’d struggle if rates rose by another 2 percent, they’ll either decline the loan or offer less attractive terms.

Understanding LVR and DTI in 2026

The factors that dictate your offer are your deposit size and your debt levels. For most existing investment properties in New Zealand, 35 percent equity is the magic number. If you have less than this, you’ll likely face higher interest costs or extra fees. You can find more details on these requirements in the official government guide to buying property.

The Debt-to-Income rules are the real game-changers for 2026. For investors, the limit is generally seven times your annual gross income. If you own several properties, this calculation includes the debt on every single one of them. To improve your position before you apply, consider these steps:

  • Close down unused credit cards or store limits. Banks count the full limit as debt even if you owe nothing.
  • Pay off high-interest car finance to free up your monthly cash flow.
  • Look into a new build investment, which often allows for a lower 20 percent deposit and different rules.

Mainstream banks vs. 2nd tier lenders

If a mainstream bank says no because your situation is a bit different, don’t worry. Mainstream banks love simple applications with a standard salary or wages. However, if you’re self-employed or have a more complex setup, a 2nd tier lender New Zealand might be a better fit. These alternative lenders are often more flexible with how they look at your money. For example, while a big bank might only count 75 percent of your rental income toward your ability to pay, an alternative lender might count the full 100 percent. This can be the difference between getting the green light or being stuck on the sidelines. If you’re unsure where you fit, reaching out to the team at Mortgage Suite Ltd can help you find the right path forward without the stress of multiple bank declines.

Comparing your options: Fixed, floating, and interest-only

Choosing the right structure for your loan is where the real money is made or lost in property investing. While everyone wants the absolute lowest number, the best mortgage rates for investment property nz are only as good as the flexibility they offer your portfolio. In a 2026 market where rates have shown some volatility, locking in a fixed rate provides a much-needed shield of certainty. For example, several major banks are currently offering one-year fixed terms around the 4.75 percent to 4.99 percent mark for those with enough equity. This allows you to forecast your expenses with precision, knowing exactly what your outgoings will be for the next twelve months regardless of what happens in the global economy.

Floating rates usually sit higher, often between 6.04 percent and 6.64 percent, but they serve a specific purpose. They’re perfect for investors who expect a lump sum of cash or want the freedom to make extra repayments without facing heavy fees for breaking a contract. If you’re looking for a balance between stability and freedom, interest-only terms can be a powerful tool. By only paying the interest, you lower your monthly commitment, which can be essential for keeping your rental income higher than your expenses while you’re growing your assets.

Fixed vs. Floating: Which way should you jump?

Many successful investors choose to split their loans into different fixed terms. You might put half on a one-year fixed rate and the other half on a two-year term. This strategy of staggering your loan end dates ensures that your entire debt doesn’t come up for renewal at the same time, protecting you from a sudden spike in market rates. Rate locking is simply the process of securing a specific interest rate for a set period so that your repayments stay the same even if market rates climb. Having a small floating portion is also a smart move if you want to use an offset account. This allows your rental income or personal savings to reduce the debt the bank charges interest on, meaning you only pay for the difference, which can save you thousands over the life of the loan.

The power of interest-only terms

Interest-only is often called the investor’s secret weapon because it helps your monthly cash flow. Since mortgage interest is now 100 percent deductible for tax purposes, many investors prefer to keep their debt levels higher on their rentals while using their spare cash to pay down the debt on their own family home. However, you need to be aware of the “sunset” period. This is the point where your interest-only term ends and the loan changes so you have to start paying back both the interest and the original amount borrowed. When this happens, your monthly costs can jump significantly. It’s vital to plan for this change well in advance. For a deeper look at how to manage these terms, check out our guide on residential investment property loans NZ. Securing the best mortgage rates for investment property nz is only the first step; the real success comes from a setup that supports your long-term growth.

Best NZ Investment Property Mortgage Rates: 2026 Guide

How to snag a better deal than the advertised rates

Reckon the rate on the website is the final word? Think again. Most banks treat those advertised numbers as a starting point for negotiation, especially for investors with a solid track record. To secure the best mortgage rates for investment property nz, you need to present an application that’s so clean the bank’s credit team can’t find a reason to say no. This process is often called “grooming” your accounts. For at least six months before you apply, you want your bank statements to show disciplined spending and consistent savings. It’s about making the bank’s job easy so they see you as a low-risk partner rather than just another file on their desk.

Step-by-step: Preparing your application

Getting your financial house in order before you approach a lender is essential. It’s not just about what you earn, but how you manage what you have. Follow these steps to make your application stand out:

  • Step 1: Minimise your ‘uncommitted’ credit. Banks look at the total limit on your credit cards and store accounts, not just what you owe. If you have a $15,000 limit but only use $500, they still factor in that full $15,000 as potential debt. Closing these unused accounts can instantly boost your borrowing power.
  • Step 2: Consolidate your debts. If you have a car loan and a separate personal loan, rolling them together can show better servicing ability by reducing your total monthly outgoings and simplifying your financial profile.
  • Step 3: Organise your rental appraisals and tax records early. Having your paperwork ready to go shows you’re a professional who knows the market. This builds trust with the lender from day one and ensures there are no dramas during the approval process.

The ‘Broker Advantage’ in rate negotiations

This is where having a veteran negotiator in your corner changes the game. We don’t just send an application to one bank and hope for the best. Instead, we pit the banks against each other to see who blinks first. Our 20 plus years of experience in the New Zealand market means we know which buttons to push and which lenders are currently hungry for investment business. Sometimes the absolute best mortgage rates for investment property nz aren’t with the big four, but with smaller lenders you might never have heard of.

We handle the hard yakka of the paperwork and the back and forth negotiation, ensuring you get a “yes” that actually helps you build wealth. We’ve seen every market cycle since 2000 and know how to navigate this one to your advantage. If you’re ready to see what’s possible beyond the standard bank offers, talk to our team of expert mortgage brokers today and let us do the heavy lifting for you.

Why Mortgage Suite makes the hard yakka easy

Finding the best mortgage rates for investment property nz shouldn’t feel like a second job. We know that the paperwork, the constant emails, and the worry about whether you’re getting a fair deal can be exhausting. That’s why we’ve built a service that takes the weight off your shoulders. We’ve seen every market cycle since 2000, from the boom times to the more challenging years. We know how to navigate the current 2026 landscape because we’ve been here before. Our approach isn’t about a quick transaction; it’s about building a long-term partnership where we help you grow your wealth property by property. We handle the tricky bits so you can focus on finding your next great investment.

We understand that every investor’s situation is unique, and we take the time to listen before we act. This isn’t just about a one-off loan; it’s about having a steady hand to guide you through the fluctuating New Zealand market. We speak plain English, not bank-talk. Our goal is to give you straightforward advice that gets results, ensuring there are no dramas along the way. Whether you’re looking for your very first rental or you’re a seasoned pro with a massive portfolio, we have the expertise to help you move forward with confidence.

Meet Krish and the team

Krish Krishna leads the team with over two decades of banking experience. This deep understanding of how banks operate is your secret weapon for securing the best mortgage rates for investment property nz. Because Krish has sat on the other side of the desk, he knows exactly how banks think and what they need to see to say “yes.” We’ve earned a reputation as dedicated negotiators who won’t take no for an answer. If a mainstream bank turns you down, we don’t just give up. We look at alternative options, including 2nd tier loans, to find a way forward that keeps your investment goals on track. We offer a national service across New Zealand, so no matter where your next property is, we’re here to help.

Ready to get your investment sorted?

Getting started is as easy as a quick, no-obligation chat. In our first conversation, we won’t just talk about numbers. We’ll talk about your strategy, your timeline, and what you’re hoping to achieve. It’s a consultative process designed to make you feel supported and confident. We’ll answer your questions, clear up any confusion about the current rules, and start mapping out a plan that works for you. There’s no pressure and no complex jargon; just professional guidance from people who genuinely care about your success. Let’s find the best rate for your investment property together and get your portfolio moving in the right direction.

Secure your property future today

Building a profitable property portfolio in 2026 requires more than just picking the lowest number on a bank’s website. Success comes from looking beyond the headline interest rate to find a structure that truly supports your specific goals. Whether that means using interest-only terms to maximise your cash flow or carefully grooming your accounts to impress a lender, a proactive strategy is your best asset. Finding the best mortgage rates for investment property nz is a journey that involves strategic positioning and expert negotiation.

Accessing both mainstream and 2nd tier lenders is much simpler when you have a partner who understands the nuances of complex investor portfolios. With 20+ years of industry experience, we handle the hard yakka and the paperwork to ensure the process is no dramas for you. We’ll do the heavy lifting. Book a free chat with our investment loan experts today and let’s get your next move sorted. You’ve done the research; now it’s time to take the next step toward building your wealth with confidence.

Frequently Asked Questions

What is the average interest rate for an investment property in NZ right now?

As of August 2026, one-year fixed rates for investment properties generally sit between 4.75 percent and 4.99 percent among the major banks. Variable or floating rates are significantly higher, often ranging from 6.04 percent to 6.64 percent. These figures change frequently based on wholesale funding costs, so it is always best to check the latest offers before making a final decision on your loan structure.

Can I use the equity in my own home to buy an investment property?

Yes, you can certainly use the equity built up in your family home to fund the deposit for an investment property. This is a common strategy for Kiwi investors to avoid using their own cash. By re-mortgaging a portion of your home’s value, you can create the 35 percent deposit required for an existing rental property without needing to save for years.

Do investment properties always have higher interest rates than home loans?

Investment properties do often have slightly higher rates because banks reserve their “special” discounts for owner-occupiers with at least 20 percent equity. While the base rates might look similar, investors sometimes face additional margins or fewer fee waivers. Securing the best mortgage rates for investment property nz requires looking past standard home loan advertisements to find products specifically designed for rental portfolios.

How much deposit do I really need for an investment property in 2026?

In 2026, you generally need a 35 percent deposit for an existing residential investment property. This means you can borrow up to 65 percent of the property’s value. However, if you are looking at a new build, the rules are often more relaxed, usually requiring only a 20 percent deposit. These limits are set by the Reserve Bank to manage risk in the housing market.

What happens if my bank declines my investment loan application?

If a mainstream bank declines your application, you still have several options through 2nd tier or alternative lenders. These lenders often have more flexible criteria and might look more favourably on self-employed income or complex financial situations. While their interest rates can be slightly higher, they provide a vital bridge for investors who don’t fit the rigid boxes of the major institutional banks.

Is it better to fix my investment loan for one year or five years?

Most investors in the current 2026 market are choosing shorter terms like one or two years to maintain flexibility. Fixing for five years provides long-term certainty but can be risky if market rates drop significantly during that time. A shorter term allows you to review your strategy more frequently and adjust your portfolio as the economy shifts or your personal circumstances change.

How do the new DTI rules affect my ability to get a good rate?

The Debt-to-Income (DTI) rules limit your total borrowing to seven times your annual gross income for investment purposes. This means that even if you have a massive deposit, your income might prevent you from getting the best mortgage rates for investment property nz if your total debt is too high. It forces a focus on your actual ability to pay the loan back comfortably.

Can a mortgage broker really get a better rate than I can get myself?

A mortgage broker can often secure a better deal because they have the power to negotiate with multiple lenders simultaneously. We know which banks are currently under quota and more likely to offer a discount to win your business. Beyond just the interest rate, we also negotiate for better terms and cash-back offers that you might not get by walking into a branch yourself.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage Rates NZ: Your 2026 Guide to Understanding Home Loan Interest

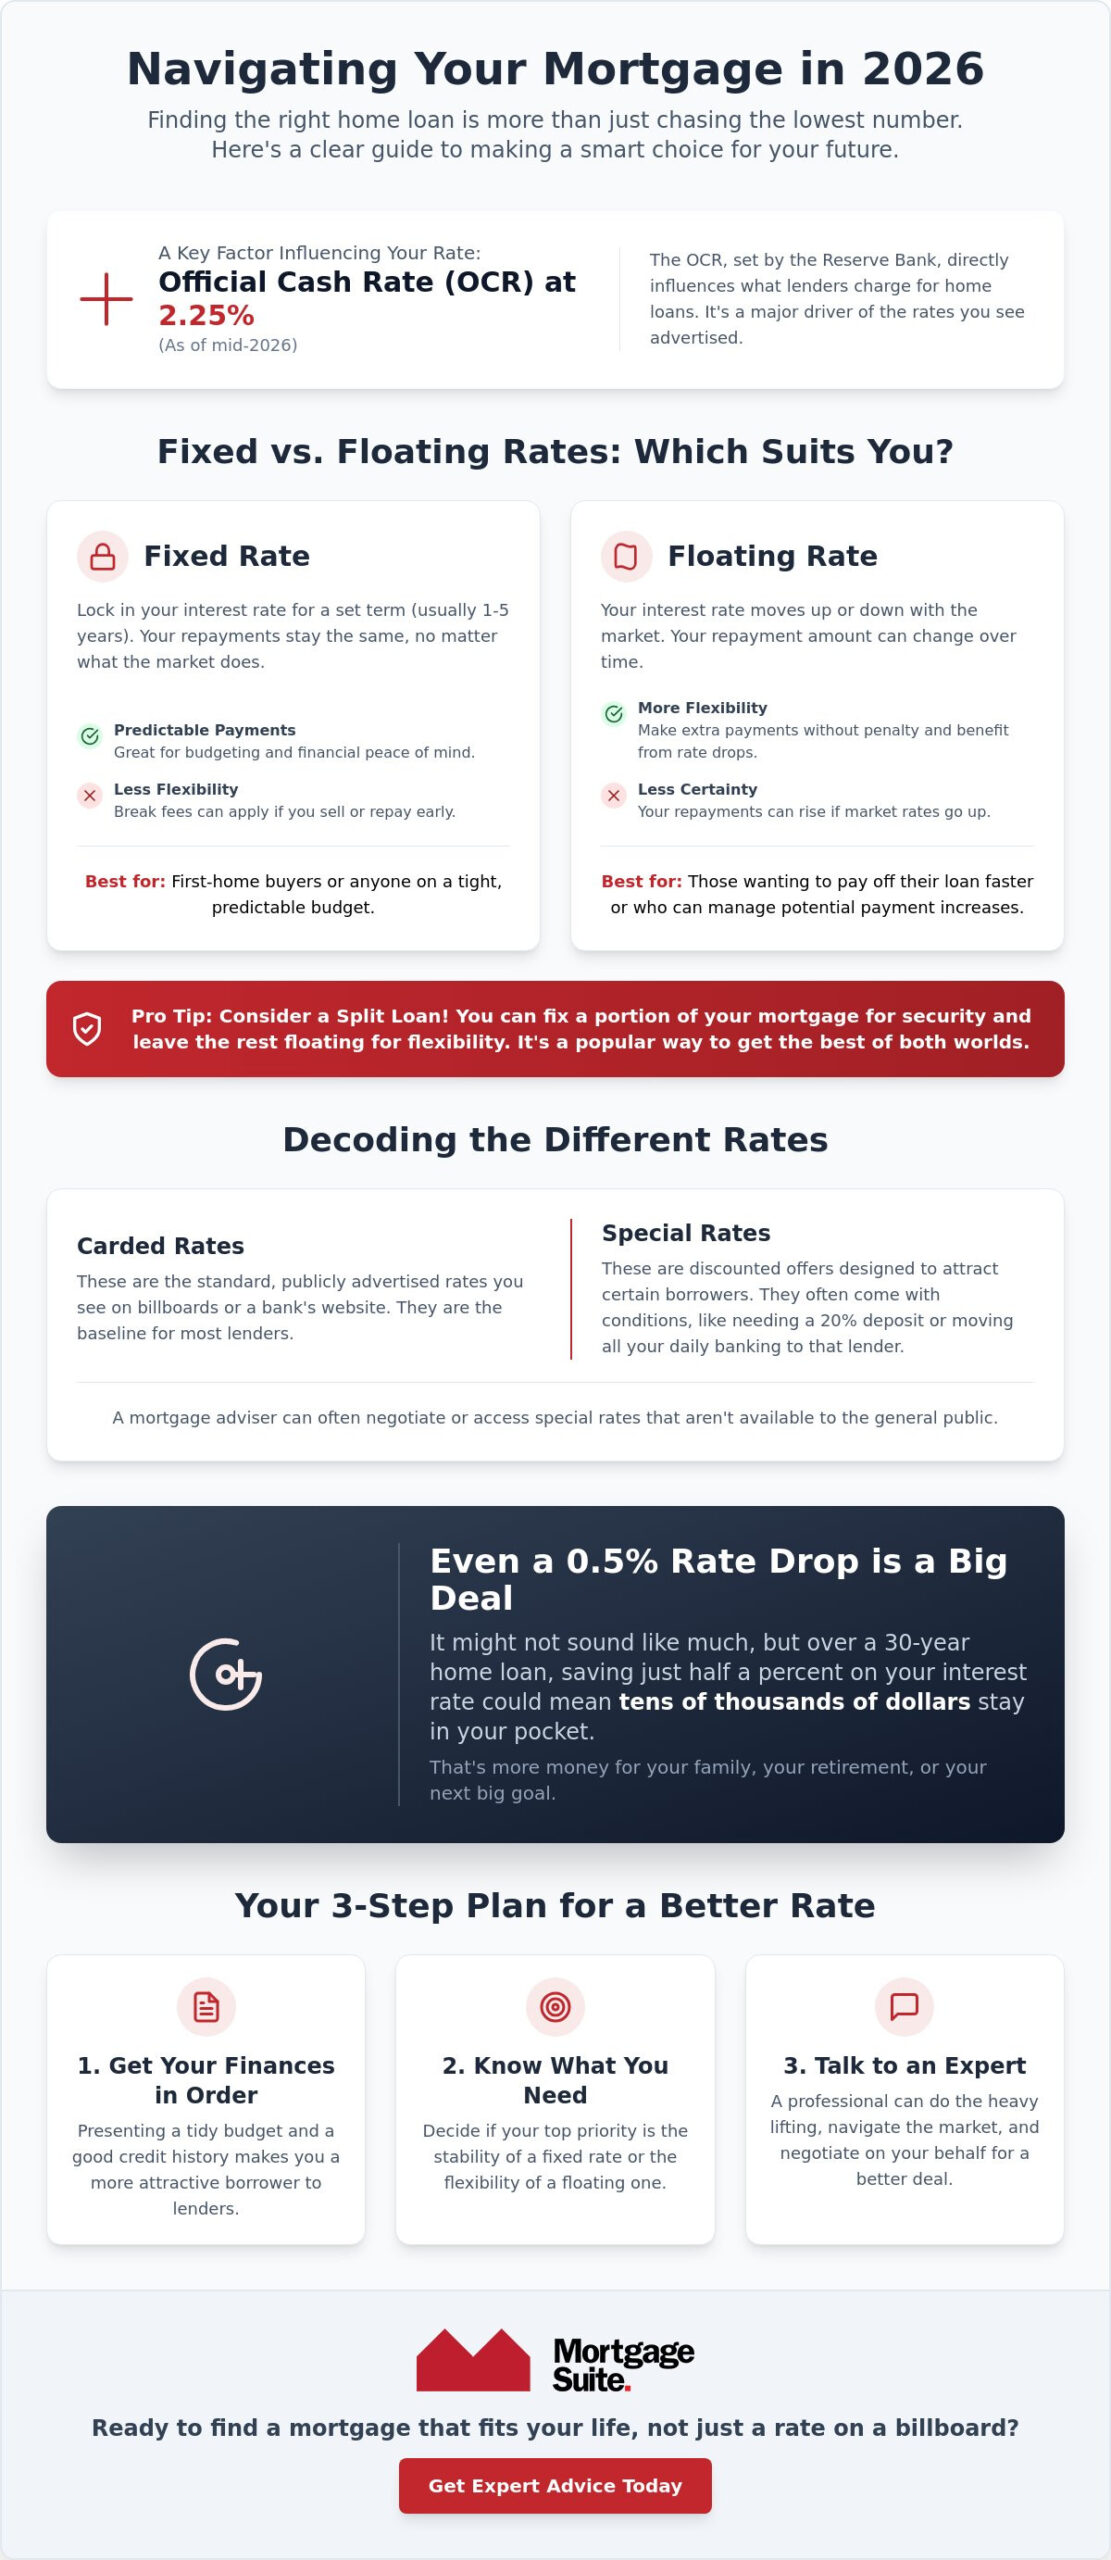
What if the lowest interest rate you see on a billboard actually ends up costing you more over the life of your loan? It’s easy to get caught up in the race for the smallest number, but the truth is that mortgage rates nz are about strategy as much as they are about price. With the Official Cash Rate sitting at 2.25% as of mid-2026, you might feel like the window for a good deal is closing or that the big banks aren’t really listening to what you actually need.

We understand that the constant talk of debt-to-income ratios and shifting lending laws can feel like a lot of noise. You want a home loan that provides stability without the confusing financial talk that usually comes with it. This guide will show you how to navigate the 2026 market with confidence. You’ll learn the real difference between fixed and floating rates, how current regulations like debt-to-income limits impact your borrowing power, and why the right lender is the one who treats you like a partner rather than just another file. By the end, you’ll have a clear, simple path forward to secure your home and manage your wallet with ease.

Key Takeaways

  • Learn how mortgage rates nz are shaped by the wider economy and what that actually means for your monthly budget.
  • Understand the difference between locking in your repayments with a fixed rate or staying flexible with a floating option.
  • Discover how the Reserve Bank’s decisions on the Official Cash Rate directly influence the interest you pay on your home loan.
  • Explore why professional second-tier lenders might be the right fit if the big mainstream banks aren’t meeting your specific needs.
  • Gain the confidence to negotiate a better deal by getting your finances in order and using expert help to do the heavy lifting.

Understanding Mortgage Rates in NZ: The Basics for 2026

When you’re comparing mortgage rates nz, it’s helpful to view them simply as the fee you pay the bank to use their money to buy your property. You can think of it as the “cost of borrowing”. In 2026, these rates are influenced by a mix of local factors, such as the Reserve Bank’s inflation targets, and global economic shifts that change how much it costs New Zealand banks to get the funds they eventually lend to you.

While the headline number is often what grabs your attention, the best rate for your situation isn’t always the lowest one on the screen. The right deal is the one that aligns with your life goals. This might mean having the flexibility to make extra payments without being charged or choosing a structure that gives you peace of mind while you grow your family.

How Interest is Calculated on Your Home Loan

Understanding how your monthly payments are split can be quite eye-opening. Every time you make a repayment, part of it goes toward paying back the original amount you borrowed. The rest is the fee for using the bank’s money.

You can think of this fee like renting the bank’s cash. Just as you might pay rent to live in someone else’s house, you pay this fee to use their capital to buy your own home. It’s a straightforward exchange, but the numbers add up quickly over time.

Even a tiny change in your interest rate can have a massive impact on your long-term wealth. Saving just 0.5% on your rate might look small on paper today, but over a 30-year term, it could save you tens of thousands of dollars. That’s money that stays in your pocket for your retirement or your children’s education rather than going to the bank’s profits.

The Difference Between Carded and Special Rates

If you’ve been browsing bank websites recently, you’ve likely noticed two different sets of numbers. “Carded” rates are the standard, advertised prices that everyone sees on billboards or in the branch. They are the baseline starting point for most lenders.

On the other hand, “special” rates are the discounted offers banks use to attract specific types of borrowers. These lower rates usually come with strict conditions. For instance, you might need a 20% deposit or be required to move all your daily banking and credit cards to that specific provider.

This environment of strict lending rules and tiered pricing grew out of the historical New Zealand property bubble, which led to much tighter controls around how banks manage their risks. Because of these complexities, a professional can be a huge asset. They often have access to special rates that aren’t even listed publicly, using their industry relationships to negotiate a deal that fits your unique financial situation.

Fixed vs Floating Rates: Finding the Right Fit for Your Budget

Deciding between a fixed or floating rate is one of the most important choices you’ll make when looking at mortgage rates nz. It isn’t just about chasing the lowest number you see on a website. It’s about how you want to manage your household stress and your long-term financial goals. Many Kiwis choose a “split” loan structure, where they keep a small portion on a floating rate and lock the rest into a fixed term. This approach lets you hedge your bets, giving you the security of a set payment while still allowing you to pay off bits of your debt faster if you have some extra cash.

A fixed rate mortgage is a tool for financial peace of mind because it removes the guesswork from your monthly bank statement for a set period, usually between one and five years.

When to Choose a Fixed Rate

If you’re a first-home buyer or a family running on a tight budget, a fixed rate is often the most sensible path. When you lock in your rate, your repayments stay exactly the same regardless of what happens with the economy. This certainty is vital when you consider that housing costs are a major part of most people’s weekly outgoings. Data from the Housing in Aotearoa New Zealand: 2025 report shows that managing these costs is a top priority for most households, and a fixed rate helps you plan your future with confidence.

There are a couple of trade-offs to keep in mind. If mortgage rates nz happen to drop while you’re locked in, you won’t benefit from those lower interest costs. You also need to be aware that banks usually charge “break fees” if you decide to sell your house or pay off the loan before the fixed term ends. It’s a commitment to a specific path, so it’s best for those who value stability over total freedom.

The Flexibility of Floating Rates

Floating rates, which are sometimes called variable rates, move up and down as the market shifts. While these rates often start a bit higher than the best fixed deals, they offer a level of freedom that fixed terms simply can’t match. You can usually make extra payments or pay off the entire loan whenever you like without being hit with any penalties. This makes them a brilliant choice if you’re expecting a pay rise, a lump sum of money, or if you’re planning to sell the property soon. If you’re still weighing up which path is right for you, looking into different home loans with a professional can help you see which structure fits your life best.

Why NZ Mortgage Rates Move: The OCR and Economic Drivers

It can feel a bit mysterious when you see mortgage rates nz change overnight. One day they are steady, and the next, every major bank has updated their website with new numbers. These movements aren’t random. They are mostly driven by the Official Cash Rate (OCR), which you can think of as the “wholesale price” of money. Just like a shop buys goods at a wholesale price and adds a bit extra before selling them to you, banks buy money at the OCR and then add their own costs and profit margins to create your mortgage rate.

The Reserve Bank uses this tool to keep the New Zealand economy stable. If things are moving too fast and prices are rising too quickly, they might hike the rate to cool things down. If the economy needs a bit of a boost, they might lower it. It is a balancing act that affects every homeowner in the country.

How the Reserve Bank Influences Your Wallet

When the Official Cash Rate (OCR) goes up, it becomes more expensive for banks to borrow money. Naturally, they pass those costs on to you by raising their mortgage rates. What is interesting is that banks don’t always wait for an official announcement. They employ teams of experts who watch the economy closely. If they expect a rate hike is coming in a few months, they might start nudging their fixed rates up early to stay ahead of the curve.

These cycles of rising and falling rates are a normal part of the financial landscape. While the headlines can sometimes sound alarming, they are just part of a larger pattern. Having a seasoned professional in your corner helps you see through the noise. We can help you decide whether to lock in a rate now or wait for the next cycle to begin.

DTI and LVR: The Rules of the Game

Beyond the OCR, banks also look at your personal scorecard to decide what rate they can offer you. The first part of this is your Loan to Value Ratio (LVR). This is just a simple way of looking at how much you want to borrow compared to what the house is actually worth. Generally, if you have a larger deposit, you are seen as a lower risk, which often unlocks those special rates we mentioned earlier.

The second part is the Debt to Income (DTI) ratios. This is a check to see how much you earn versus how much total debt you will be carrying. DTI rules are designed to protect both you and the bank from future stress by ensuring you don’t take on more than you can realistically handle if life takes an unexpected turn. It is about making sure your home remains a sanctuary rather than a financial burden.

Mortgage Rates NZ: Your 2026 Guide to Understanding Home Loan Interest

Beyond the Big Banks: Exploring 2nd Tier Lending Rates

If you’ve ever walked into a major bank and felt like just another number on a spreadsheet, you’re not alone. Many New Zealanders assume that the big four banks are the only game in town, but there is a whole world of professional, reputable alternatives known as second-tier lenders. These providers often offer mortgage rates nz that look a bit different from the ones on the high street billboards. This isn’t because they are less secure; it’s simply because they have a different way of looking at risk and a different set of rules to follow than the mainstream institutions.

A broker is often the only way to access these “hidden” options. You can’t usually just walk into a branch for these lenders because they prefer to work through experts who can package your application correctly. They are particularly brilliant for people who don’t fit the standard bank mould, such as the self-employed, contractors, or those with non-standard income that the big banks find too difficult to process. These 2nd tier lenders provide a vital service that keeps the market competitive and inclusive.

Why Consider a Non-Bank Lender?

One of the biggest benefits of looking beyond the big banks is the human element. Mainstream lenders often use rigid computer algorithms to decide your fate. If you don’t tick every single box, your application is often declined without a second thought. Second-tier lenders tend to look at your whole story. They might see that while your income was lower last year due to a business startup, your current contracts are solid. They can act as a vital stepping stone. You might start with them to get into your house now, then move back to a mainstream bank in a few years once your financial history is more traditional. You can feel confident knowing they are still strictly regulated and safe to use.

Tailored Rates for Unique Situations

There are times when the absolute lowest interest rate isn’t the most important factor in your decision. If you’re involved in property development or complex investment scenarios, you need a lender who understands the nuances of the project. In these cases, having a loan that is approved quickly and offers flexible terms is worth far more than saving a tiny fraction on mortgage rates nz. Property investors in particular may also benefit from exploring a commercial property refinance NZ strategy to unlock equity and align their debt with current market conditions. If you’ve been declined by a bank, don’t lose heart. It’s often just a sign that you need a more tailored approach rather than a “no” to your home-buying dreams. We specialise in finding these solutions for our clients, so if you’re ready to see what’s possible, you can explore our home loan options today.

Securing the Best Mortgage Rate for Your Situation

Getting the best deal on your home loan involves more than just refreshing a webpage to see the latest numbers. To truly secure the most competitive mortgage rates nz, you need to present yourself to the bank as a low-risk, high-quality borrower. This starts with getting your “financial house in order” well before you fill out an application. Banks aren’t just looking at your income. They are looking at your habits, your debts, and how you handle the money you already have.

It’s also vital to look at the total cost of the loan rather than just the interest rate. Sometimes a bank might offer a slightly higher rate but include a generous cash-back offer or waive their application fees, which could leave you better off in the first few years. Taking a long-term view of your mortgage journey allows you to see these opportunities. Your mortgage isn’t a “set and forget” product; it’s a living part of your financial life that should be reviewed as your circumstances change. If your portfolio has grown over the years, it may also be worth considering whether a commercial property refinance NZ wide could help you restructure your debt and release equity for your next move.

Tips for a Successful Application

One of the most effective ways to boost your borrowing power is to reduce or close high-interest debts before you apply. Credit cards, store cards, and personal loans are often viewed unfavourably by bank systems because they represent a high committed monthly cost. Even if you don’t owe much on a credit card, the bank often assesses you based on the total limit available to you, not just the balance.

Showing a consistent savings history is another way to score a better deal. It proves to the lender that you have the discipline to live within your means. When you have a professional advocate like Krish in your corner, the bank often takes your application more seriously. We know how to highlight the strengths in your financial story, ensuring the person on the other end of the desk sees you as a partner they want to invest in.

How Mortgage Suite Helps You Win

At Mortgage Suite, we believe that the right loan is about far more than just a percentage point. It’s about finding a structure that gives you the freedom to live your life while you pay off your home. Krish Krishna brings over 20 years of deep banking experience to the table, acting as a “secret weapon” for our clients. Having spent two decades inside the system, Krish knows exactly how banks think, how they price their loans, and where there is room to move.

Our service focuses on negotiation and advocacy. We do the heavy lifting for you, talking to multiple lenders to find the one that fits your specific needs. Whether you are a first-home buyer or a seasoned investor, we ensure you aren’t just processed by a machine. We build a bridge between your personal goals and the rigid world of institutional banking. Ready to see what rates you could qualify for? Chat with us today!

Take Control of Your Financial Future Today

Navigating the landscape of mortgage rates nz in 2026 doesn’t have to be a source of stress. Whether you’re deciding between the certainty of a fixed term or the freedom of a floating rate, the most important thing is having a strategy that fits your life. You now know that the Official Cash Rate is just one piece of the puzzle and that there are excellent options available beyond the big banks if your situation is a bit unique.

At Mortgage Suite, we bring over 20 years of banking and lending expertise to ensure you find the right path. We have access to both mainstream banks and professional second-tier lenders, providing specialised support for everyone from first-home buyers to seasoned investors. You don’t have to do the heavy lifting alone. We’re here to act as your advocate and negotiator to get the deal done. Talk to Mortgage Suite about finding the right rate for your home loan. We look forward to helping you move into your next home with total confidence.

Frequently Asked Questions

How often do mortgage rates change in New Zealand?

Mortgage rates in New Zealand can technically change every single day, although major shifts usually happen in cycles. Banks typically adjust their pricing following the Reserve Bank’s eight scheduled reviews of the economy each year. They also watch international money markets closely, so you might see rates move even when there hasn’t been an official local announcement. It’s a fast-moving environment that requires regular check-ins.

Is it better to fix my mortgage for 1 year or 5 years in 2026?

Choosing between a one-year or five-year fix depends on your need for certainty versus your desire for flexibility. In 2026, many borrowers prefer shorter terms like one or two years to see if the market cools further. A five-year fix provides absolute peace of mind for your household budget, but you might find yourself locked into a higher rate if the general market drops significantly during that time.

What is a “cash-back” offer and is it worth taking a higher rate for it?

A cash-back offer is a lump sum of money the bank gives you when your loan settles, which is often used to cover legal fees or moving costs. Whether it’s worth a slightly higher rate depends on the maths. You need to calculate if the extra interest you’ll pay over the fixed term is more than the cash you receive upfront. Often, the upfront cash is a massive help for first-home buyers.

Can I negotiate my mortgage rate directly with the bank?

You can try to negotiate with your bank, but they often reserve their best deals for those who have professional representation. Banks know that brokers have access to the pricing of all their competitors, which creates a much stronger negotiating position. Having an expert handle these conversations usually results in a better outcome than trying to manage the back-and-forth on your own while you’re busy with life.

What happens to my rate if the OCR goes down?

If the Official Cash Rate goes down, you’ll usually see an immediate drop in floating mortgage rates nz. However, if you are currently on a fixed-rate term, your repayments won’t change until that term ends. This is why some people choose to keep a portion of their loan on a floating rate. It allows them to benefit from these downward shifts in the economy as soon as they happen.

Why are 2nd tier lender rates sometimes higher than bank rates?

Second-tier lenders often charge slightly more because they are willing to take on different types of risk that mainstream banks won’t touch. They might help someone who is self-employed or has a unique income structure that doesn’t fit a standard bank algorithm. The slightly higher rate reflects the extra work and flexibility they provide to get your loan approved when a big bank has already said no.

Do I need a 20% deposit to get the best interest rates?

Generally, you do need a 20% deposit to unlock the “special” advertised rates you see on billboards. Borrowers with smaller deposits are often charged a low equity margin, which is an extra fee or a higher interest rate to cover the bank’s risk. However, there are specific schemes available in 2026 for first-home buyers that allow for a 5% deposit while still keeping your overall costs manageable.

How much does a mortgage broker charge to find me a rate?

For most standard residential home loans, a mortgage broker doesn’t charge you a fee for their service. Instead, they are paid a commission by the lender once your loan is settled. This means you get professional advice, expert negotiation, and access to a wide range of mortgage rates nz without having to pay anything out of your own pocket for the consultation and application process.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.