Mortgage approval in principle in New Zealand: timing and next steps

Finding a property is not the finish line. Approval in principle for a mortgage in NZ usually takes 2 to 5 working days once the lender has all the required documents, and is typically valid for 60 to 90 days, depending on the lender. It gives you a borrowing guide, but the lender still needs to assess the property and your financial situation before confirming the loan.

It’s natural to want a clear answer before making an offer, especially when buying a home already feels like a lot to manage. This guide explains what approval in principle means, what documents a lender may ask for and how long the decision can take. You’ll also learn what to do once you’ve found a property, from sharing its details with the lender to progressing towards formal approval.

Key Takeaways

  • Gather at least 3 months of bank statements from all your accounts, and be ready to explain regular spending or unusual transactions.
  • Prepare income records that fit your work situation, including tax records or financial statements if you’re self-employed.
  • A full credit check leaves a record on your credit file, so understand the effect before making multiple applications.
  • Once you find a property, share its details with the lender; they may also ask for the signed sale and purchase agreement, a valuation or a LIM report.
  • Approval in principle is a useful guide, but the lender still needs to assess the property and your finances before confirming the home loan.

Bank statements and deposit evidence

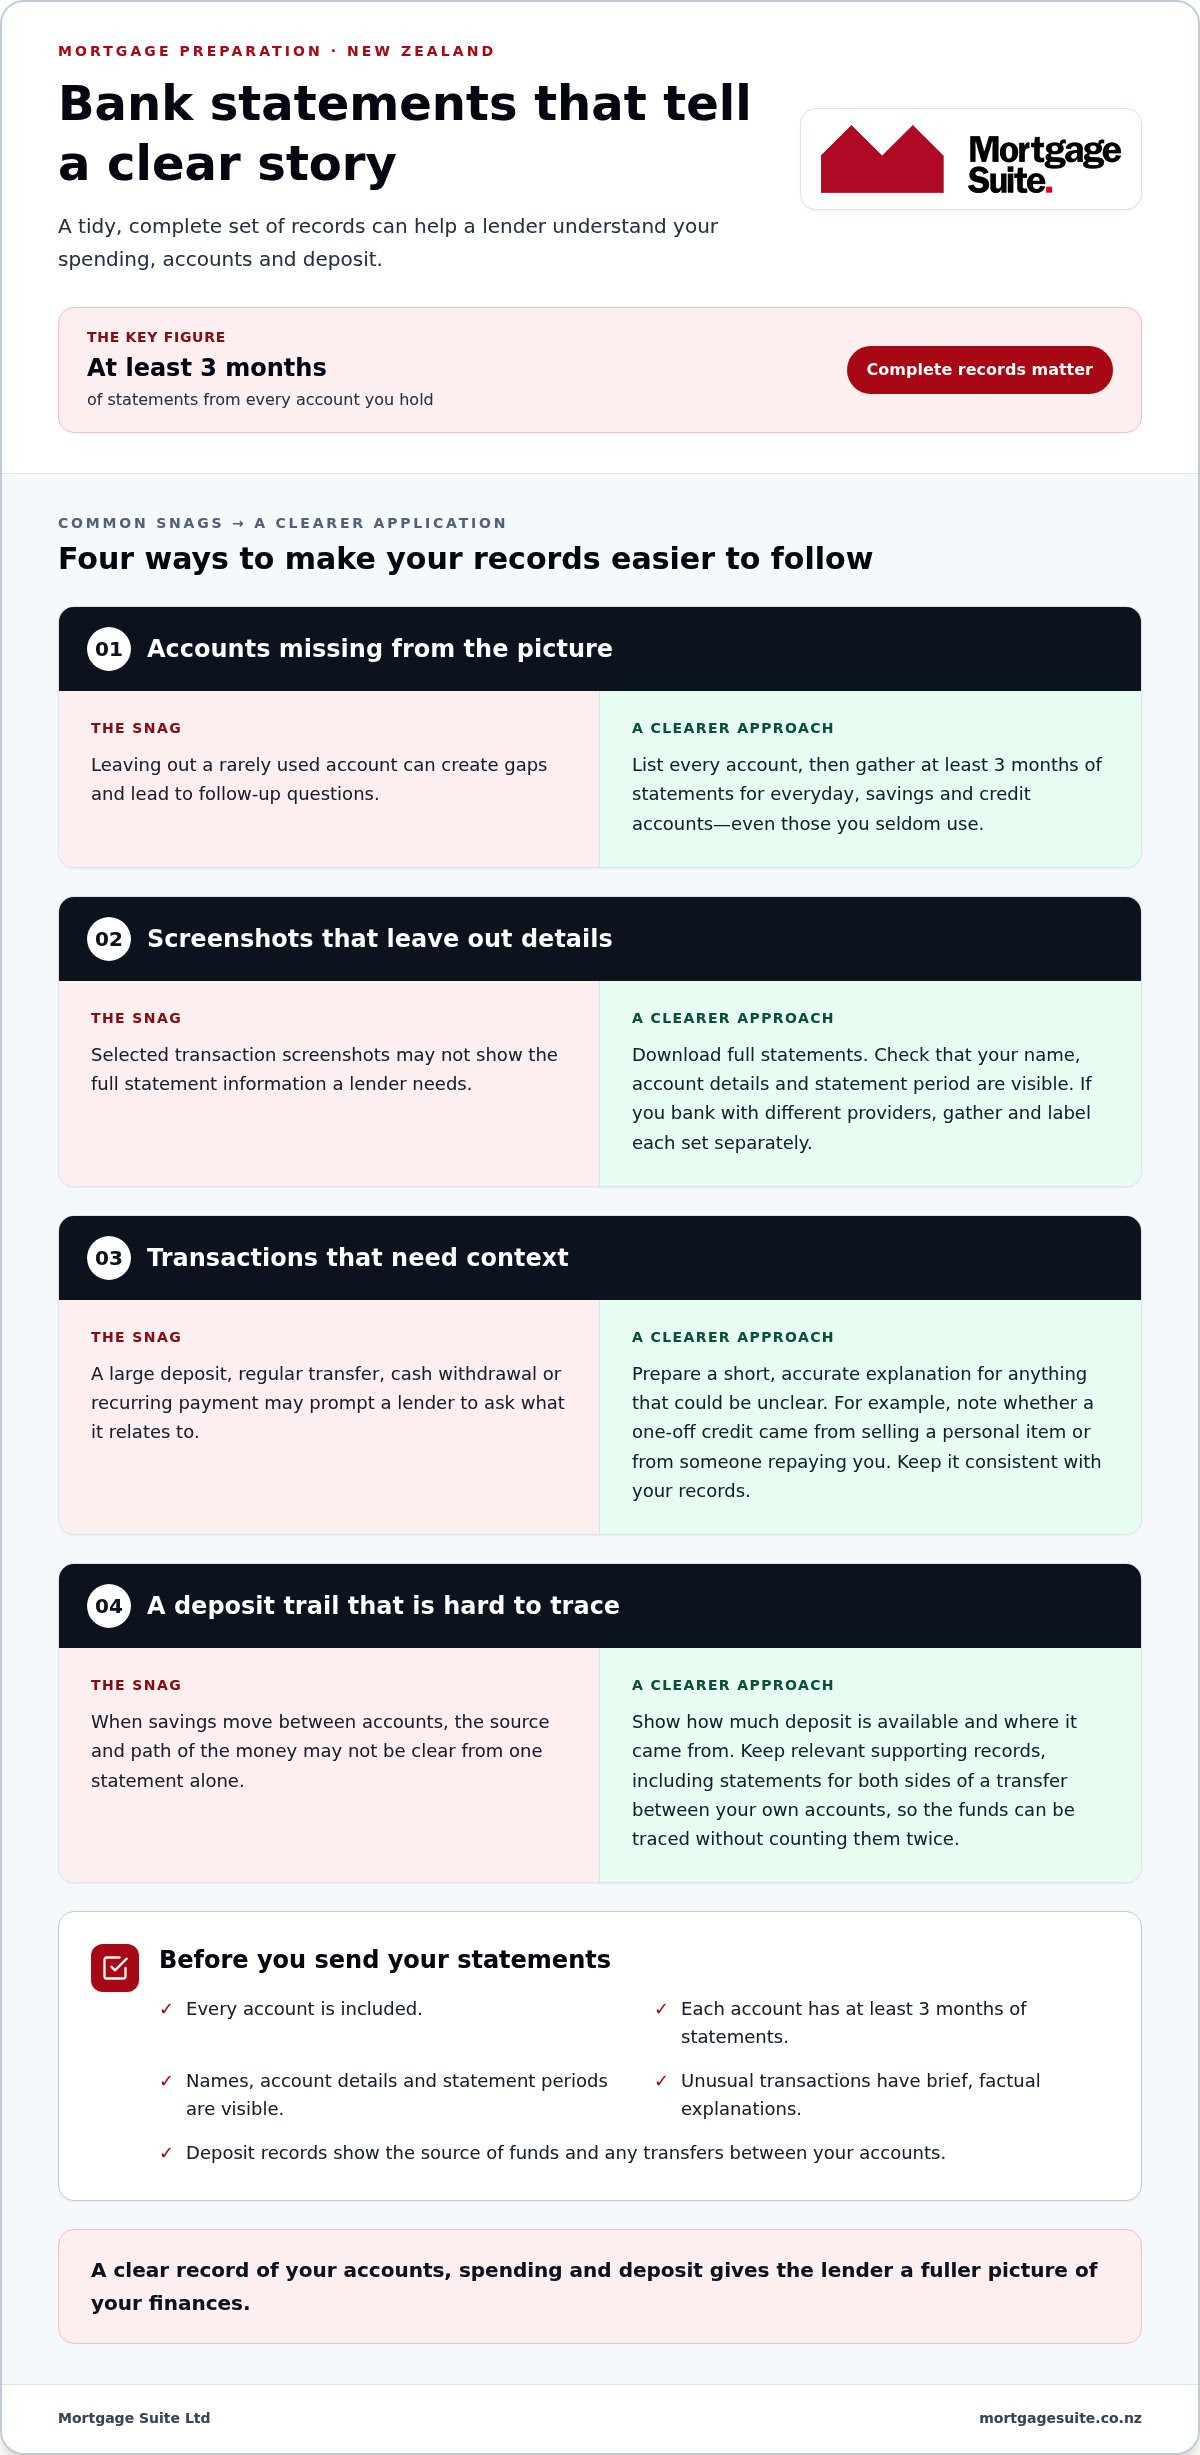
Bank statements help a lender understand how you manage money, not just what you earn. For a New Zealand home-loan application, prepare at least 3 months of statements from all your accounts. Include everyday, savings and credit accounts, even if you rarely use them. Missing accounts can leave gaps in the picture and lead to follow-up questions.

Download full bank statements instead of sending selected transaction screenshots. Check that each document shows your name, account details and statement period. If you have accounts with different banks, gather the statements separately and label them clearly. Organising files by account makes it easier to send a complete set with your application.

Transactions help explain your regular commitments and spending. A lender might ask about a large deposit, regular transfers, cash withdrawals or recurring payments. Add a short, accurate note if a transaction could be unclear. For example, explain whether a one-off credit came from selling a personal item or receiving repayment from someone you know. Keep the explanation consistent with your records.

Your deposit evidence should show how much is available and where it came from. Match account balances with supporting records where relevant, such as a savings history or documents showing a recent transfer. If money moved between your own accounts, keep statements for both sides of the transfer. This helps the lender trace the funds without counting the same money twice.

Deposit size matters. Most New Zealand lenders currently require a minimum home-loan deposit of 20%. A First Home Loan can require a deposit of at least 5% of the home’s purchase price. These are different lending pathways, so identify which one applies before relying on a deposit figure.

  • List every account you hold, then download at least 3 months of statements for each.
  • Check that statement dates, account names and balances are visible.
  • Keep records that explain where your deposit came from and how transfers moved.
  • Write brief explanations for unusual transactions before the lender asks.

For example, if your deposit is spread across two savings accounts, include both sets of statements and identify the balance in each. If a recent transfer brought the savings together, keep the statements showing the money leaving one account and arriving in the other. Clear records help the lender trace your deposit and assess your application with fewer avoidable questions.

Credit checks and multiple applications

A full credit check for mortgage pre-approval in New Zealand leaves a record on your credit file. Lenders use the application process to assess your financial position, so it helps to know when a check is being made. Before applying, ask whether the process involves a full credit check or only an initial discussion. Knowing the difference can help you plan your next steps.

Applying to several lenders at once may seem like a quick way to compare options. However, each full credit check can leave a record, so avoid submitting applications without a clear reason. First, gather details about your income, deposit and spending. Use them to consider which lending approach may suit your circumstances before deciding where to apply.

Your credit file is one part of a lender’s assessment, not a complete picture of your home-buying plans. Your application also needs to explain the loan you want and how repayments fit your budget. Include accurate details of existing debts and credit facilities rather than assuming the lender will infer them. Clear information helps keep your application consistent.

  • Ask whether a lender’s first review includes a full credit check.
  • Keep a record of the lenders you approach and when you apply.
  • Use the same accurate details for income, debt and regular commitments.
  • Read each lender’s requests carefully before sending further documents.

For example, if you’ve spoken with one lender and want to approach another, note whether the first conversation included a full credit check. If it did, mention that when discussing your next application. Keeping a clear record helps you understand what has happened and avoid duplicate applications made simply because the process feels uncertain.

Questions about credit can feel personal, but they are a practical part of assessing a mortgage application. If a lender asks about a missed payment or an existing credit facility, answer directly and provide relevant context. For instance, explain whether a payment issue was temporary or whether an account is still open. Keep your explanation factual and consistent with your documents.

Before applying, make a simple application plan. Note which lender you intend to approach, what documents are needed and whether a full credit check will take place. When comparing lending options, focus on how each proposed loan fits your budget and property plans, not on making more applications. A considered approach helps you understand decisions and respond promptly to follow-up questions.

Income documents for an application

For mortgage pre-approval, New Zealand banks assess evidence of your income. They may ask for your last 2 years of tax records, and self-employed applicants should prepare their last 2 years of financial statements.

Income document types

The right records depend on how you earn. Tax records show income over time, while financial statements help explain self-employment income. Use documents covering the periods requested, and make sure names and figures are readable. If your income comes from different sources, organise the evidence by source so the lender can follow the details.

  • Gather your last 2 years of tax records as income evidence.
  • If you’re self-employed, prepare your last 2 years of financial statements.
  • Group records by tax year and label each file clearly.

Compare the documents before sending them. For example, if a tax record and a financial statement show different income figures, explain what each figure represents. One may show business income while another records your personal income. Clear labels and a brief explanation help the lender understand the difference without guessing.

Keep the original files together, then make a separate set for your application. This makes it easier to respond if a lender asks for a particular year or income source. Don’t alter figures or crop out surrounding details. A complete document is easier to assess than a partial image.

Bank document requirements

What documents do NZ banks require for mortgage pre-approval? Prepare your last 2 years of tax records, and, if you’re self-employed, your last 2 years of financial statements. The lender’s requests depend on how you earn and what it needs to understand your income.

  • Check which income periods the application asks you to provide.
  • Include all relevant pages, not just the page showing a total.
  • Use clear file names, such as “tax records” and the year covered.
  • Keep digital copies ready if the lender requests another document.

Before submitting, check that each file opens and its text is legible. Make sure the applicant’s name matches across the records, and arrange documents in date order. If you’re applying with another borrower, keep each person’s income documents in a separate folder. This helps show whose records support each part of the application.

Self-employed applicants can make the review clearer by keeping financial statements alongside matching tax records. For example, label both sets with the same year, then check that they cover the period requested. If a document uses business terms you find unclear, add a plain-English note instead of editing the original figures. This gives the lender context while preserving the source record.
Mortgage approval in principle in New Zealand: timing and next steps

Meaning and conditions of mortgage pre-approval

Mortgage pre-approval is a lender’s conditional view of your borrowing, based on the information available at that stage. It can guide your property search, but it isn’t final approval for a specific home.

Serviceability assessment

Serviceability means whether your income can support proposed repayments alongside your other financial commitments. A lender may use a serviceability stress test, assessing repayments at a higher hypothetical interest rate to test affordability if rates change.

Debt-to-income limits and stress-test rates are different assessment tools. Don’t assume the same figure applies across every New Zealand lender. Consider how a lender assesses your income, debts and regular spending together. Existing credit limits and other repayments can also affect the amount it considers affordable.

Bank and broker approval differences

A bank assesses your application under its own lending criteria and makes its own pre-approval decision. A mortgage broker can help prepare and present your application to a lender, but the lender makes the decision.

A broker’s approval in principle still depends on the lender’s assessment. Compare what the decision covers, which conditions remain and whether a specific property has been assessed. Neither a broker’s summary nor a bank’s conditional pre-approval is a binding commitment from the lender to lend. Formal unconditional approval is that commitment.

Loan-to-value ratio rules

The loan-to-value ratio compares the amount borrowed with the property’s value. A larger deposit means you borrow a smaller share of the property’s value, which can affect whether your application fits a lender’s criteria.

Use a realistic purchase range and deposit amount when discussing pre-approval. The lender may need information about a specific property before confirming the loan. If the property value or your deposit differs from the details used earlier, the lender may need to reassess your application against its criteria.

Approval process and conditions

Conditional pre-approval is an early assessment of your borrowing, not a final decision on a particular property. The next steps depend on the lender’s conditions, including its assessment of the home and whether your financial details are still current.

Read the written decision carefully and note what the lender still needs. For example, it may require property information or a signed sale and purchase agreement before proceeding. Keep your details consistent throughout the application, and tell the lender if your circumstances or purchase plans change.

Pre-approval processing time and validity

Once a lender has all required documents, a mortgage pre-approval decision commonly takes 2 to 5 working days in New Zealand. The approval is typically valid for 60 to 90 days, depending on the lender. Use those timeframes to plan your property search, while checking the expiry date and conditions stated in your decision.

Processing starts after the lender receives the information it needs, not necessarily when you first make contact. Missing documents or unanswered questions can delay the assessment. Before submitting, check that each requested item is included, readable and covers the right period. If the lender asks for clarification, provide the specific record or explanation requested.

Keep your approval letter or email somewhere easy to access. Note its expiry date in your calendar and allow time to act before it lapses. For example, if you receive approval while still searching, check the date before making an offer later. A valid approval helps guide your budget, but it doesn’t replace the lender’s assessment of a particular property.

After finding a home, give the lender the property information it requests. Lenders in New Zealand generally need details about the property before confirming a home loan, even if you have conditional pre-approval. The lender may also ask for a signed sale and purchase agreement. This property review is separate from the assessment of your borrowing position.

If you need a home loan for an auction purchase, arrange conditional pre-approval before bidding. Auctions can move quickly, so understand your borrowing range and the conditions attached before auction day. A conditional decision is not the same as unconditional approval, and it doesn’t confirm that every property will meet the lender’s requirements.

Your finances also need to remain consistent with the information used for pre-approval. A change in income, debt or other commitments may affect the lender’s assessment. If something changes during your search, tell the lender before relying on the earlier decision. This helps keep the next assessment aligned with your current circumstances.

  • Record the lender’s stated expiry date and conditions.
  • Send requested documents promptly and answer follow-up questions clearly.
  • Once you find a property, provide the details the lender needs for its review.
  • Before an auction, understand your conditional approval and borrowing limit.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd helps first-home buyers explore home-loan options and prepare for the steps from pre-approval to a property-specific application. If a mainstream bank’s criteria don’t fit your circumstances, a decline doesn’t automatically end the conversation. Mortgage Suite Ltd also specialises in 2nd Tier Loans for borrowers who don’t fit mainstream-bank criteria, although lending still depends on the lender’s assessment.

Bring your borrowing questions and pre-approval conditions together to discuss a path that suits your goals. For support with your home-loan plans, contact Mortgage Suite Ltd to start a conversation.

Take your next step with confidence

Your next step is to turn your borrowing estimate into a plan that fits your goals. Before speaking with a lender, decide what matters most, such as manageable repayments or flexibility if your plans change. Approval in principle can help frame that conversation, while your chosen property and circumstances shape the lending decision.

If you’d like support thinking through your options, contact Mortgage Suite Ltd about pre-approval. A clear plan can make the property search feel more manageable, one considered step at a time.

Frequently Asked Questions

What happens after you find a property?

Start by comparing the property with the assumptions behind your borrowing plan. Note the agreed price, any conditions in the sale and purchase agreement, and when you need the lender’s response. Keep copies of correspondence and send requested documents together, clearly labelled. If you’re considering an auction, remember to arrange conditional pre-approval before bidding, rather than relying on a decision made afterwards.

What is mortgage pre-approval?

Mortgage pre-approval is an early lender assessment based on your financial details, designed to help set a sensible property-search range. Use it to compare homes with your budget, not as a reason to borrow the maximum offered. Before making an offer, consider how repayments would fit your spending plans and whether the proposed loan suits your longer-term goals.

Will applying for pre-approval affect my credit score in NZ?

A full credit check leaves a record on your credit file, but that record is not the same as a credit-score result. Ask the lender whether its pre-approval process includes a full enquiry, and note the date and purpose. If you’re unsure about information on your file, review it before applying so you can accurately explain any errors or unfamiliar entries.

What is an approval in principle mortgage in NZ?

It’s a lender’s preliminary view of your borrowing based on the information supplied, not a final decision on a particular home. Read the written terms carefully, including the amount, expiry date and outstanding conditions. For instance, an approval might guide your search but still require further steps before the lender commits to the loan. Keep the letter accessible so you can refer to its specific conditions.

How long does mortgage approval in principle last in NZ?

Pre-approval is typically valid for 60 to 90 days in New Zealand, depending on the lender. Use the date in your decision letter as your reference, since the lender’s stated terms apply to your application. If your search is taking longer, plan ahead rather than relying on an expired decision. Keep a note of when it was issued and make a fresh plan with the lender if needed.

Is mortgage approval in principle legally binding in New Zealand?

No. Conditional pre-approval is not the lender’s binding commitment to provide a loan. Formal unconditional approval is the lender’s commitment to lend. Keep that distinction in mind when planning a purchase, especially if your offer depends on finance. Read the written conditions closely, and don’t treat a preliminary decision as permission to proceed without completing the lender’s required steps.

How much deposit do you need for a mortgage in NZ, including low-deposit options?

Most New Zealand lenders currently require a minimum home-loan deposit of 20%. A First Home Loan requires at least 5% of the home’s purchase price. These figures describe different lending pathways, not automatic approval thresholds. Before setting your search budget, work out how much deposit you can document and whether the relevant pathway fits your circumstances. The lender assesses the full application as well.

How do you apply for mortgage pre-approval in New Zealand, and how long does it take?

Choose a lender or discuss your application with a mortgage broker, then provide the documents requested and answer follow-up questions. Lenders commonly take 2 to 5 working days to decide after receiving all required documents. To make the process easier to manage, keep a record of what you’ve sent and what remains outstanding. That way, you can respond promptly if the lender asks for clarification.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan for visa holders in NZ: your 2026 guide

Can your visa allow you to buy a home in New Zealand but still leave a lender unsure about your application? That can happen because eligibility to purchase and mortgage approval are separate decisions. If you’re looking at a home loan for visa holders nz, understanding that difference is a useful first step.

It’s understandable to feel uncertain. Property rules can affect whether you’re allowed to buy, while lenders may assess visa type, income, deposit and supporting documents in different ways. A decline from a mainstream bank isn’t necessarily the end of the road, but no lending pathway can promise approval.

This guide explains how the two decisions fit together, what lenders may look at, how mainstream and alternative lending pathways can differ, and which documents may help explain your circumstances. Mortgage Suite helps borrowers understand their options and present their situation to lenders, so you can have a clearer conversation about possible next steps.

Key Takeaways

  • Check your right to buy a property separately from a lender’s decision to approve a mortgage. They’re different assessments.
  • For a home loan for visa holders nz, be ready to explain your visa conditions, income, debts, deposit source and the property you’re considering.
  • Compare mainstream and alternative lending pathways against your circumstances, as lender criteria and flexibility can vary.
  • Organise your key documents before discussing an application, while allowing for lenders to request different information.
  • A broker can help present your circumstances clearly and negotiate with lenders, but approval depends on the details of your application.

Home loan for visa holders in NZ: separate property eligibility from loan approval

It can be hard to tell whether your visa lets you buy a home and whether a lender will support the purchase. Treat them as two separate questions. First, establish whether you’re eligible to buy the property. Then consider how a lender may assess your finances and circumstances for a home loan for visa holders nz.

Property-purchase eligibility is your legal ability to buy a particular property in New Zealand; loan approval is a lender’s decision about whether your finances can support the borrowing. Meeting one test doesn’t automatically mean you’ll meet the other.

Can visa holders buy residential property in New Zealand?

There isn’t one answer for every visa holder. Eligibility can depend on your visa category, residence history, citizenship, who you’re buying with and the property involved. New Zealand’s overseas investment rules restrict some purchases of residential land. The Overseas Investment Amendment Act 2018 provides background on changes to those rules, but your own circumstances matter.

For example, a residence class visa holder may need consent from the Overseas Investment Office (OIO), the government body that considers certain property purchases, if they haven’t yet met the “ordinarily resident” test. This generally means holding a residence class visa, living in New Zealand for the previous 12 months and being physically present here for at least 183 days during that period. OIO consent is official permission to buy or build a home in cases where the rules require it.

Temporary visa holders are generally restricted from buying a home to live in on their own, but some situations, including buying jointly with an eligible partner, can be treated differently. Australian and Singaporean citizens also have specific exemptions. Check current OIO guidance before making decisions, as eligibility depends on your circumstances.

Why property eligibility does not guarantee a home loan

Even if you’re allowed to buy, a lender makes a separate assessment of whether the loan appears affordable and suitable. It may consider your income and how steady it is, your existing debts, the size and source of your deposit, and the property you plan to buy. Your visa conditions may also affect how a lender views your circumstances. Policies differ, so one lender’s response may not predict another’s.

Keeping the two decisions separate can make the process feel more manageable. A lender’s decision isn’t a verdict on your future, and a decline from one mainstream bank doesn’t necessarily close every pathway. Review what the lender has assessed, identify any details that need explaining, and consider whether another lender’s criteria may fit your circumstances. Property eligibility and borrowing are connected, but each needs its own clear assessment.

What lenders may assess when a visa holder applies for a home loan

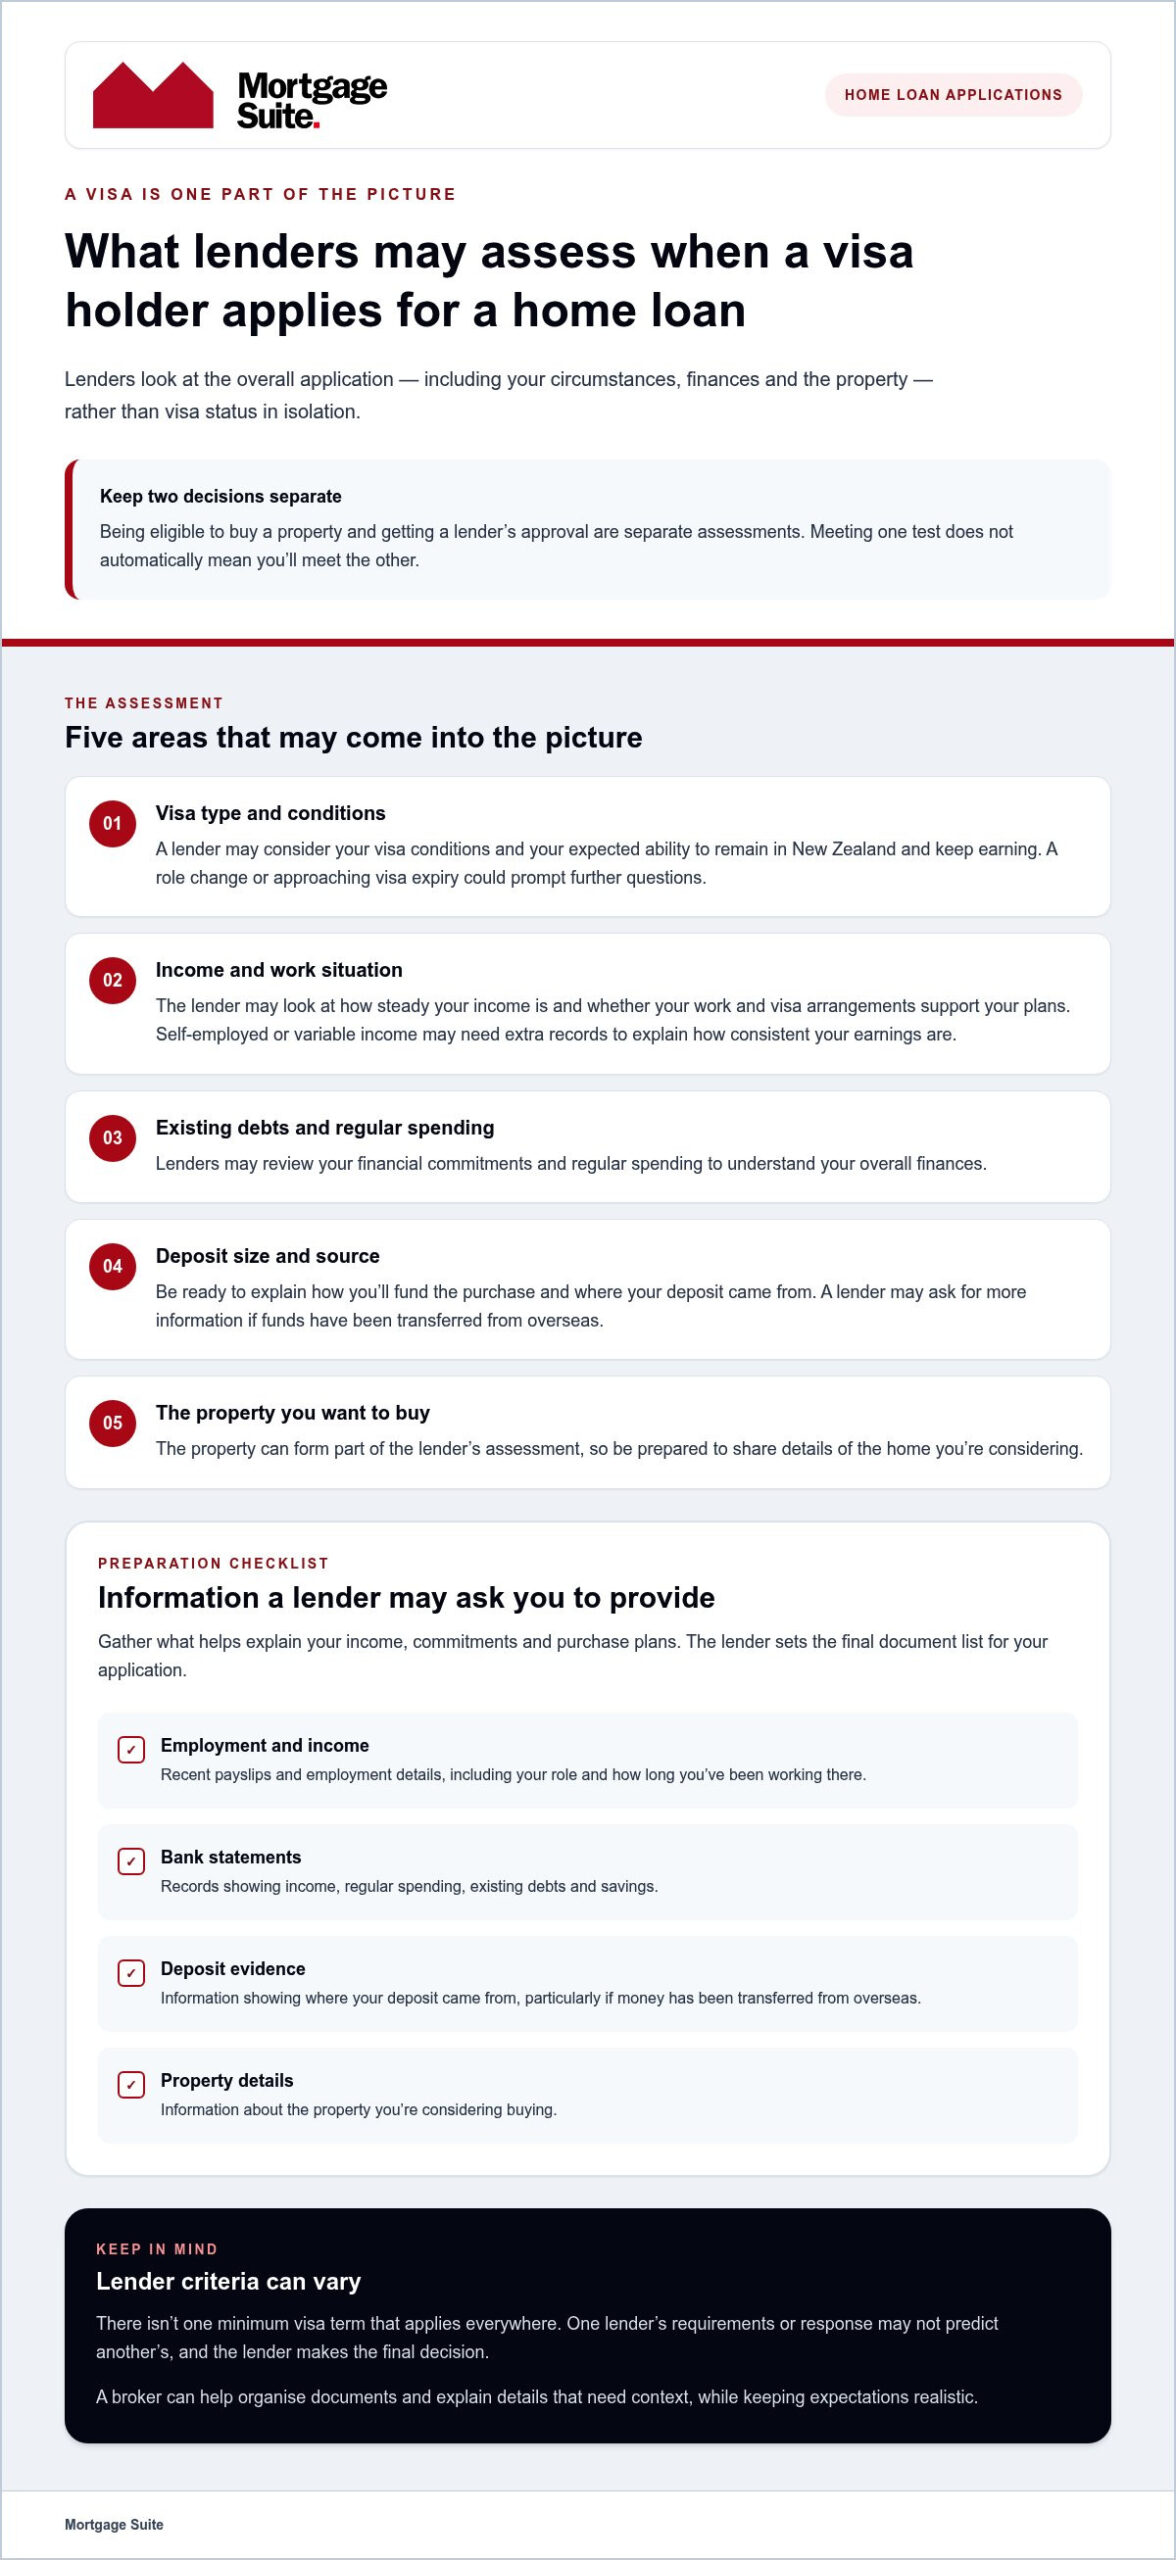
Your visa is one part of the picture, not the whole application. A lender assesses the overall application, not visa status in isolation. It may consider your visa type and conditions alongside your income, work situation, debts, deposit and the property you want to buy. Each lender sets its own criteria, so a requirement applied by one lender shouldn’t be treated as a universal rule.

This is why an application for a home loan for visa holders nz may need a clear explanation of your circumstances. A lender may want to understand how steady your income is and whether your work and visa arrangements support your plans. Questions are part of assessing the application as a whole and don’t automatically mean there’s a problem.

How visa type and remaining visa term may affect an application

Lenders may look at your visa conditions and expected ability to remain in New Zealand and keep earning. Work conditions, a role change or an approaching expiry could prompt further questions, but lender policies differ. Don’t assume there’s one minimum visa term that applies everywhere. The relevant lender’s current criteria determine what it will consider in your situation.

The same applies to named loan pathways. Kāinga Ora’s First Home Loan scheme has its own eligibility criteria, so check the current details rather than assuming a visa alone determines whether you qualify.

Income, deposit and financial records lenders may review

A lender needs a clear view of the money coming in, the commitments going out and how you’ll fund the purchase. Depending on your circumstances and the lender, you may be asked for records such as:

  • Recent payslips and details of your employment, including your role and how long you’ve been working there.
  • Bank statements showing income, regular spending, existing debts and savings.
  • Evidence showing where your deposit came from, particularly if funds have been transferred from overseas.
  • Details of the property you’re considering, as the property can form part of the lender’s assessment.

If you’re self-employed or your income varies, the lender may need extra records to understand how consistent your earnings are. Gather the documents that show your income and commitments clearly, but expect the lender to set the final list for your application. You can also explore plain-English mortgage guidance as you get your information together.

Clear information can make it easier for a lender to assess your application on its merits. A broker can help organise the documents and explain details that need context, while keeping expectations realistic: the lender makes the final decision.

Mainstream and alternative home loans for visa holders: how to compare pathways

There isn’t one lender pathway that suits every visa holder. Mainstream and alternative lenders may assess applications differently, and policies can vary within each group. When comparing a home loan for visa holders nz, look at how the lender’s criteria fit your circumstances, as well as the loan’s repayment structure and flexibility. A headline interest rate alone won’t show whether the overall arrangement suits your plans.

The 2nd tier and non-bank home loans guide explains more about alternative lending. This can be a pathway to explore if your circumstances don’t fit a mainstream lender’s criteria, though suitability depends on your application and the terms available.

What to compare Mainstream lender Alternative lender
Criteria and assessment May apply defined policies to visa status, income, deposit and property details. May consider applications that sit outside some mainstream criteria, with its own assessment requirements.
Flexibility Depends on the individual lender’s rules and how your application fits them. May offer a different way to assess some circumstances, but flexibility isn’t the same across all lenders.
Loan fit Compare repayments, structure and conditions against your needs and plans. Review the full loan terms and repayment commitments, not just the initial rate.

When a mainstream lender may be worth considering

A mainstream lender may be worth exploring if your visa, income, deposit and property plans fit its current criteria. That doesn’t guarantee acceptance. Find out how the lender treats your specific visa circumstances, what evidence it needs and whether the repayment arrangement fits your budget over time. Each lender sets its own requirements, so don’t assume one bank’s policy applies to all.

When an alternative lender may be another pathway

If a mainstream lender can’t assess your application under its usual criteria, an alternative lender may be another option to consider. It won’t suit everyone or guarantee approval, so weigh its assessment approach and loan conditions carefully. Mortgage Suite helps explain possible pathways and present more complex circumstances clearly to lenders. If you’d like support comparing options, talk with Mortgage Suite about your goals and situation.

Home loan for visa holders in NZ: your 2026 guide

How to prepare a home loan application as a visa holder

A little preparation can make a home loan conversation clearer and less stressful. Before comparing lenders, bring together the details that explain your visa, finances and property plans. This gives you a practical starting point for a home loan for visa holders nz, while allowing for lenders to request documents specific to your application.

Build a clear picture of your visa and financial position

Start by checking your property-purchase eligibility for your circumstances. Then organise your information so you can explain your situation consistently. A simple summary of your income, regular commitments, deposit source and intended property can help you spot gaps before you apply.

Depending on the lender and application, useful documents may include:

  • Current visa documents and relevant visa conditions.
  • Recent payslips, employment details or other evidence of income.
  • Bank statements showing regular income, expenses, debts and savings.
  • Information or records showing where your deposit funds came from.
  • Details of the property you’re considering, if you’ve chosen one.

If you’re self-employed or your income changes from month to month, gather records that help explain how you earn and how your income varies. Keep names, dates and other personal details consistent across forms and supporting documents. The lender may ask for more or different information, so use this as a starting checklist rather than a fixed list.

Prepare questions and compare lender fit

Use these steps to get sorted before discussing an application:

  • Clarify purchase eligibility. Understand whether your visa and circumstances allow you to buy the property you have in mind.
  • Map your finances. Note your income, work history, regular expenses, existing debts and deposit source.
  • Organise your records. Bring together relevant visa, employment, income and bank documents.
  • Discuss lender options. Ask how a lender may assess your visa and income circumstances, and what information it needs to consider your application.
  • Compare the whole loan. Look at eligibility, repayment structure, flexibility and communication, as well as the interest rate.

Useful questions can help you understand whether a lender may be a fit: Which parts of my visa or income history need explaining? What documents would help clarify them? How do the repayments and conditions match my plans? For plain-English explanations as you prepare, visit Mortgage Suite’s mortgage education resources.

Mortgage Suite can help you organise your information and discuss lender options without treating one lender’s response as the final word. Talk through your home loan options with a team that can present your circumstances clearly and negotiate with lenders.

How Mortgage Suite can help visa holders explore home loan options

Working out which lender may suit your visa and financial circumstances can feel like a lot to manage alone. Mortgage Suite takes a personal approach: we learn about your goals, understand the details of your situation and consider how your application may fit different lender criteria. This gives you a clearer view of possible next steps without treating a particular loan outcome as certain.

A personal advocate when lending criteria feel hard to navigate

Lender feedback can be difficult to interpret, especially if a decision focuses on one part of your application. A broker can help explain what the feedback means, identify information that may need more context and discuss whether another lending pathway could be worth exploring. A decline from one lender isn’t necessarily a final judgement, but it also doesn’t mean another lender will approve your application.

Mortgage Suite’s founder, Krish Krishna, brings more than two decades of banking experience to conversations about borrowing. That experience supports a practical understanding of how lenders assess applications and how a borrower’s circumstances can be presented clearly. It’s guidance and advocacy, not a promise of approval. You can read more about Mortgage Suite’s team and experience.

What to expect from an initial lending conversation

An initial conversation is a chance to explain what you’re hoping to do and get a clearer picture of the information lenders may need. You can talk through your visa conditions, income, deposit, existing commitments and property plans. If some details are still uncertain, say so. A clear, honest picture helps shape a useful discussion about lender options and what may need attention before an application is presented.

Mortgage Suite can help organise the key details, match your circumstances to potential lender criteria and present your application clearly. Where appropriate, the broker can also negotiate with lenders on your behalf. For a home loan for visa holders nz, this support can help you compare possible pathways and understand what each lender is asking for, while leaving the decision with the lender.

You don’t need to have every answer before starting a conversation. If you’d like to talk through your goals and possible next steps, discuss your home loan options with Mortgage Suite. There’s no pressure to have everything sorted first.

Take your next step with a clearer plan

Buying a home with a visa involves two separate questions: whether you’re eligible to purchase, and whether a lender is prepared to approve your borrowing. Once you understand that distinction, you can focus on the details that shape a home loan for visa holders nz, including your visa conditions, income, deposit and the lender’s own criteria.

Mainstream and alternative lending pathways may suit different circumstances, but neither guarantees approval. Preparing clear information and comparing the full loan structure can help you have a more informed conversation about your options.

Mortgage Suite supports borrowers through mainstream and alternative lending applications, with personal advocacy and lender negotiation. Founder Krish Krishna brings over two decades of banking experience to that work, helping you understand lender feedback and present your circumstances clearly.

Talk through your home loan options with Mortgage Suite and explore possible next steps at your pace. Getting started doesn’t have to be daunting.

Frequently Asked Questions

Can I get a home loan in New Zealand on a work visa?

You may be able to apply, but a lender’s decision depends on your circumstances and its current criteria. A work visa doesn’t automatically mean you can buy a home independently, so check purchase eligibility separately before making plans. Lenders may consider your visa conditions, income, employment history, deposit and other commitments. For a home loan for visa holders nz, both property rules and borrowing requirements need to be considered.

Can temporary visa holders buy a house in New Zealand?

Temporary visa holders are generally restricted from buying a home to live in on their own, but individual circumstances can affect the rules. For example, a temporary visa holder may be able to buy jointly with an eligible New Zealand partner if the property is treated as shared under relationship-property rules. This means it falls within the property-sharing rules for couples. Check current Overseas Investment Office guidance before entering a purchase agreement or assuming an exception applies.

Does a residence-class visa guarantee home loan approval?

No. A residence-class visa may affect whether you’re eligible to purchase, but it doesn’t require a lender to approve a mortgage. The lender will separately assess your income, debts, deposit, ability to manage repayments and the property. Some residence visa holders may also need Overseas Investment Office consent, depending on their circumstances. Confirm purchase eligibility and borrowing requirements as separate steps before committing to a property.

What documents might a visa holder need for a home loan application?

Possible documents include current visa details, payslips, employment information, bank statements and evidence showing where your deposit came from. If you’re self-employed or your income varies, a lender may ask for additional records to understand your earnings. You may also need to provide details of the property you’re considering. The exact documents depend on the lender and your application, so treat this as a starting list, not a universal requirement.

Do all New Zealand lenders assess visa holders in the same way?

No. Lenders set their own criteria, and they may differ in how they consider visa conditions, income, employment history, deposit and property details. One lender’s decision doesn’t necessarily tell you how another will assess your application. Compare more than the interest rate: consider eligibility, repayment structure, flexibility and the information each lender needs. A broker can help explain lender feedback and present your circumstances clearly.

Can I apply for a home loan if a bank has declined my application?

Yes, a decline from one bank doesn’t automatically rule out every other lending option. First, understand the reasons for the decision and whether anything in your application needs clarification or improvement. Lenders assess applications differently, and an alternative lender may consider circumstances outside some mainstream criteria. That isn’t a promise of approval or a suitable route for everyone, but a tailored review can help you understand possible next steps.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Hidden Costs of Buying a House in NZ: Your 2026 Guide

Saving your deposit is often the straightforward part of purchasing property; the real surprise tends to arrive in the final weeks before settlement. Many Kiwis focus entirely on the purchase price, only to feel caught off guard by the hidden costs of buying a house nz that surface during due diligence and contract reviews.

It’s completely natural to worry about running out of cash reserves right when you need them most, especially when you’re trying to decipher legal jargon, council files, and strict lender conditions. You deserve a fair go and total clarity before signing an agreement. In this guide, you will discover every unexpected fee, professional inspection charge, and council cost involved across the buying journey, along with practical ways a dedicated mortgage adviser protects your hard-earned funds.

Here is your clear breakdown of upfront, settlement, and ongoing expenses so you can budget an adequate safety buffer and get sorted with confidence.

Key Takeaways

  • Discover why saving your deposit is only the first hurdle, and how budgeting for upfront checks like a building report prevents costly physical surprises.
  • Get clear on the hidden costs of buying a house nz, from council LIM applications to legal administration, so you can make an offer with total confidence.
  • Understand how lender serviceability stress tests and Loan-to-Value restrictions can trigger specific conditions, including independent property valuations.
  • Prepare for settlement day apportionments so you have the cash reserves ready to reimburse the vendor for prepaid council rates and operational fees.
  • Learn how establishing an equity safety net and working alongside an accredited Financial Advice Provider keeps your finances protected from the start.

What Are the Hidden Costs of Buying a House in New Zealand?

Hidden purchase expenses are the compulsory third-party professional and administrative charges that surface throughout your property transaction. When buyers secure finance, it’s easy to assume the accumulated deposit covers every requirement. In reality, lenders expect your deposit to remain reserved purely for property equity. This means every auxiliary specialist must be funded from separate savings. Getting a clear view of the hidden costs of buying a house nz ensures your transaction proceeds smoothly from your initial offer through to key handover.

Why Your Purchase Deposit Is Only the Starting Point

Mainstream lending covers the physical asset, not the trail of specialists needed to confirm the purchase. If you commit every available cent toward your down payment, you risk a cash shortfall right when legal documents require execution. You need an unencumbered cash buffer to protect your borrowing position and satisfy standard loan conditions. Crucially, upfront inspection expenses accumulate even on properties you do not end up buying. Walking away after an unsatisfactory report costs money, but it successfully protects you from taking on costly physical defects.

Categorising Pre-Purchase, Settlement, and Post-Settlement Expenses

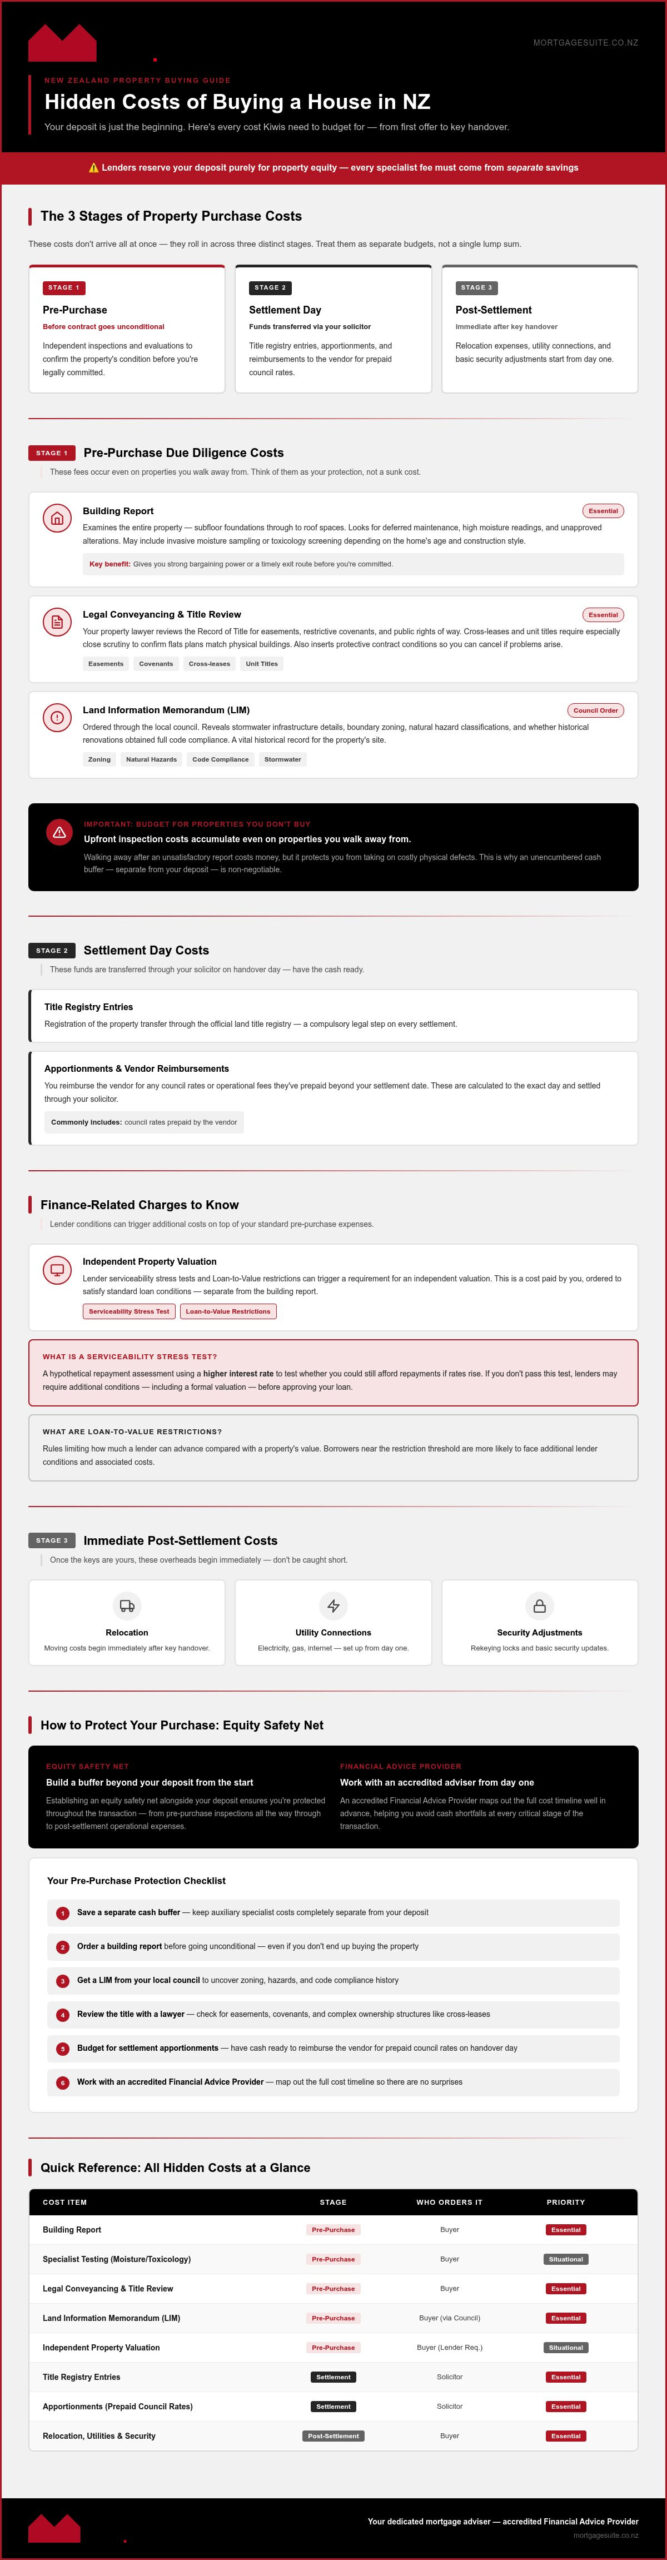
Managing your cash flow becomes much simpler when you divide these overheads into three distinct stages:

  • Pre-purchase verification: These outlays happen before a contract becomes unconditional. They cover independent evaluations such as a building report, council records, and title investigations to confirm the property’s condition.
  • Settlement transactions: Often grouped under the broader umbrella of closing costs, these represent the funds transferred through your solicitor on handover day. They include title registry entries and apportionments, where you reimburse the vendor for prepaid council rates.
  • Immediate operational overheads: Once the keys are yours, standard relocation expenses, utility connections, and basic security adjustments take effect immediately.

A common mistake is treating these stages as a single lump sum rather than a rolling series of invoices. Our team at Mortgage Suite works alongside you to map out this timeline well in advance. Understanding these stages gives Kiwis a fair go at the market, making sure you get sorted without unexpected financial pressure.

Pre-Purchase Due Diligence: Essential Reports and Advisory Fees

Before signing an unconditional sale agreement or bidding under the hammer at an auction, thorough due diligence is non-negotiable. House hunting can become an exhausting process, particularly when you need to investigate several prospective homes before finally securing an offer. These professional evaluations represent necessary hidden costs of buying a house nz, but treating them as an investment in certainty protects you from inheriting expensive structural defects or legal headaches.

Independent Building Report and Specialist Testing

An accredited specialist examines the entire property envelope from subfloor foundations through to roof spaces when completing a building report. Beyond visual checks, inspectors look for deferred maintenance, high moisture readings, and unapproved alterations that could compromise structural integrity. Depending on the construction style and age of the home, targeted testing like invasive moisture sampling or toxicology screenings may also be sensible. Paying for inspections on properties you walk away from feels frustrating, but discovering physical damage early gives you strong bargaining power or a timely exit route.

Legal Conveyancing and Land Title Review

Your property lawyer or conveyancer plays a central role in protecting your legal interests before you commit. They examine the Record of Title to uncover easements, restrictive covenants, and public rights of way that dictate how you can use the section. Complex ownership structures like cross-leases or unit titles demand even closer scrutiny to ensure flats plans match the actual physical buildings. Your legal representative also inserts protective contract conditions around inspection satisfaction, ensuring you retain the power to cancel if unexpected problems arise.

Council Property Files and Land Information Memorandum (LIM)

Ordering a Land Information Memorandum through the local council provides vital historical records regarding storm water infrastructure, boundary zoning, and natural hazard classifications. A LIM also reveals whether historical renovations or additions obtained full code compliance certificates. Unapproved works create friction with mainstream lenders and can lead to costly council enforcement notices. If you are purchasing a subdivided section, your legal team will check that a Statement of Compliance is registered to verify that the developer satisfied every local authority requirement. Taking time to work through the educational resources at Mortgage Suite’s mortgage school helps you understand these legal steps so you can move forward with complete peace of mind.

Securing conditional finance feels like a major victory, yet the lender’s final approval letter often introduces mandatory out-of-pocket requirements. These administrative checks represent another layer of the hidden costs of buying a house nz that can catch buyers off guard. When evaluating an application, banks run a serviceability stress test using elevated interest rates to confirm long-term affordability. Alongside this, strict Loan-to-Value restrictions dictate how lenders assess property risk, often triggering specific condition clauses before they release funds.

Registered Property Valuations Required by Lenders

Council rating valuations exist purely for local taxation and fail to reflect true open-market equity. If you purchase through a private treaty, buy at auction, or apply with a smaller deposit, your lender will likely require an independent registered valuation. Borrowers cannot simply select any valuer from the phone book. Mainstream banks insist on ordering reports via designated independent valuation panels to avoid bias, and the borrower pays the inspection fee directly.

Low Equity Premiums and Lender Assessment Charges

Purchasing with less than a twenty percent deposit introduces additional lending expenses. Lenders offset this higher lending risk by applying a low equity margin or an upfront premium. This charge may be applied as an ongoing interest rate loading or added directly to the total borrowing balance. Complex borrowing scenarios, such as applications with non-standard income structures, can also incur specialised administration fees. Having a dedicated mortgage adviser negotiate these terms helps keep conditional charges manageable.

Alternative Lending and 2nd Tier Finance Solutions

A decline from a traditional bank does not mean your purchasing plans are finished. Specialist non-bank lenders offer practical lending structures for self-employed workers, contractors, and borrowers recovering from past credit blips who deserve a fair go. While non-bank institutions may charge modest establishment fees to accommodate unique situations, they provide immediate access to property ownership. Once you build sufficient equity and trade reliably, your adviser can help you refinance back to a mainstream bank. Reviewing dedicated home loans for first home buyers New Zealand gives you a clear strategy to secure competitive funding without second-guessing your loan setup.

Hidden Costs of Buying a House in NZ: Your 2026 Guide

Settlement Day Realities: Apportionments, Adjustments, and Operational Expenses

Settlement day marks the official transfer of ownership, but it also brings financial reconciliations that many buyers overlook. Alongside the loan drawdown, your legal team receives a settlement statement detailing apportionments. These adjustments ensure the seller is reimbursed for any statutory liabilities paid in advance. When planning your property purchase, factoring in these final reconciliations protects you from unexpected cash demands during the final handover.

Local Council Rates and Water Apportionment Calculations

Local authorities bill property rates on set cycles throughout the year. If the current owner has prepaid rates past your handover date, your conveyancer must credit the difference back to them on settlement day. The same rule applies to regional environmental levies and metered utility accounts. A special water meter reading is taken just prior to completion, ensuring each party pays strictly for their usage up to the exact transfer minute.

Body Corporate Levies and Sinking Fund Adjustments

Purchasing a unit-title property or an apartment introduces additional shared financial commitments. Buyers must take over the vendor’s forward share of operational levies, shared building upkeep, and established sinking funds. Sinking funds represent long-term reserves set aside for major capital improvements across the development. Lenders also scrutinise these spaces closely under the Small Apartment Rule, which assesses smaller floor plans under stricter risk margins. Making sure these shared accounts are fully funded prevents surprise special levies shortly after you collect your keys.

Physical Relocation and Immediate Service Connections

Taking possession of an empty house triggers several immediate operational expenses:

  • Moving logistics: Professional moving vehicles, heavy lifting hire, or short-term storage facilities.
  • Security updates: Changing exterior locks and re-keying doors to ensure complete privacy.
  • Utility provisioning: Telecom fibre setup fees, account connection charges, and trade visits.
  • Immediate maintenance buffer: An emergency fund for plumbing washers, basic cleaning supplies, and minor repairs.

These adjustments form an unavoidable part of the hidden costs of buying a house nz. You can plan ahead and calculate your baseline monthly outlays using our free mortgage calculator to ensure your ongoing budget remains comfortable.

How to Build an Equity Safety Net and Protect Your Purchase

Establishing a resilient equity safety net is the most effective way to absorb unexpected expenses without draining your emergency savings. Rather than committing every spare cent toward a deposit, holding back liquid funds gives you room to breathe. When you account for the hidden costs of buying a house nz early, you can design a borrowing structure that protects your position right through settlement.

Structuring Your Home Loan with an Offset Account

One practical method for keeping reserves accessible is linking your lending with an offset account. Instead of locking all your surplus cash into a standard term loan, an offset facility balances your everyday savings against your mortgage debt. The lender calculates interest purely on the net difference. Keeping your contingency cash parked in an offset account reduces your ongoing interest obligations every single day, while leaving your funds completely accessible if an unexpected repair or council bill arrives. Balancing this with a fixed interest rate on the majority of your lending provides long-term certainty alongside daily flexibility.

Partnering with an Independent Mortgage Adviser

Securing property finance does not have to be a stressful, solitary process. Working alongside an accredited Financial Advice Provider gives you an experienced negotiator who advocates for your interests rather than the bank’s sales targets. A knowledgeable adviser understands where application fees can be waived, how to negotiate cash contributions toward legal bills, and how to present non-standard income profiles to secure competitive approvals. Reviewing the educational articles developed by Mortgage Suite helps clarify the lending journey, while reading client experiences in our reviews illustrates how tailored advocacy protects your finances at every step.

Practical Steps to Finalise Your Buying Strategy

Before you raise your hand at an auction or submit a tender, run a disciplined check over your total commitments:

  • Calculate total upfront cash: Ensure you have separate savings to cover pre-purchase inspections, conveyancing, and council checks before making an offer.
  • Protect your offer: Always instruct your solicitor to insert thorough clauses covering building reports, title checks, and finance confirmation.
  • Plan for settlement day: Retain liquid funds to settle vendor apportionments for local rates and utilities without stress.

Get sorted with Mortgage Suite to structure a personalised loan solution that protects your cash flow and puts you in control of your property purchase.

Step Confidently into Your Next Property Purchase

Managing the hidden costs of buying a house nz comes down to early preparation and smart financial structuring. When you budget for pre-purchase inspections, factor in settlement day apportionments, and preserve an unencumbered cash buffer, you remove the stress of unexpected shortfalls. Purchasing a home is a major milestone, and having clear visibility over every outlay keeps you in control.

You don’t need to tackle strict lender policies alone. Backed by over 20 years of hands-on banking and negotiation experience across New Zealand, Mortgage Suite acts as your personal advocate through each stage of loan structuring. With direct access to both mainstream banks and accredited 2nd tier non-bank lenders, we ensure every buyer gets a fair go, even when borrowing circumstances are complex.

Get in touch with Mortgage Suite to discuss your home loan options and get sorted. With genuine guidance and the right lending structure behind you, taking your next step onto the property ladder becomes an exciting, confident reality.

Frequently Asked Questions

What are the most overlooked hidden costs when purchasing a house in New Zealand?

The most overlooked expenses are pre-purchase reports on properties you don’t buy, council rates apportionments, and bank panel valuations. Many buyers expect their deposit to cover everything, but third-party outlays must be paid in cash before settlement. These represent classic examples of the hidden costs of buying a house nz, along with conveyancing disbursements, moving services, and immediate utility connection fees that arise right around move-in day.

Can hidden buying costs be included directly in my home loan balance?

No, lenders generally do not allow you to roll upfront due diligence or administrative charges into your mortgage borrowing. Banks require your deposit to serve strictly as security equity against the purchase price. Expenses like building inspections, council LIM requests, and legal representation must come from unencumbered personal savings, which is why preserving an independent cash buffer is so vital throughout the purchasing process.

Why do lenders require a registered valuation when buying a property?

Lenders demand an independent registered valuation to verify the property’s true market equity before issuing unconditional finance approval. This requirement usually happens if you’re buying with a low deposit, purchasing through a private treaty, or acquiring an unconventional home. Lenders rely on their approved panel valuers rather than standard council ratings to ensure the purchase price aligns with current market risks and prudent lending margins.

What happens if a building report uncovers major unconsented work before settlement?

Uncovering unconsented work gives you legal options to negotiate repairs, request a price reduction, or exit the deal if your contract includes an inspection condition. Your solicitor reviews the findings against council files to determine liability. Lenders may also withhold final finance if unapproved structural changes pose a security risk, allowing you to walk away safely before your agreement turns unconditional.

How do local council rates get adjusted between the buyer and the seller?

Council rates are apportioned on settlement day based on the exact date legal ownership changes hands. The vendor pays rates up to the handover day, and the buyer reimburses them for any days already prepaid beyond that point. Your conveyancer calculates these daily apportionments on the settlement statement, requiring you to have clear funds ready to complete the balance handover smoothly.

What financial options exist if a mainstream bank declines my home loan application?

A mainstream bank decline is not the end of your property ownership journey, as 2nd tier non-bank lenders offer practical alternative pathways. These specialised financial institutions assess unique circumstances, such as contractor roles or non-traditional earnings, with greater flexibility. An experienced adviser can match your profile with an accredited alternative lender, providing finance now while helping you build a clear strategy to refinance later.

How does working with a mortgage adviser help manage unexpected purchase expenses?

A mortgage adviser reviews your complete financial picture to identify the hidden costs of buying a house nz well before you make an offer. By negotiating lender fee waivers, structuring flexible offset accounts, and securing bank cash contributions toward your legal expenses, your adviser helps keep out-of-pocket costs down. This personal advocacy ensures you navigate complex lender conditions without facing unexpected cash shortfalls.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.