Compare NZ Second-Tier Mortgage Lenders in 2026

A mainstream bank’s decline is a setback, not a verdict on your ability to borrow. If you’re weighing up second tier mortgage lenders nz, it’s natural to feel unsure about what comes next, especially when lenders assess applications differently.

You may still have options. Second-tier lenders are non-bank lenders that can assess some applications differently from mainstream banks. That doesn’t mean every lender will suit your circumstances or approve a loan. A second-tier lender is also different from a second mortgage, which is a separate loan secured behind a first mortgage.

This guide explains how second-tier lending works in New Zealand and what to compare, including lender fit, loan terms, flexibility and your longer-term plans. It also covers what to organise before exploring options. Mortgage Suite helps borrowers compare possible lending pathways and negotiate with lenders, taking their circumstances and goals into account. A bank decline can make the road feel uncertain, but you deserve a fair go and a clear picture of what may be possible.

Key Takeaways

  • A bank decline doesn’t define your options. Your income, commitments, property and plans can all affect which lending pathways may fit.
  • When comparing second tier mortgage lenders nz, weigh lender fit, loan structure, repayment expectations, conditions and future flexibility alongside the interest rate.
  • Clarify your goal and organise a straightforward summary of your finances and property details before exploring a loan.
  • If anything has changed since a bank decision, explain what’s different so lenders can consider your current circumstances.
  • Mortgage Suite helps you compare possible lender pathways and negotiate with bank and private lenders on your behalf.

What are second-tier mortgage lenders in NZ, and when might they fit?

A bank decline or a complex application can leave you wondering where to turn next. It’s a stressful position, but a lender’s decision isn’t a personal judgement on you. It reflects how that lender assessed your application against its criteria at the time.

Exploring another lending pathway can help you understand what may be considered. It doesn’t mean you have to accept a loan, and it doesn’t guarantee another lender will approve your application. Look at your circumstances and the terms on offer before deciding whether a pathway feels workable.

What does “second-tier mortgage lender” mean in New Zealand?

“Second-tier” is a common, informal label for lenders outside the mainstream banks. It often refers to non-bank lenders, which provide lending outside the traditional bank model. For a plain-English overview of how these organisations can differ, see this explanation of non-bank financial institutions.

The label doesn’t describe one standard loan or a single set of rules. Lenders set their own criteria and may assess income, existing commitments, property type and the purpose of borrowing differently. One lender may consider an application that another views differently. So, “second-tier” shouldn’t be taken to mean that rules are always looser or that an offer will necessarily suit you.

When might borrowers explore an alternative lender?

You might explore second tier mortgage lenders nz if your application doesn’t fit a mainstream bank’s usual criteria. Perhaps your income is harder to assess, your circumstances are more complex than a standard application, or the property you want to borrow against is considered non-standard. These are reasons to explore what different lenders may consider, not signs that an application will qualify.

It can help to understand what led to the bank’s decision. Was it the way your income was assessed, the property, the amount you wanted to borrow or another part of the application? Pinpointing the concern gives you a clearer starting point for discussing alternatives and working out what information could help explain your situation.

Take it one step at a time. Exploring an option is a chance to find out whether a different lender’s approach might fit your circumstances and plans. Before accepting an offer, make sure you understand its conditions, repayment expectations and how it fits your longer-term goals. Approval is never assured, and a decline doesn’t mean every other pathway is closed. A careful comparison can help you decide whether there’s a sensible next step.

How do second-tier mortgage lenders assess a borrower’s situation?

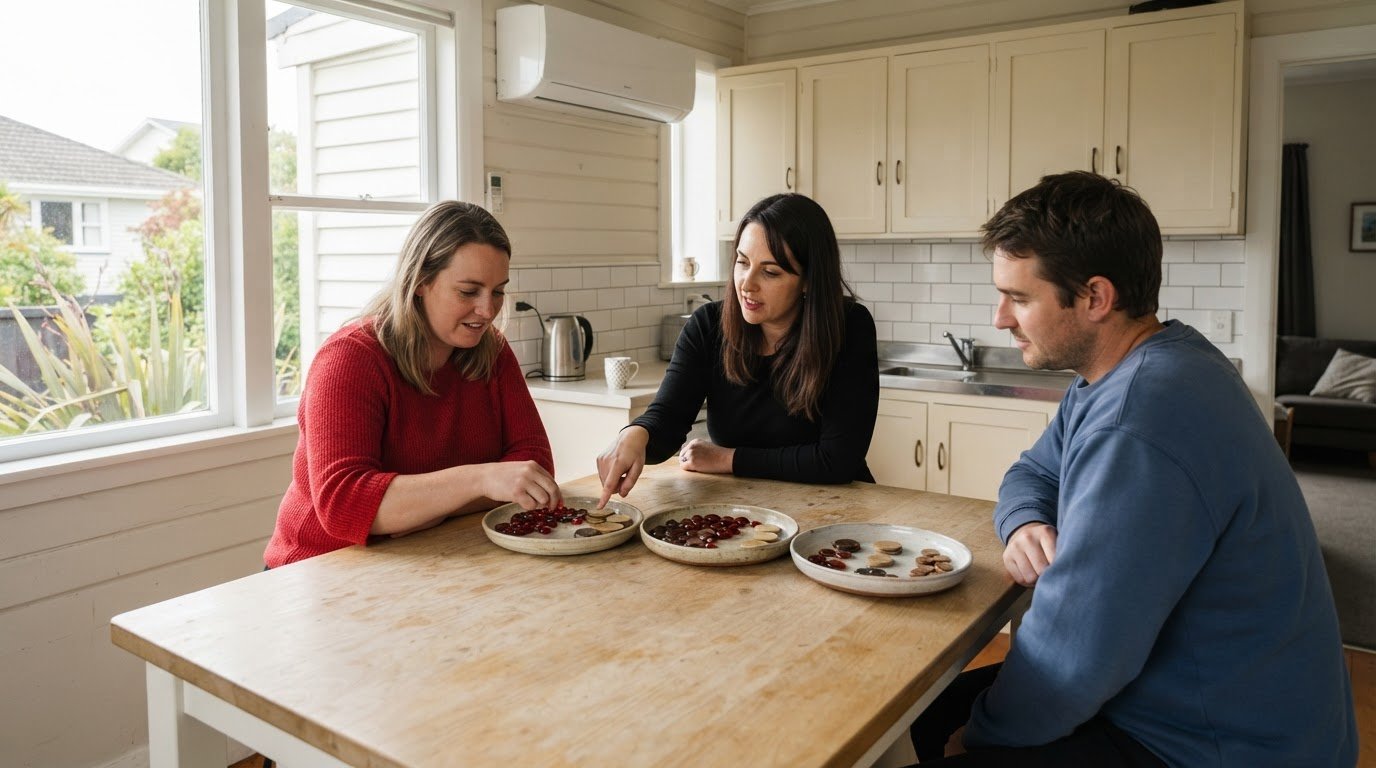
A lender’s decision usually reflects the whole application, not just one detail. To prepare for a lending conversation, organise the information around these five areas:

  • Income: How money comes in and whether it stays steady or varies over time.
  • Existing commitments: Repayments and other regular financial obligations that affect what you can manage.
  • Credit history: Information about past borrowing and repayments, considered alongside the rest of your application.
  • Property and security: The property connected with the loan and details that may affect how a lender views it.
  • Your plans: What you want the loan to achieve and how the proposed structure fits your next steps.

Non-bank lenders don’t all use the same approach. One may focus on a different part of your circumstances than another, so a factor that matters to one lender may carry less weight with the next. A clear explanation can make your application easier to understand, especially if your income or property situation doesn’t follow a straightforward pattern.

How income, commitments and credit history shape the picture

Income helps a lender understand the money available to meet repayments. If your earnings vary, explain why and what you expect ahead. Existing repayments matter too, because they form part of the broader picture of what you’re already committed to paying.

Your credit history can describe previous borrowing, but it isn’t a complete judgement of who you are or what you can manage now. The Credit Contracts and Consumer Finance Act is part of New Zealand’s consumer credit framework. For your application, focus on giving an accurate account of your current circumstances and any relevant changes.

Why property security and loan structure can matter

Security means the property connected with a loan. For example, if you borrow against a home, that home is the security for the lending. Property type and condition may affect whether it fits a lender’s criteria. A standard home and an unusual property may be viewed differently, depending on the lender and the details.

The requested structure matters too. A loan arranged for one purpose may have different repayment expectations or conditions from a loan arranged for another. Be ready to explain what you need the funds for, how you expect to manage repayments and whether your plans may change. Mortgage School lending guides can help make common mortgage terms easier to follow.

Lender fit depends on how income, commitments, credit history, property and plans work together, not on one factor alone. Comparing second tier mortgage lenders nz means looking at the full application rather than assuming one detail will decide the outcome. A clear summary of your situation can make the comparison more focused.

How can you compare second-tier mortgage lenders beyond the headline rate?

A loan can look appealing at first glance and still be a poor fit for your plans. Compare the written offer as a whole: what the lender is willing to consider, how repayments work and what conditions apply. The interest rate matters, but it’s only one part of the arrangement.

Use the same questions for each option. That makes it easier to compare second tier mortgage lenders nz without assuming one headline feature tells the full story.

What to compare What to understand
Lender fit Does the lender’s assessment take account of your circumstances, property and reason for borrowing?
Loan structure How is the lending arranged, and does that structure suit the purpose of the loan?
Repayment expectations How often are repayments due, and what does the offer say about meeting them over time?
Conditions What requirements or limits are set out in the written offer?
Future flexibility How well could the arrangement fit if your income, property or plans change?

Which loan terms deserve a close read?

Read the stated purpose, repayment structure, loan term and conditions together. Check that you understand how repayments are expected to work and what the offer requires of you. The interest rate describes one part of the lending, not whether the structure suits your needs. Get any unclear terms explained before making a decision.

Compare the written terms, not just a short summary or a single headline. Two offers can differ in structure and conditions even if they appear to serve a similar purpose. Mortgage School’s lending guides can help you get familiar with common mortgage language as you review an offer.

How should a possible bank Refinance fit into the decision?

Refinance means replacing or restructuring existing lending, often with a different deal or lender. You may have a future bank option in mind, but treat it as a possibility to review, not a promised outcome. A bank’s decision later will depend on your circumstances and its criteria at that time.

Consider what might need to change for that pathway to be worth revisiting, such as a shift in your income, commitments or plans. Make sure the immediate loan is workable on its own, rather than relying on a future move that may not be available. Compare each offer with your current needs and longer-term direction. A careful read now can help you make an informed choice without assuming what a lender will decide later.
Compare NZ Second-Tier Mortgage Lenders in 2026

What should you prepare before exploring a second-tier mortgage?

A clear starting point can make a lending conversation easier to follow. You don’t need every answer before exploring an option. Start by setting out what you need, what your circumstances look like and what you want to understand before making a decision.

  1. Clarify your goal. Explain what you want the lending to help you do, such as buying a home or changing an existing loan.
  2. Summarise your circumstances. Describe your income, regular commitments and any details that may affect how your situation is understood.
  3. Organise property information. Note which property is involved and any relevant features that could shape the lending discussion.
  4. Write down your questions. Keep track of anything you want clarified about the proposed structure, repayments or conditions.

If a bank has already considered your application, explain what has changed since that decision, if anything. This might be a change in your income, commitments, property plans or available information. Keep the explanation factual and calm. The aim is to help a lender understand your current position, not to criticise the bank’s decision or assume another lender will reach a different one.

How to make your circumstances clear

Use plain language to describe how you earn income, what you already pay regularly and which property is connected with the request. If your income varies or your circumstances have shifted, explain what is different and why. There isn’t one document list that applies to every application, so start with a clear, accurate summary that helps someone follow your situation.

Questions to ask before choosing a pathway

Before deciding, ask how the proposed loan structure fits your plans and repayment capacity. Make sure you understand the written conditions, what you’re expected to do and what might affect a future change of lender. If you’re weighing up second tier mortgage lenders nz, Mortgage School’s mortgage guidance can help make unfamiliar terms easier to discuss and compare.

Keep the next step proportionate. You can first find out what pathway may be considered and what its terms involve, without treating that conversation as a commitment to accept a loan. A possible future Refinance is something to review if your circumstances change, not an outcome to rely on. Take time to understand the written offer and how it fits your plans before deciding.

Mortgage Suite can help you think through your borrowing goal and the questions you want answered, so you can approach the next conversation with a clearer sense of direction.

How Mortgage Suite helps you explore second-tier mortgage lenders in NZ

A bank decline can leave you with more questions than answers. Mortgage Suite helps borrowers across New Zealand explore Non-Bank Lending and compare possible pathways when a standard bank approach doesn’t fit their circumstances. The aim is to make the options clearer, not to rush you towards a decision.

Mortgage Suite can access a variety of bank and private lenders and negotiate on your behalf. Your borrowing goal, financial situation and property details can be presented to help a lender understand the full picture. Each lender makes its own assessment, and exploring an option is not a promise of approval.

A personal advocate when a standard bank path does not fit

Finding a suitable lender is about more than sending the same application everywhere. Mortgage Suite considers how your circumstances fit different lender criteria, then helps explain parts of your application that may need context. If your income varies or a property is less conventional, a clear explanation can help the lender understand what you’re asking for and why.

Founder and director Krish Krishna started Mortgage Suite in 2000 after 18 years in banking. That background informs the business’s practical approach to lender conversations and negotiation. Mortgage Suite reports arranging over a billion NZD in residential, commercial and business loans, with experience across different borrowing needs. This history supports informed guidance, but it can’t guarantee that a lender will approve a particular application.

If you’re comparing second tier mortgage lenders nz, Mortgage Suite can help you look beyond the initial response and consider which lender pathway may fit your situation. The focus is on clear information, tailored support and understanding the terms before you decide what to do next.

A clear next step for borrowers weighing up alternatives

Start with a straightforward conversation about what you want the lending to achieve and what has made the standard route difficult. Explain what has changed since a bank decision, if anything, and raise the questions that matter to you. From there, the discussion can focus on possible pathways, how lenders may view your circumstances and whether an option appears to fit your plans. There’s no guarantee of approval, and you remain in control of whether to proceed.

Krish Krishna’s banking background and Mortgage Suite’s approach to supporting borrowers are outlined on the About Us page. If you’re ready to talk through your circumstances, get in touch with Mortgage Suite for a considered discussion about possible next steps.

Choose a next step that feels right for you

You don’t have to solve every part of your borrowing plan at once. First, consider what a suitable outcome would mean for you and whether a proposed loan supports that goal without putting pressure on plans that matter later. This gives you a steady point of reference as you weigh your options.

Comparing second tier mortgage lenders nz is a way to explore possible pathways, not a commitment to take one. Give yourself room to understand an offer and decide whether it feels workable. If something doesn’t make sense, pause and get clarity before moving ahead.

If you’d value a sounding board for your next move, explore your lending options with Mortgage Suite. A thoughtful conversation can help you see what may be worth considering, without assuming approval or a particular outcome. Take it one step at a time and move forward with a clearer sense of direction.

Frequently Asked Questions

Is a second-tier mortgage lender a non-bank lender?

Often, the terms refer to similar lending pathways, but the label alone won’t tell you which lender is behind an offer or how a particular loan works. Compare the lender named in the offer and the product details. Describe the same borrowing goal and circumstances for each option, then note where the lenders’ responses differ. That gives you a more useful comparison than relying on the label.

Can I explore a mortgage after a bank has declined my application?

Yes, you can look into whether another application may be worth exploring. Start by reviewing the reason the bank gave for its decision and identifying which information or circumstances were relevant. For example, if the concern related to how your income was presented, prepare a clear explanation of how you earn it. Mortgage Suite can help you consider how to present your circumstances to another lender.

Does a second-tier mortgage automatically mean the loan is unsuitable?

No, the category name alone doesn’t tell you whether a loan fits your situation. Consider how the repayment pattern would work alongside your regular household or business commitments, and whether you could manage it if your circumstances changed. Ask for unfamiliar conditions to be explained in plain language. The aim is to understand the practical effect of the offer before deciding, rather than judging it by its label.

Can self-employed borrowers explore second-tier mortgage lenders in NZ?

Yes, self-employed people can discuss their circumstances with an adviser, though being self-employed doesn’t determine the outcome. A useful starting point is to explain how your work generates income, whether it changes across the year and what affects those changes. This helps frame a conversation about second tier mortgage lenders nz without assuming every lender will assess your income in the same way or ask for the same information.

Can a borrower move from a second-tier loan to a bank later?

It may be possible to apply to a bank later, depending on your circumstances and the bank’s requirements at that time. If this is part of your longer-term thinking, understand what the current loan says about changing or ending the arrangement, and keep your future plans flexible. A later review can take account of what has changed in your income, commitments or property needs, rather than relying on today’s assumptions.

Will applying to a second-tier lender guarantee mortgage approval?

No. Mortgage Suite can help organise and present your application, but only the lender can decide whether to make an offer. The lender may ask for more information, decline the application or propose terms for you to consider. If you’ve already had a decline, you don’t need to treat it as a personal judgement. Focus on understanding the lender’s response and what it means for your choices.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Calculating Home Loan Costs, Interest and Total Repayments

Your repayment depends on more than the amount you borrow. When calculating a home loan, the loan term, repayment frequency, interest rate and repayment structure all affect your regular payments and the total interest you may pay.

It’s natural to want a clear figure before making a major decision, but an estimate is only useful when you understand its assumptions. Changing the repayment frequency or choosing an interest-only period can affect both your regular payments and how quickly you reduce the amount borrowed.

This guide explains how to estimate home loan repayments in New Zealand and what to compare when reviewing mortgage options. Learn how loan size and repayment frequency affect the calculation, how principal-and-interest repayments differ from interest-only payments, and why the lowest regular repayment may not mean the lowest total interest. Understanding these factors helps you build a more realistic picture of borrowing.

Key Takeaways

  • Compare repayment frequencies using the same loan details so you can see how payment timing changes your regular repayments.
  • Look beyond the interest rate: the loan structure and its flexibility can affect how well repayments fit your plans.
  • Use the amount you expect to borrow, rather than the property’s full price, to make your repayment estimate more relevant.
  • Separate regular repayments from total interest to understand the longer-term effect of your loan settings.
  • An interest-only period can reduce repayments for a time, but it doesn’t reduce the amount borrowed during that period.

Choosing repayment frequency

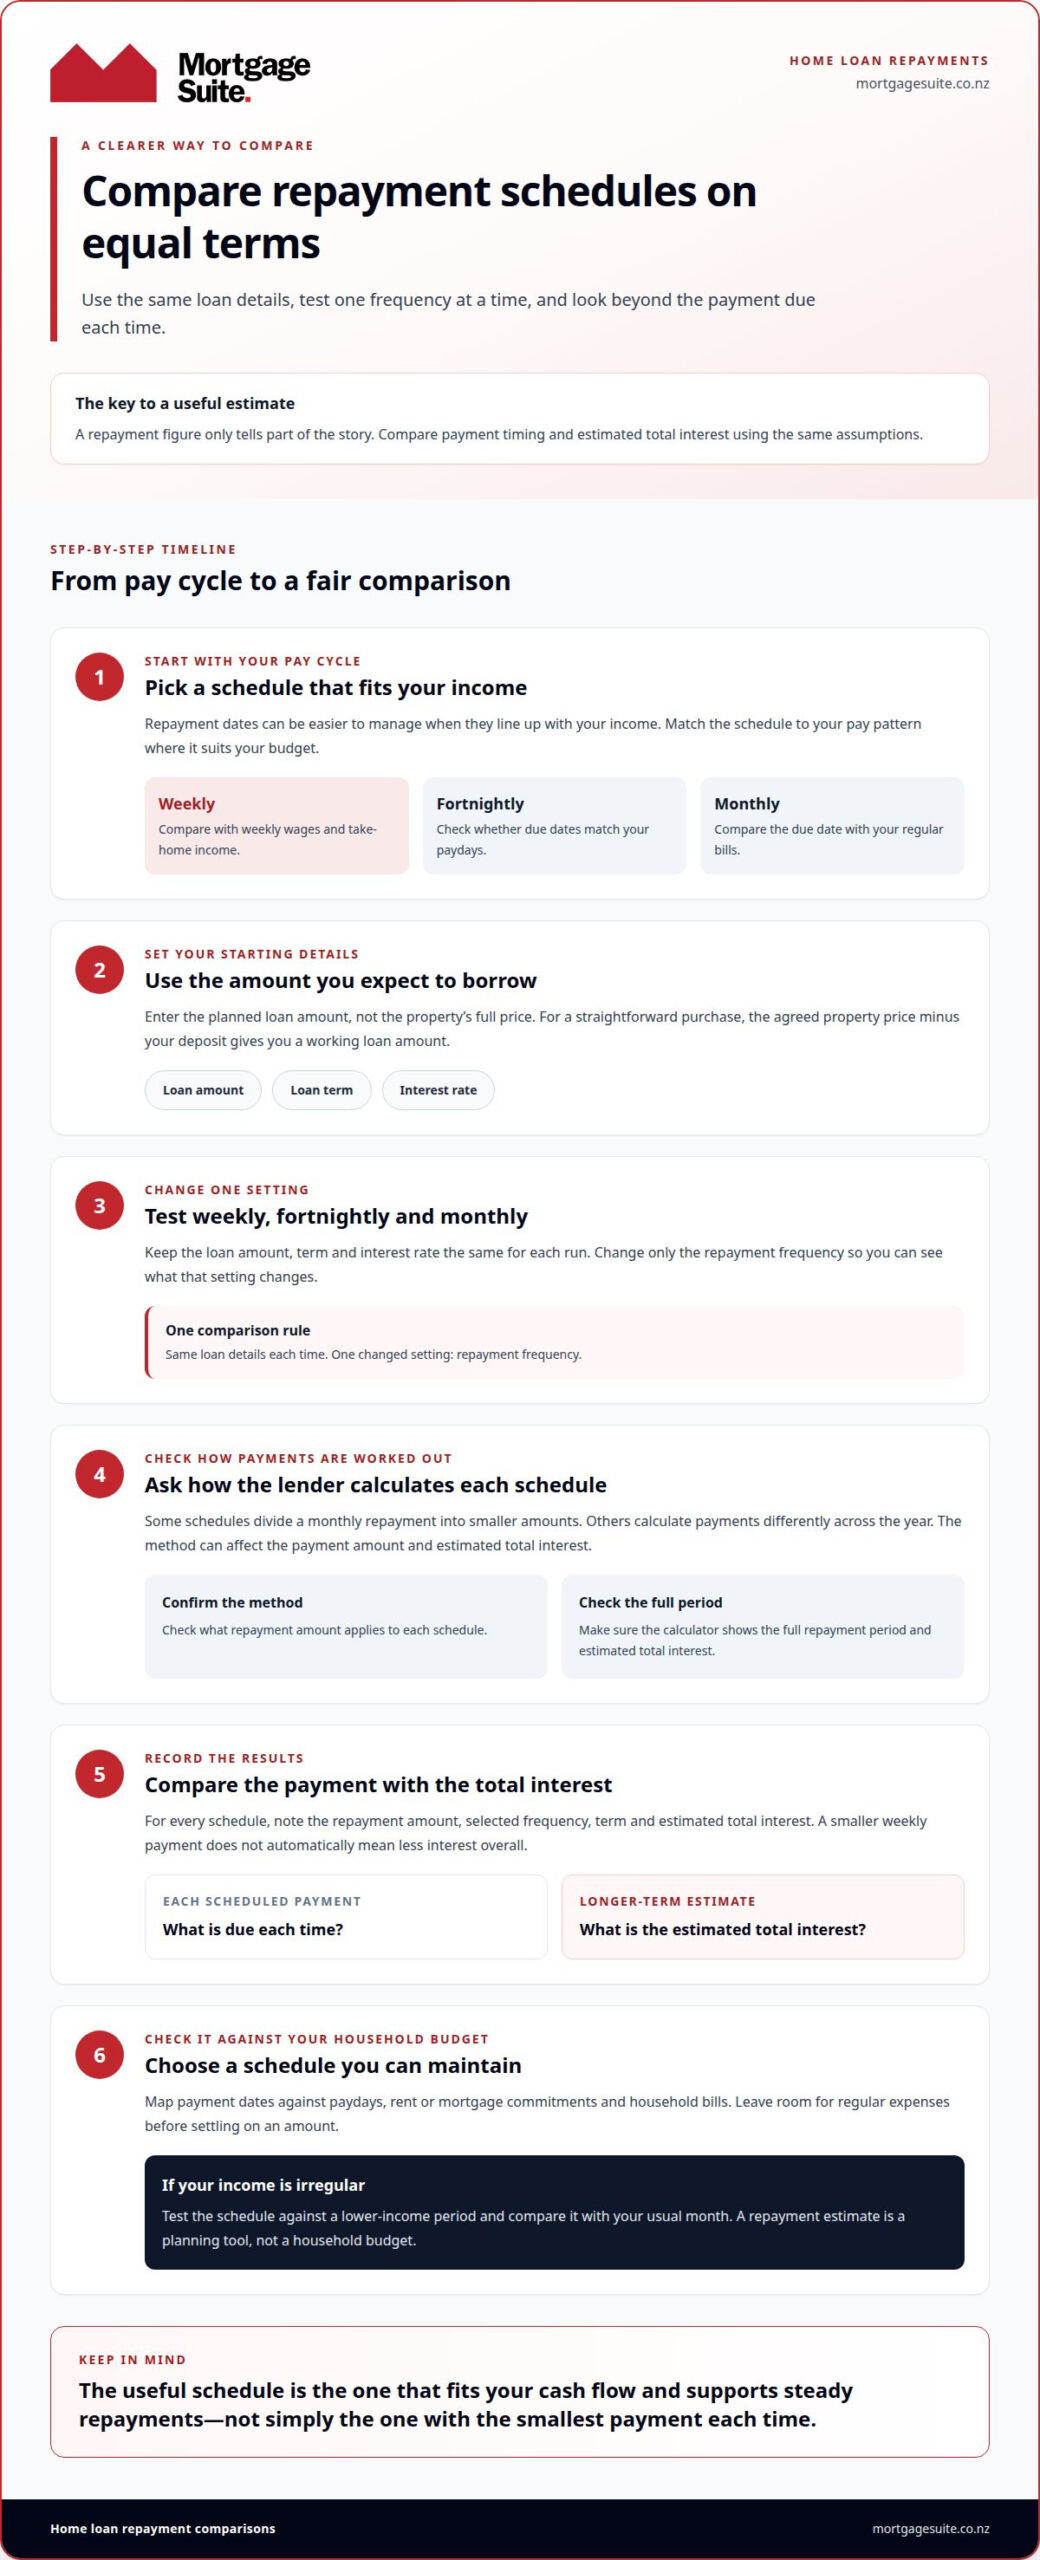
Start with your pay cycle and household budget. Repayment dates are easier to manage when they align with your income. Weekly repayments may suit weekly wages, fortnightly repayments may fit income paid every two weeks, and monthly repayments may suit a monthly salary. Frequency changes the amount due each time and may affect total interest, depending on how the lender calculates repayments. Compare schedules using the same loan amount, interest rate and term so you can see the effect of frequency alone.

Check how the lender calculates more frequent payments. Some schedules divide a monthly repayment into smaller amounts, while others calculate payments differently across the year. Ask what repayment amount applies to each schedule, and check that the calculator shows the full repayment period and estimated total interest. When calculating a home loan, the payment amount alone can be misleading: a smaller weekly payment does not automatically mean less interest overall. Compare the total paid and payment timing using the same loan assumptions.

  • Weekly: compare the payment against weekly take-home income.
  • Fortnightly: check whether payment dates match your paydays.
  • Monthly: compare the due date with regular bills.

For a practical comparison, use the same inputs each time. Enter the loan amount, term and interest rate first. Select weekly, fortnightly or monthly repayments. Record each payment and estimated total interest. A home loan repayment calculator can help you compare those settings. Change only one setting at a time. That makes it easier to identify the effect of frequency. If the figures vary, review the repayment method and assumptions. Keep notes beside each result, including the selected frequency and term.

Your deposit and finance preparation also shape your buying range. In New Zealand, most lenders require first-home buyers to have a deposit of at least 20 % of the amount they are borrowing. Conditional pre-approved finance can help you understand the price range you can buy in. Arrange it with your chosen lender before looking for a property. These steps help you work with a realistic loan amount before comparing repayment schedules. They also connect the estimate to your buying plans, rather than an arbitrary figure.

Finally, choose a frequency you can maintain through changing weeks. Map payment dates against paydays, rent or mortgage commitments, and household bills. Leave room for regular expenses before settling on an amount. If your income arrives irregularly, test the schedule against a lower-income period. Compare that result with your usual month. A repayment estimate is a planning tool, not a household budget. The right frequency is the one that fits your cash flow and supports steady repayments without relying on optimistic assumptions.

Comparing mortgage options

In New Zealand, a fixed interest rate stays unchanged for its agreed period. A floating rate can change when the lender adjusts it, which may affect your repayments or the interest charged. Compare both options using the same loan amount and term.

The rate type affects predictability and flexibility. A fixed rate stays steady during the agreed period, making scheduled repayments easier to plan. When that period ends, a new rate arrangement may change your estimate. A floating rate can move during the loan, so repayments may rise or fall. Check whether the lender changes the repayment amount or keeps it level and adjusts the loan term.

Compare more than the first repayment figure. Use the same loan amount, repayment frequency and term for each option, then note the interest rate, repayment amount and estimated total interest. Update the estimate if the rate changes. This shows how the result responds without treating today’s figure as permanent.

  • Fixed: consider how steady repayments fit your budget.
  • Floating: consider how a changing rate could affect payments.
  • Split: compare each portion separately, then review the combined repayment.

A split loan divides borrowing across different arrangements. For example, one portion could have a fixed rate and another a floating rate. This affects how much of the loan responds to rate changes, and means you need to track separate balances and repayment settings. Enter each portion separately if the calculator allows it, then add the results to estimate your total scheduled repayment. If it cannot model a split, compare each portion separately using consistent assumptions.

An offset account can also affect your comparison. Its balance reduces the loan balance used to calculate interest. For example, while money remains in a linked account, interest may be calculated on a lower balance. The effect depends on the balance and account terms. Compare the same loan with and without the offset, keeping the repayment amount and rate assumptions unchanged, to see how it may affect interest over time.

Use a home loan calculator to test different loan settings. Record each result beside its rate type and repayment assumptions. A lower first repayment doesn’t tell the whole story. Compare payment stability, flexibility and estimated interest together. Then consider which structure suits your income pattern and plans. That gives you a clearer basis for discussing options and choosing a repayment estimate that reflects the loan structure, not just the headline rate.

Entering a loan amount

Most lenders in New Zealand require first home buyers to have a deposit of at least 20 % of the amount they are borrowing. For a repayment estimate, enter the amount you plan to borrow, not the property’s full price.

For a straightforward purchase, start with the agreed property price and subtract your deposit. The result gives you a working loan amount. For example, if your deposit covers part of the purchase, the remaining amount is the starting figure for your estimate. Use the same amount across each calculator comparison. Changing it alongside the interest rate makes it harder to tell which input changed the repayment.

Keep the property value, deposit and borrowing amount distinct in your notes. They represent different parts of the purchase. A calculator’s loan amount field usually asks for the sum you plan to borrow, so check the label before entering a figure. Entering the purchase price instead could make the estimate assume you are borrowing more than intended.

Use this simple sequence before calculating:

  1. Enter the property price you are working with.
  2. Subtract the deposit you expect to contribute.
  3. Enter the remaining borrowing amount in the loan field.
  4. Check the figure and currency shown by the calculator.

Consider what your estimate includes. If you plan to borrow more than the purchase price, include those amounts in the loan figure. Don’t add an item simply because it appears in your wider budget. Include it only if you intend to borrow it, so the repayment estimate reflects your loan assumptions rather than unrelated household spending.

Use New Zealand dollars when entering the amount. A calculator may display a currency symbol or a separate currency label. Check that you have entered the full amount, with no missing digits or misplaced decimal point. Then compare the displayed loan amount with your notes. A quick check can catch a typing error before it changes the repayment estimate.

Try a second estimate with a different loan amount, keeping the rate, term and repayment frequency unchanged. This shows how borrowing size affects the scheduled payment. Record each amount beside its result. If you are still planning your purchase, treat the figures as scenarios, not as a final borrowing decision.

A home loan calculator can help you test these inputs. Start with one clear loan amount, then change one setting at a time. The resulting comparison is easier to understand when each estimate uses a consistent set of assumptions.

Calculating Home Loan Costs, Interest and Total Repayments

Interest and total repayment estimates

A repayment estimate shows a scheduled payment. The total repayment estimate adds those payments across the loan term, while the interest estimate shows the interest within that total. These figures depend on the loan amount, rate, term and repayment frequency. Enter each assumption carefully, then compare the payment, total repaid and estimated interest together.

Use a calculator to estimate repayments from your loan details. Select the repayment frequency, enter the interest rate and set the loan term, then review the payment shown. A home loan calculator can help you test these inputs. Note each setting, and record a new result whenever you change the rate or term so the comparisons are easy to follow.

Keep scheduled loan repayments separate from other financial commitments. Don’t add unrelated expenses to the loan amount unless you intend to borrow them. Use a separate budget for the rest of your home-buying costs.

In New Zealand, banks assess affordability by reviewing income, regular expenses, existing debt and proposed repayments. They may also use a serviceability stress test to check whether repayments remain manageable at a higher interest rate. Your estimate helps with planning, while a bank’s assessment considers your wider financial position.

Extra repayments can reduce the balance sooner and may lower interest over time. A shorter loan term usually increases each scheduled repayment but reduces the time interest can accrue. Compare these changes using the same loan amount and rate, and check your loan’s repayment conditions before planning extra payments.

If interest rates rise, repayments on a floating-rate loan may increase. A fixed rate stays unchanged for its agreed period, so scheduled repayments generally remain steady during that time. When the fixed period ends, a new rate may change the repayment. Test a higher-rate assumption to see how your budget responds.

Compare scenarios instead of relying on one figure. Start with your current assumptions, then test a higher rate, a shorter term and an extra repayment, changing one setting at a time. Record the new payment and estimated total interest for each scenario. This shows which changes affect cash flow most and which may reduce interest most. A lower regular repayment may mean paying for longer; a higher repayment may reduce the balance faster if it fits your budget.

Keep the estimate separate from your household budget. List your income and existing commitments alongside the proposed repayment, including regular bills and debt payments. Check whether the payment leaves room for those commitments. This helps you assess whether the estimate is workable before a full lending assessment.

Interest-only periods

With interest-only repayments, your payments cover interest rather than the loan balance. The principal, meaning the amount borrowed, stays unchanged during that period. So, interest-only payments on a home loan do not reduce the amount you owe.

Interest-only payments may be lower than principal-and-interest repayments on the same balance, rate and term. But that does not mean the loan costs less overall. Interest continues to accrue, and the original balance remains due. Compare the payment with the balance after each repayment to see whether your debt is actually reducing.

To estimate an interest-only repayment, use the outstanding balance and interest rate. A higher balance or rate means more interest to pay. Repayment frequency also affects how often you make payments. When comparing interest-only with principal-and-interest scenarios, use the same balance, rate and frequency.

Pay close attention to what happens when the interest-only period ends. If the loan then switches to principal-and-interest repayments, the remaining balance must be repaid over the remaining loan term, which may increase scheduled payments. The amount depends on the balance, rate and remaining term. Model both stages instead of looking only at the initial payment.

  • During the period: track the balance and interest payments.
  • At the changeover: note the remaining balance and term.
  • Afterward: compare the new repayment with your budget.

For a clear comparison, record the interest-only payment, then estimate principal-and-interest repayments using the same loan amount, rate and repayment frequency. Keep the term assumptions clear, especially for the period after interest-only payments end. A calculator that models only one stage will not show the full repayment path. Estimate each stage separately, then consider their combined effect across the loan.

Interest-only repayments may suit a particular short-term cash-flow need, but they do not reduce the principal. Consider the purpose of the arrangement and what may change later. If your income is expected to change, for example, compare the later repayment with your expected budget. If the balance remains unchanged, plan how you will manage the move to repayments that reduce the debt.

Use a home loan calculator to compare repayment structures and test different rates. Change one input at a time, and save each estimate with its assumptions, including the balance, rate, frequency and remaining term. This makes the differences easier to explain and discuss. If you are weighing interest-only repayments against reducing the principal, compare the scenarios before choosing a structure.

Mortgage Suite Ltd: Home Loans to First Home Buyers

Mortgage Suite Ltd helps first-home buyers explore home loan options and understand how loan structure affects repayments. If your estimates raise questions about borrowing amount, repayment type or lender fit, a conversation can help put those figures into context.

Mortgage Suite Ltd offers Home Loans to First Home Buyers and Residential Investment property loans. It also offers Business Loans and Property Development Loans. If a mainstream bank’s lending criteria don’t fit your circumstances, 2nd Tier Loans may provide another path to consider. That doesn’t mean every application will suit every lender, so it helps to discuss your goals and financial position openly.

Bring your repayment estimates and the assumptions behind them, such as the loan amount, term and repayment frequency. Mortgage Suite Ltd can help you consider suitable lending options and negotiate with lenders on your behalf. To discuss your next step, contact Mortgage Suite Ltd or visit mortgagesuite.co.nz.

Make your next borrowing decision with confidence

A repayment estimate is more useful when it reflects the plans you are working towards. Before deciding what feels manageable, consider how your borrowing needs could change if your household or work circumstances shift. That wider view can help you choose a direction that supports your priorities, not just today’s budget.

Calculating a home loan gives you a starting point for that decision. The next step is matching your plans with the type of lending you need. Home Loans to First Home Buyers, Residential Investment property loans and Business Loans support different borrowing goals. A clear sense of your priorities can make your next conversation more focused.

Ready to take that step? Discuss your options. You can talk through what matters to you and move forward at a pace that feels right.

Frequently Asked Questions

What formula calculates mortgage repayments using the loan amount, interest rate, and term?

For a standard principal-and-interest loan, the periodic repayment formula is M = P × i(1 + i)n ÷ ((1 + i)n − 1). Here, P is the amount borrowed, i is the interest rate per repayment period, and n is the total number of repayments. Convert the annual rate to the relevant period and match n to your chosen schedule.

How do you calculate total interest and total cost over a home loan term?

Add the scheduled repayments across the loan term to estimate the total amount repaid. Subtract the original amount borrowed to estimate the interest, assuming the rate and repayment schedule stay unchanged. For example, if a calculator shows total repayments and the starting loan amount, subtract the loan amount from the total. If repayments or rates change, add the payments for each period instead.

What New Zealand mortgage calculators can estimate repayments and borrowing power?

A home loan repayment calculator can compare repayments using the loan amount, rate, term and repayment frequency. Conditional pre-approved finance from your chosen lender can help you understand your buying range before looking for a property.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to work out whether you need a deposit for a business loan in NZ

A deposit isn’t the only way to support a business loan application. If you’re asking, “Do I need a deposit for a business loan in NZ?”, there’s no single deposit amount for every loan. Lenders assess your contribution alongside cash flow, credit history, business records, plans and available security. These factors can also influence the interest rate, and startup loans may have higher rates than loans to established businesses.

It’s understandable to worry that limited cash upfront could rule out borrowing. Start by clarifying what the loan will fund, how repayments would fit your cash flow, and whether assets could support the application as security. This guide explains how deposits, affordability, records, business plans, credit history and security fit together, so you can assess your position and prepare a clearer application.

Key Takeaways

  • Work out how much cash your business can contribute, then consider how security and the loan purpose may affect the lender’s assessment.
  • Map expected income and expenses in a cash flow forecast to see whether repayments fit alongside day-to-day operating needs.
  • Prepare clear financial records and a practical business plan to explain how the business will earn revenue and repay the loan.
  • Review your personal credit history and address any issues you can before applying; there’s no fixed credit score cutoff for a New Zealand startup loan.
  • Compare the interest and repayment terms with the loan’s purpose, so borrowing supports planned growth or a short-term cash need.

Cash flow forecasts and repayment affordability

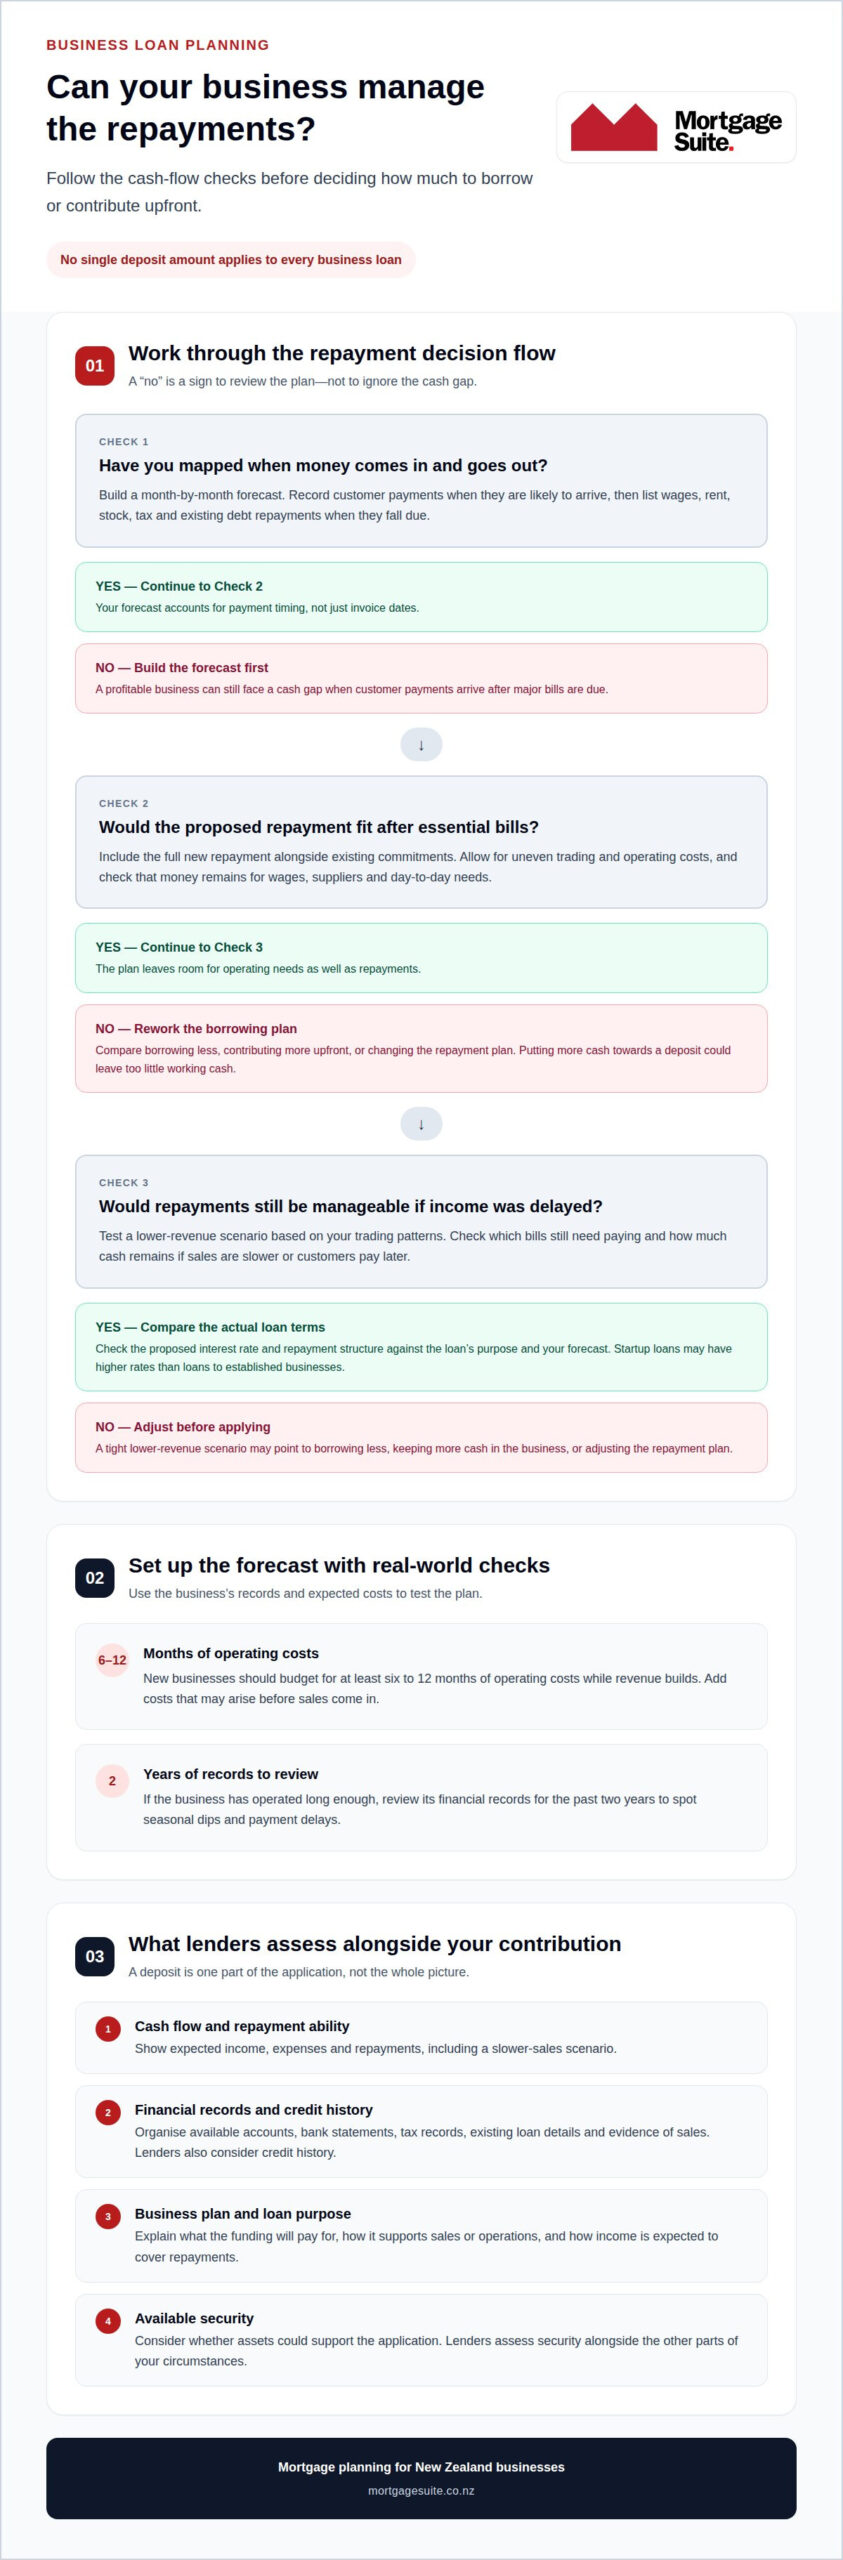
  1. Build a month-by-month cash flow forecast before deciding how much to borrow or contribute upfront. List expected customer payments in the months they’re likely to arrive, not simply when you issue invoices. Then record regular outgoings, such as wages, rent, stock, tax and existing debt repayments. This shows when cash is available for a new repayment and when it may be tight. A profitable business can still face a cash gap if customers pay after major bills fall due, so account for payment timing in every forecast.
  2. Allow for uneven trading and operating costs, particularly if the business is new or seasonal. New businesses should budget for at least six to 12 months of operating costs while revenue builds. Add expected costs that may arise before sales come in, then compare the forecast balance with the repayments you’re considering. If the business needs to retain cash for wages or suppliers, putting more money towards the loan deposit could leave too little working cash. Weigh the benefit of borrowing less against the cash buffer the business needs to keep trading.
  3. Test whether repayments remain manageable if income arrives later than expected. Create a lower-revenue scenario based on your trading patterns, then check which bills still need paying and how much cash remains. Include the full proposed repayment alongside existing commitments, rather than assessing the new loan in isolation. If the business has been operating long enough, review its financial records for the past two years to identify seasonal dips and payment delays. Use those patterns to plan repayments around actual cash flow, not just an optimistic sales forecast.
  4. Compare the interest rate and repayment structure with the loan’s purpose and cash flow. The Reserve Bank of New Zealand reported that the SME new overdraft rate was 10.06% in August 2026. That figure is an overdraft rate, not a quote for every business loan, so use the actual proposed rate and terms in your calculations. Check how repayment timing affects cash available after essential bills. A forecast that leaves little room for a slow month may point to borrowing less, contributing more upfront, or adjusting the repayment plan before applying.

Preparing financial records, a cash flow forecast and a business plan

  1. No single no-deposit business loan applies across New Zealand. Unsecured business loans, which don’t use an asset as security, are often available for amounts under NZ$50,000, but that doesn’t automatically mean no deposit is required. Lenders still assess repayment ability, credit history and the business plan. Prepare for the possibility that limited trading history or weak cash flow could narrow your choices.
  2. Gather your financial records into one clear set before approaching lenders. For an established business, organise recent accounts, bank statements, tax records, existing loan details and evidence of sales. Check that figures match across documents, and explain unusual changes, such as a large one-off expense or a major customer leaving. New businesses may have fewer trading records, so assemble available evidence of startup costs, confirmed orders, supplier quotes and money already invested.
  3. Prepare a cash flow forecast showing when money is expected to enter and leave the business. Separate expected sales from confirmed income, then list regular expenses and loan repayments by date. For example, if customers usually pay after supplier invoices fall due, show that timing instead of treating both amounts as happening together. Create another forecast with slower sales or delayed payments. This helps demonstrate how the business could manage repayments during a tighter period.
  4. Write a business plan that connects the loan amount to a clear purpose and repayment path. Explain what the funding will pay for, how that should support sales or operations, and when the business expects income to cover repayments. Startup loans in New Zealand commonly range from NZ$5,000 to NZ$500,000, depending on the plan and security offered. Use your plan to justify the amount requested, rather than choosing a figure without linking it to specific needs.
  5. If your new business lacks financial data, lending options may be more limited. A personal loan or borrowing more against a mortgage may be alternatives, but weigh the repayment obligation against your personal finances. Compare the loan term, interest and repayment schedule with the business forecast. For an unsecured loan, consider whether the higher rate still fits the plan. Records, a realistic forecast and a focused business plan give lenders a clearer basis for assessing the application.

Unsecured business loans may be available without an asset as security, often for amounts under NZ$50,000, but that does not guarantee that no deposit is required. Lenders assess each application based on factors such as repayment ability, credit history and the business plan.

Using borrowed money for growth or short-term cash needs

Before borrowing, match the loan to a specific business need and repayment plan. This helps you judge whether debt supports the business or adds pressure.

  1. Define the borrowing need

    Write down what the funds will pay for, then separate planned growth from urgent cash needs. For example, funding equipment that supports extra customer orders has a different purpose from covering a temporary delay in customer payments. New businesses should budget for at least six to 12 months of operating costs while revenue builds. Avoid borrowing without identifying which expenses the loan covers and how trading income will support repayments.

  2. Review loan risks and costs

    Before accepting a loan without a deposit, compare the interest, repayment schedule and any fees. Risks include committing future business income, leaving less cash for suppliers, and facing extra charges after late or missed repayments. Startup business loans may have higher interest rates than loans for established businesses. Check the total repayment obligation and whether the forecast shows the business can meet it, including during a slower trading period.

  3. Decide whether borrowing is suitable by linking the funds to a clear business outcome. Lenders in New Zealand assess whether a business is viable and can repay the loan and interest. A loan may suit planned growth or a short-term cash shortfall, but borrowing to bail out a business can leave the underlying problem unresolved. First identify the cause of the shortfall, such as late customer payments or rising operating expenses. Then consider whether the loan addresses that cause or only delays it.
  4. Set a repayment plan that protects essential business spending. Put each repayment date alongside expected income and regular bills, then consider what happens if a customer pays late. Don’t assume projected sales will arrive on schedule. If the forecast shows repayments competing with wages, rent or supplier invoices, reconsider the amount or timing before committing. This makes the effect on day-to-day trading easier to assess.
  5. Read the early repayment terms before planning to clear the debt ahead of schedule. Repaying early makes sense only if the interest saved exceeds any early repayment fee. Don’t make extra repayments just because of a strong sales month. First account for upcoming tax, supplier bills and operating needs. A business loan should fit the purpose, cash flow and repayment plan without leaving the business short of working cash after the funds are used.

How to work out whether you need a deposit for a business loan in NZ

Business plans and credit history

  1. Start with a business plan that clearly explains the loan request. For a startup application, the plan can carry significant weight in a lender’s assessment. State what the funds will pay for, how the business will earn income, and how that income will support repayments. For example, connect equipment funding to the work it enables, expected customer demand and resulting sales. A deposit can show your contribution, but it doesn’t replace a clear repayment plan.
  2. Make the plan practical enough to test, not just persuasive. Set out your product or service, likely customers, how you’ll reach them and key operating needs. Link expected sales to the cash flow forecast and explain assumptions, such as when customers pay. If income depends on a signed contract, identify it; if demand is untested, explain how the business will manage before sales grow. Keep the requested loan amount tied to specific expenses.
  3. Review your personal credit history before applying, especially if the business is new. A startup may have little or no trading record, so lenders may consider the founder’s credit history alongside the business plan and evidence of repayment capacity. There’s no fixed credit score cutoff for a New Zealand startup loan. A clean personal credit history with no recent defaults can strengthen an application, but credit history is only one part of the assessment.
  4. Check your credit information for errors and prepare a straightforward explanation for any past difficulty. For example, if a missed payment arose during a period of financial disruption, explain what happened and what has changed since. Don’t hide a past default or leave unexplained gaps in your application. Support your explanation with relevant records, such as evidence that an account is now up to date. Clear information helps a lender assess the circumstances rather than guess.
  5. Bring the business plan, credit information and loan request together before applying. Check that the amount requested matches the listed expenses and that forecast income supports repayments after ordinary business costs. If the business has a limited trading record, explain how the plan accounts for that gap. A deposit may strengthen the application by showing your own contribution, but the business still needs a credible purpose, realistic repayment plan and acceptable credit position.

Collateral and security for business loans

The deposit a lender requires depends on the loan purpose, your contribution, available security and evidence that repayments are affordable. Cash is only one part of the assessment; assets offered as security can also affect how the lender views risk.

  1. List the assets you could offer before deciding how much cash to put towards a deposit. Depending on the loan and lender, business equipment, vehicles or property may be considered as security. Security is an asset a lender may claim if repayments aren’t made. Record who owns each asset, whether another loan is secured against it, and its current condition. Note which items the business relies on daily, since losing access to them could disrupt trading.
  2. Separate your own contribution from the security you can provide. Your contribution is cash invested in the business or purchase; security is an asset backing the borrowing. When assessing a startup loan, lenders may consider the founder’s personal investment, security, credit history and forecast cash flow. A larger contribution or suitable security may support the application, but neither replaces evidence that repayments are affordable.
  3. Understand what could happen to each asset if the business can’t repay. If you offer personal property or equipment as security, that asset is exposed to the loan risk. Consider how losing access to it could affect your household or ability to trade. Review any existing lending against the asset, since another lender’s claim may affect its suitability as security. Keep the amount borrowed aligned with the asset’s role and the business’s repayment capacity.
  4. Compare a secured loan with an unsecured option before choosing. Unsecured business loans are often available in New Zealand for amounts under NZ$50,000, though their rates are higher because they lack security. That can avoid pledging an asset, but higher interest increases repayments. Compare the full repayment schedule with the business forecast, and weigh the cash deposit against the cost of borrowing and the risk to any asset offered.
  5. Prepare a security summary for the application. List each asset, its owner, any existing debt attached to it, and how the loan will be repaid. Include your own contribution and explain how each asset would support the application. A business loan guide can help you organise these details and understand how security fits into your borrowing plans.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you assess business loans in light of your business purpose, cash flow and available security. If a mainstream bank has declined your application, that does not necessarily end your options. A different lending approach may better suit your circumstances.

Bring details of your loan purpose, financial records, forecast repayments, and any deposit or security you can offer. These provide a practical starting point for discussing your application and identifying areas that may need attention. Mortgage Suite Ltd also offers home loans to first home buyers, but for this question, the relevant next step is to discuss business finance.

For a supportive conversation about borrowing for your business, contact Mortgage Suite Ltd today.

Take the next step with a clear borrowing plan

Working out whether you need a deposit for a business loan in NZ is only the starting point. Bring your funding purpose, contribution, security and repayment plan together to get a clearer picture of your position. This makes it easier to discuss what may suit your business and where the application needs more work.

Mortgage Suite Ltd offers Business Loans, Home Loans to First Home Buyers and Residential Investment Property Loans. If you’re considering a business loan, you can discuss your circumstances and possible lending pathways without treating a bank’s decision as the final word. A conversation can help you identify practical next steps, with no obligation to proceed.

Contact Mortgage Suite Ltd about business loans and take your next step with a clearer plan.

Frequently Asked Questions

How much interest will I pay?

The interest you pay depends on the rate and repayment terms offered for your loan. To compare options, look beyond the headline rate: consider how often repayments are due, whether the rate can change, and how much interest the repayment schedule adds over the full term. Then compare the total amount repayable with your planned use of the funds, not just the first repayment.

Do business loans in New Zealand require a deposit?

Not every business loan requires a cash deposit. A lender may instead focus on how the loan is structured, what it funds and what support is available for repayment. Before applying, separate the amount you can contribute from the amount you need to borrow. This gives you a clearer basis for discussing whether the proposed loan requires an upfront contribution.

How much deposit do NZ business lenders typically require?

There’s no single deposit percentage for every NZ business loan. To estimate your contribution, start with the amount needed for the purchase or project, then subtract the funds you can put in without leaving the business short of cash. Keep your working cash separate from your deposit figure, so you can explain how the business will cover both the upfront need and day-to-day trading.

Do NZ banks require a deposit or personal guarantee for a business loan?

Neither a deposit nor a personal guarantee is required for every NZ bank business loan. A guarantee is different from a deposit: it may make you personally responsible for repayment if the business can’t meet its obligations. Read the proposed terms carefully, identify who would sign, and understand when the guarantee could apply before agreeing.

Can business assets or equipment be used as security instead of a deposit in NZ?

An asset may sometimes support a business loan, but it doesn’t automatically replace a cash deposit. If you’re buying equipment with borrowed funds, ask how the lender treats it within the proposed loan structure. Check whether it can be used as security, who owns it during repayment, and what the agreement says if the business falls behind.

What are the deposit requirements for NZ startup business loans?

Startup loans don’t have one standard deposit amount across New Zealand. A startup loan is designed for a new business without a trading history or steady revenue, so a lender may focus on the founder’s contribution and funding plan. Separate the money needed to start trading from any contribution towards a specific purchase, then show how each amount will be used.

Do government-backed or small business loans in New Zealand require a deposit?

Government backing or a small-business label doesn’t automatically remove a deposit requirement. The terms of a particular lending programme explain whether a contribution is needed and what the funds can cover. Read those conditions alongside the repayment terms, and distinguish any required upfront contribution from other eligibility requirements. A programme’s backing alone doesn’t establish that a business qualifies or that borrowing will be deposit-free.

What documents and steps are needed to apply for a business loan in NZ?

Prepare a clear application pack that connects your request to the business’s circumstances. State the amount sought and how you intend to use it, then organise the relevant records and supporting documents consistently. Include details of existing borrowing and any assets or guarantees involved. Before submitting, check that names, dates and figures agree across the paperwork, and keep copies of the final application and lender correspondence.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage refixing strategy NZ: Compare rates and loan types

A mortgage refixing strategy in NZ starts with reviewing your loan six to twelve months before a key fixed term expires. Compare more than the headline rate: consider the loan structure, flexibility and how repayments fit your plans. Staggering fixed-term dates can also help avoid having all your lending refix at once.

It’s understandable to feel unsure when rates and your circumstances can change. A lower rate may look appealing, but the right choice also depends on how much certainty or flexibility you need and when you might need access to funds.

This guide explains how to compare banks and non-bank lenders, weigh fixed, floating and split options, and prepare for a review before your term expires. You’ll also learn how staggered expiry dates can spread decisions over time, helping you plan your mortgage with care.

Key Takeaways

  • Compare lenders on structure and flexibility as well as the interest rate, so the loan fits your plans.
  • Choose between fixed, floating or split lending by weighing repayment certainty against access to flexibility.
  • Start reviewing your mortgage six to twelve months before a key fixed term expires to give yourself time to consider your options.
  • Staggering fixed-term dates can prevent all your lending from needing to refix at once.
  • Compare current rates by lender and fixed term, then consider how each option affects your repayments and future plans.

1. Comparing banks and non-bank lenders

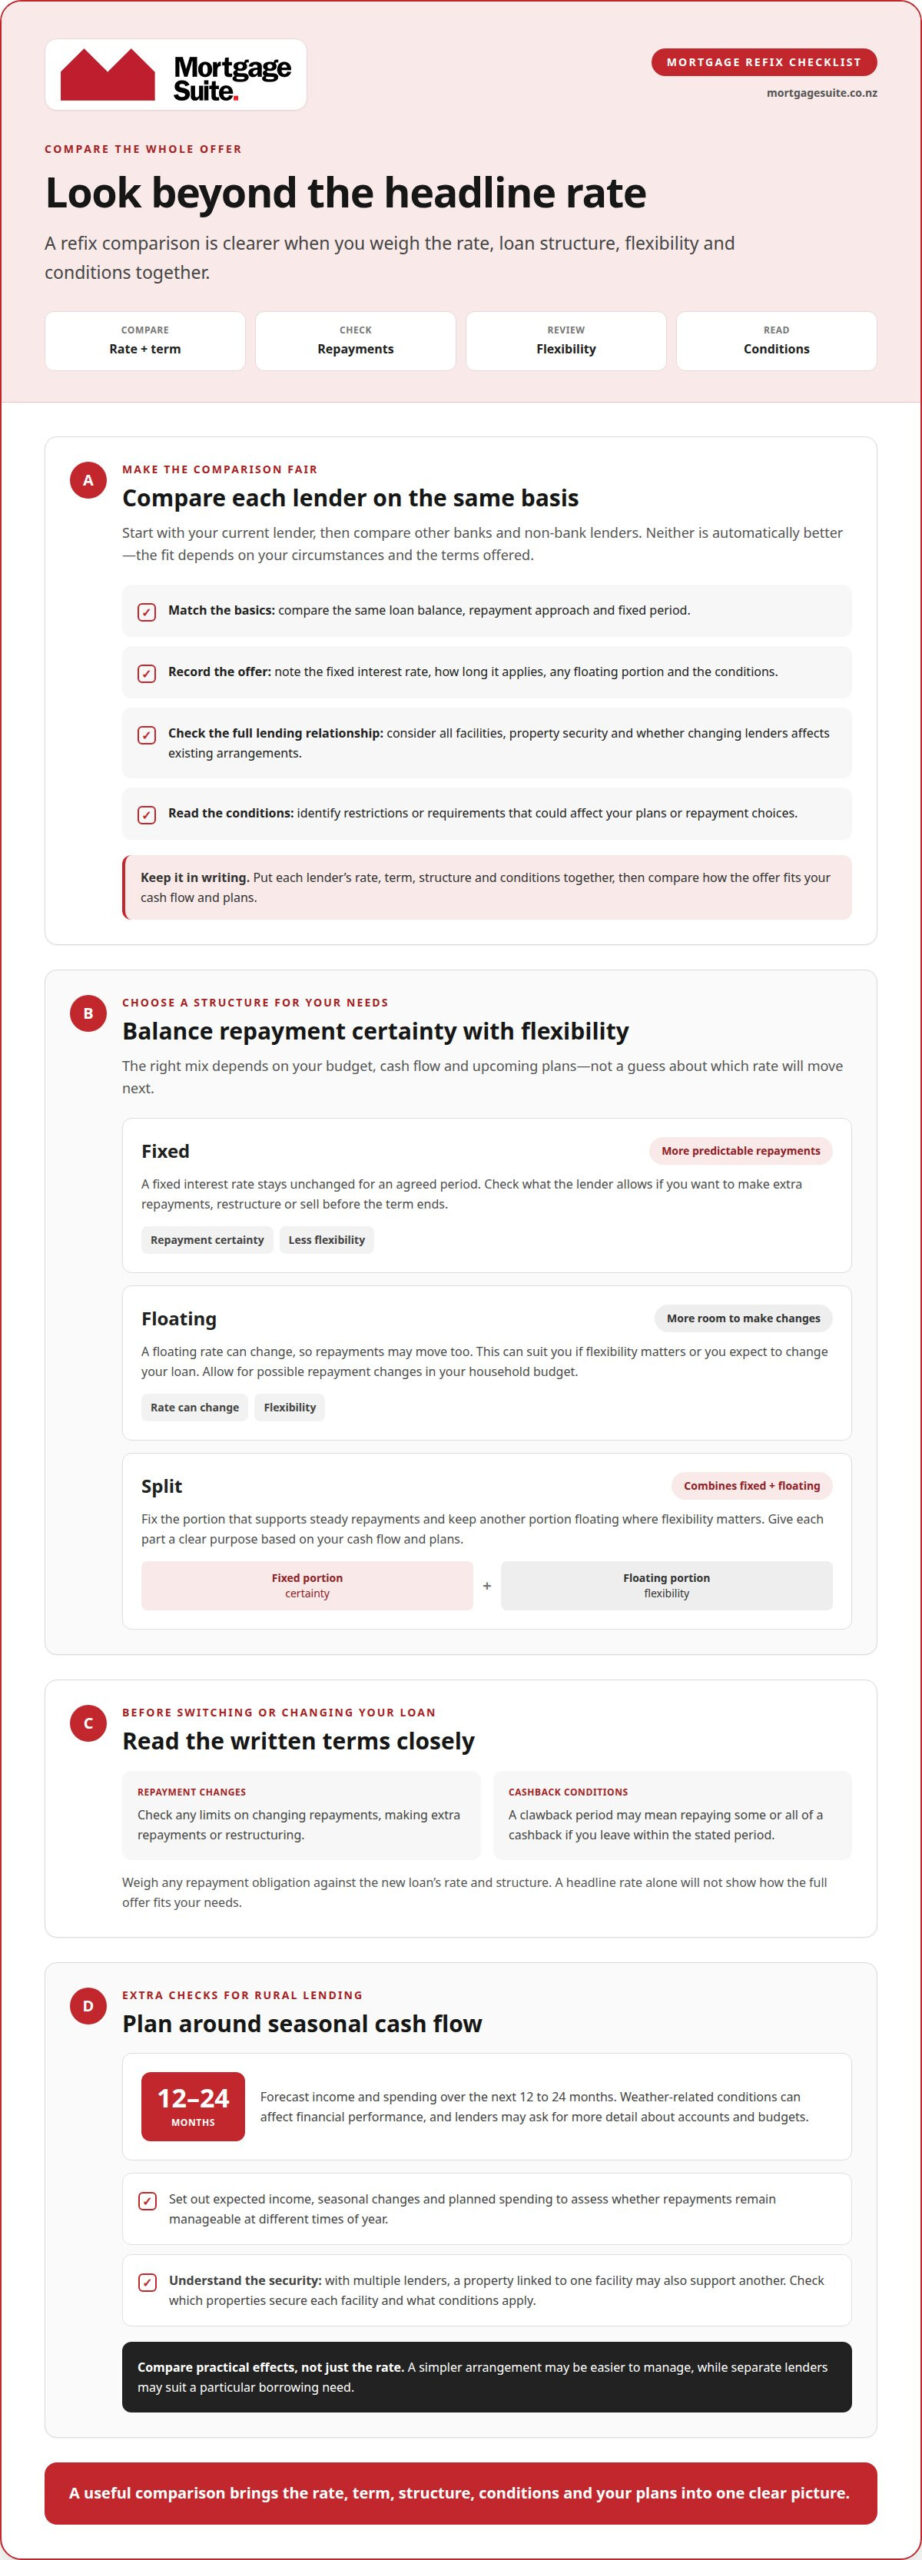
Compare your bank’s refix offer with alternatives by looking beyond the advertised rate. Assess the rate, fixed period, repayment options and conditions together. A lower rate may not suit you if the structure limits flexibility you need. Use the same loan balance and repayment approach when comparing offers, so you can make a like-for-like assessment.

Start with your current lender’s offer, then compare other banks and non-bank lenders. Ask how each option would affect your repayments and loan structure. A non-bank lender may be worth considering when mainstream bank criteria don’t fit your circumstances. Neither type of lender is automatically better: the right comparison depends on your income, security, plans and the terms available.

Use the same checklist for each lender. Record the fixed interest rate, how long it applies, any floating portion and conditions that affect how you manage the loan. Consider whether changing lenders would affect your existing lending arrangements. A headline rate won’t show the full picture if the offer changes your flexibility or requires a different security setup.

  • Compare like with like: Match the loan balance, repayment approach and fixed period across offers.
  • Read the conditions: Note restrictions or requirements that could affect your plans.
  • Review the structure: Check whether fixed and floating portions suit your need for certainty and access.
  • Consider the whole lending relationship: Look at how each lender treats all facilities and property security.

Rural borrowers have extra cash-flow factors to weigh. Forecast income and spending over the next 12 to 24 months before choosing a refix. Weather-related conditions can affect financial performance, and lenders may request more detail about accounts and budgets. Prepare a clear view of expected income, seasonal changes and planned spending. This helps you assess whether repayments remain manageable through different parts of the year.

Using multiple lenders for rural lending can also create complex security arrangements, including cross-collateralisation. This means a property linked to one facility may also support another. Before splitting lending across lenders, understand which properties secure each facility and what conditions apply. A simpler arrangement may be easier to manage, while separate lenders may suit a particular borrowing need. Compare the practical effects, not just the rate.

Keep your comparison in writing. Set out each lender’s rate, term, structure and conditions in one place, then identify the option that best fits your cash flow and plans. For rural lending, include the 12 to 24-month forecast. This turns a stressful choice into a clearer decision based on your actual circumstances.

2. Fixed, floating and split mortgage structures

Compare fixed mortgage rates and fees by matching the loan balance, fixed period and repayment type. Read each written offer for rate conditions, fee details and any limits on changing repayments. A headline rate is useful only when the surrounding terms also suit your needs.

A fixed interest rate stays unchanged for an agreed period, making repayments more predictable during that term. That certainty can help if your household budget has little room for unexpected changes. The trade-off is less flexibility: check what the lender allows if you want to make extra repayments, restructure or sell before the term ends.

A floating rate can change, so repayments may move when the lender changes its rate. This option can suit borrowers who value flexibility or expect to make changes to their loan. Factor the possibility of changing repayments into your household budget rather than assuming the current amount will stay the same.

A split structure combines fixed and floating portions. For example, you could fix the part of your loan that supports steady repayments and keep another portion floating for flexibility. Base the split on your cash flow and upcoming plans, not a guess about which rate will move next.

For rural borrowers, a split mortgage can combine a fixed portion of core term debt, a floating portion for flexibility and seasonal facilities for short-term cash-flow swings. This links different parts of the lending to different needs. Consider when income arrives, when expenses fall due and which funds need to remain accessible.

What mortgage refixing strategy suits changing interest rates and household budgets in New Zealand? Choose a fixed portion for repayment certainty and a floating portion where flexibility matters. The balance depends on your cash-flow needs and how much change your budget can absorb.

Cashbacks can affect a decision to refinance, but compare the offer with its conditions. A clawback period may require you to repay some or all of a cashback if you leave within the stated period. Read the written terms before switching, and weigh any repayment obligation against the new loan’s structure and rate.

Keep the comparison practical. Write down each portion’s purpose, rate type, repayment conditions and any relevant fee or cashback terms. Then assess the structure against your budget and plans. A suitable split gives each part of the loan a clear purpose, rather than dividing lending without a reason.

A rural mortgage refix in New Zealand can involve renegotiating the rate and loan structure with your current lender or splitting lending across multiple lenders. In either case, compare how each arrangement serves your cash-flow needs and preserves the flexibility your plans require.

3. Reviewing a mortgage before the fixed term expires

Yes, you can ask your bank to review the rate it offers for your next fixed term. Make a specific request, such as asking whether it can improve the rate or adjust the loan structure. Have your current loan details and preferred terms ready. A clear request gives the bank something practical to respond to.

Before speaking with your lender, prepare a concise snapshot of your mortgage. Include each loan portion, its balance, repayment type and current conditions. Note what you want to change, such as the repayment frequency or the amount you’d like to keep flexible. This helps keep the discussion focused on your needs.

Break fees are charges for ending or changing a fixed loan before its agreed term expires. Early repayment costs may also apply if you repay more than the loan terms allow. Read your loan documents and ask the lender for a written breakdown before making an early change. The terms and calculation determine the amount.

Use the review to check whether your current setup still reflects your circumstances. For example, a change in household income could affect what repayment amount feels manageable. List any planned property or borrowing changes, then consider how they might affect your loan structure. This gives you a practical basis for discussing options with your lender.

You can switch lenders when your fixed term expires. Compare the new lender’s written terms with your existing arrangement, including the steps needed to transfer the loan. Switching can involve charges or other costs, depending on the lending and transfer requirements. Ask for a clear breakdown before deciding, and compare the overall implications rather than focusing only on the rate.

Keep your review notes together. Record the lender’s offer, when it was provided, any conditions and questions that still need answers. If you discuss changes by phone, check the written terms afterwards. This makes it easier to compare what was discussed with the offer you’re being asked to accept.

Before agreeing to a new term, check how the proposed repayments fit your current budget. Consider whether you need the option to make extra repayments or change the structure later. A useful review ends with a clear record of the agreed rate, term, repayment arrangement and applicable conditions.

For rural borrowers in New Zealand, begin reviewing your mortgage six to twelve months before key fixed terms expire. Use that time to gather your loan details, preferred terms and planned changes, then identify what you need the lender to clarify. Setting out these points early can keep the review focused on the choices that matter to your household.

As expiry approaches, revisit the written offer alongside your notes. Check the rate, term, repayment arrangement, conditions and any costs tied to a change or transfer. If anything remains unclear, ask for an explanation in writing before deciding. Keep your decision grounded in what your budget can manage and whether the arrangement provides the flexibility you want.

Mortgage refixing strategy NZ: Compare rates and loan types

4. Staggering fixed-term expiry dates

Staggering means arranging fixed loan portions so they expire at different times. Instead of facing a single decision for the whole mortgage, you review each portion as its term ends. This can reduce the impact of a rate rise by preventing all your lending from refixing at once.

The main benefit is spreading rate changes across separate review points. If rates rise before one portion expires, that portion may refix at a higher rate while the others remain on their agreed terms. If rates fall, later expiry dates give you opportunities to consider the rates available then. Staggering spreads exposure; it doesn’t predict or prevent rate movements.

Decide how much of your mortgage to put in each portion by considering your budget and tolerance for repayment changes. A larger portion expiring at once can cause a more noticeable change to repayments. Smaller portions can spread that effect, but mean managing more individual dates and decisions. The right balance is personal, not a standard formula.

Before changing your schedule, map your existing loan portions and their expiry dates. Mark the portion that expires first, then consider whether the next expiry coincides with a planned change in household finances. For instance, if you expect a change in regular income, consider how a refix decision around that time could affect your available budget.

Staggering also has practical trade-offs. Each portion has its own rate, term and review point, so you’ll need to keep clear records. Maintain a loan schedule showing each portion, its expiry date, repayment arrangement and lender terms. A calendar reminder for each review can help you keep decisions distinct and avoid treating the mortgage as one undivided loan.

When a portion approaches expiry, assess it on its own merits. Consider the rate and terms available then, how its repayments fit your budget and whether the remaining portions still have the right schedule. A decision about one portion doesn’t have to dictate the next. Review the whole plan when circumstances change, but tie each refix choice to the portion reaching expiry.

Staggered dates are most useful when you can manage the extra administration and want to avoid concentrating every refix decision at one point. They won’t guarantee a lower rate or smoother repayments in every market. The practical aim is to make each decision manageable and keep future expiry dates visible, so you can approach them with a clear view of your mortgage.

5. What are current NZ mortgage refix rates by bank and fixed term?

Mortgage rates change, so a useful comparison needs the lender’s current offer and the fixed term you’re considering. Rather than relying on a single rate figure, compare the terms available for your loan and confirm how each offer applies to your circumstances. The rate alone won’t show whether the structure suits your budget.

Start with your bank’s current refix offer. Record the rate, fixed period, repayment conditions and date the offer applies. Then compare it with other available offers for the same loan balance and repayment approach. This keeps the comparison fair and helps you spot differences beyond the headline rate.

Fixed terms can have different rates at the same lender. Compare the options side by side using the same loan details. For example, look at the shorter and longer fixed periods available, then consider how each fits your expected budget and plans. Don’t assume a rate for one term applies to another.

A bank’s advertised rate may not be the final offer for every borrower. Your loan details and the lender’s terms affect what you’re offered. Ask for the rate and conditions that apply to your mortgage in writing. Note the date of each offer, so an older figure doesn’t distort your comparison.

Use a simple comparison record with these details:

  • Lender: Record which bank or lender made the offer.
  • Fixed period: Note the term linked to that rate.
  • Loan structure: Include any fixed and floating portions.
  • Conditions: Record repayment limits and any relevant offer terms.
  • Offer date: Write down when the lender provided the information.

For a clear decision, compare the same fixed period across lenders first, then compare other terms separately. If one offer has a lower rate but tighter repayment conditions, consider whether those limits fit your plans. A household expecting an income change may value flexibility differently from one seeking steady repayments.

Check whether your comparison includes any cashback terms or conditions associated with changing lenders. Read how long those conditions apply and what could happen if you move the loan again. Keep these details separate from the interest rate, so an upfront offer doesn’t distract from the ongoing loan terms.

Before accepting a refix, confirm that the rate, term and conditions match the lender’s written offer. If your current bank’s offer doesn’t meet your needs, use comparable written terms to discuss alternatives. A careful, dated comparison gives you a practical basis for choosing a mortgage structure that fits your budget.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd offers Home Loans to First Home Buyers, helping you consider your borrowing needs and mortgage structure. If reviewing your finances has raised questions about buying your first home, or you’re weighing a new loan against your household budget, this can be a useful next step.

Bring together your income, regular spending, existing lending and property plans before discussing your options. A clear picture of your finances can help you explore a loan structure suited to your circumstances, rather than focusing only on a headline rate. If a mainstream bank’s decision has left you unsure what to do next, you can explore alternative lending options.

Contact Mortgage Suite Ltd to discuss your home loan needs and possible next steps.

Make your next mortgage decision with confidence

Your next mortgage decision is a chance to make your borrowing fit the priorities ahead. A mortgage refixing strategy in NZ should reflect what you need from your loan and the changes you expect in your household plans. Take a moment to identify what matters most before deciding on your next step.

If you’d value a conversation about your options, discuss your situation and prepare for the decisions ahead. A clear discussion can help you frame the questions that matter and consider a path forward.

Talk through your mortgage options. A thoughtful next step can help you feel more prepared and in control.

Frequently Asked Questions

How does mortgage refixing work in New Zealand?

Refixing means agreeing a new fixed rate and term as your existing fixed term ends. Your lender presents the available options, and you choose a rate period and loan arrangement for the next term. For example, if your home loan has separate portions, you can decide on each as its term comes up. Check the new repayment amount and terms before accepting.

When should I refix my NZ mortgage before the fixed term expires?

Begin reviewing your mortgage six to twelve months before a key fixed term expires. Use that time to gather current loan details, note any changes to income or spending, and consider what repayment amount your budget can manage. For a rural household, include a cash-flow forecast for the next 12 to 24 months. This preparation gives you time to compare options before deciding.

Should I choose a short or long fixed term for a NZ home loan?

Choose a term based on how long you want repayment certainty and whether your plans may change. A longer term keeps the agreed rate in place for longer, while a shorter one brings the next review sooner. For example, if you expect a change in household income or property plans, consider how either term affects your flexibility and budget before choosing.

How do floating, fixed, and split mortgage strategies compare in NZ?

A fixed rate keeps the agreed rate in place for its term; a floating rate can change. A split arrangement combines both, so different loan portions serve different needs. For example, a household seeking predictable repayments could fix most of its lending while keeping a smaller portion flexible for planned changes. Compare repayment conditions and your capacity to manage changing payments before settling on a structure.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan pre-approval declined? What to do next

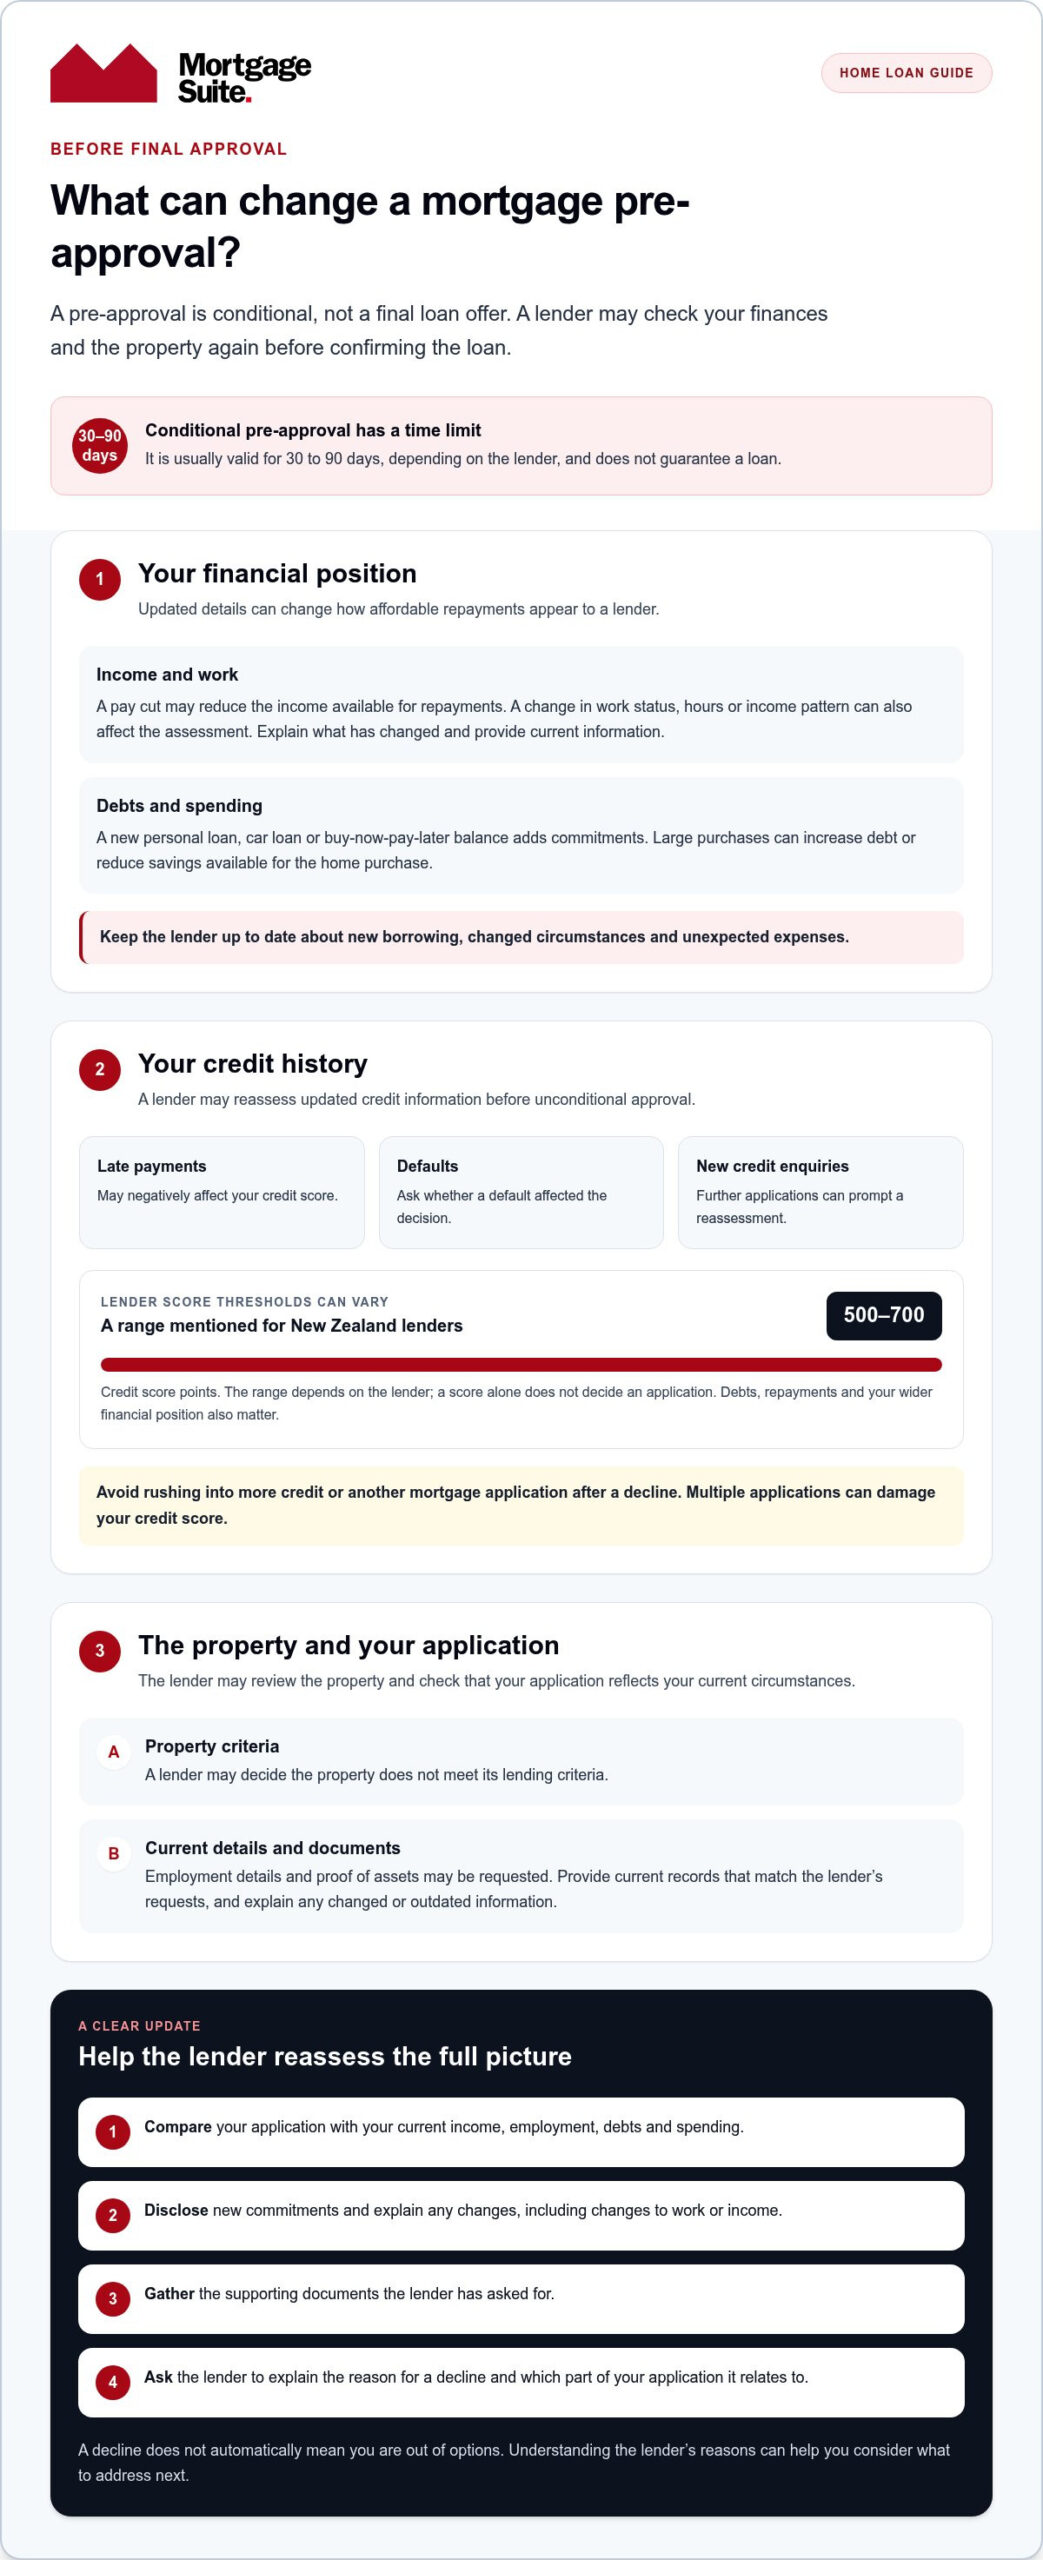
A pre-approval isn’t a final yes: a lender can still decline your home loan after reviewing your finances and the property. Conditional pre-approvals are usually valid for 30 to 90 days, depending on the lender, and don’t guarantee a loan. If your mortgage pre-approval is rejected, it doesn’t automatically mean you’re out of options.

It’s understandable to feel unsettled, especially if you thought the main hurdle was behind you. A lender may reassess your income, spending, debts or credit history, or decide the property doesn’t meet its lending criteria. This article explains why mortgage pre-approval can be rejected, what financial changes may affect your application, and how a mortgage broker may help you understand the decision and consider a suitable next step.

Key Takeaways

  • Pre-approval is conditional, not a final loan offer. A lender may reassess your finances and the property before confirming the loan.
  • Changes to your income, employment, debts or spending can affect how affordable the repayments appear to a lender.
  • Late payments and new credit applications may affect your credit history, so avoid taking on extra debt while your application is being assessed.
  • Ask the lender to explain the reason for a decline. The issue may relate to your finances, the property, or information in your application.
  • A mortgage broker can help you understand the lender’s decision and consider whether a different loan approach may suit your circumstances.

Changes in income, employment, debt and spending

Pre-approval reflects the information assessed when you applied, not every change that follows. Before final approval, updated income, employment or spending details can affect how a lender views your ability to repay.

Income and debt changes

Income and debt changes are shifts in what you earn or owe after applying for a home loan. For example, a pay cut can reduce the income available for repayments, while a new personal loan adds another commitment. These changes can alter the picture the lender assessed at pre-approval, so tell the lender if your circumstances change instead of relying on figures that are no longer accurate.

Changes don’t always mean your application has to stop. A pay rise, reduced debt or change in regular work hours can affect the assessment differently, depending on the full picture. Give the lender current details and explain what changed. If your income varies, describe the pattern clearly. Leaving out a recent change can create a mismatch between your application and your current finances.

New debt matters because repayments reduce the money left for a mortgage. A car loan, personal loan or buy-now-pay-later balance can change your regular commitments, even if you’ve kept up with payments. Before taking on new debt during the home-loan process, consider how its repayments could affect your application. Tell the lender about any new borrowing instead of assuming it won’t appear in the assessment.

Employment details and supporting documents

Employment details describe your current work and income arrangements, while supporting documents show the financial information behind your application. A lender may require employment details and proof of assets for pre-approval. If you move from salaried work to contracting, for example, update your work status and provide the information requested to support the new arrangement.

Keep relevant records together, including documents that show your current income, employment and assets. The lender’s requests depend on your circumstances, so match each document to the information they ask for. If a record is out of date or a detail has changed, explain that clearly when you submit updated information. This helps avoid confusion between your original application and your current position.

Spending changes can also affect the lender’s view of affordability. A large purchase, such as new furniture bought on credit, can increase debt or reduce savings available for the home purchase. Avoid taking on more debt or making large purchases while seeking final approval. If an unexpected expense changes your finances, record what happened and update the lender with accurate details.

Before sending an update, compare your application with your current income, employment, debts and spending. Correct outdated details, disclose new commitments and gather the requested supporting documents. For example, if your work arrangement changed and you also opened a credit account, explain both changes together. A complete, up-to-date account gives the lender a clearer basis for reassessing your application.

Credit score changes and new credit applications

Your credit score can change between pre-approval and final assessment. Late payments, defaults and new credit enquiries may negatively affect your score before unconditional approval. That matters because a lender may reassess your application using updated credit information. If your score has changed since applying, ask what part of your credit history affected the decision and what information the lender considered.

There’s no single credit-score threshold for every New Zealand home loan. The minimum scores used by lenders can range from 500 to 700 credit score points, depending on the lender. A score within that range doesn’t decide the application by itself. The lender also considers your wider financial position, including debts and repayments, so a higher score alone may not resolve other concerns.

New credit applications can add uncertainty while a lender assesses your mortgage. For example, applying for a credit card and a car loan after receiving pre-approval may prompt the lender to reassess your commitments. Opening more lines of credit can also affect your application. Avoid rushing into another mortgage application after a decline: multiple applications can damage your credit score.

If a lender declines your application, first ask for a clear explanation. Find out whether the concern involved late payments, a default, a recent credit enquiry or another part of your application. Then review your credit records and compare them with your own payment history. If an entry appears incorrect, gather the relevant account information before discussing it with the organisation that recorded it.

For a New Zealand home loan, deposit requirements and Loan-to-Value restrictions depend on the lender’s criteria and property assessment. The Loan-to-Value ratio compares the loan with the property’s value, so a larger deposit means borrowing a smaller proportion of that value. Deposit size is one part of the assessment, alongside credit history, income and existing debts.

Before applying again, pause and make a clear record of any credit applications, repayments or missed payments since pre-approval. Avoid taking on new credit while the lender reviews your position. If you’ve recently applied for finance, explain why and whether the application led to a new debt. Accurate details help the lender assess your current commitments rather than an incomplete picture.

A decline doesn’t tell you which change mattered most unless you get the lender’s reasons. For example, a recent enquiry may be less significant than an unpaid default, depending on the lender’s assessment. Use the explanation to decide what to address first, then discuss another application once you understand how your credit history and deposit affect the overall picture.

Can I be denied after a pre-approval?

Yes. A lender can decline after pre-approval if updated financial checks or the specific property change its assessment. Ask for the lender’s reasons before deciding what to do next.

Reasons for decline after pre-approval

A decline after pre-approval means the lender’s final assessment no longer supports the loan. The lender may reassess your finances and the property, including its valuation. If the valuation is below the purchase price, the lender may decide the security does not support the requested amount. Changed credit information, incorrect application details or a property that fails a condition can also affect the decision.

The property itself can be the issue. A lender may view a flood-zone property, a home in a mining town or a property needing substantial renovation as higher risk. A rise in interest rates or a change to lending policy may also prompt reassessment. These factors mean pre-approval is not final approval for every home you might choose.

Steps after a loan decline

Start by asking the lender to explain the decline clearly. Identify whether the main concern was your finances, an application error, a property condition or its valuation. Then compare that explanation with your documents and purchase details. This gives you a specific issue to address, rather than guessing or sending another application with the same problem.

If the property is the obstacle, consider whether another property may meet the lender’s criteria. If a valuation came in below the purchase price, discuss how that figure affected the requested loan. If details were missing or incorrect, prepare accurate information before reapplying. Keep the lender’s explanation and supporting documents together so the next assessment addresses the actual concern.

Applying to another lender

You can consider another New Zealand lender after a decline, but first understand why the original application failed. There is no set waiting period in the available guidance. The practical next step is to address the reason before applying again. Rushing into several mortgage applications can damage your credit score, so avoid sending multiple applications at once.

A different lender may assess your circumstances or the property differently, but the same unresolved issue can still matter. For example, a lower valuation remains relevant if you apply for the same property and loan amount. Before approaching another lender, gather the decline explanation, update any incorrect details and decide whether the property or requested borrowing needs to change.

Use the lender’s decision as a guide to what needs attention. If your mortgage pre-approval is rejected because of a property condition, changing your finances alone may not solve it. If the concern relates to your application information, correct that first. A clear reason helps you decide whether to revisit the property, update your application or seek another assessment.

Home loan pre-approval declined? What to do next

Conditional approval and approval in principle

Conditional approval, also called approval in principle, is an early indication that a lender may lend if its conditions are met. In New Zealand, it’s provisional, not a final loan offer, so the lender can still review your finances and the property before confirming the loan.

Pre-approval letters commonly include conditions that need to be satisfied before the lender proceeds. These may relate to information the lender still needs or to the property you intend to buy. For example, the lender may need to assess a specific home after you make an offer. Approval in principle therefore gives you an early guide, not confirmation that every property will qualify.

Check the letter carefully when it arrives. Note the date, the stated expiry and each condition that applies to your application. Home-loan pre-approvals are usually valid for 30 to 90 days, depending on the lender. If your search takes longer, the approval may expire, and the lender may need to reassess your circumstances before you rely on it.

That reassessment can matter if your finances change during the approval period. New debt, a change in employment or a credit-history change could affect the lender’s view of your application. Keep the information you provided accurate and current. If something changes, tell the lender rather than treating the original pre-approval as an unchanged decision.

The property is another part of the final assessment. A lender may assess the specific home and obtain a valuation before issuing unconditional approval. For example, if the valuation comes in below the agreed purchase price, the lender may reconsider the loan amount. Pre-approval for your finances does not mean the lender has accepted every property you might choose.

Unconditional approval is formal approval issued after all conditions are met and both you and the specific property have been assessed. Until then, don’t treat a conditional letter as confirmation that settlement funding is ready. Read the conditions, respond to requests for information and track the approval period. These steps help you understand what remains outstanding.

If a conditional approval expires or the lender changes its assessment, ask which condition remains unmet and what information is needed. For instance, clarify whether the issue concerns an updated financial detail or the property’s valuation. A precise explanation helps you decide whether to provide further information, revisit the property choice or discuss a revised application.

Approval in principle can help you understand your borrowing position while you look for a home, but it has limits. Treat the lender’s conditions and expiry date as part of your planning. Before making commitments based on the letter, understand that final approval depends on the lender completing its assessment of your finances and the particular property.

Using a mortgage broker

A mortgage adviser can review the lender’s reasons, help prepare a request for reconsideration and discuss other lending options. Their value lies in turning a decline into a clearer plan, not simply sending the same application again.

Broker support after rejection

A broker’s support after rejection means reviewing the decision and helping you present relevant information clearly. This matters when, for example, the lender misunderstood a change in income or overlooked a document. Share the decline explanation and application details so the adviser can identify the concern and help shape a focused response.

If the lender may reconsider, a broker can help organise supporting documents and explain how they address the issue. For example, an updated employment record may clarify a recent work change. If the property valuation is the concern, the response needs to address the property assessment, not rely only on documents about your income.

A broker can also discuss whether another lender’s criteria may better fit your circumstances. Start that comparison with the reason for the decline, not a fresh application sent everywhere. If the issue is an incorrect detail, correct it first. If the property is the obstacle, consider whether another property could change the assessment.

Working with a mortgage broker

Working with a mortgage broker means sharing your financial picture so they can help assess suitable lending options. Provide accurate information about income, existing debts, deposit and the property you’re considering. For instance, if you’re self-employed, explain how your income is recorded and supply the documents requested for assessment.

Use the lender’s decline explanation as the starting point for a practical discussion. Ask the broker to clarify which parts of your application need attention and what evidence could address them. A clear account of the issue helps avoid repeating an application without meaningful changes.

A broker can help communicate with lenders and present your circumstances in context. For example, if a mainstream bank’s criteria don’t suit your situation, discuss whether another lending approach may fit. The lender still assesses the application, so focus on a realistic plan, clear documents and loan terms that match your goals.

Before proceeding, agree on what the next application needs to show. That could mean correcting information, documenting a change or reconsidering the property. A mortgage adviser can help you weigh those options and prepare for the next conversation with a lender, rather than treating a decline as a final judgement on your borrowing plans.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd provides home loans to first home buyers, helping you consider your next move after a lender’s decision. If your pre-approval was declined, bring the lender’s explanation and your updated financial details to discuss possible lending options. Understanding whether the concern relates to your circumstances or the property can help shape a more suitable application.

Mortgage Suite Ltd also provides residential investment property loans, business loans and property development loans. For a first-home buyer, the focus is understanding your goals and borrowing situation, then considering a path that fits. A decline can be discouraging, but it isn’t a judgement on you as a borrower. Contact Mortgage Suite Ltd to talk through your circumstances and possible next steps.

Choose your next move with confidence

If your mortgage pre-approval has been rejected, take time to understand the lender’s reasons before deciding what to do next. You don’t need to treat the decline as a judgement on your plans. Focus on what you want to achieve, what needs to change and what information will help a lender assess your situation fairly.

A useful conversation can turn uncertainty into a practical direction. Mortgage Suite can talk through your circumstances and help you consider the next step, whether that means revisiting your application or exploring another lending path. You don’t need to have every answer ready before you start. A clear account of what happened is a helpful beginning.

Contact Mortgage Suite to discuss your next step. With a considered plan and the right support, you can keep moving towards your property goals.

Frequently Asked Questions

What is home loan pre-approval?

It’s an early indication of how much a lender may be willing to lend, based on the details you’ve supplied. Use it as a planning guide, not a spending target: consider whether the repayments and other homeownership commitments fit your budget. Before making an offer, read the lender’s letter closely and note what it says about the amount, property and any remaining conditions.

Why might a mortgage pre-approval be rejected in New Zealand?

A lender may decline if its assessment finds a concern it can’t accept or needs more evidence to resolve. Ask whether the decision reflects a lending policy, missing information or a specific part of your application. That distinction helps you work out whether to provide further documents, correct a detail or reconsider your plans, instead of making another application without knowing what needs to change.

What credit score and credit history issues can prevent mortgage pre-approval in NZ?

Review your credit history for accounts you don’t recognise, incorrect balances or payment entries that don’t match your records. If something looks wrong, gather statements or other relevant records and raise the specific entry with the organisation that recorded it. A lender can also explain whether its concern relates to your overall credit profile or a particular item, helping you focus on the right issue.

How do income, expenses, debt, and affordability affect NZ mortgage pre-approval?

Prepare a realistic household budget that captures regular bills as well as less frequent expenses, such as vehicle maintenance or annual charges. Compare that spending with the income you can reliably count on, then account for your existing financial commitments. This gives you a clearer view of what repayment level may fit your day-to-day life and helps you discuss your budget with the lender using specific figures from your own records.

Can a bank reject pre-approval because of the property, its valuation, or its location?

Yes. To clarify a property-related concern, keep the purchase documents and any available property reports together. Ask the lender which feature affected its assessment and whether the concern relates to value, condition or suitability. For example, if the issue is the valuation, ask how the lender’s assessed value affects the proposed loan, rather than assuming the purchase price will determine the amount it is prepared to lend.

What should I do after my NZ mortgage pre-approval is declined?

Keep the lender’s decision and related correspondence together, then ask what evidence could change the assessment. Find out whether the lender would reconsider the existing application with further information or expects a new application. If you’re working with a mortgage adviser, share the decision and your supporting records so they can help you consider the next approach without sending an application that leaves the original concern unanswered.

Does a rejected mortgage pre-approval affect my credit score in New Zealand?

The declined decision and a credit enquiry are different things. A lender’s enquiry may be recorded when it assesses an application, and new enquiries can negatively affect your score. Check your credit history for enquiries you don’t recognise, and keep track of applications you’ve made. If you’re unsure which enquiry relates to the declined application, ask the lender or the organisation holding your credit information for clarification.

What documents do NZ lenders require to assess a mortgage pre-approval?

New Zealand lenders may require employment details and proof of assets. They may also request supporting documents showing your current income and financial position.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan application in NZ: evidence for income and deposit

A practical home loan application checklist NZ borrowers can start with includes income records, proof of deposit, property details and identification showing residency status. For a First Home Loan, you must be a New Zealand citizen, permanent resident or resident visa holder ordinarily resident in New Zealand, and a first-home buyer or previous homeowner in a similar financial position. Lenders also assess whether repayments are affordable.

Gathering paperwork can feel like a hurdle, especially when your income is irregular or your circumstances do not fit a straightforward first-home-buyer profile. Organising your documents can help you explain your position and show lenders what they need to assess your application.

This guide covers the income and deposit evidence to gather, the property and residency details that matter, and the additional criteria for First Home Loan applicants. It also explains how pre-approval fits into the process and how a mortgage broker can help you prepare your application.

Key Takeaways

  • Gather recent bank statements and employment records so a lender can understand your income and regular spending.
  • Keep a clear record of where your deposit comes from, including any gifted funds.
  • Pre-approval can help you understand your borrowing position before house hunting, with final approval considered once you have a property in mind.
  • Collect property and building documents early, especially if you’re buying a home that needs work or planning a build.
  • Check residency and first-home-buyer eligibility alongside your income and deposit, as these details can affect which application pathway fits.

Income evidence for employees and casual workers

Start with records showing what you earn, how regularly you receive it and what reaches your account. Lenders consider this evidence alongside your expenses and existing debts when assessing affordability. A home loan application checklist NZ borrowers can use should make every income source easy to identify.

  • Gather your usual transactional account statements for the last three months. They help show income deposits, regular spending and other payments.
  • Collect recent payslips and your employment agreement. These help explain your pay rate, hours and employment terms.
  • If you’re on a three month trial period, include your employment contract. It gives the lender information about the trial arrangement and your role.
  • For casual work, organise records that show your shifts and changing pay. A clear run of payslips and matching bank deposits can help explain fluctuations.

How do NZ banks assess living expenses, debts, credit history, and affordability? Lenders consider your ability to repay, current debts and credit history, as well as your income and regular living expenses. They must assess affordability and suitability, so list your commitments accurately and ensure your statements tell a consistent story.

Self-employed income needs a different paper trail. Self-employed applicants may be asked to provide tax returns, financial statements and personal bank statements. They generally assess business profit after expenses, not total turnover, so high sales alone may not show the income available for repayments.

  • Prepare tax returns and financial statements for the last two years. These give a view of business earnings after costs.
  • Gather personal bank statements covering three to six months. They help connect declared income with money received and household spending.
  • If your trading history is under two years, organise the records you do have. Some lenders may consider a shorter trading history in certain circumstances.
  • Request finalised financial statements and IRD statements three months before applying. This gives you time to address missing paperwork or tax arrangements.
  • Collect bank statements, identification and deposit evidence one month before applying. Having these records together makes it easier to assemble your application.

For rental or other income, gather records showing the source, amount and consistency, such as tenancy documents and bank deposits. If you have multiple income sources, label each record clearly so the lender can distinguish employment pay, rent and other earnings.

First Home Loan income thresholds also matter. Keep evidence covering the relevant period ready for your application. A home loan application checklist NZ first-home buyers prepare should distinguish personal earnings from any co-applicant’s income.

Deposit sources and gifted funds

Loan-to-Value restrictions compare the loan amount with the property’s value, while deposit requirements depend on the lending pathway. A First Home Loan requires a minimum deposit of 5% of the purchase price; other applications are assessed against the lender’s criteria.

Your deposit evidence should show both how much you have and where it came from. Gather account statements and records for savings, transfers or a relative’s gift. A clear paper trail links the amount you declare to the money available for settlement.

  • List each deposit source. Separate personal savings, eligible withdrawals and gifted funds so each amount has a clear origin.
  • Save statements showing your savings balance. Keep the relevant account records together, including entries that show regular deposits or a transfer into your deposit account.
  • Keep evidence of large transfers. Match the incoming payment to a transfer record or written explanation, so it is clear whether the funds are your savings or a gift.
  • Record the gift’s source and amount. First Home Loan applicants may use a relative’s gift as their deposit, so keep a clear record of the relative and the gifted funds.
  • Check that your available deposit matches your purchase plans. Compare the funds you can access with the purchase price and the minimum deposit required for your chosen pathway.

For example, if a relative transfers gifted funds into your everyday account, keep the statement showing the deposit and a record explaining the transfer. If you move savings between accounts, keep statements for both. This makes the movement of funds easier to follow and helps prevent unexplained gaps in your deposit history.

A First Home Loan has a specific minimum deposit: 5% of the purchase price. That figure is the programme’s deposit requirement, not a universal deposit rule for every home loan. Loan-to-Value restrictions relate the borrowing to the property’s value, so the required deposit and lending assessment depend on the loan type and lender criteria.

Before applying, organise your evidence in one place. Make a simple record of each deposit source, its amount, the account holding it and the supporting document. For gifted funds, include the transfer record and gift details. For savings, include statements showing the balance and transfers between accounts.

A tidy deposit record helps you explain your position clearly, whether your funds come from long-term savings, a relative’s gift or a mix of sources. Keep original statements and transfer records together so you can give a consistent account of your deposit during the application process.

Mortgage pre-approval and broker assistance

Pre-approval can help you understand your borrowing position before house hunting. A New Zealand First Home Loan applicant may seek pre-approval before finding a property, then return to the lender for final approval after choosing one. Treat pre-approval as an early step, not confirmation that every property or offer will be accepted. Have your income, deposit and purchase details ready for assessment.

Use pre-approval to set a practical search range and identify any information the lender still needs. If your income varies between pay periods, for example, explain the pattern rather than relying on one unusually strong week. Keep your evidence consistent with your application. A clear account of your income, commitments and deposit helps the lender understand your circumstances.

  • Gather your financial details before applying. Include income, debts, regular expenses and deposit information, so the assessment reflects your whole position.
  • State your likely purchase plans. Share the type of property you’re considering and your expected price range, because the chosen property is reviewed later.
  • Keep a record of pre-approval conditions. Note any documents or changes the lender needs before final approval.
  • Update the lender if your circumstances change. A new debt, job change or altered deposit can affect the application between pre-approval and purchase.

Once you find a home, provide the lender with its details for final approval. The lender then assesses the specific property alongside your application. A pre-approved amount should guide your search, not replace the final review. Keep purchase information and any new financial details organised for this step.

A mortgage broker can help you present your application clearly and understand how lender criteria may differ. They can review your circumstances, identify relevant questions and help organise information for a lender. If you have casual work, self-employed income or several income sources, a broker can help explain how the details fit together. The lender makes the final decision.

Lenders in New Zealand may apply different credit criteria, so a decline from one lender does not necessarily mean another will decline your application. A broker can help identify whether another lender’s criteria may better fit your circumstances and support a clear application. This can be useful if a standard application does not capture the full picture of your income or deposit.

If you’re self-employed, consider seeking pre-approval before house hunting. It gives you an early opportunity to discuss how your trading history and income records will be assessed. Use the time to fill gaps in your paperwork and understand the next steps before making an offer. Keep your financial information current as you move from pre-approval to a chosen property.

Home loan application in NZ: evidence for income and deposit

Property purchase and construction documents

Property documents connect your borrowing request with the home or project you plan to fund. Start a separate folder for each property, then add purchase records, property details and, where relevant, construction paperwork. Clear files make it easier to explain what you’re buying and how the proposed loan relates to it.

  • Keep a copy of the sale and purchase agreement. It records the agreed transaction details, including the property and purchase terms.
  • Note the property address and type. Record whether it’s a house, apartment, section or another property type, so your application identifies the security clearly.
  • Save any property information supplied during your purchase. For example, keep the listing details and documents describing the land, dwelling or included fixtures.
  • Organise any valuation or building report you receive. These documents provide information about the property’s value or condition.
  • Keep relevant council records together. Plans, consents and correspondence can help explain the property’s status or planned work.

For a First Home Loan, the property must be less than 1 hectare, and you must use it as your primary place of residence. Keep property records that show what you’re buying and where you intend to live. If the purchase involves a section or a home with substantial work planned, separate existing property documents from proposed building documents.

Planning a build or renovation? Gather documents describing the work, expected stages and how the project will be funded. The lender needs to understand the property and proposed project together, so make that connection clear in your folder.

  • File the building plans and specifications. These describe the intended layout, materials and scope of the work.
  • Keep the builder’s contract and project schedule. These explain who is completing the work and how the project is organised.
  • Save the project budget and payment schedule. They show how the expected spending relates to the work stages.
  • Include relevant council documents. For example, keep consent records or correspondence alongside the plans they relate to.
  • Record any siteworks separately. Note ground preparation or access work as distinct project items, so the costs and tasks are easy to identify.

Use a simple document list showing the file name, date and purpose of each item. If a plan changes, keep the updated version and label it clearly instead of mixing several drafts together. For example, label a revised building plan with its issue date and match it to the relevant project schedule. This creates a tidy record for the move from purchase details to final property assessment.

Residency and first-home-buyer criteria

For a First Home Loan, check residency and buyer eligibility before preparing your application. These criteria are separate from proof of income or deposit and can determine which application pathway suits your circumstances.

How do home loan application requirements differ between banks and non-bank lenders in NZ? Lenders may apply different credit criteria, so their documents and assessment approaches can vary. A decline from one bank does not necessarily mean another lender will decline your application.

  • Confirm your residency category. First Home Loan applicants must be New Zealand citizens, permanent residents, or resident visa holders ordinarily resident in New Zealand.
  • Gather documents that show your status. Put the relevant citizenship, permanent residency or resident visa records with your application, so your residency details are clear.
  • Check whether you meet the first-home-buyer test. You must be a first-home buyer or a previous homeowner in a similar financial position to a first-home buyer.
  • Explain previous home ownership accurately. If you’ve owned a home before, prepare a clear account of your present financial position and circumstances for the eligibility assessment.
  • Confirm your intended use of the home. A First Home Loan property must be your primary place of residence, not a home you plan to use solely as a rental.
  • Check the age requirement. Check whether any age requirements apply to your application, and include accurate identification details.

What bank statements and expense records should NZ home loan applicants provide? Keep statements from your usual transactional account for the last three months, alongside a clear record of regular household spending and debt repayments. These help present your living costs and financial commitments consistently.

If you’re buying with others, explain every buyer’s residency and ownership history. One buyer may be purchasing for the first time while another has previously owned a home, for example. Set out each person’s circumstances separately, then show how you are applying together. This helps clarify the relevant eligibility pathway.

What common mistakes or delays should NZ home loan applicants avoid? Avoid gaps in residency or ownership details, inconsistencies across forms and overlooking the primary-residence requirement. Match names and dates across identification and application records, and explain any previous ownership clearly.

Before applying, use a simple eligibility checklist: confirm your residency category, buyer status, intended home use and identification details. Then organise the supporting records under those headings. If you’re unsure how the criteria fit your circumstances, explore practical mortgage guidance before lodging your application.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd provides Home Loans to First Home Buyers, helping you consider how your income, deposit and eligibility fit together in an application. If your circumstances are complex, or a mainstream bank has declined your application, a different lender’s criteria may offer another pathway to explore.

Bring your organised documents and questions about pre-approval, the property you’re considering and your next steps. Mortgage Suite Ltd can help you understand the options and prepare a lending application that reflects your circumstances, without promising an approval outcome.

If you’re ready to discuss buying your first home, visit mortgagesuite.co.nz to get in touch with Mortgage Suite Ltd.

Take your next step with a clear plan

Turn your home loan application checklist for New Zealand into a working plan: organise your documents, note any outstanding details and prepare to explain your circumstances clearly. Then match that information to a lending approach suited to your goals, rather than focusing only on whether one application pathway fits.

Mortgage Suite Ltd offers Home Loans to First Home Buyers, residential investment property loans and Business Loans. If you’re buying your first home, growing a property portfolio or financing a business, a conversation can help clarify which lending questions to tackle first. The lender makes the final decision based on its assessment of your application.

Contact Mortgage Suite Ltd to discuss your lending plans. A considered next step can help you move forward with greater clarity and confidence.

Frequently Asked Questions

What documents do NZ banks require for a home loan application?

Prepare identification, income and deposit records, along with documents for the property you intend to buy. Keep files current and easy to match to your application. Use clear filenames and group documents by applicant and type, for example. If a transfer or change in your circumstances needs explaining, keep a note with the relevant record rather than relying on memory later.

What proof of income is needed for PAYE employees and self-employed applicants in New Zealand?

PAYE employees can use payslips and employment records to show their pay and work arrangements. Self-employed applicants can organise business accounts and tax records so lenders can distinguish business turnover from personal income. If your own company pays you a regular wage, show how it is paid and recorded. Make sure the amounts in your application match the supporting documents.

What deposit and proof of funds do New Zealand lenders require?

For a First Home Loan, the minimum deposit is 5% of the purchase price. Keep evidence that makes the source of each part clear. If a relative contributes a gift, retain the transfer record and a written explanation of the funds. If you have moved savings between accounts, keep records that show the movement, rather than presenting only the final balance.

What extra home loan application requirements apply to first-home buyers?

First Home Loan applicants must be over 18 and meet the programme’s residency and buyer criteria. The home must be intended as your primary residence, and two or more applicants complete a participating lender’s application form. If you previously owned a home, explain how your current financial position is similar to that of a first-home buyer. These details help the lender assess the correct application pathway.

What are New Zealand’s current LVR rules and deposit requirements for home loans?

Loan-to-Value restrictions compare the loan amount with the property’s value. A First Home Loan requires a minimum deposit of 5% of the purchase price; other applications are assessed against the lender’s criteria.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage for a New Build in NZ: Compare Your Options and Plan Your Next Steps

What if the right mortgage for new build NZ buyers depends as much on how they buy as on the home itself? Buying a completed new home, choosing a house-and-land package and building from scratch can each involve different finance steps. Staged payments and changing build timelines can add to the uncertainty.

This guide explains the main purchase pathways, how finance may work for each and what to organise before discussing your plans. Mortgage Suite Ltd works with banks, private lenders and non-bank lenders, and negotiates on your behalf to find a lending option suited to your circumstances. Its advice is free of charge with no obligation.

Key Takeaways

  • Identify whether you’re buying a completed new home, a house-and-land package or building from scratch. Each pathway can shape your finance options.
  • Understand the drawdown process and how build milestones, payment timing and loan arrangements fit together before you commit.
  • Prepare a clear picture of your income, existing commitments, deposit position and preferred purchase pathway before discussing finance.
  • Compare mortgage for new build nz options against your plans and circumstances, rather than assuming one loan structure suits every buyer.
  • Mortgage Suite works across banks, private lenders and non-bank lenders, negotiating on your behalf as you consider a suitable way forward.

Mortgage for a New Build in NZ: Start by Identifying Your Buying Path

A “new build” might be a completed home ready to buy or a property that’s still under construction. That difference matters when arranging finance. If construction is complete, you’re generally seeking a loan to purchase the home. If you’re buying land and funding a build, the finance may also need to account for construction. Start by clarifying which pathway applies to you.

Buying a completed new home versus building from scratch

With a completed new home, the property is built and your loan is arranged for the purchase. If you’re building from scratch, you may need finance for the land and the building work, with funds released as the project progresses. The payment schedule and timing can affect how you plan your borrowing.

A house-and-land package combines the section and the home to be built. The land purchase and construction arrangements need to be considered together, but the details depend on how the package is structured and the lender’s assessment.

For example, one buyer might purchase a finished new home and arrange a home loan for settlement. Another might buy a section with a build contract, where construction finance could be relevant because the home is not yet complete. Both homes are new, but the finance discussion differs.

What a mortgage for a new build is designed to do

A home loan provides finance towards buying a property, with the property used as security for the lending. A home loan is commonly arranged to fund a purchase, while construction finance may be considered when building work and payments happen in stages. The right option depends on the purchase arrangement, project details and your finances.

Construction finance may involve a drawdown process, where loan funds are released in stages under agreed arrangements as the build progresses. Check how the funding schedule relates to the work and payments before settling on a loan structure. This overview of mortgage loan structures explains how security, interest and repayments can fit together. Your own lending terms depend on the lender’s assessment.

As you compare options, focus on what you’re buying, whether construction is part of the purchase and when funds may be needed. Mortgage Suite can help you consider these details across banks, private lenders and non-bank lenders, and negotiate on your behalf. A clear picture of your plans gives the lending discussion a practical starting point.

How New-Build Mortgages Work: Understand Stages, Drawdowns and Timing

When you’re building, finance may need to keep pace with the work rather than arrive in one lump sum. Before committing, understand how the project schedule, payment requests and lender’s funding arrangements fit together. This can help you plan ahead and spot potential timing issues.

The drawdown process is the staged release of construction-loan funds under the agreed lending arrangements. The process depends on the loan and project, including what progress information the lender needs before releasing each portion. Ask for the funding steps to be explained in plain English, including what needs to happen before each release.

How staged construction-loan funding works

In a staged build, work begins, reaches agreed points and continues towards completion. Funding may be released as those stages are reached rather than all at once. The loan arrangements set out how this works and what supporting information is needed for each release. Stage names, documents and timing can vary, so use the requirements for your own project rather than relying on another buyer’s experience.

Keep the build schedule and funding requirements side by side. If a payment is due before the lender has received the required progress update or other information, the timing may not work as planned. Check who is responsible for supplying each document and when it’s needed. This can help you plan cash flow and connect the finance steps to the build.

Why build timelines matter to your mortgage plans

A longer build can extend the time between arranging finance and reaching completion. Your income, commitments or other financial circumstances may change during that period, and a lender may need to reassess your application if relevant details change. An earlier lending discussion isn’t a promise that the same outcome will apply later.

Discuss timing early. Share the expected project schedule, when you anticipate needing funds and what you know about the build. If the schedule changes, update your finance plan rather than waiting until a payment is due. This won’t prevent every delay, but it can help you identify where a change in progress may affect the funding arrangements.

Keep a simple record of key dates, payment milestones, lender requirements and changes to the build plan. This gives you a useful reference when discussing the project and helps you see what needs attention next. When weighing up a mortgage for new build nz, consider how funding stages fit with your circumstances, not just the loan structure.

Mortgage Suite can help you compare construction lending pathways and negotiate with banks, private lenders and non-bank lenders on your behalf. The Mortgage School guides offer more plain-English information as you plan.

Compare New-Build Mortgage Options for Your Purchase Scenario

The finance pathway depends on what you’re buying and when the property or build will be ready. Use this comparison as a starting point, not a promise of eligibility. A lender will assess your circumstances alongside the property and the purchase or construction arrangements.

Purchase scenario Finance pathway to discuss What to consider
Completed new home A standard home loan may be relevant for purchasing a finished property. Consider the purchase and settlement details, your deposit position and the lender’s assessment of your application.
House-and-land package A standard home loan or construction finance may be relevant, depending on how the land and build are arranged. Clarify how the land purchase connects to the building agreement, when funding is needed and how progress payments are handled.
Build from scratch Construction finance may be relevant if funding is required as building work progresses. Consider the project plan, payment arrangements and information the lender needs as the build advances.

Standard home loan or construction finance?

A standard home loan generally funds the purchase of a completed property. Construction finance may be considered when the project is unfinished and funds are needed in stages. This distinction can shape how you plan payments and coordinate lending with the build. Neither option is automatically cheaper, quicker or easier to obtain. The fit depends on your application and project details.

If you’re building as an owner-builder, discuss your role, project plan and how the work will be managed with a mortgage adviser. The lender’s assessment may depend on those details, your financial position and the property being used as security.

Compare more than the headline rate

A lower advertised rate may catch your eye, but it doesn’t show whether the loan suits your plans. Compare the overall structure, when funds are available, how repayments are arranged and what flexibility you may need if the build schedule changes. Ask how the lending works during construction and what happens when the home is complete.

A fixed interest rate stays unchanged for an agreed period. Consider whether that arrangement suits your plans and how it fits with the timing and structure of the lending. Compare the full arrangement, not just the initial rate.

Read the Mortgage Rates NZ guide alongside this comparison for more on rates. If you’re considering a mortgage for new build nz, Mortgage Suite can compare pathways across banks, private lenders and non-bank lenders, then negotiate on your behalf. The aim is to find an option that suits your circumstances, while recognising that lenders may assess the project differently.

Mortgage for a New Build in NZ: Compare Your Options and Plan Your Next Steps

Prepare for a New-Build Mortgage: A Practical Buyer Checklist

Preparing a few key details can make a lending conversation more manageable. You don’t need every project detail finalised, but bringing together what you know helps an adviser understand your plans and discuss possible pathways. For a mortgage for new build nz buyers, explain the type of purchase and how far the project has progressed, as well as your financial position.

Information to organise before discussing your application

Pull together a snapshot of your household finances and the build. Include your income and regular income sources, existing loan or credit commitments, and your deposit position. Note your borrowing goal too: are you buying a completed home, purchasing land with a build, or constructing from scratch?

Gather any project information already available. Depending on your pathway, this may include a building contract, plans, project timeline, land purchase details and updates on the construction stage. Start with what you have. The aim is to give your adviser a practical picture, not to create a perfect file before asking questions.

  • Income: Record your income sources and any details that explain how you’re paid.
  • Commitments: List existing debts and regular financial obligations.
  • Deposit: Set out your current deposit position and where the funds are coming from.
  • Purchase pathway: Describe whether you’re buying a finished home, choosing a house-and-land package or building from scratch.
  • Project details: Collect available plans, contracts, timelines and updates on the build stage.

Questions to resolve before committing to the build

Map the expected payment stages against your household budget. Consider when funds may be needed, what other payments you’ll need to manage and how much room you have if the schedule changes. Drawdown arrangements and supporting information can vary, so discuss them alongside the construction plan rather than treating finance and building as separate issues.

Talk through what a timeline change could mean for your application. If the project takes longer or your circumstances change, a lender may reassess the application. An adviser can help you understand how the timing and your finances fit together, without assuming an earlier discussion guarantees a later lending decision.

For an initial view of repayments, Mortgage Suite’s mortgage calculator can help you explore affordability. Treat the result as a guide for planning, not a lending decision.

Bring your questions, even if some details are still taking shape. Mortgage Suite’s advice is free of charge with no obligation, and the team can help you compare options and negotiate with lenders. Explore your new-build finance options with Mortgage Suite.

Find a New-Build Mortgage Pathway That Fits Your Situation

Choosing finance for a new build involves more than the property or interest rate. Your purchase pathway, the timing of staged funding, the project details and your finances all help shape which options are worth considering. A mortgage for new build nz buyers can look different from one person to the next, so compare the choices against your own plans.

When a lender comparison may help

Lenders may assess the same borrower or project differently. Comparing banks, private lenders and non-bank lenders can show which lending channels may better fit your circumstances. Mortgage Suite can help with that comparison and negotiate on your behalf. You can also read Mortgage Suite client reviews to hear about other people’s experiences, while keeping in mind that every application is assessed on its own details.

Look beyond whether a lender is willing to consider the application. Think about how the proposed finance fits the property, build arrangements and your plans over time. If a mainstream bank has declined your application, it can feel disheartening, but it isn’t necessarily the end of your options. Other lending channels may be worth discussing, though no lender can be assumed to approve an application.

What happens when you ask Mortgage Suite for help

The first conversation is a chance to explain what you hope to buy or build, where the project stands and what matters to you financially. Talk through the documents you’ve gathered and any uncertainties about the finance or build timeline. This helps Mortgage Suite understand your goals and circumstances before comparing possible pathways.

Mortgage Suite works across banks, private lenders and non-bank lenders, acting as your advocate as lending options are considered. The team works to negotiate a suitable deal based on your situation and the project. This is support through the decision-making process, not a promise of approval. Your application remains subject to the lender’s assessment.

The advice is free of charge with no obligation, so you can discuss your plans and understand possible next steps without pressure. Bring your questions, even if the project details are still developing. A clear conversation can help you weigh the purchase pathway, funding arrangements and timing together before deciding how to proceed.

To compare a pathway that may suit your circumstances, discuss your new-build mortgage options with Mortgage Suite.

Take the Next Step With a Clear Plan

You don’t need every detail settled before exploring your options. Start with the question that feels most pressing, whether it’s how to structure your borrowing or how the project timing fits your plans. A focused conversation can help you decide what to clarify next as you consider a mortgage for new build nz.

Mortgage Suite was founded by Krish Krishna in 2000. The team can help you work through your new-build plans and consider a way forward that reflects your circumstances, without pressure to decide before you’re ready.

Talk with Mortgage Suite about your build plans and take the next step when you’re ready.

Frequently Asked Questions

Do I need pre-approval before choosing a new-build property?

Pre-approval can help you understand your borrowing position before committing, but it isn’t final loan approval. If you’re weighing up a completed home against a section with a build planned, discuss both possibilities early so the finance conversation reflects the purchase you’re considering. If the property, project or your circumstances change, the lender may reassess the application. Keep your adviser informed as your plans take shape.

Can I get a mortgage for a house-and-land package in New Zealand?

A house-and-land package may be financed, but the right pathway depends on how the land purchase and build are arranged. If you’re considering a mortgage for new build NZ, clarify whether the home is finished or still to be built, and how the agreement handles each part of the purchase. This gives your adviser useful context for the lending discussion. The lender will assess your circumstances and the project details.

How do lenders assess a mortgage application for a new build?

Lenders assess your financial position alongside the property and construction details. The information they consider can depend on the loan structure and how far the build has progressed. For example, someone discussing a home still at the planning stage may need to provide different project details from a buyer purchasing a completed home. Prepare an overview of your income, regular commitments and project information, then discuss what’s relevant to your situation.

What happens to a new-build mortgage if construction is delayed?

A construction delay may affect when you need funds and whether the finance plan still fits the project. The impact depends on your lending arrangements, the reason for the change and your circumstances. If the expected completion date moves, tell your lending adviser and lender promptly rather than assuming the original plan remains unchanged. They can explain whether the new timing affects your application or funding arrangements.

Can self-employed buyers apply for a mortgage for a new build?

Self-employed buyers can discuss a new-build mortgage, and each application is considered on its own information. Be ready to explain how you earn your income and how it supports your borrowing plans. If your income varies through the year, describing that pattern gives your adviser useful context alongside the project details. Lender requirements differ, so an adviser can help you explore options without promising approval.

Can I explore other lending options if a bank declines my new-build mortgage?

Yes. A bank’s decision doesn’t automatically mean there are no other pathways to discuss. Mortgage Suite works across banks, private lenders and non-bank lenders, whose assessments may differ depending on the lender and your application. Share the reason for the decline, any feedback you received and what has changed since you applied. An adviser can help you consider possible next steps, although each lender makes its own decision and approval isn’t guaranteed.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Getting a mortgage in your 50s in NZ: balancing repayments and retirement

Getting a mortgage in your 50s in NZ calls for a clear plan for when the loan will be paid off and whether repayments will stay manageable if your income changes. The key isn’t simply your age; it’s whether the loan fits your expected income, retirement plans and day-to-day budget.

It’s understandable to feel cautious about taking on a long-term commitment while also thinking about retirement. New Zealand retirements may last 25 or 30 years, so balancing mortgage payments with the life you want later deserves careful thought. This guide explains how to test repayments against possible income changes, weigh mortgage payments alongside retirement savings and consider ways to keep your options flexible. You’ll also find practical steps for working out what a comfortable loan could look like for your circumstances.

Key Takeaways

  • Assess when the mortgage could be paid off and whether repayments would remain manageable if your income changes.
  • Set a budget that balances mortgage payments with your retirement plans and everyday needs.
  • Consider how options such as downsizing or part-time work could affect your repayment plan.
  • Build flexibility into your approach so you can adapt as your circumstances and priorities change.
  • Plan for a retirement that may last 25 or 30 years, rather than focusing only on the first years after work.

1. Assessing mortgage repayment affordability as income changes

Taking on debt at 45 gives you a shorter available timeframe than borrowing at 30. For Kiwis getting a mortgage in their 50s in NZ, the key question is how repayments fit now and if income changes before the loan is cleared.

Compare borrowing in your 50s with borrowing in your 30s or 40s by looking at the time available to repay and your expected income. A borrower taking on more debt at 45 has a shorter timeframe than someone borrowing at 30. In your 50s, consider how a change in hours, work or retirement plans could affect each repayment.

New Zealand banks assess the proposed loan, repayment ability and plans for paying it down. There is no single mortgage term or maximum age figure that applies to every borrower; the lender considers the loan alongside your income and repayment plan. Ask how the term would affect repayments and the balance remaining as you approach retirement.

Banks may expect a plan for repaying the mortgage, but that plan doesn’t necessarily mean clearing it before retirement. Set out how repayments could continue if your income changes, and whether you expect to keep working, reduce hours or use another source of funds. People in their 50s and early 60s should assess when the mortgage is likely to be paid off and whether payments remain manageable if income shifts.

There is no single deposit amount for every New Zealand borrower in their 50s. The deposit needed depends on the property price, the amount borrowed, your available funds and the lender’s assessment. Work out how much you can contribute, then check the proposed loan against your budget and other commitments.

Mortgage rates and repayments depend on the lender’s current rate, loan amount, term and repayment frequency. Rates can change, so use the actual rate offered to estimate payments; Mortgage Suite’s mortgage calculator can help you explore repayment scenarios. Compare the effect of different terms, not just the first repayment amount.

Taking out a mortgage close to retirement can leave less room in your budget if income falls or costs rise. A longer repayment period may also mean carrying debt later in life. Test whether the payments would remain manageable without relying on full-time work.

To prepare an application, set a repayment budget and list your income, regular expenses and debts. Gather identification, evidence of income, bank statements, deposit details and property information. These records help show how the loan could fit your circumstances and support a clear discussion with the lender.

Many people in New Zealand do not stop working at age 65 and then spend the following 25-30 years simply living without further changes in priorities or needs. When testing affordability, consider how your work plans and spending priorities could evolve, rather than assuming today’s budget will stay unchanged. Check whether repayments would still fit if you reduced your hours or changed how you use your income, and revisit the plan if your circumstances shift. A repayment schedule that works now should also leave room to adapt as your needs change.

2. Balancing mortgage repayment with retirement savings

A mortgage and retirement savings both draw on the same household income. Start by listing essential costs, planned loan repayments and the amount you can set aside for later life. This gives you a clearer view of what remains for everyday spending. For someone in their 50s, the balance should reflect their expected retirement date and the mortgage’s likely finish date.

Build a retirement budget covering housing, food, transport, health needs and regular bills. Compare it with your expected income and any mortgage payments still due. If your budget relies on clearing the home loan, check that the repayment schedule supports that plan.

Try a simple monthly comparison. In one column, record your take-home income, essential spending, debt payments and retirement contributions. In a second version, reduce the income figure to reflect a possible move to part-time work. If the mortgage fits only the first version, consider a smaller loan, a different term or a repayment plan that leaves more room.

Don’t treat every spare dollar as mortgage money. Extra repayments can reduce the balance faster, but accessible savings can help cover an unexpected bill or temporary income gap. Decide how much readily available money your household needs before committing surplus cash to repayments. Review that decision when your work, health or family responsibilities change.

Compare three repayment approaches: the required payment only, a higher regular payment, and occasional extra payments when income allows. Record how each affects your monthly budget and the mortgage end date. Check how extra payments work under your loan terms before relying on them. Your plan should remain manageable in ordinary months, not just when income is higher.

Include less frequent expenses in your retirement budget, such as vehicle replacement, home maintenance and annual bills. Note when each is likely to fall, then set aside money regularly so it doesn’t unexpectedly compete with mortgage payments. A calendar of these expenses can reveal months when your usual repayment plan leaves too little room for other commitments.

Write down the decisions that shape your plan: the repayment amount you can sustain, the savings you want to protect and what would trigger a review. For example, a change in work hours could prompt you to update the household budget before increasing repayments. This turns a broad goal into practical steps and helps you adjust your mortgage plan as your priorities shift.

Considering downsizing, part-time work, or investment income

Alternatives to a standard mortgage for older homeowners can include borrowing less, selling and buying a smaller home, or continuing to earn work income for longer. Each changes the repayment picture differently. Downsizing may reduce the loan required, while part-time work may help cover payments without moving. Compare these options with your budget and plans.

Start with your home. Estimate what selling your current property could leave after paying off its mortgage and allowing for moving and purchase costs. Then compare the price and ongoing costs of a smaller property with those of your current home. A lower loan may mean lower repayments, but a new location could affect transport, support networks and access to services.

Part-time work can help support repayments if your retirement plans include paid work. Build a budget using the income you expect from those hours, then test it against a period when that work is unavailable. Don’t rely on the most optimistic version of your work plans to make the mortgage affordable.

Rental income may also contribute to household cash flow. If you own a property you could rent out, list the expected rent alongside ongoing expenses, including maintenance and regular bills. A vacancy or repair can reduce what remains for mortgage payments, so don’t count every dollar of rent as available to repay debt.

NZ Super, if applicable, and reliable rental income can form part of your repayment plan. Consider when each income source would begin, how regular it is and whether it is likely to continue. Lenders assess income and supporting evidence as part of the application, so keep records showing where the money comes from.

Before relying on an option, write down the steps and their timing. For downsizing, include the sale, purchase and move. For part-time work, set out the expected hours and income. For rental income, allow for periods without a tenant and property expenses. Comparing the options side by side can show whether one is enough or you need a combination.

A residential investment property loan may be relevant if you’re considering buying a property to rent out. Treat rent as one part of the plan, not a guaranteed source of repayments. Compare expected income with ownership costs and the mortgage payment, then consider whether your budget could cope if rent stopped temporarily.

Choose a fallback before committing to a repayment plan. You might reduce spending, increase work hours if possible, or reconsider the property if your income changes. Write down what would prompt a review, such as a change in employment or rental income. A clear trigger can help you respond early, before payments become difficult.

Getting a mortgage in your 50s in NZ: balancing repayments and retirement

4. Maintaining flexibility in later retirement

A flexible mortgage plan gives you room to respond as your needs change later in life. Start by identifying what could affect repayments, such as reduced work, a move or new household responsibilities. Decide which changes would prompt a review. For example, a change in regular income could be a reason to revisit your repayment amount and household budget.

Review the loan structure as well as the payment. A fixed interest rate stays unchanged for an agreed period, which can make repayments predictable during that time. Check what happens when the period ends and whether your budget could manage a different payment. Don’t build a plan around one rate staying in place indefinitely.

Keep a clear record of your mortgage balance, repayment amount and remaining term. Review these details alongside your current income and spending. If you’re paying extra, check the loan terms first. Some arrangements may limit when or how extra repayments can be made, so don’t assume surplus funds are always freely accessible.

Plan for changes to your housing needs. If stairs become difficult, for instance, you might consider moving to a more suitable property. Think through how a sale, a new purchase and any remaining mortgage would affect your monthly commitments. A home that works now may not suit your needs throughout retirement.

Keep flexibility in your wider budget, too. Separate essential bills from spending you could adjust if income changed. This makes it easier to see which costs could be reduced before missing a mortgage payment. Set aside time to review the figures after a change in work, housing or family circumstances.

At age 75, retirement drawdown strategies may need review. Use that milestone to reassess the mortgage alongside your income, housing needs and expected spending. Ask whether the existing repayment plan still fits, or whether a change in the loan or home should be considered. Treat the review as a practical checkpoint, not an assumption that your circumstances will follow a set path.

Write a simple action plan covering what you’ll monitor, what change would trigger a review and which options you could consider. For example, a fall in income might lead you to reassess spending before deciding whether to adjust repayments or housing plans. Writing down these steps makes them easier to revisit as your priorities evolve.

5. Preparing for retirement while paying a mortgage

Before retirement, make sure you understand how your mortgage works day to day. Keep the loan agreement and recent statements together, and note the repayment amount, payment dates and any conditions that affect changes. This gives you a clear reference when reviewing your plans with a partner or adviser.

Build a cash-flow plan around when income arrives and bills are due. Record regular income dates, mortgage payment dates and when larger household expenses fall. If a payment is due before income arrives, ask about adjusting the timing to make your budget easier to manage.

Check how your plan would work if an income source stopped or arrived later than expected. List essential payments first, then identify discretionary costs you could temporarily reduce. This helps you see what practical changes are available before a short-term disruption affects your ability to make mortgage payments.

Include the property itself in your retirement planning. Note upcoming maintenance, accessibility changes or repairs that could affect your household budget. For example, consider a planned bathroom upgrade alongside mortgage payments, rather than treating it as an unrelated future expense.

Keep a record of conversations and decisions about the loan. Note the date, who you spoke with, what you discussed and any agreed next steps. If your circumstances change, this record can help you explain the background clearly without relying on memory alone.

If you share the mortgage, agree how you’ll make decisions about repayments, spending and changes to the home. Write down who will manage routine payments and how you’ll discuss changes in income or household needs. A shared plan can reduce confusion during a stressful transition.

Revisit the plan after a major change, such as finishing work, moving home or taking on caring responsibilities. Update the figures and decide what action makes sense before changing repayments or making a large purchase. Keeping the plan practical and current can help you make considered choices as retirement approaches.

Consider how much your retirement plan depends on staying in the home, and whether that assumption still fits your expected income and needs. The 2025 Massey University Retirement Expenditure Guidelines note that future generations of New Zealand retirees are expected to have lower home-ownership levels. Treat this as a reason to examine your own housing arrangements rather than as a prediction of what will happen to you. Set out the likely costs of keeping the property, including mortgage payments and planned work, and compare them with the income you expect to have available. If the figures feel uncertain, identify what information you need before making a decision.

Discuss what you would do if staying in the home became difficult to afford or manage. Consider possible changes to your living arrangements, when you might make a decision and how each option could affect your budget. Don’t make a major commitment based only on an optimistic estimate of future income. Revisit your assumptions when your retirement plans or household circumstances change. If you share the home or mortgage, make sure everyone understands the options and has a chance to raise concerns. Including these questions alongside repayments and maintenance can help you weigh housing decisions against your wider retirement needs.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you assess home loan options when you are weighing a property purchase against retirement plans. The conversation can focus on your expected income, repayment comfort and the loan structure that fits your goals, rather than treating age as the only factor. If a mainstream bank has declined your application, that does not have to end the discussion; 2nd Tier Loans may suit borrowers who do not fit mainstream bank criteria.

Bring a clear picture of your income, regular commitments, deposit and plans for work or retirement. Mortgage Suite Ltd can help you consider these details and discuss suitable lending options, keeping the long-term repayment plan in view. Our advice is free of charge with no obligation. To talk through your circumstances, visit mortgagesuite.co.nz.

Make your next mortgage decision with confidence

A plan for getting a mortgage in your 50s in NZ should leave room for the life you want beyond the next repayment. Before taking your next step, write down the questions that matter most, such as how borrowing fits your priorities or what would prompt you to review your plans. A focused list can help you have a clearer conversation about your options.

Use the conversation to explore the options that fit your circumstances and the trade-offs involved. Take time to consider the information and decide what feels workable for you.

Discuss your borrowing plans and take the next step with a clearer sense of what matters to you.

Frequently Asked Questions

Can you get a mortgage in your 50s in New Zealand?

Yes, getting a mortgage in your 50s in New Zealand is possible; age alone doesn’t automatically rule you out. Lenders consider your income, debts, deposit and ability to manage repayments over the loan term. They may also look at how you plan to meet payments if your employment income changes. Presenting a clear picture of your finances helps show how the proposed borrowing fits your circumstances.

How do NZ lenders assess retirement income and mortgage affordability?

In NZ, lenders assess whether your expected income can cover repayments alongside regular household commitments. They may consider ongoing work income, NZ Super or rental income, and review evidence such as income records and bank statements. If you expect to reduce your working hours, for example, show how the resulting income fits your budget. Regular expenses and existing debts also affect how much room remains for mortgage payments.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage for a Tiny Home NZ: Costs, Rates and Land Rules

Owning land isn’t always essential to borrowing, but a movable tiny home can be harder to use as mortgage security. A mortgage for a tiny home in NZ may depend on whether you own land, have other assets to support the loan and can comfortably manage the repayments.

It’s understandable to feel unsure when a tiny home doesn’t fit the usual home-loan picture. The home’s design, where it will sit and what security you can offer all affect which finance options may suit.

This guide explains how land ownership and other assets may affect an application, how to set a repayment budget and where specialist finance may fit. You’ll get a clearer picture of what lenders assess and the practical details to prepare before deciding what to do next.

Key Takeaways

  • Land ownership isn’t the only factor in borrowing; the lender will also consider what security you can offer and how the tiny home is set up.
  • Build a repayment budget around your regular income and expenses, and test how it feels alongside your usual spending before committing.
  • Compare interest rates alongside repayment terms and loan structure, as specialist finance can work differently from a standard home loan.
  • Clarify who owns the land and how the tiny home will be placed there, as these details can affect the finance assessment.
  • If mainstream lending doesn’t suit your situation, specialist finance may be another avenue to explore.

Do I need to own land or other assets?

Owning the section beneath a tiny home can strengthen a borrowing application, but it isn’t the only possible security. A lender may also consider other property you own and how the home is attached to its site.

Using land or property as security

Security is property a lender can rely on if a borrower can’t repay a loan. For a tiny-home application, land or another property may provide stronger security than the home alone, particularly if the home can be moved.

Consider a house-and-land valuation of NZ$800,000. In this example, banks might lend 80% or even 90% of the combined valuation, depending on the application. That example concerns land and a house together, not a promise that a tiny home will be assessed the same way.

If you own a section, the lender can assess its value alongside the proposed home and your ability to make repayments. If you don’t own land, another property may be relevant security. The key question is what property supports the loan, not whether the tiny home looks like a conventional house.

Before applying, list what you own and how it relates to your tiny-home plans. For example, distinguish land you own from a site where you have permission to place the home. This helps show what security is available and clarifies the arrangement behind the application.

Assessing fixed and movable tiny homes

A tiny home fixed to land may be assessed together with the land, while a movable home may be considered separately. This matters because a home that can be moved may be harder for a lender to rely on as security.

A tiny home on wheels doesn’t automatically qualify for a standard home loan as a house secured by land. A lender may instead assess land or another property offered as security, alongside your ability to make repayments.

For a fixed home, explain how it is attached to the site and what land supports the application. For a movable home, describe where it will be kept and whether you own that land. These details help clarify what the lender could assess if you can’t repay.

Consider the whole arrangement, not just the build. A home on wheels placed on a section you own presents a different security picture from one parked on land you don’t own. If a bank mortgage isn’t suited to the movable home itself, other property may still be relevant to the lending discussion.

Land ownership can help, but it isn’t the only factor. A lender weighs the security available, whether the tiny home is fixed or movable, and whether the repayments fit your finances.

Budgeting for loan repayments

A repayment figure tells only part of the story. Your budget also needs to cover regular household spending, tiny-home upkeep and the income left after bills. Mapping out your monthly finances helps you judge whether a loan fits daily life, not just a lender’s assessment.

There’s no single repayment amount that suits every tiny-home loan. Repayments depend on the amount borrowed, the interest rate and the loan term. Changing any of these can alter what you need to set aside, so compare scenarios rather than relying on one estimate.

Start with your bank statements and record your regular income and outgoings. Include housing, food, transport, power, phone bills and existing debt repayments. Then add expenses linked to your plans, such as site charges or travel to work, if they apply.

  • Separate essentials from flexible spending: Identify bills you must pay and spending you could adjust.
  • Include irregular bills: Set money aside throughout the year for annual or occasional payments.
  • Allow for changes: Consider how your budget would cope if household income fell or another bill increased.
  • Compare scenarios: Test how a different borrowing amount or loan term changes the repayment.

Next, try living with the expected finance payment for at least 3 months before taking on the loan. Move that amount into a separate account on each payday, as though repayments have already started. Keep paying your usual bills from what remains. This practical test shows whether the planned payment leaves room for essentials and everyday needs.

If you need to transfer money back to cover groceries or transport, your repayment plan may be too tight. If you test a budget over time, look for missed bills, dipping into savings or relying on credit. These patterns can reveal pressure points. You may need to adjust the amount you plan to borrow or the timing of your purchase.

A repayment calculator can help you compare scenarios using different borrowing amounts, rates and terms. The mortgage calculator can help show how changing the amount borrowed affects repayments. Compare any result with your written budget and the three-month payment trial before deciding what feels manageable for your household.

An example tiny home finance repayment in New Zealand is $2,221 per month. Treat it as an illustration, not a figure that will necessarily match your borrowing or household budget. Your own estimate should reflect the amount you need, the available loan terms and your regular costs. Check that the repayment leaves enough room for essentials and unexpected expenses, and revisit your budget if your income or spending changes.

What are the interest rates?

Specialist tiny-home finance in New Zealand may have interest rates from 9.99% p.a. Lending criteria and affordability affect the rate available, so treat that figure as a starting point, not a universal offer. A rate alone doesn’t show whether a loan fits your plans. The repayment amount, loan term and conditions also shape the overall commitment.

Compare the loan structure as well as the headline rate. A fixed interest rate stays unchanged for an agreed period, making repayments more predictable during that time. Other structures work differently. Ask how the rate applies, when it can change and how the repayment schedule would affect your budget.

For a fair comparison, line up offers using the same borrowing amount and repayment period. Then check:

  • Interest rate: Note whether the quoted rate is fixed or can change.
  • Repayment schedule: Understand how often payments are due and how long they continue.
  • Loan conditions: Read the terms alongside the rate, including any requirements attached to the finance.
  • Affordability: Compare the proposed payment with your household budget, not just another lender’s rate.

A lower rate can look appealing, but it may not suit you if the loan structure doesn’t match your plans. For example, consider whether repayments remain manageable alongside your regular bills and tiny-home expenses. Comparing the rate, term and repayments together gives you a more useful basis for deciding.

Approval timing depends on the lender receiving the information needed to assess the application. Tiny-home finance approvals in New Zealand are often available within 24 hours after the lender has all the information. That timeframe begins once the application details are complete; preparing clear information about your income, existing commitments, the home and its intended location helps the assessment proceed.

Keep your application details consistent. If your purchase or build plans change, update the information provided, as the lender assesses the application presented. A prompt decision is useful, but speed shouldn’t replace a careful review of repayments and loan terms.

Before accepting an offer, write down the rate, how long it applies, the repayment schedule and the conditions. Compare these details with your budget and the home’s intended use. This helps you assess the whole borrowing arrangement rather than choosing on the interest rate alone.

Mortgage for a Tiny Home NZ: Costs, Rates and Land Rules

Land ownership requirements

Owning the land isn’t automatically a requirement for every tiny-home finance application. In New Zealand, the land arrangement still matters because it shows where the home will sit and what property may support the borrowing.

Separate three parts of your plan: owning a section, having an arrangement to place a home there, and offering land as loan security. These are distinct. You might own the tiny home but not the site, or own both the home and section. Each arrangement gives a lender different information to assess.

If you own the land, gather details showing who owns it and how the tiny home will be placed. If someone else owns the site, explain the arrangement and how long you expect to use it. A lender needs to understand whether the home’s location is stable and how the land relates to the borrowing. Details about site access, services and planned use can also help explain the setup.

Prepare these details before discussing finance:

  • Land ownership: Record whether the section is yours, jointly owned or owned by someone else.
  • Placement arrangement: Explain where the tiny home will sit and what agreement supports that plan.
  • Home setup: Describe whether it will be fixed in place or remain movable.
  • Security: Identify whether the land or another property is being offered to support the loan.

For example, you might own a section and plan to place a movable tiny home there. That doesn’t make the home and land the same asset. Explain each separately, including who owns them and how they’re connected. If the home will sit on a family member’s land, describe that arrangement clearly rather than presenting the site as your own property.

Land ownership can affect what a lender considers as security. A section you own may be assessed differently from land you can use but don’t own. The lender considers the available property, the tiny home’s placement and your ability to repay. Clear information helps distinguish the home’s location from property that can support the borrowing.

Before committing, compare the land arrangement with the loan structure you’re considering. If you’re buying land and a tiny home together, explain both parts of the purchase. If you already own a section, outline how the proposed home will fit the site. Clear details about ownership, placement and security help frame the application around your actual plans.

Specialist tiny home finance

Specialist finance can be another option when a tiny home doesn’t fit a standard mortgage. The loan type, security and repayment plan still need to suit your circumstances.

Lender eligibility criteria

Eligibility criteria are the lender’s requirements for deciding whether an application and its security fit a loan. Specialist lenders in New Zealand may consider tiny-home finance, but their criteria vary. There isn’t one lender list or rule that applies to every borrower.

Lenders assess factors such as income, existing commitments, repayment capacity, the home’s value and whether it can be moved. These factors shape possible loan terms, but they don’t determine an automatic approval amount or term.

A strong application explains the full arrangement: who owns the home, where it will sit, what security is available and how repayments fit your budget. If a mainstream bank declines, that doesn’t settle whether another lender’s criteria may suit your circumstances.

Mortgage eligibility for tiny homes

A mortgage may be possible, but the lender’s assessment depends on the tiny home, the land arrangement, available security and your ability to repay. A home on wheels may be treated differently from one fixed to land, so describe its setup clearly.

Planning and building requirements depend on the site and proposed home. Before committing, identify the relevant local council and ask how its planning rules, building consent process and site requirements apply to your proposal. Don’t assume a tiny home has the same requirements on every section.

There isn’t one total cost for every tiny-home project. Your overall budget depends on the home, land, site preparation and connections such as power or water. List each part separately, then compare the project budget with the borrowing you can manage.

Lenders may also consider whether the home can be valued as security and how readily it could be resold. A movable home’s location, condition and saleability can affect its usefulness as security. Include clear details about the home and site in your finance information.

Application steps and documents

An application brings together your financial position and tiny-home plans, helping a lender assess your repayment ability and available security. Prepare proof of income, a record of regular commitments, details of the home and a clear account of where it will be placed.

Include purchase or build information, the proposed site, land ownership details and any documents describing the placement arrangement. If you own other property, note whether it may support the borrowing. Keep the figures and project details consistent across your budget and application.

Before applying, organise these records and identify any missing project details. Then compare the lender’s proposed amount, term, repayments and conditions against your budget. For help exploring a finance path that fits your circumstances, discuss tiny-home finance options.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite can help you explore home-loan options, including Home Loans to First Home Buyers, when a tiny-home purchase forms part of your first-home plans. If a mainstream bank’s criteria don’t fit your circumstances, its 2nd Tier Loans may offer another lending pathway to discuss.

Bring together your income details, regular commitments, tiny-home plans and information about the land or other security. Mortgage Suite can help you consider how these factors fit together and discuss a suitable next step, without treating one lender’s decision as the final word.

If you’re a first-home buyer considering a tiny home, contact Mortgage Suite to discuss your borrowing situation and possible options.

Take the next step with a clear borrowing plan

Your tiny-home plans don’t have to follow a standard property path. Shape the finance conversation around your goals, how you’ll use the home and what you can comfortably repay. This gives you a clearer basis for deciding whether a mortgage for a tiny home in NZ suits your wider plans.

Mortgage Suite can help you talk through your circumstances and consider which lending pathway may fit. If a mainstream bank’s criteria don’t suit your situation, that doesn’t necessarily end the conversation. The next step is to look at your plans and finances together.

Before getting in touch, bring together an outline of your plans, income and regular commitments. You don’t need every detail sorted to start a useful conversation. A clear starting point can help you work out what to explore next.

Contact Mortgage Suite about your options and take a confident next step towards your tiny-home plans.

Frequently Asked Questions

How much can I get?

There’s no single borrowing amount for a mortgage for a tiny home in NZ. The amount a lender may offer depends on your income, existing commitments, repayment capacity and available security. Separate your borrowing goal from the full project budget, then work out how you’d fund any gap.

What financing options are out there?

For a mortgage for a tiny home in NZ, options may include a home loan supported by land or other property, or specialist finance for tiny homes. The suitable path depends on whether the home is fixed or movable, what security you can offer and how you plan to repay. Buying a tiny home and land together creates a different borrowing structure from purchasing a wheeled home without owning the site.

Can first-home support help fund a tiny home in NZ?

First-home support has its own eligibility rules, and whether it can contribute depends on the buyer and property arrangement. A wheeled tiny home, a home fixed to land and a land-and-home purchase may be treated differently. Keep your borrowing plan workable without relying on support until you know it applies to your purchase. Include any eligible assistance separately in your deposit plan, not as guaranteed funding.

What insurance, valuation, and resale risks affect tiny-home finance in NZ?

A movable tiny home can be harder for a lender to rely on as security and may be assessed separately from the land. The lender may assess the land or another property as security, alongside your ability to repay.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage approval with bad credit in NZ: what lenders assess

Bad credit doesn’t automatically prevent a mortgage application in New Zealand. For mortgage approval with bad credit in NZ, lenders assess your full application, including whether the borrowing fits your financial position. A past credit issue matters, but it is not the whole story.

If you’ve been declined or feel uneasy about applying, it’s natural to wonder whether trying again is worthwhile. The uncertainty can feel heavy, especially when buying a home matters to you. Understanding how lenders assess applications can help you decide what to prepare and which questions to ask.

This guide explains the factors lenders consider and practical ways to present your circumstances clearly. You’ll learn how to prepare for a lender’s review, weigh your options and choose a sensible next step. The aim is to help you approach the process with confidence, without treating a credit setback as a personal judgement or assuming the outcome in advance.

Key Takeaways

  • Lenders assess whether your income can cover regular expenses, existing debt and likely mortgage repayments, not just your credit history.
  • A paid, older default may be viewed differently from a recent unpaid one, so explain the circumstances and show how your finances have changed.
  • Your property’s assessed value and the equity available can affect how a lender views the application and the security for the loan.
  • Review your credit report for errors, avoid unnecessary credit applications and organise clear records of your income and spending.
  • A decline from a mainstream bank doesn’t automatically close off other options; different lenders have different criteria for home loans.

Income, expenses and existing debt

A lender compares your income with regular spending and debt repayments to assess how much room remains for a mortgage. The aim is to understand your household budget, not just your salary. For example, two applicants with similar incomes may have different borrowing capacity if one supports dependants or has higher regular commitments.

Show where your income comes from and how reliably it arrives. Employed applicants can organise payslips and employment details. If you earn through contracting or self-employment, gather business and tax records that show your income pattern across the year. A seasonal earner, for example, can distinguish a busy period from quieter months, helping the lender understand typical income rather than an unusually strong week.

Build a realistic record of household spending before applying. Include regular essentials such as housing, power, food, transport and childcare, as well as subscriptions and other recurring payments. Compare your bank statements with your budget. If your records show a sports fee or childcare payment you left out, update the budget rather than relying on an estimate that understates your commitments.

List every current credit commitment, including personal loans, vehicle finance, credit cards, overdrafts and buy-now-pay-later accounts. Record each balance, repayment and remaining term. A credit card limit can matter even if you usually pay the balance in full, so include the facility, not just the amount currently owed. If you’ve recently cleared a loan, note the change and keep evidence of its status.

The Reserve Bank’s current Loan-to-Value and DTI restrictions apply to banks’ residential lending in New Zealand. These restrictions sit alongside a bank’s assessment of your income and expenses. A serviceability stress test assesses hypothetical repayments at a higher interest rate to test future affordability. It considers how the proposed repayments fit your budget under that assessment.

Before applying, prepare a simple monthly budget and compare it with your account activity. Highlight variable income, one-off expenses and debts nearing repayment. If you’re already struggling to meet mortgage payments, contact your lender as early as possible. A clear summary of what you can afford and where you’re under pressure gives the lender useful context for discussing your position.

Lender assessment of credit history and defaults

For a bad-credit application, prepare identification, income evidence, bank statements, debt details and records showing the status of any default. How long negative information remains on a New Zealand credit report depends on the type of entry and reporting rules.

Lender options for bad-credit borrowers

Mainstream banks and non-bank lenders assess home loan applications against their own criteria. A decline from one bank doesn’t automatically mean every lender will reach the same decision. A lender may look closely at the cause of a default, whether it has been paid, your recent repayment history and the strength of the rest of your application.

A paid, older default may be assessed differently from a recent unpaid default. Recent or ongoing missed mortgage payments can make an application harder to assess. Explain clearly what happened, when you resolved it and what has changed since. Where applicable, include a payment record or other evidence that the default is settled.

Non-bank or specialist lending may provide another route when a mainstream bank’s criteria don’t fit your circumstances. Read the proposed loan terms carefully, including the interest rate, fees, repayment schedule and any conditions. Consider whether repayments remain manageable and how the loan fits your longer-term plans. A mortgage broker can present an application, but the lender makes the final decision after assessing it.

How long negative credit information remains

There isn’t one timeframe for every type of negative entry on a New Zealand credit report. The entry type and reporting rules affect how long information remains visible, while lenders may weigh an older paid default differently from a recent unpaid one. Don’t assume an old entry has disappeared; review your report before applying.

If you believe an entry on your credit report is wrong, contact the relevant credit reporting provider to query it. Gather supporting documents, such as proof of payment or correspondence about the debt. If the information is accurate, prepare a straightforward explanation and show how you’ve managed credit since the event. This gives the lender context instead of leaving a negative entry unexplained.

Organise your application documents into clear groups: identity, income, regular spending, current debts and credit history. Include a short timeline for each default, covering the original issue, any repayment arrangement and its current status. If circumstances contributed to missed payments, explain them plainly and show what has changed. Consistent records help the lender compare your explanation with the information in your application.

With specialist lending, consider the whole arrangement, not only whether an application can proceed. Check how repayments are structured, whether the terms suit your income pattern and what could happen if your circumstances change. Make sure you understand all fees and conditions before committing. Comparing proposed repayments with your household budget can help you judge whether the loan is sustainable.

Property value and home equity

There isn’t one deposit amount that suits every bad-credit home loan application. The deposit depends on the property value, the amount borrowed and the lender’s assessment of your application. A larger contribution can reduce the amount you need to borrow, but lenders also consider whether repayments fit your finances and how your credit history affects the application.

The property matters because it secures the mortgage. The lender considers its value alongside the loan amount, rather than relying only on the price you hope to pay. If the lender’s valuation is below the purchase price, you may need to reconsider your contribution or the property you’re considering.

Home equity is the property’s value minus the debt secured against it. For example, a New Zealand property worth NZ$800,000 with a NZ$500,000 mortgage has approximately NZ$300,000 in equity before other costs or secured debts. This is an estimate, not necessarily money you can freely use for another purpose.

Other lending secured against the property can reduce the equity available. If you’re relying on an existing home, list each secured debt and use current balances, not the original loan amounts. For example, a separate loan secured against the same property must be considered alongside the mortgage when assessing the overall position.

A lender’s valuation can differ from your estimate. The property’s condition, features and sale evidence may affect its assessed value. If the valuation is lower than expected, you may need to adjust the loan request. That can affect the deposit you need to contribute, so leave room to revisit your figures before committing to a purchase.

The Reserve Bank’s current Loan-to-Value restrictions apply to banks’ residential lending in New Zealand. These restrictions limit how much a bank can lend compared with a property’s value. They form one part of the assessment, alongside the bank’s own criteria and your financial position. Non-bank lenders assess applications under their own criteria.

Before applying, write down the property’s estimated value, proposed mortgage, deposit or available equity, and any debts secured against the property. Keep the figures separate and identify which funds are available for the purchase. If your credit history includes a default, explain it accurately. Equity can support the security assessment, but it doesn’t replace the lender’s review of your finances.

Mortgage approval with bad credit in NZ: what lenders assess

Steps to improve a mortgage application

A clear application helps lenders understand your finances and credit history. Focus on accurate records, manageable debt and a straightforward explanation of past issues.

Strengthening a mortgage application

Strengthening an application means making your financial position easier to assess before you apply. Complete, consistent information helps a lender understand your current repayment habits alongside earlier credit problems.

  • Avoid unnecessary credit applications, which can add new enquiries to your credit history.
  • Pay existing bills and debt repayments on time, and keep records showing your payment history.
  • List every debt and credit facility accurately, including balances and repayment commitments.
  • Explain any default clearly, including whether it has been paid and what changed afterwards.

Check that your application, bank statements and supporting documents tell the same story. If you’ve cleared a debt, for example, include evidence of its current status rather than relying on memory. If your income or spending has changed, explain when and why. A short, factual explanation is more useful than leaving a lender to interpret a gap or mismatch.

Review your recent account activity before applying. Regular unarranged overdraft use or missed payments may prompt questions about how you manage repayments. Avoid taking on new debt while preparing your application, and keep your spending records up to date. These steps won’t erase past credit events, but they can show how you manage your finances now.

Checking and correcting a credit report

Reviewing your credit report means checking the information held about your borrowing and repayment history. Before applying, look for errors, unfamiliar accounts and debts recorded with the wrong status. If you believe an entry is incorrect, contact the relevant credit reporting provider to query it.

Compare each entry with your records, such as account statements, payment confirmations and correspondence about a debt. Note the creditor, account details and what you believe is wrong. Send the provider evidence supporting your query, and keep copies of your request and any response.

If the entry is accurate, prepare a brief explanation for the lender rather than disputing it. Include the circumstances, whether the debt has been paid and any steps taken to prevent a repeat. For example, explain how a repayment arrangement brought an overdue account up to date, if applicable. Keep your explanation consistent with the dates and documents in your application.

After reviewing your report, update your application documents to reflect any corrected information. Keep the provider’s response with your records so you can explain a change if the lender asks about it. Avoid applying for several new credit facilities while you prepare. A tidy, consistent file gives a clearer picture of your current position.

Which New Zealand banks and non-bank lenders offer home loans to borrowers with bad credit?

There isn’t one fixed list of New Zealand lenders that accepts every bad-credit application. Banks and non-bank lenders assess applications using their own criteria, so the decision depends on your full financial picture, not just the type of lender.

A mainstream bank may assess your income, debts, credit history, deposit and property security together. If one bank declines, that doesn’t automatically determine how another lender will view your circumstances. For example, an older paid default and a recent unpaid default may be assessed differently.

Non-bank lenders may be another option when a bank’s criteria don’t suit your application. They still assess whether repayments are manageable and whether the property supports the lending. Their criteria and loan terms can differ, so compare the whole arrangement rather than focusing only on whether an application can proceed.

Before approaching a lender, organise a clear summary of:

  • Your income sources and regular household spending.
  • Every current debt, repayment and credit facility.
  • Any default, including its status and what has changed since.
  • The property value, deposit or available equity.

This helps show how your current position addresses the concerns behind an earlier decline. If the issue was a default, include evidence of payment where relevant. If existing debt affected affordability, show the current balances and repayments. The lender can then assess your application against its criteria using up-to-date information.

Compare the proposed interest rate, fees, repayment structure and loan conditions. A lower advertised rate doesn’t necessarily mean refinancing will reduce the overall cost. Refinancing expenses can include interest, loan fees, legal costs, valuation costs and break costs on an existing fixed-rate loan. Include these in your comparison before deciding whether a new loan suits your plans.

A non-bank or specialist loan may have different terms from a mainstream bank’s offer. Read the repayment schedule and conditions, and consider whether payments remain manageable if your income or expenses change. A repayment that fits today’s budget, for example, may feel different after a change in work hours or household costs.

To narrow your options, prepare one complete, accurate application rather than making unnecessary credit applications to several lenders. Explain the reason for the credit issue, what has improved and how the proposed repayments fit your budget. Different criteria may offer another route, but each lender makes its own assessment.

Mainstream banks and non-bank lenders may both consider home loan applications from borrowers with bad credit. Which lender may suit you depends on its criteria and your full financial picture.

Mortgage Suite: Home Loans to First Home Buyers

Mortgage Suite Ltd can help you explore Home Loans to First Home Buyers if your credit history has made the next step feel uncertain. A mainstream bank’s decision isn’t the whole picture: your income, debts, deposit and property plans all help shape an application.

Bring together your credit report, details of any defaults, income records and a clear summary of your current debts. Mortgage Suite Ltd can help you understand how these pieces fit together and discuss home loan options suited to your circumstances. The aim is to clarify your position and help you consider the lending structure, repayments and longer-term plans, rather than focusing on one headline rate.

If you’re ready to discuss your first-home application, contact Mortgage Suite Ltd to talk through your next steps.

Take your next step with a clear plan

A credit setback can make planning a home purchase feel daunting, but it doesn’t define every future lending conversation. Use your next step to understand what a lender may need to see and whether your plans fit your current financial position.

For mortgage approval with bad credit in NZ, focus on presenting your circumstances clearly and choosing a loan structure that remains workable over time. Mortgage Suite Ltd can discuss Home Loans to First Home Buyers, Residential Investment property loans and Business Loans, depending on the purpose of your borrowing.

A lender makes the final decision after assessing your application, so approval isn’t guaranteed. A thoughtful conversation can still help you identify what to prepare and which questions matter for your next move.

Contact Mortgage Suite Ltd to discuss your borrowing plans and take the next step with a clearer picture of your options.

Frequently Asked Questions

Can you get mortgage approval in New Zealand with bad credit?

Yes, it may be possible, because lenders assess applications using their own criteria and consider more than a credit entry. They may weigh the type and status of the issue alongside your current finances and the property securing the loan. A recent unpaid default differs from an older paid one. The lender makes the final decision after reviewing your application, so approval isn’t assured.

What credit score do NZ mortgage lenders require?

There isn’t one credit-score number that guarantees mortgage approval in New Zealand. Lenders use their own criteria, and a score is only one part of the information they may consider. They also assess the details behind negative entries, your current financial position and the property. If you’re unsure what appears on your file, review your credit report before applying and query any information you believe is incorrect.

How do missed payments, defaults, debt collection, and bankruptcy affect a NZ mortgage application?

Missed mortgage payments, defaults, collection activity and bankruptcy can all prompt closer scrutiny of your credit history. Recent or ongoing missed mortgage payments can make refinancing more difficult. A lender may assess an older paid default differently from a recent unpaid one. For debt collection or bankruptcy, be ready to explain the circumstances and provide accurate records of the current status. Don’t leave unresolved entries unexplained.

How can you improve your chances of mortgage approval with bad credit in New Zealand?

Prepare before applying: review your credit report, query any incorrect entry with the relevant reporting provider and avoid unnecessary credit applications. Make sure your explanation of past problems matches the dates and status in your documents. If your situation has changed, describe how, such as a debt being paid or income becoming more consistent. A complete, accurate application helps lenders assess your current position.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.