First home buyer loans NZ: 2026 deposit rules and cash-back offers

You can buy your first home in New Zealand under 2026 deposit rules with as little as 10% equity in many cases, or 5% on qualifying New Builds, and still chase lender cash-back where the offer fits your term. Working around current lending rules helps you secure government support and lender cash incentives without wasting months on the wrong pathway. We can help you get sorted with a lender that fits your goals.

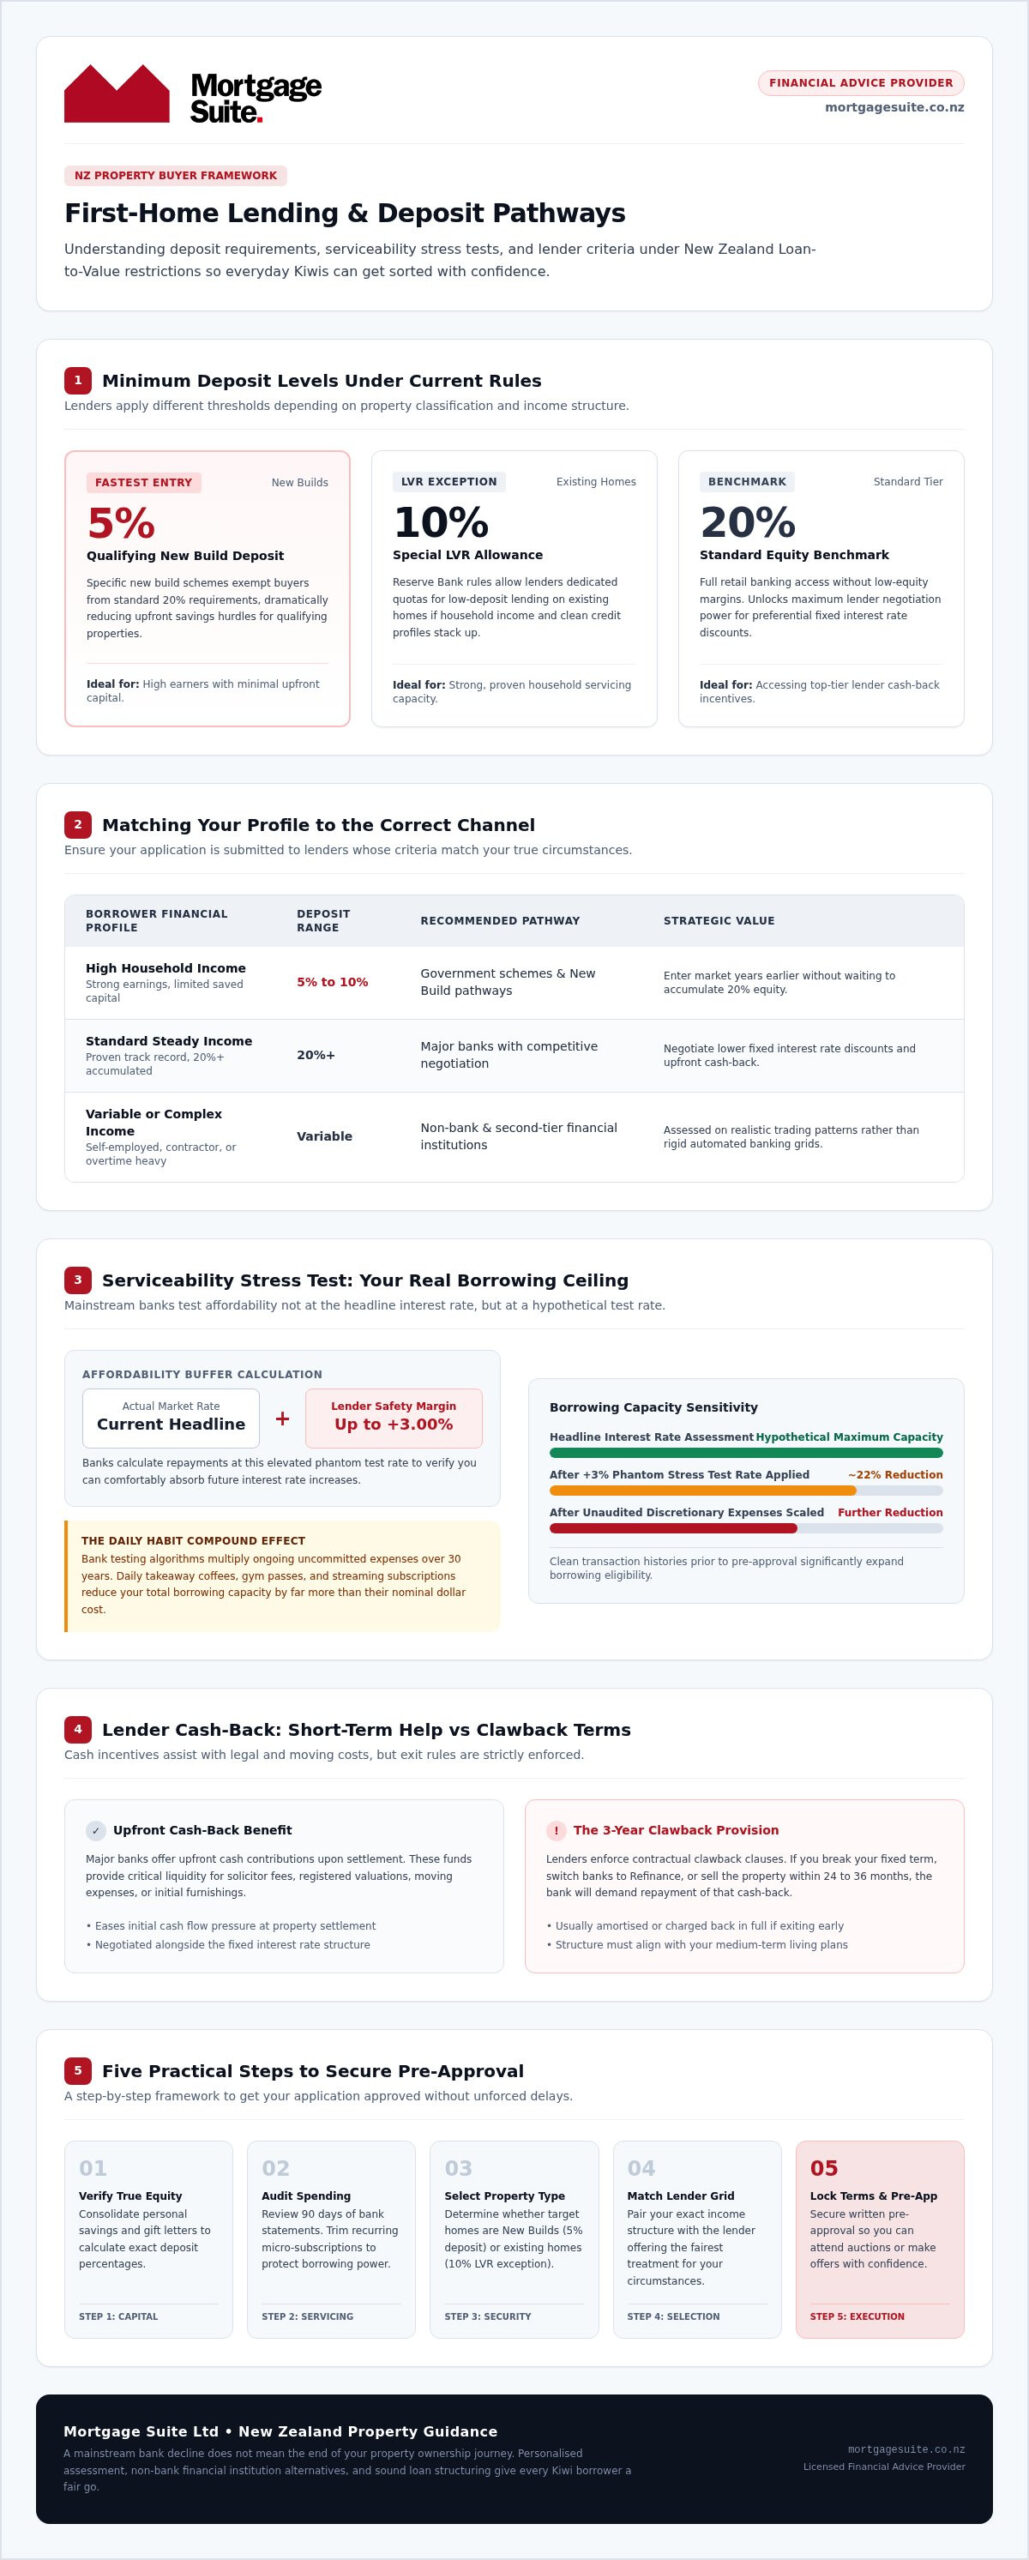
Key Takeaways: You can secure first home buyer loans in NZ with a 5% deposit for new builds or 10% for existing properties under LVR exceptions.

  • Lenders apply stress tests using phantom interest rates up to 3% above current market rates.
  • Unless you maintain your fixed term, banks strictly enforce clawback provisions on cash-back incentives.
  • Best-for high earners to target 5% to 10% deposit schemes rather than waiting for 20%.
  • Bank calculators treat daily coffee or streaming subscriptions as significant reductions to total borrowing capacity.

Match your deposit and income to the right first-home path

Your path to property depends on deposit size and household income, so match both to the right lender before you lodge a full file. With clients we see that pairing deposit level to lender early saves weeks of frustration: banks strictly review income, while alternative lenders offer more flexibility on complex files.

Three situations come up often:

  • High income with a smaller deposit: apply for low-deposit government or New Build pathways (5%-10%) rather than waiting for 20%.
  • Steady standard income with 20%+ saved: negotiate a locked-in interest rate (fixed interest rate) and compare cash-back against the rate.
  • Complex or variable income: explore non-bank and 2nd tier lending so serviceability is judged on real patterns, not a single rigid grid.

Kiwis with strong earnings can secure a First Home Loan with a 10% deposit under Loan-to-Value restrictions. If your bank says no, switching banks later (Refinance) remains an option once equity grows. You get sorted faster when the strategy fits the file you actually have.

Financial Profile Deposit Level Immediate Next Step
High Income 5% to 10% Apply for low deposit government schemes
Standard Income 20%+ Negotiate a locked-in interest rate
Complex Income Variable Explore non-bank lending options

You deserve a fair go on whichever row matches your life right now.

Yes, you can buy with a 10% deposit under LVR rules

Yes, you can secure a property with a 10% deposit under Loan-to-Value restrictions, provided you meet standard bank affordability criteria. Local rules allow Reserve Bank Loan-to-Value restrictions to include special low-deposit exceptions for buyers, so mainstream bank grids can feel rigid while usable options still sit beside them.

Think of these central bank rules like a nightclub door policy: most guests need a standard entry pass, yet venue security keeps dedicated spots open for specific buyers. For first-home buyers, some specific “New Build” schemes let you get started with as little as a 5% deposit. That is a separate pathway from a standard 20% existing-home purchase, and from the 10% LVR exceptions used when income and credit stack up cleanly.

Saving large reserves is tough when rent and living costs already claim most of the month. Working alongside our team through the first-home buyers guide gives you a fair go when negotiating with lenders. We act as your dedicated advocate so you get sorted without unnecessary stress.

Tip: Check if your prospective property qualifies as a New Build to immediately slash your deposit requirement to 5%.

Stress tests set your real borrowing limit, not the sticker rate

Banks set your home loan limit with a serviceability stress test that checks whether repayments stay affordable if interest rates rise. From client work we see that bank calculators often apply phantom interest rates up to three percent above actual market rates. That testing margin protects both you and the lender from future shocks.

A detail many buyers miss: those test rates also scale up routine daily expenses, which cuts borrowing capacity harder than the cash spent suggests. A daily coffee run or streaming subscription reduces total borrowing power by more than the nominal amount leaving your account. Kiwis often get declined by mainstream lenders simply because the formulas treat tight budgets harshly.

Presenting income and expenses clearly changes the outcome. Working with first-home buyer advisers helps you show actual income so you get sorted with a fair go rather than a blunt decline letter.

Cash-back helps upfront costs if you can hold the fixed term

Our direct professional experience shows that financial institutions rely on clawback provisions to retrieve money if you exit early, and lenders enforce those rules strictly.

You must keep your locked-in interest rate for the set term to avoid paying the funds back. If you switch banks later within three years, the bank can take that cash right back. Our team acts as your personal advocate to negotiate fair terms, and you can read more on options for Kiwis in the first-home buyer articles.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Working with an experienced adviser across multiple purchases keeps your long-term finance structure steadier against strict clawback terms. Ask us to line up the cash-back against the rate and the clawback window before you sign.

2026 Government first-home criteria hinge on income and caps

Government criteria for first-home support depend on household income, regional house caps, and total personal assets. Mainstream banks enforce those limits tightly, yet missing one grant does not end your property goals. In professional practice, applying with a 10% deposit under Loan-to-Value restrictions through a non-bank financial institution often gives more practical flexibility than waiting years to fit rigid government boxes.

From client work, buyers often get turned down by big lenders simply because earnings sit slightly over a threshold, and that outcome usually causes unnecessary panic. As detailed on the Inland Revenue Department 2026 KiwiSaver guide, special withdrawal rules apply when buying your initial home. Think of government grants as a narrow gateway, while tailored lending acts as a wide, accessible driveway.

Mortgage Suite Ltd works as your dedicated negotiator to secure a fair go when the first door closes. If mainstream banks say no, we look for answers on 2nd tier and non-bank paths. Reach out for a friendly, confidential chat to review where you sit against 2026 criteria.
First home buyer loans NZ: 2026 deposit rules and cash-back offers

When a low-deposit home loan costs you more than it saves

A 10% deposit under Loan-to-Value restrictions can backfire when your monthly budget has no room for unexpected expenses. From client work we see that buying with minimal equity creates real pressure: extra fees push regular payments higher than the spreadsheet suggested at offer time.

High loan-to-value margin fees often sit on top of your standard interest rate. Mainstream banks usually charge those extra margins when you borrow over eighty percent of a property’s value, and the premiums eat into income while you also lose interest-rate discounts. Banks still run strict serviceability stress tests on these files, which makes approval harder on a tight budget.

This route works poorly when costs already feel close to the edge, because it slows long-term equity growth as well. If rising costs worry you right now, talk with Mortgage Suite to explore safer deposit and structure pathways before you stretch to the maximum.

Secure home loan pre-approval in five practical steps

Pre-approval gives you clear spending boundaries before you make an offer on a home. From client work we see bank assessments run faster when paperwork is ready from day one, which cuts avoidable delays. Many first-home buyers are surprised to learn that our services are usually at no cost to them.

  1. Gather documents: Collect your recent payslips, bank statements, and proof of ID.
  2. Calculate your deposit: Combine your savings, family gifts, or cash assistance toward a 10% deposit under Loan-to-Value restrictions (or 5% on a qualifying New Build).
  3. Run a serviceability stress test: Check your monthly budget against higher hypothetical interest rates.
  4. Submit your application: Pass your file to a broker who matches your goals with suitable lenders.
  5. Get sorted: Receive written confirmation of your approved limit.

Getting pre-approved works like a pre-paid ticket to an auction: you know your ceiling before you bid. If you expected a large broker fee, remember our help comes free for most buyers. Contact us when you want that written limit in hand.

Split fixed and flexible balances so rate rises hurt less

Splitting your loan balance gives you flexibility when household income drops unexpectedly. Fixing a portion locks in repayments, while placing the rest in an offset account helps you pay the home down faster without losing access to emergency funds.

From client work we see rigid single-structure loans cause heavy stress during sudden life changes. Keeping extra money in a linked account reduces calculated interest daily, yet leaves cash available if money gets tight. Think of your mortgage structure like a Swiss Army knife: two tools beat one heavy blade when conditions change.

That mix suits Kiwis who want steady repayments beside quick cash access. Mortgage Suite helps you get sorted with a customised setup so Your Home Loan stays Our Priority when rates or income shift. Book a time and we will map fixed and flexible portions around your budget.

Frequently asked questions

Can you buy your first home with a 10% deposit?

You can buy a home with a 10% deposit under Loan-to-Value restrictions through low-deposit options at mainstream banks or non-bank lenders, and some New Build schemes go as low as 5%. Low-deposit applications bring extra lender checks, so strong bank statements help you get sorted quickly. Our team acts as your dedicated negotiator when deposit funds feel tight.

How much cash back can I get?

Lenders periodically offer cash incentives of $2,500–$150,000 to first-home buyers, but exact amounts depend on current bank offers and your overall loan size. We review changing bank promotions so you can weigh each incentive against the rate, the fixed term, and clawback rules before you commit.

How do I check how much I can borrow?

You calculate borrowing capacity from household income, everyday expenses, and existing personal debts, then a lender runs its own serviceability test. A mainstream-bank decline does not mean you have run out of choices for buying a house. Talking with a mortgage broker helps uncover flexible non-bank avenues and clear next steps.

How much could you afford to borrow?

Your affordable limit depends on passing a lender serviceability assessment that tests your ability to pay higher rates. Sorting your budget early keeps property searches realistic and avoids unnecessary strain. Reach out for a friendly chat to calculate your true borrowing power before you make offers.

How much deposit do I need to buy a house?

Most standard existing-property purchases require a twenty percent deposit, but select options allow lower equity. Specific New Build schemes let you buy with as little as a 5% deposit, and 10% pathways exist where LVR exceptions and income allow. First-home buyers often learn that our broking services usually come at no cost while you work toward those deposit levels.

Getting sorted with your first home purchase

Buying your first property in New Zealand in 2026 still turns on the same questions you started with: which deposit path fits you (5%, 10%, or 20%+), whether cash-back is worth the clawback term, and how stress tests shape your true limit. A mainstream bank decline is rarely the end of the road for Kiwis looking for a fair go. As advisers at Mortgage Suite Ltd, we advocate on your behalf for tailored lending and sensible cash-back choices. First home buyer loans NZ become simpler when you have a dedicated negotiator in your corner, matching long-term goals to the right lender so you step into the market with confidence. Get in touch with Mortgage Suite today to get sorted.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

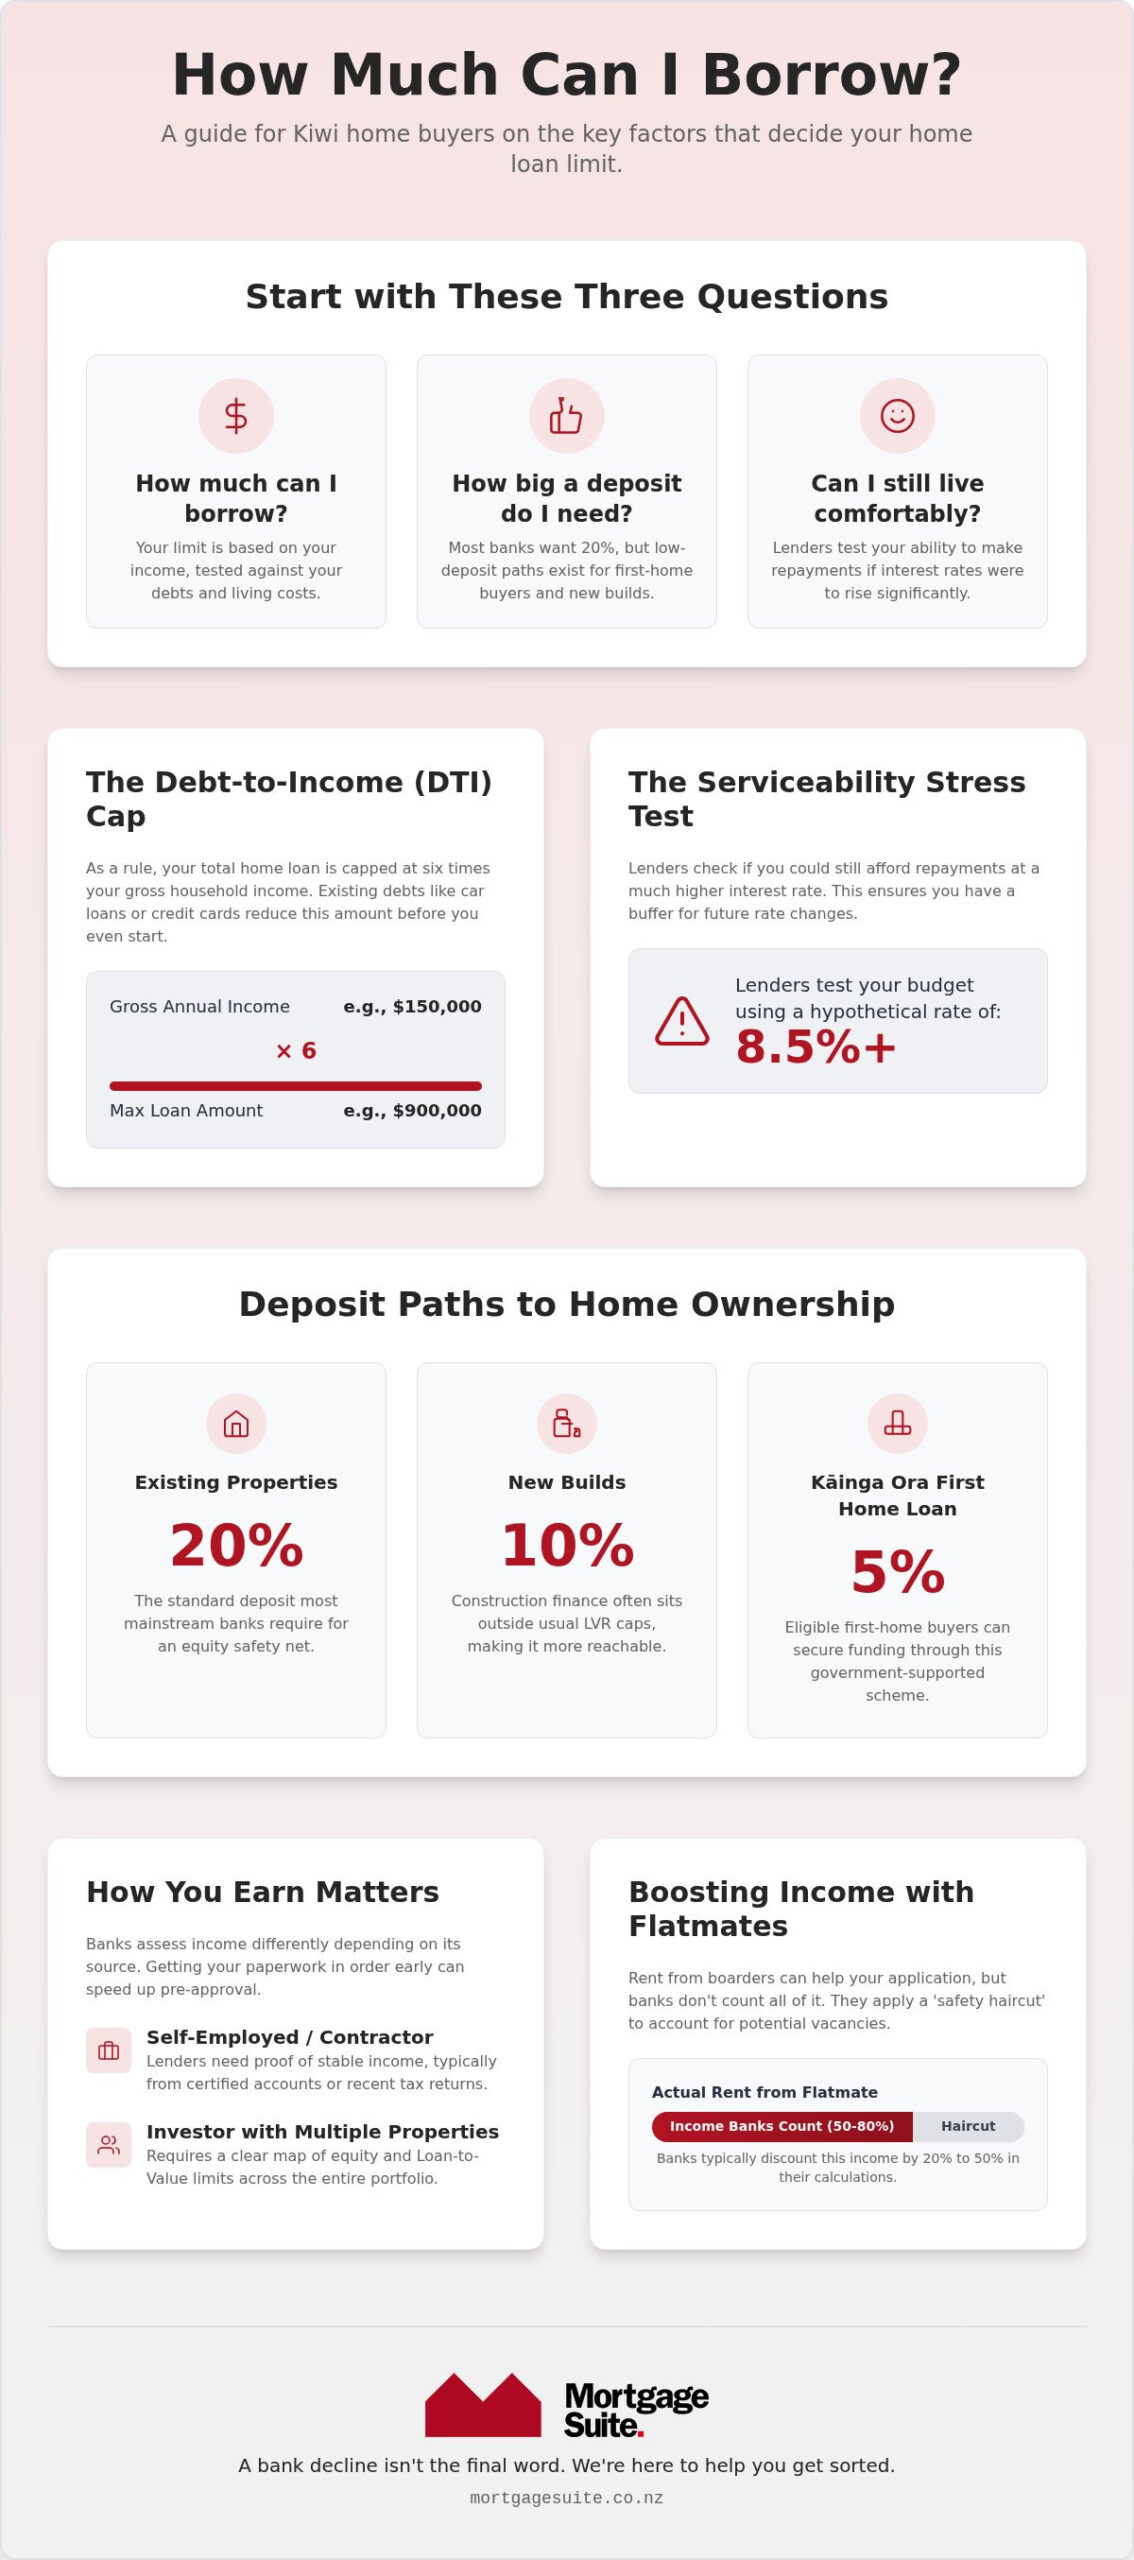
Your final home loan cap in New Zealand rests on bank serviceability tests and debt-to-income caps, not on a headline rate alone. Before you chase a listing, you need clear answers to three linked questions: how much a lender will fund against your income, how large a deposit you must show, and whether stretching to the edge of that limit still leaves you room to live. Work through those decision points in order and you avoid months of mismatched applications.

Key Takeaways: Your maximum mortgage borrowing in NZ is generally capped at six times your gross income under 2024 debt-to-income (DTI) limits and bank serviceability tests.

  • Lenders apply a serviceability stress rate of 8.5% or higher to test your repayment capacity.
  • Except when buying new builds, most mainstream banks require a 20% deposit for existing properties.
  • Therefore, first-home buyers should target the Kāinga Ora 5% deposit scheme if savings are modest.
  • Boarder income can boost eligibility but banks typically apply a 20% to 50% safety haircut.

Match your NZ borrower category before you apply

Banks do not treat every earner the same way, so the first useful step is naming the file type you will present.

  • Self-employed contractor: put certified accounts or tax returns in order early; lenders want proof of stable income before they discuss a figure.
  • Investor balancing several properties: map equity and Loan-to-Value limits across the portfolio so one highly geared title does not drag the whole application down.

Your home loan capacity depends mostly on that borrowing group. A contractor home loan is assessed very differently from a standard wage earner’s file, and criteria shift with how you earn. Naming your real category early helps you avoid mainstream declines that simply mean the file sat in the wrong queue. If you want local guidance, the team at Mortgage Suite negotiates directly with lenders as your supportive advocate. Book a short chat when you are ready to place your file in the right path.

How lenders set the figure you can actually borrow

Lenders build your borrowing power by subtracting living costs and debt commitments from total gross household income, then testing the remainder at a higher serviceability rate. They are not only looking at today’s fixed rate; they want proof you can still meet repayments if rates rise. Existing personal loans tighten debt-to-income scaling and shrink the final limit, and each bank treats board income, overtime, and living costs differently.

Tailored packaging is what secures approval. A decline from your main bank usually means your setup did not match that bank’s formula, not that you are locked out of the market. We act as your personal negotiator so the right lender sees your true financial strength. You can browse notes on borrowing power for more on how assessments differ, then book a friendly review of your own numbers when you want a concrete figure.

Deposit size that unlocks mainstream and low-deposit paths

Most New Zealand banks prefer a 20% equity safety net on existing property. Saving that sum is hard work, and standard Loan-to-Value settings limit how much high-ratio lending mainstream lenders will book. Low-deposit routes still exist. You may need only a 10% cash cushion if you meet targeted criteria, and eligible first-home buyers can secure funding with a 5% deposit through the Kāinga Ora 2026 First Home Loan programme.

Building a new home often sits outside the usual equity caps, which is why some buyers find construction finance more reachable than a second-hand purchase at the same price point. A decline from one bank manager is not the end of a homeownership plan; clear alternative pathways still reach lenders when the file is presented well. The Mortgage Suite team can walk through your deposit options in a no-obligation chat.

Tip: Check whether your prospective flat triggers the small-unit rule, as lenders may demand a higher deposit percentage.

2024 DTI limits cap your max borrowing capacity

New Reserve Bank settings restrict a home loan to six times your gross income. High earners who already carry personal debts feel the pinch first, because every store card or car loan consumes servicing space before the mortgage is even typed in. Picture your borrowing limit as a bucket: existing debt fills it before mortgage funding gets a turn.

These caps are designed to keep household debt manageable, even when they frustrate a purchase timeline. A bank decline on DTI grounds is still not the end of the path. As dedicated negotiators, we review alternative funding structures when the first formula falls short. Client stories on our testimonials page show how tightly packaged applications move through complex criteria.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Situation: a household already holding several properties needed fresh funding of $200,000 under tighter income caps. Solution: long-running advice and responsive packaging across purchases. Result: five properties settled over two decades with the same adviser relationship intact. An experienced adviser helps you read strict lending caps without giving up a sound long-term plan.

How flatmate rent can lift your borrowing capacity

Boarder income can raise overall borrowing capacity, yet mainstream banks usually count only a portion of it. Lenders apply a safety haircut so vacancy does not break the file; current market practice is a 20% to 50% discount when that cashflow enters the debt-to-income maths. Banks also run boarder payments through the higher serviceability stress rate, so the boost is real but smaller than the raw rent total.

Taking in flatmates remains a practical move for a single buyer who needs extra servicing room on a first purchase. If assessors will not accept your full boarder figure, negotiation with other lenders is the next step rather than abandoning the income line altogether. We put that case directly to the credit desk when the first pass looks too thin.

Technical Guide: How Much Can I Borrow for a Mortgage NZ

Serviceability stress tests cut what you can bid

Banks set your maximum borrowing limit with a serviceability stress test: a hypothetical repayment check at a higher interest rate to probe future affordability. Real fixed rates matter less inside the calculator than those test rates. When actual fixed rates sit well below the test rate, the bank still judges your income against the steeper threshold, and that gap trims the price you can bid.

Assessment Type Typical Interest Rate Impact on Affordability
Actual Fixed Rate Current market level Sets actual monthly repayments
Bank Stress Rate 8.5%+ Reduces calculated borrowing cap

Test rates can penalise higher incomes harder than you expect, because the same loading is applied across the board. If the stress figure leaves your shortlist out of reach, flexible non-bank or second-tier structures are worth comparing before you rewrite your property brief. Mortgage Suite acts as your personal advocate when you need that comparison done without sales pressure.

Paperwork that speeds your pre-approval

Organised files move lender assessments faster, and gathering paperwork early removes a common source of delay. Treat the pack like a road-trip checklist: one missing item stalls the whole trip.

  1. Verify income: recent payslips, or certified accounts if you are self-employed.
  2. Show savings: bank statements that prove deposit funds and a genuine savings history.
  3. List debts: a clear debt-to-income summary, including credit cards.
  4. Detail living costs: an accurate monthly household expense breakdown for the lender.

A contractor home loan usually needs two years of trading history or current contracts on the desk. Mainstream hurdles do not have to stop the process when the file is complete and directed to a lender that accepts your income type. Reach out for a confidential chat when you want a second pair of eyes on the pack before you submit.

When stretching your borrowing limit is a bad move

Maxing out mortgage potential leaves little shield against rate rises or sudden lifestyle bills. Squeezing every last dollar from an assessment often backfires once the unexpected lands. A buffer is what keeps the household steady when life shifts.

Treat the limit like a rubber band: pull it to the edge and any extra tension snaps the budget. Passing a serviceability stress test shows you can pay on today’s assumptions; it does not price future cost spikes. Borrowing below your theoretical maximum is often the steadier choice if you want sleep at night as well as keys in the door. If the numbers feel tight, ask us to model a safer cap before you sign a sale and purchase.

Secure your pre-approval with non-bank options

A bank decline is rarely the end of a property plan. Alternative lenders supply a useful safety margin when mainstream credit policy says no. Non-bank institutions often apply more flexible criteria for complex income or smaller deposits, and they look past a single computer scoreboard.

Use that path as a springboard when you need short-term flexibility, then refinance later if your profile fits a bank book. At Mortgage Suite we act as your dedicated advocate through pre-approval and drawdown, so the credit story stays consistent from first call to settlement. Contact the team for a confidential chat when you want those options laid out side by side.

Frequently asked questions

How much can you afford to repay?

Your affordable repayment depends on total household income, living expenses, and current personal debts. Lenders review day-to-day spending to confirm enough remains for ordinary life after the mortgage leaves the account. We help you line those figures up so the repayment you offer is one you can sustain.

How much will a bank lend on a property?

Banks set a maximum by running a serviceability stress test across income and expenses, using a higher test interest rate to guard against future increases. They also apply debt-to-income caps to the overall funding total. If one bank declines, our team compares alternative lenders that read the same numbers under different policy settings.

How much of my income can go to mortgage repayments?

Most lenders prefer home loan repayments at no more than 30–35% of gross income. Staying inside that band leaves room for bills you cannot defer. Each bank weights household size slightly differently, so a short adviser conversation clarifies where your file sits.

What percentage of a property’s value can banks lend?

Banks usually lend up to 80% of value on owner-occupied homes under standard Loan-to-Value settings. First-home buyers with smaller deposits can sometimes borrow a higher share when they meet low-deposit criteria. A smaller flat may attract a higher deposit demand under small-unit policy. We can test your case across more than one lender credit desk.

What is a minimum surplus or UMI and how much is needed?

Uncommitted Monthly Income is the cash left after bills, living costs, and loan repayments. Lenders want a positive surplus buffer, often $1,000 each month, as evidence you can absorb a surprise expense. Mortgage Suite works with lenders to present that surplus clearly so the buffer you actually run is the one on the page.

Getting sorted with your home loan

Working out how much you can borrow for a mortgage across NZ starts with the same three decision points you met at the top: servicing capacity, deposit path, and whether the limit you are offered still leaves a liveable buffer under debt-to-income and stress-test rules.

Mainstream criteria can feel opaque, and a decline is rarely the end of your options in 2026. Mortgage Suite Ltd advisers act as your personal advocate, comparing non-bank alternatives and negotiating structure when the first formula does not fit. If you want clarity on your borrowing capacity, contact the team for expert mortgage advice.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial construction finance Auckland: 12 month terms

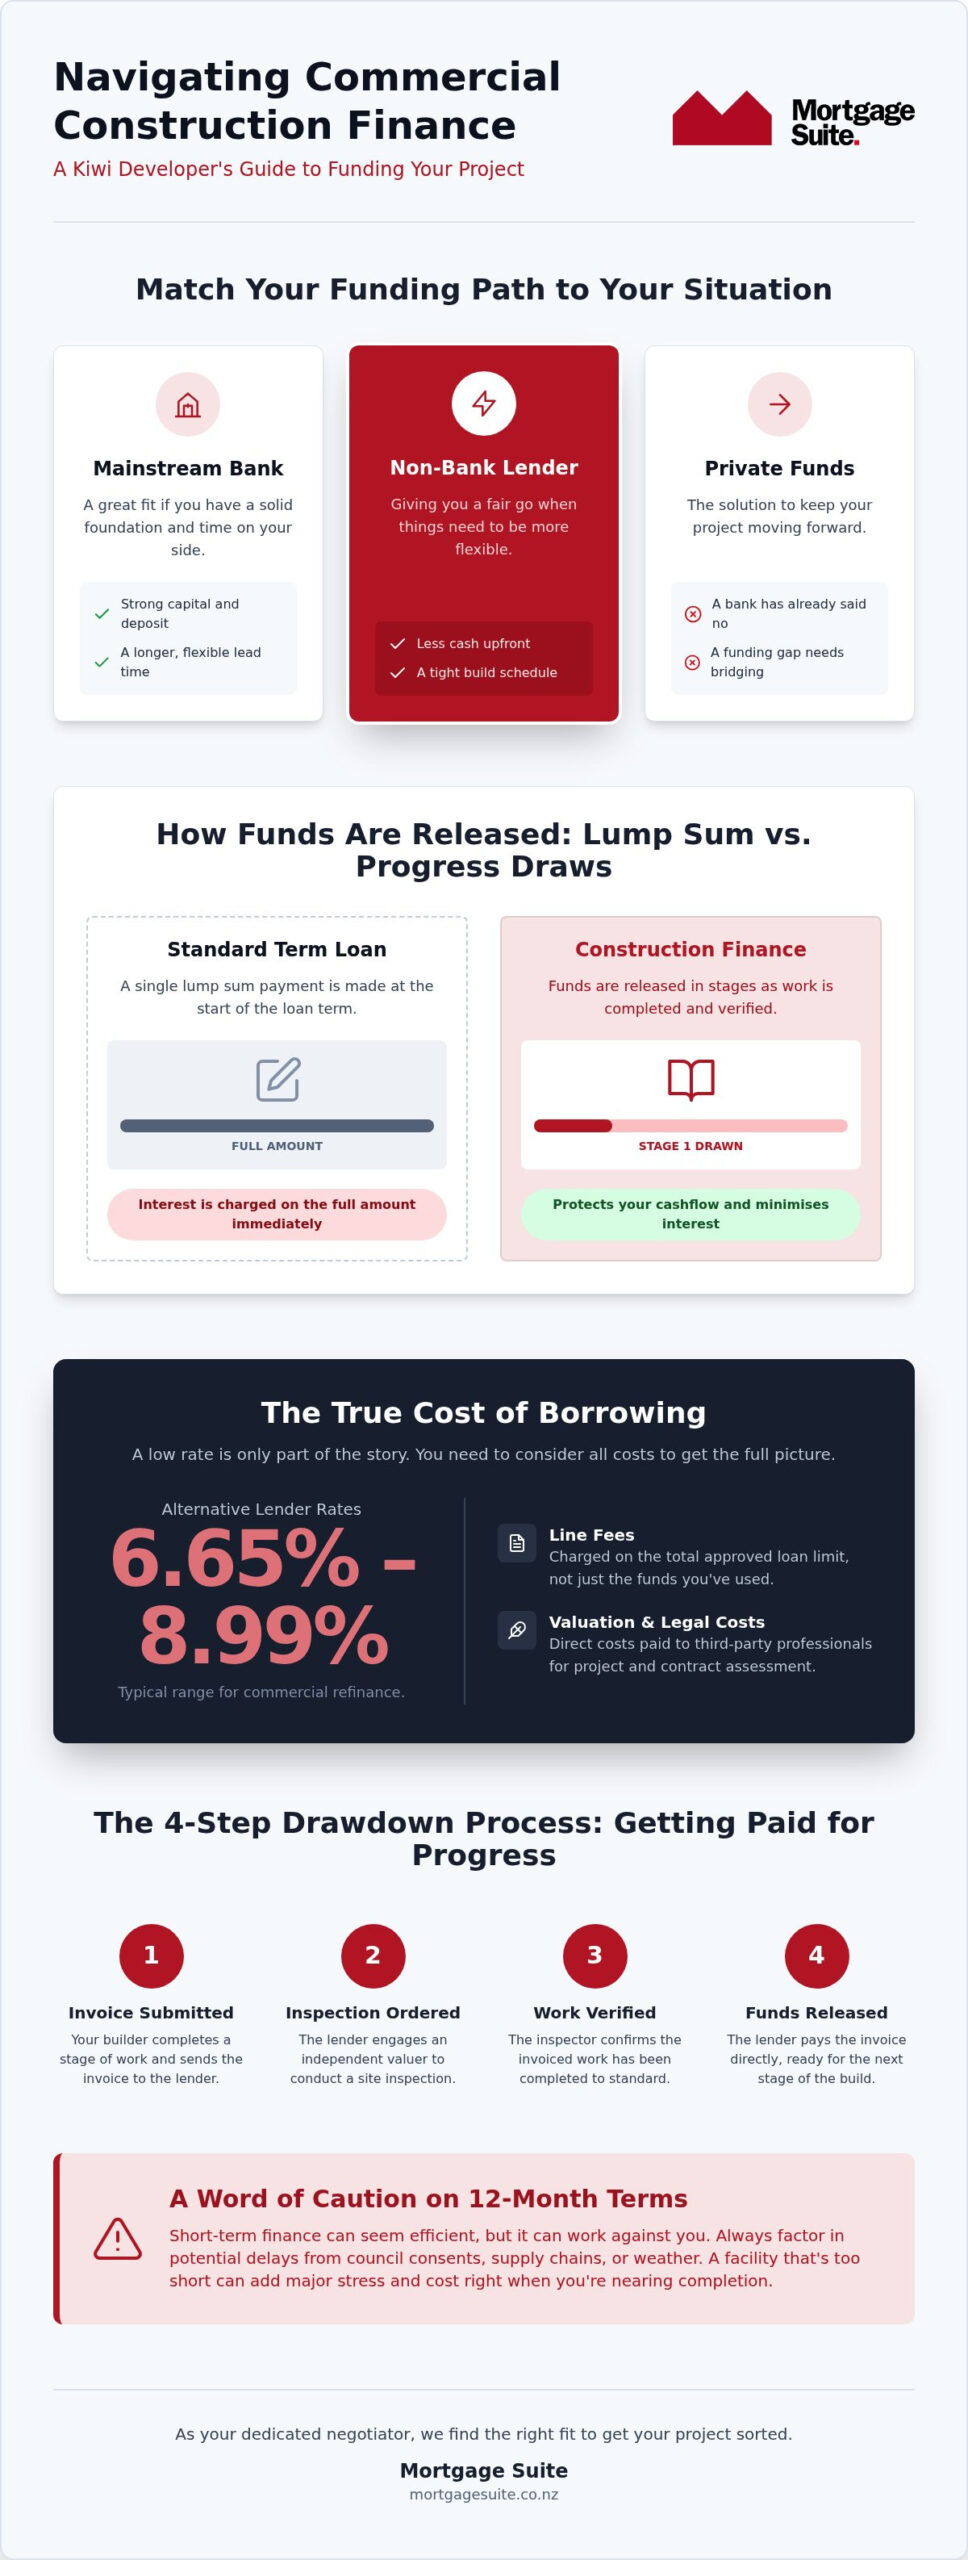
Commercial refinance loan rates from alternative lenders typically range from 6.65 percent to 8.99 percent, according to market research. For short-term capital needs, bridging finance nz typically lasts for up to 12 months to cover project timelines. The decisions that shape your build are practical ones: which funding path matches your equity and site timeline, what the full cost of borrowing looks like once fees are included, and whether a short facility gives you enough room before refinance or sale.

Key Takeaways: Commercial construction finance in Auckland uses a progress-draw structure with alternative lender rates between 6.65% and 8.99% to fund projects over 12-month terms.

  • Alternative lenders provide commercial refinance rates from 6.65% to 8.99% for short-term capital.
  • Avoid 12-month terms unless your project timeline accounts for potential council or material delays.
  • Choose non-bank lenders for faster approvals and flexible equity requirements when mainstream banks decline.
  • The drawdown process involves four steps including site inspections to verify work before payment.

Match equity and timeline to a construction finance path that fits

Your equity levels and site timelines decide which lending route makes sense for your build. Early-stage planning often collapses when the funding option does not match the cash you can put in or the speed of the programme. Picking a path that fits those two constraints saves time and money.

Typical situations we sort with clients:

  • Strong capital and a longer lead time: a mainstream bank facility can suit you if serviceability and deposit margins stack up.
  • Less cash upfront or a tight build calendar: non-bank lenders give you a fair go with practical flexibility on structure and timing.
  • A bank has already declined the application: private funds can bridge the gap so land, siteworks, or base construction do not stall.

A mainstream bank suits Kiwis with solid capital and longer lead times. If you have less cash upfront or tight build schedules, non-bank lenders offer a fair go with practical flexibility. Funding large-scale land subdivisions (big land projects) still needs clear milestones so each release of capital lines up with completed work.

Talk to us first so flexible terms keep construction on track. Mortgage Suite Ltd acts directly on your behalf as your dedicated negotiator.

Progress-draw structures that suit Auckland commercial builds

Standard property loans pay out in one lump sum, whereas commercial construction finance releases money gradually. Development funding works as a managed drip-feed rather than a single payout: lenders hold funds until builders finish specific stages of work.

Your Cashflow stays protected from premature interest because the drawdown process releases money in stages. That staged structure helps you manage risk on big land projects (large-scale land subdivisions). Standard bank term loans simply lack this staged flexibility.

Finance options depend heavily on project type. Commercial builds typically use progress-draw loans, while standard land purchases suit simpler structures. Getting the facility structured to the build gives the project a fair go.

If mainstream lenders seem hesitant about your development plans, a traditional bank decline is not the end of the journey. You still have sound options with non-bank lenders. Working with Mortgage Suite means having a dedicated advocate to negotiate with suitable lenders on your behalf. Construction remains a major driver of national economic activity, so getting sorted early on structure and timing makes a real difference to delivery.

Full borrowing cost: rates, fees, and what you actually pay

Comparing initial interest rates with establishment costs gives you the actual cost of borrowing for your build. Line fees and lender legal costs add up quickly, so a low advertised rate can cost you far more over the life of the facility. If you are managing a major development or a big land project (large-scale land subdivision), evaluate the whole cost package, not only the headline figure. A lender with slightly higher interest but no ongoing administration charges is often the stronger financial move.

Fee Component Estimated Market Structure
Refinance Loan Rates 6.65% to 8.99%
Line Fees $50 Charged on total facility
Valuation & Legal 2020 Paid directly to providers

Lenders base line fees on the entire approved loan limit, not only the funds drawn. Funding a small $50,000–$300,000 addition differs from a full build. If you need to refinance short-term debt to clear expensive bridging, alternative lenders offer specialised solutions. Commercial refinance loan rates from alternative lenders range from 6.65 percent to 8.99 percent, according to current market rates.

Brokers who understand long-term development goals help you weigh rate, fees, and exit in one view so you get a fair go on the full package.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

Long-term client relationships show how tailored advice helps property investors move through purchase, refinance, and the next project with one steady hand.

Commercial loan criteria you can meet without a bank-only plan

Commercial lenders assess your equity, property location, Cashflow, and experience before approving project funding.

Client work shows rigid deposit demands often take project leaders by surprise. Mainstream banks usually demand higher deposit margins for commercial builds than for residential ones. You will generally need a clear business plan and solid equity to get sorted.

Equity is set as a share of project value and varies with scale, location, and lender appetite. Mainstream banks apply a serviceability stress test so you can handle rate shifts. Legal structures matter on large-scale land subdivisions: clear development contracts help parties manage shared risk across the programme.

A bank decline is not the end of the road. Non-bank lenders offer flexibility when trading history is complex. Our team acts as your dedicated negotiator to secure a fair go. Review practical 2026 finance guidance when you want to compare structures, then let us chat through your numbers.

Drawdowns that protect Cashflow across each build stage

A clear payment schedule keeps the build moving while holding interest costs down. Commercial construction finance typically aligns with project milestones so you only pay for completed work. Releasing funds in controlled stages protects cash reserves throughout the build. Lenders require proof of progress before paying out each stage.

The drawdown process works in structured steps:

  1. Submit invoice: You send the certified builder invoice to your lender for review.
  2. Site inspection: An independent assessor inspects the property to verify completed work.
  3. Approve payment: The lender verifies the work matches the base construction contract stages.
  4. Release funds: Finance pays out the approved milestone amount to your contractor.

Managing this timing carefully prevents awkward pauses on site. If you need temporary gap funding while selling another asset, a bridging finance term lasts up to 12 months. Mortgage Suite acts as your personal advocate so you get sorted with lenders before the first claim is due.

Tip: Ensure your base construction contracts align with loan stages to avoid out-of-pocket delays during drawdowns.

Commercial construction finance Auckland: 12 month terms

Joint ventures and presale underwriting when bank channels close

Securing non-traditional equity support or presale underwriting gives you a safety net when traditional bank channels close off.

Pairing with an equity partner can strengthen the capital stack before a single brick is laid. Standard lenders usually demand heavy pre-commitments, while alternative joint ventures bring flexible cash in earlier.

Presale underwriting works as a firm backing agreement: a promise to purchase uncommitted units if public buyers fall short. It functions like cover on project momentum and can satisfy strict lender criteria without forcing panic discounts. Mainstream rejections do not mean the vision is dead.

We negotiate these backing structures directly so you keep control of the build schedule. Structured well, equity support protects total profits rather than simply diluting them. Ask us to map JV and presale options against your current term sheet.

When a 12-month construction term works against you

Short-term construction loans create severe refinancing pressure if the building schedule stalls or sales take longer than expected.

Brief 12-month terms leave little room for council delays or slow material deliveries. A minor hold-up can force expensive loan extensions right when the budget is tightest. A short loan term behaves like a timer on a pressure cooker. Kiwis building larger projects often need more time to complete base construction and secure final buyers.

A mainstream bank decline on your timeline does not mean the build is over. Mortgage Suite Ltd works as your personal advocate to negotiate flexible terms that match the actual build pace.

If short-term funding looks like the only door open, we can help you get sorted with a structure that leaves room for real-world delays. Reach out for a friendly chat about term length and exit.

Property development finance that keeps your schedule moving

Fast finance approvals keep construction schedules on track and limit costly project delays. Setup costs vary with facility size, valuation, and legal work, so you should budget them as part of the full capital stack rather than as a surprise at drawdown.

Slow bank processing creates real stress for Kiwi developers. Working directly with private lenders often speeds up decision times compared with traditional channels. Mainstream approvals can drag on for months, whereas non-bank options focus heavily on your equity safety net and overall project viability.

If a retail bank manager hesitates, your goals remain achievable. We act as your personal advocate, negotiating flexible terms so you get sorted without losing momentum. Mainstream declines are rarely the end of the road. Contact Mortgage Suite for a friendly, confidential chat about holding your timeline.

Frequently asked questions

What is property development finance?

Property development finance is a specialised loan designed to fund major building projects or big land projects. Mainstream banks often pull back from complex builds, but we help Kiwis get sorted with tailored funding structures. It covers the costs of turning bare ground into completed real estate, moving in stages from siteworks to final base construction. If a traditional bank manager said no to your project, non-bank alternatives can help you keep moving forward.

How do 12-month construction and bridging terms work in Auckland?

Short-term construction and bridging facilities are commonly used to cover a defined build or gap period, and bridging finance nz typically lasts for up to 12 months. That window only works if council timeframes, materials, and sales line up with the exit you have planned. If the programme needs more room, we compare longer or more flexible structures so you are not forced into a costly extension at the worst moment.

What types of loans are available?

Funding options range from short-term bridge funding to long-term facility structures tailored for commercial property developments. You can access specialised capital for initial earthworks, a term loan for completed assets, or short-term bridging finance which typically lasts for up to 12 months. When you need to refinance commercial property, alternative lenders offer commercial refinance loan rates that usually fall between 6.65 percent to 8.99 percent, according to market listings. Mortgage Suite guides you through each option so you secure a fair go without getting stuck in red tape.

How does a construction loan differ from a standard home loan?

Standard home loans provide the entire principal upfront, whereas a construction facility releases cash gradually in stages. This controlled release is known as the drawdown process, which protects both you and your lender as work progresses. You only pay interest on the money you have actually drawn down to pay contractors. This structure keeps your monthly costs lower during the early phases of your build.

How are payments structured during the construction phase?

Payments are drawn down progressively after an independent valuer inspects the building work completed at each milestone. You usually make interest-only payments on the drawn balance, easing Cashflow stress while the build is under way. Once council issues the final Statement of Compliance, your facility can convert into a standard term loan or be paid off through sales. Talk to Mortgage Suite about negotiating payment terms that match your contract stages.

Getting your Auckland build moving in 2026

Securing the commercial construction finance Auckland projects need can feel heavy when mainstream bank criteria keep shifting. You do not have to read those guidelines alone.

The same questions you started with still steer the outcome: which path fits your equity and timeline, what you will pay once rates and fees sit together, and whether a short facility leaves enough room before refinance or sale. Mortgage Suite Ltd advisers work as your personal advocate to negotiate flexible funding for your site. Whether you need help with big land projects or standard build funding, options exist beyond a basic bank decline.

Explore pathways with our finance calculator, then reach out to the team for a friendly, confidential chat about your plans so you can get sorted with a structure that matches the build you are actually delivering.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Technical Guide to Your Property Development Exit Strategy

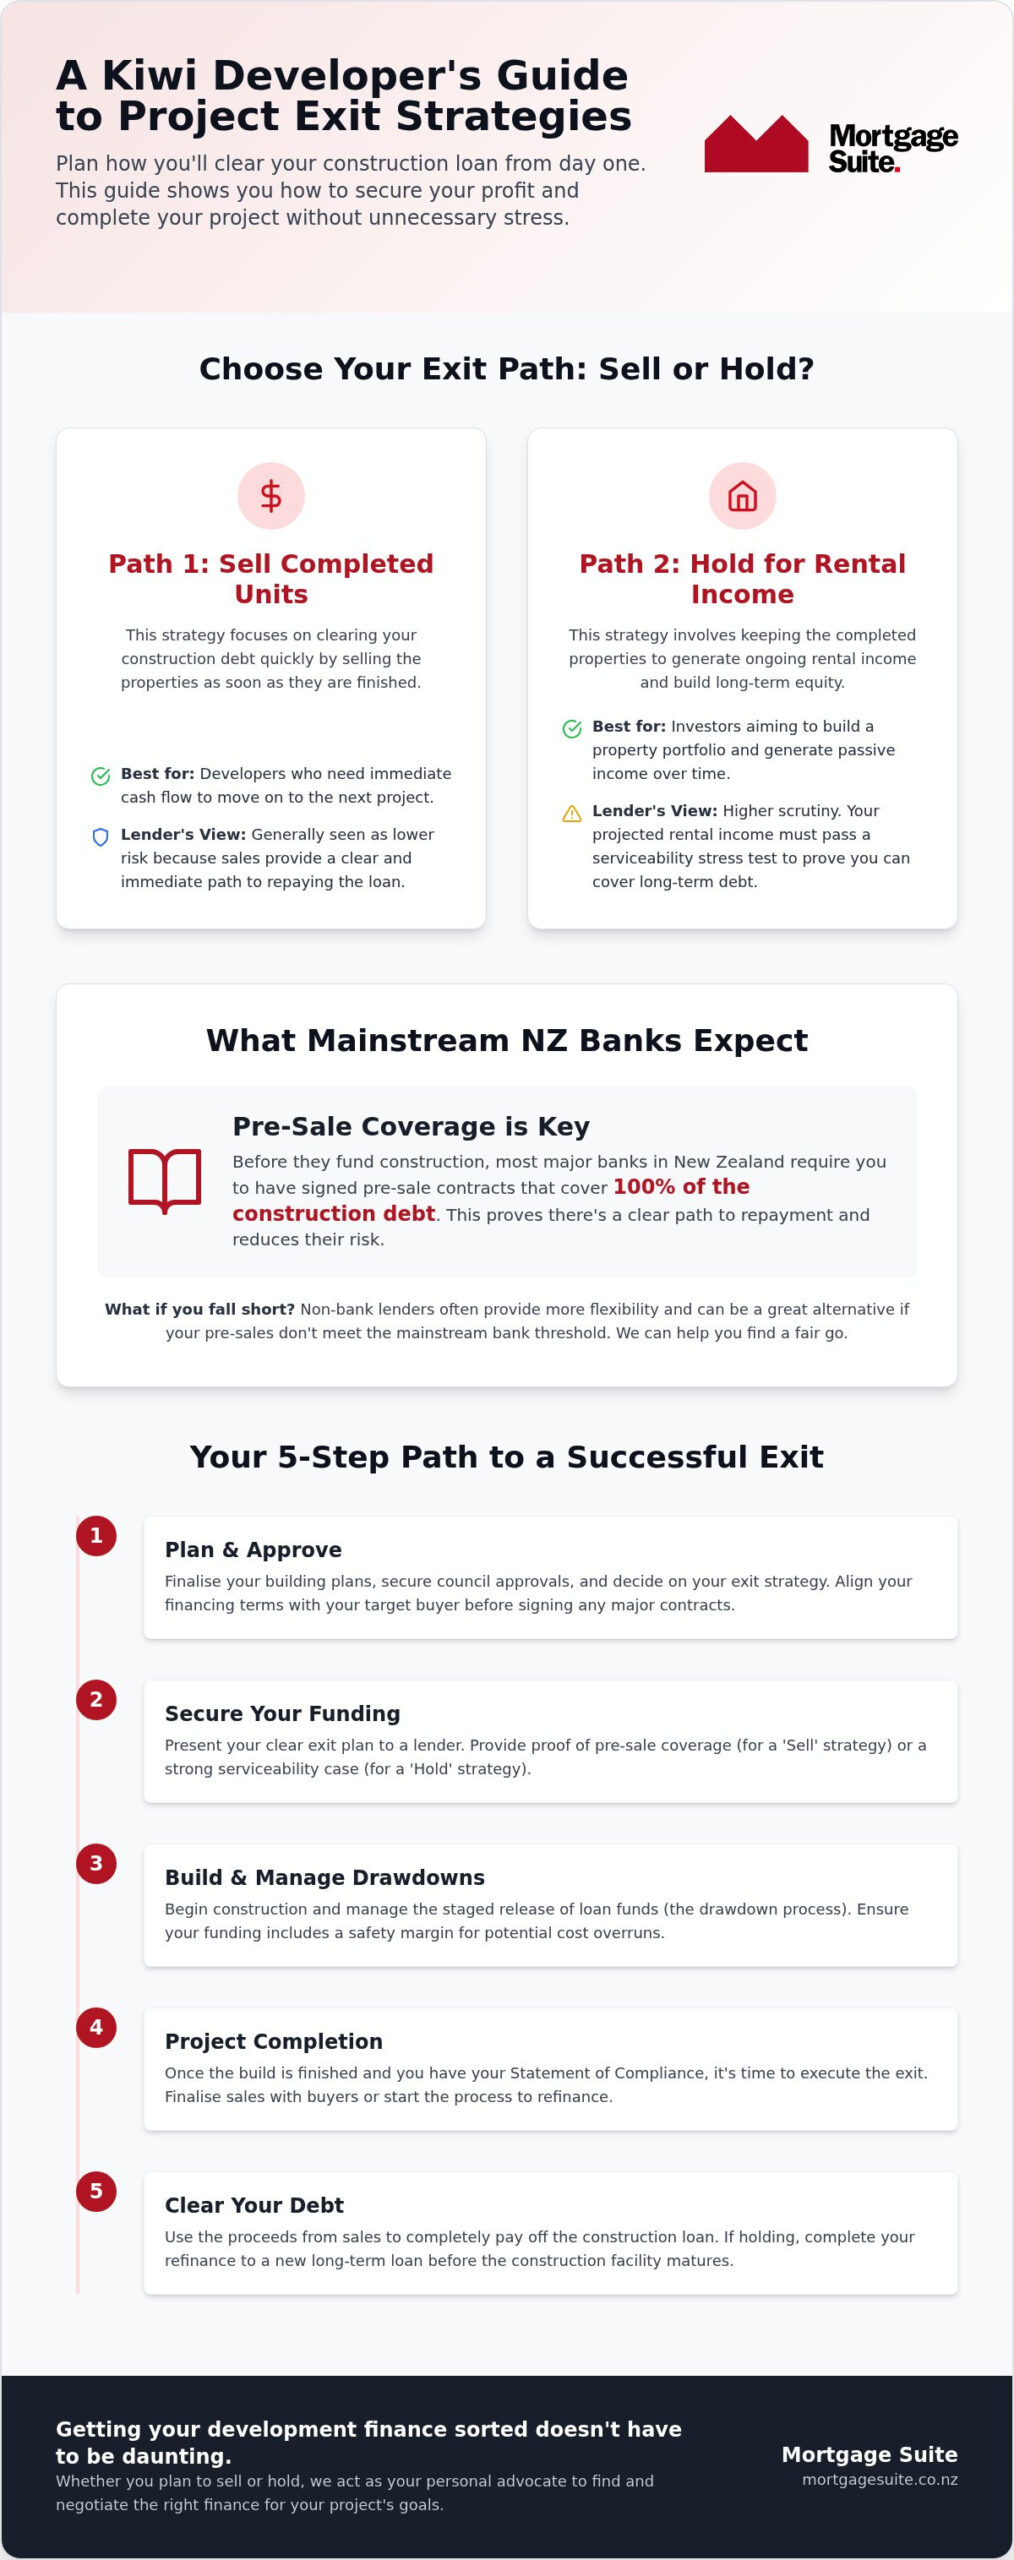
A property development exit strategy defines exactly how you will settle your construction loan, either through selling completed units or refinancing into long-term debt. Securing non-bank or mainstream bank finance requires showing pre-sale coverage or a validated serviceability stress test before ground preparation (siteworks) begins. Getting your funding sorted early gives Kiwis a fair go at completing successful projects without unnecessary stress.

Key Takeaways: A property development exit strategy ensures you clear construction debt by either selling completed units or refinancing into long-term rental debt.

  • Mainstream NZ banks typically require pre-sales to cover 100% of construction debt before funding.
  • Holding property is only viable if rental yields pass serviceability stress tests at higher rates.
  • Selling suits developers needing immediate liquidity, while holding is best for long-term equity growth.
  • The article provides a 5-step execution plan from council approvals to final debt clearance.

3 Exit scenarios: pick your project path

You can sell your build off-the-plan, retain it to rent, or sell immediately upon project completion. Choosing your exit early prevents costly refinancing delays later, and deciding on your target buyer upfront shapes your Cashflow and borrowing structure.

Here is how those paths look in practice:

  • You want profit out quickly so you can clear build debt: sell finished units and line up buyers before practical completion.
  • You want long-term equity and rental income: hold the completed property and arrange bridging into term finance before the construction facility matures.
  • Mainstream banks decline because presales fall short: use alternative lenders who will still fund against a clear exit, then refinance once the build is proven.

Selling finished units suits Kiwis who need Cashflow to clear build debt fast. Holding the completed property works better if your goal is equity growth over time. For builds you plan to retain, securing property development funding helps bridge the gap before long-term finance kicks in. Mainstream banks often say no if presales fall short, but alternative lenders still give you a path to get sorted.

Tip: Match your financing terms directly to your end-buyer profiles before signing main contractor agreements.

Sell or refinance: how you clear a development loan

You clear your development loan by either selling the finished properties or switching to long-term finance. Choosing the path early protects your profit and keeps lenders engaged with a repayment story they can follow.

If you pre-sell off the plans, you reduce your overall risk profile because guaranteed buyers satisfy bank presale targets before building starts. Relying entirely on presales can lock in lower margins if construction costs shift before ground preparation ends. Keeping properties to rent out works well if you want long-term equity, but it requires a strong serviceability position so rental income can carry the term debt.

Selling completed homes fits developers who need fast Cashflow. Retaining units suits investors building a portfolio. You can read more about options on our property development Archives, Mortgage Suite mortgage page.

Getting mainstream-bank sign-off still requires a clear repayment path on paper before they release construction funds. Contact Mortgage Suite Ltd when you want help to organise that financing around the exit you have actually chosen.

Why lenders treat a sale path as lower risk than a hold

Lenders usually view quick sales as lower risk because they clear project debt promptly through immediate capital returns. That is why a sale-led exit often moves through credit faster than a hold.

When you plan to hold properties for long-term rental income, financiers look closely at ongoing Cashflow. Banks assess whether rental yield can cover long-term debt through a serviceability assessment (using a higher hypothetical interest rate to test future affordability). If mainstream banks seem hesitant about your long-term plans, non-bank alternatives offer viable pathways forward.

Retaining finished units as rental properties frequently demands refinancing into a term loan before the construction facility matures. Switching strategies halfway through a project can surprise your financier if you have not planned the transition early, so lock the exit into the facility terms from day one.

Securing the right funding structure depends on your final goals. You can explore commercial loans with our team when you want terms shaped around sale or hold. Selling works for developers who need fast capital clearance; a hold strategy fits buyers focused on equity over the long haul.

Talk through your sale versus hold file with us when you are ready to set the structure.

Holding vs selling: tax and LTV math compared

Selling off your development frees up capital instantly, whereas holding builds long-term equity if your income streams stack up. Developers routinely miscalculate their loan-to-value ratios because standard calculators only plan for immediate sales. Choosing a hold strategy means balancing long-term tax obligations against your ongoing equity safety net.

Strategy Primary Tax Focus Capital Structure
Selling Income tax on profits Debt fully cleared
Holding Depreciation and Cashflow Retained debt against equity

Aligning financing structures with your intended exit is where many Kiwis hit a wall. Holding makes financial sense only when your rental yield covers your debt without triggering serviceability stress. For the term-loan side of a hold exit, refinancing commercial property walks through the steps for managing that long-term position.

Holding suits investors seeking passive income. Selling fits builders who need cash for their next project. Mainstream banks might hesitate if your Cashflow looks complex, yet alternative options still exist. We work as your personal advocate to negotiate terms that fit the math in the table above: reach out for a friendly chat when you want those numbers tested against lender criteria.

Pre-sale cover NZ banks expect before they fund

Mainstream lenders usually require presales to cover your construction debt before funding your build. Securing those contracts early keeps your project moving, because qualifying buyers must sign unconditional contracts or conditional deals with approved deposits. Having these agreements locked in gives your lender confidence to advance funds.

If your local bank manager seems hesitant, you still have options. Private lenders often offer flexible presale targets when mainstream banks say no. Managing your exit paths early is what keeps funding stable when buyer cover is thin.

Pre-selling fits developers who need guaranteed bank debt clearance. Holding completed units suits long-term investors aiming for rental returns. Let us negotiate with lenders on your behalf so the presale bar matches the exit you can actually deliver.

Among Mortgage Suite Ltd’s Google reviews, Baycom (5★) wrote:

"We have dealt with Krish for over 20 years and in that time we have purchased 5 properties. Krish is knowledgeable, professional, and responsive. We would highly recommend Krish and Mortgage Suite to anyone looking to invest in property, Steve & Rosie Bower"

That review traces a simple arc: a long-run investor needed repeat purchases supported over two decades, worked with a dedicated adviser across five properties, and stayed with the same broker because the process stayed responsive. That is the pattern you want when your own exit depends on advice that holds up across more than one project cycle.

Technical Guide to Your Property Development Exit Strategy

5 Steps to execute your development exit

Executing a property development exit requires a clear plan to pay off your short-term project debt without a scramble at practical completion. Early planning stops late-stage delays, and aligning your timeline early means you avoid rushed decisions when high interest charges loom. Treat the exit like flight planning: you line up the landing long before you approach the runway.

Setting up your long-term finance early also prevents expensive loan penalty fees if sales drag.

Follow these steps to get sorted:

  1. Review project progress: Confirm that your base construction and ground preparation are fully finished on time.
  2. Obtain official approvals: Secure your final council Code Compliance Certificate to prove the build meets local standards.
  3. Choose your route: Decide whether selling units or holding them to refinance commercial property fits your financial goals.
  4. Apply for finance: Secure your new long-term loan or mortgage pre-approval before your current short-term facility expires.
  5. Clear existing debt: Complete the drawdown process with your new lender to fully repay the original construction loan.

A mainstream-bank decline does not mean you have run out of options. Reach out to Mortgage Suite Ltd for a friendly chat about the pathway that matches your chosen step 3.

Structure drawdowns so cost overruns do not sink your exit

Unplanned cost escalations during a project cycle will disrupt your planned exit if your debt structure lacks a safety margin. Flexible drawdown planning is how you keep the exit intact when site costs move.

To avoid unexpected shortfalls, build a contingency buffer into your initial drawdown process. That buffer covers cost surges during ground preparation without exhausting your capital prematurely. When project timelines stretch, standard lenders often tighten their terms, and alternative non-bank options offer leeway when traditional banks stall.

Staggering your loan releases aligns Cashflow with completed build phases. That protects your equity safety net and stops high interest charges accumulating before the work is done.

Our team acts as your dedicated negotiator on repayment terms that still give you room to finish. Book a chat with Mortgage Suite Ltd when you want a funding plan with that buffer built in.

When holding finished units costs you more than it returns

Holding finished units turns into a risky gamble when Cashflow dries up or local holding costs start swallowing your profit margins. Developers often trap capital in completed builds while waiting for a slightly higher sale price; that stall blocks new projects and inflates interest payments fast.

Holding makes sense for long-term rental income. Cashing out is the stronger move when you need immediate liquidity or when loan servicing stretches your budget. You get sorted faster by choosing to sell in those conditions rather than guarding empty stock.

We will advocate for your goals with alternative lenders if high holding costs strain your position. Let us talk through the hold-versus-sale numbers on your file before the interest clock runs further.

Details and enquiries: Mortgage Suite Ltd.

Frequently asked questions

How do timing and market conditions affect exit returns?

Market conditions directly influence buyer demand and final sales prices when you finish a project. Waiting for the right market window can improve your overall profit margins. Poor timing often leads to higher holding costs such as ongoing interest payments, so you need a solid property development exit strategy that still works if demand softens.

What tax treatments apply to different exit strategies?

Selling a completed build usually triggers different tax obligations compared with keeping it as a long-term rental property. Mainstream tax rules apply to trading profits, while long-term holds focus on rental income stream assessments. Working with certified accountants helps you understand your exact obligations early, and our team can help you line the funding path up with that advice.

How should financing structures align with exit plans?

Your initial loan agreement must match your intended way out, whether that involves selling quickly or refinancing. Short-term construction finance requires a clear repayment pathway before any lender will release funds. A well-structured term loan works better if you plan to hold the finished property, and matching loan terms to your actual timeline saves unnecessary penalty costs.

How do lenders view sale versus hold strategies?

Banks generally view pre-sold units as lower risk because the repayment path is clear. Choosing to retain property requires proving you can service the ongoing debt through stable rental returns. Lenders run a serviceability stress test to ensure you can afford higher interest rates over time. We act as your personal advocate to negotiate flexible terms on either path.

What pre-sale cover do NZ banks require?

Mainstream NZ banks often insist on a set percentage of pre-sales before construction funds are released. Non-bank financial institution options can provide more realistic requirements if bank hurdles feel too high. A strong safety margin in your pre-sales protects your project from sudden market shifts, and we help you find practical funding options that fit the cover you can genuinely secure.

Getting your property development exit strategy sorted in 2026

A clear property development exit strategy keeps your project moving from construction to final payout, on the same sell-or-refinance choice you set at the start. Developers run into delays when council Code Compliance Certificate issue takes longer than planned, and having an alternative non-bank pathway gives you a safety net when mainstream bank timelines drag out.

Planning ahead saves stress and protects your profit on the exit you already chose.

Ready to secure your end position? Contact the Mortgage Suite Ltd advisers today for a friendly, confidential chat about your funding options.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Refinancing Commercial Property NZ: Your 2026 Guide to Getting a Better Deal

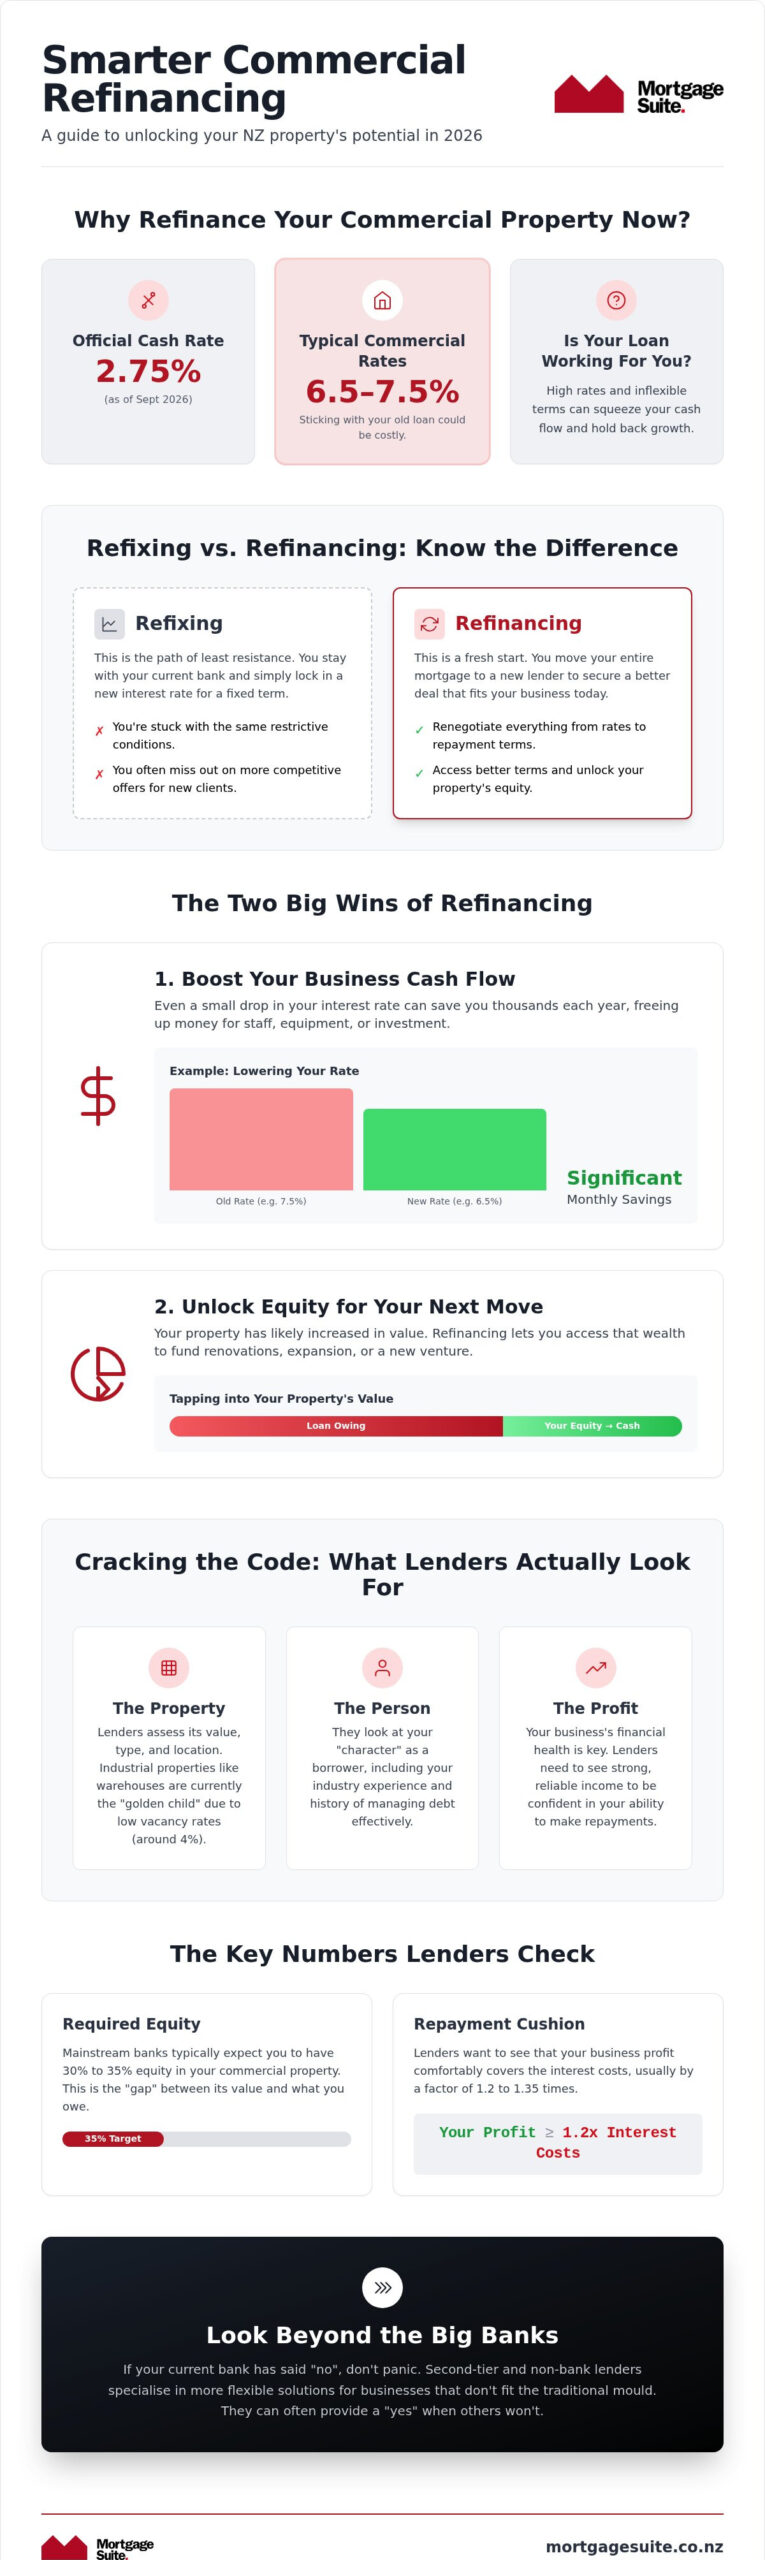
What if your commercial mortgage didn’t feel like a weight around your business’s neck? Many Kiwi owners feel stuck with high interest rates and banks that just don’t get their vision. With the OCR at 2.75 percent as of September 2026 and commercial rates hovering between 6.5 and 7.5 percent, sticking with your current lender out of habit could be a costly mistake. If you’re looking into refinancing commercial property NZ, you’ve likely realised that the traditional banks aren’t always the most flexible partners for growing businesses.

We understand how frustrating it is when your cash flow is squeezed by restrictive terms and confusing financial talk. You deserve a lending partner who sees the person behind the balance sheet and values your potential. This guide will show you how to unlock the equity in your building, slash those monthly repayments, and find a lender who actually understands your goals. We’ll walk you through the 2026 lending landscape, from non-bank options to the latest tax changes, so you can secure a deal that finally supports your growth.

Key Takeaways

  • Identify the right time to move your mortgage to take advantage of shifting market trends and improve your daily cash flow.
  • Navigate the process of refinancing commercial property NZ without the stress by following a clear, step-by-step plan.
  • Explore flexible alternatives beyond the big banks that can offer solutions even if your current lender has said “no”.
  • Learn how to present your business and property in the best light to secure the lowest possible interest rates.
  • Discover how to unlock hidden equity in your building to fund your next big project or business expansion.

Why Refinancing Your Commercial Property in New Zealand Makes Sense Right Now

The financial market has shifted significantly as we move through late 2026. With the Official Cash Rate sitting at 2.75 percent, many property owners are finding that the loan structures they set up a few years ago no longer serve their best interests. If you have been with the same lender for a long time, you might be surprised by how much the market has moved without you. Refinancing commercial property NZ isn’t just about chasing a slightly lower number; it’s about ensuring your debt structure actually supports your business goals rather than hindering them.

It is vital to understand the difference between simply refixing and a full refinance. Refixing is when you stay with your current bank and just sign up for a new interest rate term. It’s the path of least resistance, but it often leaves you stuck with the same restrictive conditions and “faceless” service. A full refinance involves moving your commercial mortgage to a different lender. This process allows you to renegotiate everything, from how much you can borrow to the way you make repayments, providing a fresh start that fits your current financial reality.

Boosting Your Cash Flow and Reducing Costs

Commercial loans are typically large, which means even a small reduction in your interest rate can put heaps of money back into your business every month. With current commercial rates ranging between 6.5 and 7.5 percent, moving from a high rate down to the lower end of that scale can save you thousands. Sticking with one bank for a decade might feel loyal, but banks often reserve their most competitive offers for new clients. By switching, you can lower your monthly overheads and use that extra cash to hire new staff or buy better equipment. You can use a mortgage calculator to see exactly how a lower rate changes your monthly commitments.

Unlocking Equity for Your Next Move

Equity is the difference between what your property is worth today and the amount you still owe. Since property values have changed, 2026 is a fair dinkum time to check what your warehouse, office, or shop is actually worth. If your property value has grown, a refinance allows you to “unlock” that value. Instead of that wealth sitting idle in the building, you can access it as cash to fund a new business venture or a major renovation. It’s a proactive way to use your existing assets to fuel future growth without needing to find a separate source of capital.

Cracking the Code: What NZ Lenders Actually Look for When You Refinance

Lenders in New Zealand don’t just look at your bank balance. They focus on what I call the “Big Three”: the property, the person, and the profit. While home loans are mostly about your salary, commercial refinancing is a different beast altogether. Lenders want to see a clear “gap” between what you owe and what the property is worth. In 2026, most mainstream banks expect you to have at least 30 to 35 percent equity in the building. If your property value has climbed, that gap becomes your ticket to a better deal. They also look at your “character” as a borrower, including your experience in the industry and your history of managing debt effectively over the years.

Your Business Health and Income

When you apply to refinance, the lender needs to know you have the “ability to pay” without breaking a sweat. They look for a repayment cushion, usually wanting to see that your profit covers your interest costs by at least 1.2 to 1.35 times. It’s essential to have your books organised and up to date before you start the conversation. If your income is a bit lumpy or seasonal, don’t panic. Specialist lenders are often more comfortable with businesses that don’t have a perfectly flat income line every month, provided the overall annual profit is solid. Understanding the tax implications for commercial property is also part of this prep, as it affects your bottom line and how much cash you actually have available. If you’re unsure where your numbers stand, you can always check in with our team for a quick review of your position.

The Property Value and Type

Not all buildings are treated equally in the eyes of a bank manager. Currently, industrial properties like warehouses are the “golden child” for lenders because vacancy rates remain low, sitting around 4 percent in major hubs. These are often easier to finance than a highly specialised shop because a warehouse can be used by almost any business if the current tenant leaves. Retail spaces can be a bit more challenging, especially if they are designed for a very specific type of tenant. Lenders also look closely at your lease terms. A long-term lease with a reliable tenant makes your application much stronger and can often secure you a better interest rate. You will almost certainly need a fresh independent valuation as part of the process. This ensures the lender is working with current 2026 market values rather than what you paid for the place years ago. Having a recent valuation can often reveal that you have more equity than you thought, opening doors to better lending products.

Beyond the Big Banks: Exploring 2nd Tier and Non-Bank Options

Many Kiwis think the big four banks are the only game in town. But there is a whole world of “2nd tier” lenders that operate right across New Zealand. Simply put, these are financial institutions that aren’t registered banks but still provide substantial loans for business and property. They don’t have the same rigid “box-ticking” culture that you find at a main bank. If your current bank has said no, it is often just because you don’t fit their very specific, narrow criteria. It is rarely the end of the road. In fact, many successful business owners find that refinancing commercial property NZ with a non-bank lender is the smartest move they’ve ever made.

The Pros and Cons of Alternative Lenders

Approval times with these lenders are often much faster. While a big bank might take weeks to shuffle your paperwork between departments, a non-bank lender can often give you a “yes” in a matter of days. This speed is vital if you need to move quickly on a new opportunity. They are also far more flexible for self-employed people or those with seasonal income. As of mid-2026, interest rates for these loans typically range from 6.65 percent to 8.99 percent. While this is higher than a main bank, you have to weigh that cost against the cost of doing nothing. If a slightly higher rate allows you to grow your business or fix a cash flow crisis, it is a small price to pay for progress.

Is a 2nd Tier Loan Right for You?

These lenders shine when you have a short-term gap to fill or perhaps a few credit hiccups from the past that the big banks won’t forgive. They look at the “big picture” of your business rather than just a computer-generated score. At Mortgage Suite, we spend our time finding the hidden gems in the market that most people never hear about. We act as your advocate, negotiating with these lenders to get you the best possible terms for refinancing commercial property NZ. For a deeper look at how these options work, you can read our 2nd Tier Lender New Zealand guide. We help you bridge the gap between where you are now and where you want to be, ensuring you aren’t held back by rigid banking rules.

Refinancing Commercial Property NZ: Your 2026 Guide to Getting a Better Deal

Your Step-by-Step Plan to Getting Your Commercial Refinance Sorted

Refinancing commercial property NZ doesn’t need to be a confusing maze of forms and phone calls. While big banks might make it feel like you’re just another number in their system, a structured approach makes the whole thing much more manageable. It starts with a clear look at your current position and ends with a loan that actually serves your business. The first thing you should do is get a clear picture of what you currently owe and exactly what you’re paying in interest and fees. You can use our mortgage calculator to run some quick numbers and see how a lower rate might change your monthly commitments.

Once you know where you stand, it’s time to have a yarn with an expert broker. This is where we look at the strategy and see what’s possible in the current market. We’ll help you decide if a traditional bank or a more flexible alternative lender is the right fit for your specific goals. After that, we move into the application and approval phase. We handle the “bank-speak” and the back-and-forth negotiations, so you can stay focused on running your business. Finally, we reach settlement, where your old, expensive loan is paid off and your new, better deal begins.

Gathering the Right Paperwork

Collecting your documents is often the part people dread most, but it’s not as bad as you think when you have a clear list. To get started, your broker will typically need:

  • Your last two years of financial statements.
  • Current lease agreements for your tenants.
  • A recent mortgage statement showing your current balance.
  • Personal identification and proof of address.

Having a good accountant in your corner helps heaps during this stage. They can quickly pull the reports we need and ensure your numbers are presented in the best possible light for the lender. When your books are organised, the approval process moves much faster.

The Role of Your Mortgage Broker

We act as the bridge between you and the rigid world of institutional banking. Because we have over 20 years of experience, we know exactly how to package your application to get a “yes”. We often secure deals that you simply can’t get by walking into a local branch because we have access to different departments and a wider range of lenders. We do the heavy lifting, the negotiating, and the problem-solving on your behalf. You can meet the team to see the experts who will be advocating for your business throughout this journey.

If you’re ready to see how much you could save by moving your loan, reach out to Mortgage Suite today for a straightforward chat about your options.

Why Mortgage Suite is Your Secret Weapon for Commercial Refinancing

When you decide on refinancing commercial property NZ, you aren’t just looking for a new set of numbers on a page. You’re looking for a partner who can navigate the corridors of the big banks and the alternative lenders with their eyes closed. Krish Krishna brings over 20 years of deep banking experience to your side of the table. Having spent decades on the inside, he knows exactly how lenders think, what they’re afraid of, and what they need to see to say “yes”. This isn’t just about filling out forms; it’s about having a dedicated negotiator who knows how to push back when a bank tries to offer a sub-par deal.

We don’t just find loans. We find solutions that fit your actual life and your long-term business strategy. Whether you’re dealing with a bank that has become too restrictive or you need to access equity for a new project, we act as your advocate. We’ve helped countless Kiwis move away from faceless bank managers who don’t understand their industry. Our reputation is built on being tough but fair negotiators who don’t take “no” for an answer when we know a deal makes sense for the client.

A Personal Approach in a Corporate World

In a world where banking has become increasingly clinical and automated, we choose to keep things personal. We treat your business like it’s our own because we know how much is on the line for you. You won’t hear any confusing jargon or feel any judgment from us, regardless of your current financial situation. We offer honest, straightforward advice that focuses on your success. If you want to see how we’ve helped others in similar spots, you can check out our Reviews to see what other property owners reckon about working with us.

Ready to See What You Could Save?

Getting started doesn’t involve a mountain of paperwork or a formal commitment right away. It begins with a simple, no-obligation chat. When you first speak with Krish, you’ll find a mentor who listens more than he talks. He’ll take the time to understand your goals, your challenges, and your vision for the future. By the end of that first conversation, you’ll have a much clearer idea of what’s possible for refinancing commercial property NZ and how we can help you get there. If you’re ready to stop overpaying and start growing, Get in touch with Mortgage Suite today and let’s get your refinance sorted.

Take Control of Your Business’s Financial Future

Refinancing is more than just a paperwork exercise; it’s a strategic move to protect your cash flow and fuel your next big venture. By now, you should have a clearer understanding of how refinancing commercial property NZ can lower your costs and why looking beyond the big banks often leads to the most flexible solutions. Whether you’re dealing with restrictive bank terms or just want to see what your equity can actually do for you, you don’t have to navigate these complex decisions alone.

With over 20 years of banking expertise and a reputation as specialists in 2nd tier lending, we’re here to ensure you get a deal that actually fits your life. We’re proud to be highly rated by New Zealand business owners who value a personal touch over a faceless corporate process. You’ve worked hard to build your business, so make sure your mortgage is working just as hard for you. Talk to Krish about your commercial refinance today and let’s find the right path forward together.

Frequently Asked Questions

How much does it cost to refinance commercial property in NZ?

Refinancing involves several standard costs such as legal fees for discharging your old mortgage and registering the new one. You will also likely need to pay for an independent valuation to confirm the building’s current worth. If you are leaving a fixed-term contract early, your current bank might charge break fees. We help you calculate these expenses beforehand to ensure the move actually saves you money in the long run.

Can I refinance if my commercial property is currently vacant?

You can certainly refinance a vacant building, though main banks often find this risky because there is no immediate rental income. Specialist 2nd tier lenders are usually more flexible in these scenarios. They will look at the property’s location, its seismic rating, and your plan for finding a new tenant. Having a solid business track record helps heaps when the building is currently empty and you need a fresh start.

Do I need a new valuation to refinance my business property?

Most lenders will require a fresh, independent valuation as part of the process. They need to know the current 2026 market value to determine how much they can safely lend. Since property values have shifted recently, a new report often reveals you have more equity than you thought. This extra equity can be a powerful tool when you are looking into refinancing commercial property NZ for a better interest rate.

How long does the commercial refinancing process usually take?

The timeframe depends heavily on which lender you choose for your business. Traditional banks can take anywhere from four to eight weeks to process everything through their various departments. If you are in a rush to secure a deal, non-bank lenders are much faster and can often provide a “yes” within a few days. We manage the back-and-forth communication to keep things moving as quickly as possible for you.

What is the maximum I can borrow against my commercial property?

For most commercial properties in New Zealand, mainstream banks will typically lend up to 65 or 70 percent of the property’s value. Some non-bank lenders are willing to go slightly higher, potentially up to 75 percent for high-quality industrial buildings. The exact amount depends on the property type, the strength of your lease, and your business’s ability to cover the interest repayments comfortably without any financial stress.

Can I consolidate other business debts into my commercial mortgage?

Consolidating business debts into your commercial mortgage is a very common and effective strategy. It allows you to move high-interest debt, like equipment finance or business credit cards, into a single loan with a much lower interest rate. This move can significantly improve your monthly cash flow. It simplifies your finances by leaving you with just one manageable payment instead of juggling multiple different lenders every month.

What happens if I have a bad credit history but own a commercial property?

Having a credit hiccup from the past doesn’t automatically mean you can’t refinance your property. While main banks are very strict about credit history, 2nd tier lenders focus more on the value of the property and your plan to move forward. As specialists in these alternative loans, we know which lenders look past the computer-generated score to see the real potential in your business and your assets.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

You’ve spent months searching for the right property, only to have your long-term bank turn you down at the final hurdle. It’s a frustrating, anxious experience that makes you feel like the system is working against you, especially with the strict debt-to-income rules currently in play. If you’re wondering what to do when bank declines mortgage nz, the first thing to remember is that a “no” from a mainstream lender isn’t the end of your journey. It’s often just a sign that you need a more flexible, expert approach to get the deal across the line.

We understand the sting of being rejected by a bank you’ve been loyal to for years. This guide shows you how to turn that setback into a successful purchase by using 2nd tier lenders as a strategic bridge. You’ll learn how these specialist providers work outside the rigid boxes of traditional banks and why a smart exit strategy is your ticket back to mainstream rates in a year or two. We’ll walk through the 2026 market conditions and give you a clear, professional plan to secure your loan and move into your new home with confidence.

Key Takeaways

  • A rejection from a main bank doesn’t mean your home-buying dreams are over; it’s simply a signal to switch to a more flexible 2nd tier lender.
  • Discover exactly what to do when bank declines mortgage nz by shifting the focus to your unique “borrower story” and long-term potential.
  • Learn why matching your specific financial situation to a specialist lender’s unique criteria is the secret to turning a decline into an approval.
  • Get a clear view of the temporary costs involved and how these non-bank options serve as a vital bridge to your property goals.
  • Master the exit strategy that allows you to “graduate” back to a mainstream bank within 12 to 24 months once your situation has stabilised.

What is a 2nd Tier Loan and Why is it Your Best Plan B?

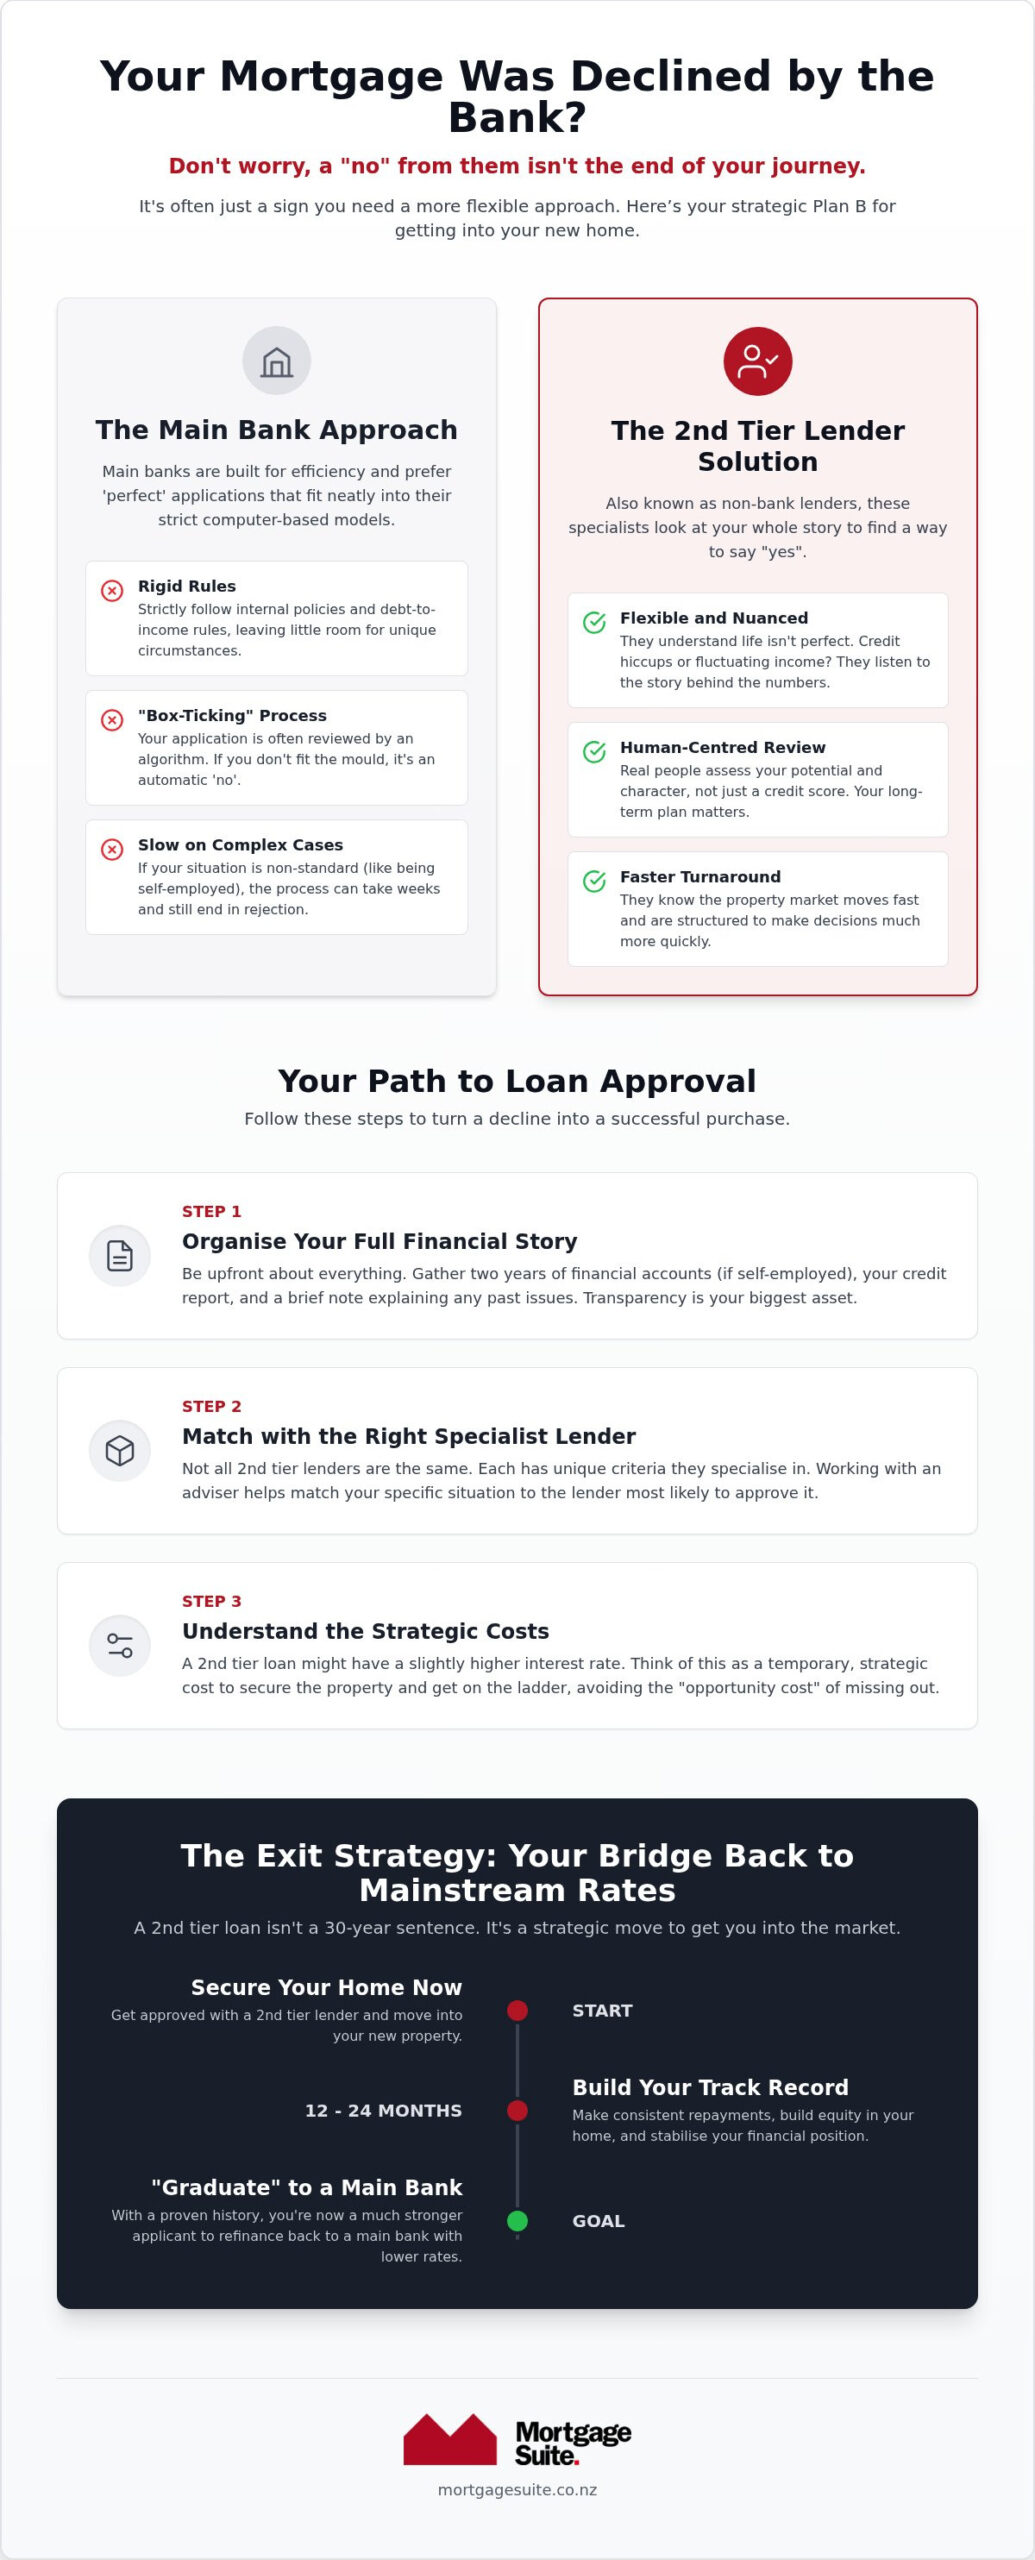
Getting a “no” from a main bank feels like a dead end, but in the New Zealand property market, it’s often just the start of a different conversation. Most people are taught that if the big four banks won’t help, nobody will. That isn’t true. A 2nd tier loan is a flexible, regulated alternative for unique financial situations. These lenders operate differently from the high-street names you see in every shopping centre. They provide a vital path forward when you’re figuring out what to do when bank declines mortgage nz.

Second-tier lenders are often called “non-bank” lenders. They don’t take deposits from the public like a traditional bank does. Instead, they raise their own capital to lend out. Because they aren’t bound by the same rigid internal rules as the main banks, they can look at your application with much more nuance. They are specialists in finding ways to say “yes” when a computer algorithm at a main bank has already said “no”.

The Difference Between Main Banks and Alternative Lenders

Main banks are designed for efficiency. They love “perfect” applications where every piece of data fits into a pre-defined box. If you’re self-employed with a fluctuating income, or if you have a slightly smaller deposit than the current 2026 regulations prefer, you might not fit that box. This is where a non-bank financial institution shines. They take the time to look at your whole story rather than just your credit score.

Speed is another major factor. While a main bank might take weeks to process a complex application, alternative lenders are often much faster. They understand that property deals move quickly and that you can’t afford to wait. The trade-off is usually a slightly higher interest rate or different fee structure, but for many Kiwis, this is a small price to pay to secure a home in a competitive market. To understand how these different options affect your long-term plans, you can explore the resources in our mortgage school.

Dispelling the Myths About Non-Bank Lending

There’s a common misconception that anything outside a main bank is risky or untrustworthy. It’s time to clear that up. These lenders are reputable, highly regulated businesses that must follow the same consumer protection laws as any other financial provider. They aren’t “loan sharks”; they are professional advocates for borrowers who need a bit more flexibility.

Think of a 2nd tier loan as a strategic stepping stone. It isn’t necessarily a thirty-year commitment. Instead, it’s a way to get into the market now, build equity, and prove your reliability. By the time you’ve held the loan for a year or two, you’ll often be in a much stronger position to “graduate” back to a main bank. Knowing what to do when bank declines mortgage nz often starts with embracing this tactical “Plan B” to keep your home-ownership goals on track.

How to Prepare Your 2nd Tier Loan Application

Preparing for a non-bank application is quite different from a standard bank meeting. It’s about building a comprehensive case for yourself. When you’re stuck on what to do when bank declines mortgage nz, your first move should be gathering every detail of your financial life, even the bits you’re worried about. Being upfront is your greatest asset in this process. If there’s a skeleton in the closet, it’s better to bring it out now rather than let a lender find it later. 2nd tier lenders invest in people and their potential, not just a credit score, so they value transparency and a clear plan over a perfect history.

The Essential Paperwork You Will Need to Organise

You’ll need to look beyond the standard documents a main bank asks for. If you’re self-employed, gather your full financial accounts and tax returns for the last two years. Lenders want to see the real-world consistency of your earnings, even if they don’t fit a standard salary pattern. If you’ve had a credit hiccup in the past, get a copy of your credit report and prepare a brief, honest note explaining the circumstances. These lenders are professional, regulated, and often belong to independent dispute resolution bodies, which ensures you’re treated with fairness throughout the application. You should also have the specific details of the property you’re eyeing ready, as the type of dwelling often impacts the lender’s risk assessment.

Telling Your Story to the Lender

This is where you move beyond the columns of a spreadsheet. A main bank might see a dip in your income from eighteen months ago and decline you without a second thought. A 2nd tier lender will listen if you explain that the dip was a one-off event, such as a temporary illness or a strategic business pivot. You need to show them that your plan for future financial stability is robust and well-thought-out. This is exactly why having a veteran negotiator on your side is a game-changer. We know how to “translate” your unique life situation into the specific language that non-bank lenders understand. If you’re ready to start building your case and want to work with a partner who knows the system, you can learn more about us and how we advocate for our clients. Knowing what to do when bank declines mortgage nz is all about presenting your future potential as clearly as your financial past.

Choosing the Right Lender for Your Specific Situation

Every non-bank lender in New Zealand has its own “personality” and set of rules. Unlike the main banks, which all tend to follow very similar guidelines, 2nd tier lenders often specialise in specific types of borrowers. One might have a high appetite for helping people buy existing family homes with smaller deposits, while another might focus almost entirely on business owners with complex tax structures. Finding what to do when bank declines mortgage nz often comes down to knowing which of these hundreds of options is the right fit for your specific hurdle.

The challenge for most Kiwis is that these lenders don’t usually advertise on television or have branches on the high street. They work primarily through specialist brokers who understand their unique criteria. Matching your situation to the right lender is a bit like solving a puzzle. It requires a deep understanding of how each provider views risk and what kind of “borrower story” they find most compelling. This is where Mortgage Suite Ltd and our 20-plus years of expertise become your biggest advantage, as we know exactly which door to knock on to get your deal across the line.

Lenders Who Favour the Self-Employed

If you run your own business, you’ve likely discovered that main banks struggle with income that isn’t a steady, fortnightly salary. Many 2nd tier lenders were built specifically to solve this problem. They offer what we call “low-doc” options. In plain English, this simply means they use alternative ways to verify your income, such as looking at your business bank statements or a simple letter from your accountant, rather than demanding years of perfect tax returns. They focus on your current ability to manage repayments and the overall health of your business, giving you the credit you deserve for your hard work.

Options for Credit Hiccups or Smaller Deposits

A past financial setback or a deposit that doesn’t quite hit the 20 per cent mark for an existing home can lead to an instant decline from a main bank. However, some lenders specialise in “recovery” loans. They look at your “risk grade”-a professional assessment of your current reliability-and offer a path forward even if your history isn’t spotless. Unlike some competitors who suggest that new builds are the only way to buy with a small deposit, we find lenders who are happy to support you in buying an existing property. These loans act as a vital bridge, allowing you to secure your home now while you work on improving your financial position for the future.

Knowing what to do when bank declines mortgage nz is about looking beyond the surface and finding a partner who sees the value in your specific situation. With the right lender, that initial rejection becomes nothing more than a temporary detour on your way to home ownership.

What to Do When the Bank Declines Your Mortgage in NZ: A 2026 Guide

Understanding the Costs: Rates, Fees, and the “Opportunity Cost”

When you’re trying to figure out what to do when bank declines mortgage nz, the numbers on the page can feel a bit heavy. It’s true that 2nd tier lenders charge higher interest rates than the main banks. This is because they’re taking on more risk by looking at applications that don’t fit the standard criteria. However, it’s vital to view these costs as a tactical investment rather than a permanent burden. You can use our Mortgage Calculator to see how these different rates look in reality and how they might fit into your monthly budget.

Interest Rates vs. The Cost of Missing Out

The real question isn’t just “how much is the interest?” but “how much will it cost me to wait?”. With inflation currently sitting at 3 per cent and the property market constantly shifting, staying on the sidelines can be expensive. If house prices rise while you’re spending another year or two saving for a larger deposit, you might find yourself priced out of the very suburb you want to live in. Most of our clients don’t stay on a 2nd tier rate forever. We view these loans as a 12-to-24-month bridge. When you calculate the “real” cost over this short period, the extra interest is often far less than the potential growth in your home’s value during that same time.

Think of it as a temporary premium for speed and flexibility. By getting into the market now, you start building equity immediately. You’re no longer paying rent to someone else, and you’re finally on the property ladder. This strategic move allows you to “graduate” back to a main bank once your financial situation has stabilised or you’ve proven your repayment history to the wider market.

Upfront Fees and Budgeting

Beyond the interest rate, you’ll need to budget for specific upfront costs. These typically include establishment or application fees, which cover the intensive manual assessment required for alternative lending. You’ll also need to factor in valuation reports from approved professionals and legal costs that might be slightly higher due to the complexity of the contracts. It’s also worth checking the early exit terms. Since the goal is to move back to a main bank as soon as possible, you want to ensure your loan structure allows for that transition without heavy penalties. If you want a clear, honest breakdown of how these costs apply to your situation, get in touch with us today for a professional assessment. We’re here to ensure there are no surprises on your journey to home ownership.

The Exit Strategy: How to Move Back to a Main Bank

Securing a 2nd tier loan is a massive win, but it’s rarely the final stop on your home ownership journey. We always encourage our clients to view this as a temporary bridge rather than a thirty-year commitment. The goal is simple: use this period to stabilise your finances and build a solid track record. When you’re considering what to do when bank declines mortgage nz, the long-term plan is just as important as the immediate approval. We work with you to set a clear 12-to-24-month target to “graduate” back to a main bank, where you can access lower interest rates and standard terms.

Cleaning Up Your Financial Profile

Your time with a 2nd tier lender is your chance to prove to the main banks that you’re a reliable borrower. The most critical factor here is maintaining a perfect repayment history. Every single payment on your new loan must be on time, without exception. This shows future lenders that your previous credit hiccup is firmly in the past. At the same time, focus on reducing other liabilities. Paying down credit cards or clearing car finance can significantly improve your debt-to-income ratio, which is a key metric for banks in 2026. If you’re a first-time owner, our Home Loans for First Home Buyers Guide offers deeper insights into how these factors influence bank decisions.

Don’t forget that as property values potentially grow, your equity increases. A higher equity position naturally lowers the bank’s risk, making it much easier to qualify for those competitive rates you missed out on initially. We’ll keep an eye on the market with you to identify the best moment to make your move.

Working with Your Broker on the Move

You shouldn’t wait until your fixed term is nearly over to start thinking about the switch. We usually begin the conversation about six months before your target graduation date. This gives us enough time to review your polished profile and identify any final adjustments needed. Re-applying with a year of perfect mortgage history and a cleaner debt profile allows you to walk into a main bank with genuine confidence. We don’t just secure your first loan and disappear; we stay with you for the whole journey. Our reputation is built on these long-term partnerships, helping Kiwis navigate what to do when bank declines mortgage nz and eventually seeing them successfully refinance into the mainstream banking system.

Take the Next Step Toward Your New Home

A bank decline is often just a nudge toward a more flexible path. By choosing a 2nd tier loan as a strategic bridge, you can secure your property now and build a solid foundation for a future return to a main bank. Knowing what to do when bank declines mortgage nz means looking past the initial rejection and focusing on your long-term potential. We’ve seen how a clear exit strategy and professional advocacy can transform an anxious situation into a successful purchase.

With over 20 years of expert banking and brokerage experience, we specialise in finding “outside the box” lending solutions that the big banks often ignore. You can read our client reviews to see how we’ve helped other Kiwis succeed where they once felt stuck. If you’re ready to move forward, book a friendly chat with Mortgage Suite to find your path forward. Your home ownership goals are still within reach, and we’re here to help you navigate the system with confidence.

Frequently Asked Questions

Is it harder to get a 2nd tier loan than a main bank loan?

Getting a 2nd tier loan is often more straightforward than a main bank loan because these lenders have more flexible criteria. While main banks rely on rigid “yes” or “no” computer models, alternative lenders take a manual approach to understand your whole financial story. They are specialists in finding ways to approve applications that don’t fit the standard box, making them a reliable path when you’re stuck on what to do when bank declines mortgage nz.

Can I still get a home loan if I have a bad credit history?

You can absolutely secure a home loan with a less-than-perfect credit history by working with a specialist non-bank lender. These providers are designed to help borrowers who have had past financial setbacks. Instead of a flat rejection, they look at your current stability and your plan for the future. They assess the “risk grade” of your application and offer a loan structure that reflects your specific recovery journey, helping you move forward with confidence.

What are the typical interest rates for non-bank lenders in 2026?

In the 2026 market, interest rates for non-bank lenders vary based on your specific situation. For “near-prime” borrowers with good credit, rates are typically 1 to 2 per cent higher than mainstream bank rates. If your application is more complex or involves significant credit issues, specialist rates can range between 10 per cent and 14.5 per cent. These higher rates reflect the extra risk the lender takes on to help you get into the property market.

How long does the 2nd tier loan application process take?

The application process with a 2nd tier lender is often significantly faster than a main bank, sometimes taking just a few days for an initial approval. Because these lenders aren’t bogged down by the same massive institutional layers, they can make decisions quickly once they have your full paperwork. This speed is a huge advantage when you’re competing for a property and need a clear answer on what to do when bank declines mortgage nz.

Do I really need a mortgage broker to access these lenders?

While you can technically approach some lenders yourself, most 2nd tier providers in New Zealand deal exclusively through professional mortgage brokers. A broker acts as your advocate, translating your “borrower story” into the specific format these lenders require. We have access to hundreds of different criteria sets and know exactly which specialist provider is most likely to say yes to your unique situation, saving you time and protecting your credit score.

What happens if I want to pay off my 2nd tier loan earlier than planned?

You can pay off your 2nd tier loan early, but you should always check the specific terms for early exit fees. Since these loans are often intended as a temporary bridge, many are structured with flexibility in mind. However, some lenders include a minimum term or a set fee to cover their setup costs. We ensure you understand these details upfront so your plan to move back to a bank remains cost-effective and clear.

Will a 2nd tier loan affect my ability to get a bank loan later?

Holding a 2nd tier loan actually strengthens your future bank application, provided you maintain a perfect repayment history. Successfully managing a non-bank loan proves to mainstream lenders that you are a reliable, low-risk borrower. This track record is exactly what banks look for when they consider taking you back. It serves as a professional “graduation” certificate that demonstrates your financial stability has been fully restored after your initial hurdle.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Your business success should be your greatest mortgage asset, not the reason a bank says no. It’s a common frustration for New Zealand entrepreneurs who feel penalised for their drive and independence. You’ve likely heard that traditional low doc home loans nz are harder to find now that the Financial Markets Authority has taken over credit regulation, but that doesn’t mean your home ownership dreams are over. We understand that your business bank statements often tell a much more accurate story than a standard tax return ever could.

You deserve a clear path to approval that doesn’t involve a mountain of confusing paperwork or endless anxiety. In this guide, we’ll show you exactly how to handle the 2026 lending market to get your home loan sorted. We will explore the rise of alternative documentation options, explain how second-tier lenders operate, and provide a step-by-step strategy to move from a bank decline to a front door key in your hand.

Key Takeaways

  • Being self-employed is a major achievement, and we will show you how to use your business success as an asset rather than a hurdle when applying for a mortgage.
  • Learn how traditional low doc home loans nz have evolved into flexible alternative documentation options from safe, regulated lenders who actually understand your business story.
  • Discover the specific, simple paperwork you need to show your true income without the stress of overwhelming accounting jargon or complex bank requirements.
  • Get practical tips on how to tidy up your accounts and why paying yourself a consistent salary can significantly boost your chances of loan approval.
  • Find out how to partner with a veteran advocate who knows the non-bank market inside out and will fight to get you into a home when the big banks say no.

What does it mean to get a mortgage for self-employed NZ borrowers?

At its heart, a self-employed mortgage is just a standard home loan. It’s helpful to understand what is a mortgage in the broadest sense: a way to secure property using the equity you build over time. For you, the only real difference is how you prove you can afford the repayments. Banks often see your business as a risk, but we see it as a massive achievement. Whether you’re a tradie on the tools or a freelancer working from a home office, your drive shouldn’t be a hurdle to getting your own place.

Many Kiwis feel like they’re being penalised for their entrepreneurial spirit. If a mainstream bank has already said no, you might think you’re out of options. The market for low doc home loans nz has evolved significantly. While the big banks are often stuck in a cycle of strict criteria, other lenders are more interested in your actual business story and your ability to manage money. We help everyone from company directors and contractors to sole traders find a path forward.

Why the big banks treat you differently

Banks love predictability. They want to see a payslip that looks exactly the same every fortnight. When you run your own show, your income might go up and down depending on the season or when a big contract finishes. Mainstream lenders also tend to focus purely on your taxable income. Because you likely work with an accountant to legally minimise your tax, your “on paper” profit might look much lower than the actual cash you have available to pay a mortgage. In 2026, banks are using test rates around 7% to see if you can handle repayments. For a business owner with fluctuating income, meeting that hurdle while staying under the debt-to-income (DTI) cap of 6 can feel impossible without an expert in your corner.

The different types of self-employed income

Not all self-employment is the same. A full-time contractor might have a steady stream of work from one source, while a small business owner manages staff and overheads. Sometimes, a one-off business expense, like a new piece of machinery or a vehicle, can confuse a bank’s computer system and make it look like your business is struggling. If you’re just starting out on this journey, our First Home Buyer Guide is a great place to see how the basics apply to you. Specialised low doc home loans nz or alternative documentation options can bridge this gap by looking at your GST returns or bank statements instead of just a standard tax summary.

The paperwork you will need to get sorted

Gathering a mountain of files can feel like a full-time job. It’s often the point where many entrepreneurs give up before they’ve even started. You might worry that your accounts aren’t perfect or that a single quiet month will ruin your chances. In 2026, the concept of low doc home loans nz has shifted. It no longer means “no documents” at all. Instead, it refers to alternative documentation that fits your life better than a standard payslip. We act as your mentor through this process, helping you pick out the right files to show your financial strength.

The Big Three documents

Lenders typically focus on three core areas to understand your situation. First, your financial statements tell the story of your business profit and loss. We keep this simple. It’s about showing that your business is a viable, living entity. Second, you’ll need tax summaries from the IRD to prove your official earnings. Finally, personal bank statements are vital. Under current regulations managed by the Financial Markets Authority, lenders often look for at least six months of business bank statements to verify your cash flow. These personal records show how you handle your household budget and prove you can manage the commitment of a home loan.

Proving your future income

Banks are naturally cautious, so showing them a bright future is just as important as showing a solid past. If you have a stack of signed contracts or a healthy pipeline of work for the coming year, these are massive assets for your approval. A simple letter from your accountant can also go a long way. They can explain the longevity of your business and why certain one-off expenses shouldn’t count against you. Essentially, income verification is just the process of proving you have the actual cash on hand to cover your repayments without struggle.

If you’re feeling overwhelmed by the requirements, it’s often helpful to see what others in your position have achieved. You can read through our client reviews to see how we’ve helped other self-employed Kiwis get their paperwork sorted and their loans approved.

When the bank says no: Exploring 2nd tier and alternative lenders

Hearing a “no” from a mainstream bank can feel like a punch in the gut. You’ve worked hard to build your business, and being told you aren’t “predictable” enough is discouraging. It’s important to remember that a bank’s rejection isn’t a reflection of your business success. It’s simply a sign that you don’t fit their very narrow, rigid box. This is where 2nd tier lenders come in. These are professional, safe, and fully regulated finance companies that operate without the big bank branding. They specialise in low doc home loans nz because they have the freedom to look at the person and the business story, not just a standard spreadsheet.

Using a non-bank lender isn’t a last resort. It’s a strategic move used by many of New Zealand’s most successful entrepreneurs. These lenders are solution-based. They understand that a business owner’s wealth is often tied up in growth and assets rather than a static salary. For a deeper dive into how these finance companies can help you, check out our 2nd Tier Lender Guide.

Mainstream Banks vs. 2nd Tier Lenders

The differences between these two worlds are significant. Mainstream banks offer lower interest rates, but their rules are incredibly strict and their processes are often slow. If you don’t have two years of perfect, steady tax returns, they’ll likely struggle to say yes. In contrast, 2nd tier lenders offer more flexible rules. As of mid-2026, while mainstream rates for one-year fixed terms sit around 4.8%, non-bank rates for alternative documentation loans typically start from about 6.35%.

A 2nd tier loan is often used as a vital stepping stone. You can secure your home now, build equity for 12 to 24 months, and then refinance with a mainstream bank once your accounts have settled into a pattern the banks recognise. This proactive approach gets you into the property market years sooner than waiting for a bank’s approval.

The benefit of a specialised negotiator

Because the non-bank world is diverse, having a veteran mentor on your side is vital. We don’t just pass on your paperwork. We act as your advocate, carefully presenting your business to the right lender to ensure they see your success rather than a risk. Krish Krishna’s 20 years of industry experience means he knows exactly which lenders are currently looking for businesses like yours. We know how to tell your story in a way that opens doors that might otherwise stay shut. Our goal is to remove the stress and provide a clear, confident path to your new home.

Mortgage for Self Employed NZ: How to Get Your Home Loan Sorted in 2026

Steps to improve your chances of approval

Preparing for a mortgage when you’re your own boss is all about presentation. Think of it like dressing your business up for an interview. One of the most effective things you can do is keep your personal and business expenses completely separate. When your accounts are clean, it’s much easier for a lender to see that your business is thriving and that you have the cash flow to handle a home loan. This clarity is especially important when we’re looking at low doc home loans nz, as it allows the lender to trust the alternative documents we provide.

Another great move is to pay yourself a consistent salary. Even if you own 100% of the company, regular transfers into your personal account look fantastic to a lender. It mimics the predictability of a standard job, which banks find very reassuring. You should also look at managing your existing debt. Clearing a car loan or closing an unused credit card can significantly boost how much you’re allowed to borrow. Before you get too far down the track, it’s a smart idea to use our mortgage calculator to see what a realistic repayment looks like for your budget.

Clean up your personal bank statements

In the three months before you apply, try to avoid any unusual spending spikes. Lenders look closely at your day-to-day habits to see how you’ll handle a mortgage. This is also the time to pause any “buy now, pay later” schemes. While they’re handy for small purchases, lenders often view them as a line of credit that reduces your overall borrowing power. Being squeaky clean with your bill payments and regular outgoings shows that you’re disciplined and reliable.

Timing your application

Timing can be everything. If you’ve just made a massive business investment, like buying new machinery or a fleet of vehicles, your cash reserves might look a bit low. It’s often better to wait until those investments start showing a return. The sweet spot for many self-employed Kiwis is right after the end of the financial year on March 31st. This is when your latest figures are fresh and your accountant can provide the most up-to-date proof of your success. Loan readiness is about showing you are a safe pair of hands. If you’re ready to see what’s possible for your business, get in touch with us today to start the conversation.

How Mortgage Suite helps self-employed Kiwis get home

At Mortgage Suite Ltd, we don’t believe your business success should be a barrier to buying a home. We take an advocacy-led approach to every application. This means we don’t just bundle up your paperwork and hope for the best. We actively fight your corner with lenders to make sure they see the full value of what you’ve built. Because we are a business ourselves, we understand the long hours and the dedication it takes to be your own boss. We aren’t a cold corporate office; we are your partners in this process. Whether you’re looking for a property in the far north or the deep south, our national reach means we can help you secure a home anywhere in New Zealand.

If you’re curious about how this works in practice, we encourage you to read our client reviews. You’ll see stories from other Kiwis who thought their dream was over after a bank decline, only to find a path forward with us. We know that every business has a unique story, and we make it our mission to ensure that story is heard by the right people.

A personal approach from an industry veteran

Krish Krishna brings over two decades of banking and finance experience to the table. He uses this deep institutional knowledge to navigate the often complex world of low doc home loans nz and alternative lending. The Mortgage Suite Ltd way is about removing the weight from your shoulders. We aim to make a process that usually feels overwhelming into something that is sorted and stress-free. You can learn more about us and our philosophy of partnership. We believe in building long-term relationships, not just processing one-off transactions.

Your next steps to home ownership

Taking the next step doesn’t have to be scary. Our first conversation is simply about understanding your goals and where you want to go. There is absolutely no pressure and definitely no confusing jargon. We’ll look at your current situation and build a clear, actionable plan together. Our goal is to move you from a “declined” status to a firm approval. You’ve already done the hard work of building a successful business. Now, let’s work together to build your future in a home you actually own. Getting your low doc home loans nz sorted is much easier when you have a veteran mentor who knows exactly which levers to pull.

Take the lead on your home ownership journey

Building a business is a major achievement that proves you have the drive to succeed. While big banks might focus on rigid boxes, you now know that alternative documentation and second-tier lenders offer a professional, regulated path to your new home. Securing low doc home loans nz is about finding the right lender who understands your unique story and sees your success as an asset. By tidying your accounts and paying yourself a consistent salary, you’re already halfway there.

With over 20 years of banking expertise, our team at Mortgage Suite acts as your dedicated negotiator. We specialise in non-bank and second-tier lending, and we know exactly how to open doors that mainstream lenders often keep shut. We’ll handle the complex paperwork so you can focus on what you do best: running your business. Ready to get your mortgage sorted? Book a chat with the Mortgage Suite team today. Your entrepreneurial spirit has built your business, now let’s use it to build your future in a home of your own. You’ve got this.

Frequently Asked Questions

Can I get a mortgage if I’ve only been self-employed for one year?

Yes, you certainly can. While major banks typically look for two years of accounts, many second tier lenders only require six to twelve months of trading history. We focus on showing the strength of your business through GST returns and bank statements. If your industry experience is solid and your current cash flow is healthy, we can often find a solution that gets you into a home much sooner than a bank would allow.

Do I need a bigger deposit if I’m self-employed in NZ?

Not always, but it helps to be prepared. If you fit a bank’s standard criteria, a 20% deposit is the norm. For those using low doc home loans nz or alternative documentation, lenders might ask for 20% to 30%. This larger deposit acts as a safety net for the lender. However, we have seen cases where a smaller deposit is possible depending on the strength of your business story and the specific property you are buying.

What is a low doc loan and is it right for me?

In 2026, these are often called “alt doc” loans. They are designed for business owners who have a solid income but don’t have standard tax returns ready yet. Instead of IRD summaries, the lender looks at your bank statements or GST filings. It’s a great fit if you’ve recently invested back into your business or have a complex income structure that a standard bank computer doesn’t understand or recognise as stable.

Will I have to pay a higher interest rate because I work for myself?

Not necessarily. If you qualify for a standard bank loan, your rate will be the same as any other borrower. However, if you need the flexibility of a non-bank lender, you should expect to pay a bit more. As of mid-2026, non-bank rates for low doc home loans nz often start around 6.35%. Many of our clients see this as a temporary cost to get into the market before refinancing later on.

Can I use my business profit to help with my mortgage application?

Absolutely. Lenders focus on your net profit before tax. We also work with your accountant to identify “add-backs.” These are one-off business expenses, like a new vehicle purchase or depreciation, that shouldn’t count against your ability to pay a mortgage. By adding these back into your profit, we can often show a much stronger income than what appears on your final tax bill, which helps with your borrowing power.

What happens if my business had a bad year recently?

A single quiet year isn’t an automatic decline. We look at the reason behind the numbers. If you had a dip because of a strategic investment or a one-off event, we can explain that story to a lender. Many second tier lenders are happy to look at your most recent six months of trading to see that your business has recovered and is currently performing well. It’s about showing your current financial health.

How do I prove my income if I’m a contractor?

Proving income as a contractor is all about showing your track record. Lenders will want to see your current signed contracts, your GST returns, and at least six months of business bank statements. They look for a pattern of regular payments and a healthy pipeline of future work. If you’ve been in the same industry for a long time, that experience counts for a lot even if you are relatively new to contracting.

Why should I use a broker instead of going straight to my bank?

Your bank only has one set of rules and one list of products. If you don’t fit their box, they simply say no. A broker has access to dozens of lenders, including specialised second tier companies that don’t deal with the public directly. We act as your advocate, using over twenty years of experience to tell your business story to the right person. We find the “yes” that your bank might have missed.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How Much Deposit for an Investment Property in NZ? Your 2026 Guide

What if the biggest barrier to starting your rental portfolio isn’t actually a massive pile of cash, but simply knowing how to unlock the value you already own? Many Kiwis feel stuck behind a wall of confusing finance rules, worried that their local bank will say no because they don’t fit a perfect mould. It is completely natural to feel a bit uncertain when you’re trying to figure out how much deposit for investment property nz requires in today’s shifting market.

We understand that you want clear answers so you can move forward with confidence. In this 2026 guide, we promise to break down the exact percentages you need for both new builds and existing homes. You will discover how to use your current home as security, potentially removing the need for a cash deposit entirely. We will also explore reliable paths to getting a loan even if the mainstream banks aren’t being helpful, ensuring you have the support of a steady hand as you grow your property wealth.

Key Takeaways

  • Learn why the current rules often require a 35% deposit for existing homes, but how you can get started with just 20% if you choose a new build.
  • Discover how to figure out how much deposit for investment property nz is required by using the “hidden” value in your own home instead of your savings account.
  • Explore how 2nd tier lenders can help you secure a loan and provide a path forward even if the big banks have said no to your application.
  • Get a clear plan for organising your paperwork and “cleaning up” your bank statements to ensure your loan gets across the line.
  • Understand how to use your home equity as a steady bridge to help you grow your property portfolio faster and more reliably.

Understanding NZ Investment Deposit Requirements in 2026

When you’re trying to figure out how much deposit for investment property nz lenders require, it’s best to think of it as your entry fee into the market. A deposit is simply the portion of the property price you pay upfront, while the bank covers the rest. In 2026, the Reserve Bank of New Zealand (RBNZ) continues to use these rules as a way to keep the national economy stable. They want to ensure that if property prices move around, both you and the bank are protected by a solid buffer.

You don’t always need a pile of cash sitting in a savings account to get started. While a cash deposit is the most straightforward method, many successful Kiwis use the equity in their current home instead. Equity is the gap between what your house is worth today and what you still owe the bank. This year is particularly unique because while deposit percentages have stayed firm, the way banks look at your total debt has become much more detailed. It’s no longer just about the cash you have; it’s about your overall financial health.

Why do investment deposits differ from home loans?

Banks view investment loans through a different lens than the mortgage on your own home. It comes down to risk. If money gets tight, most people will do whatever it takes to keep the roof over their own heads, but they might let a rental property go first. Because of this, lenders ask for a larger safety net to protect their investment. To keep things simple, Loan-to-value (LVR) rules are basically the bank’s way of saying they’ll only lend you a specific percentage of what the property is actually worth.

The “standard” vs. “special” deposit requirements

For an existing house, most big banks will ask for a 35% deposit, though you may find some lenders accepting 30% in specific cases. However, if you’re looking at a new build, you might only need 20%. This is a significant difference that can change your entire investment strategy. Your income also plays a massive role. Even if you have a huge deposit, the bank will check if your earnings can cover the repayments if interest rates were to rise. If you’re just starting to explore these ideas, our Mortgage School is a great place to get a handle on the basics before you dive into the deep end.

Is it 20% or 35%? The LVR Rules Explained

LVR is simply the bank’s way of measuring how much they’re lending compared to what the house is worth. If you’re buying a property for $1 million and the bank lends you $650,000, your LVR is 65%. The remaining $350,000 is your deposit. The Banking Ombudsman Scheme provides helpful guidance on how these lending limits are applied to protect consumers across the country. These rules act as a safety net for the entire financial system, ensuring that both the borrower and the lender have a bit of breathing room if market prices change.

Deciding how much deposit for investment property nz banks expect depends largely on the age of the house you want to buy. For most existing homes, the standard rule is a 35% deposit, though some lenders may allow 30% depending on your overall financial position. However, this isn’t a one size fits all situation. Different lenders have different appetites for risk. Some non-bank options might offer more flexibility if your situation is a bit unique or if the big banks have already turned you away. Knowing how much deposit for investment property nz lenders will ask for is the first step in planning your next move.

The New Build advantage for NZ investors

A “New Build” is typically defined as a property bought from a developer within six months of being completed. The government and the Reserve Bank encourage these because they add to the total housing supply in New Zealand. Because of this, you usually only need a 20% deposit. This smaller entry point allows you to keep more cash in your pocket or spread your capital across more properties. It’s a popular strategy for those looking to grow a portfolio quickly without needing a massive upfront sum. Choosing a fresh build also means you often face fewer maintenance costs in those first few years, which helps your cash flow stay steady.

Existing properties: Navigating the 35% hurdle

If you’ve got your eye on a character villa or a standard suburban home that’s been around for a few years, the bank will likely ask for a 35% buffer. They see older homes as slightly higher risk because of potential maintenance issues or slower capital growth in some areas. Telling the difference is usually simple: if it’s already been lived in or was finished more than six months ago, it’s “existing” in the eyes of the bank. If you’re worried about how these numbers affect your budget, you can use our mortgage calculator to see what your repayments might look like. We are here to help you find the right path even when the rules seem rigid.

No Cash? How to Use Home Equity Instead

Imagine you’ve lived in your home for several years. During that time, the property market has likely climbed, and you’ve been diligently chipping away at your mortgage. That “gap” between what your house is worth today and the amount you still owe the bank is your equity. It is essentially wealth you’ve built up simply by owning your home. When people ask how much deposit for investment property nz requires, they are often surprised to learn they might not need to provide any physical cash at all. Instead, you can use that built-up value as your deposit.

A mortgage broker acts as a professional guide to help you unlock this value. We look at your current financial setup and find ways to tap into that equity to fund your next purchase. Most mainstream banks will let you borrow up to 80% of your current home’s value for this purpose. For example, if your house is worth $1 million and you owe $400,000, you aren’t just sitting on $600,000 of “free” money. The bank requires a safety buffer, so they look at that 80% mark ($800,000) and subtract your current debt ($400,000). That leaves you with $400,000 of usable equity to put towards a rental property.

Consider the case of Sarah. She had only $5,000 in her savings account but owned a home worth $900,000 with a $400,000 mortgage. By using her equity, she was able to secure a $180,000 deposit for a new build investment property without spending a single cent of her cash savings. She effectively started her portfolio with $0 cash out of pocket because her home did the heavy lifting for her.

Calculating your usable equity

Finding your investing power involves some simple maths. First, take your home’s current market value and multiply it by 0.8. Second, subtract your existing mortgage balance from that total. The resulting figure is the amount you can potentially use to figure out how much deposit for investment property nz lenders will allow you to contribute. Banks don’t let you use 100% of your equity because they need to ensure that if the market dips, you won’t end up owing more than the house is worth. To see how these numbers look for your specific situation, you can try our mortgage calculator to get a clearer picture of your potential.

The risks and rewards of cross-collateralisation

This is a professional term for linking your home and your investment property together as security for your loans. While it is a common way to get started, it does mean your family home is tied to your investment’s performance. To keep your own home safe, we often explore ways to structure your loans so there is a “firewall” between the two properties. Getting professional advice before you sign anything is vital. You want to grow your wealth, but you also want the peace of mind that your family’s front door is always protected. We focus on creating a steady plan that balances growth with long-term security.

How Much Deposit for an Investment Property in NZ? Your 2026 Guide

Alternative Options: When the Big Banks Say No

Walking into a local branch only to be told you don’t fit their mould can be incredibly disheartening. Perhaps your income fluctuates because you’re self-employed, or maybe you’re just a few percentage points short of the standard deposit. This is where 2nd tier or non-bank lenders become a vital part of your investment strategy. When you’re trying to figure out how much deposit for investment property nz requires, these alternative lenders often provide a more practical path forward. They aren’t bound by the same rigid internal policies as the big four banks, which allows them to look at your whole financial story rather than just a tick-box on a screen.

There are trade-offs to consider, of course. Non-bank lenders generally charge interest rates that are 1% to 3% higher than mainstream banks, according to data from MoneyBalance in May 2026. However, for many investors, the slightly higher cost is a small price to pay for actually getting a foot in the door. It’s about accessibility. If a non-bank loan allows you to secure a high-performing property today rather than waiting three years to save more cash, the capital growth you gain often far outweighs the extra interest paid in the short term. It is a strategic move that treats the loan as a tool rather than a permanent burden.

The benefits of 2nd tier lending for investors

The biggest advantage here is flexibility. These lenders are often more generous when testing your income, especially if you have multiple revenue streams or rental income that a big bank might partially ignore. They also tend to move much faster. While a mainstream bank might take weeks to process a complex application, a 2nd tier lender can often provide a decision in a matter of days. This speed can be the difference between winning a deal and missing out. For more detail on how these institutions work, you can check out our 2nd Tier Lender New Zealand guide.

Is a non-bank loan right for you?

Alternative lending makes the most sense as a stepping stone. You might use a non-bank loan to buy your property now, then plan to refinance back to a mainstream bank once you’ve built up more equity or “cleaned up” your financial profile. This is where having an expert negotiator like Krish Krishna on your side is vital. We don’t just find you a loan; we build a long-term plan to ensure you aren’t paying more than you need to for longer than necessary. We act as your advocate, bridging the gap between rigid institutional rules and your personal financial goals. If the big banks have said no, contact us today to see how we can find a way forward together.

How to Get Your Investment Loan Approved

Securing a loan for a rental property involves more than just having the right amount of money in the bank. While knowing how much deposit for investment property nz lenders require is a great first step, you also need to prove that you can handle the ongoing costs. Banks are currently very thorough, often stress-testing your ability to pay at interest rates as high as 8% or 9%. This means they want to see that your finances are tidy and that you have a clear plan for the future. It’s best to start this process at least three months before you intend to buy.

One of the most effective things you can do is “clean up” your personal spending. Lenders will look closely at your last three to six months of bank statements. They aren’t just looking at your income; they’re looking at your habits. Reducing unnecessary subscriptions or frequent luxury purchases can make a significant difference in how a bank views your application. When they calculate your borrowing power, they typically only consider between 65% and 80% of your projected rental income. Showing that you have a lean, well-managed budget helps offset this conservative calculation and proves you’re a reliable borrower.

The Investor’s Application Checklist

Organising your paperwork early saves time and reduces stress when the right property finally appears. You’ll need to provide clear proof of income, such as recent payslips or financial statements if you’re self-employed. A professional rental appraisal from a reputable property manager is also essential; the bank needs an expert’s opinion on what the property will earn, not just a guess. Finally, don’t overlook your credit score. Even small, forgotten bills can cause delays, so it’s a good idea to check your record and fix any errors before the bank sees them. Having these details ready shows the lender that you’re a serious, prepared investor.

Why Mortgage Suite is your best investment partner

With over 20 years of banking experience, we know exactly how to present your story to a lender so it gets the green light. We have access to a vast network of both mainstream and 2nd tier lenders, many of whom you can’t reach on your own. This is particularly helpful if you’re still figuring out how much deposit for investment property nz banks will accept for your specific situation. We act as your advocate and negotiator, finding the right fit for your goals rather than just trying to sell you a single product. You can read our client reviews to see how we’ve helped other Kiwis navigate these rules to build successful portfolios. We’re here to be the steady hand that guides you through every step of the process.

Take the Next Step Toward Your Investment Goals

Building a property portfolio in New Zealand is a journey that requires both a solid plan and the right people in your corner. We have seen that while the rules for existing homes often demand a 35% buffer, new builds and the clever use of your current home’s equity can provide a much smoother path forward. Even if the big banks have turned you away, alternative lending options remain a powerful tool for those with a clear vision. Understanding how much deposit for investment property nz requires is only the first step; the real magic happens when you structure your finance to protect your home while growing your wealth.

At Mortgage Suite, we provide more than just a mortgage. With over 20 years of banking experience, our founder Krish Krishna offers the personalised attention and expert negotiation skills needed for non-bank and complex loans. We pride ourselves on being a steady hand in a fluctuating market, ensuring you feel like a priority rather than just a number. Chat with our expert team about your investment goals today and let us help you navigate the path to success. Your property journey is unique, and with the right support, your goals are well within reach.

Frequently Asked Questions

Can I use my KiwiSaver for an investment property deposit?

No, you cannot use your KiwiSaver funds to buy an investment property. These savings are specifically reserved for your first home or your retirement. If you have owned a home before, you might be eligible for a second chance withdrawal, but only if you intend to live in the new property yourself. For a pure rental investment, you will need to look at using cash savings or home equity instead.

How much deposit do I need for a new build investment in NZ?

You typically need a 20% deposit for a new build investment. The Reserve Bank of New Zealand provides this exemption to encourage the construction of more homes across the country. This lower entry point makes new builds a popular choice for those wondering how much deposit for investment property nz lenders require. It allows you to enter the market with less upfront capital compared to buying an existing house.

What is the “usable equity” rule for investors?

The usable equity rule allows you to borrow against 80% of your current home’s value, minus what you still owe on your mortgage. For example, if your house is worth $1 million, the bank sees $800,000 as the total lending limit. If your current mortgage is $500,000, you have $300,000 in usable equity. This amount can then be used as the deposit for your next investment property without needing physical cash.

Can I buy a rental property with a 10% deposit?

It is very unlikely that a mainstream bank will accept a 10% deposit for a rental property. The standard requirement is usually 35% for existing homes and 20% for new builds. While some 2nd tier lenders offer more flexibility, they still generally require at least 20% to manage their risk. Buying with a very small deposit is usually reserved for first home buyers who intend to live in the property themselves.

Does the Bright-line test affect how much deposit I need?

The Bright-line test doesn’t directly change how much deposit for investment property nz banks require, but it does affect your tax obligations. As of July 2024, if you sell a residential property within two years of buying it, you may have to pay tax on any profit. While this doesn’t change your upfront deposit, it is a vital factor to consider when planning your long-term investment strategy and potential future resale.

What happens if the bank declines my investment loan application?

If a mainstream bank says no, it doesn’t mean your journey is over. Many investors find success by looking at 2nd tier or non-bank lenders who have different ways of assessing income and deposits. We specialise in helping clients who don’t fit the standard bank criteria. We can often find a path forward by presenting your application to a lender that values your specific financial situation and your long-term wealth goals.

Is it better to have a cash deposit or use equity?

Neither is strictly better, as it depends on your personal goals. Using equity is the most common way Kiwis grow their portfolios because it doesn’t require years of saving cash. However, using a cash deposit can keep your home and your investment loans completely separate, which some people prefer for security. We can help you look at both options to see which structure provides the most protection for your family home.

How do interest rates affect the deposit amount required?

Interest rates affect your ability to service a loan, which is the bank’s way of checking if you can afford the repayments. If rates are high, the bank might limit how much they will lend you, even if you have a large deposit. In some cases, you might need to provide a bigger deposit than the minimum 20% or 35% just to bring the loan size down to a level your income can support.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

You’ve spent months scouring listings and finally found a place to call your own, only for your bank to decline your application because your income isn’t “traditional” or your deposit is a bit light. It feels like a total dead end, but a “no” from a mainstream bank is often just the start of a different conversation. Many people assume that non bank lenders nz home loans are a last resort for those in financial trouble, but in 2026, they’ve become a tactical tool for savvy Kiwis who simply don’t fit a rigid, standard box.

It’s completely normal to feel a bit nervous about looking beyond the big household names, especially if you’re worried about higher interest rates or confusing terms. We understand that you want a clear path to home ownership without the stress of being treated like a number. This guide is designed to strip away the mystery and show you exactly how these alternatives work, providing a steady hand to help you reach your goals.

We’ll explore how these lenders look at your whole story, explain the real difference in costs following the recent OCR shifts, and help you decide if this is the right stepping stone for your future. You’ll gain the confidence to move forward with a plan that actually fits your life.

Key Takeaways

  • Learn how to move past a bank rejection by finding lenders that look at your whole financial picture rather than just a computer-generated score.
  • Understand the actual costs of non bank lenders nz home loans and why paying a bit more now can be a smart move to secure your future home.
  • Discover how these flexible options specifically help self-employed Kiwis and first-home buyers who don’t fit the standard bank boxes.
  • Find out how working with a dedicated negotiator ensures you get a fair deal and a clear plan to eventually move back to a mainstream bank.

What exactly are non-bank lenders in the NZ home loan market?

If you’ve ever felt like just another number at a big bank, non-bank lenders might be the breath of fresh air you need. Simply put, these are companies that provide home loans but don’t hold a traditional banking licence. They are a specific type of non-bank financial institution that focuses on getting people into homes when the traditional path is blocked. By March 2024, lending from these institutions in New Zealand reached about $5.7 billion, showing just how many Kiwis are choosing this path.

Unlike the big banks that use the money in your savings account to lend to others, these lenders get their funds from private investors or larger wholesale markets. This is a major reason why non bank lenders nz home loans offer more flexibility. They aren’t tied to the same rigid rules that govern how banks must handle your neighbour’s term deposit. You might hear people call them second tier lenders. Don’t let that label fool you into thinking they are second best. It’s just a way to categorise them outside the Big Four. They’re often more agile and more willing to listen to your specific story.

The difference between a bank and a non-bank

Most Kiwis are used to the Big Four banks. They have branches on every corner and huge advertising budgets. But they also have very narrow boxes for who they will lend to. Alternative lenders don’t have those massive overheads or the same one size fits all mentality. While they aren’t registered banks, they are still strictly regulated. They must follow the Credit Contracts and Consumer Finance Act, which ensures they are responsible and safe. The real difference is their flexibility. They look at the person behind the application, not just the checkboxes on a form.

Why non-banks are a fair dinkum option for Kiwis

The biggest hurdle for many home buyers is the “computer says no” moment. If you’re self-employed or have a small credit blip from years ago, a bank might reject you instantly. Non-banks are a fair dinkum choice because they use actual humans to assess your application. They’ve helped thousands of families get sorted when the big guys turned them away. With dozens of different lenders in the NZ market today, there’s a huge variety of options. If you want to learn more about how these rules work behind the scenes, our Mortgage School is a great place to start. It’s all about finding the right partner for your journey.

Why the big banks might say no (and why non-banks say yes)

Mainstream banks love what we call “vanilla” applications. If you have a steady salary, a spotless credit history, and a 20% deposit, you are their dream client. But for many Kiwis, life isn’t always that tidy. Banks rely on rigid algorithms to make decisions. If your situation doesn’t tick every single box, the computer simply spits out a decline. This is where Canstar explains non-bank mortgage lending as a vital alternative, because these lenders use human common sense rather than just a software programme.

Common reasons for a bank decline include small credit blips from years ago, having a deposit under 20%, or trying to buy a property that doesn’t meet their strict criteria. Non-bank lenders nz home loans work differently because they look at the whole story. They want to understand why a hurdle exists and what your plan is to move past it. As your broker, my job is to act as a dedicated negotiator. I know which lenders are comfortable with certain “problems” and how to present your case so it gets a “yes” instead of a flat rejection.

Self-employed and “outside the box” income

Business owners and contractors often struggle with traditional banks because their income can fluctuate. A bank usually demands two full years of perfect tax returns, which isn’t always helpful if you’ve just had a growth year or recently started out. Non-banks offer “alt-doc” options, which means they can verify your income using GST returns or bank statements instead of just tax summaries. If you’re navigating this path, our Self Employed Home Loan Guide offers deeper insights into how to prepare your application for success.

Property types that banks often shy away from

Sometimes it isn’t you; it’s the house. Banks often refuse to lend on small apartments under 40 or 50 square metres, lifestyle blocks with unusual zoning, or “fixer-uppers” that need significant work. They see these as high-risk assets. Non-bank lenders nz home loans take a more practical view of property value and risk. They specialise in the unique corners of the New Zealand market, seeing the potential in a property where a bank only sees a liability. If you’ve found a unique spot that the big banks won’t touch, it’s worth having a chat to get to know our team and see how we can help you secure it.

The real cost: Interest rates, fees, and your budget

Let’s be direct about the numbers. You’ll likely pay more for a non-bank loan than you would at a big bank. It’s a trade-off. By choosing a lender that looks at your whole story, you might pay a slightly higher interest rate, but you’re actually getting into the property market instead of watching prices climb from the sidelines. Most people use non bank lenders nz home loans as a tactical stepping stone. You stay for one or two years, tidy up your credit or build your business history, and then move back to a mainstream bank once you fit their box.

Fees are another area where things differ. While a bank might waive an application fee, non-banks usually charge an establishment fee to cover the manual work of assessing a complex file. In the current 2026 market, these typically range between $2,000 and $5,000. You might also see small monthly admin fees around $10 to $13. It’s about looking at the total cost of the “bridge” to get you to your goal rather than just the sticker price.

Comparing interest rates: Bank vs. Non-bank

The gap between a bank rate and a non-bank rate is often called the margin. Usually, near-prime rates sit about 1% to 2% higher than what the big banks offer. With the Official Cash Rate sitting at 2.75% as of September 2026, near-prime rates often start around 6.35%. It’s vital to see how this looks in real dollars. You can use our mortgage calculator to compare different scenarios. Remember, the “cheapest” rate isn’t always the best deal if the lender won’t actually give you the money.

Managing the extra cost in your weekly budget

A higher rate doesn’t have to break your budget if you plan correctly. We often suggest structuring your loan with a focus on flexibility, allowing you to make extra payments when possible. This helps you build equity faster so you can refinance sooner. Getting into a home now, even at a higher rate, can often save you more in the long run than waiting years to save a massive deposit while house prices potentially increase. It’s about looking at the big picture of your financial success and long-term security.

Non-Bank Lenders NZ: Your 2026 Guide to Home Loan Alternatives

Common situations where non-bank home loans shine

While mainstream banks often wait for a perfect set of circumstances, non bank lenders nz home loans are built for the reality of life in New Zealand. They shine brightest when you need a solution that looks at your future potential rather than just your past paperwork. For many, these lenders provide a strategic way to move forward when the traditional path is blocked by rigid rules or timing issues.

There are several specific scenarios where these alternative options become the best tool for the job:

  • Low deposit hurdles: If you have a deposit under 20% and don’t qualify for specific government grants, non-banks can often bridge that gap.
  • New business owners: If you’ve been self-employed for less than two years, a bank will likely turn you away. Non-banks are often happy to help once you have a few months of solid trading under your belt.
  • Past credit hiccups: A single missed payment or an old default can stay on your record for years. Non-bank lenders focus on your current ability to pay rather than a mistake from the past.
  • Growing property portfolios: Investors often hit a wall with banks due to strict rules on how much they can borrow compared to their income. Non-banks don’t have to follow the same Reserve Bank limits, allowing for more growth.

Bridging the gap for first-home buyers

Getting on the property ladder is often a race against time. If you wait another two years to save a larger deposit, house prices might have climbed even further, leaving you in the same position. By using a non-bank, you can secure a property now with a smaller deposit. This allows you to start building equity in your own home rather than paying off someone else’s mortgage. Our guide on Home Loans for First Home Buyers NZ explains how to navigate these rules to your advantage.

Credit repair and moving forward

A non-bank loan is often the best way to prove to the wider market that you are a reliable borrower. By making every payment on time for 12 to 24 months, you actively repair your credit profile. This creates a clear track record that eventually makes you very attractive to mainstream banks. Think of it as a transition period where you get the house you want while tidying up your financial history. Once your situation is sorted, we can help you move back to a bank with a lower rate. See how we’ve helped other Kiwis make this exact transition and find their way to financial success.

How to find the right non-bank lender for your goals

Applying for a mortgage shouldn’t feel like a guessing game. It is tempting to jump online and send applications to every lender you find, but this can actually backfire. Every time a lender checks your credit, it leaves a footprint. Too many footprints in a short time can make you look desperate to other lenders. The trick isn’t to apply more; it is to apply smarter. Working with a specialist who understands the landscape of non bank lenders nz home loans means you only apply to the ones most likely to say yes.

A specialist broker acts as your dedicated negotiator. Because I have spent over 20 years on the inside of the banking world, I know exactly what these lenders are looking for. We do the heavy lifting by comparing different non bank lenders nz home loans to find the one that fits your specific story. This saves you time and protects your credit score from unnecessary dings. We handle the paperwork and the talking, so you can focus on finding the right house.

One thing many people forget to check is the fine print. You need to look at more than just the interest rate. Are there penalties for paying the loan off early? How much are the ongoing admin fees? Most importantly, you need a clear exit strategy from day one. We don’t view a non-bank loan as a forever home for your debt. It is a bridge. We help you map out exactly what needs to happen so you can refinance back to a mainstream bank in 12 to 24 months. This might involve tidying up spending habits or building a longer history of business income.

The Mortgage Suite advantage

When you work with us, you are getting more than just a middleman. You are getting a partner with deep institutional knowledge. Krish Krishna’s 20 years of banking experience means he knows the rules, the shortcuts, and the people who make the decisions. We have established relationships with a wide range of 2nd tier lenders across New Zealand, giving you options that you simply won’t find on your own. You can read more about our philosophy and how we prioritise your success over just closing a deal.

Your next steps to getting sorted

Getting started is simpler than you might think. Your first job is to gather your paperwork. Having your bank statements and proof of income ready to go makes a massive difference in how a lender views your application. It shows you are organised and serious. Once you have your bits and pieces together, the next step is to book a chat. We will sit down, listen to your story, and figure out a path forward together. If you are still feeling a bit unsure, read our client reviews to see how we have helped other Kiwis move from a bank rejection to home ownership.

Take the next step toward your new home

A “no” from a big bank doesn’t have to be the end of your property dreams. Non bank lenders nz home loans offer a flexible and fair dinkum alternative for Kiwis who don’t fit into a standard box. Whether you have a unique income or a past credit hurdle, these options provide a reliable bridge to financial success. By focusing on a clear exit strategy from day one, you can secure your home now and move back to a mainstream bank when the time is right.

With over 20 years of banking and brokerage experience, we specialise in navigating the inside rules to get you sorted. We’re proud to help families nationwide find a steady hand in a shifting market. You don’t have to guess your way through the process alone. Our team is here to act as your dedicated negotiator, ensuring you get a fair deal that actually works for your budget.

Book a free, no-obligation chat with Krish to see your options. It’s time to stop worrying about the paperwork and start planning your move. We’re ready to help you turn that “no” into a “yes”.

Frequently Asked Questions

Are non-bank lenders safe in New Zealand?

Yes, non-bank lenders are safe and must follow the same responsible lending laws as major banks. They are strictly regulated under the Credit Contracts and Consumer Finance Act, which ensures they treat you fairly and don’t lend more than you can afford to repay. While they aren’t registered banks, they are professional financial companies that help thousands of Kiwis. Choosing non bank lenders nz home loans is a secure way to enter the market.

Will I pay much higher interest rates with a non-bank lender?

You’ll generally pay a slightly higher rate, often around 1% to 2% above what a mainstream bank offers. This is because these lenders take on more risk by helping people who don’t fit the standard criteria. However, many borrowers find this extra cost is worth it to secure a home today rather than waiting years to save a larger deposit while house prices potentially climb even further. It’s about the long-term gain.

Can I move back to a main bank later on?

Absolutely, and that is usually the main goal for our clients. Most people use a non-bank loan as a temporary stepping stone for 12 to 24 months. During this time, you can tidy up your credit history or build a longer record of business income. Once your situation meets the big banks’ criteria, we can help you refinance to a lower rate. We build this exit strategy into your plan from the start.

Do non-bank lenders require a bigger deposit?

Not always. While big banks often demand a 20% deposit, non-bank lenders can be much more flexible. They aren’t always tied to the same strict speed limits set by the Reserve Bank regarding low-deposit lending. This means they might accept a smaller deposit if the rest of your application is strong and your income is stable. Every lender has different rules, so we look at your specific situation to find the best match.

How long does it take to get a non-bank home loan approved?

Approval times can often be faster than at a major bank because non-bank lenders are typically smaller and more agile. While a big bank might take weeks to process a complex file, an alternative lender can often give an answer within a few working days. Having your paperwork, like bank statements and proof of income, ready to go from the start will help speed up the process even more and keep things moving quickly.

Can I get a non-bank loan if I am self-employed with only one year of accounts?

Yes, this is a situation where non bank lenders nz home loans really shine. Most mainstream banks demand at least two full years of tax returns, but alternative lenders offer “alt-doc” options. They can use other evidence, such as GST returns or recent bank statements, to verify your income. This is a huge help for new business owners who are making good money but haven’t been trading long enough for a traditional bank.

Are there extra fees involved with non-bank home loans?

There are typically some extra costs, such as an establishment fee, which covers the manual work of assessing a non-standard application. These often range between $2,000 and $5,000 depending on the lender. You might also see small monthly admin fees of around $10 to $13. While these are higher than at a bank, they are often a small price to pay for the flexibility that gets you into your own home years sooner than waiting.

What happens if my credit history isn’t perfect?

Non-bank lenders focus on your whole story rather than just a computer-generated credit score. If you had a credit blip a few years ago due to a missed bill or a specific life event, they are often willing to listen to the explanation. They want to see that you are back on track and can comfortably afford the repayments today. This human approach is why many Kiwis with imperfect histories still find success.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Don’t Let Your Tax Payments Be An Afterthought

As a business owner, it is very tempting to utilise every dollar that comes into your account.

You work hard, so why shouldn’t you make the most of the money you earn?

Well, there is a simple reason why you can’t.

Not all of the money you earn is actually yours.

If your business is turning a profit, a portion will always need to go to the IRD as a tax payment. Don’t let this payment be a surprise that penalises your business!

Let’s look at how you can ensure your tax gets paid on time without hamstringing your business.

The Tax Payment Pandemic

Do you have trouble keeping up with your payments to the IRD? You are not alone! Many Kiwi business owners get a nasty surprise when their tax bill rolls around and have to scramble to find the funds needed.

Why is that?

Often, it’s not that the business isn’t making money; it’s because tax is treated as an afterthought.

This is a danger for any business, even the successful ones. You work hard, the business is growing, the cash is flowing in, and you are likely turning a bit of a profit. But when the tax bill arrives, there isn’t enough money in your account to pay it.

If this sounds like you, it’s time to shift your perspective. Yes, you are earning the dollars that come into your business, but not all of them belong to you!

Shifting Your Perspective

Successful and profitable businesses attract tax bills. Depending on the circumstances of your business, these bills can be for a significant sum. That means you need a significant amount of funds available in your account!

And that’s just for your income tax; that doesn’t even take into account any GST payments. If you are GST registered, you are basically collecting money on behalf of the government when you charge your customers. That money is not additional income for your business; it needs to be paid on accordingly.

It is easy to glance at a $100k bank balance and be excited by the funds sitting there. But you need to keep in mind that a portion of that money is actually destined for the IRD.

How Can You Keep Track?

It’s time to start budgeting for your tax in the same way that you budget for things like stock, wages, rent, marketing, and other common business expenses. You know a tax bill will be coming, so don’t wait for your accountant to tell you about it!

Start making provisions now. Tax considerations should be part of your normal cash flow management. The easiest thing to do is put money aside every time it comes into your business. If you find it hard to be disciplined in managing your tax provisions by using just your main business account, open a separate account for holding your tax money in.

For GST, you know you need to keep 15% of every payment. Sure, there will be some variation in the GST cost to your business depending on your purchases for the month, but holding aside 15% is a safe practice.

Your accountant or financial adviser will be able to give you an indication of how much you should be reserving for your income tax payments. Take a look at what your tax bills have been in the past and how your business income has changed in the last year. That should give you a ballpark indication of what to expect for this year’s tax bill. Remember, it’s better to save too much than not enough!

Every business is different, so now is the time to get educated on what your numbers look like. That way, you will never be caught off guard at tax time.

Tax Planning Should Be A Priority

Your business bank balance is one thing, but your available cash can be a very different amount. That’s why it’s vital to understand the difference between the two figures.

A highly profitable business can quickly find itself in trouble because of poor tax planning. All those hard earned dollars can disappear if you have not accounted for your tax obligations!

So, would you be able to pay a tax bill immediately if one landed in your inbox today?

If the answer is no, tax planning should be your priority.

Now is the best time to have a conversation with your financial adviser or accountant. Then, you can gain an understanding of your upcoming obligations and ensure tax provisions become a regular part of your business cash flow. The very best time to ensure you have your tax bill sorted is before you receive it.

Avoid tax panic by having a chat with our friendly team now. We can help you understand your numbers and how you can best prepare your business for those upcoming tax payments.