Debt Consolidation Mortgage NZ: How It Works and What to Weigh Up

What if one easier repayment came with a much longer journey to becoming debt-free? Keeping track of several debts and due dates can be stressful, so it’s understandable that a single, lower repayment sounds appealing. For Kiwis weighing up debt consolidation mortgage NZ options, though, the monthly amount is only part of the picture.

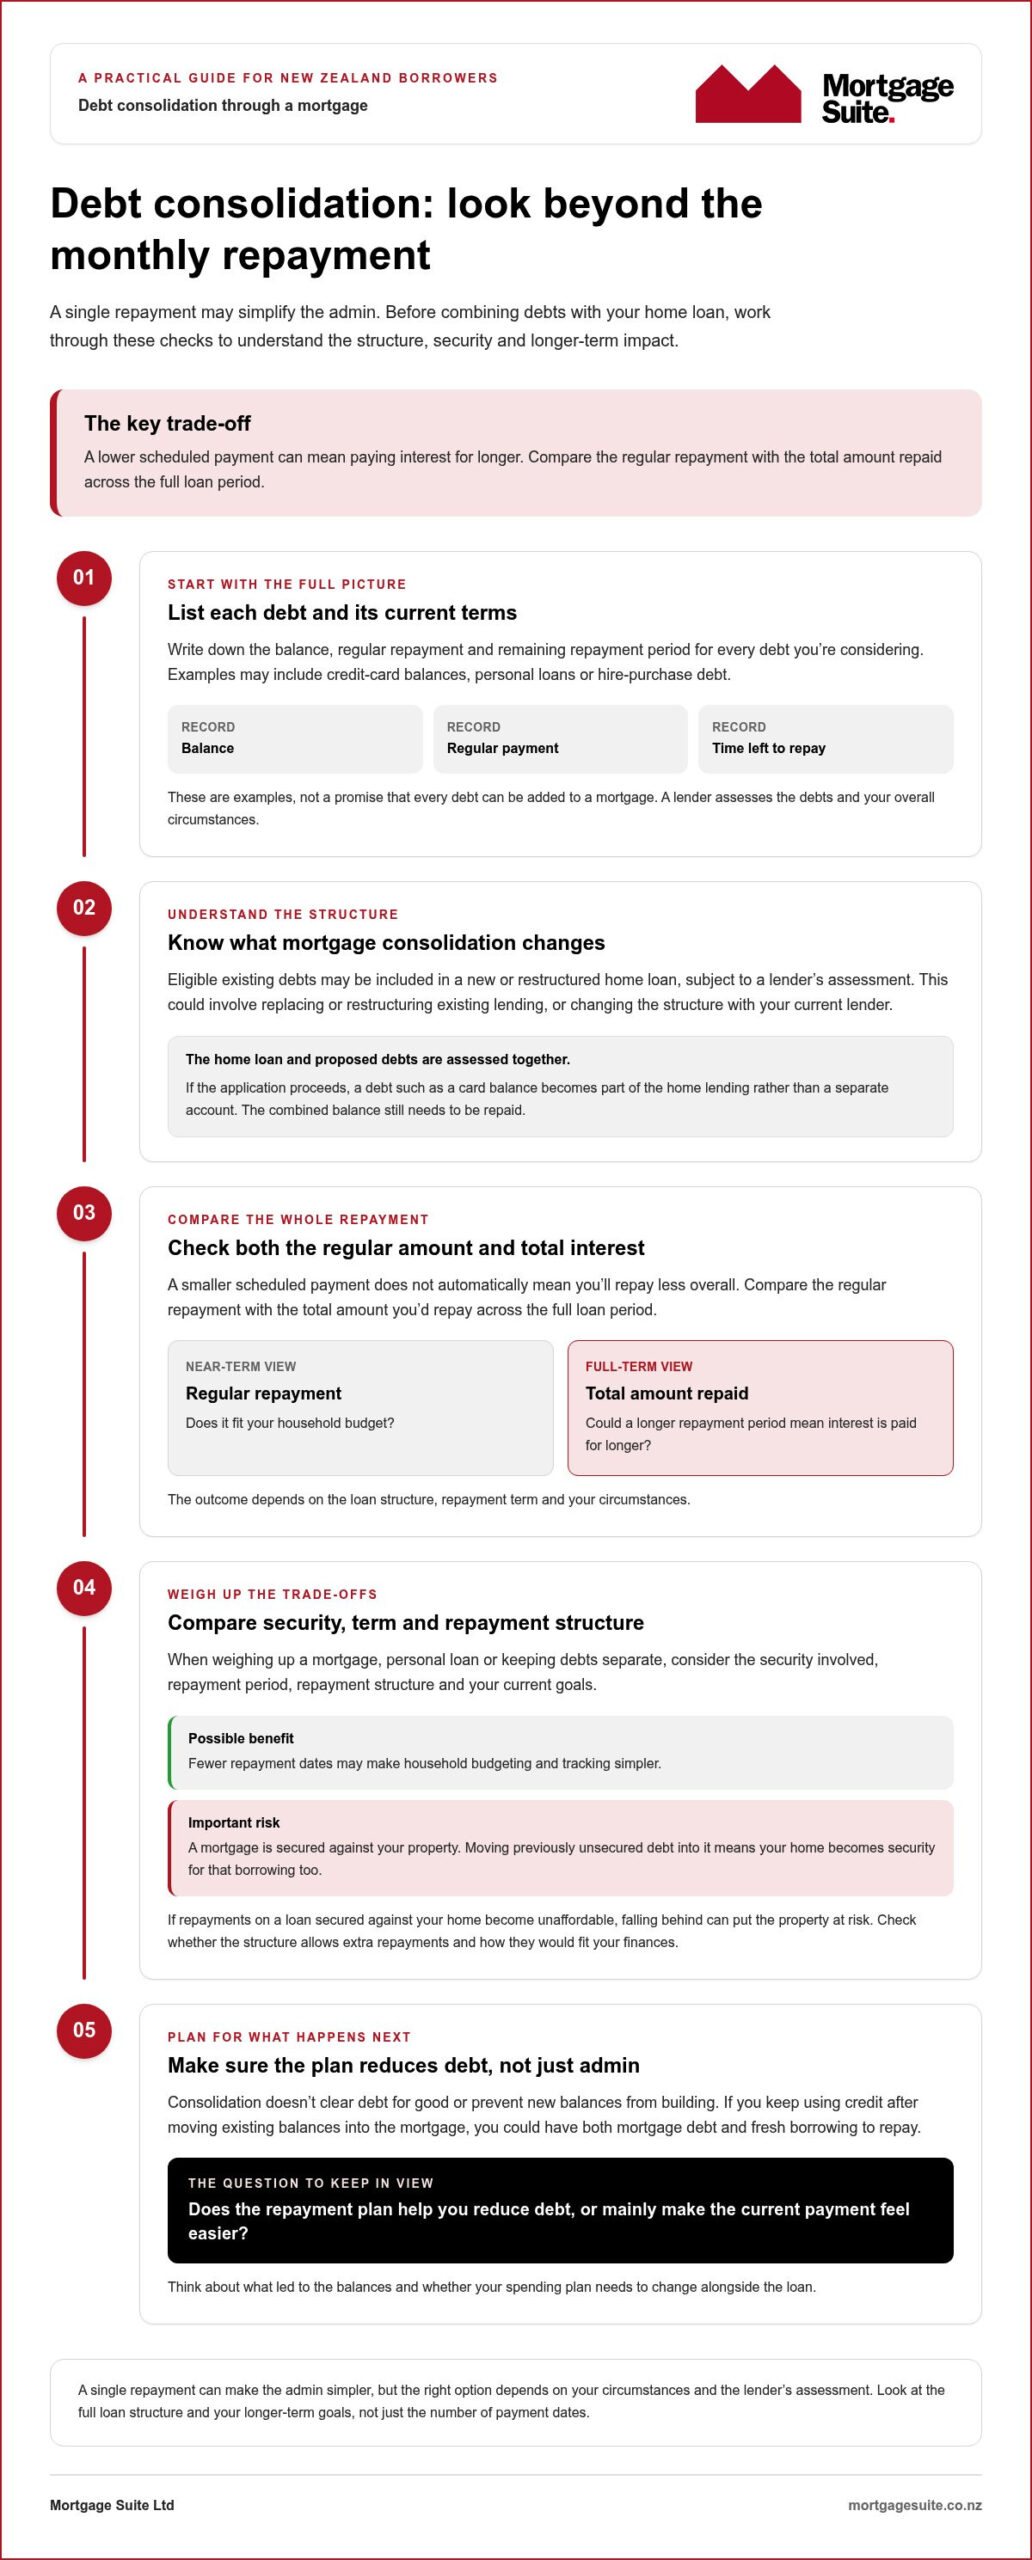
Rolling credit cards or personal loans into a mortgage may simplify repayments and reduce the interest rate on that debt. But it also means securing previously unsecured debt against your home. If you repay it over a longer mortgage term, you could pay interest for longer too. A simpler repayment helps only when the loan structure and your plan to repay it suit your circumstances.

This guide explains how mortgage-based consolidation works and what to compare with a personal loan or keeping debts separate. You’ll also learn what information to gather before discussing your options. Mortgage Suite helps borrowers explore debt consolidation and Refinance options across different lender channels, with advice that’s free of charge and comes with no obligation.

  • A debt consolidation mortgage NZ option may bring eligible debts together through a new or restructured home loan, subject to your circumstances.
  • Compare the regular repayment with the total interest over the full loan period to understand the longer-term impact.
  • Weigh up a mortgage and a personal loan by looking at security, repayment period, repayment structure and your current goals.
  • Before exploring options, list each debt, its current repayment and how long remains to repay it.
  • Mortgage Suite can discuss debt consolidation and Refinance options with your goals in mind.

What does debt consolidation through a mortgage mean in New Zealand?

Keeping up with several balances, repayment dates and lenders can feel like a lot to manage. Bringing debts together may make the admin simpler, but the right choice depends on more than having one payment. Here’s how mortgage consolidation works, what a lender may assess and why a single repayment doesn’t automatically mean you’ll repay less overall.

Mortgage debt consolidation means including eligible existing debts in a new or restructured home loan, subject to a lender’s assessment. Unlike personal-loan consolidation, which combines debts through a personal loan, mortgage consolidation uses lending secured against your property. The wider What is debt consolidation? overview explains the general idea, but the mortgage option has its own trade-offs.

How mortgage debt consolidation works

A lender considers your existing mortgage alongside the debts you want to combine and assesses whether a revised loan structure may suit your circumstances. This could involve a Refinance, which means replacing or restructuring existing lending, or changing the structure of lending with your current lender. The details, including how the debt is repaid, depend on your situation and the lender’s assessment.

For example, if you have a home loan and separate credit-card debt, a lender may consider whether the proposed mortgage can cover both. If the application proceeds, the card balance becomes part of the home lending rather than a separate account. You may then have fewer repayments to manage, but the combined balance is still debt that needs to be repaid.

Consolidation can simplify administration, but it doesn’t erase what you owe or guarantee a lower total repayment. If the added debt is repaid over a longer period as part of the mortgage, you may pay interest for longer. The repayment plan should make sense for your budget and longer-term goals, not just reduce the number of dates in your calendar.

Which debts might a borrower consider combining?

People may ask about including credit-card balances, personal loans or hire-purchase debt. These are examples, not a promise that every debt can be added to a mortgage. A lender assesses the debts and the overall application, including whether the proposed lending fits your circumstances. Your existing home loan, property and intended repayment structure also matter.

Before exploring a debt consolidation mortgage NZ option, list what you owe and the repayment arrangements for each debt. Include the balance, regular payment and remaining repayment period. This gives you a practical starting point for comparing possible structures. Some debts may not suit mortgage consolidation, so assess the whole picture rather than assuming everything can be rolled in.

How can mortgage consolidation affect repayments and long-term interest?

Mortgage consolidation can make the regular payment feel more manageable, but that figure alone won’t tell you whether the arrangement works out better over time. Compare the repayment you’d need to make with the total amount you’d repay across the full loan period. The outcome depends on the loan structure, repayment term and your circumstances, so a lower scheduled payment isn’t guaranteed.

Potential benefits of bringing repayments together

Having fewer payment dates to track can make household budgeting simpler. A clear plan can also help you see how much you’re paying towards the combined debt and monitor your progress. Before agreeing to a new structure, check how repayments are set up and whether the plan fits your regular budget. Simpler administration can be useful, but it doesn’t reduce the debt by itself.

It may help to compare repayment estimates across different terms. A mortgage repayment calculator can help you explore how a change in term affects a scheduled payment. Treat the result as an estimate, not a lender decision or a full picture of the overall repayment.

Risks to weigh before adding debt to a mortgage

Mortgage lending is secured against your property. If you add debt that was previously unsecured, such as a personal loan, to your mortgage, your home becomes security for that borrowing too. If repayments become unaffordable, falling behind on a loan secured against your home can put the property at risk. That’s a serious trade-off to weigh alongside the convenience of one repayment.

Consider the repayment period as well. If the consolidated debt is repaid over a longer mortgage term than the original debt would have taken, you may pay interest for longer. A smaller regular payment could therefore come with a higher total amount repaid. Check whether the loan structure allows extra repayments and how those would fit your finances before relying on them to reduce the balance sooner.

Consolidation doesn’t clear debt for good or prevent new balances from building. If you keep using credit after moving existing balances into the mortgage, you could end up with both the mortgage debt and fresh borrowing to repay. Think about what led to the balances and whether your spending plan needs to change alongside the loan.

  • Potential upside: fewer repayment dates and a clearer way to track the debt.
  • Potential downside: interest may be paid for longer, and unsecured borrowing becomes secured against your home.
  • Key question: does the repayment plan help you reduce debt, or mainly make the current payment feel easier?

A debt consolidation mortgage NZ option is worth assessing against both your monthly budget and your longer-term goals. If you’re weighing up how a different mortgage structure could affect your repayments, Mortgage Suite can help you explore debt consolidation and Refinance options with your circumstances in mind.

Mortgage or personal loan for debt consolidation: what should you compare?

There isn’t one option that suits every borrower. A mortgage lets you review your home lending and other debts together, while a personal loan or separate repayments may keep borrowing on a distinct repayment plan. Compare the full structure and how it fits your goals, not just how many payment dates you’ll have.

What to compare Mortgage consolidation Personal loan or separate debts
Security The combined lending is secured against your property. A personal loan may be unsecured; separate debts keep their existing arrangements.
Repayment period Debt added to a mortgage may be repaid over a longer term. A personal loan may have a shorter, defined repayment period, depending on its terms.
Repayment structure Debt becomes part of your mortgage lending and its repayment structure. A personal loan has its own scheduled repayments; separate debts keep their individual schedules.
Fit with your goals May suit a homeowner reviewing existing mortgage lending alongside other debts. May suit someone who wants a separate repayment plan or to avoid securing that debt against their home.

When mortgage-based consolidation may be worth exploring

If you own a home and want to review your mortgage and several debts as one picture, mortgage-based consolidation may be worth discussing. A lender may consider available equity, your existing lending and whether the proposed repayments are affordable. Having equity doesn’t guarantee approval, and the lender’s decision depends on your full circumstances.

Interest is only one part of the comparison. The amount borrowed, repayment period and loan structure all affect what you repay over time. The mortgage repayment calculator can help you explore how changing a repayment term affects the regular payment, but it won’t show whether a particular option suits your full situation.

When a personal loan or separate repayments may fit better

A separate repayment plan may suit you if you want to pay a debt down over a defined period, subject to a lender’s assessment and the terms offered. Keeping a debt separate can also avoid securing that borrowing against your home. You’ll still need to manage its repayment alongside your other commitments.

Compare the proposed payment with what you currently pay across all debts, then consider the full repayment period and total interest. A smaller regular repayment can look appealing, but it doesn’t show the long-term impact on its own. Think about whether the structure supports your current goals, such as reducing debt steadily or keeping your mortgage arrangements straightforward.

A debt consolidation mortgage NZ option should be weighed against your priorities, property and overall affordability, not judged on one feature alone. Mortgage Suite can help you consider debt consolidation and Refinance options across lender channels, with your circumstances in view. Explore your lending options with advice that’s free of charge and comes with no obligation.
Debt Consolidation Mortgage NZ: How It Works and What to Weigh Up

What should you prepare before exploring debt consolidation in New Zealand?

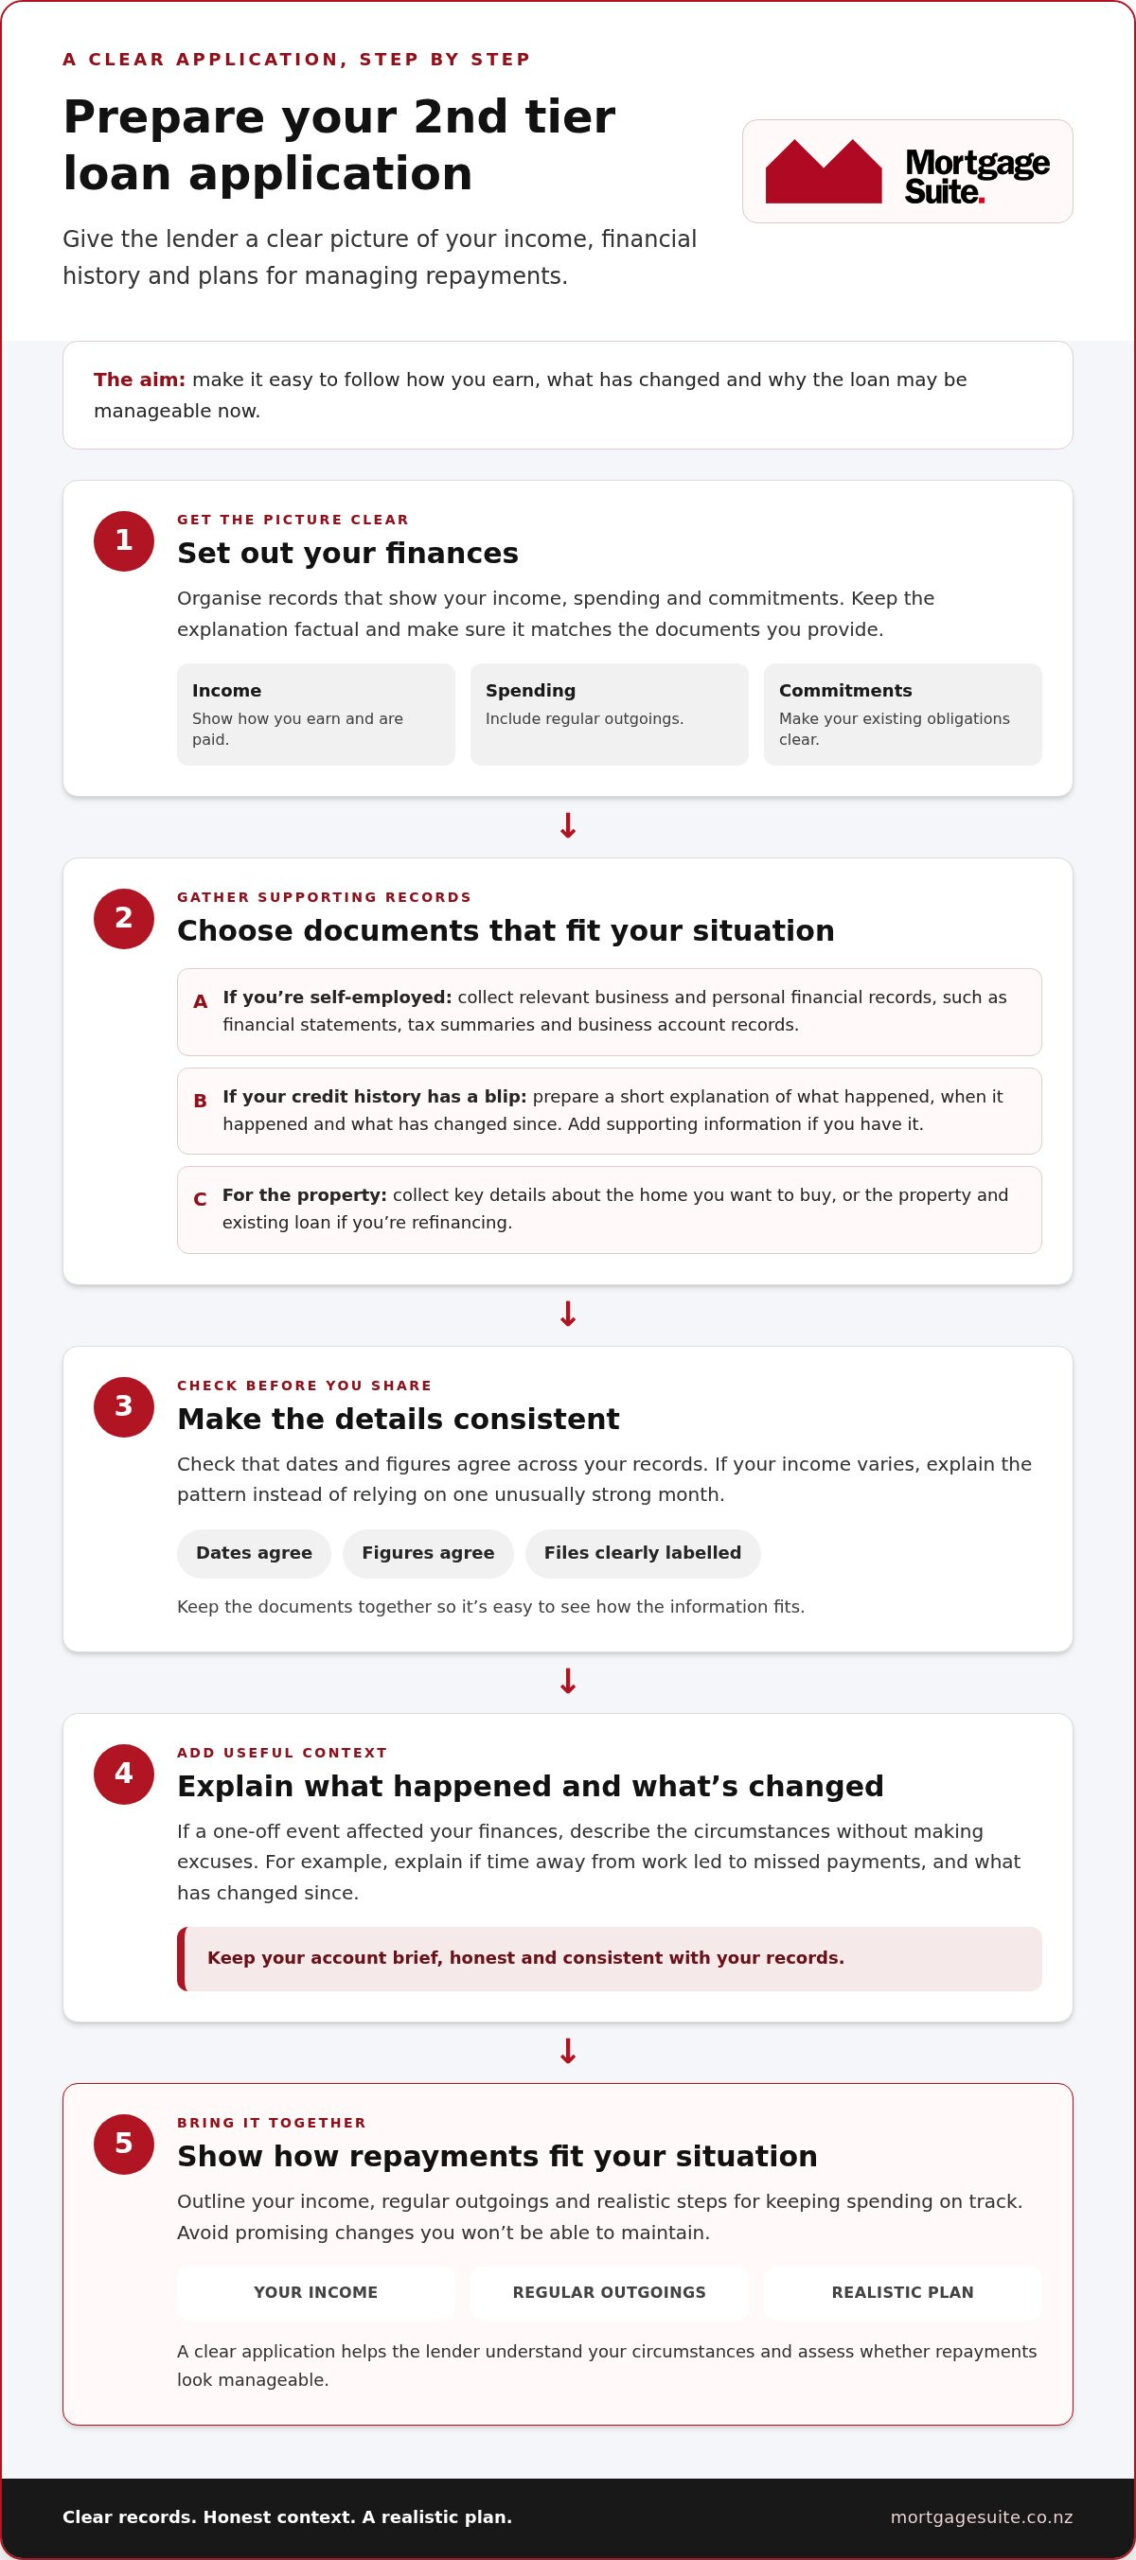
A clear snapshot of your finances can make a debt consolidation mortgage NZ discussion more practical and less daunting. You don’t need to have a preferred loan structure worked out first. Start with the facts, then be ready to explain what you want a new arrangement to achieve.

Build a clear picture of your current borrowing

Gather your mortgage details and a summary of your other debts. Include what you owe, each repayment amount and date, and how long remains on each repayment plan. Add household income and regular commitments so you can see how borrowing fits alongside day-to-day expenses. If any repayments have become difficult to maintain, note that too. It’s useful context, not a reason to feel judged.

  1. List each debt. Record the lender or provider, balance, current repayment, due date and remaining repayment period. Include credit cards, personal loans and hire-purchase agreements if you have them.
  2. Gather your mortgage information. Note your current home-loan balance, repayment schedule and remaining term. Include relevant details about the property and any recent changes to your lending arrangements.
  3. Summarise household income and commitments. Write down income sources and regular expenses, as well as other repayments. This helps you consider whether a proposed payment could fit your usual budget.
  4. Mark any pressure points. Identify repayments that have become hard to keep up with, or months when several due dates fall close together. This can help focus the discussion on what needs to change.
  5. Set your priority. Decide whether you mainly want simpler administration, a manageable regular repayment or a clear plan to pay the debt down. You may value more than one outcome, but knowing your main priority helps you weigh up the trade-offs.

Set goals for a proposed new structure

Think beyond having one payment. What would a successful outcome look like for you? You might want predictable repayments, fewer accounts to manage or a clear plan to pay the consolidated debt down within a timeframe that fits your longer-term plans. Consider whether the proposed repayment period supports those plans, rather than focusing only on the amount due each time.

If you want to explore possible mortgage repayments, the Mortgage Suite mortgage calculator can help you model scenarios. Treat any result as an estimate, not a lender decision or a full assessment of your circumstances.

If a mainstream bank has declined your application, include that outcome and any reasons you were given in your summary. It may be a prompt to explore other lender channels, but it doesn’t guarantee a different decision. A lender will assess your full circumstances and the proposed structure.

Once your notes are ready, Mortgage Suite can help you consider debt consolidation and Refinance options with your goals in mind. Discuss your debt consolidation options and decide whether you’d like to take the next step.

How Mortgage Suite can help you explore debt consolidation mortgage options

Once you’ve weighed up the repayment structure, longer-term impact and security involved, it can help to talk through your situation with someone who understands lending. Mortgage Suite helps New Zealand borrowers explore debt consolidation and Refinance options, with your goals and circumstances at the centre of the discussion. The first step is to understand what you need the repayments to achieve, then consider possible lender routes and structures without assuming one answer fits everyone.

Mortgage Suite works with banks, private lenders and non-bank lenders. These different lender channels give you options to consider, but they don’t mean a particular loan will be available or approved. Each lender makes its own assessment of your circumstances and the proposed lending.

What a conversation about your options can cover

You can talk through your current borrowing, repayment priorities and wider lending goals. That might include reviewing your existing mortgage alongside other debts, discussing whether a Refinance or different loan structure could fit, and considering how proposed repayments may affect your plans. The focus is on weighing up the whole structure, not simply aiming for one repayment or a lower regular amount.

Mortgage Suite advocates and negotiates with lenders on your behalf, seeking the best possible deal for your circumstances. That is a goal, not a promise of approval or a particular outcome. You can read Mortgage Suite client reviews to hear about other borrowers’ experiences. Each person’s experience is different and doesn’t guarantee what will happen in your situation.

Founder Krish Krishna brings over two decades of banking experience to these conversations and has personally settled well over a billion dollars in residential, commercial and business loans. That experience provides useful context when considering a debt consolidation mortgage NZ option, while the right path still depends on your circumstances and the lender’s assessment.

A straightforward next step

Getting started doesn’t require you to commit to a new loan. Explain what you owe, what’s proving difficult to manage and what you’d like your repayments to achieve. If a mainstream bank has declined an application, that doesn’t have to be the end of the discussion. It may be a reason to explore other lender channels, though no outcome can be guaranteed.

If you’re ready to talk through your circumstances and possible next steps, talk through your loan options with Mortgage Suite and decide what feels right for you.

Take the next step with a clearer plan

You don’t need to decide on a new loan before asking whether consolidation could suit you. A useful next step is to talk through what you want to change, what repayments you can manage and how a proposed structure would fit your plans. That keeps the focus on finding a workable path, not combining debts simply to have one payment.

Mortgage Suite can consider debt consolidation and Refinance options across bank, private and non-bank lenders. Advice is free of charge with no obligation, and founder Krish Krishna brings over two decades of banking experience to the discussion. No lender outcome is guaranteed, but a conversation can help you understand what may be worth exploring based on your circumstances.

If you’re considering a debt consolidation mortgage NZ option, start by sharing your goals and the borrowing picture you’ve prepared. Talk through your loan options with Mortgage Suite and take a steady first step towards a plan that feels right for you.

Frequently Asked Questions

Is debt consolidation through a mortgage the same as refinancing?

No, they’re related but not identical. Refinance means replacing or restructuring existing lending, while mortgage consolidation means including eligible debts, such as a credit-card balance, in mortgage lending. A Refinance may be one way to arrange consolidation, but you can also restructure lending without changing lenders. The important point is to understand what changes in your loan and how the added debt will be repaid.

Can I consolidate debt into my mortgage if I have little equity?

Possibly, but having little equity can limit the amount a lender may be willing to add to your mortgage. The lender will consider the property’s value alongside the total lending you’re requesting and your ability to manage the repayments. For example, a small amount of available equity may not cover all the debts you hope to combine. A lender assessment determines whether a proposed structure may fit.

Does consolidating debt into a mortgage mean I pay less overall?

No, it doesn’t automatically mean a lower total amount repaid. The result depends on the loan’s interest, repayment amount and how long you take to repay the added debt. A lower scheduled payment could mean paying for longer. Compare the full repayment plan, not just the next payment due, and consider whether you can make progress on the balance within a timeframe that suits your plans.

Can I consolidate debt if a bank has declined my application?

You can still explore whether another lending structure or lender channel may suit, but a decline doesn’t mean another lender will approve the application. The reason for the decision matters. It could relate to affordability, property value, existing commitments or other parts of your circumstances. Mortgage Suite can discuss options across bank, private and non-bank lenders, but any lender will make its own assessment and no outcome is guaranteed.

Will my credit cards be closed when I consolidate their balances?

Not necessarily. Paying a card balance from mortgage funds doesn’t, by itself, tell you whether the card account will stay open or be closed. This depends on the lender’s requirements and the arrangements made for your application. If the account remains available, avoid building a new balance while repaying the amount through your mortgage. Otherwise, you could be managing the consolidated debt and fresh card borrowing at the same time.

What happens if my home value changes after consolidating debt?

A change in your home’s value doesn’t automatically alter your loan balance or scheduled repayments. It can, however, affect the equity you have and the relationship between the property value and the amount borrowed. If you later apply to borrow more or change lenders, the lender may assess the property and your overall circumstances again. Don’t rely on a future rise in value to make today’s repayment plan affordable.

Can I still explore mortgage consolidation if I have missed repayments?

Yes, you can discuss your situation, including missed repayments, but they may affect a lender’s assessment. Be upfront about which payments were missed, when this happened and whether the accounts are now up to date. That gives an adviser a clearer picture of the challenge and the options worth considering. A missed payment doesn’t define you, but approval will depend on the full application and lender decision.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loan Pre-approval in NZ: What to Expect in 2026

What if the amount on your pre-approval isn’t the amount a lender will ultimately offer for the home you choose? It’s understandable to want a clear borrowing figure before you start house hunting. If you’re looking into home loan pre-approval NZ, remember that pre-approval is a conditional guide, not a guarantee of a loan.

This guide explains what pre-approval can tell you, what it can’t confirm and how to prepare your application. You’ll learn what financial information to gather, how changes in your circumstances or the property could affect the outcome, and what to consider before making an offer while lending is still conditional.

We’ll also cover the steps towards confirmed lending, including the lender’s assessment of the specific property. A Mortgage Suite adviser can help you understand the process, talk through your goals and circumstances, and negotiate with suitable lenders. With clear information and a steady plan, you can take the next step with more confidence, without mistaking pre-approval for final approval.

Key Takeaways

  • Home loan pre-approval NZ can help guide your budget, but the lender’s conditions still matter when you choose a property.
  • Check the expiry date and conditions in your pre-approval so you know what needs to happen before the application can progress.
  • Prepare by setting out your plans and gathering information about your income, regular spending, debts and deposit.
  • Before making an offer, find out what property details the lender needs to review and what steps remain before a final decision.
  • Mortgage Suite can explain the process, present your circumstances to suitable lenders and negotiate on your behalf.

What does home loan pre-approval in NZ actually mean?

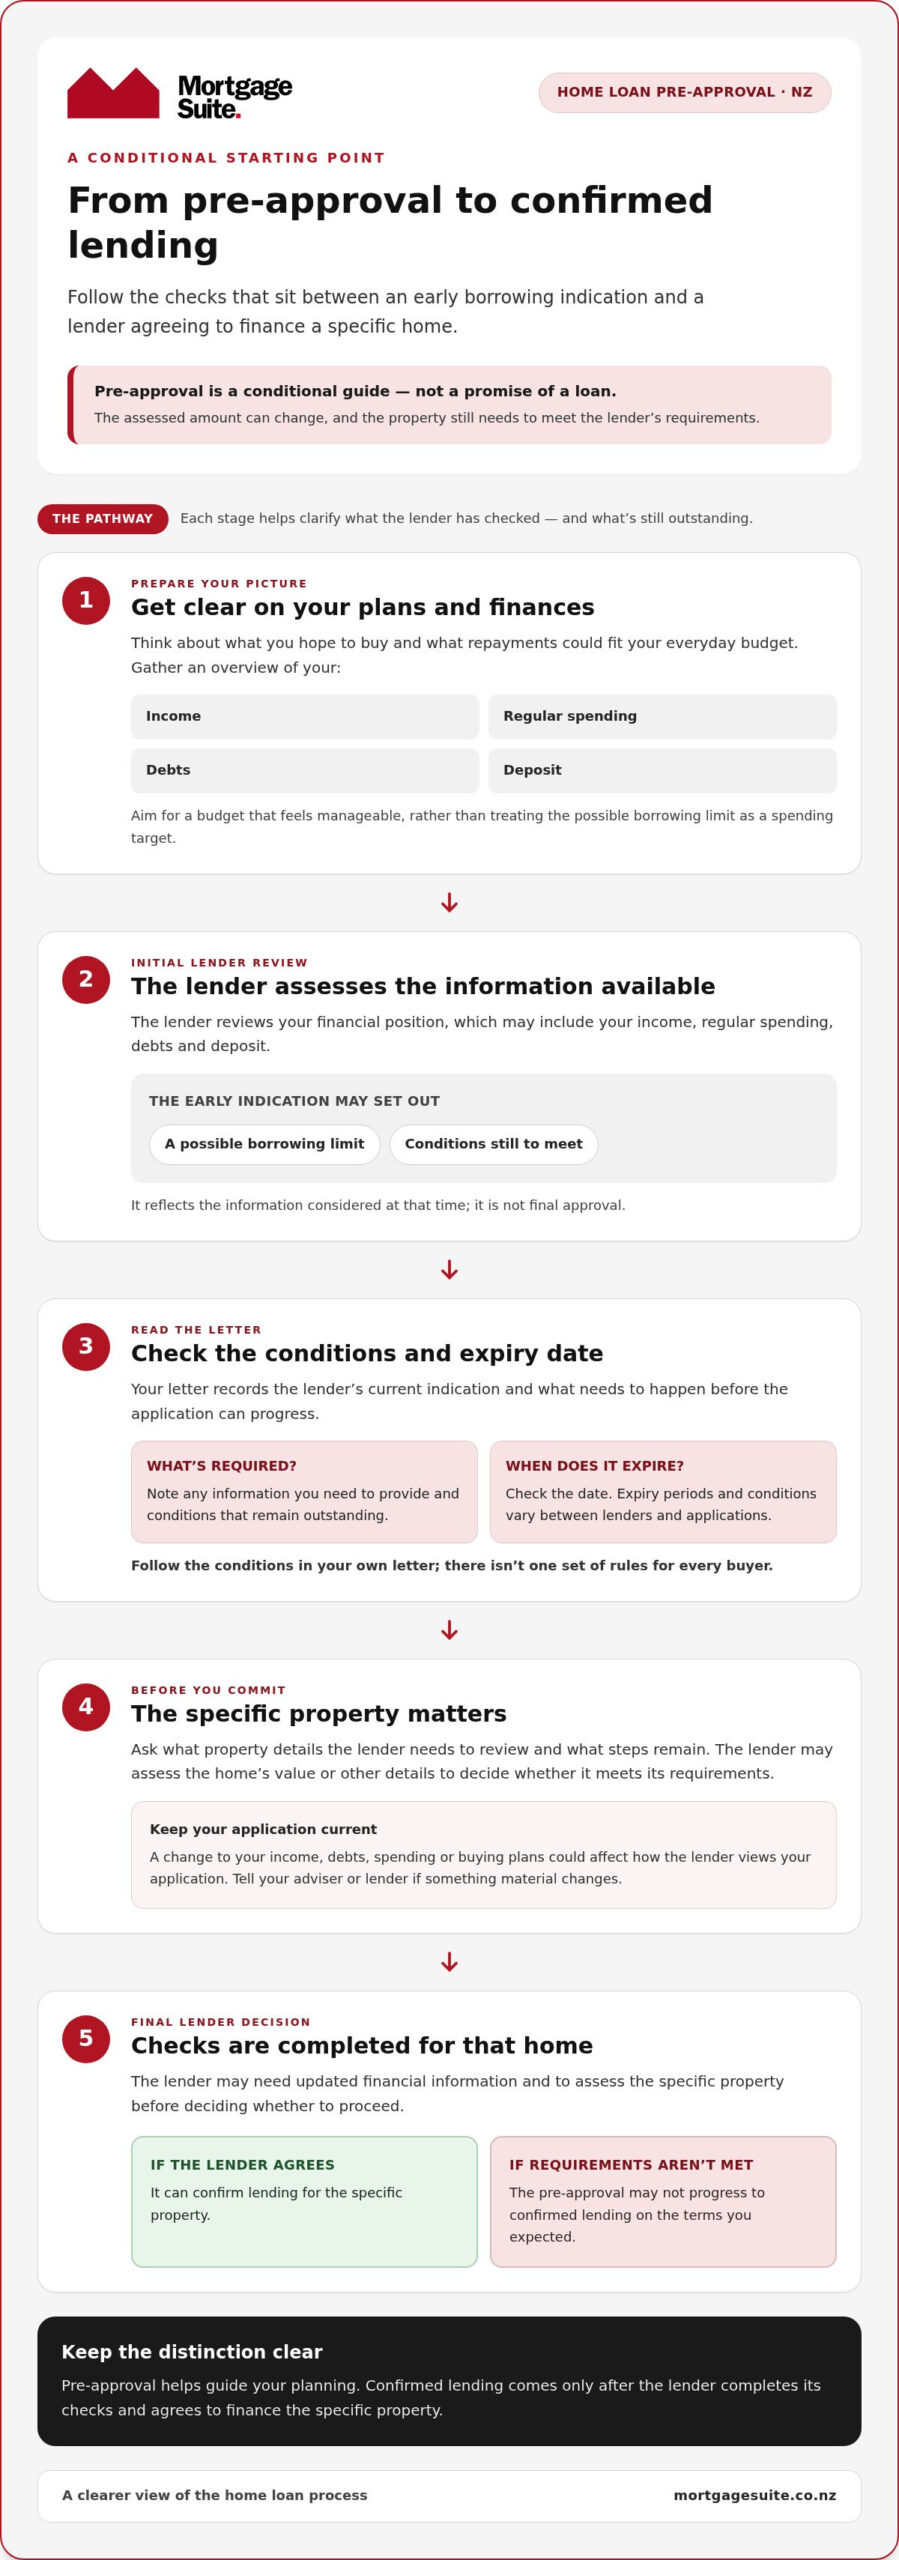
Planning to buy a home can feel exciting one moment and uncertain the next. You may be wondering what a lender could let you borrow, and whether that figure will hold once you find a property. Home loan pre-approval NZ is a conditional indication from a lender, based on the information available about your finances at the time. It can help you plan, but it isn’t final approval or a promise that the lender will fund any home you choose.

In its initial review, a lender considers your financial position, which may include your income, regular spending, debts and deposit. The outcome gives you an indication of a possible borrowing limit and any conditions still to be met. Those conditions depend on the lender and your application. The property may also need to meet the lender’s requirements before it agrees to the loan. That means the pre-approval amount could change, or the lending may not proceed for a particular home.

Think of pre-approval as an early checkpoint. The lender has considered your circumstances, but may not have completed every check needed to approve a loan for a specific property. A general overview of how lenders assess a mortgage loan can explain the broader process. Your own lender’s conditions are the ones to follow.

What does a pre-approval letter tell you?

The letter records the lender’s current indication, any borrowing limit it has assessed and the conditions that apply. Read it closely and note what the lender has considered and what remains outstanding. Treat the figure as a ceiling for planning, not a spending target. Work out a budget that leaves room for everyday expenses and feels manageable, rather than assuming you should borrow the maximum amount.

Why arrange pre-approval before house hunting?

An early indication can help you focus your search on homes that are more likely to fit your borrowing range. It also gives you time to understand the lender’s conditions before a suitable property comes up. That preparation can reduce last-minute uncertainty, but it can’t guarantee your offer will be accepted or the purchase completed. Keep your plans flexible and revisit the lender’s requirements when you’re considering a particular home.

Use pre-approval as a planning tool, not a green light to commit without checking the details. Your financial position can change, and the property itself matters to the lender’s decision. Knowing these limits helps you house hunt with a clearer idea of what may be possible while leaving room for the checks still to come.

Pre-approval conditions, expiry and final loan approval

A pre-approval can give you a useful starting point, but its conditions shape what happens next. The conditions vary between lenders and applications, so there’s no single expiry period or set of rules for every buyer in New Zealand. Check the letter for its expiry date and requirements. Make a note of anything you need to provide or do before the lender will consider the next stage.

Pre-approval is a conditional indication. Confirmed lending comes only after the lender completes its checks and agrees to finance the specific property. Keep that distinction in mind before making an offer or taking on other commitments.

What conditions might a lender attach?

Conditions may include providing updated financial information or having the lender assess the property you want to buy. The lender may also need to check that the home fits its criteria before confirming the loan. These are general examples, not a checklist for every lender. Your letter sets out the conditions for your application, so read it carefully and ask your adviser to explain anything that isn’t clear.

Property checks can affect the outcome. For example, a lender may need to review the property’s value or other details before deciding whether it can support the proposed lending. If the property doesn’t meet the lender’s requirements, the pre-approval may not progress to confirmed lending on the terms you expected. If you’re considering the Kāinga Ora scheme, its Kāinga Ora First Home Loan pre-approval information explains that scheme’s eligibility and application steps.

What happens when your circumstances or plans change?

Your application reflects the information considered at the time. A change to your income, debts, spending or buying plans could affect how a lender views it. The impact depends on your circumstances and the lender’s assessment. Tell your adviser or lender if something material changes, rather than assuming the existing indication still applies.

Timing matters, too. Check when your pre-approval expires and whether any conditions need attention before then. If it has expired or your situation has changed, the lender may need updated information or to review your application again. Don’t rely on an old letter as if it were a current, final decision.

Pre-approval is separate from deciding how your eventual loan will be set up. The interest rate and loan structure are considered as part of arranging lending, while pre-approval is an earlier, conditional assessment. Keeping these steps separate helps you consider the home alongside repayments and flexibility that suit your plans.

If you’re unsure how a condition affects your next move, talk with Mortgage Suite’s home loan advisers to understand the process and discuss your circumstances before you commit.

How to prepare for home loan pre-approval in NZ

A little preparation can make applying for home loan pre-approval NZ feel more manageable. Start by getting clear on what you hope to buy and what repayments could fit your everyday budget. Then gather an overview of your finances. You don’t need to guess every document a lender will request. Requirements differ, and your adviser can guide you on what’s needed for your application.

  1. Clarify your plans. Think about the type of home you’re looking for, who will be borrowing and what repayments feel comfortable. Note any plans that could affect the application, such as a change in work or a commitment you expect to take on.
  2. Organise your financial records. Gather current information about your income, regular spending, debts and deposit. Keeping it together can help you spot gaps and answer questions clearly.
  3. Talk through your income and commitments. Be ready to explain how you earn, what regular payments you make and any changes that could affect your finances. A clear picture helps the lender assess your application in context.
  4. Provide the information requested. Your adviser will explain what’s needed for your situation. Give complete, up-to-date details and ask if you’re unsure how to describe an item or which records are relevant.

What information should you organise?

Start with records that show how money comes in and goes out. Depending on your circumstances, these may include information about employment or business income, regular household spending, debts and savings for your deposit. This is a starting point, not a fixed document list. Your adviser will explain what information is needed and whether anything should be updated before the application is assessed.

Accuracy matters more than trying to make your finances look a certain way. If a payment or income source needs context, make a note of what it relates to so you can explain it. Clear, consistent information can help avoid confusion while your application is reviewed.

How can you prepare if your income is not straightforward?

If you’re self-employed, work as a contractor or have income that changes, it’s understandable to wonder how a lender will view it. Different income patterns call for a closer look at the full picture, and they’re not a reason to feel judged. Relevant records and a clear explanation of how your income works can help show the context behind your finances.

Mortgage Suite can present your circumstances to suitable lenders and discuss possible pathways, including alternative lending channels when mainstream criteria don’t fit. This doesn’t guarantee approval, but it can help you understand your options and what information may support an informed assessment.

For an early sense of how different loan amounts and repayments might affect your plans, try the Mortgage Suite mortgage calculator. Treat the result as a planning aid, not a decision about how much a lender will approve. Your borrowing capacity depends on your circumstances and the lender’s assessment.

Home Loan Pre-approval in NZ: What to Expect in 2026

Steps after pre-approval before making an offer

Finding a home that feels right is a big moment. Before moving from a shortlist to an offer, compare the property details with your pre-approval conditions. The lender still needs to assess the specific home, so the initial indication isn’t final confirmation that the purchase can be funded. A simple process can help you see what’s outstanding and keep the right people informed.

After initial pre-approval, the lender needs to review the chosen home before it can confirm the loan.

What changes when you find a property?

Share the property details with your adviser promptly so they can identify what the lender needs to review. The lender may assess whether the home meets its criteria and whether property-related conditions in your pre-approval have been met. The outcome depends on the property and the lender’s assessment, not just the borrowing figure in your letter.

It’s also sensible to do your own checks on the home. For example, a building report is a professional assessment of a property’s condition and defects. Other checks can help you understand the home and the purchase, but they don’t guarantee that the lender will approve the loan or that the property is free of issues. Keep these separate from the lender’s decision. Passing one check doesn’t automatically satisfy the others.

Before making commitments, reread the pre-approval conditions and make sure you understand what remains to be done. If a condition is unclear, raise it with your adviser before relying on the initial indication. This gives you a clearer view of what the lender still needs, without assuming that finance is confirmed.

How can you keep the purchase process organised?

Once you have a property in mind, keep the moving parts together in one place. A simple note or checklist can help you track:

  • The conditions in your pre-approval and any expiry date.
  • Property information and documents shared with your adviser or lender.
  • Requests for further information and whether you’ve responded.
  • Key purchase milestones to discuss with your adviser as they come up.

Update your record if the property changes or your circumstances shift. A pre-approval relates to the information and conditions considered at the time, so don’t treat it as final confirmation for a different home or a changed situation. If you’re buying your first home, consider your wider purchase plans alongside the finance steps so you can stay focused on what matters to you.

Home loan pre-approval NZ can help you plan, but the property review and outstanding conditions move the application towards a final decision. If you’ve found a home and want help understanding the next lending steps, talk with Mortgage Suite about your home loan.

How Mortgage Suite can support your home loan pre-approval

Applying for home loan pre-approval NZ can feel like a lot to manage, especially if you’re unsure what a lender will focus on. Mortgage Suite starts by learning about your home-buying plans, financial circumstances and what you want your loan to achieve. That conversation helps shape the next steps around you, rather than treating your application as a set of figures alone.

Your adviser can explain information requests and lender conditions in plain English, help present your application and negotiate with lenders that suit your situation. If your circumstances don’t fit a mainstream bank’s usual approach, that isn’t a judgement on you or your plans. Mortgage Suite can discuss alternative lending channels too. Each lender makes its own assessment, and no pathway guarantees approval.

This support can be useful if your income varies, you’re self-employed or your financial picture needs context. A clear explanation and relevant information can help a lender understand your circumstances, but the right approach depends on your application and the lender’s criteria. Your adviser can talk through the options and what may be needed before you decide how to proceed.

When can a mortgage adviser help with pre-approval?

An adviser can help you make sense of a lender’s requests, identify questions to resolve and keep track of conditions as your application progresses. If your work, income or commitments don’t follow a simple pattern, a tailored discussion can help present the full picture. For plain-English information as you prepare, Mortgage Suite’s Mortgage School home loan guides cover related topics.

An adviser can also help you consider whether a possible borrowing amount fits your plans, rather than focusing only on the maximum a lender may consider. Your goals matter: the home you hope to buy, the repayments you’re comfortable with and the flexibility you may want from your loan are all useful parts of the conversation.

What is a sensible next step?

Start with a conversation about what you hope to buy, how your finances work and what questions are on your mind. You don’t need every detail sorted before talking it through. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to helping borrowers understand the process and discuss suitable lending pathways.

From there, you can get clearer on what information may be useful and what the next step could look like for your circumstances. If you’d like to talk through your home-buying plans, get in touch with Mortgage Suite. It’s a chance to discuss your situation and options, not a promise of a particular lending outcome.

Take your next step with a clearer plan

Your next move doesn’t have to be a big commitment. Start by noting what you want your home loan to make possible, what questions are still on your mind and any changes that could affect your plans. That gives you a practical starting point for working out how home loan pre-approval NZ fits your buying journey.

A conversation can turn those questions into a clear next step, whether that’s getting your information in order or talking through a lender’s conditions. You can also discuss what matters beyond the borrowing limit, such as repayments that feel manageable and a loan structure that suits your plans. You don’t need to have every answer ready before you begin.

Talk through your home loan pre-approval options with Mortgage Suite and get a clearer sense of what to do next. With a steady plan and the right questions, you can move towards your home-buying goals with more confidence.

Frequently Asked Questions

Can I make an offer on a house with pre-approval?

You may be able to make an offer, but check how the proposed purchase fits the amount and limits in your home loan pre-approval NZ letter. Your adviser can help identify what property information the lender needs. Keep a note of outstanding items alongside your offer details so you can track what still needs attention. The seller makes a separate decision about accepting an offer, and pre-approval doesn’t reserve the property.

Does home loan pre-approval affect my credit record?

The effect can depend on the lender’s application and checking process. Before proceeding, ask what checks are part of the application and whether the lender needs to access your credit information at that stage. You can also ask what information you’ll need to provide and how it will be used for the assessment. This gives you a clearer picture of the process without assuming an enquiry will improve or harm your record.

Can I get home loan pre-approval if I am self-employed?

Yes, self-employed buyers can discuss pre-approval. To explain your circumstances, prepare a simple overview of how business income reaches you, including any changes in how you’re paid. Keep business income distinct from money available for personal use, and note regular business commitments. Your adviser can guide you on relevant records for your situation, as requirements vary between applications.

What happens if my income or debts change after pre-approval?

A change may affect your application, so record what changed and when, then update your adviser. For example, note whether a new debt has a regular repayment or whether a change in work affects your expected income. Your adviser can help identify which figures or records the lender needs to review and whether any conditions or next steps are affected. Don’t rely on the earlier figures. The lender will assess the updated information.

Can I apply for pre-approval with more than one lender?

You can discuss options with more than one lender, but first compare what each application involves. Consider the information requested, the conditions attached to any indication, and how the proposed repayments or loan structure fit your plans, not only the borrowing limit. Keep a record of applications and requests, and coordinate discussions with your adviser. That can help you avoid mixing up lender questions or providing inconsistent information.

What if a bank declines my home loan pre-approval?

Start by finding out what led to the decline and whether it relates to missing information, the lender’s assessment or another part of the application. Check that the details considered were accurate, then discuss whether further information could clarify your situation. A decline isn’t a personal judgement. Mortgage Suite can help you understand the feedback and discuss mainstream or alternative lending pathways, though no lender can be assumed to approve an application.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Commercial Property Loans Auckland: Your 2026 Guide to Simple Business Financing

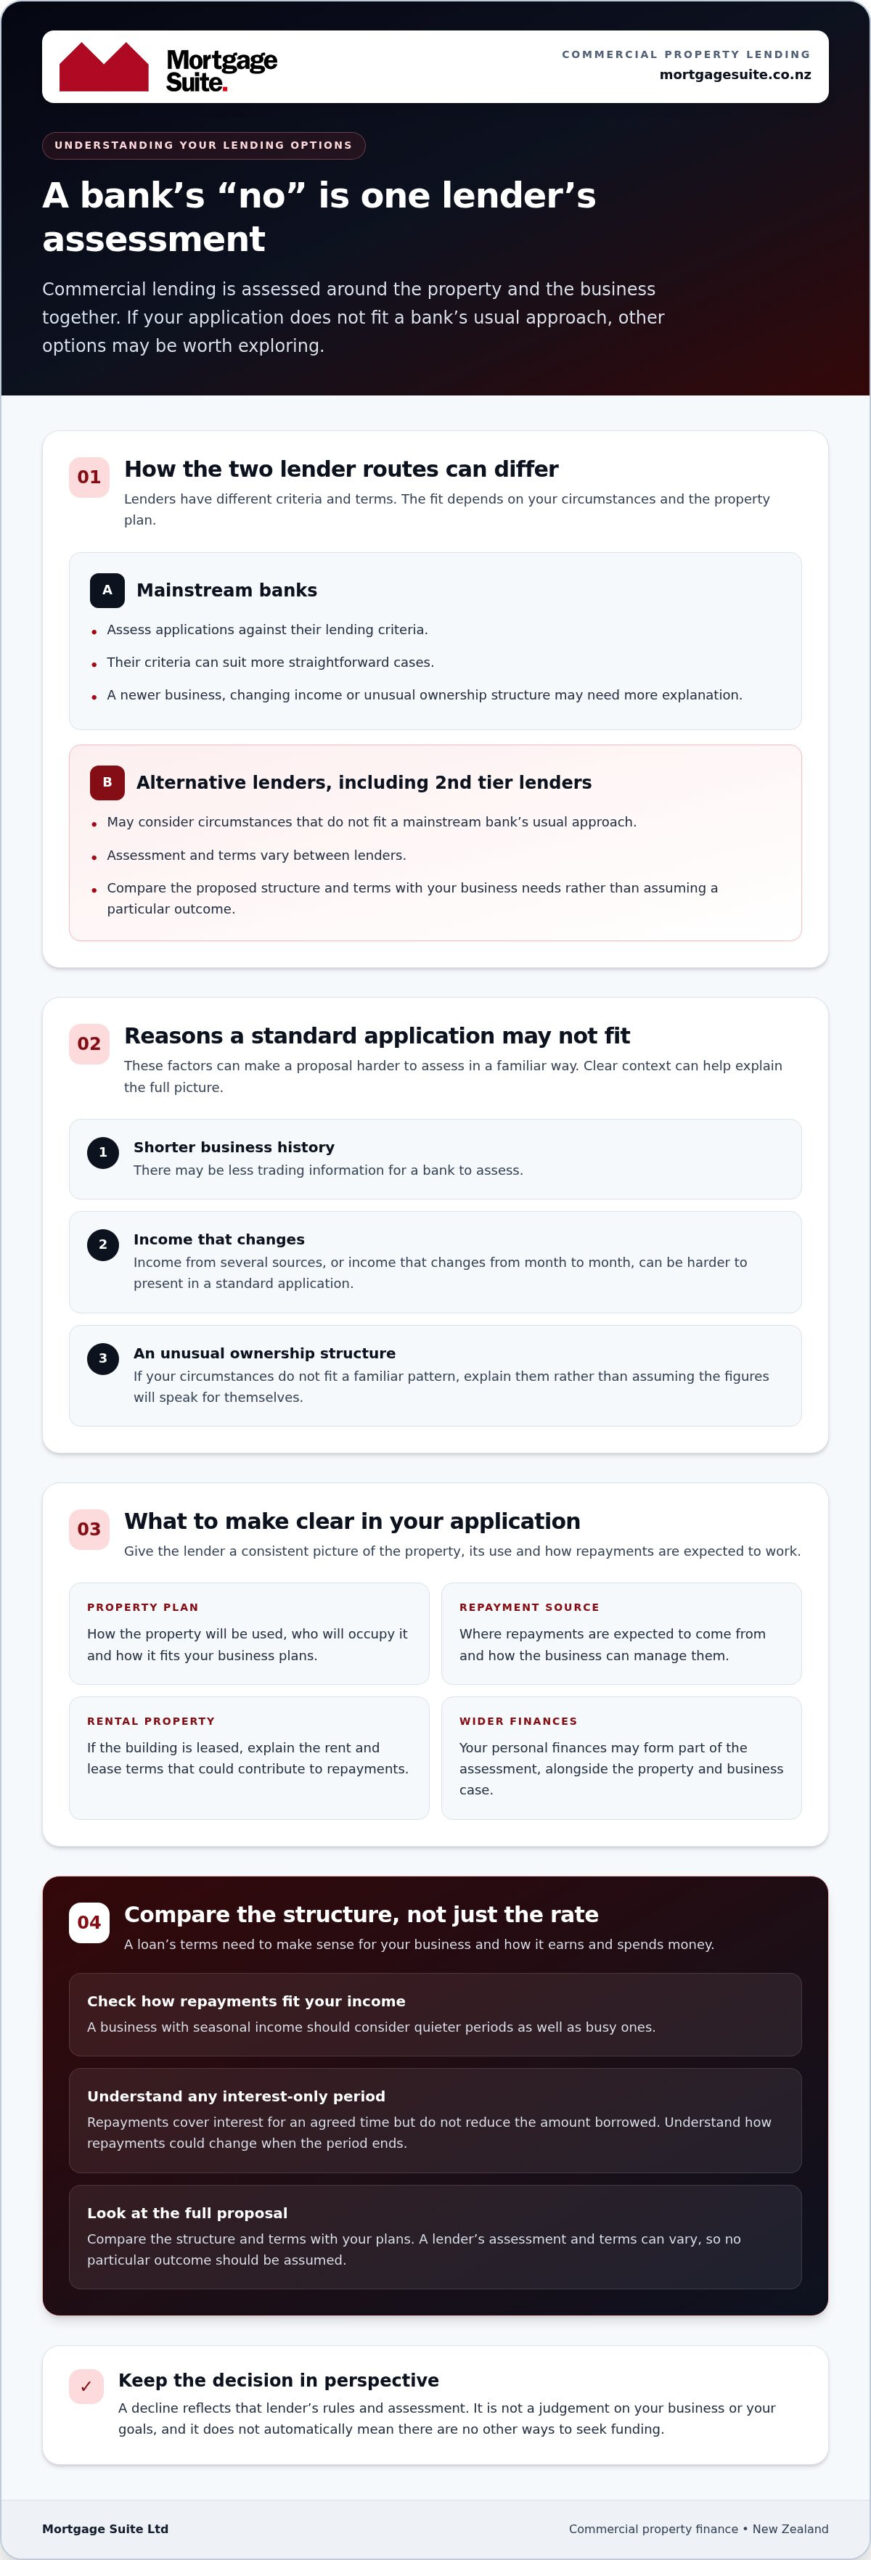
A mainstream bank’s “no” doesn’t always mean your plans are over. If you’re considering commercial property loans, it’s natural to feel uncertain: business lending can involve unfamiliar terms, and lenders assess it differently from a home loan.

You may want a clear idea of what lenders consider and what to do if your application doesn’t fit a bank’s usual approach. A decline reflects that lender’s assessment, not a judgement on your business or your goals. Other lending options may be worth exploring.

This guide covers how commercial and residential lending differ, what may shape a lender’s decision and how to prepare a clear application. It also explains how 2nd tier lending may suit borrowers who don’t fit mainstream criteria. Mortgage Suite Ltd’s Krish Krishna brings more than two decades of banking and brokerage experience to lender discussions, helping you understand your options and negotiate the terms. The aim is to give you a practical way to explore finance that fits your business plans, without jargon or pressure.

Key Takeaways

  • Commercial property loans are assessed with the building’s business use and income in mind, not just your personal salary.
  • Compare lending options by how well their criteria and terms fit your business and property plans, not only by the headline rate.
  • Prepare clear details about your contribution and how business or rental income could support repayments.
  • Organising your paperwork before you apply can make the process easier to manage.
  • A broker can present your circumstances clearly to lenders and help you understand possible next steps if a bank declines your application.

The Basics: How Commercial Property Loans Work in New Zealand

A commercial property loan is borrowing to buy a building used for business, such as an office, shop, café, warehouse or workshop. It can help you secure premises for your own business or buy a property that earns rental income.

Lenders usually consider what the property will be used for and how it may generate income. If it’s leased, the rent and lease terms can help show how the building could contribute to repayments. If your business will occupy it, explain how the premises fit your plans and how the business will manage the repayments. Your personal finances may also be part of the assessment, but they are not the only consideration.

Commercial property can involve different lease arrangements and tax considerations from a family home. These details may affect how a lender views the property and the proposed borrowing. For commercial property loans Auckland and elsewhere in New Zealand, the property, its intended use and the wider business case all matter.

Why a Commercial Loan is Different to a Standard Home Loan

A home loan is mainly assessed around buying somewhere to live. A commercial loan is assessed around the property and the business plan together. A lender may look at rental income, how the premises will be used, your business’s ability to make repayments and your wider financial position.

Commercial loan terms can differ from home loans. For example, a commercial loan might have a 15-year term rather than a 30-year home-loan term, but the structure depends on the lender and application. The lending may be shaped around business needs, so make sure you understand the repayment plan and any conditions before committing.

You may be able to apply as an individual, through a company or through a trust. The right structure depends on your circumstances and can affect how a lender assesses the application. Clarify who will own the property, who will borrow and how the building will be used. That gives the lender a consistent picture from the outset.

The Different Types of Property You Can Finance

Commercial property includes a range of premises. Its purpose, condition and income potential can all shape how a lender assesses it. Explain how the property will support your business goals and what you plan to do with it.

  • Retail spaces: Shops and cafés where customers visit. Explain whether your own business will occupy the space or whether you plan to lease it.
  • Industrial units: Warehouses and workshops used for trade, storage or manufacturing. Describe how the premises suit the business activity.
  • Professional offices: These can range from a small suite to a whole building floor, depending on your business or tenants’ needs.

Start by setting out the property’s intended use, who will occupy it and how you expect to manage repayments. Clear answers help a lender understand the proposal without relying on banking jargon.

Mainstream Banks vs Alternative Lenders: Finding Your Best Fit

A bank decline can feel like a door closing, particularly after you’ve put time into a business plan or found a suitable property. But the decision reflects that lender’s rules and assessment of your application. It doesn’t automatically mean there are no other ways to seek funding.

Mainstream banks generally assess applications against their lending criteria. Those criteria can suit straightforward cases, while a newer business, uneven income or unusual ownership structure may need more explanation. Alternative lenders, including 2nd tier lenders, may consider circumstances that don’t fit a mainstream bank’s usual approach. Compare the proposed structure and terms with your business needs rather than moving to another lender without a clear plan.

When the Big Banks Might Say No

A shorter business history may mean there’s less trading information for a bank to assess. Income from several sources, or income that changes from month to month, can also be harder to present in a standard application. If your circumstances don’t fit a familiar pattern, explain them clearly rather than assuming the figures will speak for themselves.

Set out how you’ll use the property, where repayments are expected to come from and what supports the business’s ability to meet them. A negotiator familiar with mainstream and alternative lending can help present these details and identify a possible next step. Before committing to a property, discuss the legal steps with your solicitor. The New Zealand Law Society on Property Law provides general information about property transactions and the role of a lawyer.

The Benefits of Using a Non-Bank Lender

Alternative lenders may consider applications that don’t match a mainstream bank’s usual criteria. Their assessment and terms vary, so don’t assume a particular lender or outcome in advance. Some may offer interest-only periods, where repayments cover interest for an agreed time but don’t reduce the amount borrowed. If you’re considering this structure, understand how repayments could change when the period ends.

A lender may also consider how your business earns and spends money when shaping the terms. For example, a business with seasonal income should consider how repayments fit quieter periods as well as busy ones. A negotiator can help compare options, explain trade-offs and discuss rates and terms with lenders on your behalf. The aim is to find a structure that supports your plans and remains manageable, not to promise approval or the lowest rate.

If your application doesn’t fit a bank’s usual approach, other funding routes may be worth exploring. Mortgage Suite helps businesses consider commercial property loans Auckland and across New Zealand, including 2nd tier options. Explore Mortgage Suite’s lending support to understand possible next steps.

The Checklist: What Lenders Really Look for in Your Application

Focus on the practical questions behind the paperwork: how much are you contributing, how will repayments be covered, what is your plan for paying the loan back, and is the property suitable for its intended use? Lenders may assess these factors together, so a strong point in one area doesn’t automatically make up for a gap in another.

For commercial property loans Auckland and elsewhere in New Zealand, requirements can vary by lender and property. Use this checklist to organise the main parts of your application.

Understanding the Deposit and Borrowing Limits

Loan-to-value ratio, or LVR, means the amount you borrow compared with the property’s value. Commercial lending may call for a deposit of around 30% to 35%, but the amount a lender will consider depends on the property and your application. Treat that range as a guide, not a promise.

If you own a home, its equity may sometimes help support a commercial purchase. A mortgage calculator can help you compare how different loan amounts affect estimated repayments. Use it to explore scenarios, then remember that a lender’s assessment and final terms may differ from a calculator estimate.

Why the Lease Agreement is Your Best Friend

If tenants already occupy the property, the lease can help show the lender what income the building may bring in. A tenant and a lease with a longer time remaining can make that income easier to assess. The lender will still consider the full application, not just the lease.

A vacant property can be harder to assess because it has no current rental income. That doesn’t automatically end the conversation: some alternative lenders may consider your wider plan, including how you intend to use or lease the building. Explain the steps you expect to take and how you could manage repayments while it’s empty.

Repayment Ability, Property Condition and Your Plan

Lenders want to understand how you expect to repay the loan. That may include business income, rent from tenants or a combination of both. Set out expected income and regular business commitments so the repayment plan is easy to follow. If income varies, explain the pattern instead of presenting one strong period as typical.

The property itself also matters. Its condition, safety rating and current use may affect whether it is suitable as security and fits your plans. Describe the building honestly and explain how you intend to use it.

Finally, outline your plan for repaying the loan over time. If selling the property may be part of that plan, explain how and when you expect that to happen. A realistic account helps a lender understand your thinking, even if your circumstances change. Bringing these points together gives your application a clear story rather than a stack of disconnected figures and documents.

Commercial Property Loans Auckland: Your 2026 Guide to Simple Business Financing

Steps to Get Your Commercial Loan Sorted Faster

Commercial finance can feel like a lot to manage while you’re running a business. Get key records together early, be upfront about your plans and have someone help present your application. Preparation can’t guarantee a decision, but it can reduce avoidable back-and-forth and make it easier to answer lender questions.

Organise Your Financial Story

Before you start viewing properties, gather your last two years of business accounts, current lease details if relevant and a short explanation of what you want the property to do for your business. If you’re looking to refinance, note what you want the new lending to achieve, such as changing the loan structure or reviewing the existing terms.

Clear, up-to-date records make your income, commitments and plans easier for a lender to assess. Keep information consistent and flag anything unusual instead of leaving a lender to guess. If business income varies, explain the pattern and give context for quieter or busier periods.

Tell your broker about your goals and any concerns. The more they understand your circumstances, the more clearly they can present your application and look for a lender whose approach fits. A broker can act as your advocate, explain possible structures and discuss rates and terms with lenders on your behalf.

Bring Your Professional Team Together

Your broker, accountant and solicitor each bring a different perspective. Your broker can help prepare and present the finance application; your accountant can help explain business records and cash flow; your solicitor can advise on the legal documents involved in the purchase or lending. When everyone understands the plan, questions are easier to address without crossed wires.

Krish Krishna brings more than two decades of banking and brokerage experience to lender discussions. An experienced negotiator can help you compare the overall structure, not just the headline rate, and raise questions about how the terms fit your business. Even a small difference in interest can add up over the life of a loan, but no particular saving or rate can be promised.

An early lending discussion can give you an initial view of what may be workable, subject to the lender’s assessment and the property details. It isn’t final approval, but it can help you set a sensible search range and avoid spending time on properties that don’t fit your borrowing plans.

With preparation and the right support, commercial property loans Auckland needn’t feel like a slog. Talk with Mortgage Suite about your commercial lending plans to understand the next steps.

Why Partnering with Mortgage Suite Makes the Difference

Commercial finance can be a lot to carry on your own. You’re balancing business decisions, property details and lender requirements while keeping everyday work moving. Mortgage Suite helps make the process easier to understand as you consider your options.

Krish Krishna’s experience across banking and brokerage gives him a practical understanding of how lenders assess applications. Mortgage Suite takes time to understand your goals, explain what lenders may need and present your circumstances clearly. The aim is to find a lending option that suits your business plans, not just one that looks appealing at first glance.

A Veteran Hand in a Fluctuating Market

Lending conditions and lender requirements can change, and an option that suits one business may not suit another. Working with someone who understands mainstream and alternative funding channels can help you make sense of the choices. Your rate matters, but so do the repayment structure, terms and how well the lending fits your business over time.

Mortgage Suite’s “Mortgage School” approach is about explaining the process in plain language, so you can make informed decisions rather than feel rushed through paperwork. You should understand what a lender is considering, what a proposed structure means for your business and what questions to raise before moving ahead. Mortgage Suite client reviews offer a chance to hear how other clients describe their experience.

Ready to Take the Next Step?

If you’re weighing up a purchase or a bank has already declined your application, a conversation can help clarify which options may be worth exploring. You don’t need every detail worked out before discussing your plans. Start with what you want the property to achieve, where your application stands and what is making the process feel uncertain.

From there, you can work through possible next steps, including whether a mainstream lender or a 2nd tier option may better fit your circumstances. No application is guaranteed approval, but a clear and honest discussion can help you understand where you stand and what may be worth considering.

For commercial property loans Auckland, Mortgage Suite can advocate for you, explain the choices and negotiate with lenders on your behalf. The goal is to find a workable path towards your business plans while keeping you informed at each stage.

Take the Next Step with a Clear Plan

Before pursuing commercial property loans Auckland, define what you need the property and lending to achieve. Is your priority securing premises for your business, supporting future growth or finding a structure that fits the way your income comes in? A clear goal gives your next finance conversation a useful starting point.

You don’t need every detail worked out before asking questions. Start with what you know, be open about what’s uncertain and consider which terms would help your business stay on steady footing. The right path depends on your circumstances, but a bank’s earlier decision doesn’t have to be the final word.

Mortgage Suite can help you discuss commercial finance options and next steps for your business. Talk with Krish and the team about your commercial finance plans to start working towards a funding plan that makes sense for you.

Frequently Asked Questions

How much deposit do I typically need for a commercial property loan?

There isn’t one deposit amount that suits every commercial purchase. A lender may consider the property’s value and type, your financial position and the strength of the application. For commercial property loans Auckland, the amount you need depends on how the lender assesses those details. Get a clear estimate based on your plans before committing to a purchase, as an initial figure may change after the property is assessed.

Can I get a commercial loan if I am self-employed or have a complex income?

Being self-employed or having income that varies doesn’t automatically rule you out. Lenders need to understand how your business earns money and whether that income can support the proposed repayments. If revenue rises and falls through the year, records showing the pattern can help explain your position. Lenders may assess your circumstances differently, so a bank’s criteria aren’t the only possible route.

What is the difference between a business loan and a commercial mortgage?

A business loan can fund a range of business needs, while a commercial mortgage is lending connected to buying or refinancing business property, with the property usually forming part of the lender’s security. For example, a business might borrow to support its operations, while a commercial mortgage helps fund premises. The right fit depends on what you’re borrowing for, how the funds will be used and what security is available.

How long does the approval process usually take for commercial finance?

There’s no set timeframe for every commercial finance application. The process can depend on how complete your records are, the lender’s assessment and how quickly property information can be gathered. A complicated ownership structure or missing paperwork may prompt extra questions. You can help avoid preventable delays by preparing your accounts and purchase details early, then responding promptly if the lender asks for more information.

Can I use the equity in my home to buy a commercial property?

It may be possible to use equity in your home to support a commercial purchase, depending on your financial position and the lender’s assessment. Equity is the part of your home’s value that isn’t already covered by lending. Before using it, consider how additional borrowing could affect your household if business income changes or the commercial property takes time to earn income.

Do I need to have a tenant already signed up before I apply for a loan?

Not necessarily. A tenant and signed lease can give a lender useful information about expected rental income, but a vacant building may still be considered. Explain how you plan to use or lease it, what steps you’ll take to find tenants and how you could manage repayments in the meantime. A lender will assess the whole application, so a tenant isn’t the only factor.

What happens if my bank has already turned down my application?

A bank’s decision doesn’t automatically close off other options. Start by understanding why it declined the application, such as concerns about the property, your records or the proposed loan structure. That can help you and a broker decide whether to address a gap or explore a different lender. Mortgage Suite works with 2nd tier lending for situations that don’t fit mainstream-bank criteria, though approval depends on the lender’s assessment.

Are interest rates higher for commercial loans than for home loans?

Commercial loan rates can differ from home-loan rates, but there isn’t one rate for every borrower or property. A lender may consider the security, your financial circumstances and the loan structure when setting terms. Compare more than the headline rate: repayment arrangements and flexibility also affect how well the lending suits your business. Ask for the proposed terms in plain language so you can judge the full arrangement.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Investment Property Loan to Value Ratio NZ: A 2026 Guide

What if your deposit isn’t the only number shaping your investment property borrowing options? For Kiwis, the investment property loan to value ratio nz is a useful starting point, but it doesn’t decide the whole application. The lender’s valuation, your income and your existing debts can all affect how much it may be willing to lend.

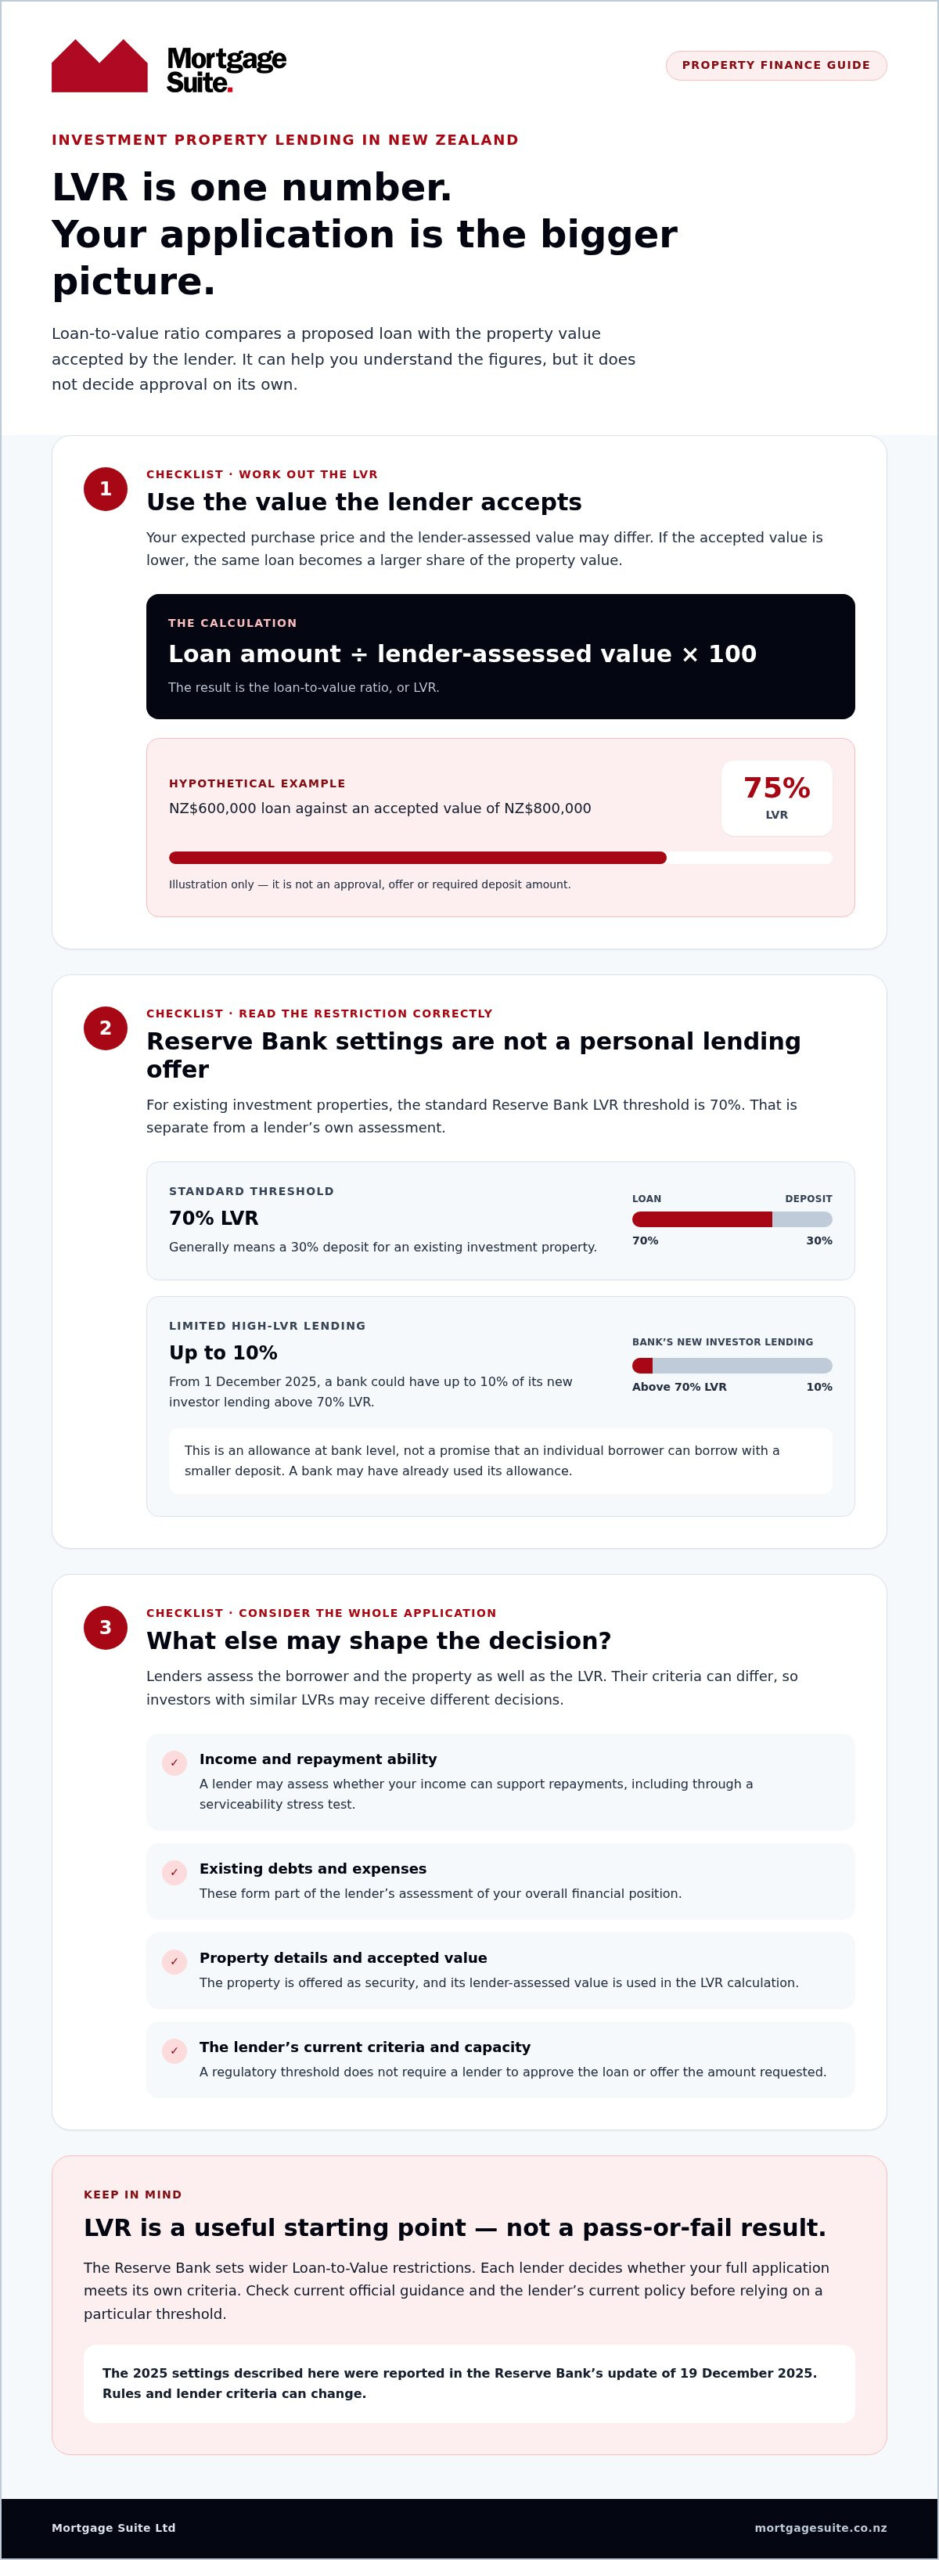
For an existing investment property, the Reserve Bank’s standard Loan-to-Value restrictions generally set a 70% LVR, meaning a 30% deposit. That’s separate from a lender’s own criteria, and limited high-LVR lending doesn’t guarantee an offer. Lenders also assess whether your income can support repayments, including through a serviceability stress test.

This guide explains how to calculate LVR, how a valuation could affect your plans, and how Reserve Bank restrictions differ from individual lender decisions. You’ll also learn what to discuss before making an offer and how a new-build property or alternative lending pathway may affect your options. Mortgage Suite Ltd can help you consider the full picture and compare possible routes, while the lender makes the final decision.

Key Takeaways

  • Learn how to calculate the investment property loan to value ratio nz lenders consider, using the loan amount and lender-assessed property value.
  • See why Reserve Bank Loan-to-Value restrictions and a lender’s own assessment are separate parts of the lending picture.
  • Gather details about your deposit or available equity, income, debts and expected rent before discussing finance.
  • Understand how the property itself, including its valuation and rental information, may form part of the lender’s assessment.
  • Explore how Mortgage Suite can help compare mainstream and alternative lending options based on your circumstances. The lender decides whether to approve an application.

What does investment property loan to value ratio mean in NZ?

Loan-to-value ratio, usually shortened to LVR, can sound technical when you’re planning an investment property purchase and weighing up the property, deposit and loan. Put simply, the investment property loan to value ratio nz is the loan amount divided by the value the lender accepts for the property, expressed as a percentage. It shows how large the loan is compared with the assessed value, but it doesn’t tell you by itself whether a lender will approve your application.

The Loan-to-value ratio is a common way to describe the relationship between borrowing and property value. Understanding the calculation helps you make sense of the figures. Remember, though, that a lender considers more than this one measure.

How is an investment property LVR calculated?

Use this formula:

LVR = loan amount ÷ lender-assessed property value × 100

Hypothetical calculation, not an approval or offer: If a lender accepts a property value of NZ$800,000 and the proposed loan is NZ$600,000, the calculation is NZ$600,000 ÷ NZ$800,000 × 100, giving an LVR of 75%. These figures are for illustration only. They don’t suggest a required deposit or indicate what a lender would offer in a real application.

The value used in the calculation matters. Your expected purchase price and the value accepted by the lender may differ. If the accepted value is lower than you anticipated, the same loan amount represents a larger share of the property’s value, resulting in a higher LVR. Treat your own estimate as a planning guide rather than assuming the lender will use the same figure.

What does a lower or higher LVR tell you?

A lower LVR means the loan is smaller relative to the property’s assessed value. It generally also means you have more equity in the property, based on that value and loan amount. Equity is the part of the property’s value not covered by the loan, although other lending secured against the property can affect the overall picture. A higher LVR means the loan makes up a larger share of the assessed value.

Think of LVR as one part of the discussion, not a pass-or-fail result. It doesn’t account for your full financial position, including income, existing debts or ability to manage repayments. Lenders consider the wider application, and their criteria can differ. A figure that looks workable on paper isn’t a promise of approval. Equally, a higher LVR doesn’t tell the whole story about your circumstances.

LVR measures the loan against the property’s assessed value. A lending decision also considers the borrower and the full application. Keeping that distinction in mind helps you understand what the percentage shows and what it can’t tell you.

How do New Zealand LVR restrictions affect investment loans?

Understanding the investment property loan to value ratio nz rules means separating two things: restrictions set by the Reserve Bank of New Zealand (RBNZ) and the lending decision made by an individual bank. The restrictions can shape how much high-LVR residential lending banks may make. They don’t set a personal borrowing limit for every investor, and they don’t require a bank to approve a loan just because an application fits within a regulatory setting.

For existing investment properties, the RBNZ’s published settings, as reported in its update of 19 December 2025, set a standard 70% LVR threshold for investor lending. Banks can make a limited share of new lending above that threshold: from 1 December 2025, up to 10% of a bank’s new lending to investors could be above 70% LVR. This is a bank-level allowance, not a promise that a particular borrower can borrow with a smaller deposit. A bank may also have already used its available high-LVR lending allowance.

What is the difference between a Reserve Bank restriction and lender policy?

The RBNZ sets Loan-to-Value restrictions that influence how banks can lend against residential property. Each lender then assesses the borrower and property under its own credit criteria. That assessment may consider the full application, including income, debts, expenses and the property offered as security. Meeting a regulatory threshold is only one part of the picture. It doesn’t guarantee that a lender will offer finance or accept the amount requested.

Two investors with similar LVRs may receive different decisions. Their income, existing commitments, property details and overall applications can differ, and lenders may apply different policies. A bank’s willingness to consider lending above the standard threshold can also depend on its available high-LVR lending allowance.

Why can investor LVR settings change?

The RBNZ reviews restrictions as conditions and risks change, and lenders can also adjust their own criteria. The 2025 settings provide a dated reference point, not a guarantee that rules will stay the same. Before basing plans on a particular threshold, check the RBNZ’s current official guidance and the relevant lender’s current policy. This is especially useful when comparing lending options or preparing to make a purchase.

Reserve Bank restrictions set the wider rules for bank lending, while each lender decides whether your application meets its own criteria. Keeping those decisions separate can make a decline easier to understand. It may reflect a lender’s assessment or current lending capacity, rather than a final judgement on your plans. Other lending channels may assess applications differently, but no pathway guarantees approval.

If you’re weighing up an investment purchase, Mortgage Suite can help you understand how the rules and your circumstances fit together. Discuss your investment property lending options with a personal advocate who can help compare mainstream and alternative lending pathways.

What else can affect an investment property loan beyond LVR?

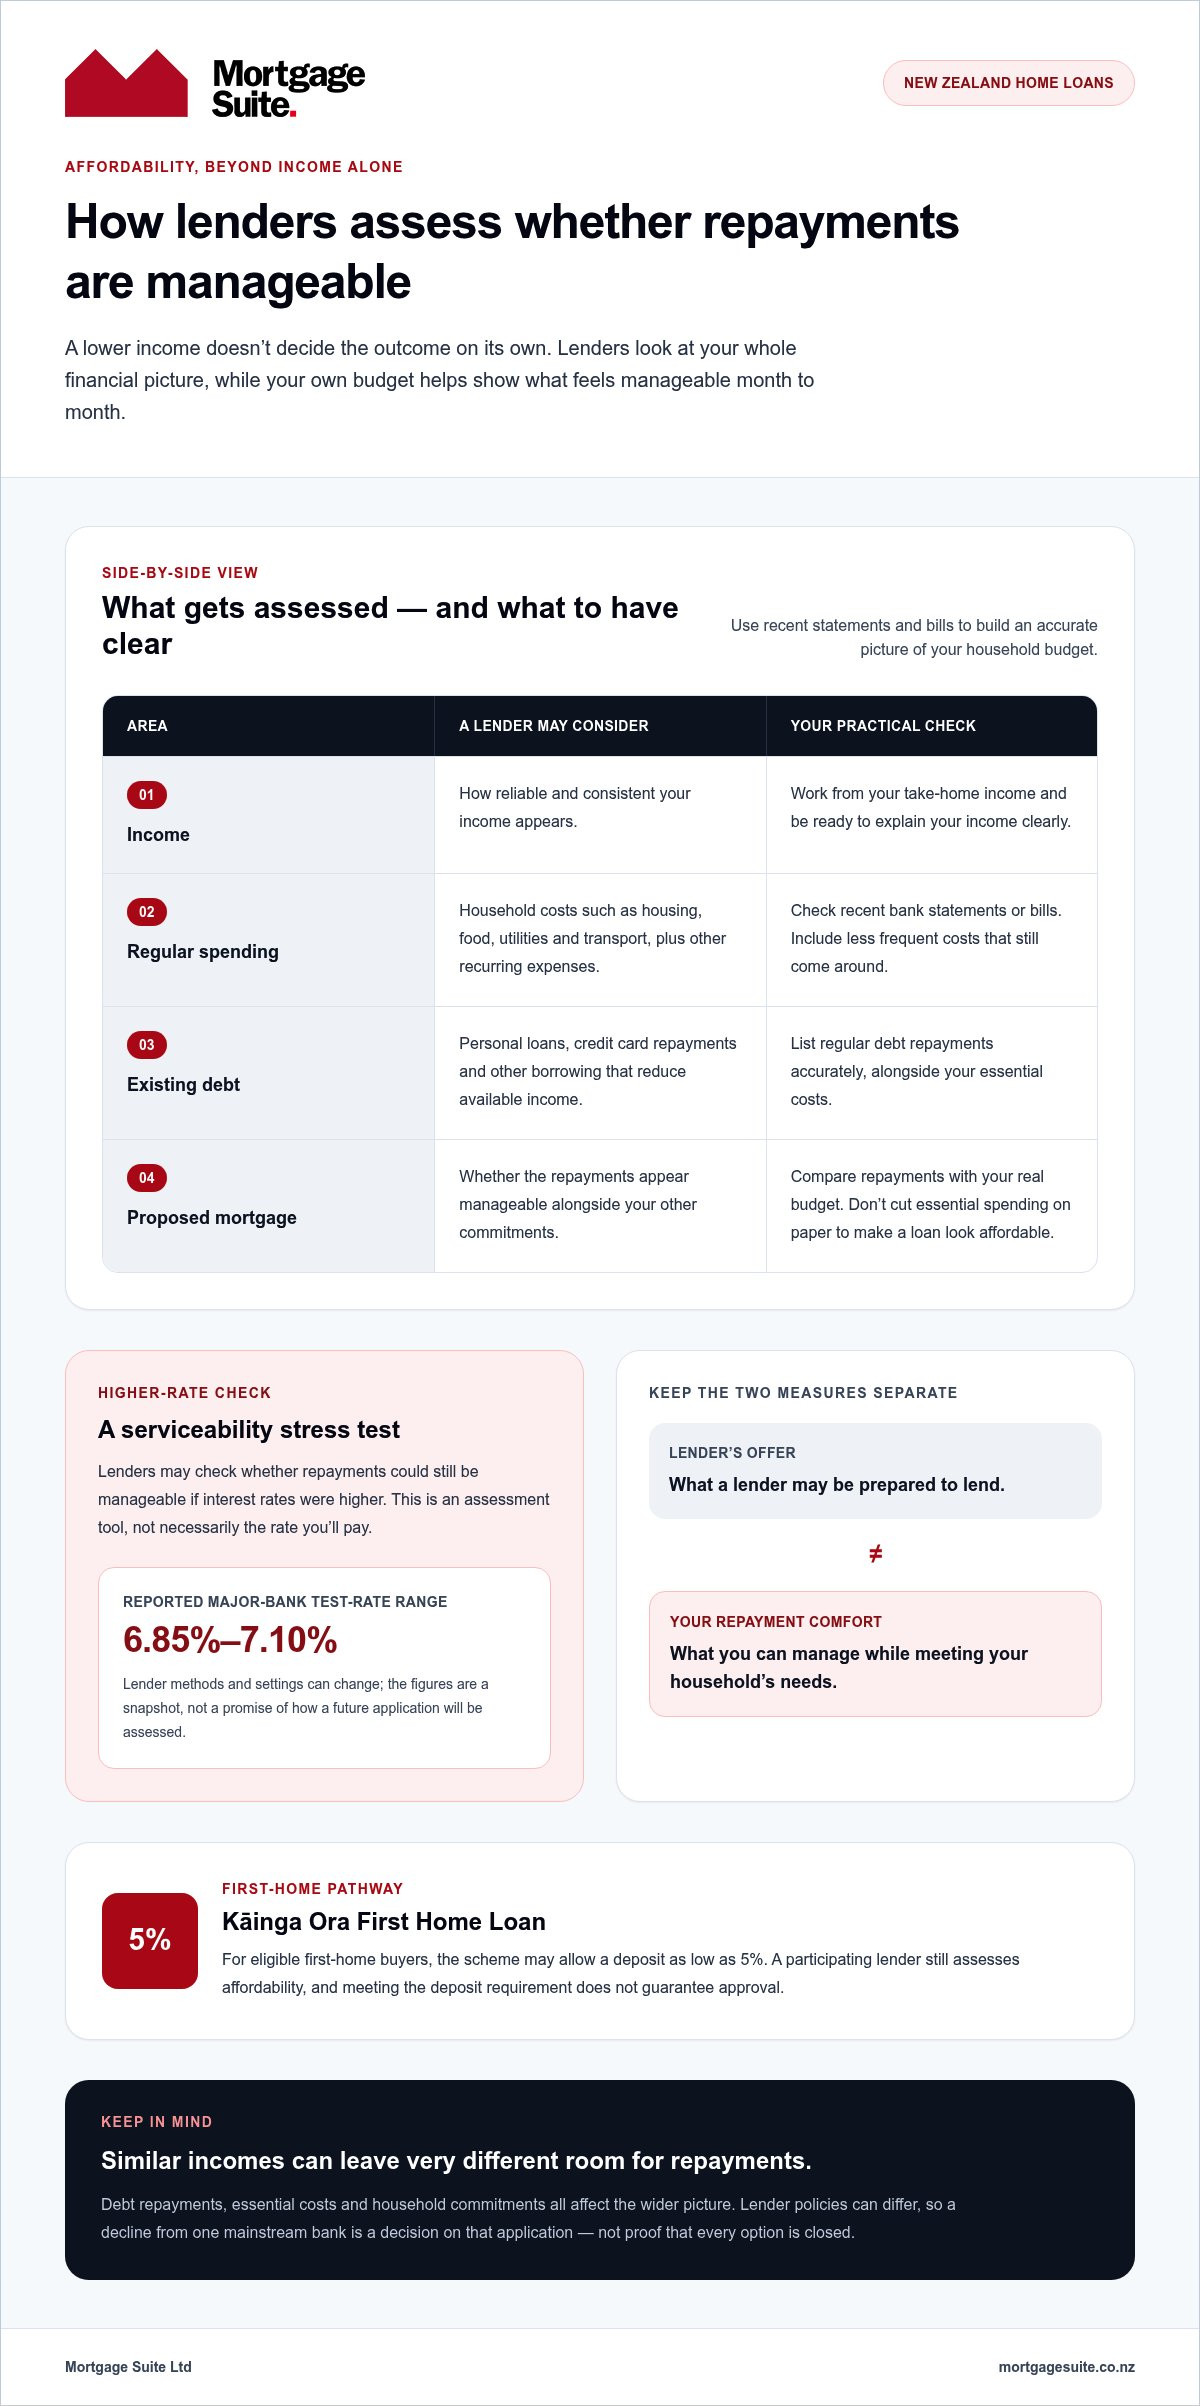
LVR shows how the proposed loan compares with the property’s accepted value, but it doesn’t show whether the repayments look manageable. A lender may also assess your income, regular expenses, existing debts and other borrowing. Together, these details provide a fuller picture of your finances and whether the proposed loan fits your circumstances.

For an investment property, expected rent and property details may also form part of the assessment. Rental income can be considered alongside other income, while the property is assessed as security for the loan. The lender’s view may differ from your expectations, so allow for uncertainty when planning rather than relying on a particular rent figure or valuation.

How does affordability fit alongside LVR?

Affordability is about whether repayments appear manageable after the lender considers the money coming in and the commitments going out. That can include your income, regular household and financial expenses, existing loans and credit commitments, as well as the proposed investment borrowing. A deposit that supports a particular LVR doesn’t, on its own, show that the repayments will suit your overall position.

A lender may also use a serviceability stress test, which checks whether repayments could remain manageable if calculated using a higher interest rate than the rate you may initially pay. It tests your ability to cope with changes. It isn’t a prediction of your future rate or repayment. The lender determines the rate and method, so a calculator estimate can’t reproduce the full assessment.

Use the mortgage calculator to explore possible repayments and see how different loan amounts or terms may affect them. Treat the result as a planning tool, not a lending decision or confirmation that a lender will offer the loan.

Why can the property and valuation change the picture?

The LVR calculation depends on the value the lender accepts, which may differ from the price you expect to pay or your own estimate of the property’s worth. If the accepted value is lower than expected, a proposed loan represents a larger share of that value, which can change the LVR. If you’re planning an offer, consider how a different valuation could affect the amount you need to borrow and your next steps.

The lender may also look at the property’s type, condition and likely saleability when deciding whether it is suitable security. The property supports the loan, so the lender assesses the asset as well as your ability to repay. The weight given to each detail can vary between lenders and applications.

That’s why the investment property loan to value ratio nz is only one part of the decision. Looking at your finances, expected rental information and the property together can help you prepare a more realistic borrowing plan. A particular valuation or repayment estimate doesn’t guarantee approval.

Investment Property Loan to Value Ratio NZ: A 2026 Guide

How can you prepare before applying for investment property finance?

Getting organised before you discuss a purchase can make the lending conversation clearer and help you spot unanswered questions early. Start with a simple plan, then gather details about your finances and the property. This gives you a more useful starting point than focusing on a single LVR figure or assuming every lender will take the same view.

  1. Outline your plan. Note what you hope to buy, why it suits your longer-term plans and when you expect to proceed. Separate confirmed details from estimates.
  2. Gather a financial snapshot. Record your available deposit or equity, income, existing loans and regular commitments.
  3. Clarify the property. Collect the details you have, such as the expected purchase price, property type, condition and realistic rental information.
  4. Discuss lending options. Use the information to talk through possible borrowing structures, lender requirements and what needs to happen before you make a firm commitment.

What information should an investor organise?

A concise summary is a practical first step. Include income sources, current borrowing, regular financial commitments and funds available for the purchase. For the property, note its key details and any rental estimate you’re using. Make clear which figures are confirmed and which are your best estimate. Keep sensitive financial documents secure and provide them through an appropriate process rather than sharing them in a public comment or post.

Before a conversation, it can help to understand the basic terms and write down what you want to know. That makes it easier to explain your plans and ask focused questions about your investment property loan to value ratio nz and the wider application.

What questions help clarify the lending pathway?

Use your discussion to understand how the lender may assess the property’s value and the borrowing you’re proposing. Ask what information could affect that assessment, how expected rent fits into the application, and what repayment structure may suit your plans. Consider how long you intend to hold the property and whether your plans could change. The lending structure needs to be considered alongside your wider goals.

Before making an offer, get clear on any finance conditions, key dates and what must be in place before those dates. A solicitor or other appropriate property professional can help you understand the conditions and timing in an offer. A mortgage broker can help present your application and negotiate with suitable lenders, including across mainstream and alternative lending channels. That support can help you understand your options, but it can’t guarantee a lender’s decision.

If you’re ready to talk through your plans, talk through your investment property finance options with Mortgage Suite and consider the next steps with a personal advocate.

How can Mortgage Suite help you assess investment property lending options?

It can be hard to know what to do next when the numbers, property details and lender requirements don’t seem to line up. Mortgage Suite can help you consider these pieces together: your goals, financial position, the property and its LVR. This wider view helps frame the questions to discuss and the possible lending paths to explore, without treating one percentage as the whole answer.

Mortgage Suite works across mainstream and alternative lending channels, supporting borrowers as a personal advocate and negotiator. Founder Krish Krishna brings more than two decades of banking experience to the business. That experience can help make a complex lending conversation easier to follow, while each lender still makes its own assessment and no particular outcome is guaranteed.

When might a tailored lending discussion be useful?

A tailored discussion may help if you’re unsure which lender’s criteria could suit your circumstances, or if your income, existing commitments or property plans make the application less straightforward. It can also help you understand how your investment property loan to value ratio nz fits with the rest of your position, rather than focusing on LVR alone.

If a mainstream bank has declined your application, that isn’t necessarily the end of the discussion. Different lending channels may assess an application in different ways, and an adviser can help you understand whether another path may be worth exploring. That doesn’t mean every application or property will qualify, so approach the conversation with realistic expectations.

What should you expect from the next conversation?

The discussion starts with what you’re aiming to do and the financial circumstances behind your plan. You can talk through the property, available deposit or equity, income, existing borrowing and any concerns about valuation or repayments. From there, Mortgage Suite can help explain how those details may fit different lenders’ requirements and what information could help present your application clearly.

Possible pathways depend on the lender’s assessment, the property and the requirements that apply at the time. A conversation can clarify likely next steps and points that need attention, but it isn’t an approval or a guarantee of finance. If your plans or circumstances are complex, explaining them early can keep the discussion focused on what matters to you.

You don’t need to have every answer before asking questions. For a calm, practical discussion about your circumstances and possible next steps, discuss your investment property loan options with Mortgage Suite.

Take your next step with a clear plan

A property purchase can move quickly, but taking time to understand your position before you commit can help you make decisions with greater confidence. Use your next step to turn the numbers you’ve gathered into a conversation about what matters to you: your plans for the property, the borrowing you’re considering and the questions still to be answered.

The investment property loan to value ratio nz is one part of that discussion, not a verdict on your plans. If your situation feels complicated, or a lender’s response has left you unsure where to turn, you don’t have to work through the options alone. Mortgage Suite was founded by Krish Krishna in 2000 and supports borrowers as they consider possible lending pathways. Any option depends on the lender’s assessment, so approval can’t be promised.

When you’re ready, talk with us about your investment property loan options. A calm, focused conversation with Mortgage Suite can help you identify practical next steps and move forward with a clearer sense of direction.

Frequently Asked Questions

Can I use equity in another property towards an investment property loan?

Yes, equity may contribute to the funds available, but it isn’t the same as cash already approved for your deposit. For example, owning a property with substantial equity doesn’t automatically mean a lender will let you borrow against it for another purchase. The lender will assess the property offered as security, any lending already attached to it and your wider finances. Get an assessment before relying on equity in your purchase plan.

Does a bank valuation always match the investment property’s purchase price?

No, the lender’s accepted value may differ from the agreed purchase price or an online estimate. If you agree to buy at one value but the lender uses a lower figure, the borrowing being considered may need to be reviewed. Ask which valuation or report the lender will use and how it affects your application. Don’t assume the sale price alone sets the value used for the LVR calculation.

Can I get an investment property loan with a small deposit?

It may be possible, but a smaller deposit can mean a higher LVR, and that’s only one part of the decision. For investment property loan to value ratio nz planning, consider current Loan-to-Value restrictions alongside lender policy, your finances and the property details. Rules can change, so avoid basing an offer on old information. A mortgage adviser can help you understand what a lender may need to assess your situation.

Do all lenders use the same investment property LVR rules?

No. Reserve Bank restrictions can affect banks, while lenders also set their own criteria and assess applications individually. One lender’s response doesn’t necessarily predict another’s. If you’re comparing options, look beyond the headline LVR and consider the proposed repayments, loan structure and conditions too. Mortgage Suite can help you compare mainstream and alternative lending pathways, though each lender makes its own decision and may apply different requirements.

Can a high rental income make up for a high LVR?

Rental income may support an application, but it doesn’t automatically offset a high LVR or secure approval. A lender may assess it alongside your other income, existing debt, regular expenses and the property’s value. For example, a rent estimate based on current listings may not be treated the same as confirmed rental information. Use realistic figures and make clear which details are estimates so the lender can consider the full picture.

Is LVR the same as a deposit percentage?

No. LVR compares the loan with the property value, while a deposit is your contribution towards the purchase. In a simple example, those percentages may appear to add up to the full property value, but a real transaction can include other funds, existing lending and a lender valuation that differs from the purchase price. Treat the maths as a guide to the relationship between borrowing and value, not as a decision on finance.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Present a Business Loan Application in New Zealand

A lender’s decision depends on more than whether your finances look perfect. If you’re unsure how to present a business loan application, you’re not alone. Gathering financial records, explaining what you need the funds for and showing how you’ll manage repayments can feel like a lot, especially if income has changed, the business already has debt or an earlier application was declined.

A clear application gives the lender a consistent picture of your business: what you need, how you’ll use the funds and how repayments may fit your cash flow. This guide covers the information and supporting documents that can help a lender assess your request, along with ways to explain your plans in plain English. You’ll also learn how to describe unusual circumstances honestly without letting them define your whole application.

The right funding route depends on your business needs, the evidence you can provide and the lender’s assessment. Mortgage Suite supports business finance applications by helping shape and negotiate the request. Founder Krish Krishna brings more than two decades of banking experience and a practical understanding of how lenders review funding proposals.

Key Takeaways

  • Present your funding need, business position and repayment plan as one clear account.
  • Prepare financial records that support your case, keeping in mind that document requests vary between lenders and applications.
  • Compare funding routes by how you’ll use the money, make repayments and access funds, including how a term loan works.
  • Check your figures, update your records and explain unusual circumstances clearly before applying.
  • Mortgage Suite can help shape and negotiate your funding request, but no particular lending decision is guaranteed.

Why a well-presented business loan application matters

Applying for business finance can feel demanding, especially if sales have shifted, costs have risen or cash flow looks different from last year. You may be keeping day-to-day work moving while also gathering records and explaining a decision that feels obvious to you. A well-presented application brings those details together, helping a lender understand what the business needs and how the proposed repayments may fit.

Good presentation isn’t about dressing up the numbers or hiding a difficult period. It means giving a consistent, straightforward account of the business, the funding request and the repayment plan. This can help a lender assess your request, but it can’t guarantee approval. Each lender makes its own assessment, and the right finance route depends on your business and its circumstances.

What does a business loan application need to communicate?

Start by stating the amount you’re seeking and what it will pay for. Keep separate needs distinct rather than grouping unrelated expenses under a broad label such as “business growth”. Briefly describe how the business operates, where its income comes from and how it manages existing commitments.

Then connect those details to your repayment plan. Explain how the business expects to meet repayments from its cash flow and what assumptions that expectation relies on. If income varies with seasonal demand, for example, describe when quieter periods occur and how you plan to manage repayments then. This gives the lender useful context instead of leaving them to guess how the figures fit together.

Why clarity and consistency matter

Figures that agree across your application and supporting records are easier to follow. If your written request describes one use for the funds but your forecast suggests another, the lender may need clarification. That doesn’t automatically determine the outcome, but it can make the assessment less direct and create extra work for you.

Check the key details across your documents: the amount requested, intended use, income figures, existing repayments and cash-flow assumptions. If figures differ because records cover different periods or use different categories, explain why rather than leaving the lender to reconcile them.

For instance, if you’re seeking funding to buy stock, say so clearly and show how the stock supports expected sales. Don’t describe the same request as equipment funding in one part of the application and working capital in another. A lender needs to see a clear connection between the funds and the business purpose. For general background on types of business loans and assessment criteria, you can also review an overview of how business loans may be structured and assessed.

In practice, how to present a business loan application comes down to making your case easy to understand and checking that each part supports the same account. Clear explanations won’t remove every concern, but they help a lender assess your request with a better understanding of the business.

Build a clear business loan case with evidence

A lender needs more than a stack of records. They need to understand how the business operates, why it needs funding and how the request connects to a realistic repayment plan. Arrange your explanation and evidence so each supports the same account. Document requests vary between lenders and applications, so use the examples below as a starting point and follow the requirements for your application.

Explain the business and the reason for borrowing

Give a short picture of your business: what it sells, how it earns income, how long it has been trading and what affects sales. Then describe the funding purpose in practical terms. For example, explain whether the request is for stock to meet expected orders, equipment to support operations, or a property or development plan. Keep different needs separate, as they may call for different funding structures and supporting evidence.

Be specific about how the funds relate to the business need. If you’re seeking finance for equipment, explain what it will allow the business to do and how that supports income or day-to-day operations. Avoid broad claims such as “this will grow the business” unless you can explain the steps behind them.

Prepare records that support the request

Depending on the application, useful evidence may include financial statements, recent management accounts, business bank statements and cash-flow forecasts. These records can help show both past performance and what you expect ahead. Check that the periods covered are clear and that the figures in your written explanation appear in the relevant records.

List current debts and other regular commitments accurately. If a balance or repayment has changed, explain what changed and when. Do the same for unusual figures: a one-off expense, delayed customer payment or seasonal drop in sales may need a brief explanation and relevant supporting evidence. Don’t leave a lender to guess, but avoid over-explaining ordinary fluctuations. Focus on the details that make the business’s position clearer.

Mortgage Suite’s business finance support can help you organise information around your funding request and shape the case you present.

Make the repayment plan understandable

Explain where repayments are expected to come from, such as regular trading income or revenue linked to the planned purchase. Set out the assumptions behind your forecast, including expected sales, costs and timing. If income changes with the season or depends on work being completed, show how that timing affects the cash available for repayments.

Think through a quieter period or delayed income. Explain how the business could manage that change, and make sure the plan accounts for existing commitments as well as the new borrowing. Forecasts are estimates, not guaranteed results, so label assumptions clearly and keep them realistic. Evidence and a measured explanation help support the request without overstating what the business can achieve.

Compare funding routes and address concerns before applying

The right finance structure depends on what the business needs, when it needs the funds and how it expects to repay them. A facility that suits regular operating expenses may not suit a property purchase or development project. Compare the purpose, repayment pattern, security and access to funds before framing your request. The options below are broad categories, and a lender’s assessment determines what may be available for a particular application.

Match the funding structure to the business need

Funding route How it works May suit
Term loan A loan provided as a lump sum with a defined repayment schedule and end date. A planned purchase or one-off business expense where the amount and purpose are known.
Revolving facility Access to funds up to an agreed limit, with repayments and access working according to the facility’s terms. Changing short-term cash-flow needs where the business may need to draw funds at different times.
Property-related finance Funding assessed in relation to a commercial property purchase or development plan. A property or development project, rather than general day-to-day business needs.

Security, timing and cash flow can all affect which route may fit. A business buying a commercial property has a different funding purpose from one managing uneven trading income. Property or development finance is shaped around the project and its supporting information, while general business funding relates to other operating needs. Set out the intended use clearly so the request can be considered in context.

What if the business has been declined or has a complex profile?

A decline from a mainstream bank can be discouraging, but it’s a decision on that application, not a judgement of your worth or the value of your business. Before applying again, review any reasons the lender gave. Was the concern about cash flow, existing commitments, proposed security or information that needed more explanation? Address the specific issue rather than sending the same request unchanged.

If income varies, trading history is unusual or a past event affected the figures, explain the circumstances plainly and support them with relevant records. A different lender or finance route may suit some applications, including options outside mainstream banks, but each lender makes its own assessment and approval can’t be assured. Changing the structure or strengthening the evidence may help present your request more clearly, though it won’t remove every concern.

Knowing how to present a business loan application also means choosing a funding route that fits your business, rather than focusing on a headline rate alone. Mortgage Suite can help shape and negotiate a business finance request around its purpose and supporting case. For a personal discussion of your funding needs, talk with Mortgage Suite about business finance.

How to Present a Business Loan Application in New Zealand

Prepare and present your application in practical steps

Once you’ve settled on the funding need, turn your notes and records into a pack that’s easy to review. Organisation can make the process feel more manageable and help you spot gaps before you submit. Use this sequence as a guide, adapting it to the lender’s document requests and your business circumstances.

A step-by-step application preparation process

  1. Set out the request. Write down the amount you’re seeking, what the funds will be used for and when you expect to need them. Be specific: describe the planned purchase or business need rather than relying on a broad phrase such as “business growth”.
  2. Gather relevant records. Collect the business information and financial documents that support the request. Check that figures agree across records, and note the period each document covers. Keep files in clearly named folders so you can find the right evidence without searching through a jumble of attachments.
  3. Draft a short business summary and repayment explanation. Describe how the business earns income and what the funding will help it do. Then explain the expected source of repayments, the assumptions behind your forecast and how you’ve allowed for existing commitments or changes in income.
  4. Review the application pack. Read the written explanation alongside the supporting records. Check that dates, figures and the stated use of funds match. Add a brief explanation where a lender might otherwise be left wondering about a gap or unusual change.

Keep a copy of what you submit and note which records you included. If the lender asks a follow-up question, respond clearly and provide the relevant information. An organised reply can help keep the discussion focused, although the lender may still need to make further enquiries while assessing the application.

Common presentation mistakes to avoid

Before sending your application, watch for these avoidable issues:

  • Unexplained differences. If a forecast doesn’t match recent bank activity or a written claim, explain the reason and point to the information that supports it.
  • A vague funding purpose. “Business growth” doesn’t tell a lender what you plan to do. Name the intended use and connect it to the business need.
  • Missing commitments. Include existing debts and regular obligations accurately. Leaving them out can create a different picture from the one shown in your records.
  • Overconfident forecasts. Present expected income as an estimate, not a sure thing. Make the assumptions clear, especially if sales or payment timing can change.

Knowing how to present a business loan application means making it straightforward for someone unfamiliar with your business to follow the request and its supporting information. If you’d like help organising and presenting your funding case, discuss your business funding needs with Mortgage Suite.

How Mortgage Suite can help with a business loan application

Putting together a business finance request can take time, especially if your income has changed, your funding need is unusual or a lender has already declined an application. You don’t have to work through every detail alone. An adviser can help organise the request, consider finance routes that may fit and make sure the supporting information explains the business case clearly.

What support can an adviser provide?

Start with the purpose. An adviser can help you describe what the funds are for, what the business needs to achieve and what information best supports that explanation. They can also help make sense of your circumstances, such as changing income, existing commitments or a previous lender decision, so relevant context isn’t lost in a bundle of documents.

From there, an adviser can discuss funding routes that may suit the request and help present it to a lender. Mortgage Suite acts as a personal advocate and negotiator, working to shape the application around your business needs and supporting evidence. Founder Krish Krishna brings more than two decades of banking experience.

That support can help organise and discuss a request, but it can’t determine the outcome. Lenders make their own assessments and may ask for more information. A well-prepared application can make the business’s position easier to understand, but no adviser can promise approval or remove every lending concern.

Take the next step with a clear funding brief

You don’t need a polished presentation to start a useful conversation. A short brief can explain what the business does, what funding you’re seeking, how you plan to use it and where repayments are expected to come from. Include known changes to trading or cash flow, along with relevant lender feedback if you’ve already applied.

Being upfront about a decline or a complex circumstance gives an adviser a clearer picture of the request. It also helps identify which parts of the case may need more explanation or supporting information before it goes to a lender. If you’re still gathering records, the next step is to work out what information is relevant and how to present it consistently.

If you’re ready to talk through your business finance needs, start a conversation with Mortgage Suite. Explain what the business needs and where you’d like help. Together, you can consider how to present a business loan application that gives a lender a clear view of the request, without assuming what the decision will be.

Take your next funding step with a clear plan

A funding request can help you look ahead as well as meet an immediate need. Before you submit, consider what you want the business to do next and whether the proposed repayments leave room for everyday commitments if trading changes. That forward view can help you discuss the request in practical terms and keep your longer-term business goals in mind.

Understanding how to present a business loan application is a strong starting point, but you don’t have to shape the case on your own. Mortgage Suite can help organise and negotiate a request that reflects your business’s needs and circumstances. Lenders make their own decisions, so there’s no promise of a particular result. The aim is to help you approach the conversation prepared and clear about what you’re asking for.

Have a funding need in mind, even if some details are still taking shape? Talk with Mortgage Suite about your business finance needs and take the next step at a pace that feels right for your business.

Frequently Asked Questions

How much should I ask for in a business loan application?

Ask for an amount you can explain and support with a clear breakdown of its intended use. For example, list the equipment, stock or project expenses the funding would cover, using relevant quotes or forecasts where available. Include a cash-flow estimate showing when the funds are needed. This makes it easier to present your request clearly and avoid asking for more than the business case supports.

Can a new business apply for a business loan without a long trading history?

Yes, a new business can apply, although a short trading history may leave less past performance for a lender to review. You may need to explain the business model, your experience in the industry, expected customers and how you arrived at your income forecasts. Evidence such as confirmed work or customer interest may help give context, but the lender decides what it needs and whether the request suits its lending approach.

Do I need a business plan to apply for a business loan?

A formal business plan isn’t always required, but a clear written outline can help explain what the business does and why it needs finance. Keep it practical: describe your customers, how the business earns income, what you’ll use the funds for and how you expect to make repayments. For a new venture, explain the assumptions behind projected sales and costs so they aren’t presented as established results.

Can I apply for a business loan if my business already has debt?

Yes, existing debt doesn’t automatically prevent you from applying. Be ready to outline current balances, regular repayments and any changes, such as a facility that has recently been reduced or repaid. A lender may consider how the new repayments sit alongside those commitments and the business’s available cash flow. If you’re seeking extra funding to manage debt pressure, explain the underlying cause as well as the immediate need.

Will a business loan application affect my personal credit file?

It may, depending on the lender, the type of credit check and whether the application involves a personal guarantee. A lender may review an owner’s personal credit information as part of its assessment, but checks aren’t all handled in the same way. Before authorising a check, ask how it will be carried out and whether an enquiry may appear on your file. Be open about any past credit issues and relevant context.

What happens after I submit a business loan application?

After submission, the lender reviews the information and may ask questions or request further documents to clarify parts of the application. For example, it may need an updated cash-flow forecast or more detail about a particular transaction. Keep your records accessible and respond accurately. The lender then communicates its decision and any proposed terms, if applicable. Processes and timing vary, so avoid making business plans that depend on an assumed decision date.

Can a business loan be secured against commercial property?

Yes, some business borrowing may be secured against commercial property, but this depends on the lender, the property and the wider application. The lender may consider the property’s value and the existing lending attached to it, alongside the business’s ability to repay. Offering property as security can put it at risk if repayments aren’t met, so understand the proposed terms and obligations before agreeing to use it as security.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Get a 2nd Tier Loan in NZ: A Step-by-Step Guide for 2026

A bank’s “no” doesn’t have to end your property plans. If you’re wondering how to get a 2nd tier loan, start by finding out why your application didn’t fit a mainstream lender’s criteria and what a specialist lender may assess differently. A decline can feel personal, but it isn’t a final judgement on you or your plans.

It’s also fair to be cautious about higher interest rates. A 2nd tier loan may cost more, so it should have a clear purpose and a realistic plan for what comes next. This guide covers how to prepare your finances, choose a suitable lending pathway, present your application and work towards a future application to a main bank if your circumstances allow.

Mortgage Suite specialises in loans for borrowers who don’t fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience and helps borrowers understand their options and present their case clearly. You’ll get practical guidance without treating a bank rejection as the end of the road.

Key Takeaways

  • Learn how to get a 2nd tier loan by preparing a clear application that explains your finances and the context behind them.
  • Match your borrowing challenge, such as a small deposit or credit history, with a lender whose approach may suit your circumstances.
  • Review the loan terms and any fees before deciding whether the offer fits your plans.
  • Set a realistic goal for applying to a main bank in the future, and understand what may need to change first.
  • Use a 12-to-24-month review point to check your progress and adjust your next steps if needed.

What is a 2nd Tier Loan and Why Consider One?

A decline from a main bank can be frustrating, especially when your plans make sense to you. It may reflect how that bank assesses applications, not a final judgement on your ability to borrow. A 2nd tier loan is an alternative for people whose financial situation or property doesn’t fit a mainstream lender’s usual criteria.

These loans are offered by lenders outside the major banks, including specialist non-bank financial institutions. The Non-bank financial institution overview explains the broader category. In practice, a specialist lender may look more closely at the circumstances behind your application, rather than relying only on standard measures.

The Difference Between Main Banks and Alternative Lenders

Main banks often assess applications against set criteria. That can be difficult if your income is irregular, your deposit is smaller than expected or your credit history has a few bumps. Alternative lenders may consider the wider picture, including how you earn your income, the reason for a past issue and whether repayments look manageable now. Flexibility isn’t automatic, though. Each lender has its own rules and will still assess your ability to repay.

Some alternative lenders may be set up to assess individual cases in a different way. The timing depends on the lender and how complete your information is, so don’t assume a quick decision is guaranteed. Interest rates and loan terms can also differ from a main bank’s offer. Look beyond the approval and consider whether the repayments and conditions fit your plans.

Dispelling the Myths About Non-Bank Lending

Non-bank doesn’t mean unregulated or informal. Lenders providing consumer credit in New Zealand must meet responsible lending requirements under the Credit Contracts and Consumer Finance Act. From 1 July 2026, conduct oversight for the Act transferred to the Financial Markets Authority. A lender still needs to assess whether the loan is suitable and affordable for you.

A specialist loan isn’t automatically a last resort. Kiwis may consider one when self-employment makes income harder to show in a standard format, when they have a smaller deposit or when a past credit issue needs explaining. A different lender’s approach may offer a route to a property purchase if the application works for both borrower and lender.

Think of it as a possible step in a longer plan, not a shortcut around affordability. Before deciding how to get a 2nd tier loan, be clear about what makes your application unusual and what you can comfortably repay. Mortgage Suite specialises in lending for situations that fall outside mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience and can help present your circumstances clearly and negotiate on your behalf.

How to Prepare Your 2nd Tier Loan Application

A clear application does more than gather figures. It helps the lender understand how you earn, what has changed and why the loan may be manageable now. Be upfront about your financial history. If there are gaps or late payments, explain them rather than leaving the lender to draw its own conclusions. Clear, consistent information makes it easier to assess your circumstances.

Your explanation can add context to your bank statements. The figures show what’s happened; your account helps make sense of them. Keep it factual and focused, and make sure your documents support what you say.

The Essential Paperwork You Will Need

Before applying, organise records that show your income, spending and commitments. The documents you need will depend on how you earn and what you plan to borrow for, but a tidy file helps the lender follow your application.

  • If you’re self-employed: Gather relevant business and personal financial records, such as financial statements, tax summaries and business account records. These can show how your business earns and pays you when a standard payslip doesn’t tell the whole story.
  • If your credit history has a blip: Prepare a short explanation of what happened, when it happened and what has changed since. Include supporting information if you have it.
  • For the property: Collect key details about the home you want to buy, or the property and existing loan if you’re refinancing. This gives the lender context for the purpose of the borrowing.

Check that dates and figures agree across your records. If your income varies, explain the pattern instead of relying on one unusually strong month. Label files clearly and keep them together so it’s easy to see how the information fits.

Telling Your Story to the Lender

If a one-off event affected your finances, explain what happened without making excuses. For example, if time away from work led to missed payments, describe the circumstances and what has changed since. Keep your account brief, honest and consistent with your records.

Then show how you plan to manage your finances from here. A clear outline of your income, regular outgoings and realistic steps for keeping spending on track can help explain how repayments fit your situation. Avoid promising changes you won’t be able to maintain.

A broker can help turn a complex financial picture into a clear application and explain your circumstances to a lender. Mortgage Suite works with borrowers whose situations don’t fit mainstream bank criteria. The team focuses on understanding your goals and presenting your case with care.

The Reserve Bank of New Zealand’s oversight of non-bank deposit takers explains its role for institutions in that category. Not every specialist lender is necessarily a deposit taker, so the information doesn’t describe every lender’s status.

Choosing the Right Lender for Your Situation

There isn’t one second-tier lender that suits every borrower. Some are more familiar with assessing self-employed income, while others may consider applications involving a smaller deposit or a past credit issue. The aim is to match your main hurdle with a lender whose criteria fit your circumstances, not to send the same application everywhere.

Start by identifying what made a mainstream bank hesitate. Is your income difficult to show through payslips, is your deposit limited, or does your credit history need context? Each situation calls for a different conversation with a lender. A specialist broker can compare potential pathways, explain how lenders may view your application and negotiate on your behalf, without promising approval.

Lenders for the Self-Employed

Some lenders are more used to assessing income that doesn’t arrive as a regular salary. They may look at business records and other evidence to understand whether your earnings can support repayments. “Low-doc” generally refers to an application that uses a different or smaller set of traditional income documents, not a loan with no checks. You’ll still need to show how you earn and demonstrate that repayments are affordable.

For example, a contractor with changing monthly income may need to explain the pattern across their records rather than rely on a single payslip. The right lender depends on the details of your work, income and existing commitments.

Lenders for Credit Issues or Small Deposits

If your deposit is smaller than a bank wants, a specialist lender may assess the whole application differently. That doesn’t mean every lender will accept a lower deposit, or that the deposit is the only factor. Your income, commitments and the property matter too. If a past financial setback affected your credit history, some lenders may consider an explanation and evidence that your situation has since changed.

You may also hear the term “risk grade”. Lenders can use their own methods to assess the risk of an application. A higher perceived risk may affect the offer’s conditions or terms, so ask for a plain-English explanation of what the assessment means for your loan. There isn’t one scale shared by every lender.

Choosing between these options can be hard when each lender has different rules. Mortgage Suite helps match your situation to a suitable lending pathway and present your case clearly. You can learn about the people and experience behind that support on the Mortgage Suite About Us page.

How to Get a 2nd Tier Loan in NZ: A Step-by-Step Guide for 2026

Understanding the Costs: Rates, Fees, and Terms

A second-tier loan may help you move ahead with a property purchase when a main bank can’t offer a suitable option. But look beyond the approval and understand how the interest rate, repayments and loan conditions fit your plans. Specialist lenders may offer more flexibility for some applications, and their interest rates are often higher than those of main banks. The rate and terms will depend on the lender and your circumstances.

Don’t decide based on the rate alone. Think about how long you expect to keep the loan, what repayments you can manage and what you’ll do if your plans change. Buying sooner isn’t automatically the right choice, and property values can rise or fall. Your loan should remain manageable even if your circumstances don’t improve as quickly as you hope.

Interest Rates and Your Plans

Consider how repayments would fit your budget over time, not just at the start. A calculator can help you compare repayment scenarios at different interest rates. Use the Mortgage Suite mortgage calculator to see how a rate change may affect repayments. Then consider whether those repayments leave enough room for your other regular commitments.

There’s no standard period for staying with a second-tier lender. Some borrowers use this kind of loan as a temporary step while they work towards meeting a main bank’s criteria. You could review your position over a 12-to-24-month period, but treat that as a planning guide, not a promise that you’ll be ready to switch. Your financial position and a future lender’s assessment will determine what’s possible.

Terms to Check Before You Commit

Read the loan offer carefully and make sure you understand how it works. Check the repayment schedule, how the interest rate is set and whether the loan has conditions that could affect your plans. If you may want to change lenders or repay sooner, review the relevant terms before signing so you know what steps may apply.

  • Understand the repayments: Check when payments are due and whether the amount could change during the loan term.
  • Review the conditions: Make sure you understand any requirements attached to the loan and what you need to do to meet them.
  • Think ahead: Consider how the loan would fit if your income, property plans or timing changed.

Choosing a loan is about more than securing approval. Take time to understand the offer and whether it supports your next step. Mortgage Suite can help you compare lending options and negotiate with the lender on your behalf. Use the calculator to test different repayment scenarios before deciding what feels manageable.

The Exit Strategy: Moving Back to a Main Bank

A 2nd tier loan is often best treated as a stepping stone, not a permanent arrangement. Before taking one out, think about what would need to change for a main bank to consider your application later. A 12-to-24-month goal can give you a useful review point, but it isn’t a promise that you’ll be ready to switch by then. Your income, repayment history, credit record, equity and the bank’s criteria will all matter.

Make a plan you can act on from the start. Keep track of what held up your original application and set practical steps to address it. If the hurdle was showing self-employed income, for example, keep your financial records organised over time. If it was limited equity, review your loan balance and property value during regular check-ins.

Cleaning Up Your Financial Profile

Build a steady record of making your loan repayments on time. A consistent repayment history can help show a future lender that you’re managing your commitments. Keep other debts under control too. Paying down a car loan or credit card balance may reduce your regular outgoings, which can help when a bank reviews whether you can afford the mortgage.

Your equity may change as you repay the loan or if the property’s value rises. More equity can help with a future application, but property values can also fall, and a lender will assess the property and your finances at the time. A main bank will also consider your income, credit history and ability to manage repayments.

Working with Your Broker on the Move

Raise the possibility of switching lenders early, rather than waiting until you think you’re ready. Your broker can help you review whether the original hurdle has improved, what evidence you may need and whether it makes sense to prepare a new application. If a past credit issue contributed to the decline, be ready to show how your circumstances have changed since.

Moving lenders means applying again, and approval isn’t automatic. A main bank will assess your current position at that time, rather than relying only on the fact that another lender approved you previously. Your broker can help prepare and present the updated application, and talk through the options if you’re not yet ready to move.

Keep your longer-term goal in view, whether that’s improving your financial position, building equity or refinancing. Mortgage Suite can support you as your circumstances change and help you consider the next step when the time is right. A well-planned move back to a main bank takes preparation, but you can work towards it one practical step at a time.

Take the Next Step with a Clear Plan

A bank decline can leave you unsure where to turn, but it doesn’t have to define what happens next. Use what you’ve learned about how to get a 2nd tier loan to start a thoughtful conversation about your options, what a lender would need to see and how borrowing could fit your longer-term plans.

Every borrower’s situation is different, so the right next step depends on your goals and financial circumstances. Mortgage Suite can help you explore a suitable lending pathway and put your case forward. You can also read our client reviews to hear about other Kiwis’ experiences.

Book a chat with Mortgage Suite to find your path forward. You don’t need to have every answer before you begin. A clear conversation can help you work out what to do next, one step at a time.

Frequently Asked Questions

Is it harder to get a 2nd tier loan than a bank loan?

Not necessarily, but the assessment may work differently. A specialist lender may be more open to considering an application that falls outside a main bank’s usual criteria, while still checking whether the loan is affordable and suitable. For example, a lender may look closely at how a recent change in work affects your income. Approval isn’t guaranteed, and each lender sets its own requirements.

How much deposit do I need for a 2nd tier lender in NZ?

There isn’t one deposit amount that applies to every 2nd tier loan. The amount a lender may require can depend on the property, your finances and how the lender assesses the overall application. A smaller deposit doesn’t automatically rule you out, but it may affect the options available. Before making an offer, check that your expected deposit and other funds fit the proposed lending terms.

Can I get a 2nd tier loan if I have bad credit?

Possibly. A credit issue doesn’t automatically mean every lender will decline your application, but the details matter. A lender may consider what caused the issue, whether it’s resolved and how you’ve managed your commitments since. For example, a paid account in dispute may be viewed differently from ongoing missed payments. Be open about your credit history and provide a clear explanation rather than leaving the lender to guess.

What are the interest rates like for non-bank lenders?

Non-bank loan rates are generally higher than main bank rates, but the difference depends on the lender and your application. The rate is only one part of the offer: repayment terms, fees and conditions can also affect whether it suits your plans. Compare written offers on the same basis, and check what happens to repayments if the rate changes. Avoid relying on claims about a typical rate without a specific offer to review.

How long does the 2nd tier loan process take?

There’s no guaranteed turnaround time. The process can depend on how quickly you provide the requested information, how complex your income is and whether the lender needs a property valuation or further checks. You can help avoid preventable delays by sending complete, consistent documents and responding promptly to questions. If you’re working towards a purchase date, allow time for assessment and legal steps rather than assuming approval will arrive immediately.

Do I need a mortgage broker to get a 2nd tier loan?

You don’t necessarily need a broker, but a specialist can help you understand which lenders may suit your circumstances and present your application clearly. If you’re weighing up how to get a 2nd tier loan after a bank decline, a broker can also help explain the lender’s questions and talk through the offer with you. Mortgage Suite supports borrowers whose applications don’t fit mainstream bank criteria, but no broker can promise approval.

Can I use a 2nd tier loan to buy an investment property?

A 2nd tier loan may be an option for a residential investment property if the lender’s criteria fit your circumstances and the property. The lender will assess your finances, existing commitments and the property as part of the application. Mortgage Suite helps borrowers explore residential investment property lending as well as other specialist loan options.

What happens if I want to pay off my 2nd tier loan early?

Check your loan agreement before making an early repayment, as the terms may set out notice requirements or charges. The details can differ between loans and may depend on whether you’re paying off the full balance or making an extra repayment. If you’re planning to refinance, ask for a current payout figure and factor in any applicable charges and legal steps before setting a completion date.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Get a Mortgage on a Low Income in NZ in 2026

What if a lower income doesn’t automatically rule out a home loan? Working out how to get a mortgage with low income nz can feel daunting, especially if you’re worried that regular bills, existing debt or a small deposit will affect your application.

Lenders look at your full financial picture: your income, regular spending, debts and whether repayments appear affordable if interest rates rise. Their lending policies can differ, so a decline from one mainstream bank doesn’t necessarily mean you’re out of options. For eligible first-home buyers, the Kāinga Ora First Home Loan may allow a deposit as low as 5%, but meeting the deposit requirement doesn’t guarantee approval.

This guide explains how lenders assess affordability, which financial records to prepare and what pathways may be worth exploring. You’ll also learn how a mortgage adviser can organise your application and negotiate with lenders, including discussing alternative options where suitable. The aim is to help you understand your next steps and get sorted with a clearer picture, without assuming any lender will approve your application.

Key Takeaways

  • See how to get a mortgage with low income nz by looking at your full financial picture, not income alone.
  • Map your regular income, essential spending and debt to see what room your household budget may have for repayments.
  • Prepare clear, consistent financial records to help lenders assess your application.
  • Compare lending pathways by affordability, repayment structure and flexibility, and consider how each fits your longer-term plans.
  • A mortgage adviser can help organise your application and negotiate with lenders, but no pathway guarantees approval.

Can you get a mortgage on a low income in NZ? Start with affordability

Borrowing can feel stressful when income is tight. You might be wondering whether there’s room for a mortgage after rent, food, transport and other regular bills. A lower income can affect how much you may be able to borrow, but it doesn’t decide the outcome on its own.

Affordability is about whether the proposed repayments appear manageable alongside your household’s other commitments. A lender considers the overall picture, including how reliable your income is, what you spend, any existing debt and the repayments for the home loan you’re seeking. The aim is to assess your application as a whole, rather than judge you by one number.

A rough income rule can offer a starting point, but only an individual lender assessment can consider how your income, spending and commitments fit together. That’s why an online estimate or a simple percentage of income shouldn’t be treated as a borrowing limit or a sign of approval.

What does a lender look at beyond your income?

Income matters, but so does the amount left after regular household costs and debt repayments. A lender may consider whether your income is consistent, what you pay towards existing borrowing, and how a proposed mortgage repayment would sit alongside essentials such as food, utilities and transport.

Two people with similar incomes can have very different budgets. One might have few debts and modest regular commitments; the other might have personal loan repayments or be supporting dependants. Those differences can affect how much room each household appears to have for a mortgage. Be ready to explain your regular costs accurately, rather than relying on a calculator result or a general rule.

Why a lower income does not tell the whole story

Lenders assess the proposed loan against your wider repayment picture, and their policies can differ. That doesn’t mean one lender will necessarily approve an application another declines. It means lender fit may be worth exploring, with affordability and the loan’s terms kept firmly in view. If a mainstream bank says no, treat that as a decision on that application, not a judgement on you or proof that every option is closed.

If you’re exploring how to get a mortgage with low income nz, focus on presenting a clear, accurate account of your finances and understanding what may affect your application. General explanations of a mortgage loan can help clarify common terms, but they don’t describe how a New Zealand lender will assess your application. If you’re buying your first home, Home Loans for First Home Buyers in New Zealand is also a useful next read about the first-home buyer pathway. A careful look at your circumstances can help you work out what to prepare next, without assuming approval is guaranteed.

How NZ lenders assess whether your mortgage repayments are manageable

A salary can look sufficient on paper but leave little breathing room once household costs are included. Lenders look beyond gross income to estimate what could realistically remain for mortgage repayments after regular expenses and existing commitments. Your own budget matters too: a lender’s maximum offer isn’t automatically an amount that will feel comfortable month to month.

A lender’s offer shows what it may be prepared to lend; repayment comfort is about what you can manage while still meeting your household’s needs. Keep that difference in mind when weighing a possible loan amount against your real-life budget.

How income, expenses and existing debt fit together

Start with your take-home income, then list regular costs using recent bank statements or bills to keep your estimates grounded. Include essentials such as housing, food, utilities and transport, along with less frequent expenses that still recur. Don’t trim essential spending on paper just to make a mortgage look affordable. Give an accurate account of your financial commitments.

Existing personal loans, credit card repayments and other borrowing can reduce the income available for a home loan. For example, two households with similar take-home pay may have different repayment room if one has regular debt repayments or higher essential costs. The point isn’t to judge those choices. It’s to give the lender an accurate picture of what your budget can carry.

Why a lender may test repayments at a higher rate

A serviceability stress test checks whether repayments might still be manageable if interest rates were higher. It’s an assessment tool, not necessarily the interest rate you’ll pay. As reported by interest.co.nz and NZ Adviser in October 2026, major banks were using test rates ranging from 6.85% to 7.10%. Lender methods and settings can change, so those figures are a snapshot, not a promise of how a future application will be assessed.

This higher-rate check can affect how much a lender considers affordable, even if the actual rate offered is lower. If you’re looking at a low-deposit first-home option, the Kāinga Ora First Home Loan scheme still involves an affordability assessment by a participating lender. A small deposit doesn’t remove the need to show that repayments fit your circumstances.

To explore how a fixed interest rate or a different loan structure could affect repayments over time, see the Mortgage Rates NZ guide. Compare more than the headline rate: consider the repayment pattern, flexibility and how each option fits your plans. If you’re unsure how a lender may assess your budget, talk through your home-loan options with an adviser who can help organise your financial picture and discuss lender fit.

Which mortgage pathways may suit a lower-income borrower?

There isn’t one lending route that suits every household. Mainstream banks and alternative lenders may assess applications differently, while a first-home loan option has its own eligibility requirements and still depends on a participating lender’s assessment. The useful question isn’t simply which pathway may lend more. It’s which one could fit your budget and plans without leaving repayments uncomfortably tight.

For eligible first-home buyers, the Kāinga Ora First Home Loan may allow a deposit as low as 5%. That deposit level isn’t a promise of approval. You still need to meet current scheme criteria, and the participating lender assesses whether the loan is affordable for you. Check the current requirements before relying on scheme details, as criteria can change.

Pathway What to consider
Mainstream lender How its assessment fits your income, commitments, deposit and property plans.
Alternative lender Whether its different assessment approach suits your circumstances, and whether the repayments and terms remain manageable.
Kāinga Ora First Home Loan Whether you meet the current scheme criteria, and whether a participating lender considers the loan affordable.

When a mainstream lender may not be the only route

A decline from one bank is a decision on that application, not necessarily a final answer from every lender. Policies and assessment approaches differ, so another lending channel may view your circumstances differently. That doesn’t mean it will approve the application or that it will be the right fit.

An adviser can help organise your information, understand your goals and present your circumstances to suitable lending channels. If you’re weighing up a second-tier option, the 2nd Tier Lender New Zealand guide can give you more context about this type of lending. Treat alternative lending as a pathway to assess carefully, not a shortcut around affordability.

How to weigh flexibility against repayment comfort

Compare the whole loan, not just the headline interest rate. Consider how repayments are structured, what flexibility is available if your circumstances change, and whether the loan supports your longer-term plans. A feature that looks helpful may matter less than repayments that reliably fit your household budget.

To make the comparison practical, write down what matters most: predictable repayments, room in your budget for changing expenses, or flexibility to adjust the loan later. Then consider each pathway against those priorities. The right fit is personal, and an option that works for one borrower may not suit another.

If you’re weighing up how to get a mortgage with low income nz, focus on matching the lender and loan structure to your circumstances, rather than chasing the largest possible offer. A careful comparison can help you explore a fair go while keeping repayment comfort front and centre.

How to Get a Mortgage on a Low Income in NZ in 2026

How to prepare a stronger mortgage application on a lower income

A well-organised application helps show a lender how your finances work in practice. You don’t need to make your budget look perfect. Give a clear, consistent account of your income, spending and commitments, then explore lending options that fit your circumstances.

Build a clear picture of your household budget

Start with a simple household budget. List your take-home income, essential spending, regular commitments and what remains for possible mortgage repayments. Include costs that don’t happen every week or month, so your estimate reflects normal life rather than an unusually quiet period.

Next, consider whether a possible repayment would leave enough room for everyday needs and unexpected changes. If the budget only works when nothing goes wrong, that’s useful to know before applying. A realistic figure gives you a better starting point for discussing a loan size and structure that may suit you.

You can use the Mortgage Suite mortgage calculator to explore how changing the loan amount, repayment frequency or term affects estimated repayments. Treat the result as an initial guide, not an approval or a substitute for a lender’s assessment. Try a few scenarios and compare them with the budget you’ve written down.

Get your application details organised before applying

Gather clear records of your income, employment and existing financial commitments. Lenders may ask for different information, so check the current requirements for the pathway being considered before you apply. Keeping your details together can make it easier to answer questions accurately and avoid gaps in your application.

If your income has changed or varies over time, explain that plainly. Note what changed and how your current income is earned, then make sure the information you provide is consistent across your application. Don’t leave an unusual item unexplained or omit a commitment to make the figures look better. Clear context helps a lender understand the financial picture you’re presenting.

Use your preparation to discuss suitable lending pathways

Once your budget and financial details are organised, you can have a more focused discussion about which lending channels may fit. Share what matters to you, such as keeping repayments manageable or having room in your budget if circumstances change. A mortgage adviser can organise the information and present your circumstances to lenders, while explaining that an application still needs to meet the lender’s criteria.

Preparing this way can make the next steps in how to get a mortgage with low income nz feel more manageable. It also helps you compare a possible offer with your own budget, rather than relying on the largest amount a lender might consider. Talk through your home loan options with Mortgage Suite and use your figures to guide a conversation about suitable pathways.

How Mortgage Suite can help you explore a mortgage on a low income

A home loan decision involves more than working out a possible borrowing amount. An adviser can first understand what you want to achieve, how your income is earned and which commitments shape your household budget. From there, Mortgage Suite can help you consider mainstream or alternative lending channels, including second-tier lending for borrowers who don’t fit mainstream bank criteria, and identify questions to resolve before taking the next step.

Mortgage Suite helps organise your application and represent your circumstances clearly when discussing options with lenders. The focus is on finding a suitable fit for your goals and budget, not pushing you towards a particular loan. Each lender makes its own assessment, so no outcome can be promised.

What to expect from an initial conversation

You can talk through your income, regular commitments, plans for a home and what you hope a mortgage will make possible. If you’ve already spoken with a lender, share what you learned and what remains unclear. This gives the adviser a practical starting point for identifying questions, organising relevant details and considering possible pathways, without treating the conversation as a promise of approval.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to this work. That background informs the firm’s approach to understanding borrowers’ circumstances and discussing lender fit.

Take the next step without feeling pressured

You don’t need to arrive with a perfect application or a definite borrowing target. Bring the information you have and use the discussion to clarify what you can prepare next. It’s also a chance to talk about what feels manageable for your household and which questions matter most before making a decision.

If you’re considering how to get a mortgage with low income nz, a calm, informed conversation can help turn uncertainty into a practical next step. Talk with Mortgage Suite about your home-loan options when you’re ready to explore what may fit.

Take your next step with a clear plan

A home-buying plan doesn’t have to start with a final borrowing figure. Start by deciding what repayment would leave your household feeling steady, then use that as a guide when considering properties and loan options. If your income or commitments change, revisit the plan before making a major decision.

Working out how to get a mortgage with low income nz is less about finding a one-size-fits-all rule and more about understanding the options for your circumstances. A conversation can help you identify what to clarify, which questions to ask and what a sensible next step might look like. You don’t need to have everything perfectly sorted before you begin.

Mortgage Suite can help you consider your goals and discuss possible lending pathways without treating approval as a given. Talk through your home loan options with Mortgage Suite and take the next step at a pace that feels right for you. With a clearer plan, you can move forward with more confidence and give your home-buying goals a fair go.

Frequently Asked Questions

Can I get a mortgage in NZ if I earn close to the minimum wage?

Possibly, but your pay alone can’t show whether a mortgage will fit your circumstances. Before approaching a lender, work out what your household regularly spends and what remains after essentials and existing commitments. There isn’t a set income threshold that guarantees an outcome. This practical budget can help you discuss how to get a mortgage with low income nz without assuming a particular borrowing amount is within reach.

Can I apply for a mortgage if my income changes from week to week?

You can discuss an application, but be ready to explain how your income varies and how you earn it. Keep a clear record over time so the pattern is easy to understand, including quieter and busier periods if that reflects your work. Lenders may assess changing income in different ways, and no single history or rule applies to every case. Share accurate details before settling on a lending pathway.

Can a partner or family member apply for a mortgage with me?

Yes, you can explore applying together. A lender will consider each applicant’s income, commitments and circumstances, so discuss everyone’s finances openly before starting. Shared borrowing also brings shared responsibility: joint and several liability means each borrower may be responsible for the whole shared debt, not only an agreed personal share. Make sure you understand how repayments will be handled and what you’d do if one person’s circumstances changed.

Does a low income mean I will have to pay a higher interest rate?

Not automatically. Income alone doesn’t determine the interest rate a lender may offer. Its decision can reflect your overall application and the loan structure being considered. As you compare options, look at the repayment pattern and any flexibility alongside the rate, then consider whether the arrangement supports your longer-term plans. A rate that looks appealing on its own may not be the best fit if the wider loan terms don’t suit your needs.

Will a mortgage calculator tell me whether a lender will approve me?

No. A calculator can’t weigh lender-specific criteria, the property being considered or all the details of your application. Use the Mortgage Suite Mortgage Calculator to explore possible repayments, then check that the figures you enter reflect the loan scenario you’re considering. The result can help you prepare questions for a lender or adviser, but it can’t confirm that a particular loan will be approved.

Does a declined mortgage application mean I cannot borrow from another lender?

Not necessarily. Before taking another step, ask the lender to explain the main reasons for its decision and whether any information was unclear or missing. Check that you understand what would need to change before another application is considered. This can help you decide whether to update your information, wait or discuss your circumstances with an adviser. Avoid applying again until you have a clearer plan, as another lender will make its own assessment.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

How to Build a Property Portfolio in NZ: 2026 Guide

What if the next property in your portfolio should be decided by your financial breathing room, not the maximum a lender might offer? If you’re working out how to build a property portfolio nz, it’s understandable to feel unsure about how existing loans, available equity and changing repayments could affect your next move.

A sustainable plan starts with your goals and what your household can comfortably manage, not a target number of properties. This guide will help you map out practical next steps, understand how lenders may assess your income and existing debt, and review the risks before taking on another commitment.

You’ll also learn how available equity may support a purchase, why lenders test whether you could manage higher repayments, and how to plan for vacancies or changes in your circumstances. Mortgage Suite helps borrowers compare suitable lending options and structure finance as their plans develop. If a mainstream bank has declined your application, that doesn’t necessarily mean your options have run out.

Key Takeaways

  • Start with clear property and personal goals, then set a pace your household budget can support.
  • See how to build a property portfolio nz by understanding how lenders may weigh your income, expenses, existing debt and proposed repayments.
  • Compare buying one property at a time with a faster purchase plan, and weigh using available equity against building savings.
  • Check whether your budget could handle vacancies, income changes, repayments and property upkeep before taking on another loan.
  • Organise your finances and compare lending paths so your plan can adapt as your circumstances change.

How to build a property portfolio in NZ: start with a clear plan

Buying a second property can feel like a major financial step. You’re not only deciding whether a particular home suits your plans; you’re taking on another loan and the responsibilities that come with it. A useful starting point for how to build a property portfolio nz is to decide what you want property ownership to do for you, and what level of debt your household can manage comfortably.

A property portfolio is a group of properties held for investment, rather than a single purchase considered on its own. It might grow through separate purchases over time. But owning several properties isn’t a plan by itself: each purchase needs to fit your borrowing, income and ability to manage the ongoing commitments. For a broad introduction, you can explore these real estate investing principles.

What does building a property portfolio involve?

Portfolio growth is usually a sequence of decisions, not one large transaction. After each purchase, your finances and options may look different, so pause and review before taking another step. More properties don’t automatically mean a better financial outcome. Your plan needs to account for the loans and responsibilities attached to each property, not just the number you own.

Set goals before you look at another property

Start by asking what you want property ownership to support. Then consider your timeframe, how steady your income is and what commitments your household already has. Set a debt level that leaves room in your budget for everyday needs and unexpected changes. These answers can help you decide whether another purchase fits your priorities now, later or not at all.

Write down your starting point before browsing listings. It can help to consider:

  • Your purpose: What do you want property ownership to contribute to your longer-term plans?
  • Your timeframe: Are you comfortable holding a property for the period your plan requires?
  • Your income: Could you manage the commitments if your income changed or became less predictable?
  • Your debt limit: What level of repayments would still feel manageable alongside your other obligations?

Be realistic about the difference between a goal and a borrowing limit. A lender’s assessment can show what may be possible, but it doesn’t decide what feels right for your household. Leave room for property ownership and maintenance, as well as changes that could affect your income or budget. That breathing space matters more than reaching a particular portfolio size.

Growing a property portfolio won’t suit every household or financial situation, and there’s no need to rush. Let your portfolio grow at the pace your finances can support, not the pace a lender may allow. If the numbers or your circumstances don’t feel settled, taking time to strengthen your plan is a sensible next step.

How lenders assess finance as your NZ property portfolio grows

As your property plans develop, a lender will look at your overall borrowing, not just the value of the next property. Existing home and property loans, income, household expenses and proposed repayments all help shape whether a new loan may be affordable. Assessments vary between lenders, so an earlier approval or decline won’t necessarily determine the outcome of a later application.

How equity and borrowing capacity fit together

Equity is the difference between a property’s current value and the lending secured against it. If the property’s value rises or the loan balance falls, your equity may increase. But that doesn’t automatically mean you can borrow more. A lender also needs to consider whether your income can support repayments on both existing and new loans. Available equity and borrowing capacity are related, but they aren’t interchangeable.

For example, you may have equity available while your household budget has little room for another repayment. In that case, the equity alone won’t show whether another purchase is manageable. The property type and lender requirements may also affect how the property is viewed as security for lending. If you’re weighing up finance for a rental purchase, this guide to mortgage lending concepts can help you get familiar with the basics.

What lenders may consider across multiple properties

A lender may review your existing repayments alongside your regular income, household commitments and the proposed repayments for the new loan. It may also consider rental income, but lenders can treat that income differently. Don’t assume the full rent will count towards your application. The same applies to property-related expenses. Current lender criteria matter.

The assessment may also include a serviceability stress test, which checks whether repayments could remain manageable if interest rates were higher than the rate offered. This helps explain why a loan that looks affordable at today’s repayment level may be assessed differently. Ask your mortgage adviser to explain the assessment assumptions in plain English, including how existing lending and rental income have been treated.

To prepare, organise an up-to-date view of your finances before discussing another purchase. Include:

  • All current lending: balances, repayments and any changes you already expect.
  • Household income and commitments: regular income alongside everyday expenses and other debt.
  • Rental details: income received and property-related expenses, while allowing for the lender’s own approach.
  • The proposed loan: expected repayments and how they fit with your existing commitments.

A clear picture makes it easier to compare possible lending paths and spot gaps before you commit to a purchase. A mortgage adviser can help present your circumstances to suitable lenders and negotiate a structure that fits your plans. If one mainstream bank says no, that isn’t automatically the end of the conversation. As you consider how to build a property portfolio nz, focus on understanding the reasons behind an assessment and which options may suit your situation.

Compare property portfolio strategies before choosing your next step

There’s no single route that suits every borrower. The right approach depends on how steady your income is, how much room your budget has for repayments and how much time you have to review each decision. A mortgage assessment can help you understand possible lending paths, but it doesn’t tell you whether a property is suitable or what return it might deliver. Consider the property choice and the finance separately.

One purchase at a time or a faster sequence?

Buying one property at a time gives you a chance to see how each new commitment affects your finances before deciding what comes next. A faster sequence may add properties sooner, but it also means taking on commitments closer together. Neither approach is automatically better. Consider how much time you want between decisions and whether your income and budget could manage the pace if circumstances change.

Approach What to weigh up
One purchase at a time More time to review repayments, income and commitments before another application, though progress may be slower.
Faster purchase sequence May add commitments sooner, so consider whether your budget and income can carry them without relying on everything going to plan.
Use available equity Could provide funds towards a purchase, but any extra borrowing adds repayments and still needs to fit lender criteria.
Build savings for a deposit Can reduce the need to borrow for the deposit, but waiting may affect your timing and requires consistent saving.

Using equity or building a deposit

Using equity means seeking further lending against value held in a property. Building savings means setting money aside towards a deposit instead. Equity may make a purchase possible sooner, but it can increase total debt and repayments. Saving first may mean waiting longer, while giving you time to build your deposit. Neither route guarantees approval or makes a property a sound choice. Compare both against your likely repayment capacity and timeframe.

Before settling on either path, consider what would happen if your income fell, expected rental income changed or a property needed attention. A plan that only works under ideal conditions may leave little room to adjust. Think about how much flexibility you want to keep and whether taking on another commitment now fits your broader financial priorities.

Use plain-English mortgage learning resources to get clearer on the lending concepts behind your options. Then compare possible finance structures against your goals, rather than choosing a purchase pace first and trying to make the borrowing fit afterwards. That’s a practical starting point for how to build a property portfolio nz while keeping the focus on a pace your finances can support.

How to Build a Property Portfolio in NZ: 2026 Guide

Check portfolio resilience before taking on another property

Before adding another loan, look beyond whether the repayments fit your budget today. A portfolio can feel manageable while income is steady and properties are occupied, but vacancies, repairs or changing household circumstances can alter the picture. A practical resilience check helps you spot pressure points before you commit.

Stress-test the household budget

A lender’s assessment and your own comfort level are two different checks. A lender decides whether an application fits its criteria; you need to decide whether repayments leave enough room for everyday needs and unexpected changes. Try the mortgage repayment calculator to explore how repayments may change under different assumptions. Treat it as a planning aid, not an approval estimate or a promise of what a lender will offer.

Work through this check before each purchase. Be honest about less favourable circumstances, not just the version where every payment arrives on time and nothing needs fixing.

  • 1. Repayments: Map the repayments for all your loans together. Would they remain manageable if rates or other household expenses rose?
  • 2. Income changes: Consider how a drop in household income, fewer work hours or a change in employment could affect your ability to meet commitments.
  • 3. Rental vacancies: Allow for a period when a property has no tenant and rental income pauses. Could you still cover its loan and other regular commitments?
  • 4. Repairs and upkeep: Think about routine maintenance as well as an unexpected repair. Does your budget have room to respond without disrupting essential household spending?
  • 5. Loan fit: Check how each loan’s repayments and structure fit with your other commitments and the plans you have for the coming years.

Plan for vacancies, repairs and changing circumstances

A suitable financial buffer can help you manage a gap in rent or property work that can’t be put off, but the right amount depends on your circumstances. Set a level that reflects your household commitments, property needs and capacity to save. Don’t rely on rent being received without interruption. Revisit the plan when your income, expenses or borrowing changes, and before taking on another property.

Keep the scope clear, too. A mortgage review can help you understand how lending fits your plans, but it doesn’t replace separate tax, legal or property-investment advice. Those matters may need input from the relevant professional. The Mortgage Suite website has information about lending options. A clear view of your commitments can help you decide whether the next step feels manageable, not simply possible.

Build your property portfolio with a finance plan that can adapt

A useful finance plan isn’t a timetable that says you must buy again by a certain date. It’s a way to keep your borrowing choices connected to your goals, income and changing commitments. If you’re considering how to build a property portfolio nz, focus on making the next decision with a clear view of what you owe, what you can manage and which finance paths may suit.

When a mortgage adviser can help

Before pursuing another purchase, an adviser can help you review your borrowing as a whole, including current loans, income and the new commitment you’re considering. They can compare lending options across suitable lenders and negotiate on your behalf, explaining how loan structure may affect your plans. The aim is to help you understand your choices, not to promise a particular rate, approval or outcome.

A mainstream-bank decline can be disappointing, but it doesn’t automatically close off every finance option. Another lender may assess your circumstances differently, depending on its current criteria and the details of your application. Mortgage Suite acts as a personal advocate through that process, helping you understand the options available and what each may mean for your wider borrowing picture.

Turn the plan into practical next steps

Get your information organised before a finance discussion. A clear picture makes it easier to identify questions, compare possible paths and work out what needs attention before you proceed. You can start with these steps:

  • Organise your finances: Gather details of your income, regular expenses, savings and existing lending.
  • Map your commitments: Include repayments and the ongoing responsibilities attached to each property.
  • Compare lending paths: Discuss how different lender criteria and loan structures may fit your plans.
  • Review your readiness: Consider whether the proposed commitment still feels manageable if circumstances change.

Then review the plan after a major change, such as a shift in income, new household commitments or a change to your existing lending. Revisit it before each purchase, too. A plan that fitted last year may need adjusting now, and there’s no need to follow someone else’s buying schedule.

Mortgage Suite’s team can support you as you consider your next finance decision. The Mortgage Suite website explains how to start a conversation about a property finance plan and explore a suitable way forward.

Make your next property decision with confidence

Your plan doesn’t have to map out every purchase from the start. Treat it as a working guide: revisit it as your income, commitments and goals change, and let those changes shape your next move. That gives you room to pause, adjust or proceed when the finances make sense for your household.

If you’re still considering how to build a property portfolio nz, a conversation about the lending side can help you understand the paths available. Mortgage Suite supports residential investment property borrowing and can discuss mainstream and alternative lending options. Founder Krish Krishna brings over two decades of banking experience to helping borrowers work through their finance choices. No lender can promise an outcome, but you can make your next decision with a clearer view of your options.

Talk through your property finance plans with Mortgage Suite when you’re ready to take that next step. A steady, considered pace can help you move towards your goals while keeping your household’s financial wellbeing in view.

Frequently Asked Questions

Can I build a property portfolio with only one investment property to start?

Yes, a property portfolio can begin with one investment property. Owning it doesn’t mean another purchase will suit your household, though. First, decide what you want the property to support and how long you expect to hold it. Then list your existing loan repayments and other commitments, and review your borrowing capacity before planning a next step. There’s no required property count or guaranteed route to growth.

Does having equity mean I can buy another investment property?

No, equity alone doesn’t mean you can buy another property or that a lender will approve a new loan. A lender may also consider your income, existing debt, expenses and the property offered as security. For example, having value available in one property won’t necessarily resolve a tight household budget. Look at whether repayments would be affordable as well as how much equity may be available.

How many properties should I have in a portfolio?

There’s no single number that suits everyone. If you’re considering how to build a property portfolio nz, start with what fits your goals, income, borrowing capacity and comfort with risk, rather than aiming for a particular count. For one household, keeping a single rental property may be the right fit; another may have room to grow over time. Judge progress by whether each commitment remains manageable, not by comparing portfolio sizes.

Can rental income help me qualify for another property loan?

It may help, but lenders can assess rental income in different ways. Don’t assume every dollar of rent will count in full or that rent will cover all your existing commitments in a lender’s assessment. For instance, a lender may take a cautious view of expected rent while still considering your other income and expenses. Review rental income alongside your full financial position and the lender’s current criteria.

Should I use equity or save a deposit for my next property?

Either approach may suit, depending on your circumstances. Using equity may mean taking on additional borrowing and repayments; saving towards a deposit may take longer but change how much you need to borrow. Compare the options against your timeframe, existing commitments and ability to manage repayments if circumstances shift. Before deciding, review the full lending position rather than treating available equity or savings as the only factor.

What happens if a bank declines my next property loan?

A decline isn’t a personal judgement, and it doesn’t automatically end every finance option. Start by understanding the reasons for the decision, such as how the lender viewed your income, commitments or property details. Another lender may assess your circumstances differently, but approval isn’t guaranteed. A mortgage adviser can review your position and discuss suitable mainstream or alternative lending pathways where appropriate.

Is it risky to build a property portfolio using borrowed money?

Borrowing adds repayments, so changes to income, property expenses or lending conditions can affect your household budget. The level of risk depends on your circumstances and how the lending is structured. Before taking on more debt, test your budget against less favourable conditions, consider a financial buffer that suits your situation and review your loans regularly. Property ownership isn’t risk-free, so avoid relying on everything going to plan.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Land Development Loans: Your 2026 Guide to Funding Your NZ Project

What if a bank’s “no” isn’t the end of your subdivision plans? If you’re looking for a land development loan, it can be hard to know where to turn when a mainstream lender isn’t comfortable with your project. The process can feel complicated, especially when you’re working out how to fund the land, the site preparation and the work needed to create new sections.

You deserve a clear explanation of your options, not a pile of lending jargon. This guide explains how lenders may assess a project, how funds can be released as work progresses, and what to plan for, from council requirements to site preparation and services.

Mortgage Suite’s Krish Krishna brings more than 20 years of banking experience to property development lending. He understands how lenders assess proposals and can advocate for you when your plans don’t fit a bank’s usual approach. We’ll walk through how to prepare your project, compare funding options and present a practical plan, so you can make informed decisions with greater confidence.

Key Takeaways

  • A land development loan can help fund more than the land itself, including work to prepare it for subdivision.
  • Break your funding needs into stages, from buying the land to completing the work and deciding what happens next.
  • If a mainstream bank says no, second-tier lenders may offer another path, depending on your project and circumstances.
  • Prepare a clear plan showing how the development could work, and bring together a capable team to support it.
  • An experienced lending guide can help you understand your options and present your project clearly to potential lenders.

What is a land development loan and how does it actually work?

A land development loan can fund a subdivision and the work needed to turn undeveloped land into prepared sections or a site ready for building. It’s different from a loan to buy a home, because the project centres on improving land rather than purchasing a finished place to live.

Depending on the project, funding may cover earthworks, pipes, roads and other work needed to make the land usable. Civil works means preparing the site and putting essential connections and access in place. The specific work depends on the land and the subdivision plan.

Land development usually involves several steps, from planning and preparing the site through to creating new sections. For a simple overview of the process, see What is land development? A development loan is generally intended to support a project over a shorter period than a typical home loan, with the aim of completing the work so you can sell the sections or build on them. The repayment plan needs to match that goal.

Why a standard home loan usually will not cut it

A standard home loan is designed around buying a home. A bare block has no finished house to live in, and its value may depend on work that hasn’t happened yet. That can make undeveloped land more difficult for a mainstream bank to assess.

Development funding needs to account for the plan as well as the land’s current value. A lender may consider what you intend to do, the work required and how the completed project could be sold or used. The funding and repayment plan may also be structured around the project rather than a standard home-loan setup.

The difference between “buying” and “developing”

Buying the land is the acquisition stage: ownership changes hands, but the site may still be untouched. Developing is the work that follows, such as preparing the ground, installing pipes and creating roads so the land can be divided or built on.

Because these stages have different funding needs, one arrangement may not suit the whole journey. You might need funds to secure the block first, followed by suitable finance for the work. Mapping out each stage helps show a lender what the money is for and how the project is expected to progress.

Be clear about your end goal from the start. Selling prepared sections and building homes are different plans, and your funding approach should reflect the one you’re pursuing. You don’t need every detail finalised before discussing finance, but it helps to have a clear picture of the land, the work ahead and what you hope to achieve.

The three main stages of funding your land project

A subdivision usually moves from buying the land to preparing it, completing the work and then selling or building. Your funding needs can change at each step, so map the whole journey early rather than focusing only on the purchase.

Stage 1: Land acquisition and holding

First, you need funding to secure the block. If you buy land and hold it while preparing for development, this is sometimes called “land banking”. Even if the diggers aren’t on site yet, set out what you intend to do, what needs to happen before work can begin and how you expect to move the project forward.

Equity in another property may help support the purchase, depending on your circumstances and how a lender assesses the overall plan. It isn’t an automatic solution, but it can be part of the funding picture. Include the holding period in your plan too, so you understand how you’ll manage the land while plans and approvals progress.

Stage 2: Getting the green light

Before physical work starts, you may need advice from professionals such as surveyors, as well as relevant consents for your proposal. This stage turns an idea into a clearer project plan. The steps depend on the land and the subdivision, so include them in your timeline rather than assuming everything can happen at once. New Zealand’s planning framework is changing; the Government’s update on planning laws for land development is useful context as you consider how planning rules may affect a project.

Stage 3: Civil works and subdivision

Once the project is ready to proceed, the work may include preparing the site, putting in infrastructure and dividing the land into separate titles. This is where one block can become several sections, but progress depends on completing the work required for that particular project.

Funding may be released in stages as agreed work is completed. This is called the drawdown process: instead of receiving all the funds at once, you access them as the project reaches agreed milestones. Ask for the release steps to be explained in plain English, so you can plan cash flow around the work.

At the finish: once the work is complete, you may plan to sell the new sections or build on them. The loan then needs to be repaid or restructured to suit what happens next. Setting out that end point early connects the land purchase, the work and your final plan into one funding story.

Banks vs Non-bank lenders: Finding the right fit for your land

A mainstream bank’s “no” can be discouraging, but it doesn’t automatically mean your project has no way forward. Banks often use set lending rules designed for more straightforward proposals. A subdivision can be harder to assess because the land still needs work before it can be sold or built on, and the outcome depends on several steps being completed.

Non-bank, or second-tier, lenders are professional lending organisations, not simply a last resort. They may assess the project plan and how it could reach completion alongside your personal finances. Their approach and terms can differ from a bank’s, so the right fit depends on your proposal and circumstances. Flexibility may help a project proceed, but it’s still important to understand the repayment plan and how the loan fits your wider goals.

When a mainstream bank may fit

A bank may suit a straightforward project if you have a clear plan, a sound financial position and enough funds available to manage the work. Banks may offer lower interest rates, but their assessment can involve detailed paperwork and firm requirements. A strong credit history may help, though lenders consider the full application. The key is whether the bank’s criteria suit your project, not just whether its rate looks appealing.

For example, a simple subdivision with a well-prepared plan and resources to manage changes may fit a bank’s usual approach. If the project has unusual features or your circumstances fall outside its standard checks, the application may be more difficult to assess. That’s a reason to understand the bank’s decision, not to assume the project itself has no merit.

The second-tier option for developers

A second-tier lender may assess a land development loan by considering the project’s purpose and expected outcome, as well as your personal finances. This can help if your proposal has a clear plan but doesn’t fit a bank’s usual approach. Terms may differ, including the interest rate, so weigh any added flexibility against the full repayment arrangement.

Timing can matter if contractors are booked or work is ready to begin. Non-bank lenders may assess proposals differently, but approval timeframes vary. A clear plan and organised information can help explain what you need funding for and how the project is expected to progress.

Mortgage Suite specialises in property development and second-tier lending. Krish Krishna brings more than 20 years of banking experience and can help you understand lender expectations and present your proposal clearly. If your application has been declined, reviewing the reasons and considering a suitable alternative funding approach can help you decide what to do next.

Land Development Loans: Your 2026 Guide to Funding Your NZ Project

Getting your ducks in a row: How to qualify for a land loan

A clear, well-prepared application helps a lender understand what you want to do and how the project could work. Before applying for a land development loan, set out the plan, the people supporting it and how you expect the project to reach its end goal. A past development can strengthen your case, but a capable team, such as surveyors and other relevant specialists, can also show that you’ve thought through the work.

Be clear about your equity, meaning the money or property value you’re contributing yourself. It shows how much of your own resources are going into the project. The amount and type of contribution a lender expects will depend on your circumstances and proposal, so explain what you can bring to the table without assuming one formula applies to every project.

What to prepare for your application

Get your paperwork together early, before the right block appears and the pressure is on. A lender may want to understand whether the numbers add up, what permissions or consents apply, and how the borrowing will be repaid. A useful preparation list includes:

  • A feasibility study: Does the plan make financial sense? Set out the expected project steps and how the figures support them.
  • Planning and consent information: Include relevant council information for your proposal, such as resource consent details where applicable. Requirements can vary by project.
  • A clear exit plan: Explain how you expect to repay the lending, for example by selling completed sections or moving on to the next stage of the project.
  • Supporting documents: Gather the land details, project plans and information from the professionals helping you prepare the development.

You don’t need to present yourself as a developer who has done it all before. A realistic plan and a team with relevant experience can help explain how the project will be managed. Be upfront about any parts still in progress, too. That gives the lender a clearer picture than leaving gaps for them to fill in.

How a mortgage adviser can help you prepare

Krish Krishna brings more than 20 years of banking experience to property development lending. He can help organise your application so the purpose, figures and proposed repayment plan are clear before it reaches a lender. That means explaining the project in a way lenders can assess and helping you compare options that may suit your circumstances.

To get a starting view of your figures, use our mortgage calculator. It’s one part of preparation, not a decision on whether a lender will approve development funding. Your application still needs to show how the project fits together. Getting organised early can make it easier to act when a suitable block comes along.

Why a seasoned expert makes all the difference for your development

A development project has a lot of moving parts, and explaining them to a lender can feel like a job in itself. Krish Krishna brings more than 20 years of banking experience to Mortgage Suite, helping make sense of lender expectations and how they relate to your plans.

Think of Mortgage Suite as a bridge between the lending process and what you want to achieve with your land. We can help present your project clearly, discuss suitable funding options and negotiate with lenders on your behalf. That can be useful when your proposal doesn’t fit a bank’s usual approach. A decline can be discouraging, but it isn’t a judgement on your goals or necessarily the end of the road.

Our approach is about working alongside you, not treating your land development loan as a one-off transaction. The right funding needs to fit the project and your wider plans, not just look good on paper at the start. We’ll explain the options in plain English, so you can make decisions with a clearer picture of what each path involves.

The Mortgage Suite approach

Preparing a development application takes planning and follow-through. We help with lender conversations and explain what information may be needed, so you’re not left trying to piece together unfamiliar requirements on your own. You can read our client reviews to hear about other people’s experiences. Our About Us page also shares more about the people and approach behind Mortgage Suite.

We believe Kiwis deserve a fair go at developing their land, even if a mainstream bank has been tough to deal with. That doesn’t mean every application will be approved. It means taking the time to understand your circumstances, look at the project carefully and explore a way forward where one may be available.

Taking the next step

Start by setting out what you want to do, where you are in the process and what’s making the funding feel difficult. This gives you a useful basis for understanding what lenders may want to see and which options could suit your circumstances. No jargon, no pressure, just a clearer discussion about the next steps.

If you’re weighing up a subdivision or have already had a lender say no, Mortgage Suite can help you talk through your plans and funding options. A considered conversation can help you see what may be possible and decide how you’d like to proceed.

Take the next step with a clear plan

Funding a subdivision is easier to approach when you break it into stages, understand what lenders may look for and prepare a clear plan for the work and the end goal. The right land development loan depends on your project and circumstances, so a bank’s decision isn’t the only factor to consider.

Mortgage Suite specialises in property development and non-bank, second-tier lending across New Zealand. Krish Krishna brings more than 20 years of banking experience and can help you understand lender expectations, present your project clearly and explore suitable options. No lender can promise approval, but you can get a clearer view of possible next steps.

Ready to discuss your project? Talk with Mortgage Suite about your plans and funding options. A well-prepared project can have a way forward, and you don’t have to work through the lending questions alone.

Frequently Asked Questions

How much deposit do I need for a land development loan in NZ?

There isn’t one deposit amount that applies to every project. A lender may consider the land, the work planned, your financial position and how much of your own money or property value you can contribute. This contribution is often called equity. Prepare a clear project plan and details of your available funds so a lender can assess your circumstances and explain what may be needed.

Can I get a loan if I have never developed land before?

Yes, a lack of development experience doesn’t automatically rule you out. You can strengthen your application by showing a clear plan and bringing together a capable team, such as surveyors and other professionals who understand the work. A lender will still assess the project and your circumstances, so be upfront about your experience and how you’ll manage parts that are new to you.

What happens if the bank has already declined my application?

A bank’s decision isn’t necessarily the end of your options. Find out what made the application unsuitable, then consider whether a different lender may assess your project another way. Mortgage Suite specialises in property development and second-tier lending for borrowers who don’t fit mainstream bank criteria. Krish Krishna can help you understand the feedback and present your plans clearly, though no lender can guarantee approval.

How long does it typically take to get a land development loan approved?

There’s no set timeframe for every application. The time needed can depend on the project’s complexity, the information available and the lender’s assessment process. A straightforward proposal with organised documents may be easier to assess than one with unanswered questions about the work or repayment plan. Gather your land details, project plans and supporting information early, and allow time for the lender to review them.

Do I need to have resource consent before I apply for funding?

Not always. The right timing can depend on the project and the lender. Some funding discussions may begin while plans or consent steps are still underway, but a lender will want to understand what approvals are relevant and where you are in the process. Be clear about what’s been completed and what remains. Don’t present a proposed subdivision as approved if it isn’t.

What is the difference between a land loan and a construction loan?

A land loan generally helps fund the purchase or holding of a block, while a construction loan is used for building work. A subdivision may also need funding for site preparation and infrastructure, such as roads and pipes. The right arrangement depends on what you’re doing and when. Explain each project stage so the proposed funding matches the work, rather than assuming one loan type covers everything.

Is it more expensive to use a non-bank lender for my subdivision?

A non-bank lender may have a higher interest rate or different terms than a mainstream bank, but the right comparison goes beyond the rate alone. Look at how the funding is structured, what flexibility it offers and whether it fits your project timeline and repayment plan. Non-bank lending isn’t automatically the right choice, but it may be an option if a bank’s standard criteria don’t fit your proposal.

Can I use the equity in my family home to fund a land development?

It may be possible to use equity in your home as part of the funding plan, depending on your finances and the lender’s assessment. Equity is the portion of your home’s value that isn’t covered by lending against it. Using your home this way can put it at risk if repayments aren’t met, so consider the impact on your household and get clear advice before deciding.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.