NZ Property Development Loan Requirements 2026

A lender’s decision on a development project depends on more than the land or your borrowing history. Lenders may also assess whether the plan can be delivered, whether the numbers make sense and how the loan will be repaid. That can make property development loan requirements nz feel unclear, especially if you’re unsure which documents to prepare or how your experience and project structure will be assessed.

It’s reasonable to want a clear picture before you apply. This guide explains the main areas lenders may assess and the project information that can support an application, including plans, budgets, building contracts and funding stages. You’ll also learn how project progress can affect the drawdown process and what options may be available if a mainstream bank’s criteria don’t fit. Mortgage Suite provides property development finance and helps organise project information and negotiate with lenders. Founder Krish Krishna brings more than two decades of banking experience to these discussions. A bank decline isn’t always the end of the conversation. Understanding what may suit your project is a practical next step.

Key Takeaways

  • Property development loan requirements nz can vary according to the lender, project type, stage and funding structure.
  • Lenders may consider your experience, finances, project feasibility, security and plan for repaying the loan.
  • Grouping supporting documents into clear categories can help you prepare a more organised application.
  • Review your project assumptions, timeline and repayment plan so you’re ready to discuss delays or changes.
  • A finance adviser can help present your project to lenders and explore suitable funding pathways if a mainstream bank isn’t the right fit.

Property development loan requirements in NZ: what lenders look at first

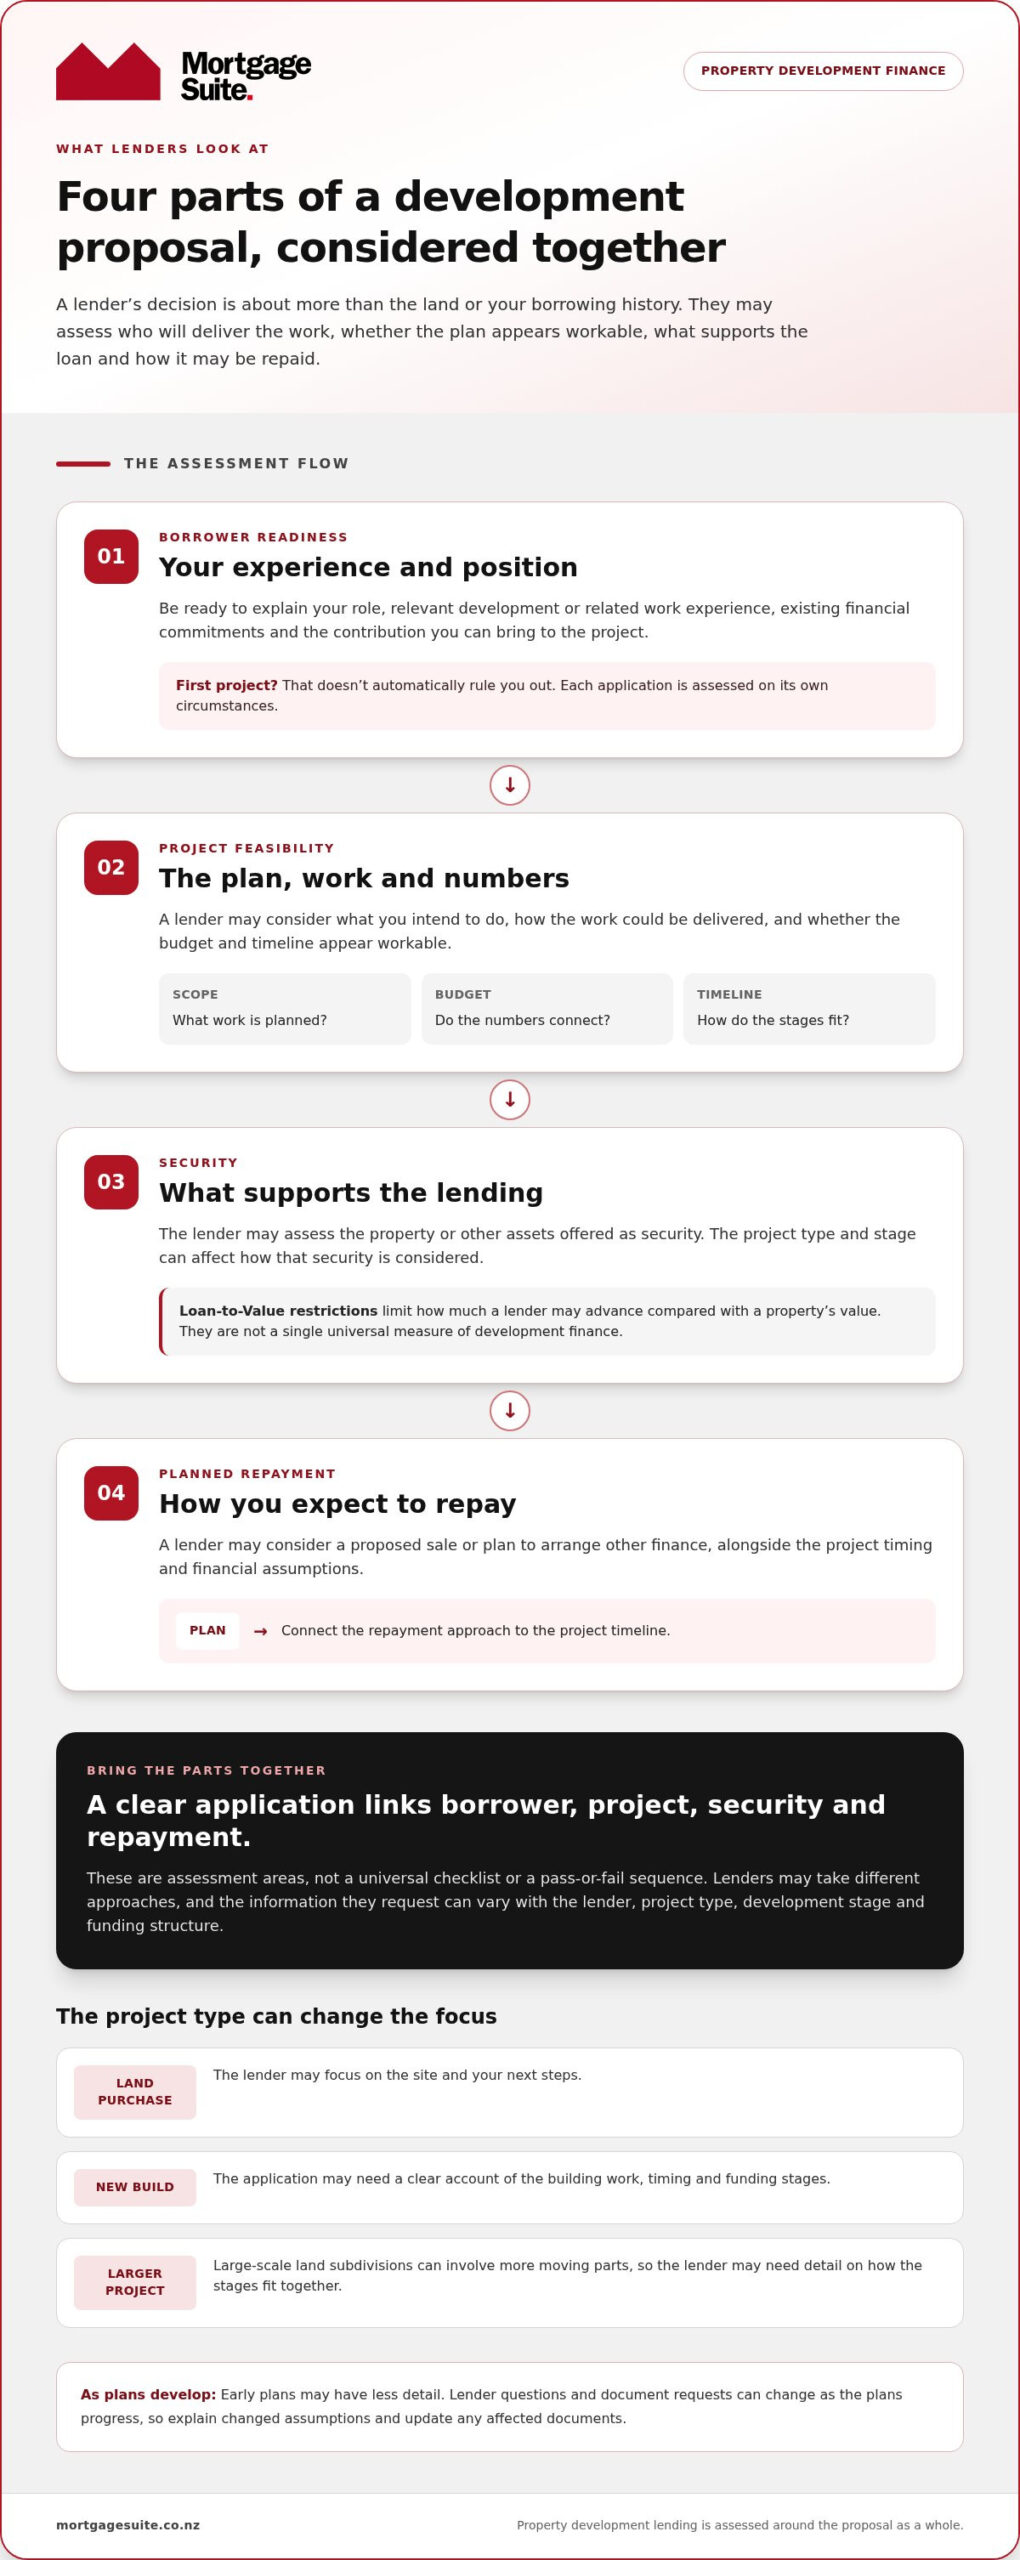
In brief: Lenders usually consider the borrower, project, available security and proposed repayment plan together. The property development loan requirements nz applicants face can vary with the lender, project type, development stage and funding structure. There isn’t one document or criterion that applies to every application.

A lender is assessing the project’s risks as a whole: who will deliver it, whether the plan appears workable, what property supports the borrowing and how you intend to repay the loan. A clear application connects these elements and explains how the project is expected to progress.

What does a property development lender assess?

Four broad areas help a lender build a picture of your proposal:

  • Your experience and position: Your background may help explain your ability to manage the work. A lender may also consider your financial position and existing commitments.
  • The project plan: The lender needs to understand what you intend to do, how the work may be delivered and whether the project appears financially workable. Development can involve connected stages, from acquiring land through to construction, as outlined in this real estate development process.
  • Security: The property or other assets offered as security help the lender assess what supports the loan. The project type and stage may affect how that security is considered.
  • Repayment plan: The lender will want to understand how you propose to repay the borrowing, such as through planned sales or by arranging other finance. The plan should fit the project timeline.

These are assessment areas, not a universal checklist. The evidence a lender requests depends on the application. Organising your information around these points can help you explain the proposal clearly.

Why development loan requirements differ between projects

A request to fund a land purchase may focus on the site and your next steps. A new build may need a clear account of the building work, timing and funding stages. A larger project, such as large-scale land subdivisions, can involve more moving parts, so a lender may need detail on how the stages fit together.

Project stage matters too. Early plans may have less detail than a project that’s further along. Lender questions and document requests can change as the plans develop, and lenders may take different approaches. The phrase property development loans in NZ covers a range of funding situations rather than one standard application. Start by organising information around your specific project and what is known at its current stage.

How lenders assess your experience, finances and project plan

A lender looks at how your background and finances fit the project, not just whether the land appears suitable. Property development loan requirements nz can differ between lenders, so use these assessment areas as guideposts rather than a pass-or-fail checklist.

Borrower readiness: What experience, financial commitments and contribution do you bring? Relevant development experience can show how you’ve handled similar work and help a lender understand your role in delivering the project. If this is your first project, that doesn’t automatically rule you out. Each application is assessed on its own circumstances.

Project feasibility: Does the plan appear workable? A clear description of the work, budget and timeline helps explain what you intend to do, how the stages connect and what could affect delivery.

Security: What property or other assets are being offered to support the lending? Owning suitable land may form part of the picture, but it doesn’t guarantee finance. The lender also considers the borrower, proposed work and repayment plan.

Planned repayment: How do you expect to repay the loan? A lender may consider your proposed sale or refinancing plan alongside the project timing and financial assumptions.

How your background and financial position may be considered

Be ready to explain your role in the project and any relevant experience, whether from previous developments or related work. Lenders may also consider your existing commitments and the contribution you can bring to the project. Together, these details give a fuller picture of your borrowing position.

How a lender may review project feasibility and security

A joined-up plan makes it easier to see how the budget, timeline and intended work relate to each other. If an assumption changes, explain why and update any documents it affects. For general property-sector context, Property Council New Zealand shares information about the industry, while lender decisions depend on the individual proposal.

Loan-to-Value restrictions are limits on how much a lender may advance compared with a property’s value. They aren’t a single universal measure of development finance. The lender, project and funding structure can all affect how security is assessed. Mortgage Suite helps organise these parts into a clear application and discuss how to present your circumstances. You can also learn about Mortgage Suite’s approach to supporting borrowers through lending decisions.

Which documents can support a property development loan application?

A well-organised application connects your circumstances with the project plan. For property development loan requirements nz, requested documents vary by lender, project type and stage. Use this preparation checklist as a starting point, then tailor it to the information available for your project. Some items may not apply, and a lender may request other evidence.

Borrower and project information to organise

  • Borrower: Identification, details of your financial position and existing commitments, and information about the project’s ownership structure.
  • Experience: A summary of relevant project history, including your role and examples of completed work, if applicable. This helps explain who will manage delivery.
  • Land or property: Information about the site, its ownership and any existing lending secured against it. A valuation or other property report may also be requested.
  • Project: A short project summary, development plans, timeline, budget and proposed funding schedule. Make clear what work is planned and when funding may be needed.
  • Repayment plan: An outline of how you expect to repay the borrowing, supported by relevant sale plans or proposed arrangements for refinancing, where applicable.

Planning, building and technical documents

Depending on the project, supporting material may include council information, consent documents, architectural or engineering plans, building reports, contractor details and building contracts. For construction, show the costs and timing for siteworks separately from base construction where that distinction helps explain the budget. A staged funding schedule can also show how these items relate to the drawdown process, the release of funds as agreed milestones are completed.

Council requirements and available evidence can differ by project and current council processes. The NZ Government Building Process guide offers information about building a home, including consents and building stages. Documents relevant to a subdivision may differ from those for a single new build.

Check that figures and dates match across your plans, contractor quotes, reports and funding schedule. If a quote changes, update the budget and timeline, or clearly explain the difference. Consistent information gives the lender a clearer view of the proposal and makes questions easier to answer. For more plain-English guidance, explore Mortgage Suite’s Mortgage School lending guides.
NZ Property Development Loan Requirements 2026

How to prepare for lender questions about risk and repayment

Lenders may ask what could change during the project and how you’d respond. Clear answers won’t guarantee approval, but they can show how your budget, timeline and repayment plan fit together.

  • 1. Review your assumptions. Check that your budget reflects the planned work, including expected changes in scope. Note what each estimate is based on and which figures are still provisional.
  • 2. Test the timeline. Set out the main project stages and consider what a delay at each point could mean for later work, funding needs or a planned sale. Record key dates and dependencies rather than relying only on a best-case schedule.
  • 3. Organise your evidence. Keep plans, quotes, reports and funding schedules together, and make sure the figures and dates agree. If an assumption changes, update related documents or explain the difference.
  • 4. Explain repayment. Describe how you expect to repay or restructure the lending and how that plan connects with project progress. Be ready to explain what could affect the timing.

How to present a clear project budget and timeline

Show how the budget lines up with project milestones and when funds may be needed. For example, if site preparation comes before building work, show those stages separately where that helps explain the funding schedule. Flag important assumptions, such as the timing of work, and explain how a change could affect the budget or completion date.

A quantity surveyor report may be useful for some projects, particularly where a lender needs more detail to understand building costs. It isn’t a universal requirement. The aim is to give a consistent, realistic picture of the work, not to suggest that every uncertainty has been removed.

How to explain the repayment or exit plan

An exit plan is how you expect to repay the development loan or restructure the lending. Depending on the project, this could involve selling completed property or arranging a Refinance. Explain the steps behind your proposal, the timing you’re working towards and the evidence that supports it. A lender may consider whether the plan fits the project’s progress, rather than treating a proposed sale or refinance as certain.

If your assumptions or timeline change, update your repayment plan too. Mortgage Suite helps organise project information and present your proposal to lenders. For general borrowing context, you can use the mortgage calculator, but remember that a calculator can’t assess a development project or predict a lender’s decision.

Getting development finance sorted with a clear application plan

Development finance can feel like a lot to pull together, especially when the project is still taking shape. A clear application plan helps you explain what you’re building, what’s already in place and how you expect to repay the borrowing. Property development loan requirements nz vary, so focus on presenting your project accurately rather than trying to fit a one-size-fits-all checklist.

What to prepare before discussing your project

Start with a short summary that gives a lender the essentials. Include:

  • Project type and stage: Explain whether you’re buying land, starting a build or progressing a subdivision, and what has happened so far.
  • Ownership structure: Set out who owns or will own the property and who is involved in the borrowing.
  • Objectives: Describe what you plan to complete and your intended repayment approach.
  • Supporting information: Bring together available financial details, property records, council or planning information, project plans, budgets, quotes and timelines.

Some details may still be developing. Mark estimates clearly and note what could change, so the application doesn’t present an assumption as a confirmed figure. You can read about Mortgage Suite and its approach to helping borrowers with lending decisions.

How Mortgage Suite can help you consider lender options

Mortgage Suite helps organise your information, identify gaps and present your project so its stages and funding needs are easy to follow. We act as your personal advocate, working with you to explain the proposal and negotiate with lenders. This can include mainstream and alternative lending channels, depending on the project and lender fit. Each lender makes its own decision, so finance can’t be guaranteed.

A mainstream-bank decline can be disappointing, but it isn’t necessarily a final judgement on your project or the end of your funding options. Another lender may assess the proposal differently, while still looking closely at its risks and repayment plan. You can read client reviews to learn about other borrowers’ experiences.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to development finance discussions. If you’re preparing an application or reconsidering your options after a decline, Mortgage Suite can help you understand your project-specific funding needs and work out a sensible next step.

Take the next step with a clearer funding plan

Understanding property development loan requirements nz starts with seeing the whole picture. Lenders may assess your experience and financial position alongside the project plan, security and intended repayment. Clear supporting documents, consistent figures and a realistic timeline can help explain how the project fits together. Requirements vary between lenders and projects.

If a mainstream bank has declined your application, that doesn’t automatically mean the project has no funding options. Mortgage Suite helps organise development finance applications and consider mainstream and alternative lending pathways. Founder Krish Krishna brings more than two decades of banking experience to those discussions, with a focus on understanding your circumstances and presenting your project clearly. Approval can’t be guaranteed, but a thoughtful funding conversation can help you identify a practical next step.

Talk through your development finance options with Mortgage Suite. A clear plan can help you approach your next steps with greater confidence.

Frequently Asked Questions

What do lenders look for in a property development loan application in NZ?

Lenders usually assess your experience and financial position alongside the project plan, security and proposed repayment. They’ll want to understand who is managing the work, whether the budget and timeline make sense, what supports the lending and how you expect to repay it. The property development loan requirements nz applicants face vary by lender and project, so prepare clear information rather than relying on a universal checklist.

How much equity do I need for a property development loan?

There’s no single equity amount that applies to every development loan. The contribution a lender expects can depend on the project, its stage, the security available and the funding structure. A lender may consider how your contribution fits with the overall budget and project risks. Before committing to a plan, get guidance on which lender criteria may suit your circumstances.

Can I get a development loan if I have not completed a project before?

Possibly. Being new to development doesn’t automatically exclude you, but a lender may want to understand how the project will be delivered. Explain your role, the experience of others involved and how the work will be managed. A clear project plan, realistic timeline and well-organised supporting information can help a lender assess the application, though they can’t guarantee approval.

What documents do I need for a property development loan?

Documents may include identification and financial details, property and ownership information, project plans, a budget, timeline, contractor quotes and relevant council or planning information. You may also need to explain how you intend to repay the loan. The exact evidence varies by lender and project stage. Keep figures and dates consistent across your plans, reports, quotes and funding schedule.

Do I need council consent before applying for development finance?

Not necessarily in every case. The information a lender requests can depend on the project, its current stage and the relevant council process. You may be asked for council information, consent documents or an update on planning progress, but don’t assume every application follows the same sequence. Set out which approvals or information you have and what remains underway, so the project status is clear.

Can I get a property development loan after a bank declines my application?

Possibly. A decline from one bank doesn’t automatically mean your project has no funding options. The decision may reflect that lender’s criteria or how the application was presented. Reviewing the reasons, project details and available evidence can help clarify next steps. Mortgage Suite assists with development finance and alternative lending options, but each lender makes its own decision and approval isn’t guaranteed.

How are development loan funds released during a project?

Some development or construction finance uses a drawdown process, meaning funds are released in stages as agreed project milestones are completed. The lender’s terms explain how releases work and what evidence may be needed at each stage. The process can vary, so align your funding schedule with the work timeline and allow for the lender’s requirements when planning cash flow.
Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

What if a lower repayment today means paying more interest over time? That’s the trade-off at the heart of debt consolidation home loan nz options. If several bills and due dates are becoming hard to manage, rolling credit-card or personal-loan debt into your mortgage may seem like a straightforward way to get sorted.

It can simplify repayments and may reduce the interest rate on the debt you move, but it also turns shorter-term borrowing into debt secured against your home. Your repayment could fall while the total interest paid rises if you take longer to repay it. You’ll also need enough usable equity, and a lender will assess whether the new loan fits your circumstances.

This guide explains how home-loan debt consolidation works in New Zealand, what to weigh against other ways of managing debt, and what information to gather before discussing your options. Mortgage Suite can help you compare suitable loan structures and navigate lender discussions, with your wider financial goals in view. A mainstream-bank decline doesn’t necessarily end the conversation, but approval is never guaranteed.

Key Takeaways

  • See how a debt consolidation home loan nz may bring eligible debts together, subject to lender assessment.
  • Compare the full loan structure, including security and repayment period, rather than judging the option by the size of the regular repayment alone.
  • Consider separate personal borrowing or keeping debts apart, as each approach can offer different flexibility and repayment terms.
  • Gather your current debt balances, repayment commitments, mortgage details and household income information before discussing options.
  • Learn how Mortgage Suite can help you review suitable lending pathways and prepare for lender discussions, without promising a particular outcome.

What does debt consolidation through a home loan mean in New Zealand?

Keeping track of several repayments, providers and due dates can become a real strain. Home-loan debt consolidation is one way a homeowner may be able to bring eligible debts together with their existing home lending. Usually, this means asking a lender to restructure or Refinance the mortgage and include borrowing to repay selected debts. The lender assesses the application and decides what, if anything, can be included.

Debt consolidation generally means combining multiple debts into one. The home-loan version has a key difference: your mortgage is secured against your property. If other borrowing is added to it, your home may also secure that debt. This can change the consequences if repayments become difficult, so the structure deserves careful thought.

Combining debts doesn’t erase what you owe or guarantee that your total repayments will be lower. It changes how the debt is arranged. The amount borrowed still needs to be repaid, and the new terms, repayment period and lender assessment all affect whether the arrangement suits you. The point of a debt consolidation home loan nz discussion is to understand those trade-offs, not just count the repayments you’d have afterwards.

How is home-loan debt consolidation different from a personal loan?

With home-loan consolidation, eligible borrowing is added to or arranged alongside your mortgage, with the property as security. A separate personal loan is a distinct borrowing agreement with its own repayments and terms. Many personal loans aren’t secured against a home, although arrangements vary. Neither route is always cheaper, quicker or easier to obtain. The lender considers your circumstances and the proposed borrowing.

That security difference matters. If you move debt that wasn’t secured against your property into your mortgage, you’re placing your home behind more of what you owe. A lower regular repayment, if offered, may also reflect a longer repayment period rather than less debt overall.

Which debts might a homeowner consider combining?

Examples could include a credit-card balance or personal borrowing. Whether a lender will consider a particular debt depends on its rules and your circumstances, including the overall loan request and your ability to meet repayments. List each balance and its current repayment so you can see exactly what you’re asking to change.

Home-loan debt consolidation is the process of combining eligible existing debts with home lending, subject to a lender’s assessment, with the property potentially securing the combined borrowing.

How does a debt consolidation home loan work, and what should you weigh up?

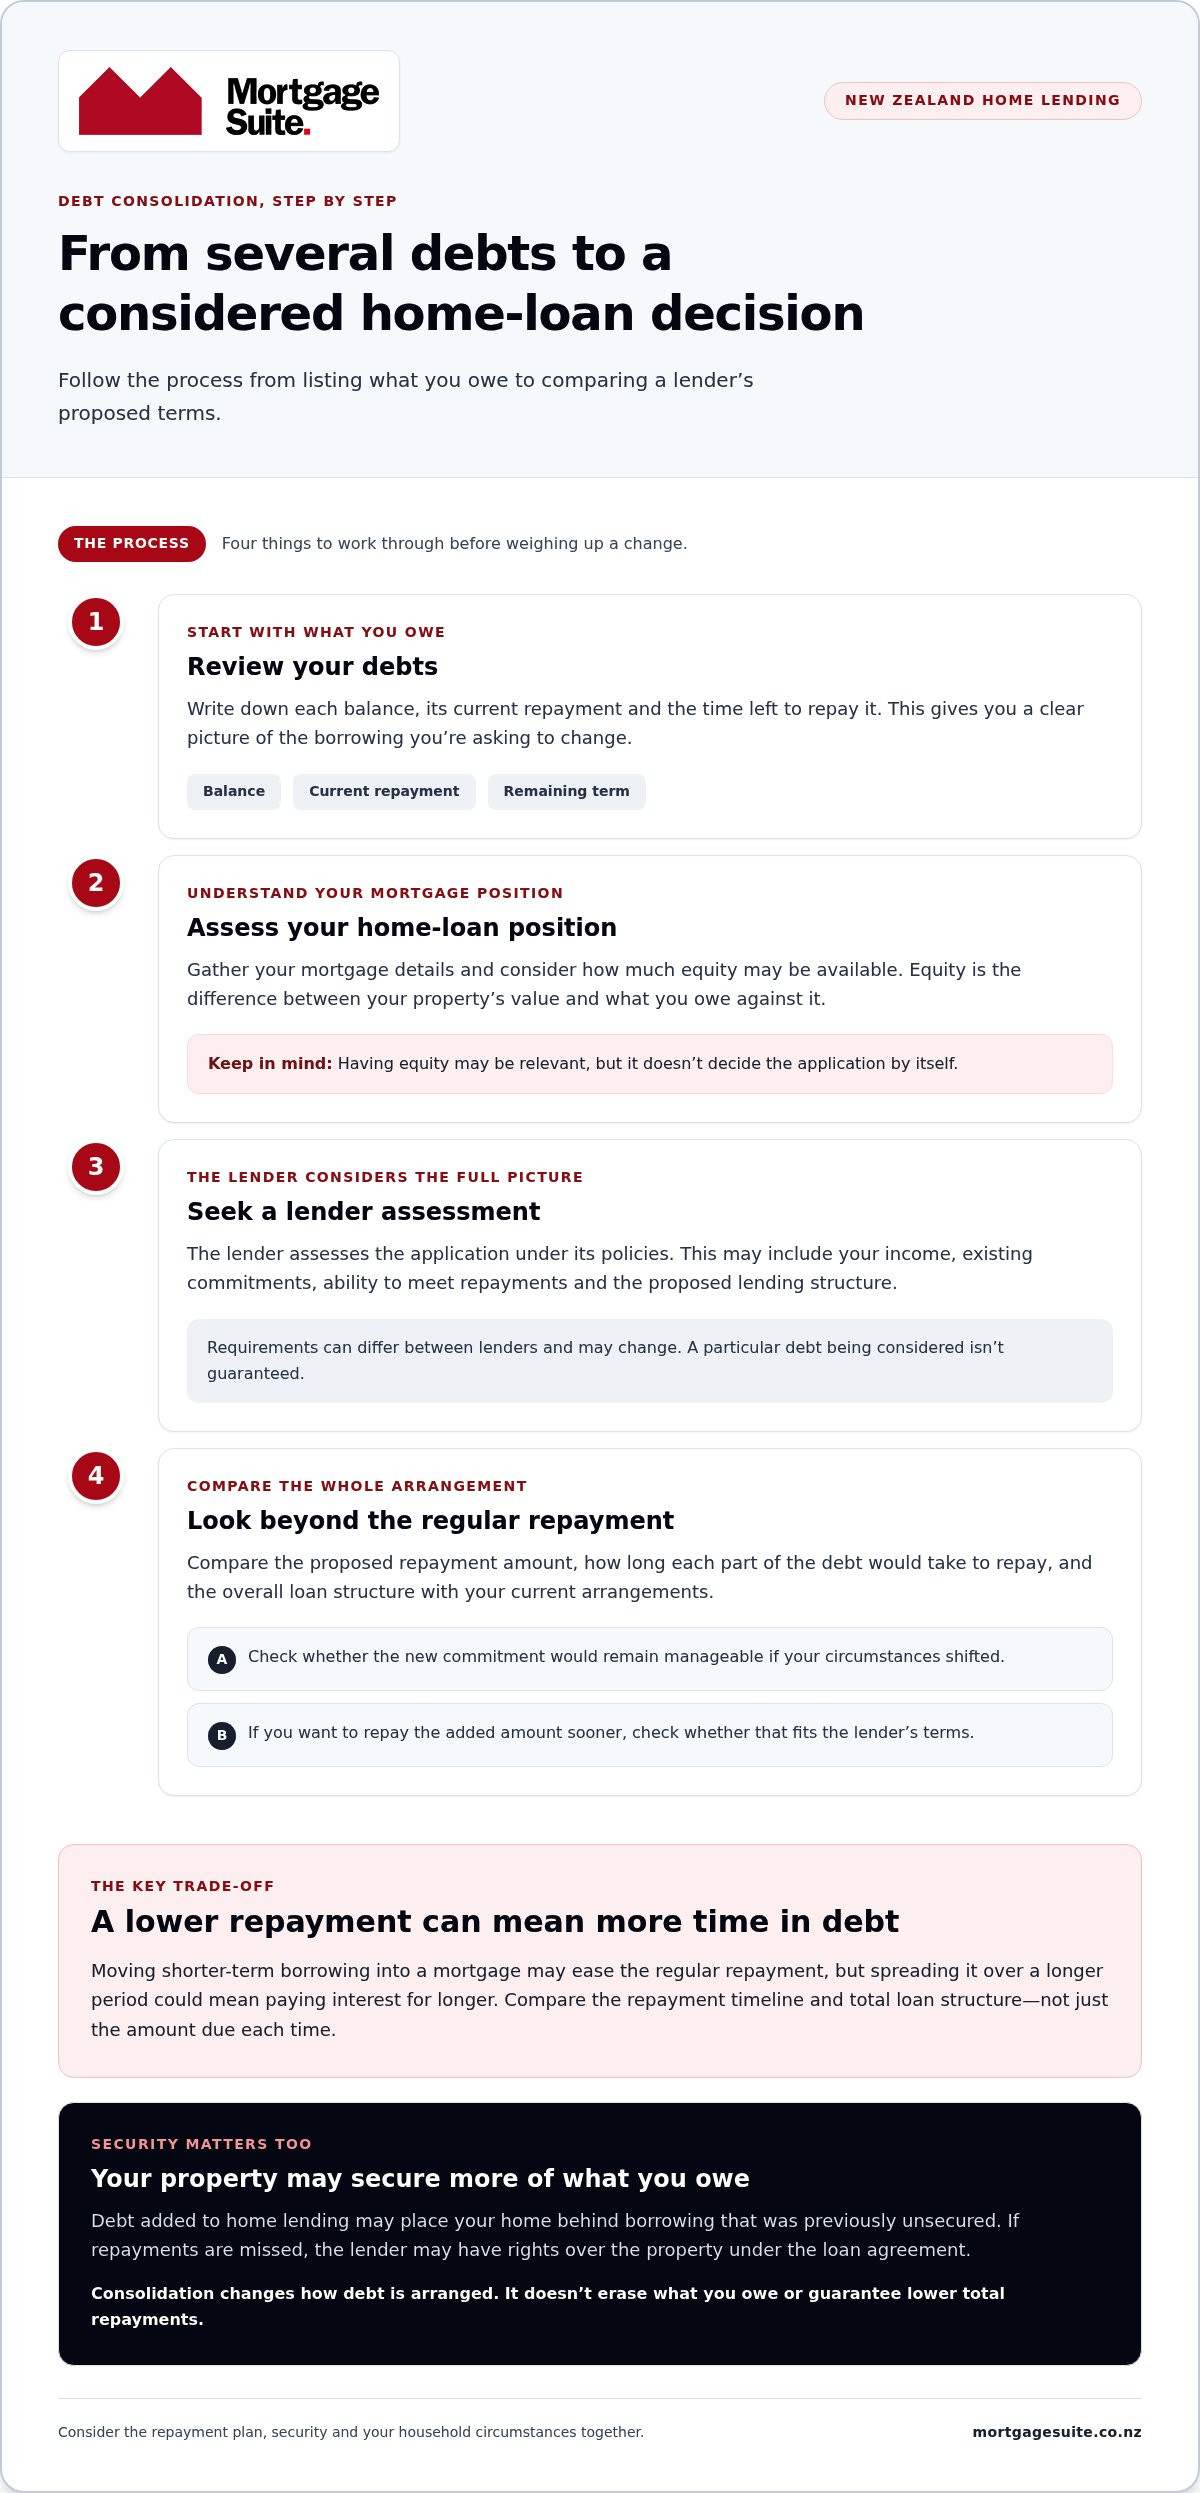
Start with a clear picture of what you owe and what you want the change to achieve. A debt consolidation home loan nz application generally involves reviewing your debts and current mortgage, considering your property position, seeking a lender’s assessment, then comparing the proposed terms with your existing arrangements.

  • Review your debts: Note each balance, repayment and remaining term.
  • Assess your home-loan position: Gather your mortgage details and consider how much equity may be available.
  • Seek lender assessment: The lender considers the full application under its current policies.
  • Compare the terms: Look at repayment amounts, the time to repay and the overall structure before deciding.

Equity is the difference between your property’s value and the amount you owe against it. Having equity may be relevant, but it doesn’t decide the application by itself. A lender may also assess your income, existing commitments, ability to meet repayments and the proposed lending structure. Requirements can differ between lenders and may change, so don’t assume a particular rule applies to every application.

Can a lower repayment mean a longer time paying off debt?

It can. If short-term debts are added to a mortgage with a longer remaining term, the regular repayment may be spread over more time. That could ease pressure on your budget, but you may pay interest for longer. Compare the proposed mortgage timeline with the remaining terms on each debt, and consider whether you can repay the added amount sooner under the lender’s terms.

A smaller repayment doesn’t necessarily mean a shorter loan or less interest overall.

What changes when debts become secured against your home?

Adding debt to home lending can mean your property secures borrowing that may previously have been unsecured. If repayments are missed, the lender may have rights over the property under the loan agreement. This isn’t a reason to rule out consolidation automatically, but it is a material change to consider alongside the repayment plan and your household circumstances.

Before weighing an offer, check what would change, how long each part of the debt would take to repay, and whether the new commitment would remain manageable if your circumstances shifted. A lower repayment can help with cash flow, but it shouldn’t be the only measure of whether the structure suits you. For more plain-English lending guidance, explore Mortgage Suite’s home loan learning resources.

Debt consolidation home loan or another option: how can you compare them?

There isn’t one right choice for every household. Compare the options against what matters to you: a simpler repayment routine, keeping your home-loan structure unchanged, or paying each debt on its own timeline. The table below is a starting point. Actual terms and lender assessment depend on your circumstances.

Option Security Repayment period Flexibility and assessment
Home-loan consolidation Your property may secure the added borrowing. May follow the mortgage term, which could be longer than the original debt’s term. Can bring eligible debts into home lending, subject to lender assessment and available equity.
Separate personal borrowing Often separate from the mortgage, depending on the loan. Set under its own loan terms. Keeps the borrowing distinct; approval and terms depend on the lender and your circumstances.
Keep debts separate Existing security arrangements remain in place. Each debt keeps its current repayment timeline. Preserves the existing mortgage structure, while you continue managing separate repayments.

Compare the whole home-loan structure, not just the interest rate. The type of rate, how long it applies and how repayments are arranged can all matter. Mortgage Suite’s mortgage rates article can provide further context on rate choices and loan structure.

When might adding debt to a mortgage suit a borrower?

If several due dates are difficult to manage, bringing eligible debts into one home-loan arrangement may be worth considering. A simpler repayment routine could help with day-to-day budgeting, but it doesn’t settle whether the option is suitable. Weigh the property security involved and the full time it may take to repay the added debt, alongside your goals and repayment capacity.

When could keeping debts separate be worth considering?

You may prefer to leave your mortgage as it is if you want to preserve its current structure or keep each debt’s balance and repayment timeline clear. Separate repayments can make it easier to see which borrowing you’re paying down. To explore how mortgage repayments may change under different settings, use the mortgage repayment calculator.

The best pathway depends on your equity, ability to manage repayments, goals and the lender’s criteria. Judge a debt consolidation home loan nz option on the full terms, including security and repayment period, rather than the repayment amount alone. If you’d like support weighing up your home-loan options, Mortgage Suite can help you explore a suitable lending pathway.

Debt Consolidation Home Loan NZ: How to Weigh Your Options in 2026

How to prepare for a debt consolidation home loan discussion in NZ

A little preparation can make a debt consolidation home loan nz discussion clearer and more useful. You don’t need every answer before you start. Bring an accurate picture of your finances, then work through what you want the new structure to achieve.

Lender requirements vary, and the information requested will depend on the application. Use this ordered list as a starting point:

  1. List your debts: Write down each current balance, repayment amount and, if you know it, the remaining repayment period.
  2. Gather your mortgage details: Note the outstanding balance, repayment amount, loan term and any fixed interest rate period that applies.
  3. Summarise household income: Include the income details relevant to your household and regular financial commitments.
  4. Set out your goals and concerns: For example, are you hoping to make repayments easier to manage, keep flexibility in the loan, or avoid securing more borrowing against your home?
  5. Check current requirements: Consider the lender’s policies and relevant CCCFA requirements using current guidance, rather than assuming another borrower’s experience applies to you.

What information may help explain your current position?

A clear summary helps show how the different repayments fit into your household budget. A lender may request supporting documents to assess your income, debts and mortgage, but the exact information can vary. If something is uncertain, note it down so it can be discussed rather than guessed.

What questions help you compare a proposed loan structure?

Ask what would change if debts were added to your home loan, including the repayment period, how each part would be structured and whether flexibility would be affected. Clarify how your home would secure the combined borrowing, and compare the proposed timeline with the time left on your existing mortgage and debts. Mortgage Suite’s guide to understanding mortgage rates and home loans can help you get familiar with the terms involved.

It can also help to ask how the lender assessed the proposed repayments and what assumptions apply. That way, you’re comparing the full arrangement, not just the amount due each month. The details matter, and a mainstream-bank decline doesn’t automatically mean there are no other lending pathways to discuss.

Want support organising your questions and weighing up the lending structure? Talk through your home-loan options with Mortgage Suite.

How Mortgage Suite can help you assess debt consolidation home loan options

Deciding whether to combine debts with your mortgage can feel like a lot to work through, especially when the repayments are already hard to keep track of. Mortgage Suite can help you look at the decision in light of your goals, current lending and household circumstances, then compare suitable lending pathways. The focus is on understanding the full structure, not simply aiming for a smaller repayment.

What can an adviser help you think through?

An adviser can help you consider how a proposed change may affect your repayment period, loan structure and use of your home as security. They can also help you understand the information a lender may consider and support you through lender discussions. The right questions depend on your circumstances, so one structure or lender won’t suit everyone.

Mortgage Suite founder Krish Krishna brings more than two decades of banking experience. That background informs a practical, personal approach to discussing home lending, including situations that may need careful explanation. Mortgage Suite works with mainstream and alternative lending channels, but no lender decision or approval can be assured.

What is a sensible next step if you are still unsure?

Before a discussion, bring together your current debt balances and repayments, mortgage details and household income information. It’s also useful to note what you hope to change and any concerns about extending repayments or securing more borrowing against your home. You don’t need to arrive with a finished plan. A clear starting picture makes it easier to talk through the options and what a lender may need to assess.

A decline from a mainstream bank doesn’t necessarily mean every pathway is closed. Different lenders may assess applications under different policies, although another pathway is never a promise of approval. You can also read Mortgage Suite reviews to learn about other clients’ experiences.

Whether you’re weighing up a debt consolidation home loan nz option or simply want to understand your choices, the conversation can start with your priorities and the details of your current lending. If you’d like a supportive discussion without pressure, talk through your home-loan options with Mortgage Suite.

Choose a home-loan structure that fits your next steps

Debt consolidation can make repayments easier to manage, but a lower regular repayment doesn’t automatically mean less interest or a shorter time in debt. Compare the whole arrangement: what becomes secured against your home, how long repayment may take, and whether another option better fits your goals and budget.

Before discussing a debt consolidation home loan nz option, organise your debt balances, repayments, mortgage details and household income information. This gives you a clearer starting point for exploring what a lender may assess and which questions matter most to you.

Mortgage Suite can help you weigh suitable lending pathways and prepare for lender discussions, acting as a personal advocate as you consider your options. Founder Krish Krishna brings more than two decades of banking experience, and Mortgage Suite supports borrowers through mainstream and alternative lending channels. That support doesn’t guarantee approval, but a decline from one mainstream bank doesn’t necessarily close every door.

If you’re ready to explore your options, talk through your home-loan options with Mortgage Suite. A clear, considered next step can help you feel more confident about what comes next.

Frequently Asked Questions

Can I consolidate credit-card debt into my home loan in New Zealand?

It may be possible, depending on your home-loan position, the lender’s criteria and your full financial circumstances. A lender will assess whether the proposed borrowing fits its requirements. A debt consolidation home loan nz arrangement doesn’t make the credit-card debt disappear. It may mean your home secures that borrowing, so compare the repayment period and the change in risk before deciding whether this structure feels right for you.

Is a debt consolidation home loan always a better option than a personal loan?

No, there isn’t one option that suits everyone. Combining debts with a home loan may bring eligible borrowing into one repayment, while a personal loan keeps that borrowing separate from your mortgage. Compare the terms offered, how long repayment may take, your goals and whether you’re comfortable using your home as security. Look beyond the regular repayment and consider how the full loan structure fits your circumstances.

How does debt consolidation through a home loan work?

You start by reviewing your existing debts and home-loan details, then discuss whether a lender may consider restructuring your mortgage or adding borrowing. The lender assesses the application against its criteria and your circumstances. If it offers an option, check how the loan structure, repayment period and security would change before accepting. Requirements and outcomes vary, so making an application doesn’t guarantee approval.

What happens if a bank declines my debt consolidation home loan application?

A decline can feel discouraging, but it isn’t a judgement on your worth or necessarily the end of every possible pathway. The bank may have criteria that don’t fit your circumstances or the proposed loan structure. A mortgage adviser can help you understand the position and discuss whether another suitable route exists. No alternative is guaranteed, so focus on a clear assessment of your finances and realistic options.

Can self-employed borrowers apply for a debt consolidation home loan in NZ?

Yes, self-employed borrowers can discuss their circumstances with a lender or adviser, but the outcome depends on the application and lender criteria. Be ready to explain your income and provide supporting information if requested. The lender will consider the wider picture, including existing commitments and the proposed loan structure. Being self-employed doesn’t automatically rule you in or out; the assessment depends on your individual circumstances.

Will consolidating debt reduce the total amount I repay?

Not necessarily. A lower regular repayment may come from spreading the borrowing over a longer period, which can affect the total interest paid over time. The result depends on the loan terms, repayment pattern and lender assessment. Compare the proposed structure with your current commitments, and ask how long the combined borrowing would remain outstanding. The repayment amount alone won’t tell you whether you’ll repay less overall.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home loan for visa holders in NZ: your 2026 guide

Can your visa allow you to buy a home in New Zealand but still leave a lender unsure about your application? That can happen because eligibility to purchase and mortgage approval are separate decisions. If you’re looking at a home loan for visa holders nz, understanding that difference is a useful first step.

It’s understandable to feel uncertain. Property rules can affect whether you’re allowed to buy, while lenders may assess visa type, income, deposit and supporting documents in different ways. A decline from a mainstream bank isn’t necessarily the end of the road, but no lending pathway can promise approval.

This guide explains how the two decisions fit together, what lenders may look at, how mainstream and alternative lending pathways can differ, and which documents may help explain your circumstances. Mortgage Suite helps borrowers understand their options and present their situation to lenders, so you can have a clearer conversation about possible next steps.

Key Takeaways

  • Check your right to buy a property separately from a lender’s decision to approve a mortgage. They’re different assessments.
  • For a home loan for visa holders nz, be ready to explain your visa conditions, income, debts, deposit source and the property you’re considering.
  • Compare mainstream and alternative lending pathways against your circumstances, as lender criteria and flexibility can vary.
  • Organise your key documents before discussing an application, while allowing for lenders to request different information.
  • A broker can help present your circumstances clearly and negotiate with lenders, but approval depends on the details of your application.

Home loan for visa holders in NZ: separate property eligibility from loan approval

It can be hard to tell whether your visa lets you buy a home and whether a lender will support the purchase. Treat them as two separate questions. First, establish whether you’re eligible to buy the property. Then consider how a lender may assess your finances and circumstances for a home loan for visa holders nz.

Property-purchase eligibility is your legal ability to buy a particular property in New Zealand; loan approval is a lender’s decision about whether your finances can support the borrowing. Meeting one test doesn’t automatically mean you’ll meet the other.

Can visa holders buy residential property in New Zealand?

There isn’t one answer for every visa holder. Eligibility can depend on your visa category, residence history, citizenship, who you’re buying with and the property involved. New Zealand’s overseas investment rules restrict some purchases of residential land. The Overseas Investment Amendment Act 2018 provides background on changes to those rules, but your own circumstances matter.

For example, a residence class visa holder may need consent from the Overseas Investment Office (OIO), the government body that considers certain property purchases, if they haven’t yet met the “ordinarily resident” test. This generally means holding a residence class visa, living in New Zealand for the previous 12 months and being physically present here for at least 183 days during that period. OIO consent is official permission to buy or build a home in cases where the rules require it.

Temporary visa holders are generally restricted from buying a home to live in on their own, but some situations, including buying jointly with an eligible partner, can be treated differently. Australian and Singaporean citizens also have specific exemptions. Check current OIO guidance before making decisions, as eligibility depends on your circumstances.

Why property eligibility does not guarantee a home loan

Even if you’re allowed to buy, a lender makes a separate assessment of whether the loan appears affordable and suitable. It may consider your income and how steady it is, your existing debts, the size and source of your deposit, and the property you plan to buy. Your visa conditions may also affect how a lender views your circumstances. Policies differ, so one lender’s response may not predict another’s.

Keeping the two decisions separate can make the process feel more manageable. A lender’s decision isn’t a verdict on your future, and a decline from one mainstream bank doesn’t necessarily close every pathway. Review what the lender has assessed, identify any details that need explaining, and consider whether another lender’s criteria may fit your circumstances. Property eligibility and borrowing are connected, but each needs its own clear assessment.

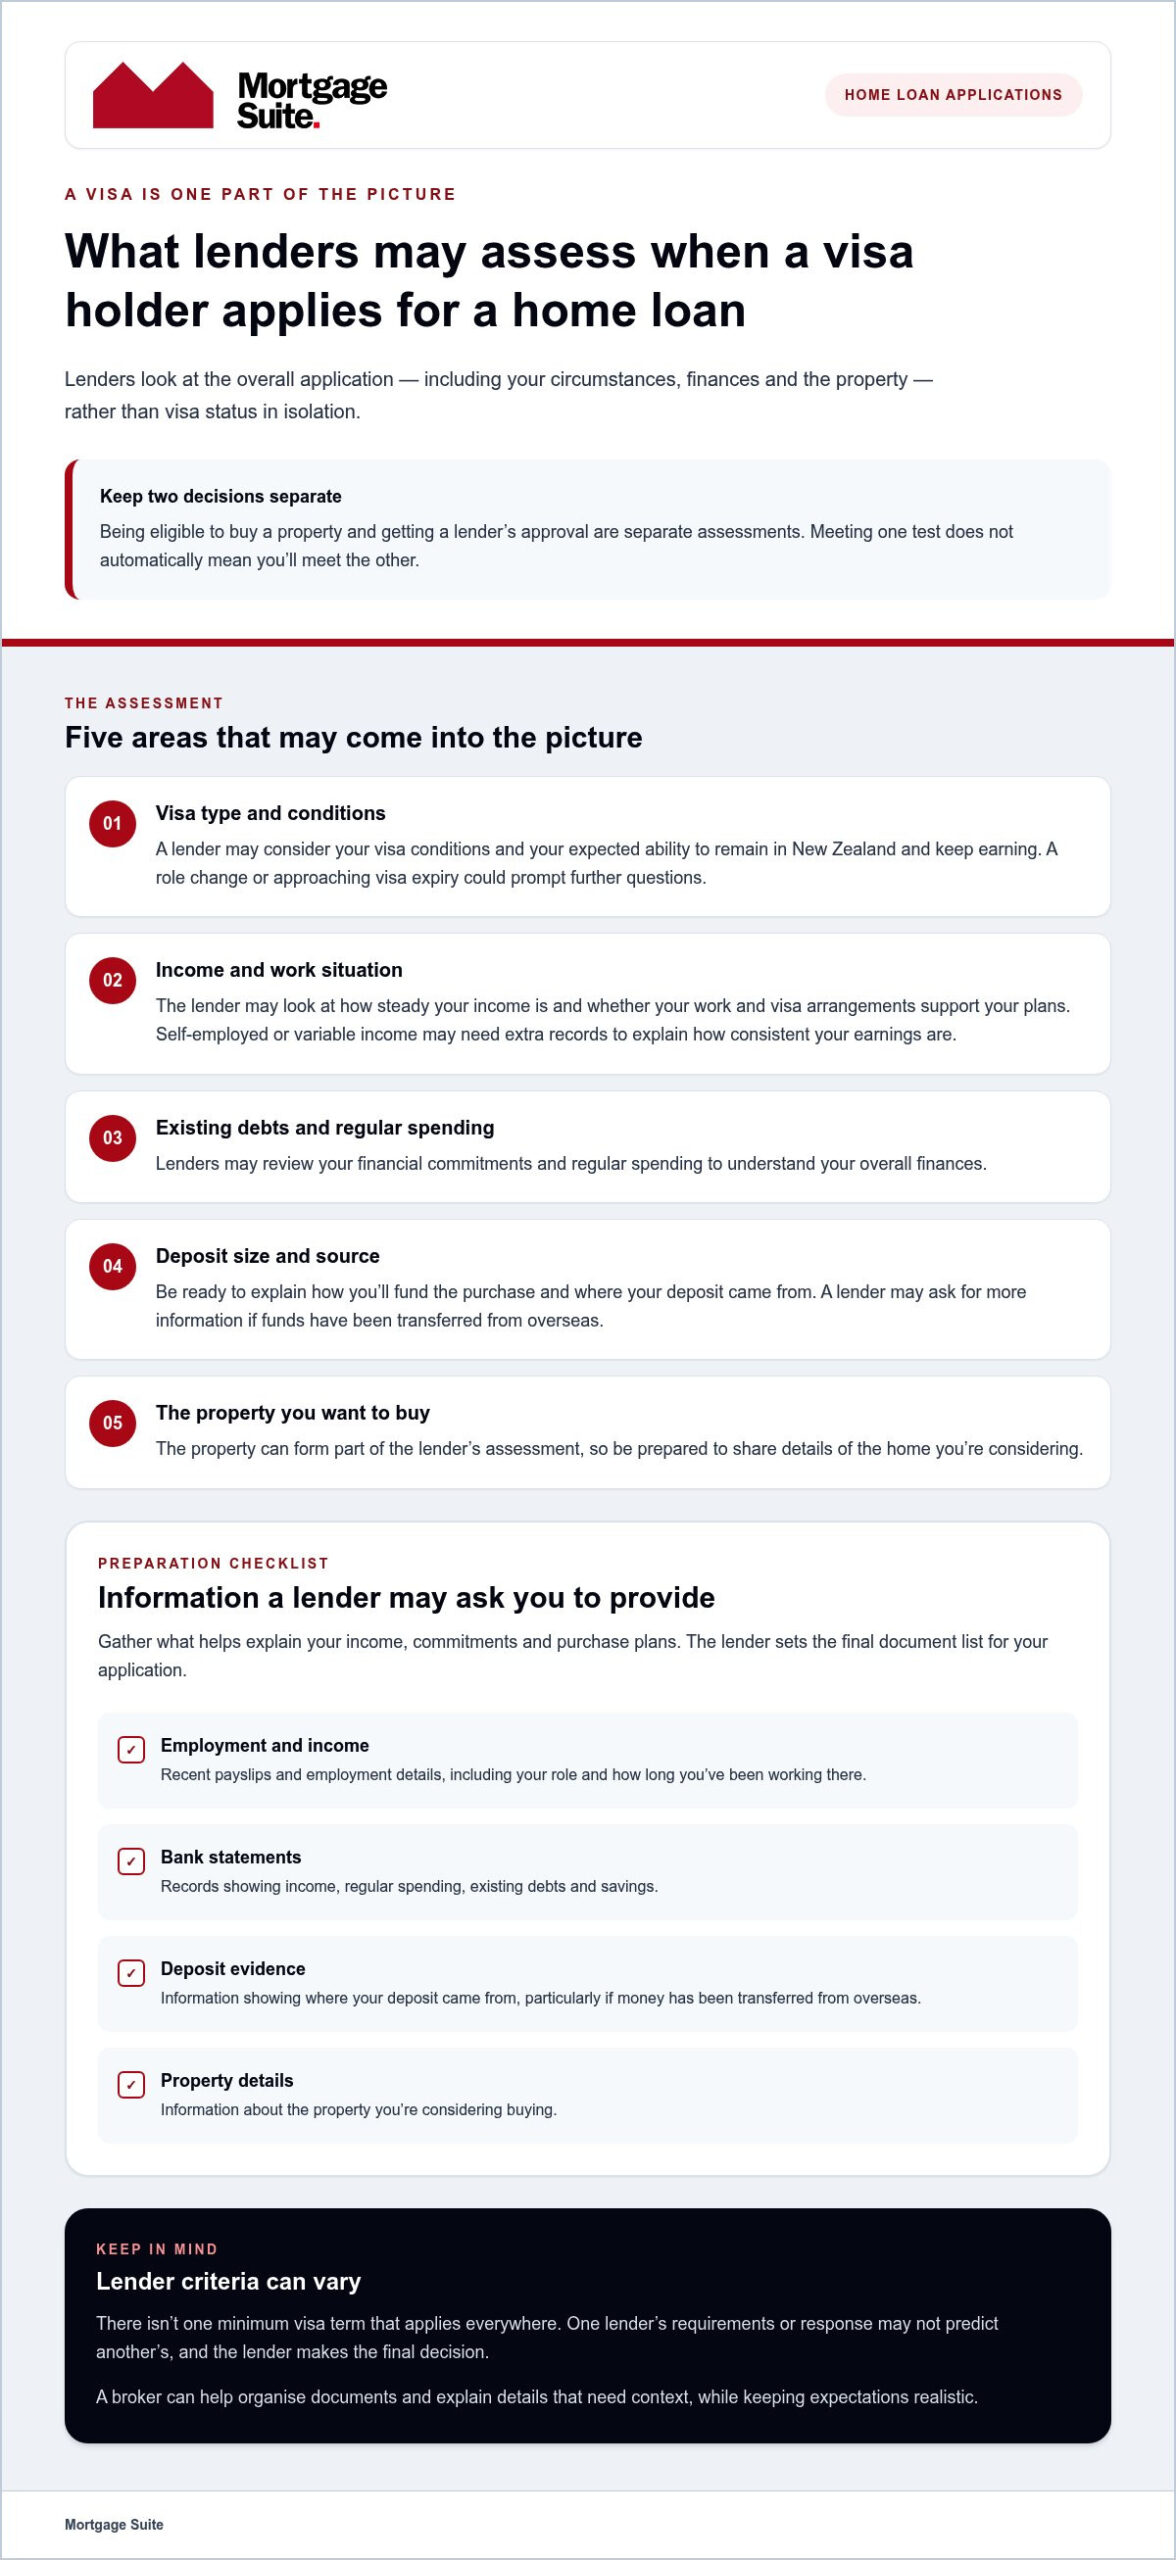
What lenders may assess when a visa holder applies for a home loan

Your visa is one part of the picture, not the whole application. A lender assesses the overall application, not visa status in isolation. It may consider your visa type and conditions alongside your income, work situation, debts, deposit and the property you want to buy. Each lender sets its own criteria, so a requirement applied by one lender shouldn’t be treated as a universal rule.

This is why an application for a home loan for visa holders nz may need a clear explanation of your circumstances. A lender may want to understand how steady your income is and whether your work and visa arrangements support your plans. Questions are part of assessing the application as a whole and don’t automatically mean there’s a problem.

How visa type and remaining visa term may affect an application

Lenders may look at your visa conditions and expected ability to remain in New Zealand and keep earning. Work conditions, a role change or an approaching expiry could prompt further questions, but lender policies differ. Don’t assume there’s one minimum visa term that applies everywhere. The relevant lender’s current criteria determine what it will consider in your situation.

The same applies to named loan pathways. Kāinga Ora’s First Home Loan scheme has its own eligibility criteria, so check the current details rather than assuming a visa alone determines whether you qualify.

Income, deposit and financial records lenders may review

A lender needs a clear view of the money coming in, the commitments going out and how you’ll fund the purchase. Depending on your circumstances and the lender, you may be asked for records such as:

  • Recent payslips and details of your employment, including your role and how long you’ve been working there.
  • Bank statements showing income, regular spending, existing debts and savings.
  • Evidence showing where your deposit came from, particularly if funds have been transferred from overseas.
  • Details of the property you’re considering, as the property can form part of the lender’s assessment.

If you’re self-employed or your income varies, the lender may need extra records to understand how consistent your earnings are. Gather the documents that show your income and commitments clearly, but expect the lender to set the final list for your application. You can also explore plain-English mortgage guidance as you get your information together.

Clear information can make it easier for a lender to assess your application on its merits. A broker can help organise the documents and explain details that need context, while keeping expectations realistic: the lender makes the final decision.

Mainstream and alternative home loans for visa holders: how to compare pathways

There isn’t one lender pathway that suits every visa holder. Mainstream and alternative lenders may assess applications differently, and policies can vary within each group. When comparing a home loan for visa holders nz, look at how the lender’s criteria fit your circumstances, as well as the loan’s repayment structure and flexibility. A headline interest rate alone won’t show whether the overall arrangement suits your plans.

The 2nd tier and non-bank home loans guide explains more about alternative lending. This can be a pathway to explore if your circumstances don’t fit a mainstream lender’s criteria, though suitability depends on your application and the terms available.

What to compare Mainstream lender Alternative lender
Criteria and assessment May apply defined policies to visa status, income, deposit and property details. May consider applications that sit outside some mainstream criteria, with its own assessment requirements.
Flexibility Depends on the individual lender’s rules and how your application fits them. May offer a different way to assess some circumstances, but flexibility isn’t the same across all lenders.
Loan fit Compare repayments, structure and conditions against your needs and plans. Review the full loan terms and repayment commitments, not just the initial rate.

When a mainstream lender may be worth considering

A mainstream lender may be worth exploring if your visa, income, deposit and property plans fit its current criteria. That doesn’t guarantee acceptance. Find out how the lender treats your specific visa circumstances, what evidence it needs and whether the repayment arrangement fits your budget over time. Each lender sets its own requirements, so don’t assume one bank’s policy applies to all.

When an alternative lender may be another pathway

If a mainstream lender can’t assess your application under its usual criteria, an alternative lender may be another option to consider. It won’t suit everyone or guarantee approval, so weigh its assessment approach and loan conditions carefully. Mortgage Suite helps explain possible pathways and present more complex circumstances clearly to lenders. If you’d like support comparing options, talk with Mortgage Suite about your goals and situation.

Home loan for visa holders in NZ: your 2026 guide

How to prepare a home loan application as a visa holder

A little preparation can make a home loan conversation clearer and less stressful. Before comparing lenders, bring together the details that explain your visa, finances and property plans. This gives you a practical starting point for a home loan for visa holders nz, while allowing for lenders to request documents specific to your application.

Build a clear picture of your visa and financial position

Start by checking your property-purchase eligibility for your circumstances. Then organise your information so you can explain your situation consistently. A simple summary of your income, regular commitments, deposit source and intended property can help you spot gaps before you apply.

Depending on the lender and application, useful documents may include:

  • Current visa documents and relevant visa conditions.
  • Recent payslips, employment details or other evidence of income.
  • Bank statements showing regular income, expenses, debts and savings.
  • Information or records showing where your deposit funds came from.
  • Details of the property you’re considering, if you’ve chosen one.

If you’re self-employed or your income changes from month to month, gather records that help explain how you earn and how your income varies. Keep names, dates and other personal details consistent across forms and supporting documents. The lender may ask for more or different information, so use this as a starting checklist rather than a fixed list.

Prepare questions and compare lender fit

Use these steps to get sorted before discussing an application:

  • Clarify purchase eligibility. Understand whether your visa and circumstances allow you to buy the property you have in mind.
  • Map your finances. Note your income, work history, regular expenses, existing debts and deposit source.
  • Organise your records. Bring together relevant visa, employment, income and bank documents.
  • Discuss lender options. Ask how a lender may assess your visa and income circumstances, and what information it needs to consider your application.
  • Compare the whole loan. Look at eligibility, repayment structure, flexibility and communication, as well as the interest rate.

Useful questions can help you understand whether a lender may be a fit: Which parts of my visa or income history need explaining? What documents would help clarify them? How do the repayments and conditions match my plans? For plain-English explanations as you prepare, visit Mortgage Suite’s mortgage education resources.

Mortgage Suite can help you organise your information and discuss lender options without treating one lender’s response as the final word. Talk through your home loan options with a team that can present your circumstances clearly and negotiate with lenders.

How Mortgage Suite can help visa holders explore home loan options

Working out which lender may suit your visa and financial circumstances can feel like a lot to manage alone. Mortgage Suite takes a personal approach: we learn about your goals, understand the details of your situation and consider how your application may fit different lender criteria. This gives you a clearer view of possible next steps without treating a particular loan outcome as certain.

A personal advocate when lending criteria feel hard to navigate

Lender feedback can be difficult to interpret, especially if a decision focuses on one part of your application. A broker can help explain what the feedback means, identify information that may need more context and discuss whether another lending pathway could be worth exploring. A decline from one lender isn’t necessarily a final judgement, but it also doesn’t mean another lender will approve your application.

Mortgage Suite’s founder, Krish Krishna, brings more than two decades of banking experience to conversations about borrowing. That experience supports a practical understanding of how lenders assess applications and how a borrower’s circumstances can be presented clearly. It’s guidance and advocacy, not a promise of approval. You can read more about Mortgage Suite’s team and experience.

What to expect from an initial lending conversation

An initial conversation is a chance to explain what you’re hoping to do and get a clearer picture of the information lenders may need. You can talk through your visa conditions, income, deposit, existing commitments and property plans. If some details are still uncertain, say so. A clear, honest picture helps shape a useful discussion about lender options and what may need attention before an application is presented.

Mortgage Suite can help organise the key details, match your circumstances to potential lender criteria and present your application clearly. Where appropriate, the broker can also negotiate with lenders on your behalf. For a home loan for visa holders nz, this support can help you compare possible pathways and understand what each lender is asking for, while leaving the decision with the lender.

You don’t need to have every answer before starting a conversation. If you’d like to talk through your goals and possible next steps, discuss your home loan options with Mortgage Suite. There’s no pressure to have everything sorted first.

Take your next step with a clearer plan

Buying a home with a visa involves two separate questions: whether you’re eligible to purchase, and whether a lender is prepared to approve your borrowing. Once you understand that distinction, you can focus on the details that shape a home loan for visa holders nz, including your visa conditions, income, deposit and the lender’s own criteria.

Mainstream and alternative lending pathways may suit different circumstances, but neither guarantees approval. Preparing clear information and comparing the full loan structure can help you have a more informed conversation about your options.

Mortgage Suite supports borrowers through mainstream and alternative lending applications, with personal advocacy and lender negotiation. Founder Krish Krishna brings over two decades of banking experience to that work, helping you understand lender feedback and present your circumstances clearly.

Talk through your home loan options with Mortgage Suite and explore possible next steps at your pace. Getting started doesn’t have to be daunting.

Frequently Asked Questions

Can I get a home loan in New Zealand on a work visa?

You may be able to apply, but a lender’s decision depends on your circumstances and its current criteria. A work visa doesn’t automatically mean you can buy a home independently, so check purchase eligibility separately before making plans. Lenders may consider your visa conditions, income, employment history, deposit and other commitments. For a home loan for visa holders nz, both property rules and borrowing requirements need to be considered.

Can temporary visa holders buy a house in New Zealand?

Temporary visa holders are generally restricted from buying a home to live in on their own, but individual circumstances can affect the rules. For example, a temporary visa holder may be able to buy jointly with an eligible New Zealand partner if the property is treated as shared under relationship-property rules. This means it falls within the property-sharing rules for couples. Check current Overseas Investment Office guidance before entering a purchase agreement or assuming an exception applies.

Does a residence-class visa guarantee home loan approval?

No. A residence-class visa may affect whether you’re eligible to purchase, but it doesn’t require a lender to approve a mortgage. The lender will separately assess your income, debts, deposit, ability to manage repayments and the property. Some residence visa holders may also need Overseas Investment Office consent, depending on their circumstances. Confirm purchase eligibility and borrowing requirements as separate steps before committing to a property.

What documents might a visa holder need for a home loan application?

Possible documents include current visa details, payslips, employment information, bank statements and evidence showing where your deposit came from. If you’re self-employed or your income varies, a lender may ask for additional records to understand your earnings. You may also need to provide details of the property you’re considering. The exact documents depend on the lender and your application, so treat this as a starting list, not a universal requirement.

Do all New Zealand lenders assess visa holders in the same way?

No. Lenders set their own criteria, and they may differ in how they consider visa conditions, income, employment history, deposit and property details. One lender’s decision doesn’t necessarily tell you how another will assess your application. Compare more than the interest rate: consider eligibility, repayment structure, flexibility and the information each lender needs. A broker can help explain lender feedback and present your circumstances clearly.

Can I apply for a home loan if a bank has declined my application?

Yes, a decline from one bank doesn’t automatically rule out every other lending option. First, understand the reasons for the decision and whether anything in your application needs clarification or improvement. Lenders assess applications differently, and an alternative lender may consider circumstances outside some mainstream criteria. That isn’t a promise of approval or a suitable route for everyone, but a tailored review can help you understand possible next steps.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Home Loan for Casual Workers NZ: How to Prepare and Compare Options

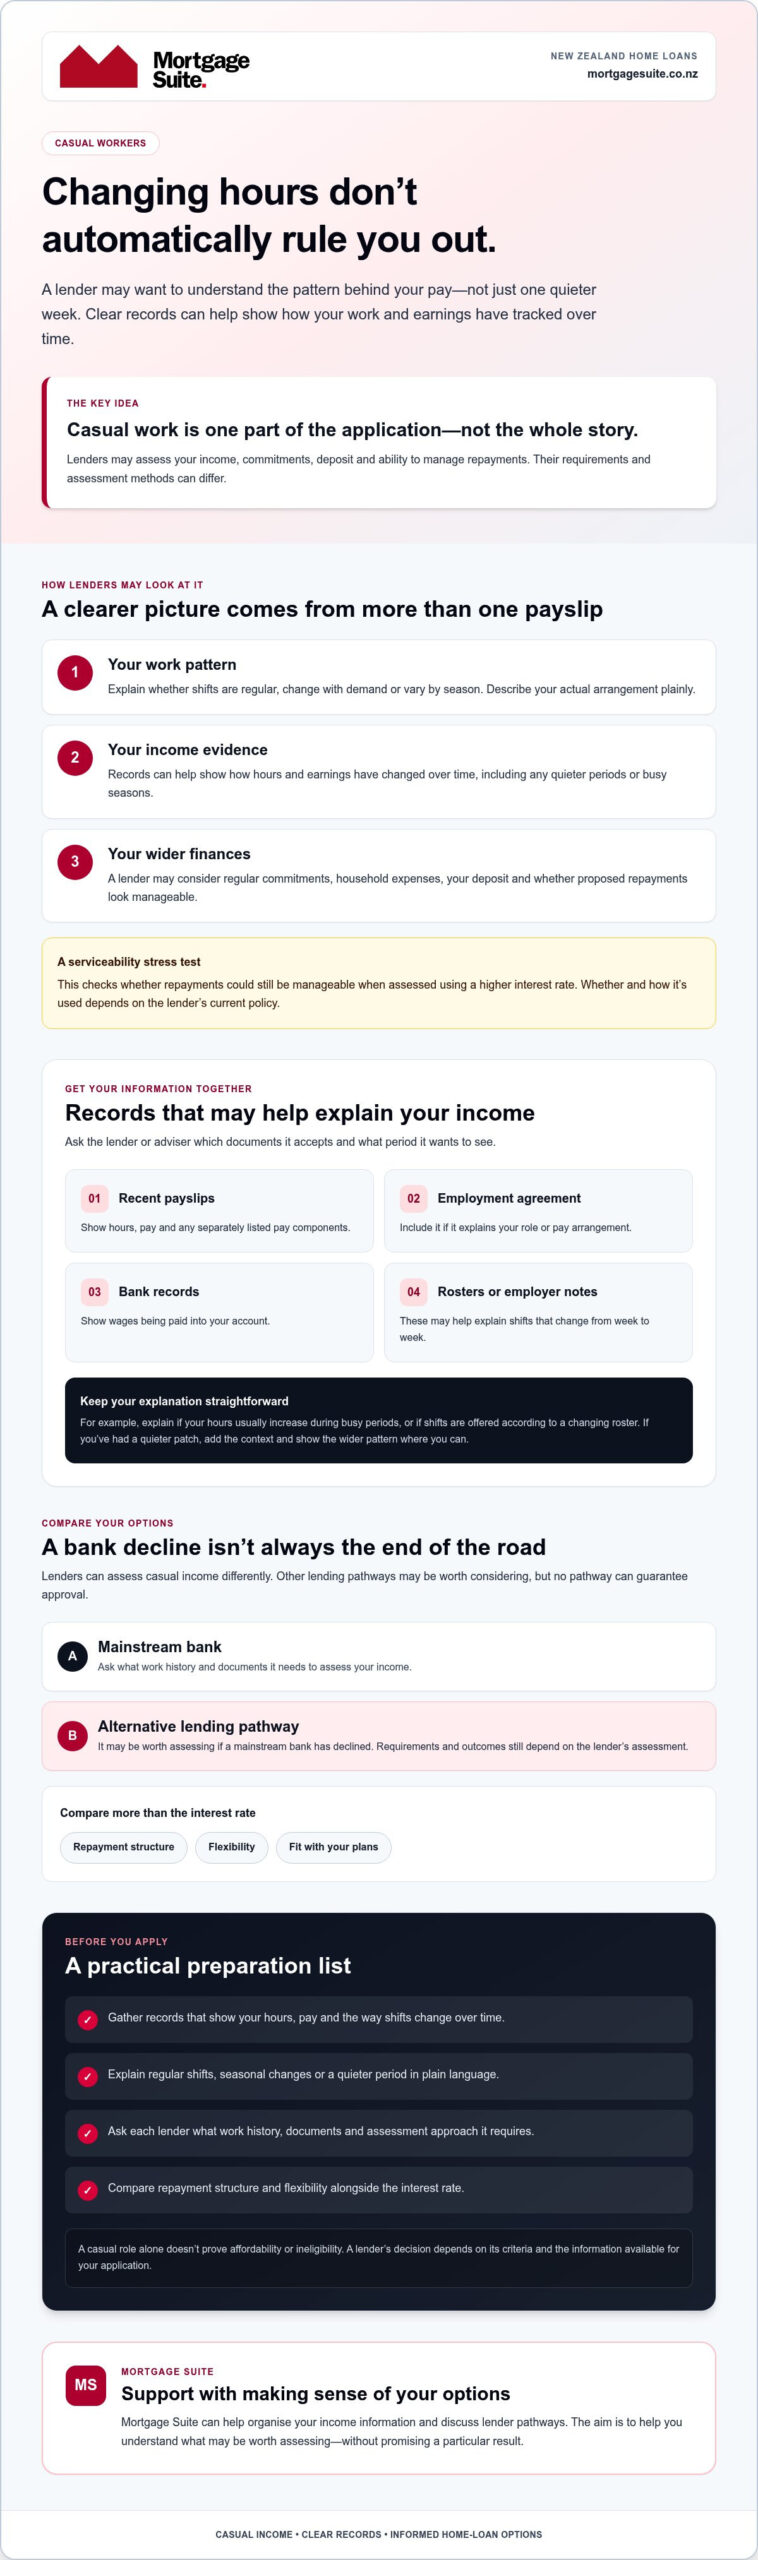
Changing hours don’t automatically rule you out of a home loan for casual workers nz. The key is helping a lender understand the pattern behind your pay, rather than judging your application by one quieter week. If your earnings rise and fall between pay periods, it’s understandable to wonder whether a bank will consider the full picture.

There may be options, but lenders can assess casual income differently and their requirements vary. Clear records of your work and earnings can help explain how your income has tracked over time. A decline from a mainstream bank isn’t necessarily the end of the road, either. Other lending pathways may be worth assessing, although none can guarantee approval.

In this guide, you’ll learn what lenders may look for when reviewing casual income, which documents can help explain your circumstances, and how to compare mainstream and alternative options across New Zealand. You’ll also find practical steps for organising your application and questions to ask before you apply.

Key Takeaways

  • Casual work doesn’t automatically rule you out. Show how your hours and earnings have tracked over time.
  • For a home loan for casual workers nz, gather income records and be ready to explain regular shifts or seasonal changes.
  • Lenders can assess casual income differently. Ask what work history and documents each one needs before applying.
  • Compare mainstream and alternative options by more than the interest rate. Check the repayment structure, flexibility and how each option fits your plans.
  • Mortgage Suite can help organise your income information and discuss lender pathways, without promising a particular result.

Can casual workers get a home loan in NZ? Start with how income is viewed

Changing shifts can make planning a home purchase feel uncertain, especially if your pay varies from one week to the next. But being a casual worker doesn’t decide your home loan application on its own. A lender will assess your income evidence and wider financial situation, and each lender may approach that assessment differently.

Quick answer: Casual workers may be considered for a home loan in New Zealand, subject to the lender’s assessment of their income, commitments and overall ability to manage repayments.

What does casual employment mean when applying for a mortgage?

In everyday terms, casual employment usually means you’re offered shifts or hours as needed, rather than receiving the same set hours every week. Your pattern may still be fairly regular, or it may change with demand, rosters or the season. Describe your actual work arrangement clearly instead of assuming every casual role looks the same to a lender.

A casual employee is paid through an employer, with income recorded through payslips and employment records. A contractor may invoice for work, while a self-employed person generally earns income through their own business. These arrangements can require different ways of showing income, so don’t describe yourself as a contractor if you’re employed casually. If your income comes from contracting or running a business, guidance for self-employed borrowers may be a better fit.

Check that your records make each part of your pay clear. For example, a payslip may list holiday pay separately. The Holidays Act 2003 sets out New Zealand leave entitlements, including rules relevant to casual employees. Keep payslips and other records that explain how your earnings are made up.

Does irregular income automatically mean a home loan decline?

No. Employment type is one part of an application, not the whole story. A lender may also consider the income evidence you provide, your regular financial commitments, your deposit and whether the proposed repayments appear manageable. The information required and assessment method can vary, so ask what the lender needs before assuming how your application will be treated.

Casual employment, by itself, proves neither affordability nor ineligibility. It isn’t a personal judgement on your reliability, either. A lender’s decision reflects its criteria and the information available for your application. If one mainstream bank says no, that doesn’t automatically close off every other pathway. For a home loan for casual workers nz, a clear account of your work pattern and income can help a lender assess the full picture, though it can’t guarantee an outcome.

How lenders may assess casual income for a New Zealand home loan

For a home loan for casual workers nz, a lender may look beyond your latest payslip to understand how your earnings behave over time. It will assess whether the income you can show may support repayments, alongside your other financial commitments. Each lender sets its own criteria, so there isn’t one universal formula or required work history.

What income evidence might a casual worker be asked to provide?

Ask the lender or adviser handling your application which records it accepts and what period it wants to see. Depending on the lender, useful documents may include:

  • Recent payslips showing your hours, pay and any separately listed components.
  • Your employment agreement, if it explains your role or pay arrangement.
  • Bank records showing wages being paid into your account.
  • Rosters or written confirmation from your employer, if these help explain shifts that change from week to week.

Keep your explanation straightforward. For example, you might say that your hours usually increase during busy periods, or that shifts are offered according to a changing roster. If you’ve had a quieter patch, explain the context and provide records that show the wider pattern. Evidence won’t guarantee that a lender accepts all your income, but it can make your circumstances easier to understand.

How do affordability checks fit into the assessment?

Income is only one part of the picture. A lender may also consider regular commitments, such as other loan repayments and household expenses, then assess whether the proposed home loan repayments appear manageable. A serviceability stress test checks whether repayments could still be manageable if calculated at a higher interest rate. Whether and how a lender applies this depends on its current policy, so ask what assessment will be used for your application.

Here’s a simple illustration, not a lending rule: imagine your hours vary between quieter weeks and busier ones. A lender may review the available records to understand that pattern rather than treating one week as your usual income. The documents and method it accepts will depend on its criteria.

If you’re a first-home buyer, you can also check whether the First Home Loan scheme may fit your circumstances, and confirm its current eligibility rules with Kāinga Ora. For an early planning estimate, Mortgage Suite’s mortgage calculator can help you explore repayments. It isn’t a lender decision or a promise of how much you can borrow.

If you’d like help organising your income records and considering lender pathways, explore Mortgage Suite’s home loan support.

Mainstream bank or alternative lender: compare home loan pathways

A mainstream bank is one possible route, but it isn’t automatically the right fit for every casual worker. If your income records show a pattern and explain changes in hours or pay, ask a bank how it would assess your particular situation. Don’t rely on assumptions about a lender’s policy. Criteria and evidence requirements can differ.

Alternative, or second-tier, lending may be worth exploring if your application doesn’t fit a mainstream lender’s approach. It isn’t a guaranteed solution, and the terms need careful review. For a separate explanation, look for a 2nd Tier Lender New Zealand guide alongside the comparisons below.

What to compare Mainstream lender Alternative lender
Assessment fit Ask how it views your casual income and work pattern under its current criteria. Ask whether its approach may better suit your circumstances, and what it needs to be comfortable with the application.
Evidence requested Confirm which income records it accepts and the period it wants to review. Check what documents are needed and how changing hours or pay will be considered.
Flexibility Ask which parts of your circumstances can be considered and what conditions apply. Clarify where the lender may be flexible, and where its requirements remain firm.
Repayment structure Compare repayment choices and how they fit your budget and plans. Review the full structure, including how repayments and conditions may affect you over time.
Questions to confirm “How will you assess my casual income, and what evidence should I provide?” “What are the full terms, conditions and options if my circumstances change?”

When might a mainstream lender be worth approaching?

It may be worth asking a mainstream lender if you can document your earnings and explain why your hours vary. Give a clear account of your work pattern, then check how the lender will treat your casual income before preparing an application based on an assumption. An organised application can help explain your situation, but it can’t ensure a particular decision.

What should you ask before considering an alternative lender?

Ask how income is assessed, which records are required and what conditions come with the loan. Compare the whole arrangement, including repayment structure and flexibility, rather than focusing only on the headline interest rate. A broker can help you compare potential pathways, but can’t guarantee acceptance or remove lender conditions. When assessing a home loan for casual workers nz, make sure the pathway suits both your evidence and your longer-term plans.

Home Loan for Casual Workers NZ: How to Prepare and Compare Options

How to prepare a stronger home loan application as a casual worker

A clear application helps a lender understand your work pattern and your plans. Before you approach lenders about a home loan for casual workers nz, work through these steps to get your information in order.

  1. Clarify your goal. Note what you hope to buy, your preferred timing and what matters most in a home loan.
  2. Gather your records. Collect available payslips, employment terms, bank statements and employer details. Ask which documents the lender wants for your application.
  3. Map your income. Prepare a short timeline of changes in your hours, role or pay, using accurate records. Explain regular shifts or known seasonal changes rather than relying on estimates.
  4. Review your commitments. List regular repayments and household expenses, along with any likely changes to your household circumstances.
  5. Ask about lender criteria. Check how the lender assesses casual income, what evidence it accepts and what else it needs to consider your application.

Build a clear record of your work and income

Arrange your documents so your income is easy to follow. Check that dates, figures and details agree across your payslips, bank records and employment information. If a pay amount differs between records, be ready to explain why. Don’t change or leave out information to make your income appear steadier. A straightforward explanation, supported by accurate documents, gives the lender a clearer picture to assess.

Your timeline doesn’t need to be complicated. It could note when you started a role, when your roster changed or when seasonal work affected your hours. Keep the explanation factual, and confirm with your lender or adviser which records will help with its assessment.

Review your goals and borrowing picture before applying

Think about the property you’re aiming for, your deposit position and the commitments that shape your budget. Consider whether your household income or expenses may change. A repayment calculator can help you explore rough scenarios, but it can’t tell you what a lender will approve. The assessment depends on your circumstances and that lender’s criteria.

For plain-English mortgage learning, explore Mortgage Suite’s Mortgage School resources. You can also use its mortgage calculator to plan possible repayments. Treat both as preparation tools, not a lending decision.

If you’d like support organising your income information and discussing possible home loan pathways, talk with Mortgage Suite about your home loan options.

How Mortgage Suite can help casual workers compare home loan options

Working out which lender may suit your casual income can feel like another job on top of everything else. Mortgage Suite arranges home loans through mainstream and alternative lending pathways across New Zealand. It can help you organise your information, clarify your goals and consider which options may be worth exploring.

For a home loan for casual workers nz, the way you explain your work pattern matters. A broker can help bring together details of your shifts, income records and financial commitments so a lender can consider them in context. They can also help you ask useful questions about lender requirements and compare potential options. The lender still makes its own assessment, and no pathway can guarantee approval.

What to expect from an initial home loan conversation

You can expect to discuss how your work and pay are structured, what records you have, what you hope to achieve and which regular commitments affect your budget. It’s also a chance to identify details to check with a lender, such as which income documents it accepts or how it reviews changing hours. The next steps will depend on your circumstances and the lender’s response.

If you’d like to learn more about the people and approach behind the business, visit the Mortgage Suite About Us page.

How to choose your next step with confidence

Before moving ahead, make sure you have accurate income records and a clear explanation of changes in shifts or pay. Ask prospective lenders how they assess casual earnings, what evidence they need and what conditions may apply. As you compare options, look beyond the headline interest rate. Consider the repayment structure, flexibility and whether the loan terms fit your plans. A broker can help you weigh up those details, but can’t remove lender conditions or promise a particular result.

You may also find it helpful to read Mortgage Suite client reviews as one source of information about others’ experiences. Every borrower’s situation is different, so reviews aren’t a guide to the outcome you’ll receive.

If you’re ready to talk through your circumstances without assuming there’s only one route, talk with Mortgage Suite about your home loan options.

Take the next step with a clearer plan

A home loan for casual workers nz may be possible, but casual status alone won’t determine the outcome. Lenders can assess changing income in different ways, so clear records of your pay and work pattern can help them understand your circumstances. Before you apply, organise your documents, review your regular commitments and ask each lender what evidence it needs.

Compare the full loan option, not just the interest rate. Repayment structure, flexibility and conditions all matter when choosing a pathway that fits your plans. A mainstream bank is one possibility, and alternative lending may be worth assessing if your circumstances don’t fit its criteria. Neither route guarantees approval, but a decline from one lender doesn’t have to be the end of your options.

Mortgage Suite works with mainstream and alternative lending channels and can help you organise your income information and discuss possible next steps. If you’re ready to talk through your situation, talk with Mortgage Suite about your home loan options. Contact Mortgage Suite to discuss your circumstances and possible home loan pathways.

Frequently Asked Questions

Can casual workers get a home loan in New Zealand?

Yes, casual workers may be considered for a home loan in New Zealand, but approval depends on the lender’s assessment of the whole application. A lender may look at your income records, work pattern, deposit, regular commitments and whether repayments appear manageable. Being employed casually doesn’t automatically rule you out. If one lender declines your application, ask why and consider whether another suitable lending pathway is worth exploring.

How long do I need to have worked casually before applying for a home loan?

There isn’t one work-history period that applies to every lender. Some lender guidance refers to six to twelve months of casual employment, but requirements can differ and policies may change. Ask the lender or adviser what history it wants to see and whether your previous work in the same industry is relevant. Prepare accurate records for the period requested rather than assuming a particular length of employment will guarantee an outcome.

What income documents do casual workers need for a home loan?

Ask your chosen lender which documents it accepts and what period it wants to review. It may request recent payslips, an employment agreement and bank records showing wages received. If your hours vary, a roster or employer confirmation may help explain your work pattern. Check that dates and figures match across your documents, and be ready to explain any differences. These records support the assessment, but don’t guarantee that all your income will be counted.

Do banks count casual income when assessing a mortgage application?

Banks may include casual income in an assessment, but how they treat it depends on their criteria and the evidence available. A lender may review your income history and consider how consistent your hours and pay have been, alongside your commitments and overall ability to manage repayments. Ask directly how the bank will assess your income before relying on assumptions. The amount it accepts, if any, is a lender decision, not a fixed rule for all applications.

Can I apply for a home loan if my casual hours change each week?

Yes, you can ask about applying even if your hours change from week to week. Give the lender a clear explanation of your work pattern, including regular shifts or known seasonal changes, and provide records that show how your earnings vary. For a home loan for casual workers nz, the lender will assess your evidence and wider financial circumstances under its own criteria. Changing hours don’t automatically mean a decline, but approval isn’t guaranteed.

What can I do if a bank declines my home loan application?

Ask the bank to explain the main reasons for its decision and whether missing or unclear information affected the assessment. You can then review your records, clarify your income pattern or address other concerns before deciding what to do next. A decline from one mainstream bank isn’t a personal judgement or necessarily the end of your options. Mortgage Suite works with mainstream and alternative lending channels, but another lender will make its own assessment.

Is an alternative lender suitable for casual workers seeking a home loan?

An alternative lender may be worth considering if your circumstances don’t fit a mainstream bank’s criteria, but it won’t suit everyone and approval isn’t assured. Before proceeding, ask how your income will be assessed, what evidence is required and what conditions apply. Compare the full loan structure, repayment arrangements and flexibility, not only the interest rate. A broker can help you consider available pathways, but can’t guarantee acceptance or remove a lender’s conditions.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

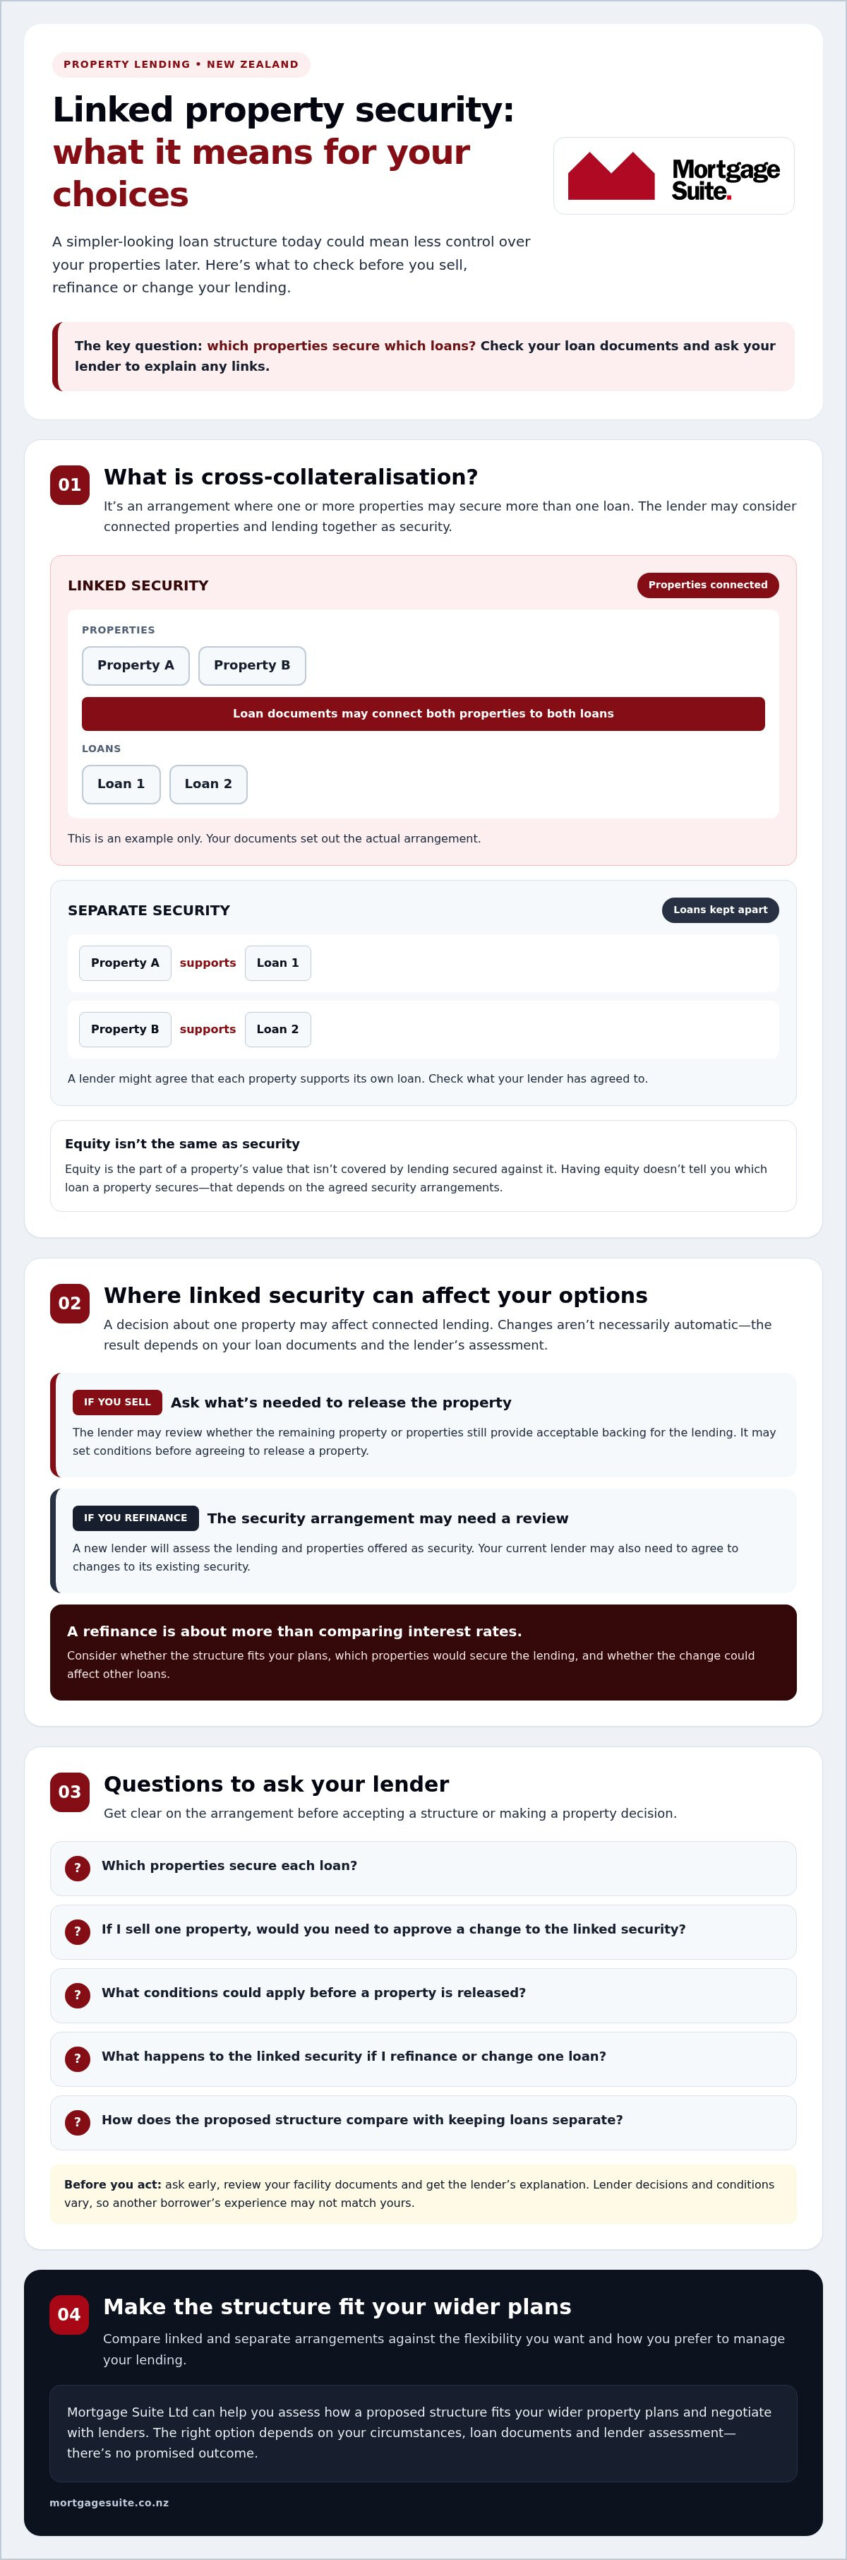
Cross-collateralisation and property loans in NZ: risks, options and next steps

A loan structure that looks simpler today can leave you with less control over your properties tomorrow. If you’re researching cross collateralization property loans nz, you may be weighing the convenience of linking properties against the risk that selling or refinancing one could affect another.

That uncertainty is understandable. When a lender uses more than one property as security, it may have a say in what happens to the linked properties, including how sale proceeds are used. The arrangement can sometimes help a loan proceed, but it may also limit your choices later.

This guide explains how linked property security works in New Zealand, what flexibility you could give up, and how it compares with keeping loans separate. You’ll also find practical questions to ask your lender before accepting a structure or changing an existing one, such as which properties secure each loan and what would happen if you sold or refinanced. With more than two decades of banking experience behind Mortgage Suite Ltd, the team understands how complex lending structures can feel. The aim is to help you make a considered choice that suits your wider property and borrowing plans.

Key Takeaways

  • With cross collateralization property loans nz, more than one property may secure lending, so check exactly which properties are linked to each loan.
  • Before selling or refinancing, ask your lender whether it needs to approve changes to the linked security and what conditions may apply.
  • Compare linked and separate loan arrangements against your plans, including how much flexibility you may want and how you prefer to manage your lending.
  • Use the article’s questions to prepare for a conversation with your lender or mortgage adviser, especially about releasing a property from linked security.
  • Mortgage Suite Ltd can help you assess how a proposed structure fits your wider property plans and negotiate with lenders, without promising a particular outcome.

What does cross-collateralisation mean for property loans in NZ?

Cross-collateralisation is an arrangement where one or more properties may secure more than one loan. In everyday terms, a property gives the lender backing for the money it lends. If you’re looking up cross collateralization property loans nz, the key point is that the properties and loans may be connected, rather than each loan relying on just one property.

For a neutral overview of the underlying idea, see Cross-collateralization. The exact arrangement for your lending depends on your loan documents and what the lender has agreed to. Don’t assume that a property secures only the loan you associate it with; check the paperwork or ask your lender to explain it.

How can one property secure more than one loan?

Think of a borrower with two properties and two loans. The lender might agree that each property supports its own loan. Or the lending documents may connect both properties to both loans, so the lender considers them together as security. These are simple examples, not a guide to what your own documents say.

Linked security can involve more than one property, more than one lending facility, or both. Your loan documents set out the actual arrangement, so review them and ask the lender which properties support each loan if anything is unclear.

Is cross-collateralisation the same as using equity?

No. Equity is the part of a property’s value that isn’t covered by lending secured against it. A lender may consider available equity when assessing a borrowing request, but equity alone doesn’t tell you which property secures which loan. That depends on the agreed security arrangements.

For example, you may have equity in a property, but that doesn’t confirm whether it supports one loan or is linked to other lending as well. If you’re considering a residential property purchase or already have a rental property, the article Residential Investment Property Loans NZ offers wider context on borrowing for this purpose. For your own position, check the loan documents and ask the lender to clarify any links before making plans around a property.

How cross-collateralised property loans can affect your options

A property decision can affect connected lending because the lender may have agreed to rely on more than one property as security. If you want to sell, Refinance or change one loan, the lender may need to review the arrangement and approve a change to the linked security. The result depends on your facility documents and the lender’s assessment, so don’t assume a change will happen automatically.

What could happen if you sell one linked property?

Before you commit to a sale, ask the lender what must happen for the property to be released from the security arrangement. It may assess whether the remaining property or properties still provide acceptable backing for the lending. Depending on your loan terms and circumstances, the lender may set conditions before agreeing to release a property.

Ask for the requirements early, and check your facility documents alongside the lender’s explanation. Lender decisions and conditions vary, so another borrower’s experience may not match yours. Consumer Affairs also outlines How cross-collateralization works, including why connected security can affect a borrower’s choices.

Could linked security affect a refinance?

It can. If you’re considering moving your lending to another lender, the existing security arrangement may need to be reviewed as part of the process. The new lender will assess the lending it’s being asked to take on and the properties offered as security. Your current lender may also need to agree to changes to its existing security.

That means a Refinance involves more than comparing interest rates. Consider whether the proposed structure fits your plans, what properties would secure the lending, and whether you could manage the change without affecting other loans. If commercial lending is involved, Commercial Property Refinance NZ is a relevant topic to explore alongside advice from your lender or mortgage adviser.

In short, a decision about one property can affect connected loans, so confirm the conditions before you act. If you’re unsure how your current or proposed structure fits your plans, you can talk through your property lending options with Mortgage Suite Ltd. That conversation can help you identify what to ask your lender, without assuming a particular outcome.

Cross-collateralisation vs separate property loans: what should you compare?

There’s no single structure that suits every borrower. Linked security may make it simpler to manage several loans with one lender, while separate security can make each property’s role clearer. Your choice should reflect your plans and the lender’s assessment, not just how the arrangement looks on paper.

Use this table as a starting point. The practical details, including whether a property can be released or a loan changed, depend on the lender and your loan documents. Confirm each point for your own situation.

What to compare Linked security Separate security
Flexibility A change involving one property may require the lender to review the connected lending. Each property may have a clearer link to its own loan, but changes still depend on lender approval and loan terms.
Administration Coordinating lending with one lender may feel more straightforward, though the security links can be harder to keep track of. It may be easier to see which property supports which loan, but separate arrangements can mean dealing with more than one facility or lender.
Future plans Consider whether linked security fits your plans to sell, refinance or change a loan. Consider whether a more distinct arrangement fits plans to sell, refinance or change ownership of a property.
What to confirm Ask which properties secure each loan and what conditions apply to changing that arrangement. Ask whether separate security is available and what each loan would require.

Linked security can simplify how lending is arranged, but separate security may offer more clarity and control over each property. That’s the central trade-off to weigh up when comparing cross collateralization property loans nz.

When might linked security suit a borrower?

It may suit someone who values coordinating lending across several properties with one lender and expects to keep that structure in place. But convenience doesn’t guarantee approval or better terms. Suitability depends on your plans, the loan documents and the lender’s assessment. Ask what flexibility you would retain if your circumstances change.

When might separate security be worth discussing?

If you may sell, Refinance or change ownership of a property, ask whether separate arrangements could make each property’s role easier to understand. Separation may not be available or accepted in every case, so confirm the lender’s position before deciding. For questions about how lending documents relate to property matters, you can consult a property solicitor or find information through the New Zealand Law Society Property Law Section.

Cross-collateralisation and property loans in NZ: risks, options and next steps

Questions to ask before accepting or changing linked property security

Before you agree to link properties or change an existing arrangement, get a clear picture of what the lender is asking you to accept. If you’re comparing cross collateralization property loans nz, take these questions to your lender or mortgage adviser and ask for answers in plain English:

  1. Which properties secure each loan? Ask for a clear list of the properties and loans involved, including any lending facility you may have overlooked.
  2. What needs to happen to release a property? Ask what conditions apply, whether the lender must approve the release, and how it would assess the remaining security.
  3. What if I sell or Refinance? Find out how either step could affect the other loans and what you need to arrange before proceeding.
  4. How would future borrowing fit? Ask whether taking on another loan could change the security arrangement or affect your current lending.
  5. Can the security be changed later? Check the process and conditions for separating properties or changing which property supports a loan.
  6. Are there alternatives? Ask whether separate security is possible for your circumstances, and what trade-offs the lender sees.

What to check in your loan documents

Find the documents that describe your loans and the properties connected to them. Look for the sections covering security, changes, releases and lender consent. If a clause is unclear, ask the lender to explain what it means for your situation. Don’t rely on a verbal summary alone; make sure you understand what the documents say before agreeing to a change.

Who can help you assess the structure?

A mortgage adviser can help compare possible loan structures against your borrowing goals and future property plans. A solicitor can explain the legal obligations and property-security documents. These roles are different: an adviser can discuss lending options, while a solicitor can provide independent legal advice. This guidance isn’t a substitute for having a solicitor review documents that affect your property.

For straightforward mortgage learning, visit Mortgage Suite’s Mortgage School. If you’d like support weighing a proposed structure against your plans, explore your property loan options with Mortgage Suite. Getting clear answers first can help you make a considered decision and feel more confident about your next step.

How Mortgage Suite can help you assess property loan options in NZ

Linked security can feel hard to untangle, especially if you have several properties, existing loans and plans that may change. Mortgage Suite can help you look at the full picture: how your current lending is arranged, what you want to do with your properties, and whether you may need to borrow again later.

Mortgage Suite acts as your advocate and negotiator with lenders. It isn’t the lender or a guarantor, and no particular lending outcome can be promised. Depending on your circumstances, the team can consider options through mainstream and alternative lending channels, then help you understand what questions to put to the lender about the proposed structure. If you’re researching cross collateralization property loans nz, the aim is to make the options clearer before you decide what fits your plans.

What to prepare for a lending conversation

A few notes and documents can help make the discussion more useful. Gather what you have, and don’t worry if you’re still trying to find out how a particular loan is secured.

  • Loan documents and any recent lender correspondence that describe your current lending or security.
  • Basic details of each property involved, and which loans you think may be connected to it.
  • Your upcoming plans, such as buying another property, selling, refinancing or changing how a property is owned.
  • Questions about what the lender may require to change or release security, and what conditions need to be confirmed.

Being clear about both your current position and what you hope to do next gives an adviser a better starting point. Your lender’s requirements still need to be confirmed directly, and a solicitor can explain legal documents and obligations.

Explore your options with a mortgage adviser

A conversation can help you compare possible structures against your goals, identify trade-offs and work out which details still need an answer from your lender or solicitor. If your plans include a rental property, you may also want to read Residential Investment Property Loans NZ for related borrowing context.

Mortgage Suite was founded by Krish Krishna, who brings more than two decades of banking experience. If you’d like a calm discussion about how your existing lending and future property plans fit together, talk through your property lending options. There’s no need to have every detail sorted before you start.

Make your next property lending decision with clarity

Cross-collateralisation can make lending feel more straightforward, but linked security may affect your choices if you want to sell, Refinance or change a loan. Before deciding, check which properties secure each loan, what your lender requires to release a property, and whether the structure fits your future plans. Separate security may be worth discussing too, though it won’t suit every situation.

If you’re weighing up cross collateralization property loans nz, remember that the right structure depends on your circumstances and lender approval. Review your loan documents, ask for unclear terms to be explained, and seek independent legal advice about your obligations.

Mortgage Suite can help you compare lending options and prepare questions for lenders. Founded by Krish Krishna in 2000, the business draws on his more than two decades of banking experience and works with mainstream and alternative lending channels. Mortgage Suite can act as your advocate and negotiator, but it can’t promise a particular outcome.

Talk through your property lending options and take a considered next step. You don’t need every answer before starting the conversation.

Frequently Asked Questions

What is cross-collateralisation in property loans?

Cross-collateralisation is when a lender uses one or more properties as security for more than one loan. In plain English, the property gives the lender backing for the money it lends. For example, two properties could be linked to two loans rather than each property supporting only one loan. The actual arrangement depends on what you and the lender have agreed, so check your loan documents to see which properties secure each loan.

Is cross-collateralisation risky?

It can affect your flexibility, but the impact depends on your loan structure and plans. Linked security may help you coordinate lending with one lender, while reducing the independence of each property. A sale, refinance or change to one loan could involve a review of connected security. If you’re researching cross collateralization property loans nz, ask your lender what the arrangement means for your specific loans rather than assuming it will have the same effect for everyone.

Can I sell a property that is cross-collateralised?

You may be able to sell, but first check whether the lender needs to approve a change to the security arrangement. It may assess the remaining properties and lending before agreeing to release a property. What happens next depends on your loan documents, lender requirements and circumstances. Before committing to a sale, ask what conditions apply, what information the lender needs, and whether any connected loan arrangements could be affected.

Can I refinance one loan if my properties are cross-collateralised?

You can ask about refinancing one loan, but linked security may affect how the lender reviews the change. The existing lender may need to consider whether its security arrangement will change, and a new lender will assess the lending and security proposed. Requirements differ between lenders and loan structures. Before making plans, check your facility documents and ask both your current lender and mortgage adviser what steps or conditions may apply.

How can I find out which properties secure my loans?

Start with your loan documents and look for the sections that describe the security and the properties involved. If the wording isn’t clear, ask your lender to identify which property secures each loan and explain the arrangement in plain English. A mortgage adviser can help you understand the lending structure, while a solicitor can explain legal wording and obligations. Don’t rely on assumptions based on which property you associate with a particular loan.

Can I ask a lender to separate cross-collateralised loans?

Yes, you can ask whether the lender will separate the loans or change which properties secure them. Whether it agrees depends on the lender, your loan documents and your circumstances. The lender may assess the proposed structure and the security that would remain for each loan. Ask what information it needs, what conditions apply and whether the change could affect other lending. A mortgage adviser can help you compare options, but the lender makes the decision.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Is Your Mortgage Working With Your Household Budget… Or Against It?

Is Your Mortgage Working With Your Household Budget… Or Against It?

Mortgages are often one of the biggest monthly expenses in any household budget.

But they shouldn’t leave you feeling like every dollar is already spoken for!

Your mortgage needs to work for your household budget.

While interest rates are an important part of that equation, there are other things to consider when deciding whether your mortgage is structured in a way that actually works for your day-to-day budget.

Let’s dive into the ways you can make your mortgage feel more manageable.

Signs Your Mortgage Isn’t Working For You

One of the biggest warning signs that things aren’t working well is when your mortgage makes it feel difficult to manage the rest of your finances.

That could mean your repayments leave very little room for unexpected expenses, or you are regularly relying on a credit card to get through to payday. But it could also be something less drastic than that. Perhaps:

  • Your repayments don’t line up with when you get paid
  • You have underutilised savings
  • You don’t have ready access to an emergency fund
  • Your fixed mortgage doesn’t give you any flexibility to make additional repayments
  • Your floating portion is larger than it needs to be
  • Your repayments are manageable now, but you are worried they may become unaffordable if interest rates increased.
  • Your financial circumstances have changed since you originally arranged your mortgage

None of these things necessarily mean you have the wrong mortgage. But they could be signs that it is time to take another look at your options.

What Can You Do About A Problematic Mortgage?

The good news is that there are always options. Your mortgage does not have to be a one-and-done transaction. You can review it at any time to see if there are things you can do to make it less problematic for your household budget.

These are some of the options:

1: Consider your repayment frequency

Changing from monthly to fortnightly repayments can help some families manage their cash flow more effectively. This is especially true if you line your repayments up with your pay cycle.

Selecting a payment frequency isn’t about getting the repayments as low as possible; it’s about finding a schedule that naturally works with the way your household income arrives and your expenses are paid.

2: Think about fixed and floating

Fixing your entire mortgage provides payment certainty, but it can also limit your flexibility. Having a portion of your mortgage on a floating rate can give you more freedom to make extra repayments or access funds.

It is important to remember that floating rates are generally higher than fixed rates, so this option may not be suitable for everyone. But for some families, splitting between fixed and floating portions can give you a useful balance between certainty and flexibility.

3: Could an offset account help?

If you have regular funds sitting in a savings account, an offset mortgage could potentially help reduce the amount of interest you pay.

Instead of your savings simply sitting in a separate account, an offset arrangement can link eligible accounts to your mortgage, meaning you may only pay interest on the difference between your mortgage balance and the money you have available in those accounts.

This can be particularly useful for keeping your emergency funds accessible, but still reducing the amount of interest that is calculated on your mortgage.

4: Review Your Mortgage Term

Your lender will have issued a date for when your mortgage funds need to be repaid by. But this date is not necessarily set in stone; depending on your age and circumstances, you may be able to change that end date.

Extending the term can reduce your repayments and potentially ease your monthly cash flow, while shortening it can help you pay the loan down faster when your budget allows. Either can be good options depending on your circumstances.

5: Don’t Forget Your Emergency Fund

Paying every spare dollar into your mortgage might look like a good option. But what would happen if you had an unexpected expense pop up?

A broken-down vehicle, an urgent home repair, or a change in income can quickly put pressure on the household budget. Keeping an emergency fund can give you a financial buffer and reduce the need for expensive forms of credit when something goes wrong.

The amount of money each family would need in an emergency fund varies, but a good estimate is three months’ worth of expenses.

Help Is Always Available

There is not one mortgage structure that works for every household budget.

Your ideal setup will depend on your income, expenses, financial goals, tolerance for risk, and your plans for the future. A structure that works brilliantly for one household might be completely unsuitable for another.

That’s where an experienced mortgage adviser can help you.

Rather than simply looking at the interest rate, we look at the bigger picture. We explore how your mortgage fits with your household budget, when your fixed terms expire, whether splitting your lending could help, and whether an offset account would work for your family.

We can also review your mortgage should your circumstances change. A pay rise, new family member, career change, renovation, or an updated financial goal can all be good reasons to revisit your structure.

Is Your Mortgage Helping Or Hindering Your Budget?

Your mortgage should be more than just a repayment that you suffer through each month. It should be something that fits into your wider financial life.

If you are constantly feeling squeezed by your repayments, or you are simply wondering whether your current structure is the right fit for you, it is time for a mortgage review.

At Mortgage Suite, our friendly team can look at your individual circumstances and help you understand the options that are available to you.

Get in touch with us today and let’s make sure your mortgage is working with your budget, not against it.

Second mortgage for business in NZ: how it works in 2026

Could business funding put your home at risk, even if you already have a mortgage? For some Kiwis, a second mortgage for business NZ may provide access to property equity without replacing an existing home loan. But it adds another loan secured against the property, so weigh the funding need against the security and repayment risks.

It’s understandable to feel cautious. You may be comparing a second mortgage with a business loan or refinancing, while considering whether your business income and circumstances will meet a lender’s requirements. If the property has to be sold to repay debt, the first mortgage lender generally has priority over the second mortgage lender. Understand how that could affect your options and have a realistic repayment plan before proceeding.

This guide explains how a second mortgage works in 2026, what lenders may assess and what information to prepare. It also sets out questions to ask about repayments, property security and your plan to repay the loan, so you can compare funding paths and make a considered decision.

Key Takeaways

  • A second mortgage for business NZ adds lending secured against property that already has a mortgage, so check how the existing loan’s priority may affect your options.
  • Before proceeding, consider whether the business can manage repayments and what could happen to the property if it can’t.
  • Compare a second mortgage with a term loan or refinancing by checking the security required, repayment structure and impact on existing lending.
  • Prepare accurate business financial information, details of existing lending and a clear plan for repaying the loan.
  • An adviser can help you weigh up the risks and discuss lender options suited to your circumstances, without guaranteeing approval.

What is a second mortgage for business in NZ?

A second mortgage for business is an additional loan secured against property that already has a mortgage. The property could be a home or business property, and the funds are intended for business needs. The second mortgage sits behind the existing mortgage in the order of security. You can read a neutral overview of what a second mortgage is, then check how a particular lender would structure and secure the loan.

In general, the first mortgage has priority over a later registered mortgage. If the property had to be sold to repay debts, the first lender would usually be paid before the second mortgage lender. The exact position can depend on registered interests and the loan documents, so confirm the details with the lender and an appropriate legal adviser before proceeding.

Using the funds for a business doesn’t change the fact that the property is security for the loan. If repayments aren’t maintained, the property offered as security could be at risk. Weigh the business purpose against the possible impact on your home or commercial property, and consider whether the business could still meet repayments if expected income is delayed.

How does a second mortgage differ from a first mortgage?

A first mortgage is usually the main loan secured against a property. A second mortgage is separate lending added while that first mortgage remains in place. The second lender’s position behind the first may affect how it assesses the property, existing lending and available security. Ask how the proposed loan would be recorded and what could happen if repayments fall behind.

Don’t assume the order or enforcement process based on a general explanation alone. Ask the lender to explain its terms and have the relevant documents checked if you’re unsure.

What business needs might prompt this type of lending?

A business owner might explore a second mortgage to cover a working capital gap, buy equipment or act on a business opportunity. These are examples of possible purposes, not a promise that a lender will approve the application. The lender will consider what the funds are for alongside the property security and the borrower’s wider circumstances.

Business-purpose borrowing is different from a home loan taken out to buy or refinance a home, even if the home is offered as security. Be specific about how the funds will be used and where repayments are expected to come from. If a mainstream bank has declined, that isn’t necessarily the end of the conversation. Other lender pathways may be worth discussing, though each has its own assessment.

How does a business second mortgage work, and what is at risk?

Taking out a second mortgage involves more than showing that a property has equity. The lender needs to understand what the business will use the funds for, what property will secure the loan, how existing lending affects that security, and how repayments are expected to be made. Review the proposed terms carefully, including the repayment schedule and what happens if payments are missed.

When property secures business borrowing, the borrower remains responsible for repayments and the property may be at risk if they aren’t made. That’s true even when the loan is intended to support business growth rather than a personal purchase.

  • Explain the purpose: Be ready to describe what the funds will pay for, when they are needed and how the spending supports the business.
  • Review the security: Discuss the property, existing mortgage and any other lending secured against it.
  • Test the repayment plan: Consider how the business will meet repayments if income is delayed or lower than expected.
  • Check the terms: Ask about the repayment schedule, the loan’s end date and any conditions that could affect your plans.

How does the second mortgage sit alongside existing lending?

More than one loan can be secured against the same property. As a general guide, the first registered mortgage has priority over a later one. If the property is sold to repay debts, the first lender is generally paid before the second. The exact position and any steps a lender can take depend on the registered interests, loan documents and applicable law.

Check your existing mortgage documents and ask the relevant lenders whether consent is needed and how the new loan could affect your current arrangements. A qualified legal professional can explain the implications for your particular circumstances. Don’t rely on a general article to settle those details.

What happens if the business cannot keep up with repayments?

If repayments fall behind, arrears can build and the lender may take steps under the loan terms and applicable law. The outcome depends on the circumstances, so don’t assume every lender will respond in the same way. Because the property secures the borrowing, it could ultimately be at risk.

If repayment pressure appears, contact the lender or your adviser early to discuss the situation and possible next steps. For consumer credit, the Commerce Commission explains the transfer of responsibility for regulation of consumer credit. Whether a business-purpose loan falls under consumer credit rules depends on the circumstances, so confirm what applies to your loan.

If you’re weighing up a second mortgage for business NZ, Mortgage Suite can help you discuss the funding need and possible lender pathways. Its mortgage learning resources explain lending terms to help you prepare for a conversation.

Second mortgage vs business loan or refinance: which path fits?

The right option depends on what the business needs, whether property can be offered as security, your existing lending and how repayments could fit your cash flow. A second mortgage for business NZ is one path to discuss, but it isn’t automatically the best fit. Compare the security and repayment structure, the impact on current lending and the consequences of missed payments, not just the amount you may be able to borrow.

Option Security Common use Questions to ask
Second mortgage Property that already secures an existing mortgage. Seeking further business funds while keeping existing lending in place. How does it sit alongside the current mortgage? What property is at risk, and how will repayments work?
Business term loan Depends on the lender and loan terms. Ask whether property or other security is required. A business funding need with a lump sum and a defined repayment schedule and end date. What security is required? How often are repayments due, and when must the loan be repaid?
Refinance Usually involves new lending secured against property or other agreed security; confirm the proposed arrangement. Replacing or restructuring existing lending, often with a different deal or lender. What happens to the existing loan terms? Will the new structure meet the business need and repayment plan?

When might a second mortgage be worth exploring?

You might raise this option if you want to seek extra funds while keeping your current mortgage in place. That’s a discussion point, not a recommendation or a sign that you’ll qualify. Ask the lender to explain how the existing loan affects its assessment, and compare proposed repayments with the business’s expected cash flow. If a mainstream lender’s criteria don’t fit, the Mortgage School guide to lending options may provide further context.

When should you compare a business loan or Refinance instead?

Compare a business loan if you want to understand whether its security and repayment structure could suit your business without adding another mortgage to a property. Terms vary between lenders, so check the details rather than assuming the loan is unsecured. Refinance means replacing or restructuring existing lending, often with a different deal or lender. It may be worth comparing if you’re open to changing your current arrangement. Mortgage Suite can help you discuss business and commercial finance pathways, but the lender will assess your circumstances.

Before choosing, ask each lender to set out the security, repayment schedule, loan end date and implications for existing lending. Mortgage Suite’s Mortgage School learning resources offer plain-English explanations of lending terms to help you prepare those questions.

Second mortgage for business in NZ: how it works in 2026

How to prepare before applying for a business second mortgage

A clear application starts with a clear picture of the business need and how the loan could be repaid. Before discussing a second mortgage for business NZ, work through these steps:

  • Define the purpose: Set out what the funds would pay for and how the spending supports the business.
  • Gather your records: Collect current business accounts and income information, along with details of existing loans.
  • Review the property: Note which property may be offered as security and share relevant ownership or mortgage details.
  • Plan repayments: Map likely repayments against realistic business cash flow and consider how you’d manage if income changed.

Preparation helps a lender understand your request, but it doesn’t guarantee approval. The property, business income and lender criteria all need individual assessment. Accurate records make the discussion clearer, particularly if your income or business circumstances don’t fit a straightforward pattern.

What information should a business owner gather?

Start with up-to-date business accounts, income records and a short explanation of the funding purpose. Add details of current loans, repayments and any property you may offer as security. Be ready to explain how the business expects to use the funds and where repayments will come from. Requirements vary, so ask the lender or adviser for the exact document list before you apply.

Accuracy matters. If figures have changed or trading has been uneven, explain that rather than leaving gaps for the lender to interpret. A broker may help organise the information and discuss which lender pathways could suit your circumstances, though the lender makes its own assessment.

How can you test whether repayments are manageable?

Set out expected repayments alongside the business’s regular income and commitments. Allow for ordinary business needs, existing debt repayments and household commitments where relevant. Then test a less favourable scenario: what if a customer pays late, sales fall or an unexpected business expense arrives? If the plan only works when everything goes smoothly, revisit the amount or structure before proceeding.

The Mortgage Suite calculator may help with general repayment planning. It isn’t a quote or assessment for a business loan, so confirm actual terms and repayments with the lender.

For help discussing business funding needs and possible lending pathways, contact Mortgage Suite about business finance.

Choosing your next step with a New Zealand business finance adviser

Before moving ahead, check that the proposed borrowing matches a real business need and a repayment plan you can explain. Weigh up the security being offered, the risk to the property and alternatives such as a business loan or changing existing lending. A second mortgage for business NZ may be worth discussing, but the right path depends on your circumstances and the lender’s assessment.

An adviser can help organise the facts, present your situation clearly and discuss possible lender options. That support can be useful if your income or business history doesn’t fit a mainstream bank’s usual approach. But advice can’t guarantee a lender will make an offer, set particular terms or approve an application.

What should you ask before accepting an offer?

Take time to understand the offer before you commit. Ask which property secures the borrowing, how repayments are scheduled and when the loan ends. Make sure you understand the conditions and what the lender may do if repayments are missed. If any legal wording or implications are unclear, consider getting independent legal advice before signing.

Then compare the proposed structure with your business plan and other funding paths. Would the repayment plan still make sense if income is delayed? Does the loan solve the need you identified, or could another arrangement better fit your longer-term plans? Ask the lender to explain anything you’re unsure about.

How can Mortgage Suite help you assess possible pathways?

Mortgage Suite arranges business and commercial finance, as well as second-tier lending for situations that may not fit mainstream bank criteria. Its founder, Krish Krishna, has more than two decades of banking experience. A discussion can help you set out the funding purpose, existing lending and repayment plan, then consider which lender pathways may be worth exploring. Each lender makes its own assessment, so there’s no guaranteed outcome.

You can learn more about Mortgage Suite’s background and approach and read client reviews of Mortgage Suite as part of your research.

Before speaking with an adviser, it may help to have your funding purpose, current loan details and repayment plan to hand. You can then use the discussion to consider possible next steps without committing to proceed.

Make your next business funding decision with care

A second mortgage for business NZ may be one way to seek business funds, but it also puts property security and repayment commitments in the picture. Before proceeding, be clear about what the funds are for, how repayments could fit your business cash flow, and whether a business loan or refinance might better suit your needs.

Mortgage Suite facilitates business, commercial property and second-tier lending solutions, including for borrowers whose circumstances may not fit mainstream bank criteria. Founder Krish Krishna brings more than two decades of banking experience to lending conversations. That experience can help you discuss your circumstances and possible lender pathways, but it can’t guarantee an offer, particular terms or approval.

If you’re ready to explore your options, talk through your business lending options with Mortgage Suite. A clear conversation can help you decide what to consider next, at a pace that feels right for you.

Frequently Asked Questions

What is a second mortgage for business in New Zealand?

A second mortgage for business in New Zealand is an additional loan secured against property that already has a mortgage. The property could be a home or business property, depending on the lender’s requirements. The existing mortgage generally has priority over the later one, but the details can depend on registered interests and loan documents. A second mortgage for business NZ still puts the property at risk if repayments aren’t maintained.

Can I use a second mortgage to fund my business?

Yes, a second mortgage may be used to fund a business purpose, such as working capital or a business opportunity, if a lender is willing to offer that structure. The lender will assess the purpose of the borrowing, the property offered as security and your circumstances, including how repayments are expected to be made. Using a home as security doesn’t make the borrowing a home loan, so ask the lender to explain the proposed terms.

Can I get a second mortgage if my bank has declined my business loan?

Possibly, but a bank decline doesn’t mean another lender will approve a second mortgage. Lenders may assess applications differently, and some specialist or second-tier lenders consider situations that don’t fit mainstream bank criteria. They’ll still assess the security, business purpose, repayment plan and your wider circumstances. A finance adviser can help you understand potential lender pathways, but can’t promise an offer or approval.

What property can be used as security for a business second mortgage?

A lender may consider residential or business property, but the type of property it accepts depends on its criteria and the details of the application. Existing mortgages and other claims registered against the property can affect the assessment. Before applying, gather information about the property and current lending, then ask the lender whether it may be acceptable security and whether any existing lender’s consent is needed.

Is a second mortgage riskier than a business loan?

It depends on the security and terms of each option. A second mortgage is secured against property, so missed repayments could put that property at risk. A business loan may have a different security arrangement, but it isn’t automatically unsecured or lower-risk. Compare the repayment schedule, loan end date, security and consequences of missed payments for each offer, and consider how the structure fits your business plan.

How much can I borrow with a second mortgage for business?

There’s no set amount that applies to every borrower. A lender will assess the property and existing lending, the business’s financial position, the requested purpose and its own criteria. The amount offered, if any, will depend on that individual assessment. Prepare accurate business income records and details of current loans, then ask the lender to explain how it arrived at any proposed amount and repayment terms.

What happens if I cannot repay a business second mortgage?

If you can’t make repayments, contact the lender as early as possible and explain what’s changed. Missed payments may lead to arrears and other steps under the loan terms and applicable rules. Because the loan is secured against property, that property could ultimately be at risk. Ask the lender or an adviser about your options and seek independent legal advice if you’re unsure what the loan documents mean.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Good Debt vs Bad Debt in NZ: How to Tell the Difference

A mortgage can be called “good debt”, but that label doesn’t tell you whether repayments will fit your life. The real question behind good debt vs bad debt nz is whether borrowing supports a goal without putting too much pressure on your day-to-day finances.

It’s understandable to feel unsure. A home loan may help you buy a home, while borrowing for everyday spending or something that loses value can leave less room in your budget. But the purpose alone doesn’t decide whether debt is right for you. Your repayments, income, plans and ability to manage change all matter, too.

This guide will help you weigh those factors without judging yourself or past choices. You’ll find a practical way to review borrowing you already have or are considering, and questions to ask before a home-loan discussion. Mortgage Suite founder Krish Krishna brings more than two decades of banking experience to conversations about different borrowing needs. A thoughtful discussion can help you explore suitable options, without treating a bank’s first response as the final word.

Key Takeaways

  • In good debt vs bad debt nz, the label matters less than whether borrowing supports a goal and stays manageable for your household.
  • Compare a loan’s purpose with its repayments, flexibility and the effect it could have if your circumstances change.
  • Use five questions about purpose, repayment fit, flexibility, future plans and downside risk to review borrowing before you commit.
  • Look at all your household commitments together, rather than judging a new loan on its own.
  • If repayments feel difficult, gather your loan details and contact your lender early to ask what options may be available.

Good debt vs bad debt in NZ: what does the difference mean?

Borrowing can feel stressful, especially when people talk about debt as if it’s automatically good or bad. The label doesn’t tell you whether a loan suits your household. A more useful question is whether the borrowing supports a goal you’ve thought through and whether you can manage the repayments alongside your other commitments.

In this guide to good debt vs bad debt nz, “good debt” means borrowing that may help you work towards a considered goal while staying within your means. “Bad debt” describes borrowing that puts ongoing pressure on your finances or offers little lasting value. These are descriptions of how debt may affect your circumstances, not judgements about you or your choices.

Why the purpose of borrowing matters

Borrowing to buy a home is different from borrowing for a short-lived treat. A home loan may support a long-term housing goal, while borrowing for discretionary spending can leave repayments after the purchase or experience has passed. Neither purpose alone makes a loan right or wrong for every household.

For example, one household might consider a home loan because buying suits its plans, while another borrows for a holiday it can’t comfortably afford. The first still needs to check the repayments and future flexibility. The second may find repayments restrict everyday choices. Looking at debt as part of personal financial planning, including your budget and spending, can help put that decision in context.

Purpose describes what borrowing is for; affordability describes whether your household can manage the repayments.

Why the label is not the whole story

A mortgage may help you buy a home, but it can still become difficult if repayments leave too little room for regular bills, unexpected needs or changes in income. The goal may matter to you, yet the loan still needs to fit your budget over time.

Small or short-term borrowing can also build pressure when several repayments add up. A business loan might support a business goal, or it might strain cash flow. A personal loan or mortgage also needs to be considered in light of its purpose and terms. No loan type is automatically good or bad.

So, when weighing up good debt vs bad debt nz, look beyond the name of the loan. Consider what it helps you do, what you’ll need to repay and how those commitments could affect your household’s choices.

How good debt and bad debt affect goals, repayments and choices

To compare borrowing fairly, look beyond what the money is for. Consider whether the loan supports a goal, how repayments fit your household budget, how much room you have if plans change and what you might need to give up to keep up with payments.

Manageable repayments matter just as much as the reason for borrowing. A home, vehicle or business purchase doesn’t guarantee future value or a financial benefit. Its value may change, and your circumstances can change too. Use the table as a starting point, not a fixed rule.

Potentially supports a goal May create ongoing pressure
Borrowing is tied to a considered goal, such as buying a home to live in. Borrowing repeatedly covers discretionary spending, with repayments continuing after the spending is over.
Repayments fit alongside household bills and other commitments. Repayments squeeze the budget or leave little room for unexpected changes.
You understand what could happen if income or plans change. You may need more borrowing to keep up with existing commitments.

When a home loan may support a longer-term goal

A home loan may help you work towards buying a place to live, but it’s still a major commitment. Consider how repayments would fit with regular household spending and whether they’d remain manageable if your income changed or other costs increased. First-home buyers can read this mortgage calculator guide to help prepare questions about repayments before discussing a home loan.

Consider the full picture: your income, existing repayments and plans for the coming years. A property purchase doesn’t guarantee that its value will rise or that it will suit your needs indefinitely. The aim is to assess whether the borrowing works for your circumstances, not just whether the goal sounds worthwhile.

When borrowing can become difficult to manage

Warning signs can include missed repayments, relying on further borrowing to cover existing commitments, or finding that repayments leave too little for everyday needs. These signs aren’t a judgement on you. They’re a reason to pause, review what’s going out and consider what support or changes may be available.

Repeated borrowing for discretionary spending can gradually reduce your flexibility, even if each decision seemed manageable at the time. Several repayments together may take up room you’d otherwise have for bills, savings or changing plans. In good debt vs bad debt nz, the useful distinction is how borrowing affects your goals and choices over time, not simply what kind of loan you have.

A practical NZ framework for comparing good debt with bad debt

A simple framework can help you compare borrowing without relying on labels. Use these five questions to assess how a loan fits your household and what it could mean for your choices over time:

  • Purpose: What goal would this borrowing support? Is there a less demanding way to reach it?
  • Repayment fit: Can you meet the repayments alongside your regular commitments, even if your income falls or household expenses rise?
  • Flexibility: What does the loan agreement allow if you want or need to change how you repay?
  • Future plans: Could the repayments affect other plans or reduce your options later?
  • Downside risk: What would you do if your circumstances changed or the purchase didn’t provide the benefit you expected?

Consider your answers together. A loan that supports a worthwhile goal may still be hard to manage if it leaves no room for change. This good debt vs bad debt nz framework is a prompt for a careful conversation, not personal financial advice or a decision about whether a lender will approve you.

Questions to ask before taking on debt

Be specific about what the borrowing is for, and ask whether a smaller commitment or another option could meet the same need. Think through changes to income or household expenses, not only how the budget looks today. Check the agreement for what it says about changing your repayment approach, and ask the lender to explain anything you’re unsure about.

How to check the effect on your household budget

Write down your regular income, essential household commitments and existing repayments before adding a new loan. Look at what remains after those obligations, and consider whether it gives you enough room for routine changes and unexpected needs. Assess the whole household picture, not just the proposed loan in isolation.

You can use the mortgage calculator to explore how possible repayments might fit your budget. Treat the result as an estimate for planning, not a prediction of approval. A lender makes its own assessment against its current criteria, while whether a loan suits your household is a separate question. Criteria can change, so ask the lender or a qualified adviser about the requirements that apply to your circumstances.

These checks can help you prepare for a home-loan discussion. They don’t replace advice tailored to your situation or guarantee an outcome. The aim is to arrive with a clearer view of your goals, budget and questions, so you can talk through the options with more confidence.

Good Debt vs Bad Debt in NZ: How to Tell the Difference

What to do if debt is putting pressure on your finances

If repayments are becoming hard to manage, that pressure is a reason to seek help, not a judgement of your character or past choices. Start by getting a clear picture of what’s due and where the strain is coming from. Having the details in front of you can make the next conversation feel more manageable.

Gather your current loan information, including repayment amounts, due dates and any changes you know are coming to your income or household spending. Note which repayments feel difficult and whether you’re relying on further borrowing to cover them. Contact your lender early and explain what’s changed. Ask what options may be available, but remember any changes depend on your circumstances and the lender’s assessment. There’s no guaranteed outcome.

How to prepare for a lender conversation

A little preparation can help you explain your situation clearly. Write down your goals, any income changes, your existing repayments and the questions you most want answered. You could ask whether repayment or loan-structure options are available, what conditions might apply and how a change could affect your future commitments. Ask the lender to explain anything that isn’t clear before you decide what to do.

It’s okay not to have a solution ready before you call. The first step is to describe what’s happening and understand what the lender can consider after reviewing your circumstances. If one option isn’t suitable, ask what else, if anything, may be available.

When to seek help with borrowing choices

If you’re considering a home loan or changes to existing lending, professional guidance can help you weigh your goals, budget and possible lending pathways. Lender requirements and your own comfort with repayments are separate parts of the decision. A loan may meet a lender’s criteria and still not feel right for your household.

Mortgage Suite can discuss your home-loan needs and suitable lending pathways, without promising approval or asking you to rush into a decision. A conversation can help you organise your questions and understand what to explore next. If you’re weighing up good debt vs bad debt nz while repayments feel tight, take the time you need to review the full picture and get support that fits your circumstances.

Talk through your home-loan needs with Mortgage Suite when you’re ready to explore your options.

How to make a more confident borrowing decision in New Zealand

A confident borrowing decision doesn’t depend on whether someone calls a loan “good” or “bad”. Focus on three practical questions: does it support a goal that matters to you, can your household manage the repayments, and what effect could it have on your future choices? Compare suitable options before committing, and ask for anything you’re unsure about to be explained in plain English.

This approach to good debt vs bad debt nz keeps the focus on your circumstances, rather than a label. You don’t need to have every answer worked out before starting a home-loan conversation. Bringing a clear picture of your situation can help you ask more useful questions and understand what to consider next.

What to bring into a home-loan discussion

It can help to prepare a few basics before you talk through a home loan:

  • Your goal: What are you hoping to do, and what matters most in choosing a loan?
  • Your finances: Note your income, any changes you expect, regular household commitments and existing repayments.
  • Your questions: Ask how the proposed loan structure and repayments could fit your plans, and what flexibility may be available if things change.

Raise uncertainties early. You’re not expected to know every lending term or arrive with a ready-made solution. If an explanation feels unclear, ask for it to be put another way before deciding whether an option suits your household.

How Mortgage Suite can support your next step

Mortgage Suite can talk through your home-loan needs, goals and budget, then help you consider which lending pathways may be suitable. The business works across mainstream and alternative lending channels and can act as a personal advocate and negotiator as options are explored. That support isn’t a promise of approval; a lender will assess your circumstances and make its own decision.

Founder Krish Krishna brings more than two decades of banking experience to these conversations. That background can help make a complex discussion easier to follow, while keeping your goals and circumstances at the centre. You can take the time you need to compare options and decide what feels manageable. A mainstream bank’s response isn’t necessarily the end of every possible conversation, but any alternative still needs careful assessment.

If you’re considering a home loan and would like to talk through your questions, Talk through your home-loan options with Mortgage Suite.

Make your next borrowing decision with clarity

Debt isn’t automatically good or bad. What matters is whether it supports a goal, fits your household budget and leaves room for the future. Before committing, look at all your repayments together, consider what could change and ask questions about any loan terms you’re unsure of.

That’s a practical way to approach good debt vs bad debt nz without judging yourself or decisions you’ve made in the past. A home-loan discussion can help you check how borrowing may fit your plans and explore which lending options could suit your circumstances. It can’t guarantee approval, but it can help you understand what to ask and what to weigh up.

Mortgage Suite supports borrowers through mainstream and alternative lending channels. Founder Krish Krishna brings more than two decades of banking experience to conversations about home loans and lender fit.

If you’re considering a home loan, talk through your home-loan options with Mortgage Suite. You can take the next step at your own pace, with a clearer picture of what matters to you.

Frequently Asked Questions

Is a mortgage always good debt?

No, a mortgage isn’t automatically good debt just because it helps you buy a home. It may support a long-term goal, but whether it suits you depends on your budget, repayments, other household commitments and plans. Consider whether you could manage the loan if your income or expenses changed. A home purchase also doesn’t guarantee that the property’s value will rise or that you’ll gain a financial benefit.

Can good debt turn into bad debt?

Yes, borrowing that once felt manageable can become a source of pressure if your circumstances change. For example, a drop in income or a rise in household commitments may make repayments harder to meet. A loan’s purpose hasn’t necessarily changed, but its effect on your budget and choices may have. Review your commitments if repayments start to feel tight, and contact your lender early to ask what options may be available.

What is the difference between good debt and bad debt?

Good debt generally describes borrowing that may support a considered goal and remains manageable. Bad debt describes borrowing that strains your finances or provides little lasting value. These labels aren’t a judgement of you, and the type of loan alone doesn’t settle the question. In good debt vs bad debt nz, look at the purpose, repayment fit and effect on future choices, as well as what could happen if your circumstances change.

How can I tell if I can manage a new loan?

Start by listing your regular income, essential household commitments and current repayments. Then consider how a new repayment would fit alongside them, including if your income changed or expenses increased. Check the loan terms and ask what flexibility may be available if your plans shift. A calculator can help you explore possible repayments, but it can’t confirm whether a lender will approve a loan or whether it’s right for your household.

Can a home loan be bad debt if I struggle with repayments?

It can become difficult debt to manage if repayments put ongoing pressure on your household, even if the loan helped you buy a home. Struggling doesn’t mean you made a bad choice or that you should feel judged. It means the loan’s effect on your finances needs attention. Review which repayments are hardest to manage, gather your current loan details and speak with your lender about what options may be available.

Does borrowing for a home guarantee a financial benefit?

No, borrowing to buy a home doesn’t guarantee a financial benefit. A property’s future value can’t be assumed, and whether home ownership suits you depends on your goals, finances and circumstances. Before taking on a mortgage, consider the repayments, other household commitments and how the loan could affect your future choices. A lender can assess an application, but that assessment is separate from deciding whether the commitment feels suitable for you.

What should I do if my debt feels unmanageable?

Gather the details of your loans, repayments and due dates, then identify which payments feel difficult. Contact your lender as early as you can and explain what’s changed. Ask what options may be available and what conditions apply. Any change depends on your circumstances and the lender’s assessment, so an outcome can’t be promised. If you’re also considering a home loan, Mortgage Suite can discuss your needs and possible lending pathways.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Guarantor Home Loan NZ: How It Works and What to Consider in 2026

Could family support help you buy a home while putting someone else’s property at risk? A guarantor home loan nz arrangement may help address a deposit shortfall, but it isn’t simply a way to get across the line. The guarantee’s limits, risks and conditions for release matter just as much as the support it may provide.

If you’re considering asking someone to guarantee your loan, it’s understandable to feel unsure about what they’d be agreeing to. A guarantor may become responsible for the guaranteed debt if you can’t repay, and the lender will still assess whether you can afford the loan.

This guide explains how guarantor home loans work in New Zealand in 2026, what lenders may consider and what to check in the guarantee documents. You’ll also find practical questions to ask the lender and an independent legal adviser, including what the guarantee covers and how the guarantor might be released. Take time to understand the arrangement before anyone agrees, and don’t feel pressured to proceed.

Key Takeaways

  • Ask whether a guarantor could help with your deposit shortfall, but remember the lender will still assess your ability to repay.
  • Before discussing a guarantor home loan nz, clarify what the guarantee covers and whether any property will be used as security.
  • Weigh the potential support for the borrower against the responsibilities the guarantor may take on under the signed terms.
  • Prepare for a lender conversation by setting out income, debts, savings and a realistic repayment plan.
  • Ask the lender and an independent legal adviser about the guarantee documents, lender criteria and possible ways to end the arrangement.

What is a guarantor home loan in New Zealand?

Saving a deposit can feel like the biggest barrier to buying your first home. If you have income to support repayments but need to discuss extra support for your application, a guarantor arrangement may be one option to explore. In a guarantor home loan nz arrangement, another person supports your home-loan application under terms agreed with the lender. That support may involve providing security, but the structure depends on the proposed arrangement.

A loan guarantee is a promise to support a loan if the borrower doesn’t meet their obligations. The guarantee documents set out what that promise means. The borrower’s loan is the debt used to buy the home; the guarantor’s promise is a separate commitment. A guarantee may strengthen an application, but it doesn’t ensure approval. The lender still considers the borrower’s circumstances and its own criteria.

For broader first-home buying and borrowing guidance, explore Mortgage Suite’s mortgage school.

How is a guarantor different from a co-borrower?

A guarantor supports a loan through a guarantee rather than simply joining in the home purchase. A co-borrower, by contrast, applies for the loan with another borrower. The responsibilities are not automatically the same, and the role names alone don’t explain the full arrangement. Check the lender’s proposal and documents to establish who is responsible for what.

Pay particular attention to what the guarantee covers, whether any security is involved and what could happen if repayments aren’t made. Don’t assume every lender uses the same structure or wording. Both parties should understand the specific terms before deciding whether to proceed.

Who might consider a guarantor home loan?

A first-home buyer might explore this option if they believe they can manage repayments but need to discuss deposit support with a lender. A guarantee doesn’t make a loan affordable by itself or mean the application will meet the lender’s criteria. The lender still needs to assess the full application.

A family member may be willing to help, but should first consider their own finances, commitments and plans. There’s no one-size-fits-all answer: the borrower’s finances, the guarantor’s position and the lender’s requirements all affect which options may be available.

How does a guarantor home loan work in New Zealand?

A guarantor arrangement is considered as part of a home-loan application, not as an automatic shortcut to approval. The borrower applies for a loan and explains the support being proposed. The lender then assesses the application and guarantee, including what the guarantor is offering and whether the arrangement meets its criteria. Criteria vary between lenders, so ask what applies to your situation.

The process generally involves these steps:

  • The borrower applies: They provide information about their finances and the home they want to buy.
  • The lender reviews the proposal: It considers the borrower’s application and the proposed guarantee, and may assess the guarantor’s circumstances too.
  • Both parties check the documents: Before signing, the borrower and guarantor should understand the terms, any security involved and what could happen if repayments aren’t made.

If the guarantee involves property, the lender may look at its equity. Equity is the difference between a property’s value and the lending secured against it. Ask whether property is part of the proposed arrangement and what that could mean for the guarantor.

The lender’s documents set out the scope of the guarantee. Read them carefully rather than relying on a general description of how these arrangements work.

What might the guarantor be agreeing to?

Don’t assume the guarantor’s responsibility is limited to a particular amount or situation. The exact commitment depends on the guarantee wording and the lender’s arrangement. Ask the lender: what event could require the guarantor to pay or provide support? What debt does the guarantee cover? What property, if any, is involved?

A general explanation of how guarantor mortgages work can introduce the concept, but it doesn’t set the terms for a New Zealand loan. The proposed lender documents do that. The guarantor should get independent legal advice before signing and ask the lender to explain its requirements.

What does the lender assess?

The lender may consider the borrower’s income, existing commitments and ability to manage repayments. It may also assess the guarantor’s financial circumstances and any property offered as security. The checks and documents required depend on the lender and the application, so confirm what is needed rather than relying on another borrower’s experience.

To build your understanding of lending terms and prepare questions for a lender, explore Mortgage Suite’s mortgage learning resources.

Guarantor home loan benefits and risks: what should both sides weigh?

A guarantor arrangement gives the borrower another option to discuss with a lender, but it also asks someone else to accept a formal commitment. For a guarantor home loan nz application, weigh the potential support against the exact responsibilities in the documents. A guarantee isn’t a risk-free shortcut or a promise that the lender will approve the loan.

Before signing, both parties should be able to explain what the guarantee covers, what security is involved and how the arrangement could end.

Possible support for the borrower Responsibilities and limits for the guarantor
A lender may consider a guarantee as part of an application where the borrower needs to discuss deposit support. The guarantor may have to provide support or meet a financial responsibility if an event described in the agreement occurs.
The arrangement may help address a deposit gap, depending on the lender’s policy and the borrower’s full financial position. Any property used as security may be affected under the agreed terms. The guarantor should confirm exactly what is involved.
It gives the borrower another option to ask about, rather than assuming the same approach suits every lender. The commitment may affect future borrowing plans, depending on how another lender views the guarantee and the guarantor’s circumstances.

What could a guarantor arrangement help with?

Some lenders may consider a guarantee when assessing an application, but their policies and criteria differ. It may be relevant if a borrower has income to manage repayments but needs to discuss a deposit shortfall. The lender will still consider the borrower’s broader financial position, including income, debts and ability to meet repayments. A guarantee doesn’t replace that assessment, and it may not be available or suitable in every case.

What risks should the guarantor understand?

The guarantor’s risk depends on the signed terms and any security involved. If the borrower can’t meet their obligations, the guarantor may face financial responsibility as set out in the agreement. Don’t rely on a verbal summary or assume the guarantee covers only one specific part of the loan. Read the documents and ask the lender to explain any wording that isn’t clear.

Consider future plans, too. If the guarantor later applies for borrowing, another lender may take the guarantee into account. The effect depends on that lender’s assessment and the details of the arrangement. Ask how and when the guarantee could end, who must agree to release it and what conditions need to be met. Don’t treat release as automatic unless the lender confirms the terms in writing.

Guarantor Home Loan NZ: How It Works and What to Consider in 2026

How to prepare for a guarantor home loan discussion

A useful conversation starts before anyone approaches a lender or signs paperwork. For a guarantor home loan nz discussion, both people need time to ask questions and decide whether the arrangement fits their circumstances. Work through the details without treating family support as a foregone conclusion.

  1. Agree to talk openly. Discuss what support is being considered, what each person feels comfortable with and whether either has concerns.
  2. Get the borrower’s finances in order. Write down income, debts, savings and planned repayments. This gives both people a clearer starting point for discussing affordability with a lender.
  3. Review the guarantor’s position. Consider existing commitments, any property that might be involved and future borrowing needs. Ask the lender what information it needs and how it will assess the proposed support.
  4. Ask about the guarantee’s terms. Clarify what the guarantee covers, whether property is used as security, how long it may apply and what conditions could allow it to be changed or released.
  5. Read, question and get advice. Review the lender’s documents, ask for plain-English explanations and make sure the guarantor gets independent legal advice before signing.

Questions the borrower and guarantor should ask

Keep a written list and check the answers against the lender’s documents. Ask:

  • What exactly would the guarantor be responsible for under these documents?
  • What conditions must be met before the guarantee can be changed or released?
  • What happens if the borrower can’t keep up with repayments?
  • Could the guarantee affect the guarantor’s future borrowing plans, and how might a lender assess that?

Ask the lender to explain anything that remains unclear. Don’t rely on assumptions about the guarantee’s scope, duration or release conditions. Those details depend on the proposed arrangement and documents.

What should each person review before signing?

Read the full set of lender documents carefully. If a term is unfamiliar, ask the lender what it means in this specific agreement. The guarantor should also seek independent legal advice to understand their position. That advice works alongside, not instead of, clear information from the lender.

Before proceeding, check that the arrangement still suits both people’s circumstances and future plans. Mortgage Suite’s Mortgage School home-loan guides offer background to help you prepare. For support understanding lender options and preparing questions, talk with Mortgage Suite about your home-loan situation.

Choosing your next step for a guarantor home loan in NZ

Before moving ahead with a guarantor home loan nz arrangement, get clear on three things: the lender’s current criteria, what the guarantee documents commit each person to, and whether the borrower’s repayment plan is realistic. If anything is uncertain, pause and ask for an explanation. A careful decision helps both the borrower and guarantor understand what they’re agreeing to.

A decline from a mainstream bank doesn’t necessarily close off every option. Different lenders may assess applications differently, but there’s no promise another lender will approve the loan. Mortgage Suite works with mainstream and alternative lending channels and can help you explore options and prepare for lender conversations based on your circumstances.

When is it worth getting professional guidance?

Consider speaking with a mortgage adviser if lender requirements are difficult to compare or you’re unsure how to present the application and proposed guarantee. An adviser may help organise the borrower’s information, clarify which lender options to discuss and communicate with potential lenders. The guarantor can also ask the lender directly about the proposed commitment.

Borrowers and guarantors may need separate legal advice about their own responsibilities. A mortgage adviser can help explain lending options, but that doesn’t replace independent legal advice for a guarantor reviewing the documents.

What happens after the first conversation?

A first discussion can cover the borrower’s goals, finances and intended purchase, as well as who may act as guarantor and what support is being considered. From there, an adviser can help identify questions to raise with lenders. Any suggested route depends on lender criteria and both people’s circumstances. The next step might be to gather more information, compare options or decide that a guarantee isn’t the right fit.

For more background on home-loan decisions and the wider buying process, visit Mortgage Suite’s Mortgage School. If you’d like to talk through your home-loan options, Mortgage Suite can help you consider a practical next step, without pressure or any promise of approval.

Take your next step with confidence

A guarantor home loan nz arrangement may help you explore a path to your first home, but the decision should rest on more than the deposit gap. Check the lender’s criteria, make sure repayments look manageable and understand exactly what the guarantee asks of the guarantor.

Both people should read the documents carefully and get clear answers about the guarantee’s scope, any security involved and how it could end. The guarantor should also seek independent legal advice. If a mainstream bank has declined your application, that doesn’t necessarily mean every option is closed. What may be possible depends on your circumstances and the lender’s assessment.

Mortgage Suite works with home-loan clients across New Zealand. Founder Krish Krishna brings more than two decades of banking experience, helping borrowers understand lender options without promising an outcome.

If you’re ready to discuss your circumstances and possible next steps, talk through your home-loan options with Mortgage Suite. Start with your questions and decide what feels right.

Frequently Asked Questions

Can a guarantor help me get a home loan in New Zealand?

A guarantor may support your application, but can’t guarantee approval. Some lenders may consider a guarantee as part of their assessment, including when you need to discuss a deposit shortfall. They’ll still assess your income, debts and ability to manage repayments, along with the proposed guarantee. If you’re considering a guarantor home loan nz option, ask the lender what criteria apply to your circumstances.

Does a guarantor have to own a home?

Not necessarily. Whether a guarantor needs to own a home depends on the lender’s requirements and the type of support being considered. Some arrangements may involve property as security, while others may be structured differently. Ask the lender what the guarantor would need to provide and whether any property is involved. Don’t assume a particular arrangement applies until you’ve checked the proposed terms.

Can a guarantor lose their home?

A guarantor could put a home at risk if it is used as security and the borrower doesn’t meet the loan obligations, depending on the signed terms and any action the lender may take. This doesn’t mean a guarantor will automatically lose their home, but the possibility should be understood before signing. Ask the lender to explain the security involved and get independent legal advice on the documents.

How much deposit do I need with a guarantor home loan?

There’s no single deposit amount that applies to every guarantor arrangement. The lender will assess the borrower’s finances, the proposed guarantee and its own lending criteria. A guarantee may help address a deposit shortfall, but it doesn’t replace checks on whether the borrower can manage repayments. Ask the lender what deposit it requires for your application and whether the guarantee changes that requirement.

Can a guarantor be removed from a home loan later?

A guarantor may be released, but this isn’t automatic. The lender’s documents set out the arrangement, and the lender will confirm whether its release conditions have been met. Before signing, ask what would need to happen for the guarantee to end, who must approve the change and how to request it. Don’t rely on an informal understanding or assume the guarantee ends after a set time.

Does being a guarantor affect your ability to borrow?

It may affect future borrowing, depending on the guarantee’s terms and how a future lender assesses the guarantor’s finances and commitments. If you’re considering borrowing for another purpose, ask the lender how this guarantee could be taken into account. The effect can vary, so don’t assume it will have no impact or prevent you from borrowing. Review your plans and seek advice before agreeing to guarantee a loan.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.

Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

A maternity-leave mortgage application isn’t decided by your current payslip alone. If you’re wondering whether getting a mortgage while on maternity leave nz is possible, the answer depends on how a lender assesses your income now, your return-to-work plans and your household’s ability to manage repayments.

Time away from work doesn’t automatically rule you out, but approval isn’t guaranteed. Lenders can assess applications differently, so it helps to give them a clear picture of your finances and plans. This guide explains what may affect an assessment and how to prepare useful information.

You’ll learn how lenders may view parental leave payments, your expected return date and a temporary drop in household income. We’ll also cover documents that may help, such as an employer letter confirming your role, salary and expected return date, and ways to explain how repayments will fit your budget. Mortgage Suite can help you understand and compare mainstream and alternative lending options, so you can consider a sensible next step without assuming every lender will reach the same decision.

Key Takeaways

  • Getting a mortgage while on maternity leave nz may be possible, but a lender will assess your circumstances and ability to manage repayments.
  • Ask how the lender will consider your current income, planned return to work and household commitments.
  • Prepare employment and income evidence, such as confirmation of your role, salary and expected return date. Check which documents the lender needs.
  • Compare how mainstream and alternative lenders assess your situation rather than assuming every lender will take the same view.
  • A mortgage adviser can help you understand your options and explain your circumstances to lenders, but can’t guarantee approval.

Can you get a mortgage while on maternity leave in NZ?

Yes, applying for a home loan while you’re on maternity leave may be possible. Being on leave doesn’t automatically mean you’ll be approved, and it doesn’t automatically rule you out. A lender needs to assess whether your household could manage the proposed repayments while your income is reduced and under your expected work arrangements after leave.

Getting a mortgage while on maternity leave nz depends on your full situation, not just the fact that you’re away from work. Lenders may consider your income, employment plans, regular household commitments and the amount you want to borrow. Requirements differ, so check what a lender currently accepts rather than relying on a friend’s experience or an old online example.

Does maternity leave automatically stop a mortgage application?

No single outcome applies to every borrower. Maternity leave is a temporary change in your work and income, but the lender will still assess the whole financial picture. Your return-to-work plans, another applicant’s income and your household commitments may all be relevant. These details help explain how your household expects to manage repayments, but none guarantees approval.

Parental leave sits within New Zealand’s employment framework. You can read more about the Parental Leave and Employment Protection Act 1987, but a lender’s mortgage assessment is separate from your employment rights.

What will a lender want to understand about your situation?

Expect to discuss your current income and how it may change during leave. A lender may ask whether your employer has confirmed your expected return date, role and salary. If your arrangements aren’t final, be upfront about that and ask what information could clarify your position.

The lender will also consider your household’s regular commitments and the proposed loan. Be ready to explain how repayments would fit your budget during leave and after you return to work. Ask which documents the lender accepts to confirm income and employment plans. Don’t assume every lender requires the same evidence or will reach the same view.

If a mainstream bank declines your application, ask what informed its decision and whether another lender may assess your circumstances differently. An alternative option would still need to be assessed on its merits, so treat the next step as a fresh conversation, not a promise of approval.

How lenders may assess income and affordability during maternity leave

A lender’s central question is whether your household appears able to manage the proposed repayments. It may discuss the income coming in now, how that could change during leave, your expected work arrangements afterwards and other regular household income. How leave-related income is treated can vary. Ask the lender how it would assess your circumstances rather than assuming your usual salary will be counted in full.

New Zealand’s Parental leave entitlements information explains the leave framework and points to payment details. It can help you understand your own situation, but it doesn’t determine how a lender will assess your mortgage application. If you’re getting a mortgage while on maternity leave nz, make clear which income is confirmed and which arrangements are planned.

How a return-to-work plan can help explain your application

If your return arrangements are confirmed, note your expected return date and whether you’ll be returning to the same role or working different hours. An employer letter may help explain your role, hours and pay. It’s supporting information, not a guarantee that the lender will count your planned income when assessing affordability. Ask what form of confirmation it accepts and whether it needs anything else.

How household commitments can affect the assessment

Income is only part of the picture. List your regular household expenses and existing repayments, then consider how the budget may change if childcare or work arrangements affect your spending or income. This gives you and the lender a practical basis for discussing whether repayments look manageable while your income is different.

You can use the Mortgage Suite mortgage calculator to explore possible repayments as part of your planning. Treat the result as an estimate, not a lender decision or a promise of approval.

Examples of evidence a lender may ask for, depending on its requirements:

  • Recent payslips or information showing income received during leave.
  • An employer letter confirming your expected return date, role, hours or pay, if available.
  • Details of other regular household income, existing repayments and ongoing expenses.

This is a starting point, not a universal checklist. Before gathering documents, ask your chosen lender or adviser which evidence it accepts and how it will consider your income and commitments. A clear explanation can help you compare options and decide what to do next.

Mainstream or alternative lender: what should you compare?

A lender’s approach can affect how your maternity-leave income and work plans are considered. Instead of looking only for an immediate yes, compare what each lender needs to understand, how it assesses your household budget and whether the proposed loan could suit your plans beyond the leave period. Criteria can change, so ask for current requirements rather than treating another borrower’s experience as a guide to your own application.

Use these questions to compare options. They don’t describe a guaranteed policy for any lender:

What to compare What to ask
Confirmed income Which income documents do you need, and how will you assess income during leave?
Return-to-work plans What evidence of my expected return date, role, hours or pay can you consider?
Household commitments How will you assess regular expenses, existing repayments and expected changes to our budget?
Loan fit What repayment choices or loan structure should we consider for our longer-term household plans?

Questions to ask before choosing a lender

Ask each lender for a clear list of the income and employment details it needs. Check how it treats a planned return to work and changing household expenses. Discuss whether the proposed repayments and loan structure fit your plans after you return. This helps you compare the overall suitability of an option, not just whether an application might proceed now.

When an alternative lending conversation may be useful

If a mainstream lender declines your application, that doesn’t mean every option is closed. Mortgage Suite can help you explore mainstream and alternative lending channels, including 2nd-tier lending, where suitable. Each option still depends on an assessment of your circumstances, and terms and suitability can differ. If you’re getting a mortgage while on maternity leave nz, ask what a lender’s decision was based on before choosing your next step.

Alternative lending isn’t automatically a better fit. Compare how the lender will assess your confirmed income, return-to-work evidence and household commitments. Make sure you understand the proposed repayments and structure. A lending adviser can help you organise your questions and explain your circumstances, without promising approval. The aim is to make a considered choice that fits your situation.

Getting a Mortgage on Maternity Leave in NZ: 2026 Guide

How to prepare a mortgage application while on maternity leave

Preparation can make an initial lending conversation clearer and help you identify missing information early. Start by mapping your household finances, confirming what you know about your employment and return-to-work plans, and gathering available evidence. Then ask which lending options may suit your circumstances. If you’re getting a mortgage while on maternity leave nz, explain changes to your income or work arrangements openly and consistently.

A practical document checklist to start with

Pull together what you already have. This is a starting point, not a list every lender will require. Check the exact document list with your chosen lender or adviser before relying on any particular item.

  • Recent payslips or other available records showing your income during leave.
  • Employment details, such as your role and any confirmed changes to your hours or working arrangements.
  • Written confirmation of your expected return date and pay, if your employer has provided it.
  • Details of regular household expenses, existing repayments and other income.
  • Information about your current leave arrangements and any expected changes to your household budget.

If something hasn’t been confirmed, say so. Clear, consistent information helps the person reviewing your application understand what’s known and what’s still being planned.

How to make the first conversation more useful

Before speaking with a lender or adviser, note your property goal, preferred timing and questions about how your income during leave and return-to-work plans may be assessed. Include relevant changes to your household finances, such as a shift in work hours or expected childcare arrangements. You don’t need every answer ready. Being clear about what’s confirmed and what’s uncertain gives the conversation a useful starting point.

Review possible repayments against your household budget. Consider whether they look manageable with your current income and how your budget might change when work arrangements shift. An estimate can support your planning, but it isn’t a lending decision. Ask how a proposed loan might fit your longer-term plans if you’re unsure.

For plain-English help with lending basics, explore Mortgage Suite’s Mortgage School. When you’re ready to discuss your circumstances, talk with Mortgage Suite about your home loan. A lending professional can help you organise information and discuss possible options, but approval depends on the lender’s assessment.

Getting support with a maternity-leave mortgage application

You don’t have to work through every lending question on your own. Gather the evidence you have, note what’s confirmed about your return to work and ask lenders how they would assess your circumstances. If getting a mortgage while on maternity leave nz feels like a lot to manage, a mortgage adviser can help organise your questions and compare possible options.

An adviser can help explain your situation to lenders and clarify what further information may be useful. Mortgage Suite can present your circumstances and discuss possible options with lenders, including whether mainstream or alternative lending channels may be worth exploring. Any recommendation depends on a careful review of your circumstances, and no particular lending decision is assured.

What a mortgage adviser can help you work through

Start by discussing the parts of your application that may need context. Your current income may differ from your expected income after returning to work, or your return date may still be unconfirmed. An adviser can help identify what needs explaining, ask what supporting evidence a lender may accept and communicate the details clearly. They can also help compare potential lender fit, while making clear that each lender makes its own assessment.

Mortgage Suite supports borrowers through mainstream and alternative lending channels. Founder Krish Krishna established the business in 2000 and brings more than two decades of banking experience. That background can inform a practical conversation about your circumstances, but it can’t assure a particular lending decision.

Choose your next step with confidence

Before getting in touch, you may want to read about Mortgage Suite’s background and browse client reviews to learn about other borrowers’ experiences. Reviews are individual accounts, not a promise that your application will have the same outcome.

Bring the information you have and ask direct questions: what needs more evidence, how could your return-to-work plans be considered, and which lender options may suit your household? Take time to understand the answers and decide what feels sensible. A mainstream lender’s decline isn’t necessarily the end of your options, but any next route still needs to suit your circumstances and pass the lender’s assessment.

If you’d like to discuss your situation and explore possible next steps, talk through your home-loan options. You don’t need every detail sorted before starting the conversation.

Take a clear next step with your home-loan plans

Getting a mortgage while on maternity leave nz may be possible, but each lender will assess your circumstances. A clear picture of your current income, confirmed work plans and household commitments can help you explain your application and ask useful questions. Requirements differ between lenders, and approval is never guaranteed.

Gather the evidence you have, check what a lender needs and compare options that could suit your household now and longer term. A decline from one lender doesn’t necessarily mean every option is closed. Mortgage Suite Ltd has supported borrowers since 2000, and founder Krish Krishna brings more than two decades of banking experience. The team can discuss mainstream and alternative lending channels, subject to an assessment of your situation.

If you’d like to discuss your next step, talk through your home-loan options. Bring your questions and the information you have, and Mortgage Suite can help you explore possible lending options.

Frequently Asked Questions

Can I get a mortgage while on maternity leave in NZ?

It may be possible, but there’s no answer that applies to every borrower. For getting a mortgage while on maternity leave nz, lenders assess your income, employment, household commitments and proposed loan using their own criteria. Explain your leave arrangements and any confirmed return-to-work plans, then ask what evidence the lender needs. A mortgage adviser can help you understand which mainstream or alternative options may be worth exploring, subject to assessment.

Will a lender count my income while I am on maternity leave?

How a lender treats income during leave can vary, so don’t assume it will count your income in a particular way. Ask how it assesses your current income and any expected change when you return to work. You may need to provide employment details or confirmation of your work arrangements. Check the lender’s current requirements before applying, as policies and accepted evidence can differ.

What documents might I need for a mortgage application during maternity leave?

The documents requested depend on the lender and your circumstances. You may be asked for information about your income, employment, leave arrangements, regular household commitments and any confirmed return-to-work plan. Treat a checklist as a starting point, not a guaranteed list of requirements. Contact the lender or adviser early to confirm exactly what they need, including whether documents must be recent or supplied in a particular format.

Can I apply for a mortgage before I return to work?

You can ask a lender or adviser about applying before your planned return, but the timing and evidence needed depend on your circumstances and the lender’s criteria. Explain your current leave, employment status and any confirmed work arrangements. The lender may also want to understand how your household commitments fit alongside the proposed repayments. Ask what information could support an assessment now rather than assuming how planned income will be treated.

Does maternity leave affect mortgage pre-approval in New Zealand?

It can affect the information a lender asks for, but it doesn’t automatically decide the outcome. Pre-approval is based on the lender’s assessment at that time and may include conditions. Be upfront about your leave arrangements, income and expected work changes, and check what evidence is needed. If your circumstances change after pre-approval, contact the lender to ask whether it needs to review your application before you rely on it.

What if my bank declines my mortgage application while I am on maternity leave?

A decline from one lender isn’t necessarily a final judgement on your borrowing prospects. Ask for a clear explanation and whether further information could help. Lenders assess applications differently, but another option isn’t guaranteed. A mortgage adviser can help you understand the issues, compare possible mainstream and alternative lending channels, and decide whether to provide more evidence or make changes before approaching another lender. Any option remains subject to assessment.

Should I wait until I return to work before applying for a mortgage?

There’s no single best time for every borrower. Applying before you return may suit some circumstances, while waiting could give you clearer income evidence. Consider your property plans, household budget and the documents available now. Ask a lender or adviser how each timing option may be assessed before deciding. Don’t treat planned income as guaranteed, and check whether changes to your circumstances or work arrangements could affect the information the lender needs.

Article by

Krish Krishna

Experienced Financial Adviser with over 46 years of Banking and Mortgage broking experience and over $2.0 Billion in loan settlements.